 filings.tools
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
155K characters. Original on sec.gov · Markdown
Item 2. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
MD&A is intended to assist readers in their analysis of the accompanying Consolidated Financial Statements and supplemental financial information. It should be read in conjunction with the Consolidated Financial Statements, the accompanying Notes to the Consolidated Financial Statements in this Form 10-Q, other information contained in this document, as well as with Truist’s Annual Report on Form 10-K for the year ended December 31, 2022.
A description of certain factors that may affect our future results and risk factors is set forth in Part I, Item 1A-Risk Factors in our Annual Report on Form 10-K for the year ended December 31, 2022.
Regulatory Considerations
The regulatory framework applicable to banking organizations is intended primarily for the protection of depositors and the stability of the financial system, rather than for the protection of shareholders and creditors. Truist is subject to banking laws and regulations, and various other laws and regulations, which affect the operations and management of Truist and its ability to make distributions to shareholders. Truist and its subsidiaries are also subject to supervision and examination by multiple regulators. The descriptions below summarize updates since the filing of the Annual Report on Form 10-K for the year ended December 31, 2022 to state and federal laws to which Truist is subject. These descriptions do not summarize all possible or proposed changes in current laws or regulations and are not intended to be a substitute for the related statues or regulatory provisions. Refer to Truist’s Annual Report on Form 10-K for the year ended December 31, 2022 for additional disclosures.
In March 2023, the FRB created the Bank Term Funding Program to support American businesses and households by making additional funding available to eligible depository institutions. This program offers loans up to one year in length to banks, savings associations, credit unions, and other eligible depository institutions pledging any collateral eligible for purchase by the FRB in open market operations, such as U.S. Treasuries, U.S. agency securities, and U.S. agency mortgage-backed securities. These assets will be valued at par.
In the aftermath of the recent bank failures, we expect that the banking agencies will propose certain actions, including reforms that may impose different capital and liquidity requirements, including increased requirements to issue long term debt. In addition, there may be special assessments to repay losses to the FDIC’s Deposit Insurance Fund. It is not yet possible to quantify the impact of these potential actions.
Executive Overview
In a challenging and unique quarter for the banking industry, Truist demonstrated strength and leadership that reflects our diverse business model, granular and relationship-oriented deposit base, and strong capital and liquidity position. Truist has significant access to liquidity and a very robust liquidity management process that includes internal and external stress testing, as well as real-time monitoring of our liquidity position. We also closed on the sale of a 20% minority stake in Truist Insurance Holdings, LLC on April 3, 2023, which provides strategic and financial flexibility for both Truist and Truist Insurance Holdings.
We continued to experience the benefits of our shift from integrating to operating, including improving organic production and integrated relationship management momentum, although these benefits were offset by higher-than-expected funding costs. Asset quality metrics remain strong, and we prudently increased our ALLL ratio by three basis points to reflect increased economic uncertainty.
Our focus on clients was unwavering during the first quarter of 2023. Our teammates continue to care for our clients and stakeholders and live our purpose to inspire and build better lives and communities. Truist continues to be a source of strength and stability for our clients and communities.
Truist made a $1 billion uninsured time deposit in First Republic Bank during the first quarter joining the nation’s largest financial intuitions to show support for the U.S. banking system and the economy. On Monday, May 1, 2023, JPMorgan Chase Bank, National Association assumed all of the deposits and purchased the substantial majority of assets of First Republic Bank from the FDIC. JPMorgan Chase Bank, National Association has indicated that the deposit Truist made at First Republic Bank will be repaid post-closing of the transaction.
Detailed below are actions that we have taken to fulfill our purpose to inspire and build better lives and communities, followed by a discussion of our financial results for the first quarter of 2023.
-
Made meaningful improvement in our client experience, with Voice of the Client metrics rising since the second quarter of 2022, and continued positive momentum with branch satisfaction scores in the first quarter of 2023
-
Opened T3 Accelerator Lab in the Innovation & Technology Center where we’re redefining the client and teammate experience, putting feedback and ideas to the test in real-world scenarios before rolling out to clients
40 Truist Financial Corporation
-
Continued growth for Truist Momentum, Truist’s financial wellness program
-
Published 2022 Corporate Responsibility Report, TCFD Report, and ESG Disclosure Summary, highlighting our progress across multiple dimensions including community, financial inclusion, DEI, and climate and energy
◦We made important progress on our sustainability commitments through 2022, including our goal of achieving a 35% reduction in both Scope 1 and Scope 2 emissions by 2030 from our baseline year of 2019. We reduced Scope 1 emissions by 17% and Scope 2 emissions by 26%.
-
Successfully migrated certain consumer and small business credit cards to a new processing platform
-
Announced a new goal to increase female and ethnically diverse representation in leadership roles by 15% and 20%, respectively, by 2025
-
Committed $282 million from Truist Community Capital to support affordable housing and job creation in underserved communities and $22 million through Truist Foundation for a multiyear program to strengthen small businesses and create career pathways for ethnically diverse individuals and entrepreneurs
-
We are also in the process of realigning our LightStream platforms with our broader consumer business, with the goal of bringing the innovation, digital capabilities, efficiencies, and certain cloud-based infrastructure of LightStream to the broader Truist client base
Financial Results
Net income available to common shareholders for the first quarter of 2023 of $1.4 billion was up 6.3% compared with the first quarter of 2022. On a diluted per common share basis, earnings for the first quarter of 2023 were $1.05, an increase of $0.06, or 6.1%, compared to the first quarter of 2022. Truist’s results of operations for the first quarter of 2023 produced an annualized return on average assets of 1.10% and an annualized return on average common shareholders’ equity of 10.3% compared to prior year returns of 1.07% and 9.0%, respectively.
-
Results for the first quarter of 2023 included merger-related and restructuring charges of $63 million ($48 million after-tax, or $0.04 per share).
-
Results for the first quarter of 2022 included $216 million ($166 million after-tax, or $0.12 per share) of merger-related and restructuring charges, $202 million ($155 million after-tax, or $0.12 per share) of incremental operating expenses related to the Merger, a gain on the redemption of noncontrolling equity interest of $74 million ($57 million after-tax, or $0.04 per share) related to the acquisition of certain merchant services relationships, and net losses on the sales of securities of $69 million ($53 million after-tax, or $0.04 per share).
Taxable-equivalent net interest income for the first quarter of 2023 was up $710 million, or 22%, compared to the first quarter of 2022 primarily due to higher short-term interest rates and strong loan growth, alongside well controlled deposit costs. These increases were partially offset by lower purchase accounting accretion and PPP revenue. Net interest margin was 3.17%, up 41 basis points.
-
The yield on the total loan portfolio was 5.81%, up 212 basis points, primarily reflecting higher market interest rates, partially offset by lower purchase accounting accretion and PPP revenue. The yield on the average securities portfolio was 2.14%, up 46 basis points primarily due to the higher rate environment. The average cost of total deposits was 1.12%, up 109 basis points.
-
The average cost of short-term borrowings was 4.69%, up 409 basis points. The average cost of long-term debt was 4.05%, up 255 basis points. The increase in rates on deposits and other funding sources was largely attributable to the higher rate environment.
Noninterest income was up $92 million, or 4.3%, compared to the first quarter of 2022 due to 12% growth in insurance income, higher mortgage banking income, higher fees from lending-related activities and card and payment related activities. These items were partially offset by lower other income. The first quarter of 2022 included $69 million of securities losses and a $74 million gain on the redemption of noncontrolling equity interest (included in other income).
Noninterest expense was up $17 million, or 0.5%, compared to the first quarter of 2022 due to higher personnel expense, other expense, and regulatory costs. These increases were partially offset by lower merger-related and restructuring charges and professional fees and outside processing expenses. Merger-related and restructuring charges and incremental operating expenses related to the merger decreased $153 million and $202 million, respectively, due to the completion of integration-related activities. Adjusted noninterest expenses, which exclude merger-related costs and the amortization of intangibles increased $373 million, or 12%.
The provision for income taxes was $394 million for the first quarter of 2023, compared to $330 million for the earlier quarter. The effective tax rate for the first quarter of 2023 was 20.6%, compared to 18.9% for the earlier quarter.
Asset quality remains excellent, reflecting Truist’s prudent risk culture and diverse portfolio. Nonperforming loans and leases held for investment were 0.36% of loans and leases held for investment at March 31, 2023, flat compared to December 31, 2022.
Truist Financial Corporation 41
-
The allowance for credit losses was $4.8 billion and includes $4.5 billion for the allowance for loan and lease losses and $282 million for the reserve for unfunded commitments. The ALLL ratio was 1.37%, up three basis points compared with December 31, 2022 primarily due to increased economic uncertainty.
-
The provision for credit losses was $502 million compared to a benefit of $95 million for the first quarter of 2022. The increase in the current quarter provision expense primarily reflects increased economic uncertainty in the current period, whereas the earlier quarter included a reserve release due to the improving credit environment during that period.
-
The net charge-off ratio was 37 basis points, up 12 basis points compared to the first quarter of 2022 driven by higher charge-offs in the indirect auto and other consumer portfolios due to normalizing trends, as well as an increase in the commercial and industrial portfolio.
Capital and liquidity remained strong compared to the regulatory requirements for well capitalized banks.
-
Truist CET1 ratio was 9.1% as of March 31, 2023. The increase since December 31, 2022 represents organic capital generation, partially offset by the CECL phase-in.
-
Truist closed the sale of the minority stake in TIH on April 3, 2023, which adds 30 basis points to the risk-based regulatory capital ratios.
-
Truist declared common dividends of $0.52 per share during the first quarter of 2023. The dividend payout ratio for the first quarter of 2023 was 49%. Truist did not repurchase any shares in the first quarter of 2023.
-
Truist’s average consolidated LCR was 113% for the three months ended March 31, 2023, compared to the regulatory minimum of 100%.
-
Truist has significant and strong access to liquidity with $166 billion of available liquidity as of March 31, 2023.
-
Truist increased its cash position in response to market events.
-
AOCI improved by $1.0 billion, or 7.5%, since December 31, 2022.
Analysis of Results of Operations
Net Interest Income and NIM
Taxable-equivalent net interest income for the first quarter of 2023 was up $710 million, or 22%, compared to the first quarter of 2022 primarily due to higher short-term interest rates and strong loan growth, alongside well controlled deposit costs. These increases were partially offset by lower purchase accounting accretion and PPP revenue. Net interest margin was 3.17%, up 41 basis points.
-
Average earning assets increased $29.2 billion, or 6.2%, primarily due to growth in average total loans of $35.1 billion, or 12%, and growth in other earning assets of $6.7 billion, or 35%, primarily due to an increase in balances held at the Federal Reserve to support liquidity build, partially offset by a decrease in average securities of $12.1 billion, or 7.9%.
-
The yield on the total loan portfolio was 5.81%, up 212 basis points, primarily reflecting higher market interest rates, partially offset by lower purchase accounting accretion and PPP revenue. The yield on the average securities portfolio was 2.14%, up 46 basis points primarily due to the higher rate environment.
-
Average deposits decreased $6.8 billion, or 1.6%, average short-term borrowings increased $17.1 billion, and average long-term debt increased $15.7 billion, or 44.5%.
-
The average cost of total deposits was 1.12%, up 109 basis points. The average cost of short-term borrowings was 4.69%, up 409 basis points. The average cost of long-term debt was 4.05%, up 255 basis points. The increase in rates on deposits and other funding sources was largely attributable to the higher rate environment.
As of March 31, 2023, the remaining unamortized fair value marks on the loan and lease portfolio and long-term debt were $673 million and $69 million, respectively. As of December 31, 2022, the remaining unamortized fair value marks on the loan and lease portfolio and long-term debt were $741 million and $81 million, respectively.
The remaining unamortized purchase accounting fair value mark on loans and leases consists of $447 million for consumer loans and leases, and $226 million for commercial loans and leases. These amounts will be recognized over the remaining contractual lives of the underlying instruments or as paydowns occur.
The major components of net interest income and the related annualized yields as well as the variances between the periods caused by changes in interest rates versus changes in volumes are summarized below.
42 Truist Financial Corporation
| Table 1: Taxable-Equivalent Net Interest Income and Rate / Volume Analysis | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended March 31, (Dollars in millions) | Average Balances**(1)** | Annualized Yield/Rate**(2)** | Income/Expense | Incr. (Decr.) | Change due to | ||||||||||||||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | 2023 | 2022 | 2023 | 2022 | Rate | Volume | ||||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| AFS and HTM securities at amortized cost: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. Treasury | $ | 11,117 | $ | 9,890 | 1.07 | % | 0.72 | % | $ | 30 | $ | 18 | $ | 12 | $ | 10 | $ | 2 | |||||||||||||||||||||||||||||||||||
| GSE | 335 | 1,120 | 2.86 | 2.13 | 2 | 6 | (4) | 2 | (6) | ||||||||||||||||||||||||||||||||||||||||||||
| Agency MBS | 124,746 | 137,052 | 2.23 | 1.72 | 694 | 590 | 104 | 160 | (56) | ||||||||||||||||||||||||||||||||||||||||||||
| States and political subdivisions | 425 | 374 | 4.07 | 3.72 | 4 | 3 | 1 | — | 1 | ||||||||||||||||||||||||||||||||||||||||||||
| Non-agency MBS | 3,907 | 4,224 | 2.34 | 2.25 | 23 | 24 | (1) | 1 | (2) | ||||||||||||||||||||||||||||||||||||||||||||
| Other | 21 | 27 | 5.30 | 2.04 | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||
| Total securities | 140,551 | 152,687 | 2.14 | 1.68 | 753 | 641 | 112 | 173 | (61) | ||||||||||||||||||||||||||||||||||||||||||||
| Interest earning trading assets | 5,462 | 5,837 | 6.09 | 3.04 | 83 | 43 | 40 | 43 | (3) | ||||||||||||||||||||||||||||||||||||||||||||
| Other earning assets(3) | 25,589 | 18,932 | 4.67 | 0.63 | 295 | 30 | 265 | 251 | 14 | ||||||||||||||||||||||||||||||||||||||||||||
| Loans and leases, net of unearned income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 165,095 | 138,872 | 5.98 | 2.88 | 2,436 | 987 | 1,449 | 1,233 | 216 | ||||||||||||||||||||||||||||||||||||||||||||
| CRE | 22,689 | 23,555 | 6.32 | 2.84 | 355 | 168 | 187 | 193 | (6) | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial Construction | 5,863 | 5,046 | 7.14 | 3.05 | 101 | 35 | 66 | 59 | 7 | ||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | 56,422 | 47,976 | 3.73 | 3.57 | 526 | 428 | 98 | 20 | 78 | ||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 10,735 | 10,822 | 6.80 | 4.33 | 180 | 116 | 64 | 65 | (1) | ||||||||||||||||||||||||||||||||||||||||||||
| Indirect auto | 27,743 | 26,088 | 5.82 | 5.56 | 398 | 357 | 41 | 17 | 24 | ||||||||||||||||||||||||||||||||||||||||||||
| Other consumer | 27,559 | 24,921 | 6.76 | 6.24 | 459 | 383 | 76 | 33 | 43 | ||||||||||||||||||||||||||||||||||||||||||||
| Student | 5,129 | 6,648 | 7.04 | 3.86 | 89 | 63 | 26 | 43 | (17) | ||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 4,785 | 4,682 | 11.43 | 8.97 | 136 | 104 | 32 | 30 | 2 | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases HFI | 326,020 | 288,610 | 5.81 | 3.70 | 4,680 | 2,641 | 2,039 | 1,693 | 346 | ||||||||||||||||||||||||||||||||||||||||||||
| LHFS | 1,527 | 3,874 | 6.71 | 2.87 | 25 | 28 | (3) | 21 | (24) | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | 327,547 | 292,484 | 5.81 | 3.69 | 4,705 | 2,669 | 2,036 | 1,714 | 322 | ||||||||||||||||||||||||||||||||||||||||||||
| Total earning assets | 499,149 | 469,940 | 4.72 | 2.90 | 5,836 | 3,383 | 2,453 | 2,181 | 272 | ||||||||||||||||||||||||||||||||||||||||||||
| Nonearning assets | 60,478 | 66,041 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 559,627 | $ | 535,981 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities and Shareholders’ Equity | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-checking | $ | 108,886 | $ | 112,159 | 1.60 | 0.05 | 430 | 14 | 416 | 416 | — | ||||||||||||||||||||||||||||||||||||||||||
| Money market and savings | 139,802 | 141,500 | 1.38 | 0.03 | 476 | 11 | 465 | 465 | — | ||||||||||||||||||||||||||||||||||||||||||||
| Time deposits | 28,671 | 15,646 | 3.10 | 0.18 | 219 | 7 | 212 | 202 | 10 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 277,359 | 269,305 | 1.64 | 0.05 | 1,125 | 32 | 1,093 | 1,083 | 10 | ||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings | 24,056 | 6,944 | 4.69 | 0.60 | 278 | 10 | 268 | 197 | 71 | ||||||||||||||||||||||||||||||||||||||||||||
| Long-term debt | 51,057 | 35,337 | 4.05 | 1.50 | 514 | 132 | 382 | 303 | 79 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 352,472 | 311,586 | 2.20 | 0.22 | 1,917 | 174 | 1,743 | 1,583 | 160 | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 131,099 | 145,933 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 13,979 | 11,664 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 62,077 | 66,798 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 559,627 | $ | 535,981 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Average interest-rate spread | 2.52 | % | 2.68 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| NIM/net interest income - taxable equivalent | 3.17 | % | 2.76 | % | $ | 3,919 | $ | 3,209 | $ | 710 | $ | 598 | $ | 112 | |||||||||||||||||||||||||||||||||||||||
| Taxable-equivalent adjustment | $ | 51 | $ | 26 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Memo: Total deposits | $ | 408,458 | $ | 415,238 | 1.12 | % | 0.03 | % | $ | 1,125 | $ | 32 | $ | 1,093 |
(1)Represents daily average balances. Excludes basis adjustments for fair value hedges.
(2)Yields are stated on a TE basis utilizing federal tax rate. The change in interest not solely due to changes in rate or volume has been allocated based on the pro-rata absolute dollar amount of each. Interest income includes certain fees, deferred costs, and dividends.
(3)Includes cash equivalents, interest-bearing deposits with banks, FHLB stock and other earning assets.
Truist Financial Corporation 43
Provision for Credit Losses
The provision for credit losses was $502 million compared to a benefit of $95 million for the first quarter of 2022. The net charge-off ratio was 37 basis points, up 12 basis points compared to the first quarter of 2022.
-
The increase in the current quarter provision expense primarily reflects increased economic uncertainty in the current period, whereas the earlier quarter included a reserve release due to the improving credit environment during that period.
-
The net charge-off ratio was up compared to the first quarter of 2022 driven by higher charge-offs in the indirect auto and other consumer portfolios due to normalizing trends, as well as an increase in the commercial and industrial portfolio.
Noninterest Income
Noninterest income is a significant contributor to Truist’s financial results. Management focuses on diversifying its sources of revenue to reduce Truist’s reliance on traditional spread-based interest income, as certain fee-based activities are a relatively stable revenue source during periods of changing interest rates. The following table provides a breakdown of Truist’s noninterest income:
| Table 2: Noninterest Income | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended March 31, | ||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | 2023 | 2022 | % Change | |||||||||||||||||||||||||||||||||||||||||||||||
| Insurance income | $ | 813 | $ | 727 | 11.8 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Wealth management income | 339 | 343 | (1.2) | |||||||||||||||||||||||||||||||||||||||||||||||
| Investment banking and trading income | 261 | 261 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Service charges on deposits | 249 | 252 | (1.2) | |||||||||||||||||||||||||||||||||||||||||||||||
| Card and payment related fees | 230 | 212 | 8.5 | |||||||||||||||||||||||||||||||||||||||||||||||
| Mortgage banking income | 142 | 121 | 17.4 | |||||||||||||||||||||||||||||||||||||||||||||||
| Lending related fees | 106 | 85 | 24.7 | |||||||||||||||||||||||||||||||||||||||||||||||
| Operating lease income | 67 | 58 | 15.5 | |||||||||||||||||||||||||||||||||||||||||||||||
| Securities gains (losses) | — | (69) | NM | |||||||||||||||||||||||||||||||||||||||||||||||
| Other income | 27 | 152 | (82.2) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total noninterest income | $ | 2,234 | $ | 2,142 | 4.3 | |||||||||||||||||||||||||||||||||||||||||||||
Noninterest income was up $92 million, or 4.3%, compared to the first quarter of 2022 due to 12% growth in insurance income, higher mortgage banking income, higher fees from lending-related activities and card and payment related activities. These items were partially offset by lower other income. The first quarter of 2022 included $69 million of securities losses and a $74 million gain on the redemption of noncontrolling equity interest (included in other income).
-
Insurance income increased primarily due to acquisitions and 4.7% organic growth.
-
Mortgage banking income increased due to a gain on the sale of a servicing portfolio, partially offset by mortgage servicing rights valuation adjustments in the current quarter.
-
Lending related fees increased primarily due to higher unused commitment fees.
-
Card and payment related fees increased due to higher volumes and the acquisition of a merchant portfolio.
-
Other income decreased due to the aforementioned gain in the year ago quarter, lower investment income from the Company’s SBIC and other investments, partially offset by higher income from investments held for certain post-retirement benefits (which is primarily offset by higher personnel expense).
44 Truist Financial Corporation
Noninterest Expense
The following table provides a breakdown of Truist’s noninterest expense:
| Table 3: Noninterest Expense | |||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | 2023 | 2022 | % Change | ||||||||||||||||||||||||||||||||||||||||||||
| Personnel expense | $ | 2,181 | $ | 2,051 | 6.3 | % | |||||||||||||||||||||||||||||||||||||||||
| Professional fees and outside processing | 314 | 363 | (13.5) | ||||||||||||||||||||||||||||||||||||||||||||
| Software expense | 214 | 232 | (7.8) | ||||||||||||||||||||||||||||||||||||||||||||
| Net occupancy expense | 183 | 208 | (12.0) | ||||||||||||||||||||||||||||||||||||||||||||
| Amortization of intangibles | 136 | 137 | (0.7) | ||||||||||||||||||||||||||||||||||||||||||||
| Equipment expense | 110 | 118 | (6.8) | ||||||||||||||||||||||||||||||||||||||||||||
| Marketing and customer development | 78 | 84 | (7.1) | ||||||||||||||||||||||||||||||||||||||||||||
| Operating lease depreciation | 46 | 48 | (4.2) | ||||||||||||||||||||||||||||||||||||||||||||
| Regulatory costs | 75 | 35 | 114.3 | ||||||||||||||||||||||||||||||||||||||||||||
| Merger-related and restructuring charges | 63 | 216 | (70.8) | ||||||||||||||||||||||||||||||||||||||||||||
| Other expense | 291 | 182 | 59.9 | ||||||||||||||||||||||||||||||||||||||||||||
| Total noninterest expense | $ | 3,691 | $ | 3,674 | 0.5 | ||||||||||||||||||||||||||||||||||||||||||
Noninterest expense was up $17 million, or 0.5%, compared to the first quarter of 2022 due to higher personnel expense, other expense, and regulatory costs. These increases were partially offset by lower merger-related and restructuring charges and professional fees and outside processing expenses. Merger-related and restructuring charges and incremental operating expenses related to the merger decreased $153 million and $202 million, respectively, due to the completion of integration-related activities. Adjusted noninterest expenses, which exclude merger-related costs and the amortization of intangibles increased $373 million, or 12%.
-
Personnel expense increased due to investments in teammates by increasing Truist’s minimum wage, the impact from acquisitions, investments in revenue producing businesses and enterprise technology, and higher other post-retirement benefit expense (which is almost entirely offset by higher other income), partially offset by lower pension expenses.
-
Other expense increased primarily due to higher pension expense (driven primarily by lower plan assets) and higher operating losses.
-
Regulatory costs increased primarily due to an increase in the FDIC’s deposit insurance assessment rate.
-
Professional fees and outside processing expenses decreased due to lower project spend for merger-related activities, partially offset by enterprise technology investments.
Merger-Related and Restructuring Charges
The following table presents a summary of merger-related and restructuring charges and the related accruals. The 2023 merger-related and restructuring costs primarily reflect charges as a result of the restructuring activities, including costs for severance and other benefits, costs related to exiting facilities, and other restructuring initiatives.
| Table 4: Merger-Related and Restructuring Accrual Activity | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | Accrual at Jan 1, 2023 | Expense | Utilized | Accrual at Mar 31, 2023 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Severance and personnel-related | $ | 9 | $ | 39 | $ | (31) | $ | 17 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Occupancy and equipment | — | 19 | (19) | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Professional services | 12 | 1 | (12) | 1 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 5 | 4 | (5) | 4 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total | $ | 26 | $ | 63 | $ | (67) | $ | 22 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Provision for Income Taxes
The provision for income taxes was $394 million for the first quarter of 2023, compared to $330 million for the earlier quarter. The effective tax rate for the first quarter of 2023 was 20.6%, compared to 18.9% for the earlier quarter.
- The effective tax rate increased compared to the first quarter of 2022 primarily driven by higher income before taxes, discrete tax expense recognized in the current quarter compared to discrete tax benefits recognized in the prior quarter, and the adoption of the Investments in Tax Credit Structures accounting standard related to the proportional amortization of tax credit investments in the current quarter. This guidance resulted in an increase in other income and an increase in tax expense of $17 million for the first quarter of 2023 with no impact to net income. The guidance was adopted prospectively and had no impact on prior periods results. Refer to “Note 1. Basis of Presentation” for additional information on the adoption of this guidance.
Truist Financial Corporation 45
Segment Results
Truist operates and measures business activity across three segments: Consumer Banking and Wealth, Corporate and Commercial Banking, and Insurance Holdings, with functional activities included in Other, Treasury, and Corporate. The Company’s business segment structure is based on the manner in which financial information is evaluated by management as well as the products and services provided or the type of client served. During the first quarter of 2023, Truist reorganized Prime Rate Premium Finance Corporation, which includes AFCO Credit Corporation and CAFO Holding Company, into the C&CB segment from the IH segment. Prior period results have been revised to conform to the current presentation.
See “Note 18. Operating Segments” herein and “Note 21. Operating Segments” in Truist’s Annual Report on Form 10-K for the year ended December 31, 2022 for additional disclosures related to Truist’s reportable business segments, including additional details related to results of operations. Fluctuations in noninterest income and noninterest expense are more fully discussed in the Noninterest Income and Noninterest Expense sections above.
| Table 5: Net Income by Reportable Segment | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | 2023 | 2022 | % Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Consumer Banking and Wealth | $ | 1,044 | $ | 861 | 21.3 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Corporate and Commercial Banking | 1,034 | 1,023 | 1.1 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Insurance Holdings | 111 | 143 | (22.4) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other, Treasury & Corporate | (674) | (611) | (10.3) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Truist Financial Corporation | $ | 1,515 | $ | 1,416 | 7.0 |
Consumer Banking and Wealth
CB&W net income was $1.0 billion for the first quarter of 2023, an increase of $183 million compared to the first quarter of 2022.
-
Segment net interest income increased $556 million primarily driven by favorable funding credit on deposits attributable to the higher rate environment and higher average loan balances, partially offset by higher funding costs, lower average deposits, and lower purchase accounting accretion.
-
The provision for credit losses increased $200 million reflecting increased economic uncertainty in the current quarter as well as higher charge offs in the indirect auto and other consumer portfolios and a reserve release in the earlier quarter.
-
Noninterest income decreased $37 million compared to earlier quarter primarily due to a gain on the redemption of noncontrolling equity interest in the earlier quarter, partially offset by higher mortgage banking income in the current quarter.
-
Noninterest expense increased $84 million compared to the earlier quarter primarily driven primarily by higher corporate technology, risk, and operations support expenses along with increased salaries expense, partially offset by lower marketing and customer development and incentives expense.
CB&W average loans and leases held for investment increased $11.2 billion, or 8.5%, for the first quarter of 2023 compared to the first quarter of 2022, primarily driven by an increase in residential mortgage balances due to slower run-off and increased correspondent production, along with increased Service Finance and Dealer Finance loans, partially offset by lower Student and Partnership loans.
Average total deposits decreased $14.4 billion, or 5.7%, for the first quarter of 2023 compared to the first quarter of 2022, primarily driven by decreases in interest bearing checking, money market and savings, and noninterest bearing deposits.
Corporate and Commercial Banking
C&CB net income was $1.0 billion for the first quarter of 2023, an increase of $11 million compared to the first quarter of 2022.
-
Segment net interest income increased $463 million primarily due to higher funding credit on deposits and higher average loan balances, partially offset by lower purchase accounting accretion and lower PPP revenue.
-
The provision for credit losses increased $382 million which reflects an increase in reserves driven by increased economic uncertainty and loan growth in the current quarter as well as an allowance release in the earlier quarter.
-
Noninterest income decreased $26 million compared to the earlier quarter primarily due to lower investment income from the Company’s SBIC and other investments, lower structured real estate fees, and commercial mortgage income, partially offset by increases in lending related fees, core trading revenues, and merger and acquisition fees.
-
Noninterest expense increased $55 million compared to the earlier quarter primarily due to higher personnel expenses, and merger-related and restructuring charges.
46 Truist Financial Corporation
C&CB average loans held for investment increased $26.7 billion, or 17%, for the first quarter of 2023 compared to the first quarter of 2022, primarily due to increases in commercial and industrial loans, partially offset by decreases in average PPP loans (commercial and industrial) and average commercial real estate.
Average total deposits decreased $11.4 billion, or 7.5%, for the first quarter of 2023 compared to the first quarter of 2022, primarily due to declines in average noninterest bearing deposits, partially offset by increases in money market and savings.
Insurance Holdings
IH net income was $111 million for the first quarter of 2023, a decrease of $32 million compared to the first quarter of 2022.
-
Segment net interest income increased $11 million driven primarily by favorable funding credits.
-
Noninterest income increased $84 million primarily due to continued organic growth and acquisitions.
-
Noninterest expense increased $138 million primarily due to the impact of acquisitions, investments in new hires and teammates, performance-driven incentive expense, and higher operational loss reserves.
Other, Treasury & Corporate
OT&C generated a net loss of $674 million in the first quarter of 2023, compared to a net loss of $611 million in the first quarter of 2022.
-
Net interest income decreased $345 million primarily due to higher funding credit on deposits to other segments, partially offset by higher funding charges to other segments from the higher rate environment.
-
The provision for credit losses increased $15 million due to increased economic uncertainty in the current quarter.
-
Noninterest income increased $71 million primarily due to losses on the sale of securities in the earlier quarter.
-
Noninterest expense decreased $260 million compared to the earlier quarter primarily due to a decrease in incremental operating expenses related to the merger, partially offset by an increase in professional fees and outside processing, salaries, and regulatory costs.
Truist Financial Corporation 47
Analysis of Financial Condition
Investment Activities
The securities portfolio totaled $128.8 billion at March 31, 2023, compared to $129.5 billion at December 31, 2022. U.S. Treasury, GSE, and Agency MBS represents 97% of the total securities portfolio as of March 31, 2023 and December 31, 2022. While the overwhelming majority of the portfolio remains in agency MBS securities, the Company also holds AAA rated non-agency MBS as the risk adjusted returns for these securities are more attractive than agency MBS.
-
The decrease includes paydowns and maturities of $2.1 billion, partially offset by unrealized gains of $1.1 billion during the quarter.
-
As of March 31, 2023, 41% of the investment securities portfolio was classified as held-to-maturity based on amortized cost.
-
As of March 31, 2023 and December 31, 2022, approximately 5.6% of the securities portfolio was variable rate, excluding the impact of swaps.
-
The effective duration of the securities portfolio was 6.7 years at March 31, 2023 and December 31, 2022.
Lending Activities
The following table presents the composition of average loans and leases:
| Table 6: Average Loans and Leases | ||||||||||||||||||||||||||||||||
| For the Three Months Ended (Dollars in millions) | Mar 31, 2023 | Dec 31, 2022 | Sep 30, 2022 | Jun 30, 2022 | Mar 31, 2022 | |||||||||||||||||||||||||||
| Commercial: | ||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 165,095 | $ | 159,308 | $ | 152,123 | $ | 145,558 | $ | 138,872 | ||||||||||||||||||||||
| CRE | 22,689 | 22,497 | 22,245 | 22,508 | 23,555 | |||||||||||||||||||||||||||
| Commercial construction | 5,863 | 5,711 | 5,284 | 5,256 | 5,046 | |||||||||||||||||||||||||||
| Consumer: | ||||||||||||||||||||||||||||||||
| Residential mortgage | 56,422 | 56,292 | 53,271 | 49,237 | 47,976 | |||||||||||||||||||||||||||
| Home equity | 10,735 | 10,887 | 10,767 | 10,677 | 10,822 | |||||||||||||||||||||||||||
| Indirect auto | 27,743 | 28,117 | 28,057 | 26,496 | 26,088 | |||||||||||||||||||||||||||
| Other consumer | 27,559 | 27,479 | 26,927 | 25,918 | 24,921 | |||||||||||||||||||||||||||
| Student | 5,129 | 5,533 | 5,958 | 6,331 | 6,648 | |||||||||||||||||||||||||||
| Credit card | 4,785 | 4,842 | 4,755 | 4,728 | 4,682 | |||||||||||||||||||||||||||
| Total average loans and leases HFI | $ | 326,020 | $ | 320,666 | $ | 309,387 | $ | 296,709 | $ | 288,610 |
Average loans increased $5.4 billion, or 1.7%, compared to the prior quarter primarily due to momentum from the prior quarter within the commercial portfolio and the impact of the BankDirect acquisition. Loan growth moderated during the quarter as production in lower return portfolios was reduced with end of period loans up 0.5% compared to December 31, 2022.
-
Average commercial loans increased 3.3% due to broad-based growth within the commercial and industrial portfolio and the BankDirect acquisition. The BankDirect acquisition contributed approximately $900 million of average loan growth compared to the fourth quarter of 2022.
-
Average consumer loans decreased 0.6% due to runoff in student loans and partnership lending, as well as lower indirect auto production.
At March 31, 2023 and December 31, 2022, 53% of loans and leases HFI were variable rate.
48 Truist Financial Corporation
Asset Quality
The following tables summarize asset quality information:
| Table 7: Asset Quality | |||||||||||||||||||||||||||||||||||
| (Dollars in millions) | Mar 31, 2023 | Dec 31, 2022 | Sep 30, 2022 | Jun 30, 2022 | Mar 31, 2022 | ||||||||||||||||||||||||||||||
| NPAs: | |||||||||||||||||||||||||||||||||||
| NPLs: | |||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 394 | $ | 398 | $ | 443 | $ | 393 | $ | 330 | |||||||||||||||||||||||||
| CRE | 117 | 82 | 5 | 19 | 27 | ||||||||||||||||||||||||||||||
| Commercial construction | 1 | — | — | — | — | ||||||||||||||||||||||||||||||
| Residential mortgage | 233 | 240 | 227 | 269 | 315 | ||||||||||||||||||||||||||||||
| Home equity | 132 | 135 | 132 | 133 | 122 | ||||||||||||||||||||||||||||||
| Indirect auto | 270 | 289 | 260 | 244 | 227 | ||||||||||||||||||||||||||||||
| Other consumer | 45 | 44 | 39 | 32 | 23 | ||||||||||||||||||||||||||||||
| Total NPLs HFI | 1,192 | 1,188 | 1,106 | 1,090 | 1,044 | ||||||||||||||||||||||||||||||
| Loans held for sale | — | — | 72 | 33 | 39 | ||||||||||||||||||||||||||||||
| Total nonaccrual loans and leases | 1,192 | 1,188 | 1,178 | 1,123 | 1,083 | ||||||||||||||||||||||||||||||
| Foreclosed real estate | 3 | 4 | 4 | 3 | 3 | ||||||||||||||||||||||||||||||
| Other foreclosed property | 66 | 58 | 58 | 47 | 49 | ||||||||||||||||||||||||||||||
| Total nonperforming assets | $ | 1,261 | $ | 1,250 | $ | 1,240 | $ | 1,173 | $ | 1,135 | |||||||||||||||||||||||||
| Loans 90 days or more past due and still accruing: | |||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 35 | $ | 49 | $ | 44 | $ | 27 | $ | 22 | |||||||||||||||||||||||||
| CRE | — | 1 | 1 | 3 | — | ||||||||||||||||||||||||||||||
| Commercial construction | — | — | — | 3 | — | ||||||||||||||||||||||||||||||
| Residential mortgage - government guaranteed | 649 | 759 | 808 | 884 | 996 | ||||||||||||||||||||||||||||||
| Residential mortgage - nonguaranteed | 25 | 27 | 26 | 27 | 31 | ||||||||||||||||||||||||||||||
| Home equity | 10 | 12 | 9 | 8 | 9 | ||||||||||||||||||||||||||||||
| Indirect auto | — | 1 | 1 | 1 | 1 | ||||||||||||||||||||||||||||||
| Other consumer | 10 | 13 | 9 | 5 | 5 | ||||||||||||||||||||||||||||||
| Student - government guaranteed | 590 | 702 | 770 | 796 | 818 | ||||||||||||||||||||||||||||||
| Student - nonguaranteed | 4 | 4 | 5 | 5 | 4 | ||||||||||||||||||||||||||||||
| Credit card | 38 | 37 | 36 | 28 | 28 | ||||||||||||||||||||||||||||||
| Total loans 90 days or more past due and still accruing | $ | 1,361 | $ | 1,605 | $ | 1,709 | $ | 1,787 | $ | 1,914 | |||||||||||||||||||||||||
| Loans 30-89 days past due and still accruing: | |||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 125 | $ | 256 | $ | 162 | $ | 223 | $ | 280 | |||||||||||||||||||||||||
| CRE | 34 | 25 | 15 | 10 | 13 | ||||||||||||||||||||||||||||||
| Commercial construction | 3 | 5 | 3 | 4 | 1 | ||||||||||||||||||||||||||||||
| Residential mortgage - government guaranteed | 232 | 268 | 234 | 233 | 216 | ||||||||||||||||||||||||||||||
| Residential mortgage - nonguaranteed | 259 | 346 | 300 | 302 | 326 | ||||||||||||||||||||||||||||||
| Home equity | 65 | 68 | 67 | 68 | 80 | ||||||||||||||||||||||||||||||
| Indirect auto | 511 | 646 | 591 | 584 | 529 | ||||||||||||||||||||||||||||||
| Other consumer | 164 | 187 | 152 | 166 | 127 | ||||||||||||||||||||||||||||||
| Student - government guaranteed | 350 | 396 | 375 | 447 | 476 | ||||||||||||||||||||||||||||||
| Student - nonguaranteed | 6 | 6 | 6 | 6 | 6 | ||||||||||||||||||||||||||||||
| Credit card | 56 | 64 | 52 | 48 | 47 | ||||||||||||||||||||||||||||||
| Total loans 30-89 days past due and still accruing | $ | 1,805 | $ | 2,267 | $ | 1,957 | $ | 2,091 | $ | 2,101 |
Nonperforming assets totaled $1.3 billion at March 31, 2023, relatively stable compared to December 31, 2022. Nonperforming loans and leases held for investment were 0.36% of loans and leases held for investment at March 31, 2023, unchanged compared to December 31, 2022.
Loans 90 days or more past due and still accruing totaled $1.4 billion at March 31, 2023, down $244 million, or seven basis points as a percentage of loans and leases, compared with the prior quarter primarily due to declines in government guaranteed student loans and government guaranteed residential mortgages. Excluding government guaranteed loans, the ratio of loans 90 days or more past due and still accruing as a percentage of loans and leases was 0.04% at March 31, 2023, flat from December 31, 2022.
Loans 30-89 days past due and still accruing of $1.8 billion at March 31, 2023 were down $462 million, or 15 basis points as a percentage of loans and leases, compared to the prior quarter primarily due to a seasonal decrease in the consumer portfolios coupled with a decline in the commercial and industrial portfolio.
Truist Financial Corporation 49
Problem loans include NPLs and loans that are 90 days or more past due and still accruing as disclosed in Table 7. In addition, for the commercial portfolio segment, loans that are rated special mention or substandard performing are closely monitored by management as potential problem loans. Refer to “Note 5. Loans and ACL” for the amortized cost basis of loans by origination year and credit quality indicator as well as additional disclosures related to NPLs.
| Table 8: Asset Quality Ratios | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mar 31, 2023 | Dec 31, 2022 | Sep 30, 2022 | Jun 30, 2022 | Mar 31, 2022 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans 30-89 days past due and still accruing as a percentage of loans and leases HFI | 0.55 | % | 0.70 | % | 0.62 | % | 0.69 | % | 0.72 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Loans 90 days or more past due and still accruing as a percentage of loans and leases HFI | 0.42 | 0.49 | 0.54 | 0.59 | 0.66 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| NPLs as a percentage of loans and leases HFI | 0.36 | 0.36 | 0.35 | 0.36 | 0.36 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| NPLs as a percentage of total loans and leases(1) | 0.36 | 0.36 | 0.37 | 0.37 | 0.37 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| NPAs as a percentage of: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets(1) | 0.22 | 0.23 | 0.23 | 0.22 | 0.21 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans and leases HFI plus foreclosed property | 0.38 | 0.38 | 0.37 | 0.38 | 0.38 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| ALLL as a percentage of loans and leases HFI | 1.37 | 1.34 | 1.34 | 1.38 | 1.44 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Ratio of ALLL to NPLs | 3.8x | 3.7x | 3.8x | 3.8x | 4.0x | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans 90 days or more past due and still accruing as a percentage of loans and leases HFI, excluding government guaranteed(2) | 0.04 | % | 0.04 | % | 0.04 | % | 0.04 | % | 0.04 | % | ||||||||||||||||||||||||||||||||||||||||||||||
(1)Includes LHFS.
(2)This asset quality ratio has been adjusted to remove the impact of government guaranteed loans. Management believes the inclusion of such assets in this asset quality ratio results in distortion of this ratio because collection of principal and interest is reasonably assured, or the ratio might not be comparable to other periods presented or to other portfolios that do not have government guarantees.
| Table 9: Asset Quality Ratios (Continued) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mar 31, 2023 | Dec 31, 2022 | Sep 30, 2022 | Jun 30, 2022 | Mar 31, 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net charge-offs as a percentage of average loans and leases HFI: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 0.15 | % | 0.08 | % | 0.02 | % | 0.01 | % | 0.04 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| CRE | 0.09 | 0.19 | (0.01) | (0.10) | 0.01 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial construction | (0.04) | (0.06) | (0.10) | (0.08) | (0.02) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Consumer: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | — | (0.02) | 0.01 | (0.02) | (0.03) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | (0.15) | (0.01) | (0.13) | (0.17) | (0.12) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Indirect auto | 1.47 | 1.52 | 1.15 | 0.77 | 1.23 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other consumer | 1.29 | 1.11 | 1.31 | 1.27 | 0.87 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Student | 0.42 | 0.34 | 0.40 | 0.30 | 0.33 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 3.54 | 3.68 | 2.80 | 2.63 | 2.77 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total | 0.37 | 0.34 | 0.27 | 0.22 | 0.25 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Ratio of ALLL to net charge-offs | 3.7x | 4.1x | 5.0x | 6.5x | 5.8x |
Ratios are annualized, as applicable.
The following table presents activity related to NPAs:
| Table 10: Rollforward of NPAs | |||||||||||||||||
| (Dollars in millions) | 2023 | 2022 | |||||||||||||||
| Balance, January 1 | $ | 1,250 | $ | 1,163 | |||||||||||||
| New NPAs | 621 | 395 | |||||||||||||||
| Advances and principal increases | 214 | 108 | |||||||||||||||
| Disposals of foreclosed assets(1) | (147) | (112) | |||||||||||||||
| Disposals of NPLs(2) | (3) | (37) | |||||||||||||||
| Charge-offs and losses | (204) | (115) | |||||||||||||||
| Payments | (306) | (180) | |||||||||||||||
| Transfers to performing status | (160) | (101) | |||||||||||||||
| Other, net | (4) | 14 | |||||||||||||||
| Ending balance, March 31 | $ | 1,261 | $ | 1,135 |
(1)Includes charge-offs and losses recorded upon sale of $42 million and $29 million for the three months ended March 31, 2023 and 2022, respectively.
(2)Includes gains, net of charge-offs recorded upon sale of $5 million and charge-offs and losses recorded upon sale of $3 million for the three months ended March 31, 2023 and 2022, respectively.
50 Truist Financial Corporation
CRE and Commercial Construction
Truist has noted that the CRE and commercial construction portfolios have the potential for heightened risk in the current environment. Truist maintains a high-quality portfolio through disciplined risk management and prudent client selection. In addition, the Company’s exposure to large CRE tends to have more institutional sponsorship and the Company has reduced exposure to smaller CRE. Truist’s CRE and commercial construction portfolios was $28.6 billion as of March 31, 2023.
Our office portfolio, which makes up approximately 18% of total CRE and commercial construction loans, is weighted towards Class A properties as of March 31, 2023. Nonperforming loans and criticized loans in this portfolio have trended higher in recent months.
| Table 11: CRE and Commercial Construction by Type | |||||||||||||||||||||||
| March 31, 2023 | December 31, 2022 | ||||||||||||||||||||||
| (Dollars in millions) | LHFI | NPL | LHFI | NPL | |||||||||||||||||||
| CRE and commercial construction: | |||||||||||||||||||||||
| Multifamily | $ | 8,085 | $ | 2 | $ | 7,762 | $ | — | |||||||||||||||
| Office | 5,151 | 109 | 5,258 | 75 | |||||||||||||||||||
| Retail | 4,582 | 3 | 4,668 | 2 | |||||||||||||||||||
| Industrial | 4,550 | — | 4,329 | — | |||||||||||||||||||
| Hotel | 2,827 | — | 2,965 | — | |||||||||||||||||||
| Other | 3,426 | 4 | 3,543 | 5 | |||||||||||||||||||
| Total | $ | 28,621 | $ | 118 | $ | 28,525 | $ | 82 | |||||||||||||||
See additional information on the CRE and commercial construction portfolios in “Note 5. Loans and ACL,” including loans by origination year and credit quality indicator.
Truist Financial Corporation 51
ACL
Activity related to the ACL is presented in the following tables:
| Table 12: Activity in ACL | ||||||||||||||||||||||||||||||||||||||||||||||||||
| For the Three Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | Mar 31, 2023 | Dec 31, 2022 | Sep 30, 2022 | Jun 30, 2022 | Mar 31, 2022 | |||||||||||||||||||||||||||||||||||||||||||||
| Balance, beginning of period(1) | $ | 4,649 | $ | 4,455 | $ | 4,434 | $ | 4,423 | $ | 4,695 | ||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 482 | 467 | 234 | 171 | (95) | |||||||||||||||||||||||||||||||||||||||||||||
| Charge-offs: | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | (75) | (44) | (51) | (17) | (31) | |||||||||||||||||||||||||||||||||||||||||||||
| CRE | (6) | (11) | — | (1) | (1) | |||||||||||||||||||||||||||||||||||||||||||||
| Commercial construction | — | — | — | — | (1) | |||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | (1) | (1) | (4) | (2) | (2) | |||||||||||||||||||||||||||||||||||||||||||||
| Home equity | (2) | (6) | (3) | (3) | (1) | |||||||||||||||||||||||||||||||||||||||||||||
| Indirect auto | (127) | (129) | (103) | (77) | (102) | |||||||||||||||||||||||||||||||||||||||||||||
| Other consumer | (105) | (96) | (109) | (100) | (76) | |||||||||||||||||||||||||||||||||||||||||||||
| Student | (5) | (5) | (7) | (4) | (6) | |||||||||||||||||||||||||||||||||||||||||||||
| Credit card | (51) | (53) | (42) | (40) | (41) | |||||||||||||||||||||||||||||||||||||||||||||
| Total charge-offs | (372) | (345) | (319) | (244) | (261) | |||||||||||||||||||||||||||||||||||||||||||||
| Recoveries: | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 13 | 14 | 43 | 13 | 17 | |||||||||||||||||||||||||||||||||||||||||||||
| CRE | 1 | 1 | — | 6 | 1 | |||||||||||||||||||||||||||||||||||||||||||||
| Commercial construction | 1 | 1 | 2 | 1 | 1 | |||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | 2 | 3 | 3 | 4 | 6 | |||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 6 | 6 | 8 | 6 | 5 | |||||||||||||||||||||||||||||||||||||||||||||
| Indirect auto | 26 | 21 | 21 | 26 | 23 | |||||||||||||||||||||||||||||||||||||||||||||
| Other consumer | 17 | 17 | 21 | 20 | 21 | |||||||||||||||||||||||||||||||||||||||||||||
| Student | — | 1 | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 9 | 8 | 8 | 9 | 9 | |||||||||||||||||||||||||||||||||||||||||||||
| Total recoveries | 75 | 72 | 106 | 85 | 83 | |||||||||||||||||||||||||||||||||||||||||||||
| Net charge-offs | (297) | (273) | (213) | (159) | (178) | |||||||||||||||||||||||||||||||||||||||||||||
| Other(2) | (73) | — | — | (1) | 1 | |||||||||||||||||||||||||||||||||||||||||||||
| Balance, end of period | $ | 4,761 | $ | 4,649 | $ | 4,455 | $ | 4,434 | $ | 4,423 | ||||||||||||||||||||||||||||||||||||||||
| ACL:(1) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| ALLL | $ | 4,479 | $ | 4,377 | $ | 4,205 | $ | 4,187 | $ | 4,170 | ||||||||||||||||||||||||||||||||||||||||
| RUFC | 282 | 272 | 250 | 247 | 253 | |||||||||||||||||||||||||||||||||||||||||||||
| Total ACL | $ | 4,761 | $ | 4,649 | $ | 4,455 | $ | 4,434 | $ | 4,423 |
(1)Excludes provision for credit losses and allowances related to other financial assets at amortized cost.
(2)The first quarter of 2023 includes the impact from the adoption of the Troubled Debt Restructurings and Vintage Disclosures accounting standard.
The allowance for credit losses was $4.8 billion and includes $4.5 billion for the allowance for loan and lease losses and $282 million for the reserve for unfunded commitments. The ALLL ratio was 1.37%, up three basis points compared with December 31, 2022 primarily due to increased economic uncertainty. The ALLL covered nonperforming loans and leases held for investment 3.8X compared to 3.7X at December 31, 2022. At March 31, 2023, the ALLL was 3.7X annualized net charge-offs, compared to 4.1X at December 31, 2022.
52 Truist Financial Corporation
The following table presents an allocation of the ALLL. The entire amount of the allowance is available to absorb losses occurring in any category of loans and leases.
| Table 13: Allocation of ALLL by Category | |||||||||||||||||||||||||||||||||||
| March 31, 2023 | December 31, 2022 | ||||||||||||||||||||||||||||||||||
| (Dollars in millions) | Amount | % ALLL in Each Category | % Loans in Each Category | Amount | % ALLL in Each Category | % Loans in Each Category | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 1,497 | 33.5 | % | 51.1 | % | $ | 1,409 | 32.3 | % | 50.3 | % | |||||||||||||||||||||||
| CRE | 251 | 5.6 | 6.9 | 224 | 5.1 | 7.0 | |||||||||||||||||||||||||||||
| Commercial construction | 87 | 1.9 | 1.8 | 46 | 1.1 | 1.8 | |||||||||||||||||||||||||||||
| Residential mortgage | 332 | 7.4 | 17.2 | 399 | 9.1 | 17.4 | |||||||||||||||||||||||||||||
| Home equity | 87 | 1.9 | 3.2 | 90 | 2.0 | 3.3 | |||||||||||||||||||||||||||||
| Indirect auto | 993 | 22.2 | 8.3 | 981 | 22.4 | 8.6 | |||||||||||||||||||||||||||||
| Other consumer | 779 | 17.4 | 8.5 | 770 | 17.6 | 8.5 | |||||||||||||||||||||||||||||
| Student | 98 | 2.2 | 1.5 | 98 | 2.2 | 1.6 | |||||||||||||||||||||||||||||
| Credit card | 355 | 7.9 | 1.5 | 360 | 8.2 | 1.5 | |||||||||||||||||||||||||||||
| Total ALLL | 4,479 | 100.0 | % | 100.0 | % | 4,377 | 100.0 | % | 100.0 | % | |||||||||||||||||||||||||
| RUFC | 282 | 272 | |||||||||||||||||||||||||||||||||
| Total ACL | $ | 4,761 | $ | 4,649 |
Truist monitors the performance of its home equity loans and lines secured by second liens similarly to other consumer loans and utilizes assumptions specific to these loans in determining the necessary ALLL. Truist also receives notification when the first lien holder, whether Truist or another financial institution, has initiated foreclosure proceedings against the borrower. When notified that the first lien is in the process of foreclosure, Truist obtains valuations to determine if any additional charge-offs or reserves are warranted. These valuations are updated at least annually thereafter.
Truist has limited ability to monitor the delinquency status of the first lien, unless the first lien is held or serviced by Truist. Truist estimates credit losses on second lien loans where the first lien is delinquent based on historical experience; the increased risk of loss on these credits is reflected in the ALLL. As of March 31, 2023, Truist held or serviced the first lien on 32% of its second lien positions.
Other Assets
The components of other assets are presented in the following table:
| Table 14: Other Assets as of Period End | ||||||||||||||
| (Dollars in millions) | Mar 31, 2023 | Dec 31, 2022 | ||||||||||||
| Bank-owned life insurance | $ | 7,651 | $ | 7,618 | ||||||||||
| Tax credit and other private equity investments | 6,730 | 6,825 | ||||||||||||
| Prepaid pension assets | 5,885 | 4,539 | ||||||||||||
| DTAs | 2,393 | 3,027 | ||||||||||||
| Accounts receivable | 2,763 | 2,682 | ||||||||||||
| Accrued income | 2,429 | 2,265 | ||||||||||||
| Leased assets and related assets | 2,059 | 2,082 | ||||||||||||
| FHLB stock | 2,426 | 1,279 | ||||||||||||
| ROU assets | 1,151 | 1,193 | ||||||||||||
| Prepaid expenses | 1,177 | 1,162 | ||||||||||||
| Equity securities at fair value | 857 | 898 | ||||||||||||
| Derivative assets | 692 | 684 | ||||||||||||
| Other | 792 | 874 | ||||||||||||
| Total other assets | $ | 37,005 | $ | 35,128 | ||||||||||
Truist Financial Corporation 53
Funding Activities
Deposits
The following table presents average deposits:
| Table 15: Average Deposits | ||||||||||||||||||||||||||||||||
| Three Months Ended (Dollars in millions) | Mar 31, 2023 | Dec 31, 2022 | Sep 30, 2022 | Jun 30, 2022 | Mar 31, 2022 | |||||||||||||||||||||||||||
| Noninterest-bearing deposits | $ | 131,099 | $ | 141,032 | $ | 146,041 | $ | 148,610 | $ | 145,933 | ||||||||||||||||||||||
| Interest checking | 108,886 | 110,001 | 111,645 | 112,375 | 112,159 | |||||||||||||||||||||||||||
| Money market and savings | 139,802 | 144,730 | 147,659 | 148,632 | 141,500 | |||||||||||||||||||||||||||
| Time deposits | 28,671 | 17,513 | 14,751 | 14,133 | 15,646 | |||||||||||||||||||||||||||
| Total average deposits | $ | 408,458 | $ | 413,276 | $ | 420,096 | $ | 423,750 | $ | 415,238 |
Average deposits for the first quarter of 2023 were $408.5 billion, a decrease of $4.8 billion, or 1.2%, compared to the prior quarter. The decrease in deposits was primarily driven by the impacts of monetary tightening and higher-rate alternatives.
Average noninterest-bearing deposits decreased 7.0% compared to the prior quarter and represented 32.1% of total deposits for the first quarter of 2023 compared to 34.1% for the fourth quarter of 2022 and 35.1% compared to the year ago quarter. Noninterest-bearing deposits declined primarily due to clients seeking high-rate alternatives. Average money market and savings and interest checking declined 3.4% and 1.0%, respectively, compared to the prior quarter. Average time deposits increased 64% due to an increase in wholesale funding and retail-client time deposits.
Truist has a very granular and relationship-based deposit franchise. Approximately 63% of deposits are insured or collateralized. Truist deposit accounts are typically based on long-term relationships and include multiple products and services. Truist has strong market share in many of the fastest-growing markets in the United States. Truist currently ranks 1st, 2nd, or 3rd in deposit share in 17 of our top 20 markets, including Atlanta, Charlotte, DC, Miami, Tampa, Orlando, and Raleigh-Durham, among others. Truist’s commercial deposits are diversified across 21 industry groups, with no one sector representing more than 10% of Corporate and Commercial Banking deposits.
The estimated amount of deposits that are uninsured was $175.9 billion and $189.6 billion as of March 31, 2023 and December 31, 2022, respectively, calculated using the same methodology as the Call Report for Truist Bank. The decrease in uninsured deposits was largely due to commercial clients that chose to diversify into money market mutual funds or across multiple banks. These outflows were primarily higher-cost, non-operational deposits.
Borrowings
At March 31, 2023, short-term borrowings totaled $23.7 billion, an increase of $256 million compared to December 31, 2022. Average short-term borrowings were $24.1 billion, or 5.0% of total funding, for the three months ended March 31, 2023, as compared to $6.9 billion, or 1.5%, for the same period in the prior year.
Long-term debt provides funding and, to a lesser extent, regulatory capital, and primarily consists of senior and subordinated notes issued by Truist and Truist Bank. Long-term debt totaled $69.9 billion at March 31, 2023, an increase of $26.7 billion compared to December 31, 2022. This funding increase was largely to increase our cash position in response to market events. During the three months ended March 31, 2023, the Company had:
-
Maturities and redemptions of $3.5 billion of senior notes.
-
Issued $1.5 billion fixed-to-floating rate senior notes with an interest rate of 4.87% due January 26, 2029 and $1.5 billion fixed-to-floating rate senior notes with an interest rate of 5.12% due January 26, 2034.
-
Issued $27.0 billion notional, net, of prepayable FHLB floating rate advances with interest rates of 5.05% to 5.07% due April 10, 2024 to March 13, 2025.
The average cost of long-term debt was 4.05% for the three months ended March 31, 2023, up 255 basis points compared to the same period in 2022.
54 Truist Financial Corporation
Shareholders’ Equity
Truist’s book value per common share and TBVPS are presented in the following table:
| Table 16: Book Value per Common Share | ||||||||||||||
| (Dollars in millions, except per share data, shares in thousands) | Mar 31, 2023 | Dec 31, 2022 | ||||||||||||
| Common equity per common share | $ | 41.82 | $ | 40.58 | ||||||||||
| Non-GAAP capital measure:(1) | ||||||||||||||
| Tangible common equity per common share | $ | 19.45 | $ | 18.04 | ||||||||||
| Calculation of tangible common equity:(1) | ||||||||||||||
| Total shareholders’ equity | $ | 62,394 | $ | 60,537 | ||||||||||
| Less: | ||||||||||||||
| Preferred stock | 6,673 | 6,673 | ||||||||||||
| Noncontrolling interests | 22 | 23 | ||||||||||||
| Goodwill and intangible assets, net of deferred taxes | 29,788 | 29,908 | ||||||||||||
| Tangible common equity | $ | 25,911 | $ | 23,933 | ||||||||||
| Common shares outstanding at end of period | 1,331,918 | 1,326,829 | ||||||||||||
(1)Tangible common equity and related measures are non-GAAP measures that exclude the impact of intangible assets, net of deferred taxes, and their related amortization. These measures are useful for evaluating the performance of a business consistently, whether acquired or developed internally. Truist’s management uses these measures to assess profitability, returns relative to balance sheet risk, and shareholder value.
Total shareholders’ equity was $62.4 billion at March 31, 2023, an increase of $1.9 billion from December 31, 2022. This increase includes $1.5 billion in net income and a $1.0 billion increase in AOCI, partially offset by $794 million in common and preferred dividends. Truist’s book value per common share at March 31, 2023 was $41.82, compared to $40.58 at December 31, 2022. Truist TBVPS of $19.45 at March 31, 2023, increased 7.8% compared to December 31, 2022 due to increases in AOCI, primarily related to AFS securities, and retained earnings.
Risk Management
Truist maintains a comprehensive risk management framework supported by people, processes, and systems to identify, measure, monitor, manage, and report significant risks arising from its exposures and business activities. Effective risk management involves optimizing risk and return while operating in a safe and sound manner, and promoting compliance with applicable laws and regulations. The Company’s risk management framework promotes the execution of business strategies and objectives in alignment with its risk appetite.
Truist has developed and employs a risk framework that further guides business functions in identifying, measuring, responding to, monitoring, and reporting on possible exposures to the organization. The risk taxonomy drives internal risk measurement and monitoring and enables Truist to clearly and transparently communicate to stakeholders the level of potential risk the Company faces and the Company’s position on managing risk to acceptable levels.
Truist is committed to fostering a culture that supports identification and escalation of risks across the organization. All teammates are responsible for upholding the Company’s purpose, mission, and values, and are encouraged to speak up if there is any activity or behavior that is inconsistent with the Company’s culture. The Truist code of ethics guides the Company’s decision making and informs teammates on how to act in the absence of specific guidance.
Truist seeks an appropriate return for the risk taken in its business operations. Risk-taking activities are evaluated and prioritized to identify those that present attractive risk-adjusted returns, while preserving asset value and capital.
Truist’s compensation plans are designed to consider teammate’s adherence to and successful implementation of Truist’s risk values and associated policies and procedures. The Company’s compensation structure supports its core values and sound risk management practices in an effort to promote judicious risk-taking behavior.
Refer to Truist’s Annual Report on Form 10-K for the year ended December 31, 2022 for additional disclosures under the section titled “Risk Management.”
Market Risk
Market risk is the risk to current or anticipated earnings, capital, or economic value arising from changes in the market value of portfolios, securities, or other financial instruments. Market risk results from changes in the level, volatility, or correlations among financial market risk factors or prices, including interest rates, credit spreads, foreign exchange rates, equity, and commodity prices.
Truist Financial Corporation 55
Effective management of market risk is essential to achieving Truist’s strategic financial objectives. Truist’s most significant market risk exposure is to interest rate risk in its balance sheet; however, market risk also results from underlying product liquidity risk, price risk, and volatility risk in Truist’s business units. Interest rate risk results from differences between the timing of rate changes and the timing of cash flows associated with assets and liabilities (re-pricing risk); from changing rate relationships among different yield curves affecting bank activities (basis risk); from changing rate relationships across the spectrum of maturities (yield curve risk); and from interest-related options inherently embedded in bank products (options risk).
The primary objectives of effective market risk management are to minimize adverse effects from changes in market risk factors on net interest income, net income, and capital, and to offset the risk of price changes for certain assets and liabilities recorded at fair value. At Truist, market risk management also includes the enterprise-wide IPV function.
Interest Rate Market Risk
As a financial institution, Truist is exposed to interest rate risk from assets, liabilities, and off-balance sheet positions. To keep net interest margin as stable as possible, Truist actively manages its interest rate risk exposure through the strategic repricing of its assets and liabilities, taking into account the volumes, maturities, and mix. Truist primarily uses three methods to measure and monitor its interest rate risk: (i) simulations of possible changes to net interest income over the next two years based on gradual changes in interest rates; (ii) analysis of interest rate shock scenarios; and (iii) analysis of economic value of equity based on changes in interest rates.
The Company’s simulation model takes into account assumptions related to prepayment trends, using a combination of market data and internal historical experiences for deposits and loans, as well as scheduled maturities and payments, and the expected outlook for the economy and interest rates. These assumptions are reviewed and adjusted monthly to reflect changes in current interest rates compared to the rates applicable to Truist’s assets and liabilities. The model also considers Truist’s current and prospective liquidity position, current balance sheet volumes, projected growth and/or contractions, accessibility of funds for short-term needs and capital maintenance.
Deposit betas (the sensitivity of deposit rate changes relative to market rate changes) are an important assumption in the interest rate risk modeling process. Truist applies deposit beta assumptions to non-maturity interest-bearing deposit accounts when determining its interest rate sensitivity. Non-maturity, interest-bearing deposit accounts include interest checking accounts, savings accounts, and money market accounts that do not have a contractual maturity. Truist applies an average deposit beta of approximately 50% to its non-maturity interest-bearing accounts when determining its interest rate sensitivity. Truist also regularly conducts sensitivity analyses on other key variables, including noninterest-bearing deposits, to determine the impact these variables could have on the Company’s interest rate risk position. The predictive value of the simulation model depends upon the accuracy of the assumptions, but management believes that it provides helpful information for the management of interest rate risk.
The following table shows the effect that the indicated changes in interest rates would have on net interest income as projected for the next 12 months assuming a gradual change in interest rates as described below.
| Table 17: Interest Sensitivity Simulation Analysis | ||||||||||||||||||||||||||
| Interest Rate Scenario | Annualized Hypothetical Percentage Change in Net Interest Income | |||||||||||||||||||||||||
| Gradual Change in Prime Rate (bps) | Prime Rate | |||||||||||||||||||||||||
| Mar 31, 2023 | Mar 31, 2022 | Mar 31, 2023 | Mar 31, 2022 | |||||||||||||||||||||||
| Up 100 | 9.00 | % | 4.50 | % | (0.29) | % | 4.27 | % | ||||||||||||||||||
| Up 50 | 8.50 | 4.00 | (0.11) | 3.29 | ||||||||||||||||||||||
| No Change | 8.00 | 3.50 | — | — | ||||||||||||||||||||||
| Down 50(1) | 7.50 | 3.00 | (0.58) | (3.46) | ||||||||||||||||||||||
| Down 100(1) | 7.00 | 2.50 | (0.70) | (3.64) |
(1)The Down 50 and 100 rate scenarios incorporate a floor of one basis point.
Rate sensitivity decreased compared to prior periods, primarily driven by higher starting rates, higher deposit betas as rates increase and move into the highest beta tiers, and the addition of forward starting swaps.
Management considers how the interest rate risk position could be impacted by changes in balance sheet mix. Liquidity in the banking industry was very strong post-COVID-19, which resulted in growth in noninterest-bearing demand deposits. However, with the significant increase in rates in 2022 and the first quarter of 2023, noninterest-bearing deposits have begun to shift to interest-bearing accounts. Additional movement above what is currently projected would reduce the asset sensitivity of Truist’s balance sheet because the Company may increase interest-bearing funds to offset the loss of these advantageous noninterest-bearing deposits. Alternatively, the Company may reduce the size of its investment portfolio to offset the loss of noninterest-bearing demand deposits to limit the impact on the balance sheet’s asset sensitivity. The behavior of these noninterest-bearing deposits is one of the most important assumptions used in determining the interest rate risk position of Truist.
56 Truist Financial Corporation
The following table shows the results of Truist’s interest-rate sensitivity position assuming the loss of additional demand deposits and an associated increase in managed rate deposits versus current projections under various interest rate scenarios. For purposes of this analysis, Truist modeled the incremental beta of managed rate deposits for the replacement of the demand deposits at 100%.
| Table 18: Deposit Mix Sensitivity Analysis | ||||||||||||||||||||
| Gradual Change in Rates (bps) | Base Scenario at March 31, 2023**(1)** | Results Assuming a Decrease in Noninterest-Bearing Demand Deposits | ||||||||||||||||||
| $20 Billion | $40 Billion | |||||||||||||||||||
| Up 100 | (0.29) | % | (1.01) | % | (1.72) | % | ||||||||||||||
| Up 50 | (0.11) | (0.63) | (1.15) |
(1)The base scenario is equal to the annualized hypothetical percentage change in net interest income at March 31, 2023 as presented in the preceding table.
Truist uses financial instruments including derivatives to manage interest rate risk related to securities, commercial loans, MSRs, and mortgage banking operations, long-term debt, and other funding sources. Truist has utilized derivatives to facilitate transactions on behalf of its clients and as part of associated hedging activities. As of March 31, 2023, Truist had derivative financial instruments outstanding with notional amounts totaling $363.0 billion. See “Note 16. Derivative Financial Instruments” for additional disclosures.
LIBOR Transition
For most tenors of U.S. dollar LIBOR, the administrator of LIBOR extended publication until June 30, 2023. To prepare for the transition to an alternative reference rate, management formed a cross-functional project team to address the LIBOR transition. The project team performed an assessment to identify the potential risks related to the transition from LIBOR to a new index or multiple indices and provides updates to Executive Leadership and the Board. As of March 31, 2023, Truist had outstanding LIBOR-based instruments that mature after June 30, 2023, including loan and lease exposures totaling approximately $98 billion, notional derivative exposure totaling approximately $131 billion, long-term debt of $1.1 billion, and preferred stock of $1.5 billion. These amounts are inclusive of remediated contracts, which contain adequate fallback language for the transition.
Contract fallback language for existing loans and leases has been reviewed and certain contracts require amendments to support the transition away from LIBOR. Impacted lines of business have started remediating these contracts to include standardized fallback language or amending contracts to new reference rates at maturities or based on client request. Current fallback language used to remediate contracts that mature after June 30, 2023 is generally consistent with ARRC recommendations and includes use of “hardwired fallback” language, which will transition loans to a SOFR based rate after June 30, 2023.
The progress and approach to remediation varies based on the type of contract and existing language used in the agreement. For commercial lending, a significant number of remaining LIBOR contracts required client outreach and remediation. Through mid-2022, the Company’s primary focus was supporting new loan production using SOFR and other alternative reference rates as well as transitioning any renewing LIBOR based contracts to alternative reference rates. Efforts have shifted to amend and remediate contracts, excluding mortgage and student loans, that mature post June 30, 2023 ($90 billion), which will continue to be the focus during 2023. Of the contracts remaining on LIBOR that have not yet been remediated or modified to a new reference rate, Truist’s intends to add updated fallback language or move these contracts to new reference rates prior to cessation. A significant portion of these contracts contain existing fallback language that will transition the contract to a Prime based rate if not remediated, while a smaller population contains no historical fallback language. Should the institution be unable to remediate all contracts, those based on Prime will be prioritized to provide a more consistent client experience with the “hardwired fallback” transition to SOFR. If there are remaining contracts without fallback language, Truist may leverage the LIBOR Act and corresponding safe harbor provision to transition these loans to SOFR.
Truist’s adjustable-rate mortgage products ($3.4 billion) have consistent and adequate fallback language to transition away from LIBOR in line with industry expectations; therefore, these contracts do not require remediation. Remediation of student loans ($4.4 billion) will follow recent guidance from the Department of Education on the replacement rate for payment allowances on certain student loans and recent guidance from the CFPB to allow transition to “comparable rates,” in the private student loan portfolio, where LIBOR is used directly. Based on the recent guidance, these portfolios will transition to rates based on SOFR.
Upon the discontinuation of LIBOR, derivatives that reference LIBOR will transition to a SOFR-based replacement rate as set forth in the ISDA protocol addressing LIBOR fallbacks through bilateral amendments, or as established under the LIBOR Act and rules promulgated thereunder by the FRB. Certain derivatives without a clearly defined or practicable replacement benchmark rate will use the LIBOR Act to replace LIBOR with a SOFR-based rate established by FRB rulemaking and follow the ISDA protocol for transition. This legislation will also provide additional administrative benefit for a small portion of the commercial and consumer lending portfolios where contracts do not contain fallback language and have not yet been remediated, providing a remediation path to a SOFR based rate.
Truist Financial Corporation 57
In addition, the transition from LIBOR to an alternative reference rate, such as SOFR, for the Company’s preferred stock and the Company’s and Truist Bank’s floating rate notes is dependent on a number of factors, including the fallback language for the applicable series of preferred stock or notes, the application of the LIBOR Act and the rules promulgated thereunder by the FRB, determinations to be made by third-party calculation or paying agents rather than the Company or Truist Bank as to the replacement rates, and the impact of any publication of a synthetic U.S. dollar LIBOR as currently proposed by the Financial Conduct Authority. With the most recent information available on these factors, Truist expects preferred stock issuances to utilize LIBOR to transition to SOFR. See “Note 12. Shareholders’ Equity” for information about preferred stock using LIBOR.
Training has been provided for impacted teammates and will continue during 2023. Truist will continue to provide timely notices and information to impacted clients about the transition during the first half of 2023. Truist continues to manage the impact of these contracts and other financial instruments, systems implications, hedging strategies, and related operational and market risks on established project plans for business and operational readiness to support the transition.
As of December 31, 2021, Truist ceased entering into new contracts with a LIBOR reference rate for all product offerings, except on a limited basis, as permissible. The Company is actively using SOFR as a reference rate and has originated approximately $124 billion of loans, issued $12.4 billion of senior and subordinated notes, including fixed rate notes that convert to SOFR in the future, and has $108 billion in notional derivative exposure using this alternative reference rate as of March 31, 2023. Alternatives, such as SOFR, may react differently from LIBOR in times of economic stress. Truist expects SOFR to be the primary pricing benchmark used across the industry and will continue to offer additional SOFR based products. Market risks associated with the transition to alternative reference rates are dependent on market conditions as loans are transitioned to alternative reference rates during 2022 and early 2023. Additional alternative reference rates, such as Bloomberg Short Term Bank Yield, will be supported based on market demand. For a further discussion of the various risks associated with the potential cessation of LIBOR and the transition to alternative reference rates, refer to the section titled “Item1A. Risk Factors” in the Form 10-K for the year ended December 31, 2022.
Market Risk from Trading Activities
As a financial intermediary, Truist provides its clients access to derivatives, foreign exchange and securities markets, which generate market risks. Trading market risk is managed using a comprehensive risk management approach, which includes measuring risk using VaR, stress testing, and sensitivity analysis. Risk metrics are monitored against a suite of limits on a daily basis at both the trading desk level and at the aggregate portfolio level, which is intended to ensure that exposures are in line with Truist’s risk appetite.
Truist is also subject to risk-based capital guidelines for market risk under the Market Risk Rule.
Covered Trading Positions
Covered positions subject to the Market Risk Rule include trading assets and liabilities, specifically those held for the purpose of short-term resale or with the intent of benefiting from actual or expected short-term price movements or to lock in arbitrage profits. Truist’s trading portfolio of covered positions results primarily from market making and underwriting services for the Company’s clients, as well as associated risk mitigating hedging activity. The trading portfolio, measured in terms of VaR, consists primarily of four sub-portfolios of covered positions: (i) credit trading, (ii) fixed income securities, (iii) interest rate derivatives, and (iv) equity derivatives. As a market maker across different asset classes, Truist’s trading portfolio also contains other sub-portfolios, including foreign exchange, loan trading, and commodity derivatives; however, these portfolios do not generate material trading risk exposures.
Valuation policies and methodologies exist for all trading positions. Additionally, these positions are subject to independent price verification. See “Note 16. Derivative Financial Instruments,” “Note 15. Fair Value Disclosures,” and “Critical Accounting Policies” herein for discussion of valuation policies and methodologies.
Securitizations
As of March 31, 2023, the aggregate market value of on-balance sheet securitization positions subject to the Market Risk Rule was $18 million, all of which were non-agency asset backed securities positions. Consistent with the Market Risk Rule requirements, the Company performs pre-purchase due diligence on each securitization position to identify the characteristics including, but not limited to, deal structure and the asset quality of the underlying assets, that materially affect valuation and performance. Securitization positions are subject to Truist’s comprehensive risk management framework, which includes daily monitoring against a suite of limits. There were no off-balance sheet securitization positions during the reporting period.
Correlation Trading Positions
The trading portfolio of covered positions did not contain any correlation trading positions as of March 31, 2023.
58 Truist Financial Corporation
VaR-Based Measures
VaR measures the potential loss of a given position or portfolio of positions at a specified confidence level and time horizon. Truist utilizes a historical VaR methodology to measure and aggregate risks across its covered trading positions. For risk management purposes, the VaR calculation is based on a historical simulation approach and measures the potential trading losses using a one-day holding period at a one-tail, 99% confidence level. For Market Risk Rule purposes, the Company calculates VaR using a 10-day holding period and a 99% confidence level. Due to inherent limitations of the VaR methodology, such as the assumption that past market behavior is indicative of future market performance, VaR is only one of several tools used to measure and manage market risk. Other tools used to actively manage market risk include stress testing, scenario analysis, and stop loss limits.
The trading portfolio’s VaR profile is influenced by a variety of factors, including the size and composition of the portfolio, market volatility, and the correlation between different positions. A portfolio of trading positions is typically less risky than the sum of the risk from each of the individual sub-portfolios, because, under normal market conditions, risk within each category partially offsets the exposure to other risk categories. The following table summarizes certain VaR-based measures for the three months ended March 31, 2023 and 2022. Average one and ten-day VaR measures for the year ended March 31, 2023 decreased from the same period of last year, primarily driven by lower market making inventory.
| Table 19: VaR-based Measures | |||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended March 31, | |||||||||||||||||||||||||||||||||||||||||||||||
| 2023 | 2022 | ||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | 10-Day Holding Period | 1-Day Holding Period | 10-Day Holding Period | 1-Day Holding Period | |||||||||||||||||||||||||||||||||||||||||||
| VaR-based Measures: | |||||||||||||||||||||||||||||||||||||||||||||||
| Maximum | $ | 22 | $ | 9 | $ | 38 | $ | 14 | |||||||||||||||||||||||||||||||||||||||
| Average | 15 | 6 | 18 | 6 | |||||||||||||||||||||||||||||||||||||||||||
| Minimum | 10 | 4 | 9 | 3 | |||||||||||||||||||||||||||||||||||||||||||
| Period-end | 22 | 9 | 15 | 4 | |||||||||||||||||||||||||||||||||||||||||||
| VaR by Risk Class: | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest Rate Risk | 8 | 4 | |||||||||||||||||||||||||||||||||||||||||||||
| Credit Spread Risk | 7 | 4 | |||||||||||||||||||||||||||||||||||||||||||||
| Equity Price Risk | 1 | 4 | |||||||||||||||||||||||||||||||||||||||||||||
| Portfolio Diversification | (9) | (8) | |||||||||||||||||||||||||||||||||||||||||||||
| Period-end | 8 | 4 |
Stressed VaR-based measures
Stressed VaR, another component of market risk capital, is calculated using the same internal models as used for the VaR-based measure. Stressed VaR is calculated over a ten-day holding period at a one-tail, 99% confidence level and employs a historical simulation approach based on a continuous twelve-month historical window selected to reflect a period of significant financial stress for the Company’s trading portfolio. The following table summarizes Stressed VaR-based measures:
| Table 20: Stressed VaR-based Measures - 10 Day Holding Period | |||||||||||||||||||||||
| Three Months Ended March 31, | |||||||||||||||||||||||
| (Dollars in millions) | 2023 | 2022 | |||||||||||||||||||||
| Maximum | $ | 77 | $ | 109 | |||||||||||||||||||
| Average | 44 | 76 | |||||||||||||||||||||
| Minimum | 25 | 59 | |||||||||||||||||||||
| Period-end | 31 | 72 |
Compared to the prior year, Stressed VaR measures decreased primarily due to lower market making inventory levels in 2023.
Specific Risk Measures
Specific risk is a measure of idiosyncratic risk that could result from risk factors other than broad market movements (e.g., default or event risks). The Market Risk Rule provides fixed risk weights under a standardized measurement method while also allowing a model-based approach, subject to regulatory approval. Truist utilizes the standardized measurement method to calculate the specific risk component of market risk regulatory capital. As such, incremental risk capital requirements do not apply.
Truist Financial Corporation 59
VaR Model Backtesting
In accordance with the Market Risk Rule, the Company evaluates the accuracy of its VaR model through daily backtesting by comparing aggregate daily trading gains and losses (excluding fees, commissions, reserves, net interest income, and intraday trading) from covered positions with the corresponding daily VaR-based measures generated by the model. As illustrated in the following graph, there were no Company-wide VaR backtesting exceptions during the twelve months ended March 31, 2023. The total number of Company-wide VaR backtesting exceptions over the preceding twelve months is used to determine the multiplication factor for the VaR-based capital requirement under the Market Risk Rule. The capital multiplication factor increases from a minimum of three to a maximum of four, depending on the number of exceptions. All Company-wide VaR backtesting exceptions are thoroughly reviewed in the context of VaR model use and performance. There was no change in the capital multiplication factor over the preceding twelve months.
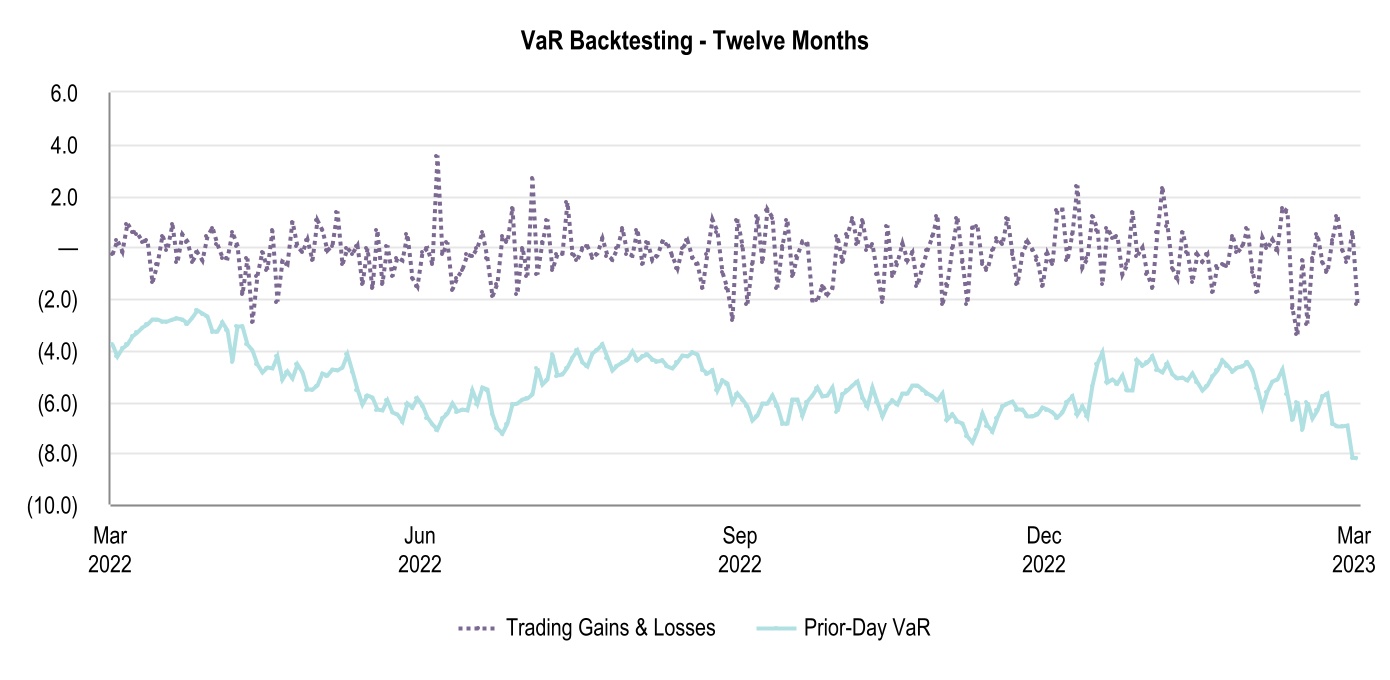
Model Risk Oversight
MRO is responsible for the independent model validation of all decision tools and models including trading market risk models. The validation activities are conducted in accordance with MRO policy, which incorporates regulatory guidance related to the evaluation of model conceptual soundness, ongoing monitoring, and outcomes analysis. As part of ongoing monitoring efforts, the performance of all trading risk models are reviewed regularly to preemptively address emerging developments in financial markets, assess evolving modeling approaches, and identify potential model enhancement.
Stress Testing
The Company uses a comprehensive range of stress testing techniques to help monitor risks across trading desks and to augment standard daily VaR and other risk limits reporting. The stress testing framework is designed to quantify the impact of extreme, but plausible, stress scenarios that could lead to large, unexpected losses. Stress tests include simulations for historical repeats and hypothetical risk factor shocks. All trading positions within each applicable market risk category (interest rate risk, equity risk, foreign exchange rate risk, credit spread risk, and commodity price risk) are included in the Company’s comprehensive stress testing framework. Management reviews stress testing scenarios on an ongoing basis and makes updates, as necessary, which is intended to ensure that both current and emerging risks are captured appropriately. Management also utilizes stress analyses to support the Company’s capital adequacy assessment standards. See the “Capital” section of MD&A for additional discussion of capital adequacy.
Liquidity
Liquidity represents the continuing ability to meet funding needs, including deposit withdrawals, repayment of borrowings and other liabilities, and funding of loan commitments. In addition to the level of liquid assets, such as cash, cash equivalents, and AFS securities, other factors affect the ability to meet liquidity needs, including access to a variety of funding sources, maintaining borrowing capacity, growing core deposits, loan repayment, and the ability to securitize or package loans for sale.
60 Truist Financial Corporation
Truist monitors the ability to meet client demand for funds under both normal and stressed market conditions. In considering its liquidity position, management evaluates Truist’s funding mix based on client core funding, client rate-sensitive funding, and national markets funding. In addition, management evaluates exposure to rate-sensitive funding sources that mature in one year or less. Management also measures liquidity needs against 30 days of stressed cash outflows for Truist and Truist Bank. To ensure a strong liquidity position and compliance with regulatory requirements, management maintains a liquid asset buffer of cash on hand and highly liquid unencumbered securities.
Internal Liquidity Stress Testing
Liquidity stress testing is designed to ensure that Truist and Truist Bank have sufficient liquidity for a variety of institution-specific and market-wide adverse scenarios. Each liquidity stress test scenario applies defined assumptions to execute sources and uses of liquidity over varying planning horizons. The types of expected liquidity uses during a stressed event may include deposit attrition, contractual maturities, reductions in unsecured and secured funding, and increased draws on unfunded commitments. To mitigate liquidity outflows, Truist has identified sources of liquidity; however, access to these sources of liquidity could be affected within a stressed environment.
Truist maintains a liquidity buffer of cash on hand and highly liquid unencumbered securities that is sufficient to meet the projected net stressed cash-flow needs and maintain compliance with regulatory requirements. The liquidity buffer consists of unencumbered highly liquid assets and Truist’s liquidity buffer is substantially the same in composition to what qualifies as HQLA under the LCR Rule.
Contingency Funding Plan
Truist has a contingency funding plan designed to ensure that liquidity sources are sufficient to meet ongoing obligations and commitments, particularly in the event of a liquidity contraction. This plan is designed to examine and quantify the organization’s liquidity under the various internal liquidity stress scenarios and is periodically tested to assess the plan’s reliability. Additionally, the plan provides a framework for management and other teammates to follow in the event of a liquidity contraction or in anticipation of such an event. The plan addresses authority for activation and decision making, liquidity options, and the responsibilities of key departments in the event of a liquidity contraction.
LCR and HQLA
The LCR rule requires that Truist and Truist Bank maintain an amount of eligible HQLA that is sufficient to meet its estimated total net cash outflows over a prospective 30 calendar-day period of stress. Eligible HQLA, for purposes of calculating the LCR, is the amount of unencumbered HQLA that satisfy operational requirements of the LCR rule. Truist and Truist Bank are subject to the Category III reduced LCR requirements. Truist held average weighted eligible HQLA of $87.4 billion and Truist’s average LCR was 113% for the three months ended March 31, 2023.
Effective July 2021, Truist became subject to final rules implementing the NSFR, which are designed to ensure that banking organizations maintain a stable, long-term funding profile in relation to their asset composition and off-balance sheet activities. At March 31, 2023, the Company was compliant with this requirement.
Sources of Funds
Management believes current sources of liquidity are sufficient to meet Truist’s on- and off-balance sheet obligations. Truist funds its balance sheet through diverse sources of funding including client deposits, secured and unsecured capital markets funding, and shareholders’ equity. Truist Bank’s primary source of funding is client deposits. Continued access to client deposits is highly dependent on public confidence in the stability of Truist Bank and its ability to return funds to clients when requested.
Truist Bank maintains a number of diverse funding sources to meet its liquidity requirements. These sources include unsecured borrowings from the capital markets through the issuance of senior or subordinated bank notes, institutional CDs, overnight and term Federal funds markets, and retail brokered CDs. Truist Bank also maintains access to secured borrowing sources including FHLB advances, repurchase agreements, and the FRB discount window. Available investment securities could be pledged to create additional secured borrowing capacity. The following table presents a summary of Truist Bank’s available secured borrowing capacity and eligible cash at the FRB:
| Table 21: Selected Liquidity Sources | |||||||||||
| (Dollars in millions) | Mar 31, 2023 | Dec 31, 2022 | |||||||||
| Unused borrowing capacity: | |||||||||||
| FRB | $ | 53,291 | $ | 49,250 | |||||||
| FHLB | 24,678 | 20,770 | |||||||||
| Available investment securities (after haircuts) | 56,626 | 85,401 | |||||||||
| Available secured borrowing capacity | 134,595 | 155,421 | |||||||||
| Eligible cash at the FRB | 31,544 | 15,556 | |||||||||
| Total | $ | 166,139 | $ | 170,977 |
Truist Financial Corporation 61
At March 31, 2023, Truist Bank’s available secured borrowing capacity represented approximately 3.6 times the amount of wholesale funding maturities in one-year or less. Truist additionally has the ability to increase sources of funding by pledging available investment securities without a haircut on fair value under the FRB Bank Term Funding Program.
Parent Company
The Parent Company serves as the primary source of capital for the operating subsidiaries. The Parent Company’s assets consist primarily of cash on deposit with Truist Bank, equity investments in subsidiaries, advances to subsidiaries, and notes receivable from subsidiaries. The principal obligations of the Parent Company are payments on long-term debt. The main sources of funds for the Parent Company are dividends and management fees from subsidiaries, repayments of advances to subsidiaries, and proceeds from the issuance of equity and long-term debt. The primary uses of funds by the Parent Company are investments in subsidiaries, advances to subsidiaries, dividend payments to common and preferred shareholders, repurchases of common stock, and payments on long-term debt. See “Note 22. Parent Company Financial Information” in Truist’s Annual Report on Form 10-K for the year ended December 31, 2022 for additional information regarding dividends from subsidiaries and debt transactions.
Access to funding at the Parent Company is more sensitive to market disruptions. Therefore, Truist prudently manages cash levels at the Parent Company to cover a minimum of one year of projected cash outflows which includes unfunded external commitments, debt service, common and preferred dividends and scheduled debt maturities, without the benefit of any new cash inflows. Truist maintains a significant buffer above the projected one year of cash outflows. In determining the buffer, Truist considers cash requirements for common and preferred dividends, unfunded commitments to affiliates, serving as a source of strength to Truist Bank, and being able to withstand sustained market disruptions that could limit access to the capital markets. At March 31, 2023 and December 31, 2022, the Parent Company had 45 months and 37 months, respectively, of cash on hand to satisfy projected cash outflows, and 26 months and 22 months, respectively, when including the payment of common stock dividends.
Credit Ratings
Credit ratings are forward-looking opinions of rating agencies as to the Company’s ability to meet its financial commitments and repay its securities and obligations in accordance with their terms of issuance. Credit ratings influence both borrowing costs and access to the capital markets. The Company’s credit ratings are continuously monitored by the rating agencies and are subject to change at any time. As Truist seeks to maintain high-quality credit ratings, management meets with the major rating agencies on a regular basis to provide financial and business updates and to discuss current outlooks and trends. See Item 1A, “Risk Factors” in Truist’s Annual Report on Form 10-K for the year ended December 31, 2022 for additional information regarding factors that influence credit ratings and potential risks that could materialize in the event of downgrade in the Company’s credit ratings: Recent changes in the Company’s credit ratings and outlooks include:
On March 31,2023, S&P Global Ratings affirmed the ratings of Truist and Truist Bank and revised the outlook on those ratings to “stable” from “positive,” citing heightened market volatility in the wake of recent bank failures and, with inflation still elevated, higher uncertainty, and greater downside risk in the economic outlook. The change in outlook was part of a broader action by S&P Global Ratings whereby the “positive” outlook on three other large U.S. banks was revised to “stable.”
Capital
The maintenance of appropriate levels of capital is a management priority and is monitored on a regular basis. Truist’s principal goals related to the maintenance of capital are to provide adequate capital to support Truist’s risk profile consistent with the Board-approved risk appetite, provide financial flexibility to support future growth and client needs, comply with relevant laws, regulations, and supervisory guidance, achieve optimal credit ratings for Truist and its subsidiaries, remain a source of strength for its subsidiaries, and provide a competitive return to shareholders. Risk-based capital ratios, which include CET1 capital, Tier 1 capital, and Total capital are calculated based on regulatory guidance related to the measurement of capital and risk-weighted assets.
62 Truist Financial Corporation
Truist regularly performs stress testing on its capital levels and is required to periodically submit the Company’s capital plans and stress testing results to the banking regulators. Management regularly monitors the capital position of Truist on both a consolidated and bank-level basis. In this regard, management’s objective is to maintain capital at levels that are in excess of internal capital limits, which are above the regulatory “well capitalized” minimums. Management has implemented internal stress capital ratio minimums to evaluate whether capital ratios calculated after the effect of alternative capital actions are likely to remain above internal minimums. Breaches of internal stressed minimums prompt a review of the planned capital actions included in Truist’s capital plan.
| Table 22: Capital Requirements | |||||||||||||||||||||||||||||||||||
| Minimum Capital | Well Capitalized | Minimum Capital Plus Stress Capital Buffer**(1)** | |||||||||||||||||||||||||||||||||
| Truist | Truist Bank | ||||||||||||||||||||||||||||||||||
| CET1 | 4.5 | % | NA | 6.5 | % | 7.0 | % | ||||||||||||||||||||||||||||
| Tier 1 capital | 6.0 | 6.0 | % | 8.0 | 8.5 | ||||||||||||||||||||||||||||||
| Total capital | 8.0 | 10.0 | 10.0 | 10.5 | |||||||||||||||||||||||||||||||
| Leverage ratio | 4.0 | NA | 5.0 | NA | |||||||||||||||||||||||||||||||
| Supplementary leverage ratio | 3.0 | NA | NA | NA | |||||||||||||||||||||||||||||||
(1)Reflects a SCB requirement of 2.5% applicable to Truist as of March 31, 2023. Truist’s SCB requirement, received in the 2022 CCAR process, is effective from October 1, 2022 to September 30, 2023. Truist will receive a new preliminary SCB requirement, to become effective October 1, 2023, following the release of CCAR 2023 results in late June 2023.
Truist’s capital ratios are presented in the following table:
| Table 23: Capital Ratios - Truist Financial Corporation | ||||||||||||||
| (Dollars in millions) | Mar 31, 2023 | Dec 31, 2022 | ||||||||||||
| Risk-based: | (preliminary) | |||||||||||||
| CET1 | 9.1 | % | 9.0 | % | ||||||||||
| Tier 1 capital | 10.6 | 10.5 | ||||||||||||
| Total capital | 12.6 | 12.4 | ||||||||||||
| Leverage ratio | 8.5 | 8.5 | ||||||||||||
| Supplementary leverage ratio | 7.3 | 7.3 | ||||||||||||
| Risk-weighted assets | $ | 436,549 | $ | 434,413 |
Capital ratios remained strong compared to the regulatory requirements for well capitalized banks. Truist declared common dividends of $0.52 per share during the first quarter of 2023. The dividend payout ratio for the first quarter of 2023 was 49%. Truist did not repurchase any shares in the first quarter of 2023 outside of standard activity related to equity compensation plans.
Truist CET1 ratio was 9.1% as of March 31, 2023. The increase since December 31, 2022 represents organic capital generation, partially offset by the CECL phase-in. Truist closed the sale of the minority stake in Truist Insurance Holdings on April 3, 2023, which adds 30 basis points and 24 basis points to the risk-based regulatory capital ratios and leverage ratios, respectively.
Share Repurchase Activity
| Table 24: Share Repurchase Activity | |||||||||||||||||||||||
| (Dollars in millions, except per share data, shares in thousands) | Total Number of Shares Purchased**(1)** | Average Price Paid Per Share**(2)** | Total Number of Shares Purchased as part of Publicly Announced Plans**(3)** | Approximate Dollar Value of Shares that may yet be Purchased Under the Plans**(3)** | |||||||||||||||||||
| January 1, 2023 to January 31, 2023 | — | $ | — | — | $ | 4,100 | |||||||||||||||||
| February 1, 2023 to February 28, 2023 | 2 | 48.84 | — | 4,100 | |||||||||||||||||||
| March 1, 2023 to March 31, 2023 | 31 | 32.10 | — | 4,100 | |||||||||||||||||||
| Total | 33 | $ | 33.09 | — |
(1)Includes shares exchanged or surrendered in connection with the exercise of equity-based awards under equity-based compensation plans.
(2)Excludes commissions.
(3)In July 2022, the Board of Directors approved, effective October 1, 2022, new repurchase authority to effectuate repurchases up to an aggregate of $4.1 billion in shares of the Company’s common stock through September 30, 2023.
Truist Financial Corporation 63
Critical Accounting Policies
The accounting and reporting policies of Truist are in accordance with GAAP and conform to the accounting and reporting guidelines prescribed by bank regulatory authorities. Truist’s financial position and results of operations are affected by management’s application of accounting policies, including estimates, assumptions, and judgments made to arrive at the carrying value of assets and liabilities, and amounts reported for revenues and expenses. Different assumptions in the application of these policies could result in material changes in the consolidated financial position and/or consolidated results of operations, and related disclosures. Material estimates that are particularly susceptible to significant change include the determination of the ACL; determination of fair value for securities, MSRs, LHFS, trading loans, and derivative assets and liabilities; goodwill and other intangible assets; income taxes; and pension and postretirement benefit obligations. Understanding Truist’s accounting policies is fundamental to understanding the consolidated financial position and consolidated results of operations. The critical accounting policies are discussed in MD&A in Truist’s Annual Report on Form 10-K for the year ended December 31, 2022. Significant accounting policies and changes in accounting principles and effects of new accounting pronouncements are discussed in “Note 1. Basis of Presentation” in Form 10-K for the year ended December 31, 2022. Disclosures regarding the effects of new accounting pronouncements are included in “Note 1. Basis of Presentation” in this report. There have been no changes to the significant accounting policies during 2023.
Previous: Item 1. FINANCIAL STATEMENTS · Next: Item 4. CONTROLS AND PROCEDURES