 filings.tools
Targa Resources (TRGP) 10-K risk factor changes: FY2023 vs FY2021
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A117 rewritten55 added56 removed525 unchanged
All filing items1,182 rewritten608 added506 removed2,931 unchanged
Summary
counted, not written
- Item 1A lists 43 risk factor headings: 1 new, 5 reworded and 37 unchanged since FY2021. 4 headings from FY2021 no longer appear.
- Sentence by sentence, 608 added, 506 removed, 1,182 rewritten and 2,931 unchanged across 17 items that differ.
- New this year: Item 1C. Cybersecurity..
New Item 1A headings (1)
- We may incur significant costs and liabilities resulting from performance of pipeline integrity testing programs and related repairs, as well as from initiatives relating to pipeline safety that require the use of new or more stringent safety controls or result in more rigorous enforcement of applicable legal requirements.
Removed Item 1A headings (4)
- We may incur significant costs and liabilities resulting from performance of pipeline integrity testing programs and related repairs.
- We may operate a portion of our business with one or more joint venture partners where we own a minority interest and/or are not the operator, which may restrict our operational and corporate flexibility. Actions taken by the other partner or third-party operator may materially impact our financial position and results of operations, and we may not realize the benefits we expect to realize from a joint venture.
- If dividends on our shares of common stock are not paid with respect to any fiscal quarter, our stockholders will not be entitled to receive that quarter’s payments in the future.
- Federal and state legislative and regulatory initiatives relating to pipeline safety that require the use of new or more stringent safety controls or result in more rigorous enforcement of applicable legal requirements could subject us to increased capital costs, operational delays and costs of operation.
Reworded Item 1A headings (5)
[removed: Climatic][added: Weather] events may damage our pipelines and other facilities, limit our ability or increase the costs to operate our business and adversely impact our customers on whom we rely on for throughput as well as third party vendors from whom we receive goods, which developments could cause us to incur significant costs and adversely affect our business, results *of operations and financial condition.- We are subject to cybersecurity risks. A cyber incident could occur and result in information theft, data corruption, operational disruption
[removed: and/or][added: ,disclosure of business sensitive, confidential or personally identifiable information, misdirected wire transfers, reputational harm, and] financial loss. - The widespread outbreak
[removed: pandemics (like COVID-19)][added: of illnesses] or any other public health[removed: crisis][added: crises] that impacts [added: operations and/or] the global demand for energy commodities may have material adverse effects on our business, financial position, results of operations and/or cash flows. - Our and our customers’ operations are subject to a number of risks arising out of the threat of climate
[removed: change][added: change, including increasingly stringent regulations for methane and other emissions from the oil and gas sector,] that could result in increased operating costs, limit the areas in which oil and natural gas production may occur,[removed: and]reduce demand for the products and services we[removed: provide.][added: provide, and reduce our or our customers’ ability to access capital.] - Increasing stakeholder and market attention to
[removed: ESG][added: sustainability] matters [added: and disclosure obligations] may impact our business.
A heading is new when no FY2021 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
24 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2021. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors.
117 rewritten, 55 added, 56 removed, 525 unchanged
[removed: Climatic] [added: Weather] events may damage our pipelines and other facilities, limit our ability or increase the costs to operate our business and adversely impact our customers on whom we rely on for throughput as well as third party vendors from whom we receive goods, which developments could cause us to incur significant costs and adversely affect our business, results of operations and financial condition.
We may incur significant costs and liabilities resulting from performance of pipeline integrity testing programs and related [removed: repairs.][added: repairs, as well as from initiatives relating to pipeline safety that require the use of new or more stringent safety controls or result in more rigorous enforcement of applicable legal requirements.]
A cyber incident could occur and result in information theft, data corruption, operational [removed: disruption and/or] [added: disruption, disclosure of business sensitive, confidential or personally identifiable information, misdirected wire transfers, reputational harm, and] financial loss.
The widespread outbreak of [removed: pandemics (like COVID-19)] [added: illnesses] or any other public health [removed: crisis] [added: crises] that impacts [added: operations and/or] the global demand for energy commodities may have material adverse effects on our business, financial position, results of operations and/or cash flows.
We may be unable to cause our joint ventures to take or not to take certain actions unless some or all of our joint venture participants [removed: agree and certain of our joint venture partners may fail or refuse to fund their respective portions of capital projects that we believe are necessary to expand or maintain such joint venture’s business.][added: agree.]
Our and our customers’ operations are subject to a number of risks arising out of the threat of climate [removed: change] [added: change, including increasingly stringent regulations for methane or other emissions from the oil and gas sector,] that could result in increased operating costs, limit the areas in which oil and natural gas production may occur, [removed: and] reduce demand for the products and services we [removed: provide.][added: provide, and reduce our or our customers’ ability to access capital.]
Increasing stakeholder and market attention to [removed: ESG] [added: sustainability] matters [added: and disclosure obligations] may impact our business.
[removed: Federal] [added: *We may incur significant costs] and [removed: state legislative] [added: liabilities resulting from performance of pipeline integrity testing programs] and [removed: regulatory] [added: related repairs, as well as from] initiatives relating to pipeline safety that require the use of new or more stringent safety controls or result in more rigorous enforcement of applicable legal [removed: requirements could subject us to increased capital costs, operational delays and costs of operation.][added: requirements.*]
The prices of natural gas, NGLs and crude oil have been [added: historically] volatile, and we expect this volatility to [removed: continue.][added: continue which impacts production activity levels.]
Our future cash flows may be materially adversely affected if we experience significant, prolonged price [removed: deterioration.][added: deterioration that also decreases production activity levels in our areas of operation.]
A reduction in demand for NGL products, whether because of general or industry-specific economic conditions, new government regulations, including the IRA, global competition, reduced demand by consumers for products made with NGL products (for example, reduced petrochemical demand observed due to lower activity in the automobile and construction industries), reduced demand for [removed: propane or butane exports whether for price or other reasons, increased competition from petroleum-based feedstocks due to pricing]
[added: propane or butane exports whether for price or other reasons, increased competition from petroleum-based feedstocks due to pricing] differences, mild winter weather for some NGL applications or other reasons, could result in a decline in the volume of NGL products we handle or reduce the fees we charge for our services.
[added: Even if new natural gas or crude] oil reserves are discovered in areas served by our assets, producers may choose [removed: not to develop those reserves.]
[removed: Furthermore, in] [added: In] response to depressed commodity prices, [removed: during 2020 and early 2021 many] operators [removed: announced substantial reductions] [added: may engage] in [added: curtailment or shut-ins or substantially reduce] their estimated capital expenditures, rig count and completion crews.
[removed: *Climatic] [added: *Weather] events may damage our pipelines and other facilities, limit our ability or increase the costs to operate our business and adversely impact our customers on whom we rely on for throughput as well as third party vendors from whom we receive goods, which developments could cause us to incur significant costs and adversely affect our business, results* *of operations and financial condition.*
[removed: Climatic] [added: Weather] events in the areas in which we or our customers operate can cause disruptions and in some cases suspension of our operations and development activities.
Potential climatic changes may have significant physical effects, such as increased frequency and severity of storms, [removed: floods] [added: floods, droughts, extreme temperatures, wildfires] and wintry conditions and could have an adverse effect on our [added: infrastructure or] continued operations as well as the operations of our oil and gas exploration and production customers that deliver natural gas to us for processing and throughput, our third party vendors that supply us with goods, [added: utilities necessary for our, our suppliers’, or our customers’ continued operations,] and third party insurance providers that make insuring products available to defray our costs or offset any damages and losses we incur.
Any unusual or prolonged severe [removed: climatic] [added: weather] events or increased frequency thereof, such as freezing weather or rain, earthquakes, hurricanes, droughts, [added: extreme temperatures, wildfires] or floods in our oil and gas exploration and production customers’ or our third party vendors’ areas of operations or markets, whether due to climatic change or otherwise, could have a material adverse effect on our business, results of operations and financial condition.
Moreover, we could incur significant costs to weatherize or upgrade weatherization of our facility equipment in anticipation of future [removed: climatic] [added: weather] events.
For example, following Texas Governor Greg [removed: Abbott's] [added: Abbott’s] direction to adopt rules related to weather resiliency, in August 2022, the Texas Railroad Commission adopted the Weather Emergency Preparedness Standards rule, which requires critical gas facilities on the state’s Electricity Supply Chain Map (including gas pipelines that directly serve electricity generation) to (i) weatherize to help ensure sustained operations during a weather emergency, (ii) correct known issues that caused weather-related forced stoppages and (iii) [removed: contact the Texas Railroad Commission if a facility sustains a weather-related forced stoppage during a weather emergency.]
[added: If, upon inspection,] we are required to further weatherize or update weatherization of certain facilities, we may incur significant costs to complete any additional weatherization.
Our operations are subject to many hazards inherent in [removed: purchasing,] gathering, compressing, treating, [removed: processing and/or] [added: processing, transporting, purchasing and] selling natural gas; [added: transporting,] storing, fractionating, [removed: treating, transporting] [added: treating] and [added: purchasing and] selling NGLs and NGL [removed: products;] [added: products, including services to LPG exporters;] and [removed: purchasing,] gathering, [removed: storing and/or] [added: storing,] terminaling [added: and purchasing and selling] crude oil, including:
damage to pipelines and plants, related equipment and surrounding properties caused by hurricanes, [added: earthquakes,] tornadoes, floods, [removed: fires] [added: fires, extreme temperatures,] and other natural disasters, [removed: explosions] [added: explosions, cyber attacks,] and acts of terrorism;
We attempt to balance sales with volumes supplied from processing operations, but unexpected volume variations due to production variability or to gathering, plant or pipeline system disruptions may expose us to volume [removed: imbalances] [added: imbalances,] which, in conjunction with movements in commodity prices, could materially impact our income from operations and cash flow.
[removed: With adoption of the] [added: The] Pipeline Safety, Regulatory Certainty, and Job Creation Act of 2011 (“2011 Pipeline Safety Act”), the Protecting our Infrastructure of Pipelines and Enhancing Safety Act of 2016 (“2016 Pipeline Safety Act”) and the Protecting Our Infrastructure of Pipelines and Enhancing Safety (“PIPES”) Act of [removed: 2020 over the past decade, existing mandates] [added: 2020,] require PHMSA to impose more stringent pipeline safety [removed: standards.][added: standards on pipeline operators.]
In August 2022, PHMSA finalized [removed: additional pipeline safety rules, which adjusted] the [removed: repair criteria for pipelines in HCAs, created new criteria] [added: last of three rules known collectively as the “Gas Mega Rule,” which collectively, among other items, imposed safety regulations on previously unregulated onshore gas gathering lines, required updated inspection and maintenance plans] for [removed: pipelines in non-HCAs,] [added: the elimination of hazardous leaks] and [added: minimization of natural gas released from pipeline facilities and adjusted and] strengthened [added: repair, maintenance and] integrity management assessment [removed: requirements, among other items.][added: criteria for pipelines in HCAs and non-HCAs.]
A cyber incident could occur and result in information theft, data corruption, operational disruption [removed: and/or] [added: ,disclosure of business sensitive, confidential or personally identifiable information, misdirected wire transfers, reputational harm, and] financial loss.*
Our systems for protecting against cybersecurity risks may not be [removed: sufficient.][added: sufficient, and no security measure is infallible.]
As cyber incidents continue to evolve, we will [removed: likely] be required to expend additional resources to enhance our security posture and cybersecurity defenses or to investigate and remediate any vulnerability to or consequences of cyber incidents.
Our insurance coverages [removed: for cyber-attacks] may not be sufficient to cover all the losses we may experience as a result of a cyber incident.
*The widespread outbreak [removed: pandemics (like COVID-19)] [added: of illnesses] or any other public health [removed: crisis] [added: crises] that impacts [added: operations and/or] the global demand for energy commodities may have material adverse effects on our business, financial position, results of operations and/or cash flows.*
[removed: The] [added: For example, the] effects of the COVID-19 pandemic, including travel bans, prohibitions on group events and gatherings, shutdowns of certain businesses, curfews, shelter-in-place orders and recommendations to practice social distancing in addition to other actions taken by both businesses and governments, resulted in a significant and swift reduction in international and U.S. economic activity.
If we are unable to develop accretive growth projects or make accretive acquisitions because we are unable to [removed: (1)] [added: (i)] develop growth projects economically or identify attractive acquisition candidates and negotiate acceptable acquisition [removed: agreements or, (2)] [added: agreements, (ii)] obtain financing for these projects or acquisitions on economically acceptable terms, or [removed: (3)] [added: (iii)] compete successfully for growth projects or acquisitions, then our future growth and ability to return increasing capital to our shareholders may be limited.
Challenges may arise whenever businesses with different operations or management are combined, and we may experience unanticipated delays in realizing the benefits of a growth project or acquisition if we fail to successfully integrate such [removed: businesses, including the Delaware Basin Acquisition and South Texas Acquisition,] [added: businesses] with our operations.
Furthermore, some bankruptcy courts have found that, in certain [removed: cases] [added: cases,] oil, gas and water gathering agreements do not create covenants running with the land under governing law and are thus subject to rejection in Chapter 11 proceedings.
[removed: These inflationary pressures] [added: remain volatile and] have resulted in and may result in additional increases to the costs of our goods, services and personnel, which in turn cause our capital expenditures and operating costs to rise.
Sustained levels of high inflation [removed: have] likewise caused the U.S. Federal Reserve and other central banks to increase interest rates multiple times in [removed: 2022.][added: 2022 and 2023.]
[removed: The] [added: Although it is currently anticipated that the] U.S. Federal Reserve [removed: has raised and may continue] [added: will make cuts] to [removed: raise] benchmark interest rates in [removed: 2023 in an effort to curb inflationary pressure on the costs of goods] [added: 2024, such cuts may not occur] and [removed: services across the U.S., which] [added: any continued increase in benchmark interest rates] could have the [removed: effects] [added: effect] of raising the cost of capital and depressing economic growth, either of [removed: which—or] [added: which (or] the combination [removed: thereof—could] [added: thereof) could] negatively impact the financial and operating results of our business.
We cannot predict any future trends in the rate of [removed: inflation] [added: inflation, or any resultant changes in monetary policy,] and a significant increase in inflation, to the extent we are unable to recover higher costs through higher prices and revenues, [added: and/or higher interest rates] would negatively impact our business, financial condition and results of operations.
[removed: Dividends] [added: Further, dividends] to our common stockholders are not cumulative.
not to develop those reserves.
contact the Texas Railroad Commission if a facility sustains a weather-related forced stoppage during a weather emergency.
Further, due to the impacts of recent weather events, certain major insurance companies are either reducing, or no longer offering, certain coverages in Texas, among other states.
If a significant accident or event occurs for which we are not fully insured or if we fail to acquire insurance for certain of our operations generally, our operations and financial results could be adversely affected.
Our technologies, systems, networks, including our operational technology systems, and those of our business partners may become the target of cyber-attacks or security breaches.
Advances in computer capabilities, rapid changes and innovation in the field of artificial intelligence, cryptography, inadequate facility security or other developments may result in a compromise or breach of the technology we use to safeguard confidential, personal, or otherwise protected information.
As the breadth and complexity of the technologies we use continue to grow, including as a result of the use of mobile devices, cloud services, open source software, social media and the increased reliance on devices connected to the internet, the potential risk of security breaches and cybersecurity attacks also increases.
Despite ongoing efforts to improve our ability to protect data from compromise, we may not be able to protect all of our data across our diverse systems.
Our efforts to improve security and protect data may also identify previously undiscovered instances of security breaches or other cyber incidents.
The rate of inflation in the U.S. began to increase significantly beginning in the second half of 2021.
Although the rate of inflation has generally declined since the second half of 2022, the rate of inflation remains higher than historical averages, and inflationary pressures
For example, for the first quarter of 2024, management intends to recommend to our board of directors an increase to the Company’s common dividend to $0.75 per common share or $3.00 per common share annualized.
The recommended common dividend per share increase, if approved, would be effective for the first quarter of 2024 and payable in May 2024.
In February 2024, S&P upgraded Targa’s rating to “BBB”.
However, because the U.S. Supreme Court has held that GHG emissions constitute
In order to support implementation of the methane emissions fee, including exemptions from the same, the EPA proposed revisions to its Greenhouse Gas Reporting Rule in late July 2023, which, per the Unified Regulatory Agenda, is expected to be finalized in 2024.
The revisions would amend requirements applicable to the petroleum and natural gas systems source category to ensure reporting is based on empirical data and accurately reflects total methane and waste emissions.
Under the final rules, states have two years to prepare and submit their plans to impose methane emission controls on existing sources.
The presumptive standards established under the final rule are generally the same for both new and existing sources and include enhanced leak detection survey requirements using optical gas imaging and other advanced monitoring to encourage the deployment of innovative technologies to detect and reduce methane emissions, reduction of emissions by 95% through capture and control systems, zero-emission requirements for certain devices, and the establishment of a “super emitter” response program that would allow third parties to make reports to EPA of large methane emission events, triggering certain investigation and repair requirements.
Fines and penalties for violations of these rules can be substantial.
Moreover, compliance with the new rules may effect the amount we owe under the IRA’s methane fee described above because compliance with EPA’s methane rules would exempt an otherwise covered facility from the requirement to pay the methane fee.
Moreover, failure to comply with these CAA requirements can result in the imposition of substantial fines and penalties as well as costly injunctive relief.
At COP28 in December 2023, parties agreed to transition away from fossil fuels in energy systems and increase renewable energy capacity, although no timeline for doing so was set.
Additionally, such agreements could result in increased pressure among financial institutions and various stakeholders to reduce or otherwise impose more stringent limitations on funding for, and increased potential opposition to, the production and use of fossil fuels.
infrastructure or the permitting of liquefied natural gas export facilities.
For example, on January 26, 2024, President Biden announced a temporary pause on pending decisions on new exports of liquified natural gas to countries that the United States does not have free trade agreements with, pending Department of Energy review of the underlying analyses for authorizations.
The pause is intended to provide time to integrate certain considerations, including potential energy cost increases for consumers and manufacturers and the latest assessment of the impact of GHG emissions, to ensure adequate guards against health risks are in place.
The rule is expected to be finalized in early 2024.
Increasingly, companies in the energy and infrastructure industries are being, and may increasingly be, subject to allegations that they are responsible for climate change impacts and/or responsible for the physical impacts of climate change.
Various financial regulators have adopted, or are considering adopting, guidance or requirements regarding the management of climate-related risk by financial institutions.
Recently, the State of California adopted several laws that require similar, or in some situations more extensive, disclosure.
While implementing rules on certain of these laws are outstanding, both the California laws and the SEC rule, to the extent finalized, may result in increased legal, accounting and financial compliance costs for us and our suppliers and customers to comply, including the implementation of significant additional internal controls processes and procedures regarding matters that have not been subject to such controls in the past, and impose increased oversight obligations on our management and board of directors.
shifts in temperature and precipitation patterns.
For further discussion, please see *Weather events may damage our pipelines and other facilities, limit our ability or increase the costs to operate our business and adversely impact our customers on whom we rely on for throughput as well as third party vendors from whom we receive goods, which developments could cause us to incur significant costs and adversely affect our business, results of operations and financial condition*.
Companies across industries are facing increasing scrutiny from a variety of stakeholders related to their sustainability practices.
Moreover, even if we are to achieve our targets and goals or complete other sustainability initiatives, there is no guarantee that doing so will have the desired effect.
For example, methodologies regarding the monitoring and calculation of climate risks and GHG emissions are evolving, and it is possible that stakeholders, either currently or at some point in future, may not agree with our approach.
If we fail to, or are perceived to fail to, comply with or advance certain sustainability initiatives (including the timeline and manner in which we complete such initiatives), we may be subject to various adverse impacts, including reputational damage and potential stakeholder engagement and/or litigation, even if such initiatives are currently voluntary.
We expect there will likely be increasing levels of regulation, disclosure-related and otherwise,
Additionally, many of our customers and suppliers may be subject to similar expectations and challenges, which may augment or create additional risks, including risks that may not be known to us.
If dividends on our shares of common stock are not paid with respect to any fiscal quarter, our stockholders will not be entitled to receive that quarter’s payments in the future.
Drilling and production activity generally decreases as crude oil and natural gas prices decrease.
Prices of crude oil and natural gas have been historically volatile, and we expect this volatility to continue.
Consequently, even if new natural gas or crude
For example, low prices for natural gas combined with high levels of natural gas in storage could result in curtailment or shut-in of natural gas production similar to the production shut-ins we experienced in 2020 due to the impacts of the COVID-19 pandemic.
If, upon inspection,
*We may incur significant costs and liabilities resulting from performance of pipeline integrity testing programs and related repairs.*
For example, more recently, in November 2021, PHMSA issued a final rule establishing two new classes of onshore gas gathering pipelines—Type R and Type C—and imposed safety regulations on approximately 400,000 miles of previously unregulated onshore gas gathering lines that, among other things, established criteria for inspection and repair of fugitive emissions, extended reporting requirements to all gas gathering operators and applied a set of minimum safety requirements to certain gas gathering pipelines with large diameters and high operating pressures.
Separately, in June 2021, PHMSA issued an Advisory Bulletin advising pipeline and pipeline facility operators of applicable requirements to update their inspection and maintenance plans for the elimination of hazardous leaks and minimization of natural gas released from pipeline facilities.
PHMSA, together with state regulators, were expected to commence inspection of operator plans in 2022.
Since the beginning of 2021, the distribution of COVID-19 vaccines progressed and many government-imposed restrictions were relaxed or rescinded.
However, we continue to monitor the effects of the pandemic on our operations.
Our results of operations and financial condition have been and may continue to be adversely affected by the COVID-19 pandemic.
The extent to which our operating and financial results are affected by COVID-19 will depend on various factors and consequences beyond our control, such as the emergence of more contagious and harmful variants of the COVID-19 virus, the duration and scope of the pandemic, additional actions by businesses and governments in response to the pandemic, and the speed and effectiveness of responses to combat the virus.
COVID-19, and the volatile regional and global economic conditions stemming from the pandemic, could also aggravate the other risk factors that we identify herein.
While the effects of the COVID-19 pandemic have lessened recently in the United States, we cannot predict the duration or future effects of the pandemic, or more contagious and harmful variants of the COVID-19 virus, and such effects may materially adversely affect our results of operations and financial condition in a manner that is not currently known to us or that we do not currently consider to present significant risks to our operations.
*We may operate a portion of our business with one or more joint venture partners where we own a minority interest and/or are not the operator, which may restrict our operational and corporate flexibility.
Actions taken by the other partner or third-party operator may materially impact our financial position and results of operations, and we may not realize the benefits we expect to realize from a joint venture.*
The U.S. inflation rate increased in 2021, 2022 and into 2023.
*If dividends on our shares of common stock are not paid with respect to any fiscal quarter, our stockholders will not be entitled to receive that quarter’s payments in the future.*
certain petroleum and natural gas system sources, implement New Source Performance Standards directing the reduction of methane from certain new, modified, or reconstructed facilities in the oil and natural gas sector, and together with the DOT, implement GHG emissions limits on vehicles manufactured for operation in the United States.
In addition, the proposed rule would create a new Subpart OOOOc which would require states to develop plans to reduce methane and volatile organic compound emissions from existing sources that must be at least as effective as presumptive standards set by the EPA.
This proposed rule would apply to upstream and midstream facilities at oil and natural gas well sites, natural gas gathering and boosting compressor stations, natural gas processing plants, and transmission and storage facilities.
Owners or operators of affected emission units or processes would have to comply with specific standards of performance that may include leak detection using optical gas imaging and subsequent repair requirements, reduction of emissions by 95% through capture and control systems, zero-emission requirements, operations and maintenance requirements, and so-called green well completion requirements.
In November 2022, the EPA published a supplemental methane proposal, which, among other items, sets forth specific revisions strengthening the first nationwide emission guidelines for states to limit methane emissions from existing crude oil and natural gas facilities.
The proposal also revises requirements for fugitive emissions monitoring and repair as well as equipment leaks and the frequency of monitoring surveys, establishes a “super-emitter” response program to timely mitigate emissions events, and provides additional options for the use of advanced monitoring to encourage the deployment of innovative technologies to detect and reduce methane emissions.
Moreover, the international community gathered again in Glasgow in November 2021 at the 26th Conference of the Parties (“COP26”), during which the multiple announcements were made, including a call for parties to eliminate certain fossil fuel subsidies and pursue further action on non-CO2 GHGs.
Although no firm commitment or timeline to phase out or phase down all fossil fuels was made at COP27, there can be no guarantees that countries will not seek to implement such a phase out in the future.
For example, in November 2022 the BLM proposed a rule that
In late 2020, the Federal Reserve announced that it had joined the Network for Greening the Financial System (NGFS), a consortium of financial regulators focused on addressing climate-related risks in the financial sector and, in September 2022, the Federal Reserve announced that six of the U.S.’ largest banks will participate in a pilot climate scenario analysis exercise to enhance the ability of firms and supervisors to measure and mange climate-related financial risk.
The Federal Reserve released its pilot exercise in January 2023 which is designed to analyze the impact of both physical and transition risks related to climate change on specific assets of the banks’ portfolios.
A final rule is anticipated to be released by Q2 2023.
Although the final form and substance of this rule and its requirements are not yet known and its ultimate impact on our business is uncertain, the proposed rule, if finalized, may result in increased legal, accounting and financial compliance costs for us and our suppliers and customers related to the assessment and disclosure of climate-related risks.
Separately, the SEC has also announced that it is scrutinizing existing climate-change related disclosures in public filings, increasing the potential for enforcement if the SEC were to allege an issuer’s existing climate disclosures misleading or deficient.
These climatic developments have the potential to cause physical damage to our assets and those of our suppliers and customers and thus could have an adverse effect on our operations and supply chain, including resulting in changes to costs associated with maintaining or insuring our assets.
Additionally, changing meteorological conditions, particularly temperature, may result in changes to the amount, timing, or location of demand for energy or the products our customers
produce.
While our consideration of changing weather conditions and inclusion of safety factors in design is intended to reduce the uncertainties that climate change and other events may potentially introduce, our ability to mitigate the adverse impacts of these events depends in part on the effectiveness of our facilities and our disaster preparedness and response and business continuity planning, which may not have considered or be prepared for every eventuality.
If any such effects of climate changes were to occur, they could have an adverse effect on our financial condition and results of operations and the financial condition and operations of our customers.
In addition, the federal Occupational Safety and Health Administration’s (“OSHA”) hazard communication standard, the EPA
An excerpt. Shown here: 40 of 117 rewritten, 40 of 55 added and 40 of 56 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors. in the FY2023 filing and the FY2021 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
198 rewritten, 68 added, 101 removed, 385 unchanged
Risk Factors.” Discussions of [removed: 2020] [added: 2021] items and year-to-year comparisons between [removed: 2021] [added: 2022] and [removed: 2020] [added: 2021] that are not included in this Annual Report can be found in Part II, Item 7.
“Management’s Discussion and Analysis of Financial Condition and Results of Operations” of our Annual Report on Form 10-K for the year ended December 31, [removed: 2021.][added: 2022.]
[removed: 2021: 45%] [added: 2023: 44%] ethane, [removed: 31%] [added: 32%] propane, 11% normal butane, 4% isobutane and 9% natural gasoline
The employees supporting our operations are employees of Targa Resources LLC, a Delaware limited liability company, and [removed: an indirect] [added: a] wholly-owned subsidiary of ours.
Please read *“Laws and regulations regarding hydraulic fracturing could result in restrictions, delays or cancellations in drilling and completing new oil and natural gas wells by our customers, which could adversely impact our revenues by decreasing the volumes of natural gas, NGLs or crude oil through our facilities and reducing the utilization of our assets”*, *“Our and our customers’ operations are subject to a number of risks arising out of the threat of climate change (including legislation or regulation to address climate change) that could result in increased operating costs, limit the areas in which oil and natural gas production may occur, and reduce demand for the products and services we provide,” and “Increasing stakeholder and market attention to [removed: ESG] [added: sustainability] matters [added: and disclosure obligations] may impact our business”* under Item 1A.
Our contract portfolio, the prevailing pricing environment for crude oil, natural gas and NGLs, the impact of our commodity hedging program and its ability to mitigate exposure to commodity price [removed: movements] [added: movements,] and the volumes of crude oil, natural gas and NGL throughput on our systems are important factors in determining our profitability.
These include: [removed: (1)] [added: (i)] throughput volumes, facility efficiencies and fuel consumption, [removed: (2)] [added: (ii)] operating expenses, [removed: (3)] [added: (iii)] capital expenditures and [removed: (4)] [added: (iv)] the following non-GAAP measures: adjusted EBITDA, distributable cash flow, adjusted free cash flow and adjusted operating margin (segment).
These expenses remain relatively stable and independent of the volumes through our systems, but may increase with system expansions and [added: inflation, and] will fluctuate depending on the scope of the activities performed during a specific period.
| | [removed: |] Year Ended December 31, | | | | | | | | [added: | | |]
| | [added: |] (In millions) | | | | | | | | | [added: | |]
| Reconciliation of Net income (loss) attributable to Targa Resources Corp. to Adjusted EBITDA, Distributable Cash Flow and Adjusted Free Cash Flow | | | | | | | | [removed: | |]
| Net income (loss) attributable to Targa Resources Corp. | $ | [removed: | 1,195.5] [added: 1,345.9] | | | $ | [removed: | 71.2] [added: 1,195.5] | |
| Interest (income) expense, net | | [removed: | 446.1 |] [added: 687.8] | | | | [removed: 387.9] [added: 446.1] | |
| Income tax expense (benefit) | | [removed: | 131.8 |] [added: 363.2] | | | | [removed: 14.8] [added: 131.8] | |
| Depreciation and amortization expense | | [removed: | 1,096.0 |] [added: 1,329.6] | | | | [removed: 870.6] [added: 1,096.0] | |
| (Gain) loss on sale or disposition of assets | | [removed: | (9.6] [added: (5.3] | ) | | | [removed: | 2.0] [added: (9.6] | [added: )] |
| Write-down of assets | | [removed: | 9.8 |] [added: 6.9] | | | | [removed: 10.3] [added: 9.8] | |
| (Gain) loss from financing activities (1) | | [removed: | 49.6 |] [added: 2.1] | | | | [removed: 16.6] [added: 49.6] | |
| (Gain) loss from sale of equity method investment | | [removed: | (435.9 | )] [added: —] | | | | [removed: —] [added: (435.9] | [added: )] |
| Transaction costs related to business acquisition (2) | | [removed: | 23.9 |] [added: —] | | | | [removed: —] [added: 23.9] | |
| Equity (earnings) loss | | [removed: | (9.1] [added: (9.0] | ) | | | [removed: | 23.9] [added: (9.1] | [added: )] |
| Distributions [added: (contributions)] from unconsolidated [removed: affiliates and preferred partner interests,] [added: affiliates,] net | | [removed: | 27.2 |] [added: 18.6] | | | | [removed: 116.5] [added: 27.2] | |
| Compensation on equity grants | | [removed: | 57.5 |] [added: 62.4] | | | | [removed: 59.2] [added: 57.5] | |
| Risk management activities | | [removed: | 302.5 |] [added: (275.4] | [added: )] | | | [removed: 116.0] [added: 302.5] | |
| Noncontrolling interests adjustments (3) | | [removed: | 15.8 |] [added: (3.7] | [added: )] | | | [removed: (89.4] [added: 15.8] | [removed: )] |
| Adjusted EBITDA | $ | [removed: | 2,901.1] [added: 3,530.0] | | | $ | [removed: | 2,052.0] [added: 2,901.1] | |
| Interest expense on debt obligations [removed: (4) |] [added: (5)] | | [removed: (447.6] [added: (675.8] | ) | | | [removed: | (376.2] [added: (447.6] | ) |
| Maintenance capital expenditures, net [removed: (5) |] [added: (6)] | | [removed: (168.1] [added: (223.4] | ) | | | [removed: | (131.7] [added: (168.1] | ) |
| Cash taxes | | [removed: | (6.7] [added: (13.6] | ) | | | [removed: | (2.7] [added: (6.7] | ) |
| Distributable Cash Flow | $ | [removed: | 2,278.7] [added: 2,617.2] | | | $ | [removed: | 1,541.4] [added: 2,278.7] | |
| Growth capital expenditures, net [removed: (5) |] [added: (6)] | | [removed: (1,177.2] [added: (2,224.5] | ) | | | [removed: | (407.7] [added: (1,177.2] | ) |
| Adjusted Free Cash Flow | $ | [removed: | 1,101.5] [added: 392.7] | | | $ | [removed: | 1,133.7] [added: 1,101.5] | |
| | [removed: 2022] [added: 2023] | | | | [removed: 2021] [added: 2022] | | | | [removed: 2022] [added: 2023] vs. [removed: 2021] [added: 2022] | | | | | |
| Sales of commodities | $ | [removed: 19,066.0] [added: 13,962.1] | | | $ | [removed: 15,602.5] [added: 19,066.0] | | | $ | [removed: 3,463.5] [added: (5,103.9] | [added: )] | | [removed: 22] [added: (27] | [removed: %] [added: %)] |
| Fees from midstream services | | [removed: 1,863.8] [added: 2,098.2] | | | | [removed: 1,347.3] [added: 1,863.8] | | | | [removed: 516.5] [added: 234.4] | | | [removed: 38] [added: 13] | % |
| Total revenues | | [removed: 20,929.8] [added: 16,060.3] | | | | [removed: 16,949.8] [added: 20,929.8] | | | | [removed: 3,980.0] [added: (4,869.5] | [added: )] | | [removed: 23] [added: (23] | [removed: %] [added: %)] |
| Product purchases and fuel | | [removed: 16,882.1] [added: 10,676.4] | | | | [removed: 13,729.5] [added: 16,882.1] | | | | [removed: 3,152.6] [added: (6,205.7] | [added: )] | | [removed: 23] [added: (37] | [removed: %] [added: %)] |
| Operating expenses | | [removed: 912.8] [added: 1,077.9] | | | | [removed: 747.0] [added: 912.8] | | | | [removed: 165.8] [added: 165.1] | | | [removed: 22] [added: 18] | % |
| Depreciation and amortization expense | | [removed: 1,096.0] [added: 1,329.6] | | | | [removed: 870.6] [added: 1,096.0] | | | | [removed: 225.4] [added: 233.6] | | | [removed: 26] [added: 21] | % |
| General and administrative expense | | [removed: 309.7] [added: 348.7] | | | | [removed: 273.2] [added: 309.7] | | | | [removed: 36.5] [added: 39.0] | | | 13 | % |
| 2023 | | | | | | | | | | | |
| 4th Quarter | $ | 2.88 | | | $ | 0.60 | | | $ | 78.33 | |
| 3rd Quarter | | 2.54 | | | | 0.62 | | | | 82.18 | |
| 2nd Quarter | | 2.09 | | | | 0.56 | | | | 73.75 | |
| 1st Quarter | | 3.45 | | | | 0.70 | | | | 76.11 | |
| 2023 Average | | 2.74 | | | | 0.62 | | | | 77.59 | |
| | 2023 | | | | 2022 | | |
| Litigation expense (4) | | 6.9 | | | | — | |
Noncontrolling interest portion of depreciation and amortization expense.
Litigation expense includes charges related to litigation resulting from the major winter storm in February 2021 that we consider outside the ordinary course of our business and/or not reflective of our ongoing core operations.
We may incur such charges from time to time, and we believe it is useful to exclude such charges because we do not consider them reflective of our ongoing core operations and because of the generally singular nature of the claims underlying such litigation.
Excludes amortization of debt issuance costs.
During 2022, we terminated our previous TRGP senior secured revolving credit facility (the “Previous TRGP Revolver”) and the Partnership’s senior secured revolving credit facility.
The premium on repurchase of noncontrolling interests, net of tax is primarily due to the Grand Prix Transaction in 2023 and the purchase of all of Stonepeak Infrastructure Partners’ interests in our development company joint ventures in 2022.
| December 31, 2023 | | $ | 2,082.2 | | | $ | 1,948.7 | | | $ | 275.5 | |
| SouthTX (6) | | | 367.4 | | | | | 276.5 | | | | | 90.9 | | | | 33 | % |
| SouthOK (6) | | | 385.0 | | | | | 406.8 | | | | | (21.8 | ) | | | (5 | %) |
| WestOK | | | 207.1 | | | | | 208.7 | | | | | (1.6 | ) | | | (1 | %) |
| Coastal | | | 541.1 | | | | | 537.6 | | | | | 3.5 | | | | 1 | % |
| Total | | | 6,898.2 | | | | | 5,511.2 | | | | | 1,387.0 | | | | 25 | % |
| Permian Delaware (5) | | | 321.6 | | | | | 188.6 | | | | | 133.0 | | | | 71 | % |
| Total Permian | | | 689.3 | | | | | 510.3 | | | | | 179.0 | | | | 35 | % |
| SouthTX (6) | | | 40.9 | | | | | 31.2 | | | | | 9.7 | | | | 31 | % |
| SouthOK (6) | | | 43.1 | | | | | 47.6 | | | | | (4.5 | ) | | | (9 | %) |
| WestOK | | | 12.5 | | | | | 14.6 | | | | | (2.1 | ) | | | (14 | %) |
| Badlands (6) | | | 15.5 | | | | | 16.1 | | | | | (0.6 | ) | | | (4 | %) |
| Total Field | | | 825.3 | | | | | 641.0 | | | | | 184.3 | | | | 29 | % |
| Coastal | | | 39.2 | | | | | 32.0 | | | | | 7.2 | | | | 23 | % |
| Total | | | 864.5 | | | | | 673.0 | | | | | 191.5 | | | | 28 | % |
| NGL sales, MBbl/d (3) | | | 495.8 | | | | | 439.8 | | | | | 56.0 | | | | 13 | % |
| | | | | | | | | | | $ | 110.7 | | | | | | | | | | | $ | (442.0 | ) |
*2023 Compared to 2022*
Natural gas inlet volumes in the Central region increased due to the acquisition of certain assets in South Texas during the second quarter of 2022 and increased producer activity.
| Operating margin | $ | | 1,948.7 | | | $ | | 1,456.3 | | | $ | | 492.4 | | | 34% |
| Operating expenses | | | 332.0 | | | | | 300.2 | | | | | 31.8 | | | 11% |
| Fractionation volumes | | | 798.1 | | | | | 731.7 | | | | | 66.4 | | | 9% |
| Export volumes (3) | | | 365.2 | | | | | 314.5 | | | | | 50.7 | | | 16% |
| NGL sales | | | 1,019.8 | | | | | 866.3 | | | | | 153.5 | | | 18% |
*2023 Compared to 2022*
LPG Export margin increased due to the completion of the expansion during the third quarter of 2023 resulting in higher volumes and fees.
| 2021 | | | | | | | | | | | |
| 4th Quarter | $ | 5.84 | | | $ | 0.94 | | | $ | 77.17 | |
| 3rd Quarter | | 4.01 | | | | 0.86 | | | | 70.55 | |
| 2nd Quarter | | 2.83 | | | | 0.66 | | | | 66.06 | |
| 1st Quarter | | 2.70 | | | | 0.65 | | | | 57.80 | |
| 2021 Average | | 3.85 | | | | 0.78 | | | | 67.90 | |
(1)
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | 2022 | | | | | 2021 | | | |
| Impairment of long-lived assets | | | — | | | | | 452.3 | |
| Change in contingent considerations | | | — | | | | | 0.1 | |
Noncontrolling interest portion of depreciation and amortization expense (including the effects of the impairment of long-lived assets on non-controlling interests).
Excludes amortization of interest expense.
| Impairment of long-lived assets | | — | | | | 452.3 | | | | (452.3 | ) | | (100 | %) |
In 2021, we recognized a non-cash pre-tax impairment loss of $452.3 million on assets in the South Texas region associated with our Central operations.
See Note 5 - Property, Plant and Equipment and Intangible Assets for further discussion.
Other operating (income) expense in 2021 consisted primarily of the write-down of certain assets to their recoverable amounts.
The increase in equity earnings is primarily due to lower losses resulting from the purchase of our remaining interests in the two joint ventures in South Texas that we previously held as investments in unconsolidated affiliates and lower losses from GCF, partially offset by lower earnings resulting from the impact of the GCX Sale and lower earnings from our investment in Little Missouri 4 LLC.
See Note 7 – Investments in Unconsolidated Affiliates for further discussion.
In addition, we terminated the Previous TRGP Revolver and the Partnership Revolver.
During 2021, the Partnership redeemed the 5.125% Senior Notes due 2025 and the 4.250% Senior Notes due 2023 and Targa Pipeline Partners LP redeemed its TPL 4.750% Senior Notes due 2021 and TPL 5.875% Senior Notes due 2023, resulting in a net loss from financing activities.
| | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| December 31, 2021 | | | | 1,325.3 | | | | | 1,264.3 | | | | | (115.9 | ) |
| SouthTX (6) | | | 276.5 | | | | | 177.7 | | | | | 98.8 | | | | 56 | % |
| SouthOK (6) | | | 406.8 | | | | | 405.9 | | | | | 0.9 | | | | — | |
| WestOK | | | 208.7 | | | | | 212.6 | | | | | (3.9 | ) | | | (2 | %) |
| Coastal | | | 537.6 | | | | | 587.2 | | | | | (49.6 | ) | | | (8 | %) |
| Total | | | 5,511.2 | | | | | 4,470.3 | | | | | 1,040.9 | | | | 23 | % |
| Permian Delaware (5) | | | 193.9 | | | | | 114.1 | | | | | 79.8 | | | | 70 | % |
| Total Permian | | | 515.6 | | | | | 392.0 | | | | | 123.6 | | | | | |
| SouthTX (6) | | | 31.2 | | | | | 22.2 | | | | | 9.0 | | | | 41 | % |
| SouthOK (6) | | | 47.6 | | | | | 49.5 | | | | | (1.9 | ) | | | (4 | %) |
| WestOK | | | 14.6 | | | | | 16.5 | | | | | (1.9 | ) | | | (12 | %) |
| Badlands (6) | | | 16.1 | | | | | 16.2 | | | | | (0.1 | ) | | | (1 | %) |
| Total Field | | | 646.3 | | | | | 516.5 | | | | | 129.8 | | | | | |
| Coastal | | | 32.0 | | | | | 33.9 | | | | | (1.9 | ) | | | (6 | %) |
| Total | | | 678.3 | | | | | 550.4 | | | | | 127.9 | | | | 23 | % |
| NGL sales, MBbl/d (3) | | | 438.7 | | | | | 394.6 | | | | | 44.1 | | | | 11 | % |
An excerpt. Shown here: 40 of 198 rewritten, 40 of 68 added and 40 of 101 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. in the FY2023 filing and the FY2021 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
16 rewritten, 6 added, 7 removed, 58 unchanged
In an effort to reduce the variability of our cash flows, as of December 31, [removed: 2022,] [added: 2023,] we have hedged the commodity price associated with a portion of our expected (i) natural gas, NGL, and condensate equity volumes in our Gathering and Processing operations that result from our percent-of-proceeds processing arrangements, (ii) future commodity purchases and sales in our Logistics and Transportation segment and (iii) natural gas transportation basis risk in our Logistics and Transportation segment.
A majority of these commodity price hedges are documented pursuant to a [removed: standard International Swap Dealers Association form] [added: ISDA] with customized credit and legal terms.
The following table shows the effect of hypothetical price movements on the estimated fair value of our derivative instruments as of December 31, [removed: 2022:][added: 2023:]
| | [removed: |] Fair Value | | | [removed: |] Result of 10% Price Decrease | | | [removed: |] Result of 10% Price Increase | | |
| | [removed: |] (In millions) | | | | | | | | | [removed: | |]
During the years ended December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] our operating revenues [removed: decreased] [added: increased (decreased)] by [removed: $(754.7)] [added: $441.1] million and [removed: $(490.6)] [added: $(754.7)] million as a result of transactions accounted for as derivatives.
The estimated fair value of our risk management position has moved from a net liability position of [removed: $316.7] [added: $255.8] million at December 31, [removed: 2021] [added: 2022] to [removed: $255.8] [added: a net asset position of $74.4] million at December 31, [removed: 2022.][added: 2023.]
Forward commodity prices have [removed: increased] [added: decreased] relative to the fixed prices on our derivative contracts, creating the net [removed: liability] [added: asset] position.
As of December 31, [removed: 2022,] [added: 2023,] we do not have any interest rate hedges.
As of December 31, [removed: 2022,] [added: 2023,] we had [removed: $3.6] [added: $1.3] billion in outstanding variable rate borrowings.
A hypothetical change of 100 basis points in the rate of our variable interest rate debt would impact our consolidated annual interest expense by [removed: $36.0] [added: $12.5] million based on our December 31, [removed: 2022] [added: 2023] debt balances.
We have master netting provisions in the [removed: International Swap Dealers Association agreements] [added: ISDAs] with our derivative counterparties.
These netting provisions allow us to net settle asset and liability positions with the same counterparties within the same Targa entity, and would reduce our maximum loss due to counterparty credit risk by [removed: $19.1] [added: $32.2] million as of December 31, [removed: 2022.][added: 2023.]
The range of losses attributable to our individual counterparties as of December 31, [removed: 2022] [added: 2023] would be between [removed: $1.9] [added: $0.2] million and [removed: $16.4] [added: $21.6] million, depending on the counterparty in default.
Our allowance for [removed: doubtful accounts] [added: credit losses] was [removed: $2.2] [added: $2.5] million and [removed: $0.1] [added: $2.2] million as of December 31, [removed: 2022] [added: 2023] and December 31, [removed: 2021,] [added: 2022,] respectively.
No customer comprised 10% or greater of our consolidated revenues during the years ended December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] respectively.
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Natural gas | $ | 12.9 | | $ | 43.2 | | $ | (17.3 | ) |
| NGLs | | 59.0 | | | 124.4 | | | (6.2 | ) |
| Crude oil | | 2.5 | | | 24.4 | | | (19.3 | ) |
| Total | $ | 74.4 | | $ | 192.0 | | $ | (42.8 | ) |
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Natural gas | | $ | (267.6 | ) | | $ | (185.1 | ) | | $ | (350.1 | ) |
| NGLs | | | 34.2 | | | | 123.1 | | | | (54.7 | ) |
| Crude oil | | | (22.4 | ) | | | 5.7 | | | | (50.5 | ) |
| Total | | $ | (255.8 | ) | | $ | (56.3 | ) | | $ | (455.3 | ) |
The change in the allowance for doubtful accounts was primarily due to the Delaware Basin Acquisition.
Item 1. Financial Statements.
540 rewritten, 198 added, 197 removed, 1,008 unchanged
| | December 31, [removed: 2022] [added: 2023] | | | | December 31, [removed: 2021] [added: 2022] | | |
| Cash and cash equivalents | $ | [removed: 219.0] [added: 141.7] | | | $ | [removed: 158.5] [added: 219.0] | |
| Trade receivables, net of allowances of [removed: $2.2] [added: $2.5] million and [removed: $0.1] [added: $2.2] million at December 31, [removed: 2022] [added: 2023] and December 31, [removed: 2021] [added: 2022] | | [removed: 1,408.4] [added: 1,471.0] | | | | [removed: 1,331.9] [added: 1,408.4] | |
| Inventories | | [removed: 393.8] [added: 371.5] | | | | [removed: 153.4] [added: 393.8] | |
| Assets from risk management activities | | [removed: 179.9] [added: 111.9] | | | | [removed: 43.1] [added: 179.9] | |
| Other current assets | | [removed: 155.5] [added: 98.5] | | | | [removed: 82.9] [added: 155.5] | |
| Total current assets | | [removed: 2,356.6] [added: 2,194.6] | | | | [removed: 1,769.8] [added: 2,356.6] | |
| Property, plant and equipment, net | | [removed: 14,214.6] [added: 15,806.4] | | | | [removed: 11,667.7] [added: 14,214.6] | |
| Intangible assets, net | | [removed: 2,734.6] [added: 2,350.6] | | | | [removed: 1,094.8] [added: 2,734.6] | |
| Long-term assets from risk management activities | | [removed: 24.5] [added: 33.3] | | | | [removed: 7.7] [added: 24.5] | |
| Investments in unconsolidated affiliates | | [removed: 131.3] [added: 146.3] | | | | [removed: 586.5] [added: 131.3] | |
| Other long-term assets | | [removed: 98.4] [added: 140.6] | | | | [removed: 81.7] [added: 98.4] | |
| Total assets | $ | [removed: 19,560.0] [added: 20,671.8] | | | $ | [removed: 15,208.2] [added: 19,560.0] | |
| Accounts payable | $ | [removed: 1,448.8] [added: 1,574.9] | | | $ | [removed: 1,402.3] [added: 1,448.8] | |
| Interest payable | | [removed: 174.0] [added: 229.6] | | | | [removed: 138.5] [added: 174.0] | |
| Liabilities from risk management activities | | [removed: 320.1] [added: 54.0] | | | | [removed: 258.2] [added: 320.1] | |
| Current debt obligations | | [removed: 834.3] [added: 620.7] | | | | [removed: 162.8] [added: 834.3] | |
| Total current liabilities | | [removed: 3,066.7] [added: 2,760.9] | | | | [removed: 2,298.5] [added: 3,066.7] | |
| Long-term debt | | [removed: 10,702.1] [added: 12,333.2] | | | | [removed: 6,434.4] [added: 10,702.1] | |
| Long-term liabilities from risk management activities | | [removed: 140.1] [added: 16.8] | | | | [removed: 109.3] [added: 140.1] | |
| Deferred income taxes, net | | [removed: 327.7] [added: 535.8] | | | | [removed: 136.0] [added: 327.7] | |
| Other long-term liabilities | | [removed: 341.2] [added: 415.1] | | | | [removed: 301.6] [added: 341.2] | |
| Series A Preferred 9.5% Stock, $1,000 per share liquidation preference (1,200,000 shares authorized, zero [removed: and 919,300] shares issued and outstanding as of December 31, [removed: 2022] [added: 2023] and December 31, [removed: 2021),] [added: 2022),] net of discount [removed: (see Note 11)] | | — | | | | [removed: 749.7] [added: —] | |
| Common stock ($0.001 par value, 450,000,000 shares authorized as of December 31, [removed: 2022] [added: 2023] and December 31, [removed: 2021)] [added: 2022)] | | 0.2 | | | | 0.2 | |
| Additional paid-in capital | | [removed: 3,702.3] [added: 3,058.8] | | | | [removed: 4,268.9] [added: 3,702.3] | |
| Retained earnings (deficit) | | [removed: (626.8] [added: 492.0] | [removed: )] | | | [removed: (1,822.3] [added: (626.8] | ) |
| Accumulated other comprehensive income (loss) | | [removed: 54.7] [added: 85.6] | | | | [removed: (230.9] [added: 54.7] | [removed: )] |
| Treasury stock, at cost [removed: (11,896,829] [added: (17,484,440] shares as of December 31, [removed: 2022] [added: 2023] and [removed: 7,884,171] [added: 11,896,829] shares as of December 31, [removed: 2021)] [added: 2022)] | | [removed: (464.7] [added: (896.9] | ) | | | [removed: (204.1] [added: (464.7] | ) |
| Total Targa Resources Corp. [removed: stockholders'] [added: stockholders’] equity | | [removed: 2,665.7] [added: 2,739.7] | | | | [removed: 2,011.8] [added: 2,665.7] | |
| Noncontrolling interests | | [removed: 2,316.5] [added: 1,870.3] | | | | [removed: 3,166.9] [added: 2,316.5] | |
| Total [removed: owners'] [added: owners’] equity | | [removed: 4,982.2] [added: 4,610.0] | | | | [removed: 5,178.7] [added: 4,982.2] | |
| Total liabilities, Series A Preferred Stock and [removed: owners'] [added: owners’] equity | $ | [removed: 19,560.0] [added: 20,671.8] | | | $ | [removed: 15,208.2] [added: 19,560.0] | |
| | [removed: |] Year Ended December 31, | | | | | | | | | | |
| | [removed: | 2022] [added: 2023] | | | | [removed: 2021] [added: 2022] | | | | [removed: 2020] [added: 2021] | | |
| | (In millions, except per share amounts) | | | | | | | | | | | [removed: |]
| Revenues: | | | | | | | | | | | | [removed: |]
| Sales of commodities | [removed: |] $ | [removed: 19,066.0] [added: 13,962.1] | | | $ | [removed: 15,602.5] [added: 19,066.0] | | | $ | [removed: 7,171.0] [added: 15,602.5] | |
| Fees from midstream services | | [removed: | 1,863.8] [added: 2,098.2] | | | | [removed: 1,347.3] [added: 1,863.8] | | | | [removed: 1,089.3] [added: 1,347.3] | |
| Total revenues | | [removed: | 20,929.8] [added: 16,060.3] | | | | [removed: 16,949.8] [added: 20,929.8] | | | | [removed: 8,260.3] [added: 16,949.8] | |
| Costs and expenses: | | | | | | | | | | | | [removed: |]
| Accrued liabilities | | 281.7 | | | | 289.5 | |
| December 31, 2023 240,095,699 222,611,259 | | | | | | | |
F-5
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Common stock dividends | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | Retained | | | Accumulated | | | | | | | | | | | | | | | | | |
| | | | | | | | | Additional | | | Earnings | | | Other | | | Treasury | | | | | | | | | Total | | | Series A | | |
| | | Common Stock | | | | | | Paid in | | | (Accumulated | | | Comprehensive | | | Shares | | | | | | Noncontrolling | | | Owners’ | | | Preferred | | |
| | | Shares | | | Amount | | | Capital | | | Deficit) | | | Income (Loss) | | | Shares | | | Amount | | | Interests | | | Equity | | | Stock | | |
| | | (In millions, except shares in thousands) | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Balance, December 31, 2022 | | | 226,042 | | $ | 0.2 | | $ | 3,702.3 | | $ | (626.8 | ) | $ | 54.7 | | | 11,897 | | $ | (464.7 | ) | $ | 2,316.5 | | $ | 4,982.2 | | $ | — | |
| Dividend equivalent rights | | | — | | | — | | | (2.3 | ) | | (1.6 | ) | | — | | | — | | | — | | | — | | | (3.9 | ) | | — | |
| Excise tax on repurchases of common stock | | | — | | | — | | | — | | | — | | | — | | | — | | | (2.7 | ) | | — | | | (2.7 | ) | | — | |
| Common stock dividends | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Repurchase of noncontrolling interests, net of tax | | | — | | | — | | | (510.1 | ) | | — | | | — | | | — | | | — | | | (459.3 | ) | | (969.4 | ) | | — | |
| Net income (loss) | | | — | | | — | | | — | | | 1,345.9 | | | — | | | — | | | — | | | 233.4 | | | 1,579.3 | | | — | |
| Balance, December 31, 2023 | | | 222,611 | | $ | 0.2 | | $ | 3,058.8 | | $ | 492.0 | | $ | 85.6 | | | 17,484 | | $ | (896.9 | ) | $ | 1,870.3 | | $ | 4,610.0 | | $ | — | |
| Repayments of term loan facility | | | (1,000.0 | ) | | | — | | | | — | |
Targa consolidates the Partnership and its subsidiaries under GAAP, and the accompanying consolidated financial statements have been prepared under the rules and regulations of the SEC.
Allowance for Credit Losses
Debt issuance costs related to revolving credit facilities and the term loan facility are amortized on a straight-line basis and those related to long-term debt are amortized using the effective-interest method.
Commercial Paper Program
Under the terms of the unsecured commercial paper note program (the “Commercial Paper Program”), we may issue, from time to time, unsecured commercial paper notes with varying maturities of less than one year.
Amounts available under the Commercial Paper Program may be issued, repaid, and re-issued from time to time, with the maximum aggregate face or principal amount outstanding at any one time not to exceed $2.75 billion.
We maintain a minimum available borrowing capacity under the $2.75 billion TRGP senior revolving credit facility (the “TRGP Revolver”) equal to the aggregate amount outstanding under the Commercial Paper Program as support.
The outstanding borrowings of the commercial paper program are classified as noncurrent because we intend to refinance the borrowings on a long-term basis through the TRGP Revolver.
We confirm, on a quarterly basis, that there is sufficient liquidity under the TRGP Revolver to refinance outstanding borrowings of the Commercial Paper Program and such liquidity is not overcommitted for other anticipated uses.
As the outstanding borrowings of the Commercial Paper Program are included as part of long-term debt (i.e., classified as noncurrent), we report Commercial Paper Program borrowings and repayments gross on the statement of cash flows (consistent with the presentation of cash flows associated with the TRGP Revolver).
Debt Modification and Extinguishment
When similar debt instruments are issued and redeemed in the same period, we evaluate whether the issuance of the new instrument should be accounted for as a modification of the existing debt or as an extinguishment of the existing debt and issuance of new debt.
We account for these debt transactions as modifications unless they are considered substantially different debt instruments, in which case we account for them as debt extinguishments and new issuances.
Transactions involving the issuance of a new debt instrument to one lender and the concurrent satisfaction of an existing debt instrument with another unrelated lender are always accounted for as an extinguishment of the existing debt and issuance of new debt.
Debt instruments are considered substantially different if the present value of the cash flows under the terms of the new debt instrument is at least 10 percent different from the present value of the remaining cash flows under the terms of the existing debt instrument.
We
consider changes in principal amounts, interest rates, and maturity dates of the existing and new instruments when evaluating the change in cash flows between the instruments.
Transactions accounted for as modifications do not result in a gain or loss.
| Accrued liabilities | | 273.3 | | | | 272.2 | |
| Distributions payable | | 16.2 | | | | 64.5 | |
| December 31, 2021 236,105,293 228,221,122 | | | | | | | |
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Balance, December 31, 2019 | | | 232,844 | | | $ | 0.2 | | | $ | 5,221.2 | | | $ | (339.6 | ) | | $ | 92.5 | | | | 1,010 | | | $ | (53.5 | ) | | $ | 3,522.1 | | | $ | 8,442.9 | | | $ | 278.8 | |
| Distribution equivalent rights | | | — | | | | — | | | | (5.4 | ) | | | — | | | | — | | | | — | | | | — | | | | — | | | | (5.4 | ) | | | — | |
| Deemed dividends - accretion of beneficial conversion feature / partial repurchase of Series A Preferred Stock | | | — | | | | — | | | | (39.2 | ) | | | — | | | | — | | | | — | | | | — | | | | — | | | | (39.2 | ) | | | 37.6 | |
| Partial repurchase of Series A Preferred Stock | | | — | | | | — | | | | (29.2 | ) | | | — | | | | — | | | | — | | | | — | | | | — | | | | (29.2 | ) | | | (15.0 | ) |
| Net income (loss) | | | — | | | | — | | | | — | | | | (1,553.9 | ) | | | — | | | | — | | | | — | | | | 228.9 | | | | (1,325.0 | ) | | | — | |
| Dividends - $1.40 per share | | | — | | | | — | | | | — | | | | (318.3 | ) | | | — | | | | — | | | | — | | | | — | | | | (318.3 | ) | | | — | |
| Dividends in excess of retained earnings | | | — | | | | — | | | | (318.3 | ) | | | 318.3 | | | | — | | | | — | | | | — | | | | — | | | | — | | | | — | |
| Change in contingent considerations | | | — | | | | 0.1 | | | | (0.3 | ) |
| Redemption of Preferred Units | | | — | | | | — | | | | (125.0 | ) |
| Distributions to Partnership unitholders | | | — | | | | — | | | | (11.7 | ) |
50% ownership interest in the Carnero G&P LLC;
75% ownership interest in Grand Prix Pipeline LLC through the Grand Prix Joint Venture (prior to the Grand Prix Transaction, as defined in Note 4 – Acquisitions and Divestitures); and
Allowance for Doubtful Accounts
Mandatorily Redeemable Preferred Interests
Mandatorily redeemable preferred interests, which represent our joint venture partners’ interests in two joint ventures, have been included in other long-term liabilities on our Consolidated Balance Sheets, and such interests with multiple or indeterminate redemption dates were reported at their estimated redemption value as of the reporting dates.
These point-in-time values did not represent the amount that ultimately would be redeemed in the future.
Changes in the redemption value have been included in interest expense, net in our Consolidated Statements of Operations.
Effective September 1, 2022, we redeemed our joint venture partner's mandatorily redeemable preferred interests in the two joint ventures that, separately, owned a 100% interest in the WestOK natural gas gathering and processing system and a 72.8% undivided interest in the WestTX natural gas gathering and processing system.
Prior to the redemption, the joint ventures collectively held $1.9 billion face value in notes receivable from our partner, which were due July 2042.
The interest rate payable under the notes receivable was a variable LIBOR-based rate.
For the years ended December 31, 2022, 2021 and 2020, interest income (expense) on the notes receivable was $(1.8) million, $12.3 million and $8.6 million, net of the return paid to our partner, which was reflected within Interest expense, net in our Consolidated Statements of Operations.
Basic earnings (loss) per common share (“EPS”) is based on the sum of the weighted-average number of common shares outstanding and vested restricted stock, restricted stock units and performance share units.
*Revenue Contract Assets and Liabilities Acquired in a Business Combination*
In October 2021, the Financial Accounting Standards Board ("FASB") issued Accounting Standards Update ("ASU") 2021-08, Business Combinations (Topic 805): Accounting for Contract Assets and Contract Liabilities from Contracts with Customers.
Amendments in this update require application of Accounting Standards Codification 606, Revenue from Contracts with Customers ("ASC 606") to recognize and measure contract assets and contract liabilities from contracts with customers acquired in a business combination.
However, an entity that elects to early adopt must apply the amendments to all business combinations that occurred during the fiscal year that includes the interim period.
We early adopted the amendments on April 1, 2022 and have applied them to business combinations in 2022.
We applied the amendments to the Delaware Basin Acquisition, as defined in Note 4 – Acquisitions and Divestitures, by recognizing contract liabilities from contracts with customers in accordance with ASC 606.
Acquisitions
DevCo Joint Ventures
In addition, the DevCo JV Repurchase resulted in an $857.9 million reduction of Noncontrolling interests on our Consolidated Balance Sheets.
*Subsequent Event*
quarter of 2022.
An excerpt. Shown here: 40 of 540 rewritten, 40 of 198 added and 40 of 197 removed. The counts are complete. For every sentence, read Item 1. Financial Statements. in the FY2023 filing and the FY2021 filing.
Item 3. Legal Proceedings.
3 rewritten, 0 added, 0 removed, 12 unchanged
Vitol [removed: seeks] [added: sought] return of $129.0 million in payments made to Targa Channelview prior to the start-up of the Splitter, as well as additional damages.
We [removed: have] filed a petition for review with the Supreme Court of [removed: Texas,] [added: Texas which was denied on October 20, 2023, but we are seeking rehearing] and the appeal remains pending.
The cumulative amount of interest on the award through December 31, [removed: 2022,] [added: 2023,] if accrued, would have been approximately [removed: $42.6] [added: $55.5] million.
Cover and table of contents
155 rewritten, 43 added, 84 removed, 626 unchanged
For the fiscal year ended December 31, [removed: 2022][added: 2023]
[removed: ][added: ]
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive [removed: officers] [added: officers] during the relevant recovery period pursuant to §240.10D-1(b).
The aggregate market value of the common stock held by non-affiliates of the registrant was [removed: $13,379.6] [added: $16,811.5] million on June 30, [removed: 2022,] [added: 2023,] based on [removed: $59.67] [added: $76.10] per share, the closing price of the common stock as reported on the New York Stock Exchange (NYSE) on such date.
As of February [removed: 17, 2023,] [added: 9, 2024,] there were [removed: 226,639,398] [added: 223,155,363] shares of the registrant’s common stock, $0.001 par value, outstanding.
Portions of the registrant’s definitive proxy statement for the [removed: 2023] [added: 2024] Annual Meeting of Stockholders, to be filed no later than 120 days after the end of the fiscal year to which this Annual Report on Form 10-K relates, are incorporated by reference into Part III of this Annual Report on Form 10-K.
| [Item 1A. Risk Factors.](#item_1a_risk_factors) | [removed: 27] [added: 26] |
| [Item 1B. Unresolved Staff Comments.](#item_1b_unresolved_staff_comments) | [removed: 52] [added: 51] |
| [Item 4. Mine Safety Disclosures.](#item_4_mine_safety_part_1) | [removed: 52] [added: 53] |
| [Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.](#item_5_market_for_registrants_common_equ) | [removed: 53] [added: 54] |
| [Item 6. Reserved](#item_6_reserved) | [removed: 54] [added: 55] |
| [Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.](#item_7_managements_discussion_analysis_f) | [removed: 55] [added: 56] |
| [Item 7A. Quantitative and Qualitative Disclosures About Market Risk.](#item_7a_quantitative_qualitative_disclos) | [removed: 71] [added: 72] |
| [Item 11. Executive Compensation.](#item_11_executive_comp) | [removed: 76] [added: 79] |
| [Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.](#item_12_security_ownership_certain_benef) | [removed: 76] [added: 79] |
| [Item 13. Certain Relationships and Related Transactions, and Director Independence.](#item_13_certain_relationships_related_tr) | [removed: 76] [added: 79] |
| [Item 14. Principal Accounting Fees and Services.](#item_14_principal_accounting_fees_servic) | [removed: 76] [added: 80] |
| [Item 15. Exhibits, Financial Statement Schedules.](#item_15_exhibits_financial_statement_sch) | [removed: 77] [added: 81] |
| [Item 16. Form 10-K Summary.](#item_16_form_10k_summary) | [removed: 86] [added: 89] |
| [Signatures](#signatures) | [removed: 87] [added: 90] |
our ability to access the capital markets, which will depend on general market conditions, including the impact of [removed: rising] [added: increased] interest [removed: rates and] [added: rates, the potential for additional rate increases,] associated Federal Reserve policies and potential economic recession, our credit ratings and [removed: debt obligations,] [added: leverage levels,] and demand for our common equity, senior notes and commercial paper;
downside commodity price volatility from a variety of potential [removed: factors;][added: factors that can result in lower activity in our areas of operation;]
changes in laws and regulations, [removed: such as the Inflation Reduction Act of 2022 (the “IRA”),] particularly with regard to taxes, safety and [added: the] protection of the environment; [added: and]
industry changes, including the impact of [removed: consolidations,] [added: consolidation,] changes in competition and the drive to reduce fossil fuel use and substitute alternative forms of energy for oil and gas;
general economic, market and business conditions; [removed: and]
Some of these and other risks and uncertainties that could cause actual results to differ materially from such forward-looking [removed: statements are more fully described in “Item 1A.]
*The following section of this Form 10-K generally refers to business developments during the year ended December 31, [removed: 2022.][added: 2023.]
Business” of our* [*Annual Report on Form 10-K for the year ended December 31, [removed: 2021*](https://www.sec.gov/ix?doc=/Archives/edgar/data/1389170/000156459022006563/trgp-10k_20211231.htm)*.*][added: 2022*](https://www.sec.gov/ix?doc=/Archives/edgar/data/1389170/000156459022006563/trgp-10k_20211231.htm)*.*]
The map below highlights our more significant assets as of December 31, [removed: 2022:][added: 2023:]
[removed: 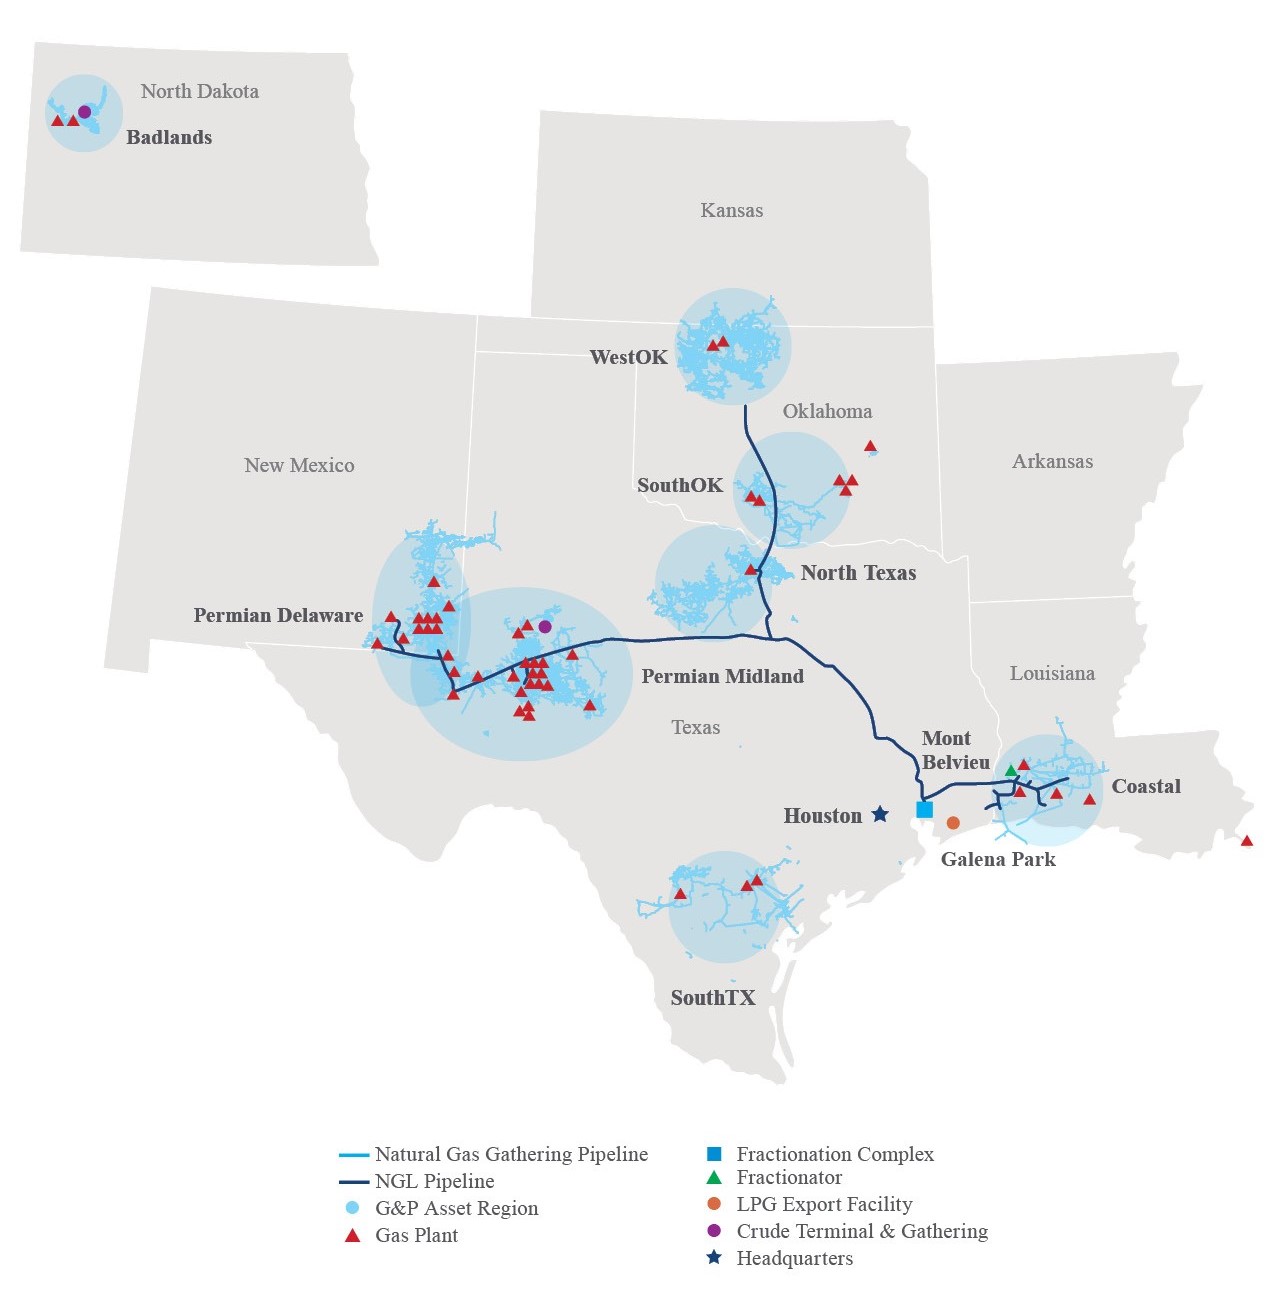][added: 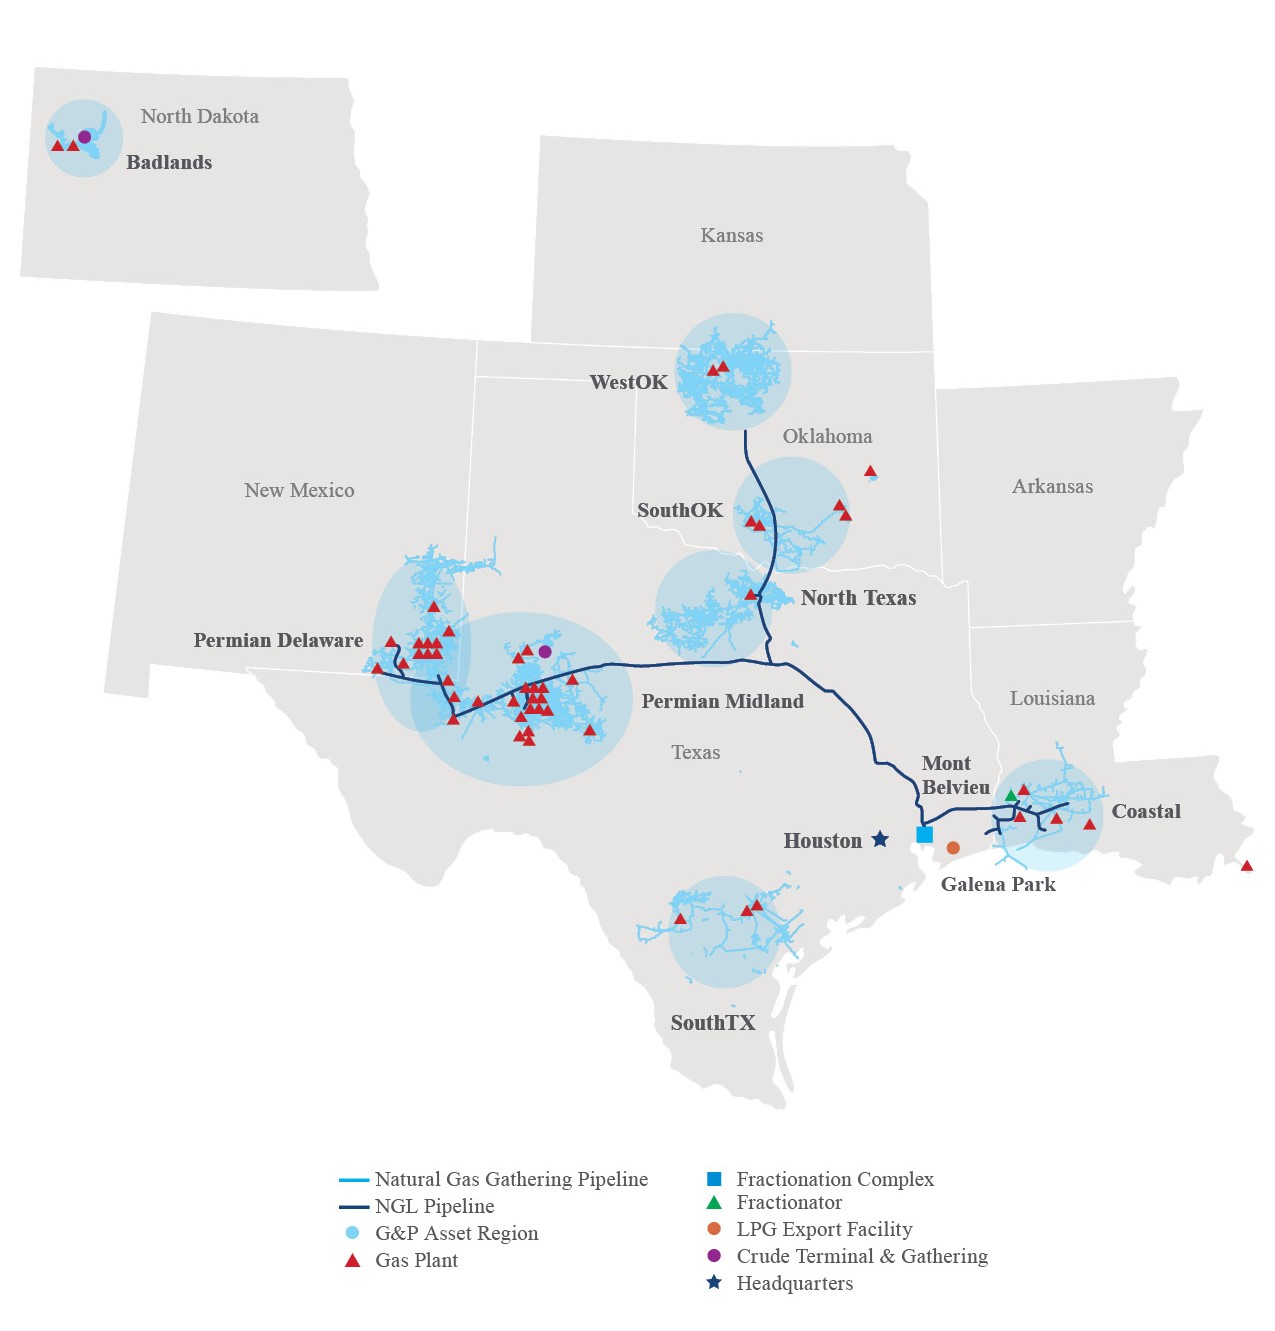]
In August [removed: 2021,] [added: 2023,] we announced the construction of a new 275 MMcf/d cryogenic natural gas processing plant in Permian Midland (the [removed: “Legacy] [added: “Greenwood II] plant”).
The Legacy [added: II] plant commenced operations in the [removed: third] [added: first] quarter of [removed: 2022.][added: 2023.]
The [removed: Legacy II] [added: Bull Moose] plant is expected to begin operations in the second quarter of [removed: 2023.][added: 2025.]
The Greenwood [added: II] plant is expected to begin operations [removed: late] in the fourth quarter of [removed: 2023.][added: 2024.]
The Midway plant [removed: is expected to begin] [added: commenced] operations in the second quarter of 2023.
The [removed: Red Hills VI] [added: Wildcat II] plant commenced operations at the end of the [removed: third] [added: fourth] quarter of [removed: 2022.][added: 2023.]
[removed: The Wildcat II plant] [added: Train 10] is expected to begin operations in the first quarter of [removed: 2024.][added: 2025.]
In February 2023, we announced the transfer of an existing cryogenic natural gas processing plant acquired in the [removed: South Texas Acquisition (as defined below)] [added: purchase of Southcross Energy Operating LLC and its subsidiaries] to the Permian Delaware.
The facility is expected to be operational [removed: during] [added: in] the [removed: first] [added: second] quarter of 2024.
The Daytona NGL Pipeline is expected to be in service [removed: by] [added: in] the [removed: end] [added: fourth quarter] of 2024.
| [Item 1C. Cybersecurity.](#item_1c_cybersecurity) | 51 |
| | |
the impact of disruptions in the bank and capital markets, including those resulting from lack of access to liquidity for banking and financial services firms;
statements are more fully described in “Item 1A.
The Greenwood plant commenced operations in the fourth quarter of 2023.
The Midway plant commenced operations in the second quarter of 2023 and we subsequently shut down an existing 165 MMcf/d cryogenic natural gas processing plant in the third quarter of 2023.
In May 2023, we announced plans to construct a new 120 MBbl/d fractionation train in Mont Belvieu, Texas (“Train 10”).
*Acquisitions*
*Capital Allocation*
In April 2023, we declared an increase to our common dividend to $0.50 per common share or $2.00 per common share annualized effective for the first quarter of 2023.
In October 2020, our Board of Directors approved a share repurchase program (the “2020 Share Repurchase Program”) for the repurchase of up to $500.0 million of our outstanding common stock.
In May 2023, our Board of Directors authorized a new $1.0 billion common share repurchase program (the “2023 Share Repurchase Program”).
The amount authorized under the 2023 Share Repurchase Program was in addition to the amount remaining under the 2020 Share Repurchase Program.
During the second quarter of 2023, we exhausted the 2020 Share Repurchase Program.
We are not obligated to repurchase any specific dollar amount or number of shares under the 2023 Share Repurchase Program and may discontinue the program at any time.
We used a portion of the net proceeds to repay $1.0 billion in borrowings under the Term Loan Facility and the remaining net proceeds for general corporate purposes, including to repay borrowings under the Commercial Paper Program.
In response to increasing production and to meet the infrastructure needs of producers, we are constructing the Bull Moose plant, a new 275 MMcf/d cryogenic natural gas processing plant, which is expected to begin operations in the second quarter of 2025.
For most of 2023, we owned a 50% interest in Carnero G&P LLC (“Carnero”).
In December 2023, we completed the acquisition of the remaining 50% membership interest in Carnero from our joint venture partner for cash consideration of $27.0 million.
| Greenwood (8) (9) | | Cryo | | Operated | | | 100.0 | | | Midland County, TX | | | 275.0 | | | | | | | | | |
| | | | | | | | | | | Area Total | | | 3,589.0 | | | | 2,535.2 | | | | 367.7 | |
| Wildcat II (12) | | Cryo | | Operated | | | 100.0 | | | Winkler County, TX | | | 275.0 | | | | | | | | | |
| | | | | | | | | | | Area Total | | | 3,055.0 | | | | 2,526.5 | | | | 321.6 | |
| | | | | | | | | | | Area Total | | | 630.0 | | | | 385.0 | | | | 43.1 | |
| | | | | | | | | | | Segment System Total | | | 10,914.0 | | | | 6,898.2 | | | | 864.5 | |
The Legacy II and Greenwood plants commenced operations in the first quarter of 2023 and fourth quarter of 2023, respectively.
The Sand Hills plant, a 165 MMcf/d cryogenic natural gas plant, was subsequently shut down in the third quarter of 2023.
The Wildcat II plant commenced operations at the end of the fourth quarter of 2023.
(13)
(14)
Following the closing of the Grand Prix Transaction, we own 100% of Grand Prix.
The Daytona NGL Pipeline is expected to be in service in the fourth quarter of 2024.
The facility is expected to be operational in the second quarter of 2024.
The GCF facility was temporarily idled in January 2021 and is expected to be reactivated and operational in the second quarter of 2024.
Currently, Targa is contesting a discrimination complaint filed as Cause No. 28550 by Enerplus Resources (USA) Corporation with the Industrial Commission of the State of North Dakota.
Oral arguments in that proceeding were held on October 25, 2023; however, a decision has not yet been issued.
The hearing on the investigation was completed in November 2023, all post-hearing briefing is complete, and the matter remains pending.
On August 31, 2023, TPL SouthTex Transmission Company LP and Targa SouthTex Transmission LP merged, with TPL SouthTex Transmission Company LP being the surviving entity.
Accordingly, Targa SouthTex Transmission LP filed to cancel its Statement of Operating Conditions for Section 311 transportation service with FERC on September 28, 2023.
We operate intrastate NGL common carrier pipelines in Texas.
In conjunction with the commencement of operations of the Midway plant, we expect to idle an existing 165 MMcf/d cryogenic natural gas processing plant (the “Sand Hills plant”).
In July 2022, we acquired a 230 MMcf/d cryogenic natural gas processing plant, which was under construction at the time of acquisition, in Permian Delaware (the “Red Hills VI plant”) as part of our Delaware Basin Acquisition (as defined below).
*Capital Investments, Acquisitions and Divestitures*
In January 2022, we completed the purchase of all of Stonepeak Infrastructure Partners’ (“Stonepeak”) interests in our development company joint ventures (“DevCo JVs”) for $926.3 million (the “DevCo JV Repurchase”).
Following the DevCo JV Repurchase, we owned a 75% interest in the Permian to Mont Belvieu segment of Grand Prix through Grand Prix Pipeline LLC (the “Grand Prix Joint Venture”) (prior to the Grand Prix Transaction, as defined below), a 100% interest in the Train 6 fractionator in Mont Belvieu, Texas and a 25% equity interest in Gulf Coast Express Pipeline (“GCX”) (prior to the GCX Sale, as defined below).
The DevCo JV Repurchase resulted in an $857.9 million reduction of Noncontrolling interests on our Consolidated Balance Sheets.
In April 2022, we completed the bolt-on acquisition of Southcross Energy Operating LLC and its subsidiaries (“Southcross”) for a purchase price of $201.9 million (the “South Texas Acquisition”), subject to customary closing adjustments.
We made a final net working capital adjustment payment of approximately $1.5 million in the fourth quarter of 2022.
We acquired a portfolio of complementary midstream infrastructure assets and associated contracts that have been integrated into our SouthTX Gathering and Processing operations, including the remaining interests in the two joint ventures in South Texas that we previously held as investments in unconsolidated affiliates, which were consolidated beginning in the second quarter of 2022.
In May 2022, we completed the sale of Targa GCX Pipeline LLC, which held a 25% equity interest in GCX, to a third party for $857.0 million (the “GCX Sale”).
As a result of the GCX Sale, we recognized a gain of $435.9 million in Gain (loss) from sale of equity method investment in our Consolidated Statements of Operations in the second quarter of 2022.
In July 2022, we completed the acquisition of all of the interests in Lucid Energy Delaware, LLC (“Lucid”) for approximately $3.5 billion in cash (the “Delaware Basin Acquisition”), subject to customary closing adjustments.
We received a final net working capital adjustment payment of approximately $11.4 million in the fourth quarter of 2022.
The assets acquired in the Delaware Basin Acquisition provide natural gas gathering, treating, and processing services in the Delaware Basin, through owning and operating approximately 1,050 miles of natural gas pipelines and approximately 1.4 billion cubic feet per day (“Bcf/d”) of cryogenic natural gas processing capacity primarily in Eddy and Lea counties of New Mexico.
The Delaware Basin Acquisition assets are integrated into our Permian Delaware operations.
*Common Share Repurchases and Preferred Stock Redemption*
In the fourth quarter of 2022, we repurchased 395,798 shares of our common stock at a weighted average price of $70.75 for a total net cost of $28.0 million.
In May 2022, we redeemed all of our issued and outstanding shares of Series A Preferred Stock (“Series A Preferred”) at a redemption price of $1,050.00 per share, plus $8.87 per share, which is the amount of accrued and unpaid dividends from April 1, 2022 up to, but not including, the redemption date of May 3, 2022.
Following the redemption, we have no Series A Preferred outstanding and all rights of the holders of shares of Series A Preferred were terminated.
See Note 11 - Preferred Stock to our Consolidated Financial Statements for further discussion.
In February 2022, we entered into a Credit Agreement with Bank of America, N.A., as the Administrative Agent and Swing Line Lender, and the other lenders party thereto (the “TRGP Revolver”).
The TRGP Revolver provides for a revolving credit facility in an initial aggregate principal amount up to $2.75 billion, with an option to increase such maximum aggregate principal amount by up to $500.0 million in the future, subject to the terms of the TRGP Revolver, including a swing line sub-facility of up to $100.0 million.
The TRGP Revolver matures in February 2027.
In connection with our entry into the TRGP Revolver, we terminated our previous TRGP senior secured revolving credit facility (the “Previous TRGP Revolver”) and the Partnership's senior secured revolving credit facility (the “Partnership Revolver”).
In February 2022, TRGP and the Partnership received a corporate investment grade credit rating from Standard & Poor’s Financial Services LLC (“S&P”) and Fitch Ratings Inc., (“Fitch”) and in March 2022, the Partnership received a corporate investment grade credit rating from Moody’s Investors Service, Inc. (“Moody's”).
As a result, in accordance with the TRGP Revolver, the collateral under the TRGP Revolver was released from the liens securing our obligations thereunder.
As a result of the termination of the Previous TRGP Revolver and the Partnership Revolver, we recorded a loss of $0.8 million due to a write-off of debt issuance costs.
In March 2022, the Partnership redeemed all of the outstanding 5.375% Senior Notes due 2027 (the “5.375% Notes”) with available liquidity under the TRGP Revolver.
As a result of the redemption of the 5.375% Notes, we recorded a loss due to debt extinguishment of $15.0 million, comprised of $12.6 million of premiums paid and a write-off of $2.4 million of debt issuance costs.
A portion of the net proceeds from the issuance was used to fund the concurrent cash tender offer (the “March Tender Offer”) and the subsequent redemption of the Partnership’s 5.875% Senior Notes due April 2026 (the “5.875% Notes”), with the remainder of the net proceeds used for repayment of the outstanding borrowings under the TRGP Revolver.
As a result of the March Tender Offer and the subsequent redemption of the 5.875% Notes, we recorded a loss due to debt extinguishment of $33.8 million, comprised of $29.3 million of premiums paid and a write-off of $4.5 million of debt issuance costs.
We used the net proceeds from the issuance to fund a portion of the Delaware Basin Acquisition.
In July 2022, we entered into the Term Loan Agreement with Mizuho Bank, Ltd. as the Administrative Agent and a lender, and other lenders party thereto (the “Term Loan Facility”).
The Term Loan Facility provides for a three-year, $1.5 billion unsecured term loan facility and matures in July 2025.
We used the proceeds to fund a portion of the Delaware Basin Acquisition.
In July 2022, we established an unsecured commercial paper note program (the “Commercial Paper Program”).
Under the terms of the Commercial Paper Program, we may issue, from time to time, unsecured commercial paper notes with varying maturities of less than one year.
Amounts available under the Commercial Paper Program may be issued, repaid and re-issued from time to time, with the maximum aggregate face or principal amount outstanding at any one time not to exceed $2.75 billion.
We maintain a minimum available borrowing capacity under the TRGP Revolver equal to the aggregate amount outstanding under the Commercial Paper Program as support.
The Commercial Paper Program is guaranteed by each subsidiary that guarantees the TRGP Revolver.
An excerpt. Shown here: 40 of 155 rewritten, 40 of 43 added and 40 of 84 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2023 filing and the FY2021 filing.
Item 1C. Cybersecurity.
0 rewritten, 43 added, 0 removed, 0 unchanged
New section this year
Description of Processes for Assessing, Identifying, and Managing Cybersecurity Risks
Cybersecurity risk is an area of focus for Targa, particularly as our operations become increasingly dependent on digital technologies.
Across the world, cybersecurity incidents are occurring more frequently, use increasingly sophisticated methods and could pose serious risks to the Company’s data integrity, reputation, operations and revenue.
The Company has a cybersecurity program, which uses technology and processes to help mitigate cybersecurity risks, with our Security Operations team working to monitor, assess, identify, and respond to potential cybersecurity incidents that threaten the Company.
The program also focuses on security awareness and training for employees and contractors with access to Company facilities or systems.
We utilize the National Institute of Standards and Technology Cybersecurity Framework as well as supplemental guidance for information and operational technologies to assess current risks against deployed current countermeasures.
We seek to follow federal and state statutory and regulatory guidance and have adopted internal policies and standards that we believe are in alignment with these requirements.
Our cybersecurity program covers Targa’s general corporate information and operational technology systems, which support our various lines of business.
Our cybersecurity program also follows defense in depth principles, which aim to implement various layered access control, detection, prevention, and response measures.
Targa has formal disaster recovery and business continuity plans, as well as a Cyber Incident Response Plan, which is periodically tested using tabletop exercises.
We regularly engage with independent third parties to assess our vulnerabilities and help us mitigate cybersecurity-related risks.
Targa’s security posture is also tested by internal Targa personnel and independent third parties to gauge its effectiveness.
Our cybersecurity program includes a formally documented process for oversight of cybersecurity risks associated with our third-party service providers.
This process begins prior to engagement.
Third-party service providers are evaluated using independent assessment tools to gauge their security posture.
The above cybersecurity risk management processes are integrated into our overall risk management program.
While we seek to continually evaluate cybersecurity risks based upon emerging threats as a part of the Company’s risk management processes, overall cybersecurity risks to the Company are also evaluated annually by independent consultants and learnings are incorporated into the overall Company risk matrices.
Our Code of Conduct communicates our expectation that employees and contractors will maintain the security of our information technology systems.
All employees are presented with Code of Conduct training annually.
Each employee’s and contractor’s ability to recognize and report cyber threats is an important component of our cybersecurity program.
As a result, security awareness and training are provided to employees and contractors with access to our facilities or systems.
We focus on increasing employee awareness of phishing attempts and train employees to be aware of cyber risks.
We recognize that cybersecurity risks continue to emerge and evolve.
Assessment and enhancement of our security posture in predicting and responding to the changing threat landscape are core goals of our cybersecurity program.
Targa maintains relationships with various cybersecurity industry subject matter experts, governmental agencies, law enforcement research and benchmarking organizations, and industry peers as part of our effort to improve our program based on threat information and available countermeasures.
We continue to make investments in new technologies to protect our facilities, users, and stakeholders, and to protect the personally identifiable information we maintain.
Board of Directors’ Oversight of Risks from Cybersecurity Risks
Cybersecurity risks are overseen at the board level through the Audit Committee.
As part of this oversight, the Audit Committee, with several key members of management, meets quarterly to discuss ongoing initiatives and seek to ensure coordination between enterprise stakeholders.
At these meetings, our Vice President of Security Operations and Senior Vice President of Technology, who oversee the Company’s cybersecurity program, review with our Audit Committee current and emerging cybersecurity-related threats as well as key performance indicators for cybersecurity process maturity, operational performance, and enterprise performance in countering these threats.
Our Vice President of Security Operations and Senior Vice President of Technology also annually review our Company's cybersecurity program with our full board.
Based on the information provided through these various processes, our board evaluates the risks facing us and provides guidance as to the appropriate risk management strategy.
Management’s Role in Assessing and Managing Cybersecurity Risks
The Vice President of Security Operations and Senior Vice President of Technology are primarily responsible for assessing and managing Targa’s material risks from cybersecurity threats, and work to monitor the effectiveness of our cybersecurity detection and response processes in countering current threats and to provide updates to our executive team.
Our Vice President of Security Operations has more than 25 years of experience working in the field of cybersecurity, including numerous years directing enterprise-level cybersecurity programs.
No Previous Material Cybersecurity Threats
As of the date of this report, though the Company and our service providers have experienced certain cybersecurity incidents, we are not aware of any previous cybersecurity threats that have materially affected or are reasonably likely to materially affect the Company.
However, we acknowledge that cybersecurity threats are continually evolving, and the possibility of future cybersecurity incidents remains.
Despite the security and risk management measures that we have implemented and any additional measures we may implement or adopt in the future, our facilities and systems, and those of our third-party service providers, have been and are vulnerable to security breaches, computer viruses, lost or misplaced data, programming errors, scams, burglary, human errors, acts of vandalism, misdirected wire transfers, or other malicious or criminal activities.
A successful attack on our information or operational technology systems could have material consequences to the Company.
An excerpt. Shown here: all 0 rewritten, 40 of 43 added and all 0 removed. The counts are complete. For every sentence, read Item 1C. Cybersecurity. in the FY2023 filing.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
8 rewritten, 8 added, 10 removed, 23 unchanged
Our common stock is listed on the NYSE under the symbol “TRGP.” As of December 31, [removed: 2022,] [added: 2023,] there were [removed: 182] [added: 170] stockholders of record of our common stock.
As of February [removed: 17, 2023,] [added: 9, 2024,] there were [removed: 226,639,398] [added: 223,155,363] shares of common stock outstanding.
The graph below compares the cumulative total return to holders of Targa Resources Corp.’s common stock, the [removed: NYSE Index, the S&P] [added: Standard & Poor's] 500 [added: Stock] Index [added: (the “S&P 500 Index”)] and the Alerian US Midstream Energy Index (the “AMUS Index”) during the period beginning on December 31, [removed: 2017] [added: 2018] and ending on December 31, [removed: 2022.][added: 2023.]
[removed: 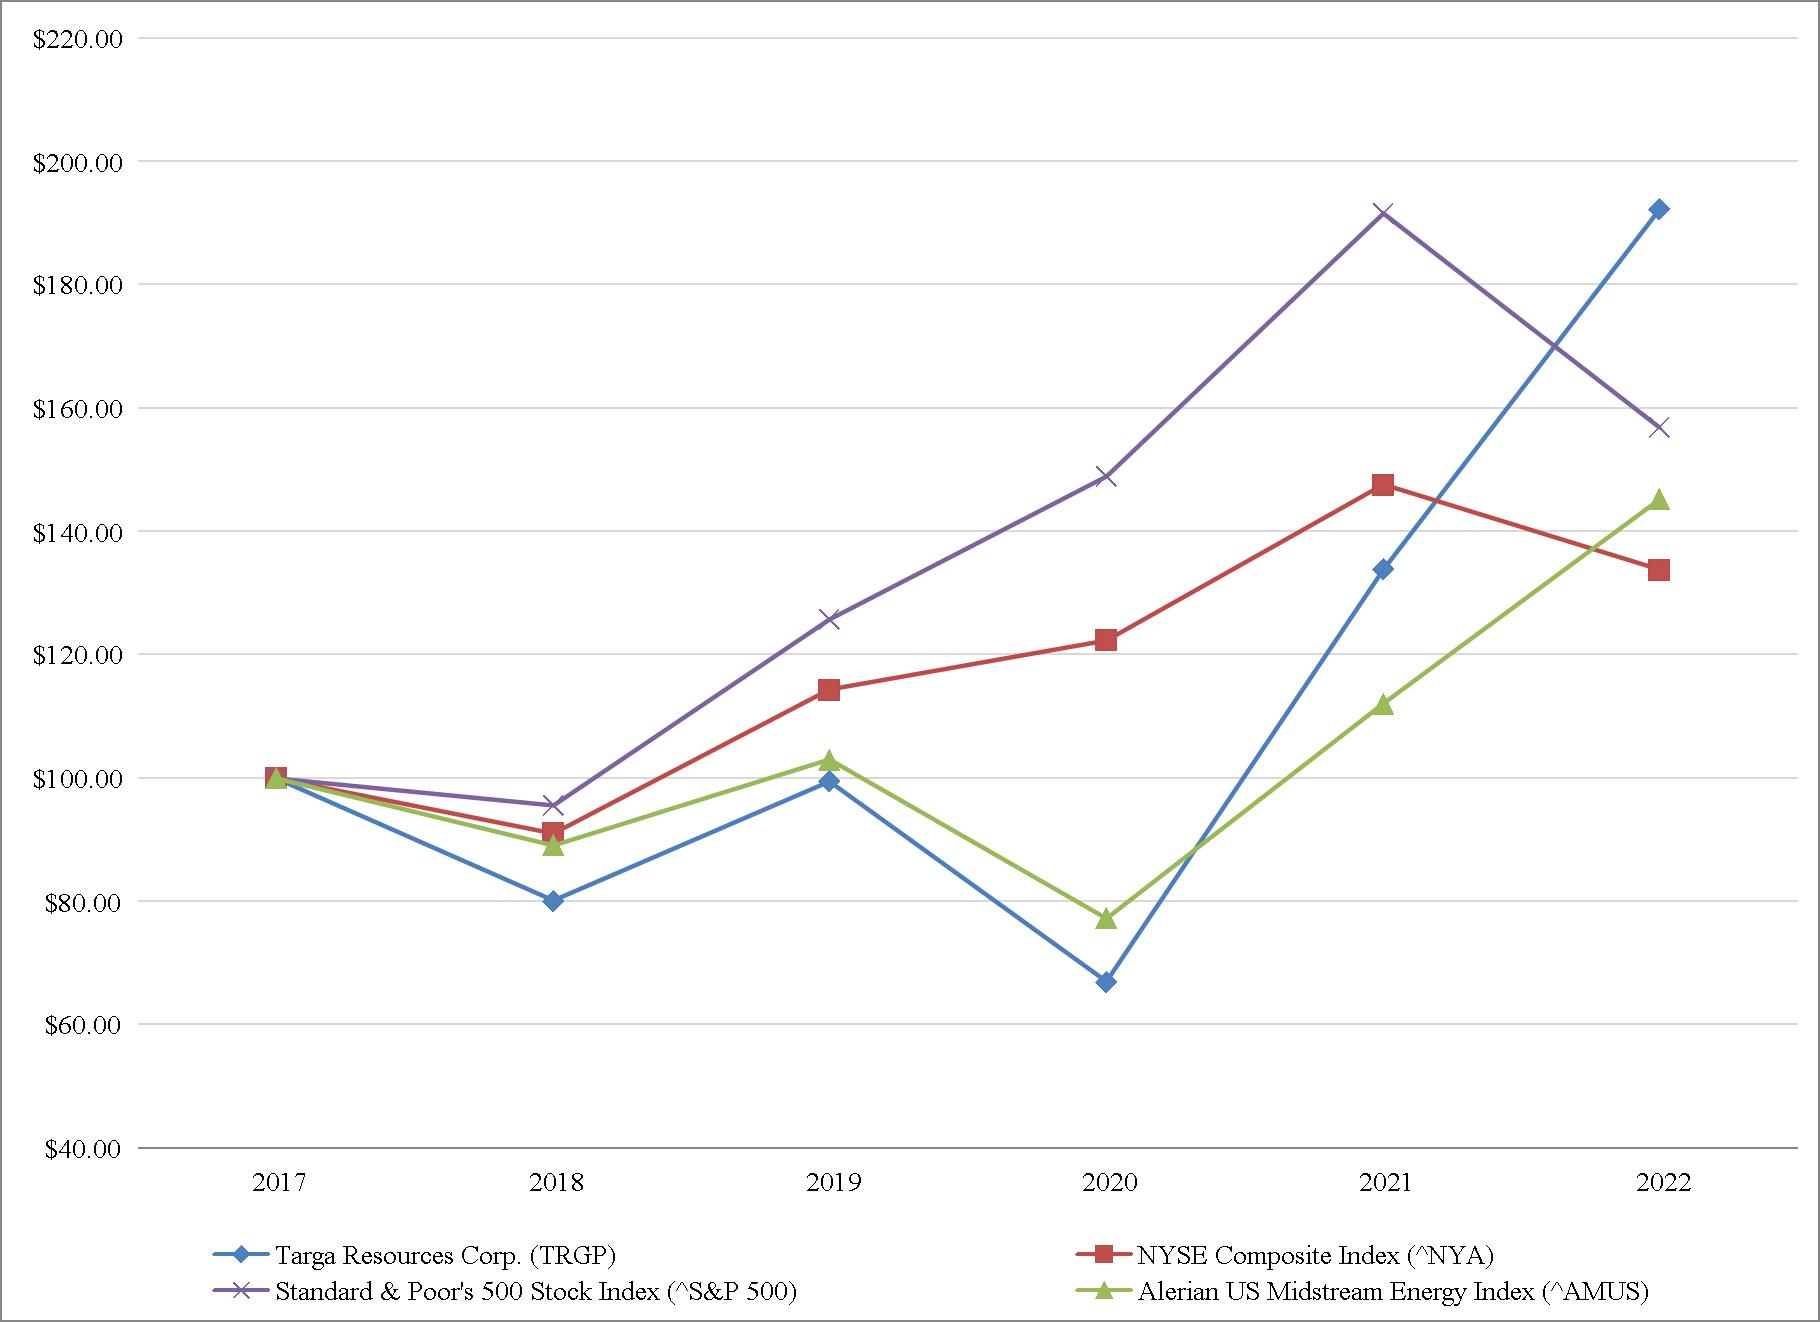][added: ]
| | | [removed: 2017 | | | |] 2018 | | | | 2019 | | | | 2020 | | | | 2021 | | | | 2022 | | | [added: | 2023 | | |]
There were no sales of unregistered equity securities for the year ended December 31, [removed: 2022.][added: 2023.]
Includes [removed: 395,798] [added: 475,040] shares purchased under our [removed: $500 million common share repurchase program,] [added: 2023 Share Repurchase Program,] as well as [removed: 74,273] [added: 2,123] shares that were withheld by us to satisfy tax withholding obligations of certain of our officers, directors and key employees that arose upon the lapse of restrictions on restricted stock.
We [removed: may discontinue this share repurchase program at any time and] are not obligated to repurchase any specific dollar amount or number of [removed: shares.][added: shares under the 2023 Share Repurchase Program and may discontinue the program at any time.]
| Targa Resources Corp. | | $ | 100.00 | | | $ | 124.19 | | | $ | 83.58 | | | $ | 167.16 | | | $ | 240.00 | | | $ | 290.34 | |
| S&P 500 Index | | $ | 100.00 | | | $ | 131.49 | | | $ | 155.68 | | | $ | 200.37 | | | $ | 164.08 | | | $ | 207.21 | |
| AMUS Index | | $ | 100.00 | | | $ | 115.56 | | | $ | 86.72 | | | $ | 125.75 | | | $ | 162.92 | | | $ | 194.13 | |
| October 1, 2023 - October 31, 2023 | | | 109,772 | | | $ | 81.82 | | | | 108,550 | | | $ | 801,820 | |
| November 1, 2023 - November 30, 2023 | | | 92,066 | | | $ | 87.74 | | | | 91,165 | | | $ | 793,820 | |
| December 1, 2023 - December 31, 2023 | | | 275,325 | | | $ | 86.23 | | | | 275,325 | | | $ | 770,080 | |
In May 2023, our Board of Directors approved the 2023 Share Repurchase Program for the repurchase of up to $1.0 billion of our outstanding common stock.
During the second quarter of 2023, we exhausted the 2020 Share Repurchase Program.
On October 12, 2022, we were added to the Standard & Poor's 500 Stock Index (the "S&P 500 Index").
We replaced the NYSE Composite Index (the “NYSE Index”) with the S&P 500 Index, as we believe this index is a more relevant benchmark to measure the Company's performance.
We have continued to present the NYSE Index in this Annual Report for 2022 as a transitional measure.
| Targa Resources Corp. | | $ | 100.00 | | | $ | 80.09 | | | $ | 99.46 | | | $ | 66.93 | | | $ | 133.87 | | | $ | 192.20 | |
| NYSE Index | | $ | 100.00 | | | $ | 91.05 | | | $ | 114.28 | | | $ | 122.26 | | | $ | 147.54 | | | $ | 133.75 | |
| S&P 500 Index | | $ | 100.00 | | | $ | 95.62 | | | $ | 125.72 | | | $ | 148.85 | | | $ | 191.58 | | | $ | 156.88 | |
| AMUS Index | | $ | 100.00 | | | $ | 89.09 | | | $ | 102.95 | | | $ | 77.26 | | | $ | 112.04 | | | $ | 145.15 | |
| October 1, 2022 - October 31, 2022 | | | 135,863 | | | $ | 62.51 | | | | 61,845 | | | $ | 167,765 | |
| November 1, 2022 - November 30, 2022 | | | 165,697 | | | $ | 72.53 | | | | 165,442 | | | $ | 155,763 | |
| December 1, 2022 - December 31, 2022 | | | 168,511 | | | $ | 71.22 | | | | 168,511 | | | $ | 173,762 | |
Item 9A. Controls and Procedures.
3 rewritten, 1 added, 5 removed, 8 unchanged
Based on such evaluation, our Chief Executive Officer and Chief Financial Officer have concluded that, as of December 31, [removed: 2022,] [added: 2023,] our disclosure controls and procedures were effective to provide reasonable assurance that information required to be disclosed in our reports filed or submitted under the Exchange Act is (i) recorded, processed, summarized and reported within the time periods specified in the rules and [removed: forms of the SEC and (ii) accumulated and communicated to management, including our Chief Executive Officer and Chief Financial Officer, as appropriate, to allow for timely decisions regarding required disclosure.]
Management concluded that our internal control over financial reporting was effective as of December 31, [removed: 2022.][added: 2023.]
[removed: Other than as set forth above, there] [added: There] have been no changes in our internal control over financial reporting during [removed: our most recent fiscal] [added: the] quarter ended December 31, [removed: 2022] [added: 2023,] that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
forms of the SEC and (ii) accumulated and communicated to management, including our Chief Executive Officer and Chief Financial Officer, as appropriate, to allow for timely decisions regarding required disclosure.
In July 2022, we completed the Delaware Basin Acquisition.
The Delaware Basin Acquisition constituted approximately 2% of total consolidated revenues for the year ended December 31, 2022 and approximately 10% of total consolidated assets at December 31, 2022.
Management’s assessment of and conclusion on the effectiveness of internal control over financial reporting as of December 31, 2022 excluded the Delaware Basin Acquisition.
This exclusion is in accordance with the SEC guidance that an assessment of recent business
combinations may be omitted from management’s assessment of internal control over financial reporting for one year following the acquisition.
Item 9B. Other Information.
0 rewritten, 2 added, 1 removed, 0 unchanged
On November 13, 2023, Julie H.
Boushka, our Senior Vice President and Chief Accounting Officer, adopted a Rule 10b5-1 trading arrangement that is intended to satisfy the affirmative defense of Rule 10b5-1(c) for the sale of up to 10,000 shares of our common stock until March 5, 2025.
None.
Item 10. Directors, Executive Officers and Corporate Governance.
1 rewritten, 166 added, 0 removed, 0 unchanged
The information required in response to this item [added: not otherwise provided herein] will be set forth in our definitive proxy statement for the [removed: 2023] [added: 2024] annual meeting of stockholders and is incorporated herein by reference.
The Board of Directors of the Company and the executive officers of the Company are:
| | | |
| --- | --- | --- |
| Name | Age (1) | Position |
| Matthew J. Meloy | 45 | Chief Executive Officer and Director |
| Patrick J. McDonie | 63 | President – Gathering and Processing |
| D. Scott Pryor | 60 | President – Logistics and Transportation |
| Robert M. Muraro | 47 | Chief Commercial Officer |
| Jennifer R. Kneale | 45 | Chief Financial Officer |
| Gerald R. Shrader | 64 | Executive Vice President, General Counsel and Secretary |
| G. Clark White | 64 | Executive Vice President - Operations |
| Julie H. Boushka | 60 | Senior Vice President and Chief Accounting Officer |
| Paul W. Chung | 63 | Chairman of the Board of Directors |
| Joe Bob Perkins | 63 | Director |
| Rene R. Joyce | 76 | Director |
| Charles R. Crisp | 76 | Director |
| Ershel C. Redd Jr. | 75 | Director |
| Laura C. Fulton | 60 | Director |
| Waters S. Davis, IV | 70 | Director |
| Robert B. Evans | 75 | Director |
| Beth A. Bowman | 67 | Director |
| Lindsey M. Cooksen | 41 | Director |
(1)
Ages as of December 31, 2023.
Matthew J.
Meloy has served as Chief Executive Officer and a director of the Company since March 1, 2020.
He also served as a director of the General Partner between March 2020 and May 2021.
Mr. Meloy has also served as Chief Executive Officer of the General Partner since March 2020.
Mr. Meloy previously served as President of the Company and the General Partner between March 2018 and March 2020.
Mr. Meloy also served as Executive Vice President and Chief Financial Officer of the Company and the General Partner between May 2015 and February 2018.
He also served as Treasurer of the Company and the General Partner until December 2015.
Mr. Meloy previously served as Senior Vice President, Chief Financial Officer and Treasurer of the Company between October 2010 and May 2015 and of the General Partner between December 2010 and May 2015.
He also served as Vice President—Finance and Treasurer of the Company between April 2008 and October 2010, and as Director, Corporate Development of the Company between March 2006 and March 2008 and of the General Partner between March 2006 and March 2008.
He served as Vice President—Finance and Treasurer of the General Partner between April 2008 and December 15, 2010.
Mr. Meloy was with The Royal Bank of Scotland in the structured finance group, focusing on the energy sector from October 2003 to March 2006.
Mr. Meloy’s extensive knowledge of the Company’s operational and strategic initiatives and capital investment program, attained from his service as President for two years and Chief Financial Officer for eight years, combined with his experience in the finance industry, brings operational, financial and capital markets experience to the Board.
Patrick J.
McDonie has served as President—Gathering and Processing of the Company and the General Partner since March 2018.
Mr. McDonie previously served as Executive Vice President—Southern Field Gathering and Processing of the Company and the General Partner between November 2015 and February 2018.
He also served as President of Atlas Pipeline Partners GP LLC (“Atlas”), which was acquired by the Partnership in February 2015, between October 2013 and February 2015.
An excerpt. Shown here: all 1 rewritten, 40 of 166 added and all 0 removed. The counts are complete. For every sentence, read Item 10. Directors, Executive Officers and Corporate Governance. in the FY2023 filing and the FY2021 filing.
Item 11. Executive Compensation
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required in response to this item will be set forth in our definitive proxy statement for the [removed: 2023] [added: 2024] annual meeting of stockholders and is incorporated herein by reference.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required in response to this item will be set forth in our definitive proxy statement for the [removed: 2023] [added: 2024] annual meeting of stockholders and is incorporated herein by reference.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required in response to this item will be set forth in our definitive proxy statement for the [removed: 2023] [added: 2024] annual meeting of stockholders and is incorporated herein by reference.
Item 14. Principal Accounting Fees and Services
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required in response to this item will be set forth in our definitive proxy statement for the [removed: 2023] [added: 2024] annual meeting of stockholders and is incorporated herein by reference.
Item 15. Exhibits, Financial Statement Schedules
97 rewritten, 7 added, 25 removed, 157 unchanged
| 3.4 | | [removed: [Amended] [added: [Third Amended] and Restated Bylaws of Targa Resources Corp. (incorporated by reference to Exhibit [removed: 3.2] [added: 3.1] to Targa Resources Corp.’s Current Report on Form 8-K filed December [removed: 16, 2010] [added: 12, 2023] (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000095012310114218/h78297exv3w2.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312523293420/d583397dex31.htm)] |
| [removed: 3.5] [added: 10.15+] | | [First Amendment to the [removed: Amended and Restated Bylaws of] Targa Resources Corp. [added: Amended and Restated Stock Incentive Plan] (incorporated by reference to Exhibit [removed: 3.1] [added: 10.16] to Targa Resources Corp.’s [removed: Current] [added: Annual] Report on Form [removed: 8-K] [added: 10-K] filed [removed: January 15, 2016] [added: February 18, 2021] (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312516430392/d10246dex31.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459021006640/trgp-ex1016_1219.htm)] |
| [removed: 3.6] [added: 10.2+] | | [Second Amended and Restated [removed: Bylaws of] Targa Resources Corp. [added: 2010 Stock Incentive Plan, as amended and restated effective August 1, 2023] (incorporated by reference to Exhibit [removed: 3.4] [added: 10.1] to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed [removed: May 5, 2022] [added: August 3, 2023] (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022018168/trgp-ex34_534.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000095017023037748/trgp-ex10_1.htm)] |
| 4.2 | | [Registration Rights Agreement, dated March 16, 2016, by and among Targa Resources Corp. and the purchasers named on Schedule A thereto (incorporated by reference to Exhibit [removed: 4.1] [added: 4.2] to Targa Resources Corp.’s Current Report on Form 8-K/A filed March 17, 2016 (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312516508783/d198929dex41.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312516508783/d198929dex42.htm)] |
| 4.3 | | [Amendment No. 1 to the Registration Rights Agreement dated March 16, 2016, dated September 13, 2016, among Targa Resources Corp. and Stonepeak Target Holdings, LP and Stonepeak Target Upper Holdings LLC (incorporated by reference to Exhibit [removed: 4.3] [added: 4.2] to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed November 4, 2016 (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459016027687/trgp-ex43_523.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459016027687/trgp-ex42_524.htm)] |
| [removed: 4.4] [added: 10.32] | | [removed: [Registration Rights] [added: [Term Loan] Agreement, dated [removed: March 16, 2016, by and] [added: as of July 12, 2022,] among Targa Resources [removed: Corp.] [added: Corp., Mizuho Bank, Ltd., as administrative agent] and [added: a lender, and] the [removed: purchasers named on Schedule A] [added: other lenders parties] thereto (incorporated by reference to Exhibit [removed: 4.2] [added: 10.1] to Targa Resources Corp.’s Current Report on Form [removed: 8-K/A] [added: 8-K] filed [removed: March 17, 2016] [added: July 12, 2022] (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312516508783/d198929dex42.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312522192023/d268181dex101.htm)] |
| [removed: 4.5] [added: 10.9+] | | [removed: [Amendment No. 1] [added: [Omnibus Amendment] to [removed: the Registration Rights Agreement] [added: Restricted Stock Unit Grant Agreements,] dated March [removed: 16, 2016, dated September 13, 2016, among Targa Resources Corp. and Stonepeak Target Holdings, LP and Stonepeak Target Upper Holdings LLC] [added: 29, 2023] (incorporated by reference to Exhibit [removed: 4.2] [added: 10.1] to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed [removed: November] [added: May] 4, [removed: 2016] [added: 2023] (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459016027687/trgp-ex42_524.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000095017023017657/trgp-ex10_1.htm)] |
| [removed: 4.6] [added: 4.55] | | [removed: [Board Representation and Observation Rights Agreement, dated as] [added: [Form] of [removed: March 16, 2016, by and between Targa Resources Corp. and Stonepeak Target Holdings LP] [added: Notes (included in Exhibit 4.54 hereto)] (incorporated by reference to Exhibit 4.3 to Targa Resources Corp.’s Current Report on Form [removed: 8-K/A] [added: 8-K] filed [removed: March 17, 2016] [added: April 6, 2022] (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312516508783/d198929dex43.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312522097513/d343533dex42.htm)] |
| [removed: 4.7] [added: 4.5] | | [removed: [Warrant Agreement,] [added: [Parent Guarantee] dated as of [removed: March 16, 2016,] [added: February 18, 2022,] by and among Targa Resources [removed: Corp., Computershare Inc.] [added: Corp.] and [removed: Computershare Trust Company, N.A.] [added: certain of its subsidiaries] (incorporated by reference to Exhibit [removed: 4.4] [added: 4.1] to Targa Resources Corp.’s Current Report on Form [removed: 8-K/A] [added: 8-K] filed [removed: March 17, 2016] [added: February 23, 2022] (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312516508783/d198929dex44.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312522050041/d305853dex41.htm)] |
| [removed: 4.8] [added: 4.4] | | [Description of Securities Registered Under Section 12 of the Exchange Act (incorporated by reference to Exhibit 4.8 to Targa Resources Corp.’s Annual Report on Form 10-K filed February 20, 2020 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459020005592/trgp-ex48_735.htm) |
| [removed: 4.9] [added: 4.53] | | [removed: [Parent Guarantee] [added: [Indenture,] dated as of [removed: February 18,] [added: April 6,] 2022, [removed: by and] among Targa Resources [removed: Corp.] [added: Corp., as issuer, the guarantors named therein] and [removed: certain of its subsidiaries] [added: U.S. Bank Trust Company, National Association, as trustee] (incorporated by reference to Exhibit 4.1 to Targa Resources Corp.’s Current Report on Form 8-K filed [removed: February 23,] [added: April 6,] 2022 (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312522050041/d305853dex41.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312522097513/d343533dex41.htm)] |
| [removed: 4.10] [added: 4.6] | | [Indenture dated as of October 17, 2017 among the Issuers and the Guarantors and U.S. Bank National Association, as trustee (incorporated by reference to Exhibit 4.1 to Targa Resources Partners LP’s Current Report on Form 8-K filed October 17, 2017 (File No. 001-33303)).](https://www.sec.gov/Archives/edgar/data/1379661/000119312517311802/d475382dex41.htm) |
| [removed: 4.11] [added: 4.8] | | [Supplemental Indenture dated [removed: December 18, 2017] [added: January 9, 2018] to Indenture dated October 17, 2017, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit [removed: 10.66] [added: 10.67] to Targa Resources Corp.’s Annual Report on Form 10-K filed February 16, 2018 (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459018002330/trgp-ex1066_291.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459018002330/trgp-ex1067_289.htm)] |
| [removed: 4.12] [added: 4.15] | | [Supplemental Indenture dated January [removed: 9, 2018] [added: 28, 2022] to Indenture dated October 17, 2017, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit [removed: 10.67] [added: 10.43] to Targa Resources Corp.’s Annual Report on Form 10-K filed February [removed: 16, 2018] [added: 24, 2022] (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459018002330/trgp-ex1067_289.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1043_131.htm)] |
| [removed: 4.13] [added: 4.9] | | [Supplemental Indenture dated July 24, 2018 to Indenture dated October 17, 2017, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.9 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed August 9, 2018 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459018020681/trgp-ex109_264.htm) |
| [removed: 4.14] [added: 4.10] | | [Supplemental Indenture dated July 19, 2019 to Indenture dated October 17, 2017, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.6 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed August 9, 2019 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459019030955/trgp-ex106_435.htm) |
| [removed: 4.15] [added: 4.11] | | [Supplemental Indenture dated February 20, 2020 to Indenture dated October 17, 2017, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.5 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed May 7, 2020 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459020022780/trgp-ex105_262.htm) |
| [removed: 4.16] [added: 4.12] | | [Supplemental Indenture dated September 17, 2020 to Indenture dated October 17, 2017, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.6 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed November 5, 2020 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459020051164/trgp-ex106_93.htm) |
| [removed: 4.17] [added: 4.13] | | [Supplemental Indenture dated September 17, 2021 to Indenture dated October 17, 2017, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.2 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed November 4, 2021 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459021054348/trgp-ex102_70.htm) |
| [removed: 4.18] [added: 4.14] | | [Supplemental Indenture dated November 30, 2021 to Indenture dated October 17, 2017, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.42 to Targa Resources Corp.’s Annual Report on Form 10-K filed February 24, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1042_76.htm) |
| [removed: 4.19] [added: 4.25] | | [Supplemental Indenture dated January 28, 2022 to Indenture dated [removed: October] [added: January] 17, [removed: 2017,] [added: 2019,] among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit [removed: 10.43] [added: 10.61] to Targa Resources Corp.’s Annual Report on Form 10-K filed February 24, 2022 (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1043_131.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1061_129.htm)] |
| [removed: 4.20] [added: 4.16] | | [Supplemental Indenture dated June 17, 2022 to Indenture dated October 17, 2017 among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.1 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed August 4, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022027962/trgp-ex101_390.htm) |
| [removed: 4.21] [added: 4.17] | | [Supplemental Indenture dated August 2, 2022 to Indenture dated October 17, 2017 among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.1 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed November 3, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000095017022021813/trgp-ex10_1.htm) |
| [removed: 4.22] [added: 4.19] | | [Indenture dated as of January 17, 2019 among the Issuers, the Guarantors and U.S. Bank National Association, as trustee (incorporated by reference to Exhibit 4.1 to Targa Resources Partners LP’s Current Report on Form 8-K filed January 23, 2019 (File No. 001-33303)).](https://www.sec.gov/Archives/edgar/data/1379661/000119312519014870/d689562dex41.htm) |
| [removed: 4.23] [added: 4.22] | | [Supplemental Indenture dated [removed: July 19, 2019] [added: September 17, 2020] to Indenture dated January 17, 2019, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.8 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed [removed: August 9, 2019] [added: November 5, 2020] (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459019030955/trgp-ex108_434.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459020051164/trgp-ex108_92.htm)] |
| [removed: 4.24] [added: 4.21] | | [Supplemental Indenture dated February 20, 2020 to Indenture dated January 17, 2019, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.7 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed May 7, 2020 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459020022780/trgp-ex107_260.htm) |
| [removed: 4.25] [added: 4.31] | | [Supplemental Indenture dated September 17, 2020 to Indenture dated [removed: January 17,] [added: November 27,] 2019, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit [removed: 10.8] [added: 10.9] to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed November 5, 2020 (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459020051164/trgp-ex108_92.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459020051164/trgp-ex109_90.htm)] |
| [removed: 4.26] [added: 4.23] | | [Supplemental Indenture dated September 17, 2021 to Indenture dated January 17, 2019, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.4 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed November 4, 2021 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459021054348/trgp-ex104_68.htm) |
| [removed: 4.27] [added: 4.24] | | [Supplemental Indenture dated November 30, 2021 to Indenture dated January 17, 2019, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.60 to Targa Resources Corp.’s Annual Report on Form 10-K filed February 24, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1060_75.htm) |
| [removed: 4.28] [added: 4.34] | | [Supplemental Indenture dated January 28, 2022 to Indenture dated [removed: January 17,] [added: November 27,] 2019, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit [removed: 10.61] [added: 10.68] to Targa Resources Corp.’s Annual Report on Form 10-K filed February 24, 2022 (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1061_129.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1068_128.htm)] |
| [removed: 4.29] [added: 4.26] | | [Supplemental Indenture dated June 17, 2022 to Indenture dated January 17, 2019 among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.2 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed August 4, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022027962/trgp-ex102_389.htm) |
| [removed: 4.30] [added: 4.27] | | [Supplemental Indenture dated August 2, 2022 to Indenture dated January 17, 2019 among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.2 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed November 3, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000095017022021813/trgp-ex10_2.htm) |
| [removed: 4.31] [added: 4.29] | | [Indenture dated as of November 27, 2019 among the Issuers, the Guarantors and U.S. Bank National Association, as trustee (incorporated by reference to Exhibit 4.1 to Targa Resources Partners LP’s Current Report on Form 8-K filed December 3, 2019 (File No. 001-33303)).](https://www.sec.gov/Archives/edgar/data/1379661/000119312519305360/d842878dex41.htm) |
| [removed: 4.32] [added: 4.30] | | [Supplemental Indenture dated February 20, 2020 to Indenture dated November 27, 2019, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.8 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed May 7, 2020 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459020022780/trgp-ex108_259.htm) |
| [removed: 4.33] [added: 4.39] | | [Supplemental Indenture dated September 17, 2020 to Indenture dated [removed: November 27, 2019,] [added: August 18, 2020,] among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit [removed: 10.9] [added: 10.10] to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed November 5, 2020 (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459020051164/trgp-ex109_90.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459020051164/trgp-ex1010_89.htm)] |
| [removed: 4.34] [added: 4.32] | | [Supplemental Indenture dated September 17, 2021 to Indenture dated November 27, 2019, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.5 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed November 4, 2021 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459021054348/trgp-ex105_67.htm) |
| [removed: 4.35] [added: 4.41] | | [Supplemental Indenture dated November 30, 2021 to Indenture dated [removed: November 27, 2019,] [added: August 18, 2020,] among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit [removed: 10.67] [added: 10.73] to Targa Resources Corp.’s Annual Report on Form 10-K filed February 24, 2022 (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1067_72.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1073_73.htm)] |
| [removed: 4.36] [added: 4.42] | | [Supplemental Indenture dated January 28, 2022 to Indenture dated [removed: November 27, 2019,] [added: August 18, 2020,] among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit [removed: 10.68] [added: 10.74] to Targa Resources Corp.’s Annual Report on Form 10-K filed February 24, 2022 (File No. [removed: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1068_128.htm)] [added: 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1074_127.htm)] |
| [removed: 4.37] [added: 4.35] | | [Supplemental Indenture dated June 17, 2022 to Indenture dated November 27, 2019 among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.3 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed August 4, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022027962/trgp-ex103_388.htm) |
| [removed: 4.38] [added: 4.36] | | [Supplemental Indenture dated August 2, 2022 to Indenture dated November 27, 2019 among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 10.3 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed November 3, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000095017022021813/trgp-ex10_3.htm) |
| 4.7 | | [Supplemental Indenture dated December 18, 2017 to Indenture dated October 17, 2017, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary](https://www.sec.gov/Archives/edgar/data/1389170/000156459018002330/trgp-ex1066_291.htm) |
| 4.20 | | [Supplemental Indenture dated July 19, 2019 to Indenture dated January 17, 2019, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and](https://www.sec.gov/Archives/edgar/data/1389170/000156459019030955/trgp-ex108_434.htm) |
| 4.28 | | [Supplemental Indenture dated April 12, 2023 to Indenture dated January 17, 2019 among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary Guarantors and U.S. Bank National Association (incorporated by reference to Exhibit 4.6 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed May 4, 2023 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000095017023017657/trgp-ex4_6.htm) |
| 4.33 | | [Supplemental Indenture dated November 30, 2021 to Indenture dated November 27, 2019, among the Guaranteeing Subsidiary, Targa Resources Partners LP, Targa Resources Partners Finance Corporation, the other Subsidiary](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex1067_72.htm) |
| 4.62 | | [Sixth Supplemental Indenture, dated as of April 12, 2023, among Targa Resources Corp., as issuer, the guarantors named therein and U.S. Bank Trust Company, National Association, as trustee (incorporated by reference to Exhibit 4.4 to Targa Resources Corp.’s Quarterly Report on Form 10-Q filed May 4, 2023 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000095017023017657/trgp-ex4_4.htm) |
| 10.13+* | | [Form of Restricted Stock Unit Agreement under Targa Resources Corp. 2010 Stock Incentive Plan.](https://www.sec.gov/Archives/edgar/data/1389170/000095017024015841/trgp-ex10_13.htm) |
| 97.1* | | [Targa Resources Corp. Incentive Compensation Recovery Policy, effective October 2, 2023.](https://www.sec.gov/Archives/edgar/data/1389170/000095017024015841/trgp-ex97_1.htm) |
| | | |
| --- | --- | --- |
| 10.18 | | [Registration Rights Agreement dated as of January 17, 2019 among the Issuers, the Guarantors and Merrill Lynch, Pierce, Fenner & Smith Incorporated, as representative of the several Initial Purchasers party thereto (incorporated by](https://www.sec.gov/Archives/edgar/data/1379661/000119312519014870/d689562dex42.htm) |
| 10.24+ | | [Targa Resources Partners LP Indemnification Agreement for Robert B. Evans dated February 14, 2007 (incorporated by reference to Exhibit 10.11 to Targa Resources Partners LP’s Annual Report on Form 10-K filed April 2, 2007 (File No. 001-33303)).](https://www.sec.gov/Archives/edgar/data/1379661/000095012907001822/h44950exv10w11.htm) |
| 10.27+ | | [Indemnification Agreement by and between Targa Resources Corp. and D. Scott Pryor, dated November 12, 2015 (incorporated by reference to Exhibit 10.1 to Targa Resources Corp.’s Current Report on Form 8-K filed November 16, 2015 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312515378560/d62331dex101.htm) |
| 10.28+ | | [Indemnification Agreement by and between Targa Resources Corp. and Patrick J. McDonie, dated November 12, 2015 (incorporated by reference to Exhibit 10.2 to Targa Resources Corp.’s Current Report on Form 8-K filed November 16, 2015 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312515378560/d62331dex102.htm) |
| 10.29+ | | [Indemnification Agreement by and between Targa Resources Corp. and Clark White, dated November 12, 2015 (incorporated by reference to Exhibit 10.4 to Targa Resources Corp.’s Current Report on Form 8-K filed November 16, 2015 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312515378560/d62331dex104.htm) |
| 10.32+ | | [Indemnification Agreement by and between Targa Resources Corp. and Beth A. Bowman, dated September 7, 2018 (incorporated by reference to Exhibit 10.1 to Targa Resources Corp.’s Current Report on Form 8-K filed September 11, 2018 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312518270987/d598723dex101.htm) |
| 10.34+ | | [Indemnification Agreement by and between Targa Resources Corp. and Jennifer Kneale, dated July 1, 2016 (incorporated by reference to Exhibit 10.90 to Targa Resources Corp.’s Annual Report on Form 10-K filed February 20, 2020 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459020005592/trgp-ex1090_736.htm) |
| 10.36 | | [Amended and Restated Registration Rights Agreement dated as of October 31, 2005 (incorporated by reference to Exhibit 10.1 to Targa Resources Corp.’s Registration Statement on Form S-1/A filed November 12, 2010 (File No. 333-169277)).](https://www.sec.gov/Archives/edgar/data/1389170/000095012310104672/h75749a3exv10w1.htm) |
| 10.41 | | [Fifth Amendment to Receivables Purchase Agreement, dated December 9, 2016, by and among Targa Receivables LLC, as seller, the Partnership, as servicer, the various conduit purchasers, committed purchasers, purchaser agents and LC participants party thereto and PNC Bank, National Association, as administrator and LC Bank (incorporated by reference to Exhibit 10.1 to Targa Resources Partners LP’s Current Report on Form 8-K filed January 6, 2017 (File No. 001-33303)).](https://www.sec.gov/Archives/edgar/data/1379661/000119312517003195/d284924dex101.htm) |
| 10.42 | | [Seventh Amendment to Receivables Purchase Agreement, dated December 7, 2018, by and among Targa Receivables LLC, as seller, the Partnership, as servicer, the various conduit purchasers, committed purchasers, purchaser agents and LC participants party thereto and PNC Bank, National Association, as administrator and LC Bank (incorporated by reference to Exhibit 10.1 to Targa Resources Partners LP’s Current Report on Form 8-K filed December 10, 2018 (File No. 001-33303)).](https://www.sec.gov/Archives/edgar/data/1379661/000119312518346218/d653818dex101.htm) |
| 10.43 | | [Eighth Amendment to Receivables Purchase Agreement, dated December 6, 2019, by and among Targa Receivables LLC, as seller, the Partnership, as servicer, the various conduit purchasers, committed purchasers, purchaser agents and LC participants party thereto and PNC Bank, National Association, as administrator and LC Bank (incorporated by reference to Exhibit 10.1 to Targa Resources Corp.’s Current Report on Form 8-K filed December 10, 2019 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312519310354/d845460dex101.htm) |
| 10.44 | | [Ninth Amendment to Receivables Purchase Agreement, dated April 22, 2020, by and among Targa Receivables LLC, as seller, Targa Resources Partners LP, as servicer, the various conduit purchasers, committed purchasers, purchaser agents and LC participants party thereto and PNC Bank, National Association, as administrator and LC Bank (incorporated by reference to Exhibit 10.1 to Targa Resources Corp.’s Current Report on Form 8-K filed April 24, 2020 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312520119187/d889904dex101.htm) |
| 10.45 | | [Tenth Amendment to Receivables Purchase Agreement, dated April 21, 2021, by and among Targa Receivables LLC, as seller, Targa Resources Partners LP, as servicer, the various conduit purchasers, committed purchasers, purchaser agents and LC participants party thereto and PNC Bank, National Association, as administrator and LC Bank](https://www.sec.gov/Archives/edgar/data/1389170/000119312521129071/d102268dex101.htm) |
| 10.46 | | [Eleventh Amendment to Receivables Purchase Agreement, dated December 13, 2021, by and among Targa Receivables LLC, as seller, Targa Resources Partners LP, as servicer, the various conduit purchasers, committed purchasers, purchaser agents and LC participants party thereto and PNC Bank, National Association, as administrator and LC Bank (incorporated by reference to Exhibit 10.104 to Targa Resources Corp.’s Annual Report on Form 10-K filed February 24, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000156459022006563/trgp-ex10104_70.htm) |
| 10.47 | | [Twelfth Amendment to Receivables Purchase Agreement, dated April 19, 2022, by and among Targa Receivables LLC, as seller, Targa Resources Partners LP, as servicer, the various conduit purchasers, committed purchasers, purchaser agents and LC participants party thereto and PNC Bank, National Association, as administrator and LC Bank (incorporated by reference to Exhibit 10.1 to Targa Resources Corp.’s Current Report on Form 8-K filed April 22, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312522115194/d946089dex101.htm) |
| 10.48 | | [Thirteenth Amendment to Receivables Purchase Agreement, dated as of September 2, 2022, by and among Targa Receivables LLC, as seller, Targa Resources Partners LP, as servicer, the various conduit purchasers, committed purchasers, purchaser agents and LC participants party thereto and PNC Bank, National Association, as administrator and LC Bank (incorporated by reference to Exhibit 10.1 to Targa Resources Corp.’s Current Report on Form 8-K filed September 6, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312522238889/d366212dex101.htm) |
| 10.49 | | [Term Loan Agreement, dated as of July 12, 2022, among Targa Resources Corp., Mizuho Bank, Ltd., as administrative agent and a lender, and the other lenders parties thereto (incorporated by reference to Exhibit 10.1 to Targa Resources Corp.’s Current Report on Form 8-K filed July 12, 2022 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312522192023/d268181dex101.htm) |
| 10.50 | | [Commitment Increase Request, dated February 23, 2017, by and among Targa Receivables LLC, as seller, the Partnership, as servicer, and PNC Bank, National Association, as administrator, purchaser agent and LC Bank (incorporated by reference to Exhibit 10.1 to Targa Resources Partners LP’s Current Report on Form 8-K filed February 24, 2017 (File No. 001-33303)).](https://www.sec.gov/Archives/edgar/data/1379661/000119312517056346/d350005dex101.htm) |
| 10.51 | | [Commitment Increase Request, dated December 11, 2020, by and among Targa Receivables LLC, as seller, the Partnership, as servicer, and PNC Bank, National Association, as administrator, purchaser agent and LC Bank, and Wells Fargo Bank, National Association, as purchaser agent and LC Participant (incorporated by reference to Exhibit 10.1 to Targa Resources Corp.’s Current Report on Form 8-K filed December 14, 2020 (File No. 001-34991)).](https://www.sec.gov/Archives/edgar/data/1389170/000119312520316958/d95108dex101.htm) |
| 101.CAL* | | Inline XBRL Taxonomy Extension Calculation Linkbase Document |
| 101.DEF* | | Inline XBRL Taxonomy Extension Definition Linkbase Document |
| 101.LAB* | | Inline XBRL Taxonomy Extension Label Linkbase Document |
| 101.PRE* | | Inline XBRL Taxonomy Extension Presentation Linkbase Document |
An excerpt. Shown here: 40 of 97 rewritten, all 7 added and all 25 removed. The counts are complete. For every sentence, read Item 15. Exhibits, Financial Statement Schedules in the FY2023 filing and the FY2021 filing.
Item 16. Form 10-K Summary
40 rewritten, 11 added, 20 removed, 118 unchanged
| Date: February [removed: 22, 2023] [added: 15, 2024] | By: | | */s/ Jennifer R. Kneale* |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed by the following persons on behalf of the registrant and in the capacities indicated on February [removed: 22, 2023.][added: 15, 2024.]
| [Consolidated Balance Sheets as of December 31, [removed: 2022] [added: 2023] and December 31, [removed: 2021](#consolidated_balance_sheets)] [added: 2022](#consolidated_balance_sheets)] | [removed: F-6] [added: F-5] |
| [Consolidated Statements of Operations for the Years Ended December 31, [removed: 2022, 2021,] [added: 2023, 2022] and [removed: 2020](#consolidated_statements_operations)] [added: 2021](#consolidated_statements_operations)] | [removed: F-7] [added: F-6] |
| [Consolidated Statements of Comprehensive Income (Loss) for the Years Ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statements_comprehensive_in)] [added: 2021](#consolidated_statements_comprehensive_in)] | [removed: F-8] [added: F-7] |
| [Consolidated Statements of Changes in Owners' Equity and Series A Preferred Stock for the Years Ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statements_changes_in_owner)] [added: 2021](#consolidated_statements_changes_in_owner)] | [removed: F-9] [added: F-8] |
| [Consolidated Statements of Cash Flows for the Years Ended December 31, [removed: 2022, 2021] [added: 2023, 2022] and [removed: 2020](#consolidated_statements_cash_flows)] [added: 2021](#consolidated_statements_cash_flows)] | [removed: F-11] [added: F-10] |
| [Notes to Consolidated Financial Statements](#notes_to_consolidated_financial_statemen) | [removed: F-12] [added: F-11] |
| [Note 1 ― Organization and Operations](#note_1_organization_operations) | [removed: F-12] [added: F-11] |
| [Note 2 ― Basis of Presentation](#note_2_basis_presentation) | [removed: F-12] [added: F-11] |
| [Note 3 ― Significant Accounting Policies](#note_3_significant_accounting_policies) | [removed: F-12] [added: F-11] |
| [Note 4 ― Acquisitions and Divestitures](#note_4_newlyformed_joint_ventures_acquis) | [removed: F-20] [added: F-19] |
| [Note 5 ― Property, Plant and Equipment and Intangible Assets](#note_6_property_plant_equipment_intangib) | [removed: F-23] [added: F-22] |
| [Note 6 ― Goodwill](#note_7_goodwill) | [removed: F-24] [added: F-23] |
| [Note 7 ― Investment in Unconsolidated Affiliates](#note_8_investments_in_unconsolidated_aff) | [removed: F-25] [added: F-24] |
| [Note 8 ― Debt Obligations](#note_10_debt_obligations) | [removed: F-27] [added: F-26] |
| [Note 9 ― Other Long-term Liabilities](#note_11_other_longterm_liabilities) | [removed: F-32] [added: F-31] |
| [Note 10 ― Leases](#note_12_leases) | [removed: F-34] [added: F-32] |
| [Note 11 ― Preferred Stock](#note_13_preferred_stock) | [removed: F-35] [added: F-33] |
| [Note 12 ― Common Stock and Related Matters](#note_14_common_stock_related_matters) | [removed: F-36] [added: F-34] |
| [Note 13 ― Earnings Per Common Share](#note_16_earnings_per_common_share) | [removed: F-37] [added: F-35] |
| [Note 14 ― Derivative Instruments and Hedging Activities](#note_17_derivative_instruments_hedging_a) | [removed: F-37] [added: F-36] |
| [Note 15 ― Fair Value Measurements](#note_18_fair_value_measurements) | [removed: F-40] [added: F-38] |
| [Note 16 ― Related Party Transactions](#note_19_related_party_transactions) | [removed: F-42] [added: F-40] |
| [Note 17 ― Commitments](#note_20_commitments_leases) | [removed: F-43] [added: F-41] |
| [Note 18 ― Contingencies](#note_21_contingencies_open_for_legal_upd) | [removed: F-43] [added: F-41] |
| [Note 19 ― Revenue](#note_20_revenue) | [removed: F-44] [added: F-42] |
| [Note [removed: 21] [added: 20] ― Income Taxes](#note_25_income_taxes) | [removed: F-44] [added: F-42] |
| [Note [removed: 22] [added: 21] ― Supplemental Cash Flow Information](#note_26_supplemental_cash_flow_informati) | [removed: F-46] [added: F-44] |
| [Note [removed: 23] [added: 22] ― Compensation Plans](#note_27_compensation_plans) | [removed: F-46] [added: F-44] |
| [Note [removed: 24] [added: 23] ― Segment Information](#note_28_segment_information) | [removed: F-48] [added: F-46] |
Based on that evaluation, management has concluded that the internal control over financial reporting was effective as of December 31, [removed: 2022.][added: 2023.]
The effectiveness of our internal control over financial reporting as of December 31, [removed: 2022] [added: 2023] has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report which appears on page F-3.
We have audited the accompanying consolidated balance sheets of Targa Resources Corp. and its subsidiaries (the “Company”) as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the related consolidated statements of operations, of comprehensive income (loss), of changes in owners’ equity and [removed: Series] [added: series] A preferred stock and of cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] including the related notes (collectively referred to as the “consolidated financial statements”).
We also have audited the Company's internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control - Integrated Framework* (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2022] [added: 2023] in conformity with accounting principles generally accepted in the United States of America.
Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in *Internal Control - Integrated Framework* (2013) issued by the COSO.
A company’s internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (ii) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of [removed: management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.]
The principal considerations for our determination that performing procedures relating to the valuation of [removed: the customer relationships intangible asset acquired in the Delaware Basin Acquisition] [added: derivative instruments and hedging activities] is a critical audit matter are (i) the significant judgment by management when developing the fair value estimate of the [removed: customer relationships intangible asset;] [added: assets and liabilities from risk management activities;] (ii) a high degree of auditor [removed: judgment, subjectivity,] [added: judgment] and effort in performing procedures and evaluating management’s significant assumptions related to [removed: future revenues, discount rate, and customer attrition rates;] [added: commodity prices;] and (iii) the audit effort involved the use of professionals with specialized skill and knowledge.
[removed: /s/PricewaterhouseCoopers] [added: /s/ PricewaterhouseCoopers] LLP
| Robert B. Evans | | |
management and directors of the company; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
*Valuation of Derivative Instruments and Hedging Activities*
As described in Note 14 to the consolidated financial statements, the primary purpose of management’s commodity risk management activities is to manage the Company’s exposure to commodity price risk and reduce volatility in operating cash flow due to fluctuations in commodity prices.
Management has entered into derivative instruments to hedge the commodity price risks.
As of December 31, 2023, there were $145.2 million of assets from risk management activities and $70.8 million of liabilities from risk management activities.
The fair value of the derivative instruments was determined by the use of present value methods with assumptions about commodity prices based on those observed in underlying markets.
These procedures included testing the effectiveness of controls relating to the valuation of the assets and liabilities from risk management activities, including controls over management’s model, data and assumptions.
These procedures also included, among others, (i) the involvement of professionals with specialized skill and knowledge to assist in developing independent fair value estimates for a sample of the assets and liabilities from risk management activities and (ii) comparing the independent fair value estimates to management’s fair value estimates to evaluate the reasonableness of management’s fair value estimates.
Developing the independent fair value estimates involved testing the completeness and accuracy of data provided by management and independently developing the commodity prices assumption.
February 15, 2024
| Robert B. Evans. | | |
| [Note 20 ― Other Operating (Income) Expense](#note_24_or_operating_income_expense) | F-44 |
In July 2022, we completed the Delaware Basin Acquisition.
The Delaware Basin Acquisition constituted approximately 2% of total consolidated revenues for the year ended December 31, 2022 and approximately 10% of total consolidated assets at December 31, 2022.
Management’s assessment of and conclusion on the effectiveness of internal control over financial reporting as of December 31, 2022 excluded the Delaware Basin Acquisition.
This exclusion is in accordance with the SEC guidance that an assessment of recent business combinations may be omitted from management’s assessment of internal control over financial reporting for one year following the acquisition.
As described in Management’s Report on Internal Control Over Financial Reporting, management has excluded Lucid Energy Delaware, LLC (“Delaware Basin Acquisition”) from its assessment of internal control over financial reporting as of December 31, 2022 because it was acquired by the Company in a purchase business combination during 2022.
We have also excluded Delaware Basin Acquisition from our audit of internal control over financial reporting.
Delaware Basin Acquisition is a wholly-owned subsidiary whose total assets and total revenues excluded from management’s assessment and our audit of internal control over financial reporting represent approximately 10% and 2%, respectively, of the related consolidated financial statement amounts as of and for the year ended December 31, 2022.
*Delaware Basin Acquisition – Valuation of the Customer Relationships Intangible Asset*
As described in Note 4 to the consolidated financial statements, the Company completed the acquisition of all of the interests in Lucid Energy Delaware, LLC (“Lucid”) for approximately $3.5 billion in cash (the “Delaware Basin Acquisition”).
The acquisition resulted in a $1,882.0 million customer relationships intangible asset being recorded.
The fair value of customer relationships was determined at the date of acquisition based on the present value of estimated future cash flows using the multi-period excess earnings method.
The significant assumptions used by management in determining the fair value of customer relationships intangible assets include future revenues, discount rate, and customer attrition rates.
These procedures included testing the effectiveness of controls relating to the acquisition accounting, including controls over management’s valuation of the acquired customer relationships intangible asset and controls over the development of the significant assumptions used by management related to future revenues, discount rate, and customer attrition rates.
These procedures also included, among others (i) reading the purchase agreement; (ii) testing management’s process for developing the fair value estimate of the customer relationships intangible asset; (iii) evaluating the appropriateness of the multi-period excess earnings method; (iv) testing the completeness and accuracy of underlying data used in the multi-period excess earnings method; and (v) evaluating the reasonableness of significant assumptions related to future revenues, discount rate, and customer attrition rates.
Evaluating the reasonableness of management’s significant assumptions related to future revenues involved considering the past performance of the acquired business, consistency with economic and industry forecasts, and whether these assumptions were consistent with evidence obtained in other areas of the audit.
Professionals with specialized skill and knowledge were used to assist in the evaluation of the appropriateness of the Company’s multi-period excess earnings method and the reasonableness of discount rate and customer attrition rates significant assumptions.
February 22, 2023
F-5