 filings.tools
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
99K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
EXECUTIVE SUMMARY
FINANCIAL SUMMARY FOR 2015 (compared to 2014)
| § | Total revenues increased $428.0 million, or 14%, to $3,422.2 million |
|---|
| § | Gross profit increased $270.0 million, or 46%, to $857.5 million |
|---|
| § | Aggregates freight-adjusted revenues increased $318.4 million, or 18%, to $2,112.5 million |
|---|
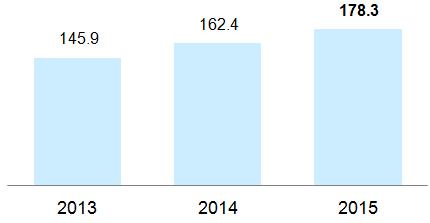
| § | Total shipments increased 10%, or 15.9 million tons to 178.3 million tons; same-store shipments increased 7% |
|---|
| § | Freight-adjusted sales price increased 7% in total and on a same-store basis |
|---|
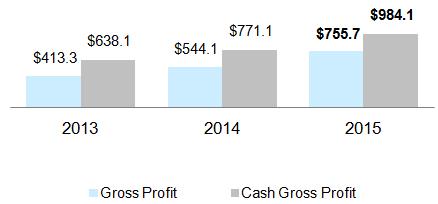
| § | Segment gross profit increased $211.6 million, or 39% to $755.7 million |
|---|
| § | Incremental gross profit as a percentage of freight-adjusted revenues was 66%; on a same-store basis was 77% |
|---|
| § | Asphalt Mix, Concrete and Calcium segment gross profit improved $58.4 million, collectively |
|---|
| § | SAG increased $14.6 million and declined (0.7 percentage points or 70 basis points) as a percentage of total revenues |
|---|
| § | Earnings from continuing operations were $232.9 million, or $1.72 per diluted share, compared to earnings of $207.1 million, or $1.56 per diluted share, in 2014 |
|---|
| § | Discrete items in 2015 include: |
|---|
| § | a $6.5 million tax charge related to a foreign tax credit carryforward impairment |
|---|
| § | a $4.7 million tax benefit related to a state NOL carryforward |
|---|
| § | a pretax charge of $67.1 million for debt purchase costs |
|---|
| § | a pretax gain of $6.3 million on the sale of real estate and businesses |
|---|
| § | a pretax charge of $9.5 million associated with acquisitions and divestitures |
|---|
| § | a pretax charge of $5.2 million for asset impairment |
|---|
| § | a pretax charge of $5.0 million for restructuring |
|---|
| § | Discrete items in 2014 include: |
|---|
| § | a pretax charge of $72.9 million for debt purchase costs |
|---|
| § | a pretax gain of $238.5 million on the sale of real estate and businesses |
|---|
| § | a pretax charge of $21.1 million associated with acquisitions and divestitures |
|---|
| § | a pretax charge of $1.3 million for restructuring |
|---|
| § | Adjusted EBITDA was $836.3 million, an increase of $231.6 million, or 38% |
|---|
KEY DRIVERS OF VALUE CREATION
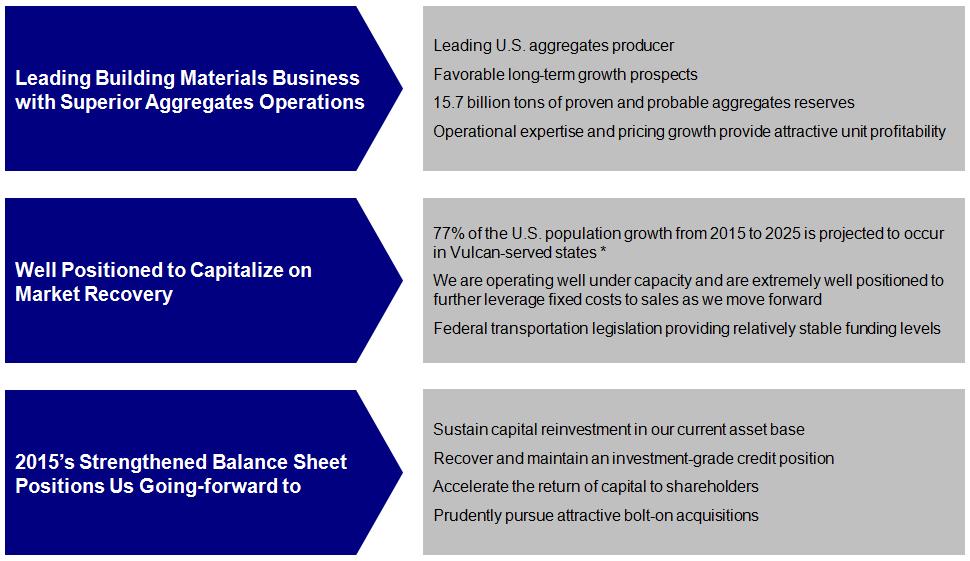
*Source: Moody's Analytics
| Part II | 28 |
EXECUTIVE LEADERSHIP TEAM AND OUR FIVE CORE DISCIPLINES
In 2014, we announced an executive leadership team led by Tom Hill, Chairman and Chief Executive Officer. Joining Mr. Hill on the leadership team were John McPherson (Executive Vice President, Chief Financial and Strategy Officer), Stan Bass (Chief Growth Officer) and Michael Mills (Chief Administrative Officer). Each member of the executive leadership team has significant senior-level general and industry specific business experience.
Under the leadership of our executive leadership team, we have instituted the following five core disciplines that we focus on daily:
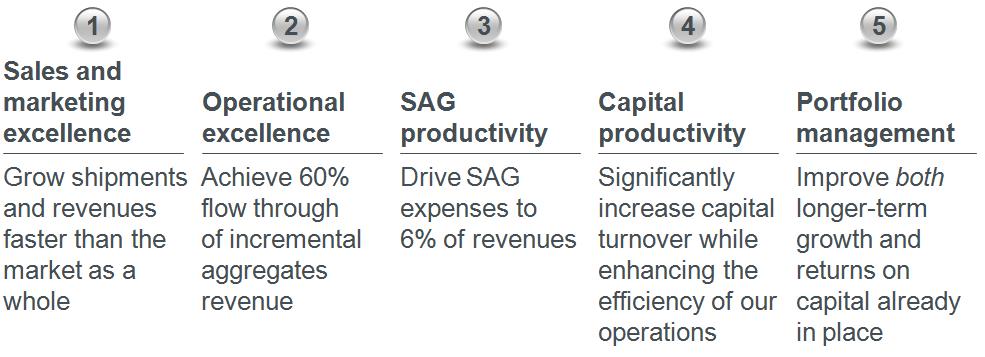
- SALES AND MARKETING EXCELLENCE
Goal: Remain the market supplier of choice in order to increase our market share while earning full and fair value for our products and services.
Execution: We are winning more than our fair share of large project bids by leveraging our scale and extensive strong customer relationships.
- OPERATIONAL EXCELLENCE
Goal: Lead the markets safest and most efficient operations by successfully leveraging and driving cost efficiencies to achieve 60% flow through of incremental aggregates revenue.
Execution: We are driving our cost of revenues down by leveraging our purchasing power and multi-modal logistics network and by better managing inventory levels. In 2015, we exceeded our long-term flow through goal of 60% by achieving 77% flow through of incremental aggregates revenue on a same-store basis.
- SELLING, ADMINISTRATIVE AND GENERAL (SAG) PRODUCTIVITY
Goal: Continue to leverage SAG in order to achieve 6% of revenues.
Execution: We are leveraging our recently reorganized central shared services and recently implemented common ERP platform to reduce administrative expenses and enable rapid integration of acquired operations. As a result, SAG as a percentage of total revenues has decreased from 9.1% in 2014 to 8.4% in 2015.
- CAPITAL PRODUCTIVITY
Goal: Drive improvement in capital turnover while maintaining the longer term health of our asset base.
Execution: We are improving capital turnover by maximizing the lifecycle value of land holdings and optimizing working capital and inventory levels.
- PORTFOLIO MANAGEMENT
Goal: Continue to pursue attractive bolt-on acquisitions and selectively enter new markets that meet our growth profile while divesting non-core businesses.
Execution: In 2015, we completed a swap of twelve ready-mixed concrete plants in California for thirteen asphalt plants primarily in Arizona. We also acquired three aggregates facilities and seven ready-mixed concrete plants in Arizona and New Mexico. These transactions together with acquisitions completed in 2014, position us as the #1 aggregates supplier in the New Mexico market and a leading aggregates supplier in Arizona.
| Part II | 29 |
2015 ACQUISITIONS/DIVESTITURES
We continually challenge ourselves as to whether we are the best owner of our individual assets and operations — this logic supports the transaction we closed in January 2015 to exchange our California ready-mixed concrete operations for 13 asphalt mix plants, primarily in Arizona. We expect to earn a higher return on the exchanged assets due to our operational and strategic focus in the Arizona asphalt market. In addition, we acquired the following in 2015:
| § | three aggregates facilities and seven ready-mixed concrete operations in Arizona and New Mexico |
|---|
| § | one aggregates facility in Tennessee |
|---|
For a detailed discussion of our acquisitions and divestitures, see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.”
MARKET DEVELOPMENTS AND OUTLOOK
We expect overall demand growth in Vulcan-served markets to be approximately 7% in 2016, driven by continued growth in both private and public construction. Private construction activity should continue to grow in both residential and nonresidential, led by double-digit growth in the residential sector. Public construction in our markets should continue to benefit from state-led highway spending in key states and record levels of state and local tax receipts. Additionally, with the passage of the new, fully funded, long-term federal highway bill in December 2015, the states now have greater funding stability and certainty to undertake much needed transportation projects. As a result, we believe that mid-single digit growth for this aggregates-intensive end-market is possible in 2016.
At this point in the recovery, the timing and pace of shipments throughout the year can be marginally more uncertain due to weather-related challenges and the start dates and shipping pace for certain large projects. For example, El Nino-related rainfall has negatively impacted early 2016 shipment rates in our California, Arizona and New Mexico operations. These factors, coupled with public transportation agencies needing time to adjust their project procurement schedules to incorporate passage of the new federal highway bill, could result in full year aggregates shipments being weighted towards the second half of the year.
We expect full year Adjusted EBITDA of $1.0 to $1.1 billion driven by: (1) the continuing recovery in demand from the trough seen in 2012, (2) strong growth in aggregates gross profit per ton, (3) earnings improvement in our non-aggregates businesses and (4) continuing leverage of our SAG expenses.
The following assumptions, which represent the mid-point of our expectations, support our outlook for strong year-over-year growth in Adjusted EBITDA in 2016.
| § | aggregates shipments of approximately 191 million tons, up 7% from 2015 |
|---|
| § | increase in average freight-adjusted aggregates pricing of 7%, with unit margins continuing to grow faster than pricing |
|---|
| § | aggregates gross profit growth of 25% |
|---|
| § | total non-aggregates gross profit improvement of 20% |
|---|
| § | SAG expenses of approximately $295 million, excluding business development-related expenses |
|---|
Other expectations include:
| § | core capital spending of approximately $275 million to support the increased level of shipments and further improve production costs and operating efficiencies |
|---|
| § | interest expense of approximately $140 million |
|---|
| § | depreciation, depletion, accretion and amortization expense of approximately $285 million |
|---|
| § | effective tax rate of 31% |
|---|
Our 2015 results and 2016 outlook are consistent with our long-range expectations. Since the beginning of this recovery in the second half of 2013, our teams’ efforts have resulted in trailing twelve month Aggregates segment gross profit increasing nearly $400 million on a 38 million ton increase in annualized shipments. We are encouraged by the ongoing recovery in demand continuing across our markets and by the positive pricing environment. Our teams continue to convert incremental revenue into incremental gross profit at an impressive rate. Our focus will remain on continuous, compounding improvement – both operational and financial.
| Part II | 30 |
RECONCILIATION OF NON-GAAP FINANCIAL MEASURES
Gross profit margin excluding freight and delivery revenues is not a Generally Accepted Accounting Principle (GAAP) measure. We present this metric as it is consistent with the basis by which we review our operating results. Likewise, we believe that this presentation is consistent with the basis by which investors analyze our operating results considering that freight and delivery services represent pass-through activities. Reconciliation of this metric to its nearest GAAP measure is presented below:
GROSS PROFIT MARGIN IN ACCORDANCE WITH GAAP
| dollars in millions | 2015 | 2014 | 2013 | |||||||
| Gross profit | $ 857.5 | $ 587.6 | $ 426.9 | |||||||
| Total revenues | $ 3,422.2 | $ 2,994.2 | $ 2,770.7 | |||||||
| Gross profit margin | 25.1% | 19.6% | 15.4% |
GROSS PROFIT MARGIN EXCLUDING FREIGHT AND DELIVERY REVENUES
| dollars in millions | 2015 | 2014 | 2013 | |||||||
| Gross profit | $ 857.5 | $ 587.6 | $ 426.9 | |||||||
| Total revenues | $ 3,422.2 | $ 2,994.2 | $ 2,770.7 | |||||||
| Freight and delivery revenues 1 | 538.1 | 473.1 | 386.2 | |||||||
| Total revenues excluding freight and delivery revenues | $ 2,884.1 | $ 2,521.1 | $ 2,384.5 | |||||||
| Gross profit margin excluding freight and delivery revenues | 29.7% | 23.3% | 17.9% |
| 1 | Includes freight to remote distribution sites. |
| Part II | 31 |
Aggregates segment gross profit margin as a percentage of freight-adjusted revenues is not a GAAP measure. We present this metric as it is consistent with the basis by which we review our operating results. We believe that this presentation is meaningful to our investors as it excludes freight, delivery and transportation revenues, which are pass-through activities. It also excludes immaterial other revenues related to services, such as landfill tipping fees, that are derived from our aggregates business. Incremental gross profit as a percentage of freight-adjusted revenues represents the year-over-year change in gross profit divided by the year-over-year change in freight-adjusted revenues. Reconciliations of these metrics to their nearest GAAP measures are presented below:
AGGREGATES SEGMENT GROSS PROFIT MARGIN IN ACCORDANCE WITH GAAP
| dollars in millions | 2015 | 2014 | 2013 | |||||||
| Aggregates segment | ||||||||||
| Gross profit | $ 755.7 | $ 544.1 | $ 413.3 | |||||||
| Segment sales | $ 2,777.8 | $ 2,346.4 | $ 2,025.0 | |||||||
| Gross profit margin | 27.2% | 23.2% | 20.4% | |||||||
| Incremental gross profit margin | 49.1% | 40.7% |
AGGREGATES SEGMENT GROSS PROFIT AS A PERCENTAGE OF FREIGHT-ADJUSTED REVENUES
| dollars in millions | 2015 | 2014 | 2013 | |||||||
| Aggregates segment | ||||||||||
| Gross profit | $ 755.7 | $ 544.1 | $ 413.3 | |||||||
| Segment sales | $ 2,777.8 | $ 2,346.4 | $ 2,025.0 | |||||||
| Less | ||||||||||
| Freight, delivery and transportation revenues 1 | 644.7 | 532.2 | 424.9 | |||||||
| Other revenues | 20.6 | 20.2 | 24.1 | |||||||
| Freight-adjusted revenues | $ 2,112.5 | $ 1,794.0 | $ 1,576.0 | |||||||
| Gross profit as a percentage of | ||||||||||
| freight-adjusted revenues | 35.8% | 30.3% | 26.2% | |||||||
| Incremental gross profit as a percentage of | ||||||||||
| freight-adjusted revenues | 66.5% | 60.0% |
| 1 | At the segment level, freight, delivery and transportation revenues include intersegment freight & delivery revenues, which are eliminated at the consolidated level. |
| Part II | 32 |
GAAP does not define "free cash flow," "cash gross profit" and "Earnings Before Interest, Taxes, Depreciation and Amortization” (EBITDA). Thus, free cash flow should not be considered as an alternative to net cash provided by operating activities or any other liquidity measure defined by GAAP. Likewise, cash gross profit and EBITDA should not be considered as alternatives to earnings measures defined by GAAP. We present these metrics for the convenience of investment professionals who use such metrics in their analyses and for shareholders who need to understand the metrics we use to assess performance. The investment community often uses these metrics as indicators of a company's ability to incur and service debt and to assess the operating performance of a company’s businesses. We use free cash flow, cash gross profit and EBITDA to assess the operating performance of our various business units and the consolidated company. Additionally, we adjust EBITDA for certain items to provide a more consistent comparison of performance from period to period. We do not use these metrics as a measure to allocate resources. Reconciliations of these metrics to their nearest GAAP measures are presented below:
FREE CASH FLOW
Free cash flow is calculated by deducting purchases of property, plant & equipment from net cash provided by operating activities.
| in millions | 2015 | 2014 | 2013 | |||||||
| Net cash provided by operating activities | $ 503.4 | $ 260.3 | $ 356.5 | |||||||
| Purchases of property, plant & equipment | (289.3) | (224.9) | (275.4) | |||||||
| Free cash flow | $ 214.1 | $ 35.4 | $ 81.1 |
CASH GROSS PROFIT
Cash gross profit adds back noncash charges for depreciation, depletion, accretion and amortization to gross profit. Cash gross profit per ton is computed by dividing cash gross profit by tons shipped.
| in millions, except per ton data | 2015 | 2014 | 2013 | |||||||
| Aggregates segment | ||||||||||
| Gross profit | $ 755.7 | $ 544.1 | $ 413.3 | |||||||
| Depreciation, depletion, accretion and amortization | 228.5 | 227.0 | 224.8 | |||||||
| Aggregates segment cash gross profit | $ 984.2 | $ 771.1 | $ 638.1 | |||||||
| Unit shipments - tons | 178.3 | 162.4 | 145.9 | |||||||
| Aggregates segment cash gross profit per ton | $ 5.52 | $ 4.75 | $ 4.37 | |||||||
| Asphalt Mix segment | ||||||||||
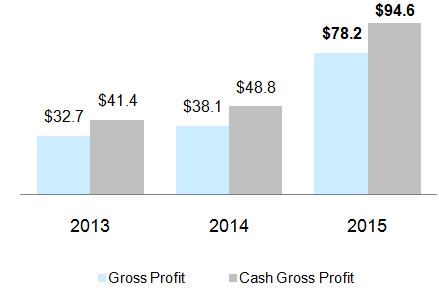
| Gross profit | $ 78.2 | $ 38.1 | $ 32.7 | |||||||
| Depreciation, depletion, accretion and amortization | 16.4 | 10.7 | 8.7 | |||||||
| Asphalt Mix segment cash gross profit | $ 94.6 | $ 48.8 | $ 41.4 | |||||||
| Concrete segment | ||||||||||
| Gross profit | $ 20.2 | $ 2.2 | $ (24.8) | |||||||
| Depreciation, depletion, accretion and amortization | 11.4 | 19.9 | 33.0 | |||||||
| Concrete segment cash gross profit | $ 31.6 | $ 22.1 | $ 8.2 | |||||||
| Calcium segment | ||||||||||
| Gross profit | $ 3.5 | $ 3.2 | $ 5.7 | |||||||
| Depreciation, depletion, accretion and amortization | 0.7 | 1.6 | 18.1 | |||||||
| Calcium segment cash gross profit | $ 4.2 | $ 4.8 | $ 23.8 |
| Part II | 33 |
EBITDA AND ADJUSTED EBITDA
EBITDA is an acronym for Earnings Before Interest, Taxes, Depreciation and Amortization and excludes discontinued operations. We adjust EBITDA for certain items to provide a more consistent comparison of performance from period to period.
| in millions | 2015 | 2014 | 2013 | |||||||
| Net earnings | $ 221.2 | $ 204.9 | $ 24.4 | |||||||
| Provision for (benefit from) income taxes | 94.9 | 91.7 | (24.5) | |||||||
| Interest expense, net of interest income | 220.3 | 242.4 | 201.7 | |||||||
| (Earnings) loss on discontinued operations, net of tax | 11.7 | 2.2 | (3.6) | |||||||
| Depreciation, depletion, accretion and amortization | 274.8 | 279.5 | 307.1 | |||||||
| EBITDA | $ 822.9 | $ 820.7 | $ 505.1 | |||||||
| Gain on sale of real estate and businesses | $ (6.3) | $ (238.5) | $ (36.8) | |||||||
| Charges associated with acquisitions and divestitures | 9.5 | 21.2 | 0.5 | |||||||
| Asset impairment | 5.2 | 0.0 | 0.0 | |||||||
| Restructuring charges | 5.0 | 1.3 | 1.5 | |||||||
| Adjusted EBITDA | $ 836.3 | $ 604.7 | $ 470.3 |
| Part II | 34 |
RESULTS OF OPERATIONS
Total revenues include sales of product to customers, net of any discounts and taxes, and freight and delivery revenues billed to customers. Related freight and delivery costs are included in cost of revenues. This presentation is consistent with the basis on which we review our consolidated results of operations. We discuss separately our discontinued operations, which consists of our former Chemicals business.
The following table highlights significant components of our consolidated operating results including EBITDA and Adjusted EBITDA.
CONSOLIDATED OPERATING RESULT HIGHLIGHTS
| For the years ended December 31 | 2015 | 2014 | 2013 | |||||||
| in millions, except per share data | ||||||||||
| Total revenues | $ 3,422.2 | $ 2,994.2 | $ 2,770.7 | |||||||
| Cost of revenues | 2,564.7 | 2,406.6 | 2,343.8 | |||||||
| Gross profit | $ 857.5 | $ 587.6 | $ 426.9 | |||||||
| Selling, administrative and general expenses | $ 286.8 | $ 272.3 | $ 259.4 | |||||||
| Gain on sale of property, plant & equipment | ||||||||||
| and businesses | $ 9.9 | $ 244.2 | $ 39.3 | |||||||
| Operating earnings | $ 549.8 | $ 538.1 | $ 190.4 | |||||||
| Interest expense | $ 220.6 | $ 243.4 | $ 202.6 | |||||||
| Earnings (loss) from continuing operations | ||||||||||
| before income taxes | $ 327.9 | $ 298.8 | $ (3.7) | |||||||
| Earnings from continuing operations | $ 232.9 | $ 207.1 | $ 20.8 | |||||||
| Earnings (loss) on discontinued operations, | ||||||||||
| net of income taxes | (11.7) | (2.2) | 3.6 | |||||||
| Net earnings | $ 221.2 | $ 204.9 | $ 24.4 | |||||||
| Basic earnings (loss) per share | ||||||||||
| Continuing operations | $ 1.75 | $ 1.58 | $ 0.16 | |||||||
| Discontinued operations | (0.09) | (0.02) | 0.03 | |||||||
| Basic net earnings per share | $ 1.66 | $ 1.56 | $ 0.19 | |||||||
| Diluted earnings (loss) per share | ||||||||||
| Continuing operations | $ 1.72 | $ 1.56 | $ 0.16 | |||||||
| Discontinued operations | (0.08) | (0.02) | 0.03 | |||||||
| Diluted net earnings per share | $ 1.64 | $ 1.54 | $ 0.19 | |||||||
| EBITDA | $ 822.9 | $ 820.7 | $ 505.1 | |||||||
| Adjusted EBITDA | $ 836.3 | $ 604.7 | $ 470.3 |
Net earnings for 2015 were $221.2 million ($1.64 per diluted share) compared to $204.9 million ($1.54 per diluted share) in 2014 and $24.4 million, or $0.19 per diluted share in 2013. Each year's results were impacted by discrete items as follows:
| § | Net earnings for 2015 include a pretax loss of $3.2 million (net of $9.5 million of charges associated with acquisitions and divestitures) related to the sale of real estate and businesses, a $5.0 pretax charge for restructuring, a $5.2 million pretax asset impairment loss, a pretax loss on debt purchase of $67.1 million presented as a component of interest expense (see Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data”), and a $6.5 million tax charge related to a foreign tax credit carryforward impairment. These unfavorable items were partially offset by a $4.7 million tax benefit related to a state NOL carryforward (see Note 9 “Income Taxes” in Item 8 “Financial Statements and Supplementary Data”) |
|---|
| § | Net earnings for 2014 include a pretax gain of $217.4 million (net of $21.1 million of disposition related charges) related to the sale of real estate and businesses including our cement and concrete businesses in the Florida area, a $1.3 million pretax charge for restructuring, and a pretax loss on debt purchase of $72.9 million presented as a component of interest expense (see Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data”) |
|---|
| Part II | 35 |
| § | Net earnings for 2013 include a pretax gain of $36.3 million (net of $0.5 million of disposition related charges) related to the sale of reclaimed real estate and businesses |
|---|
Year-over-year changes in earnings from continuing operations before income taxes are summarized below:
| in millions | |||||||
| 2013 | $ (3.7) | 2014 | $ 298.8 | ||||
| Higher aggregates gross profit | 130.8 | 211.6 | |||||
| Higher asphalt mix gross profit | 5.4 | 40.1 | |||||
| Higher concrete gross profit | 27.0 | 17.9 | |||||
| Higher (lower) calcium gross profit | (2.5) | 0.3 | |||||
| Higher selling, administrative and general expenses | (12.9) | (14.6) | |||||
| Higher (lower) gain on sale of property, plant & equipment and businesses | 205.0 | (234.3) | |||||
| Lower (higher) restructuring charges | 0.2 | (3.7) | |||||
| Lower (higher) interest expense | (40.8) | 22.8 | |||||
| All other | (9.7) | (11.0) | |||||
| 2014 | $ 298.8 | 2015 | $ 327.9 |
ADJUSTED CONCRETE AND CALCIUM SEGMENT FINANCIAL DATA
The following table compares our Concrete and Calcium segments financial data excluding both the January 2015 exchange of our California concrete businesses and the March 2014 sale of our Florida area concrete and cement businesses.
| For the years ended December 31 | 2015 | 2014 | 2013 | |||||||
| in millions | ||||||||||
| Concrete Segment | ||||||||||
| Segment sales | ||||||||||
| As reported | $ 299.3 | $ 375.8 | $ 471.7 | |||||||
| Adjusted | $ 294.1 | $ 272.6 | $ 244.9 | |||||||
| Total revenues | ||||||||||
| As reported | $ 299.3 | $ 375.8 | $ 471.7 | |||||||
| Adjusted | $ 294.1 | $ 272.6 | $ 244.9 | |||||||
| Gross profit | ||||||||||
| As reported | $ 20.2 | $ 2.2 | $ (24.8) | |||||||
| Adjusted | $ 20.9 | $ 12.0 | $ 5.8 | |||||||
| Depreciation, depletion, accretion and amortization | ||||||||||
| As reported | $ 11.4 | $ 19.9 | $ 33.0 | |||||||
| Adjusted | $ 11.3 | $ 15.7 | $ 15.5 | |||||||
| Shipments - cubic yards | ||||||||||
| As reported | 2.8 | 3.7 | 4.8 | |||||||
| Adjusted | 2.8 | 2.6 | 2.5 | |||||||
| Calcium Segment | ||||||||||
| Segment sales | ||||||||||
| As reported | $ 8.6 | $ 25.0 | $ 99.0 | |||||||
| Adjusted | $ 8.6 | $ 9.0 | $ 9.6 | |||||||
| Total revenues | ||||||||||
| As reported | $ 8.6 | $ 15.8 | $ 51.7 | |||||||
| Adjusted | $ 8.6 | $ 9.1 | $ 9.5 | |||||||
| Gross profit | ||||||||||
| As reported | $ 3.5 | $ 3.2 | $ 5.7 | |||||||
| Adjusted | $ 3.5 | $ 3.5 | $ 3.0 | |||||||
| Depreciation, depletion, accretion and amortization | ||||||||||
| As reported | $ 0.7 | $ 1.6 | $ 18.1 | |||||||
| Adjusted | $ 0.7 | $ 0.6 | $ 0.4 |
| Part II | 36 |
OPERATING RESULTS BY SEGMENT
We present our results of operations by segment at the gross profit level. We have four operating (and reportable) segments organized around our principal product lines: 1) Aggregates, 2) Asphalt Mix, 3) Concrete and 4) Calcium. Management reviews earnings for the product line segments principally at the gross profit level.
- AGGREGATES
Our year-over-year aggregates shipments:
| § | increased 10% in 2015 |
|---|
| § | increased 11% in 2014 |
|---|
| § | increased 4% in 2013 |
|---|
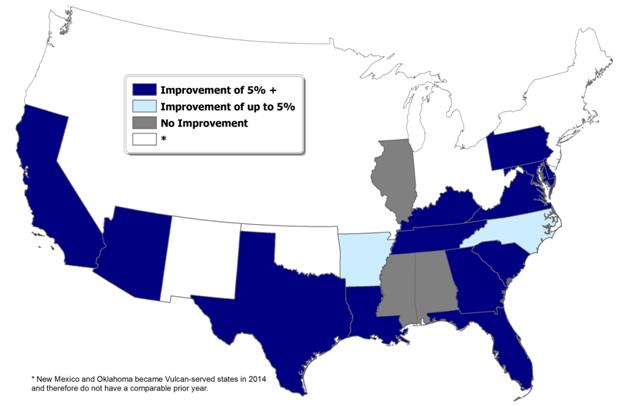
At 178.3 million tons, our 2015 aggregates shipments increased 15.9 million tons. This increase is consistent with our long-range expectations. The gradual recovery in demand continues across most of our 20-state geographic footprint. With the exception of certain markets in Texas, construction activity in Vulcan-served markets remains well below long-term levels of per capita consumption. Key states such as California, Florida, and Georgia continue to enjoy solid growth rates as they gradually recover toward more normal levels of construction activity and materials consumption. On a same-store basis, aggregates shipments increased 11.8 million tons or 7%.
The following map reflects the percentage improvement (2015 versus 2014) of aggregates shipments on a same-store basis by Vulcan-served states.
| Part II | 37 |
Our year-over-year freight-adjusted selling price1 for aggregates:
| § | increased 7% in 2015 |
|---|
| § | increased 2% in 2014 |
|---|
| § | increased 3% in 2013 |
|---|
| 1 | We routinely arrange the delivery of our aggregates to the customer. Additionally, we incur transportation costs to move aggregates from the production site to remote distribution sites. These costs are passed on to our customers in the aggregates price. We remove these pass-through freight and transportation revenues (and any other aggregates-derived revenues, such as landfill tipping fees) from the freight-adjusted selling price for aggregates. See the Reconciliation of Non-GAAP Financial Measures within this Item 7 for a reconciliation of freight-adjusted revenues. |
Our pricing environment continues to improve with the steady increase in demand. During 2015, freight-adjusted sales price increased in all Vulcan-served states. On a same-store basis, freight-adjusted sales price also increased 7%.
| AGGREGATES FREIGHT-ADJUSTED REVENUES | AGGREGATES GROSS PROFIT AND CASH GROSS PROFIT |
| in millions | in millions |
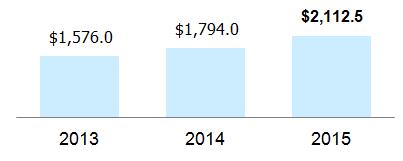 |  |
| AGGREGATES UNIT SHIPMENTS | AGGREGATES SELLING PRICE AND CASH GROSS PROFIT PER TON | ||
| Tons, in millions | Freight-adjusted average sales price per ton 2 | ||
 |  | ||
| 2 | Freight-adjusted sales price is calculated as freight-adjusted revenues divided by aggregates unit shipments |
Aggregates segment gross profit increased $211.6 million in 2015 from the prior year and gross profit as a percentage of freight-adjusted revenues increased 5.4 percentage points (540 basis points). The increase in Aggregates segment gross profit resulted from higher volumes and better unit margins. Aggregates segment unit cost of sales, excluding freight and delivery, declined 1% in 2015 versus the prior year as lower diesel and energy costs offset higher fringe and overtime labor expenses and repair & maintenance costs.
| Part II | 38 |
Aggregates segment cash gross profit per ton increased 16% to $5.52 in 2015. This measure continues to improve, reflecting our effective management of the three major profit drivers (price for service; sales and production mix; operating efficiency and leverage). These efforts resulted in a record level of unit profitability that exceeds the level achieved in 2005 ($3.28 per ton – our peak year for volume) and in 2014 ($4.75 per ton – our previous high). This trend further highlights the earnings potential of our aggregates business as volumes recover.
This aggregates earnings potential is further reflected in the flow-through rate. Same-store aggregates freight-adjusted revenues increased $271.9 million in 2015, while same-store gross profit for the segment increased $209.3 million, a flow-through rate of 77%. We have consistently exceeded our stated long-term goal of a 60% flow-through rate since volumes began to recover in the second half of 2013.
- ASPHALT MIX
Our year-over-year asphalt mix shipments:
| § | increased 30% in 2015 |
|---|
| § | increased 8% in 2014 |
|---|
| § | increased 3% in 2013 |
|---|
The significant increase in asphalt mix shipments was largely attributable to the swap of our concrete operations in California for asphalt mix operations, primarily in Arizona. On a same-store basis, asphalt mix shipments increased 10% and gross profit increased $30.8 million.
Unit gross profit increased 58% in 2015, while unit cash gross profit increased 49% to $9.80 per ton. This improvement resulted from the increased level of shipments, effective management of materials margins, and earnings from acquisitions completed since the first half of last year.
| ASPHALT MIX SEGMENT SALES | ASPHALT MIX GROSS PROFIT AND CASH GROSS PROFIT |
| in millions | in millions |
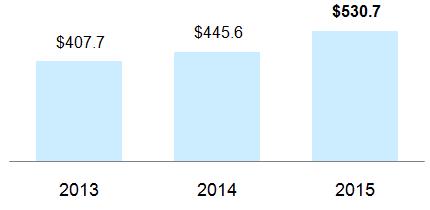 |  |
| Part II | 39 |
- CONCRETE
Our year-over-year ready-mixed concrete shipments:
| § | decreased 25% in 2015 |
|---|
| § | decreased 22% in 2014 |
|---|
| § | increased 14% in 2013 |
|---|
The significant decrease in ready-mixed concrete shipments was largely attributable to the aforementioned swap of our concrete operations in California. On a same-store basis, ready-mixed concrete shipments increased 7% and gross profit increased $8.9 million.
| CONCRETE SEGMENT SALES 1 | CONCRETE GROSS PROFIT AND CASH GROSS PROFIT 1 |
| in millions | in millions |
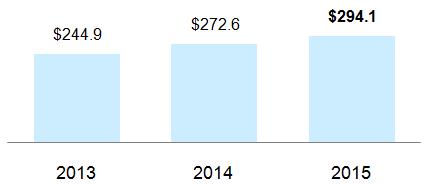 | 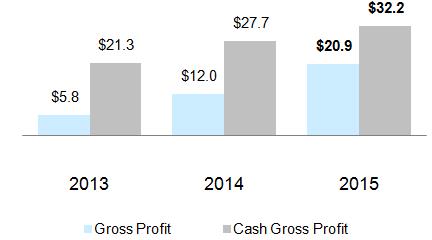 |
| 1 | The financial data above excludes both the California and Florida area concrete businesses exchanged/sold in January 2015 and March 2014, respectively. See the Adjusted Concrete and Calcium Segment Financial Data table on page 36. |
| Part II | 40 |
- CALCIUM
Calcium segment gross profit of $3.5 million was up $0.3 million from reported prior year gross profit of $3.2 million. Our cement business was sold in the first quarter of 2014 along with the Florida concrete assets. Adjusted for the sale of our cement business in the Florida area, Calcium segment gross profit was $3.5 million in 2014.
| CALCIUM SEGMENT SALES 1 | CALCIUM GROSS PROFIT AND CASH GROSS PROFIT 1 |
| in millions | in millions |
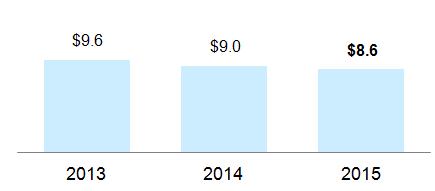 | 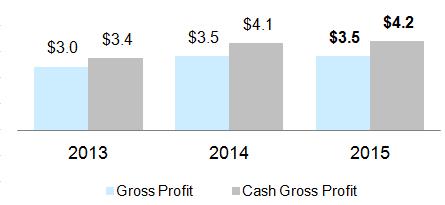 |
| 1 | The financial data above excludes the cement businesses sold in March 2014. See the Adjusted Concrete and Calcium Segment Financial Data table on page 36. |
In total, the 2015 gross profit contributions from our three non-aggregates (Asphalt Mix, Concrete and Calcium) segments exceeded plan due to margin improvements resulting from both core operating disciplines and strategic repositioning of our asset portfolio.
SELLING, ADMINISTRATIVE AND GENERAL EXPENSES
in millions

We experienced elevated SAG costs during 2015 primarily due to higher pension and other employee benefit costs, as well as continued investment in sales force effectiveness and other strategic initiatives. Other employee benefit costs, such as those associated with enhancements to the employee profit-sharing plan, also have risen. In contrast, direct SAG expenses for salaries and wages remained relatively flat with the prior year. We intend to further leverage SAG expenses to revenues as volumes recover. As a percentage of total revenues, SAG expenses declined from 9.1% in 2014 to 8.4% in 2015. In 2016, SAG expenses are expected to increase approximately 3% while revenues should increase double-digits.
Our comparative total company employment levels at year end:
| § | increased 4% in 2015 |
|---|
| § | declined 3% in 2014 |
|---|
| § | increased 5% in 2013 |
|---|
Severance charges included in SAG expenses were as follows: 2015 — $1.4 million, 2014 — $1.0 million and 2013 — $1.2 million. Severance and other related restructuring charges not included in SAG expenses were as follows: 2015 — $5.0 million, 2014 — $1.3 million and 2013 — $1.5 million.
| Part II | 41 |
GAIN ON SALE OF PROPERTY, PLANT & EQUIPMENT AND BUSINESSES
in millions
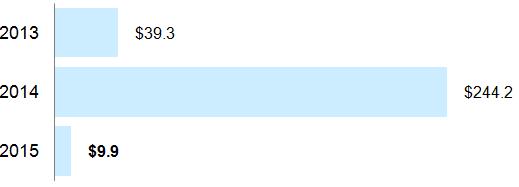
The 2015 gain includes a $5.9 million pretax gain from the previously mentioned asset exchange (we exited the ready-mixed concrete business in California and added thirteen asphalt plant locations, primarily in Arizona). The 2014 gain includes a $227.9 million pretax gain from the sale of our cement and concrete businesses in Florida to Cementos Argos and a $6.0 million pretax gain from the sale of two reclaimed operating sites. The 2013 gain includes a $24.0 million pretax gain from the sale of five non-strategic aggregates production facilities and a $9.0 million pretax gain from the sale of reclaimed and surplus real estate. See Note 19 "Acquisitions and Divestitures" in Item 8 "Financial Statements and Supplementary Data."
INTEREST EXPENSE
in millions
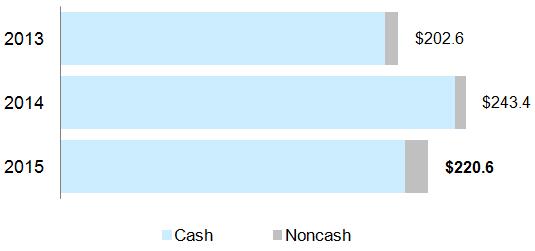
Interest expense in 2015 decreased $22.8 million from 2014 due to a lower weighted-average interest rate and a $5.8 million reduction in pretax charges for debt purchases. Interest expense in 2015 and 2014 included pretax charges for debt purchases of $67.1 million and $72.9 million, respectively, as described in Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data.”
INCOME TAXES
Our income tax provision (benefit) from continuing operations for the years ended December 31 is shown below:
| dollars in millions | 2015 | 2014 | 2013 | |||||||
| Earnings (loss) from continuing | ||||||||||
| operations before income taxes | $ 327.9 | $ 298.8 | $ (3.7) | |||||||
| Provision for (benefit from) income taxes | $ 94.9 | $ 91.7 | $ (24.5) | |||||||
| Effective tax rate | 29.0% | 30.7% | 660.5% |
The $3.3 million increase in our 2015 provision for incomes taxes is primarily related to the year-over-year improvement in our earnings from continuing operations. The 2015 reduction in the effective tax rate is due to higher benefits from the statutory depletion deduction and the U.S. production deduction, both related to higher aggregates sales. The $116.2 million increase in our 2014 income taxes is primarily related to the year-over-year improvement in our earnings from continuing operations. A reconciliation of the federal statutory rate of 35% to our effective tax rates for 2015, 2014 and 2013 is presented in Note 9 “Income Taxes” in Item 8 “Financial Statements and Supplementary Data.”
| Part II | 42 |
DISCONTINUED OPERATIONS
Pretax earnings (loss) from discontinued operations were:
| § | $(19.3) million loss in 2015 |
|---|
| § | $(3.7) million loss in 2014 |
|---|
| § | $6.0 million earnings in 2013 |
|---|
The $19.3 million and $3.7 million losses from discontinued operations for 2015 and 2014, respectively, resulted primarily from general and product liability costs, including legal defense costs and environmental remediation costs associated with our former Chemicals business. The 2013 pretax earnings include an $11.7 million gain related to the 5CP earn-out (final payment in 2013). This gain was partially offset by general and product liability costs, including legal defense costs, and environmental remediation costs. For additional information regarding discontinued operations and the 5CP earn-out, see Note 2 "Discontinued Operations" in Item 8 "Financial Statements and Supplementary Data."
LIQUIDITY AND FINANCIAL RESOURCES
Our sources of liquidity are cash provided by our operating activities and a substantial, committed bank line of credit. Additional financial resources include access to the capital markets, the sale of reclaimed and surplus real estate, and dispositions of non-strategic operating assets. We believe these liquidity and financial resources are sufficient to fund our business requirements for 2016, including:
| § | cash contractual obligations |
|---|
| § | capital expenditures |
|---|
| § | debt service obligations |
|---|
| § | dividend payments |
|---|
| § | potential share repurchases |
|---|
| § | potential future acquisitions |
|---|
Our capital deployment priorities remain unchanged from the prior year. We intend to take a balanced approach to capital deployment, one incorporating strategic reinvestment, sustained financial strength and flexibility, and the return of capital to shareholders. In 2015, we returned $53.2 million in cash to shareholders though our dividend and $21.5 million through share repurchases. We expect to increase the return of capital through dividends, share repurchases, or other mechanisms, as earnings grow.
We actively manage our capital structure and resources in order to minimize the cost of capital while properly managing financial risk. We seek to meet these objectives by adhering to the following principles:
| § | maintain substantial bank line of credit borrowing capacity |
|---|
| § | proactively manage our long-term debt maturity schedule such that repayment/refinancing risk in any single year is low |
|---|
| § | minimize financial and other covenants that limit our operating and financial flexibility |
|---|
| § | opportunistically access the capital markets when conditions and terms are favorable |
|---|
During 2015, we maintained debt of approximately $2.0 billion, eliminated nearer-term maturities, increased the weighted-average life of our debt obligations, and lowered our weighted-average interest rate by approximately 1% (100 basis points).
| Part II | 43 |
CASH
Included in our December 31, 2015 cash and cash equivalents balance of $284.1 million is $58.9 million of cash held at one of our foreign subsidiaries. All of this $58.9 million of cash relates to earnings that are indefinitely reinvested offshore. Use of this cash is currently limited to our foreign operations.
CASH FROM OPERATING ACTIVITIES
in millions
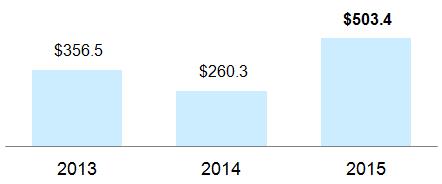
Net cash provided by operating activities is derived primarily from net earnings before noncash deductions for depreciation, depletion, accretion and amortization.
| in millions | 2015 | 2014 | 2013 | |||||||
| Net earnings | $ 221.2 | $ 204.9 | $ 24.4 | |||||||
| Depreciation, depletion, accretion | ||||||||||
| and amortization (DDA&A) | 274.8 | 279.5 | 307.1 | |||||||
| Net earnings before noncash deductions for DDA&A | $ 496.0 | $ 484.4 | $ 331.5 | |||||||
| Net gain on sale of property, plant & | ||||||||||
| equipment and businesses | (9.9) | (244.2) | (51.0) | |||||||
| Proceeds from sale of future production, | ||||||||||
| net of transaction costs | 0.0 | 0.0 | 153.1 | |||||||
| Cost of debt purchase | 67.1 | 72.9 | 0.0 | |||||||
| Other operating cash flows, net 1 | (49.8) | (52.8) | (77.1) | |||||||
| Net cash provided by operating | ||||||||||
| activities | $ 503.4 | $ 260.3 | $ 356.5 |
| 1 | Primarily reflects changes to working capital balances. |
2015 versus 2014 — Net cash provided by operating activities was $503.4 million during 2015, a $243.1 million increase compared to 2014. Net earnings before noncash deduction for DDA&A increased $11.6 million during 2015 to $496.0 million. Included in net earnings for 2014 is a pretax gain of $227.9 million (see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data”) from the March 2014 sale of our cement and concrete businesses in the Florida area. Cash received associated with gain on sale of property, plant & equipment and businesses is presented as a component of investing activities. In 2015, we purchased $485.1 million principal amount of outstanding debt and incurred charges of $67.1 million. In 2014, we purchased $506.4 million principal amount of outstanding debt and incurred charges of $72.9 million (see Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data”). Cash paid for the debt purchases is presented as a component of financing activities.
2014 versus 2013 — Net cash provided by operating activities of $260.3 million decreased $96.2 million from 2013. The decrease is attributable to a transaction in 2013 in which we sold a percentage of future production from aggregates reserves resulting in net cash proceeds of $153.1 million (see Note 1 “Summary of Significant Accounting Policies” in Item 8 “Financial Statements and Supplementary Data”). Net earnings before noncash deductions for DDA&A increased $152.9 million to $484.4 million during 2014. Included in net earnings for 2014 is a pretax gain of $227.9 million (see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data”) from the sale of our cement and concrete businesses in the Florida area. Cash received associated with the sale of property, plant & equipment and businesses is presented as a component of investing activities. Additionally, we purchased $506.4 million principal amount of outstanding debt through a tender offer and incurred a charge of $72.9 million (see Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data”). Cash paid for the debt purchase is presented as a component of financing activities.
| Part II | 44 |
CASH FROM INVESTING ACTIVITIES
in millions
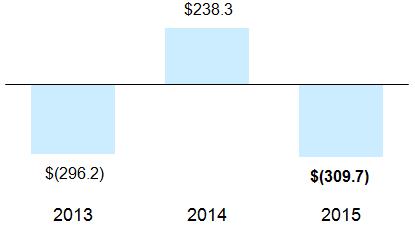
2015 versus 2014 — Net cash used for investing activities was $309.7 million during 2015, a $548.0 million decrease compared to the $238.3 million of net cash provided during 2014. This decrease is the result of lower proceeds from the sale of property, plant & equipment and businesses, less cash used in acquisitions and higher capital investments in our existing operations. During 2014, we sold: a previously mined and subsequently reclaimed tract of land for $10.7 million, land previously containing a sales yard for $5.8 million, and our cement and concrete businesses in the Florida area for $721.4 million. We had no comparable significant sales in the current year. During 2014, we completed several acquisitions for cash consideration of $284.2 million. Conversely, acquisitions during 2015 totaled $27.2 million in cash consideration (see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data”). Furthermore, during 2015, we increased investments in our existing operations by $64.4 million as reflected in the increased purchases of property, plant & equipment.
2014 versus 2013 — Net cash provided by investing activities increased $534.5 million during 2014. This increase resulted from a $678.2 million increase in proceeds from the sale of property, plant & equipment and businesses partially offset by a $143.8 million increase in purchases of property, plant & equipment and businesses. During 2014, we sold a previously mined and subsequently reclaimed tract of land for $10.7 million, land previously containing a sales yard for $5.8 million, and our cement and concrete businesses in the Florida area for $721.4 million. In the same period, we completed several acquisitions for total consideration of $331.8 million, of which $284.2 million was paid in cash (see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data”).
CASH FROM FINANCING ACTIVITIES
in millions
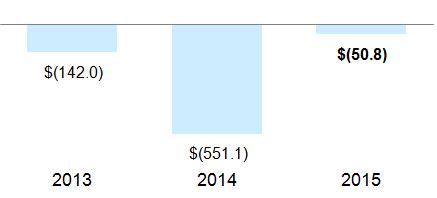
2015 VERSUS 2014 — Net cash used for financing activities in 2015 was $50.8 million, a decrease of $500.3 million from 2014. This large decrease is primarily attributable to the prior year’s $506.4 million principal amount debt purchase, which required $579.7 million of cash. The 2014 debt purchase was funded by the aforementioned sale of our cement and concrete businesses in the Florida area. In 2015, we refinanced $635.1 million principal amount of debt and entered into a new $750.0 million line of credit. The total cash requirement for these actions was $702.3 million ($635.1 million principal, $59.3 million of premiums above par and transaction fees of $7.9 million). We funded the refinancing by issuing $400.0 million of new 10-year notes, borrowing $235.0 million under our new and expanded line of credit and using $67.3 million of cash. Furthermore, in 2014 we generated $30.6 million of cash by issuing new shares to our 401(k) plan (such issuances were discontinued in the fourth quarter of 2014). Finally, in 2015 we returned capital to our investors by repurchasing 228.0 thousand shares of common stock for cash consideration of $21.5 million.
| Part II | 45 |
2014 VERSUS 2013 — Net cash used for financing activities of $551.1 million increased $409.1 million in 2014 compared to 2013. This increase is primarily attributable to the aforementioned $506.4 million principal amount purchase that required $579.7 million of cash. This increase in cash used for financing activities is partially offset by a $26.8 million increase in proceeds from the issuance of common stock. In 2014, we issued 485.3 thousand shares of common stock to the trustee of our 401(k) savings and retirement plans for cash proceeds of $30.6 million.
DEBT
Certain debt measures as of December 31 are outlined below:
| dollars in millions | 2015 | 2014 | ||||||||
| Debt | ||||||||||
| Current maturities of long-term debt | $ 0.1 | $ 150.1 | ||||||||
| Short-term debt (line of credit) | 0.0 | 0.0 | ||||||||
| Long-term debt 1 | 1,980.3 | 1,834.6 | ||||||||
| Total debt 2 | $ 1,980.4 | $ 1,984.7 | ||||||||
| Capital | ||||||||||
| Total debt 2 | $ 1,980.4 | $ 1,984.7 | ||||||||
| Equity | 4,454.2 | 4,176.7 | ||||||||
| Total capital | $ 6,434.6 | $ 6,161.4 | ||||||||
| Total Debt as a Percentage of Total Capital | 30.8% | 32.2% | ||||||||
| Weighted-average Effective Interest Rates | ||||||||||
| Line of credit 3 | 1.75% | 1.50% | ||||||||
| Term debt | 7.52% | 8.10% | ||||||||
| Fixed versus Floating Interest Rate Debt | ||||||||||
| Fixed-rate debt | 88.3% | 99.3% | ||||||||
| Floating-rate debt | 11.7% | 0.7% |
| 1 | Includes borrowing under our line of credit for which we have the intent and ability to extend repayment beyond twelve months, as follows: December 31, 2015 — $235.0 million and December 31, 2014 — $0.0 million. |
| 2 | The debt balances as of December 31, 2014 have been adjusted to reflect our early adoption of ASU 2015-03 and related election as disclosed in Note 1 “Summary of Significant Accounting Policies” in Item 8 “Financial Statements and Supplementary Data” under the caption New Accounting Standards. |
| 3 | Reflects the margin above LIBOR for LIBOR-based borrowings; we also paid upfront fees that are amortized to interest expense and pay fees for unused borrowing capacity and standby letters of credit. |
LINE OF CREDIT
In June 2015, we cancelled our secured $500.0 million line of credit and entered into an unsecured $750.0 million line of credit (incurring $2.6 million of transaction fees). The expanded borrowing capacity is part of the refinancing plans disclosed at our February 25, 2015 Investor Day (the 2015 refinancing plans). Borrowings at December 31, 2015 are consistent with the 2015 refinancing plans and are intended to remain outstanding going forward.
The line of credit agreement expires in June 2020 and contains affirmative, negative and financial covenants customary for an unsecured facility (none of which materially impact our ability to execute our strategic, operating and financial plans). The financial covenants are: (1) a maximum ratio of debt to EBITDA of 3.5:1 through September 2016 and 3.25:1 thereafter, and (2) a minimum ratio of EBITDA to net cash interest expense of 3.0:1. As of December 31, 2015, we were in compliance with the line of credit covenants.
| Part II | 46 |
Borrowings and other cost ranges and details are described in Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data.” As of December 31, 2015, the credit margin for the London Interbank Offered Rate (LIBOR) borrowings was 1.75%, the credit margin for base rate borrowings was 0.75%, and the commitment fee for the unused portion was 0.25%.
As of December 31, 2015, our available borrowing capacity under the line of credit was $476.1 million. Utilization of the borrowing capacity was as follows:
| § | $235.0 million was borrowed |
|---|
| § | $38.9 million was used to provide support for outstanding standby letters of credit |
|---|
TERM DEBT
All of our term debt is unsecured. All such debt, other than the $0.5 million of other notes, is governed by two essentially identical indentures that contain customary investment-grade type covenants. The primary covenant in both indentures limits the amount of secured debt we may incur without ratably securing such debt. As of December 31, 2015, we were in compliance with all of the term debt covenants.
In March, April and August of 2015, we completed the refinancing of $485.1 million principal amount of debt as described in Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data.” And, in December 2015 we refinanced at maturity the $150.0 million of 10.125% notes via borrowing on our line of credit. These refinancing actions are consistent with the aforementioned 2015 refinancing plans, resulted in total debt of approximately $2.0 billion as of December 31, 2015 (consistent with year-end 2014) and have the following benefits, among others: (1) eliminate $621.1 million of debt maturities in 2015 – 2018 (including the $150.0 million notes refinanced as mentioned above), (2) extend the weighted-average life of our debt portfolio, and (3) lower our weighted-average interest rate.
The 2015 refinancing actions resulted in charges totaling $67.1 million. Such charges are detailed in Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data” and are presented in the accompanying Consolidated Statement of Comprehensive Income as a component of interest expense for the year ended December 31, 2015.
In March 2014, we purchased $506.4 million principal amount of debt through a tender offer as described in Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data.” This debt purchase was funded by the aforementioned sale of our cement and concrete businesses in the Florida area and resulted in charges totaling $72.9 million (presented in the accompanying Consolidated Statement of Comprehensive Income as a component of interest expense for the year ended December 31, 2014).
DEBT PAYMENTS AND MATURITIES
Scheduled debt payments during 2015 included $150.0 million in December to retire the 10.125% notes (which were refinanced via long-term borrowings on our line of credit). Additionally, we refinanced $485.1 million of debt as described in Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data.”
As of December 31, 2015, current maturities for the next four quarters and maturities for the next five years are due as follows:
| Current | Debt | |||||
| in millions | Maturities | in millions | Maturities | |||
| First quarter 2016 | $ 0.0 | 2016 | $ 0.1 | |||
| Second quarter 2016 | 0.0 | 2017 | 0.2 | |||
| Third quarter 2016 | 0.0 | 2018 | 522.5 | |||
| Fourth quarter 2016 | 0.1 | 2019 | 0.0 | |||
| 2020 | 0.0 |
We expect to retire current maturities using existing cash.
| Part II | 47 |
DEBT RATINGS
Our debt ratings and outlooks as of December 31, 2015 are as follows:
| Rating/Outlook | Date | Description | ||||||||
| Senior Unsecured Line of Credit | ||||||||||
| Moody's | Ba2/positive | 8/12/2015 | initial coverage | |||||||
| Senior Unsecured 1 | ||||||||||
| Fitch | BB+/stable | 5/11/2015 | initial coverage | |||||||
| Moody's | Ba2/positive | 8/12/2015 | rating changed from Ba3 to Ba2 | |||||||
| Standard & Poor's | BB+/positive | 3/16/2015 | outlook changed from stable to positive |
| 1 | Not all of our long-term debt is rated. |
EQUITY
Our common stock issuances and purchases are as follows:
| in thousands | 2015 | 2014 | 2013 | |||||||
| Common stock shares at January 1, | ||||||||||
| issued and outstanding | 131,907 | 130,200 | 129,721 | |||||||
| Common Stock Issuances | ||||||||||
| Acquisitions | 0 | 715 | 0 | |||||||
| 401(k) retirement plans | 0 | 485 | 71 | |||||||
| Share-based compensation plans | 1,493 | 507 | 408 | |||||||
| Common Stock Purchases | ||||||||||
| Purchased and retired | (228) | 0 | 0 | |||||||
| Common stock shares at December 31, | ||||||||||
| issued and outstanding | 133,172 | 131,907 | 130,200 |
During 2014, we issued 715.0 thousand shares of our common stock in connection with business acquisitions as explained in Note 19 "Acquisitions and Divestitures" in Item 8 "Financial Statements and Supplementary Data."
Under a program that was discontinued in the fourth quarter of 2014, we occasionally sold shares of our common stock to the trustee of our 401(k) retirement plans to satisfy the plan participants' elections to invest in our common stock. Under this arrangement, the stock issuances and resulting cash proceeds for the years ended December 31 were:
| § | 2014 — issued 485.3 thousand shares for cash proceeds of $30.6 million |
|---|
| § | 2013 — issued 71.2 thousand shares for cash proceeds of $3.8 million |
|---|
There were no shares held in treasury as of December 31, 2015, 2014 and 2013.
On February 10, 2006, our Board of Directors authorized us to purchase up to 10,000,000 shares of our common stock. As of December 31, 2015, there were 3,183,416 shares remaining under the authorization. Depending upon market, business, legal and other conditions, we may make share purchases from time to time through open market purchases, privately negotiated transactions and/or plans designed to comply with Rule 10b5-1 of the Securities Exchange Act of 1934. The authorization has no time limit, does not obligate us to purchase any specific number of shares, and may be suspended or discontinued at any time.
Our common stock purchases (all of which were open market purchases) are detailed below:
| in thousands | 2015 | 2014 | 2013 | |||||||
| Shares Purchased | ||||||||||
| Number | 228 | 0 | 0 | |||||||
| Total cost | $ 21,475 | $ 0 | $ 0 | |||||||
| Average cost | $ 94.19 | $ 0.00 | $ 0.00 |
| Part II | 48 |
OFF-BALANCE SHEET ARRANGEMENTS
We have no off-balance sheet arrangements, such as financing or unconsolidated variable interest entities, that either have or are reasonably likely to have a current or future material effect on our:
| § | results of operations and financial position |
|---|
| § | capital expenditures |
|---|
| § | liquidity and capital resources |
|---|
STANDBY LETTERS OF CREDIT
For a discussion of our standby letters of credit see Note 6 "Debt" in Item 8 "Financial Statements and Supplementary Data."
CASH CONTRACTUAL OBLIGATIONS
We expect total capital spending of $400.0 million during 2016. Excluding future cash requirements for capital expenditures and immaterial or contingent contracts, our obligations to make future contractual payments as of December 31, 2015 are summarized in the table below:
| Note | Payments Due by Year | |||||||||||||
| in millions | Reference | 2016 | 2017-2018 | 2019-2020 | Thereafter | Total | ||||||||
| Cash Contractual Obligations | ||||||||||||||
| Bank line of credit 1 | ||||||||||||||
| Principal payments | Note 6 | $ 0.0 | $ 0.0 | $ 235.0 | $ 0.0 | $ 235.0 | ||||||||
| Interest payments and fees 2 | 7.4 | 17.1 | 13.8 | 0.0 | 38.3 | |||||||||
| Term debt | ||||||||||||||
| Principal payments | Note 6 | 0.1 | 522.7 | 0.0 | 1,246.4 | 1,769.2 | ||||||||
| Interest payments | Note 6 | 125.7 | 241.9 | 161.4 | 396.1 | 925.1 | ||||||||
| Operating leases | Note 7 | 30.9 | 56.3 | 43.0 | 128.6 | 258.8 | ||||||||
| Mineral royalties | Note 12 | 21.5 | 37.7 | 25.4 | 132.8 | 217.4 | ||||||||
| Unconditional purchase obligations | ||||||||||||||
| Capital | Note 12 | 67.6 | 79.2 | 0.1 | 0.0 | 146.9 | ||||||||
| Noncapital 3 | Note 12 | 14.4 | 17.6 | 11.6 | 5.0 | 48.6 | ||||||||
| Benefit plans 4 | Note 10 | 9.2 | 25.6 | 50.4 | 145.0 | 230.2 | ||||||||
| Total cash contractual obligations 5, 6 | $ 276.8 | $ 998.1 | $ 540.7 | $ 2,053.9 | $ 3,869.5 |
| 1 | Bank line of credit represents borrowings under our unsecured $750.0 million line of credit that expires June 2020. |
| 2 | Includes fees for unused borrowing capacity, and fees for standby letters of credit. The figures for all years assume that the amount of unused borrowing capacity, and the amount of standby letters of credit do not change from December 31, 2015. |
| 3 | Noncapital unconditional purchase obligations relate primarily to transportation and electricity contracts. |
| 4 | Payments in "Thereafter" column for benefit plans are for the years 2021-2025. |
| 5 | The above table excludes discounted asset retirement obligations in the amount of $226.6 million at December 31, 2015, the majority of which have an estimated settlement date beyond 2020 (see Note 17 "Asset Retirement Obligations" in Item 8 "Financial Statements and Supplementary Data"). |
| 6 | The above table excludes liabilities for unrecognized tax benefits in the amount of $8.5 million at December 31, 2015, as we cannot make a reasonably reliable estimate of the amount and period of related future payment of these uncertain tax positions (for more details, see Note 9 "Income Taxes" in Item 8 "Financial Statements and Supplementary Data"). |
| Part II | 49 |
CRITICAL ACCOUNTING POLICIES
We follow certain significant accounting policies when we prepare our consolidated financial statements. A summary of these policies is included in Note 1 "Summary of Significant Accounting Policies" in Item 8 "Financial Statements and Supplementary Data."
We prepare these financial statements to conform with accounting principles generally accepted in the United States of America. These principles require us to make estimates and judgments that affect reported amounts of assets, liabilities, revenues and expenses, and the related disclosures of contingent assets and contingent liabilities at the date of the financial statements. We base our estimates on historical experience, current conditions and various other assumptions we believe reasonable under existing circumstances and evaluate these estimates and judgments on an ongoing basis. The results of these estimates form the basis for our judgments about the carrying values of assets and liabilities as well as identifying and assessing the accounting treatment with respect to commitments and contingencies. Our actual results may materially differ from these estimates.
We believe the following seven critical accounting policies require the most significant judgments and estimates used in the preparation of our consolidated financial statements:
| 1. | Goodwill and goodwill impairment |
|---|
| 2. | Impairment of long-lived assets excluding goodwill |
|---|
| 3. | Reclamation costs |
|---|
| 4. | Pension and other postretirement benefits |
|---|
| 5. | Environmental compliance costs |
|---|
| 6. | Claims and litigation including self-insurance |
|---|
| 7. | Income taxes |
|---|
- GOODWILL AND GOODWILL IMPAIRMENT
Goodwill represents the excess of the cost of net assets acquired in business combinations over the fair value of the identifiable tangible and intangible assets acquired and liabilities assumed in a business combination. Goodwill impairment exists when the fair value of a reporting unit is less than its carrying amount. Goodwill is tested for impairment on an annual basis or more frequently whenever events or changes in circumstances would more likely than not reduce the fair value of a reporting unit below its carrying amount. The impairment evaluation is a critical accounting policy because goodwill is material to our total assets (as of December 31, 2015, goodwill represents 37% of total assets) and the evaluation involves the use of significant estimates, assumptions and judgment.
HOW WE TEST GOODWILL FOR IMPAIRMENT
Goodwill is tested for impairment at the reporting unit level, one level below our operating segments. We have identified 18 reporting units, of which 9 carry goodwill. We have the option of either assessing qualitative factors to determine whether it is more likely than not that the carrying value of our reporting units exceeds their respective fair value or proceeding directly to a two-step quantitative test. We elected to perform the quantitative impairment test for all years presented.
STEP 1
We compare the fair value of a reporting unit to its carrying value, including goodwill:
| § | if the fair value exceeds its carrying value, the goodwill of the reporting unit is not considered impaired |
|---|
| § | if the carrying value of a reporting unit exceeds its fair value, we go to step two to measure the amount of impairment loss, if any |
|---|
STEP 2
We compare the implied fair value of the reporting unit goodwill with the carrying amount of that goodwill. The implied fair value of goodwill is determined by hypothetically allocating the fair value of the reporting unit to its identifiable assets and liabilities in a manner consistent with a business combination, with any excess fair value representing implied goodwill:
| § | if the carrying value of the reporting unit goodwill exceeds the implied fair value of that goodwill, an impairment loss is recognized in an amount equal to that excess |
|---|
| Part II | 50 |
HOW WE DETERMINE CARRYING VALUE AND FAIR VALUE
First, we determine the carrying value of each reporting unit by assigning assets and liabilities, including goodwill, to those units as of the measurement date. Then, we estimate the fair values of the reporting units using both an income approach (which involves discounting estimated future cash flows) and a market approach (which involves the application of revenue and EBITDA multiples of comparable companies). We consider market factors when determining the assumptions and estimates used in our valuation models. Finally, to assess the reasonableness of the reporting unit fair values, we compare the total of the reporting unit fair values to our market capitalization.
OUR FAIR VALUE ASSUMPTIONS
We base our fair value estimates on market participant assumptions we believe to be reasonable at the time, but such assumptions are subject to inherent uncertainty and actual results may differ. Changes in key assumptions or management judgment with respect to a reporting unit or its prospects may result from a change in market conditions, market trends, interest rates or other factors outside of our control, or underperformance relative to historical or projected operating results. These conditions could result in a significantly different estimate of the fair value of our reporting units, which could result in an impairment charge in the future.
The significant assumptions in our discounted cash flow models include our estimate of future profitability, capital requirements and the discount rate. The profitability estimates used in the models were derived from internal operating budgets and forecasts for long-term demand and pricing in our industry. Estimated capital requirements reflect replacement capital estimated on a per ton basis and acquisition capital necessary to support growth estimated in the models. The discount rate was derived using a capital asset pricing model.
RESULTS OF OUR IMPAIRMENT TESTS
The results of our annual impairment tests for:
| § | November 1, 2015 indicated that the fair values of all reporting units with goodwill materially exceeded (in excess of 50%) their carrying values |
|---|
| § | November 1, 2014 indicated that the fair values of all reporting units with goodwill substantially exceeded (in excess of 20%) their carrying values |
|---|
| § | November 1, 2013 indicated that the fair values of all reporting units with goodwill substantially exceeded (in excess of 30%) their carrying values |
|---|
For additional information regarding goodwill, see Note 18 "Goodwill and Intangible Assets" in Item 8 "Financial Statements and Supplementary Data."
- IMPAIRMENT OF LONG-LIVED ASSETS EXCLUDING GOODWILL
We evaluate the carrying value of long-lived assets, including intangible assets subject to amortization, when events and circumstances indicate that the carrying value may not be recoverable. The impairment evaluation is a critical accounting policy because long-lived assets are material to our total assets (as of December 31, 2015, net property, plant & equipment represents 38% of total assets, while net other intangible assets represents 9% of total assets) and the evaluation involves the use of significant estimates, assumptions and judgment. The carrying value of long-lived assets is considered impaired when the estimated undiscounted cash flows from such assets are less than their carrying value. In that event, we recognize a loss equal to the amount by which the carrying value exceeds the fair value.
Fair value is estimated primarily by using a discounted cash flow methodology that requires considerable judgment and assumptions. Our estimate of net future cash flows is based on historical experience and assumptions of future trends, which may be different from actual results. We periodically review the appropriateness of the estimated useful lives of our long-lived assets.
| Part II | 51 |
We test long-lived assets for impairment at the lowest level for which identifiable cash flows are largely independent of the cash flows of other assets. As a result, our long-lived asset impairment test is at a significantly lower level than the level at which we test goodwill for impairment. In markets where we do not produce downstream products (e.g., asphalt mix and ready-mixed concrete), the lowest level of largely independent identifiable cash flows is at the individual aggregates operation or a group of aggregates operations collectively serving a local market. Conversely, in vertically integrated markets, the cash flows of our downstream and upstream businesses are not largely independently identifiable as the selling price of the upstream products (aggregates) determines the profitability of the downstream business.
During 2015, we recorded a $5.2 million loss on impairment of long-lived assets resulting from exiting a lease. During 2014, we recorded a $3.1 million impairment loss related primarily to assets retained in the divestiture of our cement and concrete businesses in the Florida area, see Note 19 "Acquisitions and Divestitures" in Item 8 "Financial Statements and Supplementary Data." We recorded no asset impairments during 2013.
We maintain certain long-lived assets that are not currently being utilized in our operations. These assets totaled $373.0 million at December 31, 2015, representing an approximate 1% decrease from December 31, 2014. Of the total $373.0 million, approximately 40% relates to real estate held for future development and expansion of our operations. In addition, approximately 25% is comprised of real estate (principally former mining sites) pending development as commercial or residential real estate, reservoirs or landfills. The remaining 35% is composed of aggregates, asphalt mix and ready-mixed concrete operating assets idled temporarily as a result of a decline in demand for our products. We anticipate moving idled assets back into operation as demand recovers. We evaluate the useful lives and the recoverability of these assets whenever events or changes in circumstances indicate that carrying amounts may not be recoverable.
For additional information regarding long-lived assets and intangible assets, see Note 4 "Property, Plant & Equipment" and Note 18 "Goodwill and Intangible Assets" in Item 8 "Financial Statements and Supplementary Data."
- RECLAMATION COSTS
Reclamation costs resulting from normal use of long-lived assets are recognized over the period the asset is in use when there is a legal obligation to incur these costs upon retirement of the assets. Additionally, reclamation costs resulting from normal use under a mineral lease are recognized over the lease term when there is a legal obligation to incur these costs upon expiration of the lease. The obligation, which cannot be reduced by estimated offsetting cash flows, is recorded at fair value as a liability at the obligating event date and is accreted through charges to operating expenses. This fair value is also capitalized as part of the carrying amount of the underlying asset and depreciated over the estimated useful life of the asset. If the obligation is settled for other than the carrying amount of the liability, a gain or loss is recognized on settlement.
Reclamation costs are considered a critical accounting policy because of the significant estimates, assumptions and judgment used to determine the fair value of the obligation and the significant carrying amount of these obligations ($226.6 million as of December 31, 2015 and $226.6 million as of December 31, 2014).
HOW WE DETERMINE FAIR VALUE OF THE OBLIGATION
To determine the fair value of the obligation, we estimate the cost (including a reasonable profit margin) for a third party to perform the legally required reclamation tasks. This cost is then increased for both future estimated inflation and an estimated market risk premium related to the estimated years to settlement. Once calculated, this cost is discounted to fair value using present value techniques with a credit-adjusted, risk-free rate commensurate with the estimated years to settlement.
We evaluate current facts and conditions to determine the most likely settlement date. If this evaluation identifies alternative estimated settlement dates, we use a weighted-average settlement date considering the probabilities of each alternative.
We review reclamation obligations at least annually for a revision to the cost or a change in the estimated settlement date. Additionally, reclamation obligations are reviewed in the period that a triggering event occurs that would result in either a revision to the cost or a change in the estimated settlement date. Examples of events that would trigger a change in the cost include a new reclamation law or amendment of an existing mineral lease. Examples of events that would trigger a change in the estimated settlement date include the acquisition of additional reserves or the closure of a facility.
For additional information regarding reclamation obligations (referred to in our financial statements as asset retirement obligations), see Note 17 "Asset Retirement Obligations" in Item 8 "Financial Statements and Supplementary Data."
| Part II | 52 |
- PENSION AND OTHER POSTRETIREMENT BENEFITS
Accounting for pension and postretirement benefits requires that we make significant assumptions regarding the valuation of benefit obligations and the performance of plan assets. Each year we review the following primary assumptions:
| § | DISCOUNT RATE — The discount rate is used in calculating the present value of projected benefit payments |
|---|
| § | EXPECTED RETURN ON PLAN ASSETS — The expected future return on plan assets reduces the recorded net benefit costs |
|---|
| § | RATE OF COMPENSATION INCREASE — Annual pay increases after 2015 will not increase our pension plan obligations as a result of a 2013 plan amendment |
|---|
| § | RATE OF INCREASE IN THE PER CAPITA COST OF COVERED HEALTHCARE BENEFITS — Future increases in the per capita cost will not increase our postretirement medical benefits obligation as a result of a 2012 plan amendment to cap medical coverage cost at the 2015 level |
|---|
HOW WE SET OUR ASSUMPTIONS
In selecting the discount rate, we consider the yield on high-quality bonds with a duration equal to the duration of plan liabilities. At December 31, 2015, the discount rates for our various plans ranged from 3.53% to 4.68% (December 31, 2014 ranged from 3.50% to 4.30%).
In estimating the expected return on plan assets, we consider past performance and long-term future expectations for the types of investments held by the plan as well as the expected long-term allocation of plan assets to these investments. At December 31, 2015, the expected return on plan assets remains at 7.50%.
Changes to the assumptions listed above would have an impact on the projected benefit obligations and the annual net benefit cost. The following table reflects the favorable and unfavorable outcomes associated with a change in certain assumptions:
| (Favorable) Unfavorable | |||||||||||
| 0.5 Percentage Point Increase | 0.5 Percentage Point Decrease | ||||||||||
| Inc (Dec) in | Inc (Dec) in | Inc (Dec) in | Inc (Dec) in | ||||||||
| in millions | Benefit Obligation | Annual Benefit Cost | Benefit Obligation | Annual Benefit Cost | |||||||
| Actuarial Assumptions | |||||||||||
| Discount rate | |||||||||||
| Pension | $ (58.9) | $ (1.3) | $ 65.4 | $ 1.3 | |||||||
| Other postretirement benefits | (1.3) | 0.0 | 1.4 | 0.0 | |||||||
| Expected return on plan assets | not applicable | (3.6) | not applicable | 3.6 |
As of the December 31, 2015 measurement date, the fair value of our pension plan assets decreased annually from $817.0 million to $745.7 million due to unfavorable investment returns and lump-sum settlement payments to a group of terminated vested participants. No contributions were made to the qualified pension plans in 2015.
During 2016, we expect to recognize net pension credit of approximately $(6.2) million and net postretirement credit of approximately $(3.7) million compared to expenses of $15.9 million and $0.2 million, respectively, in 2015. The decreases are primarily due to a change in estimate. Beginning in 2016, we are changing the method we use to estimate the service and interest cost components of net periodic benefit cost for our defined benefit pension and other postretirement benefit plans. Historically, we estimated the service and interest cost components using a single weighted-average discount rate derived from the yield curve used to measure the benefit obligation at the beginning of the period. Beginning in 2016, we elected to utilize a full yield curve approach to estimate the service and interest cost, applying the specific spot rates along the yield curve to the relevant projected cash flows.
| Part II | 53 |
We are making this change to provide a more precise measurement of service and interest costs by improving the correlation between projected benefit cash flows to the corresponding yield curve spot rates. This change will not affect the measurement of our total benefit obligations as the change in the service cost and interest cost is completely offset in the actuarial (gain) loss reported.
We are accounting for this change as a change in estimate and, accordingly, are accounting for it prospectively starting in 2016. The estimated weighted-average discount rates used to measure service and interest costs for 2016 are 4.89% and 3.80%, respectively, for our pension plans and 4.05% and 2.81%, respectively, for our other postretirement plans. The weighted-average discount rates that we would have used for service and interest costs under our prior estimation technique were 4.54% for the pension plans and 3.69% for the other postretirement plans. The reductions in benefit cost for 2016 associated with this change are estimated to be $7.2 million and $0.5 million for our pension and other postretirement plans, respectively.
We do not anticipate contributions will be required to the funded pension plans during 2016 and we do not anticipate making a discretionary contribution. We currently do not anticipate that the funded status of any of our plans will fall below statutory thresholds requiring accelerated funding or constraints on benefit levels or plan administration.
For additional information regarding pension and other postretirement benefits, see Note 10 "Benefit Plans" in Item 8 "Financial Statements and Supplementary Data."
- ENVIRONMENTAL COMPLIANCE COSTS
Our environmental compliance costs include the cost of ongoing monitoring programs, the cost of remediation efforts and other similar costs. Our accounting policy for environmental compliance costs is a critical accounting policy because it involves the use of significant estimates and assumptions and requires considerable management judgment.
HOW WE ACCOUNT FOR ENVIRONMENTAL COSTS
To account for environmental costs, we:
| § | expense or capitalize environmental costs consistent with our capitalization policy |
|---|
| § | expense costs for an existing condition caused by past operations that do not contribute to future revenues |
|---|
| § | accrue costs for environmental assessment and remediation efforts when we determine that a liability is probable and we can reasonably estimate the cost |
|---|
At the early stages of a remediation effort, environmental remediation liabilities are not easily quantified due to the uncertainties of various factors. The range of an estimated remediation liability is defined and redefined as events in the remediation effort occur, but generally liabilities are recognized no later than completion of the remedial feasibility study. When we can estimate a range of probable loss, we accrue the most likely amount. In the event that no amount in the range of probable loss is considered most likely, the minimum loss in the range is accrued. As of December 31, 2015, the difference between the amount accrued and the maximum loss in the range for all sites for which a range can be reasonably estimated was $3.2 million. Our environmental remediation obligations are recorded on an undiscounted basis.
Accrual amounts may be based on technical cost estimations or the professional judgment of experienced environmental managers. Our Safety, Health and Environmental Affairs Management Committee routinely reviews cost estimates and key assumptions in response to new information, such as the kinds and quantities of hazardous substances, available technologies and changes to the parties participating in the remediation efforts. However, a number of factors, including adverse agency rulings and unanticipated conditions as remediation efforts progress, may cause actual results to differ materially from accrued costs.
For additional information regarding environmental compliance costs, see Note 8 "Accrued Environmental Remediation Costs" in Item 8 "Financial Statements and Supplementary Data."
| Part II | 54 |
- CLAIMS AND LITIGATION INCLUDING SELF-INSURANCE
We are involved with claims and litigation, including items covered under our self-insurance program. We are self-insured for losses related to workers' compensation up to $2.0 million per occurrence and automotive and general/product liability up to $3.0 million per occurrence. We have excess coverage on a per occurrence basis beyond these retention levels.
Under our self-insurance program, we aggregate certain claims and litigation costs that are reasonably predictable based on our historical loss experience and accrue losses, including future legal defense costs, based on actuarial studies. Certain claims and litigation costs, due to their unique nature, are not included in our actuarial studies. For matters not included in our actuarial studies, legal defense costs are accrued when incurred.
Our accounting policy for claims and litigation including self-insurance is a critical accounting policy because it involves the use of significant estimates and assumptions and requires considerable management judgment.
HOW WE ASSESS THE PROBABILITY OF LOSS
We use both internal and outside legal counsel to assess the probability of loss, and establish an accrual when the claims and litigation represent a probable loss and the cost can be reasonably estimated. Significant judgment is used in determining the timing and amount of the accruals for probable losses, and the actual liability could differ materially from the accrued amounts.
For additional information regarding claims and litigation including self-insurance, see Note 1 "Summary of Significant Accounting Policies" in Item 8 "Financial Statements and Supplementary Data" under the caption Claims and Litigation Including Self-insurance.
- INCOME TAXES
VALUATION OF OUR DEFERRED TAX ASSETS
We file federal, state and foreign income tax returns and account for the current and deferred tax effects of such returns using the asset and liability method. We recognize deferred tax assets and liabilities (which reflect our best assessment of the future taxes we will pay) based on the differences between the financial statement’s carrying amounts of assets and liabilities and the amounts used for income tax purposes. Deferred tax assets represent items to be used as a tax deduction or credit in future tax returns while deferred tax liabilities represent items that will result in additional tax in future tax returns.
Significant judgments and estimates are required in determining our deferred tax assets and liabilities. These estimates are updated throughout the year to consider income tax return filings, our geographic mix of earnings, legislative changes and other relevant items.
Each quarter we analyze the likelihood that our deferred tax assets will be realized. Realization of the deferred tax assets ultimately depends on the existence of sufficient taxable income of the appropriate character in either the carryback or carryforward period. A valuation allowance is recorded if, based on the weight of all available positive and negative evidence, it is more likely than not (a likelihood of more than 50%) that some portion, or all, of a deferred tax asset will not be realized. A summary of our deferred tax assets is included in Note 9 “Income Taxes” in Item 8 “Financial Statements and Supplementary Data.”
At December 31, 2015, we have state net operating loss carryforward deferred tax assets of $61.7 million, against which we have a valuation allowance of $55.2 million. Of the deferred tax assets, $58.9 million relates to Alabama.
From 2008 through the second quarter of 2015, we carried a full valuation allowance against the Alabama deferred tax asset for the following reasons:
| § | due to our legal entity structure, we had no expectation of creating taxable income in Alabama |
|---|
| § | we had a substantial cumulative loss in Alabama |
|---|
During the second quarter of 2015, we restructured our legal entities. Among other benefits, we anticipated that the restructuring would generate significant taxable income in Alabama, and therefore, allow for the utilization of some or all of the Alabama deferred tax asset.
Our Alabama cumulative loss is calculated as pretax earnings from continuing operations, discontinued operations and other comprehensive income plus permanent differences over the last three years. While evaluating all available positive and
| Part II | 55 |
negative evidence, realizing the significance of the restructuring in our Alabama income tax filing, we determined that it was appropriate to adjust our Alabama cumulative loss calculation to consider the restructuring, remove pretax earnings from discontinued operations and other comprehensive income and remove any other significant nonrecurring items. We refer to this calculation as our Alabama adjusted earnings.
At the end of the second quarter, our Alabama adjusted earnings were negative. However, the Alabama adjusted earnings loss was dramatically smaller than our Alabama cumulative loss. Of the three adjustments made, the restructuring had the greatest impact. In addition, we considered all other forms of positive and negative evidence, including the four sources of taxable income. The first three sources of taxable income (carryback potential, reversing temporary differences and tax planning strategies) provided very little positive evidence. Because our Alabama adjusted earnings were a loss, we did not project future Alabama taxable income (the fourth source). As a result, during the second quarter we continued to carry a full valuation allowance against our Alabama deferred tax asset.
At the end of the third quarter, our Alabama adjusted earnings turned positive. This development provided sufficient positive evidence such that we determined it was appropriate to utilize projections of future Alabama taxable income in our assessment for the first time. However, because we had not yet returned to sustained profitability (i.e., three consecutive years of positive Alabama adjusted earnings) we used our Alabama trailing twelve months adjusted earnings as the basis for an objectively verifiable projection of future Alabama taxable income. This projection, in addition to considering all other positive and negative evidence, led us to conclude in the third quarter that it was more likely than not that $4.7 million of the deferred tax asset was realizable. Therefore, we recognized a deferred tax benefit of $4.7 million in the third quarter by reducing the valuation allowance. Our fourth quarter analysis further confirmed our third quarter conclusions but resulted in no further reductions of the valuation allowance.
We believe that if, or when, we have three consecutive years of positive Alabama adjusted earnings, we will have sufficient positive evidence to conclude that we have returned to sustained profitability and will no longer limit our estimate of future taxable income to our Alabama trailing twelve months adjusted earnings. At that time, we expect to realize a significant portion, if not all, of the Alabama deferred tax asset. We project that the earliest this could happen would be the fourth quarter of 2016.
LIABILITY FOR UNRECOGNIZED TAX BENEFITS
We recognize a tax benefit associated with a tax position when, in our judgment, it is more likely than not that the position will be sustained based upon the technical merits of the position. For a tax position that meets the more likely than not recognition threshold, we measure the income tax benefit as the largest amount that we judge to have a greater than 50% likelihood of being realized. A liability is established for the unrecognized portion of any tax position. Our liability for unrecognized tax benefits is adjusted periodically due to changing circumstances, such as the progress of tax audits, case law developments and new or emerging legislation.
The years open to tax examinations vary by jurisdiction. While it is often difficult to predict the final outcome or the timing of resolution of any particular tax matter, we believe our liability for unrecognized tax benefits is appropriate.
We consider a tax position to be resolved at the earlier of the issue being “effectively settled,” settlement of an examination, or the expiration of the statute of limitations. Upon resolution of a tax position, any liability for unrecognized tax benefits will be released.
Our liability for unrecognized tax benefits is generally presented as noncurrent. However, if we anticipate paying cash within one year to settle an uncertain tax position, the liability is presented as current. We classify interest and penalties associated with our liability for unrecognized tax benefits as income tax expense.
NEW ACCOUNTING STANDARDS
For a discussion of accounting standards recently adopted and pending adoption and the effect such accounting changes will have on our results of operations, financial position or liquidity, see Note 1 "Summary of Significant Accounting Policies" in Item 8 "Financial Statements and Supplementary Data" under the caption New Accounting Standards.
| Part II | 56 |
FORWARD-LOOKING STATEMENTS
The foregoing discussion and analysis, as well as certain information contained elsewhere in this Annual Report, contain "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, and are intended to be covered by the safe harbor created thereby. See the discussion in Safe Harbor Statement under the Private Securities Litigation Reform Act of 1995 in Part I, above.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK