 filings.tools
Vulcan Materials 10-K 2018-12-31
Filed 2019-02-26. 22 sections, 435K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 vmc-20181231x10k.htm 10-K
| UNITED STATES SECURITIES AND EXCHANGE COMMISSION Washington, D.C. 20549 FORM 10-K ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 For the Fiscal Year Ended December 31, 2018 Commission file number: 001-33841 VULCAN MATERIALS COMPANY (Exact Name of Registrant as Specified in Its Charter) | ||
| New Jersey (State or other jurisdiction of incorporation or organization) | 20-8579133 (I.R.S. Employer Identification No.) | |
| 1200 Urban Center Drive, Birmingham, Alabama 35242 (Address of Principal Executive Offices) (Zip Code) (205) 298-3000 (Registrant’s telephone number, including area code) | ||
| Securities registered pursuant to Section 12(b) of the Act: | ||
| Title of each class Common Stock, $1 par value | Name of each exchange on which registered New York Stock Exchange | |
| Securities registered pursuant to Section 12(g) of the Act: None | ||
| Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☑ No ☐ Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☑ Indicate by check mark whether the registrant: (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☑ No ☐ Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☑ No ☐ Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. ☑ Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company” and “emerging growth company” in Rule 12b-2 of the Exchange Act. Large accelerated filer ☑ Accelerated filer ☐ Smaller reporting company ☐ Non-accelerated filer ☐ Emerging growth company ☐ If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐ Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ☐ No ☑ |
| Aggregate market value of voting and non-voting common stock held by non-affiliates as of June 29, 2018: | $17,035,024,582 |
| Number of shares of common stock, $1.00 par value, outstanding as of February 12, 2019: | 131,830,868 |
| DOCUMENTS INCORPORATED BY REFERENCE | |
| Portions of the registrant’s annual proxy statement for the annual meeting of its shareholders to be held on May 10, 2019, are incorporated by reference into Part III of this Annual Report on Form 10-K. |
Unless otherwise stated or the context otherwise requires, references in this report to “Vulcan,” the “Company,” “we,” “our,” or “us” refer to Vulcan Materials Company and its consolidated subsidiaries.
| Table of Contents | i |
PART I
“SAFE HARBOR” STATEMENT UNDER THE PRIVATE SECURITIES LITIGATION REFORM ACT OF 1995
Certain of the matters and statements made herein or incorporated by reference into this report constitute forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934. All such statements are made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. These statements reflect our intent, belief or current expectation. Often, forward-looking statements can be identified by the use of words, such as “anticipate,” “may,” “believe,” “estimate,” “project,” “expect,” “intend” and words of similar import. In addition to the statements included in this report, we may from time to time make other oral or written forward-looking statements in other filings under the Securities Exchange Act of 1934 or in other public disclosures. Forward-looking statements are not guarantees of future performance, and actual results could differ materially from those indicated by the forward-looking statements. All forward-looking statements involve certain assumptions, risks and uncertainties that could cause actual results to differ materially from those included in or contemplated by the statements. These assumptions, risks and uncertainties include, but are not limited to:
| § | general economic and business conditions |
|---|
| § | the timing and amount of federal, state and local funding for infrastructure |
|---|
| § | changes in the level of spending for private residential and private nonresidential construction |
|---|
| § | changes in our effective tax rate |
|---|
| § | the increasing reliance on information technology infrastructure for our ticketing, procurement, financial statements and other processes could adversely affect operations in the event that the infrastructure does not work as intended or experiences technical difficulties or is subjected to cyber-attacks |
|---|
| § | the impact of the state of the global economy on our businesses and financial condition and access to capital markets |
|---|
| § | the highly competitive nature of the construction materials industry |
|---|
| § | the impact of future regulatory or legislative actions, including those relating to climate change, wetlands, greenhouse gas emissions, the definition of minerals, tax policy or international trade |
|---|
| § | the outcome of pending legal proceedings |
|---|
| § | pricing of our products |
|---|
| § | weather and other natural phenomena, including the impact of climate change |
|---|
| § | energy costs |
|---|
| § | costs of hydrocarbon-based raw materials |
|---|
| § | healthcare costs |
|---|
| § | the amount of long-term debt and interest expense we incur |
|---|
| § | changes in interest rates |
|---|
| § | volatility in pension plan asset values and liabilities, which may require cash contributions to the pension plans |
|---|
| § | the impact of environmental cleanup costs and other liabilities relating to existing and/or divested businesses |
|---|
| § | our ability to secure and permit aggregates reserves in strategically located areas |
|---|
| § | our ability to manage and successfully integrate acquisitions |
|---|
| § | the effect of changes in tax laws, guidance and interpretations, including those related to the Tax Cuts and Jobs Act that was enacted in December 2017 |
|---|
| § | significant downturn in the construction industry may result in the impairment of goodwill or long-lived assets |
|---|
| § | changes in technologies, which could disrupt the way we do business and how our products are distributed |
|---|
| § | the risks set forth in Item 1A “Risk Factors,” Item 3 “Legal Proceedings,” Item 7 “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” and Note 12 “Commitments and Contingencies” to the consolidated financial statements in Item 8 “Financial Statements and Supplementary Data,” all as set forth in this report |
|---|
| § | other assumptions, risks and uncertainties detailed from time to time in our filings made with the Securities and Exchange Commission |
|---|
| Part I | 1 |
All forward-looking statements are made as of the date of filing or publication. We undertake no obligation to publicly update any forward-looking statements, whether as a result of new information, future events or otherwise, except to the extent required by law. Investors are cautioned not to rely unduly on such forward-looking statements when evaluating the information presented in our filings, and are advised to consult any of our future disclosures in filings made with the Securities and Exchange Commission and our press releases with regard to our business and consolidated financial position, results of operations and cash flows.
| Part I | 2 |
Item 1. BUSINESS
BUSINESS
Vulcan Materials Company, a New Jersey corporation, operates primarily in the U.S. and is the nation’s largest supplier of construction aggregates (primarily crushed stone, sand and gravel) and a major producer of asphalt mix and ready-mixed concrete. We provide the basic materials for the infrastructure needed to maintain and expand the U.S. economy. Delivered by trucks, ships, barges and trains, our products are the indispensable materials building homes, offices, places of worship, schools, hospitals and factories, as well as vital infrastructure including highways, bridges, roads, ports and harbors, water systems, campuses, dams, airports and rail networks. As of December 31, 2018, we had 351 active aggregates facilities, 67 asphalt facilities and 46 concrete facilities.
BUSINESS STRATEGY
Our strategy and competitive advantage are based on our strength in aggregates which are used in most types of construction and in the production of asphalt mix and ready-mixed concrete. Our strategy for long-term value creation is built on: (1) an aggregates-focused business, (2) a disciplined approach to portfolio management and capital allocation, (3) a focus on continuous compounding improvement in profitability, (4) a holistic approach to land management, and (5) our commitment to safety, health and the environment.
- AGGREGATES FOCUS
Aggregates are used in virtually all types of public and private construction and practically no substitutes for quality aggregates exist. Given our focus on aggregates, we:
BUILD AND HOLD SUBSTANTIAL RESERVES: Our reserves are critical to our long-term success. We currently have 16.3 billion tons of permitted and proven or probable aggregates reserves. They are strategically located throughout the United States in high-growth areas that are expected to require large amounts of aggregates to meet future construction demand. Moreover, there are significant barriers to entry in many metropolitan markets due to stringent zoning and permitting regulations. These restrictions curtail expansion in certain areas, but they also increase the value of our reserves at existing locations. Our downstream businesses (asphalt and concrete) use Vulcan-produced aggregates almost exclusively.
TAKE ADVANTAGE OF SIZE AND SCALE: We are the largest aggregates supplier in the U.S. Our 351 active aggregates facilities as of December 31, 2018 provide opportunities to standardize operating practices and procure equipment (fixed and mobile), parts, supplies and services in an efficient and cost-effective manner, both regionally and nationally. Each aggregates operation is also unique because of its location within a local market and its particular geological characteristics. Every operation, however, uses a similar group of assets to produce saleable aggregates and provide customer service. Additionally, we are able to share best practices across the organization and leverage our size for administrative support, customer service, accounting, procurement, technical support and engineering.
| Part I | 3 |
- PORTFOLIO MANAGEMENT AND CAPITAL ALLOCATION
Demand for our products is dependent on construction activity and correlates positively with changes in population growth, household formation and employment. During the period 2020 - 2030, Moody's Analytics projects that 80% of the U.S. population growth, 73% of household formation and 64% of new jobs will occur in Vulcan-served states. The close proximity of our production facilities and our aggregates reserves to this projected population growth creates many opportunities to invest capital in high-return projects.
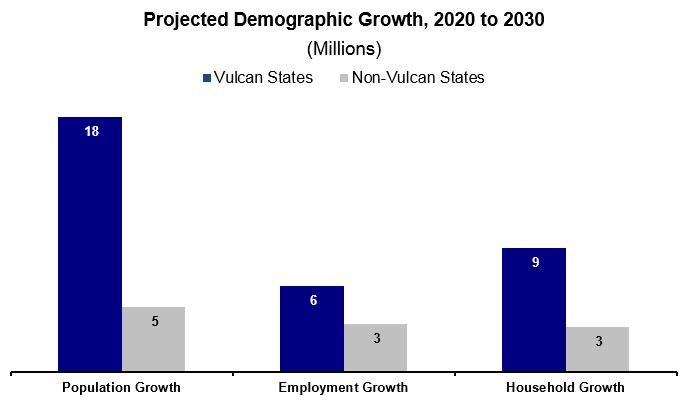
Source: Moody’s Analytics as of December 14, 2018
We have pursued a strategy to increase our presence in U.S. metropolitan areas that are expected to grow the most rapidly and by divesting assets that are no longer considered part of our long-term growth strategy. Our coast-to-coast footprint serves 19 of the top 25 highest-growth U.S. metropolitan areas in 20 states plus the District of Columbia.
Our top ten revenue producing states accounted for 86% of our 2018 revenues while our top five accounted for 61%.
| VULCAN’S TOP TEN REVENUE PRODUCING STATES IN 2018 | ||||||||||||
| 1. | California | 6. | Florida | |||||||||
| 2. | Texas | 7. | Arizona | |||||||||
| 3. | Virginia | 8. | North Carolina | |||||||||
| 4. | Tennessee | 9. | South Carolina | |||||||||
| 5. | Georgia | 10. | Alabama |
| Part I | 4 |
| § | portfolio management: Since becoming a public company in 1957, Vulcan has principally grown by mergers and acquisitions. For example, in 1999 we acquired CalMat Co., thereby expanding our aggregates operations into California and Arizona and making us one of the nation’s leading producers of asphalt mix. In 2007, we acquired Florida Rock Industries, Inc. This acquisition expanded our aggregates business in Florida and our aggregates and ready-mixed concrete businesses in other Southeastern and Mid-Atlantic states. In 2017, we acquired Aggregates USA — this acquisition greatly expanded our ability to serve customers in Florida, Georgia and South Carolina. |
|---|
Additionally, throughout our history we have completed many bolt-on acquisitions that have contributed significantly to our growth. We closed seven additional acquisitions in 2017 that complement our existing positions in Arizona, California, Illinois, New Mexico, Tennessee, and Virginia. From 2015 to 2017, we invested over $1.2 billion in acquisitions and internal projects for long-term growth, while further strengthening our portfolio through divestitures and swaps, including swapping our concrete operations in Arizona for asphalt operations in Arizona during 2017.
While an aggregates-focused business, we selectively make investments in downstream products that drive local market profitability. In January 2017, we entered the asphalt market in Tennessee through the acquisition of several asphalt mix operations and a construction paving business. During 2018, we entered the asphalt mix and construction paving markets in Alabama and expanded our asphalt operations and service offerings in Texas through the acquisition of several asphalt mix operations and construction paving businesses.
| § | capital allocation: Our long-term strategy around capital allocation has given us the ability to leverage decisions we have made over the past few years. During 2018, we reinvested $469.1 million into core operating, internal growth and maintenance capital expenditures, in addition to $459.6 million reinvested in 2017. These investments are fundamental actions that strengthen the business. They improve the longer-term efficiency, capacity and flexibility of our production, and they support our strong commitment to superior customer service. |
|---|
- compounding improvement in profitability
Our focus on the following three major profit drivers has made us one of the most profitable public companies in the industry (as measured by aggregates gross profit per ton).
| § | Price for Service — We seek to receive full and fair value for the quality of products and services we provide. We should be paid appropriately for helping our customers be successful. Our expanding margins will continue to benefit from the compounding pricing gains associated with cyclical recoveries. |
|---|
| § | Operating Efficiency and Leverage — We focus on rigorous cost management throughout the economic cycle. Small savings per ton add up to significant cost reductions. We are operating a capital-intensive business well below full capacity and are extremely well positioned to further leverage fixed costs on incremental sales as we move forward. |
|---|
| § | Sales and Production Mix — We adjust production levels to meet varying market conditions. Managing inventories responsibly results in improved cost performance and an improved return on capital. As the recovery continues and as we see a larger portion of new construction activity in the end-use mix, we will sell the entire production mix much more efficiently and at fuller value. |
|---|
We manage these factors locally and align our talent and incentives accordingly. Our knowledgeable and experienced workforce and our flexible production capabilities allow us to manage operational and overhead costs aggressively. Recovery in demand serves as a tailwind for all three major profit drivers.
| Part I | 5 |
- LAND MANAGEMENT
With approximately 240,000 acres in our land portfolio, a long-term holistic approach to preserving land and water is integral to sustaining our success. From pre-mining to mining to reclamation, we are actively managing the entire life cycle of our land, creating maximum value for the business, our shareholders and our communities.
We are putting land to use before we mine by creating opportunities for agriculture and timber development. After mining, our land and water assets will be converted to other valuable uses including drinking water reservoirs, aquifer recharge basins, public parks, habitat mitigation banks, wetlands, productive farmland and residential and commercial developments.
Because of the evolving needs of our communities, we listen to and collaborate with our neighbors to prepare the land for its highest and best use after mining is complete. Our work with state, regional and local governments to develop solutions today will benefit future generations.
- SAFETY, HEALTH AND THE ENVIRONMENT
A strategy for sustainable, long-term value creation must include doing right by your employees, your neighbors and the environment in which you operate. We are a leader in our industry in safety performance by applying the shared experiences, expertise and resources at each of our locally led sites with an emphasis on taking care of one another. We focus on our environmental stewardship programs with the same intensity that we bring to our health and safety initiatives. And, our community relations programs serve our neighbors, while ensuring that we grow and thrive in the communities where we operate.
PRODUCT LINES
Our products are used to build the roads, tunnels, bridges, railroads and airports that connect us, and to build the hospitals, schools, shopping centers, factories and places of worship that are essential to our lives and the economy. We have four operating (and reportable) segments organized around our principal product lines:
| 1. | Aggregates – 74% of 2018’s total revenues and 90% of gross profit |
|---|
| 2. | Asphalt – 17% of 2018’s total revenues and 5% of gross profit |
|---|
| 3. | Concrete – 9% of 2018’s total revenues and 5% of gross profit |
|---|
| 4. | Calcium – less than 1% of 2018’s total revenues and less than 1% of gross profit |
|---|
See Note 15 “Segment Reporting” in Item 8 “Financial Statements and Supplementary Data.”
- AGGREGATES
Our construction aggregates are used in a number of ways:
| § | as a base material underneath highways, walkways, airport runways, parking lots and railroads |
|---|
| § | to aid in water filtration, purification and erosion control |
|---|
| § | as a raw material used in combination with other resources to construct many of the items we rely on to sustain our quality of life including: |
|---|
| § | houses and apartments |
|---|
| § | roads, bridges and parking lots |
|---|
| § | schools and hospitals |
|---|
| § | commercial buildings and retail space |
|---|
| § | sewer systems |
|---|
| § | power plants |
|---|
| § | airports and runways |
|---|
| Part I | 6 |
AGGREGATES INDUSTRY
Factors that affect the U.S. aggregates industry and our business include:
| § | Location of reserves: Aggregates have a high weight-to-value ratio and, in most cases, must be produced near where they are used; if not, transportation can cost more than the materials, rendering them uncompetitive compared to locally produced materials. Exceptions to this typical market structure include areas along the U.S. Gulf Coast and the Eastern Seaboard where there are limited supplies of locally available, high-quality aggregates. We serve these markets from quarries that have access to cost-effective long-haul transportation — shipping by barge and rail — and from our quarry on Mexico’s Yucatan Peninsula with our fleet of Panamax-class, self-unloading ships. |
|---|
Where practical, we have operations located close to our local markets because the cost of trucking materials long distances is prohibitive. Approximately 80% of our total aggregates shipments are delivered exclusively from the producing location to the customer by truck, and another 15% are delivered by truck after reaching a sales yard by rail or water. The remaining 5% of aggregates shipments are delivered directly to the customer by rail or water.
| § | Limited product substitution: There are limited substitutes for quality aggregates. Recycled concrete and asphalt have certain applications as a lower-cost alternative to virgin aggregates. However, many types of construction projects cannot be served by recycled concrete and require the use of virgin aggregates to meet technical specifications and performance-based criteria for durability, strength and other qualities. Moreover, the amount of recycled asphalt included in asphalt mix as a substitute for aggregates is limited due to specifications. |
|---|
| § | Highly fragmented industry: The U.S. aggregates industry is composed of over 5,800 companies that manage more than 10,600 operations. This fragmented structure provides many opportunities for consolidation. Companies in the industry commonly enter new markets or expand positions in existing markets through the acquisition of existing facilities. |
|---|
Through strategic acquisitions and investments, we have developed an unmatched coast-to-coast footprint of strategically located permitted reserves concentrated in and serving the nation’s key growth centers. We have over 23,000 customers in 20 states, the District of Columbia, Mexico and the Bahamas.
| § | Flexible production capabilities: The production of aggregates is a mechanical process in which stone is crushed and, through a series of screens, separated into various sizes depending on how it will be used. Production capacity can be flexible by adjusting operating hours to meet changing market demand. |
|---|
| § | raw material inputs largely ControlLED: Unlike typical industrial manufacturing industries, the aggregates industry does not require the input of raw material beyond owned or leased aggregates reserves. Stone, sand and gravel are naturally occurring resources. However, production does require the use of explosives, hydrocarbon fuels and electric power. |
|---|
| § | Demand cycles: Long-term growth in demand for aggregates is largely driven by growth in population, jobs and households. While short-term and medium-term demand for aggregates fluctuates with economic cycles, declines have historically been followed by strong recoveries, with each peak establishing a new historical high. |
|---|
The drivers underpinning demand recovery — and sustained, multi-year volume and pricing growth — remain firmly in place, in both the public and private sectors of the economy. They include: population growth; gains in total employment and in household income and wages; a continuing increase in household formations; the growing need for additional housing stock and housing demand; a multi-year federal transportation law in place and continuing increases in transportation funding at state and local levels; record state tax receipts; public investment in infrastructure that is still well below the long-term trend-line, and increasing political awareness and acceptance of the need to invest in infrastructure.
| Part I | 7 |
AGGREGATES MARKETS
We focus on the U.S. markets with above-average long-term expected population growth and where construction is expected to expand. Because transportation is a significant part of the delivered cost of aggregates, our facilities are typically located in the markets they serve or have access to economical transportation via rail, barge or ship to a particular end market. We serve both the public and the private sectors.
Public sector construction activity has historically been more stable and less cyclical than privately-funded construction, and generally requires more aggregates per dollar of construction spending. Private sector construction (primarily residential and nonresidential buildings) typically is more affected by general economic cycles than publicly-funded projects (particularly highways, roads and bridges), which tend to receive more consistent levels of funding throughout economic cycles.
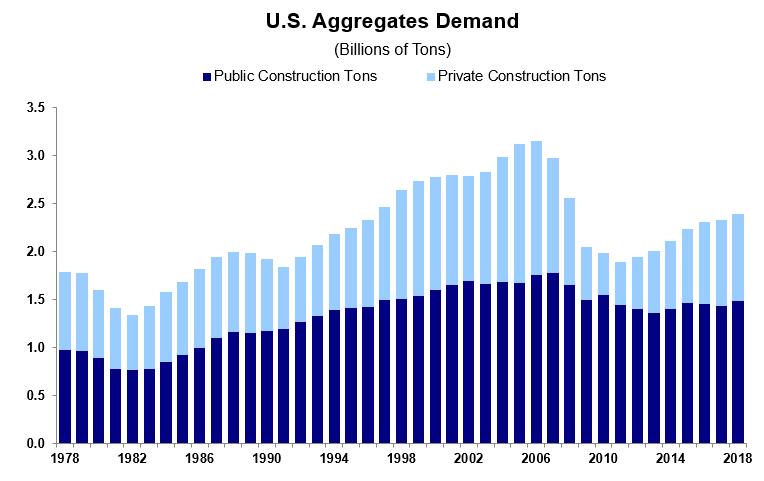
Source: Company estimates
| Part I | 8 |
PUBLIC SECTOR CONSTRUCTION MARKET
Public sector construction includes spending by federal, state, and local governments for highways, bridges, buildings, airports, schools and prisons as well as other infrastructure construction for sewer and waste disposal systems, water supply systems, dams, reservoirs and other public construction projects. Construction for power plants and other utilities is funded from both public and private sources. In 2018, publicly-funded construction accounted for approximately 44% of our total aggregates shipments, and approximately 23% of our aggregates sales by volume were used in highway construction projects.
| § | Public Sector Funding: Generally, public sector construction spending is more stable than private sector construction spending; public sector spending is less sensitive to interest rates and has historically been supported by multi-year laws, which provide certainty in funding amounts, program structures, and rules and regulations. Federal spending is governed by authorization, budget and appropriations laws. The level of state and local spending on infrastructure varies across the United States and depends on individual state needs and economies. |
|---|
| § | STATE AND LOCAL TRANSPORTATION FUNDING: Since 2012, 31 states have approved plans to increase revenues for transportation investment through motor fuel tax increases, revenues outside of fuel taxes, and one-time increases; 13 of those states, representing 81% of our 2018 revenues, are in Vulcan’s footprint. In 2017 alone, 7 state legislatures voted to raise motor fuel taxes for transportation investment. |
|---|
In the November 2018 general election, voters in 31 states approved 79% of 352 state and local transportation funding ballot measures. Major transportation funding measures in Vulcan-served areas are estimated to result in $30 billion in revenues and bond proceeds primarily dedicated to roads, streets and bridges. Including 2018, voters have approved 78% of nearly 1,700 transportation investment ballot measures since 2009.
| § | federal highway funding: In December 2015, President Obama signed a new, long-term federal highway and transit authorization bill, Fixing America’s Surface Transportation Infrastructure Act (FAST Act), into law after the final legislation received strong, bipartisan support in both the House and the Senate. The FAST Act provides multi-year funding to state and local governments in support of road, bridge, intermodal and public transportation projects. |
|---|
The FAST Act increases Federal-Aid Highway Program funding from $41 billion in the federal fiscal year (FFY) 2015 to $47 billion in FFY 2020. In addition, the Bipartisan Budget Act of 2018 added approximately $2 billion per year to base highway programs in 2018 and 2019.
The long-term nature of the FAST Act is important. The Federal-Aid Highway Program is the largest component of the law and has provided, on average, 52% of all state capital investment in roads and bridges over the last 10 years. This multi-year authorization and the associated dedicated funding provides state departments of transportation with the ability to plan and execute long-range, complex highway projects.
The FAST Act also contains important policy changes. To further accelerate the project delivery process, it augments the environmental review and permitting process reforms contained in the prior law, Moving Ahead for Progress in the 21st Century Act (MAP-21). The new law also provides assistance for states making investments in major capital projects — particularly freight projects. In states where we operate, we are well positioned to serve the large general contractors who will compete for new freight and other major capacity projects that will move forward with this FAST Act funding and policy implementation.
Project financing remains an important additional component of overall surface transportation spending, with the Transportation Infrastructure Finance & Innovation Act (TIFIA) program authorized at $275 million (in line with the previous program outlays) and growing to $300 million by 2020. The FAST Act also created a new National Surface Transportation and Innovative Finance Bureau to provide technical assistance to states seeking to pursue public-private partnerships and other financing arrangements for transportation projects.
| Part I | 9 |
| § | FEDERAL WATER INFRASTRUCTURE: In October 2018, President Trump signed America’s Water Infrastructure Act of 2018 (AWIA 2018) into law. The new law includes the Water Resources Development Act of 2018 (WRDA 2018), which reauthorizes needed investment in America’s ports, channels, locks, dams, and other infrastructure that supports the maritime and waterways transportation system and provides flood protection for communities. It also improves EPA programs for storm water, water recycling, and sewer overflow projects. Included in AWIA 2018 are improvements to the Water Infrastructure Finance and Innovation Act (WIFIA) program, which was modeled after the highly popular TIFIA program in the surface transportation sector. Created in the Water Resources Reform and Development Act of 2014 (WRRDA 2014), WIFIA allows for federal credit assistance to water resources projects in the form of low-cost loans, loan guarantees and lines of credit. |
|---|
In addition to these regular authorizations, $89.3 billion in immediate federal emergency supplemental appropriations was provided for disaster recovery in the Bipartisan Budget Act of 2018 for hurricane-affected areas in Florida, Louisiana, Texas and other states. A portion of these funds will be directed to long-term and short-term U.S. Army Corps of Engineers-supported flood control and other water resources construction projects as well as additional infrastructure projects that use aggregates and related materials.
Private sector CONSTRUCTION MARKET
The private sector construction markets include both nonresidential building construction and residential construction and are considerably more cyclical than public construction. In 2018, privately-funded construction accounted for approximately 56% of our total aggregates shipments.
| § | Nonresidential Construction: Private nonresidential building construction includes a wide array of projects. Such projects generally are more aggregates intensive than residential construction. Overall demand in private nonresidential construction generally is driven by job growth, vacancy rates, private infrastructure needs and demographic trends. The growth of the private workforce creates demand for offices, hotels and restaurants. Likewise, population growth generates demand for stores, shopping centers, warehouses and parking decks as well as hospitals, places of worship and entertainment facilities. Large industrial projects, such as a new manufacturing facility, can increase the need for other manufacturing plants to supply parts and assemblies. Construction activity in this end market is influenced by a firm's ability to finance a project and the cost of such financing. This end market also includes capital investments in public nonresidential facilities to meet the needs of a growing population. |
|---|
| § | Residential Construction: Household formations in Vulcan-served states continue to outpace household formations in the rest of the United States. The majority of residential construction is for single-family housing with the remainder consisting of multi-family construction (i.e., two family houses, apartment buildings and condominiums). Public housing comprises only a small portion of housing demand. Construction activity in this end market is influenced by the cost and availability of mortgage financing and builders’ ability to maintain skilled labor. |
|---|
U.S. housing starts, as measured by Dodge Data & Analytics data, peaked in early 2006 at over 2 million units annually. By the end of 2009, total housing starts had declined to less than 0.6 million units, well below prior historical lows of approximately 1 million units annually. In 2018, total annual housing starts in the U.S. reached 1.35 million units.
ADDITIONAL AGGREGATES PRODUCTS AND MARKETS
We sell aggregates that are used as ballast for construction and maintenance of railroad tracks. We also sell riprap and jetty stone for erosion control along roads and waterways. In addition, stone can be used as a feedstock for cement and lime plants and for making a variety of adhesives, fillers and extenders. Coal-burning power plants use limestone in scrubbers to reduce harmful emissions. Limestone that is crushed to a fine powder can be sold as agricultural lime.
We sell a relatively small amount of construction aggregates outside of the United States, principally in the areas surrounding our large quarry on the Yucatan Peninsula in Mexico. Nondomestic sales and long-lived assets outside the United States are reported in Note 15 “Segment Reporting” in Item 8 “Financial Statements and Supplementary Data.”
| Part I | 10 |
VERTICAL INTEGRATION
While aggregates is our focus and primary business, we believe vertical integration between aggregates and downstream products, such as asphalt mix and ready-mixed concrete, can be managed effectively in certain markets generating acceptable financial returns and enhancing financial returns in our core Aggregates segment. We produce and sell asphalt mix and/or ready-mixed concrete primarily in our Alabama, mid-Atlantic, Southwestern, Tennessee and Western markets. Aggregates comprise approximately 95% of asphalt mix by weight and 80% of ready-mixed concrete by weight. In both of these downstream businesses, aggregates are primarily supplied from our operations.
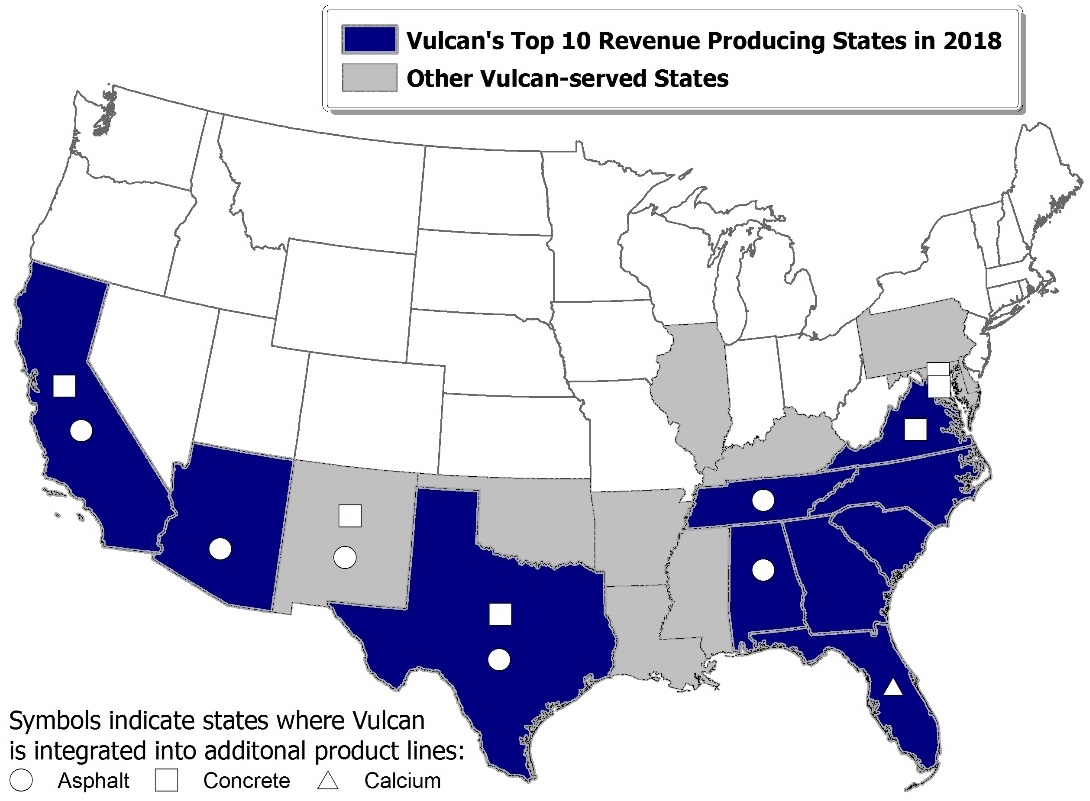
| Part I | 11 |
- ASPHALT
We produce and sell asphalt mix in Alabama, Arizona, California, New Mexico, Tennessee and Texas. In June 2018, we strengthened our asphalt position in Texas by acquiring additional asphalt mix operations and a construction paving business. In March 2018, we entered the Alabama asphalt market through the acquisition of an aggregates, asphalt mix and construction paving business. In December 2017, we strengthened our asphalt position in Arizona by swapping ready-mixed concrete operations for an asphalt mix operation. In January 2017, we entered the Tennessee asphalt market through the acquisition of several asphalt mix operations and a construction paving business. For additional details, see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.”
This segment relies on our reserves of aggregates, functioning essentially as a customer to our aggregates operations. Aggregates are a major component in asphalt mix, comprising approximately 95% by weight of this product. We meet the aggregates requirements for our Asphalt segment primarily through our Aggregates segment. These product transfers are made at local market prices for the particular grade and quality of material required.
Because asphalt mix hardens rapidly, delivery typically is within close proximity to the producing facility. The asphalt mix production process requires liquid asphalt cement, which we purchase from third-party producers. We do not anticipate any significant difficulties in obtaining the raw materials necessary for this segment to operate. We serve our Asphalt segment customers directly from our local production facilities.
- CONCRETE
We produce and sell ready-mixed concrete in California, Maryland, New Mexico, Texas, Virginia, Washington D.C. and the Bahamas. In March 2018, we exited the Georgia ready-mixed concrete market (we retained all real property which is leased to the buyer, and obtained a long-term aggregates supply agreement). As noted above, in December 2017 we exited the Arizona ready-mixed concrete market via a swap for an asphalt mix operation, continuing our strategy to focus on asphalt mix in that market. In March 2017, we reentered the California ready-mixed concrete market through an acquisition. For additional details see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.”
This segment relies on our reserves of aggregates, functioning essentially as a customer to our aggregates operations. Aggregates are a major component in ready-mixed concrete, comprising approximately 80% by weight of this product. We meet the aggregates requirements of our Concrete segment primarily through our Aggregates segment. These product transfers are made at local market prices for the particular grade and quality of material required.
We serve our Concrete segment customers from our local production facilities or by truck. Because ready-mixed concrete hardens rapidly, delivery typically is within close proximity to the producing facility. Ready-mixed concrete production also requires cement which we purchase from third-party producers. We do not anticipate any significant difficulties in obtaining the raw materials necessary for this segment to operate.
- CALCIUM
Our Calcium segment is composed of a single calcium operation in Brooksville, Florida. This facility produces calcium products for the animal feed, plastics and water treatment industries with high-quality calcium carbonate material mined at the Brooksville quarry.
| Part I | 12 |
OTHER BUSINESS-RELATED ITEMS
SEASONALITY AND CYCLICAL NATURE OF OUR BUSINESS
Almost all of our products are produced and consumed outdoors. Seasonal changes and other weather-related conditions can affect the production and sales volumes of our products. Therefore, the financial results for any quarter do not necessarily indicate the results expected for the year. Normally, the highest sales and earnings are in the third quarter and the lowest are in the first quarter. Furthermore, our sales and earnings are sensitive to national, regional and local economic conditions, demographic and population fluctuations, and particularly to cyclical swings in construction spending, primarily in the private sector.
COMPETITORS
We operate in a generally fragmented industry with a large number of small, privately-held companies. We estimate that the ten largest aggregates producers accounted for less than one-third of the total U.S. aggregates production in 2018. Despite being the industry leader, Vulcan’s total U.S. market share is less than 10%. Other publicly traded companies among the ten largest U.S. aggregates producers include the following:
| § | Cemex S.A.B. de C.V. |
|---|
| § | CRH plc |
|---|
| § | HeidelbergCement AG |
|---|
| § | LafargeHolcim |
|---|
| § | Martin Marietta Materials, Inc. |
|---|
| § | MDU Resources Group, Inc. |
|---|
| § | Summit Materials, Inc. |
|---|
Because the U.S. aggregates industry is highly fragmented, with over 5,800 companies managing more than 10,600 operations during 2018, many opportunities for consolidation exist. Therefore, companies in the industry tend to grow by acquiring existing facilities to enter new markets or extend their existing market positions.
CUSTOMERS
No material part of our business depends upon any single customer whose loss would have a significant adverse effect on our business. In 2018, our five largest customers accounted for 8% of our total revenues (excluding internal sales), and no single customer accounted for more than 2% of our total revenues. Our products typically are sold to private industry and not directly to governmental entities. Although approximately 45% to 55% of our aggregates shipments have historically been used in publicly-funded construction, such as highways, airports and government buildings, relatively insignificant sales are made directly to federal, state, county or municipal governments/agencies. Therefore, although reductions in state and federal funding can curtail publicly-funded construction, our business is not directly subject to renegotiation of profits or termination of contracts with state or federal governments.
| Part I | 13 |
ENVIRONMENTAL COSTS AND GOVERNMENTAL REGULATION
Our operations are subject to numerous federal, state and local laws and regulations relating to the protection of the environment and worker health and safety; examples include regulation of facility air emissions and water discharges, waste management, protection of wetlands, listed and threatened species, noise and dust exposure control for workers, and safety regulations under both Mine Safety and Health Administration (MSHA) and Occupational Safety and Health Administration (OSHA). Compliance with these various regulations requires a substantial capital investment, and ongoing expenditures for the operation and maintenance of systems and implementation of programs. We estimate that capital expenditures for environmental control facilities in 2019 and 2020 will be $12.2 million and $21.3 million, respectively. These anticipated expenditures are not expected to have a material impact on our earnings or competitive position.
We have received notices from the United States Environmental Protection Agency (EPA) or similar state or local agencies that we are considered a potentially responsible party (PRP) at a limited number of sites under the Comprehensive Environmental Response, Compensation and Liability Act (CERCLA or Superfund) or similar state and local environmental laws. Generally we share the cost of remediation at these sites with other PRPs or alleged PRPs in accordance with negotiated or prescribed allocations. There is inherent uncertainty in determining the potential cost of remediating a given site and in determining any individual party's share in that cost. As a result, estimates can change substantially as additional information becomes available about the nature or extent of site contamination, remediation methods, other PRPs and their probable level of involvement, and actions by or against governmental agencies or private parties.
For additional information about litigation and environmental matters, see Notes 1 and 12 to the consolidated financial statements in Item 8 “Financial Statements and Supplementary Data.”
Frequently, we are required by state and local regulations or contractual obligations to reclaim our former mining sites. These reclamation liabilities are recorded in our financial statements as a liability at the time the obligation arises. The fair value of such obligations is capitalized and depreciated over the estimated useful life of the owned or leased site. The liability is accreted through charges to operating expenses. To determine the fair value, we estimate the cost for a third party to perform the legally required reclamation, which is adjusted for inflation and risk and includes a reasonable profit margin. All reclamation obligations are reviewed at least annually. Reclaimed quarries often have potential for use in commercial or residential development or as reservoirs or landfills. However, no projected cash flows from these anticipated uses have been considered to offset or reduce the estimated reclamation liability.
For additional information about reclamation obligations (referred to in our financial statements as asset retirement obligations), see Notes 1 and 17 to the consolidated financial statements in Item 8 “Financial Statements and Supplementary Data.”
PATENTS AND TRADEMARKS
We do not own or have a license or other rights under any patents, registered trademarks or trade names that are material to any of our reporting segments.
OTHER INFORMATION ABOUT VULCAN
Vulcan is a New Jersey corporation incorporated on February 14, 2007, while its predecessor company was incorporated on September 27, 1956. Our principal sources of energy are electricity, diesel fuel and natural gas. We do not anticipate any difficulty in obtaining sources of energy required for operation of any of our reporting segments in 2019.
As of January 1, 2019, we employed 8,373 people in the United States. Of these employees, 659 are represented by labor unions. Also, as of that date, we employed 408 people in Mexico and 1 in the Bahamas, 332 of whom are represented by labor unions. We do not anticipate any significant issues with any unions in 2019.
We generally ship our products upon receipt of a purchase order or in some cases simply a price quote. Therefore, we do not have a significant order backlog.
| Part I | 14 |
shareholder return performance presentation
Below is a graph comparing the performance of our common stock, with dividends reinvested, to that of the Standard & Poor’s 500 Stock Index (S&P 500) and the Materials and Services Sector of the Wilshire 5000 Index (Wilshire 5000 M&S) from December 31, 2013 to December 31, 2018. The Wilshire 5000 M&S is a market capitalization weighted sector containing public equities of firms in the Materials and Services sector, which includes our company and approximately 1,300 other companies.
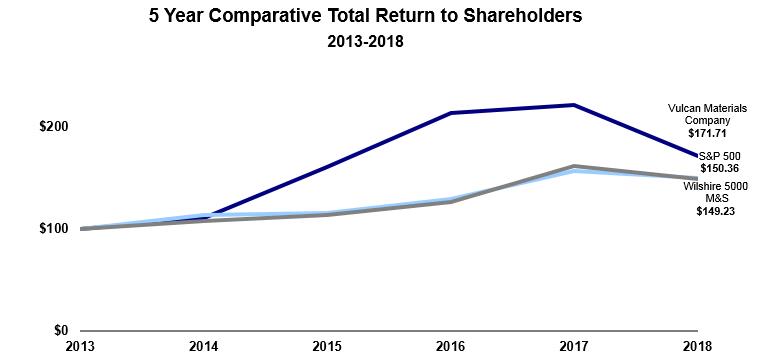
| 2013 | 2014 | 2015 | 2016 | 2017 | 2018 | |||||||||||||||||
| Comparative Total Return 1 | ||||||||||||||||||||||
| Vulcan Materials Company | $ 100.00 | $ 111.00 | $ 161.06 | $ 213.73 | $ 220.99 | $ 171.71 | ||||||||||||||||
| S&P 500 | $ 100.00 | $ 113.70 | $ 115.29 | $ 129.13 | $ 157.28 | $ 150.36 | ||||||||||||||||
| Wilshire 5000 M&S | $ 100.00 | $ 108.30 | $ 113.50 | $ 126.44 | $ 161.33 | $ 149.23 |
| 1 | Assumes an initial investment at December 31, 2013 of $100 in each stock/index, with quarterly reinvestment of dividends. |
| Part I | 15 |
INVESTOR INFORMATION
We make available on our website, www.vulcanmaterials.com, free of charge, copies of our:
| § | Annual Report on Form 10-K |
|---|
| § | Quarterly Reports on Form 10-Q |
|---|
| § | Current Reports on Form 8-K |
|---|
Our website also includes amendments to those reports filed with or furnished to the Securities and Exchange Commission (SEC) pursuant to Section 13(a) or 15(d) of the Securities Exchange Act of 1934 as well as all Forms 3, 4 and 5 filed with the SEC by our executive officers and directors, as soon as the filings are made publicly available by the SEC on its EDGAR database (www.sec.gov).
In addition to accessing copies of our reports online, you may request a copy of our Annual Report on Form 10-K, including financial statements, by writing to Jerry F. Perkins Jr., General Counsel and Secretary, Vulcan Materials Company, 1200 Urban Center Drive, Birmingham, Alabama 35242.
We have a:
| § | Business Conduct Policy applicable to all employees and directors |
|---|
| § | Code of Ethics for the CEO and Senior Financial Officers |
|---|
Copies of the Business Conduct Policy and the Code of Ethics are available on our website under the heading “Corporate Governance.” If we make any amendment to, or waiver of, any provision of the Code of Ethics, we will disclose such information on our website as well as through filings with the SEC.
Our Board of Directors has also adopted:
| § | Corporate Governance Guidelines |
|---|
| § | Charters for our Audit, Compensation, Executive, Finance, Governance and Safety, Health & Environmental Affairs Committees |
|---|
These documents meet all applicable SEC and New York Stock Exchange (NYSE) regulatory requirements.
The Charters of the Audit, Compensation and Governance Committees are available on our website under the heading, “Corporate Governance,” or you may request a copy of any of these documents by writing to Jerry F. Perkins Jr., General Counsel and Secretary, Vulcan Materials Company, 1200 Urban Center Drive, Birmingham, Alabama 35242.
Information included on our website is not incorporated into, or otherwise made a part of, this report.
CERTIFICATIONS AND ASSERTIONS
The certifications of our Chief Executive Officer and Chief Financial Officer made pursuant to Section 302 of the Sarbanes-Oxley Act of 2002 are included as exhibits to this Annual Report on Form 10-K. Additionally, on June 5, 2018 our Chief Executive Officer submitted to the NYSE the annual written affirmation required by the rules of the NYSE certifying that he was not aware of any violations of Vulcan Materials Company of NYSE corporate governance listing standards.
| Part I | 16 |
Item 1A. RISK FACTORS
RISK FACTORS
The following risks could materially and adversely affect our business, financial condition and results of operations, and cause the trading price of our common stock to decline. These risk factors do not identify all risks that we face; our operations could also be affected by factors that are not presently known to us or that we currently consider to be immaterial to our operations. Due to risks and uncertainties, known and unknown, our past financial results may not be a reliable indicator of future performance and historical trends should not be used to anticipate results or trends in future periods. You should also refer to the other information set forth in this Annual Report on Form 10-K, including Item 7 “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and Item 8 “Financial Statements and Supplementary Data.”
ECONOMIC/POLITICAL RISKS
Our business is dependent on the construction industry and is subject to economic cycles — Our products are principally sold to the U.S. construction industry. Since our business is dependent on spending in both the public and private sector construction markets, our profits are sensitive to the underlying national, regional, and local economic conditions. Construction spending, which is cyclical, is affected by general economic conditions, changes in interest rates, demographic shifts, industry cycles, employment levels, inflation and other business, economic and financial factors that are beyond our control. A downturn in construction activities or spending in Vulcan-served markets, particularly in our top revenue-generating markets, could have a material adverse effect on our business, financial condition, and results of operations.
Changes in legal requirements and governmental policies concerning zoning, land use, environmental and other areas of the law may result in additional liabilities, a reduction in operating hours and additional capital expenditures — Our operations are affected by numerous federal, state and local laws and regulations related to zoning, land use and environmental matters. Despite our compliance efforts, we have an inherent risk of liability in the operation of our business. These potential liabilities could have an adverse impact on our operations and profitability. In addition, our operations require numerous governmental approvals and permits, which often require us to make significant capital and operating expenditures to comply with the applicable requirements. Stricter laws and regulations, or more stringent interpretations of existing laws or regulations, may impose new liabilities, taxes or tariffs on us, reduce operating hours, require additional investment by us in pollution control equipment, create restrictions on our products or impede our access to reserves or opening new or expanding existing plants or facilities.
Our business is dependent on the timing and amount of federal, state and local funding for infrastructure — Our products are used in a variety of public infrastructure projects that are funded and financed by federal, state and local governments. In 2018, voters in local jurisdictions in California, Florida, Georgia, North Carolina and Texas, among others, approved bond and revenue-raising measures to provide additional resources for transportation projects. In 2017, three state legislatures in Vulcan-served areas — California, South Carolina and Tennessee — passed new long-term highway funding legislation. In 2016, three states saw one-time revenue increases for transportation, and numerous ballot measures were passed to increase investment in several Vulcan-served areas including northern and southern California, Georgia, North Carolina and South Carolina. The federal FAST Act, a five year, fully-funded road, bridge and public transportation authorization law, is providing assistance to state DOTs and metro areas. However, given varying state and local budgetary situations and the associated pressure on infrastructure spending, we cannot be entirely assured of the existence, amount and timing of appropriations for future public infrastructure projects.
Climate change and climate change legislation or regulations may adversely impact our business — A number of governmental bodies have introduced or are contemplating legislative and regulatory change in response to the potential impacts of climate change. Such legislation or regulation, if enacted, potentially could include provisions for a “cap and trade” system of allowances and credits or a carbon tax, among other provisions.
Other potential impacts of climate change include physical impacts, such as disruption in production and product distribution due to impacts from major storm events, shifts in regional weather patterns and intensities, and potential impacts from sea level changes. There is also a potential for climate change legislation and regulation to adversely impact the cost of purchased energy and electricity.
The impacts of climate change on our operations and the company overall are highly uncertain and difficult to estimate. However, climate change legislation and regulation concerning greenhouse gases could have a material adverse effect on our future financial position, results of operations or cash flows.
| Part I | 17 |
We are subject to various risks arising from our international business operations and relationships, which could adversely affect our business — We have international operations and are subject to both the risks of conducting international business and the requirements of the Foreign Corrupt Practices Act of 1977 (the FCPA). We face political and other risks associated with our international operations, including our largest production facility located in Playa del Carmen, Mexico. These risks may include changes in international trade policies, such as the North American Free Trade Agreement, imposition of duties, taxes or government royalties, arbitrary changes to permits, zoning classifications or operating agreements, or overt acts by foreign governments, including expropriations and other forms of takings of property. In addition, failure to comply with the FCPA may result in legal claims against us.
GROWTH AND COMPETITIVE RISKS
Within our local markets, we operate in a highly competitive industry which may negatively impact prices, volumes and costs — The construction aggregates industry is highly fragmented with a large number of independent local producers in a number of our markets. Additionally, in most markets, we also compete against large private and public companies, some of which are significantly vertically integrated. Therefore, there is intense competition in a number of markets in which we operate. This significant competition could lead to lower prices and lower sales volumes in some markets, negatively affecting our earnings and cash flows.
The expanded use of aggregates substitutes could have a material adverse effect on our business, financial condition and results of operations — Recycled concrete and asphalt are increasingly being used in a number of our markets, particularly urban markets, as a substitute for aggregates. The expanded use of recycled concrete and asphalt could cause a significant reduction in the demand for aggregates.
Our long-term success depends upon securing and permitting aggregates reserves in strategically located areas. If we are unable to secure and permit such reserves it could negatively affect our future earnings — Construction aggregates are bulky and heavy and, therefore, difficult to transport efficiently. Because of the nature of the products, the freight costs can quickly surpass the production costs. Therefore, except for geographic regions that do not possess commercially viable deposits of aggregates and are served by rail, barge or ship, the markets for our products tend to be localized around our quarry sites and are served by truck. New quarry sites often take years to develop; therefore, our strategic planning and new site development must stay ahead of actual growth. Additionally, in a number of urban and suburban areas in which we operate, it is increasingly difficult to permit new sites or expand existing sites due to community resistance. Therefore, our future success is dependent, in part, on our ability to accurately forecast future areas of high growth in order to locate optimal facility sites and on our ability to secure operating and environmental permits to operate at those sites.
Our future growth depends in part on acquiring other businesses in our industry and successfully integrating them with our existing operations. If we are unable to integrate acquisitions successfully, it could lead to higher costs and could negatively affect our earnings — The expansion of our business is dependent in part on the acquisition of existing businesses that own or control aggregates reserves. Disruptions in the availability of financing could make it more difficult to capitalize on potential acquisitions. Additionally, with regard to the acquisitions we are able to complete, our future results will depend in part on our ability to successfully integrate these businesses with our existing operations.
FINANCIAL/ACCOUNTING RISKS
Our industry is capital intensive, resulting in significant fixed and semi-fixed costs. Therefore, our earnings are highly sensitive to changes in product shipments — Due to the high levels of fixed capital required for extracting and producing construction aggregates, our profits are negatively affected by significant decreases in shipments.
Significant downturn in the construction industry may result in an impairment of our goodwill — We test goodwill for impairment on an annual basis or more frequently if events or circumstances change in a manner that would more likely than not reduce the fair value of a reporting unit below its carrying value. While we have not identified any events or changes in circumstances since our annual impairment test on November 1, 2018 that indicate the fair value of any of our reporting units is below its carrying value, a significant downturn in the construction industry may have a material effect on the fair value of our reporting units. A significant decrease in the estimated fair value of one or more of our reporting units could result in the recognition of a material, noncash write-down of goodwill.
| Part I | 18 |
A deterioration in our credit ratings and/or the state of the capital markets could negatively impact our business — We currently have $2.8 billion of debt with maturities between 2019 and 2048. Given our current credit metrics and ratings, together with other factors, we expect to refinance our nearer term debt maturities rather than repay them when due. Furthermore, we expect to finance acquisitions with a combination of cash flows from existing operations, additional debt and/or additional equity. The mix of financing sources for acquisitions will be situationally dependent.
A deterioration in our credit ratings, regardless of the cause, could limit our debt financing options and increase the cost of such debt financing (whether for refinancing existing debt or financing acquisitions). While we do not anticipate a credit ratings downgrade, and plan to manage our capital structure consistent with investment-grade credit metrics, we cannot assure our current credit ratings.
A deterioration in the state of the capital markets, regardless of our credit rating, could impact our access to, and cost of, new debt or equity capital.
We use estimates in accounting for a number of significant items. Changes in our estimates could adversely affect our future financial results — As discussed more fully in “Critical Accounting Policies” under Item 7 “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” we use significant judgment in accounting for:
| § | goodwill impairment |
|---|
| § | impairment of long-lived assets excluding goodwill |
|---|
| § | business combinations and purchase price allocation |
|---|
| § | pension and other postretirement benefits |
|---|
| § | environmental compliance costs |
|---|
| § | claims and litigation including self-insurance |
|---|
| § | income taxes |
|---|
These assumptions and estimates could change significantly in the future and could adversely affect our financial position, results of operations, or cash flows.
PERSONNEL RISKS
Our future success greatly depends upon attracting and retaining qualified personnel, particularly in sales and operations — A significant factor in our future profitability is our ability to attract, develop and retain qualified personnel. Our success in attracting qualified personnel, particularly in the areas of sales and operations, is affected by changing demographics of the available pool of workers with the training and skills necessary to fill the available positions, the impact on the labor supply due to general economic conditions, and our ability to offer competitive compensation and benefit packages.
Disputes with organized labor could disrupt our business operations — Labor unions represent approximately 11% of our workforce. Disputes with our trade unions, or the inability to renew our labor agreements, may lead to strikes or other actions that could disrupt our business operations leading to higher costs and/or reduced revenues resulting in lower earnings.
OTHER RISKS
A significant interruption of our information technology systems or the loss of confidential or other sensitive data could have a material adverse impact on our operations and financial results — Given our reliance on information technology (our own and our third-party providers’), a significant interruption in the availability of information technology, regardless of the cause, could negatively impact our operations. Additionally, the loss of confidential, personal, or proprietary information (whether our own, our employees’, our suppliers’, or our customers’), regardless of the cause, could result in a business interruption, reputational damage, lost revenue, litigation, penalties or higher costs. While we have, and periodically test, information technology and data protection policies and procedures, there can be no assurance that our efforts will prevent breakdowns or breaches that could adversely affect our business. Management is not aware of a cybersecurity incident that has had a material adverse impact on our operations.
| Part I | 19 |
Weather can materially affect our operating results — Almost all of our products are consumed outdoors in the public or private construction industry, and our production and distribution facilities are located outdoors. Inclement weather affects both our ability to produce and distribute our products and affects our customers’ short-term demand because their work also can be hampered by weather.
Our products are transported by truck, rail, barge or ship, often by third-party providers. Significant delays or increased costs affecting these transportation methods could materially affect our operations and earnings — Our products are distributed either by truck to local markets or by rail, barge or oceangoing vessel to remote markets. The costs of transporting our products could be negatively affected by factors outside of our control, including rail service interruptions or rate increases, tariffs, rising fuel costs, truck/railcar/barge shortages and capacity constraints. Additionally, inclement weather, including hurricanes, tornadoes and other weather events, can negatively impact our distribution network.
We use large amounts of electricity, diesel fuel, liquid asphalt and other petroleum-based resources that are subject to potential supply constraints and significant price fluctuation, which could affect our operating results and profitability — In our production and distribution processes, we consume significant amounts of electricity, diesel fuel, liquid asphalt and other petroleum-based resources. The availability and pricing of these resources are subject to market forces that are beyond our control. Our suppliers contract separately for the purchase of such resources and our sources of supply could be interrupted should our suppliers not be able to obtain these materials due to higher demand or other factors that interrupt their availability. Variability in the supply and prices of these resources could materially affect our operating results from period to period and rising costs could erode our profitability.
We are involved in a number of legal proceedings. We cannot predict the outcome of litigation and other contingencies with certainty — We are involved in several complex litigation proceedings, some arising from our previous ownership and operation of our Chemicals business. Although we divested our Chemicals business in June 2005, we retained certain liabilities related to the business. As required by generally accepted accounting principles (GAAP), we establish reserves when a loss is determined to be probable and the amount can be reasonably estimated. Our assessment of probability and loss estimates are based on the facts and circumstances known to us at a particular point in time. Subsequent developments in legal proceedings may affect our assessment and estimates of a loss contingency, and could result in an adverse effect on our financial position, results of operations or cash flows. For a description of our current significant legal proceedings see Note 12 “Commitments and Contingencies” in Item 8 “Financial Statements and Supplementary Data.”
Our construction paving business may subject us to contractually imposed penalties or lost profits — As a result of recent acquisitions, we operate construction paving businesses in Alabama, Tennessee and Texas. In some instances, including many of our fixed price paving contracts, we agree to complete a project by a certain date. If we fail to complete the project as scheduled, we may be held responsible for costs resulting from the delay. Consequently, the total project cost could exceed our original estimate and we could experience reduced profits or even a loss on the project.
We are involved in certain environmental matters. We cannot predict the outcome of these contingencies with certainty — We are involved in environmental investigations and cleanups at sites where we operate or have operated in the past or sent materials for recycling or disposal. As required by generally accepted accounting principles, we establish reserves when a loss is determined to be probable and the amount can be reasonably estimated. Our assessment of probability and loss estimates are based on the facts and circumstances known to us at a particular point in time. Subsequent developments related to these matters may affect our assessment and estimates of loss contingency, and could result in an adverse effect on our financial position, results of operations or cash flows. For a description of our current significant environmental matters see Note 12 “Commitments and Contingencies” in Item 8 “Financial Statements and Supplementary Data.”
Item 1B. UNRESOLVED STAFF COMMENTS
UNRESOLVED STAFF COMMENTS
We have not received any written comments from the Securities and Exchange Commission staff regarding our periodic or current reports under the Exchange Act of 1934 that remain unresolved.
| Part I | 20 |
Item 2. PROPERTIES
PROPERTIES
AGGREGATES
As the largest U.S. supplier of construction aggregates, we have operating facilities across the U.S. and in Mexico and the Bahamas. We principally serve markets in 20 states, Washington D.C. and the local markets surrounding our operations in Mexico and the Bahamas. Our primary focus is serving states and metropolitan markets in the U.S. that are expected to experience the most significant growth in population, households and employment. These three demographic factors are significant drivers of demand for aggregates.
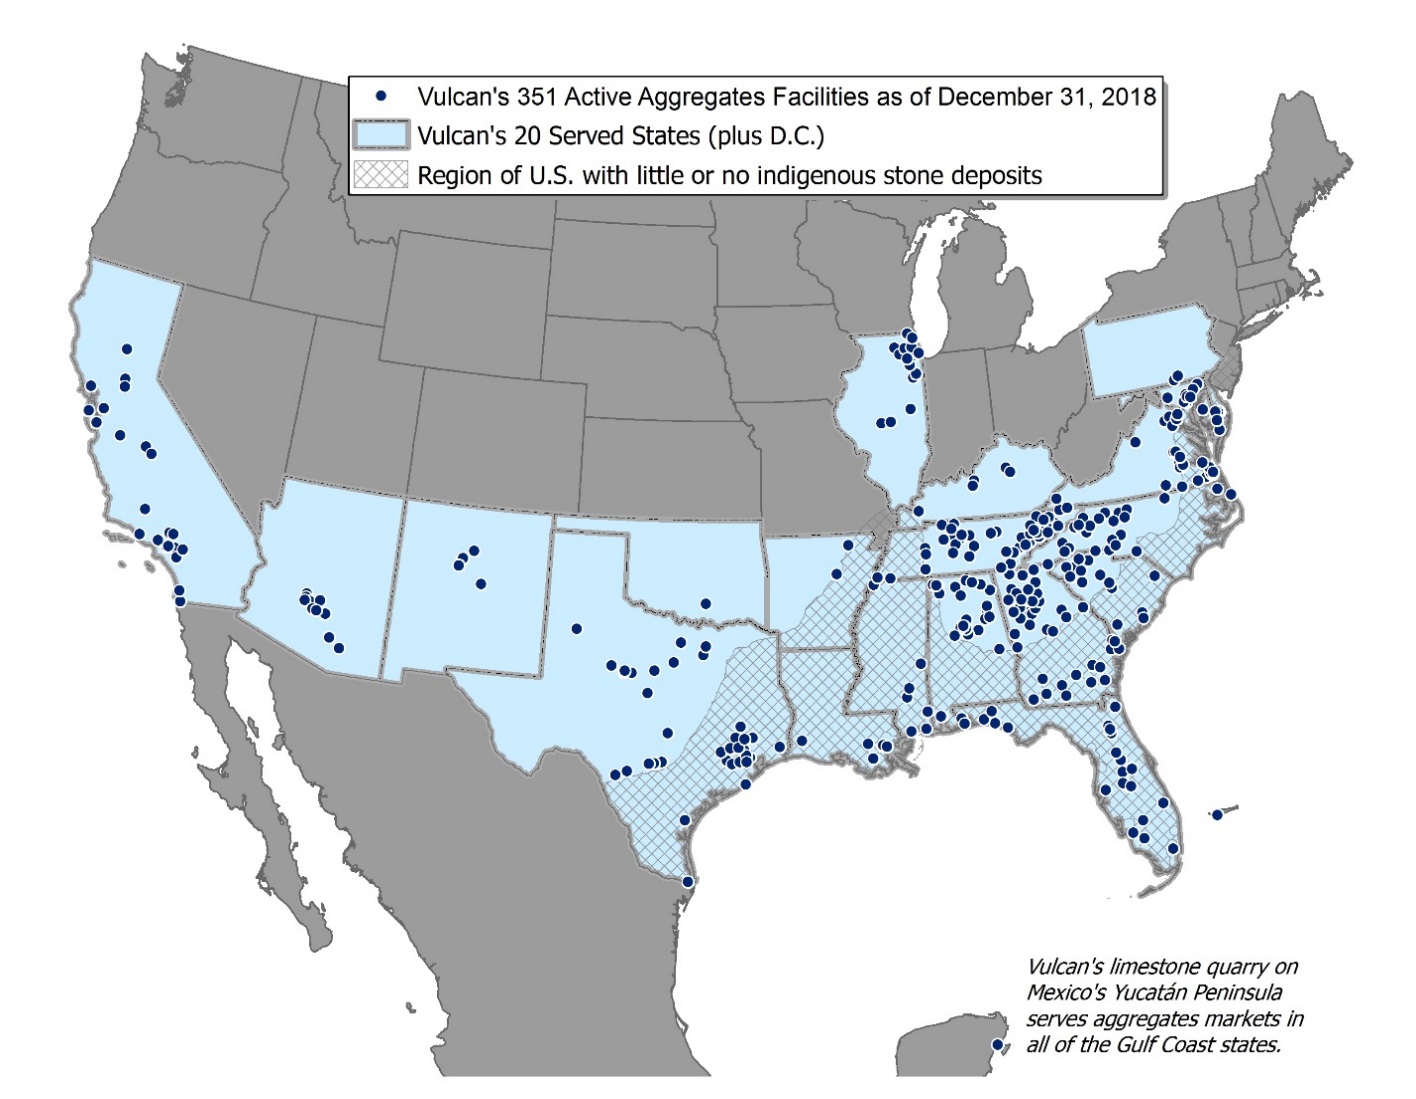
Our current estimate of 16.3 billion tons of proven and probable aggregates reserves reflects an increase of 0.3 billion tons from the prior year’s estimate. Estimates of reserves are of recoverable stone, sand and gravel of suitable quality for economic extraction, based on drilling and studies by our geologists and engineers, recognizing reasonable economic and operating constraints as to maximum depth of overburden and stone excavation, and subject to permit or other restrictions.
Proven, or measured, reserves are those reserves for which the quantity is computed from dimensions revealed by drill data, together with other direct and measurable observations, such as outcrops, trenches and quarry faces. The grade and quality of those reserves are computed from the results of detailed sampling, and the sampling and measurement data are spaced so closely and the geologic character is so well defined that size, shape, depth and mineral content of reserves are well established. Probable, or indicated, reserves are those reserves for which quantity, grade and quality are computed partly from specific measurements and partly from projections based on reasonable, though not drilled, geologic evidence. The degree of assurance, although lower than that for proven reserves, is high enough to assume continuity between points of observation.
| Part I | 21 |
Reported proven and probable reserves include only quantities that are owned in fee or under lease, and for which all appropriate zoning and permitting have been obtained through permit, contract or grandfathered status. Leases, zoning, permits, reclamation plans and other government or industry regulations often set limits on the areas, depths and lengths of time allowed for mining, stipulate setbacks and slopes that must be left in place, and designate which areas may be used for surface facilities, berms, and overburden or waste storage, among other requirements and restrictions. Our reserve estimates take into account these factors. Technical and economic factors also affect the estimates of reported reserves regardless of what might otherwise be considered proven or probable based on a geologic analysis. For example, excessive overburden or weathered rock, rock quality issues, excessive mining depths, groundwater issues, overlying wetlands, endangered species habitats, and rights of way or easements may effectively limit the quantity of reserves considered proven and probable. In addition, computations for reserves in-place are adjusted for estimates of unsaleable sizes and materials as well as pit and plant waste.
The 16.3 billion tons of estimated proven and probable aggregates reserves reported at the end of 2018 include reserves at inactive and greenfield (undeveloped) sites. The table below presents, by division, the tons of proven and probable aggregates reserves as of December 31, 2018 and the types of facilities operated.
| (millions of tons) | Count of Aggregates Operating Facilities 2 | |||||||||||||||||||||
| Aggregates Reserves | 2018 | Sand and | ||||||||||||||||||||
| Division 1 | Proven | Probable | Total | Production | Stone | Gravel | Sales Yards | |||||||||||||||
| Central | 2,875.6 | 859.9 | 3,735.5 | 38.3 | 53 | 5 | 9 | |||||||||||||||
| International | 554.2 | 0.0 | 554.2 | 12.7 | 1 | 0 | 0 | |||||||||||||||
| Mideast | 2,519.9 | 988.8 | 3,508.7 | 35.4 | 34 | 5 | 22 | |||||||||||||||
| Mountain West | 177.0 | 125.8 | 302.8 | 9.4 | 2 | 12 | 2 | |||||||||||||||
| Southeast 3 | 3,067.1 | 882.5 | 3,949.6 | 49.8 | 43 | 11 | 22 | |||||||||||||||
| Southern Gulf Coast | 1,326.8 | 45.4 | 1,372.2 | 16.3 | 22 | 0 | 19 | |||||||||||||||
| Southwest | 1,322.4 | 0.0 | 1,322.4 | 22.5 | 15 | 1 | 23 | |||||||||||||||
| Western | 1,033.6 | 504.1 | 1,537.7 | 22.2 | 5 | 13 | 2 | |||||||||||||||
| Total | 12,876.6 | 3,406.5 | 16,283.1 | 206.6 | 175 | 47 | 99 |
| 1 | The divisions are defined by states/countries as follows: Central Division — Arkansas, Illinois, Kentucky and Tennessee International Division — Mexico Mideast Division — Delaware, Maryland, North Carolina, Pennsylvania, Virginia and Washington D.C. Mountain West Division — Arizona and New Mexico Southeast Division — Florida (excluding panhandle), Georgia, South Carolina and the Bahamas Southern Gulf Coast Division — Alabama, Florida Panhandle, Louisiana and Mississippi Southwest Division — Oklahoma and Texas Western Division — California | |
| 2 | In addition to the facilities included in the table above, we operated 30 recycled concrete plants which are not dependent on reserves. | |
| 3 | Includes a maximum of 340.1 million tons of reserves encumbered by volumetric production payments as defined in Note 2 “Revenues” in Item 8 “Financial Statements and Supplementary Data.” |
Of the 16.3 billion tons of aggregates reserves at December 31, 2018, 9.0 billion tons or 55% are located on owned land and 7.3 billion tons or 45% are located on leased land.
| Part I | 22 |
The following table lists our ten largest active aggregates facilities based on the total proven and probable reserves at the sites. None of our aggregates facilities, other than Playa del Carmen, contributed more than 5% to our total revenues in 2018.
| (millions of tons) | ||||||||||||||||||||
| Reserves at 12/31/2018 | 2018 | |||||||||||||||||||
| Location (nearest major metropolitan area) | Proven | Probable | Total | Production | ||||||||||||||||
| Playa del Carmen (Cancun), Mexico | 554.2 | 0.0 | 554.2 | 12.7 | ||||||||||||||||
| Hanover (Harrisburg), Pennsylvania | 226.3 | 236.4 | 462.7 | 2.7 | ||||||||||||||||
| McCook (Chicago), Illinois | 105.8 | 266.5 | 372.3 | 5.0 | ||||||||||||||||
| Corona (Los Angeles), California | 12.5 | 321.8 | 334.3 | 2.2 | ||||||||||||||||
| Gold Hill (Charlotte), North Carolina | 148.6 | 121.2 | 269.8 | 1.0 | ||||||||||||||||
| Postell (Macon), Georgia | 195.3 | 72.3 | 267.6 | 3.8 | ||||||||||||||||
| San Emidio (Bakersfield), California | 250.0 | 0.0 | 250.0 | 1.4 | ||||||||||||||||
| Macon, Georgia | 119.2 | 128.0 | 247.2 | 1.8 | ||||||||||||||||
| Norcross (Atlanta), Georgia | 186.9 | 27.7 | 214.6 | 2.8 | ||||||||||||||||
| 1604 Stone (San Antonio), Texas | 208.1 | 0.0 | 208.1 | 1.4 |
ASPHALT, CONCRETE AND CALCIUM
As of December 31, 2018, we operated a number of facilities producing asphalt mix, ready-mixed concrete and calcium in several of our divisions as reflected in the table below:
| Asphalt 2 | Concrete 3 | Calcium 4 | ||||||||||||||||||||
| Division 1 | Facilities | Facilities | Facilities | |||||||||||||||||||
| Central | 10 | 0 | 0 | |||||||||||||||||||
| Mideast | 0 | 31 | 0 | |||||||||||||||||||
| Mountain West | 21 | 2 | 0 | |||||||||||||||||||
| Southeast | 0 | 1 | 1 | |||||||||||||||||||
| Southern Gulf Coast | 3 | 0 | 0 | |||||||||||||||||||
| Southwest | 13 | 7 | 0 | |||||||||||||||||||
| Western | 20 | 5 | 0 | |||||||||||||||||||
| Total | 67 | 46 | 1 |
| 1 | International Division has no asphalt, concrete or calcium facilities. |
| 2 | Asphalt facilities for the Central, Southern Gulf Coast and Southwest Divisions are comprised of asphalt mix facilities and construction paving businesses. |
| 3 | Southeast Division Concrete is comprised of a ready-mixed concrete plant in the Bahamas. |
| 4 | Comprised of a ground calcium plant. |
The asphalt and concrete facilities are able to meet their needs for raw material inputs with a combination of internally sourced and purchased raw materials.
| Part I | 23 |
Our Calcium segment operates a quarry at Brooksville, Florida which provides feedstock for the ground calcium operation.
| (millions of tons) | ||||||||||||||||||||||
| Reserves at 12/31/2018 | 2018 | |||||||||||||||||||||
| Location | Proven | Probable | Total | Production | ||||||||||||||||||
| Brooksville | 5.0 | 7.2 | 12.2 | 0.3 |
Our Brooksville limestone quarry is mined and processed primarily as a supplement for end-use products, such as animal feed and plastics. High purity limestone is inert and relatively inexpensive compared to the other components used in these end-use products. The Brooksville limestone quarry has an average calcium carbonate (CaCO3) content of 97%.
HEADQUARTERS
Our headquarters are located in an office complex in Birmingham, Alabama. The office space consists of approximately 184,410 square feet and is leased through December 31, 2023, with three five-year renewal periods thereafter. The annual rental cost for the current term of the lease is approximately $3.6 million.
Item 3. LEGAL PROCEEDINGS
LEGAL PROCEEDINGS
We are subject to occasional governmental proceedings and orders pertaining to occupational safety and health or to protection of the environment, such as proceedings or orders relating to noise abatement, air emissions or water discharges. As part of our continuing program of stewardship in safety, health and environmental matters, we have been able to resolve such proceedings and to comply with such orders without any material adverse effects on our business.
We are a defendant in various lawsuits in the ordinary course of business. It is not possible to determine with precision the outcome of, or the amount of liability, if any, under these lawsuits, especially where the cases involve possible jury trials with as yet undetermined jury panels.
We were not subject to any penalties in 2018 for failure to disclose transactions identified by the Internal Revenue Service as abusive under Internal Revenue Code Section 6707A.
See Note 12 “Commitments and Contingencies” in Item 8 “Financial Statements and Supplementary Data” for a discussion of our material legal proceedings.
Item 4. MINE SAFETY DISCLOSURES
MINE SAFETY DISCLOSURES
The information concerning mine safety violations or other regulatory matters required by Section 1503(a) of the Dodd-Frank Wall Street Reform and Consumer Protection Act and Item 104 of Regulation S-K is included in Exhibit 95 of this report.
| Part I | 24 |
EXECUTIVE OFFICERS OF THE REGISTRANT
The names, positions and ages, as of February 20, 2019, of our executive officers are as follows:
| __ | ||
|---|---|---|
| Name | Position | Age |
| J. Thomas Hill | Chairman, President and Chief Executive Officer | 59 |
| Suzanne H. Wood | Senior Vice President and Chief Financial Officer | 58 |
| Stanley G. Bass | Chief Growth Officer | 57 |
| Michael R. Mills | Chief Administrative Officer | 58 |
| Thompson S. Baker II | Senior Vice President | 60 |
| Jerry F. Perkins Jr. | General Counsel and Secretary | 49 |
| Randy L. Pigg | Vice President, Controller and Principal Accounting Officer | 46 |
| David P. Clement 1 | President, Central Division | 58 |
| C. Brockway Lodge, Jr. 1 | President, Western Division | 46 |
| 1 | These Division Presidents are designated as Executive Officers as a result of their significant policy-making function and direct reporting relationship to J. Thomas Hill. |
The principal occupations of the executive officers during the past five years are set forth below:
J. Thomas Hill was elected Chairman of the Board of Directors effective January 1, 2016. He was elected President and Chief Executive Officer in July 2014. Prior to that, he served as Executive Vice President and Chief Operating Officer (January 2014 – July 2014), Senior Vice President – South Region (December 2011 – December 2013). Prior to that, he served in a number of positions with Vulcan including President, Florida Rock Division (September 2010 – December 2011).
Suzanne H. Wood was elected Senior Vice President, Chief Financial Officer effective September 2018. From 2012 to 2018, she served as Group Finance Director and Chief Financial Officer of Ashtead Group plc, a FTSE 50 international equipment rental company serving the construction industry and other markets. Prior to that, she was Executive Vice President and Chief Financial Officer of Sunbelt Rentals, Inc., the North American subsidiary of Ashtead Group plc. A certified public accountant, she also previously held Chief Financial Officer positions at Tultex Corporation and Oakwood Homes Corporation. She currently serves on the board of directors and audit committee of RELX Group, a FTSE 50 global professional information and analytics company.
Stanley G. Bass was elected Chief Growth Officer in February 2016. He served as Senior Vice President – Western and Mountain West Divisions from January 2015 to February 2016. He served as Senior Vice President – West Region from September 2013 to December 2014. Prior to that, he served as Senior Vice President – Central and West Regions (February 2013 – September 2013), Senior Vice President – Central Region (December 2011 – February 2013). Prior to that, he served in a number of positions with Vulcan including President, Midsouth and Southwest Divisions (September 2010 – December 2011).
Michael R. Mills was elected Chief Administrative Officer in February 2016. He served as Senior Vice President and General Counsel from November 2012 to February 2016; and as Senior Vice President – East Region from December 2011 to October 2012. Prior to that, he was President, Southeast Division.
Thompson S. Baker II was elected Senior Vice President in March 2017. He served in a number of positions with Vulcan, including President – Florida Rock Division, prior to serving as Chief Executive Officer of FRP Holdings, Inc. from October 2010 to March 2017 and President and Chief Executive Officer of Patriot Transportation Holding, Inc. from December 2014 to March 2017.
| Part I | 25 |
Jerry F. Perkins Jr. was elected General Counsel and Secretary in February 2016. He served as Assistant General Counsel and Secretary since 2011.
Randy L. Pigg was elected Vice President, Controller and Principal Accounting Officer in April 2018. He served as Vice President, Accounting since June 2016, and prior to that served as Director, Financial Shared Services since April 2014. Prior to that, he served in a number of positions with Vulcan, including Manager Financial Research & Reporting and Finance Director – Central Region.
David P. Clement was named President, Central Division effective January 1, 2015. He served as Senior Vice President – Central Region from September 2013 through December 2014. During the five years prior to such role, he served in a number of positions with Vulcan including Vice President and General Manager, Midwest Division and Vice President of Operations, Midwest Division.
C. Brockway (Brock) Lodge, Jr. was named President, Western Division in February 2016. He served as Vice President and General Manager, Western Division from April 2015 to February 2016. Before that, he was Senior Area General Manager – Central Division (June 2013 – March 2015) and Director of Sales and Marketing – Midsouth Division (April 2010 – May 2013).
| Part I | 26 |
PART II
Item 5. MARKET FOR REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS
MARKET FOR REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Our common stock is traded on the New York Stock Exchange (ticker symbol VMC). As of February 12, 2019, the number of shareholders of record was 2,601.
ISSUER PURCHASES OF EQUITY SECURITIES
Purchases of our equity securities during the quarter ended December 31, 2018 are summarized below.
| Total Number | Maximum | ||||||||||
| of Shares | Number of | ||||||||||
| Total | Purchased as | Shares that May | |||||||||
| Number of | Average | Part of Publicly | Yet Be Purchased | ||||||||
| Shares | Price Paid | Announced Plans | Under the Plans | ||||||||
| Period | Purchased | Per Share | or Programs | or Programs 1 | |||||||
| 2018 | |||||||||||
| Oct 1 - Oct 31 | 0 | $ 0.00 | 0 | 8,623,227 | |||||||
| Nov 1 - Nov 30 | 325,438 | $ 104.68 | 325,438 | 8,297,789 | |||||||
| Dec 1 - Dec 31 | 0 | $ 0.00 | 0 | 8,297,789 | |||||||
| Total | 325,438 | $ 104.68 | 325,438 |
| 1 | On February 10, 2017, our Board of Directors authorized us to purchase up to 8,243,243 shares of our common stock to refresh the number of shares we were authorized to purchase to 10,000,000. As of December 31, 2018, there were 8,297,789 shares remaining under this authorization. Depending upon market, business, legal and other conditions, we may purchase shares from time to time through the open market (including plans designed to comply with Rule 10b5-1 of the Securities Exchange Act of 1934) and/or through privately negotiated transactions. The authorization has no time limit, does not obligate us to purchase any specific number of shares, and may be suspended or discontinued at any time. |
We did not have any unregistered sales of equity securities during the fourth quarter of 2018.
| Part II | 27 |
Item 6. SELECTED FINANCIAL DATA
SELECTED FINANCIAL DATA
The selected earnings data, per share data and balance sheet data for each of the five most recent years ended December 31 set forth below have been derived from our audited consolidated financial statements. The following data should be read in conjunction with our consolidated financial statements and notes to consolidated financial statements in Item 8 “Financial Statements and Supplementary Data.”
| 2018 | 2017 | 2016 | 2015 | 2014 | |||||||||||||
| As of and for the years ended December 31 | |||||||||||||||||
| in millions, except per share data | |||||||||||||||||
| Total revenues | $ | 4,382.9 | $ | 3,890.3 | $ | 3,592.7 | $ | 3,422.2 | $ | 2,994.2 | |||||||
| Gross profit 1 | $ | 1,100.9 | $ | 993.5 | $ | 988.9 | $ | 857.5 | $ | 587.6 | |||||||
| Gross profit margin | 25.1% | 25.5% | 27.5% | 25.1% | 19.6% | ||||||||||||
| Earnings from continuing operations 2 | $ | 517.8 | $ | 593.4 | $ | 422.4 | $ | 232.9 | $ | 207.1 | |||||||
| Earnings (loss) on discontinued operations, | |||||||||||||||||
| net of tax 3 | $ | (2.0) | $ | 7.8 | $ | (2.9) | $ | (11.7) | $ | (2.2) | |||||||
| Net earnings | $ | 515.8 | $ | 601.2 | $ | 419.5 | $ | 221.2 | $ | 204.9 | |||||||
| Basic earnings (loss) per share | |||||||||||||||||
| Continuing operations | $ | 3.91 | $ | 4.48 | $ | 3.17 | $ | 1.75 | $ | 1.58 | |||||||
| Discontinued operations | (0.01) | 0.06 | (0.02) | (0.09) | (0.02) | ||||||||||||
| Basic net earnings (loss) per share | $ | 3.90 | $ | 4.54 | $ | 3.15 | $ | 1.66 | $ | 1.56 | |||||||
| Diluted earnings (loss) per share | |||||||||||||||||
| Continuing operations | $ | 3.87 | $ | 4.40 | $ | 3.11 | $ | 1.72 | $ | 1.56 | |||||||
| Discontinued operations | (0.02) | 0.06 | (0.02) | (0.08) | (0.02) | ||||||||||||
| Diluted net earnings (loss) per share | $ | 3.85 | $ | 4.46 | $ | 3.09 | $ | 1.64 | $ | 1.54 | |||||||
| Cash and cash equivalents | $ | 40.0 | $ | 141.6 | $ | 259.0 | $ | 284.1 | $ | 141.3 | |||||||
| Total assets | $ | 9,832.1 | $ | 9,504.9 | $ | 8,471.5 | $ | 8,301.6 | $ | 8,041.1 | |||||||
| Working capital | $ | 476.6 | $ | 737.2 | $ | 764.9 | $ | 731.1 | $ | 468.6 | |||||||
| Current maturities and short-term debt | $ | 133.0 | $ | 41.4 | $ | 0.1 | $ | 0.1 | $ | 150.1 | |||||||
| Long-term debt | $ | 2,779.4 | $ | 2,813.5 | $ | 1,982.8 | $ | 1,980.3 | $ | 1,834.6 | |||||||
| Equity | $ | 5,202.9 | $ | 4,968.9 | $ | 4,572.5 | $ | 4,454.2 | $ | 4,176.7 | |||||||
| Cash dividends declared per share | $ | 1.12 | $ | 1.00 | $ | 0.80 | $ | 0.40 | $ | 0.22 |
| 1 | As a result of our first quarter 2018 adoption of ASU 2017-07 (see Note 1 “Summary of Significant Accounting Policies” in Item 8 “Financial Statements and Supplementary Data” under the caption New Accounting Standards), gross profit was reduced by $7.0 million and $11.9 million for the years ended December 31, 2017 and 2016, respectively. We have not revised years prior to 2016 as the impact is deemed as immaterial. |
| 2 | Earnings from continuing operations for 2017 include pretax interest charges of $153.1 million referable to debt purchases and $297.0 million of discrete net tax benefits. Earnings from continuing operations for 2014 include a pretax gain of $211.4 million referable to the sale of our Florida cement and concrete businesses. |
| 3 | Discontinued operations include the results attributable to our former Chemicals business. |
| Part II | 28 |
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
EXECUTIVE SUMMARY
FINANCIAL SUMMARY FOR 2018 (compared to 2017)
| § | Total revenues increased $492.6 million, or 13%, to $4,382.9 million |
|---|
| § | Gross profit increased $107.4 million, or 11%, to $1,100.9 million |
|---|
| § | Aggregates segment sales increased $417.6 million, or 13%, to $3,513.6 million |
|---|
| § | Aggregates segment freight-adjusted revenues increased $274.6 million, or 11%, to $2,667.3 million |
|---|
| § | Shipments increased 10%, or 18.2 million tons, to 201.4 million tons |
|---|
| § | Same-store shipments increased 6%, or 10.7 million tons, to 193.8 million tons |
|---|
| § | Freight-adjusted sales price increased 1%, or $0.19 per ton |
|---|
| § | Same-store freight-adjusted sales price increased 2%, or $0.21 per ton |
|---|
| § | Segment gross profit increased $137.3 million, or 16%, to $991.9 million |
|---|
| § | Asphalt, Concrete and Calcium segment gross profit decreased $29.9 million, or 22%, to $109.1 million, collectively |
|---|
| § | Selling, administrative and general (SAG) expenses increased 3% to $333.4 million and decreased 0.75 percentage points (75 basis points) as a percentage of total revenues |
|---|
| § | Operating earnings increased $108.7 million, or 17%, to $747.7 million |
|---|
| § | Earnings from continuing operations before income taxes were $623.3 million compared to $361.3 million |
|---|
| § | Effective tax rate was 16.9% compared with negative 64.2% |
|---|
| § | Earnings from continuing operations were $517.8 million, or $3.87 per diluted share, compared to $593.4 million, or $4.40 per diluted share |
|---|
| § | Discrete items in 2018 include: |
|---|
| § | $0.6 million of tax expense related to the Tax Cuts and Jobs Act (TCJA) |
|---|
| § | pretax interest charges of $7.4 million related to the January and March early debt retirements |
|---|
| § | pretax gains of $2.9 million for the sale of businesses |
|---|
| § | pretax charges of $18.5 million for divested operations |
|---|
| § | pretax gains of $2.3 million for business interruption claims |
|---|
| § | pretax charges of $5.2 million associated with non-routine business development |
|---|
| § | pretax charges of $6.2 million for restructuring |
|---|
| § | Discrete items in 2017 include: |
|---|
| § | $297.0 million of net tax benefits (including $268.2 million related to TCJA and a $28.8 million partial release of a net operating loss (NOL) carryforward valuation allowance) |
|---|
| § | pretax interest charges of $153.1 million related to debt purchases |
|---|
| § | pretax gains of $10.5 million for the sale of real estate and businesses |
|---|
| § | pretax charges of $4.3 million for property donation |
|---|
| § | pretax charges of $18.1 million for divested operations |
|---|
| § | pretax charges of $6.7 million for one-time employee bonuses |
|---|
| § | pretax charges of $3.1 million associated with non-routine business development, net of an asset purchase agreement termination fee |
|---|
| § | pretax charges of $1.9 million for restructuring |
|---|
| § | Net earnings were $515.8 million, a decrease of $85.4 million, or 14% |
|---|
| § | Adjusted EBITDA was $1,131.7 million, an increase of $149.8 million, or 15% |
|---|
| § | Returned capital to shareholders via dividends ($148.1 million versus $132.3 million) and share repurchases ($134.0 million versus $60.3 million) |
|---|
| Part II | 29 |
In 2018, we executed on our goals through a commitment to our shareholders, customers, employees and the communities we serve. We delivered growth and enhanced profitability in the face of several severe weather events that disrupted operations in some states for weeks at a time. With a clear and compelling strategy, a lean and locally-led operational structure, and unparalleled positions in attractive long-term growth markets, we are especially well-situated to benefit as infrastructure demand in key Vulcan states continues to grow, fueled by marked increases in state and local funding and we are well-equipped to overcome market challenges.
Even though the year provided plenty of headwinds for the construction industry, including weather disruptions and a 25% increase in the cost of diesel fuel during the year, we delivered strong top and bottom line growth. For the year, we increased total revenues, gross profit and earnings from continuing operations before income taxes, and adjusted earnings before interest, taxes, depreciation, and amortization (Adjusted EBITDA). Our 2018 net earnings were down compared to 2017 because of the one-time impact of TCJA on our 2017 income tax provision (-64.2% effective tax rate).
Our capital allocation and investment-grade rating priorities remain unchanged. For the full year, capital expenditures were $469.1 million. This amount included $221.7 million of core operating and maintenance capital investments to improve or replace existing property, plant & equipment. In addition, we invested $247.4 million in internal growth projects to secure new aggregates reserves, develop new production sites, enhance our distribution capabilities and support the targeted growth of our asphalt and concrete operations.
At year end, total debt was $2,912.4 million, or 2.6 times 2018 Adjusted EBITDA. Throughout 2017 and during the first quarter of 2018, we completed a number of debt refinancing activities (see Note 6 “Debt” in Item 8 “Financial Statements and Supplementary Data”) in order to extend the maturity of our debt portfolio consistent with the long-lived nature of our asset base. As a result of these actions, the weighted-average term of our debt portfolio has more than doubled to approximately 15 years.
As the leading aggregates producer in the U.S., serving many of the most attractive markets, we are well positioned for continued top line growth, particularly as federal, state and local governments increase spending on public infrastructure construction, while demand from private sector projects remains stable. In addition, our keen focus on operational excellence, cost control and disciplined investment should enable us to continue to enhance profitability and drive sustainable, long-term shareholder value.
Additionally, we advanced our world-class safety performance, improving on our record-setting results from the previous year.
2018 ACQUISITIONS
We continue to pursue opportunities for value-creating acquisitions, swaps and greenfield investments. We remain active in the pursuit of bolt-on acquisitions and other value-creating growth investments. We closed four business acquisitions during 2018 for total consideration of $219.9 million (see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data”). These acquisitions complement our existing positions in our Alabama, California and Texas markets.
We will continue to make disciplined investments in organic and acquisition-led growth, while continuing to
Showing the first 8K of 101K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
MARKET RISK
We are exposed to certain market risks arising from transactions that are entered into in the normal course of business. To manage these market risks, we may use derivative financial instruments. We do not enter into derivative financial instruments for speculative or trading purposes.
As discussed in the Liquidity and Financial Resources section of Item 7 “Management’s Discussion and Analysis of Financial Condition and Results of Operations,” we actively manage our capital structure and resources to balance the cost of capital and risk of financial stress. Such activity includes balancing the cost and risk of interest expense. In addition to floating-rate borrowings, we at times use interest rate swaps to manage the mix of fixed-rate and floating-rate debt. Over time, our EBITDA and operating income are positively correlated to floating interest rates (as measured by 3-month LIBOR). As such, our business serves as a natural hedge to rising interest rates, and floating-rate debt serves as a natural hedge against weaker operating results due to general economic weakness.
At December 31, 2018, the estimated fair value of our long-term debt including current maturities was $2,695.8 million compared to a book value of $2,779.4 million. The estimated fair value was determined by averaging several asking price quotes for the publicly traded notes and assuming par value for the remainder of the debt. The fair value estimate is based on information available as of the balance sheet date. The effect of a decline in interest rates of one percentage point would increase the fair value of our debt by approximately $236.1 million.
We are exposed to certain economic risks related to the costs of our pension and other postretirement benefit plans. These economic risks include changes in the discount rate for high-quality bonds and the expected return on plan assets. The impact of a change in these assumptions on our annual pension and other postretirement benefits costs is discussed in greater detail within the Critical Accounting Policies section of this Annual Report.
| Part II | 62 |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
To the shareholders and the Board of Directors of Vulcan Materials Company:
Opinion on the Financial Statements
We have audited the accompanying consolidated balance sheets of Vulcan Materials Company and subsidiaries (the “Company”) as of December 31, 2018 and 2017, the related consolidated statements of comprehensive income, equity, and cash flows, for each of the three years in the period ended December 31, 2018, and the related notes (collectively referred to as the “financial statements”). In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of December 31, 2018 and 2017, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2018, in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, 2018, based on the criteria established in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February 26, 2019 expressed an unqualified opinion on the Company's internal control over financial reporting.
Basis for Opinion
These financial statements are the responsibility of the Company's management. Our responsibility is to express an opinion on the Company’s financial statements based on our audits. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether due to error or fraud. Our audits included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements. We believe that our audits provide a reasonable basis for our opinion.
/s/ DELOITTE & TOUCHE LLP
Birmingham, Alabama
February 26, 2019
We have served as the Company’s auditor since 1956.
| Part II | 63 |
VULCAN MATERIALS COMPANY AND SUBSIDIARY COMPANIES
CONSOLIDATED STATEMENTS OF COMPREHENSIVE INCOME
| 2018 | 2017 | 2016 | ||||||
| For the years ended December 31 | ||||||||
| in thousands, except per share data | ||||||||
| Total revenues | $ 4,382,869 | $ 3,890,296 | $ 3,592,667 | |||||
| Cost of revenues | 3,281,924 | 2,896,783 | 2,603,782 | |||||
| Gross profit | 1,100,945 | 993,513 | 988,885 | |||||
| Selling, administrative and general expenses | 333,371 | 324,972 | 316,769 | |||||
| Gain on sale of property, plant & equipment and businesses | 14,944 | 17,827 | 15,431 | |||||
| Other operating expense, net | (34,805) | (47,324) | (21,645) | |||||
| Operating earnings | 747,713 | 639,044 | 665,902 | |||||
| Other nonoperating income, net | 13,000 | 13,357 | 14,624 | |||||
| Interest income | 554 | 4,437 | 807 | |||||
| Interest expense | 137,977 | 295,522 | 134,076 | |||||
| Earnings from continuing operations before income taxes | 623,290 | 361,316 | 547,257 | |||||
| Income tax expense (benefit) | ||||||||
| Current | 40,516 | 354 | 94,254 | |||||
| Deferred | 64,933 | (232,429) | 30,597 | |||||
| Total income tax expense (benefit) | 105,449 | (232,075) | 124,851 | |||||
| Earnings from continuing operations | 517,841 | 593,391 | 422,406 | |||||
| Earnings (loss) on discontinued operations, net of tax | (2,036) | 7,794 | (2,915) | |||||
| Net earnings | $ 515,805 | $ 601,185 | $ 419,491 | |||||
| Other comprehensive income (loss), net of tax | ||||||||
| Deferred gain on interest rate derivative | 2,496 | 0 | 0 | |||||
| Amortization of prior interest rate derivative loss | 226 | 1,862 | 1,194 | |||||
| Adjustment for funded status of benefit plans | (207) | (14,106) | (20,583) | |||||
| Amortization of actuarial loss and prior service cost for benefit plans | 4,365 | 2,154 | 82 | |||||
| Other comprehensive income (loss) | 6,880 | (10,090) | (19,307) | |||||
| Comprehensive income | $ 522,685 | $ 591,095 | $ 400,184 | |||||
| Basic earnings (loss) per share | ||||||||
| Continuing operations | $ 3.91 | $ 4.48 | $ 3.17 | |||||
| Discontinued operations | (0.01) | 0.06 | (0.02) | |||||
| Net earnings | $ 3.90 | $ 4.54 | $ 3.15 | |||||
| Diluted earnings (loss) per share | ||||||||
| Continuing operations | $ 3.87 | $ 4.40 | $ 3.11 | |||||
| Discontinued operations | (0.02) | 0.06 | (0.02) | |||||
| Net earnings | $ 3.85 | $ 4.46 | $ 3.09 | |||||
| Weighted-average common shares outstanding | ||||||||
| Basic | 132,393 | 132,513 | 133,205 | |||||
| Assuming dilution | 133,926 | 134,878 | 135,790 | |||||
| The accompanying Notes to Consolidated Financial Statements are an integral part of these statements. |
| Part II | 64 |
VULCAN MATERIALS COMPANY AND SUBSIDIARY COMPANIES
CONSOLIDATED BALANCE SHEETS
| 2018 | 2017 | ||||
| As of December 31 | |||||
| in thousands | |||||
| Assets | |||||
| Cash and cash equivalents | $ 40,037 | $ 141,646 | |||
| Restricted cash | 4,367 | 5,000 | |||
| Accounts and notes receivable | |||||
| Customers, less allowance for doubtful accounts | |||||
| 2018 — $2,090; 2017 — $2,649 | 512,279 | 434,089 | |||
| Other | 28,499 | 154,248 | |||
| Inventories | 429,330 | 384,338 | |||
| Other current assets | 64,633 | 60,780 | |||
| Total current assets | 1,079,145 | 1,180,101 | |||
| Investments and long-term receivables | 44,615 | 35,115 | |||
| Property, plant & equipment, net | 4,237,307 | 3,918,931 | |||
| Goodwill | 3,165,396 | 3,122,321 | |||
| Other intangible assets, net | 1,095,378 | 1,063,630 | |||
| Other noncurrent assets | 210,289 | 184,793 | |||
| Total assets | $ 9,832,130 | $ 9,504,891 | |||
| Liabilities | |||||
| Current maturities of long-term debt | 23 | 41,383 | |||
| Short-term debt | 133,000 | 0 | |||
| Trade payables and accruals | 216,473 | 197,335 | |||
| Accrued salaries, wages and management incentives | 91,960 | 87,208 | |||
| Accrued interest | 19,631 | 11,664 | |||
| Other current liabilities | 141,463 | 105,282 | |||
| Total current liabilities | 602,550 | 442,872 | |||
| Long-term debt | 2,779,357 | 2,813,482 | |||
| Deferred income taxes, net | 567,283 | 464,081 | |||
| Deferred management incentive and other compensation | 16,604 | 19,856 | |||
| Pension benefi |
Showing the first 8K of 202K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
None.
Item 9A. CONTROLS AND PROCEDURES
CONTROLS AND PROCEDURES
DISCLOSURE CONTROLS AND PROCEDURES
We maintain a system of controls and procedures designed to ensure that information required to be disclosed in reports we file with the SEC is recorded, processed, summarized and reported within the time periods specified by the SEC's rules and forms. These disclosure controls and procedures (as defined in the Securities Exchange Act of 1934 Rules 13a - 15(e) or 15d - 15(e)), include, without limitation, controls and procedures designed to ensure that such information is accumulated and communicated to our management, including our Chief Executive Officer and Chief Financial Officer, to allow timely decisions regarding required disclosure. Our Chief Executive Officer and Chief Financial Officer, with the participation of other management officials, evaluated the effectiveness of the design and operation of the disclosure controls and procedures as of December 31, 2018. Based upon that evaluation, our Chief Executive Officer and Chief Financial Officer concluded that our disclosure controls and procedures were effective as of December 31, 2018.
No material changes were made during the fourth quarter of 2018 to our internal control over financial reporting, nor have there been other factors that materially affect these controls.
MANAGEMENT'S REPORT ON INTERNAL CONTROL OVER FINANCIAL REPORTING
Our management is responsible for establishing and maintaining an adequate system of internal control over financial reporting as required by the Sarbanes-Oxley Act of 2002 and as defined in Securities Exchange Act Rule 13a-15(f).
Under management's supervision, an evaluation of the design and effectiveness of our internal control over financial reporting was conducted based on the framework in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission. Based on this evaluation, management concluded that our internal control over financial reporting was effective as of December 31, 2018.
Deloitte & Touche LLP, an independent registered public accounting firm, as auditors of our consolidated financial statements, has issued an attestation report on the effectiveness of our internal control over financial reporting as of December 31, 2018. Deloitte & Touche LLP's report, which expresses an unqualified opinion on the effectiveness of our internal control over financial reporting, follows this report.
LIMITATIONS OF EFFECTIVENESS OF CONTROLS AND PROCEDURES
In designing and evaluating our disclosure controls and procedures, management recognizes that any controls and procedures, no matter how well designed and operated, can provide only reasonable assurance of achieving the desired control objectives. In addition, the design of disclosure controls and procedures must reflect the fact that there are resource constraints and that management is required to apply its judgment in evaluating the benefits of possible controls and procedures relative to their costs.
| Part II | 118 |
REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM – INTERNAL CONTROL OVER FINANCIAL REPORTING
To the shareholders and Board of Directors of Vulcan Materials Company:
Opinion on Internal Control over Financial Reporting
We have audited the internal control over financial reporting of Vulcan Materials Company and subsidiaries (the “Company”) as of December 31, 2018, based on criteria established in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2018, based on criteria established in Internal Control — Integrated Framework (2013) issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated financial statements as of and for the year ended December 31, 2018, of the Company and our report dated February 26, 2019, expressed an unqualified opinion on those financial statements.
Basis for Opinion
The Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit. We are a public accounting firm registered with the PCAOB and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
Definition and Limitations of Internal Control over Financial Reporting
A company's internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company's internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company's assets that could have a material effect on the financial statements.
Because of the inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of the effectiveness to future periods are subject to the risk that the controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
| /s/ DELOITTE & TOUCHE LLP |
| Birmingham, Alabama |
| February 26, 2019 |
| Part II | 119 |
Item 9B. OTHER INFORMATION
OTHER INFORMATION
None.
| Part II | 120 |
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
On or about March 26, 2019, we expect to file a definitive proxy statement with the Securities and Exchange Commission pursuant to Regulation 14A (our “2019 Proxy Statement”). The information under the headings “Proposal 1 - Election of Directors,” “Corporate Governance of our Company and Practices of our Board of Directors,” and “General Information - Section 16(a) Beneficial Ownership Reporting Compliance” included in our 2019 Proxy Statement is incorporated herein by reference. See also the information about our executive officers and governance policies set forth above in Part I, Item I “Business” of this report.
Item 11. EXECUTIVE COMPENSATION
EXECUTIVE COMPENSATION
The information under the headings “Compensation Discussion and Analysis,” “Director Compensation,” “Executive Compensation,” “Corporate Governance of our Company and Practices of our Board of Directors,” and “Compensation Committee Report” included in our 2019 Proxy Statement is incorporated herein by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED
SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED
STOCKHOLDER MATTERS
The information under the headings “Security Ownership of Certain Beneficial Owners and Management,” “Equity Compensation Plans” and “Executive Compensation — Payments Upon Termination or Change in Control” included in our 2019 Proxy Statement is incorporated herein by reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
The information under the heading “Corporate Governance of our Company and Practices of our Board of Directors” included in our 2019 Proxy Statement is incorporated herein by reference.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
PRINCIPAL ACCOUNTING FEES AND SERVICES
The information under the heading entitled “Independent Registered Public Accounting Firm” included in our 2019 Proxy Statement is incorporated herein by reference.
| 1208 | |
|---|---|
| Part III | 121 |
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
(a) (1) Financial statements
The following financial statements are included herein on the pages shown below:
| Page in Report | |||
| Report of Independent Registered Public Accounting Firm | 63 | ||
| Consolidated Statements of Comprehensive Income | 64 | ||
| Consolidated Balance Sheets | 65 | ||
| Consolidated Statements of Cash Flows | 66 | ||
| Consolidated Statements of Equity | 67 | ||
| Notes to Consolidated Financial Statements | 68-117 |
(a) (2) Financial statement schedules
Financial statement schedules are omitted because of the absence of conditions under which they are required or because the required information is provided in the financial statements or notes thereto.
Financial statements (and summarized financial information) of 50% or less owned entities accounted for by the equity method have been omitted because they do not, considered individually or in the aggregate, constitute a significant subsidiary.
(a) (3) Exhibits
| Part IV | 122 |
| Part IV | 123 |
| Part IV | 124 |
| Part IV | 125 |
| Exhibit 101.INS | XBRL Instance Document | ||
|---|---|---|---|
| Exhibit 101.SCH | XBRL Taxonomy Extension Schema Document | ||
| Exhibit 101.CAL | XBRL Taxonomy Extension Calculation Linkbase Document | ||
| Exhibit 101.LAB | XBRL Taxonomy Extension Label Linkbase Document | ||
| Exhibit 101.PRE | XBRL Taxonomy Extension Presentation Linkbase Document | ||
| Exhibit 101.DEF | XBRL Taxonomy Extension Definition Linkbase Document | ||
| 1 | Incorporated by reference. | ||
| 2 | Management contract or compensatory plan. | ||
| 3 | The schedules and exhibits to the Purchase Agreement have been omitted pursuant to Item 601(b)(2) of Regulation S-K. Vulcan agrees to furnish supplementally a copy of such schedules and exhibits, or any section thereof, to the SEC upon request. |
Our SEC file number for documents filed with the SEC pursuant to the Securities Exchange Act of 1934, as amended, is 001-33841.
| Part IV | 126 |
Item 16. FORM 10-K SUMMARY
FORM 10-K SUMMARY
We have chosen not to include an optional summary of the information required by this Form 10-K.
| Part IV | 127 |
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized on February 26, 2019.
| VULCAN MATERIALS COMPANY | |
 J. Thomas Hill Chairman, President and Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| Signature | Title | Date |
| J. Thomas Hill | Chairman, President and Chief Executive Officer (Principal Executive Officer) | February 26, 2019 |
 Suzanne H. Wood | Senior Vice President and Chief Financial Officer (Principal Financial Officer) | February 26, 2019 |
 Randy L. Pigg | Vice President, Controller (Principal Accounting Officer) | February 26, 2019 |
| The following directors: Thomas A. Fanning O. B. Grayson Hall, Jr. Cynthia L. Hostetler Richard T. O'Brien James T. Prokopanko Kathleen L. Quirk David P. Steiner Lee J. Styslinger, III | Director Director Director Director Director Director Director Director | |
 Michael R. Mills Attorney-in-Fact | February 26, 2019 |
| Part IV | 128 |