 filings.tools
Item 1. BUSINESS
44K characters. Original on sec.gov · Markdown
Item 1. BUSINESS
BUSINESS
Vulcan Materials Company, a New Jersey corporation, operates primarily in the U.S. and is the nation’s largest supplier of construction aggregates (primarily crushed stone, sand and gravel) and a major producer of asphalt mix and ready-mixed concrete. We provide the basic materials for the infrastructure needed to maintain and expand the U.S. economy. Delivered by trucks, ships, barges and trains, our products are the indispensable materials building homes, offices, places of worship, schools, hospitals and factories, as well as vital infrastructure including highways, bridges, roads, ports and harbors, water systems, campuses, dams, airports and rail networks. As of December 31, 2018, we had 351 active aggregates facilities, 67 asphalt facilities and 46 concrete facilities.
BUSINESS STRATEGY
Our strategy and competitive advantage are based on our strength in aggregates which are used in most types of construction and in the production of asphalt mix and ready-mixed concrete. Our strategy for long-term value creation is built on: (1) an aggregates-focused business, (2) a disciplined approach to portfolio management and capital allocation, (3) a focus on continuous compounding improvement in profitability, (4) a holistic approach to land management, and (5) our commitment to safety, health and the environment.
- AGGREGATES FOCUS
Aggregates are used in virtually all types of public and private construction and practically no substitutes for quality aggregates exist. Given our focus on aggregates, we:
BUILD AND HOLD SUBSTANTIAL RESERVES: Our reserves are critical to our long-term success. We currently have 16.3 billion tons of permitted and proven or probable aggregates reserves. They are strategically located throughout the United States in high-growth areas that are expected to require large amounts of aggregates to meet future construction demand. Moreover, there are significant barriers to entry in many metropolitan markets due to stringent zoning and permitting regulations. These restrictions curtail expansion in certain areas, but they also increase the value of our reserves at existing locations. Our downstream businesses (asphalt and concrete) use Vulcan-produced aggregates almost exclusively.
TAKE ADVANTAGE OF SIZE AND SCALE: We are the largest aggregates supplier in the U.S. Our 351 active aggregates facilities as of December 31, 2018 provide opportunities to standardize operating practices and procure equipment (fixed and mobile), parts, supplies and services in an efficient and cost-effective manner, both regionally and nationally. Each aggregates operation is also unique because of its location within a local market and its particular geological characteristics. Every operation, however, uses a similar group of assets to produce saleable aggregates and provide customer service. Additionally, we are able to share best practices across the organization and leverage our size for administrative support, customer service, accounting, procurement, technical support and engineering.
| Part I | 3 |
- PORTFOLIO MANAGEMENT AND CAPITAL ALLOCATION
Demand for our products is dependent on construction activity and correlates positively with changes in population growth, household formation and employment. During the period 2020 - 2030, Moody's Analytics projects that 80% of the U.S. population growth, 73% of household formation and 64% of new jobs will occur in Vulcan-served states. The close proximity of our production facilities and our aggregates reserves to this projected population growth creates many opportunities to invest capital in high-return projects.
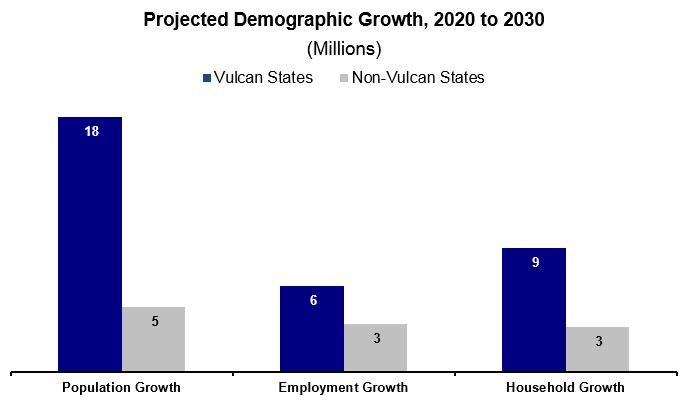
Source: Moody’s Analytics as of December 14, 2018
We have pursued a strategy to increase our presence in U.S. metropolitan areas that are expected to grow the most rapidly and by divesting assets that are no longer considered part of our long-term growth strategy. Our coast-to-coast footprint serves 19 of the top 25 highest-growth U.S. metropolitan areas in 20 states plus the District of Columbia.
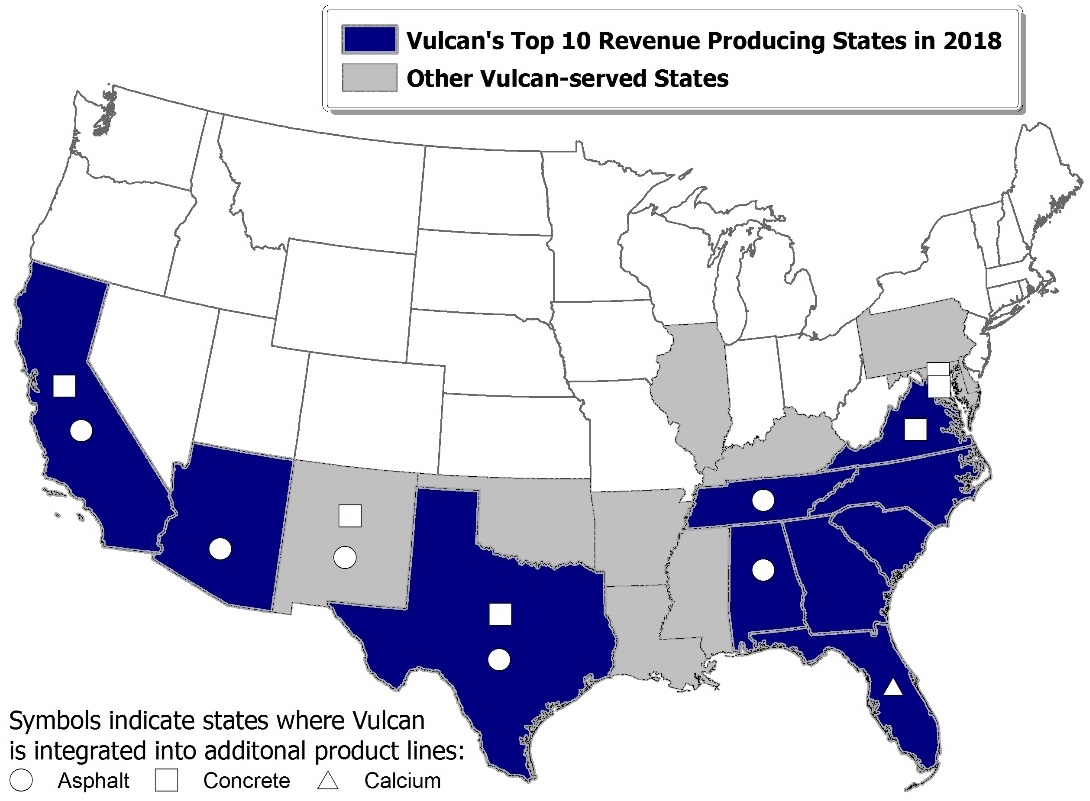
Our top ten revenue producing states accounted for 86% of our 2018 revenues while our top five accounted for 61%.
| VULCAN’S TOP TEN REVENUE PRODUCING STATES IN 2018 | ||||||||||||
| 1. | California | 6. | Florida | |||||||||
| 2. | Texas | 7. | Arizona | |||||||||
| 3. | Virginia | 8. | North Carolina | |||||||||
| 4. | Tennessee | 9. | South Carolina | |||||||||
| 5. | Georgia | 10. | Alabama |
| Part I | 4 |
| § | portfolio management: Since becoming a public company in 1957, Vulcan has principally grown by mergers and acquisitions. For example, in 1999 we acquired CalMat Co., thereby expanding our aggregates operations into California and Arizona and making us one of the nation’s leading producers of asphalt mix. In 2007, we acquired Florida Rock Industries, Inc. This acquisition expanded our aggregates business in Florida and our aggregates and ready-mixed concrete businesses in other Southeastern and Mid-Atlantic states. In 2017, we acquired Aggregates USA — this acquisition greatly expanded our ability to serve customers in Florida, Georgia and South Carolina. |
|---|
Additionally, throughout our history we have completed many bolt-on acquisitions that have contributed significantly to our growth. We closed seven additional acquisitions in 2017 that complement our existing positions in Arizona, California, Illinois, New Mexico, Tennessee, and Virginia. From 2015 to 2017, we invested over $1.2 billion in acquisitions and internal projects for long-term growth, while further strengthening our portfolio through divestitures and swaps, including swapping our concrete operations in Arizona for asphalt operations in Arizona during 2017.
While an aggregates-focused business, we selectively make investments in downstream products that drive local market profitability. In January 2017, we entered the asphalt market in Tennessee through the acquisition of several asphalt mix operations and a construction paving business. During 2018, we entered the asphalt mix and construction paving markets in Alabama and expanded our asphalt operations and service offerings in Texas through the acquisition of several asphalt mix operations and construction paving businesses.
| § | capital allocation: Our long-term strategy around capital allocation has given us the ability to leverage decisions we have made over the past few years. During 2018, we reinvested $469.1 million into core operating, internal growth and maintenance capital expenditures, in addition to $459.6 million reinvested in 2017. These investments are fundamental actions that strengthen the business. They improve the longer-term efficiency, capacity and flexibility of our production, and they support our strong commitment to superior customer service. |
|---|
- compounding improvement in profitability
Our focus on the following three major profit drivers has made us one of the most profitable public companies in the industry (as measured by aggregates gross profit per ton).
| § | Price for Service — We seek to receive full and fair value for the quality of products and services we provide. We should be paid appropriately for helping our customers be successful. Our expanding margins will continue to benefit from the compounding pricing gains associated with cyclical recoveries. |
|---|
| § | Operating Efficiency and Leverage — We focus on rigorous cost management throughout the economic cycle. Small savings per ton add up to significant cost reductions. We are operating a capital-intensive business well below full capacity and are extremely well positioned to further leverage fixed costs on incremental sales as we move forward. |
|---|
| § | Sales and Production Mix — We adjust production levels to meet varying market conditions. Managing inventories responsibly results in improved cost performance and an improved return on capital. As the recovery continues and as we see a larger portion of new construction activity in the end-use mix, we will sell the entire production mix much more efficiently and at fuller value. |
|---|
We manage these factors locally and align our talent and incentives accordingly. Our knowledgeable and experienced workforce and our flexible production capabilities allow us to manage operational and overhead costs aggressively. Recovery in demand serves as a tailwind for all three major profit drivers.
| Part I | 5 |
- LAND MANAGEMENT
With approximately 240,000 acres in our land portfolio, a long-term holistic approach to preserving land and water is integral to sustaining our success. From pre-mining to mining to reclamation, we are actively managing the entire life cycle of our land, creating maximum value for the business, our shareholders and our communities.
We are putting land to use before we mine by creating opportunities for agriculture and timber development. After mining, our land and water assets will be converted to other valuable uses including drinking water reservoirs, aquifer recharge basins, public parks, habitat mitigation banks, wetlands, productive farmland and residential and commercial developments.
Because of the evolving needs of our communities, we listen to and collaborate with our neighbors to prepare the land for its highest and best use after mining is complete. Our work with state, regional and local governments to develop solutions today will benefit future generations.
- SAFETY, HEALTH AND THE ENVIRONMENT
A strategy for sustainable, long-term value creation must include doing right by your employees, your neighbors and the environment in which you operate. We are a leader in our industry in safety performance by applying the shared experiences, expertise and resources at each of our locally led sites with an emphasis on taking care of one another. We focus on our environmental stewardship programs with the same intensity that we bring to our health and safety initiatives. And, our community relations programs serve our neighbors, while ensuring that we grow and thrive in the communities where we operate.
PRODUCT LINES
Our products are used to build the roads, tunnels, bridges, railroads and airports that connect us, and to build the hospitals, schools, shopping centers, factories and places of worship that are essential to our lives and the economy. We have four operating (and reportable) segments organized around our principal product lines:
| 1. | Aggregates – 74% of 2018’s total revenues and 90% of gross profit |
|---|
| 2. | Asphalt – 17% of 2018’s total revenues and 5% of gross profit |
|---|
| 3. | Concrete – 9% of 2018’s total revenues and 5% of gross profit |
|---|
| 4. | Calcium – less than 1% of 2018’s total revenues and less than 1% of gross profit |
|---|
See Note 15 “Segment Reporting” in Item 8 “Financial Statements and Supplementary Data.”
- AGGREGATES
Our construction aggregates are used in a number of ways:
| § | as a base material underneath highways, walkways, airport runways, parking lots and railroads |
|---|
| § | to aid in water filtration, purification and erosion control |
|---|
| § | as a raw material used in combination with other resources to construct many of the items we rely on to sustain our quality of life including: |
|---|
| § | houses and apartments |
|---|
| § | roads, bridges and parking lots |
|---|
| § | schools and hospitals |
|---|
| § | commercial buildings and retail space |
|---|
| § | sewer systems |
|---|
| § | power plants |
|---|
| § | airports and runways |
|---|
| Part I | 6 |
AGGREGATES INDUSTRY
Factors that affect the U.S. aggregates industry and our business include:
| § | Location of reserves: Aggregates have a high weight-to-value ratio and, in most cases, must be produced near where they are used; if not, transportation can cost more than the materials, rendering them uncompetitive compared to locally produced materials. Exceptions to this typical market structure include areas along the U.S. Gulf Coast and the Eastern Seaboard where there are limited supplies of locally available, high-quality aggregates. We serve these markets from quarries that have access to cost-effective long-haul transportation — shipping by barge and rail — and from our quarry on Mexico’s Yucatan Peninsula with our fleet of Panamax-class, self-unloading ships. |
|---|
Where practical, we have operations located close to our local markets because the cost of trucking materials long distances is prohibitive. Approximately 80% of our total aggregates shipments are delivered exclusively from the producing location to the customer by truck, and another 15% are delivered by truck after reaching a sales yard by rail or water. The remaining 5% of aggregates shipments are delivered directly to the customer by rail or water.
| § | Limited product substitution: There are limited substitutes for quality aggregates. Recycled concrete and asphalt have certain applications as a lower-cost alternative to virgin aggregates. However, many types of construction projects cannot be served by recycled concrete and require the use of virgin aggregates to meet technical specifications and performance-based criteria for durability, strength and other qualities. Moreover, the amount of recycled asphalt included in asphalt mix as a substitute for aggregates is limited due to specifications. |
|---|
| § | Highly fragmented industry: The U.S. aggregates industry is composed of over 5,800 companies that manage more than 10,600 operations. This fragmented structure provides many opportunities for consolidation. Companies in the industry commonly enter new markets or expand positions in existing markets through the acquisition of existing facilities. |
|---|
Through strategic acquisitions and investments, we have developed an unmatched coast-to-coast footprint of strategically located permitted reserves concentrated in and serving the nation’s key growth centers. We have over 23,000 customers in 20 states, the District of Columbia, Mexico and the Bahamas.
| § | Flexible production capabilities: The production of aggregates is a mechanical process in which stone is crushed and, through a series of screens, separated into various sizes depending on how it will be used. Production capacity can be flexible by adjusting operating hours to meet changing market demand. |
|---|
| § | raw material inputs largely ControlLED: Unlike typical industrial manufacturing industries, the aggregates industry does not require the input of raw material beyond owned or leased aggregates reserves. Stone, sand and gravel are naturally occurring resources. However, production does require the use of explosives, hydrocarbon fuels and electric power. |
|---|
| § | Demand cycles: Long-term growth in demand for aggregates is largely driven by growth in population, jobs and households. While short-term and medium-term demand for aggregates fluctuates with economic cycles, declines have historically been followed by strong recoveries, with each peak establishing a new historical high. |
|---|
The drivers underpinning demand recovery — and sustained, multi-year volume and pricing growth — remain firmly in place, in both the public and private sectors of the economy. They include: population growth; gains in total employment and in household income and wages; a continuing increase in household formations; the growing need for additional housing stock and housing demand; a multi-year federal transportation law in place and continuing increases in transportation funding at state and local levels; record state tax receipts; public investment in infrastructure that is still well below the long-term trend-line, and increasing political awareness and acceptance of the need to invest in infrastructure.
| Part I | 7 |
AGGREGATES MARKETS
We focus on the U.S. markets with above-average long-term expected population growth and where construction is expected to expand. Because transportation is a significant part of the delivered cost of aggregates, our facilities are typically located in the markets they serve or have access to economical transportation via rail, barge or ship to a particular end market. We serve both the public and the private sectors.
Public sector construction activity has historically been more stable and less cyclical than privately-funded construction, and generally requires more aggregates per dollar of construction spending. Private sector construction (primarily residential and nonresidential buildings) typically is more affected by general economic cycles than publicly-funded projects (particularly highways, roads and bridges), which tend to receive more consistent levels of funding throughout economic cycles.
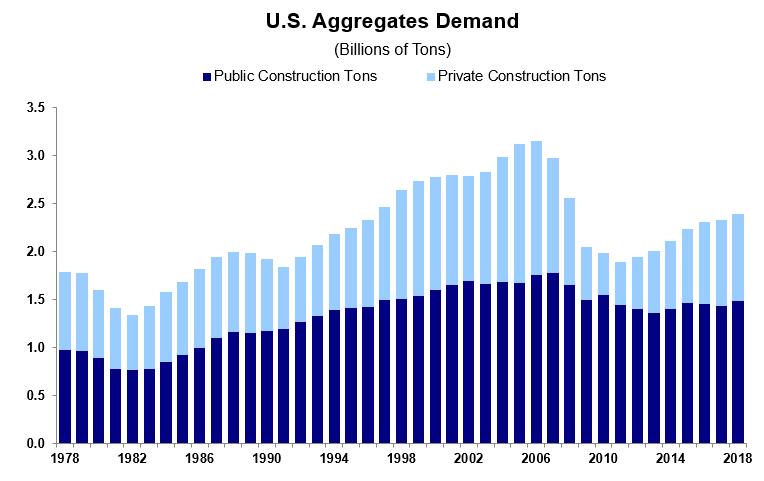
Source: Company estimates
| Part I | 8 |
PUBLIC SECTOR CONSTRUCTION MARKET
Public sector construction includes spending by federal, state, and local governments for highways, bridges, buildings, airports, schools and prisons as well as other infrastructure construction for sewer and waste disposal systems, water supply systems, dams, reservoirs and other public construction projects. Construction for power plants and other utilities is funded from both public and private sources. In 2018, publicly-funded construction accounted for approximately 44% of our total aggregates shipments, and approximately 23% of our aggregates sales by volume were used in highway construction projects.
| § | Public Sector Funding: Generally, public sector construction spending is more stable than private sector construction spending; public sector spending is less sensitive to interest rates and has historically been supported by multi-year laws, which provide certainty in funding amounts, program structures, and rules and regulations. Federal spending is governed by authorization, budget and appropriations laws. The level of state and local spending on infrastructure varies across the United States and depends on individual state needs and economies. |
|---|
| § | STATE AND LOCAL TRANSPORTATION FUNDING: Since 2012, 31 states have approved plans to increase revenues for transportation investment through motor fuel tax increases, revenues outside of fuel taxes, and one-time increases; 13 of those states, representing 81% of our 2018 revenues, are in Vulcan’s footprint. In 2017 alone, 7 state legislatures voted to raise motor fuel taxes for transportation investment. |
|---|
In the November 2018 general election, voters in 31 states approved 79% of 352 state and local transportation funding ballot measures. Major transportation funding measures in Vulcan-served areas are estimated to result in $30 billion in revenues and bond proceeds primarily dedicated to roads, streets and bridges. Including 2018, voters have approved 78% of nearly 1,700 transportation investment ballot measures since 2009.
| § | federal highway funding: In December 2015, President Obama signed a new, long-term federal highway and transit authorization bill, Fixing America’s Surface Transportation Infrastructure Act (FAST Act), into law after the final legislation received strong, bipartisan support in both the House and the Senate. The FAST Act provides multi-year funding to state and local governments in support of road, bridge, intermodal and public transportation projects. |
|---|
The FAST Act increases Federal-Aid Highway Program funding from $41 billion in the federal fiscal year (FFY) 2015 to $47 billion in FFY 2020. In addition, the Bipartisan Budget Act of 2018 added approximately $2 billion per year to base highway programs in 2018 and 2019.
The long-term nature of the FAST Act is important. The Federal-Aid Highway Program is the largest component of the law and has provided, on average, 52% of all state capital investment in roads and bridges over the last 10 years. This multi-year authorization and the associated dedicated funding provides state departments of transportation with the ability to plan and execute long-range, complex highway projects.
The FAST Act also contains important policy changes. To further accelerate the project delivery process, it augments the environmental review and permitting process reforms contained in the prior law, Moving Ahead for Progress in the 21st Century Act (MAP-21). The new law also provides assistance for states making investments in major capital projects — particularly freight projects. In states where we operate, we are well positioned to serve the large general contractors who will compete for new freight and other major capacity projects that will move forward with this FAST Act funding and policy implementation.
Project financing remains an important additional component of overall surface transportation spending, with the Transportation Infrastructure Finance & Innovation Act (TIFIA) program authorized at $275 million (in line with the previous program outlays) and growing to $300 million by 2020. The FAST Act also created a new National Surface Transportation and Innovative Finance Bureau to provide technical assistance to states seeking to pursue public-private partnerships and other financing arrangements for transportation projects.
| Part I | 9 |
| § | FEDERAL WATER INFRASTRUCTURE: In October 2018, President Trump signed America’s Water Infrastructure Act of 2018 (AWIA 2018) into law. The new law includes the Water Resources Development Act of 2018 (WRDA 2018), which reauthorizes needed investment in America’s ports, channels, locks, dams, and other infrastructure that supports the maritime and waterways transportation system and provides flood protection for communities. It also improves EPA programs for storm water, water recycling, and sewer overflow projects. Included in AWIA 2018 are improvements to the Water Infrastructure Finance and Innovation Act (WIFIA) program, which was modeled after the highly popular TIFIA program in the surface transportation sector. Created in the Water Resources Reform and Development Act of 2014 (WRRDA 2014), WIFIA allows for federal credit assistance to water resources projects in the form of low-cost loans, loan guarantees and lines of credit. |
|---|
In addition to these regular authorizations, $89.3 billion in immediate federal emergency supplemental appropriations was provided for disaster recovery in the Bipartisan Budget Act of 2018 for hurricane-affected areas in Florida, Louisiana, Texas and other states. A portion of these funds will be directed to long-term and short-term U.S. Army Corps of Engineers-supported flood control and other water resources construction projects as well as additional infrastructure projects that use aggregates and related materials.
Private sector CONSTRUCTION MARKET
The private sector construction markets include both nonresidential building construction and residential construction and are considerably more cyclical than public construction. In 2018, privately-funded construction accounted for approximately 56% of our total aggregates shipments.
| § | Nonresidential Construction: Private nonresidential building construction includes a wide array of projects. Such projects generally are more aggregates intensive than residential construction. Overall demand in private nonresidential construction generally is driven by job growth, vacancy rates, private infrastructure needs and demographic trends. The growth of the private workforce creates demand for offices, hotels and restaurants. Likewise, population growth generates demand for stores, shopping centers, warehouses and parking decks as well as hospitals, places of worship and entertainment facilities. Large industrial projects, such as a new manufacturing facility, can increase the need for other manufacturing plants to supply parts and assemblies. Construction activity in this end market is influenced by a firm's ability to finance a project and the cost of such financing. This end market also includes capital investments in public nonresidential facilities to meet the needs of a growing population. |
|---|
| § | Residential Construction: Household formations in Vulcan-served states continue to outpace household formations in the rest of the United States. The majority of residential construction is for single-family housing with the remainder consisting of multi-family construction (i.e., two family houses, apartment buildings and condominiums). Public housing comprises only a small portion of housing demand. Construction activity in this end market is influenced by the cost and availability of mortgage financing and builders’ ability to maintain skilled labor. |
|---|
U.S. housing starts, as measured by Dodge Data & Analytics data, peaked in early 2006 at over 2 million units annually. By the end of 2009, total housing starts had declined to less than 0.6 million units, well below prior historical lows of approximately 1 million units annually. In 2018, total annual housing starts in the U.S. reached 1.35 million units.
ADDITIONAL AGGREGATES PRODUCTS AND MARKETS
We sell aggregates that are used as ballast for construction and maintenance of railroad tracks. We also sell riprap and jetty stone for erosion control along roads and waterways. In addition, stone can be used as a feedstock for cement and lime plants and for making a variety of adhesives, fillers and extenders. Coal-burning power plants use limestone in scrubbers to reduce harmful emissions. Limestone that is crushed to a fine powder can be sold as agricultural lime.
We sell a relatively small amount of construction aggregates outside of the United States, principally in the areas surrounding our large quarry on the Yucatan Peninsula in Mexico. Nondomestic sales and long-lived assets outside the United States are reported in Note 15 “Segment Reporting” in Item 8 “Financial Statements and Supplementary Data.”
| Part I | 10 |
VERTICAL INTEGRATION
While aggregates is our focus and primary business, we believe vertical integration between aggregates and downstream products, such as asphalt mix and ready-mixed concrete, can be managed effectively in certain markets generating acceptable financial returns and enhancing financial returns in our core Aggregates segment. We produce and sell asphalt mix and/or ready-mixed concrete primarily in our Alabama, mid-Atlantic, Southwestern, Tennessee and Western markets. Aggregates comprise approximately 95% of asphalt mix by weight and 80% of ready-mixed concrete by weight. In both of these downstream businesses, aggregates are primarily supplied from our operations.
| Part I | 11 |
- ASPHALT
We produce and sell asphalt mix in Alabama, Arizona, California, New Mexico, Tennessee and Texas. In June 2018, we strengthened our asphalt position in Texas by acquiring additional asphalt mix operations and a construction paving business. In March 2018, we entered the Alabama asphalt market through the acquisition of an aggregates, asphalt mix and construction paving business. In December 2017, we strengthened our asphalt position in Arizona by swapping ready-mixed concrete operations for an asphalt mix operation. In January 2017, we entered the Tennessee asphalt market through the acquisition of several asphalt mix operations and a construction paving business. For additional details, see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.”
This segment relies on our reserves of aggregates, functioning essentially as a customer to our aggregates operations. Aggregates are a major component in asphalt mix, comprising approximately 95% by weight of this product. We meet the aggregates requirements for our Asphalt segment primarily through our Aggregates segment. These product transfers are made at local market prices for the particular grade and quality of material required.
Because asphalt mix hardens rapidly, delivery typically is within close proximity to the producing facility. The asphalt mix production process requires liquid asphalt cement, which we purchase from third-party producers. We do not anticipate any significant difficulties in obtaining the raw materials necessary for this segment to operate. We serve our Asphalt segment customers directly from our local production facilities.
- CONCRETE
We produce and sell ready-mixed concrete in California, Maryland, New Mexico, Texas, Virginia, Washington D.C. and the Bahamas. In March 2018, we exited the Georgia ready-mixed concrete market (we retained all real property which is leased to the buyer, and obtained a long-term aggregates supply agreement). As noted above, in December 2017 we exited the Arizona ready-mixed concrete market via a swap for an asphalt mix operation, continuing our strategy to focus on asphalt mix in that market. In March 2017, we reentered the California ready-mixed concrete market through an acquisition. For additional details see Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.”
This segment relies on our reserves of aggregates, functioning essentially as a customer to our aggregates operations. Aggregates are a major component in ready-mixed concrete, comprising approximately 80% by weight of this product. We meet the aggregates requirements of our Concrete segment primarily through our Aggregates segment. These product transfers are made at local market prices for the particular grade and quality of material required.
We serve our Concrete segment customers from our local production facilities or by truck. Because ready-mixed concrete hardens rapidly, delivery typically is within close proximity to the producing facility. Ready-mixed concrete production also requires cement which we purchase from third-party producers. We do not anticipate any significant difficulties in obtaining the raw materials necessary for this segment to operate.
- CALCIUM
Our Calcium segment is composed of a single calcium operation in Brooksville, Florida. This facility produces calcium products for the animal feed, plastics and water treatment industries with high-quality calcium carbonate material mined at the Brooksville quarry.
| Part I | 12 |
OTHER BUSINESS-RELATED ITEMS
SEASONALITY AND CYCLICAL NATURE OF OUR BUSINESS
Almost all of our products are produced and consumed outdoors. Seasonal changes and other weather-related conditions can affect the production and sales volumes of our products. Therefore, the financial results for any quarter do not necessarily indicate the results expected for the year. Normally, the highest sales and earnings are in the third quarter and the lowest are in the first quarter. Furthermore, our sales and earnings are sensitive to national, regional and local economic conditions, demographic and population fluctuations, and particularly to cyclical swings in construction spending, primarily in the private sector.
COMPETITORS
We operate in a generally fragmented industry with a large number of small, privately-held companies. We estimate that the ten largest aggregates producers accounted for less than one-third of the total U.S. aggregates production in 2018. Despite being the industry leader, Vulcan’s total U.S. market share is less than 10%. Other publicly traded companies among the ten largest U.S. aggregates producers include the following:
| § | Cemex S.A.B. de C.V. |
|---|
| § | CRH plc |
|---|
| § | HeidelbergCement AG |
|---|
| § | LafargeHolcim |
|---|
| § | Martin Marietta Materials, Inc. |
|---|
| § | MDU Resources Group, Inc. |
|---|
| § | Summit Materials, Inc. |
|---|
Because the U.S. aggregates industry is highly fragmented, with over 5,800 companies managing more than 10,600 operations during 2018, many opportunities for consolidation exist. Therefore, companies in the industry tend to grow by acquiring existing facilities to enter new markets or extend their existing market positions.
CUSTOMERS
No material part of our business depends upon any single customer whose loss would have a significant adverse effect on our business. In 2018, our five largest customers accounted for 8% of our total revenues (excluding internal sales), and no single customer accounted for more than 2% of our total revenues. Our products typically are sold to private industry and not directly to governmental entities. Although approximately 45% to 55% of our aggregates shipments have historically been used in publicly-funded construction, such as highways, airports and government buildings, relatively insignificant sales are made directly to federal, state, county or municipal governments/agencies. Therefore, although reductions in state and federal funding can curtail publicly-funded construction, our business is not directly subject to renegotiation of profits or termination of contracts with state or federal governments.
| Part I | 13 |
ENVIRONMENTAL COSTS AND GOVERNMENTAL REGULATION
Our operations are subject to numerous federal, state and local laws and regulations relating to the protection of the environment and worker health and safety; examples include regulation of facility air emissions and water discharges, waste management, protection of wetlands, listed and threatened species, noise and dust exposure control for workers, and safety regulations under both Mine Safety and Health Administration (MSHA) and Occupational Safety and Health Administration (OSHA). Compliance with these various regulations requires a substantial capital investment, and ongoing expenditures for the operation and maintenance of systems and implementation of programs. We estimate that capital expenditures for environmental control facilities in 2019 and 2020 will be $12.2 million and $21.3 million, respectively. These anticipated expenditures are not expected to have a material impact on our earnings or competitive position.
We have received notices from the United States Environmental Protection Agency (EPA) or similar state or local agencies that we are considered a potentially responsible party (PRP) at a limited number of sites under the Comprehensive Environmental Response, Compensation and Liability Act (CERCLA or Superfund) or similar state and local environmental laws. Generally we share the cost of remediation at these sites with other PRPs or alleged PRPs in accordance with negotiated or prescribed allocations. There is inherent uncertainty in determining the potential cost of remediating a given site and in determining any individual party's share in that cost. As a result, estimates can change substantially as additional information becomes available about the nature or extent of site contamination, remediation methods, other PRPs and their probable level of involvement, and actions by or against governmental agencies or private parties.
For additional information about litigation and environmental matters, see Notes 1 and 12 to the consolidated financial statements in Item 8 “Financial Statements and Supplementary Data.”
Frequently, we are required by state and local regulations or contractual obligations to reclaim our former mining sites. These reclamation liabilities are recorded in our financial statements as a liability at the time the obligation arises. The fair value of such obligations is capitalized and depreciated over the estimated useful life of the owned or leased site. The liability is accreted through charges to operating expenses. To determine the fair value, we estimate the cost for a third party to perform the legally required reclamation, which is adjusted for inflation and risk and includes a reasonable profit margin. All reclamation obligations are reviewed at least annually. Reclaimed quarries often have potential for use in commercial or residential development or as reservoirs or landfills. However, no projected cash flows from these anticipated uses have been considered to offset or reduce the estimated reclamation liability.
For additional information about reclamation obligations (referred to in our financial statements as asset retirement obligations), see Notes 1 and 17 to the consolidated financial statements in Item 8 “Financial Statements and Supplementary Data.”
PATENTS AND TRADEMARKS
We do not own or have a license or other rights under any patents, registered trademarks or trade names that are material to any of our reporting segments.
OTHER INFORMATION ABOUT VULCAN
Vulcan is a New Jersey corporation incorporated on February 14, 2007, while its predecessor company was incorporated on September 27, 1956. Our principal sources of energy are electricity, diesel fuel and natural gas. We do not anticipate any difficulty in obtaining sources of energy required for operation of any of our reporting segments in 2019.
As of January 1, 2019, we employed 8,373 people in the United States. Of these employees, 659 are represented by labor unions. Also, as of that date, we employed 408 people in Mexico and 1 in the Bahamas, 332 of whom are represented by labor unions. We do not anticipate any significant issues with any unions in 2019.
We generally ship our products upon receipt of a purchase order or in some cases simply a price quote. Therefore, we do not have a significant order backlog.
| Part I | 14 |
shareholder return performance presentation
Below is a graph comparing the performance of our common stock, with dividends reinvested, to that of the Standard & Poor’s 500 Stock Index (S&P 500) and the Materials and Services Sector of the Wilshire 5000 Index (Wilshire 5000 M&S) from December 31, 2013 to December 31, 2018. The Wilshire 5000 M&S is a market capitalization weighted sector containing public equities of firms in the Materials and Services sector, which includes our company and approximately 1,300 other companies.
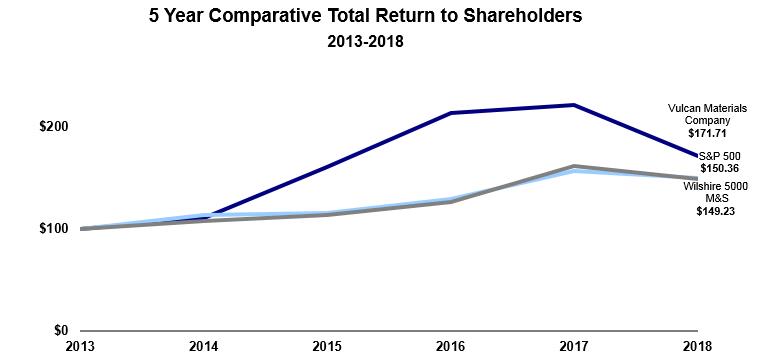
| 2013 | 2014 | 2015 | 2016 | 2017 | 2018 | |||||||||||||||||
| Comparative Total Return 1 | ||||||||||||||||||||||
| Vulcan Materials Company | $ 100.00 | $ 111.00 | $ 161.06 | $ 213.73 | $ 220.99 | $ 171.71 | ||||||||||||||||
| S&P 500 | $ 100.00 | $ 113.70 | $ 115.29 | $ 129.13 | $ 157.28 | $ 150.36 | ||||||||||||||||
| Wilshire 5000 M&S | $ 100.00 | $ 108.30 | $ 113.50 | $ 126.44 | $ 161.33 | $ 149.23 |
| 1 | Assumes an initial investment at December 31, 2013 of $100 in each stock/index, with quarterly reinvestment of dividends. |
| Part I | 15 |
INVESTOR INFORMATION
We make available on our website, www.vulcanmaterials.com, free of charge, copies of our:
| § | Annual Report on Form 10-K |
|---|
| § | Quarterly Reports on Form 10-Q |
|---|
| § | Current Reports on Form 8-K |
|---|
Our website also includes amendments to those reports filed with or furnished to the Securities and Exchange Commission (SEC) pursuant to Section 13(a) or 15(d) of the Securities Exchange Act of 1934 as well as all Forms 3, 4 and 5 filed with the SEC by our executive officers and directors, as soon as the filings are made publicly available by the SEC on its EDGAR database (www.sec.gov).
In addition to accessing copies of our reports online, you may request a copy of our Annual Report on Form 10-K, including financial statements, by writing to Jerry F. Perkins Jr., General Counsel and Secretary, Vulcan Materials Company, 1200 Urban Center Drive, Birmingham, Alabama 35242.
We have a:
| § | Business Conduct Policy applicable to all employees and directors |
|---|
| § | Code of Ethics for the CEO and Senior Financial Officers |
|---|
Copies of the Business Conduct Policy and the Code of Ethics are available on our website under the heading “Corporate Governance.” If we make any amendment to, or waiver of, any provision of the Code of Ethics, we will disclose such information on our website as well as through filings with the SEC.
Our Board of Directors has also adopted:
| § | Corporate Governance Guidelines |
|---|
| § | Charters for our Audit, Compensation, Executive, Finance, Governance and Safety, Health & Environmental Affairs Committees |
|---|
These documents meet all applicable SEC and New York Stock Exchange (NYSE) regulatory requirements.
The Charters of the Audit, Compensation and Governance Committees are available on our website under the heading, “Corporate Governance,” or you may request a copy of any of these documents by writing to Jerry F. Perkins Jr., General Counsel and Secretary, Vulcan Materials Company, 1200 Urban Center Drive, Birmingham, Alabama 35242.
Information included on our website is not incorporated into, or otherwise made a part of, this report.
CERTIFICATIONS AND ASSERTIONS
The certifications of our Chief Executive Officer and Chief Financial Officer made pursuant to Section 302 of the Sarbanes-Oxley Act of 2002 are included as exhibits to this Annual Report on Form 10-K. Additionally, on June 5, 2018 our Chief Executive Officer submitted to the NYSE the annual written affirmation required by the rules of the NYSE certifying that he was not aware of any violations of Vulcan Materials Company of NYSE corporate governance listing standards.
| Part I | 16 |
Previous: Cover and table of contents · Next: Item 1A. RISK FACTORS