 filings.tools
Vivmark Residential (VMRK) 10-K risk factor changes: FY2023 vs FY2022
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A40 rewritten45 added9 removed254 unchanged
All filing items1,037 rewritten1,030 added619 removed2,387 unchanged
Summary
counted, not written
- Item 1A lists 46 risk factor headings: 5 new, 2 reworded and 39 unchanged since FY2022. 0 headings from FY2022 no longer appear.
- Sentence by sentence, 1,030 added, 619 removed, 1,037 rewritten and 2,387 unchanged across 13 items that differ.
- New this year: Item 1C. Cybersecurity.
New Item 1A headings (5)
- We are subject to risks involved in activity through real estate technology and other real estate fund investments.
- We are subject to risks related to our properties that are subject to ground leases.
- We face certain risks related to our Non-Residential operating activities.
- Failure to hedge effectively against interest rate changes may adversely affect our results of operations.Interest rates
- Our approach to artificial intelligence may not be successful and could adversely affect our business.AI
Removed Item 1A headings (0)
Every FY2022 risk factor heading is still here, word for word or reworded.
Reworded Item 1A headings (2)
- Competition
[removed: for acquisitions]may prevent us from acquiring properties on favorable terms. - Corporate
[removed: social]responsibility, specifically related to[removed: ESG,][added: sustainability efforts,] may impose additional costs and expose us to new risks.
A heading is new when no FY2022 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
19 items, with every count and a link to each item that changed
| Item | Added | Removed | Rewritten | Unchanged |
|---|---|---|---|---|
| Item 1A. Risk Factors | 45 | 9 | 40 | 254 |
| Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations | 119 | 106 | 150 | 248 |
| Item 7A. Quantitative and Qualitative Disclosures about Market Risk | 1 | 1 | 8 | 20 |
| Item 1. Business | 27 | 15 | 53 | 94 |
| Item 3. Legal Proceedings | 8 | 0 | 1 | 0 |
| Cover and table of contents | 4 | 4 | 31 | 191 |
| Item 1B. Unresolved Staff Comments | 0 | 0 | 0 | 1 |
| Item 1C. Cybersecuritynew | 27 | 0 | 0 | 0 |
| Item 2. Properties | 25 | 29 | 36 | 67 |
| Item 4. Mine Safety Disclosures | 0 | 0 | 0 | 2 |
| Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities | 20 | 0 | 4 | 6 |
| Item 6. Reserved | 0 | 0 | 0 | 0 |
| Item 8. Financial Statements and Supplementary Data | 0 | 0 | 0 | 1 |
| Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure | 0 | 0 | 0 | 1 |
| Item 9A. Controls and Procedures | 1 | 0 | 7 | 18 |
| Item 9B. Other Information | 1 | 1 | 0 | 0 |
| Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections | 1 | 1 | 6 | 16 |
| Item 15. Exhibit and Financial Statement Schedules | 0 | 0 | 0 | 7 |
| Item 16. Form 10-K Summary | 751 | 453 | 701 | 1,461 |
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
40 rewritten, 45 added, 9 removed, 254 unchanged
While we seek to mitigate these risks through various strategies, including geographic diversification, market research and proactive asset management, among other techniques, these risks cannot be [removed: eliminated.][added: eliminated entirely.]
Changes in social [removed: preferences;] [added: preferences, demographics or migration patterns;] and
If one or more of these markets is unfavorably impacted by specific geopolitical and/or economic conditions, local real estate conditions, increases in social unrest, increases in real estate and other taxes, reduced quality of life, deterioration of local or state government health, rent control or [added: rent] stabilization [removed: laws] [added: laws, other similar regulations,] or localized environmental and climate issues, the impact of such conditions may have a more negative impact on our results of operations than if our properties were more geographically diverse.
Additionally, our properties face competition for residents as a result of [removed: technological innovation.][added: innovations in technology and amenities.]
Therefore, we may not be able to retain residents or attract new residents if we are unable to identify and cost effectively implement new, relevant [removed: technologies] [added: technologies/amenities] and keep up with constantly changing resident demand for the latest [removed: innovations.][added: innovations in these areas.]
In addition, operating expenses associated with each property, such as real estate taxes, insurance, utilities, maintenance costs and employee wages and benefits, may not decline [removed: as quickly] [added: at all] or [added: decline] at the same rate as revenues when circumstances might cause a reduction of those revenues at our properties.
*Competition [removed: for acquisitions] may prevent us from acquiring properties on favorable terms.*
We [added: have experienced and] may [removed: also] [added: continue to] experience an increase in costs due to general disruptions that affect the cost of labor and/or materials, such as supply chain disruptions, trade disputes, tariffs, labor unrest, geopolitical conflicts or other factors that create inflationary pressures.
We may abandon opportunities that we have already begun to explore for a number of reasons, and as a result, we may fail to recover [removed: expenses] [added: costs] already incurred in exploring those opportunities.
Our partners might at any time have business, tax planning or economic goals that are inconsistent with ours; [removed: and]
Our partners may be in a position to take action or withhold consent contrary to our recommendations, instructions or [removed: requests.][added: requests; and]
We [removed: also] have in the past and [removed: could choose] [added: may] in the future [added: choose] to guarantee part of or all of certain joint venture [removed: debt.][added: debt or to act as a lender to the joint venture itself.]
Such impairment charges reflect non-cash losses at the time of recognition; subsequent disposition or sale of such assets could further affect our future losses or gains, as they are based on the difference between the sale price received and adjusted [removed: amortized] [added: depreciated] cost of such assets at the time of sale.
*Corporate [removed: social] responsibility, specifically related to [removed: ESG,] [added: sustainability efforts,] may impose additional costs and expose us to new risks.*
[removed: Environmental sustainability, social and governance] [added: Corporate responsibility] evaluations remain highly important to some investors and other stakeholders.
Certain organizations that provide corporate governance and other corporate risk advisory services to investors have developed scores and ratings to evaluate companies and investment funds based upon [removed: ESG] [added: corporate responsibility] metrics.
Many investors focus on positive [removed: ESG-related] [added: corporate responsibility-related] business practices and scores when choosing to allocate their capital and may consider a company's score as a reputational or other factor in making an investment decision.
Government regulators' and investors' increased focus and activism related to [removed: ESG] [added: corporate responsibility] and similar matters may constrain our business operations or increase expenses or capital expenditures.
In addition, investors may decide to refrain from investing in us as a result of their assessment of our approach to and consideration of [removed: ESG] [added: corporate responsibility] factors.
In addition, the criteria by which companies are rated for [removed: ESG] [added: their] efforts may change, which could cause us to receive lower scores than in previous years.
A low [removed: ESG score] [added: rating] could result in a negative perception of the Company, exclusion of our securities from consideration by certain investors who may elect to invest with our competition instead and/or cause investors to reallocate their capital away from the Company, all of which could have an adverse impact on the price of our securities.
Such initiatives have involved and may involve our employees having new or different responsibilities and [removed: processes.][added: processes with which they may be unfamiliar.]
[removed: Such events may affect our ability to refinance existing debt, require us to] utilize higher cost alternatives and/or impair our ability to adjust to changing economic and business conditions.
A significant downgrade in our credit ratings, while not affecting our ability to draw proceeds under the Company’s revolving credit facility, would cause the corresponding borrowing costs to increase, impact our ability to borrow secured and unsecured debt, and [added: potentially impair our ability to access the commercial paper market or otherwise limit our access to capital.]
These regulations [added: specifically and/or effectively] limit or could continue to limit our ability to raise rents or charge certain fees (either of which could have a retroactive effect), enforce residents’ or tenants’ contractual rent obligations or pursue collections, all of which could have an adverse impact on our operations and property values.
Our properties are subject to various federal, state and local regulatory requirements, such as state and local fire and life safety requirements, building and zoning codes, environmental and other [removed: ESG] [added: related] regulations, and federal, state and local accessibility requirements, including and in addition to those imposed by the Americans with Disabilities Act and the Fair Housing Act.
Third parties may also sue the owner or operator of a site for damages and costs resulting from environmental contamination emanating from [removed: that site.]
As permitted by Maryland law, however, the Board of Trustees of the Company has opted out of these restrictions with respect to any business combination involving [removed: Samuel Zell and] certain of [removed: his] [added: Samuel Zell's] affiliates and persons acting in concert with them.
Pandemics, epidemics or other health [removed: crises, including the novel coronavirus (“COVID-19”),] [added: crises] have and could in the future disrupt our business.
Substantial inflationary pressures can adversely affect us by [added: disproportionately] increasing the costs of land, materials, labor and other costs needed to operate our business.
In addition, interest rate increases enacted to combat inflation have caused market disruption and could continue to prevent us from acquiring or disposing of assets on favorable [removed: terms.][added: terms or at all.]
[removed: A cyber incident is an intentional attack or an unintentional event that] [added: These events] can include gaining unauthorized access to systems to disrupt [removed: payment collections and] operations, corrupt data or steal confidential information, including information regarding our residents, prospective residents, employees and employees’ dependents.
We face risks associated with security breaches, whether through cyber attacks or cyber intrusions over the Internet, malware, computer viruses, attachments to emails, phishing attempts, [added: social engineering,] ransomware or other scams, persons inside our organization or persons/vendors with access to our systems and other significant disruptions of our information technology networks and related systems, including property infrastructure.
[removed: The] [added: Despite the fact that we monitor and perform a comprehensive review of businesses that we contract with that represent a cybersecurity risk to the organization, the] systems of these third-party service providers may contain defects in design or other problems that could unexpectedly compromise personally identifiable information.
We are also subject to laws, rules, and regulations in the United States, such as the California [removed: Consumer] Privacy [added: Rights] Act [removed: (“CCPA”),] [added: (“CPRA”),] relating to the collection, use, and security of resident, customer, employee and other data.
Evolving compliance and operational requirements under the [removed: CCPA] [added: CPRA] and the privacy laws of other jurisdictions in which we operate may impose significant costs that are likely to increase over time.
Our failure to comply with laws, [removed: rules,] [added: rules] and regulations related to privacy and data protection could harm our business or reputation or subject us to fines and penalties.
We are involved and may continue to be involved in legal proceedings, claims, class actions, inquiries and [added: governmental] investigations in the ordinary course of business.
While the Company has previously purchased incremental insurance coverage in the event of multiple non-catastrophic occurrences within the same policy year, these substantial deductible and self-insured retention amounts do expose the Company to greater potential for uninsured losses and this additional [removed: multiple occurrences] coverage may not be available at all or on commercially reasonable terms in the future.
While our existing preferred shares/preference units do not have all of these provisions, any future series of preferred shares/preference units may have certain voting provisions that could delay or prevent a change in control or other transactions that might otherwise be in the interest of [added: our security holders.]
Furthermore, we have in the past and may in the future decide to invest in expansion markets outside of our existing established markets by acquiring and/or developing properties in accordance with the Company's long-term investment strategy.
Our historical experience in our established markets does not ensure that we will be able to operate successfully in new markets, should we choose to enter them.
Entering into new markets may expose us to a variety of risks, including an inability to accurately evaluate local market conditions and local economies, to identify appropriate acquisition and/or development opportunities, to hire and retain key personnel and a lack of familiarity with local governmental regulations.
The possibility that our partner is either unable to or unwilling to complete their contractual development activities.
*We are subject to risks involved in activity through real estate technology and other real estate fund investments.*
We have entered into, and may continue in the future to enter into, real estate technology and other real estate fund investments.
Noncontrolling interests and passive investments are inherently risky because we have limited ability to influence business decisions.
The managers of such investments have autonomy over the day-to-day operations of the business and may make business, financial or management decisions with which we do not agree or take risks or otherwise act in a manner that does not serve our interests.
In addition, the market for the technologies or products these companies are developing are typically in the early stages and may not materialize to the expected scale, causing these companies to abandon, modify or alter their product, service or overall strategy.
Further, there is no assurance that these companies can obtain additional capital or resources or generate sufficient cash flow to sustain operations and successfully execute their strategy.
The performance of these investments may also rely on the services of a limited number of key individuals, the loss of whom could significantly adversely affect such investments’ performance.
As a result, we may recognize an impairment of our investment or be unable to sell or otherwise monetize any of the investments we have acquired or may acquire in the future.
*We are subject to risks related to our properties that are subject to ground leases.*
We have entered into, and may continue in the future to enter into, long-term ground leases with respect to assets that may restrict our ability to finance, sell or otherwise transfer our interests in these properties, limit our use and expose us to loss of the properties if such agreements are breached by us or terminated.
These restrictions may limit our ability to timely sell or exchange the properties, impair the properties’ value or negatively impact our ability to operate the properties.
In addition, as we get closer to the lease termination dates, the values of the properties could decrease if we are unable to agree upon an extension of the lease with the lessor.
Certain of these ground leases have payments subject to annual escalations and/or periodic fair market value adjustments which could adversely affect our financial condition or results of operations.
*We face certain risks related to our Non-Residential operating activities.*
The Non-Residential space (includes retail and public parking garage operations) at our properties primarily serves as an additional amenity for our residents and neighbors.
The longer-term nature of our Non-Residential leases (generally five to ten years with market based renewal options) and the characteristics of many of our Non-Residential tenants (generally small, local businesses) may subject us to certain risks.
We may not be able to lease new space for rents that are consistent with our projections or for market rates.
Also, when leases for our existing Non-Residential space expire, the space may not be relet or the terms of reletting, including the cost of allowances and concessions to tenants, may be less favorable than the current lease terms.
The presence of competitive alternatives and other market conditions (including online shopping) may affect our ability to lease our Non-Residential space and impact the level of rents we can obtain.
If our Non-Residential tenants experience financial distress or bankruptcy, they may fail to comply with their contractual obligations, seek concessions, such as rent abatements and deferrals, in order to continue operations or cease their operations, any or all of which could lead us to record a non-cash write-off of a tenant's straight-line rent receivable (like we did in 2023 due to the Rite Aid bankruptcy) and could adversely impact our results of operations and financial condition.
Such events may affect our ability to refinance existing debt, require us to
Continuing high interest rates can also negatively impact the value of our Common Shares, not just through higher interest expense on our debt, but also as investors and markets discount our earnings more and/or assume slower growth in earnings.
*Failure to hedge effectively against interest rate changes may adversely affect our results of operations.*
From time to time when we anticipate issuing debt securities, we may seek to limit our exposure to fluctuations in interest rates during the period prior to the pricing of the securities by entering into interest rate hedging contracts.
Also, from time to time we may rely on interest rate hedging contracts to limit our exposure under variable rate debt to unfavorable changes in market interest rates.
The settlement of interest rate hedging contracts may involve material charges.
In addition, our use of interest rate hedging arrangements may expose us to additional risks, including a risk that a counterparty to a hedging arrangement may default on the contract.
There can be no assurance that our hedging activities will be effective and have the desired beneficial impact on our results of operations or financial condition.
that site.
A cybersecurity incident is an unauthorized occurrence, or a series of related unauthorized occurrences, on or conducted through the Company's information systems that jeopardizes the confidentiality, integrity, or availability of our information systems or any information residing therein.
We use these systems to manage our resident and vendor relationships, internal communications, accounting and record-keeping systems and many other key aspects of our business.
Our operations rely on the secure processing, storage and transmission of confidential and other information in our computer systems and networks, which also depend on the strength of our procedures and the effectiveness of our internal controls as well as those of vendors with whom we do business.
*Our approach to artificial intelligence may not be successful and could adversely affect our business.*
We have incorporated and may continue to incorporate the use of generative artificial intelligence ("AI") within our business, and these solutions and features may become more important to our operations or to our future growth over time.
Our research and development of AI remains ongoing.
There can be no assurance that we will realize the desired or anticipated benefits, or any benefits, and we may fail to properly implement such technology.
We may also underestimate the costs necessary to operate an acquired or developed property to the standards established for its intended market position.
potentially impair our ability to access the commercial paper market or otherwise limit our access to capital.
We address potential breaches or disclosure of this confidential personally identifiable information by implementing a variety of security measures intended to protect the confidentiality and security of this information including (among others): (a) engaging reputable, recognized firms to help us design and maintain our information technology and data security systems; (b) conducting periodic testing and verification of information and data security systems, including performing ethical hacks of our systems to discover where any vulnerabilities may exist; (c) providing periodic employee awareness training around phishing and other scams, malware and other cyber risks; (d) implementing a corrective cybersecurity awareness policy that impacts an employee’s performance and compensation to articulate the potential implications of failed phishing tests; and (e) systematically deleting personally identifiable information that no longer is required.
The Company also has a cyber liability insurance policy to provide some coverage for certain risks arising out of data and network breaches and data privacy regulations which provides a policy aggregate limit and a per occurrence deductible.
Cyber liability insurance generally covers, among other things, costs associated with the wrongful release, through inadvertent breach or network attack, of personally identifiable information.
However, there can be no assurance that these measures will prevent a cyber incident or that our cyber liability insurance coverage will be sufficient to cover our losses in the event of a cyber incident.
We believe the policy specifications and insured limits of these policies are adequate and appropriate; however, there are certain types of extraordinary losses which may not be adequately covered under our insurance program.
In addition, climate change could cause a significant increase in insurance premiums and deductibles or a decrease in the availability of coverage, either of which could expose the Company to even greater uninsured losses.
our security holders.
An excerpt. Shown here: all 40 rewritten, 40 of 45 added and all 9 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2023 filing and the FY2022 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
150 rewritten, 119 added, 106 removed, 248 unchanged
[removed: 2021] [added: 2022] and [removed: 2022] [added: 2023] Transactions
In conjunction with our business objectives and operating and investing strategies, the following table provides a rollforward of the transactions that occurred during the years ended December 31, [removed: 2021] [added: 2022] and [removed: 2022:][added: 2023:]
| Completed Developments – Consolidated | | | [removed: 3] [added: 1] | | | | [removed: 824] [added: 312] | | | | | | | | | |
| Unconsolidated Land Parcels [removed: (2)] [added: (1)] | | | — | | | | — | | | $ | 56,886 | | | | | |
[removed: Worth markets,] [added: The Company acquired two properties in the Atlanta market during the year ended December 31, 2023] that [removed: were] [added: are] in lease-up and are expected to stabilize in their second year of ownership at the [removed: combined] [added: weighted average] Acquisition Cap Rate listed above.
The consolidated properties acquired in [removed: 2021] [added: 2023] are located in the Atlanta [removed: (4), Austin (3), Boston, Dallas/Ft.][added: (3) and Denver markets; and]
The consolidated property acquired in 2022 is located in the San Diego market; [removed: and]
In 2022, the Company acquired its joint venture partner’s 25% interest in a 432-unit apartment property located in the Washington, D.C. market for $32.2 million, and the property is now wholly [removed: owned.][added: owned;]
The consolidated properties disposed of in [removed: 2021] [added: 2022] were located in the [removed: Los Angeles (6),] New [removed: York, San Francisco (5), Seattle] [added: York (2)] and Washington, D.C. markets and the sales generated an Unlevered IRR of [removed: 10.4%;] [added: 5.3%;] and
The Company [removed: completed construction on three] [added: stabilized two] consolidated apartment properties during [removed: 2021,] [added: 2022,] located in the [removed: San Francisco,] Washington, D.C. and Boston markets, consisting of [removed: 824] [added: 624] apartment units totaling approximately [removed: $602.8] [added: $482.1] million of development costs;
The Company [removed: commenced] [added: completed] construction on one consolidated [removed: and three unconsolidated] apartment [removed: properties] [added: property] during [removed: 2021,] [added: 2023,] located in the [removed: Denver (2), New York and] Washington, D.C. [removed: markets,] [added: market,] consisting of [removed: 1,241] [added: 312] apartment units totaling approximately [removed: $452.7] [added: $108.0] million of [removed: expected] development costs; [added: and]
The Company stabilized [removed: two] [added: one] consolidated apartment [removed: properties] [added: property] during [removed: 2022,] [added: 2023,] located in the [removed: Washington, D.C. and Boston markets,] [added: San Francisco market,] consisting of [removed: 624] [added: 200] apartment units totaling approximately [removed: $482.1] [added: $116.4] million of development costs; [removed: and]
The Company spent approximately $203.6 million during 2022, primarily for consolidated and unconsolidated development [removed: projects.][added: projects;]
The Company entered into [removed: six] [added: two] separate unconsolidated joint ventures during [removed: 2021] [added: 2023] for the purpose of developing vacant land parcels in [removed: Texas (3), Colorado (2)] [added: the Boston] and [removed: New York.][added: Seattle markets.]
The Company’s total investment in these [removed: six] [added: two] joint ventures was approximately [removed: $72.2 million and $150.4] [added: $4.9] million as of December 31, [removed: 2021 and 2022, respectively.][added: 2023.]
[removed: Three] [added: One] of the projects [removed: are] [added: is] related to the Company’s joint venture development program with [removed: Toll, two of] [added: Toll Brothers, Inc. ("Toll"),] which commenced construction during the [removed: second and third quarters] [added: first quarter] of [removed: 2022;] [added: 2022 prior to our entrance into the joint venture;] and
Comparison of the year ended December 31, [removed: 2022] [added: 2023] to the year ended December 31, [removed: 2021][added: 2022]
The following table presents a reconciliation of diluted earnings per share/unit for the year ended December 31, [removed: 2022] [added: 2023] as compared to the same period in [removed: 2021:][added: 2022:]
| Diluted earnings per share/unit for full year [removed: 2021] [added: 2023] | | $ | [removed: 3.54] [added: 2.20] | |
| Property NOI | | | [removed: 0.60] [added: 0.29] | |
| Interest expense | | | [removed: (0.02] [added: 0.02] | [removed: )] |
| Net gain/loss on property sales | | | [removed: (1.95] [added: (0.06] | ) |
| Non-operating asset gains/losses | | | [removed: (0.07] [added: 0.04] | [removed: )] |
| Impairment – non-operating real estate assets | | | [removed: 0.04] [added: —] | | [added: | | — | | | | 16,769 | |]
| Depreciation expense | | | [removed: (0.11] [added: (0.01] | ) |
| | | Year Ended December 31, | | | | | | | | [removed: 2022] [added: 2023] vs. [removed: 2021] [added: 2022] | | | | | | |
| | | [removed: 2022] [added: 2023] | | | | [removed: 2021] [added: 2022] | | | | $ Change | | | | % Change | | |
| General and administrative | | | [removed: 58,710] [added: 60,716] | | | | [removed: 56,506] [added: 58,710] | | | | [removed: 2,204] [added: 2,006] | | | | [removed: 3.9] [added: 3.4] | % |
| Depreciation | | | [removed: 882,168 | | | | 838,272] [added: 888,709] | | | | [removed: 43,896] [added: 882,168] | | | | [removed: 5.2] [added: 838,272] | [removed: %] |
| Net (gain) loss on sales of real estate properties | | | [removed: (304,325] [added: (282,539] | ) | | | [removed: (1,072,183] [added: (304,325] | ) | | | [removed: 767,858 | | | | (71.6] [added: (1,072,183] | [removed: )%] [added: )] |
Non-same store/other NOI results consist primarily of properties acquired in calendar years [removed: 2021] [added: 2022] and [removed: 2022,] [added: 2023,] operations from the Company’s development [removed: properties] [added: properties, other corporate operations] and operations prior to disposition from [removed: 2021 and] 2022 [added: and 2023] sold properties.
The increase in consolidated total NOI is [removed: primarily] a result of the Company’s higher NOI from same store properties, largely due to improvement in same store revenues as noted above.
These expenses increased approximately [removed: $12.1] [added: $9.5] million or [removed: 12.4%] [added: 8.6%] during the year ended December 31, [removed: 2022] [added: 2023] as compared to [removed: 2021.][added: 2022.]
This increase is primarily attributable to increases in payroll-related costs, [removed: training/conference costs, temporary help/contractors] [added: workforce/contractors] costs and [added: information technology expenses, partially offset by decreases in training/marketing costs and] third-party management fees.
General and administrative expenses, which include corporate operating expenses, increased approximately [removed: $2.2] [added: $2.0] million or [removed: 3.9%] [added: 3.4%] during the year ended December 31, [removed: 2022] [added: 2023] as compared to [removed: 2021,] [added: 2022,] primarily due to increases in payroll-related [removed: costs,] [added: costs and public company expenses, partially offset by decreases in] legal and professional fees and [removed: training/conference] [added: training/marketing] costs.
Depreciation expense, which includes depreciation on non-real estate assets, increased approximately [removed: $43.9] [added: $6.5] million or [removed: 5.2%] [added: 0.7%] during the year ended December 31, [removed: 2022] [added: 2023] as compared to [removed: 2021,] [added: 2022,] primarily as a result of additional depreciation expense on properties acquired in [removed: 2021 and 2022] [added: 2023] and [removed: development properties placed in service during 2021,] [added: 2022,] partially offset by lower depreciation from properties sold in [removed: 2021] [added: 2022] and [removed: 2022.][added: 2023.]
Net gain on sales of real estate properties decreased approximately [removed: $767.9] [added: $21.8] million or [removed: 71.6%] [added: 7.2%] during the year ended December 31, [removed: 2022] [added: 2023] as compared to [removed: 2021,] [added: 2022,] primarily as a result of [removed: a lower sales volume with] the sale of [removed: three] [added: eleven] consolidated apartment properties [added: for a lower gain] in [removed: 2022] [added: 2023] as compared to the sale of [removed: fourteen] [added: three] consolidated apartment properties in the same period in [removed: 2021.][added: 2022.]
Interest and other income [removed: decreased] [added: increased] approximately [removed: $23.5] [added: $20.2] million [removed: or 91.5%] during the year ended December 31, [removed: 2022] [added: 2023] as compared to [removed: 2021.][added: 2022.]
Other expenses [removed: decreased] [added: increased] approximately [removed: $5.6] [added: $15.8] million [removed: or 29.1%] during the year ended December 31, [removed: 2022] [added: 2023] as compared to [removed: 2021,] [added: 2022,] primarily due to [removed: a decline] [added: increases] in [removed: construction defect and] litigation reserves and [removed: pursuit costs recorded between 2022 and 2021, partially offset by increases in advocacy contributions, demolition/abatement costs and] data transformation project costs.
Interest expense, including amortization of deferred financing costs, [removed: increased] [added: decreased] approximately [removed: $10.4] [added: $13.2] million or [removed: 3.7%] [added: 4.5%] during the year ended December 31, [removed: 2022] [added: 2023] as compared to [removed: 2021.][added: 2022.]
| Consolidated Rental Properties | | | 2 | | | | 577 | | | $ | 189,734 | | (3) | | 5.1 | % |
| Consolidated Rental Properties – Not Stabilized (2) | | | 2 | | | | 606 | | | $ | 176,600 | | | | 5.9 | % |
| Consolidated Rental Properties | | | (11 | ) | | | (912 | ) | | $ | (379,893 | ) | | | (5.5 | )% |
| Configuration Changes | | | — | | | | 11 | | | | | | | | | |
| 12/31/2023 | | | 302 | | | | 80,191 | | | | | | | | | |
(3)
Purchase price is net of a mark-to-market discount of approximately $11.2 million on a mortgage assumed in connection with the purchase of a property.
In 2023, the Company acquired its joint venture partner's 10% interest in a 200-unit apartment property located in the San Francisco market for $4.6 million, of which the Company paid $3.7 million in cash and ERPOP issued $0.9 million of 3.00% Series Q Preference Units.
The property is now wholly owned.
The Company also repaid $64.7 million of mortgage debt at par prior to maturity in conjunction with the buyout.
The consolidated properties disposed of in 2023 were located in the Los Angeles (8), Seattle (2) and San Francisco markets
and the sales generated an Unlevered IRR of 11.4%.
The Company spent approximately $118.2 million during 2023, primarily for consolidated and unconsolidated development projects.
| Other | | | (0.10 | ) |
| Operating income | | $ | 1,160,585 | | | $ | 1,116,046 | | | $ | 44,539 | | | | 4.0 | % |
| Property management | | | 119,804 | | | | 110,304 | | | | 9,500 | | | | 8.6 | % |
| Depreciation | | | 888,709 | | | | 882,168 | | | | 6,541 | | | | 0.7 | % |
| Total NOI | | $ | 1,947,275 | | | $ | 1,862,903 | | | $ | 84,372 | | | | 4.5 | % |
| Same store | | $ | 2,754,711 | | | $ | 2,609,766 | | | $ | 144,945 | | | | 5.6 | % |
| Non-same store/other | | | 119,253 | | | | 125,414 | | | | (6,161 | ) | | | (4.9 | )% |
| Total rental income | | | 2,873,964 | | | | 2,735,180 | | | | 138,784 | | | | 5.1 | % |
| Same store | | | 873,448 | | | | 837,602 | | | | 35,846 | | | | 4.3 | % |
| Non-same store/other | | | 53,241 | | | | 34,675 | | | | 18,566 | | | | 53.5 | % |
| Total operating expenses | | | 926,689 | | | | 872,277 | | | | 54,412 | | | | 6.2 | % |
| Same store | | | 1,881,263 | | | | 1,772,164 | | | | 109,099 | | | | 6.2 | % |
| Non-same store/other | | | 66,012 | | | | 90,739 | | | | (24,727 | ) | | | (27.3 | )% |
| Total NOI | | $ | 1,947,275 | | | $ | 1,862,903 | | | $ | 84,372 | | | | 4.5 | % |
The increase in same store rental income is primarily driven by strong demand and limited new supply, partially offset by a non-cash write-off of approximately $1.5 million in straight-line receivables due to the bankruptcy of Rite Aid.
Repairs and maintenance – A $9.9 million increase primarily driven by greater outsourcing due to higher internal staffing utilization to address issues from California rain storms that occurred earlier in 2023;
Real estate taxes – A $5.8 million increase due to modest escalation in rates and assessed values; and
On-site payroll – An $8.0 million increase due primarily to fewer staffing vacancies as compared to 2022 and elevated employee benefit costs, partially offset by the impact of innovation initiatives.
The decrease in non-same store/other NOI is due primarily to:
A negative impact of lost NOI from 2022 and 2023 dispositions of $20.2 million;
A negative impact of $2.8 million in lower NOI from two properties that have been removed from same store while undergoing major renovations;
A negative impact of $18.1 million from a real estate tax transaction adjustment in 2022 that did not reoccur in 2023; and
A positive impact of higher NOI from non-stabilized properties acquired during 2021, 2022 and 2023 of $11.2 million and higher NOI from development and other properties in lease-up of $10.9 million.
The increase is primarily due to an increase in unrealized gains of $13.5 million and realized gains of $2.7 million on various investment securities as well as short-term investment income on cash and restricted deposit accounts due to a higher rate environment and higher overall invested balances, partially offset by decreases in insurance/litigation settlement proceeds received during 2022 that did not occur in 2023.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 2023 | | | | | | | | | | | | | | | | | | | | | 2022 | | | | | | | | | |
COVID-19 Impact
The Company continues to monitor and respond to the ongoing effects of the COVID-19 pandemic.
For additional details, see Item 1A, *Risk Factors*.
| 12/31/2020 | | | 304 | | | | 77,889 | | | | | | | | | |
| Consolidated Rental Properties | | | 13 | | | | 3,533 | | | $ | 1,249,679 | | | | 3.7 | % |
| Consolidated Rental Properties – Not Stabilized (1) | | | 4 | | | | 1,214 | | | $ | 459,700 | | | | 4.0 | % |
| Consolidated Rental Properties | | | (14 | ) | | | (3,053 | ) | | $ | (1,716,775 | ) | | | (3.7 | )% |
The Company acquired four properties during the year ended December 31, 2021, one each in the Denver, Atlanta, Seattle and Dallas/Ft.
(2)
Worth (4), Denver (3), Seattle and Washington, D.C. markets.
The Atlanta, Austin and Dallas/Ft.
Worth acquisitions marked the Company’s re-entry into these markets;
Approximately $1.4 billion, or 82.0% of all acquisition activity in 2021, was in expansion markets;
The Company funded the 2021 acquisitions by selling older assets located within established markets that no longer met our long-term investment criteria;
The consolidated properties disposed of in 2022 were located in the New York (2) and Washington, D.C. markets and the sales generated an Unlevered IRR of 5.3%.
One of the projects is related to the Company’s joint venture development program with Toll, which commenced construction during the first quarter of 2022 prior to our entrance into the joint venture.
| Other | | | 0.05 | |
| Operating income | | $ | 1,116,046 | | | $ | 1,675,841 | | | $ | (559,795 | ) | | | (33.4 | )% |
| Property management | | | 110,304 | | | | 98,155 | | | | 12,149 | | | | 12.4 | % |
| Impairment | | | — | | | | 16,769 | | | | (16,769 | ) | | | (100.0 | )% |
| Total NOI | | $ | 1,862,903 | | | $ | 1,613,360 | | | $ | 249,543 | | | | 15.5 | % |
| Same store | | $ | 2,533,577 | | | $ | 2,291,604 | | | $ | 241,973 | | | | 10.6 | % |
| Non-same store/other | | | 201,603 | | | | 172,393 | | | | 29,210 | | | | 16.9 | % |
| Total rental income | | | 2,735,180 | | | | 2,463,997 | | | | 271,183 | | | | 11.0 | % |
| Same store | | | 802,291 | | | | 774,504 | | | | 27,787 | | | | 3.6 | % |
| Non-same store/other | | | 69,986 | | | | 76,133 | | | | (6,147 | ) | | | (8.1 | )% |
| Total operating expenses | | | 872,277 | | | | 850,637 | | | | 21,640 | | | | 2.5 | % |
| Same store | | | 1,731,286 | | | | 1,517,100 | | | | 214,186 | | | | 14.1 | % |
| Non-same store/other | | | 131,617 | | | | 96,260 | | | | 35,357 | | | | 36.7 | % |
The increase in same store rental income is primarily driven by strong Physical Occupancy and continued growth in pricing.
Utilities – A $13.9 million increase from gas and electric, primarily driven by higher commodity prices; and
Repairs and maintenance – A $9.8 million increase primarily driven by volume and timing of maintenance and repairs along with increases in minimum wage on contracted services.
The increase in non-same store/other NOI is due primarily to a positive impact of higher NOI from properties acquired during 2021 and 2022 of $54.5 million and higher NOI from development properties in lease-up of $20.6 million, partially offset by a negative impact of lost NOI from 2021 and 2022 dispositions of $52.2 million and a negative impact of $1.2 million in lower NOI from one former master-leased property and two properties that have been removed from same store while undergoing major renovations.
Operating expense growth remains modest due to a combination of continued success in managing controllable expenses, favorable growth in real estate tax expense (increased by only $3.2 million) and declines in payroll expense (decreased by $3.1 million) primarily due to the Company's various innovation and centralization initiatives, leading to 14.1% same store NOI growth for the year ended December 31, 2022 as compared to the prior year period.
Impairment decreased approximately $16.8 million during the year ended December 31, 2022 as compared to 2021, due to an impairment charge in 2021 on one land parcel held for development compared to no impairment charges taken during 2022.
The decrease is primarily due to a gain of $23.6 million on the sale of various investment securities that occurred during 2021 but not during 2022.
Net (income) loss attributable to Noncontrolling Interests in partially owned properties decreased approximately $14.2 million or 79.0% during the year ended December 31, 2022 as compared to 2021, primarily as a result of noncontrolling interest allocations related to the sale of one partially owned apartment property in 2021 as compared to no sales in 2022.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Revenues | $ | 2,441,522 | | | 10.7 | % | $ | 92,055 | | | 5.8 | % | $ | 2,533,577 | | | 10.6 | % | | Revenues | $ | 2,204,625 | | $ | 86,979 | | $ | 2,291,604 | |
An excerpt. Shown here: 40 of 150 rewritten, 40 of 119 added and 40 of 106 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2023 filing and the FY2022 filing.
Item 7A. Quantitative and Qualitative Disclosures about Market Risk
8 rewritten, 1 added, 1 removed, 20 unchanged
Our operating results are, therefore, affected by changes in short-term interest rates, primarily [removed: SOFR, London Interbank Offered Rate ("LIBOR")] [added: SOFR] and Securities Industry and Financial Markets Association (“SIFMA”) indices, which directly impact borrowings under our revolving credit facility and/or interest on secured and unsecured borrowings contractually tied to such rates.
The Alternative Reference Rates Committee (the “ARRC”) [removed: has] identified SOFR as the preferred alternative rate for USD [removed: LIBOR.][added: LIBOR, which was discontinued in June 2023.]
[added: During the year ended December 31, 2022,] SOFR [removed: is now] [added: became] the primary basis for determining interest payments on borrowings on the Company’s $2.5 billion revolving credit facility.
[removed: We are closely monitoring the evolution of practices in the credit markets and we do not expect such] [added: The] transition [removed: to] [added: did not] have a material impact on the [removed: Company’s] [added: Company's] financial position or cash flows.
The Company had total variable rate debt of [removed: $0.5] [added: $0.6] billion, representing [removed: 6.4%] [added: 8.7%] of total debt, and [removed: $0.6] [added: $0.5] billion, representing [removed: 7.3%] [added: 6.4%] of total debt, as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] respectively.
If interest rates had been 100 basis points higher in [removed: 2022] [added: 2023] and [removed: 2021] [added: 2022] and average balances coincided with year end balances, our annual interest expense would have been [removed: $4.7] [added: $6.4] million and [removed: $6.1] [added: $4.7] million higher, respectively.
As of December 31, [removed: 2021,] [added: 2023,] the Company had total outstanding fixed rate debt of [removed: $7.7] [added: $6.7] billion, or [removed: 92.7%] [added: 91.3%] of total debt, with an estimated fair market value of [removed: $8.4] [added: $6.2] billion.
If interest rates had been 100 basis points lower as of December 31, [removed: 2021,] [added: 2023,] the estimated fair market value would have increased by approximately [removed: $637.2] [added: $411.2] million.
As of December 31, 2023, the Company did not have any outstanding derivative instruments used for hedging purposes.
As part of the transition process that is now under way, LIBOR is no longer published for certain tenors and key USD settings are expected to be discontinued by June 2023.
Item 1. Business
53 rewritten, 27 added, 15 removed, 94 unchanged
EQR is the general partner of, and as of December 31, [removed: 2022] [added: 2023] owned an approximate [removed: 96.8%] [added: 97.0%] ownership interest in, ERPOP.
Certain capitalized terms used herein are defined in the Notes to Consolidated Financial [removed: Statements.][added: Statements or the Definitions section of Item 7, *Management's Discussion and Analysis of Financial Condition and Results of Operations*.]
We believe our markets are knowledge centers of the U.S. economy that draw [added: employers and their] talented [added: affluent] workers [removed: and employers] that drive economic growth in the United States.
We believe the locations of our properties in these markets are attractive to these [added: affluent] knowledge workers (who often choose to rent for lifestyle reasons) that we hope to convert into satisfied long-term residents.
We believe we have created an [removed: industry‐leading] [added: industry-leading] operating platform and balance sheet to run our properties.
We pair that with disciplined balance sheet management that enhances returns and value creation [removed: while maintaining flexibility to take advantage of future opportunities.]
Despite [removed: geopolitical and] [added: overall] economic [removed: uncertainties,] [added: concerns,] demand to live in our apartment communities remains [removed: robust] [added: healthy] and we believe that the long-term prospects for our business remain strong.
Our business benefits from [removed: a shortage] [added: elevated single family home ownership costs, positive household formation trends and the overall deficit] in housing across the country, especially in the areas in which we are investing.
The Company’s long-term strategy is to invest in apartment [removed: communities] [added: properties] located in strategically targeted markets with the goal of maximizing our risk-adjusted total returns [removed: and] [added: by] balancing current cash flow generation with long-term capital appreciation.
Our multi-pronged investment strategy featuring acquisitions, new stand-alone and expansion developments, densifying developments and accretive renovations of existing properties is focused on optimizing [added: and balancing] our portfolio in terms of [removed: quality] [added: location, including between our established] and [removed: location.][added: expansion markets and between urban and suburban submarkets within those markets.]
They include a number of submarkets that are attractive for long-term multifamily [removed: ownership.][added: ownership and are positioned to capture future demand.]
These jobs result in the significant presence and growth in [added: affluent] renters that work in the highest earning sectors of the economy, are not rent burdened and are attracted to our type of properties.
Many of these [added: affluent] workers are employed in the fields of Science, Technology, Engineering and Mathematics, or STEM jobs, as well as financial services, medical, legal and other higher-earning professions.
Significant apartment demand that meets new apartment supply. We remain focused on owning and operating properties in markets [removed: or] [added: and] submarkets where the supply of apartments is [removed: balanced] [added: met] with strong [removed: demand that supports superior long-term returns.][added: demand.]
Furthermore, we believe that demand for rental housing will continue to be driven primarily through household formations from the younger segments of our population, particularly Generation Z, while retaining Millennials for [removed: longer] [added: longer,] and to a lesser [removed: extent] [added: extent,] capturing the aging Baby Boomer generation.
Millennials are [removed: comprised of those] individuals born between 1981 and 1996, [removed: total] [added: totaling] approximately 72 million [removed: people] [added: people,] and continue to be a significant portion of the renter population.
They also tend to remain renters longer due to the [added: high] cost of single family home [removed: ownership and] [added: ownership,] societal trends favoring delays in marriage and having [removed: children.][added: children and caution around making large financial commitments during uncertain economic times.]
Generation Z is [removed: comprised of the] approximately [removed: 67] [added: 70] million people born between 1997 and 2012.
Baby Boomers, a demographic of more than [removed: 71] [added: 68] million people born between 1946 and 1964, also [added: may] trend toward apartment [removed: rentals.][added: rentals as they downsize and enter retirement in vibrant cities.]
We have done so by adding expansion markets to our portfolio when [added: certain submarkets in] those markets meet many of the same characteristics listed above.
Worth and Austin includes investments in both urban and suburban properties [added: in select submarkets] and is generally being funded by reducing exposure [added: to older or lower returning assets] in [removed: selective] [added: selected] established markets.
Development activity is focused on our in-house [removed: pipeline,] [added: pipeline and redevelopment of some existing operating properties and] our strategic [removed: partnership with Toll Brothers, Inc. (“Toll”)] [added: partnerships] and [removed: joint ventures] [added: joint-ventures] with [removed: other] third-party developers in both established and expansion markets.
In addition, other forms of rental properties and [removed: single-family] [added: single family] housing provide housing alternatives to potential residents of multifamily properties.
We attempt to balance occupancy and rental rates to maximize our revenue while exercising tight cost control to generate the highest possible [removed: return] [added: cash flow generation] to our shareholders.
[removed: This] [added: Our] focus [added: on operating efficiency and delivery of an exceptional resident living experience] has driven strong [removed: occupancy] [added: Physical Occupancy] and a high [removed: percentage] [added: Percentage] of [removed: residents renewing] [added: Residents Renewing] while achieving strong renewal rate growth.
We use a standardized purchasing system to control our operating expenses and a business intelligence platform [added: and other data analytics] that [removed: allows all] [added: allow] our team members to quickly identify and address issues and opportunities.
We consider building locations based on walkability, accessibility, neighborhoods and [removed: parks.][added: communities.]
[removed: We also design our communities to] [added: Our properties] support amenities such as fitness centers and we select locations near shops, restaurants, outdoor amenities such as bike/running paths and health clubs, enabling a low carbon footprint lifestyle for our residents to live, work and play.
We methodically focus on energy, water, waste and emissions to advance the program’s policies, targets and resilience [removed: outcomes.][added: outcomes as well as our shareholders' long-term financial interests.]
Together, we believe our program drives long-term asset value, responsibly manages risks and engages our communities, residents, employees and shareholders as part of our broader [removed: ESG] [added: sustainability] strategy and commitment to good corporate citizenship and maximizing investment performance.
[removed: To further strengthen our commitments to ESG initiatives, we] [added: We also] issued two sustainable fixed-income instruments (each a “green bond”) designed to support projects that contribute to environmental [removed: sustainability.][added: sustainability, becoming the first multifamily REIT to ever issue a green bond.]
[removed: In 2021, the] [added: The] Company [removed: began funding its] [added: also has a] $10.0 million investment in a [removed: new] fund focused on early stage sustainability and climate change mitigation technology relevant to the built environment.
As detailed below, we have a commitment to our employees’ engagement, diversity and inclusion and wellness that [removed: is] [added: serves as] the foundation of our corporate purpose.
For additional information regarding our [removed: ESG] [added: corporate responsibility] efforts, see our [removed: 2022] [added: 2023] Environmental, Social and Governance Report at our website, [removed: www.equityapartments.com.][added: www.equityapartments.com, which includes third-party limited assurance covering some of the environmental metrics included in the report.]
[removed: This] [added: The] report, which includes Sustainability Accounting Standards Board disclosures and incorporates recommendations from the Task Force on [removed: Climate-related] [added: Climate-Related] Financial Disclosures, was [added: reviewed and approved by the Corporate Governance Committee of our Board of Trustees, which monitors the Company’s ongoing corporate responsibility efforts.]
Furthermore, our annual proxy statements contain additional information on our [removed: ESG] [added: corporate responsibility] efforts, including detailed information regarding our corporate governance practices.
At Equity Residential, our team of approximately 2,400 employees is the driving force [removed: behind] [added: of] our success.
We believe that our richly diverse work environment captures top talent, cultivates the best ideas and creates the widest possible platform for this success in line with our corporate purpose of “*Creating communities where people thrive”.* Our core principles, affectionately named “*Ten Ways to Be a [removed: Winner”*,] [added: Winner,”*] guide our behavior as individuals and collectively as a team, helping us in our goal to deliver market-leading performance.
We have assembled [removed: a cross-functional employee-led] [added: the] Equity Values [removed: Council] [added: Council, a diverse employee group reflective of the broader Company,] to lead our efforts on these values by acting as change agents to drive initiatives, create goals and awareness, and encourage colleagues to participate in community service activities and wellness initiatives.
We are committed to [removed: hiring a diverse workforce and also] fostering a safe, inclusive and productive workplace for all employees.
On May 18, 2023, the Company announced that Samuel Zell, its Founder and Chairman of the Board of Trustees, had passed away earlier that same day.
David J.
Neithercut, the Company’s former Chief Executive Officer and a member of the Company’s Board of Trustees since 2006, has been appointed as Chairman.
Through our ownership in these markets, we seek to optimize our portfolio by balancing risk and maximizing returns.
We believe that this portfolio will allow us to produce more consistent cash flows in a volatile world where local market conditions may cause operating fundamentals to change rapidly.
while maintaining flexibility to take advantage of future opportunities.
High costs of single family home ownership. Elevated single family home ownership costs (large down payments, high interest rates, etc.), low for sale inventory and existing homeowners that are reluctant to sell given favorable locked-in financing all support renting in the long-term, especially in the markets in which we operate.
While at times supply and demand imbalances may occur, over the long-term we believe that the dynamics in our markets will support superior long-term returns.
We also focus on resiliency/environmental and regulatory issues when choosing which markets/submarkets in which to concentrate our investment efforts.
We conduct climate resilience analyses and assess the regulatory climate to identify potential risks and opportunities as part of our due diligence process for new acquisitions and developments, as well as potential markets for portfolio expansion.
Resiliency and regulatory issues also factor into our decisions to dispose of certain properties and/or exit certain submarkets.
We deliver this performance through rapidly evolving technology and innovation that is increasingly prevalent in our industry.
*Our Commitment to Corporate Responsibility*
At Equity Residential, we believe focusing on corporate responsibility is a key way to programmatically address stakeholder concerns as part of our corporate purpose as we recognize the profound impact that the real estate industry can have on our environment and society as a whole.
We strive to create and maintain a sustainable portfolio that not only has a low environmental footprint, but also one that is attractive to our customers and the community and resilient to the changing climate.
We apply best practices for sustainability across all aspects of our real estate business.
Our expertise has shown that as real estate owners, developers and managers, we have the ability to make a positive impact on the environment while also enhancing our financial performance and strengthening our organization’s sense of purpose.
To further strengthen our commitments to sustainability initiatives, we set ambitious targets to reduce our environmental impact across the portfolio aligned with global climate change initiatives.
For example, we recently set a science-based target to reduce our absolute Scope 1, 2, and 3 greenhouse gas emissions (from our two biggest categories) by 30% by 2030 from a 2018 base year.
We continue to enhance our environmental disclosure efforts by calculating and disclosing our Scope 3 emissions.
We celebrate differences and are committed to cultivating an inclusive environment of belonging for all employees, driving excellence through shared perspectives and collaborative innovation.
Consistent with the Company's purpose and commitment to the incorporation of corporate responsibility concepts in all aspects of its business, executive compensation includes a goal which focuses on environmental, social and governance factors.
The Environmental, Social and Governance Report is not part of or incorporated into this report.
Having a thriving employee base is the pinnacle of our total wellbeing efforts.
needs.
Understanding the importance of a mentally healthy workforce, we also added an industry-leading meditation app, free to all employees and their family members, designed to promote mental health.
Our dedication to mental wellness is reflected in providing tools like this, fostering a culture that values self-care and effective mental health practices.
Other favorable performance drivers including high single-family housing prices that support longer term rentership and manageable resiliency/environmental risk.
We focus on the resident experience and leveraging operating efficiency which we believe drives our success in renewing our residents.
Rapidly evolving technology continues to drive innovation in the rental industry.
*Our Commitment to Environmental, Social and Governance (“ESG”)*
At Equity Residential, we believe a focus on ESG is a key way to programmatically address stakeholder concerns as part of our corporate purpose.
This needs to be a continuous endeavor, in which we invest in resilient properties that will stand the test of time and remain attractive to our customers and the community without negatively impacting the environment.
In 2018, the Company became the first multifamily REIT ever to issue a green bond.
In 2021, the Company issued a second green bond, and the net proceeds of approximately $494.2 million from this offering were fully allocated to the development of one property in Seattle certified as LEED Platinum, one property in Boston certified as LEED Gold and one property in Washington, D.C. certified as LEED Silver.
We are also intensely focused on the “Social” and “Governance” aspects of ESG.
Executive compensation includes an ESG goal and our Board of Trustees, primarily through its Compensation Committee, takes an active role in overseeing our efforts in this regard.
reviewed and approved by the Corporate Governance Committee of our Board of Trustees, which monitors the Company’s ongoing ESG efforts.
We continue to enhance our ESG disclosure efforts, including by obtaining third-party assurance covering certain of the results outlined in the above report.
We also continue to focus on improving our female representation, which is now 36.0% of our workforce.
The Company was named the Gold Nareit 2021 Diversity, Equity and Inclusion award recipient in recognition of the Company’s demonstration of a strong commitment to the advancement of diversity and inclusion both within the Company and in the REIT and publicly traded real estate industry.
Thriving employees are the pinnacle of our efforts throughout all our business functions.
An excerpt. Shown here: 40 of 53 rewritten, all 27 added and all 15 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2023 filing and the FY2022 filing.
Item 3. Legal Proceedings
1 rewritten, 8 added, 0 removed, 0 unchanged
As of December 31, [removed: 2022,] [added: 2023,] the Company does not believe there is any litigation pending or threatened against it that, individually or in the aggregate, may reasonably be expected to have a material adverse effect on the Company.
The Company has been named as a defendant in a number of cases filed in late 2022 and 2023 alleging antitrust violations by RealPage, Inc., a seller of revenue management software products, and various owners and/or operators of multifamily housing, including us, that have utilized these products.
The complaints allege collusion among the defendants to illegally fix and inflate the pricing of multifamily rents and seek monetary damages, injunctive relief, fees and costs.
All of the cases except for one have been consolidated into a single putative class action in the United States District Court for the Middle District of Tennessee.
On December 28, 2023, motions to dismiss this consolidated action, filed by RealPage, Inc. as well as us and our multifamily co-defendants, were denied by the Court and the case is proceeding.
Another case with similar allegations has been filed by the District of Columbia against
RealPage, Inc. and a number of multifamily owners and/or operators, including us.
We believe these various lawsuits are without merit and we intend to vigorously defend against them.
As these proceedings are in the early stages, it is not possible for the Company to predict the outcome nor is it possible to estimate the amount of loss, if any, which may be associated with an adverse decision in any of these cases.
Cover and table of contents
31 rewritten, 4 added, 4 removed, 191 unchanged
For the Fiscal Year Ended December 31, [removed: 2022][added: 2023]
| Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive [removed: officers] [added: officers] during the relevant recovery period pursuant to §240.10D-1(b). | | | | | | |
The aggregate market value of Common Shares held by non-affiliates of the Registrant was approximately [removed: $26.8] [added: $25.0] billion based upon the closing price on June 30, [removed: 2022] [added: 2023] of [removed: $72.22] [added: $65.97] using beneficial ownership of shares rules adopted pursuant to Section 13 of the Securities Exchange Act of 1934 to exclude voting shares owned by Trustees and Executive Officers, some of whom may not be held to be affiliates upon judicial determination.
The number of Common Shares of Beneficial Interest, $0.01 par value, outstanding on February [removed: 10, 2023] [added: 8, 2024] was [removed: 378,602,684.][added: 379,553,591.]
Part III incorporates by reference certain information that will be contained in Equity Residential’s Proxy Statement relating to its [removed: 2023] [added: 2024] Annual Meeting of Shareholders, which Equity Residential intends to file no later than 120 days after the end of its fiscal year ended December 31, [removed: 2022,] [added: 2023,] and thus these items have been omitted in accordance with General Instruction G(3) to Form 10-K.
Equity Residential is the general partner and [removed: 96.8%] [added: 97.0%] owner of ERP Operating Limited Partnership.
This report combines the annual reports on Form 10-K for the year ended December 31, [removed: 2022] [added: 2023] of Equity Residential and ERP Operating Limited Partnership.
[removed: 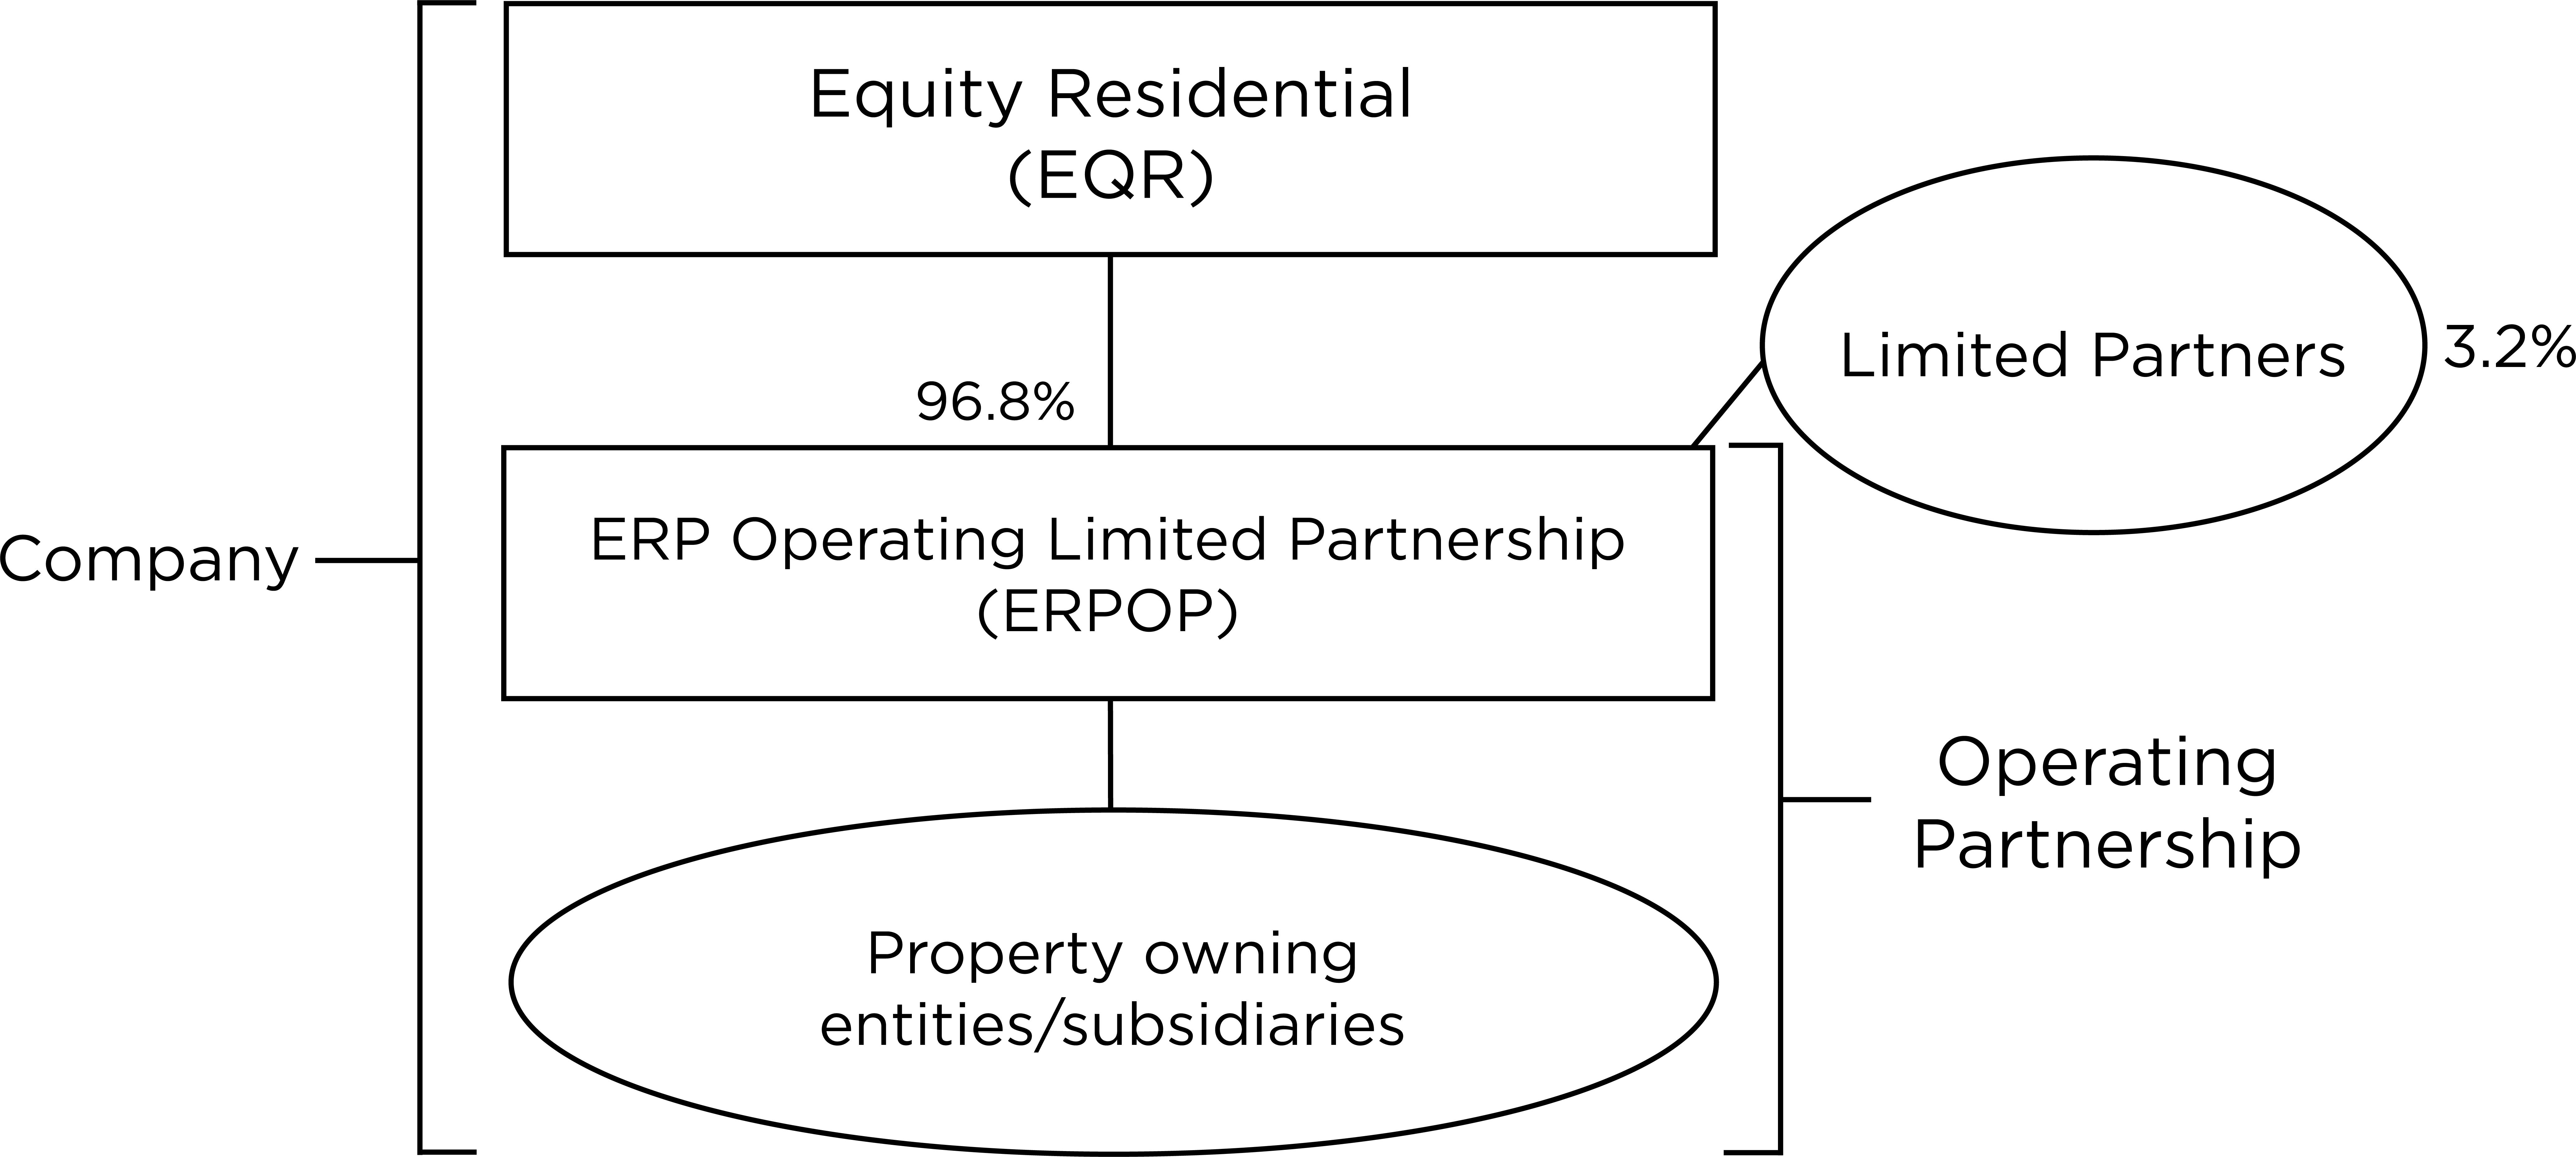][added: 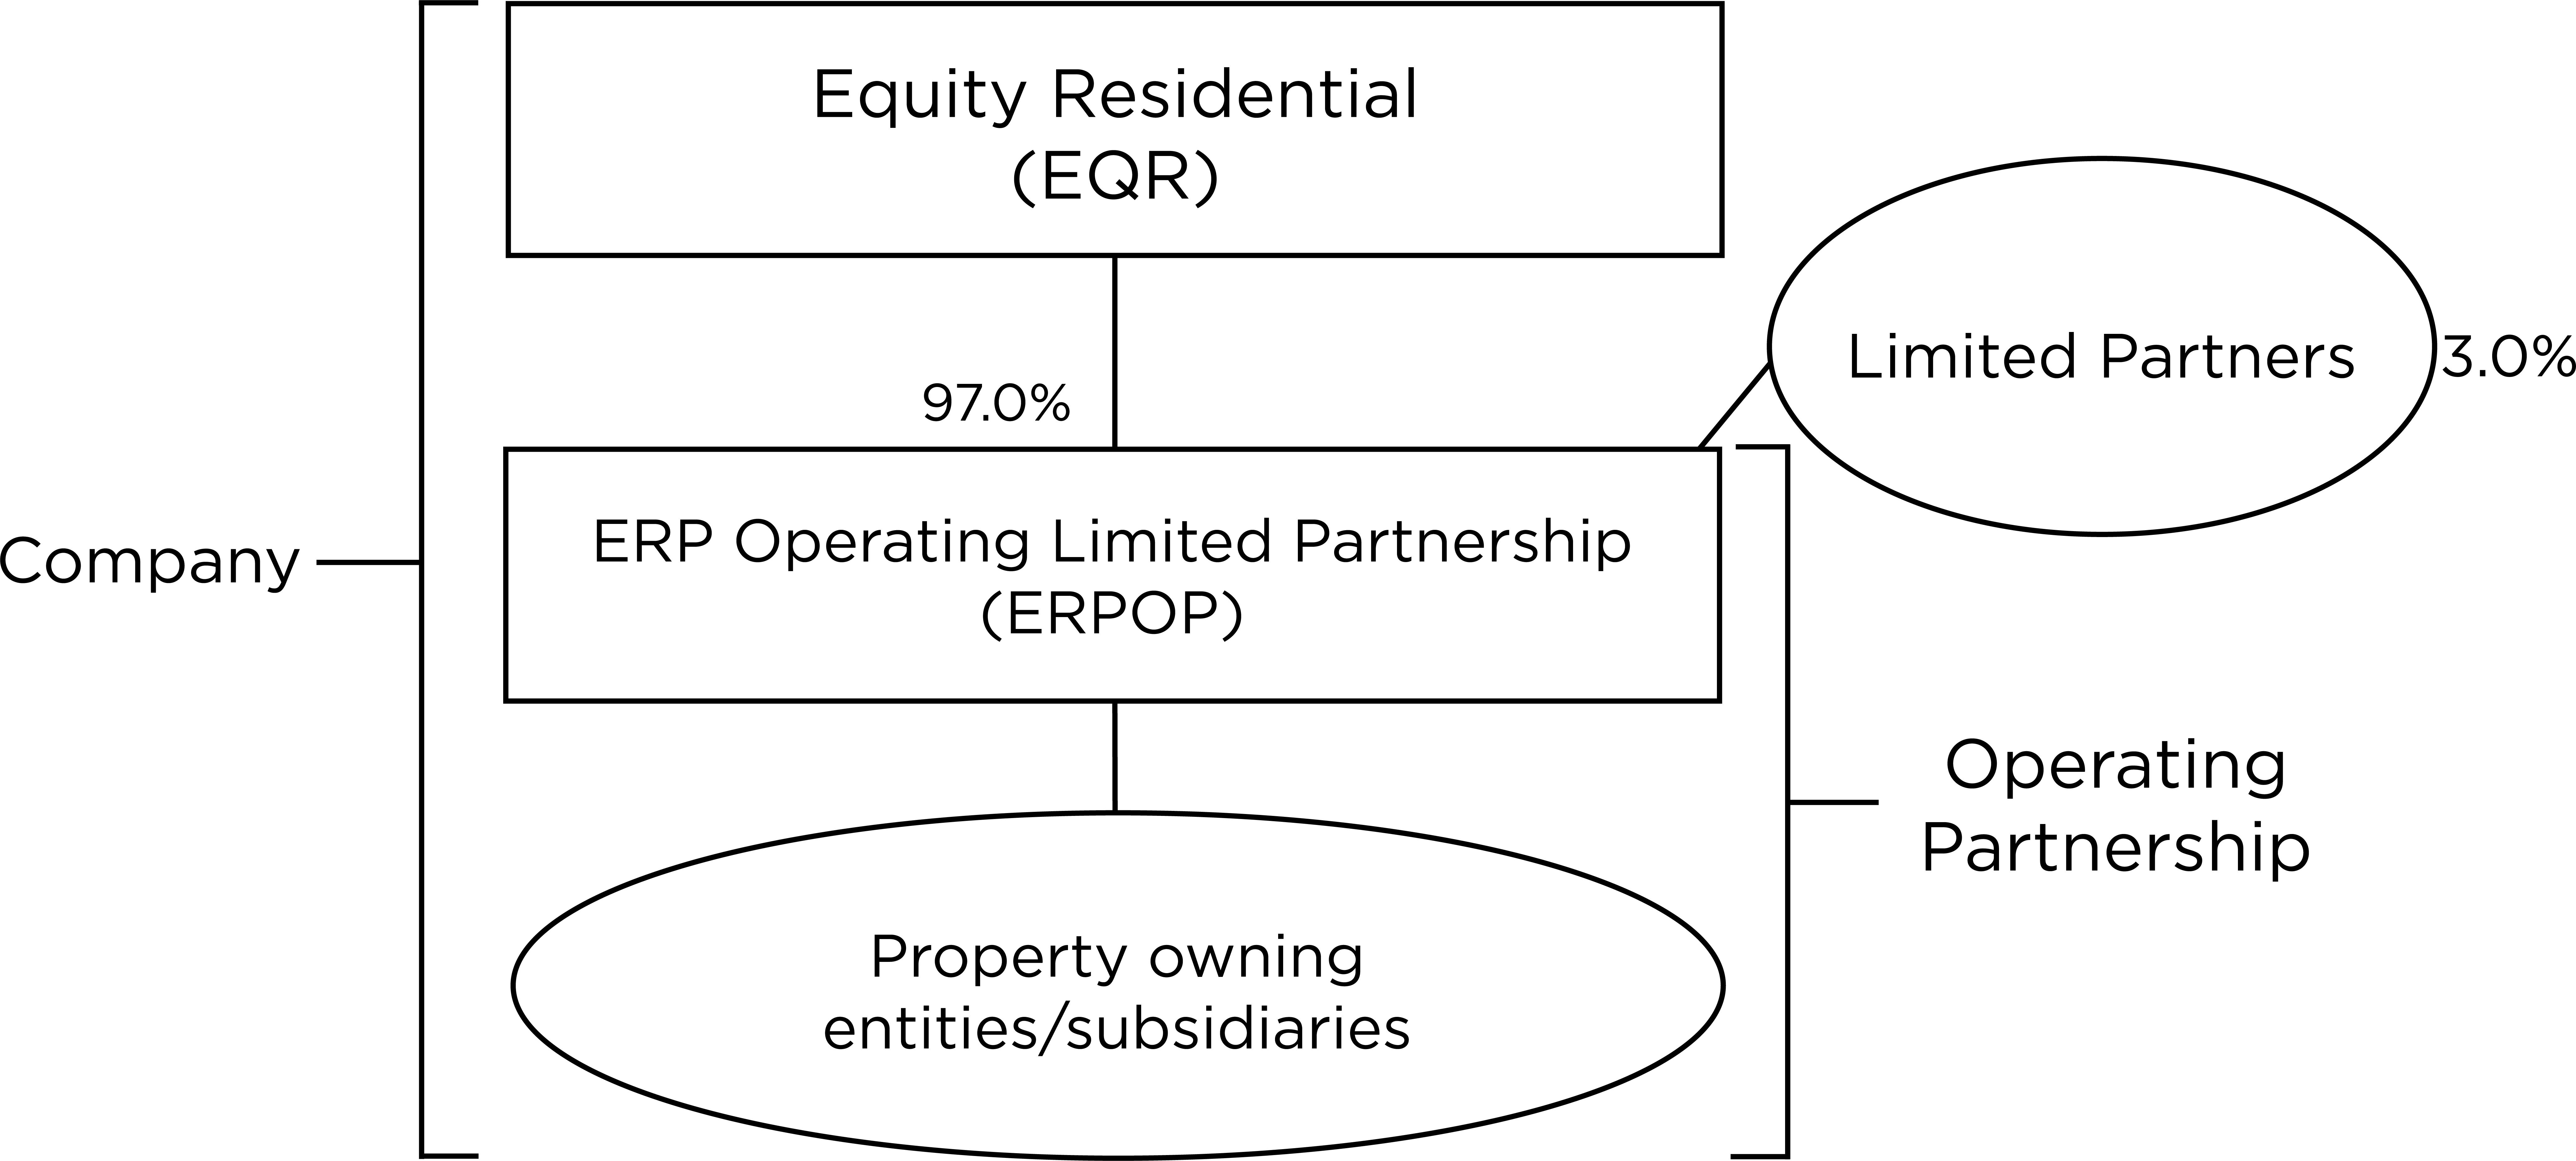]
EQR is the general partner of, and as of December 31, [removed: 2022] [added: 2023] owned an approximate [removed: 96.8%] [added: 97.0%] ownership interest in, ERPOP.
The remaining [removed: 3.2%] [added: 3.0%] interest is owned by limited partners.
| Item 1A. | | [Risk Factors](#item_1a_risk_factors) | | [removed: 11] [added: 12] |
| Item 1B. | | [Unresolved Staff Comments](#item_1b_unresolved_staff_comments) | | [removed: 21] [added: 23] |
| Item 2. | | [Properties](#item_2_properties) | | [removed: 21] [added: 24] |
| Item 3. | | [Legal Proceedings](#item_3_legal_proceedings) | | [removed: 23] [added: 26] |
| Item 4. | | [Mine Safety Disclosures](#item_4_mine_safety_disclosures) | | [removed: 23] [added: 27] |
| Item 5. | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities](#item_5_market_for_registrants_common_equ) | | [removed: 24] [added: 28] |
| Item 6. | | [Reserved](#item_6_selected_financial_data) | | [removed: 24] [added: 28] |
| Item 7. | | [Management’s Discussion and Analysis of Financial Condition and Results of Operations](#item_7_managements_discussion_analysis_f) | | [removed: 25] [added: 29] |
| Item 7A. | | [Quantitative and Qualitative Disclosures about Market Risk](#item_7a_quantitative_qualitative_disclos) | | [removed: 40] [added: 44] |
| Item 8. | | [Financial Statements and Supplementary Data](#item_8_financial_statements_supplementar) | | [removed: 41] [added: 45] |
| Item 9. | | [Changes in and Disagreements with Accountants on Accounting and Financial Disclosure](#item_9_changes_in_disagreements_with_acc) | | [removed: 41] [added: 45] |
| Item 9A. | | [Controls and Procedures](#item_9a_controls_procedures) | | [removed: 41] [added: 45] |
| Item 9B. | | [Other Information](#item_9b_or_information) | | [removed: 42] [added: 46] |
| Item 9C. | | [Disclosure Regarding Foreign Jurisdictions that Prevent Inspections](#item_9c_disclosure_regarding_foreign_jur) | | [removed: 42] [added: 46] |
| Item 10. | | [Trustees, Executive Officers and Corporate Governance](#items_10_11_12_13_14) | | [removed: 43] [added: 47] |
| Item 11. | | [Executive Compensation](#items_10_11_12_13_14) | | [removed: 43] [added: 47] |
| Item 12. | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters](#items_10_11_12_13_14) | | [removed: 43] [added: 47] |
| Item 13. | | [Certain Relationships and Related Transactions, and Trustee Independence](#items_10_11_12_13_14) | | [removed: 43] [added: 47] |
| Item 14. | | [Principal Accountant Fees and Services](#items_10_11_12_13_14) | | [removed: 43] [added: 47] |
| Item 15. | | [Exhibit and Financial Statement Schedules](#item_15_exhibits_financial_statement_sch) | | [removed: 44] [added: 48] |
| Item 16. | | [Form 10-K Summary](#item_16_form_10k_summary) | | [removed: 44] [added: 48] |
| Item 1C. | | [Cybersecurity](#item_1c_cybersecurity) | | 23 |
| EX-4.1 | | | | |
| EX-4.3 | | | | |
| EX-97 | | | | |
| EX-101 CALCULATION LINKBASE DOCUMENT | | | | |
| EX-101 LABELS LINKBASE DOCUMENT | | | | |
| EX-101 PRESENTATION LINKBASE DOCUMENT | | | | |
| EX-101 DEFINITION LINKBASE DOCUMENT | | | | |
Item 1C. Cybersecurity
0 rewritten, 27 added, 0 removed, 0 unchanged
New section this year
*Risk management and strategy*
We have an enterprise-wide information security program designed to protect our information systems from cybersecurity threats.
We identify and assess risks from cybersecurity threats by monitoring and evaluating our digital assets and our risk profile using various methods.
We monitor security events that are internally discovered or externally reported that may affect our systems and have processes and procedures to assess those events for potential cybersecurity impact or risk and consequently improve our security measures and planning.
Additionally, we work with third parties from time to time that assist us in refining our cybersecurity risk strategy in order to identify, assess and manage cybersecurity risks, including professional services firms and consulting firms.
We seek to detect and investigate unauthorized attempts and attacks against our network and services, and to minimize their occurrence and recurrence through changes or updates to our internal processes and tools and changes or updates to our services; however, we remain potentially vulnerable to known or unknown threats.
Our cybersecurity incident response processes are designed to escalate certain cybersecurity events to members of management depending on the circumstances.
Key members of management, including representatives from IT, operations, legal, finance, risk management and internal audit, serve on the Company’s senior security incident response team to help the Company mitigate and remediate cybersecurity incidents of which they are notified, and certain cybersecurity incidents are escalated to the Company’s executives.
In addition, the Company’s incident response processes include potential reporting to the Audit Committee of our Board of Trustees for certain cybersecurity incidents.
We also have a third-party risk management program in place to manage cybersecurity risks associated with third-party service providers.
While we do maintain processes and procedures to identify, prioritize and assess risks associated with third-party service providers, we must rely on third parties to augment our security program, and we cannot ensure in all circumstances that their efforts will be successful.
While to date we have not experienced a cybersecurity threat or incident that resulted in a material adverse impact to our business or operations, there can be no guarantee that we will not experience such an incident in the future.
Any significant disruption to our systems could adversely affect our business and results of operations.
Further, a cyber incident impacting our systems or a third-party’s systems could subject us to business, regulatory, litigation and reputational risk, which could have a negative effect on our business, financial condition and results of operations.
Notwithstanding the extensive approach we take to cybersecurity, we may not be successful in preventing or mitigating a cybersecurity incident that could have a material adverse effect on us.
While we maintain cybersecurity insurance, the costs related to cybersecurity threats or disruptions may not be fully insured.
See Item 1A, *Risk Factors*, for a discussion of cybersecurity risks.
*Governance*
Our Information Technology Security Team, under the oversight of our Senior Vice President of IT and the leadership of our VP of IT Infrastructure and Security, is responsible for our overall information security strategy, policy, security engineering, operations and cyber threat detection and response.
The Information Technology Security Team manages and continually enhances a robust enterprise security structure with the ultimate goal of minimizing cybersecurity incidents to the extent feasible, while simultaneously increasing our system resilience in an effort to minimize the business impact should an incident occur.
Our Information Technology Security Team possesses decades of experience in navigating cybersecurity threats and mitigating associated risks as a result of holding similar positions at other large companies.
Most members of the team hold degrees in cybersecurity and/or related disciplines, have cybersecurity certifications such as Certified Information Systems Security Professional (CISSP) and/or periodically attend various cyber-focused conferences and training programs.
Specifically, our Senior Vice President of IT and our VP of IT Infrastructure and Security combined have over 30 years of technology and cybersecurity experience.
The team provides regular reports to senior management and affected departments on various cybersecurity threats, assessments and findings.
The Audit Committee of our Board of Trustees oversees our annual enterprise risk management assessment, where we assess key risks within the Company, including security and technology risks and cybersecurity threats.
The Audit Committee oversees our ongoing cybersecurity risk management efforts and regularly receives detailed reports from representatives of our Information Technology Security Team addressing a wide range of related topics.
At least annually, our IT leadership (and external cybersecurity experts if applicable) reviews key cybersecurity strategies and policies with the full Board of Trustees, including risk assessments, mitigation strategies, areas of emerging risks, incidents and industry trends and other areas of importance.
Item 2. Properties
36 rewritten, 25 added, 29 removed, 67 unchanged
As of December 31, [removed: 2022,] [added: 2023,] the Company, directly or indirectly through investments in title holding entities, owned all or a portion of [removed: 308] [added: 302] properties located in 10 states and the District of Columbia consisting of [removed: 79,597] [added: 80,191] apartment units.
| Mid/High-Rise | | | 212 | | | | [removed: 55,148] [added: 55,638] | | | | [removed: 260] [added: 262] | |
| Wholly Owned Properties | | | [removed: 293] [added: 288] | | | | [removed: 76,483] [added: 77,131] | |
| Partially Owned Properties – Consolidated | | | [removed: 15] [added: 14] | | | | [removed: 3,114] [added: 3,060] | |
The following table sets forth certain information by market relating to the Company’s properties at December 31, [removed: 2022:][added: 2023:]
| Orange County | | | 13 | | | | 4,028 | | | | [removed: 5.2] [added: 5.4] | % | | | [removed: 2,685] [added: 2,873] | |
| San Diego | | | 12 | | | | 2,878 | | | | 4.0 | % | | | [removed: 2,894] [added: 3,108] | |
| New York | | | 34 | | | | 8,536 | | | | [removed: 14.0] [added: 14.1] | % | | | [removed: 4,378] [added: 4,566] | |
| Dallas/Ft. Worth | | | 4 | | | | 1,241 | | | | 0.7 | % | | | [removed: 1,904] [added: 1,935] | |
| Austin | | | 3 | | | | 741 | | | | 0.4 | % | | | [removed: 1,853] [added: 1,819] | |
% of Stabilized Budgeted NOI - Represents original budgeted [removed: 2023] [added: 2024] NOI for stabilized properties and projected annual NOI at stabilization (defined as having achieved 90% occupancy for three consecutive months) for properties that are in lease-up.
The following tables provide a rollforward of the apartment units included in Same Store Properties (please refer to the Definitions section in Item 7, *Management’s Discussion and Analysis of Financial Condition and Results of Operations*) and a reconciliation of apartment units included in Same Store Properties to those included in Total Properties for the year ended December 31, [removed: 2022:][added: 2023:]
| | | Year Ended December 31, [removed: 2022] [added: 2023] | | | | | | |
| Same Store Properties at December 31, [removed: 2021] [added: 2023] | | | [removed: 284] [added: 288] | | | | [removed: 74,077] [added: 76,297] | |
| Lease-up properties [added: not yet] stabilized [added: (2)] | | | [removed: 2] [added: 5] | | | | [removed: 221] [added: 1,298] | |
| Other | | | — | | | | [removed: (37] [added: 11] | [removed: )] |
| 2021 acquisitions | | | [removed: 17] [added: 16] | | | | [removed: 4,747] [added: 4,326] | |
| Total Non-Same Store | | | [removed: 25] [added: 14] | | | | [removed: 6,725] [added: 3,894] | |
| Total Properties and Apartment Units | | | [removed: 308] [added: 302] | | | | [removed: 79,597] [added: 80,191] | |
As of December 31, [removed: 2022,] [added: 2023,] the property had [removed: an occupancy] [added: a Physical Occupancy] of [removed: 65.2%.][added: 67.4%.]
Pearl MDR located in Marina Del Rey, CA containing 597 apartment units was removed from the same store portfolio in the third quarter of 2022 due to a large scale [removed: repiping] [added: re-piping] and renovation project in which significant portions of the property are being taken offline for extended time periods.
As of December 31, [removed: 2022,] [added: 2023,] the property had [removed: an occupancy] [added: a Physical Occupancy] of [removed: 79.6%.][added: 64.5%.]
[removed: As of] [added: For the year ended] December 31, [removed: 2022,] [added: 2023,] the Company’s same store [removed: occupancy] [added: Physical Occupancy] was [removed: 95.7%] [added: 95.9%] and its total portfolio-wide [removed: occupancy,] [added: Physical Occupancy,] which includes completed development properties in various stages of lease-up, was [removed: 95.6%.][added: 95.4%.]
The properties in various stages of development and lease-up at December 31, [removed: 2022] [added: 2023] are included in the following table:
| Development and Lease-Up Projects as of December 31, [removed: 2022] [added: 2023] | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Reverb (fka 9th and W) (3) | | Washington, D.C. | | 92% | | | 312 | | | [removed: $] | 108,027 | | | [removed: $] | [removed: 88,378] [added: 104,651] | | | [removed: $] | [removed: 43,714] [added: —] | | | [removed: 88%] [added: 100%] | | Q3 2021 | | [removed: Q1] [added: Q2] 2023 | | [removed: Q3] [added: Q2] 2023 | | Q3 2024 | | [removed: –] [added: 82%] / [removed: –] [added: 79%] | |
| Laguna Clara II | | Santa Clara, CA | | 100% | | | 225 | | | [added: $] | 152,621 | | | [added: $] | [removed: 24,562] [added: 78,036] | | | [added: $] | — | | | [removed: 14%] [added: 53%] | | Q2 2022 | | Q4 2024 | | Q1 2025 | | Q4 2025 | | – / – | |
| [removed: Projects Under] [added: Total] Development [added: Projects] - Consolidated | | | | | | | 537 | | | | 260,648 | | | | [removed: 112,940] [added: 182,687] | | | | [removed: 43,714] [added: —] | | | | | | | | | | | | | | |
| Alloy Sunnyside [added: (4)] | | Denver, CO | | 80% | | | 209 | | | | [removed: 66,004] [added: 70,004] | | | | [removed: 38,309] [added: 62,071] | | | | [removed: 5,931] [added: 27,304] | | | [removed: 53%] [added: 94%] | | Q3 2021 | | [removed: Q4 2023] [added: Q2 2024] | | Q2 2024 | | Q1 2025 | | – / – | |
| Solana Beeler Park [added: (4)] | | Denver, CO | | 90% | | | 270 | | | | [removed: 81,206] [added: 85,206] | | | | [removed: 27,008] [added: 56,178] | | | | [removed: —] [added: 22,858] | | | [removed: 19%] [added: 64%] | | Q4 2021 | | [removed: Q4 2023] [added: Q2 2024] | | [removed: Q2] [added: Q3] 2024 | | Q1 2025 | | – / – | |
| Remy (Toll) [added: (4)] | | Frisco, TX | | 75% | | | 357 | | | | [removed: 96,937] [added: 98,937] | | | | [removed: 46,214] [added: 77,170] | | | | [removed: 4,892] [added: 31,494] | | | [removed: 37%] [added: 80%] | | Q1 2022 | | Q1 2024 | | Q4 2024 | | Q3 2025 | | – / – | |
| [removed: Settler] [added: Sadie (fka Settler)] (Toll) [added: (4)] | | Fort Worth, TX | | 75% | | | 362 | | | | [removed: 81,775] [added: 82,775] | | | | [removed: 26,456] [added: 55,522] | | | | [removed: —] [added: 14,944] | | | [removed: 24%] [added: 69%] | | Q2 2022 | | Q2 2024 | | Q3 2024 | | Q3 2025 | | – / – | |
| Lyle (Toll) (3) | | Dallas, TX | | 75% | | | 334 | | | | 86,332 | | | | [removed: 13,732] [added: 52,914] | | | | [removed: —] [added: 21,962] | | | [removed: 13%] [added: 66%] | | Q3 2022 | | [removed: Q4] [added: Q2] 2024 | | [removed: Q2 2025] [added: Q3 2024] | | Q1 2026 | | – / – | |
| Projects Under Development - Unconsolidated | | | | | | | 1,982 | | | | [removed: 610,918] [added: 623,918] | | | | [removed: 252,641] [added: 478,990] | | | | [removed: 13,632] [added: 195,620] | | | | | | | | | | | | | | |
| Total Development Projects - Unconsolidated | | | | | | | 1,982 | | | | [removed: 610,918] [added: 623,918] | | | | [removed: 252,641] [added: 478,990] | | | | [removed: 13,632] [added: 195,620] | | | | | | | | | | | | | | |
[removed: All] [added: Except for Reverb where the Company paid off the third-party construction loan during the year ended December 31, 2023, all] non-wholly owned projects are being partially funded with project-specific construction loans.
| Garden | | | 90 | | | | 24,553 | | | | 273 | |
| | | | 302 | | | | 80,191 | | | | 266 | |
| | | | 302 | | | | 80,191 | |
| Los Angeles | | | 58 | | | | 14,732 | | | | 17.1 | % | | $ | 2,929 | |
| Subtotal – Southern California | | | 83 | | | | 21,638 | | | | 26.5 | % | | | 2,942 | |
| Washington, D.C. | | | 48 | | | | 15,028 | | | | 16.3 | % | | | 2,657 | |
| San Francisco | | | 43 | | | | 11,667 | | | | 15.4 | % | | | 3,303 | |
| Boston | | | 27 | | | | 7,170 | | | | 11.8 | % | | | 3,574 | |
| Seattle | | | 44 | | | | 9,267 | | | | 10.4 | % | | | 2,561 | |
| Subtotal – Established Markets | | | 279 | | | | 73,306 | | | | 94.5 | % | | | 3,145 | |
| Denver | | | 9 | | | | 2,792 | | | | 2.8 | % | | | 2,411 | |
| Atlanta | | | 7 | | | | 2,111 | | | | 1.6 | % | | | 2,169 | |
| Subtotal – Expansion Markets | | | 23 | | | | 6,885 | | | | 5.5 | % | | | 2,188 | |
| Total | | | 302 | | | | 80,191 | | | | 100.0 | % | | $ | 3,063 | |
| 2023 dispositions | | | (11 | ) | | | (912 | ) |
| | | Year Ended December 31, 2023 | | | | | | |
| Same Store | | | 288 | | | | 76,297 | |
| 2023 acquisitions | | | 4 | | | | 1,183 | |
| 2021 acquisitions not yet stabilized | | | 1 | | | | 421 | |
| Projects Under Development - Consolidated | | | | | | | 225 | | | | 152,621 | | | | 78,036 | | | | — | | | | | | | | | | | | | | |
| Projects Completed Not Stabilized - Consolidated | | | | | | | 312 | | | | 108,027 | | | | 104,651 | | | | — | | | | | | | | | | | | | | |
| Alexan Harrison (4) | | Harrison, NY | | 62% | | | 450 | | | | 200,664 | | | | 175,135 | | | | 77,058 | | | 92% | | Q3 2021 | | Q1 2024 | | Q4 2024 | | Q2 2026 | | – / – | |
| Total Development Projects | | | | | | | 2,519 | | | $ | 884,566 | | | $ | 661,677 | | | $ | 195,620 | | | | | | | | | | | | | | |
(4)
The Total Budgeted Capital Cost on these projects increased by an aggregate of $13.0 million or 2.5% of initial budget primarily due to higher than budgeted interest incurred on construction loans.
| Garden | | | 96 | | | | 24,449 | | | | 255 | |
| | | | 308 | | | | 79,597 | | | | 258 | |
| | | | 308 | | | | 79,597 | |
| Los Angeles | | | 66 | | | | 15,259 | | | | 18.2 | % | | $ | 2,773 | |
| Subtotal – Southern California | | | 91 | | | | 22,165 | | | | 27.4 | % | | | 2,772 | |
| San Francisco | | | 44 | | | | 11,790 | | | | 15.9 | % | | | 3,229 | |
| Washington, D.C. | | | 47 | | | | 14,716 | | | | 15.3 | % | | | 2,531 | |
| Boston | | | 27 | | | | 7,170 | | | | 11.5 | % | | | 3,373 | |
| Seattle | | | 46 | | | | 9,525 | | | | 11.0 | % | | | 2,575 | |
| Subtotal – Established Markets | | | 289 | | | | 73,902 | | | | 95.1 | % | | | 3,016 | |
| Denver | | | 8 | | | | 2,498 | | | | 2.7 | % | | | 2,372 | |
| Atlanta | | | 4 | | | | 1,215 | | | | 1.1 | % | | | 2,120 | |
| Subtotal – Expansion Markets | | | 19 | | | | 5,695 | | | | 4.9 | % | | | 2,153 | |
| Total | | | 308 | | | | 79,597 | | | | 100.0 | % | | $ | 2,956 | |
| 2019 acquisitions (not stabilized until 2020) | | | 1 | | | | 217 | |
| 2020 acquisitions | | | 1 | | | | 158 | |
| 2022 dispositions | | | (3 | ) | | | (945 | ) |
| Properties removed from same store (1) | | | (2 | ) | | | (819 | ) |
| Same Store | | | 283 | | | | 72,872 | |
| Lease-up properties not yet stabilized (2) | | | 4 | | | | 986 | |
| Aero Apartments | | Alameda, CA | | 90% | | | 200 | | | | 117,794 | | | | 113,610 | | | | 64,664 | | | 100% | | Q3 2019 | | Q2 2021 | | Q2 2021 | | Q1 2023 | | 97% / 95% | |
| Projects Completed Not Stabilized - Consolidated | | | | | | | 200 | | | | 117,794 | | | | 113,610 | | | | 64,664 | | | | | | | | | | | | | | |
| Projects Completed and Stabilized During theQuarter: | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Alcott Apartments (fka West End Tower) | | Boston, MA | | 100% | | | 470 | | | | 409,164 | | | | 408,114 | | | | — | | | 100% | | Q2 2018 | | Q3 2021 | | Q4 2021 | | Q4 2022 | | 95% / 95% | |
| Projects Completed and Stabilized During the Quarter - Consolidated | | | | | | | 470 | | | | 409,164 | | | | 408,114 | | | | — | | | | | | | | | | | | | | |
| Alexan Harrison | | Harrison, NY | | 62% | | | 450 | | | | 198,664 | | | | 100,922 | | | | 2,809 | | | 39% | | Q3 2021 | | Q3 2023 | | Q2 2024 | | Q4 2025 | | – / – | |
| Total Development Projects - Consolidated | | | | | | | 1,207 | | | | 787,606 | | | | 634,664 | | | | 108,378 | | | | | | | | | | | | | | |
| Total Development Projects | | | | | | | 3,189 | | | $ | 1,398,524 | | | $ | 887,305 | | | $ | 122,010 | | | | | | | | | | | | | | |
As of December 31, 2022, three projects have begun drawing on their construction loans for the unconsolidated joint venture projects under development.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
4 rewritten, 20 added, 0 removed, 6 unchanged
At February [removed: 10, 2023,] [added: 8, 2024,] the number of record holders of Common Shares was approximately [removed: 1,790] [added: 1,710] and [removed: 378,602,684] [added: 379,553,591] Common Shares were outstanding.
At February [removed: 10, 2023,] [added: 8, 2024,] the number of record holders of Units in the Operating Partnership was approximately [removed: 465] [added: 450] and [removed: 391,169,119] [added: 391,291,526] Units were outstanding.
*Unregistered Common Shares Issued in the Quarter Ended December 31, [removed: 2022] [added: 2023] (Equity Residential)*
During the quarter ended December 31, [removed: 2022,] [added: 2023,] EQR issued [removed: 414,871] [added: 151,199] Common Shares in exchange for [removed: 414,871] [added: 151,199] OP Units held by various limited partners of ERPOP.
*Common Shares Repurchased in the Quarter Ended December 31, 2023*
The Company repurchased and retired the following Common Shares during the quarter ended December 31, 2023:
| | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Period | | Total Number of Common Shares Purchased (1) | | | | Weighted Average Price Paid Per Share (1), (2) | | | | Total Number of Common Shares Purchased as Part of Publicly Announced Plans or Programs (1) | | | | Maximum Number of Common Shares that May Yet Be Purchased Under the Plans or Programs (1), (3) | | |
| October 1, 2023 - October 31, 2023 | | | — | | | $ | — | | | | — | | | | 13,000,000 | |
| November 1, 2023 - November 30, 2023 | | | 664,696 | | | $ | 55.44 | | | | 664,696 | | | | 12,335,304 | |
| December 1, 2023 - December 31, 2023 | | | 199,690 | | | $ | 61.28 | | | | 199,690 | | | | 12,135,614 | |
| Total | | | 864,386 | | | $ | 56.79 | | | | 864,386 | | | | | |
(1)
The Common Shares repurchased during the quarter ended December 31, 2023 represent Common Shares repurchased under the Company’s publicly announced share repurchase program approved by its Board of Trustees.
The Company's share repurchase program was publicly announced on July 30, 2013 and the increase to its 13.0 million shares capacity was publicly announced on August 4, 2016.
The program does not have an expiration date and may be suspended or discontinued at any time and does not obligate the Company to make any repurchases of its Common Shares.
In January 2024, the Company’s Board of Trustees approved replenishing the Company’s share repurchase program authorization back to its original 13.0 million shares.
(2)
Weighted average price paid per share excludes costs associated with the repurchases.
(3)
The number of shares available for purchase under the Company’s publicly announced share repurchase program authorized by the Board of Trustees.
The Company may repurchase Common Shares under its share repurchase program in open market or privately negotiated transactions.
The timing and actual number of shares repurchased under the repurchase program depend on a variety of factors, including price, general business and market conditions and other investment opportunities.
Item 9A. Controls and Procedures
7 rewritten, 1 added, 0 removed, 18 unchanged
Effective as of December 31, [removed: 2022,] [added: 2023,] the Company carried out an evaluation, under the supervision and with the participation of the Company’s management, including the Chief Executive Officer and Chief Financial Officer, of the effectiveness of the Company’s disclosure controls and procedures pursuant to Exchange Act Rules 13a-15 and 15d-15.
Based on the Company’s evaluation under the framework in Internal Control – Integrated Framework, management concluded that its internal control over financial reporting was effective as of December 31, [removed: 2022.][added: 2023.]
Our internal control over financial reporting has been audited as of December 31, [removed: 2022] [added: 2023] by Ernst & Young LLP, an independent registered public accounting firm, as stated in their report which is included herein.
There were no changes to the internal control over financial reporting of the Company identified in connection with the Company’s evaluation referred to above that occurred during the fourth quarter of [removed: 2022] [added: 2023] that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
Effective as of December 31, [removed: 2022,] [added: 2023,] the Operating Partnership carried out an evaluation, under the supervision and with the participation of the Operating Partnership’s management, including the Chief Executive Officer and Chief Financial Officer of EQR, of the effectiveness of the Operating Partnership’s disclosure controls and procedures pursuant to Exchange Act Rules 13a-15 and 15d-15.
Based on the Operating Partnership’s evaluation under the framework in Internal Control – Integrated Framework, management concluded that its internal control over financial reporting was effective as of December 31, [removed: 2022.][added: 2023.]
There were no changes to the internal control over financial reporting of the Operating Partnership identified in connection with the Operating Partnership’s evaluation referred to above that occurred during the fourth quarter of [removed: 2022] [added: 2023] that have materially affected, or are reasonably likely to materially affect, the Operating Partnership’s internal control over financial reporting.
Our internal control over financial reporting has been audited as of December 31, 2023 by Ernst & Young LLP, an independent registered public accounting firm, as stated in their report which is included herein.
Item 9B. Other Information
0 rewritten, 1 added, 1 removed, 0 unchanged
During the quarter ended December 31, 2023, no trustee or officer of the Company adopted or terminated a "Rule 10b5-1 trading arrangement" or "non-Rule 10b5-1 trading arrangement," as each term is defined in Item 408 of Regulation S-K.
None.
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
6 rewritten, 1 added, 1 removed, 16 unchanged
The information required by Item 10, Item 11, Item 12 (with the exception of the *Equity Compensation Plan Information* provided below), Item 13 and Item 14 is incorporated by reference to, and will be contained in, Equity Residential’s Proxy Statement, which the Company intends to file no later than 120 days after the end of its fiscal year ended December 31, [removed: 2022,] [added: 2023,] and thus these items have been omitted in accordance with General Instruction G(3) to Form 10-K.
Equity Residential is the general partner and [removed: 96.8%] [added: 97.0%] owner of ERP Operating Limited Partnership.
The following table provides information as of December 31, [removed: 2022] [added: 2023] with respect to the Company’s Common Shares that may be issued under its existing equity compensation plans.
The amounts shown in columns (a) and (b) of the above table do not include [removed: 289,918] [added: 320,070] outstanding Common Shares (all of which are restricted and subject to vesting requirements) that were granted under the Company’s 2019 Share Incentive Plan, as amended (the “2019 Plan”), and outstanding Common Shares that have been purchased by employees and trustees under the Company’s ESPP.
Includes [removed: 8,920,638] [added: 8,213,508] Common Shares that may be issued under the 2019 Plan and [removed: 2,486,599] [added: 2,418,463] Common Shares that may be sold to employees and trustees under the ESPP.
As of December 31, [removed: 2022, 8,920,638] [added: 2023, 8,213,508] shares were available for future issuance.
| Equity compensation plans approved by shareholders | | 3,958,252 | | $64.76 | | 10,631,971 |
| Equity compensation plans approved by shareholders | | 4,061,360 | | $62.60 | | 11,407,237 |
Item 16. Form 10-K Summary
701 rewritten, 751 added, 453 removed, 1,461 unchanged
| 4.1 | | [Description of Equity Residential Common Shares Registered Under Section 12 of the Securities Exchange Act of [removed: 1934.](https://www.sec.gov/Archives/edgar/data/906107/000156459020005562/eqr-ex41_637.htm)] [added: 1934.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex4_1.htm)] | | [removed: Included as Exhibit 4.1 to Equity Residential's and ERP Operating Limited Partnership's Form 10-K for the year ended December 31, 2019.] [added: Attached herein.] |
| 4.3 | | [Description of ERP Operating Limited Partnership OP Units Registered Under Section 12 of the Securities Exchange Act of [removed: 1934.](https://www.sec.gov/Archives/edgar/data/906107/000156459022005566/eqr-ex43_312.htm)] [added: 1934.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex4_3.htm)] | | [removed: Included as Exhibit 4.3 to Equity Residential's and ERP Operating Limited Partnership's Form 10-K for the year ended December 31, 2021.] [added: Attached herein.] |
| 10.13 | * | [Form of [removed: 2018] [added: 2022] Long-Term Incentive Plan Award [removed: Agreement.](https://www.sec.gov/Archives/edgar/data/906107/000156459018010687/eqr-ex101_301.htm)] [added: Agreement.](https://www.sec.gov/Archives/edgar/data/906107/000156459022016816/eqr-ex101_18.htm)] | | Included as Exhibit 10.1 to Equity Residential's and ERP Operating Limited Partnership's Form 10-Q for the quarterly period ended March 31, [removed: 2018.] [added: 2022.] |
| [removed: 10.14] [added: 10.21] | * | [removed: [Form] [added: [Amendment to the Equity Residential Supplemental Executive Retirement Plan, effective as] of [removed: 2022 Long-Term Incentive Plan Award Agreement.](https://www.sec.gov/Archives/edgar/data/906107/000156459022016816/eqr-ex101_18.htm)] [added: June 1, 2020.](https://www.sec.gov/Archives/edgar/data/906107/000156459020035511/eqr-ex101_104.htm)] | | Included as Exhibit 10.1 to Equity Residential's and ERP Operating Limited Partnership's Form 10-Q for the quarterly period ended [removed: March 31, 2022.] [added: June 30, 2020.] |
| [removed: 10.15] [added: 10.14] | * | [Form of Change in Control/Severance Agreement between the Company and other executive officers.](https://www.sec.gov/Archives/edgar/data/906107/000091205702009068/a2072511zex-10_13.txt) | | Included as Exhibit 10.13 to Equity Residential's Form 10-K for the year ended December 31, 2001. |
| [removed: 10.16] [added: 10.15] | * | [Form of First Amendment to Amended and Restated Change in Control/Severance Agreement with each executive officer.](https://www.sec.gov/Archives/edgar/data/906107/000119312509102717/dex101.htm) | | Included as Exhibit 10.1 to Equity Residential's Form 10-Q for the quarterly period ended March 31, 2009. |
| [removed: 10.17] [added: 10.16] | * | [Form of Indemnification Agreement between the Company and each trustee and executive officer.](https://www.sec.gov/Archives/edgar/data/906107/000110465904007155/a04-2963_2ex10d18.htm) | | Included as Exhibit 10.18 to Equity Residential's Form 10-K for the year ended December 31, 2003. |
| [removed: 10.18] [added: 10.17] | * | [Form of Executive Retirement Benefits Agreement.](https://www.sec.gov/Archives/edgar/data/906107/000110465907014819/a07-5259_1ex10d24.htm) | | Included as Exhibit 10.24 to Equity Residential's Form 10-K for the year ended December 31, 2006. |
| [removed: 10.19] [added: 10.18] | * | [Retirement Benefits Agreement between Samuel Zell and the Company dated October 18, 2001.](https://www.sec.gov/Archives/edgar/data/906107/000091205702009068/a2072511zex-10_18.txt) | | Included as Exhibit 10.18 to Equity Residential's Form 10-K for the year ended December 31, 2001. |
| [removed: 10.20] [added: 10.19] | * | [Age 62 Retirement Agreement, dated September 4, 2018, by and between Equity Residential and David J. Neithercut.](https://www.sec.gov/Archives/edgar/data/906107/000156459018025620/eqr-ex101_20.htm) | | Included as Exhibit 10.1 to Equity Residential's and ERP Operating Limited Partnership's Form 10-Q for the quarterly period ended September 30, 2018. |
| [removed: 10.21] [added: 10.22] | * | [removed: [Age 62 Retirement Agreement, dated February 27, 2020, by and between] [added: [Amendment to the] Equity Residential [removed: and Alan W. George.](https://www.sec.gov/Archives/edgar/data/906107/000156459020022867/eqr-ex101_17.htm)] [added: Supplemental Executive Retirement Plan, effective as of October 1, 2022.](https://www.sec.gov/Archives/edgar/data/906107/000095017022020464/eqr-ex10_1.htm)] | | Included as Exhibit 10.1 to Equity Residential's and ERP Operating Limited Partnership's Form 10-Q for the quarterly period ended [removed: March 31, 2020.] [added: September 30, 2022.] |
| [removed: 10.22] [added: 10.20] | * | [The Equity Residential Supplemental Executive Retirement Plan as Amended and Restated effective April 1, 2017.](https://www.sec.gov/Archives/edgar/data/906107/000156459017015496/eqr-ex102_61.htm) | | Included as Exhibit 10.2 to Equity Residential's and ERP Operating Limited Partnership's Form 10-Q for the quarterly period ended June 30, 2017. |
| 10.23 | * | [removed: [Amendment to the] [added: [The] Equity Residential [added: Grandfathered] Supplemental Executive Retirement [removed: Plan, effective] [added: Plan] as [removed: of June] [added: Amended and Restated effective January] 1, [removed: 2020.](https://www.sec.gov/Archives/edgar/data/906107/000156459020035511/eqr-ex101_104.htm)] [added: 2005.](https://www.sec.gov/Archives/edgar/data/906107/000110465908031090/a08-13376_1ex10d2.htm)] | | Included as Exhibit [removed: 10.1] [added: 10.2] to Equity Residential's [removed: and ERP Operating Limited Partnership's] Form 10-Q for the quarterly period ended [removed: June 30, 2020.] [added: March 31, 2008.] |
| 10.24 | [removed: *] | [removed: [Amendment to the Equity Residential Supplemental Executive Retirement Plan, effective as of October 1, 2022.](https://www.sec.gov/Archives/edgar/data/906107/000095017022020464/eqr-ex10_1.htm)] [added: [Distribution Agreement, dated May 18, 2022.](https://www.sec.gov/Archives/edgar/data/906107/000119312522153674/d341831dex11.htm)] | | Included as Exhibit [removed: 10.1] [added: 1.1] to Equity Residential's and ERP Operating Limited Partnership's Form [removed: 10-Q for the quarterly period ended September 30,] [added: 8-K dated and filed on May 18,] 2022. |
| [removed: 10.26] [added: 10.25] | | [removed: [Distribution Agreement, dated May 18, 2022.](https://www.sec.gov/Archives/edgar/data/906107/000119312522153674/d341831dex11.htm)] [added: [Form of Master Forward Sale Confirmation.](https://www.sec.gov/Archives/edgar/data/906107/000119312522153674/d341831dex12.htm)] | | Included as Exhibit [removed: 1.1] [added: 1.2] to Equity Residential's and ERP Operating Limited Partnership's Form 8-K dated and filed on May 18, 2022. |
| 10.27 | | [removed: [Form of Master Forward Sale Confirmation.](https://www.sec.gov/Archives/edgar/data/906107/000119312522153674/d341831dex12.htm)] [added: [Archstone Parallel Residual JV, LLC Limited Liability Company Agreement.](https://www.sec.gov/Archives/edgar/data/906107/000119312513084766/d491312dex104.htm)] | | Included as Exhibit [removed: 1.2] [added: 10.4] to Equity Residential's and ERP Operating Limited Partnership's Form 8-K dated [removed: and] [added: February 27, 2013,] filed on [removed: May 18, 2022.] [added: February 28, 2013.] |
| [removed: 10.28] [added: 10.26] | | [Archstone Residual JV, LLC Limited Liability Company Agreement.](https://www.sec.gov/Archives/edgar/data/906107/000119312513084766/d491312dex103.htm) | | Included as Exhibit 10.3 to Equity Residential's and ERP Operating Limited Partnership's Form 8-K dated February 27, 2013, filed on February 28, 2013. |
| [removed: 10.29] [added: 10.28] | | [Archstone Parallel Residual [removed: JV,] [added: JV 2,] LLC Limited Liability Company [removed: Agreement.](https://www.sec.gov/Archives/edgar/data/906107/000119312513084766/d491312dex104.htm)] [added: Agreement.](https://www.sec.gov/Archives/edgar/data/906107/000119312513084766/d491312dex105.htm)] | | Included as Exhibit [removed: 10.4] [added: 10.5] to Equity Residential's and ERP Operating Limited Partnership's Form 8-K dated February 27, 2013, filed on February 28, 2013. |
| [removed: 10.30] [added: 10.29] | | [removed: [Archstone Parallel Residual JV 2,] [added: [Legacy Holdings JV,] LLC Limited Liability Company [removed: Agreement.](https://www.sec.gov/Archives/edgar/data/906107/000119312513084766/d491312dex105.htm)] [added: Agreement.](https://www.sec.gov/Archives/edgar/data/906107/000119312513084766/d491312dex106.htm)] | | Included as Exhibit [removed: 10.5] [added: 10.6] to Equity Residential's and ERP Operating Limited Partnership's Form 8-K dated February 27, 2013, filed on February 28, 2013. |
| 21 | | [List of Subsidiaries of Equity Residential and ERP Operating Limited [removed: Partnership.](https://www.sec.gov/Archives/edgar/data/906107/000095017023003060/eqr-ex21.htm)] [added: Partnership.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex21.htm)] | | Attached herein. |
| 23.1 | | [Consent of Ernst & Young LLP - Equity [removed: Residential.](https://www.sec.gov/Archives/edgar/data/906107/000095017023003060/eqr-ex23_1.htm)] [added: Residential.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex23_1.htm)] | | Attached herein. |
| 23.2 | | [Consent of Ernst & Young LLP - ERP Operating Limited [removed: Partnership.](https://www.sec.gov/Archives/edgar/data/906107/000095017023003060/eqr-ex23_2.htm)] [added: Partnership.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex23_2.htm)] | | Attached herein. |
| 31.1 | | [Equity Residential - Certification of Mark J. Parrell, Chief Executive [removed: Officer.](https://www.sec.gov/Archives/edgar/data/906107/000095017023003060/eqr-ex31_1.htm)] [added: Officer.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex31_1.htm)] | | Attached herein. |
| 31.2 | | [Equity Residential - Certification of Robert A. Garechana, Chief Financial [removed: Officer.](https://www.sec.gov/Archives/edgar/data/906107/000095017023003060/eqr-ex31_2.htm)] [added: Officer.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex31_2.htm)] | | Attached herein. |
| 31.3 | | [ERP Operating Limited Partnership - Certification of Mark J. Parrell, Chief Executive Officer of Registrant's General [removed: Partner.](https://www.sec.gov/Archives/edgar/data/906107/000095017023003060/eqr-ex31_3.htm)] [added: Partner.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex31_3.htm)] | | Attached herein. |
| 31.4 | | [ERP Operating Limited Partnership - Certification of Robert A. Garechana, Chief Financial Officer of Registrant's General [removed: Partner.](https://www.sec.gov/Archives/edgar/data/906107/000095017023003060/eqr-ex31_4.htm)] [added: Partner.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex31_4.htm)] | | Attached herein. |
| 32.1 | | [Equity Residential - Certification Pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002, of Mark J. Parrell, Chief Executive Officer of the [removed: Company.](https://www.sec.gov/Archives/edgar/data/906107/000095017023003060/eqr-ex32_1.htm)] [added: Company.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex32_1.htm)] | | Attached herein. |
| 32.2 | | [Equity Residential - Certification Pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002, of Robert A. Garechana, Chief Financial Officer of the [removed: Company.](https://www.sec.gov/Archives/edgar/data/906107/000095017023003060/eqr-ex32_2.htm)] [added: Company.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex32_2.htm)] | | Attached herein. |
| 32.3 | | [ERP Operating Limited Partnership - Certification Pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002, of Mark J. Parrell, Chief Executive Officer of Registrant's General [removed: Partner.](https://www.sec.gov/Archives/edgar/data/906107/000095017023003060/eqr-ex32_3.htm)] [added: Partner.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex32_3.htm)] | | Attached herein. |
| 32.4 | | [ERP Operating Limited Partnership - Certification Pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002, of Robert A. Garechana, Chief Financial Officer of Registrant's General [removed: Partner.](https://www.sec.gov/Archives/edgar/data/906107/000095017023003060/eqr-ex32_4.htm)] [added: Partner.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex32_4.htm)] | | Attached herein. |
| 101.SCH | | Inline XBRL Taxonomy Extension Schema [removed: Document.] [added: With Embedded Linkbase Documents.] | | |
| | | Date: | | February [removed: 16, 2023] [added: 15, 2024] |
Kaufman, or any of them, his or her attorneys-in-fact and agents, with full power of substitution and resubstitution for him or her in any and all capacities, to do all acts and things which said attorneys and agents, or any of them, deem advisable to enable the company to comply with the Securities Exchange Act of 1934, as amended, and any requirements or regulations of the Securities and Exchange Commission in respect thereof, in connection with the company’s filing of an annual report on Form 10-K for the company’s fiscal year [removed: 2022,] [added: 2023,] including specifically, but without limitation of the general authority hereby granted, the power and authority to sign his or her name as a trustee or officer, or both, of the company, as indicated below opposite his or her signature, to the Form 10-K, and any amendment thereto; and each of the undersigned does hereby fully ratify and confirm all that said attorneys and agents, or any of them, or the substitute of any of them, shall do or cause to be done by virtue hereof.
| /s/ Mark J. Parrell | | President, Chief Executive Officer and Trustee | | February [removed: 16, 2023] [added: 15, 2024] |
| /s/ Robert A. Garechana | | Executive Vice President and Chief Financial Officer | | February [removed: 16, 2023] [added: 15, 2024] |
| /s/ Ian S. Kaufman | | Senior Vice President and Chief Accounting Officer | | February [removed: 16, 2023] [added: 15, 2024] |
| /s/ Angela M. Aman | | Trustee | | February [removed: 16, 2023] [added: 15, 2024] |
| /s/ Linda Walker Bynoe | | Trustee | | February [removed: 16, 2023] [added: 15, 2024] |
| /s/ Mary Kay Haben | | Trustee | | February [removed: 16, 2023] [added: 15, 2024] |
| /s/ T. Zia Huque | | Trustee | | February [removed: 16, 2023] [added: 15, 2024] |
| 3.6 | | [Form of Preference Unit Term Sheet for 3.00% Series Q Cumulative Redeemable Preference Units.](https://www.sec.gov/ix?doc=/Archives/edgar/data/931182/000095017023013492/ck0000931182-20230413.htm) | | Included as Exhibit 3.1 to ERP Operating Limited Partnership's Form 8-K dated April 13, 2023, filed on April 19, 2023. |
| 97 | | [Incentive-Based Compensation Clawback Policy.](https://www.sec.gov/Archives/edgar/data/906107/000095017024015907/eqr-ex97.htm) | | Attached herein. |
| | | Date: | | February 15, 2024 |
| February 15, 2024 | | |
| February 15, 2024 | | |
| February 15, 2024 | | |
| February 15, 2024 | | |
| Cash and cash equivalents | | | 50,743 | | | | 53,869 | |
| Accounts payable and accrued expenses | | | 104,430 | | | | 96,028 | |
| Net income | | $ | 868,488 | | | $ | 806,995 | | | $ | 1,396,714 | |
| Depreciation | | | 888,709 | | | | 882,168 | | | | 838,272 | |
| Unrealized (gain) loss on investment securities | | | (13,466 | ) | | | — | | | | — | |
| Consolidation of previously unconsolidated entities | | | 2,108 | | | | — | | | | — | |
| Proceeds from (payments on) settlement of derivative instruments | | | 25,169 | | | | — | | | | — | |
| Common Shares repurchased and retired | | | (49,105 | ) | | | — | | | | — | |
| Cash and cash equivalents and restricted deposits, end of year | | $ | 139,995 | | | $ | 137,172 | | | $ | 360,236 | |
| *Real estate acquisitions/dispositions/other:* | | | | | | | | | | | | |
| Mortgage loans assumed | | $ | 42,256 | | | $ | — | | | $ | — | |
| *Consolidation of previously unconsolidated entities:* | | | | | | | | | | | | |
| Investment in real estate, net | | $ | (50,315 | ) | | $ | — | | | $ | — | |
| Investments in unconsolidated entities | | $ | 46,327 | | | $ | — | | | $ | — | |
| Other liabilities | | $ | 2,000 | | | $ | — | | | $ | — | |
| Noncontrolling Interests – Partially Owned Properties | | $ | 4,021 | | | $ | — | | | $ | — | |
| Other assets | | $ | 25,613 | | | $ | — | | | $ | — | |
| Other liabilities | | $ | (444 | ) | | $ | — | | | $ | — | |
EQUITY RESIDENTIAL
| Common Shares repurchased and retired | | | (9 | ) | | | — | | | | — | |
| Net income attributable to controlling interests | | | 835,438 | | | | 776,911 | | | | 1,332,850 | |
| Common Shares repurchased and retired | | | (49,096 | ) | | | — | | | | — | |
| Unrealized holding gains (losses) arising during the year | | | 4,514 | | | | 20,654 | | | | — | |
| Losses reclassified into earnings from other comprehensive income | | | 3,737 | | | | 11,071 | | | | 9,394 | |
| Balance, end of year | | $ | 202,306 | | | $ | 209,961 | | | $ | 214,094 | |
| Consolidation of previously unconsolidated entities | | | 4,021 | | | | — | | | | — | |
| Land | | $ | 5,581,876 | | | $ | 5,580,878 | |
| Depreciable property | | | 22,938,426 | | | | 22,334,369 | |
| Projects under development | | | 78,036 | | | | 112,940 | |
| Land held for development | | | 114,300 | | | | 60,567 | |
| Investment in real estate | | | 28,712,638 | | | | 28,088,754 | |
| Accumulated depreciation | | | (9,810,337 | ) | | | (9,027,850 | ) |
| Cash and cash equivalents | | | 50,743 | | | | 53,869 | |
| | | | | |
| --- | --- | --- | --- | --- |
| 10.25 | * | [The Equity Residential Grandfathered Supplemental Executive Retirement Plan as Amended and Restated effective January 1, 2005.](https://www.sec.gov/Archives/edgar/data/906107/000110465908031090/a08-13376_1ex10d2.htm) | | Included as Exhibit 10.2 to Equity Residential's Form 10-Q for the quarterly period ended March 31, 2008. |
| 10.31 | | [Legacy Holdings JV, LLC Limited Liability Company Agreement.](https://www.sec.gov/Archives/edgar/data/906107/000119312513084766/d491312dex106.htm) | | Included as Exhibit 10.6 to Equity Residential's and ERP Operating Limited Partnership's Form 8-K dated February 27, 2013, filed on February 28, 2013. |
| 101.CAL | | Inline XBRL Taxonomy Extension Calculation Linkbase Document. | | |
| 101.DEF | | Inline XBRL Taxonomy Extension Definition Linkbase Document. | | |
| 101.LAB | | Inline XBRL Taxonomy Extension Label Linkbase Document. | | |
| 101.PRE | | Inline XBRL Taxonomy Extension Presentation Linkbase Document. | | |
| /s/ David J. Neithercut | | Trustee | | February 16, 2023 |
| Samuel Zell | | | | |
| February 16, 2023 | | |
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Net (gain) loss on debt extinguishment | | | — | | | | — | | | | 26,150 | |
| Realized/unrealized (gain) loss on derivative instruments | | | — | | | | — | | | | 50 | |
| Net gain (loss) on debt extinguishment | | | — | | | | — | | | | (327 | ) |
| Net gain (loss) on debt extinguishment | | | — | | | | — | | | | (25,823 | ) |
| | | | 308 | | | | 79,597 | |
taxes.
The Coronavirus Aid, Relief, and Economic Security Act (the “CARES Act”) included tax provisions which increased allowable interest expense deductions for 2020 (no increases for 2021 and 2022) and increased the ability for taxpayers to use net operating losses.
These provisions did not result in a material impact to the Company’s taxable income or tax liabilities.
The CARES Act also allowed corporations to request accelerated refunds of their alternative minimum tax (“AMT”) credit.
Prior to enactment of this provision, the remaining credits would have been refunded in installments in 2020, 2021 and 2022.
We received a refund of our remaining $1.6 million in AMT credits during the year ended December 31, 2020.
(1)
(2)
In April 2020, a FASB staff question and answer document was issued which intended to reduce the challenges of evaluating the enforceable rights and obligations of leases for concessions granted to lessees in response to the COVID-19 pandemic.
We elected not to evaluate whether qualifying concessions provided by the Company in response to the COVID-19 pandemic are a lease modification, subject to the criteria that the total payments under the amended lease cannot result in a substantial increase in the rights of the lessor or obligations of the lessee.
We also elected to treat the concessions as though they were contemplated as part of the existing contracts and therefore will not apply lease modification rules to the qualifying lease concession amendments.
As such, deferrals deemed collectible are recorded as rental receivables with no change to timing of rental revenues and deferrals deemed non-collectible and abatements reduce rental revenues in the deferral/abatement period and cause rental revenues to effectively follow a cash basis related to the changes.
The accounting elections provided by the FASB mainly apply to the Company’s non-residential leases and the majority of the amendments will not require a straight-line adjustment.
In June 2016, the FASB issued a standard which requires companies to adopt a new approach for estimating credit losses on certain types of financial instruments, such as trade and other receivables and loans.
The standard requires entities to estimate a lifetime expected credit loss for most financial instruments, including trade receivables.
In November 2018, the FASB issued an amendment excluding operating lease receivables accounted for under the lease standard from the scope of the credit losses standard.
| Limited Partner Units outstanding at January 1, | | | 12,659,027 | | | | 13,858,073 | | | | 13,731,315 | |
The Company may repurchase up to 13.0 million Common Shares under its share repurchase program.
No open market repurchases have occurred since 2008.
Purchase price includes an allocation of approximately $25.3 million to land and $87.7 million to depreciable property (inclusive of capitalized closing costs).
| Total | | | 17 | | | | 4,747 | | | $ | 1,709,379 | |
Purchase price includes an allocation of approximately $226.3 million to land and $1.5 billion to depreciable property (inclusive of capitalized closing costs).
An excerpt. Shown here: 40 of 701 rewritten, 40 of 751 added and 40 of 453 removed. The counts are complete. For every sentence, read Item 16. Form 10-K Summary in the FY2023 filing and the FY2022 filing.