 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
81K characters. Original on sec.gov · Markdown
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
OVERVIEW
We invest in scientific innovation to create transformative medicines for people with serious diseases with a focus on specialty markets. We have four approved medicines to treat cystic fibrosis, or CF, a life-threatening genetic disease, and we are focused on increasing the number of patients eligible and able to receive our current medicines through label expansions, approval of new medicines and expanded reimbursement. We are broadening our pipeline into additional disease areas through internal research efforts and accessing external innovation through business development transactions.
Our triple combination regimen, TRIKAFTA/KAFTRIO, was approved in 2019 in the United States, or U.S., and in 2020 in the European Union, or E.U. Collectively, our four medicines are approved to treat the majority of the approximately 83,000 people with CF in North America, Europe and Australia. We are evaluating our medicines, including our triple combination regimen, in additional patient populations, including younger children, with the goal of having small molecule treatments for up to 90% of people with CF. We are also pursuing genetic therapies to address the remaining 10% of people with CF.
Beyond CF, our small molecule programs include programs focused on developing treatments for alpha-1 antitrypsin, or AAT, deficiency, APOL1-mediated kidney diseases and pain. We are also focused on developing cell and genetic therapies for various diseases in our pipeline. We are evaluating CTX001, a genetic therapy, as a potential treatment for sickle cell disease, or SCD, and transfusion-dependent beta thalassemia, or TDT, in Phase 1/2 clinical trials in collaboration with CRISPR Therapeutics AG, or CRISPR. In T1D, we are pursuing two programs for the transplant of functional islets into patients: transplantation of islet cells alone, using immunosuppression to protect the implanted cells, and implantation of the islet cells inside a novel immunoprotective device. In 2020, we continued to advance our cell and genetic therapy pipeline programs through internal research efforts and investing in business development transactions to access emerging technologies.
Financial Highlights
Revenues
In 2020, our net product revenues continued to increase due to the approval of TRIKAFTA in late 2019 and uptake of our medicines in ex-U.S. markets following the approval of KAFTRIO and completion of several significant reimbursement agreements.
Expenses
Our total R&D and SG&A expenses increased from $2.41 billion in 2019 to $2.60 billion in 2020. In 2020, cost of sales was approximately 12% of our net product revenues.

Business Updates
Cystic Fibrosis
We expect to continue to grow our CF business through increasing the number of people with CF eligible and able to receive our medicines and providing improved treatment options for people who are already eligible for one of our medicines. Since the beginning of 2020, we have made important progress in activities supporting these efforts.
-
In August, the European Commission granted marketing authorization for KAFTRIO to treat people with CF 12 years of age and older with one F508del mutation and one minimal function mutation, or two F508del mutations.
-
The FDA expanded the eligibility for TRIKAFTA to include people with CF 12 years of age and older with certain mutations that are responsive to TRIKAFTA based on in vitro data. SYMDEKO and KALYDECO also received approvals to include additional responsive mutations in people with CF 6 years of age and older and 4 months of age and older, respectively.
-
In January 2021, the FDA accepted our supplemental New Drug Application, or sNDA, for TRIKAFTA for the treatment of children with CF 6 to 11 years of age with at least one F508del mutation or have certain mutations that are responsive to TRIKAFTA based on in vitro data. The FDA granted Priority Review of the sNDA.
-
The European Commission approved the label extension of SYMKEVI in combination with KALYDECO for the treatment of children with CF 6 years of age and older with two F508del mutations or one F508del mutation and certain residual function mutations.
-
The FDA approved KALYDECO for treatment of infants with CF four months of age and older who have at least one mutation in their CFTR gene that is responsive to KALYDECO.
-
The European Commission approved KALYDECO for treatment of infants with CF four months of age and older who have the R117H mutation or certain gating mutations.
Pipeline
We continue to advance a broad pipeline of potentially transformative small molecule, cell and genetic therapies aimed at treating serious diseases. Since the beginning of 2020, we have made important progress in activities supporting these efforts.
Beta Thalassemia and Sickle Cell Disease
*•*In December, we and our collaborator, CRISPR, announced positive interim data from 10 people with TDT or SCD treated with CTX001 and that 20 people with severe hemoglobinopathies have been dosed with CTX001 in the ongoing Phase 1/2 clinical trials. Enrollment and dosing are ongoing, and completion of enrollment in both clinical trials is expected in 2021.
Alpha-1 Antitrypsin Deficiency
-
Enrollment is ongoing in a Phase 2 proof-of-concept clinical trial for the corrector VX-864. We expect data from this clinical trial in the first half of 2021.
-
We discontinued development of VX-814, our first corrector, based on the safety and pharmacokinetic profile of VX-814 observed in a Phase 2 clinical trial.
APOL1-Mediated Kidney Diseases
- Enrollment is ongoing in a Phase 2 proof-of-concept clinical trial designed to evaluate the reduction of proteinuria in people with APOL1-mediated FSGS after treatment with VX-147. We expect data from this clinical trial in 2021.
Type 1 Diabetes
- We are developing a cell therapy designed to replace insulin-producing islet cells in patients with T1D. We are pursuing two programs for the transplant of these functional islets into patients: transplantation of islet cells alone,
using immunosuppression to protect the implanted cells, and implantation of the islet cells inside a novel immunoprotective device.
- In January 2021, the FDA cleared our IND for VX-880, the islet cells alone program. We expect to initiate a Phase 1/2 clinical trial evaluating this program in the first half of 2021. This clinical trial will involve an infusion of fully differentiated, functional islet cells, and chronic administration of concomitant immunosuppressive therapy, to protect the islet cells from immune rejection.
Investment in External Innovation
-
We entered into a collaboration with Skyhawk Therapeutics, Inc., or Skyhawk, for the discovery and development of novel small molecules that modulate RNA splicing for the treatment of serious diseases.
-
We entered into a new collaboration with Moderna, Inc., or Moderna, aimed at the discovery and development of lipid nanoparticles and mRNAs that can deliver gene-editing therapies to lung cells for the treatment of CF.
*•*We entered into a collaboration with Affinia Therapeutics, Inc., or Affinia, to gain access to a novel library of AAV capsids to support on our ongoing research and development efforts in genetic therapies, including DMD, DM1 and CF.
COVID-19
We continue to monitor the impacts of the COVID-19 global pandemic on our business. COVID-19 has not affected our supply chain or the demand for our medicines, and we believe that we will be able to continue to supply all of our approved medicines to patients globally. We have adjusted our business operations in response to COVID-19, with a majority of our employees continuing to work remotely. We continue to monitor local COVID-19 trends and government guidance for each of our site locations, and are utilizing a phased, site-specific approach to assess employee access to our sites. Currently, all of our research and manufacturing sites are open to essential employees. To provide a safe working environment for our on-site employees, we have, among other things, limited employee numbers at our open sites and increased safety measures, including at home and on-site testing in the U.S., enhanced cleaning and sanitation protocols, required use of personal protective equipment for all on-site employees, hand sanitation stations throughout our open sites and implementation of various social distancing measures while on-site.
Research
We continue to invest in our research programs and foster scientific innovation in order to identify and develop transformative medicines. Our strategy is to combine transformative advances in the understanding of human disease and the science of therapeutics in order to identify and develop new medicines. We believe that pursuing innovative approaches to treat diverse diseases of great unmet need allows us to balance the risks inherent in drug development and may provide drug candidates that will form our pipeline in future years. To supplement our internal research programs, we acquire technologies and programs and collaborate with biopharmaceutical and technology companies, leading academic research institutions, government laboratories, foundations and other organizations, as needed, to advance research in our areas of therapeutic interest and to access technologies needed to execute on our strategy.
Drug Discovery and Development
Discovery and development of a new pharmaceutical product is a difficult and lengthy process that requires significant financial resources along with extensive technical and regulatory expertise. Potential drug candidates are subjected to rigorous evaluations, driven in part by stringent regulatory considerations, designed to generate information concerning efficacy, side effects, proper dosage levels and a variety of other physical and chemical characteristics that are important in determining whether a drug candidate should be approved for marketing as a pharmaceutical product. Most chemical compounds that are investigated as potential drug candidates never progress into development, and most drug candidates that do advance into development never receive marketing approval. Because our investments in drug candidates are subject to considerable risks, we closely monitor the results of our discovery, research, clinical trials and nonclinical studies and frequently evaluate our drug development programs in light of new data and scientific, business and commercial insights, with the objective of balancing risk and potential. This process can result in rapid changes in focus and priorities as new information becomes available and as we gain additional understanding of our ongoing programs and potential new programs, as well as those of our competitors. For example, in October 2020, we discontinued development of VX-814, a
drug candidate for the treatment of AAT, based on the safety and pharmacokinetic profile of VX-814 observed in a Phase 2 clinical trial.
If we believe that data from a completed registration program support approval of a drug candidate, we submit an NDA or BLA to the FDA requesting approval to market the drug candidate in the U.S. and seek analogous approvals from comparable regulatory authorities in jurisdictions outside the U.S. To obtain approval, we must, among other things, demonstrate with evidence gathered in nonclinical studies and well-controlled clinical trials that the drug candidate is safe and effective for the disease it is intended to treat and that the manufacturing facilities, processes and controls for the manufacture of the drug candidate are adequate. The FDA and ex-U.S. regulatory authorities have substantial discretion in deciding whether or not a drug candidate should be granted approval based on the benefits and risks of the drug candidate in the treatment of a particular disease, and could delay, limit or deny regulatory approval. If regulatory delays are significant or regulatory approval is limited or denied altogether, our financial results and the commercial prospects for the drug candidate involved will be harmed.
Regulatory Compliance
Our marketing of pharmaceutical products is subject to extensive and complex laws and regulations. We have a corporate compliance program designed to actively identify, prevent and mitigate risk through the implementation of compliance policies and systems and through the promotion of a culture of compliance. Among other laws, regulations and standards, we are subject to various U.S. federal and state laws, and comparable laws in other jurisdictions, pertaining to health care fraud and abuse, including anti-kickback and false claims laws, and laws prohibiting the promotion of drugs for unapproved or off-label uses. Anti-kickback laws generally make it illegal for a prescription drug manufacturer to knowingly and willfully solicit, offer, receive or pay any remuneration in return for or to induce the referral of business, including the purchase or prescription of a particular drug that is reimbursed by a state or federal health care program. False claims laws prohibit anyone from knowingly or willfully presenting for payment to third-party payors, including Medicare and Medicaid, claims for reimbursed drugs or services that are false or fraudulent, claims for items or services not provided as claimed, or claims for medically unnecessary items or services. We are subject to laws and regulations that regulate the sales and marketing practices of pharmaceutical manufacturers, as well as laws such as the U.S. Foreign Corrupt Practices Act, which govern our international business practices with respect to payments to government officials. In addition, we are subject to various data protection and privacy laws and regulations in the U.S., E.U., U.K., Canada, Australia and other jurisdictions. We expect to continue to devote substantial resources to maintain, administer and expand these compliance programs globally.
Reimbursement
Sales of our products depend, to a large degree, on the extent to which our products are reimbursed by third-party payors, such as government health programs, commercial insurance and managed health care organizations. We dedicate substantial management and other resources in order to obtain and maintain appropriate levels of reimbursement for our products from third-party payors, including governmental organizations in the U.S. and ex-U.S. markets.
In the U.S., we have worked successfully with third party payors in order to promptly obtain appropriate levels of reimbursement for our CF medicines. We plan to continue to engage in discussions with numerous commercial insurers and managed health care organizations, along with government health programs that are typically managed by authorities in the individual states, to ensure that payors recognize the significant benefits that our medicines provide by treating the underlying cause of CF and continue to provide access to our medicines.
In Europe and other ex-U.S. markets, we seek government reimbursement for our medicines on a country-by-country basis. This is necessary for each new medicine, as well as label expansions for our current medicines. We successfully obtained reimbursement for KALYDECO in each significant ex-U.S. market within two years of approval, but experienced significant challenges in obtaining reimbursement for ORKAMBI in certain ex-U.S. markets. With the completion of reimbursement discussions in England and France in 2019, we have reimbursement for ORKAMBI or SYMKEVI in most of our significant ex-U.S. markets. In addition, in several ex-U.S. markets, including England, Ireland, Denmark and Australia, our reimbursement agreements include innovative arrangements that provide a pathway to access and rapid reimbursement for certain future CF medicines. For example, our existing reimbursement agreements in England, Ireland, and Denmark have been expanded to include KAFTRIO. We expect to continue to focus significant resources to obtain appropriate reimbursement for our products in ex-U.S. markets.
Strategic Transactions
Acquisitions
As part of our business strategy, we seek to acquire drugs, drug candidates and other technologies and businesses that have the potential to complement our ongoing research and development efforts. In 2019, we invested significantly in business development transactions designed to augment our pipeline, including the acquisition of Semma Therapeutics, Inc., or Semma, a privately-held company focused on the use of stem cell-derived human islets as a potentially curative treatment for T1D, and Exonics Therapeutics, Inc., or Exonics, a privately-held company focused on creating transformative gene-editing therapies to repair mutations that cause DMD and other severe neuromuscular diseases, including DM1. In the Semma acquisition, we paid approximately $950.0 million in cash to Semma equity holders. In the Exonics acquisition, we paid approximately $245.0 million upfront to Exonics equity holders and agreed to additional payments based upon successful achievement of specified development and regulatory milestones. We expect to continue to identify and evaluate potential acquisitions and may include larger transactions or later stage assets.
Both of our 2019 acquisitions were accounted for as business combinations. As of the acquisition date for each transaction, the cash payments, as well as the fair value of contingent consideration for Exonics, were allocated primarily to goodwill and the fair value of several in-process research and development assets that we acquired. The fair value of contingent consideration related to Exonics was recorded as a liability and continues to be adjusted on a quarterly basis. As a result, these acquisitions are primarily reflected in additional assets and liabilities on our consolidated balance sheet. Operating expenses incurred by Exonics and Semma after the acquisition dates and specific expenses associated with the acquisitions are reflected in our consolidated statement of operations.
Please refer to our critical accounting policies, “Acquisitions,” for further information regarding the significant judgments and estimates related to our acquisitions.
Collaboration and Licensing Arrangements
We enter into arrangements with third parties, including collaboration and licensing arrangements, for the development, manufacture and commercialization of drugs, drug candidates and other technologies that have the potential to complement our ongoing research and development efforts. We expect to continue to identify and evaluate collaboration and licensing opportunities that may be similar to or different from the collaborations and licenses that we have engaged in previously.
In-License Agreements
We have entered into collaborations with biotechnology and pharmaceutical companies in order to acquire rights or to license drug candidates or technologies that enhance our pipeline and/or our research capabilities. Over the last several years, we entered into collaboration agreements with a number of companies, including Affinia, Arbor Biotechnologies, Inc., CRISPR, Kymera Therapeutics, Inc., Moderna, Molecular Templates, Inc. and Skyhawk. Generally, when we in-license a technology or drug candidate, we make upfront payments to the collaborator, assume the costs of the program and/or agree to make contingent payments, which could consist of milestone, royalty and option payments. Most of these collaboration payments are expensed as research and development expenses; however, depending on many factors, including the structure of the collaboration, the significance of the in-licensed drug candidate to the collaborator’s operations and the other activities in which our collaborators are engaged, the accounting for these transactions can vary significantly. Our research and development expenses included $184.6 million in 2020, $318.3 million in 2019 and $111.9 million in 2018 related to upfront and milestone payments pursuant to our collaboration agreements.
Out-License Agreements
We also have out-licensed internally-developed programs to collaborators who are leading the development of these programs. These out-license arrangements include our agreement with Merck KGaA, Darmstadt, Germany, which licensed oncology research and development programs from us in early 2017. Pursuant to these out-licensing arrangements, our collaborators are responsible for the research, development and commercialization costs associated with these programs, and we are entitled to receive contingent milestone and/or royalty payments. As a result, we do not expect to incur significant expenses in connection with these programs and have the potential for future collaborative and royalty revenues resulting from these programs.
Please refer to Note B, “Collaborative Arrangements,” for further information regarding our in-license agreements and out-license agreements.
Strategic Investments
In connection with our business development activities, we have periodically made equity investments in our collaborators. As of December 31, 2020, we held strategic equity investments in several public companies and certain private companies, and we plan to make additional strategic equity investments in the future. While we invest the majority of our cash, cash equivalents and marketable securities in instruments that meet specific credit quality standards and limit our exposure to any one issue or type of instrument, our strategic investments are maintained and managed separately from our other cash, cash equivalents and marketable securities. Any changes in the fair value of equity investments with readily determinable fair values (including publicly traded securities) are recorded to other income (expense), net in our consolidated statement of operations.
In 2020, 2019 and 2018, we recorded within other income (expense), net gains of $311.9 million, $197.6 million and $2.6 million, respectively, related to changes in the fair value of our strategic investments and from sales of certain investments. As of December 31, 2020, the fair value of our investments in publicly traded companies was $195.8 million. To the extent that we continue to hold strategic investments, particularly strategic investments in publicly traded companies, we will record other income (expense) related to these strategic investments on a quarterly basis. Due to the increased volatility of the global markets, including as a result of COVID-19, and the high volatility of stocks in the biotechnology industry, we expect the value of these strategic investments to fluctuate and that the increases or decreases in the fair value of these strategic investments will continue to have material impacts on our net income (expense) and our profitability on a quarterly and/or annual basis.
RESULTS OF OPERATIONS
| 2020/2019 Comparison | 2019/2018 Comparison | ||||||||||||||||||||||||||||||||||||||||
| Increase/(Decrease) | Increase/(Decrease) | ||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | |||||||||||||||||||||||||||||||||||
| (in thousands, except percentages and per share amounts) | |||||||||||||||||||||||||||||||||||||||||
| Revenues | $ | 6,205,683 | $ | 4,162,821 | $ | 3,047,597 | $ | 2,042,862 | 49 | % | $ | 1,115,224 | 37 | % | |||||||||||||||||||||||||||
| Operating costs and expenses | 3,349,393 | 2,965,255 | 2,412,447 | 384,138 | 13 | % | 552,808 | 23 | % | ||||||||||||||||||||||||||||||||
| Income from operations | 2,856,290 | 1,197,566 | 635,150 | 1,658,724 | 139 | % | 562,416 | 89 | % | ||||||||||||||||||||||||||||||||
| Other non-operating income (expense), net | 260,508 | 197,353 | (25,116) | 63,155 | 32 | % | ** | ** | |||||||||||||||||||||||||||||||||
| Provision for (benefit from) income taxes | 405,151 | 218,109 | (1,486,862) | 187,042 | 86 | % | ** | ** | |||||||||||||||||||||||||||||||||
| Net income attributable to Vertex | $ | 2,711,647 | $ | 1,176,810 | $ | 2,096,896 | $ | 1,534,837 | 130 | % | $ | (920,086) | ** | ||||||||||||||||||||||||||||
| Net income per diluted share attributable to Vertex common shareholders | $ | 10.29 | $ | 4.51 | $ | 8.09 | |||||||||||||||||||||||||||||||||||
| Diluted shares used in per share calculations | 263,396 | 260,673 | 259,185 | ||||||||||||||||||||||||||||||||||||||
| ** Not meaningful |
Net Income Attributable to Vertex
Our net income attributable to Vertex increased to $2.71 billion in 2020 as compared to $1.18 billion in 2019 primarily due to increased revenues and increased other income (expense) related to our strategic investments partially offset by increased operating costs and expenses and an increased provision for income taxes. The increased revenues were primarily due to the U.S. approval of TRIKAFTA in the fourth quarter of 2019, E.U. approval of KAFTRIO in the third quarter of 2020 and continued uptake of our medicines in ex-U.S. markets. The increased operating costs and expenses were primarily due to increased cost of sales consistent with increased net product revenues, increased investment in research and development and increased sales, general and administrative expenses to support our business.
Net income attributable to Vertex in 2018 included a one-time non-cash benefit from income taxes of $1.56 billion resulting from our release of our valuation allowance. Net income attributable to Vertex decreased in 2019 as compared to 2018 as a result of this one-time tax benefit and increased operating costs and expenses. The increases in operating costs and expenses were primarily due to increased cost of sales due to increased net product revenues and increased research expenses associated with our business development activities. These decreases in our net income in 2019 as compared to 2018 were partially offset by increased net product revenues and increased gains recorded to other income (expense) related to our strategic investments.
Earnings Per Share
In 2020, 2019, and 2018, net income attributable to Vertex was $10.29, $4.51 and $8.09, respectively, per diluted share. In 2018, the benefit from income taxes as a result of the release of our valuation allowance increased net income attributable to Vertex by $6.03 per diluted share.
Revenues
| 2020/2019 Comparison | 2019/2018 Comparison | ||||||||||||||||||||||||||||||||||||||||
| Increase/(Decrease) | Increase/(Decrease) | ||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | |||||||||||||||||||||||||||||||||||
| (in thousands, except percentages) | |||||||||||||||||||||||||||||||||||||||||
| Product revenues, net | $ | 6,202,783 | $ | 4,160,726 | $ | 3,038,325 | $ | 2,042,057 | 49 | % | $ | 1,122,401 | 37 | % | |||||||||||||||||||||||||||
| Collaborative and royalty revenues | 2,900 | 2,095 | 9,272 | 805 | 38 | % | (7,177) | (77) | % | ||||||||||||||||||||||||||||||||
| Total revenues | $ | 6,205,683 | $ | 4,162,821 | $ | 3,047,597 | $ | 2,042,862 | 49 | % | $ | 1,115,224 | 37 | % |
Product Revenues, Net
| 2020 | 2019 | 2018 | |||||||||||||||
| (in thousands) | |||||||||||||||||
| TRIKAFTA/KAFTRIO | $ | 3,863,824 | $ | 420,105 | $ | — | |||||||||||
| SYMDEKO/SYMKEVI | 628,577 | 1,417,668 | 768,657 | ||||||||||||||
| ORKAMBI | 907,512 | 1,331,891 | 1,262,166 | ||||||||||||||
| KALYDECO | 802,870 | 991,062 | 1,007,502 | ||||||||||||||
| Product revenues, net | $ | 6,202,783 | $ | 4,160,726 | $ | 3,038,325 |
In 2020, our net product revenues increased by $2.04 billion as compared to 2019. In 2019, our net product revenues increased by $1.12 billion as compared to 2018. The increase in total net product revenues in 2020 was primarily due to the launch of TRIKAFTA in the U.S in the fourth quarter of 2019 and KAFTRIO in the E.U. in the third quarter of 2020. Decreases in revenues for our other products were the result of patients in the U.S. switching from these medicines to TRIKAFTA, partially offset by label expansions and expanded access to our medicines in ex-U.S. markets. The increase in total net product revenues in 2019 was primarily due to the increasing number of patients being treated with SYMDEKO/SYMKEVI, the October 2019 approval of TRIKAFTA in the U.S., label expansions for KALYDECO and ORKAMBI and expanded access to our medicines in ex-U.S. markets. In 2020, 2019 and 2018, our net product revenues included product revenues of $1.4 billion, $1.1 billion and $682.4 million, respectively, from ex-U.S. markets.
We expect that our net product revenues will increase in 2021 due to increasing numbers of people being treated with our medicines as a result of the continued uptake of TRIKAFTA, the approval of KAFTRIO by the European Commission, label expansions for our previously approved products and expanded access to our medicines.
Upon reaching an agreement with the French government for ORKAMBI in the fourth quarter of 2019, including the final amount for ORKAMBI distributed through early access programs, we recognized an adjustment to increase net product revenues related to prior period shipments of ORKAMBI distributed through early access programs of $155.8 million. Please refer to “Critical Accounting Policies - Revenue Recognition” below for a discussion of our accounting treatment for our early access program for ORKAMBI in France.
Collaborative and Royalty Revenues
Our collaborative and royalty revenues were $2.9 million, $2.1 million and $9.3 million in 2020, 2019 and 2018, respectively. Our collaborative revenues have historically fluctuated significantly from one period to another and may continue to fluctuate in the future. Our future royalty revenues will be dependent on if, and when, our collaborators are able to successfully develop drug candidates that we have out-licensed to them.
Operating Costs and Expenses
| 2020/2019 Comparison | 2019/2018 Comparison | ||||||||||||||||||||||||||||||||||||||||
| Increase/(Decrease) | Increase/(Decrease) | ||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | |||||||||||||||||||||||||||||||||||
| (in thousands, except percentages) | |||||||||||||||||||||||||||||||||||||||||
| Cost of sales | $ | 736,300 | $ | 547,758 | $ | 409,539 | $ | 188,542 | 34 | % | $ | 138,219 | 34 | % | |||||||||||||||||||||||||||
| Research and development expenses | 1,829,537 | 1,754,540 | 1,416,476 | 74,997 | 4 | % | 338,064 | 24 | % | ||||||||||||||||||||||||||||||||
| Sales, general and administrative expenses | 770,456 | 658,498 | 557,616 | 111,958 | 17 | % | 100,882 | 18 | % | ||||||||||||||||||||||||||||||||
| Change in fair value of contingent consideration | 13,100 | 4,459 | — | 8,641 | 194 | % | 4,459 | ** | |||||||||||||||||||||||||||||||||
| Restructuring income | — | — | (184) | — | ** | 184 | ** | ||||||||||||||||||||||||||||||||||
| Intangible asset impairment charge | — | — | 29,000 | — | ** | (29,000) | ** | ||||||||||||||||||||||||||||||||||
| Total costs and expenses | $ | 3,349,393 | $ | 2,965,255 | $ | 2,412,447 | $ | 384,138 | 13 | % | $ | 552,808 | 23 | % | |||||||||||||||||||||||||||
| ** Not meaningful |
Cost of Sales
Our cost of sales primarily consists of the third-party royalties payable on our net sales of our products as well as the cost of producing inventories that corresponded to product revenues for the reporting period. Pursuant to our agreement with the Cystic Fibrosis Foundation, or CFF, our tiered third-party royalties on sales of TRIKAFTA/KAFTRIO, SYMDEKO/SYMKEVI, KALYDECO and ORKAMBI, calculated as a percentage of net sales, range from the single digits to the sub-teens, with royalties on sales of TRIKAFTA/KAFTRIO slightly lower than for our other products. Over the last several years, our cost of sales has been increasing due to increased net product revenues. Our cost of sales as a percentage of our net product revenues was approximately 12%, 13%, and 13% for 2020, 2019 and 2018, respectively. In 2021, we expect our total cost of sales will increase due to expected increases in our net product revenues and our cost of sales as a percentage of total net product revenues will be similar to our cost of sales as a percentage of total net product revenues in 2020.
Research and Development Expenses
| 2020/2019 Comparison | 2019/2018 Comparison | ||||||||||||||||||||||||||||||||||||||||
| Increase/(Decrease) | Increase/(Decrease) | ||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | |||||||||||||||||||||||||||||||||||
| (in thousands, except percentages) | |||||||||||||||||||||||||||||||||||||||||
| Research expenses | $ | 636,759 | $ | 732,772 | $ | 438,360 | $ | (96,013) | (13) | % | $ | 294,412 | 67 | % | |||||||||||||||||||||||||||
| Development expenses | 1,192,778 | 1,021,768 | 978,116 | 171,010 | 17 | % | 43,652 | 4 | % | ||||||||||||||||||||||||||||||||
| Total research and development expenses | $ | 1,829,537 | $ | 1,754,540 | $ | 1,416,476 | $ | 74,997 | 4 | % | $ | 338,064 | 24 | % |
Our research and development expenses include internal and external costs incurred for research and development of our drugs and drug candidates and expenses related to certain technology that we acquire or license through business development transactions. We do not assign our internal costs, such as salary and benefits, stock-based compensation expense, laboratory supplies and other direct expenses and infrastructure costs, to individual drugs or drug candidates, because the employees within our research and development groups typically are deployed across multiple research and development programs. These internal costs are significantly greater than our external costs, such as the costs of services provided to us by clinical research organizations and other outsourced research, which we allocate by individual program. All research and development costs for our drugs and drug candidates are expensed as incurred.
Over the past three years, we have incurred $5.0 billion in research and development expenses associated with drug discovery and development. The successful development of our drug candidates is highly uncertain and subject to a number of risks. In addition, the duration of clinical trials may vary substantially according to the type, complexity and novelty of the drug candidate and the disease indication being targeted. The FDA and comparable agencies in foreign countries impose substantial requirements on the introduction of therapeutic pharmaceutical products, typically requiring lengthy and detailed laboratory and clinical testing procedures, sampling activities and other costly and time-consuming procedures. Data obtained from nonclinical and clinical activities at any step in the testing process may be adverse and lead to discontinuation or redirection of development activities. Data obtained from these activities also are susceptible to varying interpretations,
which could delay, limit or prevent regulatory approval. The duration and cost of discovery, nonclinical studies and clinical trials may vary significantly over the life of a project and are difficult to predict. Therefore, accurate and meaningful estimates of the ultimate costs to bring our drug candidates to market are not available.
In 2020, 2019 and 2018, costs related to our CF programs represented the largest portion of our development costs. Any estimates regarding development and regulatory timelines for our drug candidates are highly subjective and subject to change. Until we have data from Phase 3 clinical trials, we cannot make a meaningful estimate regarding when, or if, a clinical development program will generate revenues and cash flows.
Research Expenses
| 2020/2019 Comparison | 2019/2018 Comparison | ||||||||||||||||||||||||||||||||||||||||
| Increase/(Decrease) | Increase/(Decrease) | ||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | |||||||||||||||||||||||||||||||||||
| (in thousands, except percentages) | |||||||||||||||||||||||||||||||||||||||||
| Research Expenses: | |||||||||||||||||||||||||||||||||||||||||
| Salary and benefits | $ | 129,835 | $ | 134,642 | $ | 87,773 | $ | (4,807) | (4) | % | $ | 46,869 | 53 | % | |||||||||||||||||||||||||||
| Stock-based compensation expense | 85,609 | 69,417 | 62,925 | 16,192 | 23 | % | 6,492 | 10 | % | ||||||||||||||||||||||||||||||||
| Outsourced services and other direct expenses | 116,182 | 116,575 | 89,355 | (393) | — | % | 27,220 | 30 | % | ||||||||||||||||||||||||||||||||
| Collaborative payments | 184,600 | 307,828 | 111,600 | (123,228) | (40) | % | 196,228 | 176 | % | ||||||||||||||||||||||||||||||||
| Infrastructure costs | 120,533 | 104,310 | 86,707 | 16,223 | 16 | % | 17,603 | 20 | % | ||||||||||||||||||||||||||||||||
| Total research expenses | $ | 636,759 | $ | 732,772 | $ | 438,360 | $ | (96,013) | (13) | % | $ | 294,412 | 67 | % | |||||||||||||||||||||||||||
We expect to continue to invest in our research programs with a focus on identifying drug candidates with the goal of creating transformative medicines for serious diseases. Our total research expenses have historically fluctuated, and are expected to continue to fluctuate, from one period to another due to upfront and milestone payments related to our business development activities that are reflected in the preceding table as collaborative payments. Our research expenses, excluding these collaborative payments, have been increasing over the last several years as we have invested in our pipeline and expanded our cell and genetic therapies capabilities.
Development Expenses
| 2020/2019 Comparison | 2019/2018 Comparison | ||||||||||||||||||||||||||||||||||||||||
| Increase/(Decrease) | Increase/(Decrease) | ||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | |||||||||||||||||||||||||||||||||||
| (in thousands, except percentages) | |||||||||||||||||||||||||||||||||||||||||
| Development Expenses: | |||||||||||||||||||||||||||||||||||||||||
| Salary and benefits | $ | 295,744 | $ | 249,860 | $ | 220,128 | $ | 45,884 | 18 | % | $ | 29,732 | 14 | % | |||||||||||||||||||||||||||
| Stock-based compensation expense | 177,081 | 155,141 | 140,187 | 21,940 | 14 | % | 14,954 | 11 | % | ||||||||||||||||||||||||||||||||
| Outsourced services and other direct expenses | 512,157 | 425,149 | 471,338 | 87,008 | 20 | % | (46,189) | (10) | % | ||||||||||||||||||||||||||||||||
| Collaborative payments | — | 10,440 | 250 | (10,440) | ** | 10,190 | ** | ||||||||||||||||||||||||||||||||||
| Infrastructure costs | 207,796 | 181,178 | 146,213 | 26,618 | 15 | % | 34,965 | 24 | % | ||||||||||||||||||||||||||||||||
| Total development expenses | $ | 1,192,778 | $ | 1,021,768 | $ | 978,116 | $ | 171,010 | 17 | % | $ | 43,652 | 4 | % | |||||||||||||||||||||||||||
| ** Not meaningful |
Our development expenses increased by $171.0 million, or 17%, in 2020 as compared to 2019 and increased by $43.7 million, or 4%, in 2019 as compared to 2018, primarily due to increased expenses related to our diversifying pipeline, including clinical trials, headcount and infrastructure costs. We expect our development expenses to continue to increase in 2021 as a result of our advancing pipeline.
Sales, General and Administrative Expenses
| 2020/2019 Comparison | 2019/2018 Comparison | ||||||||||||||||||||||||||||||||||||||||
| Increase/(Decrease) | Increase/(Decrease) | ||||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | 2018 | $ | % | $ | % | |||||||||||||||||||||||||||||||||||
| (in thousands, except percentages) | |||||||||||||||||||||||||||||||||||||||||
| Sales, general and administrative expenses | $ | 770,456 | $ | 658,498 | $ | 557,616 | $ | 111,958 | 17 | % | $ | 100,882 | 18 | % |
Sales, general and administrative expenses increased by 17% in 2020 as compared to 2019, and by 18% in 2019 as compared to 2018, primarily due to increased global support for our medicines, including incremental investment to support the launch of our triple combination regimen and increased support for our CF pipeline products and other disease areas. We expect our sales, general and administrative expenses to continue to increase in 2021.
Contingent Consideration
In 2020 and 2019, the increase in the fair value of contingent consideration potentially payable to Exonics’ former equity holders was $13.1 million and $4.5 million, respectively, primarily due to changes in market interest rates. There were no similar amounts in 2018. In future periods, we expect the fair value of contingent consideration to increase or decrease based on, among other things, our estimates of the probability of achieving and the timing of these contingent development and regulatory milestone payments, as well as the time value of money changes in market interest rates.
Intangible Asset Impairment Charge
In 2018, we recorded a $29.0 million impairment charge related to VX-210 that was licensed from BioAxone Biosciences, Inc., or BioAxone, in 2014. This charge was attributable to non-controlling interest on our consolidated statement of operations because we consolidated BioAxone as a variable interest entity, or VIE, until December 31, 2018. There were no corresponding intangible asset impairment charges in 2020 or 2019.
Other Non-Operating Income (Expense), Net
Interest Income
Interest income increased from $38.4 million in 2018 to $63.7 million in 2019 and decreased to $22.2 million in 2020. The increase in our interest income in 2019 as compared to 2018 was primarily due to increases in our cash equivalents and available-for-sale debt securities and prevailing market interest rates. The decrease in our interest income in 2020 as compared to 2019 was primarily due to a decrease in prevailing market interest rates despite continued increases in our cash equivalents and available-for-sale debt securities. Our future interest income will be dependent on the amount of, and prevailing market interest rates on, our outstanding cash equivalents and available-for-sale debt securities.
Interest Expense
Interest expense was $58.2 million in 2020, $58.5 million in 2019 and $72.5 million in 2018. The majority of our interest expense in these periods was related to imputed interest expense associated with our leased corporate headquarters in Boston and our research site in San Diego. On January 1, 2019, we adopted ASC 842, Leases, which resulted in a reduction in our imputed interest expense associated with these leases in 2020 and 2019. Our future interest expense will be dependent on whether, and to what extent, we borrow amounts under our credit facilities.
Other Income (Expense), Net
In 2020 and 2019, we recorded net other income of $296.4 million and $192.2 million, respectively, primarily related to changes in the fair value of our strategic investments. In 2018, we recorded net other expense of $0.8 million. We expect that due to the volatility of the stock price of biotechnology companies, our other income (expense), net will fluctuate in future periods based on increases or decreases in the fair value of our strategic investments.
Noncontrolling Interest (VIEs)
In 2018, our $9.8 million net loss attributable to noncontrolling interest reflects BioAxone’s net loss for the reporting period. We deconsolidated BioAxone from our consolidated financial statements as of December 31, 2018 and did not consolidate any VIEs into our consolidated financial statements in 2020 or 2019.
Income Taxes
Our provision for income taxes was $405.2 million for 2020 and $218.1 million for 2019. Our effective tax rate of 13% for 2020 was lower than the U.S. statutory rate primarily due to (i) discrete tax benefits associated with the $209.0 million transfer of intellectual property rights to the U.K., the write-off of a long-term intercompany receivable, and an increase in the U.K.’s corporate tax rate; and (ii) excess tax benefits related to stock-based compensation. The impact of these items was partially offset by a U.S. deemed dividend. Our effective tax rate of 16% for 2019 was lower than the U.S. statutory rate primarily due to excess tax benefits related to stock-based compensation and research and development tax credits.
In 2018, we recorded a benefit from income taxes of $1.5 billion because we released our valuation allowance on the majority of our net operating losses and other deferred tax assets in the fourth quarter of 2018, resulting in a non-cash credit to net income of $1.56 billion. Starting in 2019, we began recording a provision for income taxes on our pre-tax income using an effective tax rate approximating statutory rates. Due to our ability to offset our pre-tax income against previously benefited net operating losses, the majority of our tax provision in 2020 and 2019 represented a non-cash expense. We utilized substantially all of our remaining previously benefited U.S. net operating losses in 2020. As a result, a larger portion of our tax provision will represent a cash tax payable in future periods.
LIQUIDITY AND CAPITAL RESOURCES
The following table summarizes the components of our financial condition as of December 31, 2020 and 2019:
| Increase/(Decrease) | |||||||||||||||||||||||
| 2020 | 2019 | $ | % | ||||||||||||||||||||
| (in thousands, except percentages) | |||||||||||||||||||||||
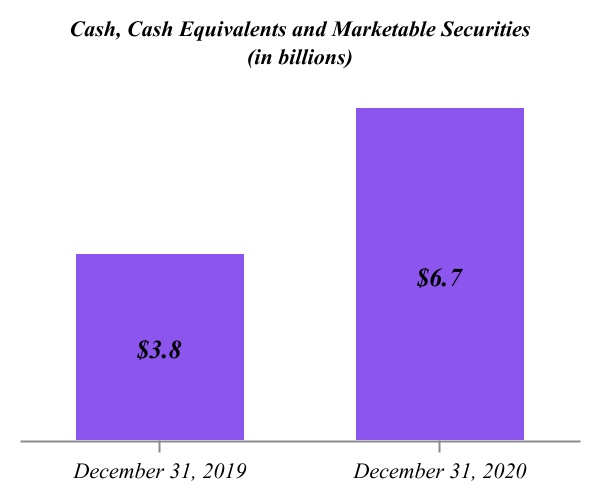
| Cash, cash equivalents and marketable securities | $ | 6,658,897 | $ | 3,808,294 | $ | 2,850,603 | 75 | % | |||||||||||||||
| Working Capital: | |||||||||||||||||||||||
| Total current assets | $ | 8,133,379 | $ | 4,822,829 | $ | 3,310,550 | 69 | % | |||||||||||||||
| Total current liabilities | (1,877,533) | (1,334,827) | (542,706) | (41) | % | ||||||||||||||||||
| Total working capital | $ | 6,255,846 | $ | 3,488,002 | $ | 2,767,844 | 79 | % |
As of December 31, 2020, total working capital was $6.3 billion, which represented an increase of $2.8 billion from $3.5 billion as of December 31, 2019. The increase in total working capital in 2020 was primarily related to $3.3 billion of cash provided by operations partially offset by $539.1 million of cash used to repurchase our common stock pursuant our share repurchase programs and purchases of property and equipment of $259.8 million.
Sources of Liquidity
As of December 31, 2020, we had cash, cash equivalents and marketable securities of $6.7 billion, which represented an increase of $2.9 billion from $3.8 billion as of December 31, 2019. We intend to rely on our existing cash, cash equivalents and marketable securities together with cash flows from product sales as our primary source of liquidity.
We may borrow up to a total of $2.5 billion pursuant to two revolving credit facilities. We may repay and reborrow amounts under these revolving credit agreements without penalty. Subject to certain conditions, we may request that the borrowing capacity for each of the credit agreements be increased by an additional $500.0 million, for a total of $3.5 billion collectively. Other possible sources of future liquidity include commercial debt, public and private offerings of our equity and debt securities, strategic sales of assets or businesses and financial transactions. Negative covenants in our credit agreement may prohibit or limit our ability to access these sources of liquidity. As of December 31, 2020, we were in compliance with these covenants.
Future Capital Requirements
We have significant future capital requirements including:
-
significant expected operating expenses to conduct research and development activities and to operate our organization; and
-
substantial facility and finance lease obligations.
In addition:
-
We have entered into certain collaboration agreements with third parties that include the funding of certain research, development and commercialization efforts. Certain of our business development transactions, including collaborations and acquisitions, include the potential for future milestone and royalty payments by us upon the achievement of pre-established developmental and regulatory targets and/or commercial targets. We may enter into additional business development transactions, including acquisitions, collaborations and equity investments, that require additional capital.
-
To the extent we borrow amounts under the credit agreements we entered into in 2020 and 2019, we would be required to repay any outstanding principal amounts in 2022 or 2024, respectively.
-
As of December 31, 2020, $424.9 million remained available to fund repurchases under the 2020 Share Repurchase Program that we announced in November 2020.
We expect that cash flows from our products together with our current cash, cash equivalents and marketable securities will be sufficient to fund our operations for at least the next twelve months and do not expect COVID-19 to have an adverse effect on our liquidity. The adequacy of our available funds to meet our future operating and capital requirements will depend on many factors, including the amounts of future revenues generated by our products, and the potential introduction of one or more of our other drug candidates to the market, the level of our business development activities and the number, breadth, cost and prospects of our research and development programs.
Financing Strategy
We may raise additional capital by borrowing under credit agreements, through public offerings or private placements of our securities or securing new collaborative agreements or other methods of financing. We will continue to manage our capital structure and will consider all financing opportunities, whenever they may occur, that could strengthen our long-term liquidity profile. There can be no assurance that any such financing opportunities will be available on acceptable terms, if at all.
CONTRACTUAL COMMITMENTS AND OBLIGATIONS
The following table sets forth our commitments and obligations as of December 31, 2020:
| Payments Due by Period | |||||||||||||||||||||||||||||
| 2021 | 2022-2023 | 2024-2025 | 2026 and later | Total | |||||||||||||||||||||||||
| (in thousands) | |||||||||||||||||||||||||||||
| Fan Pier Leases | $ | 66,540 | $ | 145,177 | $ | 155,942 | $ | 233,913 | $ | 601,572 | |||||||||||||||||||
| Finance leases, excluding Fan Pier Leases | 18,930 | 33,028 | 30,913 | 182,542 | 265,413 | ||||||||||||||||||||||||
| Operating leases | 15,266 | 68,782 | 65,677 | 320,684 | 470,409 | ||||||||||||||||||||||||
| Research and development costs | 66,955 | 1,724 | — | — | 68,679 | ||||||||||||||||||||||||
| Total contractual commitments and obligations | $ | 167,691 | $ | 248,711 | $ | 252,532 | $ | 737,139 | $ | 1,406,073 |
Leases
We lease two buildings that are located at Fan Pier in Boston, Massachusetts. We commenced lease payments on these two buildings in December 2013 and the initial lease periods end in December 2028. We also lease office and laboratory
space in San Diego, California. We commenced lease payments for this building in the second quarter of 2019 pursuant to an initial 16 year lease term. The future minimum rental payments that we are obligated to pay related to the San Diego building are included in “Finance leases, excluding Fan Pier Leases,” which also reflects leases of equipment and a land lease. The remainder of our real estate leases are reflected in “Operating leases” in the table above, including office and laboratory space at our Cell and Genetic Therapies facility near our corporate headquarters. Base rent payments will commence for this building in the fourth quarter of 2021 pursuant to an initial 15 year lease term.
Research and Development Costs
“Research and development costs” included in the table above primarily relate to pharmaceutical materials to be utilized in our clinical trials and research costs related to our advancing pipeline. The amounts reflected in “Research and development costs” do not include certain payments we anticipate making to clinical research organizations, or CROs, because these contracts are cancelable, at our option, with notice. However, we historically have not cancelled such contracts. As of December 31, 2020, we had accrued $42.8 million related to these contracts for costs incurred for services provided through December 31, 2020, and we have approximately $237.6 million in cancelable future commitments based on existing contracts as of December 31, 2020. These amounts reflect planned expenditures based on existing contracts and do not reflect any future modifications to, or terminations of, existing contracts or anticipated or potential new contracts.
Collaborative Arrangements and Asset Acquisitions
We have entered into certain research and development collaboration agreements with third parties and acquired certain assets that include the funding of certain development, manufacturing and commercialization efforts with the potential for future milestone and royalty payments by us upon the achievement of pre-established developmental, regulatory and/or commercial targets. Our obligation to fund these efforts is contingent upon continued involvement in the programs and/or the lack of any adverse events that could cause the discontinuance of the programs. These payments, which are not included in the contractual obligations table above, include:
*•*CFF: We pay royalties, which are included in cost of sales, to CFF on sales of our CF products.
- Research and Development Milestones: The majority of our in-license agreements and our acquisitions have milestone and royalty payments payable by us upon the successful achievement of pre-established developmental, regulatory and/or commercial targets or net sales. Contingent payments under these agreements become due and payable only upon achievement of certain milestones.
Tax-related Obligations
We exclude liabilities pertaining to uncertain tax positions from our summary of contractual obligations as we cannot make a reliable estimate of the period of cash settlement with the respective taxing authorities. As of December 31, 2020, our liabilities associated with uncertain tax positions were $86.6 million.
Other Funding Commitments
Our table detailing contractual commitments and obligations does not include severance payment obligations to certain of our executive officers in the event of a not-for-cause employment termination under existing employment contracts. We will provide information regarding these obligations annually in our proxy statement for our annual meeting of shareholders.
CRITICAL ACCOUNTING POLICIES AND ESTIMATES
Our discussion and analysis of our financial condition and results of operations are based upon our consolidated financial statements prepared in accordance with generally accepted accounting principles in the U.S. The preparation of these financial statements requires us to make certain estimates and assumptions that affect the reported amounts of assets and liabilities, the disclosure of contingent assets and liabilities at the date of the consolidated financial statements and the reported amounts of revenues and expenses during the reported periods. These items are monitored and analyzed by management for changes in facts and circumstances, and material changes in these estimates could occur in the future. Changes in estimates are reflected in reported results for the period in which the change occurs. We base our estimates on historical experience and various other assumptions that we believe to be reasonable under the circumstances. Actual results may differ from our estimates if past experience or other assumptions do not turn out to be substantially accurate.
We believe that our application of the following accounting policies, each of which requires significant judgments and estimates on the part of management, are the most critical to aid in fully understanding and evaluating our reported financial results:
-
revenue recognition;
-
acquisitions, including intangible assets, goodwill and contingent consideration; and
-
income taxes.
Our accounting policies, including the ones discussed below, are more fully described in the Notes to our consolidated financial statements, including Note A, “Nature of Business and Accounting Policies,” included in this Annual Report on Form 10-K.
Revenue Recognition
Product Revenues, Net
We generate product revenues from sales in the U.S. and in international markets. We sell our products principally to a limited number of specialty pharmacy and specialty distributors in the U.S., which account for the largest portion of our total revenues, and make international sales primarily to specialty distributors and retail chains, as well as hospitals and clinics, many of which are government-owned or supported customers, collectively, our customers. Our customers in the U.S. subsequently resell our products to patients and health care providers. We contract with government agencies so that our products will be eligible for purchase by, or partial or full reimbursement from, such third-party payors. We recognize net product revenues from sales of our products when our customers obtain control of our products, which typically occurs upon delivery to our customers. Revenues from our product sales are recorded at the net sales price, or “transaction price,” which requires us to make several significant estimates regarding the net sales price.
The most significant estimate we are required to make is related to government and private payor rebates, chargebacks, discounts and fees, collectively rebates. The value of the rebates provided to third-party payors per course of treatment vary significantly and are based on government-mandated discounts and our arrangements with other third-party payors. In order to estimate our total rebates, we estimate the percentage of prescriptions that will be covered by each third-party payor, which is referred to as the payor mix. We track available information regarding changes, if any, to the payor mix for our products, to our contractual terms with third-party payors and to applicable governmental programs and regulations and levels of our products in the distribution channel. We adjust our estimated rebates based on new information, including information regarding actual rebates for our products, as it becomes available. Claims by third-party payors for rebates are submitted to us significantly after the related sales, potentially resulting in adjustments in the period in which the new information becomes known. Our credits to revenue related to prior period sales, excluding the adjustment to the transaction price for ORKAMBI distributed through early access programs in France in 2019, have not been significant (typically less than 1% of gross product revenues) and primarily related to U.S. rebates.
The following table summarizes activity related to our accruals for rebates (including our refund liability to the French government related to ORKAMBI distributed through early access programs in France as described below) for the three years ended December 31, 2020:
| (in thousands) | |||||
| Balance as of December 31, 2017 | $ | 112,215 | |||
| Provision related to 2018 sales and the adoption of ASC 606 | 684,299 | ||||
| Adjustments related to prior year(s) sales | (22,099) | ||||
| Credits/payments made | (229,361) | ||||
| Balance as of December 31, 2018 | $ | 545,054 | |||
| Provision related to 2019 sales | 655,980 | ||||
| Adjustments related to prior year(s) sales | (95,480) | ||||
| Credits/payments made | (469,832) | ||||
| Balance as of December 31, 2019 | $ | 635,722 | |||
| Provision related to 2020 sales | 1,284,068 | ||||
| Adjustments related to prior year(s) sales | 631 | ||||
| Credits/payments made | (1,144,832) | ||||
| Balance as of December 31, 2020 | $ | 775,589 |
We have also entered into annual contracts with government-owned and supported customers in international markets that limit the amount of annual reimbursement we can receive. Upon exceeding the annual reimbursement amount, products are provided free of charge, which is a material right. We defer a portion of the consideration received, which includes upfront payments and fees, for shipments made up to the annual reimbursement limit as “Other current liabilities.” The deferred amount is recognized as revenue when the free products are shipped. In order to estimate the portion of the consideration received to recognize as revenue and the portion of the amount to defer, we rely on our forecast of the number of units we will distribute during the applicable annual period in each international market in which our contracts with government-owned and supported customers limit the amount of annual reimbursement we can receive. Our forecasts are based on, among other things, our historical experience.
The preceding estimates and judgments materially affect our recognition of net product revenues. Changes in our estimates of net product revenues could have a material effect on net product revenues recorded in the period in which we determine that change occurs.
French Early Access Programs
In 2015, we began distributing ORKAMBI through early access programs in France and remained engaged in reimbursement discussions with the French government for ORKAMBI, including ORKAMBI distributed through early access programs, until November 2019, when we reached an agreement with the French government. From the time we began distributing ORKAMBI through early access programs in France, we expected that the difference between the amounts collected based on the invoiced amount and the final amount for ORKAMBI distributed through these programs would be returned to the French government. Our refund liability related to the early access programs in France was classified in “Accrued expenses” on our consolidated balance sheets.
From the first quarter of 2018 through the third quarter of 2019, we recognized net product revenues for ORKAMBI sales in France under the early access programs based on a transaction price that reflected our estimate of consideration we expected to retain that would not be subject to a significant reversal in amounts recognized, which resulted in revenue representing a portion of the invoiced amount.
Upon reaching an agreement with the French government for ORKAMBI, including the final amount for ORKAMBI distributed through early access programs in France in the fourth quarter of 2019, we updated the transaction price related to ORKAMBI distributed through early access programs and recognized net product revenues of $155.8 million related to these shipments, which occurred from 2015 through the date of our agreement with the French government, because the final amount for these shipments exceeded our previous estimate.
Acquisitions
We are required to make several significant judgments and estimates in order to calculate the purchase price for our business combinations and then allocate it to the assets that we have acquired and the liabilities that we have assumed on our consolidated balance sheet. The most significant judgments and estimates relate to the fair value of the in-process research and development assets and contingent consideration liabilities related to these business combinations. Based on these judgments and estimates, the fair value of the goodwill that we record as a result of these business combinations may be material. Once recorded, these assets are subject to quarterly impairment analysis and our contingent consideration liability is adjusted quarterly, which requires similar judgments and estimates.
Intangible Assets
In 2019, we recorded in-process research and development assets related to our acquisitions of Exonics and Semma totaling $400.0 million on our consolidated balance sheet, which remained on our consolidated balance sheet as of December 31, 2020. Each of these assets is accounted for as an indefinite-lived intangible asset and is maintained on our consolidated balance sheet until either the project underlying it is completed or the asset becomes impaired. When we determine that an asset has become impaired or we abandon a project, we write down the carrying value of the related intangible asset to its fair value and record an impairment charge in the period in which the impairment occurs. In 2018, we recorded a full impairment charge of $29.0 million for the in-process research and development asset that had previously been recorded on our consolidated balance sheets related to our collaboration with BioAxone.
To determine the fair value of our in-process research and development assets, we utilize the multi-period excess earnings method of the income approach, which requires us to make estimates of the probability of technical and regulatory success, development cost assumptions, revenue projections and growth rates, commercial cost estimates and appropriate discount rates. These assumptions require significant management judgment and reasonable changes in the assumptions can cause material changes to the fair value of the intangible assets. Due to the early stage of Exonics and Semma’s programs, these significant assumptions could be affected by future economic and market conditions.
Contingent Consideration
As of December 31, 2020 and 2019, we had $189.6 million and $176.5 million, respectively, of liabilities on our consolidated balance sheet attributable to the fair value of the contingent development and regulatory payments that we may owe to Exonics’ former equity holders upon the achievement of certain events. Our acquisition of Semma in 2019 did not include similar contingent payments; therefore, we are not required to record contingent consideration liabilities related to our acquisition of Semma.
We record an increase or a decrease in the fair value of the contingent consideration liability on our consolidated balance sheet and in our consolidated statement of operations on a quarterly basis. We determine the fair value of our contingent consideration liability using a probability weighted discounted cash flow method of the income approach, which requires us to make estimates of the timing of regulatory and commercial milestone achievement and the corresponding estimated probability of technical and regulatory success rates. Significant judgment is used in determining the appropriateness of these assumptions during each reporting period. Reasonable changes in these assumptions can cause material changes to the fair value of our contingent consideration liability. Due to the early stage of Exonics’ DMD and DM1 programs, these significant assumptions could be affected by future economic and market conditions.
Goodwill
In 2020, we did not have any business combinations; therefore, we did not record any additional goodwill on our consolidated balance sheet. In 2019, we recorded goodwill of $554.6 million and $397.1 million related to our acquisitions of Semma and Exonics, respectively. Goodwill reflects the difference between the fair value of the consideration transferred and the fair value of the net assets acquired. Thus, the goodwill that we record is dependent on the significant judgments and estimates inherent in the fair value of our in-process research and development assets and contingent consideration liabilities.
Income Taxes
We utilize the asset and liability method of accounting for income taxes. Under this method, deferred tax assets and liabilities are determined based on the difference between the financial statement carrying amounts and tax basis of assets and liabilities using enacted tax rates in effect for years in which the temporary differences are expected to reverse. If our estimate
of the tax effect of reversing temporary differences is (i) not reflective of actual outcomes, (ii) modified to reflect new developments or interpretations of the tax law, or (iii) revised to incorporate new accounting principles, or changes in the expected timing or manner of the reversal, our results of operations could be materially impacted.
We are engaged in research and development activities and incurred significant net operating losses for a number of years before recently becoming profitable. Accordingly, we did not report any tax benefits relating to our net operating loss carryforwards and income tax credit carryforwards that were available for utilization in future periods because we maintained a valuation allowance on the majority of our net operating losses and other deferred tax assets until December 31, 2018. We released the valuation allowance on the majority of our net operating losses and other deferred tax assets resulting in a non-cash benefit from income taxes of $1.56 billion in the fourth quarter of 2018.
We provide a valuation allowance when it is more likely than not that deferred tax assets will not be realized. On a periodic basis, we reassess our valuation allowances on our deferred tax assets, weighing positive and negative evidence to assess the recoverability of the deferred tax assets. In the fourth quarter of 2018, we reassessed our valuation allowances and considered positive evidence including significant cumulative consolidated and U.S. income over the three years ended December 31, 2018, revenue growth, clinical program progression, including the advancement and clinical trial data from our triple combination regimens, and expectations regarding future profitability, and negative evidence, including potential impact of competition on our projections and cumulative losses in the jurisdictions. After assessing both the positive evidence and the negative evidence, we released the valuation allowance on the majority of our net operating losses and other deferred tax assets as of December 31, 2018.
Significant judgment is required in making these assessments to maintain or reverse our valuation allowances and, to the extent our future expectations change we would have to assess the recoverability of these deferred tax assets at that time. The determination to release the majority of our valuation allowances increased our net income by $1.56 billion, or $6.03 per share in 2018.
RECENT ACCOUNTING PRONOUNCEMENTS
Refer to Note A, “Nature of Business and Accounting Policies,” in the accompanying notes to the consolidated financial statements for a discussion of recent accounting pronouncements and new accounting pronouncements adopted during 2020.
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK