 filings.tools
Williams Companies 10-K 2016-12-31
Filed 2017-02-22. 21 sections, 666K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 wmb_20161231x10k.htm 10-K
UNITED STATES SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
Form 10-K
(Mark One)
| þ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
| For the fiscal year ended December 31, 2016 | |
| OR | |
| ¨ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
| For the transition period from to |
Commission file number 1-4174
The Williams Companies, Inc.
(Exact Name of Registrant as Specified in Its Charter)
| Delaware | 73-0569878 | |
| (State or Other Jurisdiction of Incorporation or Organization) | (IRS Employer Identification No.) | |
| One Williams Center, Tulsa, Oklahoma | 74172 | |
| (Address of Principal Executive Offices) | (Zip Code) |
918-573-2000
(Registrant’s Telephone Number, Including Area Code)
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Name of Each Exchange on Which Registered | |
| Common Stock, $1.00 par value | New York Stock Exchange |
Securities registered pursuant to Section 12(g) of the Act:
None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes þ No ¨
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ¨ No þ
Indicate by check mark whether the registrant: (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes þ No ¨
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes þ No ¨
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. ¨
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act. (Check one):
| Large accelerated filer þ | Accelerated filer ¨ | Non-accelerated filer ¨ | Smaller reporting company ¨ | ||||||
| (Do not check if a smaller reporting company) |
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ¨ No þ
The aggregate market value of the voting and non-voting common equity held by non-affiliates computed by reference to the price at which the common equity was last sold as of the last business day of the registrant’s most recently completed second quarter was approximately $16,207,908,251.
The number of shares outstanding of the registrant’s common stock outstanding at February 17, 2017 was 825,823,918.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the Registrant’s Definitive Proxy Statement for the Registrant’s Annual Meeting of Stockholders to be held on May 18, 2017, are incorporated into Part III, as specifically set forth in Part III.
THE WILLIAMS COMPANIES, INC.
FORM 10-K
TABLE OF CONTENTS
DEFINITIONS
The following is a listing of certain abbreviations, acronyms and other industry terminology used throughout this Annual Report.
Measurements:
Barrel: One barrel of petroleum products that equals 42 U.S. gallons
Bcf : One billion cubic feet of natural gas
Bcf/d: One billion cubic feet of natural gas per day
British Thermal Unit (Btu): A unit of energy needed to raise the temperature of one pound of water by one degree
Fahrenheit
Dekatherms (Dth): A unit of energy equal to one million British thermal units
Mbbls/d: One thousand barrels per day
Mdth/d: One thousand dekatherms per day
MMcf/d: One million cubic feet per day
MMdth: One million dekatherms or approximately one trillion British thermal units
MMdth/d: One million dekatherms per day
Tbtu: One trillion British thermal units
Consolidated Entities:
ACMP: Access Midstream Partners, L.P. prior to its merger with Pre-Merger WPZ
Cardinal: Cardinal Gas Services, L.L.C.
Constitution: Constitution Pipeline Company, LLC
Gulfstar One: Gulfstar One LLC
Jackalope: Jackalope Gas Gathering Services, L.L.C.
Northwest Pipeline: Northwest Pipeline LLC
Pre-merger WPZ: Williams Partners L.P. prior to its merger with ACMP
Transco: Transcontinental Gas Pipe Line Company, LLC
WPZ: Williams Partners L.P.
Partially Owned Entities: Entities in which we do not own a 100 percent ownership interest and which, as of December 31, 2016, we account for as an equity-method investment, including principally the following:
Aux Sable: Aux Sable Liquid Products LP
Bluegrass: Bluegrass Pipeline Company LLC
Caiman II: Caiman Energy II, LLC
Discovery: Discovery Producer Services LLC
Gulfstream: Gulfstream Natural Gas System, L.L.C.
Laurel Mountain: Laurel Mountain Midstream, LLC
Moss Lake: Moss Lake Fractionation LLC and Moss Lake LPG Terminal LLC
OPPL: Overland Pass Pipeline Company LLC
UEOM: Utica East Ohio Midstream LLC
Government and Regulatory:
EPA: Environmental Protection Agency
Exchange Act, the: Securities and Exchange Act of 1934, as amended
FERC: Federal Energy Regulatory Commission
GAAP: Generally accepted accounting principles
IRS: Internal Revenue Service
SEC: Securities and Exchange Commission
Other:
DRIP: Distribution reinvestment program
Energy Transfer: Energy Transfer Equity, L.P.
ETC: Energy Transfer Corp LP
ETC Merger: Merger wherein Williams would have been merged into ETC
Fractionation: The process by which a mixed stream of natural gas liquids is separated into its constituent products,
such as ethane, propane, and butane
IDR: Incentive distribution right
LNG: Liquefied natural gas; natural gas which has been liquefied at cryogenic temperatures
Merger Agreement: Merger Agreement and Plan of Merger of Williams with Energy Transfer and certain of its
affiliates
MVC: Minimum volume commitment
NGLs: Natural gas liquids; natural gas liquids result from natural gas processing and crude oil refining and are
used as petrochemical feedstocks, heating fuels, and gasoline additives, among other applications
NGL margins: NGL revenues less Btu replacement cost, plant fuel, transportation, and fractionation
PDH facility: Propane dehydrogenation facility
RGP Splitter: Refinery grade propylene splitter
Throughput: The volume of product transported or passing through a pipeline, plant, terminal, or other facility
PART I
Item 1. Business
In this report, Williams (which includes The Williams Companies, Inc. and, unless the context otherwise indicates, all of our subsidiaries) is at times referred to in the first person as “we,” “us” or “our.” We also sometimes refer to Williams as the “Company.”
WEBSITE ACCESS TO REPORTS AND OTHER INFORMATION
We file our annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, proxy statements and other documents electronically with the SEC under the Exchange Act. You may read and copy any materials that we file with the SEC at the SEC’s Public Reference Room at 100 F Street, N.E., Washington, DC 20549. You may obtain information on the operation of the Public Reference Room by calling the SEC at 1-800-SEC-0330. You may also obtain such reports from the SEC’s Internet website at www.sec.gov.
Our Internet website is www.williams.com. We make available, free of charge, through the Investor tab of our Internet website our annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act as soon as reasonably practicable after we electronically file such material with, or furnish it to, the SEC. Our Corporate Governance Guidelines, Code of Ethics for Senior Officers, Board committee charters, and the Williams Code of Business Conduct are also available on our Internet website. We will also provide, free of charge, a copy of any of our corporate documents listed above upon written request to our Corporate Secretary, One Williams Center, Suite 4700, Tulsa, Oklahoma 74172.
GENERAL
We are primarily an energy infrastructure company focused on connecting North America’s significant hydrocarbon resource plays to markets for natural gas, NGLs, and olefins. Our operations are located principally in the United States.
As of December 31, 2016, our interstate gas pipelines, midstream, and olefins production interests were largely held through our significant investment in Williams Partners L.P. (WPZ). We owned the general partner interest and a 58 percent limited-partner interest in WPZ. See the Financial Repositioning discussion below for recent changes to our interest in WPZ.
We were founded in 1908, originally incorporated under the laws of the state of Nevada in 1949 and reincorporated under the laws of the state of Delaware in 1987. Williams’ headquarters are located in Tulsa, Oklahoma, with other major offices in Salt Lake City, Utah; Houston, Texas; Oklahoma City, Oklahoma; Pittsburgh, Pennsylvania; and the Four Corners Area. Our telephone number is 918-573-2000.
FINANCIAL REPOSITIONING
In January 2017, we announced agreements with WPZ, wherein we permanently waived the general partner’s incentive distribution rights and converted our 2 percent general partner interest in WPZ to a non-economic interest in exchange for 289 million newly issued WPZ common units. Pursuant to this agreement, we also purchased approximately 277 thousand WPZ common units for $10 million. Additionally, we purchased approximately 59 million common units of WPZ at a price of $36.08586 per unit in a private placement transaction, funded with proceeds from our equity offering (see Note 15 - Stockholders’ Equity of Notes to Consolidated Financial Statements). Following these transactions, we own a 74 percent limited partner interest in WPZ. It is anticipated that the combination of these measures will improve WPZ’s cost of capital, provide for debt reduction, and eliminate WPZ’s need to access the public equity markets for several years.
In addition to the previously announced Geismar monetization process, we have announced plans to monetize other select assets that are not core to our strategy. We expect to raise more than $2 billion in after-tax proceeds from the monetization process of Geismar and the other select assets.
SALE OF OUR CANADIAN OPERATIONS
In September 2016, we completed the sale of our Canadian operations. Consideration received to date totaled $1.020 billion, net of $31 million of cash divested and subject to customary working capital adjustments. We recognized an impairment charge of $747 million during the second quarter of 2016 related to these operations and an additional loss of $66 million upon completion of the sale. (See Note 3 – Divestiture of Notes to Consolidated Financial Statements.)
ENERGY TRANSFER MERGER AGREEMENT
On September 28, 2015, we publicly announced in a press release that we had entered into a Merger Agreement with Energy Transfer and certain of its affiliates. The Merger Agreement provided that, subject to the satisfaction of customary closing conditions, we would merge with and into the newly formed ETC, with ETC surviving the ETC Merger.
On June 29, 2016, Energy Transfer provided us written notice terminating the Merger Agreement, citing the alleged failure of certain conditions under the Merger Agreement.
ORGANIZATIONAL REALIGNMENT
In September 2016, we announced organizational changes aiming to simplify our structure, increase direct operational alignment to advance our natural gas-focused strategy, and drive continued focus on customer service and execution. Effective January 1, 2017, we implemented these changes, which combined the management of certain of our operations and reduced the overall number of operating areas managed within our business.
Information in this report has generally been prepared to be consistent with the reportable segment presentation in our consolidated financial statements in Part II, Item 8 of this document. These segments are discussed in further detail in the following sections.
FINANCIAL INFORMATION ABOUT SEGMENTS
See “Item 8 — Financial Statements and Supplementary Data — Notes to Consolidated Financial Statements — Note 19 – Segment Disclosures.”
BUSINESS SEGMENTS
Substantially all our operations are conducted through our subsidiaries. Our activities in 2016 were operated through the following reporting segments as presented in the accompanying financial statements and management’s discussion and analysis.
| • | Williams Partners — comprised of our consolidated master limited partnership, WPZ, which includes gas pipeline and midstream businesses. The gas pipeline business includes interstate natural gas pipelines and pipeline joint project investments. The midstream business provides natural gas gathering, treating, processing and compression services; NGL production, fractionation, storage, marketing and transportation; deepwater production handling and crude oil transportation services; an olefin production business and is comprised of several wholly owned and partially owned subsidiaries and joint project investments. |
Prior to September 2016, this reporting segment also included our Canadian midstream operations comprised of an oil sands offgas processing plant near Fort McMurray, Alberta, an NGL/olefin fractionation facility, and the Boreal Pipeline which were subsequently sold.
| • | Williams NGL & Petchem Services — comprised of our Texas Belle pipeline and certain other domestic olefins pipeline assets. Prior to September 2016, this reporting segment also included certain Canadian growth projects under development, including a propane dehydrogenation facility and a recently completed liquids extraction plant which were subsequently sold. |
| • | Other — primarily comprised of corporate operations and our Canadian construction services company. |
As previously discussed, in September 2016 we announced organizational changes aiming to simplify our structure, increase direct operational alignment to advance our natural gas-focused strategy, and drive continued focus on customer service and execution. Effective January 1, 2017, we implemented these changes, which combined the management of certain of our operations and reduced the overall number of o
Showing the first 8K of 67K characters. Open the full section
Item 1A. Risk Factors
FORWARD-LOOKING STATEMENTS AND CAUTIONARY STATEMENT
FOR PURPOSES OF THE “SAFE HARBOR” PROVISIONS OF
THE PRIVATE SECURITIES LITIGATION REFORM ACT OF 1995
The reports, filings and other public announcements of The Williams Companies, Inc. (Williams) may contain or incorporate by reference statements that do not directly or exclusively relate to historical facts. Such statements are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended (Securities Act), and Section 21E of the Securities Exchange Act of 1934, as amended (Exchange Act). These forward-looking statements relate to anticipated financial performance, management’s plans and objectives for future operations, business prospects, outcome of regulatory proceedings, market conditions and other matters. We make these forward-looking statements in reliance on the safe harbor protections provided under the Private Securities Litigation Reform Act of 1995.
All statements, other than statements of historical fact, included in this report that address activities, events or developments that we expect, believe or anticipate will exist or may occur in the future, are forward-looking statements. Forward-looking statements can be identified by various forms of words such as “anticipates,” “believes,” “seeks,” “could,” “may,” “should,” “continues,” “estimates,” “expects,” “forecasts,” “intends,” “might,” “goals,” “objectives,” “targets,” “planned,” “potential,” “projects,” “scheduled,” “will,” “assumes,” “guidance,” “outlook,” “in service date” or other similar expressions. These forward-looking statements are based on management’s beliefs and assumptions and on information currently available to management and include, among others, statements regarding:
| • | Levels of cash distributions by Williams Partners L.P. (WPZ) with respect to limited partner interests; |
| • | Levels of dividends to Williams stockholders; |
| • | Future credit ratings of Williams, WPZ, and their affiliates; |
| • | Amounts and nature of future capital expenditures; |
| • | Expansion and growth of our business and operations; |
| • | Financial condition and liquidity; |
| • | Business strategy; |
| • | Cash flow from operations or results of operations; |
| • | Seasonality of certain business components; |
| • | Natural gas, natural gas liquids, and olefins prices, supply, and demand; |
| • | Demand for our services. |
Forward-looking statements are based on numerous assumptions, uncertainties and risks that could cause future events or results to be materially different from those stated or implied in this report. Many of the factors that will determine these results are beyond our ability to control or predict. Specific factors that could cause actual results to differ from results contemplated by the forward-looking statements include, among others, the following:
| • | Whether WPZ will produce sufficient cash flows to provide the level of cash distributions that we expect; |
| • | Whether we are able to pay current and expected levels of dividends; |
| • | Whether WPZ elects to pay expected levels of cash distributions and we elect to pay expected levels of dividends; |
| • | Whether we will be able to effectively execute our financing plan including the receipt of anticipated levels of proceeds from planned asset sales; |
| • | Whether we will be able to effectively manage the transition in our board of directors and management as well as successfully execute our business restructuring; |
| • | Availability of supplies, including lower than anticipated volumes from third parties served by our midstream business, and market demand; |
| • | Volatility of pricing including the effect of lower than anticipated energy commodity prices and margins; |
| • | Inflation, interest rates, and general economic conditions (including future disruptions and volatility in the global credit markets and the impact of these events on customers and suppliers); |
| • | The strength and financial resources of our competitors and the effects of competition; |
| • | Whether we are able to successfully identify, evaluate, and timely execute our capital projects and other |
investment opportunities in accordance with our forecasted capital expenditures budget;
| • | Our ability to successfully expand our facilities and operations; |
| • | Development of alternative energy sources; |
| • | Availability of adequate insurance coverage and the impact of operational and developmental hazards and unforeseen interruptions; |
| • | The impact of existing and future laws, regulations, the regulatory environment, environmental liabilities, and litigation, as well as our ability to obtain permits and achieve favorable rate proceeding outcomes; |
| • | Our costs and funding obligations for defined benefit pension plans and other postretirement benefit plans; |
| • | Changes in maintenance and construction costs; |
| • | Changes in the current geopolitical situation; |
| • | Our exposure to the credit risk of our customers and counterparties; |
| • | Risks related to financing, including restrictions stemming from debt agreements, future changes in credit ratings as determined by nationally-recognized credit rating agencies and the availability and cost of capital; |
| • | The amount of cash distributions from and capital requirements of our investments and joint ventures in which we participate; |
| • | Risks associated with weather and natural phenomena, including climate conditions and physical damage to our facilities; |
| • | Acts of terrorism, including cybersecurity threats and related disruptions; |
| • | Additional risks described in our filings with the Securities and Exchange Commission (SEC). |
Given the uncertainties and risk factors that could cause our actual results to differ materially from those contained in any forward-looking statement, we caution investors not to unduly rely on our forward-looking statements. We disclaim any obligations to and do not intend to update the above list or announce publicly the result of any revisions to any of the forward-looking statements to reflect future events or developments.
In addition to causing our actual results to differ, the factors listed above and referred to below may cause our intentions to change from those statements of intention set forth in this report. Such changes in our intentions may also cause our results to differ. We may change our intentions, at any time and without notice, based upon changes in such factors, our assumptions, or otherwise.
Because forward-looking statements involve risks and uncertainties, we caution that there are important factors, in addition to those listed above, that may cause actual results to differ materially from those contained in the forward-looking statements. These factors are described in the following section.
RISK FACTORS
You should carefully consider the following risk factors in addition to the other information in this report. Each of these factors could adversely affect our business, prospects, financial condition, results of operations, cash flows and, in some cases our reputation. The occurrence of any of such risks cou
Showing the first 8K of 74K characters. Open the full section
Item 1B. Unresolved Staff Comments
Not applicable.
Item 2. Properties
Please read “Business” for a description of the location and general character of our principal physical properties. We generally own our facilities, although a substantial portion of our pipeline and gathering facilities is constructed and maintained pursuant to rights-of-way, easements, permits, licenses, or consents on and across properties owned by others.
Item 3. Legal Proceedings
Environmental
Certain reportable legal proceedings involving governmental authorities under federal, state, and local laws regulating the discharge of materials into the environment are described below. While it is not possible for us to predict the final outcome of the proceedings which are still pending, we do not anticipate a material effect on our consolidated financial position if we receive an unfavorable outcome in any one or more of such proceedings.
On January 21, 2016, we received a Compliance Order from the Pennsylvania Department of Environmental Protection requiring the correction of several alleged deficiencies arising out of the construction of the Springville Gathering Line, the Pennsylvania Mainline Gathering Line, and the 2008 Core Zone Gathering Line. The original Order identified civil penalties in the amount of approximately $712,000. On December 28, 2016, we entered into an Order with the Pennsylvania Department of Environmental Protection to address the issues and paid the associated penalty of $581,477.
On February 21, 2017, we received notice from the Environmental Enforcement Section of the United States Department of Justice regarding certain alleged violations of the Clean Air Act at our Moundsville facility as set forth in a Notice of Noncompliance issued by the EPA on January 14, 2016. The notice includes an offer to avoid further legal action on the alleged violations by paying $2,000,000. We are currently evaluating the communication and our response.
Other
The additional information called for by this item is provided in Note 18 – Contingent Liabilities and Commitments of Notes to Consolidated Financial Statements included under Part II, Item 8 Financial Statements of this report, which information is incorporated by reference into this item.
Item 4. Mine Safety Disclosures
Not applicable.
Executive Officers of the Registrant
The name, age, period of service, and title of each of our executive officers as of February 22, 2017, are listed below. As previously discussed, Williams Partners L.P. merged with ACMP in February 2015 (the ACMP Merger). ACMP was the surviving entity in the ACMP Merger and changed its name to Williams Partners L.P. References in the biographical information below to (a) “Pre-merger WPZ” will mean Williams Partners L.P. prior to the ACMP Merger and (b) “ACMP/WPZ” will refer to both ACMP prior to and after the ACMP Merger, when it changed its name to Williams Partners L.P.
| Alan S. Armstrong | Director, Chief Executive Officer, and President |
| Age: 54 | |
| Position held since 2011. | |
| From 2002 to 2011, Mr. Armstrong served as Senior Vice President - Midstream and acted as President of our midstream business. From 1999 to 2002, Mr. Armstrong was Vice President, Gathering and Processing in our midstream business and from 1998 to 1999 was Vice President, Commercial Development. Mr. Armstrong has served as a director of the general partner of ACMP/WPZ since 2012, as Chief Executive Officer since December 31, 2014, and as Chairman of the Board since February 2, 2015. Mr. Armstrong has served as a director of BOK Financial Corporation, a financial services company, since 2013. Mr. Armstrong also served as Chairman of the Board and Chief Executive Officer of the general partner of Pre-merger WPZ from 2011 until the ACMP Merger, as Senior Vice President - Midstream from 2010 to 2011, and director and Chief Operating Officer from 2005 to 2010. |
| Walter J. Bennett | Senior Vice President — West |
| Age: 47 | |
| Position held since January 2015. | |
| Mr. Bennett was formerly Chief Operating Officer of Chesapeake Midstream Development and served as Senior Vice President-Operations at Boardwalk Pipeline Partners. Previously, Mr. Bennett served in a variety of senior positions at Gulf South Pipeline Company that included operations and commercial responsibilities. Mr. Bennett began his career at a subsidiary of Koch Industries. Mr. Bennett has served as Senior Vice President - West of the general partner of ACMP/WPZ since December 2013 and served as Senior Vice President - West of the general partner of Pre-merger WPZ from January 2015 until the ACMP Merger. He has served as a director of the general partner of ACMP/WPZ since February 2017. |
| Francis (Frank) E. Billings | Senior Vice President — Corporate Strategic Development |
| Age: 54 | |
| Position held since January 2014. | |
| Mr. Billings served as Senior Vice President - Northeast G&P of us and Pre-merger WPZ from January 2013 to January 2014. Mr. Billings served as Vice President of our midstream gathering and processing business from 2011 until 2013 and as Vice President, Business Development from 2010 to 2011. Mr. Billings served as President of Cumberland Plateau Pipeline Company, a privately held company developing an ethane pipeline to serve the Marcellus Shale area, from 2009 until 2010. From 2008 to 2009, Mr. Billings served as Senior Vice President of Commercial for Crosstex Energy, Inc. and Crosstex Energy L.P., an independent midstream energy services master limited partnership and its parent corporation. In 1988, Mr. Billings joined MAPCO Inc., which merged with one of our subsidiaries in 1998, serving in various management roles, including in 2008 as a Vice President in the midstream business. Mr. Billings served as Senior Vice President - Corporate Strategic Development of the general partner of Pre-merger WPZ from January 2014 until the ACMP Merger. He has served as Senior Vice President - Corporate Strategic Development since the ACMP Merger, and as a director of the general partner of ACMP/WPZ since the ACMP Merger until February 2017. |
| Donald R. Chappel | Senior Vice President and Chief Financial Officer |
| Age: 65 | |
| Position held since 2003. | |
| Prior to joining us, Mr. Chappel held various financial, administrative and operational leadership positions. Mr. Chappel has served as a director of the general partner of ACMP/WPZ since 2012 and as Chief Financial Officer of the general partner of ACMP/WPZ since December 31, 2014. Mr. Chappel has also served as a member of the Management Committee of Northwest Pipeline since 2007. Mr. Chappel served as Chief Financial Officer and a director of the general partner of Pre-merger WPZ from 2005 until the ACMP Merger. Mr. Chappel was Chief Financial Officer from 2007 and a director from 2008 of the general partner of Williams Pipeline Partners L.P. (WMZ), until its merger with Pre-merger WPZ in 2010. Mr. Chappel is a director of SUPERVALU, Inc. (a grocery and pharmacy company). |
| John R. Dearborn | Senior Vice President — NGL & Petchem Services |
| Age: 59 | |
| Position held since 2013. | |
| Mr. Dearborn served as a senior leader for Saudi Basic Industries Corporation, a petrochemical company, from 2011 to 2013. From 2001 to 2011, Mr. Dearborn served in a variety of leadership positions with the Dow Chemical Company. Mr. Dearborn also worked for Union Carbide Corporation, prior to its merger with DOW, from 1981 to 2001 where he served in several leadership roles. Mr. Dearborn also served as Senior Vice President - NGL & Petchem Services of the general partner of Pre-merger WPZ from 2013 until the ACMP Merger and has served in that role for the general partner of ACMP/WPZ since the ACMP Merger. |
| Robyn L. Ewing | Senior Vice President and Chief Administrative Officer |
| Age: 61 | |
| Position held since 2008. | |
| From 2004 to 2008, Ms. Ewing was Vice President of Human Resources. Prior to joining Williams, Ms. Ewing worked at MAPCO, which merged with Williams in 1998. Ms. Ewing began her career with Cities Service Company in 1976. |
| Rory L. Miller | Senior Vice President — Atlantic - Gulf |
| Age: 56 | |
| Position held since 2013. | |
| From 2011 until 2013, Mr. Miller was Senior Vice President - Midstream of Williams and the general partner of Pre-merger WPZ, acting as President of Williams’ midstream business. Mr. Miller was a Vice President of Williams’ midstream business from 2004 until 2011. Mr. Miller served as a director and Senior Vice-President - Atlantic-Gulf of the general partner of Pre-merger WPZ from 2011 until the ACMP Merger and has served in those roles for the general partner of ACMP/WPZ since the ACMP Merger. Mr. Miller has also served as a member of the Management Committee of Transco, since 2013. |
| Sarah C. Miller | Senior Vice President and General Counsel |
| Age: 45 | |
| Position held since 2015. | |
| Ms. Miller joined Williams in 2000, where she has served in a variety of legal leadership positions, including Vice President, Corporate Secretary and Assistant General Counsel for the company’s corporate secretary team, Senior Counsel for the company’s midstream business, and as Senior Attorney for the legal department’s business development team. She was named Senior Vice President and General Counsel on June 20, 2015. Prior to joining Williams, Ms. Miller was a litigation associate at Crowe & Dunlevy. |
| James E. Scheel | Senior Vice President — Northeast G&P |
| Age: 52 | |
| Position held since January 2014. | |
| From 2012 to 2014, Mr. Scheel served as Senior Vice President - Corporate Strategic Development of us and the general partner of Pre-merger WPZ. From 2011 until 2012, Mr. Scheel served as Vice President of Business Development for our midstream business. Mr. Scheel joined Williams in 1988 and has served in leadership roles in business strategic development, engineering and operations, our NGL business, and international operations. Mr. Scheel has served as a director and Senior Vice President - Northeast G&P of the general partner of ACMP/WPZ since the ACMP Merger, having previously served as a director of the general partner of ACMP/WPZ from 2012 to February 2014. Mr. Scheel served as a director of the general partner of Pre-merger WPZ from 2012 until the ACMP Merger. |
| John D. Seldenrust | Senior Vice President — Engineering Services |
| Age: 52 | |
| Position held since July 2015. | |
| Mr. Seldenrust served as Senior Vice President - Eastern Operations for us from January 2015 to July 2015, and for ACMP/WPZ from 2013 to July 2015. Mr. Seldenrust also previously served in a variety of operations and engineering leadership roles at ACMP and Chesapeake Energy from 2004 to August 2013. Prior to joining Chesapeake, Mr. Seldenrust held reservoir, production and facilities engineering positions with ARCO Oil & Gas, Vastar Resources and BP America. |
| Ted T. Timmermans | Vice President, Controller, and Chief Accounting Officer |
| Age: 60 | |
| Position held since 2005. | |
| Mr. Timmermans served as Assistant Controller of Williams from 1998 to 2005. Mr. Timmermans served as Vice President, Controller & Chief Accounting Officer of the general partner of Pre-merger WPZ until the ACMP Merger and has served in those roles for the general partner of ACMP/WPZ since the ACMP Merger. Mr. Timmermans served as Chief Accounting Officer of the general partner of WMZ from 2008 until its merger with Pre-merger WPZ in 2010. |
PART II
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
Our common stock is listed on the New York Stock Exchange under the symbol “WMB.” At the close of business on February 17, 2017, we had approximately 7,376 holders of record of our common stock. The high and low sales price ranges (New York Stock Exchange composite transactions) and dividends declared by quarter for each of the past two years are as follows:
| High | Low | Dividend | |||||||||
| 2016 | |||||||||||
| First Quarter | $ | 26.68 | $ | 10.22 | $ | 0.64 | |||||
| Second Quarter | 23.89 | 14.60 | 0.64 | ||||||||
| Third Quarter | 31.43 | 19.68 | 0.20 | ||||||||
| Fourth Quarter | 32.21 | 27.35 | 0.20 | ||||||||
| 2015 | |||||||||||
| First Quarter | $ | 51.15 | $ | 40.07 | $ | 0.58 | |||||
| Second Quarter | 61.38 | 46.28 | 0.59 | ||||||||
| Third Quarter | 58.77 | 34.64 | 0.64 | ||||||||
| Fourth Quarter | 44.51 | 20.95 | 0.64 |
Some of our subsidiaries’ borrowing arrangements may limit the transfer of funds to us. These terms have not impeded, nor are they expected to impede, our ability to pay dividends. On February 20, 2017, our board of directors approved a regular quarterly dividend of $0.30 per share payable on March 27, 2017, representing a 50 percent increase from our previous quarterly dividend.
Performance Graph
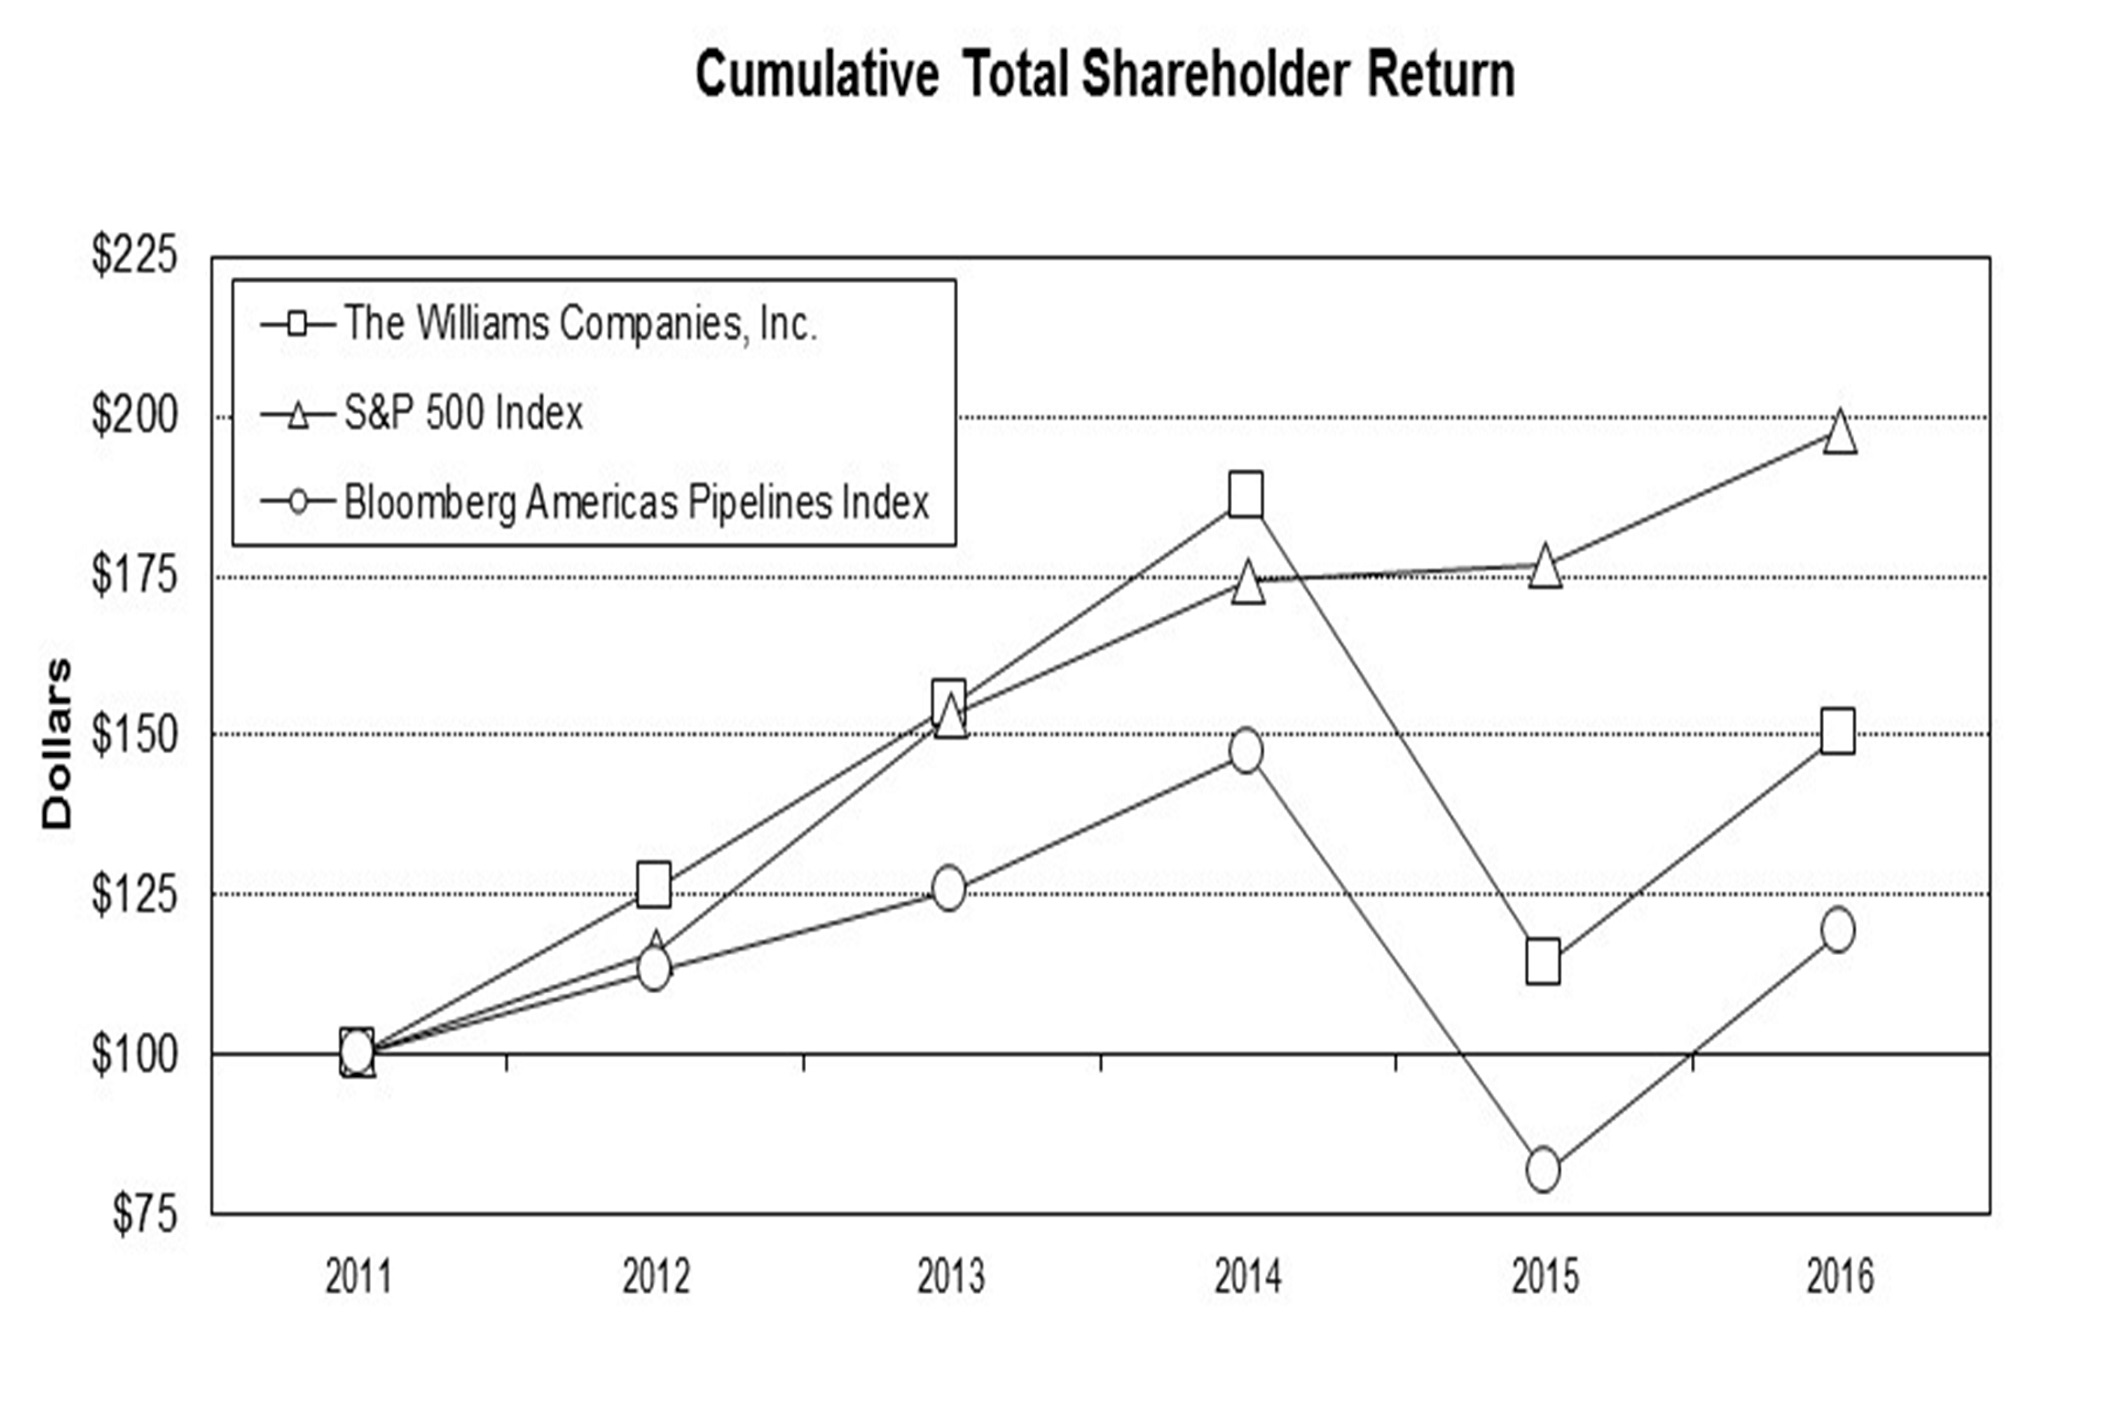
Set forth below is a line graph comparing our cumulative total stockholder return on our common stock (assuming reinvestment of dividends) with the cumulative total return of the S&P 500 Stock Index and the Bloomberg Americas Pipelines Index for the period of five fiscal years commencing January 1, 2012. The Bloomberg Americas Pipelines Index is composed of Enbridge, Inc., Inter Pipeline Ltd., Kinder Morgan, Inc., ONEOK, Inc., Pembina Pipeline Corp, Plains GP Holdings LP, Spectra Energy Corp, TransCanada Corp., Keyera Corp., AltaGas Ltd., and Williams. The graph below assumes an investment of $100 at the beginning of the period.
| 2011 | 2012 | 2013 | 2014 | 2015 | 2016 | ||||||
| The Williams Companies, Inc. | 100.0 | 126.1 | 154.5 | 187.4 | 114.2 | 150.0 | |||||
| S&P 500 Index | 100.0 | 115.9 | 153.4 | 174.3 | 176.8 | 197.8 | |||||
| Bloomberg Americas Pipelines Index | 100.0 | 113.4 | 125.9 | 147.3 | 81.5 | 119.2 |
Item 6. Selected Financial Data
The following financial data at December 31, 2016 and 2015, and for each of the three years in the period ended December 31, 2016, should be read in conjunction with the other financial information included in Part II, Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations and Part II, Item 8, Financial Statements and Supplementary Data of this Form 10-K. All other financial data has been prepared from our accounting records.
| 2016 | 2015 | 2014 | 2013 | 2012 | |||||||||||||||
| (Millions, except per-share amounts) | |||||||||||||||||||
| Revenues (1) | $ | 7,499 | $ | 7,360 | $ | 7,637 | $ | 6,860 | $ | 7,486 | |||||||||
| Income (loss) from continuing operations (2) | (350 | ) | (1,314 | ) | 2,335 | 679 | 929 | ||||||||||||
| Amounts attributable to The Williams Companies, Inc.: | |||||||||||||||||||
| Income (loss) from continuing operations (2) | (424 | ) | (571 | ) | 2,110 | 441 | 723 | ||||||||||||
| Diluted earnings (loss) per common share: | |||||||||||||||||||
| Income (loss) from continuing operations (2) | (.57 | ) | (.76 | ) | 2.91 | .64 | 1.15 | ||||||||||||
| Total assets at December 31 (3) | 46,835 | 49,020 | 50,455 | 27,065 | 24,248 | ||||||||||||||
| Commercial paper and long-term debt due within one year at December 31 (4) | 878 | 675 | 802 | 226 | 1 | ||||||||||||||
| Long-term debt at December 31 (3) | 22,624 | 23,812 | 20,780 | 11,276 | 10,656 | ||||||||||||||
| Stockholders’ equity at December 31 (3) | 4,643 | 6,148 | 8,777 | 4,864 | 4,752 | ||||||||||||||
| Cash dividends declared per common share | 1.680 | 2.450 | 1.9575 | 1.438 | 1.196 |
| (1) | Revenues for 2014 increased reflecting the consolidation of ACMP beginning in third quarter and new Canadian construction management services. |
| (2) | Income (loss) from continuing operations: |
| • | For 2016 includes an $873 million impairment of certain assets and a $430 million impairment of certain equity-method investments; |
| • | For 2015 includes a $1.4 billion impairment of certain equity-method investments and a $1.1 billion impairment of goodwill; |
| • | For 2014 includes $2.5 billion pretax gain recognized as a result of remeasuring to fair value the equity-method investment we held before we acquired a controlling interest in ACMP, $246 million of insurance recoveries related to the 2013 Geismar Incident, and $154 million of cash received related to a contingency settlement. 2014 also includes $78 million of pretax equity losses from Bluegrass Pipeline and Moss Lake related primarily to the underlying write-off of previously capitalized project development costs and $76 million of pretax acquisition, merger, and transition expenses related to our acquisition of ACMP; |
| • | For 2013 includes $99 million of deferred income tax expense incurred on undistributed earnings of our foreign operations that are no longer considered permanently reinvested. |
| (3) | The increases in 2014 reflect assets acquired and debt assumed primarily related to our acquisition of ACMP (see Note 2 – Acquisitions) in third quarter as well as $1.9 billion of related debt issuances and $2.8 billion of debt issuances at WPZ. Additionally, we issued $3.4 billion of equity (see Note 15 – Stockholders' Equity). |
| (4) | The increases in 2014 and 2013 reflect borrowings under WPZ’s commercial paper program, which was initiated in 2013. |
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
General
We are an energy infrastructure company focused on connecting North America’s significant hydrocarbon resource plays to growing markets for natural gas, NGLs, and olefins. Our operations are located principally in the United States and are organized into the Williams Partners and Williams NGL & Petchem Services reportable segments. All remaining business activities are included in Other.
Williams Partners
Williams Partners consists of our consolidated master limited partnership, WPZ, which includes gas pipeline and midstream businesses. The gas pipeline businesses include interstate natural gas pipelines and pipeline joint project investments; and the midstream businesses provide natural gas gathering, treating, and processing services; NGL production, fractionation, storage, marketing and transportation; deepwater production handling and crude oil transportation services; an olefin production business, and is comprised of several wholly owned and partially owned subsidiaries and joint project investments. As of December 31, 2016, we owned approximately 60 percent of the interests in WPZ, including the interests of the general partner, which were wholly owned by us, and IDRs.
Williams Partners’ gas pipeline businesses consist primarily of Transco and Northwest Pipeline. The gas pipeline business also holds interests in joint venture interstate and intrastate natural gas pipeline systems including a 50 percent equity-method investment in Gulfstream and a 41 percent interest in Constitution (a consolidated entity), which is under development. As of December 31, 2016, Transco and Northwest Pipeline own and operate a combined total of approximately 13,600 miles of pipelines with a total annual throughput of approximately 4,230 Tbtu of natural gas and peak-day delivery capacity of approximately 15.5 MMdth of natural gas.
Williams Partners' midstream businesses primarily consist of (1) natural gas gathering, treating, compression, and processing; (2) NGL fractionation, storage and transportation; (3) crude oil production handling and transportation; and (4) olefins production. (See Geismar Olefins Facility Monetization below.) The primary service areas are concentrated in major producing basins in Colorado, Texas, Oklahoma, Kansas, New Mexico, Wyoming, the Gulf of Mexico, Louisiana, Pennsylvania, West Virginia, New York, and Ohio which include the Barnett, Eagle Ford, Haynesville, Marcellus, Niobrara, and Utica Shale plays as well as the Mid-Continent region.
The midstream businesses include equity-method investments in natural gas gathering and processing assets and NGL fractionation and transportation assets, including a 62 percent equity-method investment in UEOM, a 50 percent equity-method investment in the Delaware basin gas gathering system (DBJV) in the Mid-Continent region, a 69 percent equity-method investment in Laurel Mountain, a 58 percent equity-method investment in Caiman II, a 60 percent equity-method investment in Discovery, a 50 percent equity-method investment in OPPL, and Appalachia Midstream Services, LLC, which owns an approximate average 41 percent equity-method investment interest in multiple gas gathering systems in the Marcellus Shale (Appalachia Midstream Investments).
The midstream businesses previously included our Canadian midstream operations, which were comprised of an oil sands offgas processing plant near Fort McMurray, Alberta and an NGL/olefin fractionation facility at Redwater, Alberta. In September 2016, these Canadian operations were sold. (See Note 3 – Divestiture of Notes to Consolidated Financial Statements.)
Williams Partners’ ongoing strategy is to safely and reliably operate large-scale, interstate natural gas transmission and midstream infrastructures where our assets can be fully utilized and drive low per-unit costs. We focus on consistently attracting new business by providing highly reliable service to our customers and investing in growing markets, including the deepwater Gulf of Mexico, the Marcellus Shale, the Gulf Coast Region, and areas of increasing natural gas demand.
Williams Partners’ interstate transmission and related storage activities are subject to regulation by the FERC and as such, our rates and charges for the transportation of natural gas in interstate commerce, and the extension, expansion
or abandonment of jurisdictional facilities and accounting, among other things, are subject to regulation. The rates are established through the FERC’s ratemaking process. Changes in commodity prices and volumes transported have limited near-term impact on these revenues because the majority of cost of service is recovered through firm capacity reservation charges in transportation rates.
Williams NGL & Petchem Services
Williams NGL & Petchem Services includes certain domestic olefins pipeline assets as well as the previously owned Canadian assets which included a liquids extraction plant near Fort McMurray, Alberta, that began operations in March 2016 and a propane dehydrogenation facility under development in Canada. In September 2016, these Canadian operations were sold. (See Note 3 – Divestiture of Notes to Consolidated Financial Statements.)
Unless indicated otherwise, the following discussion and analysis of results of operations and financial condition and liquidity relates to our current continuing operations and should be read in conjunction with the consolidated financial statements and notes thereto included in Part II, Item 8 of this report.
Dividends
In December 2016, we paid a regular quarterly dividend of $0.20 per share. On February 20, 2017, our board of directors approved a regular quarterly dividend of $0.30 per share payable on March 27, 2017, representing a 50 percent increase from our previous quarterly dividend.
Overview
Net income (loss) attributable to The Williams Companies, Inc., for the year ended December 31, 2016, increased $147 million compared to the year ended December 31, 2015, reflecting the absence of certain goodwill impairments, lower impairments of equity-method investments, an increase in olefins margins associated with our Geismar plant, decreases in operating and maintenance expenses, and higher equity earnings. These favorable changes were partially offset by an unfavorable change in net income attributable to noncontrolling interests driven primarily by higher WPZ income as well as the impact of reduced incentive distributions from WPZ associated with the termination of the WPZ Merger Agreement. The favorable changes were also partially offset by increased impairment charges and loss on sale associated with our Canadian operations, lower insurance recoveries, as well as higher interest incurred. See additional discussion in Results of Operations.
Acquisition of Additional Interests in Appalachia Midstream Investments
In February, 2017, we announced agreements to acquire additional interests in two Marcellus Shale gathering systems within Williams Partners’ Appalachia Midstream Investments in exchange for equity-method investment interests in DBJV and the Ranch Westex gas processing plant, both currently reported within the Williams Partners segment. We also expect to receive a total of $200 million in cash as part of the agreements subject to customary closing conditions and purchase price adjustments. The transactions are expected to close in late first-quarter or early second-quarter 2017.
Financial Repositioning
In January 2017, we announced agreements with WPZ, wherein we permanently waived the general partner’s incentive distribution rights and converted our 2 percent general partner interest in WPZ to a non-economic interest in exchange for 289 million newly issued WPZ common units. Pursuant to this agreement, we also purchased approximately 277 thousand WPZ common units for $10 million. Additionally, we purchased approximately 59 million common units of WPZ at a price of $36.08586 per unit in a private placement transaction
Showing the first 8K of 116K characters. Open the full section
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
Interest Rate Risk
Our current interest rate risk exposure is related primarily to our debt portfolio. Our debt portfolio is primarily comprised of fixed rate debt, which mitigates the impact of fluctuations in interest rates. Any borrowings under the credit facilities and any issuances under WPZ’s commercial paper program could be at a variable interest rate and could expose us to the risk of increasing interest rates. The maturity of our long-term debt portfolio is partially influenced by the expected lives of our operating assets. (See Note 14 – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements.)
The tables below provide information by maturity date about our interest rate risk-sensitive instruments as of December 31, 2016 and 2015. Long-term debt in the tables represents principal cash flows, net of (discount) premium and debt issuance costs, and weighted-average interest rates by expected maturity dates. The fair value of our publicly traded long-term debt is valued using indicative year-end traded bond market prices. Private debt is valued based on market rates and the prices of similar securities with similar terms and credit ratings.
| 2017 | 2018 | 2019 | 2020 | 2021 | Thereafter (1) | Total | Fair Value December 31, 2016 | |||||||||||||||||
| (Millions) | ||||||||||||||||||||||||
| Long-term debt, including current portion: | ||||||||||||||||||||||||
| Fixed rate | $ | 785 | $ | 500 | $ | 32 | $ | 2,121 | $ | 871 | $ | 17,475 | $ | 21,784 | $ | 22,465 | ||||||||
| Interest rate | 5.2 | % | 5.2 | % | 5.2 | % | 5.2 | % | 5.2 | % | 5.6 | % | ||||||||||||
| Variable rate | $ | — | $ | 850 | $ | — | $ | 775 | $ | — | $ | — | $ | 1,625 | $ | 1,625 | ||||||||
| Interest rate (3) | ||||||||||||||||||||||||
| Commercial paper: | ||||||||||||||||||||||||
| Variable rate | $ | 93 | $ | — | $ | — | $ | — | $ | — | $ | — | $ | 93 | $ | 93 | ||||||||
| Interest rate (4) | ||||||||||||||||||||||||
| 2016 | 2017 | 2018 | 2019 | 2020 | Thereafter (1) | Total | Fair Value December 31, 2015 | |||||||||||||||||
| (Millions) | ||||||||||||||||||||||||
| Long-term debt, including current portion: (2) | ||||||||||||||||||||||||
| Fixed rate | $ | 375 | (*) | $ | 785 | $ | 500 | $ | 32 | $ | 2,121 | $ | 17,364 | $ | 21,177 | $ | 16,796 | |||||||
| Interest rate | 5.1 | % | 5.1 | % | 5.0 | % | 5.0 | % | 5.0 | % | 5.5 | % | ||||||||||||
| Variable rate | $ | — | $ | — | $ | 850 | $ | — | $ | 1,960 | $ | — | $ | 2,810 | $ | 2,810 | ||||||||
| Interest rate (5) | ||||||||||||||||||||||||
| Commercial paper: | ||||||||||||||||||||||||
| Variable rate | $ | 499 | $ | — | $ | — | $ | — | $ | — | $ | — | $ | 499 | $ | 499 | ||||||||
| Interest rate (4) | ||||||||||||||||||||||||
| _____________ | ||||||||||||||||||||||||
| (*) $200 million presented as long-term debt at December 31, 2015, due to WPZ’s intent and ability to refinance. |
| (1) | Includes unamortized discount / premium and debt issuance costs. |
| (2) | Excludes capital leases. |
| (3) | The weighted-average interest rates for WPZ’s $850 million term loan, and our $775 million credit facility borrowing at December 31, 2016 were 2.50 percent and 2.51 percent, respectively. |
| (4) | The weighted-average interest rate was 1.06 percent and 0.92 percent at December 31, 2016 and 2015, respectively. |
| (5) | The weighted-average interest rates for WPZ’s $1.3 billion credit facility borrowing, WPZ’s $850 million term loan, and our $650 million credit facility borrowing at December 31, 2015 were 1.63 percent, 1.85 percent, and 2.32 percent, respectively. |
Commodity Price Risk
We are exposed to the impact of fluctuations in the market price of NGLs, olefins, and natural gas, as well as other market factors, such as market volatility and energy commodity price correlations. We are exposed to these risks in connection with our owned energy-related assets, our long-term energy-related contracts, and limited proprietary trading activities. Our management of the risks associated with these market fluctuations includes maintaining sufficient liquidity, as well as using various derivatives and nonderivative energy-related contracts. The fair value of derivative contracts is subject to many factors, including changes in energy commodity market prices, the liquidity and volatility of the markets in which the contracts are transacted, and changes in interest rates. At December 31, 2016 and 2015, our derivative activity was not material. (See Note 17 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
Foreign Currency Risk
In September 2016, we disposed of our Canadian operations, which comprised substantially all of our foreign operations. (See Note 3 – Divestiture of Notes to Consolidated Financial Statements.)
Item 8. Financial Statements and Supplementary Data
Report of Independent Registered Public Accounting Firm
The Board of Directors and Stockholders of
The Williams Companies, Inc.
We have audited the accompanying consolidated balance sheet of The Williams Companies, Inc. as of December 31, 2016 and 2015, and the related consolidated statements of operations, comprehensive income (loss), changes in equity and cash flows for each of the three years in the period ended December 31, 2016. Our audits also included the financial statement schedules listed in the index at Item 15(a). These financial statements and schedules are the responsibility of the Company's management. Our responsibility is to express an opinion on these financial statements and schedules based on our audits. We did not audit the financial statements of Gulfstream Natural Gas System, L.L.C. (“Gulfstream”), a limited liability corporation in which the Company has a 50 percent interest. In the consolidated financial statements, the Company’s investment in Gulfstream was $261 million and $293 million as of December 31, 2016 and 2015, respectively, and the Company’s equity earnings in the net income of Gulfstream were $69 million and $65 million, respectively, for the years then ended. For the periods indicated above, Gulfstream’s financial statements were audited by other auditors whose report has been furnished to us, and our opinion, insofar as it relates to the amounts included for Gulfstream for 2016 and 2015, is based solely on the report of the other auditors.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement. An audit includes examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements. An audit also includes assessing the accounting principles used and significant estimates made by management, as well as evaluating the overall financial statement presentation. We believe that our audits and the report of other auditors provide a reasonable basis for our opinion.
In our opinion, based on our audits and, for 2016 and 2015, the report of other auditors, the financial statements referred to above present fairly, in all material respects, the consolidated financial position of The Williams Companies, Inc. at December 31, 2016 and 2015, and the consolidated results of its operations and its cash flows for each of the three years in the period ended December 31, 2016, in conformity with U.S. generally accepted accounting principles. Also, in our opinion, the related financial statement schedules, when considered in relation to the basic financial statements taken as a whole, present fairly in all material respects the information set forth therein.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), The Williams Companies, Inc.'s internal control over financial reporting as of December 31, 2016, based on criteria established in Internal Control - Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated February 22, 2017 expressed an unqualified opinion thereon.
/s/ Ernst & Young LLP
Tulsa, Oklahoma
February 22, 2017
Report of Independent Registered Public Accounting Firm
To the Members of Gulfstream Natural Gas System, L.L.C.
We have audited the balance sheets of Gulfstream Natural Gas System, L.L.C. (the “Company”) as of December 31, 2016 and 2015, and the related statements of operations, comprehensive income, cash flows, and members’ equity for each of the three years in the period ended December 31, 2016. These financial statements are the responsibility of the Company's management. Our responsibility is to express an opinion on these financial statements based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States) and in accordance with auditing standards generally accepted in the United States of America. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement. The Company is not required to have, nor were we engaged to perform, an audit of its internal control over financial reporting. Our audits included consideration of internal control over financial reporting as a basis for designing audit procedures that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the effectiveness of the Company's internal control over financial reporting. Accordingly, we express no such opinion. An audit also includes examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements, assessing the accounting principles used and significant estimates made by management, as well as evaluating the overall financial statement presentation. We believe that our audits provide a reasonable basis for our opinion.
In our opinion, such financial statements present fairly, in all material respects, the financial position of Gulfstream Natural Gas System, L.L.C. as of December 31, 2016 and 2015, and the results of its operations and its cash flows for each of the three years in the period ended December 31, 2016, in conformity with accounting principles generally accepted in the United States of America.
/s/ DELOITTE & TOUCHE LLP
Houston, Texas
February 22, 2017
The Williams Companies, Inc.
Consolidated Statement of Operations
| Years Ended December 31, | ||||||||||||
| 2016 | 2015 | 2014 | ||||||||||
| (Millions, except per-share amounts) | ||||||||||||
| Revenues: | ||||||||||||
| Service revenues | $ | 5,171 | $ | 5,164 | $ | 4,116 | ||||||
| Product sales | 2,328 | 2,196 | 3,521 | |||||||||
| Total revenues | 7,499 | 7,360 | 7,637 | |||||||||
| Costs and expenses: | ||||||||||||
| Product costs | 1,725 | 1,779 | 3,016 | |||||||||
| Operating and maintenance expenses | 1,580 | 1,655 | 1,492 | |||||||||
| Depreciation and amortization expenses | 1,763 | 1,738 | 1,176 | |||||||||
| Selling, general, and administrative expenses | 723 | 741 | 661 | |||||||||
| Impairment of goodwill (Note 17) | — | 1,098 | — | |||||||||
| Impairment of certain assets (Note 17) | 873 | 209 | 52 | |||||||||
| Net insurance recoveries – Geismar Incident | (7 | ) | (126 | ) | (232 | ) | ||||||
| Other (income) expense – net | 142 | 40 | (97 | ) | ||||||||
| Total costs and expenses | 6,799 | 7,134 | 6,068 | |||||||||
| Operating income (loss) | 700 | 226 | 1,569 | |||||||||
| Equity earnings (losses) | 397 | 335 | 144 | |||||||||
| Gain on remeasurement of equity-method investment (Note 2) | — | — | 2,544 | |||||||||
| Impairment of equity-method investments (Note 17) | (430 | ) | (1,359 | ) | — | |||||||
| Other investing income (loss) – net | 63 | 27 | 43 | |||||||||
| Interest incurred | (1,217 | ) | (1,118 | ) | (888 | ) | ||||||
| Interest capitalized | 38 | 74 | 141 | |||||||||
| Other income (expense) – net | 74 | 102 | 31 | |||||||||
| Income (loss) from continuing operations before income taxes | (375 | ) | (1,713 | ) | 3,584 | |||||||
| Provision (benefit) for income taxes | ( |
Showing the first 8K of 281K characters. Open the full section
Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure
None.
Item 9A. Controls and Procedures
Disclosure Controls and Procedures
Our management, including our Chief Executive Officer and Chief Financial Officer, does not expect that our disclosure controls and procedures (as defined in Rules 13a - 15(e) and 15d - 15(e) of the Securities Exchange Act) (Disclosure Controls) will prevent all errors and all fraud. A control system, no matter how well conceived and operated, can provide only reasonable, not absolute, assurance that the objectives of the control system are met. Further, the design of a control system must reflect the fact that there are resource constraints, and the benefits of controls must be considered relative to their costs. Because of the inherent limitations in all control systems, no evaluation of controls can provide absolute assurance that all control issues and instances of fraud, if any, within the company have been detected. These inherent limitations include the realities that judgments in decision-making can be faulty, and that breakdowns can occur because of simple error or mistake. Additionally, controls can be circumvented by the individual acts of some persons, by collusion of two or more people, or by management override of the control. The design of any system of controls also is based in part upon certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals under all potential future conditions. Because of the inherent limitations in a cost-effective control system, misstatements due to error or fraud may occur and not be detected. We monitor our Disclosure Controls and make modifications as necessary; our intent in this regard is that the Disclosure Controls will be modified as systems change and conditions warrant.
Evaluation of Disclosure Controls and Procedures
An evaluation of the effectiveness of the design and operation of our Disclosure Controls was performed as of the end of the period covered by this report. This evaluation was performed under the supervision and with the participation of our management, including our Chief Executive Officer and Chief Financial Officer. Based upon that evaluation, our Chief Executive Officer and Chief Financial Officer concluded that these Disclosure Controls are effective at a reasonable assurance level.
Changes in Internal Control Over Financial Reporting
There have been no changes during the fourth quarter of 2016 that have materially affected, or are reasonably likely to materially affect, our Internal Control over Financial Reporting.
Management’s Annual Report on Internal Control over Financial Reporting
Management is responsible for establishing and maintaining adequate internal control over financial reporting (as defined in Rules 13a - 15(f) and 15d - 15(f) under the Securities Exchange Act of 1934). Our internal control over financial reporting is designed to provide reasonable assurance to our management and board of directors regarding the preparation and fair presentation of financial statements in accordance with accounting principles generally accepted in the United States. Our internal control over financial reporting includes those policies and procedures that (i) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of our assets; (ii) provide reasonable assurance that transactions are recorded as to permit preparation of financial statements in accordance with generally accepted accounting principles, and that our receipts and expenditures are being made only in accordance with authorization of our management and board of directors; and (iii) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use or disposition of our assets that could have a material effect on our financial statements.
All internal control systems, no matter how well designed, have inherent limitations including the possibility of human error and the circumvention or overriding of controls. Therefore, even those systems determined to be effective can provide only reasonable assurance with respect to financial statement preparation and presentation.
Under the supervision and with the participation of our management, including our Chief Executive Officer and Chief Financial Officer, we assessed the effectiveness of our internal control over financial reporting as of December 31, 2016, based on the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) in Internal Control — Integrated Framework (2013). Based on our assessment, we concluded that, as of December 31, 2016, our internal control over financial reporting was effective.
Ernst & Young LLP, our independent registered public accounting firm, has audited our internal control over financial reporting, as stated in their report which is included in this Annual Report on Form 10-K.
Report of Independent Registered Public Accounting Firm
On Internal Control Over Financial Reporting
The Board of Directors and Stockholders of
The Williams Companies, Inc.
We have audited The Williams Companies, Inc.’s internal control over financial reporting as of December 31, 2016, based on criteria established in Internal Control - Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria). The Williams Companies, Inc.’s management is responsible for maintaining effective internal control over financial reporting, and for its assessment of the effectiveness of internal control over financial reporting included in the accompanying Management’s Annual Report on Internal Control over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, testing and evaluating the design and operating effectiveness of internal control based on the assessed risk, and performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
In our opinion, The Williams Companies, Inc. maintained, in all material respects, effective internal control over financial reporting as of December 31, 2016, based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated balance sheet of The Williams Companies, Inc. as of December 31, 2016 and 2015, and the related consolidated statements of operations, comprehensive income (loss), changes in equity and cash flows for each of the three years in the period ended December 31, 2016, and our report dated February 22, 2017, expressed an unqualified opinion thereon.
/s/ Ernst & Young LLP
Tulsa, Oklahoma
February 22, 2017
Item 9B. Other Information
None.
PART III
Item 10. Directors, Executive Officers and Corporate Governance
The information regarding our directors and nominees for director required by Item 401 of Regulation S-K will be presented under the heading “Election of Directors” in our definitive proxy statement prepared for the solicitation of proxies in connection with our Annual Meeting of Stockholders to be held May 18, 2017, which shall be filed no later than April 30, 2017 (Proxy Statement), which information is incorporated by reference herein.
Information regarding our executive officers required by Item 401(b) of Regulation S-K is presented at the end of Part I herein and captioned “Executive Officers of the Registrant” as permitted by General Instruction G(3) to and Instruction 3 to Item 401(b) of Regulation S-K.
Information required by Item 405 of Regulation S-K will be included under the heading “Section 16(a) Beneficial Ownership Reporting Compliance” in our Proxy Statement, which information is incorporated by reference herein.
Information required by paragraphs (c)(3), (d)(4) and (d)(5) of Item 407 of Regulation S-K will be included under the heading “Questions and Answers About the Annual Meeting and Voting” and “Corporate Governance and Board Matters” in our Proxy Statement, which information is incorporated by reference herein.
We have adopted a Code of Ethics for Senior Officers that applies to our Chief Executive Officer, Chief Financial Officer, and Controller, or persons performing similar functions. The Code of Ethics for Senior Officers, together with our Corporate Governance Guidelines, the charters for each of our board committees, and our Code of Business Conduct applicable to all employees are available on our Internet website at www.williams.com. We will provide, free of charge, a copy of our Code of Ethics or any of our other corporate documents listed above upon written request to our Corporate Secretary at Williams, One Williams Center, Suite 4700, Tulsa, Oklahoma 74172. We intend to disclose any amendments to or waivers of the Code of Ethics on behalf of our Chief Executive Officer, Chief Financial Officer, Controller, and persons performing similar functions on the corporate governance section of our Internet website at www.williams.com, promptly following the date of any such amendment or waiver.
Item 11. Executive Compensation
The information required by Item 402 and paragraphs (e)(4) and (e)(5) of Item 407 of Regulation S-K regarding executive compensation will be presented under the headings “Compensation Discussion and Analysis,” “Executive Compensation and Other Information,” “Compensation of Directors,” “Compensation and Management Development Committee Report on Executive Compensation,” and “Compensation Committee Interlocks and Insider Participation” in our Proxy Statement, which information is incorporated by reference herein. Notwithstanding the foregoing, the information provided under the heading “Compensation Committee Report on Executive Compensation” in our Proxy Statement is furnished and shall not be deemed to be filed for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, is not subject to the liabilities of that section and is not deemed incorporated by reference in any filing under the Securities Act of 1933, as amended.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
The information regarding securities authorized for issuance under equity compensation plans required by Item 201
(d) of Regulation S-K and the security ownership of certain beneficial owners and management required by Item 403 of Regulation S-K will be presented under the headings “Equity Compensation Stock Plans” and “Security Ownership
of Certain Beneficial Owners and Management” in our Proxy Statement, which information is incorporated by reference herein.
Item 13. Certain Relationships and Related Transactions, and Director Independence
The information regarding certain relationships and related transactions required by Item 404 and Item 407(a) of Regulation S-K will be presented under the heading “Corporate Governance and Board Matters” in our Proxy Statement, which information is incorporated by reference herein.
Item 14. Principal Accountant Fees and Services
The information regarding our principal accounting fees and services required by Item 9(e) of Schedule 14A will be presented under the heading “Principal Accountant Fees and Services” in our Proxy Statement, which information is incorporated by reference herein.
PART IV
Item 15. Exhibits and Financial Statement Schedules
(a) 1 and 2.
All other schedules have been omitted since the required information is not present or is not present in amounts sufficient to require submission of the schedule, or because the information required is included in the financial statements and notes thereto.
(a) 3 and (b). The exhibits listed below are filed as part of this annual report.
INDEX TO EXHIBITS
| Exhibit No. | Description | |
| 2.1+ | — | Agreement and Plan of Merger dated as of May 12, 2015, by and among The Williams Companies, Inc., SCMS LLC, Williams Partners L.P., and WPZ GP LLC (filed on May 13, 2015 as Exhibit 2.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference). |
| 2.2 | — | Amendment No 1. to Agreement and Plan of Merger dated as of May 1, 2016, by and among The Williams Companies, Inc., Energy Transfer Corp LP, Energy Transfer Corp GP, LLC, Energy Transfer Equity, L.P., LE GP, LLC and Energy Transfer Equity GP, LLC (filed on May 3, 2016 as Exhibit 2.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference). |
| 2.3+ | — | Agreement and Plan of Merger dated as of September 28, 2015, by and among The Williams Companies, Inc., Energy Transfer Corp LP, Energy Transfer Corp GP, LLC, Energy Transfer Equity, L.P., LE GP, LLC and Energy Transfer Equity GP, LLC (filed on October 1, 2015 as Exhibit 2.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference). |
| Exhibit No. | Description | |
| 2.4 | — | Share Purchase Agreement by and between The Williams Companies International Holdings B.V. and Inter Pipeline Ltd. and The Williams Companies, Inc., dated August 8, 2016 (filed on August 12, 2016 as Exhibit 2.1 to The Williams Companies, Inc.’s current report on Form 8-K (file No. 001-04174) and incorporated herein by reference). |
| 2.5 | — | Share Purchase Agreement by and between Williams Energy Canada LP and Inter Pipeline Ltd. and Williams Partners L.P., dated August 8, 2016 (filed on August 12, 2016 as Exhibit 2.2 to The Williams Companies, Inc.’s current report on Form 8-K (file No. 001-04174) and incorporated herein by reference). |
| 2.6+ | — | Interest Swap and Purchase Agreement by and among Western Gas Partners, LP, WGR Operating, LP, Delaware Basin JV Gathering LLC, Williams Partners L.P., Williams Midstream Gas Services LLC, and Appalachia Midstream Services, L.L.C., dated February 9, 2017 (filed on February 10, 2017 as exhibit 2.1 to The Williams Companies Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference). |
| 3.1 | — | Amended and Restated Certificate of Incorporation, as supplemented (filed on May 26, 2010 as Exhibit 3.1 to The Williams Companies Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference). |
| 3.2 | — | By-Laws (filed on January 20, 2017, as Exhibit 3.1 to The Williams Companies Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference). |
| 4.1 | — | Senior Indenture dated February 25, 1997, between MAPCO Inc. and Bank One Trust Company, N.A. (formerly The First National Bank of Chicago), as Trustee (filed February 25, 1997 as Exhibit 4.5.1 to MAPCO Inc.’s Amendment No. l to registration statement on Form S-3 (File No. 333-20837) and incorporated herein by reference). |
| 4.2 | — | Supplemental Indenture No. 1 dated March 5, 1997, between MAPCO Inc. and Bank One Trust Company, N.A. (formerly The First National Bank of Chicago), as Trustee (filed as Exhibit 4(o) to MAPCO Inc.’s annual report on Form 10-K for the fiscal year ended December 31, 1997 (File No. 001-05254) and incorporated herein by reference). |
| 4.3 | — | Supplemental Indenture No. 2 dated March 5, 1997, between MAPCO Inc. and Bank One Trust Company, N.A. (formerly The First National Bank of Chicago), as Trustee (filed as Exhibit 4(p) to MAPCO Inc.’s annual report on Form 10-K for the fiscal year ended December 31, 1997 (File No. 001-05254) and incorporated herein by reference). |
| 4.4 | — | Supplemental Indenture No. 3 dated March 31, 1998, among MAPCO Inc., Williams Holdings of Delaware, Inc. and Bank One Trust Company, N.A. (formerly The First National Bank of Chicago), as Trustee (filed as Exhibit 4(J) to Williams Holdings of Delaware, Inc.’s annual report on Form 10 K for the fiscal year ended December 31, 1998 (File No. 000-20555) and incorporated herein by reference). |
| 4.5 | — | Supplemental Indenture No. 4 dated as of July 31, 1999, among Williams Holdings of Delaware, Inc., Williams and Bank One Trust Company, N.A. (formerly The First National Bank of Chicago), as Trustee (filed on March 28, 2000 as Exhibit 4(q) to The Williams Companies, Inc.’s annual report on Form 10-K (File No. 001-04174) and incorporated herein by reference). |
| 4.6 | — | Fifth Supplemental Indenture between Williams and Bank One Trust Company, N.A., as Trustee, dated as of January 17, 2001 (filed on March 12, 2001 as Exhibit 4(k) to The Williams Companies, Inc.’s annual report on Form 10-K (File No. 001-04174) and incorporated herein by reference). |
| 4.7 | — | Seventh Supplemental Indenture dated March 19, 2002, between The Williams Companies, Inc. as Issuer and Bank One Trust Company, National Association, as Trustee (filed on May 9, 2002 as Exhibit 4.1 to The Williams Companies, Inc.’s quarterly report on Form 10-Q (File No. 001-04174) and incorporated herein by reference). |
| Exhibit No. | Description | |
| 4.8 | — | Indenture dated as of May 28, 2003, by and between The Williams Companies, Inc. and JPMorgan Chase Bank, as Trustee for the issuance of the 5.50% Junior Subordinated Convertible Debentures due 2033 (filed on August 12, 2003 as Exhibit 4.2 to The Williams Companies, Inc.’s quarterly report on Form 10-Q (File No. 001-04174) and incorporated herein by reference). |
| 4.9 | — | Indenture dated as of March 5, 2009, among Th |
Showing the first 8K of 78K characters. Open the full section