 filings.tools
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
116K characters. Original on sec.gov · Markdown
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
General
We are an energy infrastructure company focused on connecting North America’s significant hydrocarbon resource plays to growing markets for natural gas, NGLs, and olefins. Our operations are located principally in the United States and are organized into the Williams Partners and Williams NGL & Petchem Services reportable segments. All remaining business activities are included in Other.
Williams Partners
Williams Partners consists of our consolidated master limited partnership, WPZ, which includes gas pipeline and midstream businesses. The gas pipeline businesses include interstate natural gas pipelines and pipeline joint project investments; and the midstream businesses provide natural gas gathering, treating, and processing services; NGL production, fractionation, storage, marketing and transportation; deepwater production handling and crude oil transportation services; an olefin production business, and is comprised of several wholly owned and partially owned subsidiaries and joint project investments. As of December 31, 2016, we owned approximately 60 percent of the interests in WPZ, including the interests of the general partner, which were wholly owned by us, and IDRs.
Williams Partners’ gas pipeline businesses consist primarily of Transco and Northwest Pipeline. The gas pipeline business also holds interests in joint venture interstate and intrastate natural gas pipeline systems including a 50 percent equity-method investment in Gulfstream and a 41 percent interest in Constitution (a consolidated entity), which is under development. As of December 31, 2016, Transco and Northwest Pipeline own and operate a combined total of approximately 13,600 miles of pipelines with a total annual throughput of approximately 4,230 Tbtu of natural gas and peak-day delivery capacity of approximately 15.5 MMdth of natural gas.
Williams Partners' midstream businesses primarily consist of (1) natural gas gathering, treating, compression, and processing; (2) NGL fractionation, storage and transportation; (3) crude oil production handling and transportation; and (4) olefins production. (See Geismar Olefins Facility Monetization below.) The primary service areas are concentrated in major producing basins in Colorado, Texas, Oklahoma, Kansas, New Mexico, Wyoming, the Gulf of Mexico, Louisiana, Pennsylvania, West Virginia, New York, and Ohio which include the Barnett, Eagle Ford, Haynesville, Marcellus, Niobrara, and Utica Shale plays as well as the Mid-Continent region.
The midstream businesses include equity-method investments in natural gas gathering and processing assets and NGL fractionation and transportation assets, including a 62 percent equity-method investment in UEOM, a 50 percent equity-method investment in the Delaware basin gas gathering system (DBJV) in the Mid-Continent region, a 69 percent equity-method investment in Laurel Mountain, a 58 percent equity-method investment in Caiman II, a 60 percent equity-method investment in Discovery, a 50 percent equity-method investment in OPPL, and Appalachia Midstream Services, LLC, which owns an approximate average 41 percent equity-method investment interest in multiple gas gathering systems in the Marcellus Shale (Appalachia Midstream Investments).
The midstream businesses previously included our Canadian midstream operations, which were comprised of an oil sands offgas processing plant near Fort McMurray, Alberta and an NGL/olefin fractionation facility at Redwater, Alberta. In September 2016, these Canadian operations were sold. (See Note 3 – Divestiture of Notes to Consolidated Financial Statements.)
Williams Partners’ ongoing strategy is to safely and reliably operate large-scale, interstate natural gas transmission and midstream infrastructures where our assets can be fully utilized and drive low per-unit costs. We focus on consistently attracting new business by providing highly reliable service to our customers and investing in growing markets, including the deepwater Gulf of Mexico, the Marcellus Shale, the Gulf Coast Region, and areas of increasing natural gas demand.
Williams Partners’ interstate transmission and related storage activities are subject to regulation by the FERC and as such, our rates and charges for the transportation of natural gas in interstate commerce, and the extension, expansion
or abandonment of jurisdictional facilities and accounting, among other things, are subject to regulation. The rates are established through the FERC’s ratemaking process. Changes in commodity prices and volumes transported have limited near-term impact on these revenues because the majority of cost of service is recovered through firm capacity reservation charges in transportation rates.
Williams NGL & Petchem Services
Williams NGL & Petchem Services includes certain domestic olefins pipeline assets as well as the previously owned Canadian assets which included a liquids extraction plant near Fort McMurray, Alberta, that began operations in March 2016 and a propane dehydrogenation facility under development in Canada. In September 2016, these Canadian operations were sold. (See Note 3 – Divestiture of Notes to Consolidated Financial Statements.)
Unless indicated otherwise, the following discussion and analysis of results of operations and financial condition and liquidity relates to our current continuing operations and should be read in conjunction with the consolidated financial statements and notes thereto included in Part II, Item 8 of this report.
Dividends
In December 2016, we paid a regular quarterly dividend of $0.20 per share. On February 20, 2017, our board of directors approved a regular quarterly dividend of $0.30 per share payable on March 27, 2017, representing a 50 percent increase from our previous quarterly dividend.
Overview
Net income (loss) attributable to The Williams Companies, Inc., for the year ended December 31, 2016, increased $147 million compared to the year ended December 31, 2015, reflecting the absence of certain goodwill impairments, lower impairments of equity-method investments, an increase in olefins margins associated with our Geismar plant, decreases in operating and maintenance expenses, and higher equity earnings. These favorable changes were partially offset by an unfavorable change in net income attributable to noncontrolling interests driven primarily by higher WPZ income as well as the impact of reduced incentive distributions from WPZ associated with the termination of the WPZ Merger Agreement. The favorable changes were also partially offset by increased impairment charges and loss on sale associated with our Canadian operations, lower insurance recoveries, as well as higher interest incurred. See additional discussion in Results of Operations.
Acquisition of Additional Interests in Appalachia Midstream Investments
In February, 2017, we announced agreements to acquire additional interests in two Marcellus Shale gathering systems within Williams Partners’ Appalachia Midstream Investments in exchange for equity-method investment interests in DBJV and the Ranch Westex gas processing plant, both currently reported within the Williams Partners segment. We also expect to receive a total of $200 million in cash as part of the agreements subject to customary closing conditions and purchase price adjustments. The transactions are expected to close in late first-quarter or early second-quarter 2017.
Financial Repositioning
In January 2017, we announced agreements with WPZ, wherein we permanently waived the general partner’s incentive distribution rights and converted our 2 percent general partner interest in WPZ to a non-economic interest in exchange for 289 million newly issued WPZ common units. Pursuant to this agreement, we also purchased approximately 277 thousand WPZ common units for $10 million. Additionally, we purchased approximately 59 million common units of WPZ at a price of $36.08586 per unit in a private placement transaction, funded with proceeds from our equity offering (see Note 15 - Stockholders’ Equity of Notes to Consolidated Financial Statements). Following these transactions, we own a 74 percent limited partner interest in WPZ. It is anticipated that the combination of these measures will improve WPZ’s cost of capital, provide for debt reduction, and eliminate WPZ’s need to access the public equity markets for several years.
In addition to the previously announced Geismar monetization process, we have announced plans to monetize other select assets that are not core to our strategy. We expect to raise more than $2 billion in after-tax proceeds from
the monetization process of Geismar and the other select assets. As we pursue these other asset monetizations, it is possible that we may incur impairments of certain equity-method investments, property, plant, and equipment, and intangible assets. Such impairments could potentially be caused by indications of fair value implied through the monetization process or, in the case of asset dispositions that are part of a broader asset group, the impact of the loss of future estimated cash flows.
Energy Transfer Merger Agreement
On September 28, 2015, we publicly announced in a press release that we had entered into a Merger Agreement with Energy Transfer and certain of its affiliates. The Merger Agreement provided that, subject to the satisfaction of customary closing conditions, we would merge with and into the newly formed ETC, with ETC surviving the ETC Merger.
On June 29, 2016, Energy Transfer provided us written notice terminating the Merger Agreement, citing the alleged failure of certain conditions under the Merger Agreement.
Termination of WPZ Merger Agreement
On May 12, 2015, we entered into an agreement for a unit-for-stock transaction whereby we would have acquired all of the publicly held outstanding common units of WPZ in exchange for shares of our common stock (WPZ Merger Agreement).
On September 28, 2015, prior to our entry into the Merger Agreement, we entered into a Termination Agreement and Release (Termination Agreement), terminating the WPZ Merger Agreement. Under the terms of the Termination Agreement, we were required to pay a $428 million termination fee to WPZ, at which time we owned approximately 60 percent, including the interests of the general partner and IDRs. Such termination fee settled through a reduction of quarterly incentive distributions we were entitled to receive from WPZ (such reduction not to exceed $209 million per quarter). The distributions from WPZ in November 2015, February 2016, and May 2016 were reduced by $209 million, $209 million, and $10 million, respectively, related to this termination fee.
Organizational Realignment
In September 2016, we announced organizational changes aiming to simplify our structure, increase direct operational alignment to advance our natural gas-focused strategy, and drive continued focus on customer service and execution. Effective January 1, 2017, we implemented these changes, which combined the management of certain of our operations and reduced the overall number of operating areas managed within our business.
Information in this report has generally been prepared to be consistent with the reportable segment presentation in our consolidated financial statement in Part II, Item 8 of this document. These segments are discussed in further detail in the following sections.
Williams Partners
Northwest Pipeline rate case
On January 23, 2017, Northwest Pipeline filed a Stipulation and Settlement Agreement with the FERC for new rates. The new rates become effective January 1, 2018, and are not expected to materially affect our trend of earnings. Pursuant to this agreement, Northwest Pipeline can file for new rates to be effective after October 1, 2018, and must file a general rate case for new rates to become effective no later than January 1, 2023.
Geismar olefins facility monetization
In September 2016, Williams Partners announced the initiation of an ongoing process to explore monetization of its ownership interest in the Geismar, Louisiana, olefins plant and complex, consistent with our strategy to narrow our focus and allocate capital to our natural gas–focused business.
Sale of Canadian operations
In September 2016, we completed the sale of our Canadian operations for total consideration of $1.02 billion. We recognized an impairment charge of $747 million during the second quarter of 2016 related to these operations and an additional loss of $66 million upon completion of the sale. (See Note 3 – Divestiture.)
Barnett Shale and Mid-Continent contract restructurings
In August 2016, Williams Partners conditionally committed to execute a new gas gathering agreement in the Barnett Shale. The agreement was executed in the fourth quarter of 2016, in conjunction with our existing customer, Chesapeake Energy Corporation, closing the sale of its Barnett Shale properties to another producer. That other producer, which has an investment grade credit rating, is now our customer under the new gas gathering agreement. The restructured agreement provided a $754 million up-front cash payment to us primarily in exchange for eliminating future minimum volume commitments. The restructured agreement also provides for revised gathering rates. Based on current commodity price assumptions at the time of the agreement, we generally expect the up-front cash proceeds and the ongoing cash flows generated by gathering services, to represent equivalent net present value of cash flows as compared to expected performance under the existing agreement. Additionally, Williams Partners agreed to a revised contract in the Mid-Continent region, also with Chesapeake Energy Corporation. The revised contract was executed in the third quarter of 2016 and provided an up-front cash payment to us of $66 million primarily in exchange for changing from a cost of service contract to fixed-fee terms. The majority of the up-front cash proceeds from both agreements were recognized as deferred revenue and will be amortized into income in future periods. In the near term, we do not expect that our trend of reported results will be significantly impacted by the effect of the discount associated with the up-front cash proceeds relative to the original minimum volume commitments and reduced gathering rates. It was anticipated that both agreements would reduce customer concentration risk and provide support to realize additional drilling and improved volumes in these regions.
Powder River basin contract restructuring
In October 2016, in conjunction with our partner in the Bucking Horse natural gas processing plant and Jackalope Gas Gathering System, we announced an agreement with Chesapeake Energy Corporation to restructure gathering and processing contracts in the Powder River basin. The restructured contracts became effective in January 2017 and replaced the previous cost-of-service arrangement with MVCs in the near-term such that we do not expect that our near-term trend of reported results will be significantly impacted by the restructured terms.
Rock Springs expansion
In August 2016, the Rock Springs expansion was placed into service. The project expanded Transco’s existing natural gas transmission system from New Jersey to a generation facility in Maryland and increased capacity by 192 Mdth/d.
Gulf Trace expansion
In February 2017, the Gulf Trace expansion was placed into service. The project expanded Transco’s existing natural gas transmission system together with greenfield facilities to provide incremental firm transportation capacity from Station 65 in St. Helena Parish, Louisiana to a new interconnection with Sabine Pass Liquefaction in Cameron Parish, Louisiana. It is expected to increase capacity by 1,200 Mdth/d.
Redwater expansion
In March 2016, we completed the expansion of our Redwater facilities in support of a long-term agreement to provide gas processing services to a second bitumen upgrader in Canada’s oil sands near Fort McMurray, Alberta. The expanded Redwater facility receives NGL/olefins mixtures from the second bitumen upgrader and fractionates the mixtures into an ethane/ethylene mix, propane, polymer grade propylene, normal butane, an alkylation feed and condensate. We sold these operations in September 2016. (See Note 3 – Divestiture of Notes to Consolidated Financial Statements.)
Williams NGL & Petchem Services
Horizon liquids extraction plant
In March 2016, we completed a new liquids extraction plant near Fort McMurray, Alberta. The Boreal pipeline was extended to enable transportation of the NGL/olefins mixture from the new liquids extraction plant to Williams Partners’ expanded Redwater facilities. The plant increased the amount of NGLs produced in Canada to a total of approximately 40 Mbbls/d. To mitigate ethane price risk associated with our processing services, we had a long-term agreement with a minimum price for ethane sales to a third-party customer. We sold these operations in September 2016. (See Note 3 – Divestiture of Notes to Consolidated Financial Statements.)
Commodity Prices
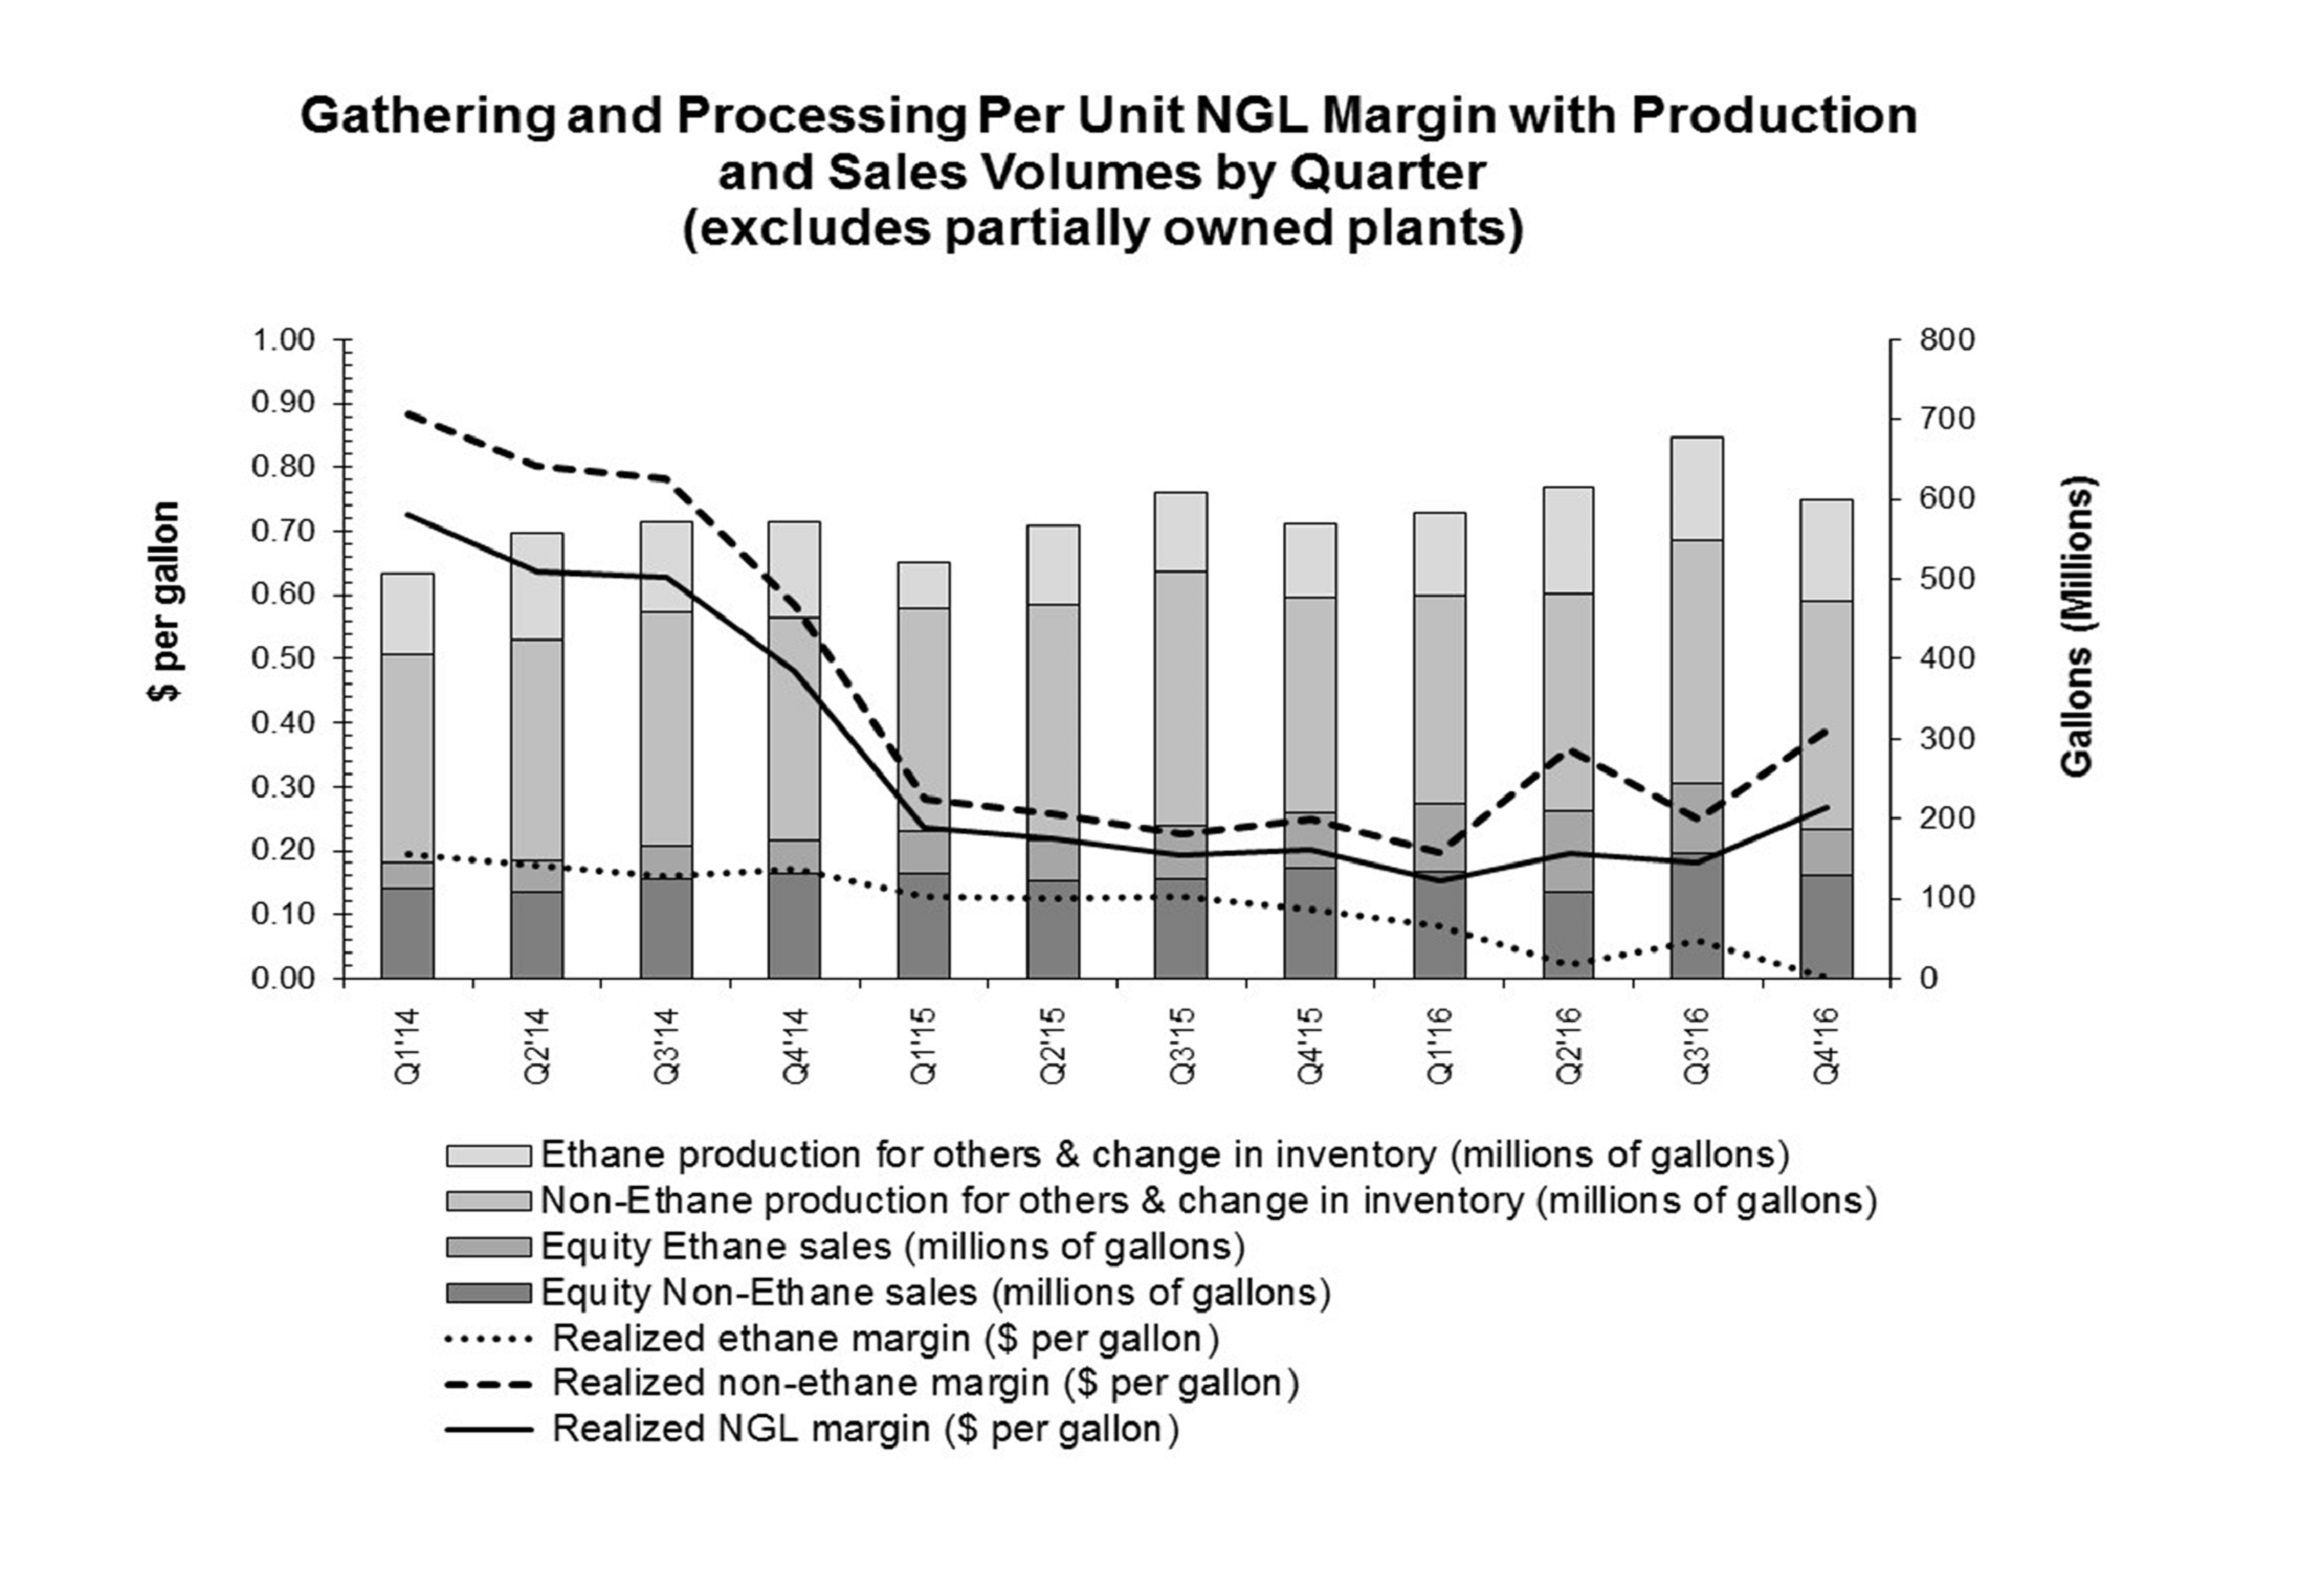
NGL per-unit margins were approximately 7 percent lower in 2016 compared to the same period of 2015. Following a sharp decline in late 2014 to early 2015, total NGL margins have remained somewhat consistent in 2015 and 2016. While 2014 and 2015 reflect limited ethane recoveries, we have seen an increase in ethane production during 2016.
NGL margins are defined as NGL revenues less any applicable Btu replacement cost, plant fuel, and third-party transportation and fractionation. Per-unit NGL margins are calculated based on sales of our own equity volumes at the processing plants. Our equity volumes include NGLs where we own the rights to the value from NGLs recovered at our plants under both “keep-whole” processing agreements, where we have the obligation to replace the lost heating value with natural gas, and “percent-of-liquids” agreements whereby we receive a portion of the extracted liquids with no obligation to replace the lost heating value.
The following graph illustrates the NGL production and sales volumes, as well as the margin differential between ethane and non-ethane products and the relative mix of those products.
 |
The potential impact of commodity prices on our business is further discussed in the following Company Outlook.
Company Outlook
Our strategy is to provide large-scale energy infrastructure designed to maximize the opportunities created by the vast supply of natural gas and natural gas products that exists in the United States. We accomplish this by connecting the growing demand for cleaner fuels and feedstocks with our major positions in the premier natural gas and natural gas products supply basins. We continue to maintain a strong commitment to safety, environmental stewardship, operational excellence, and customer satisfaction. We believe that accomplishing these goals will position us to deliver safe and reliable service to our customers and an attractive return to our shareholders.
Our business plan for 2017 includes the previously announced agreement with WPZ to permanently waive our incentive distribution rights in exchange for WPZ common units as well as our private purchase of $2.1 billion newly issued WPZ commits units. We expect to increase our dividend to $0.30 per share, or $1.20 annually, beginning in the first quarter of 2017. Our business plan also includes previously discussed asset monetizations, which include our ownership interest in the Geismar olefins facility as well as other select assets that are not core to our strategy. The monetizations are expected to yield after-tax proceeds of greater than $2.0 billion. For WPZ, these transactions are expected to improve its cost of capital, remove its need to access the public equity markets for the next several years, enhance growth, and provide for debt reduction, solidifying WPZ as an attractive financing vehicle. The transactions are also expected to facilitate a reduction of our parent-level debt and provides for dividend growth flexibility, while retaining strategic and financing flexibility.
Our growth capital and investment expenditures in 2017 are expected to total $2.1 billion to $2.8 billion. Approximately $1.4 billion to $1.9 billion of our growth capital funding needs include Transco expansions and other interstate pipeline growth projects, most of which are fully contracted with firm transportation agreements. The remaining growth capital spending in 2017 primarily reflects investment in gathering and processing systems in the Northeast region limited primarily to known new producer volumes, including volumes that support Transco expansion projects including our Atlantic Sunrise project. In addition to growth capital and investment expenditures, we also remain committed to projects that maintain our assets for safe and reliable operations, as well as projects that meet legal, regulatory, and/or contractual commitments.
As a result of our significant continued capital and investment expenditures on Transco expansions and fee-based gathering and processing projects, as well as the previously discussed sale of our Canadian operations and the planned monetization of the Geismar olefins facility, fee-based businesses are becoming an even more significant component of our portfolio and serve to reduce the influence of commodity price fluctuations on our operating results and cash flows. We expect to benefit as continued growth in demand for low-cost natural gas is driven by increases in LNG exports, industrial demand and power generation. Current forward market prices indicate a slightly more favorable energy commodity price environment in 2017 as compared to 2016, including higher natural gas and NGL prices. However, some of our customers may continue to curtail or delay drilling plans until there is a more sustained recovery in prices, which may negatively impact our gathering volumes. Although there has been some improvement, the credit profiles of certain of our producer customers remain challenged. Unfavorable changes in energy commodity prices or the credit profile of our producer customers may also result in noncash impairments of our assets.
In 2017, our operating results will include increases from our fee-based businesses recently placed in service or expected to be placed in service in 2017 primarily along the Transco system, a full year benefit of expanded capacity on our Gulfstar FPS™, and lower general and administrative expenses due to cost reduction initiatives and asset monetizations. We expect overall gathering and processing volumes to remain steady in 2017 and increase thereafter to meet the growing demand for natural gas and natural gas products.
Potential risks and obstacles that could impact the execution of our plan include:
| • | Opposition to infrastructure projects, including the risk of delay in permits needed for our projects; |
| • | Unexpected significant increases in capital expenditures or delays in capital project execution; |
| • | Counterparty credit and performance risk, including that of Chesapeake Energy Corporation and its affiliates; |
| • | Inability to execute or delay in completing planned asset monetizations; |
| • | Lower than anticipated demand for natural gas and natural gas products which could result in lower than expected volumes, energy commodity prices and margins; |
| • | General economic, financial markets, or further industry downturn, including increased interest rates; |
| • | Physical damages to facilities, including damage to offshore facilities by named windstorms; |
| • | Reduced availability of insurance coverage; |
| • | Lower than expected distributions from WPZ. |
We seek to maintain a strong financial position and liquidity, as well as manage a diversified portfolio of energy infrastructure assets which continue to serve key growth markets and supply basins in the United States.
Expansion Projects
Our ongoing major expansion projects include the following:
Williams Partners
Eagle Ford
We plan to expand our gathering infrastructure in the Eagle Ford region in order to meet our customers’ production plans. The expansion of the gathering infrastructure includes the addition of new facilities, well connections, and gathering pipeline to the existing systems.
Oak Grove Expansion
We plan to expand our processing capacity at our Oak Grove facility by adding a second 200 MMcf/d cryogenic natural gas processing plant, which, based on our customers’ needs, is expected to be placed into service in 2020.
Gathering System Expansion
We will continue to expand the gathering systems in the Marcellus and Utica Shale regions that are needed to meet our customers’ production plans. The expansion of the gathering infrastructure includes additional compression and gathering pipeline to the existing system.
Constitution Pipeline
In December 2014, we received approval from the FERC to construct and operate the jointly owned Constitution pipeline, which will have an expected capacity of 650 Mdth/d. However, in April 2016, the New York State Department of Environmental Conservation (NYSDEC) denied a necessary water quality certification for the New York portion of the pipeline. We remain steadfastly committed to the project, and in May 2016, Constitution appealed the NYSDEC’s denial of the certification and filed an action in federal court seeking a declaration that the State of New York’s authority to exercise permitting jurisdiction over certain other environmental matters is preempted by federal law. (See Note 4 – Variable Interest Entities of Notes to Consolidated Financial Statements.) We currently own 41 percent of Constitution with three other parties holding 25 percent, 24 percent, and 10 percent, respectively. We will be the operator of Constitution. The 126-mile Constitution pipeline will connect our gathering system in Susquehanna County, Pennsylvania, to the Iroquois Gas Transmission and Tennessee Gas Pipeline systems in New York, as well as to a local distribution company serving New York and Pennsylvania. In light of the NYSDEC’s denial of the water quality certification and the actions taken to challenge the decision, the target in-service date has been revised to as early as the second half of 2018, which assumes that the legal challenge process is satisfactorily and promptly concluded.
Garden State
In April 2016, we received approval from the FERC to expand Transco’s existing natural gas transmission system to provide incremental firm transportation capacity from Station 210 in New Jersey to a new interconnection on our Trenton Woodbury Lateral in New Jersey. The project will be constructed in phases and is expected to increase capacity by 180 Mdth/d. We plan to place the initial phase of the project into service during the third quarter of 2017 and the remaining portion in the second quarter of 2018, assuming timely receipt of all necessary regulatory approvals.
Norphlet Project
In March 2016, we announced that we have reached an agreement to provide deepwater gas gathering services to the Appomattox development in the Gulf of Mexico. The project will provide offshore gas gathering services to our existing Transco lateral, which will provide transmission services onshore to our Mobile Bay processing facility. We also plan to make modifications to our Main Pass 261 Platform to install an alternate delivery route from the platform, as well as modifications to our Mobile Bay processing facility. The project is scheduled to go into service during the second quarter of 2020.
Hillabee
In February 2016, the FERC issued a certificate order for the initial phases of Transco’s Hillabee Expansion Project. The project involves an expansion of Transco’s existing natural gas transmission system from Station 85 in west central Alabama to a proposed new interconnection with the Sabal Trail project in Alabama. The project will be constructed in phases, and all of the project expansion capacity will be leased to Sabal Trail. We plan to place the initial phase of the project into service concurrent with the in-service date of the Sabal Trail project, which is planned to occur as early as the second quarter of 2017. The in-service date of the second phase of the project is planned for the second quarter of 2020 and together they are expected to increase capacity by 1,025 Mdth/d.
In March 2016, WPZ entered into an agreement with the member-sponsors of Sabal Trail to resolve several matters. In accordance with the agreement, the member-sponsors will pay us an aggregate amount of $240 million in three equal installments as certain milestones of the project are met. The first $80 million payment was received in March 2016 and the second installment was received in September 2016. WPZ expects to recognize income associated with these receipts over the term of the capacity lease agreement.
New York Bay Expansion
In July 2016, we received approval from the FERC to expand Transco’s existing natural gas transmission system to provide incremental firm transportation capacity from Pennsylvania to the Rockaway Delivery Lateral transfer point and the Narrows meter station in Richmond County, New York. We plan to place the project into service during the fourth quarter of 2017, and it is expected to increase capacity by 115 Mdth/d.
Atlantic Sunrise
In February 2017, we received approval from the FERC to expand Transco’s existing natural gas transmission system along with greenfield facilities to provide incremental firm transportation capacity from the northeastern Marcellus producing area to markets along Transco’s mainline as far south as Station 85 in west central Alabama. We expect to place a portion of the project facilities into service during the second half of 2017 and are targeting a full in-service during mid-2018, assuming timely receipt of all necessary regulatory approvals. The project is expected to increase capacity by 1,700 Mdth/d.
Virginia Southside II
In July 2016, we received approval from the FERC to expand Transco’s existing natural gas transmission system together with greenfield facilities to provide incremental firm transportation capacity from Station 210 in New Jersey and Station 165 in Virginia to a new lateral extending from our Brunswick Lateral in Virginia. We plan
to place the project into service during the fourth quarter of 2017 and it is expected to increase capacity by 250 Mdth/d.
Dalton
In August 2016, we obtained approval from the FERC to expand Transco’s existing natural gas transmission system together with greenfield facilities to provide incremental firm transportation capacity from Station 210 in New Jersey to markets in northwest Georgia. We plan to place the project into service in 2017 and it is expected to increase capacity by 448 Mdth/d.
Gulf Connector
In August 2016, we filed an application with the FERC to expand Transco’s existing natural gas transmission system to provide incremental firm transportation capacity from Station 65 in Louisiana to delivery points in Wharton and San Patricio Counties, Texas. The project will be constructed in two phases, with the initial phase of the project expected to be in service during the second half of 2018 and the remaining phase in 2019, assuming timely receipt of all necessary regulatory approvals. The project is expected to increase capacity by 475 Mdth/d.
Williams NGL & Petchem Services
Gulf Coast NGL and Olefin Infrastructure Expansion
Certain previously acquired liquids pipelines in the Gulf Coast region are expected to be combined with an organic build-out of several projects to expand our petrochemical services in that region. The projects include the construction and commissioning of pipeline systems capable of transporting various purity natural gas liquids and olefins products in the Gulf Coast region. In response to the current conditions in the midstream industry, we are slowing the pace of development and may seek partners for these projects.
Critical Accounting Estimates
The preparation of financial statements in conformity with generally accepted accounting principles requires management to make estimates and assumptions. We believe that the nature of these estimates and assumptions is material due to the subjectivity and judgment necessary, or the susceptibility of such matters to change, and the impact of these on our financial condition or results of operations.
Pension and Postretirement Obligations
We have employee benefit plans that include pension and other postretirement benefits. Net periodic benefit cost and obligations for these plans are impacted by various estimates and assumptions. These estimates and assumptions include the expected long-term rates of return on plan assets, discount rates, expected rate of compensation increase, health care cost trend rates, and employee demographics, including retirement age and mortality. These assumptions are reviewed annually and adjustments are made as needed. The assumptions utilized to compute cost and the benefit obligations are shown in Note 10 – Employee Benefit Plans of Notes to Consolidated Financial Statements.
The following table presents the estimated increase (decrease) in net periodic benefit cost and obligations resulting from a one-percentage-point change in the specific assumption.
| Benefit Cost | Benefit Obligation | ||||||||||||||
| One- Percentage- Point Increase | One- Percentage- Point Decrease | One- Percentage- Point Increase | One- Percentage- Point Decrease | ||||||||||||
| (Millions) | |||||||||||||||
| Pension benefits: | |||||||||||||||
| Discount rate | $ | (9 | ) | $ | 10 | $ | (130 | ) | $ | 154 | |||||
| Expected long-term rate of return on plan assets | (13 | ) | 13 | — | — | ||||||||||
| Rate of compensation increase | 3 | (2 | ) | 9 | (7 | ) | |||||||||
| Other postretirement benefits: | |||||||||||||||
| Discount rate | 1 | 1 | (21 | ) | 25 | ||||||||||
| Expected long-term rate of return on plan assets | (2 | ) | 2 | — | — | ||||||||||
| Assumed health care cost trend rate | — | — | 6 | (5 | ) |
Our expected long-term rates of return on plan assets, as determined at the beginning of each fiscal year, are based on the average rate of return expected on the funds invested in the plans. We determine our long-term expected rates of return on plan assets using our expectations of capital market results, which include an analysis of historical results as well as forward-looking projections. These capital market expectations are based on a period of at least 10 years and take into account our investment strategy and mix of assets, which are weighted toward domestic and international equity securities. We develop our expectations using input from our third-party independent investment consultant. The forward-looking capital market projections start with current conditions of interest rates, equity pricing, economic growth, and inflation and those are overlaid with forward looking projections of normal inflation, growth, and interest rates to determine expected returns. The capital market return projections for specific asset classes in the investment portfolio are then applied to the relative weightings of the asset classes in the investment portfolio. The resulting rates are an estimate of future results and, thus, likely to be different than actual results.
In 2016, the benefit plans’ assets outperformed their respective benchmarks for fixed income strategies, but generally underperformed the respective benchmarks for equity strategies. While the 2016 investment performance was greater than our expected rates of return, the expected rates of return on plan assets are long-term in nature and are not significantly impacted by short-term market performance. Changes to our asset allocation would also impact these expected rates of return. Our expected long-term rate of return on plan assets used for our pension plans was 6.85 percent in 2016. The 2016 actual return on plan assets for our pension plans was approximately 7.5 percent. The 10-year average rate of return on pension plan assets through December 2016 was approximately 3.7 percent.
The discount rates are used to measure the benefit obligations of our pension and other postretirement benefit plans. The objective of the discount rates is to determine the amount, if invested at the December 31 measurement date in a portfolio of high-quality debt securities, that will provide the necessary cash flows when benefit payments are due. Increases in the discount rates decrease the obligation and, generally, decrease the related cost. The discount rates for our pension and other postretirement benefit plans are determined separately based on an approach specific to our plans and their respective expected benefit cash flows as described in Note 1 – General, Description of Business, Basis of Presentation, and Summary of Significant Accounting Policies and Note 10 – Employee Benefit Plans of Notes to Consolidated Financial Statements. Our discount rate assumptions are impacted by changes in general economic and market conditions that affect interest rates on long-term, high-quality debt securities as well as by the duration of our plans’ liabilities.
The expected rate of compensation increase represents average long-term salary increases. An increase in this rate causes the pension obligation and cost to increase.
The assumed health care cost trend rates are based on national trend rates adjusted for our actual historical cost rates and plan design. An increase in this rate causes the other postretirement benefit obligation and cost to increase.
Equity-Method Investments
At the end of the third quarter of 2016, we became aware of changes involving certain of DBJV’s customer contracts, which impacted our estimates of DBJV’s future cash flows. As such, we evaluated this investment for impairment at September 30, 2016, and determined that no impairment was necessary. We also entered into initial discussions with the system operator regarding the terms and economic assumptions of these contract changes.
During the fourth quarter of 2016, these discussions led to negotiations with the system operator to exchange our interest in DBJV and another equity-method investment in the Permian basin (Ranch Westex) for its interests in certain gathering systems in the Northeast and cash. We already hold partial interests in these Northeast gathering systems through our Appalachia Midstream Investments. As previously discussed, we reached agreements for such transactions in February 2017.
As part of the preparation of our year-end financial statements, we evaluated the carrying amounts of our investments in DBJV, Ranch Westex and these certain gathering systems within our Appalachia Midstream Investments for impairment. We also evaluated other equity-method investments within the Northeast area for impairment as of December 31, 2016, including other gathering systems within our Appalachia Midstream Investments and our investment in UEOM. Our impairment evaluations utilized an income approach, but also considered the fair values indicated by the previously described transaction. The estimated fair value of our investment in DBJV exceeded its carrying value and no impairment was necessary. Based on the fair value of the consideration expected to be received, we currently expect to recognize a gain upon consummation of the previously described exchange transaction in 2017.
We estimated the fair value of our Appalachia Midstream Investments and UEOM using an income approach with discount rates ranging from 10.2 percent to 12.5 percent and also considered the value implied by the previously described transactions as applicable. For certain gathering systems within our Appalachia Midstream Investments, the fair value was determined to be less than our carrying value, resulting in an other-than-temporary impairment charge of $294 million. No impairment was necessary for other gathering systems within our Appalachia Midstream Investments or our investment in UEOM. For those investments evaluated for which no impairment was required, our estimate of fair value exceeded our carrying value by amounts ranging from approximately 2.5 percent to 7.5 percent. We estimate that an increase in the discount rate utilized of 50 basis points would have resulted in an additional impairment charge of approximately $45 million. We also recorded an additional impairment of $24 million related to our interest in Ranch Westex.
Judgments and assumptions are inherent in our estimates of future cash flows, discount rates, and market measures utilized. The use of alternate judgments and assumptions could result in a different calculation of fair value, which could ultimately result in the recognition of a different impairment charge in the consolidated financial statements.
At December 31, 2016, our Consolidated Balance Sheet includes approximately $6.7 billion of investments that are accounted for under the equity-method of accounting. We evaluate these investments for impairment when events or changes in circumstances indicate, in our management’s judgment, that the carrying value of such investments may have experienced an other-than-temporary decline in value. We continue to monitor our equity-method investments for any indications that the carrying value may have experienced an other-than-temporary decline in value. When evidence of a loss in value has occurred, we compare our estimate of the fair value of the investment to the carrying value of the investment to determine whether an impairment has occurred. We generally estimate the fair value of our investments using an income approach where significant judgments and assumptions include expected future cash flows and the appropriate discount rate. In some cases, we may utilize a form of market approach to estimate the fair value of our investments.
If the estimated fair value is less than the carrying value and we consider the decline in value to be other-than-temporary, the excess of the carrying value over the fair value is recognized in the consolidated financial statements as an impairment charge. Events or changes in circumstances that may be indicative of an other-than-temporary decline in value will vary by investment, but may include:
| • | A significant or sustained decline in the market value of an investee; |
| • | Lower than expected cash distributions from investees; |
| • | Significant asset impairments or operating losses recognized by investees; |
| • | Significant delays in or lack of producer development or significant declines in producer volumes in markets served by investees; |
| • | Significant delays in or failure to complete significant growth projects of investees. |
Constitution Pipeline Capitalized Project Costs
As of December 31, 2016, Property, plant, and equipment – net in our Consolidated Balance Sheet includes approximately $381 million of capitalized project costs for Constitution, for which we are the construction manager and own a 41 percent consolidated interest. In December 2014, we received approval from the FERC to construct and operate this jointly owned pipeline. However, in April 2016, the New York State Department of Environmental Conservation (NYSDEC) denied a necessary water quality certification for the New York portion of the Constitution pipeline. We remain steadfastly committed to the project, and in May 2016, Constitution appealed the NYSDEC's denial of the certification and filed an action in federal court seeking a declaration that the State of New York's authority to exercise permitting jurisdiction over certain other environmental matters is preempted by federal law.
As a result of the denial by the NYSDEC, we evaluated the capitalized project costs for impairment as of March 31, 2016, and as of December 31, 2016, and determined that no impairment was necessary. Our evaluation considered probability-weighted scenarios of undiscounted future net cash flows, including a scenario assuming successful resolution with the NYSDEC and construction of the pipeline, as well as a scenario where the project does not proceed. We continue to monitor the capitalized project costs associated with Constitution for potential impairment.
Results of Operations
Consolidated Overview
The following table and discussion is a summary of our consolidated results of operations for the three years ended December 31, 2016. The results of operations by segment are discussed in further detail following this consolidated overview discussion.
| Years Ended December 31, | |||||||||||||||||||||||
| 2016 | $ Change from 2015* | % Change from 2015* | 2015 | $ Change from 2014* | % Change from 2014* | 2014 | |||||||||||||||||
| (Millions) | |||||||||||||||||||||||
| Revenues: | |||||||||||||||||||||||
| Service revenues | $ | 5,171 | +7 | — | % | $ | 5,164 | +1,048 | +25 | % | $ | 4,116 | |||||||||||
| Product sales | 2,328 | +132 | +6 | % | 2,196 | -1,325 | -38 | % | 3,521 | ||||||||||||||
| Total revenues | 7,499 | 7,360 | 7,637 | ||||||||||||||||||||
| Costs and expenses: | |||||||||||||||||||||||
| Product costs | 1,725 | +54 | +3 | % | 1,779 | +1,237 | +41 | % | 3,016 | ||||||||||||||
| Operating and maintenance expenses | 1,580 | +75 | +5 | % | 1,655 | -163 | -11 | % | 1,492 | ||||||||||||||
| Depreciation and amortization expenses | 1,763 | -25 | -1 | % | 1,738 | -562 | -48 | % | 1,176 | ||||||||||||||
| Selling, general, and administrative expenses | 723 | +18 | +2 | % | 741 | -80 | -12 | % | 661 | ||||||||||||||
| Impairment of goodwill | — | +1,098 | +100 | % | 1,098 | -1,098 | NM | — | |||||||||||||||
| Impairment of certain assets | 873 | -664 | NM | 209 | -157 | NM | 52 | ||||||||||||||||
| Net insurance recoveries – Geismar Incident | (7 | ) | -119 | -94 | % | (126 | ) | -106 | -46 | % | (232 | ) | |||||||||||
| Other (income) expense – net | 142 | -102 | NM | 40 | -137 | NM | (97 | ) | |||||||||||||||
| Total costs and expenses | 6,799 | 7,134 | 6,068 | ||||||||||||||||||||
| Operating income (loss) | 700 | 226 | 1,569 | ||||||||||||||||||||
| Equity earnings (losses) | 397 | +62 | +19 | % | 335 | +191 | +133 | % | 144 | ||||||||||||||
| Gain on remeasurement of equity-method investment | — | — | — | % | — | -2,544 | -100 | % | 2,544 | ||||||||||||||
| Impairment of equity-method investments | (430 | ) | +929 | +68 | % | (1,359 | ) | -1,359 | NM | — | |||||||||||||
| Other investing income (loss) – net | 63 | +36 | +133 | % | 27 | -16 | -37 | % | 43 | ||||||||||||||
| Interest expense | (1,179 | ) | -135 | -13 | % | (1,044 | ) | -297 | -40 | % | (747 | ) | |||||||||||
| Other income (expense) – net | 74 | -28 | -27 | % | 102 | +71 | NM | 31 | |||||||||||||||
| Income (loss) from continuing operations before income taxes | (375 | ) | (1,713 | ) | 3,584 | ||||||||||||||||||
| Provision (benefit) for income taxes | (25 | ) | -374 | -94 | % | (399 | ) | +1,648 | NM | 1,249 | |||||||||||||
| Income (loss) from continuing operations | (350 | ) | (1,314 | ) | 2,335 | ||||||||||||||||||
| Income (loss) from discontinued operations | — | — | — | % | — | -4 | -100 | % | 4 | ||||||||||||||
| Net income (loss) | (350 | ) | (1,314 | ) | 2,339 | ||||||||||||||||||
| Less: Net income (loss) attributable to noncontrolling interests | 74 | -817 | NM | (743 | ) | +968 | NM | 225 | |||||||||||||||
| Net income (loss) attributable to The Williams Companies, Inc. | $ | (424 | ) | $ | (571 | ) | $ | 2,114 |
| * | + = Favorable change; - = Unfavorable change; NM = A percentage calculation is not meaningful due to a change in signs, a zero-value denominator, or a percentage change greater than 200. |
2016 vs. 2015
Service revenues increased slightly primarily due to expansion projects placed in service in 2015 and 2016, partially offset by a decrease in gathering, processing, and fractionation revenue primarily due to lower volumes in the Barnett Shale and Anadarko basin.
Product sales increased primarily due to higher olefin sales reflecting increased volumes at our Geismar plant as a result of the plant operating at higher production levels in 2016, partially offset by a decrease from our other olefin operations associated with lower volumes and per-unit sales prices. Product sales also reflect higher marketing revenues associated with higher NGL and propylene prices and natural gas and crude oil volumes, partially offset by lower NGL volumes, and crude oil prices.
The decrease in Product costs includes lower olefin feedstock purchases and lower costs associated with other product sales, partially offset by higher marketing purchases primarily due to the same factors that increased marketing sales. The decline in olefin feedstock purchases is primarily associated with lower per-unit feedstock costs and volumes at our other olefin operations, partially offset by an increase in olefin feedstock purchases at our Geismar plant reflecting increased volumes resulting from higher production levels in 2016.
Operating and maintenance expenses decreased primarily due to lower labor-related and outside service costs resulting from our first-quarter 2016 workforce reductions and cost containment efforts and lower costs associated with general maintenance activities in the Marcellus Shale, as well as the absence of ACMP transition-related costs recognized in 2015. These decreases are partially offset by $16 million of severance and related costs recognized in 2016 and higher pipeline testing and general maintenance costs at Transco.
Depreciation and amortization expenses increased primarily due to depreciation on new assets placed in service, including Transco pipeline projects, partially offset by lower depreciation related to Canadian operations sold in 2016.
Selling, general, and administrative expenses (SG&A) decreased primarily due to lower merger and transition costs associated with the ACMP merger and lower labor-related costs resulting from our first-quarter 2016 workforce reductions and cost containment efforts. These decreases were partially offset by certain project development costs associated with the Canadian PDH facility that we began expensing in 2016, as well as $26 million of severance and related costs recognized in 2016 and $17 million of higher costs associated with our evaluation of strategic alternatives.
Impairment of goodwill decreased due to the absence of a 2015 impairment charge associated with certain goodwill. (See Note 17 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
Impairment of certain assets reflects 2016 impairments of our Canadian operations and certain Mid-Continent assets, and other assets. Impairments recognized in 2015 relate primarily to previously capitalized development costs and surplus equipment write-downs. (See Note 17 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
Net insurance recoveries – Geismar Incident changed unfavorably reflecting the receipt of $126 million of insurance proceeds in the second quarter of 2015, as compared to the receipt of $7 million of proceeds in the fourth quarter of 2016.
The unfavorable change in Other (income) expense – net within Operating income (loss) includes a loss on the sale of our Canadian operations that were sold in September 2016, project development costs at Constitution as we discontinued capitalization of these costs in April 2016, and an unfavorable change in foreign currency exchange that primarily relates to losses incurred on foreign currency transactions and the remeasurement of the U.S. dollar-denominated current assets and liabilities within our former Canadian operations, partially offset by a $10 million gain on the sale of idle pipe in 2016.
Operating income (loss) changed favorably primarily due to the absence of a goodwill impairment in 2015, higher olefin margins related to the Geismar plant operating at higher production levels in 2016, lower costs related to the merger and integration of ACMP, and lower costs and expenses primarily associated with cost containment efforts.
These favorable changes are partially offset by impairments and loss on sale of certain assets in 2016, a decrease in insurance proceeds received, expensed Canadian PDH facility project development costs, and higher depreciation expenses related to new projects placed in service.
Equity earnings (losses) changed favorably primarily due to a $30 million increase at Discovery driven by the completion of the Keathley Canyon Connector in the first quarter of 2015. Additionally, OPPL, Laurel Mountain, and DBJV improved $16 million, $11 million, and $10 million, respectively.
Impairment of equity-method investments reflects 2016 impairment charges associated with our Appalachia Midstream Investments, DBJV, and Laurel Mountain equity-method investments, while the 2015 impairment charges relate to our equity-method investments in Appalachia Midstream Investments, DBJV, UEOM, and Laurel Mountain. (See Note 6 – Investing Activities of Notes to Consolidated Financial Statements.)
Other investing income (loss) – net changed favorably due to a 2016 gain on the sale of an equity-method investment interest in a gathering system that was part of our Appalachia Midstream Investments and higher interest income associated with a receivable related to the sale of certain former Venezuela assets. (See Note 6 – Investing Activities of Notes to Consolidated Financial Statements.)
Interest expense increased due to higher Interest incurred of $99 million primarily attributable to new debt issuances in 2016 and 2015 and lower Interest capitalized of $36 million primarily related to construction projects that have been placed into service, partially offset by lower interest due to 2015 and 2016 debt retirements. (See Note 14 – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements.)
Other income (expense) – net below Operating income (loss) changed unfavorably primarily due to a decrease in allowance for equity funds used during construction (AFUDC) due to decreased spending on Constitution and the absence of a $14 million gain on early debt retirement in 2015.
Provision (benefit) for income taxes changed unfavorably primarily due to a decrease in pretax loss in 2016. See Note 8 – Provision (Benefit) for Income Taxes of Notes to Consolidated Financial Statements for a discussion of the effective tax rates compared to the federal statutory rate for both years.
The unfavorable change in Net income (loss) attributable to noncontrolling interests is primarily due to higher operating results at WPZ, the impact of decreased income allocated to the WPZ general partner driven by the impact of reduced incentive distributions from WPZ associated with the termination of the WPZ Merger Agreement, and the absence of the accelerated amortization of a beneficial conversion feature from the first quarter of 2015. These changes are partially offset by a favorable change primarily related to our partners’ share of Constitution project development costs in 2016.
2015 vs. 2014
Service revenues increased primarily due to additional revenues associated with a full year of ACMP operations in 2015, increased revenues associated with the start-up of operations at Gulfstar One during the fourth quarter of 2014, and an increase in Transco’s natural gas transportation fees due to new projects placed in service in 2014 and 2015. Revenues from operations associated with our acquisition of ACMP and the northeast region also increased due to higher volumes related to new well connects. A decrease in Canadian construction management revenues, reflecting a shift to internal customer construction projects, partially offset these increases.
Product sales decreased due to a decrease in marketing revenues primarily associated with lower prices across all products, partially offset by higher non-ethane volumes, and a decrease in revenues from our equity NGLs reflecting lower NGL prices, partially offset by higher NGL volumes. Product sales also decreased due to lower olefin sales from other olefin operations associated with lower per-unit sales prices, partially offset by higher volumes. These decreases are partially offset by an increase in olefin sales primarily due to resuming our Geismar operations during 2015.
Product costs decreased due to a decrease in marketing purchases primarily associated with lower per-unit costs, partially offset by higher non-ethane volumes, and a decrease in natural gas purchases associated with the production of equity NGLs primarily due to lower natural gas prices, partially offset by higher volumes. Product costs also decreased
due to lower feedstock purchases in our other olefin operations primarily due to lower per-unit feedstock costs across all products as well as lower per-unit costs, partially offset by significantly higher volumes in 2015. These decreases are partially offset by an increase in olefin feedstock purchases primarily associated with resuming our Geismar operations.
Operating and maintenance expenses increased primarily due to new expenses associated with operations acquired in our acquisition of ACMP, increased growth of operating activity in certain areas, increased maintenance and repair expenses, and the return to operations of the Geismar plant. These increases are partially offset by a decrease in Canadian construction management expenses that reflect a shift to internal customer construction projects.
Depreciation and amortization expenses increased primarily due to new expenses associated with operations acquired in our acquisition of ACMP and from depreciation on new projects placed in service, including Gulfstar One and the Geismar expansion.
SG&A increased primarily due to administrative expenses associated with operations acquired in our acquisition of ACMP, including $31 million higher ACMP merger and transition-related costs, partially offset by the absence of $16 million of acquisition costs incurred in 2014. In addition, 2015 includes $32 million of costs associated with our evaluation of strategic alternatives. These increases are partially offset by the absence of $18 million of project development costs incurred in 2014 related to the Bluegrass Pipeline reflecting 100 percent of such costs. The 50 percent noncontrolling interest share of these costs are presented in Net income (loss) attributable to noncontrolling interests.
Impairment of goodwill reflects a 2015 impairment charge associated with certain goodwill. (See Note 17 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
Impairment of certain assets relate primarily to 2015 impairments of previously capitalized development costs and surplus equipment write-downs. (See Note 17 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
Net insurance recoveries – Geismar Incident changed unfavorably primarily due to the receipt of $126 million of insurance recoveries in 2015 as compared to the receipt of $246 million of insurance recoveries in 2014.
Other (income) expense – net within Operating income (loss) changed unfavorably primarily due to the absence of $154 million of cash proceeds received in 2014 related to a contingency settlement gain and the absence of a $12 million net gain recognized in 2014 related to a partial acreage dedication release. (See Note 7 – Other Income and Expenses of Notes to Consolidated Financial Statements.)
Operating income (loss) changed unfavorably primarily due to a 2015 impairment of goodwill, higher impairments of certain assets, higher depreciation, operating, and maintenance expenses related to construction projects placed in service and the start-up of the Geismar plant, $229 million lower NGL margins driven by lower prices, lower insurance recoveries related to the Geismar Incident, higher costs related to the merger and integration of ACMP into WPZ, and 2015 strategic alternative expenses. These decreases were partially offset by increased service revenues related to construction projects placed in service, $116 million higher olefin margins primarily due to our Geismar plant that returned to operations in 2015, and contributions from the operations acquired in our acquisition of ACMP.
Equity earnings (losses) changed favorably primarily due to the absence of equity losses from Bluegrass Pipeline and Moss Lake in 2014 and due to contributions from investments acquired in our acquisition of ACMP. In addition, equity earnings at Discovery increased $76 million primarily related to the completion of the Keathley Canyon Connector in early 2015. These changes were partially offset by $33 million of losses associated with our share of impairments recognized at equity investees in 2015. (See Note 6 – Investing Activities of Notes to Consolidated Financial Statements.)
Gain on remeasurement of equity-method investment reflects the 2014 gain recognized as a result of remeasuring to fair value the equity-method investment that we held before we acquired a controlling interest in ACMP. (See Note 2 – Acquisitions of Notes to Consolidated Financial Statements.)
Impairment of equity-method investments reflects 2015 impairment charges associated with certain equity-method investments. (See Note 6 – Investing Activities of Notes to Consolidated Financial Statements.)
Other investing income (loss) – net changed unfavorably primarily due to lower interest income associated with a receivable related to the sale of certain former Venezuela assets.
Interest expense increased due to a $230 million increase in Interest incurred primarily due to new debt issuances in 2014 and 2015 and interest expense associated with debt assumed in conjunction with our acquisition of ACMP. This increase was partially offset by lower interest due to 2015 debt retirements and the absence of a $9 million transaction-related financing fee incurred in the second quarter of 2014 related to our acquisition of ACMP. In addition, Interest capitalized decreased $67 million primarily related to construction projects that have been placed into service. (See Note 2 – Acquisitions and Note 14 – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements.)
Other income (expense) – net below Operating income (loss) changed favorably primarily due to a $43 million benefit related to an increase in AFUDC associated with an increase in spending on various Transco expansion projects and Constitution, a $14 million gain on early debt retirement in April 2015, and a $9 million contingency gain settlement.
Provision (benefit) for income taxes changed favorably primarily due to lower pretax income in 2015. See Note 8 – Provision (Benefit) for Income Taxes of Notes to Consolidated Financial Statements for a discussion of the effective tax rates compared to the federal statutory rate for both years.
The favorable change in Net income (loss) attributable to noncontrolling interests related to our investment in WPZ is primarily due to lower operating results at WPZ, our increased percentage of limited partner ownership of WPZ, and the impact of increased income allocated to the WPZ general partner, held by us, associated with IDRs. These changes are partially offset by an unfavorable change related to our investment in Gulfstar One associated with its start up in 2014.
Year-Over-Year Operating Results – Segments
We evaluate segment operating performance based upon Modified EBITDA. Note 19 – Segment Disclosures of Notes to Consolidated Financial Statements includes a reconciliation of this non-GAAP measure to Net income (loss). Management uses Modified EBITDA because it is an accepted financial indicator used by investors to compare company performance. In addition, management believes that this measure provides investors an enhanced perspective of the operating performance of our assets. Modified EBITDA should not be considered in isolation or as a substitute for a measure of performance prepared in accordance with GAAP.
Williams Partners
| Years Ended December 31, | |||||||||||
| 2016 | 2015 | 2014 | |||||||||
| (Millions) | |||||||||||
| Service revenues | $ | 5,173 | $ | 5,135 | $ | 3,888 | |||||
| Product sales | 2,318 | 2,196 | 3,521 | ||||||||
| Segment revenues | 7,491 | 7,331 | 7,409 | ||||||||
| Product costs | (1,728 | ) | (1,779 | ) | (3,016 | ) | |||||
| Other segment costs and expenses | (2,203 | ) | (2,229 | ) | (1,760 | ) | |||||
| Net insurance recoveries – Geismar Incident | 7 | 126 | 232 | ||||||||
| Impairment of certain assets | (457 | ) | (145 | ) | (52 | ) | |||||
| Proportional Modified EBITDA of equity-method investments | 754 | 699 | 431 | ||||||||
| Williams Partners Modified EBITDA | $ | 3,864 | $ | 4,003 | $ | 3,244 | |||||
| NGL margin | $ | 169 | $ | 159 | $ | 388 | |||||
| Olefin margin | 337 | 226 | 110 |
2016 vs. 2015
Modified EBITDA decreased primarily due to higher impairments, lower insurance recoveries associated with the Geismar Incident, and loss on sale associated with our Canadian operations. These decreases were partially offset by higher olefin margins related to the Geismar plant operating at higher production levels in 2016, lower segment costs and expenses, and higher earnings related to our equity-method investments, including the completion of the Keathley Canyon Connector at Discovery in the first quarter of 2015. Additionally, higher marketing margins, higher service revenues related to projects placed in service, and higher NGL margins improved Modified EBITDA.
The increase in Service revenues is primarily due to a $79 million increase in Transco’s natural gas transportation fee revenues primarily associated with expansion projects placed in service in 2015 and 2016 and a $31 million transportation and fractionation revenue increase associated with Williams NGL & Petchem’s Horizon liquids extraction plant in Canada. The Canadian operations were sold in late September 2016. These increases were partially offset by a decrease in gathering, processing, and fractionation revenue primarily due to lower volumes primarily in the Barnett Shale and Anadarko basin and a $15 million decrease in Transco’s storage revenue related to potential refunds associated with a ruling received in certain rate case litigation in 2016.
Product sales increased primarily due to:
| • | A $94 million increase in olefin sales comprised of a $170 million increase from our Geismar plant that returned to service in late March 2015, partially offset by a $76 million decrease from our other olefin operations. The increase at Geismar includes $153 million associated with increased volumes as a result of the plant operating at higher production levels in 2016 than when production resumed in March 2015 following the Geismar Incident and $17 million primarily associated with higher ethylene per-unit sales prices. The decrease in other olefin sales includes a $14 million reduction due to the absence of our former Canadian operations in the fourth quarter of 2016, as well as lower volumes and lower per-unit sales prices within our other olefin operations; |
| • | A $70 million increase in marketing revenues primarily due to higher NGL and propylene prices and natural gas and crude oil volumes, partially offset by lower NGL volumes and crude oil prices (partially offset in marketing purchases); |
| • | A $6 million increase in revenues from our equity NGLs due to a $10 million increase associated with higher volumes, partially offset by a $4 million decrease associated with lower NGL prices; |
| • | A $39 million decrease in system management gas sales from Transco. System management gas sales are offset in Product costs and, therefore, have no impact on Modified EBITDA. |
The decrease in Product costs includes:
| • | A $39 million decrease in system management gas costs (offset in Product sales); |
| • | A $17 million decrease in olefin feedstock purchases is primarily comprised of $78 million in lower purchases at our other olefins operations, partially offset by $61 million of higher purchases due primarily to increased volumes at our Geismar plant resulting from higher productions levels. The lower costs at our other olefin operations are comprised of $54 million in lower per-unit feedstock costs and $24 million in primarily lower propylene volumes; |
| • | A $4 million decrease in natural gas purchases associated with the production of equity NGLs reflecting a decrease of $13 million due to lower natural gas prices, partially offset by a $9 million increase associated with higher volumes; |
| • | Lower costs associated with various other products, primarily condensate; |
| • | A $22 million increase in marketing purchases primarily due to the same factors that increased marketing sales (more than offset in marketing revenues). The increase in marketing costs does not reflect the intercompany costs associated with certain gathering and processing services performed by an affiliate. |
The decrease in Other segment costs and expenses is primarily due to lower operating costs and general and administrative expenses reflecting decreases in primarily labor-related and outside services costs resulting from our first-quarter 2016 workforce reductions and ongoing cost containment efforts and lower costs associated with general maintenance activities in the Marcellus Shale, as well as $43 million of lower ACMP Merger and transition-related expenses. Other items partially offsetting these decreases are as follows:
| • | $34 million increase related to the 2016 loss on sale of our Canadian operations; |
| • | $37 million increase for severance and related costs associated with workforce reductions incurred in the first quarter of 2016 and the organizational realignment in the fourth quarter of 2016; |
| • | $28 million higher project development costs at Constitution as we discontinued capitalization of development costs related to this project beginning in April 2016; |
| • | $22 million higher contract services for pipeline testing and general maintenance at Transco; |
| • | $20 million unfavorable change in foreign currency exchange that primarily relates to losses incurred on foreign currency transactions and the remeasurement of the U.S. dollar-denominated current assets and liabilities within our former Canadian operations; |
| • | $19 million unfavorable change in AFUDC associated with a decrease in spending on Constitution; |
| • | The absence of a $14 million gain recognized in second-quarter 2015 resulting from the early retirement of certain debt. |
Net insurance recoveries – Geismar Incident decreased reflecting $7 million of insurance proceeds received in 2016 compared to $126 million received in 2015.
Impairment of certain assets increased primarily due to 2016 impairments of $341 million associated with our Canadian operations and $63 million associated with certain Mid-Continent gathering assets as well as impairments or write-downs of other certain assets that may no longer be in use or are surplus in nature, partially offset by the absence of 2015 impairments of $94 million associated with previously capitalized project development costs for a gas processing plant and $20 million associated with certain surplus equipment within our Ohio Valley Midstream business. (See Note 17 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
The increase in Proportional Modified EBITDA of equity-method investments is primarily due to a $30 million increase from Discovery primarily associated with higher fee revenues attributable to the completion of the Keathley Canyon Connector in the first quarter of 2015. Additionally, Caiman II contributed a $20 million increase resulting from higher volumes due to assets placed into service in 2015, OPPL contributed a $16 million increase primarily due to higher transportation volumes and lower expenses, and UEOM contributed an $11 million increase primarily associated with an increase in our ownership percentage. These increases were partially offset by an $29 million decrease from Appalachia Midstream Investments primarily due to lower fee revenues driven by lower rates, partially offset by lower impairments and higher volumes.
2015 vs. 2014
Modified EBITDA increased primarily due to the acquisition of ACMP during the third quarter of 2014 and increased fee revenue associated with contributions from new and expanded facilities, including Gulfstar One during the fourth quarter of 2014, in addition to resuming our Geismar operations and contributions related to the completion of the Keathley Canyon Connector at Discovery. Partially offsetting these increases to Modified EBITDA is a decrease in
NGL margins as a result of a significant decline in commodity prices beginning in the fourth quarter of 2014 and lower insurance recoveries related to the Geismar Incident.
The increase in Service revenues is primarily due to $810 million additional revenues associated with a full year of ACMP operations in 2015 which includes a $72 million increase in the minimum volume commitment fees, $223 million in increased revenues associated with the start-up of operations at Gulfstar One during the fourth quarter of 2014, and a $155 million increase in Transco’s natural gas transportation fees due to new projects placed in service in 2015 and 2014. Additionally, service revenues reflect higher fees associated with increased volumes and additional contributions in the Northeast. Higher revenues in the Northeast include expanded gathering operations and processing, fractionation and transportation operations, contributing $59 million and $27 million of additional fees, respectively.
The decrease in Product sales includes:
| • | A $1,173 million decrease in marketing revenues primarily associated with lower prices across all products, partially offset by higher non-ethane volumes (more than offset in marketing purchases); |
| • | A $324 million decrease in revenues from our equity NGLs reflecting a decrease of $365 million due to lower NGL prices, partially offset by a $41 million increase associated with higher NGL volumes; |
| • | A $41 million decrease in revenues primarily due to lower condensate prices; |
| • | A $214 million increase in olefin sales primarily due to $298 million in higher sales from our Geismar plant that returned to operation, partially offset by an $84 million decrease from our other olefin operations due to lower sales prices, partially offset by higher volumes across all products, particularly propylene. |
The decrease in Product costs includes:
| • | A $1,219 million decrease in marketing purchases primarily due to a decrease in non-ethane per-unit cost (substantially offset in marketing revenues); |
| • | A $95 million decrease in the natural gas purchases associated with the production of equity NGLs reflecting a decrease of $126 million due to lower natural gas prices, partially offset by a $31 million increase associated with higher volumes; |
| • | A $20 million decrease in costs primarily due to lower gas prices; |
| • | A $98 million increase in olefin feedstock purchases is comprised of $127 million in higher purchases due to increased volumes at our Geismar plant as it returned to operation, partially offset by $29 million in lower other olefin operations feedstock purchases primarily due to lower per-unit feedstock costs, partially offset by higher volumes across most products, particularly propylene. |
The increase in Other segment costs and expenses includes:
| • | An increase for new expenses associated with operations associated with the acquisition of ACMP; |
| • | The absence of $154 million of cash received in the fourth quarter of 2014 associated with the resolution of a contingent gain related to claims arising from the purchase of a business in a prior period (see Note 7 – Other Income and Expenses of Notes to Consolidated Financial Statements); |
| • | A $16 million increase in operating expense due to the Geismar plant returning to operation in 2015; |
| • | The absence of a $12 million net gain recognized in 2014 related to a partial acreage dedication release. |
The decrease in Net insurance recoveries – Geismar Incident is primarily due to the 2015 receipt of $126 million of insurance proceeds compared to $246 million received in 2014, partially offset by the absence of covered insurable
expenses in excess of our retentions (deductibles) related to the Geismar Incident in 2015 compared to $14 million in 2014.
Impairment of certain assets increased primarily due to a 2015 $94 million impairment charge associated with previously capitalized project development costs for a gas processing plant. (See Note 17 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
The increase in Proportional Modified EBITDA of equity-method investments is primarily due to a full year contribution of $160 million from investments associated with the acquisition of ACMP and a $103 million increase from Discovery associated with higher fee revenues attributable to the completion of the Keathley Canyon Connector in the first quarter of 2015. Additionally, Caiman II increased $21 million resulting from assets placed into service in 2014 and 2015, partially offset by the absence of business interruption insurance proceeds received in the prior year, and an $11 million decrease at Laurel Mountain. The decrease at Laurel Mountain was primarily due to $13 million of impairments and lower gathering fees due to lower gathering rates indexed to natural gas prices, partially offset by 24 percent higher volumes and an increase in our ownership percentage compared to the prior year.
Williams NGL & Petchem Services
| Years Ended December 31, | |||||||||||
| 2016 | 2015 | 2014 | |||||||||
| (Millions) | |||||||||||
| Service revenues | $ | 2 | $ | 2 | $ | — | |||||
| Product sales | 26 | — | — | ||||||||
| Segment revenues | 28 | 2 | — | ||||||||
| Product costs | (13 | ) | — | — | |||||||
| Other segment costs and expenses | (139 | ) | (85 | ) | (37 | ) | |||||
| Impairment of certain assets | (416 | ) | — | — | |||||||
| Proportional Modified EBITDA of equity-method investments | — | — | (78 | ) | |||||||
| Williams NGL & Petchem Services Modified EBITDA | $ | (540 | ) | $ | (83 | ) | $ | (115 | ) |
2016 vs. 2015
The unfavorable change in Modified EBITDA is primarily due to the 2016 impairment and subsequent loss on disposal of our Canadian operations as well as the expensing of certain development costs associated with the Canadian PDH facility, partially offset by the absence of the 2015 write-off of previously capitalized project development costs for an olefins pipeline project.
The increase in Product sales and Product costs is primarily due to the Horizon liquids extraction plant coming online in March 2016 until it was sold in September 2016.
The unfavorable change in Other segment costs and expenses is primarily due to $61 million of certain project development costs associated with the Canadian PDH facility that we began expensing in 2016. Additionally, the unfavorable change includes $33 million of transportation and fractionation fees associated with our new Horizon volumes and a $32 million loss on the sale of our Canadian operations in September 2016. (See Note 3 – Divestiture of Notes to Consolidated Financial Statements.) The unfavorable change in Other segment costs and expenses is partially offset by a $10 million gain on the sale of unused pipe in 2016 and the absence of the $64 million write-off of previously capitalized project development costs for an olefins pipeline project in 2015. (See Note 17 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
The unfavorable change in Impairment of certain assets primarily reflects the 2016 impairment of our Canadian operations and an $8 million impairment of idle pipe. (See Note 17 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
.
2015 vs. 2014
The favorable change in Modified EBITDA is primarily due to the absence of our share of the 2014 write-off of previously capitalized project development costs at Bluegrass Pipeline and Moss Lake, as well as costs incurred in 2014 relating to the development of the Bluegrass Pipeline, partially offset by the 2015 write-off of previously capitalized project development costs for an olefins pipeline project.
Other segment costs and expenses increased primarily due to the $64 million write-off of previously capitalized project development costs for an olefins pipeline project in 2015, partially offset by the absence of $18 million of project development costs incurred in 2014 relating to the Bluegrass Pipeline.
The favorable change in Proportional Modified EBITDA of equity-method investments is primarily due to the absence of our share of the 2014 write-off of previously capitalized project development costs at Bluegrass Pipeline and Moss Lake.
Other
| Years Ended December 31, | |||||||||||
| 2016 | 2015 | 2014 | |||||||||
| (Millions) | |||||||||||
| Other Modified EBITDA | $ | (2 | ) | $ | (29 | ) | $ | 103 |
2016 vs. 2015
Modified EBITDA improved primarily due to a $31 million decrease in ACMP merger and transition related costs, as well as the impact of various other individually insignificant items, partially offset by a $17 million increase in costs related to our evaluation of strategic alternatives.
2015 vs. 2014
Modified EBITDA decreased significantly as the results from the businesses acquired with our acquisition of ACMP are presented within Williams Partners for periods subsequent to the July 1, 2014, acquisition. Other included the proportional Modified EBITDA of $104 million of our former equity-method investment in ACMP for the first half of 2014, which was partially offset by $19 million associated with our share of compensation costs triggered by the ACMP Acquisition recognized in July 2014. Modified EBITDA also decreased by $30 million related to costs incurred in 2015 related to evaluating our strategic alternatives and the Merger Agreement with Energy Transfer, as well as $24 million of higher costs associated with integration and re-alignment of resources following the ACMP acquisition and merger. These decreases are partially offset by a $9 million contingency gain settlement recognized in fourth quarter 2015.
Management’s Discussion and Analysis of Financial Condition and Liquidity
Overview
In 2016, we continued to focus upon growth in our businesses through disciplined investment and reducing our costs and funding needs. Examples of this activity included:
| • | Expansion of WPZ’s interstate natural gas pipeline system through projects such as Rock Springs to meet the demand of growth markets; |
| • | Completion of WPZ’s Gulfstar One expansion project to provide production handling and gathering services for the Gunflint oil and gas discovery in the eastern deepwater Gulf of Mexico; |
| • | WPZ’s restructuring of contracts in the Barnett Shale and Mid-Continent region,which included cash payments to WPZ of $820 million; |
| • | Sale of our Canadian operations (see Note 3 – Divestiture of Notes to Consolidated Financial Statements). |
Outlook
Fee-based businesses are becoming an even more significant component of our portfolio and serve to reduce the influence of commodity price fluctuations on our cash flows. We expect to benefit as continued growth in demand for low-cost natural gas is driven by increases in LNG exports, industrial demand, and power generation.
We believe we have, or have access to, the financial resources and liquidity necessary to meet our requirements for working capital, capital and investment expenditures, dividends and distributions, debt service payments, and tax payments, while maintaining a sufficient level of liquidity. In particular, as previously discussed in Company Outlook, our expected growth capital and investment expenditures total approximately $2.1 billion to $2.8 billion in 2017. Approximately $1.4 billion to $1.9 billion of our growth capital funding needs include Transco expansions and other interstate pipeline growth projects, most of which are fully contracted with firm transportation agreements. The remaining growth capital spending in 2017 primarily reflects investment in gathering and processing systems in the Northeast region limited primarily to known new producer volumes, including volumes that support Transco expansion projects including our Atlantic Sunrise project. In addition to growth capital and investment expenditures, we also remain committed to projects that maintain our assets for safe and reliable operations, as well as projects that meet legal, regulatory, and/or contractual commitments. We retain the flexibility to adjust planned levels of capital and investment expenditures in response to changes in economic conditions or business opportunities.
In January 2017, WPZ announced that it will redeem all of its $750 million 6.125 percent senior notes due 2022 on February 23, 2017. In addition, we expect after-tax proceeds in excess of $2 billion from planned asset monetizations of Geismar and other select assets during 2017, which we expect Williams Partners to use for additional debt reduction and to fund capital and investment expenditures.
Liquidity
Based on our forecasted levels of cash flow from operations and other sources of liquidity, we expect to have sufficient liquidity to manage our businesses in 2017. Our internal and external sources of consolidated liquidity to fund working capital requirements, capital and investment expenditures, debt service payments, dividends and distributions, and tax payments include:
| • | Cash and cash equivalents on hand; |
| • | Cash generated from operations; |
| • | Distributions from WPZ; |
| • | Distributions from our equity-method investees based on our level of ownership; |
| • | Use of our credit facility; |
| • | Cash proceeds from issuances of debt and/or equity securities. |
WPZ is expected to fund its cash needs through its cash flows from operations and its credit facility and/or commercial paper program, as well as proceeds from planned asset monetizations as previously mentioned. WPZ also established a distribution reinvestment program (DRIP) in the third quarter of 2016.
We previously announced that we intended to reinvest approximately $1.2 billion into WPZ in 2017 via the DRIP, funded primarily by our reduced quarterly cash dividend which would have allowed us to annually retain approximately $1.3 billion for reinvestment. As part of the Financial Repositioning announced in January 2017, we discontinued our participation in the DRIP and expect to increase our regular quarterly cash dividend to $0.30 for the dividend to be paid in March 2017. (See Note 1 – General, Description of Business, Basis of Presentation, and Summary of Significant Accounting Policies of Notes to Consolidated Financial Statements.)
We anticipate our more significant uses of cash to be:
| • | Working capital requirements; |
| • | Maintenance and expansion capital and investment expenditures; |
| • | Interest on our long-term debt; |
| • | Repayment of current debt maturities, and additional reductions in WPZ’s debt with funds received as part of the Financial Repositioning; |
| • | Investment in WPZ as part of the Financial Repositioning (see Note 15 – Stockholders' Equity of Notes to Consolidated Financial Statements); |
| • | Quarterly dividends to our shareholders. |
Potential risks associated with our planned levels of liquidity discussed above include those previously discussed in Company Outlook.
As of December 31, 2016, we had a working capital deficit (current liabilities, inclusive of $785 million in Long-term debt due within one year, in excess of current assets) of $1.487 billion. Our available liquidity is as follows:
| December 31, 2016 | ||||||||||||
| Available Liquidity | WPZ | WMB | Total | |||||||||
| (Millions) | ||||||||||||
| Cash and cash equivalents | $ | 145 | $ | 25 | $ | 170 | ||||||
| Capacity available under our $1.5 billion credit facility (1) | 725 | 725 | ||||||||||
| Capacity available to WPZ under its $3.5 billion credit facility, less amounts outstanding under its $3 billion commercial paper program (2) | 3,407 | 3,407 | ||||||||||
| $ | 3,552 | $ | 750 | $ | 4,302 |
| (1) | The highest amount outstanding under our credit facility during 2016 was $1.224 billion. At December 31, 2016, we were in compliance with the financial covenants associated with this credit facility. See Note 14 – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements for additional information on our credit facility. Borrowing capacity available under this facility as of February 20, 2017, was $1.265 billion. |
| (2) | In managing our available liquidity, we do not expect a maximum outstanding amount in excess of the capacity of WPZ’s credit facility inclusive of any outstanding amounts under its commercial paper program. WPZ has $93 million of Commercial paper outstanding at December 31, 2016. The highest amount outstanding under WPZ’s |
commercial paper program and credit facility during 2016 was $2.326 billion. At December 31, 2016, WPZ was in compliance with the financial covenants associated with this credit facility. See Note 14 – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements for additional information on WPZ’s credit facility and WPZ’s commercial paper program. Borrowing capacity available under WPZ’s $3.5 billion credit facility as of February 20, 2017, was $3.5 billion.
As described in Note 14 – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements, we have determined that we have net assets that are technically considered restricted in accordance with Rule 4-08(e) of Regulation S-X of the Securities and Exchange Commission in excess of 25 percent of our consolidated net assets. We do not expect this determination will impact our ability to pay dividends or meet future obligations as the terms of WPZ’s partnership agreement require it to make quarterly distributions of all available cash, as defined, to its unitholders.
WPZ Incentive Distribution Rights
As part of the Financial Repositioning, we permanently waived our right to incentive distributions from WPZ. (See Overview in Management’s Discussion and Analysis of Financial Condition and Results of Operations.)
Through December 31, 2016, our ownership interest in WPZ included the right to incentive distributions determined in accordance with WPZ’s partnership agreement. In connection with the sale of WPZ’s Canadian operations in the third quarter of 2016, we agreed to waive $150 million of incentive distributions otherwise payable by WPZ to us in the fourth quarter of 2016. (See Note 3 – Divestiture of Notes to Consolidated Financial Statements.)
We had agreed to temporarily waive incentive distributions of approximately $2 million per quarter in connection with WPZ’s acquisition of an approximate 13 percent additional interest in UEOM on June 10, 2015. The waiver would have continued through the quarter ending September 30, 2017.
We were required to pay a $428 million termination fee to WPZ, associated with the Termination Agreement (as described in Note 1 – General, Description of Business, Basis of Presentation, and Summary of Significant Accounting Policies of Notes to Consolidated Financial Statements), which settled through a reduction of quarterly incentive distributions we are entitled to receive from WPZ (such reduction not to exceed $209 million per quarter). The November 2015, February 2016, and May 2016 distributions from WPZ were reduced by $209 million, $209 million, and $10 million, respectively, related to this termination fee.
Registrations
In September 2016, WPZ filed a registration statement for its new DRIP discussed above. In November 2016, WPZ received reinvested distributions of $260 million, of which $250 million related to us.
In May 2015, we filed a shelf registration statement, as a well-known seasoned issuer.
In February 2015, WPZ filed a shelf registration statement, as a well-known seasoned issuer, and WPZ also filed a shelf registration statement for the offer and sale from time to time of common units representing limited partner interests in WPZ having an aggregate offering price of up to $1 billion. These sales are to be made over a period of time and from time to time in transactions at prices which are market prices prevailing at the time of sale, prices related to market price, or at negotiated prices. Such sales are to be made pursuant to an equity distribution agreement between WPZ and certain banks who may act as sales agents or purchase for their own accounts as principals. During 2016 and 2015, WPZ received net proceeds of approximately $115 million and approximately $59 million, respectively, from equity issued under this registration.
Distributions from Equity-Method Investees
The organizational documents of entities in which we have an equity-method investment generally require distribution of their available cash to their members on a quarterly basis. In each case, available cash is reduced, in part, by reserves appropriate for operating their respective businesses. (See Note 6 – Investing Activities of Notes to Consolidated Financial Statements for our more significant equity-method investees.)
Credit Ratings
Our ability to borrow money is impacted by our credit ratings and the credit ratings of WPZ. The current ratings are as follows:
| Rating Agency | Outlook | Senior Unsecured Debt Rating | Corporate Credit Rating | ||||
| WMB: | S&P Global Ratings | Stable | BB | BB | |||
| Moody’s Investors Service | Stable | Ba2 | N/A | ||||
| Fitch Ratings | Stable | BB+ | N/A | ||||
| WPZ: | S&P Global Ratings | Stable | BBB- | BBB- | |||
| Moody’s Investors Service | Stable | Baa3 | N/A | ||||
| Fitch Ratings | Stable | BBB- | N/A |
Considering our credit ratings as of December 31, 2016, we estimate that we could be required to provide up to $36 million in additional collateral of either cash or letters of credit with third parties under existing contracts. At the present time, we have not provided any additional collateral to third parties but no assurance can be given that we will not be requested to provide collateral in the future. As of December 31, 2016, we estimate that a downgrade to a rating below investment-grade for WPZ could require it to provide up to $376 million in additional collateral of either cash or letters of credit with third parties under existing contracts.
Sources (Uses) of Cash
The following table summarizes the sources (uses) of cash and cash equivalents for each of the periods presented (see Notes to Consolidated Financial Statements for the Notes referenced in the table):
| Cash Flow | Years Ended December 31, | ||||||||||||
| Category | 2016 | 2015 | 2014 | ||||||||||
| (Millions) | |||||||||||||
| Sources of cash and cash equivalents: | |||||||||||||
| Operating activities - net | Operating | $ | 3,664 | $ | 2,678 | $ | 2,115 | ||||||
| Proceeds from WPZ’s credit-facility borrowings | Financing | 3,250 | 3,832 | 1,646 | |||||||||
| Proceeds from our credit-facility borrowings | Financing | 2,280 | 2,097 | 1,040 | |||||||||
| Proceeds from sale of Canadian operations (see Note 3) | Investing | 1,020 | — | — | |||||||||
| Proceeds from WPZ’s debt offerings (see Note 14) | Financing | 998 | 3,842 | 2,740 | |||||||||
| Distributions from unconsolidated affiliates in excess of cumulative earnings | Investing | 472 | 404 | 206 | |||||||||
| Proceeds from equity offerings | Financing | 123 | 86 | 3,471 | |||||||||
| Contributions from noncontrolling interests | Financing | 29 | 111 | 340 | |||||||||
| Special distribution from Gulfstream (see Note 6) | Financing | — | 396 | — | |||||||||
| Proceeds from our debt offerings | Financing | — | — | 1,895 | |||||||||
| Proceeds from WPZ’s commercial paper - net | Financing | — | — | 572 | |||||||||
| Uses of cash and cash equivalents: | |||||||||||||
| Payments on WPZ’s credit-facility borrowings | Financing | (4,560 | ) | (3,162 | ) | (1,156 | ) | ||||||
| Payments on our credit-facility borrowings | Financing | (2,155 | ) | (1,817 | ) | (670 | ) | ||||||
| Capital expenditures | Investing | (2,051 | ) | (3,167 | ) | (4,031 | ) | ||||||
| Quarterly dividends on common stock | Financing | (1,261 | ) | (1,836 | ) | (1,412 | ) | ||||||
| Dividends and distributions to noncontrolling interests | Financing | (940 | ) | (942 | ) | (840 | ) | ||||||
| Payments of WPZ’s commercial paper - net | Financing | (409 | ) | (306 | ) | — | |||||||
| Payments on WPZ’s debt retirements (see Note 14) | Financing | (375 | ) | (1,533 | ) | — | |||||||
| Purchases of and contributions to equity-method investments | Investing | (177 | ) | (595 | ) | (482 | ) | ||||||
| Contribution to Gulfstream for repayment of debt (see Note 6) | Financing | (148 | ) | (248 | ) | — | |||||||
| Purchases of businesses, net of cash acquired | Investing | — | (112 | ) | (5,958 | ) | |||||||
| Other sources / (uses) - net | Financing and Investing | 310 | 132 | 83 | |||||||||
| Increase (decrease) in cash and cash equivalents | $ | 70 | $ | (140 | ) | $ | (441 | ) |
Operating activities
The factors that determine operating activities are largely the same as those that affect Net income (loss), with the exception of noncash items such as Depreciation and amortization, Provision (benefit) for deferred income taxes, Impairment of goodwill, Impairment of equity-method investments, Impairment of and net (gain) loss on sale of assets and businesses, and Gain on remeasurement of equity-method investment.
Our Net cash provided (used) by operating activities in 2016 increased from 2015 primarily due to the impact of net favorable changes in operating working capital and receipts from contract restructurings.
Our Net cash provided (used) by operating activities in 2015 increased from 2014 primarily due to the impact of net favorable changes in operating working capital and the absence of contributions from ACMP for the first six months of 2014.
Off-Balance Sheet Arrangements and Guarantees of Debt or Other Commitments
We have various other guarantees and commitments which are disclosed in Note 4 – Variable Interest Entities, Note 11 – Property, Plant, and Equipment, Note 14 – Debt, Banking Arrangements, and Leases, Note 17 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk, and Note 18 – Contingent Liabilities and Commitments of Notes to Consolidated Financial Statements. We do not believe these guarantees and commitments or the possible fulfillment of them will prevent us from meeting our liquidity needs.
Contractual Obligations
The table below summarizes the maturity dates of our contractual obligations at December 31, 2016:
| 2017 | 2018 - 2019 | 2020 - 2021 | Thereafter | Total | |||||||||||||||
| (Millions) | |||||||||||||||||||
| Long-term debt: (1)(2) | |||||||||||||||||||
| Principal | $ | 785 | $ | 1,382 | $ | 3,767 | $ | 17,506 | $ | 23,440 | |||||||||
| Interest | 1,099 | 2,132 | 1,928 | 7,947 | 13,106 | ||||||||||||||
| Commercial paper | 93 | — | — | — | 93 | ||||||||||||||
| Operating leases | 66 | 109 | 81 | 90 | 346 | ||||||||||||||
| Purchase obligations (3) | 1,074 | 733 | 646 | 320 | 2,773 | ||||||||||||||
| Other obligations (4)(5) | 2 | 1 | 1 | 1 | 5 | ||||||||||||||
| Total | $ | 3,119 | $ | 4,357 | $ | 6,423 | $ | 25,864 | $ | 39,763 |
| (1) | Includes the borrowings outstanding under credit facilities, but does not include any related variable-rate interest payments. |
| (2) | Includes $750 million of 6.125 percent senior notes due 2022 that WPZ intends to redeem on February 23, 2017 and related interest, presented in the table above according to the original contractual terms. |
| (3) | Includes approximately $244 million in open property, plant, and equipment purchase orders. Includes an estimated $418 million long-term ethane purchase obligation with index-based pricing terms that is reflected in this table at December 31, 2016 prices. This obligation is part of an overall exchange agreement whereby volumes we transport on OPPL are sold at a third-party fractionator near Conway, Kansas, and we are subsequently obligated to purchase ethane volumes at Mont Belvieu. The purchased ethane volumes may be utilized or resold at comparable prices in the Mont Belvieu market. Includes an estimated $619 million long-term ethane purchase obligation with index-based pricing terms that primarily supplies third parties at their plants and is valued in this table at a price calculated using December 31, 2016 prices. Any excess purchased volumes may be sold at comparable market prices. Includes an estimated $586 million long-term mixed NGLs purchase obligation with index-based pricing terms that is reflected in this table at December 31, 2016 prices. In addition, we have not included certain natural gas life-of-lease contracts for which the future volumes are indeterminable. We have not included commitments, beyond purchase orders, for the acquisition or construction of property, plant, and equipment or expected contributions to our jointly owned investments. (See Company Outlook — Expansion Projects.) |
| (4) | Does not include estimated contributions to our pension and other postretirement benefit plans. We made contributions to our pension and other postretirement benefit plans of $72 million in 2016 and $70 million in 2015. In 2017, we expect to contribute approximately $69 million to these plans (see Note 10 – Employee Benefit Plans of Notes to Consolidated Financial Statements). Tax-qualified pension plans are required to meet minimum contribution requirements. In the past, we have contributed amounts to our tax-qualified pension plans in excess of the minimum required contribution. These excess amounts can be used to offset future minimum contribution requirements. During 2016, we contributed $60 million to our tax-qualified pension plans. In addition to these contributions, a portion of the excess contributions was used to meet the minimum contribution requirements. During 2017, we expect to contribute approximately $60 million to our tax-qualified pension plans and use excess amounts to satisfy minimum contribution requirements, if needed. Additionally, estimated future minimum funding requirements may vary significantly from historical requirements if actual results differ significantly from estimated |
results for assumptions such as returns on plan assets, interest rates, retirement rates, mortality, and other significant assumptions or by changes to current legislation and regulations.
| (5) | We have not included income tax liabilities in the table above. See Note 8 – Provision (Benefit) for Income Taxes of Notes to Consolidated Financial Statements for a discussion of income taxes, including our contingent tax liability reserves. |
Effects of Inflation
Our operations have historically not been materially affected by inflation. Approximately 39 percent of our gross property, plant, and equipment is comprised of our interstate natural gas pipeline assets. They are subject to regulation, which limits recovery to historical cost. While amounts in excess of historical cost are not recoverable under current FERC practices, we anticipate being allowed to recover and earn a return based on increased actual cost incurred to replace existing assets. Cost-based regulations, along with competition and other market factors, may limit our ability to recover such increased costs. For our gathering and processing assets, operating costs are influenced to a greater extent by both competition for specialized services and specific price changes in crude oil and natural gas and related commodities than by changes in general inflation. Crude oil, natural gas, and NGL prices are particularly sensitive to the market perceptions concerning the supply and demand balance in the near future, as well as general economic conditions. However, our exposure to certain of these price changes is reduced through the fee-based nature of certain of our services and the use of hedging instruments.
Environmental
We are a participant in certain environmental activities in various stages including assessment studies, cleanup operations, and/or remedial processes at certain sites, some of which we currently do not own (see Note 18 – Contingent Liabilities and Commitments of Notes to Consolidated Financial Statements). We are monitoring these sites in a coordinated effort with other potentially responsible parties, the EPA, or other governmental authorities. We are jointly and severally liable along with unrelated third parties in some of these activities and solely responsible in others. Current estimates of the most likely costs of such activities are approximately $38 million, all of which are included in Accrued liabilities and Regulatory liabilities, deferred income, and other on the Consolidated Balance Sheet at December 31, 2016. We will seek recovery of approximately $9 million of these accrued costs through future natural gas transmission rates. The remainder of these costs will be funded from operations. During 2016, we paid approximately $6 million for cleanup and/or remediation and monitoring activities. We expect to pay approximately $9 million in 2017 for these activities. Estimates of the most likely costs of cleanup are generally based on completed assessment studies, preliminary results of studies, or our experience with other similar cleanup operations. At December 31, 2016, certain assessment studies were still in process for which the ultimate outcome may yield different estimates of most likely costs. Therefore, the actual costs incurred will depend on the final amount, type, and extent of contamination discovered at these sites, the final cleanup standards mandated by the EPA or other governmental authorities, and other factors.
In March 2008, the EPA promulgated a new, lower National Ambient Air Quality Standard (NAAQS) for ground-level ozone. In May 2012, the EPA completed designation of new eight-hour ozone nonattainment areas. Several Transco facilities are located in 2008 ozone nonattainment areas. In December 2014, the EPA proposed to further reduce the ground-level ozone NAAQS from the March 2008 levels and subsequently finalized a rule on October 1, 2015. We are monitoring the rule's implementation as the reduction will trigger additional federal and state regulatory actions that may impact our operations. To date, no federal actions have been proposed to mandate additional emission controls at these facilities. Pursuant to recently finalized state regulatory actions associated with implementation of the 2008 ozone standard, we anticipate that some facilities may be subject to increased controls within five years. Implementation of the regulations is expected to result in impacts to our operations and increase the cost of additions to Property, plant, and equipment – net on the Consolidated Balance Sheet for both new and existing facilities in affected areas. We are unable at this time to estimate with any certainty the cost of additions that may be required to meet the regulations.
On January 22, 2010, the EPA set a new one-hour nitrogen dioxide (NO2) NAAQS. The effective date of the new NO2 standard was April 12, 2010. On January 20, 2012, the EPA determined pursuant to available information that no area in the country is violating the 2010 NO2 NAAQS and thus designated all areas of the country as “unclassifiable/attainment.” Also, at that time the EPA noted its plan to deploy an expanded NO2 monitoring network beginning in 2013. However on October 5, 2012, the EPA proposed a graduated implementation of the monitoring network between
January 1, 2014 and January 1, 2017. Once three years of data is collected from the new monitoring network, the EPA will reassess attainment status with the one-hour NO2 NAAQS. Until that time, the EPA or states may require ambient air quality modeling on a case by case basis to demonstrate compliance with the NO2 standard. Because we are unable to predict the outcome of the EPA’s or states’ future assessment using the new monitoring network, we are unable to estimate the cost of additions that may be required to meet this regulation.
Our interstate natural gas pipelines consider prudently incurred environmental assessment and remediation costs and the costs associated with compliance with environmental standards to be recoverable through rates.
Previous: Item 6. Selected Financial Data · Next: Item 7A. Quantitative and Qualitative Disclosures About Market Risk