 filings.tools
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
123K characters. Original on sec.gov · Markdown
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
General
We are an energy infrastructure company focused on connecting North America’s significant hydrocarbon resource plays to growing markets for natural gas and NGLs. Our operations are located principally in the United States. We have one reportable segment, Williams Partners. All remaining business activities are included in Other.
Williams Partners
Williams Partners consists of our consolidated master limited partnership, WPZ, which includes gas pipeline and midstream businesses. The gas pipeline businesses include interstate natural gas pipelines and pipeline joint project investments; and the midstream businesses provide natural gas gathering, treating, and processing services; NGL production, fractionation, storage, marketing, and transportation; deepwater production handling and crude oil transportation services; and are comprised of several wholly owned and partially owned subsidiaries and joint project investments. As of December 31, 2017, we own 74 percent of the interests in WPZ.
Williams Partners’ gas pipeline businesses consist primarily of Transco and Northwest Pipeline. The gas pipeline business also holds interests in joint venture interstate and intrastate natural gas pipeline systems including a 50 percent equity-method investment in Gulfstream and a 41 percent interest in Constitution (a consolidated entity), which is developing a pipeline project. (See Note 3 – Variable Interest Entities of Notes to Consolidated Financial Statements.) As of December 31, 2017, Transco and Northwest Pipeline owned and operated a combined total of approximately 13,600 miles of pipelines with a total annual throughput of approximately 4,533 Tbtu of natural gas and peak-day delivery capacity of approximately 18.8 MMdth of natural gas.
Williams Partners’ midstream businesses primarily consist of (1) natural gas gathering, treating, compression, and processing; (2) NGL fractionation, storage, and transportation; (3) crude oil production handling and transportation; and (4) olefins production. (See Note 2 – Acquisitions and Divestitures of Notes to Consolidated Financial Statements.) The primary service areas are concentrated in major producing basins in Colorado, Texas, Oklahoma, Kansas, New Mexico, Wyoming, the Gulf of Mexico, Louisiana, Pennsylvania, West Virginia, New York, and Ohio, which include the Barnett, Eagle Ford, Haynesville, Marcellus, Niobrara, and Utica shale plays as well as the Mid-Continent region.
The midstream businesses include equity-method investments in natural gas gathering and processing assets and NGL fractionation and transportation assets, including a 62 percent equity-method investment in UEOM, a 69 percent equity-method investment in Laurel Mountain, a 58 percent equity-method investment in Caiman II, a 60 percent equity-method investment in Discovery, a 50 percent equity-method investment in OPPL, and Appalachia Midstream Services, LLC, which owns an approximate average 66 percent equity-method investment interest in multiple gas gathering systems in the Marcellus Shale (Appalachia Midstream Investments), as well as our previously owned 50 percent equity-method investment in the Delaware basin gas gathering system (DBJV) in the Mid-Continent region (see Note 5 – Investing Activities of Notes to Consolidated Financial Statements).
The midstream businesses previously included Canadian midstream operations, which were comprised of an oil sands offgas processing plant near Fort McMurray, Alberta and an NGL/olefin fractionation facility at Redwater, Alberta. In September 2016, these Canadian operations were sold.
Williams Partners’ ongoing strategy is to safely and reliably operate large-scale, interstate natural gas transmission and midstream infrastructures where our assets can be fully utilized and drive low per-unit costs. We focus on consistently attracting new business by providing highly reliable service to our customers and investing in growing markets and areas of increasing natural gas demand.
Williams Partners’ interstate transmission and related storage activities are subject to regulation by the FERC and as such, our rates and charges for the transportation of natural gas in interstate commerce, and the extension, expansion or abandonment of jurisdictional facilities and accounting, among other things, are subject to regulation. The rates are established through the FERC’s ratemaking process. Changes in commodity prices and volumes transported have
limited near-term impact on these revenues because the majority of cost of service is recovered through firm capacity reservation charges in transportation rates.
Other
Other is comprised of business activities that are not operating segments, as well as corporate operations. Other also includes certain domestic olefins pipeline assets as well as certain Canadian assets, which included a liquids extraction plant located near Fort McMurray, Alberta, that began operations in March 2016, and a propane dehydrogenation facility which was under development. In September 2016, the Canadian assets were sold.
Financial Repositioning
In January 2017, we entered into agreements with WPZ, wherein we permanently waived the general partner’s IDRs and converted our 2 percent general partner interest in WPZ to a noneconomic interest in exchange for 289 million newly issued WPZ common units. Pursuant to this agreement, we also purchased approximately 277 thousand WPZ common units for $10 million. Additionally, we purchased approximately 59 million common units of WPZ at a price of $36.08586 per unit in a private placement transaction, funded with proceeds from our equity offering (see Note 14 – Stockholders’ Equity of Notes to Consolidated Financial Statements). According to the terms of this agreement, concurrent with WPZ’s quarterly distributions in February 2017 and May 2017, we paid additional consideration totaling $56 million to WPZ for these units. Subsequent to these transactions and as of December 31, 2017, we own a 74 percent limited partner interest in WPZ.
Unless indicated otherwise, the following discussion and analysis of results of operations and financial condition and liquidity relates to our current continuing operations and should be read in conjunction with the consolidated financial statements and notes thereto included in Part II, Item 8 of this report.
Dividends
In December 2017, we paid a regular quarterly dividend of $0.30 per share. On February 21, 2018, our board of directors approved a regular quarterly dividend of $0.34 per share payable on March 26, 2018.
Overview
Net income (loss) attributable to The Williams Companies, Inc., for the year ended December 31, 2017, changed favorably by $2.598 billion compared to the year ended December 31, 2016, reflecting a $1.949 billion improvement in the provision (benefit) for income taxes primarily due to Tax Reform, the absence of $430 million of impairments of equity-method investments incurred in 2016, a $219 million increase in Other investing income (loss) – net primarily associated with the disposition of certain equity-method investments in 2017, a $204 million increase in operating income and reduced interest expense, partially offset by a $261 million increase in net income attributable to noncontrolling interests primarily due to increased income at WPZ. The increase in operating income reflects a gain of $1.095 billion from the sale of our Geismar Interest, increased service revenue from expansion projects, and lower costs and expenses, partially offset by a $674 million regulatory charge resulting from Tax Reform, a $375 million increase in impairments of certain assets, and a $184 million decrease in product margins primarily due to the loss of olefins volumes as a result of the sale of our Gulf Olefins and Canadian operations.
Tax Reform
In December 2017, the Tax Cuts and Jobs Act was enacted, which, among other things, reduced the federal corporate income tax rate from 35 percent to 21 percent (Tax Reform). As a result, we have remeasured our existing deferred income tax assets and liabilities, to reflect the expected future realization of existing temporary differences at the lower income tax rate. This resulted in the recognition of a net income tax provision benefit of $1.923 billion for the year ended December 31, 2017. Certain adjustments within the provision benefit are considered provisional and are potentially subject to change in the future. (See Note 7 – Provision (Benefit) for Income Taxes of Notes to Consolidated Financial Statements.)
Transco and Northwest Pipeline have recognized regulatory liabilities to reflect the probable return to customers through future rates of the future decrease in income taxes payable associated with Tax Reform. These liabilities represent an obligation to return amounts directly to our customers. The regulatory liabilities were recorded in December 2017 through regulatory charges to operating income totaling $674 million. (See Note 1 – General, Description of Business, Basis of Presentation, and Summary of Significant Accounting Policies of Notes to Consolidated Financial Statements.) The timing and actual amount of such return will be subject to future negotiations regarding this matter and many other elements of cost-of-service rate proceedings, including other costs of providing service.
Revenue Recognition
As a result of the adoption of Accounting Standards Update 2014-09, Revenues from Contracts with Customers (ASC 606), we expect that our 2018 revenues will increase in situations where we receive noncash consideration, which exists primarily in certain of our gas processing contracts where we receive commodities as full or partial consideration for services provided. This increase in revenues will be offset by a similar increase in costs and expenses when the commodities received are subsequently sold. Based on commodities received during 2017 as consideration for services and market prices during 2017, we estimate the impact to revenues and costs would have been approximately $350 million.
Additionally, we expect future revenues will be impacted by application of the new accounting standard to certain contracts for which we received prepayments for services and have recorded deferred revenue (contract liabilities). For these contracts, which underwent modifications in periods prior to January 1, 2018, the modification is treated as a termination of the existing contract and the creation of a new contract. The new accounting guidance requires that the transaction price, including any remaining deferred revenue from the old contract, be allocated to the performance obligations over the term of the new contract. As a result, we will recognize the deferred revenue over longer periods than application of revenue recognition under accounting guidance prior to January 1, 2018. The application of ASC 606 to prior periods related to these contracts would have resulted in lower revenues in 2016 and 2017. Revenues will also be lower in 2018 and 2019 than what would have been recorded under the previous guidance, offset by increased revenues in later reporting periods given the longer period of recognition.
We are adopting ASC 606 utilizing the modified retrospective transition approach, effective January 1, 2018, by recognizing the cumulative effect of initially applying ASC 606 for periods prior to January 1, 2018, which we expect to result in a decrease of approximately $255 million, net of tax, to the opening balance of Total equity in the Consolidated Balance Sheet. This adjustment is primarily associated with the impact to the timing of deferred revenue (contract liabilities) for certain contracts as noted above.
Pension Deferred Vested Benefit Early Payout Program
In September 2017, we initiated a program to pay out certain deferred vested pension benefits to reduce investment risk, cash funding volatility, and administrative costs. In December 2017, the lump-sum payments were made and the annuity payments were commenced in relation to this program. As a result of these lump-sum payments, as well as lump-sum benefit payments made throughout 2017, settlement accounting was required. We settled $261 million in liabilities and recognized a pre-tax, non-cash settlement charge of $71 million. (See Note 9 – Employee Benefit Plans of Notes to Consolidated Financial Statements.)
Expansion Project Completions
Virginia Southside II
In December 2017, the Virginia Southside II expansion project to the Transco system was placed into service. The project expanded Transco’s existing natural gas transmission system together with greenfield facilities to provide incremental firm transportation capacity from our Station 210 in New Jersey and our Station 165 in Virginia to a new lateral extending from our Brunswick Lateral in Virginia. The project increased capacity by 250 Mdth/d.
New York Bay Expansion
In October 2017, the New York Bay expansion to the Transco system was placed into service. The project expanded Transco’s existing natural gas transmission system to provide incremental firm transportation capacity from Station 195 in Pennsylvania to the Rockaway Delivery Lateral transfer point and the Narrows meter station in New York. The project increased capacity by 115 Mdth/d.
Dalton
In August 2017, the Dalton expansion to the Transco system was placed into service. This project expanded Transco’s existing natural gas transmission system together with greenfield facilities to provide incremental firm transportation capacity from our Station 210 in New Jersey to markets in northwest Georgia. On April 1, 2017, we began providing firm transportation service through the mainline portion of the project on an interim basis and we placed the full project into service in August 2017. The project increased capacity by 448 Mdth/d.
Hillabee
In July 2017, Phase I of the Hillabee Expansion Project was placed into service. The project involves an expansion of Transco’s existing natural gas transmission system from our Station 85 in west central Alabama to a new interconnection with the Sabal Trail pipeline in Alabama. The project will be constructed in phases, and all of the project expansion capacity is dedicated to Sabal Trail pursuant to a capacity lease agreement. We placed a portion of Phase I into service in June of 2017 and the remainder of Phase I into service in July of 2017. Phase I increased capacity by 818 Mdth/d. The in-service date of Phase II is planned for the second quarter of 2020 and together they are expected to increase capacity by 1,025 Mdth/d.
In March 2016, WPZ entered into an agreement with the member-sponsors of Sabal Trail to resolve several matters. In accordance with the agreement, the member-sponsors paid us an aggregate amount of $240 million in three equal installments as certain milestones of the project were met. The first $80 million payment was received in March 2016, the second installment was received in September 2016 and the third installment was received in July 2017. WPZ expects to recognize income associated with these receipts over the term of the capacity lease agreement.
In August 2017, the Court of Appeals for the District of Columbia Circuit granted an appeal of the FERC certificate order for the Southeast Market Pipelines projects (a group of related projects, including the Hillabee Expansion Project) filed by certain non-governmental organizations. In doing so, the court (i) remanded the matter to the FERC for preparation of an Environmental Impact Statement (EIS) that conforms with the court’s opinion regarding quantifying certain greenhouse gas emissions, and (ii) vacated the FERC’s certificate order for the projects, which would be effective following the court’s mandate (by court order, the mandate will not issue until after disposition of all petitions for rehearing). We, along with other intervenors, and the FERC filed petitions for rehearing with the court to overturn the remedy that would involve vacating the FERC certificate order, but on January 31, 2018 the court denied the petitions. In compliance with the court’s directive, on February 5, 2018, the FERC issued a Final Supplemental EIS for the projects, reaffirming that while the projects would result in temporary and permanent impacts on the environment, those impacts would not be significant. On February 6, 2018, we, along with other intervenors, and the FERC filed motions with the court to stay the issuance of the mandate in order to give the FERC time to re-issue the authorizations for the projects. The filing of the motions automatically stays the effectiveness of the court’s mandate. If the court’s mandate is issued prior to the FERC re-issuing the authorizations for the projects, we believe that the FERC will take the necessary steps (which may include issuing temporary certificate authority) to avoid any lapse in federal authorization for the projects.
Geismar olefins facility monetization
In July 2017, WPZ completed the sale of its Geismar Interest for $2.084 billion in cash. WPZ received a final working capital adjustment of $12 million in October 2017. Additionally, WPZ entered into a long-term supply and transportation agreement with the purchaser to provide feedstock to the plant via its Bayou Ethane pipeline system, which is expected to provide a long-term, fee-based revenue stream. (See Note 2 – Acquisitions and Divestitures of Notes to Consolidated Financial Statements.)
Following this sale, the cash proceeds were used to repay WPZ’s $850 million term loan. WPZ has also been using these proceeds to fund a portion of the capital and investment expenditures that are a part of its growth portfolio.
Acquisition of additional interests in Appalachia Midstream Investments
During the first quarter of 2017, WPZ exchanged all of its 50 percent interest in DBJV for an increased interest in two natural gas gathering systems that are part of the Appalachia Midstream Investments and $155 million in cash. Following this exchange, WPZ has an approximate average 66 percent interest in the Appalachia Midstream Investments. WPZ also sold all of its interest in Ranch Westex JV LLC for $45 million. These transactions resulted in a total gain of $269 million reflected in Other investing income (loss) – net in the Consolidated Statement of Operations within the Williams Partners segment. (See Note 5 – Investing Activities of Notes to Consolidated Financial Statements.)
Commodity Prices
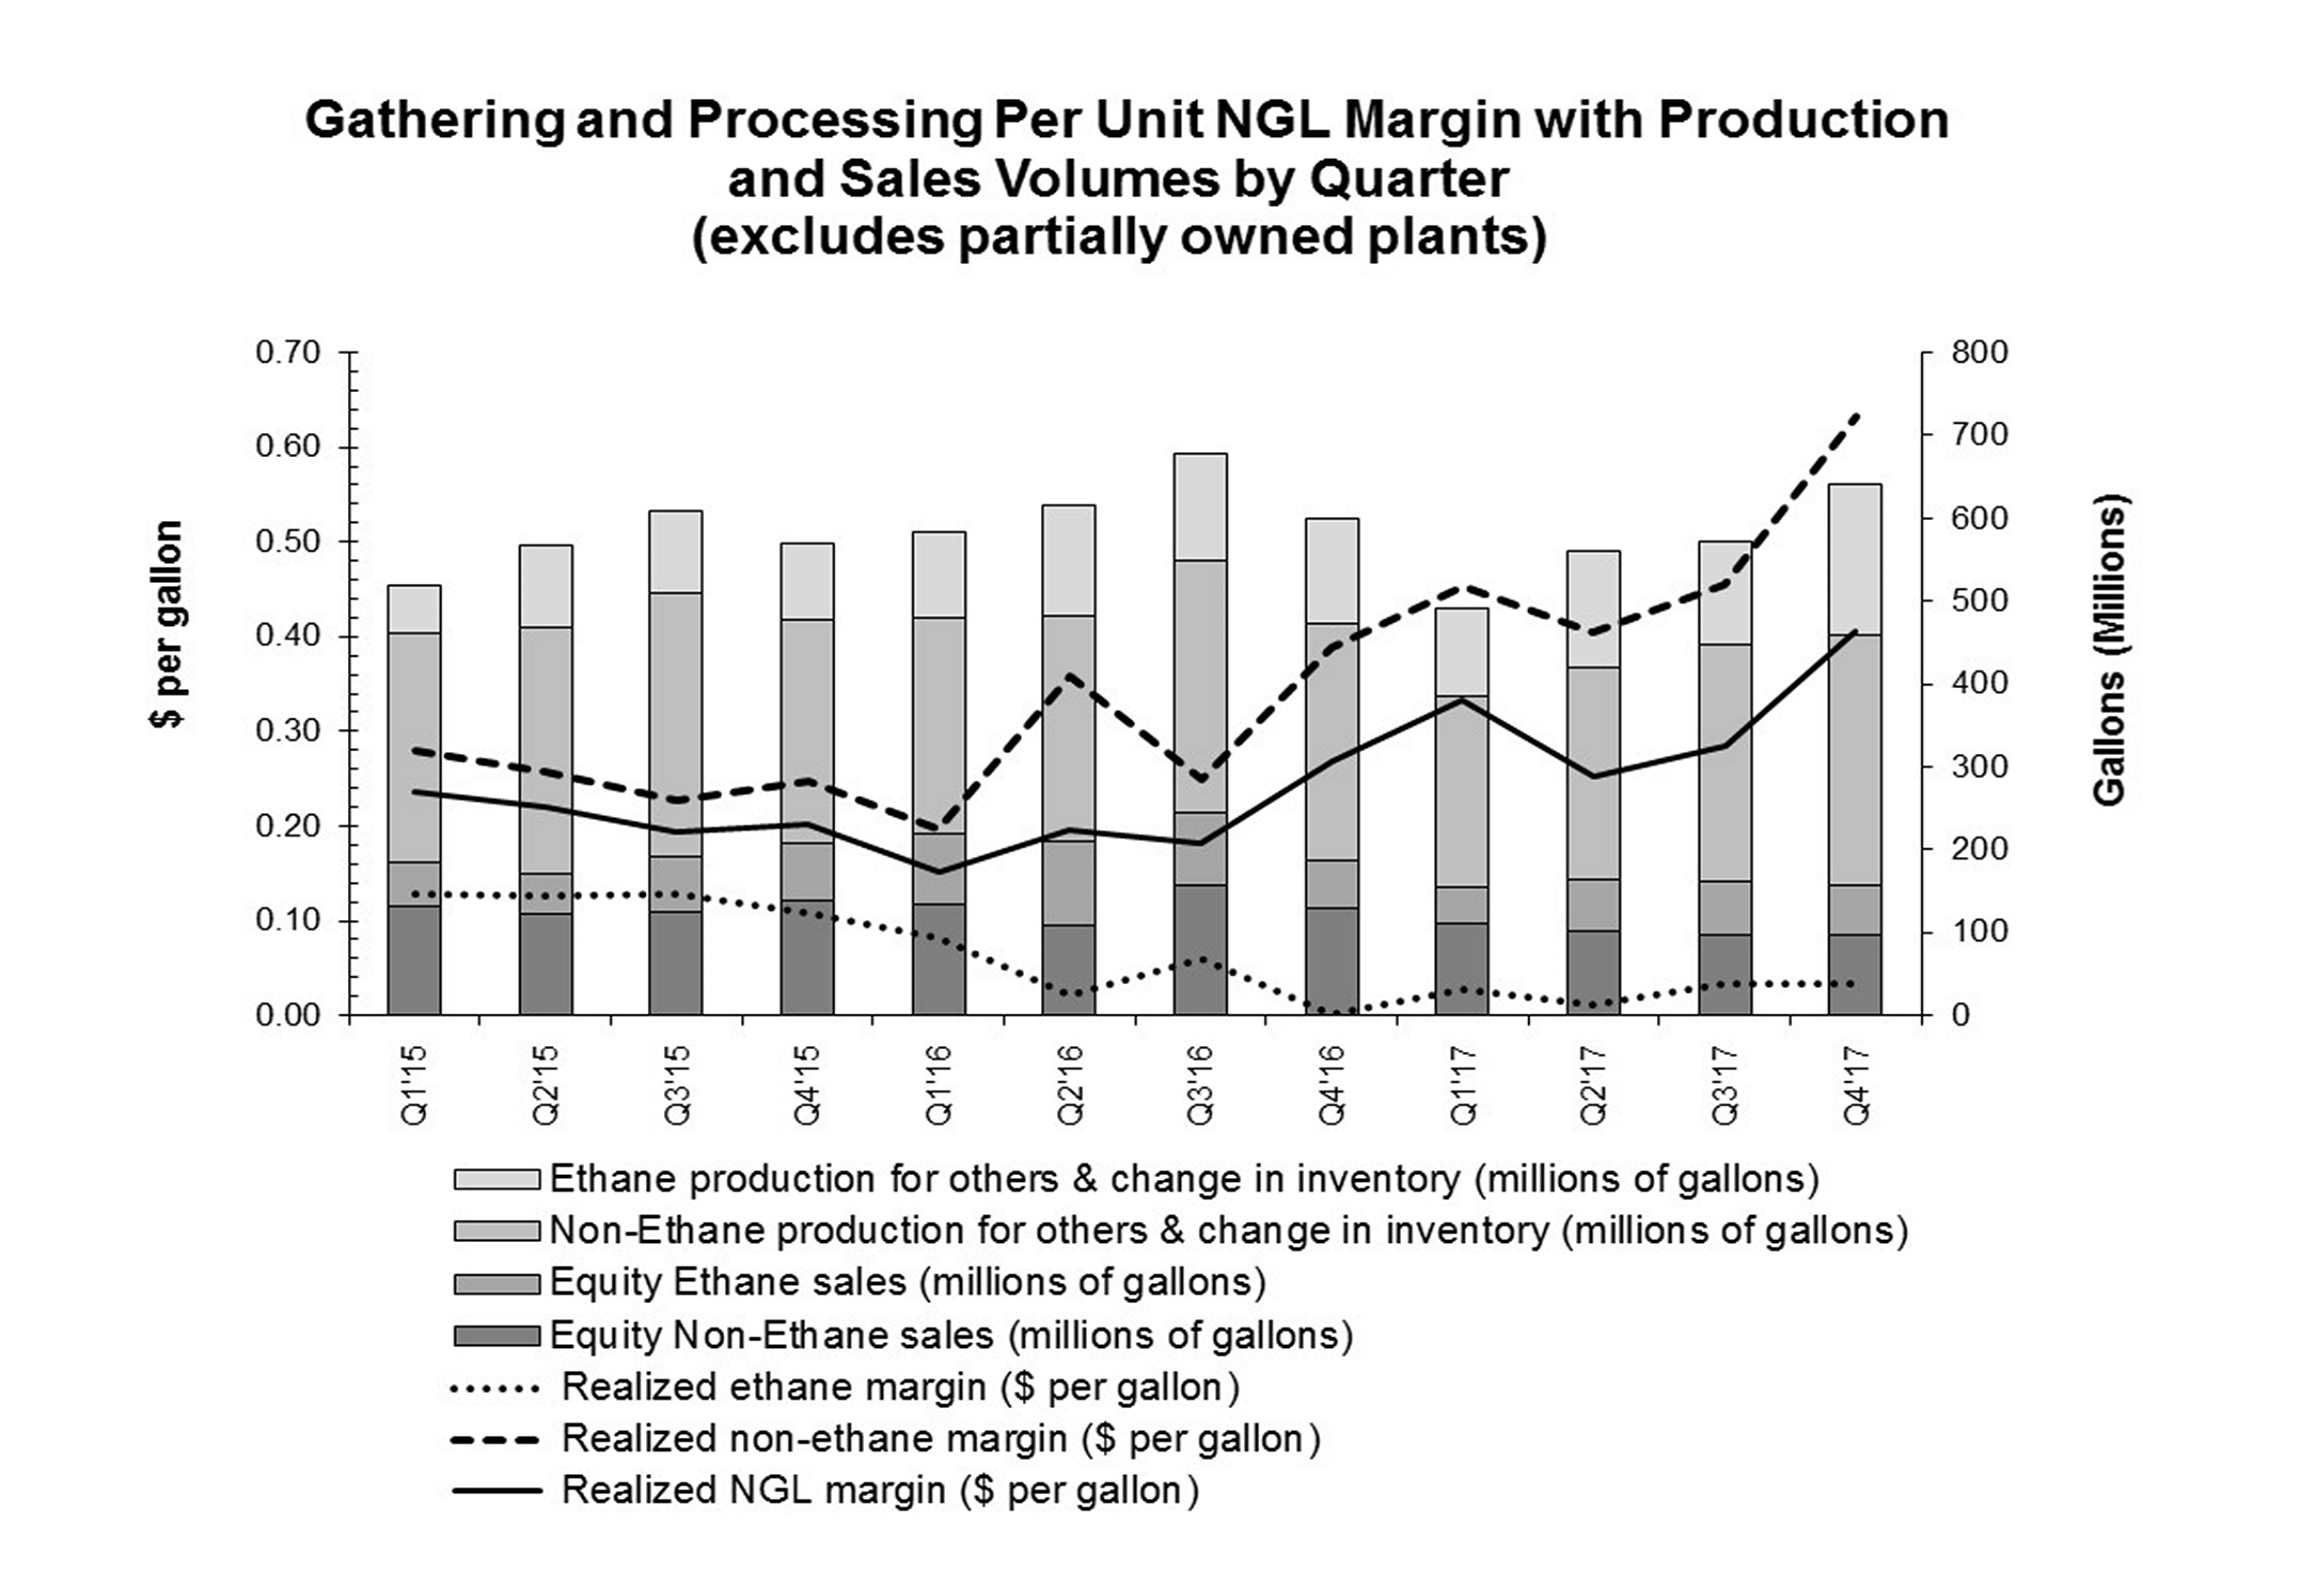
NGL per-unit margins were approximately 62 percent higher in 2017 compared to 2016 due to a 42 percent increase in per-unit non-ethane prices. The per-unit margin increase also reflects the absence of our former Canadian operations which had lower per-unit non-ethane margins in the prior year compared to our domestic operations. These favorable impacts were partially offset by an approximate 26 percent increase in per-unit natural gas feedstock prices.
NGL margins are defined as NGL revenues less any applicable Btu replacement cost, plant fuel, and third-party transportation and fractionation. Per-unit NGL margins are calculated based on sales of our own equity volumes at the processing plants. Our equity volumes include NGLs where we own the rights to the value from NGLs recovered at our plants under both “keep-whole” processing agreements, where we have the obligation to replace the lost heating value with natural gas, and “percent-of-liquids” agreements whereby we receive a portion of the extracted liquids with no obligation to replace the lost heating value.
The following graph illustrates the NGL production and sales volumes, as well as the margin differential between ethane and non-ethane products and the relative mix of those products.
 |
The potential impact of commodity prices on our business is further discussed in the following Company Outlook.
Company Outlook
Our strategy is to provide large-scale energy infrastructure designed to maximize the opportunities created by the vast supply of natural gas and natural gas products that exists in the United States. We accomplish this by connecting the growing demand for cleaner fuels and feedstocks with our major positions in the premier natural gas and natural gas products supply basins. We continue to maintain a strong commitment to safety, environmental stewardship, operational excellence, and customer satisfaction. We believe that accomplishing these goals will position us to deliver safe and reliable service to our customers and an attractive return to our shareholders.
Our business plan for 2018 includes a continued focus on growing our fee-based businesses, executing growth projects and accomplishing cost discipline initiatives to ensure operations support our strategy. We anticipate operating results will increase through organic business growth driven primarily by Transco expansion projects and continued growth in the Northeast region. WPZ intends to fund planned growth capital with retained cash flow and debt, and based on currently forecasted projects, does not expect to access public equity markets for the next several years.
Our growth capital and investment expenditures in 2018 are expected to be approximately $2.7 billion. Approximately $1.7 billion of our growth capital funding needs include Transco expansions and other interstate pipeline growth projects, most of which are fully contracted with firm transportation agreements. The remaining growth capital spending in 2018 primarily reflects investment in gathering and processing systems in the Northeast region limited primarily to known new producer volumes, including volumes that support Transco expansion projects including our Atlantic Sunrise project. In addition to growth capital and investment expenditures, we also remain committed to projects that maintain our assets for safe and reliable operations, as well as projects that meet legal, regulatory, and/or contractual commitments.
As a result of our significant continued capital and investment expenditures on Transco expansions and fee-based gathering and processing projects, fee-based businesses are a significant component of our portfolio and serve to reduce the influence of commodity price fluctuations on our operating results and cash flows. We expect to benefit as continued growth in demand for low-cost natural gas is driven by increases in LNG exports, industrial demand and power generation. For 2018, current forward market prices indicate oil prices are expected to be higher compared to 2017, while natural gas and NGL prices are expected to be lower or comparable with 2017. We continue to address certain pricing risks through the utilization of commodity hedging strategies. However, some of our customers may continue to curtail or delay drilling plans until there is a more sustained recovery in prices, which may negatively impact our gathering and processing volumes. The credit profiles of certain of our producer customers have been, and may continue to be, challenged as a result of lower energy commodity prices. Unfavorable changes in energy commodity prices or the credit profile of our producer customers may also result in noncash impairments of our assets.
In 2018, our operating results are expected to include increases from our regulated Transco fee-based business, primarily related to projects recently placed in-service or expected to be placed in-service in 2018 including the Atlantic Sunrise project. For our non-regulated businesses, we anticipate increases in fee-based revenue in the Northeast region, partially offset by lower fee-based revenue in the West region. As previously discussed, under the new accounting guidance for revenue recognition, deferred revenue under certain contracts will be recognized over longer periods than under the prior guidance, resulting in a decrease in revenue for the West region. We expect overall gathering and processing volumes to grow in 2018 and increase thereafter to meet the growing demand for natural gas and natural gas products. We also anticipate lower general and administrative expenses due to the full year impact of prior year cost reduction initiatives.
Potential risks and obstacles that could impact the execution of our plan include:
| • | Certain aspects of Tax Reform, including regulatory liabilities relating to reduced corporate federal income tax rates, could adversely impact the rates we can charge on our regulated pipelines; |
| • | Opposition to infrastructure projects, including the risk of delay or denial in permits and approvals needed for our projects; |
| • | Unexpected significant increases in capital expenditures or delays in capital project execution; |
| • | Counterparty credit and performance risk, including that of Chesapeake Energy Corporation and its affiliates; |
| • | Lower than anticipated demand for natural gas and natural gas products which could result in lower than expected volumes, energy commodity prices and margins; |
| • | General economic, financial markets, or further industry downturn, including increased interest rates; |
| • | Physical damages to facilities, including damage to offshore facilities by named windstorms; |
| • | Lower than expected distributions from WPZ; |
| • | Production issues impacting offshore gathering volumes; |
| • | Other risks set forth under Part I, Item 1A. Risk Factors in this report. |
We seek to maintain a strong financial position and liquidity, as well as manage a diversified portfolio of energy infrastructure assets which continue to serve key growth markets and supply basins in the United States.
Expansion Projects
Williams Partners’ ongoing major expansion projects include the following:
Atlantic Sunrise
In February 2017, we received approval from the FERC to expand Transco’s existing natural gas transmission system along with greenfield facilities to provide incremental firm transportation capacity from the northeastern Marcellus producing area to markets along Transco’s mainline as far south as Station 85 in west central Alabama. We placed a portion of the mainline project facilities into service in September 2017 and it increased capacity by 400 Mdth/d. We plan to place the full project into service during mid-2018, assuming timely receipt of all remaining regulatory approvals. The full project is expected to increase capacity by 1,700 Mdth/d.
Constitution Pipeline
We currently own 41 percent of Constitution with three other parties holding 25 percent, 24 percent, and 10 percent, respectively. We are the operator of Constitution. The 126-mile Constitution pipeline is proposed to connect our gathering system in Susquehanna County, Pennsylvania, to the Iroquois Gas Transmission and Tennessee Gas Pipeline systems in New York, as well as to a local distribution company serving New York and Pennsylvania.
In December 2014, Constitution received approval from the FERC to construct and operate its proposed pipeline, which will have an expected capacity of 650 Mdth/d. However, in April 2016, the New York State Department of Environmental Conservation (NYSDEC) denied the necessary water quality certification under Section 401 of the Clean Water Act for the New York portion of the pipeline. In May 2016, Constitution appealed the NYSDEC’s denial of the Section 401 certification to the United States Court of Appeals for the Second Circuit and in August 2017, the court issued a decision denying in part and dismissing in part Constitution’s appeal. The court expressly declined to rule on Constitution’s argument that the delay in the NYSDEC’s decision on Constitution’s Section 401 application constitutes a waiver of the certification requirement. The court determined that it lacked jurisdiction to address that contention, and found that jurisdiction over the waiver issue lies exclusively with the United States Court of Appeals for the District of Columbia Circuit. As to the denial itself, the court determined that NYSDEC’s action was not arbitrary or capricious. Constitution filed a petition for rehearing with the Second Circuit Court of Appeals, but in October the court denied our petition.
In October 2017, we filed a petition for declaratory order requesting the FERC to find that, by operation of law, the Section 401 certification requirement for the New York State portion of Constitution’s pipeline project was waived due to the failure by the NYSDEC to act on Constitution’s Section 401 application within a reasonable period of time as required by the express terms of such statute. In January 2018, the FERC denied our petition, finding that Section 401 provides that a state waives certification only when it does not act on an application within one year from the date of the application.
The project’s sponsors remain committed to the project, and, in that regard, we are pursuing two separate and independent paths in order to overturn the NYSDEC’s denial of the Section 401 certification. In January 2018, we filed a petition with the United States Supreme Court to review the decision of the Second Circuit Court of Appeals that upheld the merits of the NYSDEC’s denial of the Section 401 certification. And, in February 2018, we filed a request with the FERC for rehearing of its finding that the NYSDEC did not waive the Section 401 certification requirement. If the FERC denies such request, we will file a petition for review with the D.C. Circuit Court of Appeals.
We estimate that the target in-service date for the project would be approximately 10 to 12 months following any court or FERC decision that the NYSDEC denial order was improper or that the NYSDEC waived the Section 401 certification requirement. (See Note 3 – Variable Interest Entities of Notes to Consolidated Financial Statements.)
Garden State
In April 2016, we received approval from the FERC to expand Transco’s existing natural gas transmission system to provide incremental firm transportation capacity from Station 210 in New Jersey to a new interconnection
on our Trenton Woodbury Lateral in New Jersey. The project will be constructed in phases and is expected to increase capacity by 180 Mdth/d. We placed the initial phase of the project into service in September 2017 and plan to place the remaining portion of the project into service during the first quarter of 2018.
Gateway
In November 2017, we filed an application with the FERC to expand Transco’s existing natural gas transmission system to provide incremental firm transportation capacity from PennEast Pipeline Company's proposed interconnection with Transco’s mainline south of Station 205 in New Jersey to other existing Transco meter stations within New Jersey. We plan to place the project into service in the first quarter of 2021, assuming timely receipt of all necessary regulatory approvals. The project is expected to increase capacity by 65 Mdth/d.
Gulf Connector
In November 2017, we received approval from the FERC allowing Transco to expand its existing natural gas transmission system to provide incremental firm transportation capacity from Station 65 in Louisiana to delivery points in Wharton and San Patricio Counties, Texas. The project will be constructed in two phases and we plan to place both phases into service during the first half of 2019, assuming timely receipt of all necessary regulatory approvals. The project is expected to increase capacity by 475 Mdth/d.
Hillabee
In February 2016, the FERC issued a certificate order for the initial phases of Transco’s Hillabee Expansion Project. The project involves an expansion of Transco’s existing natural gas transmission system from Station 85 in west central Alabama to a new interconnection with the Sabal Trail pipeline in Alabama. The project will be constructed in phases, and all of the project expansion capacity will be leased to Sabal Trail. We placed a portion of Phase I into service in June of 2017 and the remainder of Phase I into service in July of 2017. Phase I increased capacity by 818 Mdth/d. The in-service date of Phase II is planned for the second quarter of 2020 and together they are expected to increase capacity by 1,025 Mdth/d. See Expansion Project Completions within Overview.
Norphlet Project
In March 2016, we announced that we have reached an agreement to provide deepwater gas gathering services to the Appomattox development in the Gulf of Mexico. The project will provide offshore gas gathering services to our existing Transco lateral, which will provide transmission services onshore to our Mobile Bay processing facility. We also plan to make modifications to our Main Pass 261 Platform to install an alternate delivery route from the platform, as well as modifications to our Mobile Bay processing facility. The project is scheduled to go into service during the second half of 2019.
North Seattle Lateral Upgrade
In May 2017, we filed an application with the FERC to expand delivery capabilities on Northwest Pipeline’s North Seattle Lateral. The project consists of the removal and replacement of approximately 5.9 miles of 8-inch diameter pipeline with new 20-inch diameter pipeline. We plan to place the project into service as early as the fourth quarter of 2019. The project is expected to increase capacity by up to 159 Mdth/d.
Northeast Supply Enhancement
In March 2017, we filed an application with the FERC to expand Transco’s existing natural gas transmission system to provide incremental firm transportation capacity from Station 195 in Pennsylvania to the Rockaway Delivery Lateral transfer point in New York. We plan to place the project into service in late 2019 or during the first half of 2020, assuming timely receipt of all necessary regulatory approvals. The project is expected to increase capacity by 400 Mdth/d.
Ohio River Supply Hub Expansion
We agreed to expand our services to a customer to provide 660 MMcf/d of processing wet gas capacity in the Marcellus and Upper Devonian Shale in West Virginia. Associated with this agreement, we expect to further expand the processing capacity of our Oak Grove facility, which has the ability to increase capacity by an additional 1.8 Bcf/d. Additionally, with the same customer, we secured a gathering dedication agreement to gather dry gas in this same region. These expansions will be supported by long-term, fee-based agreements and volumetric commitments.
Rivervale South to Market
In August 2017, we filed an application with the FERC to expand Transco’s existing natural gas transmission system to provide incremental firm transportation capacity from the existing Rivervale interconnection with Tennessee Gas Pipeline on Transco’s North New Jersey Extension to other existing Transco locations within New Jersey. We plan to place the project into service as early as the fourth quarter of 2019, assuming timely receipt of all necessary regulatory approvals. The project is expected to increase capacity by 190 Mdth/d.
Susquehanna Supply Hub Expansion
The Susquehanna Supply Hub Expansion, which involves two new compression facilities with an additional 49,000 horsepower and 59 miles of 12 inch to 24 inch pipeline, is expected to increase gathering capacity, allowing a certain producer to fulfill its commitment to deliver 850 Mdth/d to our Atlantic Sunrise development. We placed a portion of this project into service in January 2018 and anticipate this expansion will be fully commissioned in the first quarter of 2018.
Critical Accounting Estimates
The preparation of financial statements in conformity with generally accepted accounting principles requires management to make estimates and assumptions. We believe that the nature of these estimates and assumptions is material due to the subjectivity and judgment necessary, or the susceptibility of such matters to change, and the impact of these on our financial condition or results of operations.
Pension and Postretirement Obligations
We have employee benefit plans that include pension and other postretirement benefits. Net periodic benefit cost and obligations for these plans are impacted by various estimates and assumptions. These estimates and assumptions include the expected long-term rates of return on plan assets, discount rates, expected rate of compensation increase, health care cost trend rates, and employee demographics, including retirement age and mortality. These assumptions are reviewed annually and adjustments are made as needed. The assumptions utilized to compute cost and the benefit obligations are shown in Note 9 – Employee Benefit Plans of Notes to Consolidated Financial Statements.
The following table presents the estimated increase (decrease) in net periodic benefit cost and obligations resulting from a one-percentage-point change in the specific assumption.
| Benefit Cost | Benefit Obligation | ||||||||||||||
| One- Percentage- Point Increase | One- Percentage- Point Decrease | One- Percentage- Point Increase | One- Percentage- Point Decrease | ||||||||||||
| (Millions) | |||||||||||||||
| Pension benefits: | |||||||||||||||
| Discount rate | $ | (8 | ) | $ | 9 | $ | (118 | ) | $ | 140 | |||||
| Expected long-term rate of return on plan assets | (12 | ) | 12 | — | — | ||||||||||
| Rate of compensation increase | 2 | (1 | ) | 9 | (6 | ) | |||||||||
| Other postretirement benefits: | |||||||||||||||
| Discount rate | 1 | 1 | (22 | ) | 27 | ||||||||||
| Expected long-term rate of return on plan assets | (2 | ) | 2 | — | — | ||||||||||
| Assumed health care cost trend rate | — | — | 5 | (5 | ) |
Our expected long-term rates of return on plan assets, as determined at the beginning of each fiscal year, are based on the average rate of return expected on the funds invested in the plans. We determine our long-term expected rates of return on plan assets using our expectations of capital market results, which include an analysis of historical results as well as forward-looking projections. These capital market expectations are based on a period of at least 10 years and take into account our investment strategy and mix of assets. We develop our expectations using input from our third-party independent investment consultant. The forward-looking capital market projections start with current conditions of interest rates, equity pricing, economic growth, and inflation and those are overlaid with forward looking projections of normal inflation, growth, and interest rates to determine expected returns. The capital market return projections for specific asset classes in the investment portfolio are then applied to the relative weightings of the asset classes in the investment portfolio. The resulting rates are an estimate of future results and, thus, likely to be different than actual results.
In 2017, the benefit plans’ assets outperformed their respective benchmarks for fixed income strategies, but generally underperformed the respective benchmarks for equity strategies. While the 2017 investment performance was greater than our expected rates of return, the expected rates of return on plan assets are long-term in nature and are not significantly impacted by short-term market performance. Changes to our asset allocation would also impact these expected rates of return. Our expected long-term rate of return on plan assets used for our pension plans was 6.45 percent in 2017. The 2017 actual return on plan assets for our pension plans was approximately 15.5 percent. The 10-year average rate of return on pension plan assets through December 2017 was approximately 4.3 percent.
The discount rates are used to measure the benefit obligations of our pension and other postretirement benefit plans. The objective of the discount rates is to determine the amount, if invested at the December 31 measurement date in a portfolio of high-quality debt securities, that will provide the necessary cash flows when benefit payments are due. Increases in the discount rates decrease the obligation and, generally, decrease the related cost. The discount rates for our pension and other postretirement benefit plans are determined separately based on an approach specific to our plans and their respective expected benefit cash flows as described in Note 1 – General, Description of Business, Basis of Presentation, and Summary of Significant Accounting Policies and Note 9 – Employee Benefit Plans of Notes to Consolidated Financial Statements. Our discount rate assumptions are impacted by changes in general economic and market conditions that affect interest rates on long-term, high-quality debt securities as well as by the duration of our plans’ liabilities.
The expected rate of compensation increase represents average long-term salary increases. An increase in this rate causes the pension obligation and cost to increase.
The assumed health care cost trend rates are based on national trend rates adjusted for our actual historical cost rates and plan design. An increase in this rate causes the other postretirement benefit obligation and cost to increase.
Property, Plant, and Equipment and Other Identifiable Intangible Assets
We evaluate our property, plant, and equipment and other identifiable intangible assets for impairment when events or changes in circumstances indicate, in our judgment, that the carrying value of such assets may not be recoverable. When an indicator of impairment has occurred, we compare our estimate of undiscounted future cash flows attributable to the assets to the carrying value of the assets to determine whether an impairment has occurred and we may apply a probability-weighted approach to consider the likelihood of different cash flow assumptions and possible outcomes including selling in the near term or holding for the remaining estimated useful life. If an impairment of the carrying value has occurred, we determine the amount of the impairment recognized by estimating the fair value of the assets and recording a loss for the amount that the carrying value exceeds the estimated fair value. This evaluation is performed at the lowest level for which separately identifiable cash flows exist.
During the third quarter of 2017, we received solicitations and engaged in negotiations for the sale of certain gas gathering assets within the Mid-Continent region. As a result of these events, we evaluated the Mid-Continent asset group, which includes property, plant, and equipment and intangible assets, for impairment. Our evaluation considered the likelihood of divesting certain assets within the Mid-Continent region as well as information developed from the negotiation process that impacted our estimate of future cash flows associated with these assets. The estimated undiscounted future cash flows were determined to be below the carrying amount for these assets. We computed the
estimated fair value using an income approach and incorporated market inputs based on ongoing negotiations for the potential sale of a portion of the underlying assets. For the income approach, we utilized a discount rate of 10.2 percent, reflecting an estimated cost of capital and risks associated with the underlying assets. As a result of this evaluation, we recorded an impairment charge of $1.019 billion for the difference between the estimated fair value and carrying amount of these assets.
Judgments and assumptions are inherent in estimating undiscounted future cash flows, fair values, and the probability-weighting of possible outcomes. The use of alternate judgments and assumptions could result in a different determination affecting the consolidated financial statements.
Equity-Method Investments
At December 31, 2017, our Consolidated Balance Sheet includes approximately $6.6 billion of investments that are accounted for under the equity-method of accounting. We evaluate these investments for impairment when events or changes in circumstances indicate, in our management’s judgment, that the carrying value of such investments may have experienced an other-than-temporary decline in value. We continue to monitor our equity-method investments for any indications that the carrying value may have experienced an other-than-temporary decline in value. When evidence of a loss in value has occurred, we compare our estimate of the fair value of the investment to the carrying value of the investment to determine whether an impairment has occurred. We generally estimate the fair value of our investments using an income approach where significant judgments and assumptions include expected future cash flows and the appropriate discount rate. In some cases, we may utilize a form of market approach to estimate the fair value of our investments.
If the estimated fair value is less than the carrying value and we consider the decline in value to be other-than-temporary, the excess of the carrying value over the fair value is recognized in the consolidated financial statements as an impairment charge. Events or changes in circumstances that may be indicative of an other-than-temporary decline in value will vary by investment, but may include:
| • | A significant or sustained decline in the market value of an investee; |
| • | Lower than expected cash distributions from investees; |
| • | Significant asset impairments or operating losses recognized by investees; |
| • | Significant delays in or lack of producer development or significant declines in producer volumes in markets served by investees; |
| • | Significant delays in or failure to complete significant growth projects of investees. |
As of December 31, 2017, the carrying value of our equity-method investment in Discovery is $534 million. During the fourth quarter of 2017, certain customers of Discovery terminated a significant offshore gas gathering agreement following the shut-in of production after the associated wells ceased flowing. As a result, we evaluated this investment for impairment and determined that no impairment was necessary.
We estimated the fair value of our investment in Discovery using an income approach that primarily considered probability-weighted assumptions of additional commercial development, the continued operation of the business under existing contracts, and a discount rate of 11.3 percent. Higher probabilities were generally assigned to those commercial development opportunities that were more advanced in the discussion and contracting process, utilizing existing infrastructure due to producer capital constraints, and/or we believe Discovery has a competitive advantage due to geographical proximity to the prospect. The estimated fair value of our investment in Discovery exceeded its carrying value by approximately 6 percent and thus no impairment was necessary.
Judgments and assumptions are inherent in our estimates of future cash flows, discount rates, and additional development probabilities. It is reasonably possible that an impairment could be required in the future if commercial development activities are not as successful or as timely as assumed. The use of alternate judgments and assumptions
could result in a different calculation of fair value, which could ultimately result in the recognition of an impairment charge in the consolidated financial statements.
Constitution Pipeline Capitalized Project Costs
As of December 31, 2017, Property, plant, and equipment – net in our Consolidated Balance Sheet includes approximately $381 million of capitalized project costs for Constitution, for which we are the construction manager and own a 41 percent consolidated interest. As a result of the events discussed in Company Outlook, we evaluated the capitalized project costs for impairment as recently as December 31, 2017, and determined that no impairment was necessary. Our evaluation considered probability-weighted scenarios of undiscounted future net cash flows, including scenarios assuming construction of the pipeline, as well as a scenario where the project does not proceed. These scenarios included our most recent estimate of total construction costs. The probability-weighted scenarios also considered our assessment of the likelihood of success of the two separate and independent paths to obtain necessary certification, as described in Company Outlook. It is reasonably possible that future unfavorable developments, such as a reduced likelihood of success, increased estimates of construction costs, or further significant delays, could result in a future impairment.
Regulatory Liabilities resulting from Tax Reform
In December 2017, Tax Reform was enacted, which, among other things, reduced the corporate income tax rate from 35 percent to 21 percent. Rates charged to customers of our regulated natural gas pipelines are subject to the rate-making policies of the FERC, which permit the recovery of an income tax allowance that includes a deferred income tax component. As a result of the reduced income tax rate from Tax Reform and the collection of historical rates that reflected historical federal income tax rates, we expect that our regulated natural gas pipelines will be required to return amounts to certain customers through future rates and have established regulatory liabilities accordingly. These liabilities were recorded in December 2017 through regulatory charges to operating income totaling $674 million. (See Note 1 – General, Description of Business, Basis of Presentation, and Summary of Significant Accounting Policies of Notes to Consolidated Financial Statements.) The timing and actual amount of such return will be subject to future negotiations regarding this matter and many other elements of cost–of–service rate proceedings, including other costs of providing service.
Our estimation of these regulatory liabilities incorporated the following significant judgments and assumptions involving income taxes collected from our customers.
| • | We utilized current FERC guidance for the default income tax rate for non-corporate taxpayers, which is an element of our overall effective tax rate. It is possible that the FERC will provide updated implementation guidance in the future, including an updated default income tax rate for non-corporate taxpayers. We estimate that a decline of one percentage point in our assumed overall effective tax rate would increase our regulatory liabilities by approximately $42 million. |
| • | We made assumptions regarding the allocation of WPZ taxable income between corporate and non-corporate taxpayers. This allocation is subject to annual variation that could impact the weighted average federal tax component of the overall income tax allowance rate. |
| • | We made assumptions regarding the allocation of WPZ taxable income among the states in which WPZ conducts business. This allocation is subject to annual variation that could impact the weighted average state tax component of the overall income tax allowance rate. It is possible that certain states may change their income tax laws and/or rates in the future in response to Tax Reform. |
| • | In determining the estimated liability that we currently believe is probable of return to customers through future rates, we considered the mix of services provided by our regulated natural gas pipelines, taking into consideration that certain of these services are provided under contractually-based rates, in lieu of recourse-based rates. The contractually-based rates are designed to recover the cost of providing those services, with |
no expected future rate adjustment for the term of those contracts. We estimate that a one percent change in the relative mix of services would change the regulatory liability by approximately $8 million.
The use of alternative judgments and assumptions could result in the recognition of different regulatory liabilities and associated charges in the consolidated financial statements.
Results of Operations
Consolidated Overview
The following table and discussion is a summary of our consolidated results of operations for the three years ended December 31, 2017. The results of operations by segment are discussed in further detail following this consolidated overview discussion.
| Years Ended December 31, | |||||||||||||||||||||||
| 2017 | $ Change from 2016* | % Change from 2016* | 2016 | $ Change from 2015* | % Change from 2015* | 2015 | |||||||||||||||||
| (Millions) | |||||||||||||||||||||||
| Revenues: | |||||||||||||||||||||||
| Service revenues | $ | 5,312 | +141 | +3 | % | $ | 5,171 | +7 | — | % | $ | 5,164 | |||||||||||
| Product sales | 2,719 | +391 | +17 | % | 2,328 | +132 | +6 | % | 2,196 | ||||||||||||||
| Total revenues | 8,031 | 7,499 | 7,360 | ||||||||||||||||||||
| Costs and expenses: | |||||||||||||||||||||||
| Product costs | 2,300 | -575 | -33 | % | 1,725 | +54 | +3 | % | 1,779 | ||||||||||||||
| Operating and maintenance expenses | 1,585 | -5 | — | % | 1,580 | +75 | +5 | % | 1,655 | ||||||||||||||
| Depreciation and amortization expenses | 1,736 | +27 | +2 | % | 1,763 | -25 | -1 | % | 1,738 | ||||||||||||||
| Selling, general, and administrative expenses | 608 | +115 | +16 | % | 723 | +18 | +2 | % | 741 | ||||||||||||||
| Impairment of goodwill | — | — | — | % | — | +1,098 | +100 | % | 1,098 | ||||||||||||||
| Impairment of certain assets | 1,248 | -375 | -43 | % | 873 | -664 | NM | 209 | |||||||||||||||
| Gain on sale of Geismar Interest | (1,095 | ) | +1,095 | NM | — | — | — | % | — | ||||||||||||||
| Regulatory charges resulting from Tax Reform | 674 | -674 | NM | — | — | — | % | — | |||||||||||||||
| Insurance recoveries – Geismar Incident | (9 | ) | +2 | +29 | % | (7 | ) | -119 | -94 | % | (126 | ) | |||||||||||
| Other (income) expense – net | 80 | +62 | +44 | % | 142 | -102 | NM | 40 | |||||||||||||||
| Total costs and expenses | 7,127 | 6,799 | 7,134 | ||||||||||||||||||||
| Operating income (loss) | 904 | 700 | 226 | ||||||||||||||||||||
| Equity earnings (losses) | 434 | +37 | +9 | % | 397 | +62 | +19 | % | 335 | ||||||||||||||
| Impairment of equity-method investments | — | +430 | +100 | % | (430 | ) | +929 | +68 | % | (1,359 | ) | ||||||||||||
| Other investing income (loss) – net | 282 | +219 | NM | 63 | +36 | +133 | % | 27 | |||||||||||||||
| Interest expense | (1,083 | ) | +96 | +8 | % | (1,179 | ) | -135 | -13 | % | (1,044 | ) | |||||||||||
| Other income (expense) – net | (2 | ) | -76 | NM | 74 | -28 | -27 | % | 102 | ||||||||||||||
| Income (loss) before income taxes | 535 | (375 | ) | (1,713 | ) | ||||||||||||||||||
| Provision (benefit) for income taxes | (1,974 | ) | +1,949 | NM | (25 | ) | -374 | -94 | % | (399 | ) | ||||||||||||
| Net income (loss) | 2,509 | (350 | ) | (1,314 | ) | ||||||||||||||||||
| Less: Net income (loss) attributable to noncontrolling interests | 335 | -261 | NM | 74 | -817 | NM | (743 | ) | |||||||||||||||
| Net income (loss) attributable to The Williams Companies, Inc. | $ | 2,174 | $ | (424 | ) | $ | (571 | ) |
| * | + = Favorable change; - = Unfavorable change; NM = A percentage calculation is not meaningful due to a change in signs, a zero-value denominator, or a percentage change greater than 200. |
2017 vs. 2016
Service revenues increased due to higher transportation fee revenues at Transco and in the eastern Gulf reflecting expansion projects placed in-service in 2016 and 2017; partially offset by a decrease in gathering, processing, and fractionation revenue including lower rates, primarily in the Barnett Shale region associated with the restructuring of
contracts in the fourth quarter of 2016; lower volumes in the western regions, driven by natural declines and extreme weather conditions in the Rocky Mountains in 2017; and the sale of our former Canadian and Gulf Olefins operations.
Product sales increased primarily due to higher marketing revenues reflecting significantly higher prices and volumes. Revenues from the sale of our equity NGLs increased primarily due to higher non-ethane NGL prices, partially offset by lower volumes. These increases were partially offset by lower olefin production sales due to lower volumes resulting from the sale of our former Gulf Olefins and Canadian operations.
The increase in Product costs is primarily due to the same factors that increased marketing sales, partially offset by lower olefin feedstock purchases associated with the sale of our Gulf Olefins and Canadian operations.
Operating and maintenance expenses increased primarily due to higher pipeline integrity testing and general maintenance at Transco and a settlement charge from a pension early payout program (see Note 9 – Employee Benefit Plans of Notes to Consolidated Financial Statements), partially offset by the absence of costs associated with our former Canadian and Gulf Olefins operations and lower labor-related costs resulting from our workforce reductions that occurred late in first-quarter 2016, and ongoing cost containment efforts.
Depreciation and amortization expenses decreased primarily due to the absence of our former Canadian and Gulf Olefins operations, partially offset by new assets placed in-service.
Selling, general, and administrative expenses (SG&A) decreased primarily due to the absence of certain project development costs associated with the Canadian PDH facility that were expensed in 2016, lower labor-related costs resulting from our workforce reductions that occurred late in first-quarter 2016, ongoing cost containment efforts, lower strategic development costs, and the absence of costs associated with our former Canadian and Gulf Coast operations. These decreases were partially offset by higher severance and organizational realignment costs in 2017 (see Note 6 – Other Income and Expenses of Notes to Consolidated Financial Statements) and a settlement charge from a pension early payout program.
The unfavorable change in Impairment of certain assets reflects 2017 impairments of certain gathering operations in the Mid-Continent and Marcellus South regions, certain NGL pipeline assets, and an olefins pipeline project in the Gulf coast region. These 2017 impairments are partially offset by the absence of 2016 impairments of our former Canadian operations and certain Mid-Continent assets (see Note 16 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements).
The Gain on sale of Geismar Interest reflects the gain recognized on the sale of our Geismar Interest in July 2017. (See Note 2 – Acquisitions and Divestitures of Notes to Consolidated Financial Statements.)
Regulatory charges resulting from Tax Reform relates to the recognition of regulatory liabilities for the probable return to customers through future rates of the future decrease in income taxes payable associated with Tax Reform. (See Note 1 – General, Description of Business, Basis of Presentation, and Summary of Significant Accounting Policies of Notes to Consolidated Financial Statements).
The favorable change in Other (income) expense – net within Operating income (loss) includes the absence of the 2016 loss on the sale of our Canadian operations, gains from certain contract settlements and terminations in 2017, a gain on the sale of our RGP Splitter in 2017, and the absence of an unfavorable change in foreign currency exchange associated with our former Canadian operations. These favorable changes are partially offset by additional expense associated with an annual revision to the ARO liability, accrual of additional expenses in 2017 related to the Geismar Incident, as well as the absence of a gain in first-quarter 2016 associated with the sale of unused pipe.
Operating income (loss) changed favorably primarily due to the Gain on sale of Geismar Interest, the absence of the 2016 impairments of certain Mid-Continent assets and our former Canadian operations, higher service revenues primarily from expansion projects placed in-service in 2016 and 2017, the absence of expensed Canadian PDH facility project development costs in 2016, as well as ongoing cost containment efforts, including workforce reductions in first-quarter 2016. Operating income (loss) also improved due to the absence of a 2016 loss on the sale of our Canadian operations, the absence of an operating loss associated with our former Canadian operations, gains from certain contract settlements and the sale of our RGP Splitter. These favorable changes were partially offset by 2017 impairments of
certain gathering operations in the Mid-Continent and Marcellus South regions, regulatory charges resulting from Tax Reform, and certain NGL pipeline assets, as well as the absence of operating income associated with our former Gulf Olefins operations, and a settlement charge from a pension early payout program.
The favorable change in Equity earnings (losses) is due to an increase in ownership of our Appalachia Midstream Investments and improved results at Aux Sable due to favorable pricing and higher volumes, partially offset by lower UEOM results driven by lower processing volumes from the Utica gathering system and lower Discovery results due to lower volumes.
The decrease in Impairment of equity-method investments reflects the absence of 2016 impairment charges associated with our Appalachia Midstream Investments, DBJV, Laurel Mountain, and Ranch Westex equity-method investments. (See Note 16 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
Other investing income (loss) – net reflects the gain on disposition of our investments in DBJV and Ranch Westex JV LLC in 2017, partially offset by the absence of interest income received in 2016 associated with a receivable related to the sale of certain former Venezuelan assets and the absence of a 2016 gain on the sale of an equity-method investment interest in a gathering system that was part of our Appalachia Midstream Investments. (See Note 5 – Investing Activities of Notes to Consolidated Financial Statements).
Interest expense decreased primarily due to lower Interest incurred primarily attributable to debt retirements in 2017 and lower borrowings on our credit facilities in 2017. (See Note 13 – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements.)
Other income (expense) – net below Operating income (loss) changed unfavorably primarily due to charges reducing regulatory assets related to deferred taxes on equity funds used during construction (AFUDC) resulting from Tax Reform and a settlement charge from a pension early payout program, partially offset by a net gain on early debt retirements in 2017, and other favorable changes related to AFUDC. (See Note 5 – Other Income and Expenses of Notes to Consolidated Financial Statements.)
Provision (benefit) for income taxes changed favorably primarily due to a reduction in the federal statutory rate from 35 percent to 21 percent with the enactment of Tax Reform. The remeasurement of our existing deferred tax assets and liabilities at the reduced rate resulted in the recognition of a net income tax provision benefit of $1.923 billion. Adjustments within this provision benefit are considered provisional and are potentially subject to change in the future. See Note 7 – Provision (Benefit) for Income Taxes of Notes to Consolidated Financial Statements for a discussion of the effective tax rate compared to the federal statutory rate for both periods.
The unfavorable change in Net income (loss) attributable to noncontrolling interests is primarily due to the impact of decreased income allocated to us driven by the permanent waiver of IDRs and higher operating results at WPZ, partially offset by a decrease in the ownership of the noncontrolling interests. Both the permanent waiver of IDRs and the change in ownership are associated with the first-quarter 2017 Financial Repositioning (see Note 1 – General, Description of Business, and Basis of Presentation of Notes to Consolidated Financial Statements). In addition, improved results in our Gulfstar operations also contributed to the increase in Net income (loss) attributable to noncontrolling interests, partially offset by lower results for our Cardinal gathering system.
2016 vs. 2015
Service revenues increased slightly primarily due to expansion projects placed in service in 2015 and 2016, partially offset by a decrease in gathering, processing, and fractionation revenue primarily due to lower volumes in the Barnett Shale and Anadarko basin.
Product sales increased primarily due to higher olefin sales reflecting increased volumes at our former Geismar plant as a result of the plant operating at higher production levels in 2016, partially offset by a decrease from our other olefin operations associated with lower volumes and per-unit sales prices. Product sales also reflect higher marketing revenues associated with higher NGL and propylene prices and natural gas and crude oil volumes, partially offset by lower NGL volumes, and crude oil prices.
The decrease in Product costs includes lower olefin feedstock purchases and lower costs associated with other product sales, partially offset by higher marketing purchases primarily due to the same factors that increased marketing sales. The decline in olefin feedstock purchases is primarily associated with lower per-unit feedstock costs and volumes at our other olefin operations, partially offset by an increase in olefin feedstock purchases at our former Geismar plant reflecting increased volumes resulting from higher production levels in 2016.
Operating and maintenance expenses decreased primarily due to lower labor-related and outside service costs resulting from our first-quarter 2016 workforce reductions and cost containment efforts and lower costs associated with general maintenance activities in the Marcellus Shale, as well as the absence of ACMP transition-related costs recognized in 2015. These decreases are partially offset by $16 million of severance and related costs recognized in 2016 and higher pipeline testing and general maintenance costs at Transco.
Depreciation and amortization expenses increased primarily due to depreciation on new assets placed in service, including Transco pipeline projects, partially offset by lower depreciation related to Canadian operations sold in 2016.
SG&A decreased primarily due to lower merger and transition costs associated with the ACMP merger and lower labor-related costs resulting from our first-quarter 2016 workforce reductions and cost containment efforts. These decreases were partially offset by certain project development costs associated with the Canadian PDH facility that we began expensing in 2016, as well as $26 million of severance and related costs recognized in 2016 and $17 million of higher costs associated with our evaluation of strategic alternatives.
Impairment of goodwill decreased due to the absence of a 2015 impairment charge associated with certain goodwill. (See Note 16 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
Impairment of certain assets reflects 2016 impairments of our Canadian operations and certain Mid-Continent assets, and other assets. Impairments recognized in 2015 relate primarily to previously capitalized development costs and surplus equipment write-downs. (See Note 16 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
Insurance recoveries – Geismar Incident changed unfavorably reflecting the receipt of $126 million of insurance proceeds in the second quarter of 2015, as compared to the receipt of $7 million of proceeds in the fourth quarter of 2016.
The unfavorable change in Other (income) expense – net within Operating income (loss) includes a loss on the sale of our Canadian operations that were sold in September 2016, project development costs at Constitution as we discontinued capitalization of these costs in April 2016, and an unfavorable change in foreign currency exchange that primarily relates to losses incurred on foreign currency transactions and the remeasurement of the U.S. dollar-denominated current assets and liabilities within our former Canadian operations, partially offset by a $10 million gain on the sale of idle pipe in 2016.
Operating income (loss) changed favorably primarily due to the absence of a goodwill impairment in 2015, higher olefin margins related to the Geismar plant operating at higher production levels in 2016, lower costs related to the merger and integration of ACMP, and lower costs and expenses primarily associated with cost containment efforts. These favorable changes are partially offset by impairments and loss on sale of certain assets in 2016, a decrease in insurance proceeds received, expensed Canadian PDH facility project development costs, and higher depreciation expenses related to new projects placed in service.
Equity earnings (losses) changed favorably primarily due to a $30 million increase at Discovery driven by the completion of the Keathley Canyon Connector in the first quarter of 2015. Additionally, OPPL, Laurel Mountain, and DBJV improved $16 million, $11 million, and $10 million, respectively.
Impairment of equity-method investments reflects 2016 impairment charges associated with our Appalachia Midstream Investments, DBJV, Laurel Mountain, and Ranch Westex equity-method investments, while the 2015 impairment charges relate to our equity-method investments in Appalachia Midstream Investments, DBJV, UEOM, and Laurel Mountain. (See Note 5 – Investing Activities of Notes to Consolidated Financial Statements.)
Other investing income (loss) – net changed favorably due to a 2016 gain on the sale of an equity-method investment interest in a gathering system that was part of our Appalachia Midstream Investments and higher interest income associated with a receivable related to the sale of certain former Venezuela assets. (See Note 5 – Investing Activities of Notes to Consolidated Financial Statements.)
Interest expense increased due to higher Interest incurred of $99 million primarily attributable to new debt issuances in 2016 and 2015 and lower Interest capitalized of $36 million primarily related to construction projects that have been placed into service, partially offset by lower interest due to 2015 and 2016 debt retirements. (See Note 13 – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements.)
Other income (expense) – net below Operating income (loss) changed unfavorably primarily due to a decrease in AFUDC due to decreased spending on Constitution and the absence of a $14 million gain on early debt retirement in 2015.
Provision (benefit) for income taxes changed unfavorably primarily due to a decrease in pre-tax loss in 2016. See Note 7 – Provision (Benefit) for Income Taxes of Notes to Consolidated Financial Statements for a discussion of the effective tax rates compared to the federal statutory rate for both years.
The unfavorable change in Net income (loss) attributable to noncontrolling interests is primarily due to higher operating results at WPZ, the impact of decreased income allocated to the WPZ general partner driven by the impact of reduced incentive distributions from WPZ, and the absence of the accelerated amortization of a beneficial conversion feature from the first quarter of 2015. These changes are partially offset by a favorable change primarily related to our partners’ share of Constitution project development costs in 2016.
Year-Over-Year Operating Results – Segments
We evaluate segment operating performance based upon Modified EBITDA. Note 18 – Segment Disclosures of Notes to Consolidated Financial Statements includes a reconciliation of this non-GAAP measure to Net income (loss). Management uses Modified EBITDA because it is an accepted financial indicator used by investors to compare company performance. In addition, management believes that this measure provides investors an enhanced perspective of the operating performance of our assets. Modified EBITDA should not be considered in isolation or as a substitute for a measure of performance prepared in accordance with GAAP.
Williams Partners
| Years Ended December 31, | |||||||||||
| 2017 | 2016 | 2015 | |||||||||
| (Millions) | |||||||||||
| Service revenues | $ | 5,292 | $ | 5,173 | $ | 5,135 | |||||
| Product sales | 2,718 | 2,318 | 2,196 | ||||||||
| Segment revenues | 8,010 | 7,491 | 7,331 | ||||||||
| Product costs | (2,300 | ) | (1,728 | ) | (1,779 | ) | |||||
| Other segment costs and expenses | (2,124 | ) | (2,203 | ) | (2,229 | ) | |||||
| Net insurance recoveries – Geismar Incident | 9 | 7 | 126 | ||||||||
| Gain on sale of Geismar Interest | 1,095 | — | — | ||||||||
| Impairment of certain assets | (1,156 | ) | (457 | ) | (145 | ) | |||||
| Regulatory charges resulting from Tax Reform | (713 | ) | — | — | |||||||
| Proportional Modified EBITDA of equity-method investments | 795 | 754 | 699 | ||||||||
| Williams Partners Modified EBITDA | $ | 3,616 | $ | 3,864 | $ | 4,003 | |||||
| NGL margin | $ | 203 | $ | 169 | $ | 159 | |||||
| Olefin margin | 126 | 337 | 226 |
2017 vs. 2016
Modified EBITDA decreased primarily due to $713 million of regulatory charges associated with the impact of Tax Reform for Transco and Northwest Pipeline, impairments of certain gathering operations in 2017 and lower olefin margins due to the sale of our Gulf Olefins operations early in the third quarter of 2017 and $35 million of expense in 2017 related to a settlement charge from a pension early payout program (see Note 9 – Employee Benefit Plans of Notes to Consolidated Financial Statements). These decreases are partially offset by the $1.095 billion gain on the sale of our Geismar Interest in third-quarter 2017, the absence of impairments of our former Canadian operations and certain gathering assets in the Mid-Continent region in 2016, the absence of a loss on the sale of our former Canadian operations in third-quarter 2016, higher service revenues, lower segment costs and expenses, and higher Proportional Modified EBITDA of equity-method investments.
Service revenues increased primarily due to:
| • | Transco’s natural gas transportation fee revenues increased $135 million primarily due to a $150 million increase associated with expansion projects placed in-service in 2016 and 2017, partially offset by lower volume-based transportation services revenues; |
| • | Higher eastern Gulf Coast region revenue of $103 million associated primarily with higher volumes, including the impact of new volumes at Gulfstar One related to the Gunflint expansion placed in-service in the third quarter of 2016, the absence of the temporary shut-down and subsequent ramp-up of Gulfstar One in the second and third quarters of 2016 to tie-in Gunflint and the absence of producers’ operational issues in the Tubular Bells field during the first quarter of 2016. This increase is partially offset by lower volumes as a result of a temporary increase in 2016 due to disrupted operations of a competitor; |
| • | A $39 million increase related to the amortization of deferred revenue associated with the up-front cash payment received in conjunction with the fourth quarter 2016 Barnett Shale contract restructuring; |
| • | A $15 million increase in Transco’s storage revenue primarily reflecting the absence of an accrual for potential refunds associated with a ruling received in certain rate case litigation in 2016; |
| • | In the Northeast region, a slight increase reflecting a $38 million increase in gathering fee revenue at Susquehanna Supply Hub driven by 11 percent higher gathered volumes reflecting increased customer production and a $23 million increase in fee revenue at Ohio Valley Midstream reflecting the absence of shut-in volumes from the first half of 2016, as well as new production coming online. The increases were substantially offset by a $56 million decrease in the Utica gathering system primarily due to 14 percent lower gathered volumes driven by natural declines in the wet gas areas which are partially offset by higher volumes from new development in the dry gas areas; |
| • | A $79 million decrease in the West region related to net lower gathering rates in the Barnett Shale area primarily due to the fourth quarter 2016 contract restructuring, along with lower rates recognized in the Niobrara, Eagle Ford Shale, and Haynesville Shale regions. These rate decreases are offset by higher commodity-based fee revenues in the Piceance area primarily due to higher per-unit NGL margins and higher rates in the Wamsutter area as a result of renegotiated rates in conjunction with infrastructure expansions. Rates recognized in the Niobrara region represent a portion of the total contractual rate that is received, with the difference reflected as deferred revenue; |
| • | A $34 million decrease driven by lower volumes in the West region primarily as a result of natural declines and more extreme weather conditions in the Rocky Mountains in the first quarter of 2017, partially offset by higher volumes in the Haynesville Shale region as a result of increased drilling in certain areas; |
| • | A $36 million decrease due to the absence of revenue generated by our former Canadian operations that were sold in September 2016; |
| • | A $15 million decrease in western Gulf Coast region fee revenues due to lower volumes primarily associated with producer maintenance. |
Product sales increased primarily due to:
| • | A $735 million increase in marketing revenues primarily due to significantly higher prices across all products and higher NGL volumes (substantially offset in marketing purchases); |
| • | A $32 million increase in revenues from our equity NGLs including a $102 million increase driven primarily by higher non-ethane prices, partially offset by a $36 million decrease due to the absence of NGL production revenues associated with our former Canadian operations and a $34 million decrease primarily related to lower non-ethane volumes at our domestic plants driven by the absence of temporary volumes in 2016 related to disrupted operations of a competitor, severe winter conditions in the first quarter of 2017, and natural declines; |
| • | A $12 million increase in system management gas sales from Transco. System management gas sales are offset in Product costs and, therefore, have no impact on Modified EBITDA; |
| • | A $380 million decrease in olefin sales primarily due to a $343 million decrease reflecting the absence of third- and fourth-quarter sales of our Gulf Olefins operations, a $29 million decrease due to the sale of the Canadian operations in 2016, and a $16 million decrease at our Geismar plant in the first half of 2017 primarily due to lower volumes associated with the electrical outage in second-quarter 2017, as well as planned maintenance downtime in first-quarter 2017. These items were partially offset by $8 million higher sales at the RGP Splitter in the first half 2017 primarily due to higher propylene prices. |
Product costs increased primarily due to:
| • | A $725 million increase in marketing purchases primarily due to the same factors that increased marketing sales (more than offset in marketing revenues). The increase in marketing costs does not reflect the intercompany costs associated with certain gathering and processing services performed by an affiliate; |
| • | A $12 million increase in system management gas costs (offset in Product sales); |
| • | A $166 million decrease in olefin feedstock purchases primarily due to the absence of $163 million in feedstock purchases in the second half of 2017 reflecting the sale of the Gulf Olefins operations, as well as the absence of $9 million in costs associated with our former Canadian operations, partially offset by $6 million higher feedstock costs in the first half of 2017. |
| • | A $2 million decrease in costs from our equity NGLs including a $35 million increase driven primarily by higher gas prices, partially offset by a $24 million decrease due to the absence of NGL production revenues associated with our former Canadian operations and a $13 million decrease primarily related to lower volumes at our domestic plants driven by severe winter conditions in the first quarter of 2017, and the absence of temporary volumes in 2016 related to disrupted operations of a competitor and natural declines. |
The favorable change in Other segment costs and expenses includes a decrease in labor-related expenses primarily due to our first quarter 2016 workforce reduction and ongoing cost containment efforts; the absence of $117 million of operating and other expenses associated with our Gulf Olefins and Canadian operations; and the absence of a $34 million loss on the sale of our former Canadian operations. Additional favorable changes in Other segment costs and expenses include a $27 million net gain associated with early debt retirement; a $15 million gain related to favorable contract settlements and terminations; a favorable change in equity AFUDC, primarily associated with an increase in Transco’s capital spending, which is partially offset by a decrease in capital spending at Constitution; and a $12 million gain on the sale of the RGP Splitter. These decreases are partially offset by $35 million of expense in 2017 related to a settlement charge from a pension early payout program (see Note 9 – Employee Benefit Plans of Notes to Consolidated Financial Statements), higher various maintenance expenses, an increase in pipeline integrity testing on Transco, and higher Geismar selling expenses and repairs related to a Geismar electrical outage.
Gain on sale of Geismar Interest reflects the gain recognized on the sale of our Geismar Interest in July 2017. (See Note 2 - Acquisitions and Divestitures of Notes to Consolidated Financial Statements.)
Impairment of certain assets increased primarily due to a $1.032 billion impairment of certain gathering operations primarily in the Mid-Continent region and a $115 million impairment of certain gathering operations in the Marcellus South region, partially offset by the absence of a $341 million impairment of our former Canadian operations and a $100 million impairment of certain Mid-Continent gathering assets and impairments or write-downs of other certain assets that may no longer be in use or are surplus in nature during 2016. (See Note 16 - Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
Regulatory charges resulting from Tax Reform reflects $713 million of regulatory charges associated with the impact of Tax Reform at Transco and Northwest Pipeline with $674 million presented as Regulatory charges resulting from Tax Reform and $39 million included within Other income (expense) – net below Operating income (loss) in the Consolidated Statement of Operations.
The increase in Proportional Modified EBITDA of equity-method investments includes a $100 million increase at Appalachia Midstream Investments reflecting our increased ownership acquired late in the first quarter of 2017, higher gathering volumes reflecting the absence of shut-in volumes from 2016 and increased customer production, and a $20 million increase at Aux Sable due to increased customer production. These increases are partially offset by a $34 million decrease at UEOM reflecting lower processing volumes from the wet gas areas of the Utica gathering system, the divestiture of our interests in DBJV and Ranch Westex JV LLC late in the first quarter of 2017, a $12 million decrease from Discovery primarily attributable to lower fee revenue driven by production issues at certain wells and higher turbine maintenance expenses.
2016 vs. 2015
Modified EBITDA decreased primarily due to higher impairments, lower insurance recoveries associated with the Geismar Incident, and loss on sale associated with our Canadian operations. These decreases were partially offset by higher olefin margins related to the Geismar plant operating at higher production levels in 2016, lower segment costs and expenses, and higher earnings related to our equity-method investments, including the completion of the Keathley Canyon Connector at Discovery in the first quarter of 2015. Additionally, higher marketing margins, higher service revenues related to projects placed in service, and higher NGL margins improved Modified EBITDA.
The increase in Service revenues is primarily due to a $79 million increase in Transco’s natural gas transportation fee revenues primarily associated with expansion projects placed in service in 2015 and 2016 and a $31 million transportation and fractionation revenue increase associated with Williams’ Horizon liquids extraction plant in Canada. The Canadian operations were sold in late September 2016. These increases were partially offset by a decrease in gathering, processing, and fractionation revenue primarily due to lower volumes primarily in the Barnett Shale and Anadarko basin and a $15 million decrease in Transco’s storage revenue related to potential refunds associated with a ruling received in certain rate case litigation in 2016.
Product sales increased primarily due to:
| • | A $94 million increase in olefin sales comprised of a $170 million increase from the Geismar plant that returned to service in late March 2015, partially offset by a $76 million decrease from our other former olefin operations. The increase at Geismar includes $153 million associated with increased volumes as a result of the plant operating at higher production levels in 2016 than when production resumed in March 2015 following the Geismar Incident and $17 million primarily associated with higher ethylene per-unit sales prices. The decrease in other olefin sales includes a $14 million reduction due to the absence of our former Canadian operations in the fourth quarter of 2016, as well as lower volumes and lower per-unit sales prices within our other olefin operations; |
| • | A $70 million increase in marketing revenues primarily due to higher NGL and propylene prices and natural gas and crude oil volumes, partially offset by lower NGL volumes and crude oil prices (partially offset in marketing purchases); |
| • | A $6 million increase in revenues from our equity NGLs due to a $10 million increase associated with higher volumes, partially offset by a $4 million decrease associated with lower NGL prices; |
| • | A $39 million decrease in system management gas sales from Transco. System management gas sales are offset in Product costs and, therefore, have no impact on Modified EBITDA. |
The decrease in Product costs includes:
| • | A $39 million decrease in system management gas costs (offset in Product sales); |
| • | A $17 million decrease in olefin feedstock purchases is primarily comprised of $78 million in lower purchases at our former other olefins operations, partially offset by $61 million of higher purchases due primarily to increased volumes at the Geismar plant resulting from higher productions levels. The lower costs at our former other olefin operations are comprised of $54 million in lower per-unit feedstock costs and $24 million in primarily lower propylene volumes; |
| • | A $4 million decrease in natural gas purchases associated with the production of equity NGLs reflecting a decrease of $13 million due to lower natural gas prices, partially offset by a $9 million increase associated with higher volumes; |
| • | Lower costs associated with various other products, primarily condensate; |
| • | A $22 million increase in marketing purchases primarily due to the same factors that increased marketing sales (more than offset in marketing revenues). The increase in marketing costs does not reflect the intercompany costs associated with certain gathering and processing services performed by an affiliate. |
The decrease in Other segment costs and expenses is primarily due to lower operating costs and general and administrative expenses reflecting decreases in primarily labor-related and outside services costs resulting from our first-quarter 2016 workforce reductions and ongoing cost containment efforts and lower costs associated with general maintenance activities in the Marcellus Shale, as well as $43 million of lower ACMP Merger and transition-related expenses. Other items partially offsetting these decreases are as follows:
| • | $37 million increase for severance and related costs associated with workforce reductions incurred in the first quarter of 2016 and the organizational realignment in the fourth quarter of 2016; |
| • | $34 million increase related to the 2016 loss on sale of our Canadian operations; |
| • | $28 million higher project development costs at Constitution as we discontinued capitalization of development costs related to this project beginning in April 2016; |
| • | $22 million higher contract services for pipeline testing and general maintenance at Transco; |
| • | $20 million unfavorable change in foreign currency exchange that primarily relates to losses incurred on foreign currency transactions and the remeasurement of the U.S. dollar-denominated current assets and liabilities within our former Canadian operations; |
| • | $19 million unfavorable change in AFUDC associated with a decrease in spending on Constitution; |
| • | The absence of a $14 million gain recognized in second-quarter 2015 resulting from the early retirement of certain debt. |
Net insurance recoveries – Geismar Incident decreased reflecting $7 million of insurance proceeds received in 2016 compared to $126 million received in 2015.
Impairment of certain assets increased primarily due to 2016 impairments of $341 million associated with our Canadian operations and $63 million associated with certain Mid-Continent gathering assets as well as impairments or write-downs of other certain assets that may no longer be in use or are surplus in nature, partially offset by the absence of 2015 impairments of $94 million associated with previously capitalized project development costs for a gas processing plant and $20 million associated with certain surplus equipment within our Ohio Valley Midstream business. (See Note 16 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
The increase in Proportional Modified EBITDA of equity-method investments is primarily due to a $30 million increase from Discovery primarily associated with higher fee revenues attributable to the completion of the Keathley Canyon Connector in the first quarter of 2015. Additionally, Caiman II contributed a $20 million increase resulting from higher volumes due to assets placed into service in 2015, OPPL contributed a $16 million increase primarily due to higher transportation volumes and lower expenses, and UEOM contributed an $11 million increase primarily associated with an increase in our ownership percentage. These increases were partially offset by a $29 million decrease from Appalachia Midstream Investments primarily due to lower fee revenues driven by lower rates, partially offset by lower impairments and higher volumes.
Other
| Years Ended December 31, | |||||||||||
| 2017 | 2016 | 2015 | |||||||||
| (Millions) | |||||||||||
| Other Modified EBITDA | $ | (150 | ) | $ | (542 | ) | $ | (112 | ) |
2017 vs. 2016
The favorable change in Modified EBITDA is primarily due to:
| • | The absence of the $406 million 2016 impairment of our Canadian operations, partially offset by the $23 million impairment of an olefins pipeline project in the Gulf Coast region in the second quarter of 2017 and the $68 million impairment of a certain NGL pipeline asset in the third quarter of 2017 (see Note 16 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements); |
| • | The absence of $61 million of certain project development costs associated with the Canadian PDH facility that we expensed in 2016; |
| • | A $31 million favorable change in the loss on the sale of our Canadian operations in September 2016; |
| • | The absence of $32 million of transportation and fractionation fees incurred in 2016 related to the Redwater fractionation facility, which was included in the sale of our Canadian operations in September 2016; |
| • | A $38 million decrease in costs related to our evaluation of strategic alternatives; |
| • | A $29 million increase in income associated with an increase in a regulatory asset primarily driven by our increased ownership in WPZ. |
These favorable changes are partially offset by:
| • | A $63 million charge reducing regulatory assets related to deferred taxes on AFUDC resulting from Tax Reform (see Note 6 – Other Income and Expenses of Notes to Consolidated Financial Statements); |
| • | A $35 million settlement charge expense related to the program to pay out certain deferred vested pension benefits of employees associated with former operations. (See Note 9 – Employee Benefit Plans of Notes to Consolidated Financial Statements); |
| • | A reduction in revenues associated with an NGL pipeline near the Houston Ship Channel region; |
| • | The absence of a $10 million gain on the sale of unused pipe in 2016. |
2016 vs. 2015
The unfavorable change in Modified EBITDA is primarily due to:
| • | The impairment and loss on sale of our Canadian operations totaling $438 million in 2016; |
| • | An increase of $61 million of certain project development costs associated with the Canadian PDH facility that we began expensing in 2016; |
| • | A $17 million increase in costs related to our evaluation of strategic alternatives. |
These unfavorable changes are partially offset by:
| • | A $10 million gain on the sale of unused pipe in 2016; |
| • | A $31 million decrease in ACMP merger and transition related costs; |
| • | The absence of a $64 million write-off of previously capitalized project development costs for an olefins pipeline project in 2015. |
Management’s Discussion and Analysis of Financial Condition and Liquidity
Overview
In 2017, we exceeded our target for asset sales, significantly improved our balance sheet to provide ample available liquidity, and continued to focus on growth in our businesses by identifying, contracting, permitting, and constructing attractive expansion projects. Examples of this activity included:
| • | Sale of our Geismar Interest (see Note 2 – Acquisitions and Divestitures of Notes to Consolidated Financial Statements). |
| • | Repayment of WPZ’s $850 million variable interest rate term loan that was due December 2018, and early retirement of WPZ’s $750 million of 6.125 percent senior unsecured notes that were due in 2022; |
| • | Repayment of WPZ’s $1.4 billion of 4.875 percent senior unsecured notes that were due in 2023 with proceeds from the issuance of WPZ’s $1.45 billion of 3.75 percent senior unsecured notes due in 2027; |
| • | Extension to 2021 for the maturity dates of our long-term credit facility and WPZ’s long-term credit facility; |
| • | Expansion of WPZ’s interstate natural gas pipeline system through completion of 2017 strategic projects (Gulf Trace, Hillabee Phase 1, Dalton, New York Bay, and Virginia Southside II) to meet the demand of growth markets. |
Outlook
Fee-based businesses are a significant component of our portfolio and serve to reduce the influence of commodity price fluctuations on our cash flows. We expect to benefit as continued growth in demand for low-cost natural gas is driven by increases in LNG exports, industrial demand, and power generation.
As previously discussed in Company Outlook, our consolidated growth capital and investment expenditures in 2018 are expected to be approximately $2.7 billion. Approximately $1.7 billion of our growth capital funding needs include Transco expansions and other interstate pipeline growth projects, most of which are fully contracted with firm transportation agreements. The remaining growth capital spending in 2018 primarily reflects investment in gathering and processing systems in the Northeast region limited primarily to known new producer volumes, including volumes that support Transco expansion projects including our Atlantic Sunrise project. In addition to growth capital and investment expenditures, we also remain committed to projects that maintain our assets for safe and reliable operations, as well as projects that meet legal, regulatory, and/or contractual commitments. WPZ intends to fund their planned 2018 growth capital with retained cash flow and debt. We retain the flexibility to adjust planned levels of growth capital and investment expenditures in response to changes in economic conditions or business opportunities.
Liquidity
Based on our forecasted levels of cash flow from operations and other sources of liquidity, we expect to have sufficient liquidity to manage our businesses in 2018. WPZ expects to be self-funding and maintain separate bank accounts and credit facilities, including its commercial paper program. Our potential material internal and external sources and uses of consolidated liquidity for 2018 are as follows:
| Applicable To: | |||||
| WPZ | WMB | ||||
| Sources: | |||||
| Cash and cash equivalents on hand | ü | ü | |||
| Cash generated from operations | ü | ||||
| Distributions from investment in WPZ | ü | ||||
| Distributions from equity-method investees | ü | ||||
| Utilization of credit facilities and/or commercial paper program | ü | ü | |||
| Cash proceeds from issuance of debt and/or equity securities | ü | ü | |||
| Proceeds from asset monetizations | ü | ||||
| Uses: | |||||
| Working capital requirements | ü | ü | |||
| Capital and investment expenditures | ü | ||||
| Investment in WPZ | ü | ||||
| Quarterly distributions to unitholders | ü | ||||
| Quarterly dividends to shareholders | ü | ||||
| Debt service payments, including payments of long-term debt | ü | ü |
Potential risks associated with our planned levels of liquidity discussed above include those previously discussed in Company Outlook.
As of December 31, 2017, we had a working capital deficit of $467 million. Our available liquidity is as follows:
| December 31, 2017 | ||||||||||||
| Available Liquidity | WPZ | WMB | Total | |||||||||
| (Millions) | ||||||||||||
| Cash and cash equivalents | $ | 881 | $ | 18 | $ | 899 | ||||||
| Capacity available under our $1.5 billion credit facility (1) | 1,230 | 1,230 | ||||||||||
| Capacity available to WPZ under its $3.5 billion credit facility, less amounts outstanding under its $3 billion commercial paper program (2) | 3,500 | 3,500 | ||||||||||
| $ | 4,381 | $ | 1,248 | $ | 5,629 |
| (1) | The highest amount outstanding under our credit facility during 2017 was $805 million. At December 31, 2017, we were in compliance with the financial covenants associated with this credit facility. See Note 13 – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements for additional information on our credit facility. Borrowing capacity available under this facility as of February 20, 2018, was $1.5 billion. |
| (2) | In managing our available liquidity, we do not expect a maximum outstanding amount in excess of the capacity of WPZ’s credit facility inclusive of any outstanding amounts under its commercial paper program. As of December 31, 2017, no Commercial paper was outstanding under WPZ’s commercial paper program. The highest amount outstanding under WPZ’s commercial paper program and credit facility during 2017 was $178 million. At December 31, 2017, WPZ was in compliance with the financial covenants associated with this credit facility. See Note 13 – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements for additional information on WPZ’s credit facility and WPZ’s commercial paper program. Borrowing capacity available under WPZ’s $3.5 billion credit facility as of February 20, 2018, was $3.5 billion. |
As described in Note 13 – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements, we have determined that we have net assets that are technically considered restricted in accordance with Rule 4-08(e) of Regulation S-X of the Securities and Exchange Commission in excess of 25 percent of our consolidated net assets. We do not expect this determination will impact our ability to pay dividends or meet future obligations as the terms of WPZ’s partnership agreement require it to make quarterly distributions of all available cash, as defined, to its unitholders.
Dividends
As part of the Financial Repositioning, we increased our regular quarterly cash dividend by 50 percent from the previous quarterly dividend of $0.20 per share paid in December 2016, to $0.30 per share for the dividends paid in each quarter of 2017.
Registrations
In September 2016, WPZ filed a registration statement for its distribution reinvestment program.
In May 2015, we filed a shelf registration statement, as a well-known seasoned issuer.
In February 2015, WPZ filed a shelf registration statement, as a well-known seasoned issuer, registering common units representing limited partner interests and debt securities. Also in February 2015, WPZ filed a shelf registration statement for the offer and sale from time to time of common units representing limited partner interests in WPZ having an aggregate offering price of up to $1 billion. These sales are to be made over a period of time and from time to time in transactions at prices which are market prices prevailing at the time of sale, prices related to market price, or at negotiated prices. Such sales are to be made pursuant to an equity distribution agreement between WPZ and certain banks who may act as sales agents or purchase for their own accounts as principals. During 2016 and 2015, WPZ received net proceeds of approximately $115 million and approximately $59 million, respectively, from equity issued under this registration; there was no activity during 2017.
Distributions from Equity-Method Investees
The organizational documents of entities in which we have an equity-method investment generally require distribution of their available cash to their members on a quarterly basis. In each case, available cash is reduced, in part, by reserves appropriate for operating their respective businesses. (See Note 5 – Investing Activities of Notes to Consolidated Financial Statements for our more significant equity-method investees.)
Credit Ratings
Our ability to borrow money is impacted by our credit ratings and the credit ratings of WPZ. The current ratings are as follows:
| Rating Agency | Outlook | Senior Unsecured Debt Rating | Corporate Credit Rating | ||||
| WMB: | S&P Global Ratings | Stable | BB+ | BB+ | |||
| Moody’s Investors Service | Positive | Ba2 | N/A | ||||
| Fitch Ratings | Stable | BB+ | N/A | ||||
| WPZ: | S&P Global Ratings | Stable | BBB | BBB | |||
| Moody’s Investors Service | Positive | Baa3 | N/A | ||||
| Fitch Ratings | Positive | BBB- | N/A |
During March 2017, S&P Global Ratings upgraded its rating for both WMB and WPZ. These credit ratings are included for informational purposes and are not recommendations to buy, sell, or hold our or WPZ’s securities, and each rating should be evaluated independently of any other rating. No assurance can be given that the credit rating agencies will continue to assign us or WPZ the ratings shown above even if we or WPZ meet or exceed their current criteria. A downgrade of our credit ratings or the credit ratings of WPZ might increase our future cost of borrowing and would require us to provide additional collateral to third parties, negatively impacting our available liquidity.
Sources (Uses) of Cash
The following table summarizes the sources (uses) of cash and cash equivalents for each of the periods presented (see Notes to Consolidated Financial Statements for the Notes referenced in the table):
| Cash Flow | Years Ended December 31, | ||||||||||||
| Category | 2017 | 2016 | 2015 | ||||||||||
| (Millions) | |||||||||||||
| Sources of cash and cash equivalents: | |||||||||||||
| Operating activities – net | Operating | $ | 2,556 | $ | 3,680 | $ | 2,708 | ||||||
| Proceeds from equity offerings | Financing | 2,131 | 123 | 86 | |||||||||
| Proceeds from sale of businesses, net of cash divested (see Note 2) | Investing | 2,067 | 1,020 | — | |||||||||
| Proceeds from long-term debt (see Note 13) | Financing | 1,698 | 998 | 3,842 | |||||||||
| Proceeds from our credit-facility borrowings | Financing | 1,635 | 2,280 | 2,097 | |||||||||
| Distributions from unconsolidated affiliates in excess of cumulative earnings | Investing | 529 | 472 | 404 | |||||||||
| Contributions in aid of construction | Investing | 426 | 218 | 87 | |||||||||
| Proceeds from dispositions of equity-method investments (see Note 5) | Investing | 200 | 34 | — | |||||||||
| Contributions from noncontrolling interests | Financing | 17 | 29 | 111 | |||||||||
| Proceeds from WPZ’s credit-facility borrowings | Financing | — | 3,250 | 3,832 | |||||||||
| Special distribution from Gulfstream (see Note 5) | Financing | — | — | 396 | |||||||||
| Uses of cash and cash equivalents: | |||||||||||||
| Payments of long-term debt (see Note 13) | Financing | (3,785 | ) | (375 | ) | (1,533 | ) | ||||||
| Capital expenditures | Investing | (2,399 | ) | (2,051 | ) | (3,167 | ) | ||||||
| Payments on our credit-facility borrowings | Financing | (2,140 | ) | (2,155 | ) | (1,817 | ) | ||||||
| Dividends paid | Financing | (992 | ) | (1,261 | ) | (1,836 | ) | ||||||
| Dividends and distributions paid to noncontrolling interests | Financing | (822 | ) | (940 | ) | (942 | ) | ||||||
| Purchases of and contributions to equity-method investments | Investing | (132 | ) | (177 | ) | (595 | ) | ||||||
| Payments of WPZ’s commercial paper – net | Financing | (93 | ) | (409 | ) | (306 | ) | ||||||
| Payments on WPZ’s credit-facility borrowings | Financing | — | (4,560 | ) | (3,162 | ) | |||||||
| Contribution to Gulfstream for repayment of debt (see Note 5) | Financing | — | (148 | ) | (248 | ) | |||||||
| Purchases of businesses, net of cash acquired | Investing | — | — | (112 | ) | ||||||||
| Other sources / (uses) – net | Financing and Investing | (167 | ) | 42 | 15 | ||||||||
| Increase (decrease) in cash and cash equivalents | $ | 729 | $ | 70 | $ | (140 | ) |
Operating activities
The factors that determine operating activities are largely the same as those that affect Net income (loss), with the exception of noncash items such as Depreciation and amortization, Provision (benefit) for deferred income taxes, Net (gain) loss on disposition of equity-method investments, Impairment of goodwill, Impairment of equity-method investments, Impairment of and net (gain) loss on sale of assets and businesses, Gain on sale of Geismar Interest, and Regulatory charges resulting from Tax Reform.
Our Net cash provided (used) by operating activities in 2017 decreased from 2016 primarily due to the absence in 2017 of receipts from 2016 contract restructurings, partially offset by higher operating income in 2017.
Our Net cash provided (used) by operating activities in 2016 increased from 2015 primarily due to the impact of net favorable changes in operating working capital and receipts from contract restructurings.
Off-Balance Sheet Arrangements and Guarantees of Debt or Other Commitments
We have various other guarantees and commitments which are disclosed in Note 3 – Variable Interest Entities, Note 10 – Property, Plant, and Equipment, Note 13 – Debt, Banking Arrangements, and Leases, Note 16 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk, and Note 17 – Contingent Liabilities and Commitments of Notes to Consolidated Financial Statements. We do not believe these guarantees and commitments or the possible fulfillment of them will prevent us from meeting our liquidity needs.
Contractual Obligations
The table below summarizes the maturity dates of our contractual obligations at December 31, 2017:
| 2018 | 2019 - 2020 | 2021 - 2022 | Thereafter | Total | |||||||||||||||
| (Millions) | |||||||||||||||||||
| Long-term debt: (1) | |||||||||||||||||||
| Principal | $ | 502 | $ | 2,156 | $ | 3,146 | $ | 15,277 | $ | 21,081 | |||||||||
| Interest | 1,049 | 1,995 | 1,743 | 7,795 | 12,582 | ||||||||||||||
| Operating leases | 44 | 74 | 62 | 137 | 317 | ||||||||||||||
| Purchase obligations (2) | 1,171 | 914 | 632 | 277 | 2,994 | ||||||||||||||
| Other obligations (3)(4) | 1 | 2 | 1 | 1 | 5 | ||||||||||||||
| Total | $ | 2,767 | $ | 5,141 | $ | 5,584 | $ | 23,487 | $ | 36,979 |
| (1) | Includes the borrowings outstanding under credit facilities, but does not include any related variable-rate interest payments. |
| (2) | Includes approximately $348 million in open property, plant, and equipment purchase orders. Includes an estimated $314 million long-term ethane purchase obligation with index-based pricing terms that is reflected in this table at December 31, 2017 prices. This obligation is part of an overall exchange agreement whereby volumes we transport on OPPL are sold at a third-party fractionator near Conway, Kansas, and we are subsequently obligated to purchase ethane volumes at Mont Belvieu. The purchased ethane volumes may be utilized or sold at comparable prices in the Mont Belvieu market. Includes an estimated $454 million long-term ethane purchase obligation with index-based pricing terms that primarily supplies third parties at their plants and is valued in this table at a price calculated using December 31, 2017 prices. Any excess purchased volumes may be sold at comparable market prices. Includes an estimated $765 million long-term mixed NGLs purchase obligation with index-based pricing terms that is reflected in this table at December 31, 2017 prices. Includes an estimated $278 million long-term ethane purchase obligation with index-based pricing terms that primarily supplies a third party for consumption at their plant and is reflected in this table at a price calculated using December 31, 2017 prices. Any excess purchased volumes may be sold at comparable market prices. In addition, we have not included certain natural gas life-of-lease contracts for which the future volumes are indeterminable. We have not included commitments, beyond purchase orders, for the acquisition or construction of property, plant, and equipment or expected contributions to our jointly owned investments. (See Company Outlook — Expansion Projects.) |
| (3) | Does not include estimated contributions to our pension and other postretirement benefit plans. We made contributions to our pension and other postretirement benefit plans of $90 million in 2017 and $72 million in 2016. In 2018, we expect to contribute approximately $91 million to these plans (see Note 9 – Employee Benefit Plans of Notes to Consolidated Financial Statements). Tax-qualified pension plans are required to meet minimum contribution requirements. In the past, we have contributed amounts to our tax-qualified pension plans in excess of the minimum required contribution. These excess amounts can be used to offset future minimum contribution requirements. During 2017, we contributed $80 million to our tax-qualified pension plans. In addition to these contributions, a portion of the excess contributions was used to meet the minimum contribution requirements. During 2018, we expect to contribute approximately $80 million to our tax-qualified pension plans and use excess amounts to satisfy minimum contribution requirements, if needed. Additionally, estimated future minimum funding requirements may vary significantly from historical requirements if actual results differ significantly from estimated results for assumptions such as returns on plan assets, interest rates, retirement rates, mortality, and other significant assumptions or by changes to current legislation and regulations. |
| (4) | We have not included income tax liabilities in the table above. See Note 7 – Provision (Benefit) for Income Taxes of Notes to Consolidated Financial Statements for a discussion of income taxes, including our contingent tax liability reserves. |
Effects of Inflation
Our operations have historically not been materially affected by inflation. Approximately 43 percent of our gross property, plant, and equipment is comprised of our interstate natural gas pipeline assets. They are subject to regulation, which limits recovery to historical cost. While amounts in excess of historical cost are not recoverable under current FERC practices, we anticipate being allowed to recover and earn a return based on increased actual cost incurred to replace existing assets. Cost-based regulations, along with competition and other market factors, may limit our ability to recover such increased costs. For our gathering and processing assets, operating costs are influenced to a greater extent by both competition for specialized services and specific price changes in crude oil and natural gas and related commodities than by changes in general inflation. Crude oil, natural gas, and NGL prices are particularly sensitive to the market perceptions concerning the supply and demand balance in the near future, as well as general economic conditions. However, our exposure to certain of these price changes is reduced through the fee-based nature of certain of our services and the use of hedging instruments.
Environmental
We are a participant in certain environmental activities in various stages including assessment studies, cleanup operations, and/or remedial processes at certain sites, some of which we currently do not own (see Note 17 – Contingent Liabilities and Commitments of Notes to Consolidated Financial Statements). We are monitoring these sites in a coordinated effort with other potentially responsible parties, the EPA, or other governmental authorities. We are jointly and severally liable along with unrelated third parties in some of these activities and solely responsible in others. Current estimates of the most likely costs of such activities are approximately $38 million, all of which are included in Accrued liabilities and Regulatory liabilities, deferred income, and other in the Consolidated Balance Sheet at December 31, 2017. We will seek recovery of the accrued costs related to remediation activities by our interstate gas pipelines totaling approximately $7 million through future natural gas transmission rates. The remainder of these costs will be funded from operations. During 2017, we paid approximately $6 million for cleanup and/or remediation and monitoring activities. We expect to pay approximately $10 million in 2018 for these activities. Estimates of the most likely costs of cleanup are generally based on completed assessment studies, preliminary results of studies, or our experience with other similar cleanup operations. At December 31, 2017, certain assessment studies were still in process for which the ultimate outcome may yield different estimates of most likely costs. Therefore, the actual costs incurred will depend on the final amount, type, and extent of contamination discovered at these sites, the final cleanup standards mandated by the EPA or other governmental authorities, and other factors.
The EPA and various state regulatory agencies routinely promulgate and propose new rules, and issue updated guidance to existing rules. More recent rules and rulemakings include, but are not limited to, rules for reciprocating internal combustion engine maximum achievable control technology, air quality standards for one hour nitrogen dioxide emissions, and volatile organic compound and methane new source performance standards impacting design and operation of storage vessels, pressure valves, and compressors. On October 1, 2015, the EPA issued its rule regarding National Ambient Air Quality Standards for ground-level ozone, setting a stricter standard of 70 parts per billion. We are monitoring the rule's implementation as the reduction will trigger additional federal and state regulatory actions that may impact our operations. Implementation of the regulations is expected to result in impacts to our operations and increase the cost of additions to Property, plant, and equipment – net in the Consolidated Balance Sheet for both new and existing facilities in affected areas. We are unable to reasonably estimate the cost of additions that may be required to meet the regulations at this time due to uncertainty created by various legal challenges to these regulations and the need for further specific regulatory guidance.
Our interstate natural gas pipelines consider prudently incurred environmental assessment and remediation costs and the costs associated with compliance with environmental standards to be recoverable through rates.
Previous: Item 6. Selected Financial Data · Next: Item 7A. Quantitative and Qualitative Disclosures About Market Risk