 filings.tools
Williams Companies (WMB) 10-K risk factor changes: FY2018 vs FY2017
The 2018-12-31 10-K against the 2017-12-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A49 rewritten22 added57 removed440 unchanged
All filing items1,395 rewritten1,182 added989 removed3,088 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 1,182 added, 989 removed, 1,395 rewritten and 3,088 unchanged across 15 items that differ.
Sentences by item
22 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2018; struck-through words were in FY2017. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
49 rewritten, 22 added, 57 removed, 440 unchanged
Such statements are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended (Securities Act) and Section 21E of the Securities Exchange Act of 1934, as [removed: amended (Exchange Act).][added: amended.]
These forward-looking statements relate to anticipated financial performance, management’s plans and objectives for future operations, business prospects, outcome of regulatory proceedings, market conditions, and other [removed: matters.][added: matters as discussed below.]
| • | Future credit ratings of [removed: Williams, WPZ,] [added: Williams] and [removed: their] [added: its] affiliates; |
Forward-looking statements are based on numerous assumptions, [removed: uncertainties,] [added: uncertainties] and risks that could cause future events or results to be materially different from those stated or implied in this report.
| • | Inflation, interest rates, and general economic conditions (including future disruptions and volatility in the global credit markets and the impact of these events on [removed: our] customers and suppliers); |
| • | Whether we are able to successfully identify, [removed: evaluate,] [added: evaluate] and timely execute our capital projects and [removed: other] [added: investment opportunities;] |
| • | The impact of operational and developmental hazards and unforeseen [removed: interruptions, and the availability of adequate insurance coverage;] [added: interruptions;] |
| • | The impact of existing and future laws [removed: (including,] [added: and regulations (including] but not limited [removed: to,] [added: to] the Tax Cuts and [removed: Job Acts] [added: Jobs Act] of 2017), [removed: regulations,] the regulatory environment, environmental liabilities, and litigation, as well as our ability to obtain necessary permits and [removed: approvals] [added: approvals,] and achieve favorable rate proceeding outcomes; |
| • | Acts of terrorism, [removed: including] cybersecurity [removed: threats,] [added: incidents,] and related disruptions; |
| • | Additional risks described in our filings with the Securities and Exchange [removed: Commission (SEC).] [added: Commission.] |
We disclaim any obligations to and do not intend to update the above list or [removed: to] announce publicly the result of any revisions to any of the forward-looking statements to reflect future events or developments.
Our revenues, operating results, future rate of growth, and the value of certain components of our businesses depend primarily upon the prices of natural gas, NGLs, oil, or other commodities, and the differences between prices of these commodities and could be materially adversely affected by an extended period of [removed: current] low commodity prices, or a [removed: further] decline in commodity prices.
[removed: Prices affect the amount of cash flow available] for capital expenditures and our ability to borrow money or raise additional capital.
| • | The price and quantity of foreign imports [added: and domestic exports] of natural gas and oil; |
We are exposed to the credit risk of our customers and counterparties, [removed: including Chesapeake Energy Corporation] and [removed: its affiliates, and] our credit risk management will not be able to completely eliminate such risk.
Regarding potential acquisitions, suitable acquisition candidates [added: or assets] may not be available on terms and conditions we find acceptable or, where multiple parties are trying to acquire an acquisition [removed: candidate,] [added: candidate or assets,] we may not be chosen as the acquirer.
| • | Acquisitions and capital projects may require substantial new capital, including [added: proceeds from] the issuance of debt or equity, and we may not be able to access capital markets or obtain acceptable terms. |
We [removed: may] face opposition to [removed: the construction and] operation [added: and expansion] of our pipelines and facilities from various [added: individuals and] groups.
We [removed: may face] [added: have experienced, and we anticipate that we will continue to face,] opposition to the [removed: construction and] operation [added: and expansion] of our pipelines and facilities from [added: governmental officials,] environmental groups, landowners, tribal groups, local groups and other advocates.
[removed: Such opposition could] [added: Opposition to our operation and expansion can] take many forms, including [added: the delay or denial of required governmental permits,] organized protests, attempts to block or sabotage our operations, intervention in regulatory or administrative proceedings involving [added: our assets, or lawsuits or other actions designed to prevent, disrupt or delay the operation or expansion of our assets and business.]
Any such event that [added: delays or prevents the expansion of our business, that] interrupts the revenues generated by our operations, or which causes us to make significant expenditures not covered by insurance, could adversely affect our financial condition and results of operations.
| • | The amount of cash that [removed: WPZ and] our [removed: other] subsidiaries distribute to us; |
[added: Failure to successfully] compete against current and future competitors could have a material adverse effect on our business, results of operations, financial condition, and cash flows.
We do not own [removed: all] [added: 100 percent] of the [added: equity] interests [removed: in] [added: of certain subsidiaries, including] the Partially Owned Entities, which [removed: could adversely affect] [added: may limit] our ability to operate and control these [removed: assets in a manner beneficial to us.][added: subsidiaries.]
[removed: Conflicts] [added: In addition, conflicts] of interest may arise [removed: in the future] between us, on the one hand, and [removed: our Partially Owned Entities,] [added: other interest owners,] on the other [removed: hand, with regard to our Partially Owned Entities’ governance, business, or operations.][added: hand.]
| • | We cannot control the amount of capital expenditures that we are required to fund [removed: with respect] [added: and we are dependent on third parties] to [removed: these operations;] [added: fund their required share of capital expenditures;] |
| • | We have limited ability to influence or control certain day to day activities affecting the [removed: operations.] [added: operations;] |
The risks described above or the failure to continue [removed: joint ventures, or to resolve disagreements with joint venture partners] [added: such arrangements] could adversely affect our ability to conduct [removed: our] [added: the] operations that are the subject of [removed: any joint venture,] [added: such arrangements] which [removed: could] [added: could,] in [removed: turn] [added: turn,] negatively affect our [added: business, growth strategy,] financial condition and results of operations.
An impairment of our assets, including [removed: goodwill,] property, plant, and equipment, intangible assets, and/or equity-method investments, could reduce our earnings.
The outcome of such testing could result in impairments of our assets including our [removed: goodwill,] property, plant, and equipment, intangible assets, and/or [removed: equity method] [added: equity-method] investments.
Our business could be negatively impacted by acts of terrorism and [removed: security threats, including cybersecurity threats, and] related disruptions.
While we believe that we maintain appropriate information security policies, practices, and protocols, we [added: regularly] face cybersecurity and other security threats to our information technology infrastructure, which could include threats to our operational industrial control systems [removed: and safety systems] that [added: are used to] operate our pipelines, plants, and assets.
We [removed: could] face unlawful attempts to gain access to our information technology infrastructure, including coordinated [removed: attacks from hackers, whether state-sponsored groups, “hacktivists”, or private individuals.]
[removed: The] [added: However, the] age, operating systems, or condition of our current information technology infrastructure and software assets and our ability to maintain and upgrade such assets could affect our ability to resist cybersecurity threats.
We [removed: could] also face attempts to gain access to information related to our assets through attempts to obtain unauthorized access by targeting acts of deception against individuals with legitimate access to physical locations or information.
Breaches in our information technology infrastructure or physical facilities, or other disruptions including those arising from theft, vandalism, fraud, or unethical conduct, could result in damage to [added: or destruction of] our assets, unnecessary waste, safety incidents, damage to the environment, reputational damage, potential liability, [removed: or] the loss of contracts, [added: the imposition of significant costs associated with remediation] and [removed: have] [added: litigation, heightened regulatory scrutiny, increased insurance costs, and] a material adverse effect on our operations, financial condition, results of operations, and cash flows.
If these pipelines or facilities were to become temporarily or permanently unavailable for any reason, or if throughput were reduced because of testing, line repair, damage to pipelines or facilities, reduced operating pressures, lack of capacity, increased credit requirements or rates charged by such pipelines or facilities or other causes, we and our customers would have reduced capacity to transport, store or deliver [added: natural gas or NGL products to end use markets or to receive deliveries of mixed NGLs, thereby reducing our revenues.]
If stockholder activists were to again take or threaten to take actions against the Company or seek to involve themselves in the governance, strategic direction or operations of the Company, we could incur significant costs as well as the distraction of management, [removed: which could have an adverse effect on our business or financial results.]
If there is a determination that the spin-off of WPX Energy, Inc. (WPX) stock to our stockholders is taxable for U.S. federal income tax purposes because the facts, representations or undertakings underlying a U.S. Internal Revenue Service [removed: (IRS)] private letter ruling or a tax opinion are incorrect or for any other reason, then we and our stockholders could incur significant income tax liabilities.
As of the date of the filing of this report, we have been assigned [removed: below] [added: an] investment-grade credit [removed: ratings] [added: rating] by each of the three credit ratings agencies.
| • | Availability of supplies, market demand, and volatility of prices; |
| • | Our ability to acquire new businesses and assets and successfully integrate those operations and assets into existing businesses as well as successfully expand our facilities, and to consummate asset sales on acceptable terms; |
| • | Changes in maintenance and construction costs, as well as our ability to obtain sufficient construction related inputs including skilled labor; |
Prices affect the amount of cash flow available
In some instances, we encounter opposition which disfavors hydrocarbon-based energy supplies regardless of practical implementation or financial considerations.
Certain operations, including the Partially Owned Entities, are conducted through arrangements that may limit our ability to operate and control these operations.
The operations of our current non-wholly-owned subsidiaries, including the Partially Owned Entities, are conducted in accordance with their organizational documents.
We anticipate that we will enter into more such arrangements, including through new joint venture structures or new Partially Owned Entities.
We may have limited operational flexibility in such current and future arrangements and we may not be able to control the timing or amount of cash distributions received.
| • | We cannot control the amount of cash reserves determined to be necessary to operate the business, which reduces cash available for distributions; |
| • | We may have additional obligations, such as required capital contributions, that are important to the success of the operations. |
If such conflicts of interest arise, we may not have the ability to control the outcome with respect to the matter in question.
Disputes between us and other interest owners may also result in delays, litigation or operational impasses.
A breach of our information technology infrastructure, including a breach caused by a cybersecurity attack on us or third parties with whom we are interconnected, may interfere with the safe operation of our assets, result in the disclosure of personal or proprietary information, and harm our reputation.
Our Board of Directors has oversight responsibility with regard to assessment of the major risks inherent in our business, including cybersecurity risks, and reviews management’s efforts to address and mitigate such risks, including the establishment and implementation of policies to address cybersecurity threats.
We have invested, and expect to continue to invest, significant time, manpower and capital in our information technology infrastructure.
attacks from hackers, whether state-sponsored groups, “hacktivists”, or private individuals.
We face the threat of theft and misuse of sensitive data and information, including customer and employee information.
We also are subject to cybersecurity risks arising from the fact that our business operations are interconnected with third parties, including third-party pipelines, other facilities and our contractors and vendors.
In addition, the breach of certain business systems could affect our ability to correctly record, process and report financial information.
which could have an adverse effect on our business or financial results.
stricter conditions on or revocation of permits, the issuance of injunctions limiting or preventing some or all of our operations, and delays or denials in granting permits.
| | |
| --- | --- |
| • | Expected levels of cash distributions by WPZ with respect to limited partner interests; |
| • | Whether WPZ will produce sufficient cash flows to provide expected levels of cash distributions; |
| • | Whether WPZ elects to pay expected levels of cash distributions and we elect to pay expected levels of dividends; |
| • | Availability of supplies, including lower than anticipated volumes from third parties served by our midstream business, and market demand; |
| • | Volatility of pricing including the effect of lower than anticipated energy commodity prices and margins; |
investment opportunities in accordance with our forecasted capital expenditures budget;
| • | Our ability to successfully expand our facilities and operations; |
| • | Changes in maintenance and construction costs; |
For example, Chesapeake
Energy Corporation and its affiliates, which accounted for approximately 10 percent of our 2017 consolidated revenues, have experienced significant, negative financial results due to sustained low commodity prices.
In the current environment, we may face political opposition by landowners, environmental activists, and others resulting in the delay and/or denial of required governmental permits.
our assets, or lawsuits or other actions designed to prevent, disrupt or delay the operation of our assets and business.
Our cash flow is heavily dependent on the earnings and distributions of WPZ.
Our partnership interest in WPZ is our largest cash-generating asset.
Therefore, we are indirectly exposed to all of the risks to which WPZ is subject, as our cash flow is heavily dependent upon the ability of WPZ to make distributions to its partners.
A significant decline in WPZ’s earnings and/or distributions would have a corresponding negative impact on us.
One of our subsidiaries acts as the general partner of a publicly traded limited partnership, Williams Partners L.P. As such, this subsidiary’s operations may involve a greater risk of liability than ordinary business operations.
One of our subsidiaries acts as the general partner of WPZ, a publicly traded limited partnership.
This subsidiary may be deemed to have undertaken contractual obligations with respect to WPZ as the general partner and to the limited partners of WPZ.
Activities, determined to involve such obligations to other persons or entities typically involve a higher standard of conduct than ordinary business operations and therefore may involve a greater risk of liability, particularly when a conflict of interest is found to exist.
Our control of the general partner of WPZ may increase the possibility of claims of breach of such duties, including claims brought due to conflicts of interest (including conflicts of interest that may arise between WPZ, on the one hand, and its general partner and that general partner’s affiliates, including us, on the other hand).
Any liability resulting from such claims could be material.
Failure to successfully
Because we do not control the Partially Owned Entities, we may have limited flexibility to control the operation of or cash distributions received from these entities.
The Partially Owned Entities’ organizational documents generally require distribution of their available cash to their members on a quarterly basis; however, in each case, available cash is reduced, in part, by reserves appropriate for operating the businesses.
As of December 31, 2017, our investments in the Partially Owned Entities accounted for approximately 7 percent of our total consolidated assets.
If a conflict of interest arises between us and a Partially Owned Entity, other owners may control the Partially Owned Entity’s actions with respect to such matter (subject to certain limitations), which could be detrimental to our business.
Any future disagreements with the other co-owners of these assets could adversely affect our ability to respond to changing economic or industry conditions, which could have a material adverse effect on our business, financial condition, results of operations, and cash flows.
We will conduct certain operations through joint ventures that may limit our operational flexibility or require us to make additional capital contributions.
Some of our operations are conducted through joint venture arrangements, and we may enter additional joint ventures in the future.
In a joint venture arrangement, we have less operational flexibility, as actions must be taken in accordance with the applicable governing provisions of the joint venture.
| • | We are dependent on third parties to fund their required share of capital expenditures; |
In addition, joint venture participants may have obligations that are important to the success of the joint venture, such as the obligation to pay substantial carried costs pertaining to the joint venture and to pay their share of capital and other costs of the joint venture, the performance of which is outside our control.
Similarly, if we fail to make a required capital contribution under the applicable governing provisions of a joint venture arrangement, we could be deemed to be in default under the joint venture agreement.
Joint venture partners may be in a position to take actions contrary to instructions or requests or contrary to our policies or objectives, and disputes between us and our joint venture partners may result in delays, litigation or operational impasses.
natural gas or NGL products to end use markets or to receive deliveries of mixed NGLs, thereby reducing our revenues.
Litigation pertaining to the ETC Merger, including litigation related to Energy Transfer Equity, L.P.’s (ETE’s) termination of and failure to close the ETC Merger, may negatively impact our business and operations.
We have incurred and may continue to incur additional costs in connection with the prosecution, defense or settlement of the currently pending and any future litigation relating to the ETC Merger or ETE’s termination of and failure to close the ETC Merger.
An excerpt. Shown here: 40 of 49 rewritten, all 22 added and 40 of 57 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2018 filing and the FY2017 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
220 rewritten, 345 added, 285 removed, 393 unchanged
We are an energy infrastructure company focused on connecting North America’s significant hydrocarbon resource plays to growing markets for natural gas and [removed: NGLs.][added: NGLs through our gas pipeline and midstream business.]
Our operations are located [removed: principally] in the United States.
[removed: The gas pipeline businesses] [added: These services] include [removed: interstate] natural gas [removed: pipelines and pipeline joint project investments; and the midstream businesses provide natural gas] gathering, [added: processing,] treating, and [removed: processing services;] [added: compression,] NGL [removed: production, fractionation, storage, marketing,] [added: fractionation] and [removed: transportation; deepwater] [added: transportation, crude oil] production handling and [removed: crude] [added: transportation, marketing services for NGL,] oil [removed: transportation services;] and [removed: are comprised of several wholly owned and partially owned subsidiaries and joint project investments.][added: natural gas, as well as storage facilities.]
[removed: The] [added: | • | Northeast G&P is comprised of our] midstream [removed: businesses include equity-method investments in natural gas] gathering and processing [removed: assets] [added: businesses in the Marcellus Shale region primarily in Pennsylvania, New York,] and [removed: NGL fractionation] [added: West Virginia] and [removed: transportation assets, including] [added: the Utica Shale region of eastern Ohio, as well as] a [added: 66 percent interest in Cardinal (a consolidated entity), a] 62 percent equity-method investment in UEOM, a 69 percent equity-method investment in Laurel Mountain, a 58 percent equity-method investment in Caiman II, [removed: a 60 percent equity-method investment in Discovery, a 50 percent equity-method investment in OPPL,] and Appalachia Midstream Services, LLC, which owns [added: equity-method investments with] an approximate average 66 percent [removed: equity-method investment] interest in multiple gas gathering systems in the Marcellus Shale (Appalachia Midstream [removed: Investments), as well as our previously owned 50 percent equity-method investment in the Delaware basin gas gathering system (DBJV) in the Mid-Continent region (see Note 5 – Investing Activities of Notes to Consolidated Financial Statements).][added: Investments). |]
[removed: Williams Partners’] [added: The] ongoing strategy [added: of our midstream operations] is to safely and reliably operate [removed: large-scale, interstate natural gas transmission and] [added: large-scale] midstream [removed: infrastructures] [added: infrastructure] where our assets can be fully utilized and drive low per-unit costs.
We focus on consistently attracting new business by providing highly reliable service to our [removed: customers and investing in growing markets and areas of increasing natural gas demand.][added: customers.]
[removed: Williams Partners’] [added: Our gas pipeline businesses’] interstate transmission and [removed: related] storage activities are subject to regulation by the FERC and as such, our rates and charges for the transportation of natural gas in interstate commerce, and the extension, expansion or abandonment of jurisdictional facilities and accounting, among other things, are subject to regulation.
[added: Changes in commodity prices and volumes transported have] limited near-term impact on these revenues because the majority of cost of service is recovered through firm capacity reservation charges in transportation rates.
[added: |] Other [added: obligations (3)(4) | 2 | | | | 4 | | | | 1 | | | | — | | | | 7 | | |]
In December [removed: 2017,] [added: 2018,] we paid a regular quarterly dividend of [removed: $0.30] [added: $0.34] per share.
On February [removed: 21, 2018,] [added: 20, 2019,] our board of directors approved a regular quarterly dividend of [removed: $0.34] [added: $0.38] per share payable on March [removed: 26, 2018.][added: 25, 2019.]
(See Note 7 – [removed: Provision (Benefit) for] [added: Other] Income [removed: Taxes] [added: and Expenses] of Notes to Consolidated Financial Statements.)
[removed: Transco and Northwest Pipeline have recognized] [added: Regulatory charges resulting from Tax Reform relates to the 2017 recognition of] regulatory liabilities [removed: to reflect] [added: for] the probable return to customers through future rates of the future decrease in income taxes payable associated with Tax Reform.
[removed: (See Note 1 – General, Description of Business, Basis of Presentation, and Summary of Significant Accounting Policies of Notes to Consolidated Financial Statements.)] The timing and actual amount of such return will be subject to future negotiations regarding this matter and many other elements of cost-of-service rate proceedings, including other costs of providing service.
As a result of the adoption of Accounting Standards Update 2014-09, Revenues from Contracts with Customers (ASC [removed: 606),] [added: 606) in January 2018,] we [removed: expect that our 2018] [added: now record] revenues [removed: will increase in situations] [added: for transactions] where we receive noncash consideration, [removed: which exists] primarily in certain of our gas processing contracts [removed: where we receive] [added: that provide] commodities as full or partial consideration for services provided.
Additionally, [removed: we expect] future revenues [removed: will be] [added: are] impacted by application of the new accounting standard to certain contracts for which we received prepayments for services and have recorded deferred revenue (contract liabilities).
The new accounting guidance requires that the transaction price, including any remaining deferred revenue from the old contract, be allocated to the performance obligations over [removed: the term of the new contract.]
(See Note [removed: 9] [added: 3] – [removed: Employee Benefit Plans] [added: Divestitures] of Notes to Consolidated Financial Statements.)
Expansion Project [removed: Completions][added: Updates]
[removed: The] [added: This] project expanded Transco’s existing natural gas transmission system [removed: together with greenfield facilities] to provide incremental firm transportation capacity from [removed: our] Station 210 in New Jersey [removed: and our Station 165 in Virginia] to a new [removed: lateral extending from] [added: interconnection on] our [removed: Brunswick] [added: Trenton Woodbury] Lateral in [removed: Virginia.][added: New Jersey.]
The project increased capacity by [removed: 250] [added: 475] Mdth/d.
[removed: The] [added: This] project expanded Transco’s existing natural gas transmission system to provide incremental firm transportation capacity from Station [removed: 195] [added: 65] in [removed: Pennsylvania] [added: Louisiana] to [removed: the Rockaway Delivery Lateral transfer point and the Narrows meter station] [added: delivery points] in [removed: New York.][added: Wharton and San Patricio Counties, Texas.]
[removed: The] [added: In total, the] project increased [added: Transco’s] capacity by [removed: 115] [added: 1,700] Mdth/d.
This project expanded Transco’s existing natural gas transmission system [removed: together] [added: along] with greenfield facilities to provide incremental firm transportation capacity from [removed: our Station 210 in New Jersey] [added: the northeastern Marcellus producing area] to markets [added: along Transco’s mainline as far south as Station 85] in [removed: northwest Georgia.][added: west central Alabama.]
The project [removed: increased] [added: is expected to increase] capacity by [removed: 448] [added: 296] Mdth/d.
In [removed: July 2017,] [added: March 2018,] Phase [removed: I] [added: 2] of the [removed: Hillabee] [added: Garden State] Expansion [removed: Project] [added: project] was placed into service.
The project [removed: will be] [added: is being] constructed in phases, and all of the project expansion capacity is dedicated to Sabal Trail pursuant to a capacity lease agreement.
The in-service date of Phase II is planned for the second quarter of [removed: 2020] [added: 2020,] and together [removed: they] [added: Phases I and II] are expected to increase capacity by 1,025 Mdth/d.
(See Note [removed: 2] [added: 7] – [removed: Acquisitions] [added: Other Income] and [removed: Divestitures] [added: Expenses] of Notes to Consolidated Financial Statements.)
(See Note [removed: 5] [added: 6] – Investing Activities of Notes to Consolidated Financial Statements.)
NGL per-unit margins were approximately [removed: 62] [added: 19] percent higher in [removed: 2017] [added: 2018] compared to [removed: 2016] [added: 2017 primarily] due to a [removed: 42] [added: 22] percent increase in [added: realized] per-unit non-ethane [added: prices and an approximate 9 percent decrease in per-unit natural gas feedstock] prices.
Our business plan for [removed: 2018] [added: 2019] includes a continued focus on growing our fee-based businesses, executing growth [removed: projects] [added: projects, including through joint ventures,] and accomplishing cost discipline initiatives to ensure operations support our strategy.
We anticipate operating results will increase through organic business growth driven [removed: primarily] by [removed: Transco expansion projects and] continued [removed: growth] [added: expansion] in the Northeast [removed: region.][added: region and Transco expansion projects.]
Our growth capital and investment expenditures in [removed: 2018] [added: 2019] are expected to be [removed: approximately] [added: in a range from] $2.7 [added: billion to $2.9] billion.
As a result of our significant continued capital and investment expenditures on Transco [removed: expansions] [added: expansion projects] and fee-based gathering and processing projects, fee-based businesses are a significant component of our portfolio and serve to reduce the influence of commodity price fluctuations on our operating results and cash flows.
For [removed: 2018,] [added: 2019,] current forward market prices indicate [removed: oil prices are expected to be higher compared to 2017, while] [added: oil,] natural [removed: gas] [added: gas,] and NGL prices are expected to be lower [removed: or comparable with 2017.][added: compared to 2018.]
In [removed: 2018,] [added: 2019,] our operating results are expected to include increases from our regulated Transco fee-based business, primarily related to projects recently placed [removed: in-service or expected to be placed in-service in 2018 including the Atlantic Sunrise project.][added: in-service.]
For our non-regulated businesses, we anticipate increases in fee-based revenue in the Northeast [removed: region,] [added: G&P segment associated with recent expansion projects,] partially offset [removed: by lower fee-based revenue] [added: with a decrease] in the West [removed: region.][added: segment primarily due to recent asset divestitures.]
| • | Opposition [removed: to] [added: to, and legal regulations affecting, our] infrastructure projects, including the risk of delay or denial in permits and approvals needed for our projects; |
| • | Counterparty credit and performance [removed: risk, including that of Chesapeake Energy Corporation and its affiliates;] [added: risk;] |
Our interstate natural gas pipeline strategy is to create value by maximizing the utilization of our pipeline capacity by providing high quality, low cost transportation of natural gas to large and growing markets.
Prior to our merger with Williams Partners L.P., our previously consolidated master limited partnership, in August 2018, we had one reportable segment, Williams Partners.
Beginning in the third-quarter 2018, consistent with the manner in which our chief operating decision maker evaluates performance and allocates resources, our operations are now presented within the following reportable segments: Northeast G&P, Atlantic-Gulf, and West.
Prior period segment disclosures have been recast for the new segment presentation.
Our reportable segments are comprised of the following businesses:
| • | Atlantic-Gulf is comprised of our interstate natural gas pipeline, Transco, and significant natural gas gathering and processing and crude oil production handling and transportation assets in the Gulf Coast region, including a 51 percent interest in Gulfstar One (a consolidated entity), which is a proprietary floating production system, and various petrochemical and feedstock pipelines in the Gulf Coast region, as well as a 50 percent equity-method investment in Gulfstream, a 60 percent equity-method investment in Discovery, and a 41 percent interest in Constitution (a consolidated entity), which is developing a pipeline project (see Note 4 – Variable Interest Entities of Notes to Consolidated Financial Statements). |
| • | West is comprised of our interstate natural gas pipeline, Northwest Pipeline, and our gathering, processing, and treating operations in Colorado, Wyoming, and the Barnett Shale region of north-central Texas, the Eagle Ford Shale region of south Texas, the Haynesville Shale region of northwest Louisiana, and the Mid-Continent region which includes the Anadarko, Arkoma, Delaware, and Permian basins. This segment also includes our NGL and natural gas marketing business, storage facilities, an undivided 50 percent interest in an NGL fractionator near Conway, Kansas, and a 50 percent equity-method investment in OPPL, a 50 percent interest in Jackalope (an equity-method investment following deconsolidation as of June 30, 2018), a 50 percent equity-method investment in RMM, a 15 percent equity-method investment in Brazos Permian II, and our previously owned 50 percent equity-method investment in the Delaware basin gas gathering system (DBJV) in the Mid- |
West also included our former natural gas gathering and processing assets in the Four Corners area of New Mexico and Colorado (see Note 3 – Divestitures of Notes to Consolidated Financial Statements).
| • | Other includes our previously owned operations, including an 88.5 percent undivided interest in an olefins production facility in Geismar, Louisiana, which was sold in July 2017 (see Note 3 – Divestitures of Notes to Consolidated Financial Statements), and a refinery grade propylene splitter in the Gulf region, which was sold in June 2017. This segment also included our previously owned Canadian assets, which included an oil sands offgas processing plant near Fort McMurray, Alberta, and an NGL/olefin fractionation facility at Redwater, Alberta. In September 2016, these Canadian operations were sold. Other also includes minor business activities that are not operating segments, as well as corporate operations. |
Net income (loss) attributable to The Williams Companies, Inc., for the year ended December 31, 2018, decreased by $2.329 billion compared to the year ended December 31, 2017, reflecting a $2.112 billion increase to the provision for income taxes driven by the absence of a 2017 benefit resulting from Tax Reform and a $159 million decrease in operating income.
The decrease in operating income reflects an increase of $667 million in Impairment of certain assets and $403 million in lower gains from the sale of certain assets.
These unfavorable changes were partially offset by the absence of $674 million in regulatory charges resulting from Tax Reform in 2017, and a $190 million increase in service revenues primarily resulting from expansion projects placed into service in 2017 and 2018.
WPZ Merger
On August 10, 2018, we completed our merger with Williams Partners L.P. (WPZ), pursuant to which we acquired all of the approximately 256 million publicly held outstanding common units of WPZ in exchange for 382 million shares of our common stock in a noncash equity transaction.
Williams continued as the surviving entity.
FERC Income Tax Policy Revision
On March 15, 2018, the FERC issued a revised policy statement (the revised policy statement) regarding the recovery of income tax costs in rates of natural gas pipelines.
The FERC found that an impermissible double recovery results from granting a Master Limited Partnership (MLP) pipeline both an income tax allowance and a return on equity pursuant to the discounted cash flow methodology.
As a result, the FERC will no longer permit an MLP pipeline to recover an income tax allowance in its cost of service.
The FERC further stated it will address the application of this policy to non-MLP partnership forms as those issues arise in subsequent proceedings.
One of the benefits of the recent WPZ Merger is to allow our FERC-regulated pipelines to continue to recover an income tax allowance in their cost of service rates.
On July 18, 2018, the FERC issued an order dismissing the requests for rehearing and clarification of the revised policy statement.
In addition, the FERC provided guidance that an MLP pipeline (or other pass-through entity) no longer recovering an income tax allowance pursuant to the revised policy may eliminate previously accumulated deferred income taxes (ADIT) from its cost of service instead of flowing these ADIT balances to ratepayers.
This guidance, if implemented, would significantly mitigate the impact of the revised policy statement.
However, the FERC stated that the revised policy statement and such guidance do not establish a binding rule but are instead expressions of general
policy intent designed to provide guidance by notifying entities of the course of action the FERC intends to follow in future adjudications.
To the extent the FERC addresses these issues in future proceedings, it will consider any arguments regarding not only the application of the revised policy to the facts of the case, but also any arguments regarding the underlying validity of the policy itself.
The FERC’s guidance on ADIT likely will be challenged by customers and state commissions, which would result in a long period of revenue uncertainty for pipelines eliminating ADIT from their cost of service.
The WPZ Merger has the additional benefit of eliminating this uncertainty.
On March 15, 2018, the FERC also issued a Notice of Proposed Rulemaking proposing a filing process that will allow it to determine which natural gas pipelines may be collecting unjust and unreasonable rates in light of the recent reduction in the corporate income tax rate in the Tax Cuts and Jobs Act (Tax Reform) and the revised policy statement.
On July 18, 2018, the FERC issued a Final Rule, retaining the filing requirement and reaffirming the options that pipelines have to either reflect the reduced tax rate or explain why no rate change is necessary.
The FERC also clarified that a natural gas company organized as a pass-through entity and all of whose income or losses are consolidated on the federal income tax return of its corporate parent is considered to be subject to the federal corporate income tax and is thus eligible for a tax allowance.
We believe this Final Rule and the previously discussed WPZ Merger allow for the continued recovery of income tax allowances in Transco’s and Northwest Pipeline’s rates.
Transco’s August 31, 2018, general rate case filing reflects a tax allowance based on this clarification, and the FERC’s September 28, 2018, order in that rate case proceeding finds that Transco is exempt from the Final Rule’s Form 501-G filing requirement.
In addition, on October 19, 2018, Northwest Pipeline filed a petition requesting that the FERC waive its Form 501-G filing requirement under this Final Rule because (i) the reduction in the corporate income tax is already addressed in Northwest Pipeline’s 2017 rate settlement, and (ii) as discussed above, the WPZ Merger allows for the continued recovery of income tax allowances in Northwest Pipeline’s rates.
The FERC agreed and granted Northwest Pipeline’s petition for waiver on November 19, 2018.
On October 11, 2018 and December 6, 2018, Discovery Gas Transmission, LLC and Pine Needle LNG Company, LLC, respectively, filed their Form 501-Gs, including explanations as to why no adjustments to rates are needed.
On March 15, 2018, the FERC also issued a Notice of Inquiry seeking comments on the additional impacts of Tax Reform on jurisdictional rates, particularly whether, and if so how, the FERC should address changes relating to ADIT amounts after the corporate income tax rate reduction and bonus depreciation rules, as well as whether other features of Tax Reform require FERC action.
We are evaluating the impact of these developments on our interstate natural gas pipelines and currently expect any associated impacts would be prospective and determined through subsequent rate proceedings.
We also continue to monitor developments that may impact our regulatory liabilities resulting from Tax Reform.
We have one reportable segment, Williams Partners.
All remaining business activities are included in Other.
Williams Partners
Williams Partners consists of our consolidated master limited partnership, WPZ, which includes gas pipeline and midstream businesses.
As of December 31, 2017, we own 74 percent of the interests in WPZ.
Williams Partners’ gas pipeline businesses consist primarily of Transco and Northwest Pipeline.
The gas pipeline business also holds interests in joint venture interstate and intrastate natural gas pipeline systems including a 50 percent equity-method investment in Gulfstream and a 41 percent interest in Constitution (a consolidated entity), which is developing a pipeline project.
(See Note 3 – Variable Interest Entities of Notes to Consolidated Financial Statements.) As of December 31, 2017, Transco and Northwest Pipeline owned and operated a combined total of approximately 13,600 miles of pipelines with a total annual throughput of approximately 4,533 Tbtu of natural gas and peak-day delivery capacity of approximately 18.8 MMdth of natural gas.
Williams Partners’ midstream businesses primarily consist of (1) natural gas gathering, treating, compression, and processing; (2) NGL fractionation, storage, and transportation; (3) crude oil production handling and transportation; and (4) olefins production.
(See Note 2 – Acquisitions and Divestitures of Notes to Consolidated Financial Statements.) The primary service areas are concentrated in major producing basins in Colorado, Texas, Oklahoma, Kansas, New Mexico, Wyoming, the Gulf of Mexico, Louisiana, Pennsylvania, West Virginia, New York, and Ohio, which include the Barnett, Eagle Ford, Haynesville, Marcellus, Niobrara, and Utica shale plays as well as the Mid-Continent region.
The midstream businesses previously included Canadian midstream operations, which were comprised of an oil sands offgas processing plant near Fort McMurray, Alberta and an NGL/olefin fractionation facility at Redwater, Alberta.
In September 2016, these Canadian operations were sold.
Changes in commodity prices and volumes transported have
Other is comprised of business activities that are not operating segments, as well as corporate operations.
Other also includes certain domestic olefins pipeline assets as well as certain Canadian assets, which included a liquids extraction plant located near Fort McMurray, Alberta, that began operations in March 2016, and a propane dehydrogenation facility which was under development.
In September 2016, the Canadian assets were sold.
Financial Repositioning
In January 2017, we entered into agreements with WPZ, wherein we permanently waived the general partner’s IDRs and converted our 2 percent general partner interest in WPZ to a noneconomic interest in exchange for 289 million newly issued WPZ common units.
Pursuant to this agreement, we also purchased approximately 277 thousand WPZ common units for $10 million.
Additionally, we purchased approximately 59 million common units of WPZ at a price of $36.08586 per unit in a private placement transaction, funded with proceeds from our equity offering (see Note 14 – Stockholders’ Equity of Notes to Consolidated Financial Statements).
According to the terms of this agreement, concurrent with WPZ’s quarterly distributions in February 2017 and May 2017, we paid additional consideration totaling $56 million to WPZ for these units.
Subsequent to these transactions and as of December 31, 2017, we own a 74 percent limited partner interest in WPZ.
Net income (loss) attributable to The Williams Companies, Inc., for the year ended December 31, 2017, changed favorably by $2.598 billion compared to the year ended December 31, 2016, reflecting a $1.949 billion improvement in the provision (benefit) for income taxes primarily due to Tax Reform, the absence of $430 million of impairments of equity-method investments incurred in 2016, a $219 million increase in Other investing income (loss) – net primarily associated with the disposition of certain equity-method investments in 2017, a $204 million increase in operating income and reduced interest expense, partially offset by a $261 million increase in net income attributable to noncontrolling interests primarily due to increased income at WPZ.
The increase in operating income reflects a gain of $1.095 billion from the sale of our Geismar Interest, increased service revenue from expansion projects, and lower costs and expenses, partially offset by a $674 million regulatory charge resulting from Tax Reform, a $375 million increase in impairments of certain assets, and a $184 million decrease in product margins primarily due to the loss of olefins volumes as a result of the sale of our Gulf Olefins and Canadian operations.
Tax Reform
In December 2017, the Tax Cuts and Jobs Act was enacted, which, among other things, reduced the federal corporate income tax rate from 35 percent to 21 percent (Tax Reform).
As a result, we have remeasured our existing deferred income tax assets and liabilities, to reflect the expected future realization of existing temporary differences at the lower income tax rate.
This resulted in the recognition of a net income tax provision benefit of $1.923 billion for the year ended December 31, 2017.
Certain adjustments within the provision benefit are considered provisional and are potentially subject to change in the future.
These liabilities represent an obligation to return amounts directly to our customers.
The regulatory liabilities were recorded in December 2017 through regulatory charges to operating income totaling $674 million.
This increase in revenues will be offset by a similar increase in costs and expenses when the commodities received are subsequently sold.
Based on commodities received during 2017 as consideration for services and market prices during 2017, we estimate the impact to revenues and costs would have been approximately $350 million.
The application of ASC 606 to prior periods related to these contracts would have resulted in lower revenues in 2016 and 2017.
Revenues will also be lower in 2018 and 2019 than what would have been recorded under the previous guidance, offset by increased revenues in later reporting periods given the longer period of recognition.
We are adopting ASC 606 utilizing the modified retrospective transition approach, effective January 1, 2018, by recognizing the cumulative effect of initially applying ASC 606 for periods prior to January 1, 2018, which we expect to result in a decrease of approximately $255 million, net of tax, to the opening balance of Total equity in the Consolidated Balance Sheet.
This adjustment is primarily associated with the impact to the timing of deferred revenue (contract liabilities) for certain contracts as noted above.
Pension Deferred Vested Benefit Early Payout Program
In September 2017, we initiated a program to pay out certain deferred vested pension benefits to reduce investment risk, cash funding volatility, and administrative costs.
In December 2017, the lump-sum payments were made and the annuity payments were commenced in relation to this program.
An excerpt. Shown here: 40 of 220 rewritten, 40 of 345 added and 40 of 285 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2018 filing and the FY2017 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
11 rewritten, 3 added, 10 removed, 27 unchanged
Any borrowings under [removed: the] [added: our] credit [removed: facilities] [added: facility] and any issuances under [removed: WPZ’s] [added: our] commercial paper program could be at a variable interest rate and could expose us to the risk of increasing interest rates.
(See Note [removed: 13] [added: 14] – Debt, Banking Arrangements, and Leases of Notes to Consolidated Financial Statements.)
The tables below provide information by maturity date about our interest rate risk-sensitive instruments as of December 31, [removed: 2017] [added: 2018] and [removed: 2016.][added: 2017.]
| Variable rate [removed: (2)] [added: (3)] | | $ | — | | | $ | — | | | $ | — | | | $ | 270 | | | $ | — | | | $ | — | | | $ | 270 | | | $ | 270 | |
| | | [removed: 2017] [added: 2019] | | | | [removed: 2018] [added: 2020] | | | | [removed: 2019] [added: 2021] | | | | [removed: 2020] [added: 2022] | | | | [removed: 2021] [added: 2023] | | | | Thereafter (1) | | | | Total | | | | Fair Value December 31, [removed: 2016] [added: 2018] | | |
| Weighted-average interest rate | | 5.2 | | % | | 5.2 | | % | | 5.2 | | % | | [removed: 5.2] [added: 5.3] | | % | | [removed: 5.2] [added: 5.5] | | % | | [removed: 5.6] [added: 5.7] | | % | | | | | | | | |
| Variable rate [removed: (4)] [added: (2)] | | $ | [removed: 93] [added: —] | | | $ | — | | | $ | — | | | $ | — | | | $ | [removed: —] [added: 160] | | | $ | — | | | $ | [removed: 93] [added: 160] | | | $ | [removed: 93] [added: 160] | |
| [removed: (2)] [added: (3)] | The weighted-average interest rate for our $270 million credit facility borrowing at December 31, 2017 was 3.16 percent. |
[added: The fair value of derivative contracts is subject] to many factors, including changes in energy commodity market prices, the liquidity and volatility of the markets in which the contracts are transacted, and changes in interest rates.
At December 31, [removed: 2017] [added: 2018] and [removed: 2016,] [added: 2017,] our derivative activity was not material.
(See Note [removed: 16] [added: 17] – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements.)
See Note 17 – Fair Value Measurements, Guarantees, and Concentration of Credit Risk of Notes to Consolidated Financial Statements for the methods used in determining the fair value of our long-term debt.
| Fixed rate | | $ | 47 | | | $ | 2,138 | | | $ | 890 | | | $ | 2,021 | | | $ | 1,473 | | | $ | 15,685 | | | $ | 22,254 | | | $ | 23,170 | |
| (2) | The weighted-average interest rate for our $160 million credit facility borrowing at December 31, 2018 was 3.77 percent. |
The fair value of our publicly traded long-term debt is valued using indicative year-end traded bond market prices.
Private debt is valued based on market rates and the prices of similar securities with similar terms and credit ratings.
| Fixed rate | | $ | 785 | | | $ | 500 | | | $ | 32 | | | $ | 2,121 | | | $ | 871 | | | $ | 17,475 | | | $ | 21,784 | | | $ | 22,465 | |
| Variable rate (3) | | $ | — | | | $ | 850 | | | $ | — | | | $ | 775 | | | $ | — | | | $ | — | | | $ | 1,625 | | | $ | 1,625 | |
| Commercial paper: | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | |
| --- | --- |
| (3) | The weighted-average interest rates for WPZ’s $850 million term loan and our $775 million credit facility borrowing at December 31, 2016 were 2.50 percent and 2.51 percent, respectively. |
| (4) | The weighted-average interest rate was 1.06 percent at December 31, 2016. |
The fair value of derivative contracts is subject
Item 1. Business
128 rewritten, 151 added, 110 removed, 241 unchanged
Our Corporate Governance Guidelines, [added: information regarding corporate social responsibility,] Code of Ethics for Senior Officers, Board committee charters, and the Williams Code of Business Conduct are also available on our Internet website.
Our operations are located [removed: principally] in the United States.
Williams’ headquarters are located in Tulsa, Oklahoma, with other major offices in Salt Lake City, Utah; Houston, Texas; [removed: Pittsburgh, Pennsylvania;] and [removed: the Four Corners Area.][added: Pittsburgh, Pennsylvania.]
Financial Statements and Supplementary Data — [added: Note 18 – Contingent Liabilities and Commitments of] Notes to Consolidated Financial [removed: Statements — Note 18 – Segment Disclosures.”][added: Statements.]
[added: | • | Other includes our previously owned operations, including an 88.5 percent undivided interest in an olefins production facility in Geismar, Louisiana, which was sold in July 2017 (see Note 3 – Divestitures of Notes to Consolidated Financial Statements), and a refinery grade propylene splitter in the Gulf region, which was sold in June 2017.] This [removed: reporting] segment also included our [removed: former] [added: previously owned] Canadian [removed: midstream operations comprised of] [added: assets, which included] an oil sands offgas processing plant near Fort McMurray, Alberta, [added: and] an NGL/olefin fractionation [removed: facility, and the Boreal Pipeline, which were sold in] [added: facility at Redwater, Alberta. In] September [removed: 2016 (see Note 2 – Acquisitions and Divestitures of Notes to Consolidated Financial Statements).][added: 2016, these Canadian operations were sold. Other also includes minor business activities that are not operating segments, as well as corporate operations. |]
[removed: Our gas pipeline business also holds interests in joint venture] [added: | • | Atlantic-Gulf is comprised of our] interstate [added: natural gas pipeline, Transco,] and [removed: intrastate] [added: significant] natural gas [removed: pipeline systems] [added: gathering and processing and crude oil production handling and transportation assets in the Gulf Coast region,] including a [added: 51 percent interest in Gulfstar One (a consolidated entity), which is a proprietary floating production system, and various petrochemical and feedstock pipelines in the Gulf Coast region, as well as a] 50 percent equity-method investment in [removed: Gulfstream] [added: Gulfstream, a 60 percent equity-method investment in Discovery,] and a 41 percent interest in Constitution (a consolidated entity), which is developing a pipeline project (see Note [removed: 3] [added: 4] – Variable Interest Entities of Notes to Consolidated Financial Statements). [added: |]
Transco is an interstate natural gas transmission company that owns and operates a [removed: 9,700-mile] [added: 9,900-mile] natural gas pipeline system, which is regulated by the FERC, extending from Texas, Louisiana, [removed: Mississippi] [added: Mississippi,] and the Gulf of Mexico through Alabama, Georgia, South Carolina, North Carolina, Virginia, Maryland, Delaware, [removed: Pennsylvania] [added: Pennsylvania,] and New Jersey to the New York City metropolitan area.
At December 31, [removed: 2017,] [added: 2018,] Transco’s system, which extends from Texas to New York, had a system-wide delivery capacity totaling approximately [removed: 15.0] [added: 16.7] MMdth of natural gas per day.
During [removed: 2017,] [added: 2018,] Transco completed [removed: five] [added: two] fully-contracted expansions, which added more than [removed: 2.8] [added: 1.75] MMdth of firm transportation capacity per day to the existing pipeline system.
Transco’s system includes [removed: 50] [added: 55] compressor stations, four underground storage fields, and [removed: an] [added: one] LNG storage facility.
Compression facilities at sea level-rated capacity total approximately [removed: 2.1] [added: 2.2] million horsepower.
[removed: Shippers on Transco’s system include] [added: Our interstate natural gas pipelines transport and store natural gas for a broad mix of customers, including local natural gas distribution companies,] public utilities, municipalities, [removed: intrastate pipelines,] direct industrial users, electric power generators, and natural gas marketers and producers.
[removed: Transco’s] [added: We have] firm transportation [removed: agreements] [added: and storage contracts that] are generally long-term [removed: agreements] [added: contracts] with various expiration dates and account for the major portion of [removed: Transco’s business.][added: our regulated businesses.]
Additionally, [removed: Transco offers] [added: we offer storage services and] interruptible transportation services under shorter-term agreements.
At December 31, [removed: 2017,] [added: 2018,] Transco’s customers had stored in its facilities approximately [removed: 141][added: 130 Bcf of natural gas.]
At December 31, [removed: 2017,] [added: 2018,] Northwest Pipeline’s system, having long-term firm transportation and storage redelivery agreements with aggregate capacity reservations of approximately [removed: 3.8] [added: 3.9] MMdth/d, was composed of approximately 3,900 miles of mainline and lateral transmission pipeline and 41 transmission compressor stations having a combined sea level-rated capacity of approximately 472,000 horsepower.
[removed: Williams Partners owns,] [added: We own,] through a subsidiary, a 50 percent equity-method investment in Gulfstream.
[removed: Williams Partners shares] [added: We share] operating responsibilities for Gulfstream with the other 50 percent owner.
Key variables for [removed: this] [added: our] business will continue to be:
| • | Prices impacting [added: our] commodity-based activities; |
| • | Disciplined growth in [added: our] service areas. |
Gathering, [removed: Processing,] [added: Processing] and Treating [added: Assets]
[removed: Williams Partners’] [added: Our] gathering systems receive natural gas from producers’ oil and natural gas wells and gather these volumes to gas processing, treating or redelivery facilities.
[removed: Williams Partners’] [added: Our] treating facilities remove water vapor, carbon [removed: dioxide,] [added: dioxide] and other contaminants and collect condensate, but do not extract NGLs.
[removed: Williams Partners’ is] [added: We are] generally paid a fee based on the volume of natural gas gathered and/or treated, generally measured in the Btu heating value.
| • | Normal butane, [removed: isobutane] [added: isobutane,] and natural gasoline, primarily used by the refining industry as blending stocks for motor gasoline or as a petrochemical feedstock. |
| • | Fee-based: We are paid a fee based on the volume of natural gas processed, generally measured in the Btu heating value. Our customers are entitled to the NGLs produced in connection with this type of processing agreement. A portion of our fee-based processing [removed: revenues] [added: revenue] includes a share of the margins on the NGLs produced. For the year ended December 31, [removed: 2017, 70] [added: 2018, 74] percent of our NGL production volumes were under fee-based contracts. |
| • | Noncash commodity-based: We also process gas under two types of commodity-based contracts, keep-whole and percent-of-liquids, where we receive consideration for our services in the form of NGLs. Under these contracts, we retain some or all of the extracted NGLs as compensation for our services. For a keep-whole arrangement we replace the Btu content of the retained NGLs that were extracted during processing with natural gas purchases, also known as shrink replacement gas. For a percent-of-liquids arrangement, we deliver to customers an agreed-upon percentage of the extracted NGLs and retain the remainder. NGLs we retain in connection with these types of processing agreements are referred to as our equity NGL production. Under keep-whole agreements, we have commodity price exposure on the difference between NGL and natural gas prices. For the year ended December 31, [removed: 2017, 30] [added: 2018, 26] percent of our NGL production volumes were under noncash commodity-based contracts. |
[removed: Williams Partners’] [added: Our] gas gathering and processing customers are generally natural gas producers who have proved and/or producing natural gas fields in the areas surrounding [removed: its] [added: our] infrastructure.
During [removed: 2017, Williams Partners’] [added: 2018, our] facilities gathered and processed gas and crude oil for approximately 260 customers.
[removed: Williams Partners’] [added: Our] top ten customers accounted for approximately [removed: 75] [added: 70] percent of our gathering and processing fee revenues and NGL margins from our noncash commodity-based agreements.
Demand for our equity NGLs is affected by economic conditions and the resulting demand from industries using these commodities to produce petrochemical-based products such as plastics, carpets, packing [removed: materials] [added: materials,] and blending stocks for motor gasoline and the demand from consumers using these commodities for heating and fuel.
| | [added: | | |] Natural Gas Gathering Assets | | | | | | | | |
| | [added: | |] Location | | Pipeline Miles | | Inlet Capacity (Bcf/d) | | Ownership Interest | | Supply Basins/Shale Formations |
[removed: |] Northeast [removed: | | | | | | | | | |][added: G&P]
| [added: |] Ohio Valley Midstream | [added: | |] Ohio, West Virginia, & Pennsylvania | | 216 | | 0.8 | | 100% | | Appalachian |
| [added: |] Susquehanna Supply Hub | [added: | |] Pennsylvania & New York | | [removed: 436] [added: 454] | | [removed: 3.2] [added: 3.6] | | 100% | | Appalachian |
| [added: |] Cardinal (1) | [added: | |] Ohio | | [removed: 353] [added: 360] | | [removed: 1.0] [added: 0.9] | | 66% | | Appalachian |
| [added: |] Flint | [added: | |] Ohio | | 75 | | [removed: 0.4] [added: 0.5] | | 100% | | Appalachian |
| [removed: Marcellus South (2)] | [added: Beaver Creek | | |] Pennsylvania | | 41 | | 0.1 | | 100% | | Appalachian |
WPZ MERGER
On August 10, 2018, we completed our merger with Williams Partners L.P. (WPZ), our previously consolidated master limited partnership, pursuant to which we acquired all of the approximately 256 million publicly held outstanding common units of WPZ in exchange for 382 million shares of our common stock in a noncash equity transaction.
Prior to our merger with WPZ, we had one reportable segment, Williams Partners.
Beginning in the third-quarter 2018, consistent with the manner in which our chief operating decision maker evaluates performance and allocates resources, our operations are now presented within the following reportable segments: Northeast G&P, Atlantic-Gulf, and West.
Prior period segment disclosures have been recast for the new segment presentation.
Our reportable segments are comprised of the following businesses:
This segment includes our natural gas gathering, compression, processing, and NGL fractionation business in the Marcellus and Utica Shale regions in Pennsylvania, West Virginia, New York, and Ohio.
The following tables summarize the significant consolidated assets of this segment:
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | |
| | | | | | | | | | | | | |
| | | | | | | | | Inlet | | | | |
| | | | | | | Pipeline | | Capacity | | Ownership | | |
| | | | | Location | | Miles | | (Bcf/d) | | Interest | | Supply Basins |
| | | | | | | | | | | | | |
_____________
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | |
| | | | | | | | | | | | | |
| | | | | | | | | NGL | | | | |
| | | | | | | Inlet | | Production | | | | |
| | | | | | | Capacity | | Capacity | | Ownership | | |
| | | | | | | | | | | | | |
The resulting products are then transported on truck or rail.
Ohio Valley Midstream provides residue natural gas take away options for our customers with interconnections to three interstate transmission pipelines.
| | | | | | | | | |
| Gathering (Bcf/d) | | 3.63 | | | 3.31 | | | 3.21 |
| Plant inlet natural gas volumes (Bcf/d) | | 0.52 | | | 0.43 | | | 0.33 |
| NGL production volumes (Mbbls/d) (2) | | 46 | | | 38 | | | 32 |
Blue Racer provides gathering, processing, and marketing service primarily under percentage of liquids and fixed fee agreements.
capacity, a 135 Mbbls/d NGL fractionation facility, approximately 950,000 barrels of NGL storage capacity, and other ancillary assets, including loading and terminal facilities.
This segment includes the Transco interstate natural gas pipeline that extends from the Gulf of Mexico to the eastern seaboard, as well as natural gas gathering, processing and treating, crude oil production handling, and NGL fractionation assets within the onshore, offshore shelf, and deepwater areas in and around the Gulf Coast states of Texas, Louisiana, Mississippi, and Alabama.
This segment also includes various petrochemical and feedstock pipelines in the Gulf Coast region.
Gas Gathering, Processing, and Treating Assets
The following tables summarize the significant consolidated assets of this segment:
| | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | |
You may read and copy any materials that we file with the SEC at the SEC’s Public Reference Room at 100 F Street, N.E., Washington, DC 20549.
You may obtain information on the operation of the Public Reference Room by calling the SEC at 1-800-SEC-0330.
You may also obtain such reports from the SEC’s Internet website at www.sec.gov.
As of December 31, 2017, our interstate gas pipelines and midstream interests were largely held through our significant investment in WPZ.
We own the general partner interest and a 74 percent limited partner interest in WPZ.
FINANCIAL INFORMATION ABOUT SEGMENTS
See Part II, “Item 8.
Substantially all our operations are conducted through our subsidiaries.
Our activities in 2017 were operated through the following reporting segments as presented in the accompanying financial statements and management’s discussion and analysis.
| • | Williams Partners — comprised of our consolidated master limited partnership, WPZ, which includes gas pipeline and midstream businesses. The gas pipeline business includes interstate natural gas pipelines and pipeline joint project investments. The midstream business provides natural gas gathering, treating, processing and compression services; NGL production, fractionation, storage, marketing and transportation; deepwater production handling and crude oil transportation services; an olefin production business (see Note 2 – |
Acquisitions and Divestitures of Notes to Consolidated Financial Statements), and is comprised of several wholly owned and partially owned subsidiaries and joint project investments.
| • | Other — comprised of business activities that are not operating segments, as well as corporate operations. Other also includes certain domestic olefins pipeline assets as well as certain Canadian assets, which included a liquids extraction plant located near Fort McMurray, Alberta, that began operations in March 2016, and a propane dehydrogenation facility which was under development. In September 2016, the Canadian assets were sold (see Note 2 – Acquisitions and Divestitures of Notes to Consolidated Financial Statements). |
Williams Partners
Gas Pipeline Business
Williams Partners’ gas pipeline businesses consist primarily of Transco and Northwest Pipeline.
Transco and Northwest Pipeline own and operate a combined total of approximately 13,600 miles of pipelines with a total annual throughput of approximately 4,533 TBtu of natural gas and peak-day delivery capacity of approximately 18.8 MMdth of natural gas.
Pipeline system and customers
Transco’s major natural gas transportation customers are public utilities and municipalities that provide service to residential, commercial, industrial and electric generation end users.
Bcf of natural gas.
Northwest Pipeline transports and stores natural gas for a broad mix of customers, including local natural gas distribution companies, municipal utilities, direct industrial users, electric power generators, and natural gas marketers and producers.
Northwest Pipeline’s firm transportation and storage contracts are generally long-term contracts with various expiration dates and account for the major portion of Northwest Pipeline’s business.
Additionally, Northwest Pipeline offers interruptible and short-term firm transportation service.
Midstream Business
Williams Partners’ midstream business, one of the nation’s largest natural gas gatherers and processors, has primary service areas concentrated in major producing basins in Arkansas, Colorado, New Mexico, Oklahoma, Texas, Wyoming, the Gulf of Mexico, Louisiana, Pennsylvania, West Virginia, New York, and Ohio.
The primary businesses are: (1) natural gas gathering, treating, and processing; (2) NGL fractionation, storage and transportation; (3) crude oil transportation; and (4) olefins production (see Note 2 – Acquisitions and Divestitures of Notes to Consolidated Financial Statements).
These fall within the middle of the process of taking raw natural gas and crude oil from the producing fields to the consumer.
If the minimum annual or semi-annual volume commitment is not met, these customers are obligated to pay a fee equal to
the applicable fee for each Mcf by which the applicable customer’s minimum annual or semi-annual volume commitment exceeds the actual volume gathered.
The revenue associated with such shortfall fees is generally recognized in the fourth quarter of each year.
Geographically, the midstream natural gas assets are positioned to maximize commercial and operational synergies with our other assets.
For example, most of the offshore gathering and processing assets attach and process or condition natural gas supplies delivered to the Transco pipeline.
Our San Juan basin, southwest Wyoming, and Piceance systems are capable of delivering residue gas volumes into Northwest Pipeline’s interstate system in addition to third-party interstate systems.
Our gathering systems in Pennsylvania delivers residue gas volumes into Transco’s pipeline in addition to third-party interstate systems.
The following table summarizes our significant consolidated natural gas gathering assets:
| | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Four Corners | Colorado & New Mexico | | 3,742 | | 1.8 | | 100% | | San Juan |
| Niobrara | Wyoming | | 224 | | 0.2 | | (4) | | Powder River |
| (2) | Statistics reflect 100 percent of the Beaver Creek assets in the consolidated Marcellus South gathering system. |
| (4) | Statistics reflect 100 percent of the assets from our 50 percent ownership of the Jackalope gathering system. |
An excerpt. Shown here: 40 of 128 rewritten, 40 of 151 added and 40 of 110 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2018 filing and the FY2017 filing.
Item 3. Legal Proceedings
6 rewritten, 12 added, 5 removed, 11 unchanged
On October 21, 2013, the [removed: EPA] [added: EPA, Region 6,] issued an Inspection Report pursuant to the Clean Air Act’s Risk Management Program following its inspection of the facility on June 24 through June 28, 2013.
On [removed: January 19,] [added: July 23,] 2018, we received an offer from the DOJ to globally settle the government’s claim for civil penalties associated with the alleged violations at both the Moundsville and the Oak Grove facilities for [removed: $1.955] [added: $1.6] million.
On May 5, 2017, we entered into a Consent Order with the Georgia Department of Natural Resources, Environmental Protection Division (GADNR) pertaining to alleged violations of the Georgia Water Quality Control Act and associated rules arising from a permit issued by GADNR for construction of [removed: the] [added: Transco’s] Dalton [removed: Project.][added: expansion project.]
Pursuant to the Consent Order, we paid a fine of $168,750 and agreed to perform a Corrective Action [removed: Order to remedy] [added: Plan,] the [removed: alleged violations.][added: completion of which is pending.]
Other environmental matters called for by this Item are described under the caption “Environmental Matters” in Note [removed: 17] [added: 18] – Contingent Liabilities and Commitments of Notes to Consolidated Financial Statements included under Part II, Item 8 Financial Statements of this report, which information is incorporated by reference into this Item.
The additional information called for by this Item is provided in Note [removed: 17] [added: 18] – Contingent Liabilities and Commitments of Notes to Consolidated Financial Statements included under Part II, Item 8 Financial Statements of this report, which information is incorporated by reference into this Item.
We are continuing to work with the agencies to resolve this matter.
On March 19, 2018, we received a Notice of Violation from the EPA, Region 8, regarding certain alleged violations of the Clean Air Act at our Ignacio Gas Plant in Durango, Colorado, following a previous on-site inspection of the facility.
We were subsequently informed that this matter has been referred to the DOJ for handling.
The Notice of Violation does not contain an initial penalty assessment.
We have responded to the alleged violations and continue to work with the agencies to resolve this matter.
On March 20, 2018, we also received a Notice of Violation from the EPA, Region 8, regarding certain alleged violations of the Clean Air Act at our Parachute Creek Gas Plant in Parachute, Colorado, following a previous on-site inspection of the facility.
We were informed that this matter has been referred to the DOJ for handling.
The Notice of Violation does not contain an initial penalty assessment.
We have responded to the alleged violations and continue to work with the agencies to resolve this matter.
On August 27, 2018, Northwest Pipeline LLC received a Notice of Violation/Cease and Desist Order from the Colorado Department of Public Health & Environment regarding certain alleged violations of the Colorado Water Quality Control Act and its General Permit under the Colorado Discharge Permit System related to its stormwater management practices at two construction sites.
The Notice of Violation does not contain an initial penalty assessment.
We have responded to the alleged violations and continue to work with the agency to resolve this matter.
We are currently evaluating the penalty assessment and the proposed global settlement offer and will respond to the agencies.
On January 19, 2018, we received notice from the PHMSA regarding certain alleged violations of PHMSA regulations in connection with a fire and release of liquid ethane that occurred at our Houston Meter Station located near Houston, Washington County, PA on December 24, 2014.
The Notice of Probable Violation and Proposed Civil Penalty issued by PHMSA alleges failure to timely notify the National Response Center of a release of a hazardous
liquid resulting in a fire or explosion and failure to verify that the facility was constructed, inspected, tested, and calibrated in accordance with comprehensive written specifications or standards and proposes a total civil penalty of $174,100.
We are currently evaluating the penalty assessment and will respond to the agency.
Cover and table of contents
36 rewritten, 14 added, 10 removed, 124 unchanged
| | For the fiscal year ended December 31, [removed: 2017] [added: 2018] |
Indicate by check mark whether the registrant has submitted electronically [removed: and posted on its corporate Web site, if any,] every Interactive Data File required to be submitted [removed: and posted] pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files).
The aggregate market value of the voting and non-voting common equity held by non-affiliates computed by reference to the price at which the common equity was last sold as of the last business day of the registrant’s most recently completed second quarter was approximately [removed: $24,993,673,967.][added: $21,489,112,717.]
The number of shares outstanding of the registrant’s common stock outstanding at February [removed: 19, 2018] [added: 15, 2019] was [removed: 827,327,336.][added: 1,210,981,263.]
Portions of the Registrant’s Definitive Proxy Statement for the Registrant’s Annual Meeting of Stockholders to be held on May [removed: 10, 2018,] [added: 9, 2019,] are incorporated into Part III, as specifically set forth in Part III.
| Item 1. | [removed: [Business](#sC3B842F71B9DF9F3CCFEED341592623E)] [added: [Business](#s95E6E192A97BE26351F9EB16E19B6424)] | [removed: [4](#sC3B842F71B9DF9F3CCFEED341592623E)] [added: [4](#s95E6E192A97BE26351F9EB16E19B6424)] |
| | [Website Access to Reports and Other [removed: Information](#s7D5F43C1A5E147AA913DED3415B04D30)] [added: Information](#s500F8CA67C702B2BAEE2EB16E1D943ED)] | [removed: [4](#s7D5F43C1A5E147AA913DED3415B04D30)] [added: [4](#s500F8CA67C702B2BAEE2EB16E1D943ED)] |
| | [Business [removed: Segments](#s9EC831D7582D87C102B9ED3416DCE1BC)] [added: Segments](#sB0D7F4D947F062258DAAEB16E2F27653)] | [removed: [4](#s9EC831D7582D87C102B9ED3416DCE1BC)] [added: [4](#sB0D7F4D947F062258DAAEB16E2F27653)] |
| | [Additional Business Segment [removed: Information](#s945B802BA746C1B646BDED3406ECDD63)] [added: Information](#s77324D761144956B91E7EB16D52CF9EC)] | [removed: [14](#s945B802BA746C1B646BDED3406ECDD63)] [added: [14](#s77324D761144956B91E7EB16D52CF9EC)] |
| | [Regulatory [removed: Matters](#sAEB570E3C831E9696D6CED3417865FEF)] [added: Matters](#s55C8C0D3ED8C71BE9017EB16E46883A1)] | [removed: [15](#sAEB570E3C831E9696D6CED3417865FEF)] [added: [15](#s55C8C0D3ED8C71BE9017EB16E46883A1)] |
| | [Environmental [removed: Matters](#sC4C4F47F75D2E39AFFC3ED3417A4AE06)] [added: Matters](#sF378FCF44E16C64B3FC5EB16E4971EE6)] | [removed: [17](#sC4C4F47F75D2E39AFFC3ED3417A4AE06)] [added: [17](#sF378FCF44E16C64B3FC5EB16E4971EE6)] |
| Item 1A. | [Risk [removed: Factors](#s69BA0CB293CC9CBD10BDED34184E6C4D)] [added: Factors](#sC53206FB55FFBE06DEA9EB16E533A4B4)] | [removed: [20](#s69BA0CB293CC9CBD10BDED34184E6C4D)] [added: [19](#sC53206FB55FFBE06DEA9EB16E533A4B4)] |
| Item 1B. | [Unresolved Staff [removed: Comments](#s6C9C264522FAA7F07665ED341880EE6B)] [added: Comments](#s7D2A39930F3F9EAD1D4AEB16E562B80C)] | [removed: [36](#s6C9C264522FAA7F07665ED341880EE6B)] [added: [33](#s7D2A39930F3F9EAD1D4AEB16E562B80C)] |
| Item 2. | [removed: [Properties](#s473228526EB7DB70AD12ED34189EE7F7)] [added: [Properties](#sB704BAB53D8AD743638DEB16E58174F6)] | [removed: [36](#s473228526EB7DB70AD12ED34189EE7F7)] [added: [33](#sB704BAB53D8AD743638DEB16E58174F6)] |
| Item 3. | [Legal [removed: Proceedings](#sDE1DE7EDD97A2292218CED3418D0E71D)] [added: Proceedings](#sE615200F9D30085612F6EB16E5C0A2F0)] | [removed: [36](#sDE1DE7EDD97A2292218CED3418D0E71D)] [added: [34](#sE615200F9D30085612F6EB16E5C0A2F0)] |
| Item 4. | [Mine Safety [removed: Disclosures](#s6BE4CA09885CA6EACEA3ED3418F8BF56)] [added: Disclosures](#s1C82D837E05582349CF7EB16E5DF2490)] | [removed: [37](#s6BE4CA09885CA6EACEA3ED3418F8BF56)] [added: [35](#s1C82D837E05582349CF7EB16E5DF2490)] |
| | [Executive Officers of the [removed: Registrant](#sF9A132383B132D344956ED34192AFA49)] [added: Registrant](#s8295B477412DB76A96F0EB16E60EC999)] | [removed: [38](#sF9A132383B132D344956ED34192AFA49)] [added: [36](#s8295B477412DB76A96F0EB16E60EC999)] |
| Item 5. | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#s6762210A85011A697389ED34197A3580)] [added: Securities](#s542B383604FA7F21ACAFEB16D8583E60)] | [removed: [42](#s6762210A85011A697389ED34197A3580)] [added: [38](#s542B383604FA7F21ACAFEB16D8583E60)] |
| Item 6. | [Selected Financial [removed: Data](#s7C6C1D2A139B6F4BB409ED3419980EB5)] [added: Data](#sDC8D24F7E3AFBAA83220EB16E68AEC74)] | [removed: [43](#s7C6C1D2A139B6F4BB409ED3419980EB5)] [added: [39](#sDC8D24F7E3AFBAA83220EB16E68AEC74)] |
| Item 7. | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#sD0759AECE5E17AF8D756ED3419F22EC5)] [added: Operations](#s60AD7BB6D61221C44457EB16E6D8F54A)] | [removed: [44](#sFC2B58C6083970DC6BFCED341A420277)] [added: [40](#s44D7952C02EAC237F2B2EB16E72643EB)] |
| Item 7A. | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#sD4C3212E9DB10F52BF30ED34073C3DD1)] [added: Risk](#s49E771E30FE06C47DAD4EB16D423F9A5)] | [removed: [75](#sD4C3212E9DB10F52BF30ED34073C3DD1)] [added: [72](#s49E771E30FE06C47DAD4EB16D423F9A5)] |
| Item 8. | [Financial Statements and Supplementary [removed: Data](#s9F7ED0145707F30F592BED341CD684D6)] [added: Data](#sFE0268083587F0B01BCFEB16EA42D969)] | [removed: [77](#s9F7ED0145707F30F592BED341CD684D6)] [added: [73](#sFE0268083587F0B01BCFEB16EA42D969)] |
| Item 9. | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure](#sF906C1039C4C0298E42CED3425DCB806)] [added: Disclosure](#s2603560A0D7B4C36FBF3EB16F366DC39)] | [removed: [154](#sF906C1039C4C0298E42CED3425DCB806)] [added: [149](#s2603560A0D7B4C36FBF3EB16F366DC39)] |
| Item 9A. | [Controls and [removed: Procedures](#sAE58E5272DBE8BEB8CDFED3425FAA82A)] [added: Procedures](#sC930A49570D8B69590A8EB16F385363E)] | [removed: [154](#sAE58E5272DBE8BEB8CDFED3425FAA82A)] [added: [149](#sC930A49570D8B69590A8EB16F385363E)] |
| Item 9B. | [Other [removed: Information](#s1B33F3530728E2588E81ED34262C74BE)] [added: Information](#s827981C81E8B4DE617AFEB16F3B4C2F8)] | [removed: [157](#s1B33F3530728E2588E81ED34262C74BE)] [added: [152](#s827981C81E8B4DE617AFEB16F3B4C2F8)] |
| Item 10. | [Directors, Executive Officers and Corporate [removed: Governance](#s6C9158E2076274F674A3ED34267C9821)] [added: Governance](#s72CDB6E0FB69C17901AAEB16D79C081D)] | [removed: [157](#s6C9158E2076274F674A3ED34267C9821)] [added: [152](#s72CDB6E0FB69C17901AAEB16D79C081D)] |
| Item 11. | [Executive [removed: Compensation](#s458E327EF408B777FEEFED3426A45137)] [added: Compensation](#s716B720DD720469038CEEB16F4316489)] | [removed: [157](#s458E327EF408B777FEEFED3426A45137)] [added: [152](#s716B720DD720469038CEEB16F4316489)] |
| Item 12. | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#s49CAE9973630EB327AADED3426D63ECB)] [added: Matters](#s00288FD1210E432EE4CDEB16F4603D90)] | [removed: [157](#s49CAE9973630EB327AADED3426D63ECB)] [added: [152](#s00288FD1210E432EE4CDEB16F4603D90)] |
| Item 13. | [Certain Relationships and Related Transactions, and Director [removed: Independence](#s800633FE722E723BED47ED3426F42A64)] [added: Independence](#s60D52A122AE24DE95D78EB16F47F93A4)] | [removed: [158](#s800633FE722E723BED47ED3426F42A64)] [added: [153](#s60D52A122AE24DE95D78EB16F47F93A4)] |
| Item 14. | [Principal Accountant Fees and [removed: Services](#s829E3B042DCCF4A5347CED3427261C08)] [added: Services](#s13727A26761772371C14EB16F4AE9E4A)] | [removed: [158](#s829E3B042DCCF4A5347CED3427261C08)] [added: [153](#s13727A26761772371C14EB16F4AE9E4A)] |
| Item 15. | [Exhibits and Financial Statement [removed: Schedules](#s614F9EE5CBA54C2CD154ED340A48C404)] [added: Schedules](#sCFB6F45D1E7A266467B0EB16D72F9A6E)] | [removed: [159](#s614F9EE5CBA54C2CD154ED340A48C404)] [added: [154](#sCFB6F45D1E7A266467B0EB16D72F9A6E)] |
| Item 16. | [Form 10-K [removed: Summary](#s5d39f9c7e8fe47ef96bb64d7257f2da1)] [added: Summary](#s2DAFCE88FCE2E021F406EB16F52A8A3D)] | [removed: [168](#s5d39f9c7e8fe47ef96bb64d7257f2da1)] [added: [163](#s2DAFCE88FCE2E021F406EB16F52A8A3D)] |
MMdth: One million dekatherms or [removed: approximately] one trillion British thermal units
Partially Owned Entities: Entities in which we do not own a 100 percent ownership interest and which, as of December 31, [removed: 2017,] [added: 2018,] we account for as an equity-method investment, including principally the following:
ACMP: Access Midstream Partners, L.P. prior to its [added: 2015] merger with Pre-Merger WPZ
[added: ETE] Merger Agreement: Merger Agreement and Plan of Merger of Williams with Energy Transfer [added: Equity, L.P.] and certain of its [added: affiliates]
10-K 1 wmb_20181231x10k.htm 10-K
| | [General](#sBFA6F20A7BD3A1F6EE15EB16E1F8CF5C) | [4](#sBFA6F20A7BD3A1F6EE15EB16E1F8CF5C) |
| | [Northeast G&P](#s14BDDC216F5B8A3A7ACFEB16E32167C9) | [5](#s14BDDC216F5B8A3A7ACFEB16E32167C9) |
| | [Atlantic-Gulf](#sF0E4B5AFD98C1D683C72EB16E3402007) | [7](#sF0E4B5AFD98C1D683C72EB16E3402007) |
| | [West](#s452AF91C35F4A31B8C15EB16E36F3391) | [10](#s452AF91C35F4A31B8C15EB16E36F3391) |
| | [Other](#s7F7266CA7B8DE1C2A48CEB16E41AD4E9) | [12](#s7F7266CA7B8DE1C2A48CEB16E41AD4E9) |
| | [Service Assets, Customers, and Contracts](#s76037D57C6BFF8AE8237EB16E3CC80E1) | [12](#s76037D57C6BFF8AE8237EB16E3CC80E1) |
| | [Competition](#s01B6BDC1F1BFD8EDC8F2EB16E4C65C64) | [18](#s01B6BDC1F1BFD8EDC8F2EB16E4C65C64) |
| | [Employees](#s81C556BE9BB595B704F7EB16E4E5FC87) | [18](#s81C556BE9BB595B704F7EB16E4E5FC87) |
WPZ: Williams Partners L.P. Effective August 10, 2018, we completed our merger with WPZ, pursuant to which we acquired all outstanding common units of WPZ held by others and Williams continued as the surviving entity.
Brazos Permian II: Brazos Permian II, LLC
RMM: Rocky Mountain Midstream Holdings LLC
Geismar Incident: An explosion and fire which occurred on June 13, 2013, at our formerly owned Geismar olefins plant and rendered the facility temporarily inoperable.
WPZ Merger: The August 10, 2018, merger transactions pursuant to which we acquired all outstanding common units of WPZ held by others, merged WPZ into Williams, and Williams continued as the surviving entity.
10-K 1 wmb_20171231x10k.htm 10-K
| | | | | (Do not check if a smaller reporting company) | | | | |
| | [General](#s3F96111E69F8160F33CEED3415E24504) | [4](#s3F96111E69F8160F33CEED3415E24504) |
| | [Financial Information About Segments](#s41447FB84C5C9F796302ED3416AA90E8) | [4](#s41447FB84C5C9F796302ED3416AA90E8) |
| | [Williams Partners](#sC15442525A7E36F9A504ED3417041126) | [5](#sC15442525A7E36F9A504ED3417041126) |
| | [Competition](#s9A93322D0AA2F28CCC69ED3417D6B57A) | [18](#s9A93322D0AA2F28CCC69ED3417D6B57A) |
| | [Employees](#s023459CDD0FFDC69EE6BED3417FE9B67) | [19](#s023459CDD0FFDC69EE6BED3417FE9B67) |
| | [Financial Information about Geographic Areas](#s00DDDDDB0794688A7800ED3418302DA7) | [19](#s00DDDDDB0794688A7800ED3418302DA7) |
WPZ: Williams Partners L.P.
affiliates
Item 4. Mine Safety Disclosures
10 rewritten, 40 added, 30 removed, 5 unchanged
The name, [added: title,] age, period of service, and [removed: title] [added: recent business experience] of each of our executive officers as of February [removed: 22, 2018,] [added: 21, 2019,] are listed below.
| Alan S. Armstrong | [added: | 56 | | 2011 to present | |] Director, Chief Executive Officer, and [removed: President] [added: President, The Williams Companies, Inc.] |
| Walter J. Bennett | [added: | 49 | | 2015 to present | |] Senior Vice [removed: President - West] [added: President- West, The Williams Companies, Inc.] |
| John D. Chandler | [added: | 49 | | 2017 to present | |] Senior Vice President and Chief Financial [removed: Officer] [added: Officer, The Williams Companies, Inc.] |
| Micheal G. Dunn | [added: | 53 | | 2017 to present | |] Executive Vice President and Chief Operating [removed: Officer] [added: Officer, The Williams Companies, Inc.] |
| John E. Poarch | [added: | 53 | | 2017 to present | |] Senior Vice President - Engineering [removed: Services] [added: Services, The Williams Companies, Inc.] |
| James E. Scheel | [added: | 54 | | 2014 to present | |] Senior Vice President - Northeast [removed: G&P] [added: G&P, The Williams Companies, Inc.] |
| Ted T. Timmermans | [added: | 62 | | 2005 to present | |] Vice President, Controller, and Chief Accounting [removed: Officer] [added: Officer, The Williams Companies, Inc.] |
| [removed: T. Lane Wilson] [added: Senior Vice President and General Counsel] | [added: | | | 2017 to 2018 | |] Senior Vice President, General [removed: Counsel] [added: Counsel,] and Chief Compliance [removed: Officer] [added: Officer, The Williams Companies, Inc.] |
| Chad J. Zamarin | [added: | 42 | | 2017 to present | |] Senior Vice President - Corporate Strategic [removed: Development] [added: Development, The Williams Companies, Inc.] |
| | | | | | | |
| --- | --- | --- | --- | --- | --- | --- |
| | | | | | | |
| Name and Title | | Age | | Period of Service | | Business Experience in Past Five Years |
| Director, Chief Executive Officer, and President | | | | 2015 to 2018 | | Chairman of the Board, ACMP/WPZ |
| | | | | 2014 to 2018 | | Chief Executive Officer, ACMP/WPZ |
| | | | | 2012 to 2018 | | Director of the general partner, ACMP/WPZ |
| | | | | 2011 to 2015 | | Chairman of the Board and Chief Executive Officer of the general partner of Pre-merger WPZ |
| Senior Vice President - West | | | | 2013 to 2018 | | Senior Vice President - West of the general partner, ACMP/WPZ |
| | | | | 2017 | | Director of the general partner, ACMP/WPZ |
| | | | | 2015 | | Senior Vice President - West of the general partner, Pre-merger WPZ |
| Senior Vice President and Chief Financial Officer | | | | 2017 to 2018 | | Director of the general partner, ACMP/WPZ |
| | | | | 2009 to 2014 | | Senior Vice President and Chief Financial Officer, Magellan GP, LLC |
| Debbie Cowan | | 41 | | 2018 to present | | Senior Vice President - Chief Human Resources Officer, The Williams Companies, Inc. |
| Senior Vice President - Chief Human Resources Officer | | | | 2013 to 2018 | | Global Vice President of Human Resources, Koch Chemical Technology Group, LLC |
| Executive Vice President and Chief Operating Officer | | | | 2017 to 2018 | | Director of the general partner, ACMP/WPZ |
| | | | | 2015 to 2017 | | President / Executive Vice President, Questar Pipeline / Questar Corporation |
| | | | | 2010 to 2015 | | President and Chief Executive Officer, PacifiCorp Energy |
| Scott A. Hallam | | 42 | | 2019 to present | | Senior Vice President - Atlantic-Gulf, The Williams Companies, Inc. |
| Senior Vice President - Atlantic-Gulf | | | | 2017 to 2019 | | Vice President GM Atlantic-Gulf, The Williams Companies, Inc. |
| | | | | 2015 to 2017 | | Vice President Northeast OA, The Williams Companies, Inc. |
| | | | | 2013 to 2015 | | General Manager - Utica, ACMP |
| Senior Vice President - Engineering Services | | | | 2017 | | Vice President - Commercial - West, The Williams Companies, Inc. |
| | | | | 2015 to 2017 | | Vice President - Commercial & Business Development, The Williams Companies, Inc. |
| | | | | 2011 to 2015 | | General Manager - Eagle Ford, ACMP |
| | | | | | | |
| --- | --- | --- | --- | --- | --- | --- |
| | | | | | | |
| Name and Title | | Age | | Period of Service | | Business Experience in Past Five Years |
| Senior Vice President - Northeast G&P | | | | 2015 to 2017 | | Director of the general partner, ACMP/WPZ |
| | | | | 2012 to 2015 | | Director of the general partner, Pre-merger WPZ |
| | | | | 2012 to 2014 | | Director of the general partner, Pre-merger ACMP |
| | | | | 2012 to 2014 | | Senior Vice President - Corporate Strategic Development, The Williams Companies, Inc. |
| | | | | 2012 to 2014 | | Senior Vice President - Corporate Strategic Development of the general partner, Pre-merger WPZ |
| Vice President, Controller, and Chief Accounting Officer | | | | 2015 to 2018 | | Vice President, Controller, and Chief Accounting Officer of the general partner, ACMP/WPZ |
| T. Lane Wilson | | 52 | | 2018 to present | | Senior Vice President and General Counsel, The Williams Companies, Inc. |
| | | | | 2009 to 2017 | | United States Magistrate Judge for the Northern District of Oklahoma |
| Senior Vice President - Corporate Strategic Development | | | | 2017 to 2018 | | Director of the general partner, ACMP/WPZ |
| | | | | 2014 to 2017 | | President - Pipeline and Midstream, Cheniere Energy |
| | | | | 2011 to 2014 | | Chief Operating Officer, NiSource Midstream, LLC and NiSource Energy Ventures, LLC |
| | |
| --- | --- |
| | Age: 55 |
| | Position held since January 2011. |
| | Mr. Armstrong has served as our Chief Executive Officer and President and a director of Williams since January 2011. Mr. Armstrong has served as a director of the general partner of ACMP/WPZ since 2012, as Chief Executive Officer of ACMP/WPZ since December 31, 2014, and as Chairman of the Board of ACMP/WPZ since February 2, 2015. Mr. Armstrong also served as Chairman of the Board and Chief Executive Officer of the general partner of Pre-merger WPZ from 2011 until the ACMP Merger, as Senior Vice President - Midstream of Pre-merger WPZ from 2010 to 2011, and a director and Chief Operating Officer of Pre-merger WPZ from 2005 to 2010. From 2002 to 2011, Mr. Armstrong served as Williams’ Senior Vice President - Midstream and acted as president of our midstream business. From 1999 to 2002, Mr. Armstrong was Vice President, Gathering and Processing in our midstream business and from 1998 to 1999 was Vice President, Commercial Development. Mr. Armstrong has served as a director of BOK Financial Corporation, a financial services company, since 2013. |
| | Age: 48 |
| | Position held since January 2015. |
| | Mr. Bennett has served as our Senior Vice President - West since January 2015. Mr. Bennett has served as Senior Vice President - West of the general partner of ACMP/WPZ since December 2013 and as Senior Vice President - West of the general partner of Pre-merger WPZ from January 2015 until the ACMP Merger. Mr. Bennett previously served as a director of the general partner of ACMP/WPZ from February 2017 through November 2017. Mr. Bennett was formerly Chief Operating Officer of Chesapeake Midstream Development and served as Senior Vice President - Operations at Boardwalk Pipeline Partners. |
| | Position held since September 2017. |
| | Mr. Chandler has served as our Senior Vice President and Chief Financial Officer since September 2017, and as a director of the general partner of ACMP/WPZ since November 2017. Mr. Chandler most recently served as Senior Vice President and Chief Financial Officer of Magellan GP, LLC, the general partner of Magellan Midstream Partners, LP from 2009 until his retirement in March 2014. From 2003 until 2009, he served as Senior Vice President and Chief Financial Officer for the general partner of Magellan Midstream Holdings, L.P. From 1992 until 2002, Mr. Chandler held various accounting and finance roles within Williams and MAPCO Inc., prior to its acquisition by Williams. Mr. Chandler has served as a director of Matrix Service Company since June 2017. |
| | Age: 52 |
| | Position held since February 2017. |
| | Mr. Dunn has served as our Executive Vice President and Chief Operating Officer and as a director of the general partner of ACMP/WPZ since February 2017. Previously, Mr. Dunn served as President of Questar Pipeline and as Executive Vice President of Questar Corporation from 2015 through 2017. Prior to that, Mr. Dunn served as President and Chief Executive Officer of PacifiCorp Energy from 2010 through 2015, a subsidiary of Berkshire Hathaway Energy. Earlier, Mr. Dunn was president of Kern River Gas Transmission Company, a Berkshire Hathaway Energy interstate natural gas pipeline subsidiary. He joined Kern River in 1990, having served in various leadership roles in the areas of operations, construction, engineering and information technology before being named President of Kern River in 2007. Mr. Dunn began his career with Williams as an operations engineer and spent 14 years with the company in a variety of technical and leadership roles. |
| Frank J. Ferazzi | Senior Vice President - Atlantic Gulf |
| | Age: 61 |
| | Position held since June 2017 |
| | Mr. Ferazzi has served as our Senior Vice President - Atlantic-Gulf since June 2017. Previously, Mr. Ferazzi served as VP & GM Eastern Interstates from November 2014 through June 2017, and previously as VP & GM Transco from January 2013 through January 2015. Prior to that, Mr. Ferazzi served as VP Commercial Operations - Gas Pipeline from May 2010 through December 2012. |
| | Position held since November 2017. |
| | Mr. Poarch has served as our Senior Vice President - Engineering Services since November 2017. Previously, he served as VP Commercial West OA from March 2017 through November 2017, and before that, as VP Commercial & Business Development from January 2015 through March 2017. Previously, Mr. Poarch was the general manager for Access Midstream’s Eagle Ford operations. |
| | Age: 53 |
| | Position held since January 2014. |
| | Mr. Scheel has served as our Senior Vice President - Northeast G&P since January 2014. Mr. Scheel served as a director of ACMP/WPZ from the ACMP Merger until November 2017. Mr. Scheel served as a director of the Pre-merger WPZ general partner from 2012 until the ACMP Merger. Mr. Scheel served as a director of the Pre-merger ACMP general partner from December 2012 to February 2014. Previously, Mr. Scheel served as Senior Vice President - Corporate Strategic Development of Williams and the Pre-merger WPZ general partner from February 2012 to January 2014. Mr. Scheel served as Vice President of Business Development of Williams’ midstream business from January 2011 to February 2012. |
| | Position held since July 2005. |
| | Mr. Timmermans has served as our Vice President, Controller, and Chief Accounting Officer since July 2005. Mr. Timmermans has served in the same roles for the general partner of ACMP/WPZ since the ACMP Merger. Mr. Timmermans served as Chief Accounting Officer of WMZ from 2008 until its merger with Pre-Merger WPZ in 2010. Previously, Mr. Timmermans served as our Assistant Controller from 1998 to 2005. |
| | Age: 51 |
| | Position held since April 2017. |
| | Mr. Wilson has served as Senior Vice President, General Counsel and Chief Compliance Officer since April 2017. Prior to joining Williams, Mr. Wilson served as a United States Magistrate Judge for the Northern District of Oklahoma from 2009 until he joined Williams in April 2017. Mr. Wilson previously served as a shareholder and member of the board of directors of the Hall Estill law firm from 1994 through 2008. |
| | Age: 41 |
| | Position held since June 2017. |
| | Mr. Zamarin has served as our Senior Vice President - Corporate Strategic Development since June 2017. Mr. Zamarin has served as a director of the general partner of ACMP/WPZ since November 2017. Previously, he served as President, Pipeline and Midstream at Cheniere Energy from 2014 through 2017. Prior to joining Cheniere, Mr. Zamarin served as the Chief Operating Officer at NiSource Midstream, LLC and NiSource Energy Ventures, LLC, as well as the President of Pennant Midstream, LLC, a joint venture with Hilcorp Energy. |
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
5 rewritten, 3 added, 20 removed, 5 unchanged
Our common stock is listed on the New York Stock Exchange under the symbol “WMB.” At the close of business on February [removed: 19, 2018,] [added: 15, 2019,] we had [removed: approximately 6,979] [added: 6,780] holders of record of our common stock.
Set forth below is a line graph comparing our cumulative total stockholder return on our common stock (assuming reinvestment of dividends) with the cumulative total return of the S&P 500 Stock Index and the Bloomberg Americas Pipelines Index for the period of five fiscal years commencing January 1, [removed: 2013.][added: 2014.]
The Bloomberg Americas Pipelines Index is composed of Enbridge Inc., Kinder Morgan, Inc., TransCanada Corporation, ONEOK, Inc., Pembina Pipeline Corporation, Cheniere Energy, Inc., Targa Resources Corp., Inter Pipeline Ltd., Keyera Corp., [removed: AltaGas Ltd., Plains GP Holdings,] [added: Tallgrass Energy] L.P., and Williams.
[removed: 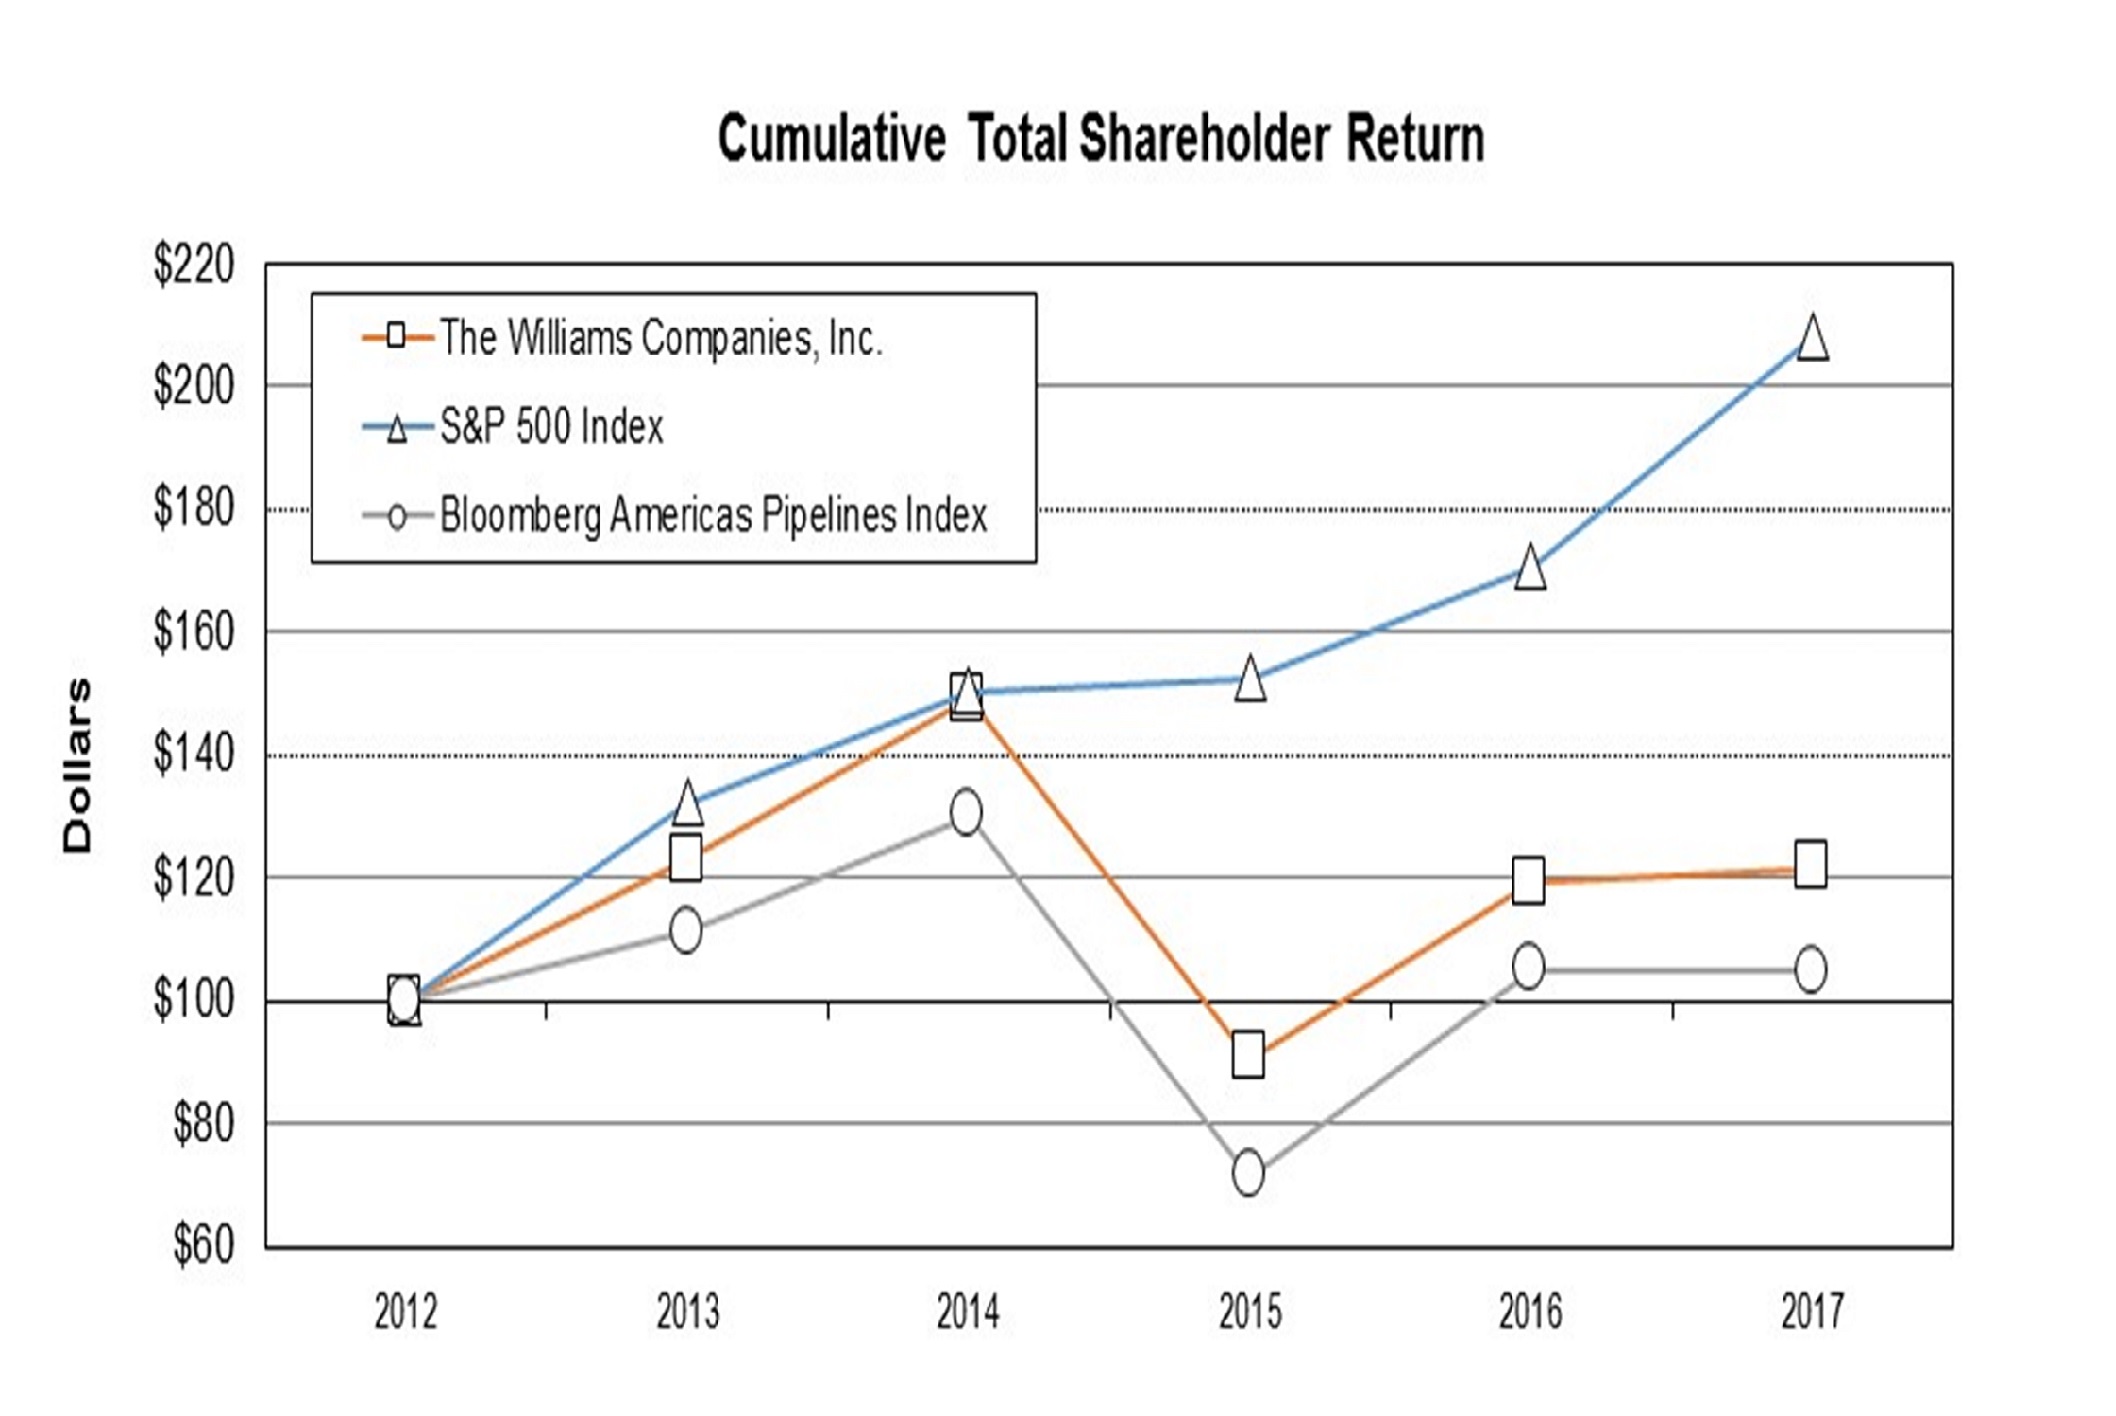][added: ]
| | [removed: 2012 | |] 2013 | | 2014 | | 2015 | | 2016 | | 2017 | [added: | 2018 |]
| The Williams Companies, Inc. | 100.0 | | 121.4 | | 73.8 | | 97.0 | | 98.9 | | 75.3 |
| S&P 500 Index | 100.0 | | 113.7 | | 115.2 | | 129.0 | | 157.2 | | 150.3 |
| Bloomberg Americas Pipelines Index | 100.0 | | 117.1 | | 64.4 | | 94.5 | | 94.3 | | 80.8 |
The high and low sales price ranges (New York Stock Exchange composite transactions) and dividends declared by quarter for each of the past two years are as follows:
| | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | High | | | | Low | | | | Dividend | | |
| 2017 | | | | | | | | | | | |
| First Quarter | $ | 32.69 | | | $ | 27.68 | | | $ | 0.30 | |
| Second Quarter | 31.25 | | | | 27.65 | | | | 0.30 | | |
| Third Quarter | 32.18 | | | | 28.76 | | | | 0.30 | | |
| Fourth Quarter | 30.72 | | | | 26.82 | | | | 0.30 | | |
| 2016 | | | | | | | | | | | |
| First Quarter | $ | 26.68 | | | $ | 10.22 | | | $ | 0.64 | |
| Second Quarter | 23.89 | | | | 14.60 | | | | 0.64 | | |
| Third Quarter | 31.43 | | | | 19.68 | | | | 0.20 | | |
| Fourth Quarter | 32.21 | | | | 27.35 | | | | 0.20 | | |
Some of our subsidiaries’ borrowing arrangements may limit the transfer of funds to us.
These terms have not impeded, nor are they expected to impede, our ability to pay dividends.
On February 21, 2018, our board of directors approved a regular quarterly dividend of $0.34 per share payable on March 26, 2018.
| The Williams Companies, Inc. | 100.0 | | 122.8 | | 149.1 | | 90.6 | | 119.1 | | 121.5 |
| S&P 500 Index | 100.0 | | 132.4 | | 150.5 | | 152.5 | | 170.8 | | 208.1 |
| Bloomberg Americas Pipelines Index | 100.0 | | 111.0 | | 130.0 | | 71.5 | | 105.0 | | 104.7 |
Item 6. Selected Financial Data
14 rewritten, 3 added, 6 removed, 25 unchanged
The following financial data at December 31, [removed: 2017] [added: 2018] and [removed: 2016,] [added: 2017,] and for each of the three [added: preceding] years in the period ended December 31, [removed: 2017,] [added: 2018,] should be read in conjunction with the other financial information included in Part II, Item 7, Management’s Discussion and Analysis of Financial Condition and Results of Operations and Part II, Item 8, Financial Statements and Supplementary Data of this Form 10-K.
| | [removed: 2017] [added: 2018] | | | | [removed: 2016] [added: 2017] | | | | [removed: 2015] [added: 2016] | | | | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | |
| Revenues [removed: (1)] | $ | [removed: 8,031] [added: 8,686] | | | $ | [removed: 7,499] [added: 8,031] | | | $ | [removed: 7,360] [added: 7,499] | | | $ | [removed: 7,637] [added: 7,360] | | | $ | [removed: 6,860] [added: 7,637] | |
| [removed: Income] [added: Net income] (loss) from continuing operations [removed: (2)] [added: (1)] | [added: 193 | | | |] 2,509 | | | | (350 | | ) | | (1,314 | | ) | | 2,335 | | | [removed: | 679 | | |]
| [removed: Income] [added: Net income] (loss) from continuing operations [removed: (2)] [added: (1)] | [added: (155 | | ) | |] 2,174 | | | | (424 | | ) | | (571 | | ) | | 2,110 | | | [removed: | 441 | | |]
| [removed: Income] [added: Net income] (loss) from continuing operations [removed: (2)] [added: (1)] | [added: (.16 | | ) | |] 2.62 | | | | (.57 | | ) | | (.76 | | ) | | 2.91 | | | [removed: | .64 | | |]
| Total assets at December 31 [removed: (3)] | [removed: 46,352] [added: 45,302] | | | | [removed: 46,835] [added: 46,352] | | | | [removed: 49,020] [added: 46,835] | | | | [removed: 50,455] [added: 49,020] | | | | [removed: 27,065] [added: 50,455] | | |
| Commercial paper and long-term debt due within one year at December 31 [removed: (4)] | [removed: 501] [added: 47] | | | | [removed: 878] [added: 501] | | | | [removed: 675] [added: 878] | | | | [removed: 802] [added: 675] | | | | [removed: 226] [added: 802] | | |
| Long-term debt at December 31 [removed: (3)] | [removed: 20,434] [added: 22,367] | | | | [removed: 22,624] [added: 20,434] | | | | [removed: 23,812] [added: 22,624] | | | | [removed: 20,780] [added: 23,812] | | | | [removed: 11,276] [added: 20,780] | | |
| Stockholders’ equity at December 31 [removed: (3) (5)] [added: (2)] | [removed: 9,656] [added: 14,660] | | | | [removed: 4,643] [added: 9,656] | | | | [removed: 6,148] [added: 4,643] | | | | [removed: 8,777] [added: 6,148] | | | | [removed: 4,864] [added: 8,777] | | |
| Cash dividends declared per common share | [removed: 1.200] [added: 1.360] | | | | [removed: 1.680] [added: 1.200] | | | | [removed: 2.450] [added: 1.680] | | | | [removed: 1.958] [added: 2.450] | | | | [removed: 1.438] [added: 1.958] | | |
| [removed: (2)] [added: (1)] | [removed: Income] [added: Net income] (loss) from continuing operations: |
| • | For 2014 includes $2.5 billion pre-tax gain recognized as a result of remeasuring to fair value the equity-method investment we held before we acquired a controlling interest in ACMP, $246 million of insurance recoveries related to the 2013 Geismar Incident, and $154 million of cash received related to a contingency settlement. 2014 also includes $78 million of pre-tax equity losses from Bluegrass Pipeline and Moss Lake related primarily to the underlying write-off of previously capitalized project development costs and $76 million of pre-tax acquisition, merger, and transition expenses related to our acquisition of [removed: ACMP;] [added: ACMP.] |
[removed: | (5) |] [added: -] The increase in 2017 includes our issuance of common stock as part of our Financial Repositioning. [removed: |]
| • | For 2018 includes a $1.849 billion impairment of certain assets located in the Barnett Shale region, partially offset by a $591 million gain on the sale of our Four Corners area assets, a $141 million gain on the deconsolidation of certain Permian assets, and a $101 million gain from the sale of our Gulf Coast pipeline system assets; |
| (2) | Stockholders’ equity at December 31: |
- The increase in 2018 reflects our merger with WPZ;
| | |
| --- | --- |
| (1) | Revenues for 2014 increased reflecting the consolidation of ACMP beginning in third quarter and new Canadian construction management services. |
| • | For 2013 includes $99 million of deferred income tax expense incurred on undistributed earnings of our foreign operations that are no longer considered permanently reinvested. |
| (3) | The increases in 2014 reflect assets acquired and debt assumed primarily related to our acquisition of ACMP in third quarter as well as $1.9 billion of related debt issuances and $2.8 billion of debt issuances at WPZ. Additionally, we issued $3.4 billion of equity. |
| (4) | The increase in 2014 reflects borrowings under WPZ’s commercial paper program, which was initiated in 2013. |
Item 8. Financial Statements and Supplementary Data
801 rewritten, 580 added, 439 removed, 1,540 unchanged
[added: |] The Williams Companies, Inc. [added: | | | | |]
We have audited the accompanying consolidated balance sheet of The Williams Companies, Inc. (the [removed: “Company”)] [added: Company)] as of December 31, [removed: 2017] [added: 2018] and [removed: 2016,] [added: 2017,] the related consolidated statements of operations, comprehensive income (loss), changes in equity and cash flows for each of the three years in the period ended December 31, [removed: 2017,] [added: 2018,] and the related notes and [added: the] financial statement [removed: schedules] [added: schedule] listed in the index at Item 15(a) (collectively referred to as the “consolidated financial statements”).
In our opinion, based on our audits and the reports of other auditors, the consolidated financial statements present fairly, in all material respects, the consolidated financial position of the Company at December 31, [removed: 2017] [added: 2018] and [removed: 2016,] [added: 2017,] and the consolidated results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2017,] [added: 2018,] in conformity with U.S. generally accepted accounting principles.
We did not audit the financial statements of Gulfstream Natural Gas System, L.L.C. [removed: (“Gulfstream”),] [added: (Gulfstream),] a limited liability corporation in which the Company has a 50 percent interest.
In the consolidated financial statements, the Company’s investment in Gulfstream was [removed: $244] [added: $225] million and [removed: $261] [added: $244] million as of December 31, [removed: 2017] [added: 2018] and [removed: 2016,] [added: 2017,] respectively, and the Company’s equity earnings in the net income of Gulfstream were $75 million in [removed: 2017, $69] [added: 2018, $75] million in [removed: 2016] [added: 2017] and [removed: $65] [added: $69] million in [removed: 2015.][added: 2016.]
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) [removed: (“PCAOB”),] [added: (PCAOB),] the [removed: Company’s] [added: Company's] internal control over financial reporting as of December 31, [removed: 2017,] [added: 2018,] based on criteria established in Internal [removed: Control - Integrated] [added: Control-Integrated] Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated February [removed: 22, 2018] [added: 21, 2019] expressed an unqualified opinion thereon.
We have audited the balance [removed: sheet] [added: sheets] of Gulfstream Natural Gas System, L.L.C. (the “Company”) as of December 31, [added: 2018 and] 2017, and the related statements of operations, comprehensive income, cash flows, and members’ equity for the [removed: year] [added: years] then ended, including the related notes (collectively referred to as the “financial statements;” not presented herein).
In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of December 31, [added: 2018 and] 2017, and the results of its operations and its cash flows for the [removed: year] [added: years] then ended in conformity with accounting principles generally accepted in the United States of America.
Our responsibility is to express an opinion on the Company’s financial statements based on our [removed: audit.][added: audits.]
We conducted our [removed: audit] [added: audits] of these financial statements in accordance with the standards of the PCAOB and in accordance with auditing standards generally accepted in the United States of America.
Our [removed: audit] [added: audits] included performing procedures to assess the risks of material misstatement of the financial statements, whether due to error or fraud, and performing procedures that respond to those risks.
Our [removed: audit] [added: audits] also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statements.
We have audited the [removed: balance sheet of Gulfstream Natural Gas System, L.L.C. (the "Company") as of December 31, 2016, and the related] statement of operations, comprehensive income, cash flows, and members’ equity [removed: for each] of [removed: the two years in] [added: Gulfstream Natural Gas System, L.L.C. (the "Company") for] the period ended December 31, 2016.
Our responsibility is to express an opinion on these financial statements based on our [removed: audits.][added: audit.]
We conducted our [removed: audits] [added: audit] in accordance with the standards of the Public Company Accounting Oversight Board (United States) and in accordance with auditing standards generally accepted in the United States of America.
Our [removed: audits] [added: audit] included consideration of internal control over financial reporting as a basis for designing audit procedures that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the effectiveness of the Company's internal control over financial reporting.
In our opinion, such financial statements present fairly, in all material respects, the [removed: financial position] [added: results] of [added: operations of] Gulfstream Natural Gas System, L.L.C. [removed: as of December 31, 2016,] and [removed: the results of] its [removed: operations and its] cash flows for [removed: each of] the [removed: two years in the] period ended December 31, 2016, in conformity with accounting principles generally accepted in the United States of America.
| | | [removed: 2017] [added: 2018] | | | | [removed: 2016] [added: 2017] | | | | [removed: 2015] [added: 2016] | | |
| Service revenues | | $ | [removed: 5,312] [added: 5,502] | | | $ | [removed: 5,171] [added: 5,312] | | | $ | [removed: 5,164] [added: 5,171] | |
| Product sales | | [removed: 2,719] [added: 2,784] | | | | [removed: 2,328] [added: 2,719] | | | | [removed: 2,196] [added: 2,328] | | |
| Total revenues | | [removed: 8,031] [added: 8,686] | | | | [removed: 7,499] [added: 8,031] | | | | [removed: 7,360] [added: 7,499] | | |
| Product costs | | [removed: 2,300] [added: 2,707] | | | | [removed: 1,725] [added: 2,300] | | | | [removed: 1,779] [added: 1,725] | | |
| Operating and maintenance expenses | [removed: | 1,585] [added: 1,507] | | | | [removed: 1,580] [added: 1] | | | | [removed: 1,655] [added: 1,508] | | |
| Depreciation and amortization expenses | | [removed: 1,736] [added: 1,725] | | | | [removed: 1,763] [added: 1,736] | | | | [removed: 1,738] [added: 1,763] | | |
| Selling, general, and administrative expenses | | [removed: 608] [added: 569] | | | | [removed: 723] [added: 594] | | | | [removed: 741] [added: 722] | | |
| Impairment of certain assets (Note [removed: 16)] [added: 17)] | | [removed: 1,248] [added: 1,915] | | | | [removed: 873] [added: 1,248] | | | | [removed: 209] [added: 873] | | |
| Gain on sale of [removed: Geismar Interest] [added: certain assets] (Note [removed: 2)] [added: 3)] | | [removed: (1,095] [added: (692] | | ) | | [removed: —] [added: (1,095] | | [added: )] | | — | | |
| Regulatory charges resulting from Tax Reform (Note 1) | | [removed: 674] [added: (17] | | [added: )] | | [removed: —] [added: 674] | | | | — | | |
| Other [removed: (income) expense] [added: income (expense)] – net | | [removed: 80] [added: 92] | | | | [removed: 142] [added: (25] | | [added: )] | | [removed: 40] [added: 85] | | |
| Total costs and expenses | [removed: | 7,127] [added: 7,918] | | | | [removed: 6,799] [added: (56] | | [added: )] | | [removed: 7,134] [added: 7,862] | | |
| Equity earnings (losses) | | [removed: 434] [added: 396] | | | | [removed: 397] [added: 434] | | | | [removed: 335] [added: 397] | | |
| Impairment of equity-method investments (Note [removed: 16)] [added: 17)] | | [removed: —] [added: (32] | | [added: )] | | [removed: (430] [added: —] | | [removed: )] | | [removed: (1,359] [added: (430] | | ) |
| Other investing income (loss) – net | | [removed: 282] [added: 219] | | | | [removed: 63] [added: 282] | | | | [removed: 27] [added: 63] | | |
| Interest incurred | | [removed: (1,116] [added: (1,160] | | ) | | [removed: (1,217] [added: (1,116] | | ) | | [removed: (1,118] [added: (1,217] | | ) |
| Interest capitalized | | [removed: 33] [added: 48] | | | | [removed: 38] [added: 33] | | | | [removed: 74] [added: 38] | | |
| Other [removed: income (expense)] [added: (income) expense] – net | | [removed: (2] [added: 67] | | [removed: )] | | [removed: 74] [added: 71] | | | | [removed: 102] [added: 135] | | |
| Income (loss) before income taxes | | [removed: 535] [added: 331] | | | | [removed: (375] [added: 535] | | [removed: )] | | [removed: (1,713] [added: (375] | | ) |
| Provision (benefit) for income taxes | | [removed: (1,974] [added: 138] | | [removed: )] | | [removed: (25] [added: (1,974] | | ) | | [removed: (399] [added: (25] | | ) |
| Net income (loss) | | [removed: 2,509] [added: 193] | | | | [removed: (350] [added: 2,509] | | [removed: )] | | [removed: (1,314] [added: (350] | | ) |
| Less: Net income (loss) attributable to noncontrolling interests | | [removed: 335] [added: 348] | | | | [removed: 74] [added: 335] | | | | [removed: (743] [added: 74] | | [removed: )] |
Adoption of New Accounting Standards
As discussed in Note 1 and Note 2 to the consolidated financial statements, the Company changed its method for accounting for revenue in 2018.
February 21, 2019
February 21, 2019
| Service revenues - commodity consideration (Note 1) | | 400 | | | | — | | | | — | | |
| Processing commodity expenses (Note 1) | | 137 | | | | — | | | | — | | |
| Operating and maintenance expenses | | 1,507 | | | | 1,576 | | | | 1,592 | | |
| Total costs and expenses | | 7,918 | | | | 7,104 | | | | 6,810 | | |
| Operating income (loss) | | 768 | | | | 927 | | | | 689 | | |
| Preferred stock (Note 15) | | 35 | | | | — | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Adoption of new accounting standard | — | | | | — | | | | 1 | | | | 36 | | | | — | | | | — | | | | 37 | | | | — | | | | 37 | | |
| Adoption of new accounting standards (Note 1) | — | | | | — | | | | — | | | | (23 | | ) | | (61 | | ) | | — | | | | (84 | | ) | | (37 | | ) | | (121 | | ) |
| Net income (loss) | — | | | | — | | | | — | | | | (155 | | ) | | — | | | | — | | | | (155 | | ) | | 348 | | | | 193 | | |
| WPZ Merger (Note 1) | — | | | | 382 | | | | 6,112 | | | | — | | | | (3 | | ) | | — | | | | 6,491 | | | | (4,629 | | ) | | 1,862 | | |
| Issuance of preferred stock (Note 15) | 35 | | | | — | | | | — | | | | — | | | | — | | | | — | | | | 35 | | | | — | | | | 35 | | |
| Cash dividends – common stock ($1.36 per share) | — | | | | — | | | | — | | | | (1,386 | | ) | | — | | | | — | | | | (1,386 | | ) | | — | | | | (1,386 | | ) |
| Deconsolidation of subsidiary (Note 4) | — | | | | — | | | | — | | | | — | | | | — | | | | — | | | | — | | | | (267 | | ) | | (267 | | ) |
| Net increase (decrease) in equity | 35 | | | | 384 | | | | 6,185 | | | | (1,568 | | ) | | (32 | | ) | | — | | | | 5,004 | | | | (5,182 | | ) | | (178 | | ) |
| Balance – December 31, 2018 | $ | 35 | | | $ | 1,245 | | | $ | 24,693 | | | $ | (10,002 | ) | | $ | (270 | ) | | $ | (1,041 | ) | | $ | 14,660 | | | $ | 1,337 | | | $ | 15,997 | |
| Distributions from unconsolidated affiliates | | 693 | | | | 784 | | | | 742 | | |
| Gain on sale of certain assets (Note 3) | | (692 | | ) | | (1,095 | | ) | | — | | |
| Gain on deconsolidation of businesses (Note 6) | | (203 | | ) | | — | | | | — | | |
On August 10, 2018, we completed our merger with Williams Partners L.P. (WPZ), our previously consolidated master limited partnership, pursuant to which we acquired all of the approximately 256 million publicly held outstanding common units of WPZ in exchange for 382 million shares of our common stock (WPZ Merger).
Williams continued as the surviving entity.
The WPZ Merger was accounted for as a noncash equity transaction resulting in increases to Common stock of $382 million, Capital in excess of par value of $6.112 billion, and Regulatory assets, deferred charges, and other of $33 million and decreases to Accumulated other comprehensive income (loss) (AOCI) of $3 million, Noncontrolling interests in consolidated subsidiaries of $4.629 billion, and Deferred income tax liabilities of $1.829 billion in the Consolidated Balance Sheet.
Beginning in the third-quarter 2018, consistent with the manner in which our chief operating decision maker evaluates performance and allocates resources, our operations are now presented within the following reportable segments: Northeast G&P, Atlantic-Gulf, and West.
Prior period segment disclosures have been recast for the new segment presentation.
Atlantic-Gulf is comprised of our interstate natural gas pipeline, Transcontinental Gas Pipe Line Company, LLC (Transco), and significant natural gas gathering and processing and crude oil production handling and transportation
West is comprised of our interstate natural gas pipeline, Northwest Pipeline LLC (Northwest Pipeline), and our gathering, processing, and treating operations in Colorado, Wyoming, and the Barnett Shale region of north-central Texas, the Eagle Ford Shale region of south Texas, the Haynesville Shale region of northwest Louisiana, and the Mid-Continent region which includes the Anadarko, Arkoma, Delaware, and Permian basins.
This segment also includes our natural gas liquid (NGL) and natural gas marketing business, storage facilities, an undivided 50 percent interest in an NGL fractionator near Conway, Kansas, and a 50 percent equity-method investment in Overland Pass Pipeline, LLC (OPPL), a 50 percent interest in Jackalope Gas Gathering Services, L.L.C. (Jackalope) (an equity-method investment following deconsolidation as of June 30, 2018), a 50 percent equity-method investment in Rocky Mountain Midstream Holdings LLC (RMM), a 15 percent equity-method investment in Brazos Permian II, LLC (Brazos Permian II), and our previously owned 50 percent equity-method investment in the Delaware basin gas gathering system (DBJV) in the Mid-Continent region (see Note 6 – Investing Activities).
West also included our former natural gas gathering and processing assets in the Four Corners area of New Mexico and Colorado (see Note 3 – Divestitures).
Other includes our previously owned operations, including our former Williams Olefins, L.L.C., a wholly owned subsidiary which owned our 88.5 percent undivided interest in the Geismar, Louisiana, olefins plant (Geismar Interest), which was sold in July 2017 (see Note 3 – Divestitures), and a refinery grade propylene splitter in the Gulf region, which was sold in June 2017.
We believe that the carrying value of certain of our property, plant, and equipment and other identifiable intangible assets, notably certain acquired assets accounted for as business combinations between 2012 and 2014, may be in excess of current fair value.
However, the carrying value of these assets, in our judgment, continues to be recoverable based on our evaluation of undiscounted future cash flows.
It is reasonably possible that future strategic decisions, including transactions such as monetizing non-core assets or contributing assets to new ventures with third parties, as well as unfavorable changes in expected producer activities could impact our assumptions and ultimately result in impairments of these assets.
Such transactions or developments may also indicate that certain of our equity-method investments have experienced other-than-temporary declines in value, which could also result in impairment.
On March 15, 2018, the Federal Energy Regulatory Commission (FERC) issued a revised policy statement (the revised policy statement) regarding the recovery of income tax costs in rates of natural gas pipelines.
February 22, 2018
| Impairment of goodwill (Note 16) | | — | | | | — | | | | 1,098 | | |
| Insurance recoveries – Geismar Incident | | (9 | | ) | | (7 | | ) | | (126 | | ) |
| Operating income (loss) | | 904 | | | | 700 | | | | 226 | | |
See accompanying notes.
| | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Commercial paper | | — | | | | 93 | | |
| Balance – December 31, 2014 | $ | 782 | | | $ | 14,925 | | | $ | (5,548 | ) | | $ | (341 | ) | | $ | (1,041 | ) | | $ | 8,777 | | | $ | 11,395 | | | $ | 20,172 | |
| Net increase (decrease) in equity | 2 | | | | (118 | | ) | | (2,412 | | ) | | (101 | | ) | | — | | | | (2,629 | | ) | | (1,318 | | ) | | (3,947 | | ) |
| Adoption of ASU 2016-09 (Note 1) | — | | | | 1 | | | | 36 | | | | — | | | | — | | | | 37 | | | | — | | | | 37 | | |
| Impairment of goodwill | | — | | | | — | | | | 1,098 | | |
| Special distribution from Gulfstream | | — | | | | — | | | | 396 | | |
| Purchases of businesses, net of cash acquired | | — | | | | — | | | | (112 | | ) |
| Distributions from unconsolidated affiliates in excess of cumulative earnings | | 529 | | | | 472 | | | | 404 | | |
Subsequent to these transactions and as of December 31, 2017, we own a 74 percent limited partner interest in WPZ.
On May 12, 2015, we entered into an agreement for a unit-for-stock transaction whereby we would have acquired all of the publicly held outstanding common units of WPZ in exchange for shares of our common stock (WPZ Merger Agreement).
On September 28, 2015, we entered into a Termination Agreement and Release (Termination Agreement), terminating the WPZ Merger Agreement.
Under the terms of the Termination Agreement, we were required to pay a $428 million termination fee to WPZ, at which time we owned approximately 60 percent, including the interests of the general partner and IDRs.
Such termination fee settled through a reduction of quarterly incentive distributions we were entitled to receive from WPZ (such reduction not to exceed $209 million per quarter).
The distributions from WPZ in November 2015, February 2016, and May 2016 were reduced by $209 million, $209 million, and $10 million, respectively, related to this termination fee.
ACMP Merger
On February 2, 2015, Williams Partners L.P. merged with and into Access Midstream Partners, L.P. (ACMP Merger).
For the purpose of these financial statements and notes, WPZ refers to the renamed merged partnership, while Pre-merger Access Midstream Partners, L.P. (ACMP) and Pre-merger Williams Partners L.P. (Pre-merger WPZ) refer to the separate partnerships prior to the consummation of the ACMP Merger and subsequent name change.
The net assets of Pre-merger WPZ and ACMP were combined at our historical basis.
Our basis in ACMP reflected our business combination accounting resulting from acquiring control of ACMP on July 1, 2014.
All remaining business activities are included in Other.
Williams Partners
Williams Partners consists of our consolidated master limited partnership, WPZ, and primarily includes gas pipeline and midstream businesses.
WPZ’s midstream businesses primarily consist of (1) natural gas gathering, treating, compression, and processing; (2) natural gas liquid (NGL) fractionation, storage, and transportation; (3) crude oil production handling and transportation; and (4) olefins production (see Note 2 – Acquisitions and Divestitures).
The primary service areas are concentrated in major producing basins in Colorado, Texas, Oklahoma, Kansas, New Mexico, Wyoming, the Gulf of Mexico, Louisiana, Pennsylvania, West Virginia, New York, and Ohio, which include the Barnett, Eagle Ford, Haynesville, Marcellus, Niobrara, and Utica shale plays as well as the Mid-Continent region.
(See Note 2 – Acquisitions and Divestitures.)
Other also includes certain domestic olefins pipeline assets as well as certain Canadian assets, which included a liquids extraction plant located near Fort McMurray, Alberta, that began operations in March 2016, and a propane dehydrogenation facility which was under development.
Consolidated master limited partnership
As of December 31, 2017, we owned approximately 74 percent of the interests in WPZ, a variable interest entity (VIE) (see Note 3 – Variable Interest Entities).
These common unit issuances, the Financial Repositioning, WPZ’s quarterly distribution of additional paid-in-kind Class B units to us, and other equity issuances by WPZ had the combined net impact of decreasing Noncontrolling interests in consolidated subsidiaries by $2.407 billion, and increasing Capital in excess of par value by $1.497 billion and Deferred income tax liabilities by $910 million in the Consolidated Balance Sheet.
WPZ is self-funding and maintains separate lines of bank credit and cash management accounts and also has a commercial paper program.
(See Note 13 – Debt, Banking Arrangements, and Leases.) Cash distributions from WPZ to all partners, including us, are governed by WPZ’s partnership agreement.
Discontinued operations
Unless indicated otherwise, the information in the Notes to Consolidated Financial Statements relates to our continuing operations.
An excerpt. Shown here: 40 of 801 rewritten, 40 of 580 added and 40 of 439 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data in the FY2018 filing and the FY2017 filing.
Item 9A. Controls and Procedures
6 rewritten, 1 added, 2 removed, 41 unchanged
There have been no changes during the fourth quarter of [removed: 2017] [added: 2018] that have materially affected, or are reasonably likely to materially affect, our Internal Control over Financial Reporting.
Under the supervision and with the participation of our management, including our Chief Executive Officer and Chief Financial Officer, we assessed the effectiveness of our internal control over financial reporting as of December 31, [removed: 2017,] [added: 2018,] based on the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) in Internal Control — Integrated Framework (2013).
Based on our assessment, we concluded that, as of December 31, [removed: 2017,] [added: 2018,] our internal control over financial reporting was effective.
We have audited The Williams Companies, Inc.’s internal control over financial reporting as of December 31, [removed: 2017,] [added: 2018,] based on criteria established in Internal [removed: Control - Integrated] [added: Control-Integrated] Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the [removed: “COSO criteria”).][added: COSO criteria).]
In our opinion, The Williams Companies, Inc. (the [removed: “Company”)] [added: Company)] maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2017,] [added: 2018,] based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) [removed: (“PCAOB”),] [added: (PCAOB),] the consolidated balance sheet of the Company as of December 31, [removed: 2017] [added: 2018] and [removed: 2016,] [added: 2017,] and the related consolidated statements of operations, comprehensive income (loss), changes in equity and cash flows for each of the three years in the period ended December 31, [removed: 2017,] [added: 2018,] and the related notes and [added: the] financial statement [removed: schedules] [added: schedule] listed in the index at Item 15(a) and our report dated February [removed: 22, 2018] [added: 21, 2019] expressed an unqualified opinion thereon.
February 21, 2019
on Internal Control Over Financial Reporting
February 22, 2018
Item 10. Directors, Executive Officers and Corporate Governance
1 rewritten, 0 added, 0 removed, 7 unchanged
The information regarding our directors and nominees for director required by Item 401 of Regulation S-K will be presented under the heading “Election of Directors” in our definitive proxy statement prepared for the solicitation of proxies in connection with our Annual Meeting of Stockholders to be held May [removed: 10, 2018,] [added: 9, 2019,] which shall be filed no later than [removed: April 30, 2018] [added: March 28, 2019] (Proxy Statement), which information is incorporated by reference herein.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
1 rewritten, 0 added, 1 removed, 0 unchanged
The information regarding securities authorized for issuance under equity compensation plans required by Item 201(d) of Regulation S-K and the security ownership of certain beneficial owners and management required by Item 403 of Regulation S-K will be presented under the headings “Equity Compensation Stock Plans” and “Security [added: Ownership of Certain Beneficial Owners and Management” in our Proxy Statement, which information is incorporated by reference herein.]
Ownership of Certain Beneficial Owners and Management” in our Proxy Statement, which information is incorporated by reference herein.
Item 15. Exhibits and Financial Statement Schedules
94 rewritten, 3 added, 12 removed, 173 unchanged
| [Consolidated statement of operations for each year in the three-year period ended December 31, [removed: 2017](#sAAB28B8056D659021131ED33F8BE4D68)] [added: 2018](#s0102A5FD990DD8B8891FEB16C18DCFB3)] | [removed: [80](#sAAB28B8056D659021131ED33F8BE4D68)] [added: [76](#s0102A5FD990DD8B8891FEB16C18DCFB3)] |
| [Consolidated statement of comprehensive income (loss) for each year in the three-year period ended December 31, [removed: 2017](#sBD662989B161CB3545C4ED33FB5C81A7)] [added: 2018](#s5F82732F09E4C38ED3F0EB16BF7B77C9)] | [removed: [81](#sBD662989B161CB3545C4ED33FB5C81A7)] [added: [77](#s5F82732F09E4C38ED3F0EB16BF7B77C9)] |
| [Consolidated balance sheet at December 31, [removed: 2017] [added: 2018] and [removed: 2016](#s696FFD198EC49CC9C43FED33F8AA24A9)] [added: 2017](#sA13F290852D249451CD1EB16BE24F59A)] | [removed: [82](#s696FFD198EC49CC9C43FED33F8AA24A9)] [added: [78](#sA13F290852D249451CD1EB16BE24F59A)] |
| [Consolidated statement of changes in equity for each year in the three-year period ended December 31, [removed: 2017](#s4C3AABE9DBFDB4B0D0E1ED33FA9EC83B)] [added: 2018](#s9E6270BB73B30AAD70A2EB16BD8819C6)] | [removed: [83](#s4C3AABE9DBFDB4B0D0E1ED33FA9EC83B)] [added: [79](#s9E6270BB73B30AAD70A2EB16BD8819C6)] |
| [Consolidated statement of cash flows for each year in the three-year period ended December 31, [removed: 2017](#sB49E79B2D744A5833F9FED33FA307684)] [added: 2018](#sD1F2742DD5CF8636AE1AEB16BF0E147E)] | [removed: [84](#sB49E79B2D744A5833F9FED33FA307684)] [added: [80](#sD1F2742DD5CF8636AE1AEB16BF0E147E)] |
| [Notes to consolidated financial [removed: statements](#s38DB9F89DDF3761BE445ED341E2004D6)] [added: statements](#s282A753DE1FC1EEF1406EB16EC06E2AE)] | [removed: [85](#s38DB9F89DDF3761BE445ED341E2004D6)] [added: [81](#s282A753DE1FC1EEF1406EB16EC06E2AE)] |
| Schedule for each year in the three-year period ended December 31, [removed: 2017:] [added: 2018:] | |
| [II — Valuation and qualifying [removed: accounts](#s27AED38617EEA3F4BAE1ED33F8D29443)] [added: accounts](#s1D8A5B13F1CA839CAAA8EB16BD6891AA)] | [removed: [153](#s27AED38617EEA3F4BAE1ED33F8D29443)] [added: [148](#s1D8A5B13F1CA839CAAA8EB16BD6891AA)] |
| [Quarterly financial data [removed: (unaudited)](#sCF94C732902298EB7935ED3407E6C30A)] [added: (unaudited)](#s307CC73FDA905A0AD129EB16D397A064)] | [removed: [147](#sCF94C732902298EB7935ED3407E6C30A)] [added: [146](#s307CC73FDA905A0AD129EB16D397A064)] |
| 2.1+ | __ | [Agreement and Plan of Merger dated as of May 12, 2015, by and among The Williams Companies, Inc., SCMS LLC, Williams Partners, L.P., and WPZ GP LLC (filed on May 13, [removed: 2015] [added: 2015,] as Exhibit 2.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312515185008/d925124dex21.htm) |
| 2.2 | — | [Amendment No 1. to Agreement and Plan of Merger dated as of May 1, 2016, by and among The Williams Companies, Inc., Energy Transfer Corp LP, Energy Transfer Corp GP, LLC, Energy Transfer Equity, L.P., LE GP, LLC and Energy Transfer Equity GP, LLC (filed on May 3, [removed: 2016] [added: 2016,] as Exhibit 2.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312516573267/d176661dex21.htm) |
| 2.3+ | — | [Agreement and Plan of Merger dated as of September 28, 2015, by and among The Williams Companies, Inc., Energy Transfer Corp LP, Energy Transfer Corp GP, LLC, Energy Transfer Equity, L.P., LE GP, LLC and Energy Transfer Equity GP, LLC (filed on October 1, [removed: 2015] [added: 2015,] as Exhibit 2.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312515335515/d56210dex21.htm) |
| [removed: 2.4] [added: 3.3] | — | [removed: [Share Purchase Agreement by and between The Williams Companies International Holdings B.V. and Inter Pipeline Ltd. and The Williams Companies, Inc.,] [added: [Certificate of Amendment] dated August [removed: 8, 2016] [added: 10, 2018] (filed on August [removed: 12, 2016] [added: 10, 2018,] as Exhibit [removed: 2.1] [added: 3.1] to The Williams Companies, Inc.’s current report on Form 8-K [removed: (file] [added: (File] No. 001-04174) and incorporated herein by [removed: reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312516680304/d189781dex21.htm)] [added: reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312518246104/d599321dex31.htm)] |
| [removed: 2.5] [added: 10.33] | — | [removed: [Share Purchase Agreement by and] [added: [Tax Sharing Agreement, dated as of December 30, 2011,] between [added: The] Williams [removed: Energy Canada LP and Inter Pipeline Ltd.] [added: Companies, Inc.] and [removed: Williams Partners L.P., dated August 8, 2016] [added: WPX Energy, Inc.] (filed on [removed: August 12, 2016] [added: January 6, 2012,] as Exhibit [removed: 2.2] [added: 10.3] to The Williams Companies, Inc.’s current report on Form 8-K [removed: (file] [added: (File] No. 001-04174) and incorporated herein by [removed: reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312516680304/d189781dex22.htm)] [added: reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312512005398/d275552dex103.htm)] |
| [removed: 2.6+] [added: 2.4] | — | [Interest Swap and Purchase Agreement by and among Western Gas Partners, LP, WGR Operating, LP, Delaware Basin JV Gathering LLC, Williams Partners L.P., Williams Midstream Gas Services LLC, and Appalachia Midstream Services, L.L.C., dated February 9, 2017 (filed on February 10, [removed: 2017] [added: 2017,] as Exhibit 2.1 to The Williams Companies Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312517037519/d338496dex21.htm) |
| [removed: 2.7] [added: 2.5] | __ | [Membership Interest Purchase Agreement, dated as of April 13, 2017, among Williams Field Services Group, LLC, Williams Partners L.P., Williams Olefins, L.L.C., NOVA Chemicals Inc., and NOVA Chemicals Corporation (filed on August 3, [removed: 2017] [added: 2017,] as Exhibit 2.2 to Williams Partners L.P.’s quarterly report on Form 10-Q (File No. 001-34831) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/1483096/000148309617000012/wpz_2176030xex22.htm) |
| 3.1 | — | [Amended and Restated Certificate of Incorporation, (filed on May 26, [removed: 2010] [added: 2010,] as Exhibit 3.(i)1 to The Williams Companies Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000095012310053200/c58430exv3wxiy1.htm) |
| [removed: 3.2] [added: 3.4] | — | [By-Laws (filed on January 20, 2017, as Exhibit 3.1 to The Williams Companies Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312517014098/d331523dex31.htm) |
| 4.1 | — | [Senior Indenture, dated February 25, 1997, between MAPCO Inc. and Bank One Trust Company, N.A. (formerly The First National Bank of Chicago), as Trustee (filed on February 25, [removed: 1997] [added: 1997,] as Exhibit 4.5.1 to MAPCO Inc.’s Amendment No. l to registration statement on Form S-3 (File No. 333-20837) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/62142/0000950134-97-001365.txt) |
| 4.3 | — | [Supplemental Indenture No. 2, dated March 5, 1997, between MAPCO Inc. and Bank One Trust Company, N.A. (formerly The First National Bank of Chicago), as Trustee (filed on March 4, [removed: 1998] [added: 1998,] as Exhibit 4(p) to MAPCO Inc.’s annual report on Form 10-K for the fiscal year ended December 31, 1997 (File No. 001-05254) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/62142/0000950134-98-001719.txt) |
| 4.4 | — | [Supplemental Indenture No. 3, dated March 31, 1998, among MAPCO Inc., Williams Holdings of Delaware, Inc. and Bank One Trust Company, N.A. (formerly The First National Bank of Chicago), as Trustee (filed on March 30, [removed: 1999] [added: 1999,] as Exhibit 4(J) to Williams Holdings of Delaware, Inc.’s annual report on Form 10-K for the fiscal year ended December 31, 1998 (File No. 000-20555) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/947779/0000950134-99-002187.txt) |
| 4.5 | — | [Fourth Supplemental Indenture, dated as of July 31, 1999, among Williams Holdings of Delaware, Inc., The Williams Companies, Inc. and Bank One Trust Company, N.A. (formerly The First National Bank of Chicago), as Trustee (filed on March 28, [removed: 2000] [added: 2000,] as Exhibit 4(q) to The Williams Companies, Inc.’s annual report on Form 10-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000095013400002540/0000950134-00-002540.txt) |
| 4.6 | — | [Fifth Supplemental Indenture, dated as of February 1, 2010, between The Williams Companies, Inc. and The Bank of New York Mellon Trust Company, N.A. (filed on February 2, [removed: 2010] [added: 2010,] as Exhibit 4.3 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000095012310007517/c55964exv4w3.htm) |
| 4.7 | — | [Fifth Supplemental Indenture between The Williams Companies, Inc. and Bank One Trust Company, N.A., as Trustee, dated as of January 17, 2001 (filed on March 12, [removed: 2001] [added: 2001,] as Exhibit 4(k) to The Williams Companies, Inc.’s annual report on Form 10-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000095013401002063/d84653ex4-k.txt) |
| 4.8 | — | [Seventh Supplemental Indenture, dated March 19, 2002, between The Williams Companies, Inc. as Issuer and Bank One Trust Company, National Association, as Trustee (filed on May 9, [removed: 2002] [added: 2002,] as Exhibit 4.1 to The Williams Companies, Inc.’s quarterly report on Form 10-Q (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000095013402004940/d96548ex4-1.txt) |
| 4.9 | — | [Eleventh Supplemental Indenture, dated as of February 1, 2010, between The Williams Companies, Inc. and The Bank of New York Mellon Trust Company, N.A. (filed on February 2, [removed: 2010] [added: 2010,] as Exhibit 4.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000095012310007517/c55964exv4w1.htm) |
| [removed: 4.10] [added: 4.17] | — | [removed: [Indenture,] [added: [Second Supplemental Indenture,] dated as of [removed: May 28, 2003, by and] [added: August 10, 2018,] between The Williams Companies, Inc. and [removed: JPMorgan Chase Bank, as Trustee] [added: The bank of New York Mellon Trust Company, N.A.] (filed on August [removed: 12, 2003] [added: 10, 2018,] as [removed: Exhibit] [added: exhibit] 4.2 to The Williams Companies, Inc.’s [removed: quarterly] [added: current] report on Form [removed: 10-Q] [added: 8-K] (File No. 001-04174) and incorporated herein by [removed: reference).](http://www.sec.gov/Archives/edgar/data/107263/000095013403011381/d07692exv4w2.txt)] [added: reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312518246104/d599321dex42.htm)] |
| [removed: 4.11] [added: 4.10] | — | [Indenture, dated as of March 5, 2009, among The Williams Companies, Inc. and The Bank of New York Mellon Trust Company, N.A., as Trustee (filed on March 11, [removed: 2009] [added: 2009,] as Exhibit 4.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000129993309001142/exhibit1.htm) |
| [removed: 4.12] [added: 4.11] | — | [First Supplemental Indenture, dated as of February 1, 2010, between The Williams Companies, Inc. and The Bank of New York Mellon Trust Company, N.A. (filed on February 2, [removed: 2010] [added: 2010,] as Exhibit 4.2 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000095012310007517/c55964exv4w2.htm) |
| [removed: 4.13] [added: 4.12] | — | [Indenture, dated December 18, 2012, between The Williams Companies, Inc. and The Bank of New York Mellon Trust Company, N.A. as trustee (filed on December 20, [removed: 2012] [added: 2012,] as Exhibit 4.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312512508695/d456994dex41.htm) |
| [removed: 4.14] [added: 4.13] | — | [First Supplemental Indenture, dated December 18, 2012, between The Williams Companies, Inc. and The Bank of New York Mellon Trust Company, N.A. as trustee (filed on December 20, [removed: 2012] [added: 2012,] as Exhibit 4.2 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312512508695/d456994dex42.htm) |
| [removed: 4.15] [added: 4.14] | — | [Second Supplemental Indenture, dated as of June 24, 2014, between The Williams Companies, Inc. and The Bank of New York Mellon Trust Company, N.A., as trustee (filed on June 24, [removed: 2014] [added: 2014,] as Exhibit 4.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312514247357/d748302dex41.htm) |
| [removed: 4.16] [added: 4.15] | — | [Indenture, dated as of February 9, 2010, between Williams Partners L.P. and The Bank of New York Mellon Trust Company, N.A. (filed on February 10, [removed: 2010] [added: 2010,] as Exhibit 4.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000095012310010940/c56234exv4w1.htm) |
| [removed: 4.17] [added: 4.16] | — | [First Supplemental Indenture, dated as of February 2, 2015, between Williams Partners L.P. and The Bank of New York Mellon Trust Company, N.A. (filed on February 3, 2015, as Exhibit 4.5 to Williams Partners L.P.’s current report on Form 8-K (File No. 001-34831) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/1483096/000119312515031434/d862478dex45.htm) |
| 4.18 | — | [Indenture, dated as of November 9, 2010, between Williams Partners L.P. and The Bank of New York Mellon Trust Company, N.A., as trustee (filed on November 12, [removed: 2010] [added: 2010,] as Exhibit 4.1 to Williams Partners L.P.’s current report on Form 8-K (File No. 001-32599) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/1324518/000095012310104733/c61303exv4w1.htm) |
| 4.19 | — | [First Supplemental Indenture, dated as of November 9, 2010, between Williams Partners L.P. and The Bank of New York Mellon Trust Company, N.A., as trustee (filed on November 12, [removed: 2010] [added: 2010,] as Exhibit 4.2 to Williams Partners L.P.’s current report on Form 8-K (File No. 001-32599) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/1324518/000095012310104733/c61303exv4w2.htm) |
| 4.20 | — | [Second Supplemental Indenture, dated as of November 17, 2011, between Williams Partners L.P. and The Bank of New York Mellon Trust Company, N.A., as trustee (filed November 18, [removed: 2011] [added: 2011,] as Exhibit 4.1 to Williams Partners L.P.’s current report on Form 8-K (File No. 001-32599) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/1324518/000119312511317239/d258324dex41.htm) |
| 4.22 | — | [Fourth Supplemental Indenture, dated as of November 15, 2013, between Williams Partners L.P. and The Bank of New York Mellon Trust Company, N .A., as trustee (filed on November 18, [removed: 2013] [added: 2013,] as Exhibit 4.1 to Williams Partners L.P.’s current report on Form 8-K (File No. 001-32599) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/1324518/000119312513445562/d630054dex41.htm) |
| 4.23 | — | [Fifth Supplemental Indenture, dated as of March 4, 2014, between Williams Partners L.P. and The Bank of New York Mellon Trust Company, N.A., as trustee (filed on March 4, [removed: 2014] [added: 2014,] as Exhibit 4.1 to Williams Partners L.P.’s current report on Form 8-K (File No. 001-32599) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/1324518/000119312514082303/d686854dex41.htm) |
| 4.24 | — | [Sixth Supplemental Indenture, dated as of June 27, 2014, between Williams Partners L.P. and The Bank of New York Mellon Trust Company, N.A., as trustee (filed on June 27, [removed: 2014] [added: 2014,] as Exhibit 4.1 to Williams Partners L.P.’s current report on Form 8-K (File No. 001-32599) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/1324518/000119312514253320/d750827dex41.htm) |
| 10.4§ | — | [Form of 2013 Restricted Stock Unit Agreement among Williams and certain nonmanagement directors (filed on February 26, 2014, as Exhibit 10.11 to The Williams Companies, Inc. annual report on Form 10-K (File No. 001-04174) and incorporated herein by reference).](#s0F22F3DB1ED6BDDAA208EB16D2207447) |
| 10.28§* | — | [Change in Control and Restrictive Covenant Agreement between certain executive officers (Tier One Executives) and The Williams Companies, Inc.](https://www.sec.gov/Archives/edgar/data/107263/000010726319000007/wmb_20181231xex1028.htm) |
| 10.29§* | — | [Change in Control and Restrictive Covenant Agreement between certain executive officers (Tier Two Executives) and The Williams Companies, Inc.](https://www.sec.gov/Archives/edgar/data/107263/000010726319000007/wmb_20181231xex1029.htm) |
| [I — Condensed financial information of registrant](#s18E7A67A4B6CCD808ED2ED33F9A43AB5) | [149](#s18E7A67A4B6CCD808ED2ED33F9A43AB5) |
| | | |
| 10.36 | — | [Termination Agreement and Release, dated as of September 29, 2015, by and among The Williams Companies, Inc., SCMS LLC, Williams Partners L.P. and WPZ GP LLC (filed on September 28, 2015 as Exhibit 10.1 to Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312515331008/d56210dex101.htm) |
| 10.37 | — | [Second Amended and Restated Credit Agreement dated as of February 2, 2015, between The Williams Companies, Inc., the lenders named therein, and Citibank, N.A. as Administrative Agent (filed on February 3, 2015 as Exhibit 10.1 to The Williams Companies, Inc.’s current report on Form 8-K (File 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312515031479/d863835dex101.htm) |
| 10.38 | __ | [Amendment No. 1 and Extension Agreement, dated as of November 17, 2017, by and among The Williams Companies, Inc., the lenders party thereto and Citibank, N.A. (filed on November 22, 2017 as Exhibit 10.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312517349886/d497355dex101.htm) |
| 10.39 | — | [Second Amended and Restated Credit Agreement dated as of February 2, 2015, between Williams Partners L.P., Northwest Pipeline LLC, Transcontinental Gas Pipeline Company, LLC, as co-borrowers, the lenders named therein, and Citibank, N.A. as Administrative Agent (filed on February 3, 2015 as Exhibit 10.1 to Williams Partners L.P.’s current report on Form 8-K (File No. 001-34831) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/1483096/000119312515031434/d862478dex101.htm) |
| 10.40 | — | [Amendment No. 1 to Second Amended and Restated Credit Agreement dated as of December 18, 2015, between Williams Partners L.P., Northwest Pipeline LLC, Transcontinental Gas Pipe Line Company, LLC, as co-borrowers, the lenders named therein, and Citibank, N.A. as Administrative Agent (filed on December 23, 2015 as Exhibit 10.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/99250/000119312515413023/d110984dex101.htm) |
| 10.41 | __ | [Amendment No. 2 and Extension Agreement, dated as of November 17, 2017, by and among Williams Partners L.P., Northwest Pipeline LLC, and Transcontinental Gas Pipe Line Company LLC, the lenders party thereto and Citibank, N.A. (filed on November 22, 2017 as Exhibit 10.2 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312517349886/d497355dex102.htm) |
| 10.42 | — | [Form of Amended and Restated Commercial Paper Dealer Agreement, dated as of February 2, 2015, between Williams Partners L.P., as Issuer, and the Dealer party thereto (filed on February 3, 2015 as Exhibit 10.3 to Williams Partners L.P.’s current report on Form 8-K (File No. 001-34831) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/1483096/000119312515031434/d862478dex103.htm) |
| 10.45 | __ | [Separation Agreement and General Release entered into by and among Robert S. Purgason and The William Companies, Inc., dated March 21, 2017 (filed on March 24, 2017, as Exhibit 10.1 to The Williams Companies, Inc.’s current report on Form 8-K (File No. 001-04174) and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000119312517095568/d350437dex101.htm) |
| 12* | — | [Computation of Ratio of Earnings to Combined Fixed Charges.](https://www.sec.gov/Archives/edgar/data/107263/000010726318000006/wmb_20171231x10kxex12.htm) |
| 14 | — | [Code of Ethics for Senior Officers (filed on March 15, 2004 as Exhibit 14 to The Williams Companies, Inc.’s annual report on Form 10-K and incorporated herein by reference).](http://www.sec.gov/Archives/edgar/data/107263/000095013404003499/d12870exv14.txt) |
An excerpt. Shown here: 40 of 94 rewritten, all 3 added and all 12 removed. The counts are complete. For every sentence, read Item 15. Exhibits and Financial Statement Schedules in the FY2018 filing and the FY2017 filing.
Item 16. Form 10-K Summary
13 rewritten, 5 added, 2 removed, 45 unchanged
Date: February [removed: 22, 2018][added: 21, 2019]
| /s/ ALAN S. ARMSTRONG | | President, Chief Executive Officer and Director | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ JOHN D. CHANDLER | | Senior Vice President and Chief Financial Officer | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ TED T. TIMMERMANS | | Vice President, Controller and Chief Accounting Officer | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ STEPHEN W. BERGSTROM | | Chairman of the Board | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ STEPHEN I. CHAZEN | | Director | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ CHARLES I. COGUT | | Director | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ KATHLEEN B. COOPER | | Director | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ MICHAEL A. CREEL | | Director | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ PETER A. RAGAUSS | | Director | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ SCOTT D. SHEFFIELD | | Director | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ MURRAY D. SMITH | | Director | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ WILLIAM H. SPENCE | | Director | | February [removed: 22, 2018] [added: 21, 2019] |
| /s/ NANCY K. BUESE | | Director | | February 21, 2019 |
| Nancy K. Buese | | | | |
| /s/ VICKI L. FULLER | | Director | | February 21, 2019 |
| Vicki L. Fuller | | | | |
| | | | | |
| /s/ JANICE D. STONEY | | Director | | February 22, 2018 |
| Janice D. Stoney | | | | |