 filings.tools
Williams-Sonoma 10-K 2017-01-29
Filed 2017-03-30. 20 sections, 275K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
10-K 1 d265187d10k.htm 10-K
Table of Contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 10-K
(Mark One):
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the fiscal year ended January 29, 2017.
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the transition period from to
Commission file number 001-14077
WILLIAMS-SONOMA, INC.
(Exact name of registrant as specified in its charter)
| Delaware | 94-2203880 | |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |
| 3250 Van Ness Avenue, San Francisco, CA | 94109 | |
| (Address of principal executive offices) | (Zip Code) |
Registrant’s telephone number, including area code: (415) 421-7900
Securities registered pursuant to Section 12(b) of the Act:
| Common Stock, $.01 par value | New York Stock Exchange, Inc. | |
| (Title of class) | (Name of each exchange on which registered) |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Web site, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). Yes ☒ No ☐
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. ☒
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer or a smaller reporting company. See definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act. (Check one):
Large accelerated filer ☒ Accelerated filer ☐ Non-accelerated filer ☐ (Do not check if a smaller
reporting company) Smaller reporting company ☐
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). Yes ☐ No ☒
As of July 31, 2016, the approximate aggregate market value of the registrant’s common stock held by non-affiliates was $4,757,778,000. It is assumed for purposes of this computation that an affiliate includes all persons as of July 31, 2016 listed as executive officers and directors with the Securities and Exchange Commission. This aggregate market value includes all shares held in the Williams-Sonoma, Inc. Stock Fund within the registrant’s 401(k) Plan.
As of March 26, 2017, 86,840,278 shares of the registrant’s common stock were outstanding.
Table of Contents
DOCUMENTS INCORPORATED BY REFERENCE
Portions of our definitive Proxy Statement for the 2017 Annual Meeting of Stockholders, also referred to in this Annual Report on Form 10-K as our Proxy Statement, which will be filed with the Securities and Exchange Commission, or SEC, have been incorporated in Part III hereof.
FORWARD-LOOKING STATEMENTS
This Annual Report on Form 10-K and the letters to stockholders contained in this Annual Report contain forward-looking statements within the “safe harbor” provisions of the Private Securities Litigation Reform Act of 1995 that involve risks and uncertainties, as well as assumptions that, if they do not fully materialize or prove incorrect, could cause our business and operating results to differ materially from those expressed or implied by such forward-looking statements. Such forward-looking statements include, without limitation, statements related to: projections of earnings, revenues, growth and other financial items; the strength of our business and our brands; our strategic initiatives regarding innovation and operational excellence and related investments; our beliefs about our advantages and leadership position across our brands; our ability to drive long-term profitable growth; the plans, strategies, initiatives and objectives of management for future operations; our brands, products and related initiatives, including our ability to introduce new brands, new products and product lines and bring in new customers; our belief that our e-commerce websites and direct mail catalogs act as a cost-efficient means of testing market acceptance of new products and new brands; the complementary nature of our e-commerce and retail channels; our marketing efforts; our global business and expansion efforts, including franchise, other third-party arrangements and company-owned operations; our ability to attract new customers; the seasonal variations in demand; our ability to recruit, retain and motivate skilled personnel; our belief in the reasonableness of the steps taken to protect the security and confidentiality of the information we collect; our belief in the adequacy of our facilities and the availability of suitable additional or substitute space; our belief in the ultimate resolution of current legal proceedings; the payment of dividends; our stock repurchase program; our capital allocation strategy in fiscal 2017; our planned use of cash in fiscal 2017; our compliance with financial covenants; our belief that our cash on hand and available credit facilities will provide adequate liquidity for our business operations over the next 12 months; our belief that our accumulated undistributed earnings of our foreign subsidiaries are sufficient to support our anticipated future cash needs of our foreign operations; our intentions regarding the utilization of such undistributed earnings; our belief regarding the effects of potential losses under our indemnification obligations; the impact of inflation; the effects of changes in our inventory reserves; the impact of new accounting pronouncements; and statements of belief and statements of assumptions underlying any of the foregoing. You can identify these and other forward-looking statements by the use of words such as “will,” “may,” “should,” “expects,” “plans,” “anticipates,” “believes,” “estimates,” “predicts,” “intends,” “potential,” “continue,” or the negative of such terms, or other comparable terminology.
The risks, uncertainties and assumptions referred to above that could cause our results to differ materially from the results expressed or implied by such forward-looking statements include, but are not limited to, those discussed under the heading “Risk Factors” in Item 1A hereto and the risks, uncertainties and assumptions discussed from time to time in our other public filings and public announcements. All forward-looking statements included in this document are based on information available to us as of the date hereof, and we assume no obligation to update these forward-looking statements.
Table of Contents
WILLIAMS-SONOMA, INC.
ANNUAL REPORT ON FORM 10-K
FISCAL YEAR ENDED JANUARY 29, 2017
TABLE OF CONTENTS
Table of Contents
PART I
Item 1. BUSINESS
| --- | --- |
OVERVIEW
Williams-Sonoma, Inc., incorporated in 1973, is a multi-channel specialty retailer of high quality products for the home.
In 1956, our founder, Chuck Williams, turned a passion for cooking and eating with friends into a small business with a big idea. He opened a store in Sonoma, California, to sell the French cookware that intrigued him while visiting Europe but that could not be found in America. Chuck’s business, which set a standard for customer service, took off and helped fuel a revolution in American cooking and entertaining that continues today.
In the decades that followed, the quality of our products, our ability to identify new opportunities in the market and our people-first approach to business have facilitated our expansion beyond the kitchen into nearly every area of the home. Growth across the Williams-Sonoma, Inc. portfolio has been fueled by three areas of strategic investment: brand experimentation and innovation, for a best-in-class approach to multi-channel retail experiences; operational excellence across the enterprise, from quality product and sourcing, to efficient manufacturing and supply chain; and culture and corporate social responsibility, from commitments to foster women in leadership and embrace diversity, to a healthy impact on our community and environment.
Today, Williams-Sonoma, Inc. is one of the United States’ largest e-commerce retailers with some of the best known and most beloved brands in home furnishings. We currently operate retail stores in the U.S., Puerto Rico, Canada, Australia and the United Kingdom, and franchise our brands to third parties in the Middle East, the Philippines and Mexico. In addition, during fiscal 2016, we entered into a franchise agreement with an unaffiliated franchisee to operate stores and e-commerce websites in South Korea, beginning in 2017. Our products are also available to customers through our catalogs and online worldwide.
Williams Sonoma
From the beginning, our namesake brand, Williams Sonoma, has been bringing people together around food. A leading specialty retailer of high-quality products for the kitchen and home, the brand seeks to provide world-class service and an engaging customer experience. Williams Sonoma products include everything for cooking, dining and entertaining, including: cookware, tools, electrics, cutlery, tabletop and bar, outdoor, furniture and a vast library of cookbooks. The brand also includes Williams Sonoma Home, a premium concept that offers classic home furnishings and decorative accessories, extending the Williams Sonoma lifestyle beyond the kitchen into every room of the home.
Pottery Barn
Established in 1949 and acquired by Williams-Sonoma, Inc. in 1986, Pottery Barn is a premier multi-channel home furnishings retailer. The brand was founded on the idea that home furnishings should be exceptional in comfort, quality, style and value. Pottery Barn stores, website, and catalogs are specially designed to make shopping an enjoyable experience, with inspirational lifestyle displays dedicated to every space in the home. Pottery Barn products include furniture, bedding, bathroom accessories, rugs, curtains, lighting, tabletop, outdoor and decorative accessories.
Pottery Barn Kids
Launched in 1999, Pottery Barn Kids serves as an inspirational destination for creating childhood memories by decorating nurseries, bedrooms and play spaces. Pottery Barn Kids offers exclusive, innovative and high-quality products designed specifically for creating magical spaces where children can play, laugh, learn and grow.
West Elm
West Elm helps customers express their personal style at home. Headquartered in Brooklyn, New York, West Elm opened its first store in 2003 in Dumbo, the neighborhood it still proudly calls home. Mixing clean lines, natural materials and handcrafted collections from the U.S. and around the world, West Elm creates unique, affordable designs for modern living. From its commitment to Fair Trade Certified, local and handcrafted products, to its community-driven in-store events and collaborations, and to its role as part of an active
Table of Contents
community on social media, everything West Elm does is designed to make an impact. West Elm also operates West Elm Workspace, which provides furnishings to the commercial sector, and recently announced its expansion into the travel and hospitality industry with the launch of West Elm Hotels.
PBteen
Launched in 2003, PBteen is the first home concept to focus exclusively on the teen market. The brand offers a complete line of furniture, bedding, lighting, decorative accents and more for teen bedrooms, dorm rooms, study spaces and lounges. PBteen’s innovative products are specifically designed to help teens create a comfortable and stylish room that reflects their own individual aesthetic.
Rejuvenation
Rejuvenation, founded in 1977 with a passion for old buildings, vintage lighting and house parts and great design, was acquired by Williams-Sonoma, Inc. in 2011. With manufacturing facilities in Portland, Oregon, Rejuvenation offers a wide assortment of high-quality lighting, hardware, furniture and home décor inspired by history, designed for today and made to last for years to come.
Mark and Graham
Launched in 2012, Mark and Graham is designed to be a premier destination for personalized gift buying. With over 100 monograms and font types to choose from, a Mark and Graham purchase is uniquely personal. The brand’s product lines include women’s and men’s accessories, small leather goods, jewelry, key item apparel, paper, entertaining and bar, home décor and seasonal items.
E-COMMERCE OPERATIONS
As of January 29, 2017, the e-commerce channel had the following merchandise strategies: Williams Sonoma, Pottery Barn, Pottery Barn Kids, West Elm, PBteen, Williams Sonoma Home, Rejuvenation and Mark and Graham, which sell our products through our e-commerce websites and direct-mail catalogs. We offer shipping from many of our brands to countries worldwide, while our catalogs reach customers throughout the U.S. and Australia. The e-commerce channel complements the retail channel by building brand awareness and acting as an effective advertising vehicle. In addition, we believe that our e-commerce websites and our direct mail catalogs act as a cost-efficient means of testing market acceptance of new products and new brands. Leveraging these insights and our multi-channel positioning, our marketing efforts, including the use of online advertising and the circulation of catalogs, are targeted toward driving sales to each of our channels. Consistent with our published privacy policies, we send our catalogs to addresses from our proprietary customer list, as well as to addresses from lists of other mail order direct marketers, magazines and companies with which we establish a business relationship. In accordance with prevailing industry practice and our privacy policies, we may also rent our list to select mailers. Our customer mailings are continually updated to include new prospects and to eliminate non-responders.
Detailed financial information about the e-commerce channel is found in Note K to our Consolidated Financial Statements.
RETAIL STORES
As of January 29, 2017, the retail channel had the following merchandise strategies: Williams Sonoma, Pottery Barn, Pottery Barn Kids, West Elm and Rejuvenation, operating 629 stores comprising 583 stores in 43 states, Washington, D.C. and Puerto Rico, 26 stores in Canada, 19 stores in Australia and 1 store in the United Kingdom. We also have multi-year franchise agreements with third parties that currently operate 66 franchised stores and/or e-commerce websites in the Middle East, the Philippines and Mexico. In addition, during fiscal 2016, we entered into a franchise agreement with an unaffiliated franchisee to operate stores and e-commerce websites in South Korea, beginning in 2017. The retail channel complements the e-commerce channel by building brand awareness and attracting new customers to our brands. Our retail stores serve as billboards for our brands, which we believe inspires our customers to also shop online and through our catalogs.
Table of Contents
Detailed financial information about the retail channel is found in Note K to our Consolidated Financial Statements.
SUPPLIERS
We purchase most of our merchandise from numerous foreign and domestic manufacturers and importers, the largest of which accounted for approximately 2% of our purchases during fiscal 2016. Approximately 64% of our merchandise purchases in fiscal 2016 were sourced from foreign vendors in 43 countries, predominantly in Asia and Europe. Approximately 99% of these purchases were negotiated and paid for in U.S. dollars. In addition, we manufacture merchandise, primarily upholstered furniture and lighting, at our facilities located in North Carolina, California and Oregon.
COMPETITION AND SEASONALITY
The specialty retail business is highly competitive. Our specialty retail stores, e-commerce websites and direct-mail catalogs compete with other retailers, including large department stores, discount retailers, other specialty retailers offering home-centered assortments, other e-commerce websites and other direct mail catalogs. The substantial sales growth in the direct-to-customer industry within the last decade, particularly in e-commerce, has encouraged the entry of many new competitors and an increase in competition from established companies. In addition, we face increased competition from discount retailers who, in the past, may not have competed with us or to this degree. We compete on the basis of our brand authority, the quality of our merchandise, service to our customers, our proprietary customer list, our e-commerce websites and our marketing capabilities, as well as the location and appearance of our stores. We believe that we compare favorably with many of our current competitors with respect to some or all of these factors.
Our business is subject to substantial seasonal variations in demand. Historically, a significant portion of our net revenues and net earnings have been realized during the period from October through January, and levels of net revenues and net earnings have typically been lower during the period from February through September. We believe this is the general pattern associated with the retail industry. In preparation for and during our holiday selling season, we hire a substantial number of additional temporary employees, primarily in our retail stores, customer care centers and distribution facilities, and incur significant fixed catalog production and mailing costs.
EMPLOYEES
As of January 29, 2017, we had approximately 28,300 employees, of whom approximately 10,500 were full-time. In preparation for and during our fiscal 2016 holiday selling season, we hired approximately 9,100 temporary employees primarily in our retail stores, distribution facilities and customer care centers.
TRADEMARKS, COPYRIGHTS, PATENTS AND DOMAIN NAMES
We own and/or have applied to register 118 separate trademarks and service marks. We own and/or have applied to register our key brand names as trademarks in the U.S. and 93 additional jurisdictions. Generally, exclusive rights to the trademarks and service marks are held by Williams-Sonoma, Inc. and are used by our subsidiaries and franchisees under a license. These marks include our core brand names as well as brand names for selected products and services. The core brand names in particular, including “Williams Sonoma,” “Pottery Barn,” “pottery barn kids,” “PBteen,” “west elm,” “Williams Sonoma Home,” “Rejuvenation” and “Mark and Graham” are of material importance to us. Trademarks are generally valid as long as they are in use and/or their registrations are properly maintained, and they have not been found to have become generic. Trademark registrations can generally be renewed indefinitely so long as the marks are in use. We also own numerous copyrights and trade dress rights for our products, product packaging, catalogs, books, house publications, website designs and store designs, among other things, which are used by our subsidiaries and franchisees under a license. We hold patents on certain product functions and product designs. Patents are generally valid for 14 to 20 years as long as their registrations are properly maintained. In addition, we have registered and maintain numerous Internet domain names, including “williams-sonoma.com,” “potterybarn.com,” “potterybarnkids.com,”
Table of Contents
“pbteen.com,” “westelm.com,” “wshome.com,” “williams-sonomainc.com,” “rejuvenation.com” and “markandgraham.com.” Collectively, the trademarks, copyrights, trade dress rights and domain names that we hold are of material importance to us.
AVAILABLE INFORMATION
We file annual reports on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, proxy and information statements and amendments to reports filed or furnished pursuant to Sections 13(a), 14 and 15(d) of the Securities Exchange Act of 1934, as amended. The public may read and copy these materials at the SEC’s Public Reference Room at 100 F Street, N.E., Washington, D.C. 20549-0213. The public may obtain information on the operation of the Public Reference Room by calling the SEC at 1-800-SEC-0330. The SEC also maintains a website at www.sec.gov that contains reports, proxy and information statements and other information regarding Williams-Sonoma, Inc. and other companies that file materials electronically with the SEC. Our annual reports, Forms 10-K, Forms 10-Q, Forms 8-K and proxy and information statements are also available, free of charge, on our website at www.williams-sonomainc.com.
Item 1A. RISK FACTORS
| --- | --- |
A description of the risks and uncertainties associated with our business is set forth below. You should carefully consider such risks and uncertainties, together with the other information contained in this report and in our other public filings. If any of such risks and uncertainties actually occurs, our business, financial condition or operating results could differ materially from the plans, projections and other forward-looking statements included in the section titled “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and elsewhere in this report and in our other public filings. In addition, if any of the following risks and uncertainties, or if any other risks and uncertainties, actually occurs, our business, financial condition or operating results could be harmed substantially, which could cause the market price of our stock to decline, perhaps significantly.
Declines in general economic conditions, and the resulting impact on consumer confidence and consumer spending, could adversely impact our results of operations.
Our financial performance is subject to declines in general economic conditions and the impact of such economic conditions on levels of consumer confidence and consumer spending. Consumer confidence and consumer spending may deteriorate significantly, and could remain depressed for an extended period of time. Consumer purchases of discretionary items, including our merchandise, generally decline during periods when disposable income is limited, unemployment rates increase or there is economic uncertainty. An uncertain economic environment could also cause our vendors to go out of business or our banks to discontinue lending to us or our vendors, or it could cause us to undergo restructurings, any of which would adversely impact our business and operating results.
We are unable to control many of the factors affecting consumer spending, and declines in consumer spending on home furnishings and kitchen products in general could reduce demand for our products.
Our business depends on consumer demand for our products and, consequently, is sensitive to a number of factors that influence consumer spending, including general economic conditions, consumer disposable income, fuel prices, recession and fears of recession, unemployment, war and fears of war, inclement weather, availability of consumer credit, consumer debt levels, conditions in the housing market, interest rates, sales tax rates and rate increases, inflation, consumer confidence in future economic conditions and political conditions, and consumer perceptions of personal well-being and security. In particular, past economic downturns have led to decreased discretionary spending, which adversely impacted our business. In addition, periods of decreased home purchases typically lead to decreased consumer spending on home products. These factors have affected, and may in the future affect, our various brands and channels differently. Adverse changes in factors affecting discretionary consumer spending have reduced and may in the future reduce consumer demand for our products, thus reducing our sales and harming our business and operating results.
Table of Contents
If we are unable to identify and analyze factors affecting our business, anticipate changing consumer preferences and buying trends, and manage our inventory commensurate with customer demand, our sales levels and operating results may decline.
Our success depends, in large part, upon our ability to identify and analyze factors affecting our business and to anticipate and respond in a timely manner to changing merchandise trends and customer demands in order to maintain and attract customers. For example, in the specialty home products business, style and color trends are constantly evolving. Consumer preferences cannot be predicted with certainty and may change between selling seasons. Changes in customer preferences and buying trends may also affect our brands differently. We must be able to stay current with preferences and trends in our brands and address the customer tastes for each of our target customer demographics. We must also be able to identify and adjust the customer offerings in our brands to cater to customer demands. For example, a change in customer preferences for children’s room furnishings may not correlate to a similar change in buying trends for other home furnishings. If we misjudge either the market for our merchandise or our customers’ purchasing habits, our sales may decline significantly or may be delayed while we work to fill backorders. We may be required to mark down certain products to sell any excess inventory or to sell such inventory through our outlet stores or other liquidation channels at prices which are significantly lower than our retail prices, any of which would negatively impact our business and operating results.
In addition, we must manage our inventory effectively and commensurate with customer demand. Much of our inventory is sourced from vendors located outside of the U.S. Thus, we usually must order merchandise, and enter into contracts for the purchase and manufacture of such merchandise, up to twelve months and generally multiple seasons in advance of the applicable selling season and frequently before trends are known. The extended lead times for many of our purchases may make it difficult for us to respond rapidly to new or changing trends. Our vendors also may not have the capacity to handle our demands or may go out of business in times of economic crisis. In addition, the seasonal nature of the specialty home products business requires us to carry a significant amount of inventory prior to peak selling season. As a result, we are vulnerable to demand and pricing shifts and to misjudgments in the selection and timing of merchandise purchases. If we do not accurately predict our customers’ preferences and acceptance levels of our products, our inventory levels will not be appropriate, and our business and operating results may be negatively impacted.
We may be exposed to cybersecurity risks and costs associated with credit card fraud and identity theft that could cause us to incur unexpected expenses and loss of revenue.
A significant portion of our customer orders are placed through our e-commerce websites or through our customer care centers. In addition, a significant portion of sales made through our retail channel require the collection of certain customer data, such as credit card information. In order for our sales channels to function successfully, we, our banking and authorizations partners, and other parties involved in processing customer transactions must be able to transmit confidential information, including credit card information and other personal information of our customers, securely over public and private networks. Third parties may have or develop the technology or knowledge to breach, disable, disrupt or interfere with our systems or processes or those of our vendors. Although we take the security of our systems and the privacy of our customers’ confidential information seriously, and we believe we take reasonable steps to protect the security and confidentiality of the information we collect, we cannot guarantee that our security measures will effectively prevent others from obtaining unauthorized access to our information and our customers’ information. The techniques used to obtain unauthorized access to systems change frequently and are not often recognized until after they have been launched. Any person who circumvents our security measures could destroy or steal valuable information or disrupt our operations. Any security breach could cause consumers to lose confidence in the security of our information systems, including our e-commerce websites or stores, and choose not to purchase from us. Any security breach could also expose us to risks of data lo
Showing the first 8K of 73K characters. Open the full section
Item 1B. UNRESOLVED STAFF COMMENTS
None.
Item 2. PROPERTIES
We lease store locations, distribution and manufacturing facilities, corporate facilities and customer care centers for our U.S. and foreign operations for original terms generally ranging from 5 to 22 years. Certain leases contain renewal options for periods of up to 20 years.
Table of Contents
For our store locations, our gross leased store space as of January 29, 2017 totaled approximately 6,359,000 square feet for 629 stores compared to approximately 6,163,000 square feet for 618 stores as of January 31, 2016.
Leased Properties
The following table summarizes the location and size of our leased facilities occupied as of January 29, 2017:
| Location | Occupied Square Footage (Approximate) | |||
| Distribution and Manufacturing Facilities | ||||
| Mississippi | 2,105,000 | |||
| New Jersey | 2,103,000 | |||
| California | 1,432,000 | |||
| Georgia | 1,075,000 | |||
| Texas | 896,000 | |||
| Tennessee | 603,000 | |||
| North Carolina | 412,000 | |||
| Oregon | 91,000 | |||
| Other | 573,000 | |||
| Corporate Facilities | ||||
| New York | 264,000 | |||
| California | 240,000 | |||
| Oregon | 71,000 | |||
| Customer Care Centers | ||||
| Nevada | 36,000 | |||
| Oklahoma | 36,000 | |||
| Other | 25,000 |
In addition to the above contracts, we enter into other agreements for offsite storage needs for our distribution facilities and our retail store locations, as necessary. As of January 29, 2017, the total leased space relating to these properties was not material to us and is not included in the occupied square footage reported above.
Owned Properties
As of January 29, 2017 we owned 471,000 square feet of space, primarily in California, for our corporate headquarters and certain data center operations.
We believe that all of our facilities are adequate for our current needs and that suitable additional or substitute space will be available in the future to replace our existing facilities, or to accommodate the expansion of our operations, if necessary.
Item 3. LEGAL PROCEEDINGS
We are involved in lawsuits, claims and proceedings incident to the ordinary course of our business. These disputes, which are not currently material, are increasing in number as our business expands and our company grows. We review the need for any loss contingency reserves and establish reserves when, in the opinion of management, it is probable that a matter would result in liability, and the amount can be reasonably estimated. In view of the inherent difficulty of predicting the outcome of these matters, it may not be possible to determine whether any loss is probable or to reasonably estimate the amount of the loss until the case is close to resolution, in which case no reserve is established until that time. Any claims against us, whether meritorious or not, could result in costly litigation, require significant amounts of management time and result in the diversion of significant operational resources. The results of these lawsuits, claims and proceedings cannot be predicted with certainty. However, we believe that the ultimate resolution of these current matters will not have a material adverse effect on our consolidated financial statements taken as a whole.
Item 4. MINE SAFETY DISCLOSURES
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
| --- | --- |
MARKET INFORMATION
Our common stock is traded on the New York Stock Exchange, or the NYSE, under the symbol WSM. The following table sets forth the high and low selling prices of our common stock on the NYSE for the periods indicated:
| Fiscal 2016 | High | Low | ||||||||
| 4th Quarter | $56.94 | $45.98 | ||||||||
| 3rd Quarter | $57.40 | $45.96 | ||||||||
| 2nd Quarter | $61.03 | $47.66 | ||||||||
| 1st Quarter | $61.97 | $49.39 | ||||||||
| Fiscal 2015 | High | Low | ||||||||
| 4th Quarter | $75.90 | $47.33 | ||||||||
| 3rd Quarter | $89.38 | $71.03 | ||||||||
| 2nd Quarter | $85.37 | $74.75 | ||||||||
| 1st Quarter | $84.75 | $73.14 |
The closing price of our common stock on the NYSE on March 26, 2017 was $47.96.
STOCKHOLDERS
The number of stockholders of record of our common stock as of March 26, 2017 was 358. This number excludes stockholders whose stock is held in nominee or street name by brokers.
Table of Contents
PERFORMANCE GRAPH
This graph compares the cumulative total stockholder return for our common stock with those of the NYSE Composite Index and the S&P Retailing Index, our peer group index. The cumulative total return listed below assumed an initial investment of $100 and reinvestment of dividends. The graph shows historical stock price performance, including reinvestment of dividends, and is not necessarily indicative of future performance.
COMPARISON OF FIVE YEAR CUMULATIVE TOTAL RETURN*
Among Williams-Sonoma, Inc., the NYSE Composite Index,
and the S&P Retailing Index
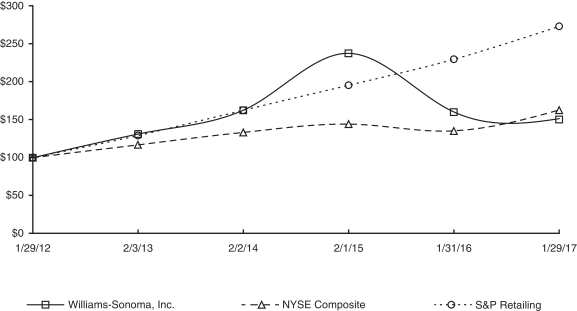
| 1/29/12 | 2/3/13 | 2/2/14 | 2/1/15 | 1/31/16 | 1/29/17 | |||||||
| Williams-Sonoma, Inc. | 100.00 | 131.04 | 162.36 | 237.56 | 160.06 | 151.39 | ||||||
| NYSE Composite Index | 100.00 | 116.94 | 133.26 | 144.28 | 135.18 | 162.58 | ||||||
| S&P Retailing Index | 100.00 | 129.17 | 162.55 | 195.46 | 229.73 | 273.22 |
*** Notes:**
| A. | The lines represent monthly index levels derived from compounded daily returns that include all dividends. |
|---|
| B. | The indices are re-weighted daily, using the market capitalization on the previous trading day. |
|---|
| C. | If the monthly interval, based on the fiscal year-end, is not a trading day, the preceding trading day is used. |
|---|
Table of Contents
DIVIDENDS
In fiscal 2016, fiscal 2015 and fiscal 2014, total cash dividends declared were approximately $133,588,000, or $1.48 per common share, $130,290,000, or $1.40 per common share, and $125,378,000, or $1.32 per common share, respectively. In March 2017, we announced that our Board of Directors had authorized a 5% increase in our quarterly cash dividend, from $0.37 to $0.39 per common share, subject to capital availability. Our quarterly cash dividend may be limited or terminated at any time.
STOCK REPURCHASE PROGRAMS
During fiscal 2016, we repurchased 2,871,480 shares of our common stock at an average cost of $52.68 per share and a total cost of $151,272,000. During fiscal 2015, we repurchased 2,950,438 shares of our common stock at an average cost of $76.26 per share and a total cost of $224,995,000. During fiscal 2014, we repurchased 3,331,557 shares of our common stock at an average cost of $67.35 per share and a total cost of $224,377,000.
The following table summarizes our repurchases of shares of our common stock during the fourth quarter of fiscal 2016 under our $500,000,000 stock repurchase program:
| Fiscal period | Total Number of Shares Purchased | Average Price Paid Per Share | Total Number of Shares Purchased as Part of a Publicly Announced Program | Maximum Dollar Value of Shares That May Yet Be Purchased Under the Program | ||||||||||||||
| October 31, 2016 | – November 27, 2016 | 179,052 | $ 49.33 | 179,052 | $ 437,851,000 | |||||||||||||
| November 28, 2016 | – December 25, 2016 | 256,723 | $ 54.46 | 256,723 | $ 423,871,000 | |||||||||||||
| December 26, 2016 | – January 29, 2017 | 271,232 | $ 49.01 | 271,232 | $ 410,578,000 | |||||||||||||
| Total | 707,007 | $ 51.07 | 707,007 | $ 410,578,000 |
Stock repurchases under our program may be made through open market and privately negotiated transactions at times and in such amounts as management deems appropriate. The timing and actual number of shares repurchased will depend on a variety of factors including price, corporate and regulatory requirements, capital availability and other market conditions. The stock repurchase program does not have an expiration date and may be limited or terminated at any time without prior notice.
Table of Contents
Item 6. SELECTED FINANCIAL DATA
| --- | --- |
Five-Year Selected Financial Data
| In thousands, except percentages, per share amounts and retail stores data | Fiscal 2016 (52 Weeks) | Fiscal 2015 (52 Weeks) | Fiscal 2014 (52 Weeks) | Fiscal 2013 (52 Weeks) | Fiscal 2012 (53 Weeks) | |||||||||||||||
| Results of Operations | ||||||||||||||||||||
| Net revenues | $ | 5,083,812 | $ | 4,976,090 | $ | 4,698,719 | $ | 4,387,889 | $ | 4,042,870 | ||||||||||
| Net revenue growth | 2.2% | 5.9% | 7.1% | 8.5% | 8.7% | |||||||||||||||
| Comparable brand revenue growth_1_ | 0.7% | 3.7% | 7.1% | 8.8% | 6.1% | |||||||||||||||
| Gross profit | $ | 1,883,310 | $ | 1,844,214 | $ | 1,800,504 | $ | 1,704,216 | $ | 1,592,476 | ||||||||||
| Gross margin | 37.0% | 37.1% | 38.3% | 38.8% | 39.4% | |||||||||||||||
| Operating income | $ | 472,599 | $ | 488,634 | $ | 502,265 | $ | 452,098 | $ | 409,163 | ||||||||||
| Operating margin_2_ | 9.3% | 9.8% | 10.7% | 10.3% | 10.1% | |||||||||||||||
| Net earnings | $ | 305,387 | $ | 310,068 | $ | 308,854 | $ | 278,902 | $ | 256,730 | ||||||||||
| Basic earnings per share | $ | 3.45 | $ | 3.42 | $ | 3.30 | $ | 2.89 | $ | 2.59 | ||||||||||
| Diluted earnings per share | $ | 3.41 | $ | 3.37 | $ | 3.24 | $ | 2.82 | $ | 2.54 | ||||||||||
| Weighted average basic shares outstanding during the period | 88,594 | 90,787 | 93,634 | 96,669 | 99,266 | |||||||||||||||
| Weighted average diluted shares outstanding during the period | 89,462 | 92,102 | 95,200 | 98,765 | 101,051 | |||||||||||||||
| Financial Position | ||||||||||||||||||||
| Working capital_3_ | $ | 405,924 | $ | 339,673 | $ | 515,975 | $ | 558,007 | $ | 659,645 | ||||||||||
| Total assets | $ | 2,476,879 | $ | 2,417,427 | $ | 2,330,277 | $ | 2,336,734 | $ | 2,187,679 | ||||||||||
| Return on assets | 12.5% | 13.1% | 13.2% | 12.3% | 12.0% | |||||||||||||||
| Net cash provided by operating activities | $ | 524,709 | $ | 544,026 | $ | 461,697 | $ | 453,769 | $ | 364,127 | ||||||||||
| Capital expenditures | $ | 197,414 | $ | 202,935 | $ | 204,800 | $ | 193,953 | $ | 205,404 | ||||||||||
| Long-term debt and other long-term obligations | $ | 71,215 | $ | 49,713 | $ | 62,698 | $ | 61,780 | $ | 50,216 | ||||||||||
| Stockholders’ equity | $ | 1,248,220 | $ | 1,198,226 | $ | 1,224,706 | $ | 1,256,002 | $ | 1,309,138 | ||||||||||
| Stockholders’ equity per share (book value) | $ | 14.29 | $ | 13.38 | $ | 13.33 | $ | 13.35 | $ | 13.39 | ||||||||||
| Return on equity | 25.0% | 25.6% | 24.9% | 21.7% | 20.0% | |||||||||||||||
| Annual dividends declared per share | $ | 1.48 | $ | 1.40 | $ | 1.32 | $ | 1.24 | $ | 0.88 | ||||||||||
| E-commerce Net Revenues | ||||||||||||||||||||
| E-commerce net revenue growth | 4.4% | 6.4% | 12.1% | 13.1% | 14.5% | |||||||||||||||
| E-commerce net revenues as a percent of net revenues | 51.8% | 50.7% | 50.5% | 48.2% | 46.2% | |||||||||||||||
| Retail Net Revenues | ||||||||||||||||||||
| Retail net revenue growth (decline) | (0.1% | ) | 5.4% | 2.4% | 4.6% | 4.1% | ||||||||||||||
| Retail net revenues as a percent of net revenues | 48.2% | 49.3% | 49.5% | 51.8% | 53.8% | |||||||||||||||
| Number of stores at year-end | 629 | 618 | 601 | 585 | 581 | |||||||||||||||
| Store selling square footage at year-end | 3,951,000 | 3,827,000 | 3,684,000 | 3,590,000 | 3,548,000 | |||||||||||||||
| Store leased square footage at year-end | 6,359,000 | 6,163,000 | 5,965,000 | 5,838,000 | 5,778,000 |
| 1 | Comparable brand revenue is calculated on a 52-week to 52-week basis, with the exception of fiscal 2012 which was calculated on a 53-week to 53-week basis. See definition of comparable brand revenue within “Management’s Discussion and Analysis of Financial Condition and Results of Operations.” |
|---|
| 2 | Operating margin is defined as operating income as a percent of net revenues. |
|---|
| 3 | In fiscal 2015, we prospectively adopted ASU 2015-17, Balance Sheet Classification of Deferred Taxes, and now present both deferred tax assets and deferred tax liabilities as noncurrent in our Consolidated Balance Sheets. Prior balance sheets were not retrospectively adjusted and, as a result, working capital for fiscal 2012, fiscal 2013 and fiscal 2014 may not be comparable to fiscal 2015 and fiscal 2016. |
|---|
The information set forth above is not necessarily indicative of future operations and should be read in conjunction with “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and the Consolidated Financial Statements and notes thereto in this Annual Report on Form 10-K.
Table of Contents
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
| --- | --- |
The following discussion and analysis of our financial condition, results of operations, and liquidity and capital resources for the 52 weeks ended January 29, 2017 (“fiscal 2016”), the 52 weeks ended January 31, 2016 (“fiscal 2015”), and the 52 weeks ended February 1, 2015 (“fiscal 2014”) should be read in conjunction with our Consolidated Financial Statements and notes thereto. All explanations of changes in operational results are discussed in order of magnitude.
OVERVIEW
Net revenues in fiscal 2016 increased by $107,722,000 or 2.2%, compared to fiscal 2015, with comparable brand revenue growth of 0.7%. This increase in net revenues was driven by a 4.4% increase in e-commerce net revenues (primarily driven by West Elm, Williams Sonoma and Rejuvenation), with particular strength in furniture. This net revenue increase was partially offset by a 0.1% decrease in retail net revenues (primarily in Pottery Barn and Williams Sonoma, partially offset by increases in West Elm and Rejuvenation). Total fiscal 2016 net revenue growth included a 7.5% increase in international revenues primarily related to our company-owned international operations.
In Pottery Barn, our largest brand, comparable brand revenues declined 3.5% in fiscal 2016 compared to fiscal 2015. This decrease was primarily driven by our furniture, decorative accessories and table top collections, partially offset by stronger sales in upholstery. In the Williams Sonoma brand, comparable brand revenues increased 1.3% in fiscal 2016 compared to fiscal 2015. Growth in cookware, cutlery, tabletop and our Williams Sonoma Home business contributed to these results. In West Elm, comparable brand revenues increased 12.8% in fiscal 2016 on top of 14.8% in fiscal 2015. Growth continued to be broad-based across categories, primarily furniture. In Pottery Barn Kids, comparable brand revenues declined 1.4% in fiscal 2016 compared to fiscal 2015. Strength in our furniture business was more than offset by softness in textiles and decorative accessories. In PBteen, comparable brand revenues declined 6.2% in fiscal 2016 compared to fiscal 2015. Strength in back to school and dorm categories was more than offset by weakness in textiles and out of stock inventory in key furniture collections and gifting categories. And in our emerging brands, Rejuvenation and Mark and Graham, net revenues increased 26.6%.
Additionally, in fiscal 2016, diluted earnings per share increased to $3.41, versus $3.37 in fiscal 2015, and we returned $284,811,000 to our stockholders through stock repurchases and dividends.
As we look forward to fiscal 2017, we plan to drive growth by focusing on our strategic priorities of innovation and operational excellence. We plan to increase our competitive advantage through innovation in e-commerce, our products and our services, as well as the retail experience. To accomplish this, we plan to invest in digital and online advertising initiatives. In Pottery Barn Kids and PBteen, we plan to drive innovation in product offerings across all stages of early life, and in Williams Sonoma, we plan to introduce high-quality products under the Williams Sonoma brand, as well as to develop innovative exclusives with our third party vendors. To enhance the customer experience in all of our stores, we plan to invest in point-of-sale technology and scheduling tools which will provide additional functionality and operational efficiencies. We plan to evaluate the role our retail stores can and should play and plan to invest in optimizing top-performing stores while closing underperforming stores. We also plan to continue to focus on operational excellence, driving strategies that directly improve our customers’ experience and value perceptions. We believe that collectively these strategies will extend our leadership position across all of our brands.
Table of Contents
Results of Operations
NET REVENUES
Net revenues consist of e-commerce net revenues and retail net revenues. E-commerce net revenues include sales of merchandise to customers through our e-commerce websites and our catalogs, as well as shipping fees. Retail net revenues include sales of merchandise to customers at our retail stores and to our franchisees, as well as shipping fees on any products shipped to our customers’ homes. Shipping fees consist of revenue received from customers for delivery of merchandise to their homes. Revenues are presented net of sales returns and other discounts.
| In thousands | Fiscal 2016 | % Total | Fiscal 2015 | % Total | Fiscal 2014 | % Total | ||||||||||||||||||
| E-commerce net revenues | $ | 2,633,602 | 51.8% | $ | 2,522,580 | 50.7% | $ | 2,370,694 | 50.5% | |||||||||||||||
| Retail net revenues | 2,450,210 | 48.2% | 2,453,510 | 49.3% | 2,328,025 | 49.5% | ||||||||||||||||||
| Net revenues | $ | 5,083,812 | 100.0% | $ | 4,976,090 | 100.0% | $ | 4,698,719 | 100.0% |
Net revenues in fiscal 2016 increased by $107,722,000 or 2.2%, compared to fiscal 2015, with comparable brand revenue growth of 0.7%. This increase in net revenues was driven by a 4.4% increase in e-commerce net revenues (primarily driven by West Elm, Williams Sonoma and Rejuvenation), with particular strength in furniture. This net revenue increase was partially offset by a 0.1% decrease in retail net revenues (primarily in Pottery Barn and Williams Sonoma, partially offset by increases in West Elm and Rejuvenation). Total fiscal 2016 net revenue growth included a 7.5% increase in international revenues primarily related to our company-owned international operations.
Net revenues in fiscal 2015 increased by $277,371,000, or 5.9%, compared to fiscal 2014, with comparable brand revenue growth of 3.7%. This increase in net revenues was driven by a 6.4% increase in e-commerce net revenues (primarily driven by West Elm, Williams Sonoma and Pottery Barn Kids), and a 5.4% increase in our retail net revenues (primarily driven by West Elm), with particular strength in furniture. Total fiscal 2015 net revenue growth included a 26.8% increase in international revenues primarily related to our franchise operations, and a 3.3% increase in retail leased square footage primarily due to 17 net new stores.
The following table summarizes our net revenues by brand for fiscal 2016, fiscal 2015 and fiscal 2014:
| In thousands | Fiscal 2016 | Fiscal 2015 | Fiscal 2014 | |||||||||
| Pottery Barn | $ | 2,024,218 | $ | 2,074,051 | $ | 2,022,331 | ||||||
| Williams Sonoma | 1,002,194 | 993,609 | 994,651 | |||||||||
| West Elm | 971,568 | 821,136 | 669,074 | |||||||||
| Pottery Barn Kids | 635,381 | 640,073 | 624,594 | |||||||||
| PBteen | 237,818 | 253,602 | 260,617 | |||||||||
| Other_1_ | 212,633 | 193,619 | 127,452 | |||||||||
| Total | $ | 5,083,812 | $ | 4,976,090 | $ | 4,698,719 |
| 1 | Primarily consists of net revenues from our international franchise operations, Rejuvenation, and Mark and Graham. |
|---|
Comparable Brand Revenue
Comparable brand revenue includes retail comparable store sales and e-commerce sales, as well as shipping fees, sales returns and other discounts associated with current period sales. Outlet comparable store net revenues are included in their respective brands. Comparable brand revenue excludes sales from certain operations until such time that we believe those sales are meaningful to evaluating the performance of the brand. Sales to our international franchisees have also been excluded as their stores and e-commerce websites are not operated by us.
Comparable stores are defined as permanent stores where gross square footage did not change by more than 20% in the previous 12 months and which have been open for at least 12 consecutive months without closure for seven or more consecutive days.
Table of Contents
| Comparable brand revenue growth (decline) | Fiscal 2016 | Fiscal 2015 | Fiscal 2014 | |||||||||
| Pottery Barn | (3.5% | ) | 1.9% | 5.8% | ||||||||
| Williams Sonoma | 1.3% | 1.1% | 3.8% | |||||||||
| West Elm | 12.8% | 14.8% | 18.2% | |||||||||
| Pottery Barn Kids | (1.4% | ) | 2.2% | 5.9% | ||||||||
| PBteen | (6.2% | ) | (2.7% | ) | 5.7% | |||||||
| Total | 0.7% | 3.7% | 7.1% |
RETAIL STORE DATA
| In thousands | Fiscal 2016 | Fiscal 2015 | Fiscal 2014 | |||||||||
| Retail net revenues | $ | 2,450,210 | $ | 2,453,510 | $ | 2,328,025 | ||||||
| Retail net revenue growth (decline) | (0.1% | ) | 5.4% | 2.4% | ||||||||
| Store count – beginning of year | 618 | 601 | 585 | |||||||||
| Store openings | 29 | 34 | 35 | |||||||||
| Store closings | (18 | ) | (17 | ) | (19 | ) | ||||||
| Store count – end of year | 629 | 618 | 601 | |||||||||
| Store selling square footage at year-end | 3,951,000 | 3,827,000 | 3,684,000 | |||||||||
| Store leased square footage (“LSF”) at year-end | 6,359,000 | 6,163,000 | 5,965,000 |
| Fiscal 2016 | Fiscal 2015 | Fiscal 2014 | ||||||||||||||||||||||
| Store Count | Avg. LSF Per Store | Store Count | Avg. LSF Per Store | Store Count | Avg. LSF Per Store | |||||||||||||||||||
| Williams Sonoma | 234 | 6,600 | 239 | 6,600 | 243 | 6,600 | ||||||||||||||||||
| Pottery Barn | 201 | 13,900 | 197 | 13,800 | 199 | 13,700 | ||||||||||||||||||
| West Elm | 98 | 13,300 | 87 | 13,200 | 69 | 13,700 | ||||||||||||||||||
| Pottery Barn Kids | 89 | 7,400 | 89 | 7,500 | 85 | 7,600 | ||||||||||||||||||
| Rejuvenation | 7 | 9,100 | 6 | 9,000 | 5 | 10,000 | ||||||||||||||||||
| Total | 629 | 10,100 | 618 | 10,000 | 601 | 9,900 |
COST OF GOODS SOLD
| In thousands | Fiscal 2016 | % Net Revenues | Fiscal 2015 | % Net Revenues | Fiscal 2014 | % Net Revenues | ||||||||||||||||||
| Cost of goods sold_1_ | $ | 3,200,502 | 63.0% | $ | 3,131,876 | 62.9% | $ | 2,898,215 | 61.7% |
| 1 | Includes occupancy expenses of $664,177,000, $631,817,000 and $603,357,000 in fiscal 2016, fiscal 2015 and fiscal 2014, respectively. |
|---|
Cost of goods sold includes cost of goods, occupancy expenses and shipping costs. Cost of goods consists of cost of merchandise, inbound freight expenses, freight-to-store expenses and other inventory related costs such as shrinkage, damages and replacements. Occupancy expenses consist of rent, depreciation and other occupancy costs, including common area maintenance, property taxes and utilities. Shipping costs consist of third-party delivery services and shipping materials.
Our classification of expenses in cost of goods sold may not be comparable to other public companies, as we do not include non-occupancy related costs associated with our distribution network in cost of goods sold. These costs, which include distribution network employment, third-party warehouse management and other distribution related administrative expenses, are recorded in selling, general and administrative expenses.
Within our reportable segments, the e-commerce channel does not incur freight-to-store or store occupancy expenses, and typically operates with lower markdowns and inventory shrinkage than the retail channel.
Table of Contents
However, the e-commerce channel incurs higher customer shipping, damage and replacement costs than the retail channel.
Fiscal 2016 vs. Fiscal 2015
Cost of goods sold increased by $68,626,000, or 2.2%, in fiscal 2016 compared to fiscal 2015. Cost of goods sold as a percentage of net revenues remained relatively flat, increasing less than 10 basis points to 63.0% in fiscal 2016 from 62.9% in fiscal 2015. Higher selling margins from reduced shipping and fulfillment-related costs as a result of our focus on our supply chain and inventory initiatives were offset by an increase in occupancy costs related to investments in our supply chain.
In the e-commerce channel, cost of goods sold as a percentage of net revenues decreased in fiscal 2016 compared to fiscal 2015 primarily driven by higher selling margins from reduced shipping and fulfillment-related costs as a result of our focus on our supply chain and inventory initiatives, partially offset by an increase in occupancy costs related to investments in our supply chain.
In the retail channel, cost of goods sold as a percentage of net revenues increased in fiscal 2016 compared to fiscal 2015, primarily driven by occupancy deleverage and lower selling margins.
Fiscal 2015 vs. Fiscal 2014
Cost of goods sold increased by $233,661,000, or 8.1%, in fiscal 2015 compared to fiscal 2014. Cost of goods sold as a percentage of net revenues increased to 62.9% in fiscal 2015 from 61.7% in fiscal 2014. This increase was driven by increased shipping and fulfillment-related costs and higher franchise revenues, which have a lower gross margin.
In the e-commerce channel, cost of goods sold as a percentage of net revenues increased in fiscal 2015 compared to fiscal 2014 primarily driven by increased shipping and fulfillment-related costs, and an increase in occupancy expenses.
In the retail channel, cost of goods sold as a percentage of net revenues increased for fiscal 2015 compared to fiscal 2014 driven by higher franchise revenues and increased fulfillment-related costs, partially offset by a reduction in advertising and employment costs.
SELLING, GENERAL AND ADMINISTRATIVE EXPENSES
| In thousands | Fiscal 2016 | % Net Revenues | Fiscal 2015 | % Net Revenues | Fiscal 2014 | % Net Revenues | ||||||||||||||||||
| Selling, general and administrative expenses | $ | 1,410,711 | 27.7% | $ | 1,355,580 | 27.2% | $ | 1,298,239 | 27.6% |
Selling, general and administrative expenses consist of non-occupancy related costs associated with our retail stores, distribution and manufacturing facilities, customer care centers, supply chain operations (buying, receiving and inspection) and corporate administrative functions. These costs include employment, advertising, third-party credit card processing and other general expenses.
We experience differing employment and advertising costs as a percentage of net revenues within the retail and e-commerce channels due to their distinct distribution and marketing strategies. Employment costs represent a greater percentage of net revenues within the retail channel as compared to the e-commerce channel. However, advertising expenses are higher within the e-commerce channel than in the retail channel.
Fiscal 2016 vs. Fiscal 2015
Selling, general and administrative expenses increased by $55,131,000, or 4.1%, in fiscal 2016 compared to fiscal 2015. Selling, general and administrative expenses as a percentage of net revenues increased to 27.7% in fiscal 2016 from 27.2% in fiscal 2015. This increase as a percentage of net revenues was primarily driven by severance-related reorganization charges of approximately $14,406,000 during fiscal 2016, as well as an increase in digital advertising expenses.
Table of Contents
In the e-commerce channel, selling, general and administrative expenses as a percentage of net revenues increased in fiscal 2016 compared to fiscal 2015 primarily driven by an increase in digital advertising expenses as a result of our focus on new customer acquisition, partially offset by the leverage of employment costs.
In the retail channel, selling, general and administrative expenses as a percentage of net revenues decreased in fiscal 2016 compared to fiscal 2015 primarily driven by the leverage of employment costs.
Fiscal 2015 vs. Fiscal 2014
Selling, general and administrative expenses for fiscal 2015 increased by $57,341,000, or 4.4%, compared to fiscal 2014. Selling, general and administrative expenses as a percentage of net revenues decreased to 27.2% in fiscal 2015 from 27.6% in fiscal 2014. This decrease as a percentage of net revenues was primarily driven by the leverage of advertising expenses and employment costs, partially offset by litigation settlement income of $7,414,000 recorded in fiscal 2014 that did not recur in fiscal 2015.
In the e-commerce channel, selling, general and administrative expenses as a percentage of net revenues was relatively flat for fiscal 2015 compared to fiscal 2014 primarily due to advertising leverage, offset by an increase in employment costs associated with incremental labor costs in our supply chain.
In the retail channel, selling, general and administrative expenses as a percentage of net revenues decreased for fiscal 2015 compared to fiscal 2014 primarily driven by the leverage of employment costs due to higher franchise revenues.
INCOME TAXES
Our effective income tax rate was 35.3% for fiscal 2016, 36.5% for fiscal 2015, and 38.5% for fiscal 2014. The decrease in the effective income tax rate in fiscal 2016 reflects a one-time favorable tax adjustment. The decrease in the effective income tax rate in fiscal 2015 compared to fiscal 2014 reflects fluctuations in the level and mix of earnings, as well as the favorable resolution of certain income tax matters.
LIQUIDITY AND CAPITAL RESOURCES
As of January 29, 2017, we held $213,713,000 in cash and cash equivalents, the majority of which is held in demand deposit accounts and money market funds, and of which $72,995,000 was held by our foreign subsidiaries. As is consistent within our industry, our cash balances are seasonal in nature, with the fourth quarter historically representing a significantly higher level of cash than other periods.
Throughout the fiscal year, we utilize our cash balances to build our inventory levels in preparation for our fourth quarter holiday sales. In fiscal 2017, we plan to use our cash resources to fund our inventory and inventory related purchases, advertising and marketing initiatives, property and equipment purchases, stock repurchases and dividend payments. In addition to our cash balances on hand, we have a $500,000,000 unsecured revolving line of credit (“credit facility”) that may be used to borrow revolving loans or to request the issuance of letters of credit. We may, upon notice to the administrative agent, request existing or new lenders to increase the credit facility by up to $250,000,000, at such lenders’ option, to provide for a total of $750,000,000 of unsecured revolving credit. During fiscal 2016, we had borrowings of $125,000,000 under the credit facility, all of which were repaid in the fourth quarter of fiscal 2016. During fiscal 2015, we had borrowings of $200,000,000 under the credit facility, all of which were repaid in the fourth quarter of fiscal 2015.
During fiscal 2014, we redeemed restricted cash deposits of $14,289,000 previously held under collateralized trust agreements. These deposits, which secured potential liabilities associated with our workers’ compensation and other insurance programs, were replaced with standby letters of credit. As of January 29, 2017, a total of $12,090,000 in issued but undrawn standby letters of credit was outstanding under the credit facility. Additionally, we had three unsecured letter of credit reimbursement facilities, which were amended during the year, for a total of $70,000,000, of which an aggregate of $6,565,000 was outstanding as of January 29, 2017. These letter of credit facilities represent only a future commitment to fund inventory purchases to which we had not taken legal title. We are currently in compliance with all of our financial covenants under the credit facility
Table of Contents
and, based on our current projections, we expect to remain in compliance throughout fiscal 2017. We believe our cash on hand, in addition to our available credit facilities, will provide adequate liquidity for our business operations over the next 12 months.
Cash Flows from Operating Activities
For fiscal 2016, net cash provided by operating activities was $524,709,000 compared to $544,026,000 in fiscal 2015. For fiscal 2016, net cash provided by operating activities was primarily attributable to net earnings adjusted for non-cash items, an increase in deferred rent and lease incentives, as well as accrued salaries, benefits and other liabilities, partially offset by a decrease in income taxes payable. This represents a decrease in net cash provided by operating activities compared to fiscal 2015 primarily due to an increase in income taxes paid in fiscal 2016 compared to fiscal 2015.
For fiscal 2015, net cash provided by operating activities was $544,026,000 compared to $461,697,000 in fiscal 2014. For fiscal 2015, net cash provided by operating activities was primarily attributable to net earnings adjusted for non-cash items and an increase in accounts payable, customer deposits and income taxes payable, partially offset by an increase in merchandise inventories. This represents an increase in net cash provided by operating activities compared to fiscal 2014 primarily due to an increase in accounts payable and income taxes payable due to the timing of payments, partially offset by an increase in merchandise inventories.
Cash Flows from Investing Activities
For fiscal 2016, net cash used in investing activities was $196,975,000 compared to $202,166,000 for fiscal 2015, and was primarily attributable to purchases of property and equipment. Net cash used in investing activities compared to fiscal 2015 decreased primarily due to a reduction in purchases of property and equipment.
For fiscal 2015, net cash used in investing activities was $202,166,000 compared to $188,600,000 for fiscal 2014, and was primarily attributable to purchases of property and equipment. Net cash used in investing activities compared to fiscal 2014 increased primarily due to restricted cash receipts received in fiscal 2014 that did not recur in fiscal 2015.
Cash Flows from Financing Activities
For fiscal 2016, net cash used in financing activities was $305,806,000 compared to $369,383,000 in fiscal 2015. For fiscal 2016, net cash used in financing activities was primarily attributable to repurchases of common stock of $151,272,000 and the payment of dividends of $133,539,000. Net cash used in financing activities compared to fiscal 2015 decreased primarily due to a decrease in repurchases of common stock.
For fiscal 2015, net cash used in financing activities was $369,383,000 compared to $379,020,000 in fiscal 2014. For fiscal 2015, net cash used in financing activities was primarily attributable to repurchases of common stock of $224,995,000 and the payment of dividends of $127,636,000. Net cash used in financing activities compared to fiscal 2014 decreased primarily due to a decrease in tax withholding payments related to stock-based awards.
Dividends
See section titled Dividends within Part II, Item 5 of this Annual Report on Form 10-K for further information.
Stock Repurchase Programs
See section titled Stock Repurchase Programs within Part II, Item 5 of this Annual Report on Form 10-K for further information.
Table of Contents
Contractual Obligations
The following table provides summary information concerning our future contractual obligations as of January 29, 2017:
| Payments Due by Period_1_ | ||||||||||||||||||||
| In thousands | Fiscal 2017 | Fiscal 2018 to Fiscal 2020 | Fiscal 2021 to Fiscal 2022 | Thereafter | Total | |||||||||||||||
| Operating leases_2_ | $ | 268,593 | $ | 703,308 | $ | 322,910 | $ | 531,699 | $ | 1,826,510 | ||||||||||
| Purchase obligations_3_ | 973,102 | 8,889 | 871 | — | 982,862 | |||||||||||||||
| Total | $ | 1,241,695 | $ | 712,197 | $ | 323,781 | $ | 531,699 | $ | 2,809,372 |
| 1 | This table excludes $28.7 million of liabilities for unrecognized tax benefits associated with uncertain tax positions as we are not able to reasonably estimate when and if cash payments for these liabilities will occur. This amount, however, has been recorded as a liability in our accompanying Consolidated Balance Sheet as of January 29, 2017. |
|---|
| 2 | Projected payments include only those amounts that are fixed and determinable as of the reporting date. See Note E to our Consolidated Financial Statements for discussion of our operating leases. |
|---|
| 3 | Represents estimated commitments at year-end to purchase inventory and other goods and services in the normal course of business to meet operational requirements. |
|---|
Other Contractual Obligations
We have other liabilities reflected in our Consolidated Balance Sheet. The payment obligations associated with these liabilities are not reflected in the table above due to the absence of scheduled maturities. The timing of these payments cannot be determined, except for amounts estimated to be payable in fiscal 2017, which are included in our current liabilities as of January 29, 2017.
We are party to a variety of contractual agreements under which we may be obligated to indemnify the other party for certain matters. These contracts primarily relate to commercial matters, operating leases, trademarks, intellectual property, and financial matters. Under these contracts, we may provide certain routine indemnification relating to representations and warranties or personal injury matters. The terms of these indemnifications range in duration and may not be explicitly defined. Historically, we have not made significant payments for these indemnifications. We believe that if we were to incur a loss in any of these matters, the loss would not have a material effect on our financial condition or results of operations.
Commercial Commitments
The following table provides summary information concerning our outstanding commercial commitments as of January 29, 2017:
| Amount of Outstanding Commitment Expiration By Period_1_ | ||||||||||||||||||||
| In thousands | Fiscal 2017 | Fiscal 2018 to Fiscal 2020 | Fiscal 2021 to Fiscal 2022 | Thereafter | Total | |||||||||||||||
| Standby letters of credit | $ | 12,090 | — | — | — | $ | 12,090 | |||||||||||||
| Letter of credit facilities | 6,565 | — | — | — | 6,565 | |||||||||||||||
| Credit facility | — | — | — | — | — | |||||||||||||||
| Total | $ | 18,655 | — | — | — | $ | 18,655 |
| 1 | See Note C to our Consolidated Financial Statements for discussion of our borrowing arrangements. |
|---|
IMPACT OF INFLATION
The impact of inflation (or deflation) on our results of operations for the past three fiscal years has not been significant. However, we cannot be certain of the effect inflation (or deflation) may have on our results of operations in the future.
Table of Contents
CRITICAL ACCOUNTING POLICIES AND ESTIMATES
Management’s Discussion and Analysis of Financial Condition and Results of Operations is based on our Consolidated Financial Statements, which have been prepared in accordance with accounting principles generally accepted in the United States of America. The preparation of these Consolidated Financial Statements requires us to make estimates and assumptions that affect the reported amounts of assets, liabilities, revenues and expenses and related disclosures of contingent assets and liabilities. These estimates and assumptions are evaluated on an ongoing basis and are based on historical experience and various other factors that we believe to be reasonable under the circumstances. Actual results could differ from these estimates.
We believe the following critical accounting policies used in the preparation of our Consolidated Financial Statements include the significant estimates and assumptions that we consider to be the most critical to an understanding of our financial statements because they involve significant judgments and uncertainties. See Note A to our Consolidated Financial Statements for a detailed description of each policy.
Merchandise Inventories
Merchandise inventories, net of an allowance for excess quantities and obsolescence, are stated at the lower of cost (weighted average method) or market. To determine if the value of our inventory should be reduced below cost, we consider current and anticipated demand, customer preferences and age of the merchandise. The significant estimates used in inventory valuation are obsolescence (including excess and slow-moving inventory and lower of cost or market reserves) and estimates of inventory shrinkage. We reserve for obsolescence based on historical trends, aging reports, specific identification and our estimates of future sales and selling prices.
Reserves for shrinkage are estimated and recorded throughout the year as a percentage of net sales based on historical shrinkage results, expectations of future shrinkage and current inventory levels. Actual shrinkage is recorded at year-end based on the results of our physical inventory counts and can vary from our estimates due to such factors as changes in operations, the mix of our inventory (which ranges from large furniture to small tabletop items) and execution against loss prevention initiatives in our stores, distribution facilities, off-site storage locations, and with our third-party warehouse and transportation providers. Accordingly, there is no shrinkage reserve at year-end. Historically, actual shrinkage has not differed materially from our estimates.
Our obsolescence and shrinkage reserve calculations contain estimates that require management to make assumptions and to apply judgment regarding a number of factors, including market conditions, the selling environment, historical results and current inventory trends. If actual obsolescence or shrinkage estimates change from our original estimate, we will adjust our reserves accordingly throughout the year. We have made no material changes to our assumptions included in the calculations of the obsolescence and shrinkage reserves throughout the year. In addition, we do not believe a 10% change in our inventory reserves would have a material effect on net earnings. As of January 29, 2017 and January 31, 2016, our inventory obsolescence reserves were $13,770,000 and $9,782,000, respectively.
Property and Equipment
Property and equipment is stated at cost. Depreciation is computed using the straight-line method over the estimated useful lives of the assets.
We review the carrying value of all long-lived assets for impairment, primarily at an individual store level, whenever events or changes in circumstances indicate that the carrying value of an asset may not be recoverable. Our impairment analyses determine whether projected cash flows from operations are sufficient to recover the carrying value of these assets. Impairment may result when the carrying value of the asset exceeds the estimated undiscounted future cash flows over its remaining useful life. For store impairment, our estimate of undiscounted future cash flows over the store lease term is based upon our experience, the historical operations of the stores and estimates of future store profitability and economic conditions. The estimates of future store profitability and economic conditions require estimating such factors as sales growth, gross margin, employment costs, lease escalations, inflation and the overall economics of the retail industry, and are therefore subject to variability and difficult to predict. Actual future results may differ from those estimates. If a long-lived asset is found to be
Table of Contents
impaired, the amount recognized for impairment is equal to the difference between the asset’s net carrying value and its fair value. Long-lived assets are measured at fair value on a nonrecurring basis using Level 3 inputs as defined in the fair value hierarchy. The fair value is based on the present value of estimated future cash flows using a discount rate that approximates our weighted average cost of capital.
During fiscal 2016, fiscal 2015 and fiscal 2014, we recorded asset impairment charges of approximately $1,765,000, $2,100,000 and $241,000, respectively, related to our retail stores, which is recorded within selling, general and administrative expenses.
Goodwill
Goodwill is not amortized, but rather is subject to impairment testing annually (on the first day of the fourth quarter), or between annual tests whenever events or changes in circumstances indicate that the fair value of a reporting unit may be below its carrying amount. We first perform a qualitative assessment to evaluate goodwill for potential impairment. If based on that assessment it is more likely than not that the fair value of the reporting unit is below its carrying value, a two-step quantitative test is necessary. The first step of the quantitative impairment test requires determining the fair value of the reporting unit. We use the income approach, whereby we calculate the fair value based on the present value of estimated future cash flows using a discount rate that approximates our weighted average cost of capital. The process of evaluating the potential impairment of goodwill is subjective and requires significant estimates and assumptions about the future such as sales growth, gross margins, employment rates, capital expenditures, inflation and future economic and market conditions. Actual future results may differ from those estimates. If the carrying value of the reporting unit’s assets and liabilities, including goodwill, exceeds its fair value, goodwill may be impaired. We then must perform a second step of comparing the implied fair value of the goodwill to its carrying value to determine the impairment charge, if any.
At January 29, 2017 and January 31, 2016, we had goodwill of $18,680,000 and $18,703,000, respectively, included in other assets primarily related to our fiscal 2011 acquisition of Rejuvenation Inc. In fiscal 2016, we performed a qualitative assessment of potential goodwill impairment and determined it was more likely than not that the fair value of each of our reporting units exceeded its carrying value. Accordingly, no further impairment testing of goodwill was performed and we did not recognize any goodwill impairment in fiscal 2016. In fiscal 2015 and fiscal 2014, we performed a quantitative goodwill impairment test and determined that the fair value of both our reporting units substantially exceeded their carrying value. Accordingly, we did not recognize any goodwill impairment in fiscal 2015 or fiscal 2014.
Self-Insured Liabilities
We are primarily self-insured for workers’ compensation, employee health benefits and product and general liability claims. We record self-insurance liability reserves based on claims filed, including the development of those claims, and an estimate of claims incurred but not yet reported. Factors affecting these estimates include future inflation rates, changes in severity, benefit level changes, medical costs and claim settlement patterns. Should a different number of claims occur compared to what was estimated, or costs of the claims increase or decrease beyond what was anticipated, reserves may need to be adjusted accordingly. We determine our workers’ compensation liability and product and general liability claims reserves based on an actuarial analysis of historical claims data. Self-insurance reserves for workers’ compensation, employee health benefits and product and general liability claims were $24,988,000 and $25,290,000 as of January 29, 2017 and January 31, 2016, respectively.
Income Taxes
Income taxes are accounted for using the asset and liability method. Under this method, deferred income taxes arise from temporary differences between the tax basis of assets and liabilities and their reported amounts in our Consolidated Financial Statements. We record reserves for our estimates of the additional income tax liability that is more likely than not to result from the ultimate resolution of foreign and domestic tax examinations. At any one time, many tax years are subject to examination by various taxing jurisdictions. The results of these audits and negotiations with taxing authorities may affect the ultimate settlement of these issues. We review and
Table of Contents
update the estimates used in the accrual for uncertain tax positions as more definitive information becomes available from taxing authorities, upon completion of tax examination, upon expiration of statutes of limitation, or upon occurrences of other events.
In order to compute income tax on an interim basis, we estimate what our effective tax rate will be for the full fiscal year and adjust these estimates throughout the year as necessary. Adjustments to our income tax provision due to changes in our estimated effective tax rate are recorded in the interim period in which the change occurs. The tax expense (or benefit) related to items other than ordinary income is individually computed and recognized when the items occur. Our effective tax rate in a given financial statement period may be materially impacted by changes in the mix and level of our earnings in various taxing jurisdictions.
Table of Contents
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
| --- | --- |
We are exposed to market risks, which include significant deterioration of the U.S. and foreign markets, changes in U.S. interest rates, foreign currency exchange rate fluctuations and the effects of economic uncertainty which may affect the prices we pay our vendors in the foreign countries in which we do business. We do not engage in financial transactions for trading or speculative purposes.
Interest Rate Risk
Our revolving line of credit has a variable interest rate which, when drawn upon, subjects us to risks associated with changes in that interest rate. During fiscal 2016, we had borrowings of $125,000,000 under the credit facility, all of which were repaid in the fourth quarter of fiscal 2016. A hypothetical increase or decrease of one percentage point on our existing variable rate debt instrument would not materially affect our results of operations or cash flows.
In addition, we have fixed and variable income investments consisting of short-term investments classified as cash and cash equivalents, which are also affected by changes in market interest rates. As of January 29, 2017, our investments, made primarily in demand deposit accounts and money market funds, are stated at cost and approximate their fair values.
Foreign Currency Risks
We purchase a significant amount of inventory from vendors outside of the U.S. in transactions that are denominated in U.S. dollars. Approximately 1% of our international purchase transactions are in currencies other than the U.S. dollar, primarily the euro. Any foreign currency impact related to these international purchase transactions was not significant to us during fiscal 2016 or fiscal 2015. Since we pay for the majority of our international purchases in U.S. dollars, however, a decline in the U.S. dollar relative to other foreign currencies would subject us to risks associated with increased purchasing costs from our vendors in their effort to offset any lost profits associated with any currency devaluation. We cannot predict with certainty the effect these increased costs may have on our financial statements or results of operations.
In addition, our retail and/or e-commerce businesses in Canada, Australia and the United Kingdom, and our operations throughout Asia and Europe, expose us to market risk associated with foreign currency exchange rate fluctuations. Substantially all of our purchases and sales are denominated in U.S. dollars, which limits our exposure to this risk. However, some of our foreign operations have a functional currency other than the U.S. dollar. While the impact of foreign currency exchange rate fluctuations was not material to us in fiscal 2016, we have continued to see volatility in the exchange rates in the countries in which we do business. As we continue to expand globally, the foreign currency exchange risk related to our foreign operations may increase. To mitigate this risk, we hedge a portion of our foreign currency exposure with foreign currency forward contracts in accordance with our risk management policies (see Note L to our Consolidated Financial Statements).
Table of Contents
| ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA |
|---|
Williams-Sonoma, Inc.
Consolidated Statements of Earnings
| In thousands, except per share amounts | Fiscal 2016 | Fiscal 2015 | Fiscal 2014 | |||||||||
| E-commerce net revenues | $ 2,633,602 | $ 2,522,580 | $ 2,370,694 | |||||||||
| Retail net revenues | 2,450,210 | 2,453,510 | 2,328,025 | |||||||||
| Net revenues | 5,083,812 | 4,976,090 | 4,698,719 | |||||||||
| Cost of goods sold | 3,200,502 | 3,131,876 | 2,898,215 | |||||||||
| Gross profit | 1,883,310 | 1,844,214 | 1,800,504 | |||||||||
| Selling, general and administrative expenses | 1,410,711 | 1,355,580 | 1,298,239 | |||||||||
| Operating income | 472,599 | 488,634 | 502,265 | |||||||||
| Interest (income) expense, net | 688 | 627 | 62 | |||||||||
| Earnings before income taxes | 471,911 | 488,007 | 502,203 | |||||||||
| Income taxes | 166,524 | 177,939 | 193,349 | |||||||||
| Net earnings | $ 305,387 | $ 310,068 | $ 308,854 | |||||||||
| Basic earnings per share | $ 3.45 | $ 3.42 | $ 3.30 | |||||||||
| Diluted earnings per share | $ 3.41 | $ 3.37 | $ 3.24 | |||||||||
| Shares used in calculation of earnings per share: | ||||||||||||
| Basic | 88,594 | 90,787 | 93,634 | |||||||||
| Diluted | 89,462 | 92,102 | 95,200 | |||||||||
| See Notes to Consolidated Financial Statements. Williams-Sonoma, Inc. Consolidated Statements of Comprehensive Income | ||||||||||||
| In thousands | Fiscal 2016 | Fiscal 2015 | Fiscal 2014 | |||||||||
| Net earnings | $ 305,387 | $ 310,068 | $ 308,854 | |||||||||
| Other comprehensive income (loss): | ||||||||||||
| Foreign currency translation adjustments | 1,523 | (7,958 | ) | (9,305 | ) | |||||||
| Change in fair value of derivative financial instruments, net of tax | (916 | ) | 1,074 | 806 | ||||||||
| Reclassification adjustment for realized (gain) loss on derivative financial instruments, net of tax | 106 | (1,184 | ) | (573 | ) | |||||||
| Comprehensive income | $ 306,100 | $ 302,000 | $ 299,782 |
See Notes to Consolidated Financial Statements.
Table of Contents
Williams-Sonoma, Inc.
Consolidated Balance Sheets
| In thousands, except per share amounts | Jan. 29, 2017 | Jan. 31, 2016 | ||||||
| ASSETS | ||||||||
| Current assets | ||||||||
| Cash and cash equivalents | $ 213,713 | $ 193,647 | ||||||
| Accounts receivable, net | 88,803 | 79,304 | ||||||
| Merchandise inventories, net | 977,505 | 978,138 | ||||||
| Prepaid catalog expenses | 23,625 | 28,919 | ||||||
| Prepaid expenses | 52,882 | 44,654 | ||||||
| Other assets | 10,652 | 11,438 | ||||||
| Total current assets | 1,367,180 | 1,336,100 | ||||||
| Property and equipment, net | 923,283 | 886,813 | ||||||
| Deferred income taxes, net | 135,238 | 141,784 | ||||||
| Other assets, net | 51,178 | 52,730 | ||||||
| Total assets | $ 2,476,879 | $ 2,417,427 | ||||||
| LIABILITIES AND STOCKHOLDERS’ EQUITY | ||||||||
| Current liabilities | ||||||||
| Accounts payable | $ 453,710 | $ 447,412 | ||||||
| Accrued salaries, benefits and other liabilities | 130,187 | 127,122 | ||||||
| Customer deposits | 294,276 | 296,827 | ||||||
| Income taxes payable | 23,245 | 67,052 | ||||||
| Other liabilities | 59,838 | 58,014 | ||||||
| Total current liabilities | 961,256 | 996,427 | ||||||
| Deferred rent and lease incentives | 196,188 | 173,061 | ||||||
| Other long-term obligations | 71,215 | 49,713 | ||||||
| Total liabilities | 1,228,659 | 1,219,201 | ||||||
| Commitments and contingencies – See Note I | ||||||||
| Stockholders’ equity | ||||||||
| Preferred stock: $.01 par value; 7,500 shares authorized; none issued | — | — | ||||||
| Common stock: $.01 par value; 253,125 shares authorized; | ||||||||
| 87,325 and 89,563 shares issued and outstanding at January 29, 2017 and January 31, 2016, re |
Showing the first 8K of 100K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
| --- | --- |
None.
Item 9A. CONTROLS AND PROCEDURES
| --- | --- |
Evaluation of Disclosure Controls and Procedures
As of January 29, 2017, an evaluation was performed by management, with the participation of our Chief Executive Officer (“CEO”) and our Chief Financial Officer (“CFO”), of the effectiveness of our disclosure controls and procedures. Based on that evaluation, our management, including our CEO and CFO, concluded that our disclosure controls and procedures are effective to ensure that information we are required to disclose in reports that we file or submit under the Securities Exchange Act of 1934 is accumulated and communicated to our management, including our CEO and CFO, as appropriate, to allow for timely discussions regarding required disclosures, and that such information is recorded, processed, summarized and reported within the time periods specified in the rules and forms of the SEC.
Management’s Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over the company’s financial reporting. These internal controls are designed to provide reasonable assurance that the reported information is fairly presented, that disclosures are adequate and that the judgments inherent in the preparation of financial statements are reasonable. There are inherent limitations in the effectiveness of any internal control, including the possibility of human error and the circumvention or overriding of controls. Further, because of changes in conditions, the effectiveness of any internal control may vary over time.
Table of Contents
Our management assessed the effectiveness of the company’s internal control over financial reporting as of January 29, 2017. In making this assessment, we used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) in Internal Control-Integrated Framework (2013). Based on our assessment using those criteria, our management concluded that, as of January 29, 2017, our internal control over financial reporting is effective.
Our independent registered public accounting firm audited the Consolidated Financial Statements included in this Annual Report on Form 10-K and the company’s internal control over financial reporting. Their audit report appears on pages 58 and 59 of this Annual Report on Form 10-K.
Changes in Internal Control Over Financial Reporting
There was no change in our internal control over financial reporting that occurred during our most recent fiscal quarter that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. OTHER INFORMATION
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
| --- | --- |
Information required by this Item is incorporated by reference herein to information under the headings “Election of Directors,” “Information Concerning Executive Officers,” “Audit and Finance Committee Report,” “Corporate Governance — Corporate Governance Guidelines and Code of Business Conduct and Ethics,” “Corporate Governance — Audit and Finance Committee” and “Section 16(a) Beneficial Ownership Reporting Compliance” in our Proxy Statement.
Item 11. EXECUTIVE COMPENSATION
| --- | --- |
Information required by this Item is incorporated by reference herein to information under the headings “Corporate Governance — Compensation Committee,” “Corporate Governance — Director Compensation,” and “Executive Compensation” in our Proxy Statement.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
| --- | --- |
Information required by this Item is incorporated by reference herein to information under the headings “Security Ownership of Principal Stockholders and Management” and “Equity Compensation Plan Information” in our Proxy Statement.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
| --- | --- |
Information required by this Item is incorporated by reference herein to information under the heading “Certain Relationships and Related Transactions” in our Proxy Statement.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
| --- | --- |
Information required by this Item is incorporated by reference herein to information under the headings “Committee Reports — Audit and Finance Committee Report” and “Proposal 4 — Ratification of Selection of Independent Registered Public Accounting Firm — Deloitte Fees and Services” in our Proxy Statement.
Table of Contents
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
| --- | --- |
| (a)(1) | Financial Statements: |
|---|
The following Consolidated Financial Statements of Williams-Sonoma, Inc. and subsidiaries and the related notes are filed as part of this report pursuant to Item 8:
Consolidated Statements of Earnings for the fiscal years ended January 29, 2017, January 31, 2016 and February 1, 2015
Consolidated Statements of Comprehensive Income for the fiscal years ended January 29, 2017, January 31, 2016 and February 1, 2015
Consolidated Balance Sheets as of January 29, 2017 and January 31, 2016
Consolidated Statements of Stockholders’ Equity for the fiscal years ended January 29, 2017, January 31, 2016 and February 1, 2015
Consolidated Statements of Cash Flows for the fiscal years ended January 29, 2017, January 31, 2016 and February 1, 2015
Notes to Consolidated Financial Statements
Report of Independent Registered Public Accounting Firm
Quarterly Financial Information
| (a)(2) | Financial Statement Schedules: Schedules have been omitted because they are not required, are not applicable, or because the required information, where material, is included in the financial statements, notes, or supplementary financial information. |
|---|
| (a)(3) | Exhibits: See Exhibit Index on pages 65 through 69. |
|---|
| (b) | Exhibits: See Exhibit Index on pages 65 through 69. |
|---|
| (c) | Financial Statement Schedules: Schedules have been omitted because they are not required or are not applicable. |
|---|
Table of Contents
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| WILLIAMS-SONOMA, INC. | ||||||||
| Date: March 30, 2017 | By | /s/ LAURA J. ALBER | ||||||
| Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| Date: March 30, 2017 | /s/ ADRIAN D.P. BELLAMY | |
| Adrian D.P. Bellamy | ||
| Chairman of the Board of Directors | ||
| Date: March 30, 2017 | /s/ LAURA J. ALBER | |
| Laura J. Alber | ||
| Chief Executive Officer | ||
| (principal executive officer) | ||
| Date: March 30, 2017 | /s/ JULIE P. WHALEN | |
| Julie P. Whalen | ||
| Chief Financial Officer | ||
| (principal financial officer and principal accounting officer) | ||
| Date: March 30, 2017 | /s/ ROSE MARIE BRAVO | |
| Rose Marie Bravo | ||
| Director | ||
| Date: March 30, 2017 | /s/ ADRIAN T. DILLON | |
| Adrian T. Dillon | ||
| Director | ||
| Date: March 30, 2017 | /s/ ANTHONY A. GREENER | |
| Anthony A. Greener | ||
| Director | ||
| Date: March 30, 2017 | /s/ TED W. HALL | |
| Ted W. Hall | ||
| Director | ||
| Date: March 30, 2017 | /s/ SABRINA SIMMONS | |
| Sabrina Simmons | ||
| Director | ||
| Date: March 30, 2017 | /s/ JERRY D. STRITZKE | |
| Jerry D. Stritzke | ||
| Director | ||
| Date: March 30, 2017 | ||
| Lorraine Twohill | ||
| Director |
Table of Contents
EXHIBIT INDEX TO ANNUAL REPORT ON FORM 10-K
FOR THE
FISCAL YEAR ENDED JANUARY 29, 2017
| EXHIBIT NUMBER | EXHIBIT DESCRIPTION | |
| CERTIFICATE OF INCORPORATION AND BYLAWS | ||
| 3.1 | Amended and Restated Certificate of Incorporation (incorporated by reference to Exhibit 3.1 to the Company’s Current Report on Form 8-K as filed with the Commission on May 25, 2011, File No. 001-14077) | |
| 3.2 | Amended and Restated Bylaws (incorporated by reference to Exhibit 3.1 to the Company’s Current Report on Form 8-K as filed with the Commission on February 2, 2016, File No. 001-14077) | |
| INSTRUMENTS DEFINING THE RIGHTS OF SECURITY HOLDERS, INCLUDING INDENTURES | ||
| 4.1 | Form of Common Stock Certificate (incorporated by reference to Exhibit 4.1 to the Company’s Current Report on Form 8-K as filed with the Commission on May 25, 2011, File No. 001-14077) | |
| FINANCING AGREEMENTS | ||
| 10.1 | Sixth Amended and Restated Credit Agreement, dated November 19, 2014, between the Company and Bank of America, N.A., as administrative agent, letter of credit issuer and swingline lender, Wells Fargo Bank, National Association, as syndication agent, JPMorgan Chase Bank, N.A., MUFG Union Bank, NA and U.S. Bank, National Association, as co-documentation agents, and the lenders party thereto (incorporated by reference to Exhibit 10.1 to the Company’s Annual Report on Form 10-K for the fiscal year ended February 1, 2015 as filed with the Commission on April 2, 2015, File No. 001-14077) | |
| 10.2 | Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd. and Bank of America, N.A., dated as of August 30, 2013 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the period ended November 3, 2013 as filed with the Commission on December 12, 2013, File No. 001-14077) | |
| 10.3 | First Amendment to Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd. and Bank of America, N.A., dated as of August 29, 2014 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the period ended November 2, 2014 as filed with the Commission on December 5, 2014, File No. 001-14077) | |
| 10.4 | Second Amendment to Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd. and Bank of America, N.A., dated as of August 28, 2015 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the period ended November 1, 2015 as filed with the Commission on December 11, 2015, File No. 001-14077) | |
| 10.5 | Third Amendment to Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd., and Bank of America, N.A., dated as of August 26, 2016 (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the period ended October 30, 2016 as filed with the Commission on December 7, 2016, File No. 001-14077) |
Table of Contents
| EXHIBIT NUMBER | EXHIBIT DESCRIPTION | |
| 10.6 | Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd. and Wells Fargo Bank, N.A., dated as of August 30, 2013 (incorporated by reference to Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q for the period ended November 3, 2013 as filed with the Commission on December 12, 2013, File No. 001-14077) | |
| 10.7 | First Amendment to Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd. and Wells Fargo Bank, N.A., dated as of August 29, 2014 (incorporated by reference to Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q for the period ended November 2, 2014 as filed with the Commission on December 5, 2014, File No. 001-14077) | |
| 10.8 | Second Amendment to Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd. and Wells Fargo Bank, N.A., dated as of August 28, 2015 (incorporated by reference to Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q for the period ended November 1, 2015 as filed with the Commission on December 11, 2015, File No. 001-14077) | |
| 10.9 | Third Amendment to Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd., and Wells Fargo Bank, N.A., dated as of August 26, 2016 (incorporated by reference to Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q for the period ended October 30, 2016 as filed with the Commission on December 7, 2016, File No. 001-14077) | |
| 10.10 | Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd. and U.S. Bank National Association, dated as of August 30, 2013 (incorporated by reference to Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q for the fiscal quarter ended November 3, 2013 as filed with the Commission on December 12, 2013, File No. 001-14077) | |
| 10.11 | First Amendment to Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd. and U.S. Bank National Association, dated as of August 29, 2014 (incorporated by reference to Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q for the fiscal quarter ended November 2, 2014 as filed with the Commission on December 5, 2014, File No. 001-14077) | |
| 10.12 | Second Amendment to Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd. and U.S. Bank National Association, dated as of August 28, 2015 (incorporated by reference to Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q for the period ended November 1, 2015 as filed with the Commission on December 11, 2015, File No. 001-14077) | |
| 10.13 | Third Amendment to Reimbursement Agreement between the Company, Williams-Sonoma Singapore Pte. Ltd., and U.S. Bank National Association, dated as of August 26, 2016 (incorporated by reference to Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q for the period ended October 30, 2016 as filed with the Commission on December 7, 2016, File No. 001-14077) | |
| STOCK PLANS | ||
| 10.14+ | Williams-Sonoma, Inc. 2000 Nonqualified Stock Option Plan (incorporated by reference to Exhibit 4 to the Company’s Registration Statement on Form S-8 as filed with the Commission on October 27, 2000, File No. 333-48750) |
Table of Contents
| EXHIBIT NUMBER | EXHIBIT DESCRIPTION | |
| 10.15+ | Williams-Sonoma, Inc. 2001 Long-Term Incentive Plan, as amended (incorporated by reference to Exhibit D to the Company’s definitive proxy statement on Schedule A as filed on April 7, 2011, File No. 001-14077) | |
| 10.16+ | Forms of Notice of Grant and Stock Option Agreement under the Company’s 2000 Nonqualified Stock Option Plan and 2001 Long-Term Incentive Plan (incorporated by reference to Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q for the period ended October 31, 2004 as filed with the Commission on December 10, 2004, File No. 001-14077) | |
| 10.17+ | Form of Williams-Sonoma, Inc. 2001 Long-Term Incentive Plan Stock-Settled Stock Appreciation Right Award Agreement for Director Grants (incorporated by reference to Exhibit 10.31 to the Company’s Annual Report on Form 10-K for the fiscal year ended February 3, 2008 as filed with the Commission on April 3, 2008, File No. 001-14077) | |
| 10.18+ | Form of Williams-Sonoma, Inc. 2001 Long-Term Incentive Plan Stock-Settled Stock Appreciation Right Award Agreement for Employee Grants (incorporated by reference to Exhibit 10.2 to the Company’s Current Report on Form 8-K filed with the Commission on March 22, 2010, File No. 001-14077) | |
| 10.19+ | Williams-Sonoma, Inc. 2001 Long-Term Incentive Plan Stock-Settled Stock Appreciation Right Award Agreement for CEO Grant (incorporated by reference to Exhibit 10.38 to the Company’s Annual Report on Form 10-K for the fiscal year ended February 1, 2009 as filed with the Commission on April 2, 2009, File No. 001-14077) | |
| 10.20+ | Form of Williams-Sonoma, Inc. 2001 Long-Term Incentive Plan Restricted Stock Unit Award Agreement for Grants to Non-Employee Directors (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the period ended May 4, 2014 as filed with the Commission on June 12, 2014, File No. 001-14077) | |
| 10.21+ | Form of Williams-Sonoma, Inc. 2001 Long-Term Incentive Plan Restricted Stock Unit Award Agreement for Grants to Employees (incorporated by reference to Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q for the period ended May 4, 2014 as filed with the Commission on June 12, 2014, File No. 001-14077) | |
| 10.22+ | Form of Williams-Sonoma, Inc. 2001 Long Term Incentive Plan Performance Stock Unit Award Agreement for Grants to Employees (incorporated by reference to Exhibit 10.15 to the Company’s Annual Report on Form 10-K for the fiscal year ended February 2, 2014 as filed with the Commission on April 3, 2014, File No. 001-14077) | |
| OTHER INCENTIVE PLANS | ||
| 10.23+ | Williams-Sonoma, Inc. 2001 Incentive Bonus Plan, as amended (incorporated by reference to the Company’s Definitive Proxy Statement on Schedule 14A as filed with the Commission on April 6, 2012, File No. 001-14077) | |
| 10.24+ | Williams-Sonoma, Inc. Pre-2005 Executive Deferral Plan (incorporated by reference to Exhibit 10.40 to the Company’s Annual Report on Form 10-K for the fiscal year ended February 1, 2009 as filed with the Commission on April 2, 2009, File No. 001-14077) |
Table of Contents
| EXHIBIT NUMBER | EXHIBIT DESCRIPTION | |
| 10.25+ | Williams-Sonoma, Inc. Amended and Restated Executive Deferred Compensation Plan (incorporated by reference to Exhibit 10.19 to the Company’s Annual Report on Form 10-K for the fiscal year ended February 1, 2015 as filed with the Commission on April 2, 2015, File No. 001-14077) | |
| 10.26+ | Williams-Sonoma, Inc. 401(k) Plan, as amended and restated effective January 1, 2016 (incorporated by reference to Exhibit 10.23 to the Company’s Annual Report on Form 10-K for the fiscal year ended January 31, 2016 as filed with the Commission on March 31, 2016, File No. 001-14077) | |
| PROPERTIES | ||
| 10.27 | Memorandum of Understanding between the Company and the State of Mississippi, Mississippi Business Finance Corporation, Desoto County, Mississippi, the City of Olive Branch, Mississippi and Hewson Properties, Inc., dated August 24, 1998 (incorporated by reference to Exhibit 10.6 to the Company’s Quarterly Report on Form 10-Q for the period ended August 2, 1998 as filed with the Commission on September 14, 1998, File No. 001-14077) | |
| 10.28 | Olive Branch Distribution Facility Lease, dated December 1, 1998, between the Company as lessee and WSDC, LLC (the successor-in-interest to Hewson/Desoto Phase I, L.L.C.) as lessor (incorporated by reference to Exhibit 10.3D to the Company’s Annual Report on Form 10-K for the fiscal year ended January 31, 1999 as filed with the Commission on April 30, 1999, File No. 001-14077) | |
| 10.29 | First Amendment, dated September 1, 1999, to the Olive Branch Distribution Facility Lease between the Company as lessee and WSDC, LLC (the successor-in-interest to Hewson/Desoto Phase I, L.L.C.) as lessor, dated December 1, 1998 (incorporated by reference to Exhibit 10.3B to the Company’s Annual Report on Form 10-K for the fiscal year ended January 30, 2000 as filed with the Commission on May 1, 2000, File No. 001-14077) | |
| 10.30 | Lease for an additional Company distribution facility located in Olive Branch, Mississippi between Williams-Sonoma Retail Services, Inc. as lessee and SPI WS II, LLC (the successor-in-interest to Hewson/Desoto Partners, L.L.C.) as lessor, dated November 15, 1999 (incorporated by reference to Exhibit 10.14 to the Company’s Annual Report on Form 10-K for the fiscal year ended January 30, 2000 as filed with the Commission on May 1, 2000, File No. 001-14077) | |
| EMPLOYMENT AGREEMENTS | ||
| 10.31+ | Amended and Restated Employment Agreement with Laura Alber, dated September 6, 2012 (incorporated by reference to Exhibit 10.4 to the Company’s Quarterly Report on Form 10-Q for the period ended October 28, 2012 as filed with the Commission December 7, 2012, File No. 001-14077) | |
| 10.32+ | Amended and Restated Management Retention Agreement with Laura Alber, dated September 6, 2012 (incorporated by reference to Exhibit 10.5 to the Company’s Quarterly Report on Form 10-Q for the period ended October 28, 2012 as filed with the Commission December 7, 2012, File No. 001-14077) |
Table of Contents
| EXHIBIT NUMBER | EXHIBIT DESCRIPTION | |
| 10.33+ | Amended and Restated 2012 EVP Level Management Retention Plan (incorporated by reference to Exhibit 10.30 to the Company’s Annual Report on Form 10-K for the fiscal year ended January 31, 2016 as filed with the Commission on March 31, 2016, File No. 001-14077) | |
| OTHER AGREEMENTS | ||
| 10.34+ | Form of Williams-Sonoma, Inc. Indemnification Agreement (incorporated by reference to Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q for the quarter ended July 31, 2011 as filed with the Commission on September 9, 2011, File No. 001-14077) | |
| OTHER EXHIBITS | ||
| 21.1* | Subsidiaries | |
| 23.1* | Consent of Independent Registered Public Accounting Firm | |
| CERTIFICATIONS | ||
| 31.1* | Certification of Chief Executive Officer, pursuant to Rule 13a-14(a) and Rule 15d-14(a) of the Securities Exchange Act, as amended | |
| 31.2* | Certification of Chief Financial Officer, pursuant to Rule 13a-14(a) and Rule 15d-14(a) of the Securities Exchange Act, as amended | |
| 32.1* | Certification of Chief Executive Officer, pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002 | |
| 32.2* | Certification of Chief Financial Officer, pursuant to 18 U.S.C. Section 1350, as adopted pursuant to Section 906 of the Sarbanes-Oxley Act of 2002 | |
| XBRL | ||
| 101.INS* | XBRL Instance Document | |
| 101.SCH* | XBRL Taxonomy Extension Schema Document | |
| 101.CAL* | XBRL Taxonomy Extension Calculation Linkbase Document | |
| 101.DEF* | XBRL Taxonomy Extension Definition Linkbase Document | |
| 101.LAB* | XBRL Taxonomy Extension Label Linkbase Document | |
| 101.PRE* | XBRL Taxonomy Extension Presentation Linkbase Document |
| * | Filed herewith. |
|---|
| + | Indicates a management contract or compensatory plan or arrangement. |
|---|