 filings.tools
Williams-Sonoma 10-K 2021-01-31
Filed 2021-03-30. 22 sections, 336K characters. Original on sec.gov · Markdown · JSON
Cover and table of contents
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM
10-K
(Mark One):
| ☒ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the fiscal year ended January 31, 2021.
OR
| ☐ | TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 |
|---|
For the transition period from
to
Commission file number
001-14077
WILLIAMS-SONOMA, INC.
(Exact name of registrant as specified in its charter)
| Delaware | 94-2203880 | |
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |
| 3250 Van Ness Avenue, San Francisco, CA | 94109 | |
| (Address of principal executive offices) | (Zip Code) |
Registrant’s telephone number, including area code:
(415) 421-7900
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class: | Trading Symbol(s): | Name of each exchange on which registered: | ||
| Common Stock, par value $.01 per share | WSM | New York Stock Exchange, Inc. |
Securities registered pursuant to Section 12(g) of the Act: None
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. Yes ☒ No ☐
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. Yes ☐ No ☒
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. Yes ☒ No ☐
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation
S-T
(§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such files). Yes ☒ No ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a
non-accelerated
filer, a smaller reporting company, or emerging growth company. See definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company,” and “emerging growth company” in Rule
12b-2
of the Exchange Act.
Large accelerated
filer
☒ Accelerated filer ☐ Non-accelerated
filer ☐
Smaller reporting company ☐ Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. ☒
Indicate by check mark whether the registrant is a shell company (as defined in Rule
12b-2
of the Act). Yes ☐ No ☒
As of August 2, 2020, the approximate aggregate market value of the registrant’s common stock held by
non-affiliates
was $6,720,032,000. It is assumed for purposes of this computation that an affiliate includes all persons as of August 2, 2020 listed as executive officers and directors with the Securities and Exchange Commission. This aggregate market value includes all shares held in the Williams-Sonoma, Inc. Stock Fund within the registrant’s 401(k) Plan.
As of March 21, 2021, 76,192,973 shares of the registrant’s common stock were outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of our definitive Proxy Statement for the 2021 Annual Meeting of Stockholders, also referred to in this Annual Report on Form
10-K
as our Proxy Statement, which will be filed with the Securities and Exchange Commission, or SEC, have been incorporated in Part III hereof.
FORWARD-LOOKING STATEMENTS
This Annual Report on Form
10-K
and the letter to stockholders contained in this Annual Report contain forward-looking statements within the “safe harbor” provisions of the Private Securities Litigation Reform Act of 1995 that involve risks and uncertainties, as well as assumptions that, if they do not fully materialize or prove incorrect, could cause our business and operating results to differ materially from those expressed or implied by such forward-looking statements. Such forward-looking statements include, without limitation, statements related to: projections of earnings, revenues, growth and other financial items; the strength of our business and our brands; our ability to execute strategic priorities and growth initiatives regarding digital leadership, product and technology innovation, cross-brand initiatives, retail transformation and operational excellence; our beliefs about our competitive advantages and areas of potential future growth in the market; our ability to drive long-term sustainable returns; the plans, strategies, initiatives and objectives of management for future operations; our brands, products and related initiatives, including our ability to introduce new brands, brand extensions, products and product lines and bring in new customers; our belief that our
e-commerce
websites and direct-mail catalogs act as a cost-efficient means of testing market acceptance of new products and new brands; the complementary nature of our
e-commerce
and retail channels; our marketing efforts; our acquisition of Outward, Inc., including the valuation of intangible assets acquired; our global business and expansion efforts, including franchise, other third-party arrangements and company-owned operations; our ability to attract new customers; the seasonal variations in demand; our ability to recruit, retain and motivate skilled personnel; our belief in the reasonableness of the steps taken to protect the security and confidentiality of the information we collect; our belief in the adequacy of our facilities and the availability of suitable additional or substitute space; our belief in the ultimate resolution of current legal proceedings; the payment of dividends; our stock repurchase program; our capital allocation strategy in fiscal 2021; our planned use of cash in fiscal 2021; our compliance with financial covenants; our belief that our cash on hand and available credit facilities will provide adequate liquidity for our business operations over the next 12 months; the impact of the 2017 Tax Cuts and Jobs Act; the impact of tariffs on our business and our results of operations; our belief regarding the effects of potential losses under our indemnification obligations; the impact of inflation; the effects of changes in our inventory reserves; the impact of new accounting pronouncements; the impact of the coronavirus on our retail store operations, global supply chain and customer spending and demand; and statements of belief and statements of assumptions underlying any of the foregoing. You can identify these and other forward-looking statements by the use of words such as “will,” “may,” “should,” “expects,” “plans,” “anticipates,” “believes,” “estimates,” “predicts,” “intends,” “potential,” “continue,” or the negative of such terms, or other comparable terminology.
The risks, uncertainties and assumptions referred to above that could cause our results to differ materially from the results expressed or implied by such forward-looking statements include, but are not limited to, those discussed under the heading “Risk Factors” in Item 1A hereto and the risks, uncertainties and assumptions discussed from time to time in our other public filings and public announcements. All forward-looking statements included in this document are based on information available to us as of the date hereof, and we assume no obligation to update these forward-looking statements.
WILLIAMS-SONOMA, INC.
ANNUAL REPORT ON FORM
10-K
FISCAL YEAR ENDED JANUARY 31, 2021
TABLE OF CONTENTS
PART I
Item 1. BUSINESS
| --- | --- |
OVERVIEW
Williams-Sonoma, Inc., (“the Company”) incorporated in 1973, is an omni-channel specialty retailer of high-quality products for the home.
In 1956, our founder, Chuck Williams, turned a passion for cooking and eating with friends into a small business with a big idea. He opened a store in Sonoma, California, to sell the French cookware that intrigued him while visiting Europe but that could not be found in America. Chuck’s business, which set a standard for customer service, took off and helped fuel a revolution in American cooking and entertaining that continues today.
In the decades that followed, the quality of our products, our ability to identify new opportunities in the market and our people-first approach to business have facilitated our expansion beyond the kitchen into nearly every area of the home. Growth across the Williams-Sonoma, Inc. portfolio has been fueled by three areas of strategic investment: brand experimentation and innovation, for a
best-in-class
approach to omni-channel retail experiences; operational excellence across the enterprise, from quality product and sourcing, to efficient manufacturing and supply chain; and culture and corporate social responsibility, from commitments to foster women in leadership and embrace diversity, to a healthy impact on our community and environment.
Williams-Sonoma, Inc. is the world’s largest digital-first, design-led and sustainable home retailer. Our products represent distinct merchandise strategies — Williams Sonoma, Pottery Barn, Pottery Barn Kids, Pottery Barn Teen, West Elm, Williams Sonoma Home, Rejuvenation, and Mark and Graham — are marketed through
e-commerce
websites, direct-mail catalogs and retail stores. These brands are also part of The Key Rewards, our
free-to-join
loyalty program that offers members exclusive benefits across the Williams-Sonoma family of brands. We operate in the U.S., Puerto Rico, Canada, Australia and the United Kingdom, offer international shipping to customers worldwide, and have unaffiliated franchisees that operate stores in the Middle East, the Philippines, Mexico, South Korea and India, as well as
e-commerce
websites in certain locations. We are also proud to lead the industry with our Environmental, Social and Governance (“ESG”) efforts.
Williams Sonoma
From the beginning, our namesake brand, Williams Sonoma, has been bringing people together around food. A leading specialty retailer of high-quality products for the kitchen and home, the brand seeks to provide world-class service and an engaging customer experience. Williams Sonoma products include everything for cooking, dining and entertaining, including: cookware, tools, electrics, cutlery, tabletop and bar, outdoor, furniture and a vast library of cookbooks. The brand also includes Williams Sonoma Home, a premium concept that offers classic home furnishings and decorative accessories, extending the Williams Sonoma lifestyle beyond the kitchen into every room of the home.
Pottery Barn
Established in 1949 and acquired by Williams-Sonoma, Inc. in 1986, Pottery Barn is a premier omni-channel home furnishings retailer. America’s most meaningful, beautiful design source, Pottery Barn brings together good products, people and values — seeking inspiration, quality, sustainability and service in everything we do. Thoughtfully designed and crafted to last, Pottery Barn’s furniture, bedding, lighting, rugs, table essentials, decorative accessories and more can be loved for a lifetime.
Pottery Barn Kids
Kids are, and have always been, the inspiration behind what we do at Pottery Barn Kids. Since 1999, it’s been our mission to bring the utmost in quality, sustainability, safety and style into every family’s home. Most importantly, all our designs are rigorously tested to meet the highest child safety standards and expertly crafted from the best materials to last beyond their childhood years.
West Elm
Born in Brooklyn in 2002, West Elm is dedicated to transforming people’s lives and spaces through creativity, style and purpose. West Elm creates unique, modern and affordable home decor and curate a global selection of local, ethically-sourced and Fair Trade Certified products, available online and in our stores worldwide.
Pottery Barn Teen
Launched in 2003, Pottery Barn Teen is the first home concept to focus exclusively on the teen market. Our purpose is to make safe and sustainable designs that inspire teens to create the world they want to live in. We’re designing everything from organic bedding to multi-purpose furniture that adapts and lasts. Our mission is to create for the future.
Rejuvenation
Rejuvenation, founded in 1977 with a passion for timeless design and quality craftsmanship, was acquired by Williams-Sonoma, Inc. in 2011. With design, manufacturing and distribution facilities in Portland, Oregon, Rejuvenation offers a wide assortment of
made-to-order
lighting, hardware, furniture and home décor inspired by history, designed for today and made to last for years to come.
Mark and Graham
Launched in 2012, Mark and Graham is designed to be a premier online destination for personalized gift buying. With over 100 monograms and font types to choose from, a Mark and Graham purchase is uniquely personal. The brand’s product lines include women’s and men’s accessories, small leather goods, jewelry, key item apparel, paper, entertaining and bar, home décor and seasonal items.
Outward
In 2017, we acquired Outward, Inc., a
3-D
imaging and augmented reality platform for the home furnishings and décor industry. Headquartered in San Jose, California, Outward’s technology enables scalable applications in product visualization, digital room design and augmented and virtual reality.
OPERATIONS
As of January 31, 2021, we had the following merchandise strategies: Williams Sonoma, Pottery Barn, Pottery Barn Kids, Pottery Barn Teen, West Elm, Williams Sonoma Home, Rejuvenation and Mark and Graham, which sell our products through our
e-commerce
websites, direct-mail catalogs and retail stores. We offer shipping from many of our brands to countries worldwide, while our catalogs reach customers throughout the U.S. The
e-commerce
business complements the retail business by building brand awareness and acting as an effective advertising vehicle. We believe that our
e-commerce
websites and our direct-mail catalogs act as a cost-efficient means of testing market acceptance of new products and new brands. Leveraging these insights and our omni-channel positioning, our marketing efforts, including digital advertising and the circulation of catalogs, are targeted toward driving sales to each of our channels. Consistent with our published privacy policies, we send our catalogs to addresses from our proprietary customer list, as well as to addresses from lists of other mail order direct marketers, magazines and companies with which we establish a business relationship. In accordance with prevailing industry practice and our privacy policies, we may also rent our list to select mailers. Our customer mailings are continually updated to include new prospects and to eliminate
non-responders.
In addition, the retail business complements the
e-commerce
business by building brand awareness and attracting new customers to our brands. Our retail stores serve as billboards for our brands, which we believe inspires our customers to also shop online and through our catalogs. We operate 581 stores, which include 538 stores in 42 states, Washington, D.C. and Puerto Rico, 21 stores in Canada, 19 stores in Australia and 3 stores in the United Kingdom. We also have multi-year franchise agreements with third parties in the Middle East, the Philippines, Mexico, South Korea and India that currently operate 136 franchised locations as well as
e-commerce
websites in certain locations.
SUPPLIERS
We purchase most of our merchandise from numerous foreign and domestic manufacturers and importers, the largest of which accounted for approximately 4% of our purchases during fiscal 2020. Approximately 65% of our merchandise purchases in fiscal 2020 were sourced from foreign vendors, predominantly in Asia and Europe. Substantially all of these purchases were negotiated and paid for in U.S. dollars. In addition, we manufacture merchandise, primarily upholstered furniture and lighting, at our facilities located in North Carolina, California, Oregon and Mississippi.
COMPETITION AND SEASONALITY
The specialty
e-commerce
and retail businesses are highly competitive. Our
e-commerce
websites, direct-mail catalogs and retail stores compete with other retailers, including
e-commerce
retailers, large department stores, discount retailers, other specialty retailers offering home-centered assortments and other direct-mail catalogs. The substantial sales growth in the
direct-to-customer
industry within the last decade, particularly in
e-commerce,
has encouraged the entry of many new competitors, including discount retailers selling undifferentiated products at reduced prices, new business models and has resulted in increased competition from established companies. We compete on the basis of our brand authority, the quality of our merchandise, our customer service, our proprietary customer list, our e-commerce websites and marketing capabilities, the location and appearance of our stores, as well as our in-house design, our digital-first channel strategy, and our values, which we believe have become increasingly relevant and set us apart from our competitors. Our in-house teams design our own products and work with our talented vendors to bring quality, sustainable products to market through our high-touch multichannel platform.
Our business is subject to substantial seasonal variations in demand. Historically, a significant portion of our net revenues and net earnings have been realized during the period from October through January, and levels of net revenues and net earnings have typically been lower during the period from February through September. We believe this is the general pattern associated with the retail industry. In preparation for and during our holiday selling season, we hire a substantial number of additional temporary employees, primarily in our retail stores, customer care centers and distribution facilities, and incur significant fixed catalog production and mailing costs.
HUMAN CAPITAL MANAGEMENT
As of January 31, 2021, we had approximately 21,000 employees, of whom approximately 12,200 were full-time. In preparation for and during our fiscal 2020 holiday selling season, we hired approximately 10,000 temporary employees, primarily in our retail stores, customer care centers and distribution facilities. None of our employees are represented by a collective bargaining agreement.
In fiscal 2020, we announced three new ESG pillars as key areas of focus for our company. One of those three pillars is “People” in keeping with our long-held “People First” culture. This includes the following areas of focus:
Employee Engagement
We conduct an annual Associate Opinion Survey to directly engage with and collect feedback from our associates, which we use to improve the experience of our teams. Our human resources department maintains an open-door policy for associates to report concerns, and we provide an anonymous reporting hotline, available in multiple languages and managed by an independent company not affiliated with us. We strive to deliver a workplace experience where the quality of our engagement with fellow associates, business partners and customers matches the quality of the products and services we bring to the marketplace.
Talent Development
We invest in our employees through accessible resources and structured training programs that help our associates to create the career they envision for themselves. We offer a large selection of development opportunities for our employees including
in-person
and online learning, as well as professional development courses, such as goal setting, unconscious bias and inclusive leadership training. We have a company-wide
Advisor Program, which matches associates in a Manager and above role with
non-managers
to form advisor/advisee relationships to provide career guidance and receive support in working through career and development challenges. Additionally, our LEAD program — Leadership Education and Development — provides a leadership training program for nominated Directors and Vice Presidents. We also foster other team-based programs to develop talent at all levels of the Company, supplying associates with new skills and training. Through these programs, we give our associates the tools to succeed, learn new skills and develop their careers.
Diversity, Equity and Inclusion
Associate engagement and retention require an understanding of the needs of a diverse, creative and purpose-driven workforce. We firmly believe that working in a culture focused on diversity, equity and inclusion spurs innovation, creates healthy and high-performing teams, and delivers superior customer experiences. We aim to provide equal opportunity for all employees. As of October 2019, 69% of our total workforce identified as female and 38% were minorities. Additionally, 52% of our Vice Presidents and above identified as female.
We are focused on increasing the representation of minority talent through hiring and career development. In June 2020, we established an Equity Action Plan and formed an Equity Action Committee, including a diverse group of executives and associates, to drive positive change in the fight for racial justice. We also have several systems under which associates can report incidents or discrimination confidentially or anonymously and without fear of reprisal.
We are currently building relationships with over 175 organizations, universities, colleges and networks to expand our reach to potential candidates. As of the end of fiscal 2020, 100% of open roles have a diverse slate of candidates, and we have had a double-digit increase in Black representation since we launched our Equity Action Plan. We are also a member of CEO Action for Diversity & Inclusion, in which we announced a goal to “identify and establish associate networks for underrepresented communities to promote diversity and inclusion throughout the Company.” In furtherance of our stated goal, we have developed associate groups including an LGBTQ+ Alliance, Black Associate Network, Veterans Appreciation Group, Hispanic Heritage Group, and an Asian American Pacific Islander Network.
Safety/Health and Wellness
Our vision is to provide a safe and healthy work environment for our associates and customers. Aligned with our values, we strive to continuously improve our work environments to keep our associates and customers as safe as possible. Our efforts include:
| • | Incident and hazard reporting; |
|---|
| • | Standard operating procedures aimed at reducing risk of injury; |
|---|
| • | Associate and management training; |
|---|
| • | Promotion of best practices; and |
|---|
| • | Measurement of key safety metrics. |
|---|
During fiscal 2020, to address the safety and health of our workforce due to the
COVID-19
pandemic, we implemented a number of safety-related protocols, including:
| • | Temporarily closing our stores and corporate offices, and implementing temporary work-from-home-policies; |
|---|
| • | Establishing strict safety protocols and procedures company-wide, including social distancing measures, enhanced sanitization, daily wellness checks and supplying personal protective gear such as masks and gloves; |
|---|
| • | Developing and distributing a playbook to guide the safe return to offices, stores, and work sites; and |
|---|
| • | Creating and refining protocols to address actual and suspected COVID-19 cases and potential exposure of our team members, customers, and trade partners. |
|---|
Compensation and Benefits
We offer a benefits package designed to put our associates’ health and well-being, and that of their families, at the forefront. Depending on position and location, associates may be eligible for: 401(k) plan and other investment opportunities; paid vacations, holidays and other
time-off
programs; health, dental and vision insurance; health and dependent care
tax-free
spending accounts; medical, family and bereavement leave; paid maternity/primary caregiver benefits;
tax-free
commuter benefits; wellness programs; time off to volunteer, and matching donations to qualifying nonprofit organizations. In addition, consistent with our commitment to diversity and inclusion, we have expanded our benefit offerings to include coverage for transgender-inclusive services, including gender confirmation surgery and hormone therapy.
In connection with the
COVID-19
pandemic, we acted quickly to meet the needs of our team members, by providing certain enhanced benefits, such as:
| • | Increased company minimum wage to $14 per hour; |
|---|
| • | Provided special bonuses to all frontline workers; |
|---|
| • | Approved special bonuses to high-performing non-executive associates to reward extraordinary efforts in COVID-19 environment; |
|---|
| • | Created a dedicated associate hotline to provide real time support for any COVID-19-related issues; |
|---|
| • | Reinforced social distancing through signage, floor markers, taped grid patterns on floors, and directional arrows; |
|---|
| • | Continued telehealth support and employee assistance programs; and |
|---|
| • | Provided special wellness resources and tools. |
|---|
Community Involvement
Since 2017 we have donated over $42 million in corporate, customer and associate donations. Our partners include organizations that promote and strengthen the wellbeing of children, women, families and LGBTQ+ communities, such as St. Jude Children’s Research Hospital, No Kid Hungry, AIDS Walk and Canada Children’s Hospitals. We raised $5 million for St. Jude Children’s Research Hospital during the fiscal 2020 St. Jude
Thanks and Giving
Campaign, which included donations from our customers at time of purchase, special St. Jude-designated product sales where a portion of the sale was donated, employee donations, and donations from the Company. We also support organizations and partners, such as GlobalGiving and Good360, which assist those whose homes have been damaged or lost. We give charitable grants, donate our merchandise, donate proceeds from the sale of certain products, and provide matching grants for charitable donations made by our associates. Our Williams-Sonoma, Inc. Foundation also provides need-based grants to our associates directly impacted by the
COVID-19
pandemic.
We also support our communities through our associates’ time and leadership, and we provide 8 hours of paid Community Involvement Time each year. We believe volunteering deepens our presence in the community, enhances our relationships with customers and strengthens employee engagement.
INTELLECTUAL PROPERTY
As of January 31, 2021, we own and/or have applied to register approximately 179 unique trademarks or service marks. We own and/or have applied to register our key brand names in the U.S. as well as in 95 additional jurisdictions. Generally, exclusive rights to the trademarks and service marks are held by Williams-Sonoma, Inc. and are used by our subsidiaries and franchisees under license. These marks include our core brand names as well as brand names for selected products and services. The core brand names in particular, including “Williams Sonoma,” “Pottery Barn,” “pottery barn kids,” “Pottery Barn Teen,” “west elm,” “Williams Sonoma Home,” “Rejuvenation” and “Mark and Graham” are of material importance to us. Trademarks are generally valid as long as they are in use and/or their registrations are properly maintained, and they have not been found to have become generic. Trademark registrations can generally be renewed indefinitely so long as the marks are in use. We also own numerous copyrights and trade dress rights for our products, product packaging, catalogs, books,
publications, website designs and store designs, among other things, which are used by our subsidiaries and franchisees under license. As of January 31, 2021, we own or have applied to register approximately 322 patents in connection with certain product designs, inventions and proprietary technology. Patents in the U.S. are generally valid for 14 to 20 years as long as their registrations are properly maintained. In addition, we have registered and maintain numerous Internet domain names, including “williams-sonoma.com,” “potterybarn.com,” “potterybarnkids.com,” “potterybarnteen.com,” “westelm.com,” “wshome.com,” “williams-sonomainc.com,” “rejuvenation.com” and “markandgraham.com.” Collectively, the trademarks, patents, copyrights, trade dress rights, domain names, trade secrets and other proprietary technology that we hold are of material importance to us.
AVAILABLE INFORMATION
We file annual reports on Form
10-K,
quarterly reports on Form
10-Q,
current reports on Form
8-K,
proxy and information statements and amendments to reports filed or furnished pursuant to Sections 13(a), 14 and 15(d) of the Securities Exchange Act of 1934, as amended. The SEC maintains a website at www.sec.gov that contains reports, proxy and information statements and other information regarding Williams-Sonoma, Inc. and other companies that file materials electronically with the SEC. Our annual reports, Forms
10-K,
Forms
10-Q,
Forms 8-K
and proxy and information statements are also available, free of charge, on our website at www.williams-sonomainc.com.
Investors and others should note that we announce material financial and operational information to our investors on our Investor Relations website (http://ir.williams-sonomainc.com), press releases, SEC filings and public conference calls and webcasts. Information on our website is not, and will not, be deemed a part of this report or incorporated into any other filings we make with the SEC.
Item 1A. RISK FACTORS
| --- | --- |
A description of the risks and uncertainties associated with our business is set forth below. You should carefully consider such risks and uncertainties, together with the other information contained in this report and in our other public filings before investing in our common stock. If any of such risks and uncertainties actually occurs, our business, financial condition or operating results could differ materially from the plans, projections and other forward-looking statements included in the section titled “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and elsewhere in this report and in our other public filings. In addition, if any of the following risks and uncertainties, or if any other risks and uncertainties, actually occurs, our business, financial condition or operating results could be harmed substantially, which could cause the market price of our stock to decline, perhaps significantly.
Risk Factor Summary
The following is a summary of the risks and uncertainties that could cause our business, financial condition or operating results to be harmed. We encourage you to carefully review the full risk factors contained in this report in their entirety for additional information regarding these risks and uncertainties.
Risks Related to Our Business
| • | Our business has been and may continue to be materially impacted by the COVID-19 pandemic, and the duration and extent to which this will impact our future financial performance remains uncertain. |
|---|
| • | Declines in general economic conditions, and the resulting impact on consumer confidence and consumer spending, could adversely impact our results of operations. |
|---|
| • | We are unable to control many of the factors affecting consumer spending, and declines in consumer spending on home furnishings and kitchen products in general could reduce demand for our products. |
|---|
| • | If we are unable to identify and analyze factors affecting our business, anticipate changing consumer preferences and buying trends, and manage our inventory commensurate with customer demand, our sales levels and operating results may decline. |
|---|
| • | Our business and operating results may be harmed if we are unable to timely and effectively deliver merchandise to our stores and customers. |
|---|
| • | Our failure to successfully manage our order-taking and fulfillment operations could have a negative impact on our business and operating results . |
|---|
| • | We must protect and maintain our brand image and reputation. |
|---|
| • | Our sales may be negatively impacted by increasing competition from companies with brands or products similar to ours. |
|---|
| • | Our facilities and systems, as well as those of our vendors, are vulnerable to natural disasters, adverse weather conditions, technology issues and other unexpected events, any of which could result in an interruption in our business and harm our operating results. |
|---|
| • | If we are unable to effectively manage our e-commerce business and digital marketing efforts, our reputation and operating results may be harmed. |
|---|
| • | Declines in our comparable brand revenues may harm our operating results and cause a decline in the market price of our common stock. |
|---|
| • | Our failure to successfully anticipate merchandise returns might have a negative impact on our business. |
|---|
| • | Our failure to successfully manage the costs and performance of our catalog mailings might have a negative impact on our business. |
|---|
| • | If we are unable to successfully manage the complexities associated with an omni-channel and multi-brand business, we may suffer declines in our existing business and our ability to attract new business. |
|---|
| • | A number of factors that affect our ability to successfully open new stores or close existing stores are beyond our control, and these factors may harm our ability to expand or contract our retail operations and harm our ability to increase our sales and profits. |
|---|
| • | Our inability or failure to protect our intellectual property would have a negative impact on our brands, reputation and operating results. |
|---|
| • | We outsource certain aspects of our business to third-party vendors and are in the process of insourcing certain business functions from third-party vendors, both of which subject us to risks. |
|---|
| • | If we fail to attract and retain key personnel, our business and operating results may be harmed. |
|---|
| • | If we are unable to introduce new brands and brand extensions successfully, or to reposition or close existing brands, our business and operating results may be negatively impacted. |
|---|
| • | We may be subject to legal proceedings that could result in costly litigation, require significant amounts of management time and result in the diversion of significant operational resources. |
|---|
Risks Related to Technology
| • | We may be exposed to cybersecurity risks and costs associated with credit card fraud, identity theft and business interruption that could cause us to incur unexpected expenses and loss of revenue. |
|---|
| • | We receive, process, store, use and share data, some of which contains personal information, which subjects us to complex and evolving governmental regulation and other legal obligations related to data privacy, data protection and other matters. |
|---|
| • | We are undertaking certain systems changes that might disrupt our business operations. |
|---|
Risks Related to Our Vendors and Our Global Operations
| • | Our dependence on foreign vendors and our increased global operations subject us to a variety of risks and uncertainties that could impact our operations and financial results. |
|---|
| • | We depend on foreign vendors and third-party agents for timely and effective sourcing of our merchandise, and we may not be able to acquire products in sufficient quantities and at acceptable prices to meet our needs. |
|---|
| • | If our vendors fail to adhere to our quality control standards and test protocols, we may delay a product launch or recall a product, which could damage our reputation and negatively affect our operations and financial results. |
|---|
| • | Our efforts to expand globally may not be successful and could negatively impact the value of our brands. |
|---|
| • | We have limited experience operating on a global basis and our failure to effectively manage the risks and challenges inherent in a global business could adversely affect our business, operating results and financial condition and growth prospects. |
|---|
Risks Related to Taxes and Tariffs
| • | Any significant changes in tax, trade or other policies in the U.S. or other countries, including policies that restrict imports or increase import tariffs, could have a material adverse effect on our results of operations. |
|---|
| • | Tariffs could result in increased prices and/or costs of goods or delays in product received from our vendors and could adversely affect our results of operations. |
|---|
| | • | | Fluctuations in our tax obligations and effective tax rate may result in vol
Showing the first 8K of 102K characters. Open the full section
Item 1B. UNRESOLVED STAFF COMMENTS
| --- | --- |
None.
Item 2. PROPERTIES
We lease store locations, distribution and manufacturing facilities, corporate facilities and customer care centers for our U.S. and foreign operations for original terms generally ranging from 5 to 22 years. Certain leases contain renewal options for periods of up to 20 years.
For our store locations, our gross leased store space as of January 31, 2021 totaled approximately 6,301,000 square feet for 581 stores compared to approximately 6,558,000 square feet for 614 stores as of February 2, 2020.
Leased Properties
The following table summarizes the location and size of our leased facilities occupied by us as of January 31, 2021:
| Location | Occupied Square Footage (Approximate) | |||
| Distribution and Manufacturing Facilities | ||||
| Mississippi | 2,258,000 | |||
| New Jersey | 2,103,000 | |||
| California | 2,030,000 | |||
| Texas | 1,298,000 | |||
| Georgia | 1,075,000 | |||
| Tennessee | 603,000 | |||
| North Carolina | 442,000 | |||
| Ohio | 153,000 | |||
| Massachusetts | 140,000 | |||
| Florida | 135,000 | |||
| Oregon | 91,000 | |||
| Colorado | 80,000 | |||
| Corporate Facilities | ||||
| California | 269,000 | |||
| New York | 238,000 | |||
| Oregon | 49,000 | |||
| Customer Care Centers | ||||
| Nevada | 36,000 | |||
| Other | 32,000 |
In addition to the above leased properties, we enter into agreements for other offsite storage needs for our distribution facilities and our retail store locations, as necessary. As of January 31, 2021, the total leased space related to these properties was not material to us and is not included in the occupied square footage reported above.
Owned Properties
As of January 31, 2021, we owned 471,000 square feet of space, primarily in California, for our corporate headquarters and certain data center operations.
We believe that all of our facilities are adequate for our current needs and that suitable additional or substitute space will be available in the future to replace our existing facilities, or to accommodate the expansion of our operations, if necessary.
Item 3. LEGAL PROCEEDINGS
We are involved in lawsuits, claims and proceedings incident to the ordinary course of our business. These disputes, which are not currently material, are increasing in number as our business expands and our company grows. We review the need for any loss contingency reserves and establish reserves when, in the opinion of management, it is probable that a matter would result in liability, and the amount can be reasonably estimated. In view of the inherent difficulty of predicting the outcome of these matters, it may not be possible to determine whether any loss is probable or to reasonably estimate the amount of the loss until the case is close to resolution, in which case no reserve is established until that time. Any claims against us, whether meritorious or not, could result in costly litigation, require significant amounts of management time and result in the diversion of significant operational resources. The results of these lawsuits, claims and proceedings cannot be predicted with certainty. However, we believe that the ultimate resolution of these current matters will not have a material adverse effect on our consolidated financial statements taken as a whole.
Item 4. MINE SAFETY DISCLOSURES
Not applicable.
PART II
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
| --- | --- |
MARKET INFORMATION
Our common stock is traded on the New York Stock Exchange, or the NYSE, under the symbol WSM. The closing price of our common stock on the NYSE on March 21, 2021 was $174.84.
STOCKHOLDERS
The number of stockholders of record of our common stock as of March 21, 2021 was 299. This number excludes stockholders whose stock is held in nominee or street name by brokers.
PERFORMANCE GRAPH
This graph compares the cumulative total stockholder return for our common stock with those of the NYSE Composite Index and S&P Retailing, our peer group index. The cumulative total return listed below assumed an initial investment of $100 and reinvestment of dividends. The graph shows historical stock price performance, including reinvestment of dividends, and is not necessarily indicative of future performance.
COMPARISON OF FIVE YEAR CUMULATIVE TOTAL RETURN*
Among Williams-Sonoma, Inc., the NYSE Composite Index,
and S&P Retailing
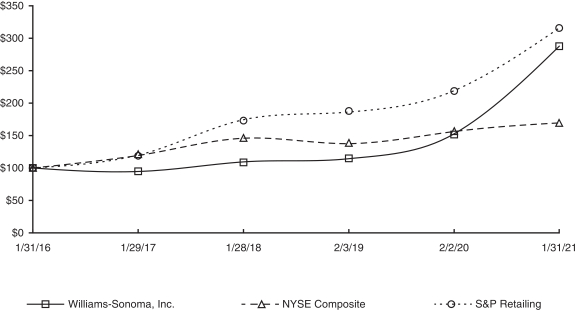
| * | $100 invested on 1/31/16 in stock or index, including reinvestment of dividends. Fiscal year ending January 31, 2021. |
|---|
| 1/31/16 | 1/29/17 | 1/28/18 | 2/3/19 | 2/2/20 | 1/31/21 | |||||||
| Williams-Sonoma, Inc. | $100.00 | $94.58 | $109.64 | $114.38 | $152.80 | $287.90 | ||||||
| NYSE Composite Index | $100.00 | $119.63 | $146.03 | $137.82 | $156.52 | $169.59 | ||||||
| S&P Retailing | $100.00 | $120.09 | $174.49 | $186.29 | $219.46 | $316.05 |
Notes:
| A. | The lines represent monthly index levels derived from compounded daily returns that include all dividends. |
|---|
| B. | The indices are re-weighted daily, using the market capitalization on the previous trading day. |
|---|
| C. | If the monthly interval, based on the fiscal year-end, is not a trading day, the preceding trading day is used. |
|---|
STOCK REPURCHASE PROGRAM
During fiscal 2020, we repurchased 1,496,100 shares of our common stock at an average cost of $100.26 per share and a total cost of $150,000,000. As of January 31, 2021, there was approximately $424,982,000 remaining under our current stock repurchase program. In March 2021, our Board of Directors authorized a new stock repurchase program for $1,000,000,000, which replaced our existing program. During fiscal 2019, we repurchased 2,341,931 shares of our common stock, of which 16,368 shares were designated as treasury stock, at an average cost of $63.55 per share and a total cost of $148,834,000. During fiscal 2018, we repurchased 5,373,047 shares of our common stock at an average cost of $54.96 per share and a total cost of $295,304,000.
The following table summarizes our repurchases of shares of our common stock during the fourth quarter of fiscal 2020 under our stock repurchase program:
| Fiscal period | Total Number of Shares Purchased 1 | Average Price Paid Per Share | Total Number of Shares Purchased as Part of a Publicly Announced Program 1 | Maximum Dollar Value of Shares That May Yet Be Purchased Under the Program | ||||||||||||||
| November 2, 2020 – November 29, 2020 | 125,310 | $ 98.91 | 125,310 | $ 453,539,000 | ||||||||||||||
| November 30, 2020 – December 27, 2020 | 116,800 | $ 108.75 | 116,800 | $ 440,837,000 | ||||||||||||||
| December 28, 2020 – January 31, 2021 | 134,655 | $ 117.75 | 134,655 | $ 424,982,000 | ||||||||||||||
| Total | 376,765 | $ 108.69 | 376,765 | $ 424,982,000 |
| 1 | Excludes shares withheld for employee taxes upon vesting of stock-based awards. |
|---|
Stock repurchases under our program may be made through open market and privately negotiated transactions at times and in such amounts as management deems appropriate. The timing and actual number of shares repurchased will depend on a variety of factors including price, corporate and regulatory requirements, capital availability and other market conditions. The stock repurchase program does not have an expiration date and may be limited or terminated at any time without prior notice.
Item 6. SELECTED FINANCIAL DATA
| --- | --- |
Five-Year Selected Financial Data
| In thousands, except percentages, per share amounts and retail stores data | Fiscal 2020 (52 Weeks) | Fiscal 2019 (52 Weeks) | Fiscal 2018 1 (53 Weeks) | Fiscal 2017 (52 Weeks) | Fiscal 2016 (52 Weeks) | |||||||||||||||
| Results of Operations | ||||||||||||||||||||
| Net revenues | $ | 6,783,189 | $ | 5,898,008 | $ | 5,671,593 | $ | 5,292,359 | $ | 5,083,812 | ||||||||||
| Net revenue growth | 15.0% | 4.0% | 7.2% | 4.1% | 2.2% | |||||||||||||||
| Comparable brand revenue growth 2 | 17.0% | 6.0% | 3.7% | 3.2% | 0.7% | |||||||||||||||
| Gross profit | $ | 2,636,269 | $ | 2,139,092 | $ | 2,101,013 | $ | 1,931,711 | $ | 1,883,310 | ||||||||||
| Gross margin | 38.9% | 36.3% | 37.0% | 36.5% | 37.0% | |||||||||||||||
| Operating income | $ | 910,697 | $ | 465,874 | $ | 435,953 | $ | 453,811 | $ | 472,599 | ||||||||||
| Operating margin 3 | 13.4% | 7.9% | 7.7% | 8.6% | 9.3% | |||||||||||||||
| Net earnings | $ | 680,714 | $ | 356,062 | $ | 333,684 | $ | 259,545 | $ | 305,387 | ||||||||||
| Basic earnings per share | $ | 8.81 | $ | 4.56 | $ | 4.10 | $ | 3.03 | $ | 3.45 | ||||||||||
| Diluted earnings per share | $ | 8.61 | $ | 4.49 | $ | 4.05 | $ | 3.02 | $ | 3.41 | ||||||||||
| Shares used in calculation of earnings per share: Basic | 77,260 | 78,108 | 81,420 | 85,592 | 88,594 | |||||||||||||||
| Diluted | 79,055 | 79,225 | 82,340 | 86,080 | 89,462 | |||||||||||||||
| Financial Position | ||||||||||||||||||||
| Working capital 4 | $ | 619,080 | $ | 146,080 | $ | 619,531 | $ | 628,622 | $ | 405,924 | ||||||||||
| Total assets 4 | $ | 4,661,424 | $ | 4,054,042 | $ | 2,812,844 | $ | 2,785,749 | $ | 2,476,879 | ||||||||||
| Return on assets 4 | 15.6% | 10.4% | 11.9% | 9.9% | 12.5% | |||||||||||||||
| Net cash provided by operating activities | $ | 1,274,848 | $ | 607,294 | $ | 585,986 | $ | 499,704 | $ | 524,709 | ||||||||||
| Capital expenditures | $ | 169,513 | $ | 186,276 | $ | 190,102 | $ | 189,712 | $ | 197,414 | ||||||||||
| Long-term debt and other long-term liabilities 4 | $ | 1,141,627 | $ | 1,180,968 | $ | 380,944 | $ | 372,226 | $ | 71,215 | ||||||||||
| Stockholders’ equity | $ | 1,651,185 | $ | 1,235,860 | $ | 1,155,714 | $ | 1,203,566 | $ | 1,248,220 | ||||||||||
| Stockholders’ equity per share (book value) | $ | 21.63 | $ | 16.02 | $ | 14.66 | $ | 14.37 | $ | 14.29 | ||||||||||
| Return on equity | 47.2% | 29.8% | 28.3% | 21.2% | 25.0% | |||||||||||||||
| Annual dividends declared per share | $ | 2.02 | $ | 1.92 | $ | 1.72 | $ | 1.56 | $ | 1.48 | ||||||||||
| Number of stores at year-end | 581 | 614 | 625 | 631 | 629 | |||||||||||||||
| Store selling square footage at year-end | 3,975,000 | 4,129,000 | 4,105,000 | 4,019,000 | 3,951,000 | |||||||||||||||
| Store leased square footage at year-end | 6,301,000 | 6,558,000 | 6,557,000 | 6,451,000 | 6,359,000 |
| 1 | In fiscal 2018, we adopted Accounting Standards Update (“ASU”) 2014-09, Revenue from Contracts with Customers, using the modified retrospective method. Amounts reported for fiscal 2017 and fiscal 2016 have not been adjusted, and continue to be reported in accordance with previous revenue recognition guidance. |
|---|
| 2 | Comparable brand revenue is calculated on a 52-week to 52-week basis, with the exception of fiscal 2018 which is calculated on a 53-week to 53-week basis. See definition of comparable brand revenue within “Management’s Discussion and Analysis of Financial Condition and Results of Operations.” |
|---|
| 3 | Operating margin is defined as operating income as a percent of net revenues. |
|---|
| 4 | In fiscal 2019, we adopted ASU 2016-02, Leases, as of the adoption date. Amounts reported for fiscal 2018 and prior years have not been adjusted, and continue to be reported in accordance with previous lease accounting guidance. See Note A to the Consolidated Financial Statements. |
|---|
The information set forth above is not necessarily indicative of future operations and should be read in conjunction with “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and the Consolidated Financial Statements and notes thereto in this Annual Report on Form
10-K.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
| --- | --- |
The following discussion and analysis of our financial condition, results of operations, and liquidity and capital resources for the 52 weeks ended January 31, 2021 (“fiscal 2020”), and the 52 weeks ended February 2, 2020 (“fiscal 2019”) should be read in conjunction with our Consolidated Financial Statements and notes thereto. All explanations of changes in operational results are discussed in order of magnitude.
A discussion and analysis of our financial condition, results of operations, and liquidity and capital resources for the 52 weeks ended February 2, 2020 (“fiscal 2019”), compared to the 53 weeks ended February 3, 2019 (“fiscal 2018”), can be found under Item 7 in our Annual Report on Form
10-K
for fiscal 2019, filed with the SEC on March 27, 2020, which is available on the SEC’s website at www.sec.gov and under the Financial Reports section of our Investor Relations website.
OVERVIEW
Williams-Sonoma, Inc. is a specialty retailer of high-quality sustainable products for the home. Our products, representing distinct merchandise strategies — Williams Sonoma, Pottery Barn, Pottery Barn Kids, Pottery Barn Teen, West Elm, Williams Sonoma Home, Rejuvenation, and Mark and Graham — are marketed through
e-commerce
websites, direct-mail catalogs and retail stores. These brands are also part of The Key Rewards, our
free-to-join
loyalty program that offers members exclusive benefits across the Williams-Sonoma family of brands. We operate in the U.S., Puerto Rico, Canada, Australia and the United Kingdom, offer international shipping to customers worldwide, and have unaffiliated franchisees that operate stores in the Middle East, the Philippines, Mexico, South Korea and India, as well as
e-commerce
websites in certain locations. We are also proud to lead the industry with our ESG efforts.
COVID-19
On March 11, 2020, the World Health Organization declared
COVID-19
to be a global pandemic and recommended containment and mitigation measures worldwide. In March 2020, we announced the temporary closures of all of our retail store operations to protect our employees, customers and the communities in which we operate and to help contain the
COVID-19
pandemic. As of January 31, 2021, the majority of our retail stores have reopened for
in-person
shopping. However, given the continued uncertainty around
COVID-19
due to high rates of infections in certain areas, state and local officials in certain geographies have extended closures or restrictions on retail capacity, which may continue to impact our store traffic and retail revenues, and may result in future store impairments. Throughout fiscal 2020, we have continued to operate our
e-commerce
sites and distribution centers and continued to deliver products to our customers. However, governmental mandates, illness, or the absence of a substantial number of distribution center employees may require in the future that we temporarily close one or more of our distribution centers, or may prohibit or significantly limit us, or our third-party logistics providers from delivering packages to our customers and our stores, which could complicate or prevent us from fulfilling
e-commerce
orders and supplying merchandise to our stores.
Fiscal 2020 Financial Results
Net revenues in fiscal 2020 increased by $885,181,000, or 15.0%, compared to fiscal 2019, with comparable brand revenue growth of 17.0% and double-digit comparable brand revenue growth across all our brands. This was primarily driven by an increase of approximately 44% in
e-commerce
revenues, due to both an increase in demand for our product as well as a larger portion of our net revenues being driven by furniture, which has a higher average selling price, partially offset by a decrease in retail revenues driven by limited capacity in stores and reduced customer store traffic due to
COVID-19.
During fiscal 2020, we delivered double-digit comparable brand revenue growth across all our brands. The Williams Sonoma brand delivered comparable brand revenue growth of 23.8% as we implemented a content-driven marketing strategy that featured exclusive products and relevant lifestyle stories over promotions. We also
grew our exclusive products to 70% of our total business, consistent with one of our key strategic initiatives to increase the mix of product that is only available at Williams Sonoma. In our Pottery Barn Kids and Teen business, we delivered 16.6% comparable brand revenue growth, as we continue to amplify our leadership in design and sustainability in the children’s home furnishings business. In addition to strong core introductions in furniture, we have added a new modern aesthetic that is driving growth and attracting new customers to our brands. The Pottery Barn brand delivered comparable brand revenue growth of 15.2% and our multi-year work to improve our value proposition is paying off. Our value-engineered products are attracting new customers and we believe our multi-step finish, high-quality furniture pieces are the best value in the market. In West Elm, we delivered strong comparable brand revenue growth of 15.2% on top of 14.4% last year. We continue to build this business with original design and by filling white space in underdeveloped categories. And, our emerging brands, Rejuvenation and Mark and Graham, combined delivered another year of double-digit comparable brand revenue growth.
We ended the year with a cash balance of $1,200,337,000, compared to $432,162,000 last year, which reflects our strong financial performance as well as operating cash flow, which was more than double last year. In addition to our strong cash balance, we also ended the year with no amount outstanding under our line of credit. This strong liquidity position allowed us to fund the operations of the business, and to provide shareholder returns of approximately $307,645,000 through dividends and share repurchases.
In fiscal 2020, diluted earnings per share was $8.61 (which included a $0.26 impact related to store asset impairments, a $0.13 impact from acquisition-related expenses of Outward, Inc., an $0.11 impact related to inventory write-offs, and a $0.06 benefit related to the adjustment of certain deferred tax assets and liabilities) versus $4.49 in fiscal 2019 (which included a $0.30 impact from acquisition-related expenses and the operations of Outward, Inc., an $0.11 impact related to certain employment-related expenses, and an $0.08 benefit related to the adjustment of a deferred tax liability).
Throughout fiscal 2020, our three key differentiators were instrumental to our strong financial performance. They are: our
in-house
design, our
digital-first
channel strategy, and our values.
Our
in-house
teams design our own products, create original aesthetics, and work with our talented vendors to bring quality, sustainable products to market. The majority of our products cannot be found elsewhere and the design, quality, and value that we offer is strong. Throughout fiscal 2020, we were very deliberate in reducing promotions in all of our brands, resulting in product margin expansion compared to fiscal 2019.
Our second differentiator is our digital-first channel strategy. One of the key reasons for our results over the past year was because our e-commerce platform was able to serve our customers at scale. In our digital channels, we have been acquiring a significant number of new customers all year, and our customer retention metrics continue to improve among new customers. We are digital-first but not digital only. Our stores are a competitive advantage that support our online business, for customers who want to experience our products in person, as well as for those who prefer the convenience of our omni-channel fulfillment services, including buy online pick up in store and ship from store.
Our third differentiator is our values. We care deeply about sustainability, equity action and supporting our associates and the communities where we work. We believe our commitment to sustainability is one of the main reasons our customers choose us over our competitors and diversity, equity and inclusion is central to who we are as a company. We continued to support our associates and customers throughout fiscal 2020 by continuing to pay our associates during the initial months of COVID-19 while our stores and offices were closed, providing pandemic bonuses and hourly wage increases to our frontline workers, as well as providing personal protective gear and COVID-19 testing to our store and supply chain associates.
Looking Ahead to 2021
As we look forward to the year ahead, we will continue to focus on our three key differentiators to drive net revenue and operating margin growth. In our retail stores, we plan to further optimize our store footprint with fewer, better stores that serve as design centers and omni-channel fulfillment hubs. We believe our digital-first channel strategy will continue to accelerate, with our future growth driven predominantly by
e-commerce.
In our
supply chain, we expect to expand our U.S. manufacturing and fulfillment capacity by over
20%-30%
next year, including adding close to two million square feet of distribution space to our delivery network. We also plan to deepen our sustainability commitments including our goal to reach 100% responsibly-sourced cotton and 50% responsibly-sourced wood. In fiscal 2021, we believe operating margin expansion will predominantly be driven by overall sales leverage from higher sales levels, a continued shift to our more efficient and profitable e-commerce business, as well as reduced occupancy costs, continued strength in our product margins, and overall strong financial discipline. However, we have experienced and may continue to experience delays in inventory receipts due to
COVID-19-related
slowdowns, inclement weather, port congestion, and shipping container shortages, and we have incurred and may continue to incur higher shipping charges as we deliver goods to our customers. In addition, given the continued uncertainty around
COVID-19
and extended closures or restrictions on retail capacity by state and local officials in certain geographies, we have experienced and may continue to experience reduced store traffic. Overall, the long-term impact of
COVID-19
on our business, results of operations and financial condition still remains uncertain. A prolonged pandemic could further interrupt our operations, our vendors’ operations, the economy and overall consumer spending, which could have a material impact on our revenues, results of operations, and cash flows. For more information on risks associated with
COVID-19,
please see “Risk Factors” in Part I, Item 1A.
Results of Operations
NET REVENUES
Net revenues consist of sales of merchandise to our customers through our
e-commerce
websites, direct-mail catalogs, and at our retail stores and include shipping fees received from customers for delivery of merchandise to their homes. Our revenues also include sales to our franchisees and wholesale customers, breakage income related to our stored-value cards, and incentives received from credit card issuers in connection with our private label and
co-branded
credit cards.
Net revenues in fiscal 2020 increased by $885,181,000, or 15.0%, compared to fiscal 2019, with comparable brand revenue growth of 17.0% and double-digit comparable brand revenue growth across all our brands. This was primarily driven by an increase of approximately 44% in e-commerce revenues, due to both an increase in demand for our product as well as a larger portion of our net revenues being driven by furniture, which has a higher average selling price, partially offset by a decrease in retail revenues driven by limited capacity in stores and reduced customer store traffic due to
COVID-19.
The following table summarizes our net revenues by brand for fiscal 2020 and fiscal 2019:
| In thousands | Fiscal 2020 | Fiscal 2019 | ||||||
| Pottery Barn | $ | 2,526,241 | $ | 2,214,397 | ||||
| West Elm | 1,682,254 | 1,466,537 | ||||||
| Williams Sonoma | 1,242,271 | 1,032,368 | ||||||
| Pottery Barn Kids and Teen | 1,042,531 | 908,561 | ||||||
| Other 1 | 289,892 | 276,145 | ||||||
| Total | $ | 6,783,189 | $ | 5,898,008 |
| 1 | Primarily consists of net revenues from our international franchise operations, Rejuvenation and Mark and Graham. |
|---|
Comparable Brand Revenue
Comparable brand revenue includes comparable store sales and
e-commerce
sales, including through our direct-mail catalog, as well as shipping fees, sales returns and other discounts associated with current period sales. Comparable stores are defined as permanent stores where gross square footage did not change by more than 20% in the previous 12 months and which have been open for at least 12 consecutive months without closure for seven or more consecutive days. Comparable stores that were temporarily closed during the year due to
COVID-19
were not excluded from the comparable stores calculation. Outlet comparable store net revenues are included in their respective brands. Sales to our international franchisees are excluded from comparable brand revenue as their stores and
e-commerce
websites are not operated by us. Sales from certain operations are also excluded until such time that we believe those sales are meaningful to evaluating their performance. Additionally, comparable brand revenue growth for newer concepts is not separately disclosed until such time that we believe those sales are meaningful to evaluating the performance of the brand.
| Comparable brand revenue growth | Fiscal 2020 | Fiscal 2019 | ||||||
| Pottery Barn | 15.2 | % | 4.1 | % | ||||
| West Elm | 15.2 | 14.4 | ||||||
| Williams Sonoma | 23.8 | 0.4 | ||||||
| Pottery Barn Kids and Teen | 16.6 | 4.5 | ||||||
| Total 1 | 17.0 | % | 6.0 | % |
| 1 | Total comparable brand revenue growth includes the results of Rejuvenation and Mark and Graham. |
|---|
RETAIL STORE DATA
| Fiscal 2020 | 1 | Fiscal 2019 | ||||||
| Store count – beginning of year | 614 | 625 | ||||||
| Store openings | 10 | 14 | ||||||
| Store closings | (43 | ) | (25 | ) | ||||
| Store count – end of year | 581 | 614 | ||||||
| Store selling square footage at year-end | 3,975,000 | 4,129,000 | ||||||
| Store leased square footage (“LSF”) at year-end | 6,301,000 | 6,558,000 |
| 1 | Store count at the end of the year for fiscal 2020 includes stores temporarily closed due to COVID-19. Store count data excludes temporary closures and re-openings of our stores due to COVID-19. |
|---|
| Fiscal 2020 | Fiscal 2019 | |||||||||||||||
| Store Count | Avg. LSF Per Store | Store Count | Avg. LSF Per Store | |||||||||||||
| Williams Sonoma | 198 | 6,800 | 211 | 6,900 | ||||||||||||
| Pottery Barn | 195 | 14,600 | 201 | 14,400 | ||||||||||||
| West Elm | 121 | 13,100 | 118 | 13,100 | ||||||||||||
| Pottery Barn Kids | 57 | 7,800 | 74 | 7,700 | ||||||||||||
| Rejuvenation | 10 | 8,500 | 10 | 8,500 | ||||||||||||
| Total | 581 | 10,800 | 614 | 10,700 |
COST OF GOODS SOLD
| In thousands | Fiscal 2020 | % Net Revenues | Fiscal 2019 | % Net Revenues | ||||||||||||
| Cost of goods sold 1 | $ | 4,146,920 | 61.1% | $ | 3,758,916 | 63.7% |
| 1 | Includes occupancy expenses of $696.3 million and $710.5 million fiscal 2020 and fiscal 2019, respectively. |
|---|
Cost of goods sold includes cost of goods, occupancy expenses and shipping costs. Cost of goods consists of cost of merchandise, inbound freight expenses,
freight-to-store
expenses and other inventory related costs such as replacements, damages, obsolescence and shrinkage. Occupancy expenses consist of rent, depreciation and other occupancy costs, including common area maintenance, property taxes and utilities. Shipping costs consist of third-party delivery services and shipping materials.
Our classification of expenses in cost of goods sold may not be comparable to other public companies, as we do not include
non-occupancy-related
costs associated with our distribution network in cost of goods sold. These costs, which include distribution network employment, third-party warehouse management and other distribution-related administrative expenses, are recorded in selling, general and administrative expenses.
Fiscal 2020 vs. Fiscal 2019
Cost of goods sold increased by $388,004,000, or 10.3%, in fiscal 2020 compared to fiscal 2019. Cost of goods sold as a percentage of net revenues decreased to 61.1% in fiscal 2020 from 63.7% in fiscal 2019. This rate decrease was primarily driven by higher merchandise margins from reduced promotional activity in fiscal 2020 and the leverage of occupancy expenses resulting from higher sales and reduced occupancy costs year-over-year due to our efforts to renegotiate rent and close less profitable stores. This decrease was partially offset by higher shipping costs due to a significantly greater portion of our total net revenues being generated from
e-commerce
and surcharges from our third-party shippers, as well as inventory write-offs of approximately $11,378,000 resulting from the closure of our outlet stores due to
COVID-19
in the first quarter of fiscal 2020.
SELLING, GENERAL AND ADMINISTRATIVE EXPENSES
| In thousands | Fiscal 2020 | % Net Revenues | Fiscal 2019 | % Net Revenues | ||||||||||||
| Selling, general and administrative expenses | $ | 1,725,572 | 25.4% | $ | 1,673,218 | 28.4% |
Selling, general and administrative expenses consist of
non-occupancy-related
costs associated with our retail stores, distribution and manufacturing facilities, customer care centers, supply chain operations (buying, receiving and inspection) and corporate administrative functions. These costs include employment, advertising, third-party credit card processing and other general expenses.
Fiscal 2020 vs. Fiscal 2019
Selling, general and administrative expenses increased by $52,354,000, or 3.1%, for fiscal 2020, compared to fiscal 2019. Selling, general and administrative expenses as a percentage of net revenues decreased to 25.4% for fiscal 2020 from 28.4% for fiscal 2019. This rate decrease was primarily driven by lower advertising costs as we further optimized our digital spend on those initiatives that drove higher returns in traffic and conversion, and the leverage of employment costs from higher sales and lower variable store payroll. This decrease was partially offset by store asset impairment charges of approximately $27,069,000 for fiscal 2020 due in part to the impact of
COVID-19
on our retail stores.
INCOME TAXES
The effective income tax rate was 23.9% for fiscal 2020 and 22.1% for fiscal 2019. The increase in the effective tax rate in fiscal 2020 is primarily due to the tax effect of the change in the mix and level of our earnings.
LIQUIDITY AND CAPITAL RESOURCES
As of January 31, 2021, we held $1,200,337,000 in cash and cash equivalents, the majority of which was held in interest-bearing demand deposit accounts and money market funds, and of which $147,464,000 was held by our international subsidiaries. As is consistent within our industry, our cash balances are seasonal in nature, with the fourth quarter historically representing a significantly higher level of cash than other periods.
Throughout the fiscal year, we utilize our cash resources to build our inventory levels in preparation for our fourth quarter holiday sales. In fiscal 2021, we plan to use our cash resources to fund our inventory and inventory-related purchases, advertising and marketing initiatives, stock repurchases and dividend payments, early repayment of our term loan and property and equipment purchases.
In addition to our cash balances on hand, we have a credit facility, which provides for a $500,000,000 unsecured revolving line of credit (“revolver”), and a $300,000,000 unsecured term loan facility (“term loan”). The revolver may be used to borrow revolving loans or to request the issuance of letters of credit. We may, upon notice to the administrative agent, request existing or new lenders to increase the revolver by up to $250,000,000, at such lenders’ option, to provide for a total of $750,000,000 of unsecured revolving credit.
During fiscal 2020, we had borrowings of $487,823,000 under our revolver, all of which were repaid prior to the end of the fiscal year. No amounts were outstanding as of January 31, 2021. Additionally, as of January 31, 2021, a total of $12,609,000 in issued but undrawn standby letters of credit were outstanding under our revolver. The standby letters of credit were primarily issued to secure the liabilities associated with workers’ compensation and other insurance programs.
In May 2020, we entered into an amendment to our credit facility, which, among other changes, extends the maturity date and amends the interest rate of the term loan, modifies covenants under the credit facility, and maintains the maturity date and interest rate of the revolver.
As of January 31, 2021, we had $300,000,000 outstanding under our term loan. In February 2021, prior to maturity, we repaid the full outstanding balance on the term loan.
In addition to the Credit Facility Amendment, during the second quarter of fiscal 2020 we entered into a new agreement (the
“364-Day
Credit Agreement”) for an additional $200,000,000 unsecured revolving line of credit. During fiscal 2020, we had no borrowings under the
364-Day
Credit Agreement. We do not expect to renew the 364-Day Credit Agreement upon its maturity in May 2021.
The Credit Facility Amendment and the
364-Day
Credit Agreement contain certain restrictive loan covenants, including, among others, a financial covenant requiring a maximum leverage ratio (funded debt adjusted for lease and rent expense to earnings before interest, income tax, depreciation, amortization and rent expense), and covenants limiting our ability to incur indebtedness, grant liens, make acquisitions, merge or consolidate, and dispose of assets. As of January 31, 2021, we were in compliance with our financial covenants under our credit facilities and, based on our current projections, we expect to remain in compliance throughout the next 12 months. We believe our cash on hand, in addition to our available credit facilities, will provide adequate liquidity for our business operations over the next 12 months.
Letter of Credit Facilities
We have three unsecured letter of credit reimbursement facilities for a total of $35,000,000, each of which matures on August 22, 2021. The letter of credit facilities contain covenants that are consistent with our credit facility. Interest on unreimbursed amounts under the letter of credit facilities accrues at a base rate as defined in the credit facility, plus an applicable margin based on our leverage ratio. As of January 31, 2021, an aggregate of $3,843,000 was outstanding under the letter of credit facilities, which represents only a future commitment to fund inventory purchases to which we had not taken legal title. The latest expiration date possible for any future letters of credit issued under the facilities is January 19, 2022.
Cash Flows from Operating Activities
For fiscal 2020, net cash provided by operating activities was $1,274,848,000 compared to $607,294,000 in fiscal 2019. For fiscal 2020, net cash provided by operating activities was primarily attributable to net earnings adjusted for
non-cash
items, an increase in accrued expenses and other liabilities, a decrease in merchandise inventories and an increase in gift card and other deferred revenue. Net cash provided by operating activities compared to fiscal 2019 increased primarily due to an increase in net earnings, an increase in accrued expenses and other liabilities, an increase in gift card and other deferred revenue and a decrease in merchandise inventories.
Cash Flows from Investing Activities
For fiscal 2020, net cash used in investing activities was $168,884,000 compared to $185,548,000 in fiscal 2019 and was primarily attributable to purchases of property and equipment.
Cash Flows from Financing Activities
For fiscal 2020, net cash used in financing activities was $343,019,000 compared to $327,226,000 in fiscal 2019 and was primarily attributable to the payment of dividends and repurchases of common stock. Net cash used in financing activities compared to fiscal 2019 increased primarily due to an increase in the payment of dividends.
Dividends
In fiscal 2020 and fiscal 2019, total cash dividends declared were approximately $163,316,000, or $2.02 per common share, and $156,103,000, or $1.92 per common share, respectively. In March 2021, our Board of Directors authorized a $0.06, or 11.3%, increase in our quarterly cash dividend, from $0.53 to $0.59 per common share, subject to capital availability. Our quarterly cash dividend may be limited or terminated at any time.
Stock Repurchase Program
See section titled “Stock Repurchase Program” within Part II, Item 5 of this Annual Report on Form
10-K
for further information.
Contractual Obligations
The following table provides summary information concerning our future contractual obligations as of January 31, 2021:
| Payments Due by Period 1 | ||||||||||||||||||||
| In thousands | Fiscal 2021 | Fiscal 2022 to Fiscal 2024 | Fiscal 2025 to Fiscal 2026 | Thereafter | Total | |||||||||||||||
| Current debt 2 | $ | 300,000 | $ | — | $ | — | $ | — | $ | 300,000 | ||||||||||
| Interest | 542 | — | — | — | 542 | |||||||||||||||
| Operating leases 3 | 267,760 | 605,121 | 263,192 | 291,356 | 1,427,429 | |||||||||||||||
| Purchase obligations 4 | 1,350,121 | 22,456 | — | — | 1,372,577 | |||||||||||||||
| Total | $ | 1,918,423 | $ | 627,577 | $ | 263,192 | $ | 291,356 | $ | 3,100,548 |
| 1 | This table excludes $46.9 million of liabilities for unrecognized tax benefits associated with uncertain tax positions as we are not able to reasonably estimate when and if cash payments for these liabilities will occur. This amount, however, has been recorded as a liability in our accompanying Consolidated Balance Sheet as of January 31, 2021. |
|---|
| 2 | Current debt consists of term loan borrowings under our credit facility, all of which was repaid in full, prior to maturity, in February 2021. See Note C to our Consolidated Financial Statements for discussion of our borrowing arrangements. |
|---|
| 3 | Projected undiscounted payments include only those amounts that are fixed and determinable as of the reporting date. See Note E to our Consolidated Financial Statements for discussion of our operating leases. |
|---|
| 4 | Represents estimated commitments at year-end to purchase inventory and other goods and services in the normal course of business to meet operational requirements. |
|---|
Other Contractual Obligations
We have other liabilities reflected in our Consolidated Balance Sheet. The payment obligations associated with these liabilities are not reflected in the table above due to the absence of scheduled maturities. The timing of these payments cannot be determined, except for amounts estimated to be payable in fiscal 2021, which are included in our current liabilities as of January 31, 2021.
In connection with our acquisition of Outward Inc., we have agreed to pay certain additional amounts to former stockholders of Outward, contingent upon their continued service or the achievement of certain financial performance targets. These contingent obligations are not reflected in the table above.
We are party to a variety of contractual agreements under which we may be obligated to indemnify the other party for certain matters. These contracts primarily relate to commercial matters, operating leases, trademarks, intellectual property and financial matters. Under these contracts, we may provide certain routine indemnification relating to representations and warranties or personal injury matters. The terms of these indemnifications range in duration and may not be explicitly defined. Historically, we have not made significant payments for these indemnifications. We believe that if we were to incur a loss in any of these matters, the loss would not have a material effect on our financial condition or results of operations.
Commercial Commitments
The following table provides summary information concerning our outstanding commercial commitments as of January 31, 2021:
| Amount of Outstanding Commitment Expiration by Period 1 | ||||||||||||||||||||
| In thousands | Fiscal 2021 | Fiscal 2022 to Fiscal 2024 | Fiscal 2025 to Fiscal 2026 | Thereafter | Total | |||||||||||||||
| Standby letters of credit | $ | 12,609 | $ | — | $ | — | $ | — | $ | 12,609 | ||||||||||
| Letter of credit facilities | 3,843 | — | — | — | 3,843 | |||||||||||||||
| Total | $ | 16,452 | $ | — | $ | — | $ | — | $ | 16,452 |
| 1 | See Note C to our Consolidated Financial Statements for discussion of our borrowing arrangements. |
|---|
IMPACT OF INFLATION
The impact of inflation (or deflation) on our results of operations for the past three fiscal years has not been significant. However, we cannot be certain of the effect inflation (or deflation) may have on our results of operations in the future.
CRITICAL ACCOUNTING POLICIES AND ESTIMATES
Management’s Discussion and Analysis of Financial Condition and Results of Operations is based on our Consolidated Financial Statements, which have been prepared in accordance with accounting principles generally accepted in the United States of America. The preparation of these Consolidated Financial Statements requires us to make estimates and assumptions that affect the reported amounts of assets, liabilities, revenues and expenses and related disclosures of contingent assets and liabilities. These estimates and assumptions are evaluated on an ongoing basis and are based on historical experience and various other factors that we believe to be reasonable under the circumstances. Actual results could differ from these estimates.
We believe the following critical accounting policies used in the preparation of our Consolidated Financial Statements include the significant estimates and assumptions that we consider to be the most critical to an understanding of our financial statements because they involve significant judgments and uncertainties. See Note A to our Consolidated Financial Statements for further discussion of each policy.
Merchandise Inventories
Merchandise inventories, net of an allowance for shrinkage and obsolescence, are stated at the lower of cost (weighted average method) or market. To determine if the value of our inventory should be reduced below cost, we consider current and anticipated demand, customer preferences and age of the merchandise. The significant estimates used in inventory valuation are obsolescence (including excess and slow-moving inventory and lower of cost or market reserves) and estimates of inventory shrinkage. We reserve for obsolescence based on historical trends of inventory sold below cost and specific identification.
Reserves for shrinkage are estimated and recorded throughout the year based on historical shrinkage results, cycle count results within our distribution centers, expectations of future shrinkage and current inventory levels. Actual shrinkage is recorded at
year-end
based on the results of our cycle counts and year end physical inventory counts, and can vary from our estimates due to such factors as changes in operations, the mix of our inventory (which ranges from large furniture to small tabletop items) and execution against loss prevention initiatives in our stores, distribution facilities and
off-site
storage locations, and with our third-party warehouse and transportation providers. Accordingly, there is no shrinkage reserve at
year-end.
Historically, actual shrinkage has not differed materially from our estimates.
Our obsolescence and shrinkage reserve calculations contain estimates that require management to make assumptions and to apply judgment regarding a number of factors, including market conditions, the selling environment, historical results and current inventory trends. If actual obsolescence or shrinkage estimates change from our original estimate, we will adjust our reserves accordingly throughout the year. We have made no material changes to our assumptions included in the calculations of the obsolescence and shrinkage reserves throughout the year. In addition, we do not believe a 10% change in our inventory reserves would have a material effect on our net earnings. As of January 31, 2021 and February 2, 2020, our inventory obsolescence reserves were $9,827,000 and $13,424,000, respectively.
Long-lived Assets
Property and equipment is stated at cost. Depreciation is computed using the straight-line method over the estimated useful lives of the assets.
We review the carrying value of all long-lived assets for impairment, primarily at an individual store level, whenever events or changes in circumstances indicate that the carrying value of an asset or asset group may not be recoverable. Our impairment analyses determine whether projected cash flows from operations are sufficient
to recover the carrying value of these assets. The asset group is comprised of both property and equipment and operating lease
right-of-use
assets. Impairment may result when the carrying value of the asset or asset group exceeds the estimated undiscounted future cash flows over its remaining useful life. For store asset impairment, our estimate of undiscounted future cash flows over the store lease term is based upon our experience, the historical operations of the stores and estimates of future store profitability and economic conditions. The estimates of future store profitability and economic conditions require estimating such factors as sales growth, gross margin, employment costs, lease escalations, inflation and the overall economics of the retail industry, and are therefore subject to variability and difficult to predict. For
right-of-use
assets, we determine the fair value of the assets by using estimated market rental rates. These estimates can be affected by factors such as future store results, real estate supply and demand, store closure plans, and economic conditions that can be difficult to predict. Actual future results may differ from those estimates. If a long-lived asset is found to be impaired, the amount recognized for impairment is equal to the excess of the asset or asset group’s net carrying value over its estimated fair value. We measure property and equipment at fair value on a nonrecurring basis using Level 3 inputs as defined in the fair value hierarchy (see Note M to our Consolidated Financial Statements). We measure
right-of-use
assets at fair value on a nonrecurring basis using Level 2 inputs, primarily market rental rates, that are corroborated by market data. Where Level 2 inputs are not readily available, we use Level 3 inputs. Fair value of these long-lived assets is based on the present value of estimated future cash flows using a discount rate commensurate with the risk.
Given the material reductions in our retail store revenues and operating income during fiscal 2020 as a result of the COVID-19 pandemic, we evaluated our estimates and assumptions related to our stores’ future sales and cash flows, and performed a comprehensive review of our stores’ long-lived assets for impairment, including both property and equipment and operating lease
right-of-use
assets, at an individual store level. Our assumptions account for the estimated impact on future cash flows from the recent temporary store closures and capacity restrictions, including reduced store traffic and longer recovery times in those stores we have
re-opened,
as well as the reinstatement of closures or restrictions on retail capacity in certain areas.
These events and changes in circumstances, including a more prolonged and/or severe
COVID-19
pandemic and the reinstatement of closures or restrictions on retail capacity, may lead to increased impairment risk in the future; therefore, we will continue to monitor events and changes in circumstances that may indicate the need to test our long-lived assets, including goodwill, for potential impairment.
During fiscal 2020, we recognized asset impairment charges of approximately $19,204,000 related to property and equipment and $7,865,000 related to
right-of
use assets for our retail stores, which is recognized within selling, general and administrative expenses. During fiscal 2019, we recognized an approximate $3,303,000, net of tax, reduction to the opening balance of retained earnings resulting from the impairment of certain long-lived assets upon adoption of Accounting Standards Update (“ASU”)
2016-02,
Leases
.
Leases
We lease store locations, distribution and manufacturing facilities, corporate facilities, customer care centers and certain equipment for our U.S. and foreign operations with initial terms generally ranging from 2 to 22 years. We determine whether an arrangement is or contains a lease at inception by evaluating potential lease agreements, including service and operating agreements, to determine whether an identified asset exists that we control over the term of the arrangement.
Lease commencement is determined to be when the lessor provides us access to, and the right to control, the identified asset.
Upon lease commencement, we recognize a
right-of-use
asset and a corresponding lease liability measured at the present value of the fixed future minimum lease payments. We record a
right-of-use
asset for an amount equal to the lease liability, increased for any prepaid lease costs and initial direct costs and reduced by any lease incentives. We remeasure the lease liability and
right-of-use
asset when a remeasurement event occurs.
Many of our leases contain renewal and early termination options. The option periods are generally not included in the lease term used to measure our lease liabilities and
right-of-use
assets upon commencement, as we do not believe the exercise of these options to be reasonably certain. We remeasure the lease liability and
right-of-use
asset when we are reasonably certain to exercise a renewal or an early termination option.
Our leases generally do not provide information about the rate implicit in the lease. Therefore, we utilize an incremental borrowing rate to calculate the present value of our future lease obligations. The incremental borrowing rate represents the rate of interest we would have to pay on a collateralized borrowing, for an amount equal to the lease payments, over a similar term and in a similar economic environment. We use judgment in determining our incremental borrowing rate, which is applied to each lease based on the lease term. An increase or decrease in the incremental borrowing rate applied would impact the value of our
right-of-use
assets and lease liabilities.
We use judgment in determining lease classification, including our determination of the economic life and the fair market value of the identified asset. The fair market value of the identified asset is generally estimated based on comparable market data provided by third-party sources. All of our leases are currently classified as operating leases.
Income Taxes
Income taxes are accounted for using the asset and liability method. Under this method, deferred income taxes arise from temporary differences between the tax basis of assets and liabilities and their reported amounts in our Consolidated Financial Statements. We record reserves for our estimates of the additional income tax liability that is more likely than not to result from the ultimate resolution of foreign and domestic tax examinations. At any one time, many tax years are subject to examination by various taxing jurisdictions. The results of these audits and negotiations with taxing authorities may affect the ultimate settlement of these issues. We review and update the estimates used in the accrual for uncertain tax positions as more definitive information becomes available from taxing authorities, upon completion of tax examination, upon expiration of statutes of limitation, or upon occurrence of other events.
In order to compute income tax on an interim basis, we estimate what our effective tax rate will be for the full fiscal year and adjust these estimates throughout the year as necessary. Adjustments to our income tax provision due to changes in our estimated effective tax rate are recorded in the interim period in which the change occurs. The tax expense (or benefit) related to items other than ordinary income is individually computed and recognized when the items occur. Our effective tax rate in a given financial statement period may be materially impacted by changes in the mix and level of our earnings in various taxing jurisdictions or changes in tax law.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
| --- | --- |
We are exposed to market risks, which include significant deterioration of the U.S. and foreign markets, changes in U.S. interest rates, foreign currency exchange rate fluctuations and the effects of economic uncertainty which may affect the prices we pay our vendors in the foreign countries in which we do business. We do not engage in financial transactions for trading or speculative purposes.
Interest Rate Risk
Our revolver, our term loan and our
364-Day
Credit Agreement each have a variable interest rate which, when drawn upon, subjects us to risks associated with changes in that interest rate. During the first quarter of fiscal 2020, we had borrowings of $487,823,000 under the revolver, all of which were repaid prior to the end of the fiscal year. Additionally, as of January 31, 2021, we had $300,000,000 outstanding under our term loan, all of which was repaid in full in February 2021 prior to maturity, and no amount outstanding under our 364-Day Credit Agreement, which has not been drawn upon. A hypothetical increase or decrease of one percentage point on our existing variable rate debt instruments would not materially affect our results of operations or cash flows.
In addition, we have fixed and variable income investments consisting of short-term investments classified as cash and cash equivalents, which are also affected by changes in market interest rates. As of January 31, 2021, our investments, made primarily in interest bearing demand deposit accounts and money market funds, are stated at cost and approximate their fair values.
Foreign Currency Risks
We purchase the majority of our inventory from vendors outside of the U.S. in transactions that are primarily denominated in U.S. dollars and, as such, any foreign currency impact related to these international purchase transactions was not significant to us during fiscal 2020 or fiscal 2019. Since we pay for the majority of our international purchases in U.S. dollars, however, a decline in the U.S. dollar relative to other foreign currencies would subject us to risks associated with increased purchasing costs from our vendors in their effort to offset any lost profits associated with any currency devaluation. We cannot predict with certainty the effect these increased costs may have on our financial statements or results of operations.
In addition, our businesses in Canada, Australia and the United Kingdom, and our operations throughout Asia and Europe, expose us to market risk associated with foreign currency exchange rate fluctuations. Substantially all of our purchases and sales are denominated in U.S. dollars, which limits our exposure to this risk. However, some of our foreign operations have a functional currency other than the U.S. dollar. While the impact of foreign currency exchange rate fluctuations was not material to us in fiscal 2020, we have continued to see volatility in the exchange rates in the countries in which we do business. As we continue to expand globally, the foreign currency exchange risk related to our foreign operations may increase. To mitigate this risk, we hedge a portion of our foreign currency exposure with foreign currency forward contracts in accordance with our risk management policies (see Note L to our Consolidated Financial Statements).
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
| --- | --- |
Williams-Sonoma, Inc.
Consolidated Statements of Earnings
| In thousands, except per share amounts | Fiscal 2020 (52 weeks) | Fiscal 2019 (52 weeks) | Fiscal 2018 (53 weeks) | |||||||||
| Net revenues | $ | 6,783,189 | $ | 5,898,008 | $ | 5,671,593 | ||||||
| Cost of goods sold | 4,146,920 | 3,758,916 | 3,570,580 | |||||||||
| Gross profit | 2,636,269 | 2,139,092 | 2,101,013 | |||||||||
| Selling, general and administrative expenses | 1,725,572 | 1,673,218 | 1,665,060 | |||||||||
| Operating income | 910,697 | 465,874 | 435,953 | |||||||||
| Interest expense, net | 16,231 | 8,853 | 6,706 | |||||||||
| Earnings before income taxes | 894,466 | 457,021 | 429,247 | |||||||||
| Income taxes | 213,752 | 100,959 | 95,563 | |||||||||
| Net earnings | $ | 680,714 | $ | 356,062 | $ | 333,684 | ||||||
| Basic earnings per share | $ | 8.81 | $ | 4.56 | $ | 4.10 | ||||||
| Diluted earnings per share | $ | 8.61 | $ | 4.49 | $ | 4.05 | ||||||
| Shares used in calculation of earnings per share: | ||||||||||||
| Basic | 77,260 | 78,108 | 81,420 | |||||||||
| Diluted | 79,055 | 79,225 | 82,340 |
See Notes to Consolidated Financial Statements.
Williams-Sonoma, Inc.
Consolidated Statements of Comprehensive Income
| In thousands | Fiscal 2020 (52 weeks) | Fiscal 2019 (52 weeks) | Fiscal 2018 (53 weeks) | |||||||||
| Net earnings | $ 680,714 | $ 356,062 | $ 333,684 | |||||||||
| Other comprehensive income (loss): | ||||||||||||
| Foreign currency translation adjustments | 8,195 | (3,334 | ) | (5,032 | ) | |||||||
| Change in fair value of derivative financial instruments, net of tax (tax benefit) of $(113), $ 195 and $390 | (315 | ) | 163 | 1,098 | ||||||||
| Reclassification adjustment for realized (gain) loss on derivative financial instruments, net of tax (tax benefit) of $149, $261 and $122 | (410 | ) | (343 | ) | (357 | ) | ||||||
| Comprehensive income | $ 688,184 | $ 352,548 | $ 329,393 |
See Notes to Consolidated Financial Statements.
Williams-Sonoma, Inc.
Consolidated Balance Sheets
| In thousands, except per share amounts | Jan. 31, 2021 | Feb. 2, 2020 | ||||||
| ASSETS | ||||||||
| Current assets | ||||||||
| Cash and cash equivalents | $ | 1,200,337 | $ | 432,162 | ||||
| Accounts receivable, net | 143,728 | 111,737 | ||||||
| Merchandise inventories, net | 1,006,299 | 1,100,544 | ||||||
| Prepaid expenses | 93,822 | 90,426 | ||||||
| Other current assets | 22,894 | 20,766 | ||||||
| Total current assets | 2,467,080 | 1,755,635 | ||||||
| Property and equipment, net | 873,894 | 929,038 | ||||||
| Operating lease right-of-use assets | 1,086,009 | 1,166,383 | ||||||
| Deferred income taxes, net | 61,854 | 47,977 | ||||||
| Goodwill | 85,446 | 85,343 | ||||||
| Other long-term assets, net | 87,141 | 69,666 | ||||||
| Total assets | $ | 4,661,424 | $ | 4,054,042 | ||||
| LIABILITIES AND STOCKHOLDERS’ EQUITY | ||||||||
| Current liabilities | ||||||||
| Accounts payable | $ | 542,992 | $ | 521,235 | ||||
| Accrued expenses | 267,592 | 175,003 | ||||||
| Gift card and other deferred revenue | 373,164 | 289,613 | ||||||
| Income taxes payable | 69,476 | 22,501 | ||||||
| Current debt | 299,350 | 299,818 | ||||||
| Operating lease liabilities | 209,754 | 227,923 | ||||||
| Other current liabilities | 85,672 | 73,462 | ||||||
| Total current liabilities | 1,848,000 | 1,609,555 | ||||||
| Deferred lease incentives | 20,612 | 27,659 | ||||||
| Long-term operating lease liabilities | 1,025,057 | 1,094,579 | ||||||
| Other long-term liabilities | 116,570 | 86,389 | ||||||
| Total liabilities | 3,010,239 | 2,818,182 | ||||||
| Commitments and contingencies – See Note I | ||||||||
| Stockholders’ equity | ||||||||
| Preferred stock: $.01 par value; 7,500 shares authorized; none issued | — | — | ||||||
| Common stock: $.01 par value; 253,125 shares authorized; 76,340 and 77,137 shares issued and outstanding at January 31, 2021 and February 2, 2020, respectively | 764 | 772 | ||||||
| Additional paid-in capital | 638,375 | 605,822 | ||||||
| Retained earnings | 1,019,762 | 644,794 | ||||||
| Accumulated other comprehensive loss | (7,117 | ) | (14,587 | ) | ||||
| Treasury stock, at cost: 8 and 14 shares as of January 31, 2021 and February 2, 2020, respectively | (599 | ) | (941 | ) | ||||
| Total stockholders’ equity | 1,651,185 | 1,235,860 | ||||||
| Total liabilities and stockholders’ equity | $ | 4,661,424 | $ | 4,054,042 |
See Notes to Consolidated Financial Statements.
Williams-Sonoma, Inc.
Consolidated Statements of Stockholders’ Equity
| Common Stock | Additional Paid-in Capital | Retained Earnings | Accumulated Other Comprehensive Income (Loss) | Treasury Stock | Total Stockholders’ Equity | |||||||||||||||||||||||
| In thousands | Shares | Amount | ||||||||||||||||||||||||||
| Balance at January 28, 2018 | 83,726 | $ | 837 | $ | 562,814 | $ | 647,422 | $ | (6,782) | $ | (725 | ) | $ | 1,203,566 | ||||||||||||||
| Net earnings | — | — | — | 333,684 | — | — | 333,684 | |||||||||||||||||||||
| Foreign currency translation adjustments | — | — | — | — | (5,032 | ) | — | (5,032 | ) | |||||||||||||||||||
| Change in fair value of derivative financial instruments, net of tax | — | — | — | — | 1,098 | — | 1,098 | |||||||||||||||||||||
| Reclassification adjustment for realized (gain) loss on derivative financial instruments, net of tax | — | — | — | — | (357 | ) | — | (357 | ) | |||||||||||||||||||
| Conversion/release of stock-based awards 1 | 460 | 5 | (14,149 | ) | — | — | (291 | ) | (14,435 | ) | ||||||||||||||||||
| Repurchases of common stock | (5,373 | ) | (53 | ) | (25,775 | ) | (269,476 | ) | — | — | (295,304 | ) | ||||||||||||||||
| Reissuance of treasury stock under stock-based compensation plans 1 | — | — | (418 | ) | (363 | ) | — | 781 | — | |||||||||||||||||||
| Stock-based compensation expense | — | — | 59,428 | — | — | — |
Showing the first 8K of 108K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
| --- | --- |
None.
Item 9A. CONTROLS AND PROCEDURES
| --- | --- |
Evaluation of Disclosure Controls and Procedures
As of January 31, 2021, an evaluation was performed by management, with the participation of our Chief Executive Officer (“CEO”) and our Chief Financial Officer (“CFO”), of the effectiveness of our disclosure controls and procedures. Based on that evaluation, our management, including our CEO and CFO, concluded that our disclosure controls and procedures are effective to ensure that information we are required to disclose in reports that we file or submit under the Securities Exchange Act of 1934 is accumulated and communicated to our management, including our CEO and CFO, as appropriate, to allow for timely discussions regarding required disclosures, and that such information is recorded, processed, summarized and reported within the time periods specified in the rules and forms of the SEC.
Management’s Report on Internal Control Over Financial Reporting
Our management is responsible for establishing and maintaining adequate internal control over the Company’s financial reporting. These internal controls are designed to provide reasonable assurance that the reported information is fairly presented, that disclosures are adequate and that the judgments inherent in the preparation of financial statements are reasonable. There are inherent limitations in the effectiveness of any internal control, including the possibility of human error and the circumvention or overriding of controls. Further, because of changes in conditions, the effectiveness of any internal control may vary over time.
Our management assessed the effectiveness of the Company’s internal control over financial reporting as of January 31, 2021. In making this assessment, we used the criteria set forth by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) in
Internal Control-Integrated Framework (2013).
Based on our assessment using those criteria, our management concluded that, as of January 31, 2021, our internal control over financial reporting is effective.
Our independent registered public accounting firm audited the Consolidated Financial Statements included in this Annual Report on Form
10-K
and the Company’s internal control over financial reporting. Their audit report appears on pages 69 through 71 of this Annual Report on Form
10-K.
Changes in Internal Control Over Financial Reporting
There were no significant changes in our internal control over financial reporting that occurred during the fourth quarter of fiscal 2020, that materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. OTHER INFORMATION
| --- | --- |
None.
PART III
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
| --- | --- |
Information required by this Item is incorporated by reference herein to information under the headings “Election of Directors,” “Information Concerning Executive Officers,” “Audit and Finance Committee Report,” “Corporate Governance — Corporate Governance Guidelines and Code of Business Conduct and Ethics,” and “Corporate Governance — Audit and Finance Committee” in our Proxy Statement for the 2021 Annual Meeting of Stockholders (the “Proxy Statement”). With regard to the information required by this item regarding compliance with Section 16(a) of the Exchange Act, we will provide disclosure of delinquent Section 16(a) reports, if any, in our Proxy Statement, and such disclosure, if any, is incorporated herein by reference.
Item 11. EXECUTIVE COMPENSATION
| --- | --- |
Information required by this Item is incorporated by reference herein to information under the headings “Corporate Governance — Compensation Committee,” “Corporate Governance — Director Compensation,” and “Executive Compensation” in our Proxy Statement.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
| --- | --- |
Information required by this Item is incorporated by reference herein to information under the heading “Security Ownership of Principal Stockholders and Management” in our Proxy Statement.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
| --- | --- |
Information required by this Item is incorporated by reference herein to information under the heading “Certain Relationships and Related Transactions” in our Proxy Statement.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
| --- | --- |
Information required by this Item is incorporated by reference herein to information under the headings “Audit and Finance Committee Report” and “Proposal 4 — Ratification of Selection of Independent Registered Public Accounting Firm — Deloitte Fees and Services” in our Proxy Statement.
PART IV
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
| --- | --- |
| (a | )(1) | Financial Statements: | ||||||
| The following Consolidated Financial Statements of Williams-Sonoma, Inc. and subsidiaries and the related notes are filed as part of this report pursuant to Item 8: | ||||||||
| PAGE | ||||||||
| Consolidated Statements of Earnings | 46 | |||||||
| Consolidated Statements of Comprehensive Income | 46 | |||||||
| Consolidated Balance Sheets | 47 | |||||||
| Consolidated Statements of Stockholders’ Equity | 48 | |||||||
| Consolidated Statements of Cash Flows | 49 | |||||||
| Notes to Consolidated Financial Statements | 50 | |||||||
| Report of Independent Registered Public Accounting Firm | 69 | |||||||
| Quarterly Financial Information | 72 | |||||||
| (a | )(2) | Financial Statement Schedules: Schedules have been omitted because they are not required, are not applicable, or because the required information, where material, is included in the financial statements, notes, or supplementary financial information. | ||||||
| (a | )(3) | Exhibits: The exhibits listed in the below Exhibit Index are filed or incorporated by reference as part of this Form 10-K | ||||||
| (b | ) | Exhibits: The exhibits listed in the below Exhibit Index are filed or incorporated by reference as part of this Form 10-K | ||||||
| (c | ) | Financial Statement Schedules: Schedules have been omitted because they are not required or are not applicable. |
Exhibit Index
| XBRL | ||||
| 101 | * | The following financial statements from the Company’s Annual Report on Form 10-K for the fiscal year ended January 31, 2021, formatted in Inline XBRL: (i) Consolidated Statements of Earnings, (ii) Consolidated Statements of Comprehensive Income, (iii) Consolidated Balance Sheets, (iv) Consolidated Statements of Stockholders’ Equity, (v) Consolidated Statements of Cash Flows and (vi) Notes to Consolidated Financial Statements, tagged as blocks of text and including detailed tags | ||
| 104 | * | Cover Page Interactive Data File (formatted as Inline XBRL and contained in the Interactive Data Files submitted under Exhibit 101). |
| * | Filed herewith. |
|---|
| + | Indicates a management contract or compensatory plan or arrangement. |
|---|
Item 16. FORM 10-K SUMMARY
| --- | --- |
None.
SIGNATURES
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| WILLIAMS-SONOMA, INC. | ||||||
| Date: March 30, 2021 | By | /S/ LAURA ALBER | ||||
| Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, this report has been signed below by the following persons on behalf of the registrant and in the capacities and on the dates indicated.
| Date: March 30, 2021 | /s/ SCOTT DAHNKE | |
| Scott Dahnke | ||
| Chairman of the Board of Directors | ||
| Date: March 30, 2021 | /s/ LAURA ALBER | |
| Laura Alber | ||
| Chief Executive Officer and Director | ||
| (principal executive officer) | ||
| Date: March 30, 2021 | /s/ JULIE WHALEN | |
| Julie Whalen | ||
| Chief Financial Officer | ||
| (principal financial officer and principal accounting officer) | ||
| Date: March 30, 2021 | /s/ ANNE MULCAHY | |
| Anne Mulcahy | ||
| Director | ||
| Date: March 30, 2021 | /s/ WILLIAM READY | |
| William Ready | ||
| Director | ||
| Date: March 30, 2021 | /s/ SABRINA SIMMONS | |
| Sabrina Simmons | ||
| Director | ||
| Date: March 30, 2021 | /s/ FRITS VAN PAASSCHEN | |
| Frits van Paasschen | ||
| Director |