 filings.tools
Weyerhaeuser 2015 10-K Annual Report
WY · CIK 106535 · Form 10-K · Fiscal year ended December 31, 2015 · Filed February 17, 2016
Revenue fell 4.3% to $7.08 billion. Operating margin was 13.0%, against 17.8% the year before. Net income was $506 million.
19 sections, 485K characters. Original on sec.gov · ·
Risk FactorsBusinessMD&AFinancial StatementsWhat changed vs 2014
| Measure | Year ended Dec 31, 2015 | Year ended Dec 31, 2014 | Change |
|---|---|---|---|
| Revenue | $7.08B | $7.40B | -4.3% |
| Operating income | $919M | $1.32B | -30.4% |
| Net income | $506M | $1.83B | -72.3% |
| Diluted EPS | $0.89 | $3.18 | -72.0% |
| Free cash flow* | $621M | $734M | -15.4% |
| Cash and equivalents | $1.01B | $1.58B | -35.9% |
| Operating margin* | 13.0% | 17.8% | -4.9 pts |
From the XBRL facts tagged to this filing; both columns are as reported in this filing. * Computed by filings.tools: free cash flow is operating cash flow less capital spending; operating margin is operating income over revenue.
Cover and table of contents
10-K 1 wy-123115x10k.htm 10-K
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 10-K
[X] ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(D) OF THE SECURITIES EXCHANGE ACT OF 1934
FOR THE FISCAL YEAR ENDED DECEMBER 31, 2015
or
[ ] TRANSITION REPORT PURSUANT TO SECTION 13 OR 15(D) OF THE SECURITIES EXCHANGE ACT OF 1934
FOR THE TRANSITION PERIOD FROM TO
COMMISSION FILE NUMBER 1-4825
WEYERHAEUSER COMPANY
A WASHINGTON CORPORATION
91-0470860
(IRS EMPLOYER IDENTIFICATION NO.)
33663 WEYERHAEUSER WAY SOUTH, FEDERAL WAY, WASHINGTON 98063-9777 TELEPHONE (253) 924-2345
SECURITIES REGISTERED PURSUANT TO SECTION 12(B) OF THE ACT:
| TITLE OF EACH CLASS | NAME OF EACH EXCHANGE ON WHICH REGISTERED: | |
| Common Shares ($1.25 par value) | Chicago Stock Exchange | |
| New York Stock Exchange | ||
| 6.375% Mandatory Convertible Preference Shares, Series A ($1.00 par value) | New York Stock Exchange |
Indicate by check mark if the registrant is a well-known seasoned issuer, as defined in Rule 405 of the Securities Act. [X] Yes [ ] No
Indicate by check mark if the registrant is not required to file reports pursuant to Section 13 or Section 15(d) of the Act. [ ] Yes [X] No
Indicate by check mark whether the registrant (1) has filed all reports required to be filed by Section 13 or 15(d) of the Securities Exchange Act of 1934 during the preceding 12 months (or for such shorter period that the registrant was required to file such reports), and (2) has been subject to such filing requirements for the past 90 days. [X] Yes [ ] No
Indicate by check mark whether the registrant has submitted electronically and posted on its corporate Website, if any, every Interactive Data File required to be submitted and posted pursuant to Rule 405 of Regulation S-T (§ 232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit and post such files). [X] Yes [ ] No
Indicate by check mark if disclosure of delinquent filers pursuant to Item 405 of Regulation S-K (§ 229.405 of this chapter) is not contained herein, and will not be contained, to the best of registrant’s knowledge, in definitive proxy or information statements incorporated by reference in Part III of this Form 10-K or any amendment to this Form 10-K. [ ]
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, or a smaller reporting company. See the definitions of “large accelerated filer,” “accelerated filer” and “smaller reporting company” in Rule 12b-2 of the Exchange Act.
Large accelerated filer [X] Accelerated filer [ ] Non-accelerated filer [ ] Smaller reporting company [ ]
Indicate by check mark whether the registrant is a shell company (as defined in Rule 12b-2 of the Act). [ ] Yes [X] No
As of June 30, 2015, the aggregate market value of the registrant’s common stock held by non-affiliates of the registrant was $16.0 billion based on the closing sale price as reported on the New York Stock Exchange Composite Price Transactions.
As of January 29, 2016, 510,492,965 shares of the registrant’s common stock ($1.25 par value) were outstanding.
DOCUMENTS INCORPORATED BY REFERENCE
Portions of the Notice of 2016 Annual Meeting of Shareholders and Proxy Statement for the company’s Annual Meeting of Shareholders to be held May 20, 2016, are incorporated by reference into Part II and III.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K
TABLE OF CONTENTS
Item 1. OUR BUSINESS
OUR BUSINESS
We are one of the world's largest private owners of timberlands. We own or control nearly 7 million acres of timberlands, primarily in the U.S., and manage additional timberlands under long-term licenses in Canada. We manage these timberlands on a sustainable basis in compliance with internationally recognized forestry standards. We are also one of the largest manufacturers of wood and specialty cellulose fibers products. Our company is a real estate investment trust (REIT).
We are committed to operate as a sustainable company and are listed on the Dow Jones World Sustainability Index. We focus on increasing energy and resource efficiency, reducing greenhouse gas emissions, reducing water consumption, conserving natural resources, and offering products that meet human needs with superior sustainability attributes. We operate with world class safety results, understand and address the needs of the communities in which we operate, and present ourselves transparently.
In 2015, we generated $7.1 billion in net sales and employed approximately 12,600 people who serve customers worldwide.
This portion of our Annual Report and Form 10-K provides detailed information about who we are, what we do and where we are headed. Unless otherwise specified, current information reported in this Form 10-K is as of the fiscal year ended December 31, 2015.
We break out financial information such as revenues, earnings and assets by the business segments that form our company. We also discuss the development of our company and the geographic areas where we do business.
Throughout this Form 10-K, unless specified otherwise, references to “we,” “our,” “us” and “the company” refer to the consolidated company.
| WE CAN TELL YOU MORE |
AVAILABLE INFORMATION
We meet the information-reporting requirements of the Securities Exchange Act of 1934 by filing periodic reports, proxy statements and other information with the Securities and Exchange Commission (SEC). These reports and statements — information about our company’s business, financial results and other matters — are available at:
| • | the SEC website — www.sec.gov; |
| • | the SEC’s Public Conference Room, 100 F St. N.E., Washington, D.C., 20549, (800) SEC-0330; and |
| • | our website — www.weyerhaeuser.com. |
When we file the information electronically with the SEC, it also is posted to our website.
| WHO WE ARE |
We started out as Weyerhaeuser Timber Company, incorporated in the state of Washington in January 1900, when Frederick Weyerhaeuser and 15 partners bought 900,000 acres of timberland. Today, we are working to grow a truly great company for our shareholders, customers and employees. We grow and harvest trees and manufacture and sell products made from trees.
REAL ESTATE INVESTMENT TRUST (REIT) ELECTION
Starting with our 2010 fiscal year, we elected to be taxed as a REIT. We expect to derive most of our REIT income from investments in timberlands, including the sale of standing timber through pay-as-cut sales contracts and lump sum timber deeds. REIT income can be distributed to shareholders without first paying corporate level tax, substantially eliminating the double taxation on income. A significant portion of our timberland segment earnings receives this favorable tax treatment. We continue to be required to pay federal corporate income taxes on earnings of our Taxable REIT Subsidiary (TRS), which includes our manufacturing businesses and the portion of our Timberlands segment income included in the TRS.
PENDING MERGER WITH PLUM CREEK
On November 6, 2015 Weyerhaeuser Company and Plum Creek Timber Company, Inc. (“Plum Creek”) entered into an Agreement and Plan of Merger (“Merger Agreement”) pursuant to which Plum Creek will merge with and into Weyerhaeuser Company with Weyerhaeuser continuing as the surviving corporation. Under the terms of the Merger Agreement, Plum Creek shareholders will receive 1.60 shares of Weyerhaeuser common shares for each share of Plum Creek common stock at the closing date. Plum Creek is a REIT that owns and manages more than 6 million acres of timberland in the United States. In addition Plum Creek produces wood products, develops opportunities for mineral and other natural resource extraction, and develops and sells real estate properties. See Note 4: Acquisitions in the Notes to Consolidated Financial Statements for further information about the pending merger.
OUR BUSINESS SEGMENTS
In the Consolidated Results section of Management’s Discussion and Analysis of Financial Condition and Results of Operations, you will find our overall performance results for our business segments:
| • | Timberlands, |
| • | Wood Products and |
| • | Cellulose Fibers. |
Detailed financial information about our business segments and our geographic locations is in Note 2: Business Segments and Note 21: Geographic Areas in the Notes to Consolidated Financial Statements, as well as in this section and in Management’s Discussion and Analysis of Financial Condition and Results of Operations.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 1
On November 8, 2015 Weyerhaeuser announced that the board authorized the exploration of strategic alternatives for its Cellulose Fibers business. At this time there can be no assurance that the board's evaluation process will result in any transaction or that any transaction, if pursued, will be consummated.
EFFECT OF MARKET CONDITIONS
The health of the U.S. housing market strongly affects our Wood Products and Timberlands segments. Wood Products primarily sells into the new residential building and repair and remodel markets. Demand for logs from our Timberlands segment is affected by the production of wood-based building products as well as export demand. Cellulose Fibers is primarily affected by global demand and the relative strength of the U.S. dollar.
COMPETITION IN OUR MARKETS
We operate in highly competitive domestic and foreign markets, with numerous companies selling similar products. Many of our products also face competition from substitutes for wood and wood-fiber products. We compete in our markets primarily through price, product quality and service levels. We are relentlessly focused on improving operational excellence to ensure a competitive cost structure and producing quality products customers want and are wiling to pay for.
Our business segments’ competitive strategies are as follows:
| • | Timberlands — Extract maximum value from each acre we own or manage. |
| • | Wood Products — Deliver high-quality lumber, structural panels, engineered wood products and complementary building products for residential, multi-family, industrial and light commercial applications at competitive costs. |
| • | Cellulose Fibers — Concentrate on value-added pulp products and low cost manufacturing assets. |
SALES OUTSIDE THE U.S.
In 2015, $2.3 billion — 32 percent — of our total consolidated sales from continuing operations were to customers outside the U.S. Our sales outside the U.S. are generally denominated in U.S. dollars. The table below shows sales outside the U.S. for the last three years.
| SALES OUTSIDE THE U.S. IN MILLIONS OF DOLLARS | |||||||||
| 2015 | 2014 | 2013 | |||||||
| Exports from the U.S. | $ | 1,719 | $ | 1,892 | $ | 1,891 | |||
| Canadian export and domestic sales | 400 | 472 | 488 | ||||||
| Other foreign sales | 144 | 150 | 114 | ||||||
| Total | $ | 2,263 | $ | 2,514 | $ | 2,493 | |||
| Percent of total sales | 32 | % | 34 | % | 29 | % |
OUR EMPLOYEES
We have approximately 12,600 employees. This number includes:
| • | 11,700 employed in North America and |
| • | 900 employed by our operations outside of North America. |
Of these employees, approximately 3,500 are members of unions covered by multi-year collective-bargaining agreements. More information about these agreements is in Note 9: Pension and Other Postretirement Benefit Plans in the Notes to Consolidated Financial Statements.
| WHAT WE DO |
This section provides information about how we:
| • | grow and harvest trees and |
| • | manufacture and sell products made from them. |
For each of our business segments, we provide details about what we do, where we do it, how much we sell and where we are headed.
TIMBERLANDS
Our Timberlands segment manages 6.9 million acres of private commercial timberlands worldwide. We own 6.3 million of those acres and have long-term leases on the other 0.6 million acres. In addition, we have renewable, long-term licenses on Canadian timberlands. The tables presented in this section include data from this segment's business units as of the end of 2015.
WHAT WE DO
Forestry Management
Our Timberlands segment:
| • | grows and harvests trees to be converted into lumber, other wood and building products and pulp and paper; |
| • | exports logs to other countries where they are made into products; |
| • | plants seedlings to reforest harvested areas using the most effective regeneration method for the site and species (in parts of Canada natural regeneration is employed); |
| • | monitors and cares for the planted trees as they grow to maturity; and |
| • | strives to sustain and maximize the timber supply from our timberlands while keeping the health of our environment a key priority. |
Our goal is to maximize returns by selling logs and stumpage to internal and external customers. We focus on solid wood and use intensive silviculture to improve forest productivity and returns while managing our forests on a sustainable basis to meet customer and public expectations.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 2
Sustainable Forestry Practices
We are committed to responsible environmental stewardship wherever we operate, managing forests to produce financially mature timber while protecting the ecosystem services they provide. Our working forests include places with unique environmental, cultural, historical or recreational value. To protect their unique qualities, we follow regulatory requirements, voluntary standards and implement the Sustainable Forestry Initiative® (SFI) standard. Independent auditing of all of the forests we own or manage in the United States and Canada certifies that we meet the SFI standard. Our timberlands in Uruguay are certified under the Forest Stewardship Council (FSC) standard or the Uruguayan national forestry management standard which is endorsed by the Program for the Endorsement of Forest Certification (PEFC).
Canadian Forestry Operations
In Canada, we manage timberlands under long-term licenses that provide raw material for our manufacturing facilities in various provinces. When we harvest trees, we pay the provinces at stumpage rates set by the government, which generally are based on prevailing market prices. We transfer logs to our manufacturing facilities at cost, and do not generate any profit in the Timberlands segment from the harvest of timber from the licensed acres in Canada.
Other Values From Our Timberlands
In the United States, we actively manage mineral, oil and gas leases on our land and use geologic databases to identify and market opportunities for commercial mineral and geothermal development. We recognize leasing, bonus, and option revenue over the terms of agreements with customers. Revenue primarily comes from:
| • | royalty payments on oil and gas production; |
| • | bonus payments from oil and gas leasing and exploration activity; |
| • | royalty payments on hard minerals (rock, sand and gravel); |
| • | geothermal lease and option revenues; and |
| • | the sale of mineral assets. |
In managing mineral resources, we generate revenue related to our ownership of the minerals and, separately, related to our ownership of the surface. The ownership of mineral rights and surface acres may be held by two separate parties. Materials that can be mined from the surface, and whose value comes from factors other than their chemical composition, typically belong to the surface owner. Examples of surface materials include rock, sand, gravel, dirt and topsoil. The mineral owner holds the title to commodities that derive value from their unique chemical composition. Examples of mineral rights include oil, gas, coal (even if mined at the surface) and precious metals. If the two types of rights conflict, then mineral rights generally are superior to surface rights. A third type of land right is geothermal, which can belong to either the surface or mineral owner. We routinely reserve mineral and geothermal rights when selling surface timberlands acreage.
Timberlands Products
| PRODUCTS | HOW THEY’RE USED |
| Logs | Logs are made into lumber, other wood and building products, and pulp and paper products. |
| Timberlands | Timberland tracts are sold or exchanged to maximize value or improve our timberland portfolio. |
| Timber | Standing timber is sold to third parties. |
| Minerals, oil and gas | Minerals, oil and gas are sold into construction and energy markets. |
| Other products | Seed and seedlings grown in the U.S. and plywood produced at our mill in Uruguay are sold to third parties. U.S. timberlands are leased to the public for recreational purposes. |
HOW WE MEASURE OUR PRODUCT
We report Timberlands data in cubic meters. Cubic meters measure the total volume of wood fiber in a tree or log that we can sell. Cubic meter volume is determined from the large and small-end diameters and length and provides a comparative measure of timber and log volume among operating regions, species, size and seasons of the year.
We also use multiple units of measure when transacting business including:
| • | Thousand board feet (MBF) — used in the West to measure the expected lumber recovery from a tree or log. This measure does not include taper or recovery of non-lumber residual products. |
| • | Hundred cubic feet (CCF) — used in the West to measure the volume of a log. The measure does not include any calculation for expected lumber recovery. |
| • | Green tons (GT) — used in the South to measure weight; factors used for conversion to product volume can vary by species, size, location and season. |
WHERE WE DO IT
Our timberlands assets are located primarily in North America. In the U.S. we own and manage sustainable timberlands in nine states for use in wood products and pulp and paper manufacturing. We own or lease:
| • | 4.0 million acres in the southern U.S. (Alabama, Arkansas, Louisiana, Mississippi, North Carolina, Oklahoma and Texas); and |
| • | 2.6 million acres in the Pacific Northwest (Oregon and Washington). |
We also own and operate nurseries and seed orchards in Washington, Oregon, South Carolina and Georgia.
Our international operations are located in Uruguay, where we own 298,000 acres and have long-term leases on 25,000 acres. In Canada, we manage timberlands under long-term licenses that provide raw material for our manufacturing facilities. These licenses are in Alberta, British Columbia, Ontario (license is managed by partnership) and Saskatchewan.
Our total timber inventory — including timber on owned and leased land— is approximately 350 million cubic meters. The amount of timber inventory does not translate into an amount of lumber or panel products because the quantity of end products:
| • | varies according to the species, size and quality of the timber; and |
| • | will change through time as the mix of these variables adjust. |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 3
The species, size and grade of the trees affects the relative value of our timberlands.
We maintain our timber inventory in an integrated resource inventory and geographic information system (“GIS”). The resource inventory component of the system is proprietary and is largely based on internally developed technologies, including growth and yield models developed by our research and development organization. The GIS component is based on GIS software that is viewed as the standard in our industry.
Timber inventory data collection and verification techniques include the use of industry standard field sampling procedures as well as proprietary remote sensing technologies in some geographies where they generate improved estimates. The data is collected and maintained at the timber stand level.
United States
Summary of 2015 United States Standing Timber Inventory
| GEOGRAPHIC AREA | MILLIONS OF CUBIC METERS AT DECEMBER 31, 2015 | |
| TOTAL INVENTORY(1) | ||
| West: | ||
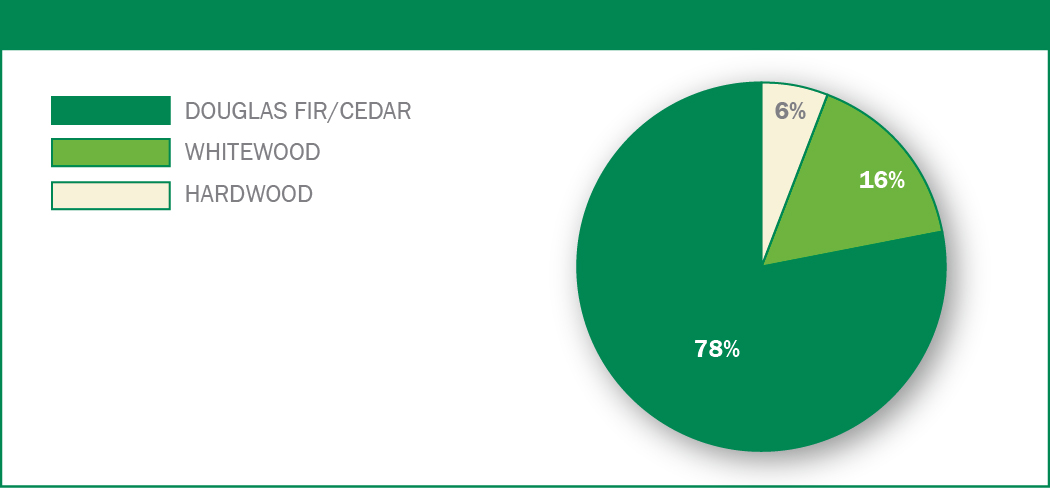
| Douglas fir/Cedar | 153 | |
| Whitewood | 31 | |
| Hardwood | 12 | |
| 196 | ||
| South: | ||
| Southern yellow pine | 113 | |
| Hardwood | 29 | |
| 142 | ||
| Total U.S. | 338 | |
| (1) Inventory includes all conservation and set aside areas. |
Summary of 2015 United States Timberland Locations
| GEOGRAPHIC AREA | THOUSANDS OF ACRES AT DECEMBER 31, 2015 | |||||
| FEE OWNERSHIP | LONG- TERM LEASES | TOTAL ACRES(1) | ||||
| U.S.: | ||||||
| West | 2,594 | — | 2,594 | |||
| South | 3,403 | 630 | 4,033 | |||
| Total U.S. | 5,997 | 630 | 6,627 | |||
| (1) Acres include all conservation and set aside areas. |
We provide a constant year round flow of logs to internal and third-party customers. We sell grade logs to mills that manufacture a diverse range of products including lumber, plywood and veneer. We also sell chips and fiber logs to pulp, paper and oriented strand board mills. We also sell standing timber to third parties. Our timberlands are well located to take advantage of road, logging and transportation systems for efficient delivery of logs to these customers.
Western United States
Our Western acres are well situated to serve the wood product markets in Oregon and Washington. In addition, our location on the West Coast provides access to higher-value export markets for Douglas fir and whitewood logs in Japan, China and Korea. The size and quality of our Western Timberlands, coupled with their proximity to several deep-water port facilities, positions us to meet the needs of Pacific Rim log markets.
Our lands are composed primarily of Douglas fir, a species highly valued for its structural strength. Our coastal lands also contain whitewood and have a higher proportion of hemlock and other whitewoods than our interior holdings. Our management systems provide us a competitive operating advantage and range from research and forestry, to technical planning models, mechanized harvesting, and marketing and logistics.
On July 23, 2013, we purchased 100 percent of the equity interests in Longview Timber LLC (Longview Timber) for $1.58 billion cash and assumed debt of $1.07 billion, for an aggregate purchase price of $2.65 billion. Longview Timber was a privately-held Delaware limited liability company engaged in the ownership and management of approximately 645,000 acres of timberlands in Oregon and Washington. More information on this transaction can be found in Note 4: Acquisitions in the Notes to Consolidated Financial Statements.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 4
2015 Western U.S. Inventory by Species
2015 Western U.S. Inventory by Age / Species

The average age of timber harvested in 2015 was 52 years. Most of our U.S. timberland is intensively managed for timber production, but some areas are conserved for environmental, historical, recreational or cultural reasons. Some of our older trees are protected in acreage set aside for conservation, and some are not yet logged due to harvest rate regulations. While over the long term our average harvest age will decrease in accordance with our sustainable forestry practices, we harvest generally 2 percent of our Western acreage each year.
Southern United States
Our Southern acres predominantly contain southern yellow pine and encompass timberlands in seven states.
We intensively manage our timber plantations using forestry research and planning systems to optimize grade log production. We also actively manage our land to capture revenues from our oil, gas and hard minerals resources. We do this while providing quality habitat for a range of animals and birds. We lease more than 94 percent of our acres to the public and state wildlife agencies for recreational purposes.
2015 Southern U.S. Inventory by Species

WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 5
2015 Southern U.S. Inventory by Age / Species

The average age of timber harvested in 2015 was 31 years for southern yellow pine. In accordance with our sustainable forestry practices, we harvest generally 3 percent of our acreage each year in the South.
International
Summary of 2015 International Standing Timber Inventory
| GEOGRAPHIC AREA | MILLIONS OF CUBIC METERS AT DECEMBER 31, 2015 | |
| TOTAL INVENTORY | ||
| Uruguay: | ||
| Pine | 8 | |
| Eucalyptus | 4 | |
| Total International | 12 |
Summary of 2015 International Timberland Locations
| GEOGRAPHIC AREA | THOUSANDS OF ACRES AT DECEMBER 31, 2015 | |||||
| FEE OWNERSHIP | LONG-TERM LEASES | TOTAL ACRES | ||||
| Uruguay | 298 | 25 | 323 |
Our timberland acres in Uruguay are split approximately 49 percent loblolly pine and 51 percent eucalyptus. Loblolly pine comprises more of our timber inventory due to its older age. On average, the timber in Uruguay is in the second third of its rotation age. It is entering into that part of the growth rotation when we will see increased volume accretion. About 97 percent of the area to be planted has been afforested to date.
2015 International Inventory by Species (Uruguay)

In Uruguay, the target rotation ages are 21 to 22 years for pine and 14 to 17 years for eucalyptus. We manage both species to a grade (appearance) regime.
We also operate a plywood mill in Uruguay with a production capacity of 250,000 cubic meters. Production volume reached 218,000 cubic meters in 2015.
In Brazil, we were a managing partner in a joint venture that operated a hardwood sawmill. We sold our interest in this joint venture during 2014.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 6
Canada — Licensed Timberlands
We manage timberlands in Canada under long-term licenses from the provincial governments to secure volume for our manufacturing facilities in various provinces. The provincial governments regulate the volume of timber that may be harvested each year through Annual Allowable Cuts (AAC), which are updated every 10 years. As of December 31, 2015, our AAC by province was:
| • | Alberta — 3,906 thousand cubic meters, |
| • | British Columbia — 804 thousand cubic meters, |
| • | Ontario — 146 thousand cubic meters and |
| • | Saskatchewan — 788 thousand cubic meters. |
When the volume is harvested, we pay the province at stumpage rates set by the government and generally based on prevailing market prices. The harvested logs are transferred to our manufacturing facilities at cost (stumpage plus harvest, haul and overhead costs less any margin on selling logs to third parties). Any profit from harvesting the log through to converting it to a finished product is recognized at the respective mill in either the Cellulose Fibers or Wood Products segment.
| GEOGRAPHIC AREA | THOUSANDS OF ACRES AT DECEMBER 31, 2015 | |
| TOTAL LICENSE ARRANGEMENTS | ||
| Canada: | ||
| Alberta | 5,306 | |
| British Columbia | 1,008 | |
| Ontario(1) | 2,574 | |
| Saskatchewan | 4,987 | |
| Total Canada | 13,875 | |
| (1) License is managed by partnership. |
Five-Year Summary of Timberlands Fee Harvest Volumes
| FEE HARVEST VOLUMES IN THOUSANDS | ||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||
| Fee harvest volume – cubic meters: | ||||||||||
| West | 11,130 | 11,173 | 8,907 | 7,170 | 6,595 | |||||
| South | 11,568 | 11,676 | 11,596 | 11,488 | 9,738 | |||||
| International | 889 | 990 | 818 | 763 | 854 | |||||
| Total | 23,587 | 23,839 | 21,321 | 19,421 | 17,187 |
Our Timberlands annual fee harvest volumes represents the depletion of the timber assets we own. Depletion is a method of expensing the cost of establishing the fee timber asset base over the harvest or timber sales volume.
Our fee harvest volumes are managed sustainably across all regions to ensure the preservation of long-term economic value of the timber and to capture maximum value from the markets. This is accomplished by ensuring annual harvest schedules target financially mature timber and reforestation activities align with the growing of timber through its life cycle to financial maturity.
Five-Year Summary of Timberlands Fee Harvest Volumes - Percentage of Grade and Fiber
| PERCENTAGE OF GRADE AND FIBER | |||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | |||||||
| West | Grade | 87 | % | 89 | % | 90 | % | 90 | % | 90 | % |
| Fiber | 13 | % | 11 | % | 10 | % | 10 | % | 10 | % | |
| South | Grade | 59 | % | 59 | % | 57 | % | 59 | % | 58 | % |
| Fiber | 41 | % | 41 | % | 43 | % | 41 | % | 42 | % | |
| International | Grade | 65 | % | 63 | % | 60 | % | 67 | % | 55 | % |
| Fiber | 35 | % | 37 | % | 40 | % | 33 | % | 45 | % | |
| Total | Grade | 73 | % | 73 | % | 69 | % | 71 | % | 70 | % |
| Fiber | 27 | % | 27 | % | 31 | % | 29 | % | 30 | % |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 7
HOW MUCH WE SELL
Our net sales to unaffiliated customers over the last two years were:
| • | $1.4 billion in 2015 — down 10 percent from 2014; and |
| • | $1.5 billion in 2014. |
Our intersegment sales over the last two years were:
| • | $830 million in 2015 — down 4 percent from 2014; and |
| • | $867 million in 2014. |
Five-Year Summary of Net Sales for Timberlands
| NET SALES IN MILLIONS OF DOLLARS | |||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | |||||||||||
| To unaffiliated customers: | |||||||||||||||
| Logs: | |||||||||||||||
| West | $ | 830 | $ | 972 | $ | 828 | $ | 559 | $ | 545 | |||||
| South | 241 | 257 | 256 | 233 | 196 | ||||||||||
| Canada | 24 | 22 | 19 | 19 | 17 | ||||||||||
| Total | 1,095 | 1,251 | 1,103 | 811 | 758 | ||||||||||
| Chip sales | 15 | 12 | 9 | 18 | 19 | ||||||||||
| Timberlands sales and exchanges(1) | 62 | 52 | 65 | 59 | 77 | ||||||||||
| Higher and better use land sales(1) | 14 | 19 | 19 | 22 | 25 | ||||||||||
| Minerals, oil and gas | 26 | 32 | 32 | 31 | 53 | ||||||||||
| Products from international operations(2) | 87 | 96 | 90 | 106 | 86 | ||||||||||
| Other products | 51 | 35 | 25 | 30 | 26 | ||||||||||
| Subtotal sales to unaffiliated customers | 1,350 | 1,497 | 1,343 | 1,077 | 1,044 | ||||||||||
| Intersegment sales: | |||||||||||||||
| United States | 559 | 576 | 518 | 447 | 424 | ||||||||||
| Other | 271 | 291 | 281 | 236 | 222 | ||||||||||
| Subtotal intersegment sales | 830 | 867 | 799 | 683 | 646 | ||||||||||
| Total | $ | 2,180 | $ | 2,364 | $ | 2,142 | $ | 1,760 | $ | 1,690 | |||||
| (1) Significant dispositions of higher and better use timberland and some nonstrategic timberlands are made through subsidiaries. (2) Products include logs, plywood and hardwood lumber harvested or produced by our international operations. Includes sales from our operations in Uruguay, Brazil (sold in 2014) and China (sold in 2012). |
Five-Year Trend for Total Net Sales in Timberlands

WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 8
Percentage of 2015 Sales Dollars to Unaffiliated Customers

Log Sales Volumes
Logs sold to unaffiliated customers in 2015 decreased 0.5 million cubic meters — 3 percent — from 2014.
| • | Sales volumes in the West decreased 0.3 million cubic meters — 3 percent — primarily due to lower export sales to China and Korea. |
| • | Sales to unaffiliated customers in the South decreased 378 thousand cubic meters — 7 percent — primarily due to lower fee log harvest production. |
| • | Sales volumes from Canada increased 95 thousand cubic meters — 16 percent — in 2015. The increase in volume to unaffiliated customers was primarily due to an increase in delivered log sales versus stumpage sales. |
| • | Sales volumes from our international operations increased 44 thousand cubic meters — 7 percent — in 2015. The increase in volume was primarily due to increased fiber log sales in Uruguay. |
We sell three grades of logs — domestic grade, domestic fiber and export. Factors that may affect log sales in each of these categories include:
| • | domestic grade log sales — lumber usage, primarily for housing starts and repair and remodel activity, the needs of our own mills and the availability of logs from both outside markets and our own timberlands; |
| • | domestic fiber log sales — demand for chips by pulp, containerboard mills, and OSB mills; and |
| • | export log sales — the level of housing starts in Japan and construction in China. |
Our sales volumes include logs purchased in the open market and all our domestic and export logs that are sold to unaffiliated customers or transferred at market prices to our internal mills.
Five-Year Summary of Log Sales Volumes to Unaffiliated Customers for Timberlands
| SALES VOLUMES IN THOUSANDS | ||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||
| Logs – cubic meters: | ||||||||||
| West | 8,672 | 8,980 | 7,708 | 5,898 | 5,267 | |||||
| South | 5,300 | 5,678 | 5,888 | 5,575 | 4,879 | |||||
| Canada | 687 | 592 | 511 | 531 | 479 | |||||
| International | 648 | 604 | 357 | 343 | 314 | |||||
| Total | 15,307 | 15,854 | 14,464 | 12,347 | 10,939 |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 9
Log Prices
The majority of our log sales to unaffiliated customers involve sales to domestic sawmills and the export market. Log prices in the following tables are on a delivered (mill) basis:
Five-Year Summary of Published Domestic Log Prices (#2 Sawlog Bark On — $/MBF)

Five-Year Summary of Export Log Prices (#2 Sawlog Bark On — $/MBF)

Our log prices are affected by the supply of and demand for grade and fiber logs and are influenced by the same factors that affect log sales. Export log prices are particularly affected by the Japanese housing market and Chinese demand.
Our average 2015 log realizations in the West decreased from 2014 — primarily due to weaker export log markets. Our average 2015 log realizations in the South were flat from 2014.
Minerals and Energy Products
Mineral revenue was down in 2015 as royalty revenue from natural gas declined amid weaker oil and gas prices and construction aggregates declined.
WHERE WE’RE HEADED
Our competitive strategies include:
| • | continuing to capitalize on our scale operations, silviculture expertise and sustainability practices; |
| • | maximizing cash flow through operational excellence initiatives such as merchandising for value, harvest and transportation efficiencies, and flexing harvest to seasonal and short term opportunities; |
| • | sustaining our export and domestic market access, infrastructure and strong customer relationships; and |
| • | increasing non-timber revenue streams. |
On November 6, 2015 we entered into a Merger Agreement with Plum Creek. Plum Creek is among the largest and most geographically diverse private landowners in the United States with more than 6 million acres of timberlands in 19 states, including significant holdings in proximity to our Western and Southern timberlands. Pending the completion of the merger, the combined company will own more than 13 million acres of timberlands.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 10
WOOD PRODUCTS
We are a large manufacturer and distributor of wood products primarily in North America and Asia.
WHAT WE DO
Our wood products segment:
| • | provides a family of high-quality softwood lumber, engineered wood products, structural panels and other specialty products to the residential, multi-family, industrial, light commercial and repair and remodel markets; |
| • | distributes our products as well as complementary building products that we purchase from other manufacturers; and |
| • | exports our softwood lumber, oriented strand board (OSB) and engineered wood products primarily to Asia. |
Wood Products
| PRODUCTS | HOW THEY’RE USED |
| Structural lumber | Structural framing for new residential, repair and remodel, treated applications, industrial and commercial structures |
| Engineered wood products • Solid section • I-joists | Floor and roof joists, and headers and beams for residential, multi-family and commercial structures |
| Structural panels • OSB • Softwood plywood | Structural sheathing, subflooring and stair tread for residential, multi-family and commercial structures |
| Other products | Wood chips and other byproducts |
| Complimentary building products | Complementary building products such as cedar, decking, siding, insulation and rebar sold in our distribution facilities |
WHERE WE DO IT
We operate manufacturing facilities in the United States and Canada. We distribute through a combination of Weyerhaeuser and third-party locations. Information about the locations, capacities and actual production of our manufacturing facilities is included below.
Principal Manufacturing Locations
Locations of our principal manufacturing facilities as of December 31, 2015, by major product group were:
| • | Structural lumber |
– U.S. — Alabama, Arkansas, Louisiana, Mississippi, North Carolina, Oklahoma, Oregon and Washington
– Canada — Alberta and British Columbia
| • | Engineered wood products |
– U.S. — Alabama, Louisiana, Oregon and West Virginia
– Canada — British Columbia and Ontario
| • | Oriented strand board |
– U.S. — Louisiana, Michigan, North Carolina and West Virginia
– Canada — Alberta and Saskatchewan
| • | Softwood plywood |
– U.S. — Arkansas and Louisiana
We also own or lease 17 distribution centers in the U.S. where our major products and complementary building products are sold. During 2015, we decided to close our distribution centers in Baltimore, Pittsburgh, Chicago, and St. Paul.
Summary of Wood Products Capacities as of December 31, 2015
| CAPACITIES IN MILLIONS | ||||
| PRODUCTION CAPACITY | NUMBER OF FACILITIES | |||
| Structural lumber – board feet | 4,750 | 18 | ||
| Engineered solid section – cubic feet(1) | 43 | 6 | ||
| Oriented strand board – square feet (3/8”) | 3,035 | 6 | ||
| Softwood plywood – square feet (3/8”) | 460 | 2 | ||
| (1) Three engineered wood products facilities also produce engineered I-Joists to meet market demand. 2015 production of I-Joists was 185 million lineal feet. |
Production capacities listed represent annual production volume under normal operating conditions and producing a normal product mix for each individual facility. Production capacities do not include any capacity for facilities that were sold or permanently closed as of the end of 2015. We also operate a facility in Foster, Oregon that produces veneer, primarily for use in our engineered wood products facilities.
In 2014, we decided to reopen our Evergreen, Alabama engineered wood products facility. This facility was previously indefinitely closed.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 11
Five-Year Summary of Wood Products Production
| PRODUCTION IN MILLIONS | ||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||
| Structural lumber – board feet | 4,252 | 4,152 | 4,084 | 3,846 | 3,528 | |||||
| Engineered solid section – cubic feet(1) | 20.9 | 20.4 | 18.0 | 15.4 | 13.4 | |||||
| Engineered I-joists – lineal feet(1) | 185 | 182 | 168 | 147 | 122 | |||||
| Oriented strand board – square feet (3/8”) | 2,847 | 2,749 | 2,723 | 2,511 | 2,127 | |||||
| Softwood plywood – square feet (3/8”)(2) | 248 | 252 | 241 | 214 | 197 | |||||
| (1) Weyerhaeuser engineered I-joist facilities also may produce engineered solid section. (2) All Weyerhaeuser plywood facilities also produce veneer. |
HOW MUCH WE SELL
Revenues of our Wood Products segment come from sales to wood products dealers, do-it-yourself retailers, builders and industrial users. Wood Products net sales were $3.9 billion in 2015 and $4 billion 2014.
Five-Year Summary of Net Sales for Wood Products
| NET SALES IN MILLIONS OF DOLLARS | |||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | |||||||||||
| Structural lumber | $ | 1,741 | $ | 1,901 | $ | 1,873 | $ | 1,400 | $ | 1,087 | |||||
| Engineered solid section | 428 | 402 | 353 | 279 | 235 | ||||||||||
| Engineered I-joists | 284 | 277 | 247 | 190 | 161 | ||||||||||
| Oriented strand board | 595 | 610 | 809 | 612 | 354 | ||||||||||
| Softwood plywood | 129 | 143 | 144 | 115 | 66 | ||||||||||
| Other products produced | 189 | 176 | 171 | 167 | 142 | ||||||||||
| Complementary building products | 506 | 461 | 412 | 295 | 231 | ||||||||||
| Total | $ | 3,872 | $ | 3,970 | $ | 4,009 | $ | 3,058 | $ | 2,276 |
Five-Year Trend for Total Net Sales in Wood Products

Percentage of 2015 Net Sales Dollars in Wood Products

WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 12
Wood Products Volume
The volume of structural lumber, OSB, and engineered wood products sold in 2015 increased from 2014 due to increased demand.
Five-Year Summary of Sales Volume for Wood Products
| SALES VOLUMES IN MILLIONS | ||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||
| Structural lumber – board feet | 4,588 | 4,463 | 4,436 | 4,031 | 3,586 | |||||
| Engineered solid section – cubic feet | 21.3 | 20.0 | 18.2 | 15.4 | 12.3 | |||||
| Engineered I-joists – lineal feet | 188 | 184 | 177 | 152 | 128 | |||||
| Oriented strand board – square feet (3/8”) | 2,972 | 2,788 | 2,772 | 2,508 | 1,977 | |||||
| Softwood Plywood – square feet (3/8”) | 381 | 395 | 402 | 340 | 249 | |||||
| Sales volumes include sales of internally produced products and complementary building products sold primarily through our distribution centers. |
Wood Products Prices
Prices for commodity wood products — Structural lumber, OSB and Plywood — decreased in 2015 from 2014.
In general, the following factors influence prices for wood products:
| • | Demand for wood products used in residential and multi-family construction and the repair and remodel of existing homes affects prices. Residential construction is influenced by factors such as population growth and other demographics, the level of employment, consumer confidence, consumer income, availability of financing and interest rate levels, and the supply and pricing of existing homes on the market. Repair and remodel activity is affected by the size and age of existing housing inventory and access to home equity financing and other credit. |
| • | The availability of supply of commodity building products such as structural lumber, OSB and plywood affects prices. A number of factors can influence supply, including changes in production capacity and utilization rates, weather, raw material supply and availability of transportation. |
The North American housing market continued to show steady but slow improvement in 2015. Oversupply and weak Canadian currency resulted in generally lower lumber commodity pricing in 2015. The following graphs reflect product price trends for the past five years.
Five-Year Summary of Published Lumber Prices — $/MBF

Five-Year Summary of Published Oriented Strand Board Prices — $/MSF

WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 13
WHERE WE’RE HEADED
Our competitive strategies include:
| • | reduce controllable manufacturing costs through operational excellence and capital execution; |
| • | maintain a value-added product mix; |
| • | leverage our brand and reputation as the preferred provider of quality building products; and |
| • | pursue disciplined, profitable sales growth. |
CELLULOSE FIBERS
Our cellulose fibers segment is one of the world’s largest producers of absorbent fluff pulp used in products such as diapers. We also manufacture liquid packaging board and other pulp products. We have a 50 percent interest in North Pacific Paper Corporation (NORPAC) — a joint venture with Nippon Paper Industries that produces primarily high-brightness publication papers and newsprint.
WHAT WE DO
Our cellulose fibers segment:
| • | provides cellulose fibers for absorbent products in markets around the world; |
| • | works closely with our customers to develop unique or specialized applications; |
| • | manufactures liquid packaging board used primarily for the production of containers for liquid products; and |
| • | is largely energy self sufficient, with over 80 percent of its energy derived from black liquor produced at the mills and biomass. |
Cellulose Fibers Products
| PRODUCTS | HOW THEY’RE USED |
| Pulp • Fluff pulp (Southern softwood kraft fiber) • Softwood papergrade pulp • Specialty chemical cellulose pulp | • Used in sanitary disposable products that require bulk, softness and absorbency • Used in products that include printing and writing papers and tissue • Used in textiles, absorbent products, specialty packaging, specialty applications and proprietary high-bulking fibers |
| Liquid packaging board | Converted into containers to hold liquids such as milk, juice and tea |
| Other products • Slush pulp • Wet lap pulp | Used in the manufacture of paper products |
WHERE WE DO IT
Our cellulose fibers products are distributed globally through a direct sales network. Locations of our principal manufacturing facilities by major product group are:
| • | Pulp Manufacturing |
– U.S. — Georgia (2), Mississippi and North Carolina
– Canada — Alberta
| • | Pulp Converting |
– U.S. — Mississippi
– Poland
| • | Liquid packaging board |
– U.S. — Washington
Summary of Cellulose Fibers Capacities as of December 31, 2015
| CAPACITIES IN THOUSANDS | ||||
| PRODUCTION CAPACITY | NUMBER OF FACILITIES | |||
| Pulp – air-dry metric tons | 1,870 | 5 | ||
| Liquid packaging board – metric tons | 315 | 1 |
Production capacities listed represent annual production volume under normal operating conditions and producing a normal product mix for each individual facility.
Five-Year Summary of Cellulose Fibers Production
| PRODUCTION IN THOUSANDS | ||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||
| Pulp – air-dry metric tons | 1,822 | 1,859 | 1,815 | 1,773 | 1,769 | |||||
| Liquid packaging board – metric tons | 255 | 265 | 279 | 265 | 279 |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 14
HOW MUCH WE SELL
Revenues of our Cellulose Fibers segment come from sales to customers who use the products for further manufacturing or distribution and for direct use. Our net sales were $1.9 billion in 2015 and 2014.
Five-Year Summary of Net Sales for Cellulose Fibers
| NET SALES IN MILLIONS OF DOLLARS | |||||||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | |||||||||||
| Pulp | $ | 1,499 | $ | 1,559 | $ | 1,501 | $ | 1,433 | $ | 1,617 | |||||
| Liquid packaging board | 305 | 310 | 326 | 332 | 346 | ||||||||||
| Other products | 56 | 67 | 75 | 89 | 95 | ||||||||||
| Total | $ | 1,860 | $ | 1,936 | $ | 1,902 | $ | 1,854 | $ | 2,058 |
Five-Year Trend for Total Net Sales in Cellulose Fibers

Percentage of 2015 Net Sales Dollars in Cellulose Fibers

Pulp Volumes
Our sales volumes of cellulose fiber products were 1.8 million tons in 2015 and 2014.
Factors that affect sales volumes for cellulose fiber products include:
| • | growth of the world gross domestic product, |
| • | demand for absorbent hygiene products and paper and |
| • | relative strength of the U.S. dollar. |
Five-Year Summary of Sales Volume for Cellulose Fibers
| SALES VOLUMES IN THOUSANDS | ||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | ||||||
| Pulp – air-dry metric tons | 1,821 | 1,826 | 1,866 | 1,762 | 1,756 | |||||
| Liquid packaging board – metric tons | 255 | 249 | 277 | 262 | 269 |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 15
Pulp Prices
Our average pulp prices in 2015 decreased compared with 2014 due to a stronger US dollar and available supply.
Five-Year Summary of Published NBSK Pulp Prices — $/ADMT

WHERE WE’RE HEADED
Our competitive strategies include:
| • | profitably growing with long-term strategic customers; |
| • | developing enhanced products for existing and new markets; |
| • | continued execution of operational excellence initiatives such as manufacturing reliability and quality management systems; and |
| • | focusing capital investments on cost reduction, green energy opportunities and product quality. |
On November 8, 2015 Weyerhaeuser announced that the board authorized the exploration of strategic alternatives for its Cellulose Fibers business. At this time there can be no assurance that the board's evaluation process will result in any transaction or that any transaction, if pursued, will be consummated.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 16
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
| EXECUTIVE OFFICERS OF THE REGISTRANT |
Patricia M. Bedient, 62, has been executive vice president and chief financial officer since 2007. She was senior vice president, Finance and Strategic Planning from February 2006 to 2007. She served as vice president, Strategic Planning from 2003, when she joined the company, to 2006. Prior to joining the company, she was a partner with Arthur Andersen LLP (Independent Accountant) from 1987 to 2002 and served as the managing partner for the Seattle office and as the partner in charge of the firm’s forest products practice from 1999 to 2002. She is on the board of directors for Alaska Air Group and Oregon State University and also serves as Treasurer and a board member of Overlake Hospital Medical Center. She is a CPA and member of the American Institute of CPAs.
Adrian M. Blocker, 59, has been senior vice president, Wood Products since January 2015. Previously, he served as senior vice president, Lumber from August 2013 to December 2014. He joined the company in May 2013 as vice president, Lumber. Prior to joining the company, he served as CEO of the Wood Products Council. He has held numerous leadership positions in the industry focused on forest management, fiber procurement, consumer packaging, strategic planning, business development and manufacturing, including at West Fraser, International Paper and Champion International.
Rhonda D. Hunter, 53, has been senior vice president, Timberlands, since January 2014. Previously, she was vice president, Southern Timberlands from 2010 to 2014. She held a number of leadership positions in the Southern Timberlands organization and has experience in inventory and planning, regional timberlands management, environmental and work systems, finance and land acquisition. She joined Weyerhaeuser in 1987 as an accountant.
Denise M. Merle, 52, has been senior vice president, Human Resources and Investor Relations since August 2014. She served as senior vice president, Human Resources beginning February 2014. Prior to that, she was director, Finance and Human Resources for the Lumber business from 2013, director, Compliance & Enterprise Planning from 2009 to 2013, and director of Internal Audit from 2004 to 2009. She has held various roles in the company’s paper and packaging businesses, including finance, capital planning and analysis, and business development. She joined the company in 1981. She is a licensed CPA in the state of Washington.
Doyle R. Simons, 52, has been president and chief executive officer since August 2013 and a director of the company since June 2012. He was appointed chief executive officer-elect and an executive officer of the company in June 2013. Prior to joining the company, he served as chairman and chief executive officer of Temple-Inland, Inc. from 2008 until February 2012 when it was acquired by International Paper Company. He held various management positions with Temple-Inland, including executive vice president from 2005 through 2007 and chief administrative officer from 2003 to 2005. Prior to joining Temple-Inland in 1992, he practiced real estate and banking law with Hutcheson and Grundy, L.L.P. He also serves on the Board of Fiserv, Inc.
Catherine I. Slater, 52, has been senior vice president, Cellulose Fibers effective January 2015. She has served as senior vice president, Engineered Products and Distribution since August 2013 and vice president, OSB from 2011 to 2013. Prior to that role, she held a number of other leadership positions in the company’s Wood Products business, including vice president for both engineered wood products manufacturing and veneer technologies. Before joining the Wood Products team, she held positions in Cellulose Fibers business, including leadership roles at Flint River and Port Wentworth pulp mills, and leadership oversight for the company’s operations in Alberta, Canada, which included pulp, timberlands, OSB, lumber, and engineered wood products. Prior to joining the company in 1992, she held several leadership roles at Procter and Gamble.
Devin W. Stockfish, 42, has been senior vice president, general counsel and corporate secretary since July 2014. He leads the company's Law & Corporate Affairs department, with responsibility for global Legal, Compliance, Government Affairs, Real Estate Services, Land Title, and Environmental, Health and Safety functions. He joined the company in March 2013 as corporate secretary and assistant general counsel. Before joining the company, he was vice president & associate general counsel at Univar Inc. where he focused on mergers and acquisitions, corporate governance and securities law. Previously, he was an attorney in the law department at Starbucks Corporation and practiced corporate law at K&L Gates LLP. Before he began practicing law, Mr. Stockfish was an engineer with the Boeing Company.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 17
| NATURAL RESOURCE AND ENVIRONMENTAL MATTERS |
We are subject to a multitude of laws and regulations in the operation of our businesses. We also participate in voluntary certification of our timberlands to assure that we sustain their values including the protection of wildlife and water quality. Changes in law and regulation, or certification standards, can significantly affect our business.
REGULATIONS AFFECTING FORESTRY PRACTICES
In the United States, regulations established by federal, state and local government agencies to protect water quality and wetlands could affect future harvests and forest management practices on some of our timberlands. Forest practice laws and regulations that affect present or future harvest and forest management activities in certain states include:
| • | limits on the size of clearcuts, |
| • | requirements that some timber be left unharvested to protect water quality and fish and wildlife habitat, |
| • | regulations regarding construction and maintenance of forest roads, |
| • | rules requiring reforestation following timber harvest, and |
| • | various related permit programs. |
Each state in which we own timberlands has developed best management practices to reduce the effects of forest practices on water quality and aquatic habitats. Additional and more stringent regulations may be adopted by various state and local governments to achieve water-quality standards under the federal Clean Water Act, protect fish and wildlife habitats, or achieve other public policy objectives.
In Canada, our forest operations are carried out on public timberlands under forest licenses with the provinces. All forest operations are subject to:
| • | forest practices and environmental regulations, and |
| • | license requirements established by contract between us and the relevant province designed to: |
- protect environmental values, and
- encourage other stewardship values.
In Canada, 21 member companies of the Forest Products Association of Canada (FPAC), including Weyerhaeuser’s Canadian subsidiary, announced in May 2010 the signing of a Canadian Boreal Forest Agreement (CBFA) with nine environmental organizations. The CBFA applies to approximately 72 million hectares of public forests licensed to FPAC members and, when fully implemented, is expected to lead to the conservation of significant areas of Canada’s boreal forest and protection of boreal species at risk, in particular woodland caribou. CBFA signatories continue to work on management plans with provincial governments, and seek the participation of aboriginal and local communities in advancing the goals of the CBFA. Progress under the CBFA is measured and reported on by an independent auditor.
ENDANGERED SPECIES PROTECTIONS
In the United States, a number of fish and wildlife species that inhabit geographic areas near or within our timberlands have been listed as threatened or endangered under the federal Endangered Species Act (ESA) or similar state laws, such as:
| • | the northern spotted owl, the marbled murrelet, a number of salmon species, bull trout and steelhead trout in the Pacific Northwest, |
| • | several freshwater mussel and sturgeon species, and |
| • | the red-cockaded woodpecker, gopher tortoise, gopher frog, American burying beetle and Northern long-eared bat in the South or Southeast. |
Additional species or populations may be listed as threatened or endangered as a result of pending or future citizen petitions or petitions initiated by federal or state agencies. In addition, significant citizen litigation seeks to compel the federal agencies to designate "critical habitat" for ESA-listed species, and many cases have resulted in settlements under which designations will be implemented over time. Such designations may adversely affect some management activities and options. Restrictions on timber harvests can result from:
| • | federal and state requirements to protect habitat for threatened and endangered species, |
| • | regulatory actions by federal or state agencies to protect these species and their habitat, and |
| • | citizen suits under the ESA. |
Such actions could increase our operating costs and affect timber supply and prices in general. To date, we do not believe that these measures have had, and we do not believe that in 2016 they will have, a significant effect on our harvesting operations. We anticipate that likely future actions will not disproportionately affect Weyerhaeuser as compared with comparable operations of U.S. competitors.
In Canada:
| • | The federal Species at Risk Act (SARA) requires protective measures for species identified as being at risk and for critical habitat, pursuant to SARA, Environment Canada continues to identify and assess species deemed to be at risk and their critical habitat, and |
| • | in October 2012, the Canadian Minister of the Environment released a strategy for the recovery of the boreal population of woodland caribou under the SARA. The population and distribution objectives for boreal caribou across Canada are to (1) maintain the current status of existing, self-sustaining local caribou populations and (2) stabilize and achieve self-sustaining status for non-self-sustaining local caribou populations. Critical habitat for boreal caribou is identified for all boreal caribou ranges, except for northern Saskatchewan’s Boreal Shield range (SK1) where additional information is required for that population. Species assessment and recovery plans are developed in consultation with aboriginal communities and stakeholders. |
The identification and protection of habitat and the implementation of range plans and land use action plans may, over time, result in additional restrictions on timber harvests and other forest management practices that could increase operating costs for operators of timberlands in Canada. To date, we do not believe that these Canadian measures have had, and we do not believe that in 2016 they will have, a significant effect on our harvesting operations. We anticipate that likely future measures will not disproportionately affect Weyerhaeuser as compared with similar operations of Canadian competitors.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 18
FOREST CERTIFICATION STANDARDS
We operate in North America under the Sustainable Forestry Initiative (SFI®). This is a certification standard designed to supplement government regulatory programs with voluntary landowner initiatives to further protect certain public resources and values. SFI® is an independent standard, overseen by a governing board consisting of:
| • | conservation organizations, |
| • | academia, |
| • | the forest industry, and |
| • | large and small forest landowners. |
Ongoing compliance with SFI® may result in some increases in our operating costs and curtailment of our timber harvests in some areas. There also is competition from other private certification systems, primarily the Forest Stewardship Council (FSC), coupled with efforts by supporters to further those systems by persuading customers of forest products to require products certified to their preferred system. Certain features of the FSC system could impose additional operating costs on timberland management. Because of the considerable variation in FSC standards, and variability in how those standards are interpreted and applied, if sufficient marketplace demand develops for products made from raw materials sourced from other than SFI-certified forests, we could incur substantial additional costs for operations and be required to reduce harvest levels.
WHAT THESE REGULATIONS AND CERTIFICATION PROGRAMS MEAN TO US
The regulatory and nonregulatory forest management programs described above have:
| • | increased our operating costs, |
| • | resulted in changes in the value of timber and logs from our timberlands, |
| • | contributed to increases in the prices paid for wood products and wood chips during periods of high demand, |
| • | sometimes made it more difficult for us to respond to rapid changes in markets, extreme weather or other unexpected circumstances, and |
| • | potentially encouraged further reductions in the use of, or substitution of other products for, lumber, oriented strand board, and plywood. |
We believe that these kinds of programs have not had, and in 2016 will not have, a significant effect on our total harvest of timber in the United States or Canada. However, these kinds of programs may have such an effect in the future. We expect we will not be disproportionately affected by these programs as compared with typical owners of comparable timberlands. We also expect that these programs will not significantly disrupt our planned operations over large areas or for extended periods.
CANADIAN ABORIGINAL RIGHTS
Many of the Canadian timberlands are subject to the constitutionally protected treaty or common-law rights of aboriginal peoples of Canada. Most of British Columbia (B.C.) is not covered by treaties, and as a result the claims of B.C.’s aboriginal peoples relating to forest resources have been largely unresolved. On June 26, 2014 the Supreme Court of Canada ruled that the Tsilhqot’in Nation holds aboriginal title to approximately 1,900 square kilometers in B.C. This was the first time that the court has declared title to exist based on historical occupation by aboriginal peoples. Many aboriginal groups continue to be engaged in treaty discussions with the governments of B.C., other provinces and Canada.
Final or interim resolution of claims brought by aboriginal groups can be expected to result in:
| • | additional restrictions on the sale or harvest of timber, |
| • | potential increase in operating costs, and |
| • | impact to timber supply and prices in Canada. |
We believe that such claims will not have a significant effect on our total harvest of timber or production of forest products in 2016, although they may have such an effect in the future. In 2008, FPAC, of which we are a member, signed a Memorandum of Understanding with the Assembly of First Nations, under which the parties agree to work together to strengthen Canada’s forest sector through economic-development initiatives and business investments, strong environmental stewardship and the creation of skill-development opportunities particularly targeted to aboriginal youth.
POLLUTION-CONTROL REGULATIONS
Our operations are subject to various laws and regulations, including:
| • | federal, |
| • | state, |
| • | provincial, and |
| • | local pollution controls. |
These laws and regulations, as well as market demands, impose controls with regard to:
| • | air, water and land, |
| • | solid and hazardous waste management, |
| • | waste disposal, |
| • | remediation of contaminated sites, and |
| • | the chemical content of some of our products. |
Compliance with these laws, regulations and demands usually involves capital expenditures as well as additional operating costs. We cannot easily quantify the future amounts of capital expenditures we might have to make to comply with these laws, regulations and demands or the effects on our operating costs because in some instances compliance standards have not been developed or have not become final or definitive. In addition, it is difficult to isolate the environmental component of most manufacturing capital projects.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 19
Our capital projects typically are designed to:
| • | enhance safety, |
| • | extend the life of a facility, |
| • | increase capacity, |
| • | increase efficiency, |
| • | facilitate raw material changes and handling requirements, |
| • | increase the economic value of assets or products, and |
| • | comply with regulatory standards. |
We had capital expenditures of $23 million relating primarily to environmental compliance in 2015. Based on our understanding of current regulatory requirements in the U.S. and Canada, we expect no material capital expenditures relating primarily to environmental compliance in 2016.
ENVIRONMENTAL CLEANUP
We are involved in the environmental investigation or remediation of numerous sites. Of these sites:
| • | we may have the sole obligation to remediate, |
| • | we may share that obligation with one or more parties, |
| • | several parties may have joint and several obligations to remediate, or |
| • | we may have been named as a potentially responsible party for sites designated as U.S. Superfund sites. |
Our liability with respect to these various sites ranges from insignificant to substantial. The amount of liability depends on:
| • | the quantity, toxicity and nature of materials at the site, and |
| • | the number and economic viability of the other responsible parties. |
We spent approximately $7 million in 2015 and expect to spend approximately $7 million in 2016 on environmental remediation of these sites.
It is our policy to accrue for environmental-remediation costs when we:
| • | determine it is probable that such an obligation exists, and |
| • | can reasonably estimate the amount of the obligation. |
We currently believe it is reasonably possible that our costs to remediate all the identified sites may exceed our current accruals of $37 million. The excess amounts required may be insignificant or could range, in the aggregate, up to $116 million over several years. This estimate of the upper end of the range of reasonably possible additional costs is much less certain than the estimates we currently are using to determine how much to accrue. The estimate of the upper range also uses assumptions less favorable to us among the range of reasonably possible outcomes.
REGULATION OF AIR EMISSIONS IN THE U.S.
The United States Environmental Protection Agency (EPA) has promulgated regulations for air emissions from:
| • | pulp and paper manufacturing facilities, |
| • | wood products facilities, and |
| • | industrial boilers. |
These regulations cover:
| • | hazardous air pollutants that require use of maximum achievable control technology (MACT); and |
| • | controls for pollutants that contribute to smog, haze and more recently, greenhouse gases. |
Between 2011 and 2015 EPA issued three related portions of new MACT standards for industrial boilers and process heaters. EPA had completed a technology and residual risk review for MACT standards applicable to pulping and bleaching operations at pulp and paper manufacturing facilities in 2012 and in 2014 had issued a revised New Source Performance Standard for kraft pulp mills. These latter two rules apply on a project specific basis when certain thresholds are exceeded; as a result, we cannot predict whether or when those rules may have a material impact on future projects. Regarding other recent final actions by the EPA, we do not expect any material expenditures in 2016 to comply with MACT standards.
The EPA must still promulgate:
| • | technology and residual risk review standards for additional operations at pulp and paper manufacturing facilities and |
| • | supplemental MACT standards for plywood, lumber and composite wood products facilities. |
We cannot currently quantify the amount of capital we will need in the future to comply with new regulations being developed by the EPA because final rules have not been promulgated.
In 2010 EPA issued a final greenhouse gas rule limiting the growth of emissions from new projects meeting certain thresholds. On June 23, 2014, the US Supreme Court issued a decision that removed potential applicability of the underlying 2010 regulations based solely on greenhouse gas emissions and limited application of the rule’s technology requirements to larger emission sources as a result of new emissions from non-greenhouse gas pollutants. As a result of this Supreme Court ruling, EPA is expected to issue new regulations to set thresholds for when the greenhouse gas technology requirements apply if the non-greenhouse gas emissions trigger the rule in the first instance. The impact of the Supreme Court ruling is to end the potential applicability of the technology requirements for our smaller manufacturing operations and limit the applicability for our other operations.
In 2015 EPA issued an extensive regulatory program for new and existing electric utility generating units to scale back emissions of greenhouse gas carbon dioxide (CO2) arising from fossil fuel use to generate electricity. EPA also proposed additional regulations related to how states and federal agencies may implement the requirements finalized in 2015. This regulatory program potentially will have indirect impacts on our operations, such as from rising purchased electricity prices or from mandated energy demand reductions that could apply to our mills and other facilities that we operate. We are evaluating the regulations and additional proposals but are not able to predict whether the regulations, when complete and implemented, will have a material impact on our operations.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 20
We use significant biomass for energy production at our mills. EPA is currently working on rules regarding regulation of biomass emissions.
The impact of these greenhouse gas and biomass rules, as well as recent court decisions, on our operations remains uncertain.
To address concerns about greenhouse gases as a pollutant, we:
| • | closely monitor legislative, regulatory and scientific developments pertaining to climate change; |
| • | adopted in 2006, as part of the Company's sustainability program, a goal of reducing greenhouse gas emissions by 40 percent by 2020 compared with our emissions in 2000, assuming a comparable portfolio and regulations; |
| • | determined to achieve this goal by increasing energy efficiency and using more greenhouse gas-neutral, biomass fuels instead of fossil fuels; and |
| • | reduced greenhouse gas emissions by approximately 25 percent considering changes in the asset portfolio according to 2014 data, compared to our 2000 baseline. |
Additional factors that could affect greenhouse gas emissions in the future include:
| • | policy proposals by federal or state governments regarding regulation of greenhouse gas emissions, |
| • | Congressional legislation regulating greenhouse gas emissions within the next several years and |
| • | establishment of a multistate or federal greenhouse gas emissions reduction trading systems with potentially significant implications for all U.S. businesses. |
We believe these developments have not had, and in 2016 will not have, a significant effect on our operations. Although these measures could have a material adverse effect on our operations in the future, we expect that we will not be disproportionately affected by these measures as compared with owners of comparable operations. We maintain an active forestry research program to track and understand any potential effect from actual climate change related parameters that could affect the forests we own and manage and do not anticipate any disruptions to our planned operations.
REGULATION OF AIR EMISSIONS IN CANADA
In addition to existing provincial air quality regulations, the Canadian federal government has proposed an air quality management system (AQMS) as a comprehensive national approach for improving air quality in Canada. The federal proposed AQMS includes:
| • | ambient air quality standards for outdoor air quality management across the country, |
| • | a framework for air zone air management within provinces and territories that targets specific sources of air emissions, |
| • | regional airsheds that facilitate coordinated action across borders, |
| • | industrial sector based emission requirements that set a national base level of performance for major industries in Canada, and |
| • | improved intergovernmental collaboration to reduce emissions from the transportation sector. |
Environment Canada is developing a “Greenhouse Gas Emission Framework” that is expected to be proposed in 2016 with implementation in 2020. The framework will put in place a national, sector-based greenhouse gas reduction program applicable to a number of industries, including pulp and paper manufacturing.
All Canadian provincial governments:
| • | have greenhouse gas reporting requirements, |
| • | are working on reduction strategies, and |
| • | together with the Canadian federal government, are considering new or revised emission standards. |
In addition, British Columbia has adopted a carbon tax and Alberta has a mandatory GHG emission reduction regulation. Our Grande Prairie, Alberta cellulose fiber mill generates and sells carbon credits.
We believe these measures have not had, and in 2016 will not have, a significant effect on our operations. Although these measures could have a material adverse effect on our operations in the future, we expect that we will not be disproportionately affected by these measures as compared with owners of comparable operations. We also expect that these measures will not significantly disrupt our planned operations.
REGULATION OF AIR EMISSIONS IN POLAND AND URUGUAY
The European Union’s “Clean Air Programme” includes new air quality objectives that Poland and other European Union countries will implement through 2030. Some provinces in Uruguay have established air quality monitoring networks and ambient air objectives have been proposed for the region where our Los Piques mill is located.
We believe these measures have not had, and in 2016 will not have, a significant effect on our operations. Although these measures could have a material adverse effect on our operations in the future, we expect that we will not be disproportionately affected by these measures as compared with owners of comparable operations. We also expect that these measures will not significantly disrupt our planned operations.
REGULATION OF WATER
In the U.S., as a result of litigation under the federal Clean Water Act, additional federal or state permits are now required in some states for the application of pesticides, including herbicides, on timberlands. Those permits have entailed additional costs. In addition, there are continuing regulatory developments and continuing litigation in the federal courts that may result in permit requirements for pollution discharges from forest roads and other drainage features on timberland, which would entail additional costs for forest landowners including Weyerhaeuser. Finally, federal regulatory agencies adopted rules in 2015 that potentially expand the definition of waters subject to federal Clean Water Act jurisdiction, which could increase the scope and number of permits required for forestry-related activities and entail additional costs for Weyerhaeuser and other forest landowners in the U.S. Those rules have been challenged in federal court by multiple parties and states and an injunction has been entered that prevents them from going into effect. We are not able to predict the ultimate resolution of these pending legal actions.
In August 2014 EPA issued a final regulation on thermal cooling water intakes for the protection of aquatic resources. The final rule is not expected to have a material impact although the technology requirements to protect aquatic resources outlined in the rule may be applied on a case-by-case basis when water permits are renewed.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 21
In 2015, Washington State Department of Ecology (WA DOE) and the regional federal EPA proposed rules to update the Human Health Water Quality Criteria for the protection of human health. It is unclear what effect, if any, the proposed rules will have on our manufacturing operations in Washington State.
In addition:
| • | In 2013, amendments to the Canadian Federal Fisheries Act came into force. These amendments change the focus from habitat protection to fisheries protection and increase penalties. We expect further changes to these regulations in 2016, but we cannot predict the scope or potential impact, if any, on our operations. |
| • | Uruguay's national policy for water includes regulation of river basin planning, management and water use permits. Wastewater discharge authorization is required for industry, including our Los Piques mill. |
| • | In response to an European Union Water Framework Directive, in 2015 Polish authorities announced their intention to develop a water management plan to reduce total nitrogen and phosphorous loads in municipal waste water by 75 percent. The plan could impact our Poland facility, although it is unclear what effect, if any, the water management plan may have on our operation in Poland until the plan is complete. |
We believe the above developments have not had, and in 2016 will not have, a significant effect on our operations. Although these measures could have a material adverse effect on our operations in the future, we expect that we will not be disproportionately affected by these measures as compared with owners of comparable operations. We also expect that these measures will not significantly disrupt our planned operations.
POTENTIAL CHANGES IN POLLUTION REGULATION
State governments continue to promulgate total maximum daily load (TMDL) requirements for pollutants in water bodies that do not meet state or EPA water quality standards. State TMDL requirements may:
| • | set limits on pollutants that may be discharged to a body of water; or |
| • | set additional requirements, such as best management practices for nonpoint sources, including timberland operations, to reduce the amounts of pollutants. |
It is not possible to estimate the capital expenditures that may be required for us to meet pollution allocations across the various proposed state TMDL programs until a specific TMDL is promulgated.
In Canada, various levels of government have been working to address water issues including use, quality and management. Recent areas of focus include water allocation, regional watershed protection, protection of drinking water, water pricing and a national water quality index.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 22
| FORWARD-LOOKING STATEMENTS |
This report contains statements concerning our future results and performance that are forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements:
| • | are based on various assumptions we make, and |
| • | may not be accurate because of risks and uncertainties surrounding the assumptions we make. |
These statements reflect our current views with respect to future events. Factors listed in this section, factors discussed under "Risk Factors" and "Management's Discussion and Analysis of Financial Condition and Results of Operations" in this report, and other factors not included, may cause our actual results to differ significantly from our forward-looking statements. There is no guarantee that any of the events anticipated by our forward-looking statements will occur. Or if any of the events occur, there is no guarantee what effect it will have on our operations, cash flows, or financial condition.
We undertake no obligation to update our forward-looking statements after the date of this report.
FORWARD-LOOKING TERMINOLOGY
Forward-looking statements can be identified by the fact that they do not relate strictly to historical or current facts. They often use words such as expects, may, should, will, believes, anticipates, estimates, projects, intends, plans, targets or approximately. They may use the positive or negative or a variation of those and similar words.
STATEMENTS
In this report we make forward-looking statements concerning our plans, strategies, intentions and expectations, including with respect to our strategic corporate initiatives; operational excellence initiatives, including costs and product development and production; estimated taxes and tax rates; future dividends; future restructuring charges; expected results of litigation and the sufficiency of litigation reserves; expected uses of cash, including share repurchases; expected capital expenditures; expected economic conditions, including markets, pricing and demand for our products; laws and regulations relevant to our businesses; and our expectations relating to pension contributions and benefit payments.
RISKS, UNCERTAINTIES AND ASSUMPTIONS
Major risks and uncertainties, and assumptions that we make, that affect our business and may cause actual results to differ from these forward-looking statements include, but are not limited to:
| • | the effect of general economic conditions, including employment rates, interest rate levels, housing starts, availability of financing for home mortgages and strength of the U.S. dollar; |
| • | market demand for our products, which is related to the strength of the various U.S. business segments and U.S. and international economic conditions; |
| • | performance of our manufacturing operations, including maintenance requirements; |
| • | potential disruptions in our manufacturing operations; |
| • | level of competition from domestic and foreign producers; |
| • | our ability to successfully realize the expected benefits from the merger with Plum Creek; |
| • | the results of our strategic alternatives review of the Cellulose Fibers business; |
| • | the successful execution of our internal plans and strategic initiatives, including restructurings and cost reduction initiatives; |
| • | raw material availability and prices; |
| • | the effect of weather; |
| • | the risk of loss from fires, floods, windstorms, hurricanes, pest infestations and other natural disasters; |
| • | energy prices; |
| • | transportation and labor availability and costs; |
| • | federal tax policies; |
| • | the effect of forestry, land use, environmental and other governmental regulations; |
| • | legal proceedings; |
| • | performance of pension fund investments and related derivatives; |
| • | the effect of timing of retirements and changes in the market price of our common stock on charges for share-based compensation; |
| • | changes in accounting principles; and |
| • | other factors described under Risk Factors. |
EXPORTING ISSUES
We are a large exporter. Our business is affected by:
| • | economic activity in Europe and Asia, especially Japan and China; |
| • | currency exchange rates, particularly the relative value of the U.S. dollar to the euro and the Canadian dollar, and the relative value of the euro to the yen; and |
| • | restrictions on international trade, tariffs imposed on imports and the availability and cost of shipping and transportation. |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 23
Item 1A. RISK FACTORS
RISK FACTORS
We are subject to various risks and events that could adversely affect our business, our financial condition, our results of operations, our cash flows and the price of our common stock.
You should consider the following risk factors, in addition to the information presented elsewhere in this report, particularly in “Forward-Looking Statements” and "Management's Discussion and Analysis of Financial Condition and Results of Operations" as well as in the filings we make from time to time with the SEC, in evaluating us, our business and an investment in our securities.
The risks discussed below are not the only risks we face. Additional risks not currently known to us or that we currently deem immaterial also may adversely affect our business.
| RISKS RELATED TO OUR INDUSTRIES AND BUSINESS |
MACROECONOMIC CONDITIONS
The industries in which we operate are sensitive to macroeconomic conditions and consequently are highly cyclical.
The overall levels of demand for the products we manufacture and distribute reflect fluctuations in levels of end-user demand, which consequently impact our sales and profitability. End-user demand depends in part on general macroeconomic conditions, both in the U.S. and globally, as well as on local economic conditions. Current economic conditions in the United States reflect growth at or below historical trends and general business uncertainty. Global economic conditions reflect issues such as inflation and slowing growth in emerging countries. The construction and homebuilding industries continue to slowly recover from the severe downturn caused by the overall collapse of credit markets and recession of 2009. However, construction activity remains below pre-recession and trend levels. Our Wood Products segment is highly dependent on the strength of the homebuilding industry. The decline in home construction activity due to the recession resulted in depressed prices of and reduced demand for wood products and building materials. This resulted in lower prices and demand for logs and reduced harvests in our Timberlands segment. The length and magnitude of industry cycles vary over time and by product, but generally reflect changes in macroeconomic conditions and levels of industry capacity. Those conditions have improved since the recession, but if macroeconomic conditions do not continue to improve we could experience lower sales volumes and smaller margins.
COMMODITY PRODUCTS
Many of our products are commodities that are widely available from other producers.
Because commodity products have few distinguishing properties from producer to producer, competition for these products is based primarily on price, which is determined by supply relative to demand and competition from substitute products. In addition, prices for our products are affected by many other factors outside of our control. As a result, we have little influence over the timing and extent of price changes, which often are volatile. Our profitability with respect to these products depends, in part, on managing our costs, particularly raw material and energy costs, which represent significant components of our operating costs and can fluctuate based upon factors beyond our control. Both sales and profitability of our products are subject to volatility due to market forces beyond our control.
INDUSTRY SUPPLY OF LOGS, WOOD PRODUCTS AND PULP
Excess supply of products may adversely affect prices and margins.
Oversupply of products may result from producers introducing new capacity for manufactured products or increasing harvest levels in response to favorable short-term pricing trends. Industry supplies of pulp are also influenced by global production capacity, which has grown in recent years and is expected to continue to grow. Continuation of these factors could adversely affect our sales volumes and margins.
HOMEBUILDING MARKET AND ECONOMIC RISKS
High unemployment, low demand and low levels of consumer confidence can adversely affect our business and results of operations.
Our business is dependent upon the health of the U.S. housing market. Demand for homes is sensitive to changes in economic conditions such as the level of employment, consumer confidence, consumer income, the availability of financing and interest rate levels. The legacy of the housing bubble, its collapse and ensuing credit crisis was tightened credit requirements and a reduced number of mortgage loans available for financing home purchases. Although credit conditions have eased, they remain more restrictive than prior to the housing bubble. Demand for new homes also has been adversely affected by factors such as unemployment and lower job participation, limited wage growth and weak consumer confidence. Additionally, rising student loan debt among younger adults is limiting access to mortgage financing and home ownership. Foreclosure rates and distress sales of houses, have fallen significantly and are less of an impact compared to the years immediately following the housing collapse.
Homebuyers’ ability to qualify for and obtain affordable mortgages could be affected by changes in government sponsored entities and private mortgage insurance companies supporting the mortgage market.
The federal government has historically had a significant role in supporting mortgage lending through its sponsorship of Fannie Mae and Freddie Mac. As a result of turbulence in credit markets and the mortgage finance industry in the last few years, the effect of the federal government’s conservatorship of these government sponsored entities on the short-term and long-term demand for new housing remains unclear. The liquidity provided to the mortgage industry by Fannie Mae and Freddie Mac, both of which purchase home mortgages and mortgage-backed securities originated by mortgage lenders, is critical to the housing market. There have been significant concerns about the future purpose of Fannie Mae and Freddie Mac and a number of proposals to curtail their activities over time are under review. Limitations or restrictions on the availability of financing by these entities could adversely affect interest rates and the availability of mortgage financing, which could reduce demand for housing and adversely affect demand for our products.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 24
Changes in mortgage interest expense and real estate tax regulations could harm our future sales and earnings.
Significant costs of homeownership include mortgage interest expense and real estate taxes, both of which are generally deductible for an individual’s federal and, in some cases, state income taxes. Any changes to income tax laws by the federal government or a state government to eliminate or substantially reduce these income tax deductions, as has been considered from time to time, would increase the after-tax cost of owning a home. Increases in real estate taxes by local governmental authorities would also increase the cost of homeownership. Any such increases to the cost of homeownership could adversely affect the demand for our products.
CAPITAL MARKETS
Deterioration in economic conditions and the credit markets could adversely affect our access to capital.
Upset financial or credit market conditions can impair the company’s ability to borrow money or otherwise access credit markets on terms acceptable to us, which may, among other impacts, reduce our ability to take advantage of growth and expansion opportunities. Similarly, our customers may be unable to borrow money to fund their operations. Similarly, deteriorating or volatile market conditions could have an adverse effect on our customers and suppliers and their ability to purchase our products or sell products to us.
CHANGES IN CREDIT RATINGS
Changes in credit ratings issued by nationally recognized rating organizations could adversely affect our cost of financing and have an adverse effect on the market price of our securities.
Credit rating agencies rate our debt securities on factors that include our operating results, actions that we take, their view of the general outlook for our industry and their view of the general outlook for the economy. Actions taken by the rating agencies can include maintaining, upgrading or downgrading the current rating or placing the company on a watch list for possible future downgrading. Downgrading the credit rating of our debt securities or placing us on a watch list for possible future downgrading could limit our access to the credit markets, increase our cost of financing, and have an adverse effect on the market price of our securities.
SUBSTITUTION
Some of our products are vulnerable to declines in demand due to competing technologies or materials.
Our products may compete with nonfiber-based alternatives or with alternative products in certain market segments. For example, plastic, wood/plastic or composite materials may be used by builders as alternatives to the products produced by our Wood Products businesses such as lumber, veneer, plywood and oriented strand board. Changes in prices for oil, chemicals and wood-based fiber can change the competitive position of our products relative to available alternatives and could increase substitution of those products for our products. If use of these alternative products grows, demand for and pricing of our products could be adversely affected.
CHANGES IN PRODUCT MIX OR PRICING
Our results of operations and financial condition could be materially adversely affected by changes in product mix or pricing.
Our results may be adversely affected by a change in our product mix or pricing. If we are not successful in implementing previously announced or future price increases, or in our plans to increase sales of higher-priced, higher-value products, or if there are delays in acceptance of price increases or failure of customers to accept higher-priced products our results of operations and financial condition could be materially and adversely affected. Price discounting, if required to maintain our competitive position, could result in lower than anticipated price realizations.
INTENSE COMPETITION
We face intense competition in our markets, and the failure to compete effectively could have a material adverse effect on our business, financial condition and results of operations.
We compete with North American and, for many of our product lines, global producers, some of which may have greater financial resources and lower production costs than we do. The principal basis for competition for many of our products is selling price. Our ability to maintain satisfactory margins depends in large part on our ability to control our costs. Our industries also are particularly sensitive to other factors including innovation, design, quality and service, with varying emphasis on these factors depending on the product line. To the extent that one or more of our competitors become more successful with respect to any key competitive factor, our ability to attract and retain customers could be materially adversely affected. If we are unable to compete effectively, such failure could have a material adverse effect on our business, financial condition and results of operations.
Expiration of the Softwood Lumber Agreement creates uncertainty about competition from Canadian imports.
Historically, Canada has been a significant source of lumber for the U.S. market, particularly in the new home construction market. We produce lumber in our Canadian mills, but the bulk of our production is in the U.S. The Softwood Lumber Agreement (SLA) between Canada and the U.S., originally signed in October 2006, expired in October 2015. The 2006 SLA required Canadian softwood lumber facilities, including our mills, to pay an export tax when the price of lumber is at or below a threshold price. We are not able to predict when or if a new agreement will be reached or, if reached, what the terms of the agreement would be. We could experience downward pressure on timber and lumber prices caused by Canadian lumber imports.
Another emerging form of competition is between brands of sustainably produced products; customer demand for certain brands could reduce competition among buyers for our products or cause other adverse effects.
In North America, our forests are third party-certified to the Sustainable Forestry Initiative (SFI®) standard. Some of our customers have expressed a preference in certain of our product lines for products made from raw materials sourced from forests certified to different standards, including standards of the Forest Stewardship Council (FSC). If and to the extent that preference for a standard other than SFI® becomes a customer requirement, there may be reduced demand and lower prices for our products relative to competitors who can supply products sourced from forests certified to competing certification standards. If we seek to comply with such other standards, we could incur materially increased costs for our operations or be required to modify our operations, such as reducing harvest levels. FSC, in particular, employs standards that are geographically variable and could cause a material reduction in the harvest levels of some of our timberlands, most notably in the Pacific Northwest.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 25
MATERIAL DISRUPTION OF MANUFACTURING
A material disruption at one of our manufacturing facilities could prevent us from meeting customer demand, reduce our sales or negatively affect our results of operation and financial condition.
Any of our manufacturing facilities, or any of our machines within an otherwise operational facility, could cease operations unexpectedly due to a number of events, including:
| • | unscheduled maintenance outages, |
| • | prolonged power failures, |
| • | equipment failure, |
| • | a chemical spill or release, |
| • | explosion of a boiler, |
| • | fires, floods, windstorms, earthquakes, hurricanes or other severe weather conditions or catastrophes, affecting the production of goods or the supply of raw materials (including fiber), |
| • | the effect of drought or reduced rainfall on water supply, |
| • | labor difficulties, |
| • | disruptions in transportation infrastructure, including roads, bridges, rail, tunnels, shipping and port facilities, |
| • | terrorism or threats of terrorism, |
| • | governmental regulations, and |
| • | other operational problems. |
Any such downtime or facility damage could prevent us from meeting customer demand for our products or require us to make unplanned capital expenditures. If one of our facilities or machines were to incur significant downtime, our ability to meet our production targets and satisfy customer requirements could be impaired, resulting in lower sales and income. Although some risks are not insurable and some coverage is limited, we purchase insurance protecting our manufacturing facilities from fires, floods, windstorms, earthquakes, equipment failures and boiler explosions.
STRATEGIC INITIATIVES
Our business and financial results may be adversely impacted if we are unable to successfully execute on important strategic initiatives.
There can be no assurance that we will be able to successfully implement important strategic initiatives in accordance with our expectations, which may result in an adverse impact on our business and financial results. These strategic initiatives are designed to improve our results of operations and drive long-term shareholder value, and include, among others: maximizing cash flow through operational excellence; reducing costs to achieve industry-leading cost structure; and innovating in higher-margin products.
We may be unsuccessful in carrying out our acquisition strategy.
We intend to strategically pursue acquisitions of timberland properties when market conditions warrant. As with any investment, our acquisitions may not perform in accordance with our expectations. In addition, we anticipate financing such acquisitions through cash from operations, borrowings under our unsecured credit facilities, proceeds from equity or debt offerings or proceeds from asset dispositions, or any combination thereof. Our inability to finance future acquisitions on favorable terms could adversely affect our results of operations.
CAPITAL REQUIREMENTS
Our operations require substantial capital.
Our businesses require substantial capital for expansion and for repair or replacement of existing facilities or equipment. Although we maintain our production equipment with regular scheduled maintenance, key pieces of equipment may need to be repaired or replaced periodically. The costs of repairing or replacing such equipment and the associated downtime of the affected production line could have a material adverse effect on our financial condition, results of operations and cash flows.
While we believe our capital resources will be adequate to meet our current projected operating needs, capital expenditures and other cash requirements, if for any reason we are unable to provide for our operating needs, capital expenditures and other cash requirements on acceptable economic terms, we could experience a material adverse effect on our business, financial condition, results of operations and cash flows.
ENVIRONMENTAL LAWS AND REGULATIONS
We could incur substantial costs as a result of compliance with, violations of, or liabilities under applicable environmental laws and other laws and regulations.
We are subject to a wide range of general and industry-specific laws and regulations relating to the protection of the environment, including those governing:
| • | air emissions, |
| • | wastewater discharges, |
| • | harvesting and other silvicultural activities, |
| • | forestry operations and endangered species habitat protection, |
| • | surface water management, |
| • | the storage, management and disposal of hazardous substances and wastes, |
| • | the cleanup of contaminated sites, |
| • | landfill operation and closure obligations, |
| • | building codes, and |
| • | health and safety matters. |
We have incurred, and we expect to continue to incur, significant capital, operating and other expenditures complying with applicable environmental laws and regulations and as a result of remedial obligations. We also could incur substantial costs, such as civil or criminal fines,
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 26
sanctions and enforcement actions (including orders limiting our operations or requiring corrective measures, installation of pollution control equipment or other remedial actions), cleanup and closure costs, and third-party claims for property damage and personal injury as a result of violations of, or liabilities under, environmental laws and regulations.
As the owner and operator of real estate, we may be liable under environmental laws for cleanup, closure and other damages resulting from the presence and release of hazardous substances on or from our properties or operations. In addition, surface water management regulations may present liabilities and are subject to change. The amount and timing of environmental expenditures is difficult to predict, and in some cases, our liability may exceed forecasted amounts or the value of the property itself. The discovery of additional contamination or the imposition of additional cleanup obligations at our sites or third-party sites may result in significant additional costs. Any material liability we incur could adversely affect our financial condition or preclude us from making capital expenditures that otherwise would benefit our business.
We also anticipate public policy developments at the state, federal and international level regarding climate change and energy access, security and competitiveness. We expect these developments to address emission of carbon dioxide, renewable energy and fuel standards, and the monetization of carbon. Compliance with regulations that implement new public policy in these areas might require significant expenditures. These developments may also include mandated changes to energy use and building codes which could affect our homebuilding practices. Enactment of new environmental laws or regulations or changes in existing laws or regulations, or the interpretation of these laws or regulations, might require significant expenditures. We also anticipate public policy developments at the state, federal and international level regarding taxes and a number of other areas that could require significant expenditures.
Changes in global or regional climate conditions and governmental response to such changes at the international, U.S. federal and state levels may affect our operations or our planned or future growth activities.
There continue to be numerous international, U.S. federal and state-level initiatives and proposals to address domestic and global climate issues. Within the U.S. and Canada, some of these proposals would (and have in some Canadian provinces) regulate and/or tax the production of carbon dioxide and other “greenhouse gases” to facilitate the reduction of carbon compound emissions into the atmosphere and provide tax and other incentives to produce and use “cleaner” energy. Climate change impacts, if they occur, and governmental initiatives, laws and regulations to address potential climate concerns, could increase our costs and have a long-term adverse impact on our businesses and results of operations. Future legislation or regulatory activity in this area remains uncertain, and its impact on our operations is unclear at this time. However, it is possible that legislation or government mandates, standards or regulations intended to mitigate or reduce carbon compound or greenhouse gas emissions or other climate change impacts could adversely affect our operations. For example, such activities could limit harvest levels or result in significantly higher costs for energy and other raw materials. Because our manufacturing operations depend upon significant amounts of energy and raw materials, these initiatives could have an adverse impact on our results of operations and profitability.
CURRENCY EXCHANGE RATES
We will be affected by changes in currency exchange rates.
We have manufacturing operations in Canada, Poland and Uruguay. We are also a large exporter and compete with global producers of products very similar to ours. Therefore, we are affected by changes in the strength of the U.S. dollar, particularly relative to the Canadian dollar, euro and yen, and the strength of the euro relative to the yen. Changes in exchange rates could materially and adversely affect our sales volumes, margins and results of operations.
AVAILABILITY OF RAW MATERIALS AND ENERGY
Our business and operations could be materially adversely affected by changes in the cost or availability of raw materials and energy.
We rely heavily on certain raw materials (principally wood fiber and chemicals) and energy sources (principally natural gas, electricity, coal and fuel oil) in our manufacturing processes. Our ability to increase earnings has been, and will continue to be, affected by changes in the costs and availability of such raw materials and energy sources. We may not be able to fully offset the effects of higher raw material or energy costs through hedging arrangements, price increases, productivity improvements or cost-reduction programs.
PEOPLE
Our business is dependent upon attracting, retaining and developing key personnel.
We believe that our success depends, to a significant extent, upon our ability to attract, retain and develop key senior management and operations management personnel. Our failure to recruit, retain, and develop key personnel could adversely affect our financial condition or results of operations.
TRANSPORTATION
We depend on third parties for transportation services and increases in costs and disruptions in the availability of transportation could materially adversely affect our business and operations.
Our business depends on the transportation of a large number of products, both domestically and internationally. We rely primarily on third parties for transportation of the products we manufacture or distribute as well as delivery of our raw materials. A significant portion of the goods we manufacture and raw materials we use are transported by marine, rail and truck, each of which is highly regulated. In addition, each has historically been subject to periodic disruption due to labor issues.
If any of our third-party transportation providers were to fail to deliver the goods we manufacture or distribute in a timely manner, we may be unable to sell those products at full value, or at all. Similarly, if any of these providers were to fail to deliver raw materials to us in a timely manner, we may be unable to manufacture our products in response to customer demand. In addition, if any of these third parties were to cease operations or cease doing business with us, we may be unable to replace them at reasonable cost. Our third-party transportation providers are also subject to events outside of their control, such as disruption of transportation infrastructure due to labor issues or natural disasters.
Any failure of a third-party transportation provider to deliver raw materials or finished products in a timely manner could harm our reputation, negatively affect our customer relationships and have a material adverse effect on our financial condition and results of operation.
In addition, an increase in transportation rates or fuel surcharges could materially adversely affect our sales and profitability.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 27
REIT STATUS AND TAX IMPLICATIONS
If we fail to remain qualified as a REIT, our taxable income would be subject to tax at corporate rates and we would not be able to deduct dividends to shareholders.
In any taxable year in which we fail to qualify as a REIT, unless we are entitled to relief under the Internal Revenue Code:
| • | We would not be allowed to deduct dividends to shareholders in computing our taxable income. |
| • | We would be subject to federal and state income tax on our taxable income at applicable corporate rates. |
| • | We also would be disqualified from treatment as a REIT for the four taxable years following the year during which we lost qualification. |
Qualification as a REIT involves the application of highly technical and complex provisions of the Internal Revenue Code to our operations and the determination of various factual matters and circumstances not entirely within our control. There are only limited judicial or administrative interpretations of these provisions. Although we operate in a manner consistent with the REIT qualification rules, we cannot assure you that we are or will remain so qualified.
Certain of our business activities are subject to corporate-level income tax and potentially subject to prohibited transactions tax.
Under the Internal Revenue Code, REITs generally must engage in the ownership and management of income producing real estate. For the Company, this generally includes owning and managing a timberland portfolio for the production and sale of standing timber. Accordingly, the harvesting and sale of logs, the development or sale of certain timberlands and other real estate, the manufacture and sale of wood products and the manufacture and sale of pulp products are conducted through one or more of our wholly-owned taxable REIT subsidiaries (TRSs) because such activities could generate non-qualifying REIT income and could constitute “prohibited transactions.” Prohibited transactions are defined by the Internal Revenue Code generally to be sales or other dispositions of property to customers in the ordinary course of a trade or business. By conducting our business in this manner we believe that we satisfy the REIT requirements of the Internal Revenue Code and are not subject to the 100 percent tax that could be imposed if a REIT were to conduct a prohibited transaction. The net income of our TRSs is subject to corporate-level income tax.
The extent of our use of our TRS may affect the price of our common shares relative to the share price of other REITs.
We conduct a significant portion of our business activities through one or more TRSs. Our use of our TRSs enables us to engage in non-REIT qualifying business activities such as the sale of logs, production and sale of wood products and pulp products, and sale of HBU property. Our TRSs are subject to corporate-level tax. Therefore, we pay income taxes on the income generated by our TRSs. Under the Code, no more than 25 percent (20 percent after December 31, 2017) of the value of the gross assets of a REIT may be represented by securities of one or more TRS. This limitation may affect our ability to increase the size of our TRSs’ operations. Furthermore, our use of TRSs may cause the market to value our common shares differently than the shares of other REITs, which may not use TRSs as extensively as we use them.
We may be limited in our ability to fund distributions using cash generated through our taxable REIT subsidiaries.
The ability of the REIT to receive dividends from our TRS is limited by the rules with which we must comply to maintain our status as a REIT. In particular, at least 75 percent of gross income for each taxable year as a REIT must be derived from passive real estate sources including sales of our standing timber and other types of qualifying real estate income and no more than 25 percent of our gross income may consist of dividends from our TRS and other non-real estate income.
This limitation on our ability to receive dividends from our TRSs may affect our ability to fund cash distributions to our shareholders using cash flows from our TRSs. The net income of our TRSs is not required to be distributed, and income that is not distributed will not be subject to the REIT income distribution requirement.
Our cash dividends are not guaranteed and may fluctuate.
Generally, REITs are required to distribute 90 percent of their ordinary taxable income and 95 percent of their net capital gains income. Capital gains may be retained by the REIT, but would be subject to income taxes. If capital gains are retained rather than distributed, our shareholders would be notified and they would be deemed to have received a taxable distribution, with a refundable credit for any federal income tax paid by the REIT. Accordingly, we believe that we are not required to distribute material amounts of cash since substantially all of our taxable income is treated as capital gains income. Our board of directors, in its sole discretion, determines the amount of quarterly dividends to be provided to our shareholders based on consideration of a number of factors. These factors include, but are not limited to, our results of operations, cash flow and capital requirements, economic conditions, tax considerations, borrowing capacity and other factors, including debt covenant restrictions that may impose limitations on cash payments, future acquisitions and divestitures, harvest levels, changes in the price and demand for our products and general market demand for timberlands including those timberland properties that have higher and better uses. Consequently, our dividend levels may fluctuate.
Changes in tax laws or their interpretation could adversely affect our shareholders and our results of operations.
Federal and state tax laws are constantly under review by persons involved in the legislative process, the Internal Revenue Service, the United States Department of the Treasury, and state taxing authorities. Changes to tax laws could adversely affect our shareholders or increase our effective tax rates. We cannot predict with certainty whether, when, in what forms, or with what effective dates, the tax laws applicable to us or our shareholders may be changed.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 28
LEGAL PROCEEDINGS
We are a party to a number of legal proceedings, and adverse judgments in certain legal proceedings could have a material adverse effect on our financial condition.
The costs and other effects of pending litigation against us and related insurance recoveries cannot be determined with certainty. Although the disclosure in Note 15: Legal Proceedings, Commitments and Contingencies of Notes to Consolidated Financial Statements contains management’s current views of the effect such litigation will have on our financial results, there can be no assurance that the outcome of such proceedings will be as expected.
It is possible that there could be adverse judgments against us in some or all major litigation against us and that we could be required to take a charge and make cash payments for all or a portion of any damage award. Any such charge or cash payment could materially and adversely affect our results of operations or cash flows for the quarter or year in which we record or pay it.
IMPORT/EXPORT TAXES AND DUTIES
We may be required to pay significant taxes on our exported products or countervailing and anti-dumping duties on our imported products.
International trade disputes occur frequently and can be taken to an International Trade Court for resolution of unfair trade practices between countries. As an example, there have been many disputes and subsequent trade agreements regarding sales of softwood lumber between Canada and the United States. The Softwood Lumber Agreement (SLA) between Canada and the U.S., originally signed in October 2006, expired in October 2015. A new agreement has not been reached. The SLA required Canadian softwood lumber facilities, including our mills, to pay an export tax when the price of lumber is at or below a threshold price, which could be as high as 22.5 percent if a province exceeds its total allotted export share, as well as potentially impose additional countervailing antidumping duties. We could experience reduced revenues and margins in any business that is subject to such tariffs or to the terms of the settlements of such international disputes. To the extent such tariffs increase prices, they could also reduce the demand for our products. These tariffs or settlement terms could have a material adverse effect on our business, financial results and financial condition, including facility closures or impairments of assets. We cannot predict whether or when there will be a further extension of the SLA or a new agreement or, if any extension or new agreement is completed, its impact on our business.
DISTRIBUTION OF WRECO SHARES
We could incur substantial U.S. federal tax liability if the WRECO transaction were found not to qualify as a tax-free “reorganization” or the distribution of WRECO shares to Weyerhaeuser shareholders were found not to qualify as a tax-free distribution.
In 2014 we closed the divestiture of our home building business, Weyerhaeuser Real Estate Company (WRECO), via a "Reverse Morris Trust" transaction pursuant to which a wholly-owned subsidiary of TRI Pointe Homes, Inc. (TRI Pointe) merged with and into WRECO, with WRECO surviving the merger and becoming a wholly-owned subsidiary of TRI Pointe. The Reverse Morris Trust transaction was structured to qualify as a tax-free reorganization and the associated distribution of WRECO shares to Weyerhaeuser shareholders as a tax-free distribution. If the transaction were determined not to qualify as a tax-free reorganization, or if the distribution does not qualify as a tax-free distribution, then Weyerhaeuser or its subsidiaries or Weyerhaeuser shareholders may be required to pay substantial U.S. federal income taxes.
If the transaction were determined not to qualify as a tax-free reorganization or the distribution not to qualify as a tax-free distribution, or if Weyerhaeuser were required to indemnify TRI Pointe and WRECO, such taxes and indemnification obligations could be substantial and could materially and adversely affect the company’s liquidity, financial condition and results of operations.
OUR MERGER WITH PLUM CREEK TIMBER COMPANY, INC.
The merger may not be completed on the terms currently contemplated, or at all.
On November 6, 2015 Weyerhaeuser Company and Plum Creek Timber Company, Inc. (“Plum Creek”) entered into an Agreement and Plan of Merger (“Merger Agreement”) pursuant to which Plum Creek will merge with and into Weyerhaeuser Company with Weyerhaeuser continuing as the surviving corporation. If the merger is not completed, our businesses may be adversely affected and we may be subject to various risks without realizing any of the benefits of having the merger completed, including the following:
| • | We may be required, under certain circumstances, to pay a termination fee of $250 million. |
| • | We may be required to reimburse Plum Creek for all reasonable documented out-of-pocket fees and expenses incurred in connection with the Merger Agreement and the merger up to a maximum of $40 million. |
| • | We may experience negative reactions from the financial markets or from our customers, suppliers or employees. |
| • | We may be subject to litigation related to failure to complete the merger or to enforcement proceedings to perform our obligations under the Merger Agreement. |
A delay in completing the merger, which is subject to a number of conditions, some of which are outside our control, may reduce or eliminate the expected benefits from the merger.
The merger is subject to a number of conditions, some of which are beyond our control, that could prevent, delay or otherwise materially adversely affect its completion. We cannot predict whether and when the conditions will be satisfied. In addition, several putative class action lawsuits relating to the merger have been filed and additional lawsuits may be filed, which could delay completion of the merger. We intend to vigorously defend the litigation but we cannot predict the outcome. The requirement to obtain certain regulatory approvals could delay the completion of the merger for a significant period of time or prevent it from occurring. A delay in completing the merger could cause the combined company not to realize some or all of the synergies and other benefits that it expects to achieve if the merger is successfully completed within its expected time frame. The Merger Agreement contains certain restrictions on the conduct of our business. If the merger is delayed, these restrictions could adversely affect our ability to execute business strategies or pursue attractive business opportunities. In addition, a delay could cause management to focus on completion of the merger instead of on other opportunities that could be beneficial to the company.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 29
The merger will involve substantial costs, and the combined company may be unable to successfully integrate the businesses of the two companies and realize the anticipated benefits of the merger.
We have incurred and expect to continue to incur substantial costs and expenses relating directly to the merger, including fees and expenses payable to financial and other professional advisors, SEC filing fees, printing and mailing costs and other transaction-related costs, fees and expenses. We expect to incur substantial expenses in connection with the integration of the businesses, policies, procedures, operations, employees, technologies and systems of Plum Creek with those of Weyerhaeuser. There are a large number of systems that must be integrated, including management information, purchasing, accounting and finance, sales, billing, payroll and benefits, fixed asset and lease administration systems and regulatory compliance. Expenses related to this integration are by their nature difficult to estimate accurately. These expenses could, particularly in the near term, exceed the savings that we expect to achieve from the realization of economies of scale and cost savings and synergies related to the integration of the businesses. These integration expenses likely will result in significant charges against earnings following the completion of the merger, but the amount and timing of such charges are uncertain.
The merger involves the combination of two independently operated public companies. The merger will require management to devote significant attention and resources to integrating business practices and operations. The combined company may fail to realize some or all of the anticipated benefits of the merger if the integration process takes longer than expected or is more costly than expected.
Uncertainties associated with the merger may adversely affect our business and operations.
Uncertainties associated with the merger could cause customers, suppliers or other entities with whom we have a business relationship to delay or defer decisions, which could negatively impact our revenues, earnings and cash flows. In addition, customers or suppliers may elect to cease doing business with us or the combined company in anticipation of or following the merger, or seek to take advantage of potential uncertainty or disruption resulting from the merger to interfere with relationships with customers, suppliers or employees.
We are dependent on the valuable experience and industry knowledge of our officers and other employees to execute our business plans and successfully conduct operations. Our success after the merger will depend in part upon our ability to retain key personnel. Current and prospective employees may feel uncertain about their roles following the merger, which may materially adversely affect our ability to attract and retain key personnel.
The market price of our common stock may decline in the future as a result of the merger.
The market price of our common stock may decline in the future as a result of the merger for a number of reasons, including our inability to successfully integrate the two companies or our failure to achieve the perceived benefits of the merger, including financial results, as rapidly as or to the extent anticipated by financial or industry analysts. Failure to successfully integrate the two companies could negatively impact our revenues, earnings and cash flows, and could materially adversely affect our ability to pay dividends at historical levels, or at all.
The combined company may incur adverse tax consequences if either Weyerhaeuser or Plum Creek has failed or fails to qualify as a REIT for U.S. federal income tax purposes.
Each of Weyerhaeuser and Plum Creek has operated in a manner that it believes has allowed it to qualify as a REIT for U.S. federal income tax purposes under the Code. See “REIT Status and Tax Implications” above for a description of the REIT requirements and consequences of failing to maintain REIT status. We intend to operate in a manner that allows us to continue to qualify as a REIT after the merger. However, even if we have operated so as to retain our REIT status, if Plum Creek were to lose its REIT status for a taxable year before the merger or that includes the merger, we will face serious tax consequences that could substantially reduce cash available for distribution to our shareholders and significantly impair our ability to expand our business and raise capital. If the merger were determined not to qualify as a tax-free merger, we could incur substantial federal tax liability that could materially and adversely affect the company's liquidity, financial condition and results of operations.
TIMBERLAND SPECIFIC RISKS
Our ability to harvest and deliver timber may be subject to limitations which could adversely affect our results of operations.
Our primary assets are our timberlands. Weather conditions, timber growth cycles, access limitations, and availability of contract loggers and haulers, may restrict our ability to harvest our timberlands. Other factors that may restrict our timber harvest include damage to our standing timber by fire or by insect infestation, disease, prolonged drought, flooding, severe weather and other natural disasters. Changes in global climate conditions could intensify one or more of these factors. Although damage from such causes usually is localized and affects only a limited percentage of standing timber, there can be no assurance that any damage affecting our timberlands will in fact be limited. As is common in the forest products industry, we do not maintain insurance coverage for damage to our timberlands. Our revenues, net income and cash flow from operations are dependent to a significant extent on the pricing of our products and our continued ability to harvest timber at adequate levels. Therefore, if we were to be restricted from harvesting on a significant portion of our timberlands for a prolonged period of time, or if material damage to a significant portion of our standing timber were to occur, we could suffer a materially adverse impact to our results of operations.
On a short-term basis, we may adjust our timber harvest levels in response to market conditions. Longer term, our timber harvest levels may be affected by acquisitions of additional timberlands, sales of existing timberlands and shifts in harvest from one region to another. In addition to timberland acquisitions and sales, future timber harvest levels may be affected by changes in estimates of long-term sustainable yield because of silvicultural advances, natural disasters, fires, pests, insects and other hazards, regulatory constraints and other factors beyond our control.
Timber harvest activities are also subject to a number of federal, state and local regulations pertaining to the protection of fish, wildlife, water and other resources. Regulations, re-interpretations and litigation can restrict timber harvest activities and increase costs. Examples are federal and state laws protecting threatened, endangered and “at-risk” species, harvesting and forestry road building activities that may be restricted under the U.S. Federal Clean Water Act, state forestry practices laws, laws protecting aboriginal rights, and other similar regulations.
Our estimates of timber inventories and growth rates may be inaccurate, include risks inherent to such estimates, and may impair our ability to realize expected revenues.
We rely upon estimates of merchantable timber inventories, which include judgments regarding inventories that may be lawfully and economically harvested, timber growth rates and end-product yields when acquiring and managing working forests. These estimates, which are inherently inexact and uncertain in nature, are central to forecasting our anticipated timber harvests, revenues and expected cash flows. Timber
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 30
growth rates and yield estimates are developed by forest biometricians and other experts using statistical measurements of a sample of trees on a given property. Timber growth equations are used that predict the rate of height and diameter growth of trees so that foresters can estimate the volume of timber that may be present in the tree stand at a given age. Tree growth varies by soil type, geographic area, and climate. Inappropriate application of growth equations in forest management planning may lead to inaccurate estimates of future volumes. If these estimates are inaccurate, our ability to manage our timberlands in a sustainable or profitable manner may be diminished, which may cause our results of operations and our stock price to be adversely affected.
Our operating results and cash flows will be materially affected by supply and demand for timber.
A variety of factors affect prices for timber, including available supply, changes in economic conditions that impact demand, the level of domestic new construction and remodeling activity, interest rates, credit availability, population growth, weather conditions and pest infestation, and other factors. These factors vary by region, timber type (sawlogs or pulpwood logs) and species.
Timber prices are affected by changes in demand on a local, national or international level. The closure of a mill in the regions where we own timber can have a material adverse effect on demand, and therefore pricing. As the demand for paper continues to decline, closures of pulp mills have adversely affected the demand for pulpwood and wood chips in certain regions in which we operate. We export logs to Asia. While demand for Asia has remained steady, recently Asian markets have experienced a high degree of volatility, especially in China. A decrease in demand of logs from Asia may have a negative impact on log and lumber in the markets in which we compete.
Timber prices are affected by changes in timber availability at the local, national and international level. Our timberland ownership is concentrated in Alabama, Arkansas, Louisiana, Mississippi, North Carolina, Oklahoma, Oregon and Washington. In some of these states, much of the timberland is privately owned. Increases in timber prices often result in substantial increases in harvesting on private timberlands, including lands not previously made available for commercial timber operations, causing a short-term increase in supply that moderates price increases. In western states such as Oregon, and Washington, where a greater proportion of timberland is government owned, any substantial increase in timber harvesting from government-owned land could significantly reduce timber prices. On a local level, timber supplies can fluctuate depending upon factors such as changes in weather conditions and harvest strategies of local timberland owners, as well as occasionally high timber salvage efforts due to events such as unusual pest infestations or fires.
Timberlands make up a significant portion of our business portfolio.
Our real estate holdings are primarily timberlands and we may make additional timberlands acquisitions in the future. As the owner and manager of approximately 6.9 million acres of timberlands, we are subject to the risks that are inherent in concentrated real estate investments. A downturn in the real estate industry generally, or the timber or forest products industries specifically, could reduce the value of our properties and adversely affect our results of operations. Such a downturn could also adversely affect our customers and reduce the demand for our products. The risks we face may be more pronounced than if we diversified our investments outside real estate or outside timberlands.
CYBERSECURITY RISKS
We rely on information technology to support our operations and reporting environments. A security failure of that technology could impact our ability to operate our businesses effectively, adversely affect our reported financial results, impact our reputation and expose us to potential liability or litigation.
We use information systems to carry out our operational activities and maintain our business records. Some systems are internally managed and some are maintained by third-party service providers. We and our service providers employ what we believe are adequate security measures. Our ability to conduct business could be materially and adversely affected if these systems or resources are compromised, damaged or fail. This could be a result of a cyber incident, natural disaster, hardware or software corruption, failure or error, telecommunications system failure, service provider error or failure, intentional or unintentional personnel actions or other disruption.
In the ordinary course of our business, we collect and store sensitive data, including intellectual property, other proprietary information and personally identifiable information. If this data is compromised, destroyed or inappropriately disclosed, it could have a material adverse effect, including damage to our reputation, loss of customers, significant expenses to address and resolve the issues, or litigation or other proceedings by affected individuals, business partners and/or regulators.
| RISKS RELATED TO OWNERSHIP OF OUR COMMON STOCK |
STOCK-PRICE VOLATILITY
The market price of our common stock may be influenced by many factors, some of which are beyond our control.
The market price of our common stock may be influenced by many factors, some of which are beyond our control, including those described above under "Risks Related to our Industries and Business" and the following:
| • | actual or anticipated fluctuations in our operating results or our competitors' operating results, |
| • | announcements by us or our competitors of new products, capacity changes, significant contracts, acquisitions or strategic investments, |
| • | our growth rate and our competitors’ growth rates, |
| • | general economic conditions, |
| • | conditions in the financial markets, |
| • | changes in stock market analyst recommendations regarding us, our competitors or the forest products industry generally, or lack of analyst coverage of our common stock, |
| • | sales of our common stock by our executive officers, directors and significant stockholders, |
| • | sales or repurchases of substantial amounts of common stock, |
| • | changes in accounting principles, and |
| • | changes in tax laws and regulations. |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 31
In addition, there has been significant volatility in the market price and trading volume of securities of companies operating in the forest products industry that often has been unrelated to the operating performance of particular companies.
Some companies that have had volatile market prices for their securities have had securities litigation brought against them. If litigation of this type is brought against us, it could result in substantial costs and divert management’s attention and resources.
PREFERENCE SHARES
Our common shares will rank junior to our mandatory convertible preference shares with respect to dividends and amounts payable in the event of our liquidation.
Our common shares will rank junior to our mandatory convertible preference shares with respect to the payment of dividends and amounts payable in the event of our liquidation, dissolution or winding-up. This means that, unless full cumulative dividends have been paid or set aside for payment on all outstanding mandatory convertible preference shares for all past dividend periods and the then current dividend period, no dividends may be declared or paid on our common shares. Likewise, in the event of our voluntary or involuntary liquidation, dissolution or winding-up, no distribution of our assets may be made to holders of our common shares until we have paid to holders of the mandatory convertible preference shares a liquidation preference equal to $50.00 per share plus accrued and unpaid dividends.
Certain provisions in the mandatory convertible preference shares could delay or prevent an otherwise beneficial takeover or takeover attempt of us and, therefore, the ability of holders to exercise their rights associated with a potential fundamental change.
Certain provisions in our mandatory convertible preference shares could make it more difficult or more expensive for a third party to acquire us. For example, if a fundamental change were to occur on or prior to July 1, 2016, holders of the mandatory convertible preference shares may have the right to convert their mandatory convertible preference shares, in whole or in part, at an increased conversion rate and be entitled to receive a fundamental change dividend make-whole amount equal to the present value of all remaining dividend payments on their mandatory convertible preference shares. These features of the mandatory convertible preference shares could increase the cost of acquiring us or otherwise discourage a third party from acquiring us or removing incumbent management.
Item 1B. UNRESOLVED STAFF COMMENTS
UNRESOLVED STAFF COMMENTS
There are no unresolved comments that were received from the SEC staff relating to our periodic or current reports under the Securities Exchange Act of 1934.
Item 2. PROPERTIES
PROPERTIES
Details about our facilities, production capacities and locations are found in the Our Business — What We Do section of this report.
| • | For details about our Timberlands properties, go to Our Business/What We Do/Timberlands/Where We Do It. |
| • | For details about our Wood Products properties, go to Our Business/What We Do/Wood Products/Where We Do It. |
| • | For details about our Cellulose Fibers properties, go to Our Business/What We Do/Cellulose Fibers/Where We Do It. |
Item 3. LEGAL PROCEEDINGS
LEGAL PROCEEDINGS
See Note 15: Legal Proceedings, Commitments and Contingencies in the Notes to Consolidated Financial Statements for a summary of legal proceedings.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 32
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
Our common stock trades on the following exchanges under the symbol WY:
| • | New York Stock Exchange and |
| • | Chicago Stock Exchange |
As of December 31, 2015, there were 7,700 holders of record of our common shares. Dividend-per-share data and the range of closing market prices for our common stock for each of the four quarters in 2015 and 2014 are included in Note 22: Selected Quarterly Financial Information (unaudited) in the Notes to Consolidated Financial Statements.
INFORMATION ABOUT SECURITIES AUTHORIZED FOR ISSUANCE UNDER OUR EQUITY COMPENSATION PLAN
| NUMBER OF SECURITIES TO BE ISSUED UPON EXERCISE OF OUTSTANDING OPTIONS, WARRANTS AND RIGHTS | WEIGHTED AVERAGE EXERCISE PRICE OF OUTSTANDING OPTIONS, WARRANTS AND RIGHTS | NUMBER OF SECURITIES REMAINING AVAILABLE FOR FUTURE ISSUANCE UNDER EQUITY COMPENSATION PLANS (EXCLUDING SECURITIES TO BE ISSUED UPON EXERCISE) | |||||
| Equity compensation plans approved by security holders(1) | 14,935,316 | $ | 22.74 | 17,317,903 | |||
| Equity compensation plans not approved by security holders | N/A | N/A | N/A | ||||
| Total | 14,935,316 | $ | 22.74 | 17,317,903 | |||
| (1) Includes 1,104,621 restricted stock units and 685,535 performance share units. Because there is no exercise price associated with restricted stock units and performance share units, excluding these stock units the weighted average exercise price calculation would be $25.83. |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 33
INFORMATION ABOUT COMMON STOCK REPURCHASES DURING 2015
| TOTAL NUMBER OF SHARES (OR UNITS) PURCHASED | AVERAGE PRICE PAID PER SHARE (OR UNIT) | TOTAL NUMBER OF SHARES (OR UNITS) PURCHASED AS PART OF PUBLICLY ANNOUNCED PLANS OF PROGRAMS | MAXIMUM NUMBER (OR APPROXIMATE DOLLAR VALUE) OF SHARES (OR UNITS) THAT MAY YET BE PURCHASED UNDER THE PLANS OR PROGRAMS(1)(2) | |||||||
| Common Stock Repurchases During First Quarter: | ||||||||||
| January | 228,429 | $ | 35.85 | 228,429 | $ | 488,348,381 | ||||
| February | 3,038,219 | $ | 35.21 | 3,038,219 | $ | 381,369,837 | ||||
| March | 4,074,918 | $ | 33.69 | 4,074,918 | $ | 244,089,600 | ||||
| Total repurchases during first quarter | 7,341,566 | $ | 34.39 | 7,341,566 | $ | 244,089,600 | ||||
| Common Stock Repurchases During Second Quarter: | ||||||||||
| April | 1,949,315 | $ | 31.84 | 1,949,315 | $ | 182,017,591 | ||||
| May | 1,570,276 | $ | 31.81 | 1,570,276 | $ | 132,064,000 | ||||
| June | 1,322,926 | $ | 31.76 | 1,322,926 | $ | 90,047,982 | ||||
| Total repurchases during second quarter | 4,842,517 | $ | 31.81 | 4,842,517 | $ | 90,047,982 | ||||
| Common Stock Repurchases During Third Quarter: | ||||||||||
| July | — | — | — | $ | 90,047,982 | |||||
| August | 145,720 | $ | 28.00 | 145,720 | $ | 585,967,414 | ||||
| September | 3,112,428 | $ | 27.56 | 3,112,428 | $ | 500,190,226 | ||||
| Total repurchases during third quarter | 3,258,148 | $ | 27.58 | 3,258,148 | $ | 500,190,226 | ||||
| Common Stock Repurchases During Fourth Quarter: | ||||||||||
| October | 616,265 | $ | 28.76 | 616,265 | $ | 482,469,449 | ||||
| November | 130,930 | $ | 30.75 | 130,930 | $ | 478,442,984 | ||||
| December | — | $ | — | — | $ | 478,442,984 | ||||
| Total repurchases during fourth quarter | 747,195 | $ | 29.11 | 747,195 | $ | 478,442,984 | ||||
| Total common stock repurchases during 2015 | 16,189,426 | $ | 32.00 | 16,189,426 | $ | 478,442,984 | ||||
| (1) On August 13, 2014, our board of directors approved a stock repurchase program under which we were authorized to repurchase up to $700 million of outstanding shares (the 2014 Repurchase Program). The 2014 stock repurchase program replaced the prior 2011 stock repurchase program. During 2014, we repurchased $203 million of outstanding shares under the 2014 Repurchase Program. During 2015, we completed the 2014 Repurchase Program by purchasing $497 million of outstanding shares. All common stock purchases under the stock repurchase program were made in open-market transactions. (2) On August 27, 2015, our board of directors approved a new share repurchase program of up to $500 million of outstanding shares (the 2015 Repurchase Program), commencing upon completion of the 2014 Repurchase Program. During 2015, we repurchased $22 million of outstanding shares under the 2015 Repurchase Program. All common stock purchases under the stock repurchase program were made in open-market transactions. |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 34
COMPARISON OF FIVE-YEAR CUMULATIVE TOTAL SHAREHOLDER RETURN
Weyerhaeuser Company, S&P 500 and S&P Global Timber & Forestry Index

PERFORMANCE GRAPH ASSUMPTIONS
| • | Assumes $100 invested on December 31, 2010 in Weyerhaeuser common stock, the S&P 500 Index and the S&P Global Timber & Forestry Index. |
| • | Total return assumes dividends received are reinvested at month end. |
| • | Measurement dates are the last trading day of the calendar year shown. |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 35
Item 6. SELECTED FINANCIAL DATA
SELECTED FINANCIAL DATA
DOLLAR AMOUNTS IN MILLIONS, EXCEPT PER-SHARE FIGURES
| PER COMMON SHARE | |||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | |||||||
| Diluted earnings from continuing operations attributable to Weyerhaeuser common shareholders | $ | 0.89 | 1.40 | 0.82 | 0.58 | 0.50 | |||||
| Diluted earnings from discontinued operations attributable to Weyerhaeuser common shareholders(1) | — | 1.78 | 0.13 | 0.13 | 0.11 | ||||||
| Diluted net earnings attributable to Weyerhaeuser common shareholders | $ | 0.89 | 3.18 | 0.95 | 0.71 | 0.61 | |||||
| Dividends paid per common share | $ | 1.20 | 1.02 | 0.81 | 0.62 | 0.60 | |||||
| Weyerhaeuser shareholders’ interest (end of year) | $ | 9.54 | 10.11 | 11.64 | 7.50 | 7.95 | |||||
| FINANCIAL POSITION | |||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | |||||||
| Total assets | $ | 12,486 | 13,265 | 14,372 | 12,609 | 12,523 | |||||
| Total long-term debt | $ | 4,891 | 4,891 | 4,891 | 4,291 | 4,478 | |||||
| Weyerhaeuser shareholders’ interest | $ | 4,869 | 5,304 | 6,795 | 4,070 | 4,263 | |||||
| Percent earned on average Weyerhaeuser shareholders’ interest | 9.1 | % | 29.5 | % | 9.9 | % | 9.2 | % | 7.5 | % | |
| OPERATING RESULTS | |||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | |||||||
| Net sales | $ | 7,082 | 7,403 | 7,254 | 5,989 | 5,378 | |||||
| Earnings from continuing operations | $ | 506 | 828 | 491 | 312 | 270 | |||||
| Discontinued operations, net of income taxes(1) | — | 998 | 72 | 72 | 61 | ||||||
| Net earnings | 506 | 1,826 | 563 | 384 | 331 | ||||||
| Net loss (earnings) attributable to noncontrolling interest | — | — | — | 1 | — | ||||||
| Net earnings attributable to Weyerhaeuser | 506 | 1,826 | 563 | 385 | 331 | ||||||
| Dividends on preference shares | (44 | ) | (44 | ) | (23 | ) | — | — | |||
| Net earnings attributable to Weyerhaeuser common shareholders | $ | 462 | 1,782 | 540 | 385 | 331 | |||||
| CASH FLOWS | |||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | |||||||
| Net cash from operations | $ | 1,064 | 1,088 | 1,004 | 581 | 291 | |||||
| Cash from investing activities | (487 | ) | 361 | (1,829 | ) | (192 | ) | 122 | |||
| Cash from financing activities | (1,145 | ) | (704 | ) | 762 | (444 | ) | (927 | ) | ||
| Net change in cash and cash equivalents | $ | (568 | ) | 745 | (63 | ) | (55 | ) | (514 | ) | |
| STATISTICS (UNAUDITED) | |||||||||||
| 2015 | 2014 | 2013 | 2012 | 2011 | |||||||
| Number of employees | 12,600 | 12,800 | 13,700 | 13,200 | 12,800 | ||||||
| Number of common shareholder accounts at year-end | 7,700 | 8,248 | 8,859 | 9,227 | 9,724 | ||||||
| Number of common shares outstanding at year-end (thousands) | 510,483 | 524,474 | 583,548 | 542,393 | 536,425 | ||||||
| Weighted average common shares outstanding – diluted (thousands) | 519,618 | 560,899 | 571,239 | 542,310 | 539,879 |
| (1) | See Note 3: Discontinued Operations in the Notes to Consolidated Financial Statements. |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 36
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (MD&A)
| WHAT YOU WILL FIND IN THIS MD&A |
Our MD&A includes the following major sections:
| • | economic and market conditions affecting our operations; |
| • | financial performance summary; |
| • | results of our operations — consolidated and by segment; |
| • | liquidity and capital resources — where we discuss our cash flows; |
| • | off-balance sheet arrangements; |
| • | environmental matters, legal proceedings and other contingencies; and |
| • | accounting matters — where we discuss critical accounting policies and areas requiring judgments and estimates. |
| ECONOMIC AND MARKET CONDITIONS AFFECTING OUR OPERATIONS |
The strength of the U.S. housing market strongly affects our Wood Products and Timberlands segments. As published by the U.S. Census Bureau, total U.S. housing starts for 2015 were 1,111,000 units, with single-family units accounting for 715,000 of the total. This represents a 10 percent increase in single-family starts from 2014, which were 648,000 units. Multi-family construction also increased in 2015 to 396,000 units compared with 358,000 in 2014. Expectations are for a similar increase in 2016. Consensus forecasts place expected total housing starts between 1.2 and 1.3 million units for 2016. Sources include IHS Global Insight, John Burns Real Estate and RISI. While housing has improved significantly since the recession of 2009, current demand for new housing continues to run below historic pre bubble averages. The 25-year period of 1976-2000 averaged 1.5 million total starts and 1.1 million single family starts, levels which have not yet been achieved in the post recession period.
Wood Products primarily sells into the new residential building and repair and remodel markets. Demand for wood products continued to improve in 2015 following the growth in home construction, however, growth in production also expanded and prices were lower in 2015 than 2014. The Random Lengths framing lumber composite was 14 percent lower in 2015 versus 2014 while oriented strand board (OSB) was 4 percent lower in 2015 as measured by Random Lengths North Central Price. Expectations are for similar to slightly higher wood product prices in 2016 as demand continues to increase with growth in housing starts and remodeling.
Demand for logs from our Timberlands segment is affected by the production of wood-based building products as well as export demand in our Western holdings. In the South, Southern pine sawlog prices were flat to slightly higher in 2015 as available supplies continue to match or exceed growth in demand. Western log prices were lower in 2015 due primarily to the pullback in demand from China which had been actively competing with domestic lumber producers for sawlogs. Expectations are for slightly improved log prices as off-shore demand improves over 2015 and domestic wood products manufacturing output increases with rising housing starts creating increased log demand.
Cellulose Fibers is primarily affected by global supply and demand factors and the relative strength of the U.S. dollar. The slowdown in global growth and reduced expectations for emerging economies slowed demand growth for pulp in 2015. The U.S. dollar continued to strengthen versus the Euro in 2015, rising 12 percent due to stronger US economic growth and increasingly accommodative monetary policies in Eurozone economies. Consequently prices for benchmark NBSK pulp were 8% lower in 2015 versus 2014. Expectations are for similar to slightly lower prices in 2016 as global economic growth is expected to be weak, which will limit growth in demand for products made with cellulose fibers. Furthermore, the US dollar is expected to remain strong relative to other currencies including the euro and a weak euro has historically been associated with lower US dollar prices for cellulose fibers.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 37
| FINANCIAL PERFORMANCE SUMMARY |
Net Sales by Segment

Contribution to Pretax Earnings by Segment
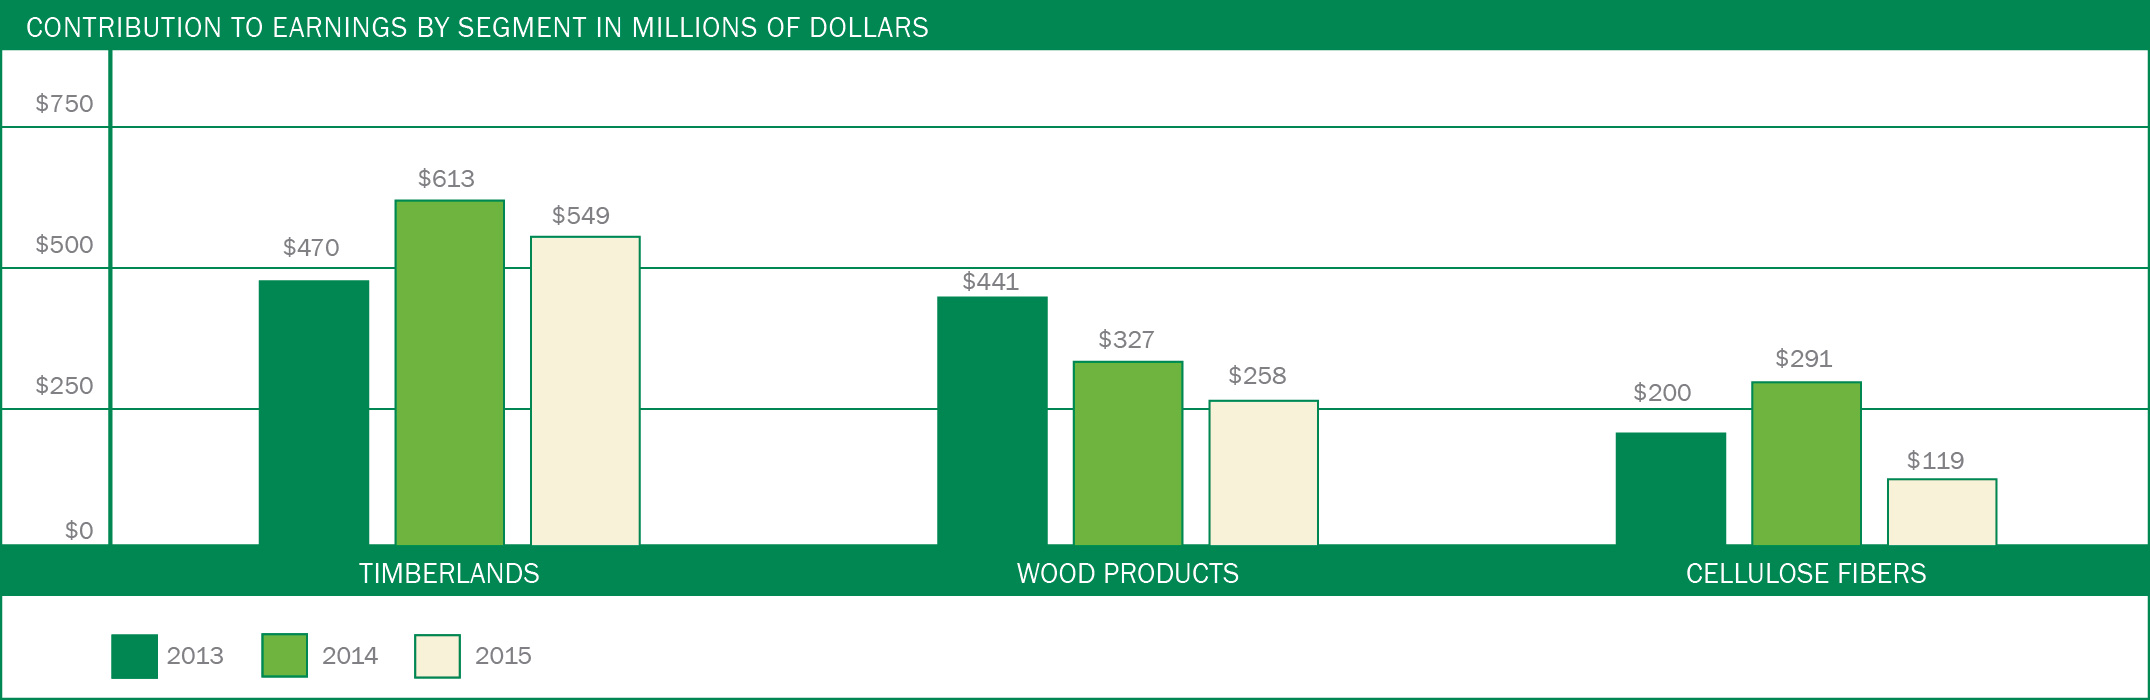
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 38
| RESULTS OF OPERATIONS |
In reviewing our results of operations, it is important to understand these terms:
| • | Sales realizations refer to net selling prices — this includes selling price plus freight minus normal sales deductions. |
| • | Net contribution to earnings refers to earnings (loss) attributable to Weyerhaeuser shareholders before interest expense and income taxes. |
CONSOLIDATED RESULTS
HOW WE DID IN 2015
Summary of Financial Results
| DOLLAR AMOUNTS IN MILLIONS, EXCEPT PER-SHARE FIGURES | |||||||||||||||
| AMOUNT OF CHANGE | |||||||||||||||
| 2015 | 2014 | 2013 | 2015 vs. 2014 | 2014 vs. 2013 | |||||||||||
| Net sales | $ | 7,082 | $ | 7,403 | $ | 7,254 | $ | (321 | ) | $ | 149 | ||||
| Operating income | $ | 919 | $ | 1,320 | $ | 634 | $ | (401 | ) | $ | 686 | ||||
| Earnings from discontinued operations, net of tax | $ | — | $ | 998 | $ | 72 | $ | (998 | ) | $ | 926 | ||||
| Net earnings attributable to Weyerhaeuser common shareholders | $ | 462 | $ | 1,782 | $ | 540 | $ | (1,320 | ) | $ | 1,242 | ||||
| Basic earnings per share attributable to Weyerhaeuser common shareholders | $ | 0.89 | $ | 3.20 | $ | 0.95 | $ | (2.31 | ) | $ | 2.25 | ||||
| Diluted earnings per share attributable to Weyerhaeuser common shareholders | $ | 0.89 | $ | 3.18 | $ | 0.95 | $ | (2.29 | ) | $ | 2.23 |
COMPARING 2015 WITH 2014
Net Sales
Net sales decreased $321 million — 4 percent — primarily due to:
| • | lower Timberlands segment sales — $147 million — primarily due to lower average log sales realizations and export sales volumes in the West, and lower log sales volumes in the South; |
| • | lower Wood Products segment sales — $98 million — primarily due to decreased structural lumber and OSB average realizations, partially offset by higher structural lumber, OSB, and engineered solid section sales volumes and higher sales of complementary building products; and |
| • | lower Cellulose Fibers segment sales — $76 million — primarily due to lower pulp and liquid packaging board average sales realizations. |
Net Earnings Attributable to Weyerhaeuser Common Shareholders
Our net earnings attributable to Weyerhaeuser common shareholders decreased $1,320 million primarily due to:
| • | earnings from discontinued operation recognized in 2014 — $998 million. There were no earnings from discontinued operations in 2015; |
| • | lower gross margin — $252 million — primarily due to lower average sales realizations in lumber and OSB in our Wood Products segment, lower average log sales realizations and sales volumes in our Timberlands segment, and lower average sales realizations for pulp and liquid packaging board, and higher operating costs due to scheduled maintenance outages and the West Coast port slowdown in our Cellulose Fibers segment; |
| • | lower other operating income — $219 million — primarily due to a $151 million pretax gain recognized in 2014 relat |
Showing the first 8K of 76K characters. Open the full section
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
| LONG-TERM DEBT OBLIGATIONS |
The following summary of our long-term debt obligations includes:
| • | scheduled principal repayments for the next five years and after, |
| • | weighted average interest rates for debt maturing in each of the next five years and after and |
| • | estimated fair values of outstanding obligations. |
We estimate the fair value of long-term debt based on quoted market prices we received for the same types and issues of our debt or on the discounted value of the future cash flows using market yields for the same type and comparable issues of debt. Changes in market rates of interest affect the fair value of our fixed-rate debt.
SUMMARY OF LONG-TERM DEBT OBLIGATIONS AS OF DECEMBER 31, 2015
| DOLLAR AMOUNTS IN MILLIONS | ||||||||||||||||||||||||
| 2016 | 2017 | 2018 | 2019 | 2020 | THEREAFTER | TOTAL | FAIR VALUE | |||||||||||||||||
| Fixed-rate debt | $ | — | $ | 281 | $ | 62 | $ | 500 | $ | — | $ | 3,503 | $ | 4,346 | $ | 5,070 | ||||||||
| Average interest rate | — | % | 6.95 | % | 7.00 | % | 7.38 | % | — | % | 7.09 | % | 7.12 | % | N/A | |||||||||
| Variable-rate debt | $ | — | $ | — | $ | — | $ | — | $ | 550 | $ | — | $ | 550 | $ | 550 | ||||||||
| Average interest rate | — | % | — | % | — | % | — | % | 2.07 | % | — | % | 2.07 | % | N/A |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 55
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
| REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM |
The Board of Directors and Shareholders
Weyerhaeuser Company:
We have audited the accompanying consolidated balance sheets of Weyerhaeuser Company and subsidiaries as of December 31, 2015 and 2014, and the related consolidated statements of operations, comprehensive income, cash flows, and changes in equity for each of the years in the three-year period ended December 31, 2015. These consolidated financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on these consolidated financial statements based on our audits.
We conducted our audits in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement. An audit includes examining, on a test basis, evidence supporting the amounts and disclosures in the financial statements. An audit also includes assessing the accounting principles used and significant estimates made by management, as well as evaluating the overall financial statement presentation. We believe that our audits provide a reasonable basis for our opinion.
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of Weyerhaeuser Company and subsidiaries as of December 31, 2015 and 2014, and the results of their operations and their cash flows for each of the years in the three-year period ended December 31, 2015, in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), Weyerhaeuser Company’s internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO), and our report dated February 17, 2016 expressed an unqualified opinion on the effectiveness of the Company’s internal control over financial reporting.
/s/ KPMG LLP
Seattle, Washington
February 17, 2016
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 56
| CONSOLIDATED STATEMENT OF OPERATIONS |
FOR THE THREE-YEAR PERIOD ENDED DECEMBER 31, 2015
| DOLLAR AMOUNTS IN MILLIONS, EXCEPT PER-SHARE FIGURES | |||||||||
| 2015 | 2014 | 2013 | |||||||
| Net sales | $ | 7,082 | $ | 7,403 | $ | 7,254 | |||
| Costs of products sold | 5,694 | 5,763 | 5,716 | ||||||
| Gross margin | 1,388 | 1,640 | 1,538 | ||||||
| Selling expenses | 113 | 112 | 125 | ||||||
| General and administrative expenses | 289 | 338 | 404 | ||||||
| Research and development expenses | 24 | 27 | 33 | ||||||
| Charges for restructuring, closures and impairments (Note 18) | 25 | 44 | 377 | ||||||
| Other operating costs (income), net (Note 19) | 18 | (201 | ) | (35 | ) | ||||
| Operating income | 919 | 1,320 | 634 | ||||||
| Earnings (loss) from equity affiliates (Note 8) | (105 | ) | (1 | ) | 1 | ||||
| Interest income and other | 36 | 38 | 54 | ||||||
| Interest expense, net of capitalized interest | (347 | ) | (344 | ) | (369 | ) | |||
| Earnings from continuing operations before income taxes | 503 | 1,013 | 320 | ||||||
| Income taxes (Note 20) | 3 | (185 | ) | 171 | |||||
| Earnings from continuing operations | 506 | 828 | 491 | ||||||
| Earnings from discontinued operations, net of income taxes (Note 3) | — | 998 | 72 | ||||||
| Net earnings | 506 | 1,826 | 563 | ||||||
| Dividends on preference shares | (44 | ) | (44 | ) | (23 | ) | |||
| Net earnings attributable to Weyerhaeuser common shareholders | $ | 462 | $ | 1,782 | $ | 540 | |||
| Basic earnings per share attributable to Weyerhaeuser common shareholders (Note 5): | |||||||||
| Continuing operations | $ | 0.89 | $ | 1.41 | $ | 0.82 | |||
| Discontinued operations | — | 1.79 | 0.13 | ||||||
| Net earnings per share | $ | 0.89 | $ | 3.20 | $ | 0.95 | |||
| Diluted earnings per share attributable to Weyerhaeuser common shareholders (Note 5): | |||||||||
| Continuing operations | $ | 0.89 | $ | 1.40 | $ | 0.82 | |||
| Discontinued operations | — | 1.78 | 0.13 | ||||||
| Net earnings per share | $ | 0.89 | $ | 3.18 | $ | 0.95 | |||
| Dividends paid per common share | $ | 1.20 | $ | 1.02 | $ | 0.81 | |||
| Weighted average shares outstanding (in thousands) (Note 5): | |||||||||
| Basic | 516,371 | 556,705 | 566,329 | ||||||
| Diluted | 519,618 | 560,899 | 571,239 |
See accompanying Notes to Consolidated Financial Statements.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 57
| CONSOLIDATED STATEMENT OF COMPREHENSIVE INCOME |
FOR THE THREE-YEAR PERIOD ENDED DECEMBER 31, 2015
| DOLLAR AMOUNTS IN MILLIONS | |||||||||
| 2015 | 2014 | 2013 | |||||||
| Comprehensive income: | |||||||||
| Net earnings | $ | 506 | $ | 1,826 | $ | 563 | |||
| Other comprehensive income (loss): | |||||||||
| Foreign currency translation adjustments | (97 | ) | (50 | ) | (59 | ) | |||
| Changes in unamortized net pension and other postretirement benefit gain (loss), net of tax expense (benefit) of $131 in 2015, ($323) in 2014, and $480 in 2013 | 282 | (554 | ) | 902 | |||||
| Changes in unamortized prior service credit (cost), net of tax expense (benefit) of ($1) in 2015, ($64) in 2014 and $23 in 2013 | (4 | ) | (103 | ) | 27 | ||||
| Unrealized gains on available-for-sale securities | — | — | 2 | ||||||
| Total comprehensive income attributable to Weyerhaeuser shareholders | $ | 687 | $ | 1,119 | $ | 1,435 |
See accompanying Notes to Consolidated Financial Statements.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 58
| CONSOLIDATED BALANCE SHEET |
| ASSETS | ||||||
| DOLLAR AMOUNTS IN MILLIONS | ||||||
| DECEMBER 31, 2015 | DECEMBER 31, 2014 | |||||
| Current assets: | ||||||
| Cash and cash equivalents | $ | 1,012 | $ | 1,580 | ||
| Receivables, less discounts and allowances of $3 and $3 | 487 | 525 | ||||
| Receivables for taxes | 30 | 25 | ||||
| Inventories (Note 6) | 568 | 595 | ||||
| Prepaid expenses | 77 | 80 | ||||
| Total current assets | 2,174 | 2,805 | ||||
| Property and equipment, less accumulated depreciation of $6,294 and $6,324 (Note 7) | 2,586 | 2,623 | ||||
| Construction in progress | 195 | 131 | ||||
| Timber and timberlands at cost, less depletion charged to disposals | 6,480 | 6,530 | ||||
| Investments in and advances to equity affiliates (Note 8) | 74 | 188 | ||||
| Goodwill | 40 | 40 | ||||
| Deferred tax assets (Note 20) | 4 | 44 | ||||
| Other assets | 318 | 289 | ||||
| Restricted financial investments held by variable interest entities (Note 10) | 615 | 615 | ||||
| Total assets | $ | 12,486 | $ | 13,265 | ||
| LIABILITIES AND EQUITY |
Showing the first 8K of 209K characters. Open the full section
Item 9. CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
CHANGES IN AND DISAGREEMENTS WITH ACCOUNTANTS ON ACCOUNTING AND FINANCIAL DISCLOSURE
Not applicable.
Item 9A. CONTROLS AND PROCEDURES
CONTROLS AND PROCEDURES
| EVALUATION OF DISCLOSURE CONTROLS AND PROCEDURES |
The company’s principal executive officer and principal financial officer have evaluated the effectiveness of the company’s disclosure controls and procedures as of the end of the period covered by this annual report on Form 10-K. Disclosure controls are controls and other procedures that are designed to ensure that information required to be disclosed in the reports filed or submitted under the Exchange Act is recorded, processed, summarized and reported within the time periods specified in the Securities and Exchange Commission’s (SEC) rules and forms. Disclosure controls and procedures include, without limitation, controls and procedures designed to ensure that information required to be disclosed by an issuer in the reports that it files or submits under the Act is accumulated and communicated to the issuer’s management, including its principal executive and principal financial officers, to allow timely decisions regarding required disclosure.
Based on their evaluation, the company’s principal executive officer and principal financial officer have concluded that the company’s disclosure controls and procedures are effective to ensure that information required to be disclosed complies with the SEC’s rules and forms.
| CHANGES IN INTERNAL CONTROL |
No changes occurred in the company’s internal control over financial reporting during the period that have materially affected, or are reasonably likely to materially affect, the company’s internal control over financial reporting.
| MANAGEMENT’S REPORT ON INTERNAL CONTROL OVER FINANCIAL REPORTING |
Management is responsible for establishing and maintaining adequate internal control over financial reporting as is defined in the Securities and Exchange Act of 1934 rules. Management, under our supervision, conducted an evaluation of the effectiveness of the company’s internal control over financial reporting based on the framework in Internal Control — Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO). Based on our evaluation under the framework in Internal Control — Integrated Framework (2013), management concluded that the company’s internal control over financial reporting was effective as of December 31, 2015. The effectiveness of the company’s internal control over financial reporting as of December 31, 2015, has been audited by KPMG LLP, an independent registered public accounting firm, as stated in their report, which is included herein.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 107
| REPORT OF INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM |
The Board of Directors and Shareholders
Weyerhaeuser Company:
We have audited Weyerhaeuser Company’s internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO) . Weyerhaeuser Company’s management is responsible for maintaining effective internal control over financial reporting and for its assessment of the effectiveness of internal control over financial reporting, included in the accompanying Management’s Report on Internal Control Over Financial Reporting. Our responsibility is to express an opinion on the Company’s internal control over financial reporting based on our audit.
We conducted our audit in accordance with the standards of the Public Company Accounting Oversight Board (United States). Those standards require that we plan and perform the audit to obtain reasonable assurance about whether effective internal control over financial reporting was maintained in all material respects. Our audit included obtaining an understanding of internal control over financial reporting, assessing the risk that a material weakness exists, and testing and evaluating the design and operating effectiveness of internal control based on the assessed risk. Our audit also included performing such other procedures as we considered necessary in the circumstances. We believe that our audit provides a reasonable basis for our opinion.
A company’s internal control over financial reporting is a process designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles. A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
Because of its inherent limitations, internal control over financial reporting may not prevent or detect misstatements. Also, projections of any evaluation of effectiveness to future periods are subject to the risk that controls may become inadequate because of changes in conditions, or that the degree of compliance with the policies or procedures may deteriorate.
In our opinion, Weyerhaeuser Company maintained, in all material respects, effective internal control over financial reporting as of December 31, 2015, based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated balance sheets of Weyerhaeuser Company and subsidiaries as of December 31, 2015 and 2014, and the related consolidated statements of operations, comprehensive income, cash flows, and changes in equity for each of the years in the three-year period ended December 31, 2015, and our report dated February 17, 2016 expressed an unqualified opinion on those consolidated financial statements.
/s/ KPMG LLP
Seattle, Washington
February 17, 2016
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 108
DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
A list of our executive officers and biographical information are found in the Our Business — Executive Officers of the Registrant section of this report. Information with respect to directors of the company and other governance matters, as required by this item is included in the Notice of the 2016 Annual Meeting and Proxy Statement for the company’s Annual Meeting of Shareholders to be held May 20, 2016 under the headings “Nominees for Election,” “Board of Directors and Committee Information,” “Section 16(a) Beneficial Ownership Reporting Compliance” and “Potential Payment upon Termination or Change in Control — Change in Control,” and “ — Severance,” and is incorporated herein by reference.
Item 11. EXECUTIVE AND DIRECTOR COMPENSATION
EXECUTIVE AND DIRECTOR COMPENSATION
Information with respect to executive and director compensation contained in the Notice of the 2016 Annual Meeting and Proxy Statement for the company’s Annual Meeting of Shareholders to be held May 20, 2016, under the headings “Board of Directors and Committee Information — Directors’ Compensation,” “Compensation Discussion and Analysis,” “Compensation Committee Report,” “Compensation Committee Interlocks and Insider Participation,” “Summary Compensation Table,” “Grants of Plan-Based Awards,” “Outstanding Equity Awards at Fiscal Year-End,” “Option Exercises and Stock Vested in Fiscal 2015,” “Pension Benefits,” “Nonqualified Deferred Compensation,” and “Potential Payments Upon Termination or Change of Control” is incorporated herein by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
Information with respect to security ownership of certain beneficial owners and management contained in the Notice of the 2016 Annual Meeting and Proxy Statement for the company’s Annual Meeting of Shareholders to be held May 20, 2016 under the heading “Beneficial Ownership of Common Shares” is incorporated herein by reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS
CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS
Information with regard to certain relationships and related transactions contained in the Notice of the 2016 Annual Meeting and Proxy Statement for the company’s Annual Meeting of Shareholders to be held May 20, 2016 under the headings “Review, Approval or Ratification of Transactions with Related Persons” and “Board of Directors and Committee Information” is incorporated herein by reference.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
PRINCIPAL ACCOUNTING FEES AND SERVICES
Information with respect to principal accounting fees and services in the Notice of the 2016 Annual Meeting and Proxy Statement for the company’s Annual Meeting of Shareholders to be held May 20, 2016 under the heading “Ratification of Selection of Independent Registered Public Accounting Firm” is incorporated herein by reference.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 109
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
All financial statement schedules have been omitted because they are not applicable or the required information is included in the consolidated financial statements, or the notes thereto, in Financial Statements and Supplementary Data above.
| EXHIBITS |
| 2 | — | Plan of Acquisition, Reorganization, Arrangement, Liquidation or Succession | |
| (a) | Stock Purchase Agreement, dated as of June 14, 2013, by and among Longview Timber Holdings, Corp., the securityholders listed on the signature pages thereto, Weyerhaeuser Columbia Holding Co., LLC and Weyerhaeuser Company (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission June 17, 2013 — Commission File Number 1-4825) | ||
| (b) | Transaction Agreement, dated as of November 3, 2013, among Weyerhaeuser Company, Weyerhaeuser Real Estate Company, TRI Pointe Homes, Inc. and Topaz Acquisition, Inc. (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission November 4, 2013 — Commission File Number 1-4825) | ||
| (c) | Agreement and Plan of Merger, dated as of November 6, 2015, between Weyerhaeuser Company and Plum Creek Timber Company, Inc. (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission November 9, 2015 - Commission File Number 1-4825) | ||
| 3 | — | Articles of Incorporation | |
| (a) | Articles of Incorporation (incorporated by reference to Quarterly Report on Form 10-Q filed with the Securities and Exchange Commission May 6, 2011 — Commission File Number 1-4825 and Current Report on Form 8-K filed with the Securities and Exchange Commission June 20, 2013 — Commission File Number 1-4825) | ||
| (b) | Bylaws (incorporated by reference to Quarterly Report on Form 10-Q filed with the Securities and Exchange Commission May 6, 2011 — Commission File Number 1-4825) | ||
| 4 | — | Instruments Defining the Rights of Security Holders, Including Indentures | |
| (a) | Indenture dated as of April 1, 1986 between Weyerhaeuser Company and The Bank of New York Mellon Trust Company, N.A. (as successor to JPMorgan Chase Bank, formerly known as The Chase Manhattan Bank and Chemical Bank), a national banking association, as Trustee (incorporated by reference from the Registration Statement on Form S‑3, Registration No. 333-36753). | ||
| (b) | First Supplemental Indenture dated as of February 15, 1991 between Weyerhaeuser Company and The Bank of New York Mellon Trust Company, N.A. (as successor to JPMorgan Chase Bank, formerly known as The Chase Manhattan Bank and Chemical Bank), a national banking association, as Trustee (incorporated by reference from the Registration Statement on Form S‑3, Registration No. 33-52982). | ||
| (c) | Second Supplemental Indenture dated as of February 1, 1993 between Weyerhaeuser Company and The Bank of New York Mellon Trust Company, N.A. (as successor to JPMorgan Chase Bank, formerly known as The Chase Manhattan Bank and Chemical Bank), a national banking association, as Trustee (incorporated by reference from the Registration Statement on Form S‑3, Registration No. 33-59974). | ||
| (d) | Third Supplemental Indenture dated as of October 22, 2001 between Weyerhaeuser Company and The Bank of New York Mellon Trust Company, N.A. (as successor to JPMorgan Chase Bank, formerly known as The Chase Manhattan Bank and Chemical Bank), a national banking association, as Trustee (incorporated by reference from the Registration Statement on Form S-3, Registration No. 333-72356). | ||
| (e) | Fourth Supplemental Indenture dated as of March 12, 2002 between Weyerhaeuser Company and The Bank of New York Mellon Trust Company, N.A. (as successor to JPMorgan Chase Bank, formerly known as The Chase Manhattan Bank and Chemical Bank), a national banking association, as Trustee (incorporated by reference from the Registration Statement on Form S-4, Registration No. 333-82376). | ||
| 10 | — | Material Contracts | |
| (a) | Form of Executive Change of Control Agreement (incorporated by reference to Form 8-K filed with the Securities and Exchange Commission February 13, 2015 — Commission File Number 1-4825) * | ||
| (b) | Form of Executive Severance Agreement (incorporated by reference to Form 8-K filed with the Securities and Exchange Commission March 9, 2015 — Commission File Number 1-4825) * | ||
| (c) | Weyerhaeuser Company 2013 Long-Term Incentive Plan (incorporated by reference to Form 8-K filed with the Securities and Exchange Commission February 19, 2013 — Commission File Number 1-4825) * | ||
| (d) | Form of Weyerhaeuser Company 2013 Long-Term Incentive Plan Stock Option Award Terms and Conditions (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission April 16, 2013 — Commission File Number 1-4825) * | ||
| (e) | Form of Weyerhaeuser Company 2013 Long-Term Incentive Plan Performance Share Unit Award Terms and Conditions (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission April 16, 2013 — Commission File Number 1-4825) * | ||
| (f) | Form of Weyerhaeuser Company 2013 Long-Term Incentive Plan Performance Share Unit Award Terms and Conditions (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission December 22, 2014 — Commission File Number 1-4825) * | ||
| (g) | Form of Weyerhaeuser Company 2013 Long Term Incentive Plan Performance Share Unit Award Terms and Conditions (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission January 22, 2016 — Commission File Number 1-4825) * |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 110
| (h) | Form of Weyerhaeuser Company 2013 Long-Term Incentive Plan Restricted Stock Unit Award 2013 Terms and Conditions (incorporated by reference to Form 8-K filed with the Securities and Exchange Commission April 16, 2013 — Commission File Number 1-4825) * | ||
| (i) | Form of Weyerhaeuser Company 2013 Long-Term Incentive Plan Restricted Stock Unit Award Terms and Conditions (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission January 22, 2016 - Commission File Number 1-4825) * | ||
| (j) | Form of Weyerhaeuser Company 2004 Long-Term Incentive Plan Stock Option Award 2013 Terms and Conditions (incorporated by reference to Form 8-K filed with the Securities and Exchange Commission February 11, 2013 — Commission File Number 1-4825) * | ||
| (k) | Form of Weyerhaeuser Company 2004 Long-Term Incentive Plan Performance Share Award 2013 Terms and Conditions (incorporated by reference to Form 8-K filed with the Securities and Exchange Commission February 11, 2013 — Commission File Number 1-4825) * | ||
| (l) | Form of Weyerhaeuser Company 2004 Long-Term Incentive Plan Restricted Stock Award 2013 Terms and Conditions (incorporated by reference to Form 8-K filed with the Securities and Exchange Commission February 11, 2013 — Commission File Number 1-4825) * | ||
| (m) | Weyerhaeuser Company Annual Incentive Plan for Salaried Employees (Amended and Restated Effective January 1, 2015) (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission December 22, 2014 — Commission File Number 1-4825) * | ||
| (n) | Weyerhaeuser Company 2015 Deferred Compensation Plan (incorporated by reference to Form 8-K filed with the Securities and Exchange Commission December 22, 2014 — Commission File Number 1-4825) * | ||
| (o) | Weyerhaeuser Company Salaried Employees Supplemental Retirement Plan (incorporated by reference to 2004 Form 10-K filed with the Securities and Exchange Commission January 27, 2009 — Commission File Number 1-4825) * | ||
| (p) | 2016 Fee Deferral Plan for Directors of Weyerhaeuser Company (Amended and Restated Effective January 1, 2016) * | ||
| (q) | Form of Weyerhaeuser Company 2013 Long-Term Incentive Plan Restricted Stock Unit Award for Directors Grant Notice and Terms and Conditions * | ||
| (r) | Revolving Credit Facility Agreement among Weyerhaeuser Company, Weyerhaeuser Real Estate Company, JP Morgan Chase Bank, N.A. as administrative agent, Citibank, N.A., as syndication agent, CoBank, ACB, PNC Bank, National Association, The Bank of Tokyo-Mitsubishi UFJ, Ltd, and Wells Fargo Bank, N.A., as documentation agents, and the lenders, swing-line banks and initial fronting banks named therein (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission September 12, 2013 — Commission File Number 1-4825) | ||
| (s) | Credit Agreement among Weyerhaeuser Company, CoBank, ACB as administrative agent, and the lenders party thereto (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission September 16, 2013 — Commission File Number 1-4825) | ||
| (t) | Form of Tax Sharing Agreement to be entered into by and among Weyerhaeuser Company, Weyerhaeuser Real Estate Company and TRI Pointe Homes, Inc. (incorporated by reference to Current Report on Form 8-K filed with the Securities and Exchange Commission November 4, 2013 — Commission File Number 1-4825) | ||
| (u) | First Amendment to Tax Sharing Agreement dated as of July 7, 2015 by and among Weyerhaeuser Company, TRI Pointe Holdings, Inc. (f/k/a Weyerhaeuser Real Estate Company) and TRI Pointe Homes, Inc. (incorporated by reference to Quarterly Report on Form 10-Q filed with the Securities and Exchange Commission July 31, 2015) | ||
| (v) | Executive Employment Agreement with Doyle R. Simons dated February 17, 2016 * | ||
| (w) | Retention Agreement with Catherine I. Slater dated effective November 4, 2015 * | ||
| 12 | — | Statements regarding computation of ratios | |
| 14 | — | Code of Business Conduct and Ethics (incorporated by reference to Form 8-K filed with the Securities and Exchange Commission April 20, 2010 — Commission File Number 1-4825) | |
| 21 | — | Subsidiaries of the Registrant | |
| 23 | — | Consent of Independent Registered Public Accounting Firm | |
| 31 | — | Certification pursuant to Rule 13a-14(a) under the Securities Exchange Act of 1934, as amended | |
| 32 | — | Certification pursuant to Rule 13a-14(b) under the Securities Exchange Act of 1934, as amended, and Section 1350 of Chapter 63 of Title 18 of the United States Code (18 U.S.C. 1350) | |
| 101.INS | — | XBRL Instance Document | |
| 101.SCH | — | XBRL Taxonomy Extension Schema Document | |
| 101.CAL | — | XBRL Taxonomy Extension Calculation Linkbase Document | |
| 101.DEF | — | XBRL Taxonomy Extension Definition Linkbase Document | |
| 101.LAB | — | XBRL Taxonomy Extension Label Linkbase Document | |
| 101.PRE | — | XBRL Taxonomy Extension Presentation Linkbase Document |
- Denotes a management contract or compensatory plan or arrangement.
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 111
| SIGNATURES |
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized February 17, 2016.
| WEYERHAEUSER COMPANY |
| /s/ DOYLE R. SIMONS |
| Doyle R. Simons |
| President and Chief Executive Officer |
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of the registrant in the capacities indicated February 17, 2016.
| /s/ DOYLE R. SIMONS | /s/ JOHN I. KIECKHEFER | |
| Doyle R. Simons Principal Executive Officer and Director | John I. Kieckhefer Director | |
| /s/ PATRICIA M. BEDIENT | /s/ WAYNE W. MURDY | |
| Patricia M. Bedient Principal Financial Officer | Wayne W. Murdy Director | |
| /s/ JEANNE M. HILLMAN | /s/ NICOLE W. PIASECKI | |
| Jeanne M. Hillman Principal Accounting Officer | Nicole W. Piasecki Director | |
| /s/ DAVID P. BOZEMAN | /s/ D. MICHAEL STEUERT | |
| David P. Bozeman Director | D. Michael Steuert Director | |
| /s/ DEBRA A. CAFARO | /s/ KIM WILLIAMS | |
| Debra A. Cafaro Director | Kim Williams Director | |
| /s/ MARK A. EMMERT | /s/ CHARLES R. WILLIAMSON | |
| Mark A. Emmert Director | Charles R. Williamson Chairman of the Board and Director |
WEYERHAEUSER COMPANY > 2015 ANNUAL REPORT AND FORM 10-K 112