 filings.tools
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
107K characters. Original on sec.gov ·
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (MD&A)
| WHAT YOU WILL FIND IN THIS MD&A |
Our MD&A includes the following major sections:
| • | economic and market conditions affecting our operations; |
| • | financial performance summary; |
| • | discussion of the softwood lumber agreement; |
| • | results of our operations — consolidated and by segment; |
| • | liquidity and capital resources — where we discuss our cash flows; |
| • | off-balance sheet arrangements; |
| • | environmental matters, legal proceedings and other contingencies; and |
| • | accounting matters — where we discuss critical accounting policies and areas requiring judgments and estimates. |
| ECONOMIC AND MARKET CONDITIONS AFFECTING OUR OPERATIONS |
The demand for logs within our Timberlands segment is directly affected by production levels of domestic wood-based building products. This segment, specifically the Western region, is also affected by export demand. Japanese housing starts are a key driver of export log demand in Japan. The strength of the U.S. housing market strongly affects demand in our Wood Products segment, as does repair and remodeling activity.
According to the U.S. Census Bureau, housing starts in 2017 totaled 1.2 million units. Single family units accounted for 0.8 million of total housing starts year to date, increasing the share of single family units to 71 percent of total housing starts compared with 67 percent in 2016. While total housing start growth slowed in 2017, rising by a modest 2.4 percent overall, there has been a shift in construction away from multifamily units, which are down 10 percent year over year, to single family units, which have increased 9 percent over the same period. This shift to the more wood intensive single family construction has been positive for wood products demand. We continue to expect improving U.S. housing starts and anticipate a 4 percent to 10 percent increase in total starts in 2018. Consensus forecasts place expected total housing starts between 1.25 and 1.31 million units for 2018 (sources include National Association of Home Builders (NAHB), Fannie Mae, Mortgage Bankers Association, The Engineered Wood Association (APA), and Forest Economic Advisors, LLC (FEA)). Demand for homes remains strong relative to inventories. U.S. Census reported new homes sales of 608 thousand units in 2017, an increase of 8.4 percent over 2016. This sales level was characterized by consistently low inventories as measured by months of supply, which averaged 5.4 months through 2017. Existing home sales continued to rise in 2017, with total sales of 5.51 million units, a gain of 1.1 percent over 2016 and the highest sales level since 2006 according to the National Association of Realtors. Existing home inventories were also tight with supplies averaging 3.9 months for the year, down from 4.3 months in 2016. We attribute this continued improvement primarily to employment growth, improving consumer confidence and favorable mortgage rates.
According to the Joint Center for Housing Studies at Harvard University, the Leading Indicator of Remodeling Activity (LIRA) increased by 6.4 percent in 2017 and is expected to increase by 7.5 percent year over year for 2018.
U.S. wood product markets advanced in 2017, consistent with growth in homebuilding and remodeling segments, as described above. According to FEA, North American lumber consumption grew at a 7.2 percent rate in 2017. The Random Lengths framing lumber composite price increased 19.4 percent in 2017 versus 2016 while oriented strand board (OSB) increased 31 percent in 2017 versus 2016 as measured by Random Lengths North Central Price. We expect similar to slightly higher wood product prices in 2018 as demand continues to increase with growth in housing starts and remodeling.
Consistent with this, demand for logs increased with wood products production within our Western region. This coupled with higher market prices year over year drove higher realizations within this region. Douglas fir sawlog prices as reported by Loglines increased 10 percent from 2016 for the domestic market and 5.7 percent for Japan export logs. In the South, log supplies increased consistent with increased demand, leaving prices flat to slightly down year-over-year. According to TimberMart - South, prices for delivered sawtimber and stumpage were down 2.6 percent and 4.6 percent respectively.
Log inventories in Chinese ports have been stable through 2017, ranging from 1.0 million to 1.5 million cubic meters (M3) per month as reported by International Wood Markets China Bulletin. Log and lumber demand in China remain strong, primarily due to the strength of construction activity. Total imports of logs and lumber increased 13 percent and 20 percent, respectively, for the first 11 months of 2017 compared on a year ago basis. In Japan, post and beam housing starts (the primary source of log demand) for January through November 2017 are up 1.0 percent from the same period last year while total housing starts are down 0.1 percent on a year ago basis.
We expect demand from China and Japan in 2018 to be similar to modestly improved from demand experienced in 2017.
Our Real Estate, Energy and Natural Resources segment is affected by the health of the U.S. economy and especially the U.S. housing sector of the economy. According to the Realtors Land Institute of the National Association of Realtors, the dollar volume of rural properties, including timber, sold in 2017 grew 4 percent over 2016 sales while per acre prices were up 3 percent on average.
Energy markets recovered steadily in 2017. For the year, Brent crude oil averaged $54 per barrel in 2017, an increase of $10 per barrel from 2016 levels. Prices increased fairly steadily through the second half of the year, with year-end prices higher than the annual average. Natural gas prices were also higher in 2017 averaging $2.99 per million British thermal units (MMBtu) a 19 percent increase over 2016. Expectations are for energy prices to be stable to gradually increasing in 2018.
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 36
| FINANCIAL PERFORMANCE SUMMARY |
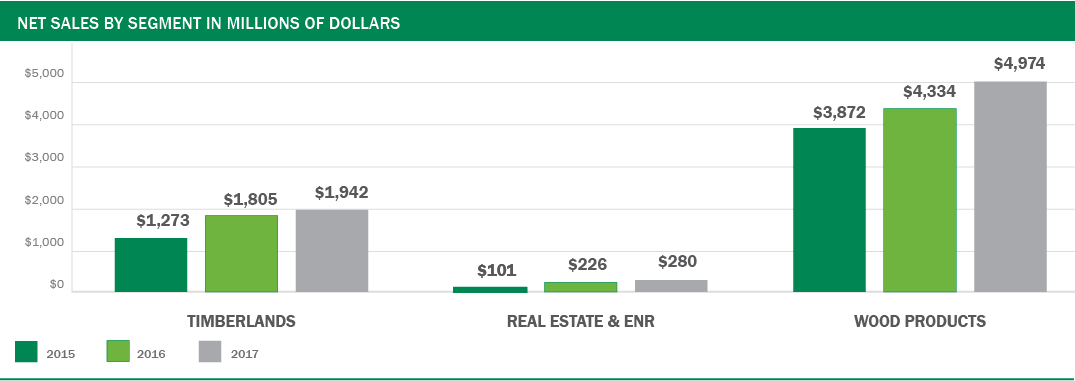
Net Sales by Segment
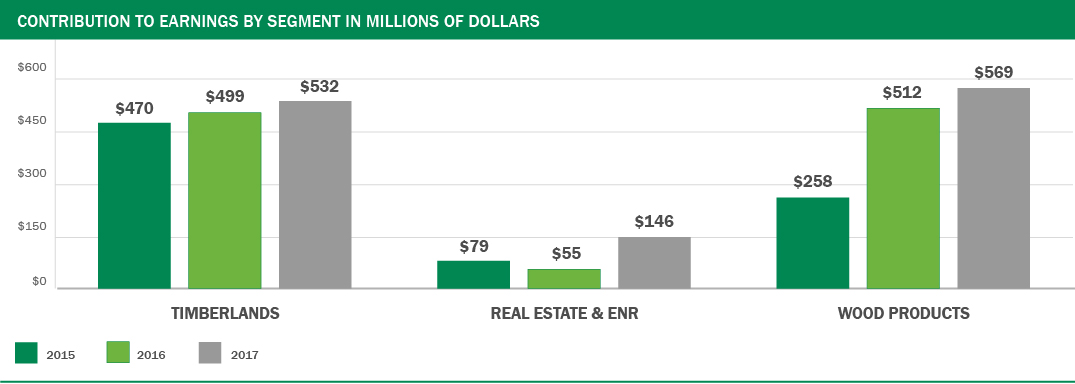
Contribution to Earnings by Segment
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 37
| SOFTWOOD LUMBER AGREEMENT |
We operate a total of 19 softwood lumber mills with a total capacity of 4.9 billion board feet. Three of these mills, located in Canada, produce approximately 900 million board feet annually, and sell products in Canada, Asia, and the U.S.
On April 24, 2017, the U.S. Department of Commerce announced a preliminary determination that it would implement countervailing duties on Canadian softwood lumber shipments to the U.S. The rate applicable to Weyerhaeuser was 19.88 percent and became effective as of April 28, 2017. The U.S. Department of Commerce also announced that retroactive deposits at the 19.88 percent rate would be collected from certain Canadian lumber producers, including Weyerhaeuser, for softwood lumber shipments from Canada to the U.S. during the 90-day period prior to April 28, 2017.
The preliminary countervailing duties were suspended on August 26, 2017, at which time we effectively stopped accruing for the expense. The suspension of the countervailing duties was set to last until the US International Trade Commission reaches its final determination of injury, which was issued December 28, 2017.
On June 26, 2017, the U.S. Department of Commerce announced a preliminary determination that it would implement anti-dumping duties on Canadian softwood lumber shipments to the U.S. The rate applicable to Weyerhaeuser was 6.87 percent and became effective as of June 30, 2017. The U.S. Department of Commerce also announced that retroactive deposits at the 6.87 percent rate would be collected from certain Canadian lumber producers, including Weyerhaeuser, for softwood lumber shipments from Canada to the U.S. during the 90-day period prior to June 30, 2017.
Based on affirmative final determinations by the Department of Commerce (DOC) and the US International Trade Commission (USITC) on December 28, 2017, the DOC issued countervailing duty (CVD) and anti-dumping (AD) duty orders on certain softwood lumber products from Canada.
The CVD rate applicable to Weyerhaeuser is 14.19 percent and will be assessed on entries of softwood lumber from Canada for consumption on or after April 28, 2017, the date of publication of the preliminary determination. It will not include entries occurring after the expiration of the provisional measures period and before publication of the ITC’s final injury determination (CVD suspension date was August 26, 2017 - December 27, 2017).
The AD rate applicable to Weyerhaeuser is 6.04 percent and will be assessed on entries of softwood lumber from Canada for consumption on or after June 30, 2017, the date of publication of the preliminary determination. It will not include entries occurring after the expiration of the provisional measures period, until and through the day preceding the day of publication of the USITC’s final injury determinations in the Federal Register (AD suspension date was December 26, 2017 - January 2, 2018).
For retroactive imposition of CVD and AD duties to apply 90 days prior to the dates of publication of the preliminary determinations, both the USITC and DOC must make a positive determination. The USITC made a negative determination regarding critical circumstances on December 7, 2017. As a result, we reversed the accrual for the retroactive duties for both CVD and AD, which totaled $9 million. Additionally, we reduced our accrual by $2 million related to reduced rate applicable to prospective period duties. As of December 31, 2017, we have expensed CVD and AD duties at the final published rates totaling $7 million.
| RESULTS OF OPERATIONS |
In reviewing our results of operations, it is important to understand these terms:
| • | Sales realizations refer to net selling prices — this includes selling price plus freight minus normal sales deductions. |
| • | Net contribution to earnings refers to earnings (loss) attributable to Weyerhaeuser shareholders before interest expense and income taxes. |
Our merger with Plum Creek during first quarter 2016 significantly affected the comparability of our consolidated operating results between 2016 and prior periods. As a result of progress made to integrate financial processes and systems since the merger date, the results beginning on February 19, 2016, from acquired Plum Creek operations and the respective impacts of these results on our current period results are impracticable to disclose in the year-to-date period ended December 31, 2016. Our prior period results do not include pre-merger results of Plum Creek operations.
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 38
CONSOLIDATED RESULTS
HOW WE DID IN 2017
Summary of Financial Results
| DOLLAR AMOUNTS IN MILLIONS, EXCEPT PER-SHARE FIGURES | |||||||||||||||
| AMOUNT OF CHANGE | |||||||||||||||
| 2017 | 2016 | 2015 | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||
| Net sales | $ | 7,196 | $ | 6,365 | $ | 5,246 | $ | 831 | $ | 1,119 | |||||
| Costs of products sold | $ | 5,298 | $ | 4,980 | $ | 4,153 | $ | 318 | $ | 827 | |||||
| Operating income | $ | 1,131 | $ | 822 | $ | 644 | $ | 309 | $ | 178 | |||||
| Earnings from discontinued operations, net of tax | $ | — | $ | 612 | $ | 95 | $ | (612 | ) | $ | 517 | ||||
| Net earnings attributable to Weyerhaeuser common shareholders | $ | 582 | $ | 1,005 | $ | 462 | $ | (423 | ) | $ | 543 | ||||
| Basic earnings per share attributable to Weyerhaeuser common shareholders | $ | 0.77 | $ | 1.40 | $ | 0.89 | $ | (0.63 | ) | $ | 0.51 | ||||
| Diluted earnings per share attributable to Weyerhaeuser common shareholders | $ | 0.77 | $ | 1.39 | $ | 0.89 | $ | (0.62 | ) | $ | 0.50 |
COMPARING 2017 WITH 2016
Net Sales
Net sales increased $831 million — 13 percent — primarily due to:
| • | Wood Products segment Net sales to unaffiliated customers increased $640 million, primarily attributable to increased sales realizations across all product lines, as well as increased sales volumes within our oriented strand board, engineered I-joists, medium density fiberboard, and our engineered solid section product lines. Additionally, upon completion of the sales of our former Cellulose Fibers businesses, chips previously sold to Cellulose Fibers are now sales to unaffiliated customers. Refer to Note 3: Discontinued Operations and Other Divestitures in the Notes to Consolidated Financial Statements for further details regarding these divestitures. |
| • | Timberlands segment Net sales to unaffiliated customers increased $137 million, which is primarily attributable to increased Southern and Other (includes our Canadian operations and timberlands included in the Twin Creeks Venture) delivered log sales volumes, as well as, an increase in Western log sales prices. |
| • | Real Estate & ENR segment Net sales to unaffiliated customers increased $54 million attributable to an increase in timberlands acres sold in Real Estate and an increase in royalties. |
Costs of Products Sold
Costs of products sold increased $318 million — 6 percent — primarily due to:
| • | Wood Products segment Costs of products sold increased $192 million primarily attributable to an overall increase in sales volumes, as discussed above. This increase was offset by the mix of products sold during 2017 compared to 2016. |
| • | Intercompany eliminations decreased $144 million, therefore increasing our consolidated Cost of products sold. This reduction in intercompany costs of products sold is primarily due to the completion of the divestitures of our former Cellulose Fibers businesses. Prior to the completion of these divestitures the sales and related cost of products sold for chips and logs sold to our Cellulose Fibers businesses were considered intercompany and therefore were not included in our consolidated results. However, subsequent to the divestitures these sales and the related cost of products sold are considered sales to unaffiliated customers and therefore included in our consolidated results. |
These increases were partially offset by a decrease in Real Estate and ENR costs of $24 million, primarily attributable to the mix in properties sold in 2017 compared to 2016.
Operating Income
Operating income increased $309 million — 38 percent — primarily due to:
| • | an increase in consolidated gross margin of $513 million, as described above; |
| • | an increase in "Other operating income, net" of $75 million, which is primarily attributable to: |
| ◦ | a $99 million gain recorded in fourth quarter 2017 as a result of the sale of land in our Southern timberlands region to Twin Creeks (refer to Note 8: Related Parties in the Notes to Consolidated Financial Statements for further details); |
◦a $42 million benefit related to environmental remediation insurance recoveries received in 2017; and
| ◦ | a $44 million decrease in gains on disposition of nonstrategic assets, primarily attributable to a $36 million pretax gain recognized in the first quarter of 2016 on the sale of our Federal Way, Washington headquarters campus (refer to Note 19: Other Operating Costs (Income) in the Notes to Consolidated Financial Statements for further information). |
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 39
These increases were partially offset by the following:
| • | the addition of $290 million in "Charges for product remediation" in 2017, as there were no similar charges during 2016. Refer to Note 18: Charges for Product Remediation in the Notes to Consolidated Financial Statements for further information. |
| • | a $24 million increase in "Charges for integration and restructuring, closures and asset impairments," which is primarily attributable to a $147 million noncash impairment charge recognized during second quarter 2017 in relation to the divestiture of our Uruguayan operations. This was partially offset by a $112 million decrease in charges related to our merger with Plum Creek. Refer to Note 17: Charges for integration and restructurings, closures, and asset impairments in the Notes to Consolidated Financial Statements for further details regarding the impairment as well as the Plum Creek merger related costs. |
Net Earnings Attributable to Weyerhaeuser Common Shareholders
Our Net earnings attributable to Weyerhaeuser common shareholders decreased $423 million — 42 percent — compared to 2016. Excluding "Earnings from discontinued operations, net of tax," Net earnings attributable to Weyerhaeuser common shareholders increased $189 million — 48 percent — primarily due to the increase in Operating income, as explained above. The increases in Operating income were partially offset by a $110 million increase in expense related to "Non-operating pension and other postretirement benefits (costs) credits" due to a decrease in the expected return on our plan assets as well as an increase in the amortization of actuarial losses.
Earnings from discontinued operations, net of tax, decreased $612 million — 100 percent — as all discontinued operations were sold in 2016.
COMPARING 2016 WITH 2015
Net Sales
Net sales increased $1,119 million — 21 percent — primarily due to the following developments:
| • | Timberlands segment sales increased $532 million primarily due to sales from acquired Plum Creek operations. This increase was partially offset by lower average sales realizations. The decrease in average sales realizations is primarily attributable to the increase in sales volume for the South, which has lower average sales realizations compared to the West. The South comprised 31 percent of Timberlands' sales to unaffiliated customers in 2016 compared to 19 percent in 2015. |
| • | Real Estate & ENR segment sales increased $125 million attributable to increased volume of timberland acres sold and increased ENR sales volume attributable to the operations acquired in our merger with Plum Creek. These increases were partially offset by a decrease in average price realized per acre due to geographic mix of properties sold. |
| • | Wood Products segment sales increased $462 million due to increased medium density fiberboard and plywood sales generated from our operations acquired from our merger with Plum Creek and increased oriented strand board and lumber average sales realizations. |
Costs of Products Sold
Costs of products sold increased $827 million — 20 percent — primarily attributable to the following developments:
| • | Timberlands costs of products sold increased $488 million due to increased sales volume as explained above and to higher depletion rates in the South and West for acquired Plum Creek timberlands, which were measured at fair value as of the merger date. |
| • | Real Estate & ENR costs of products sold increased $114 million attributable to increased real estate and ENR sales volume and higher basis of real estate sold, which is a result of measuring acquired Plum Creek properties at fair value as of the February 19, 2016 merger date. |
| • | Wood Products costs of products sold increased $201 million primarily attributable to increased sales volume as explained above. This increase was partially offset by lower log costs and lower manufacturing costs per unit. |
Operating Income
Operating income increased $178 million — 28 percent — primarily due to:
| • | an increase to company-wide gross margin of $292 million as described above; |
| • | a favorable shift in gain on foreign currency remeasurement — $52 million; and |
| • | a gain on the sale of our Federal Way headquarters campus — $36 million. |
These increases were partially offset by:
| • | a $131 million increase in charges for integration and restructuring, closures and asset impairments, primarily attributable to incurring $146 million of costs related to our merger with Plum Creek in 2016 compared to $14 million in 2015; and |
| • | a $76 million increase in selling, general and administrative expenses primarily attributable to merging legacy Weyerhaeuser and Plum Creek operations. |
Net Earnings Attributable to Weyerhaeuser Common Shareholders
Our net earnings attributable to Weyerhaeuser common shareholders increased $543 million — 118 percent — compared to 2015. Earnings from continuing operations before income taxes increased $151 million — 43 percent — due to variances in net sales, costs of products sold and operating income explained above. The increase was offset by a $147 million increase to income taxes from continuing operations resulting from increased taxable earnings generated by our TRSs.
Earnings from discontinued operations, net of tax, increased $517 million — 544 percent — primarily due to:
| • | the after-tax gains recognized from divesting our Cellulose Fibers business in 2016 — $546 million; |
| • | a decrease in the equity loss from our printing papers joint venture — $101 million — primarily attributable to an $84 million noncash asset impairment recorded in fourth quarter 2015; and |
| • | lower costs of products sold, primarily due to lower sales volumes and the cessation of depreciation when Cellulose Fibers manufacturing assets were classified as held-for-sale in second quarter 2016. |
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 40
These increases were partially offset by:
| • | lower average sales realizations for pulp and liquid packaging board; |
| • | lower sales volume for pulp and liquid packaging board attributable to a partial year of operations in 2016 compared to a full year in 2015; and |
| • | increased charges for restructuring, closures and asset impairments and transaction-related costs related to our strategic evaluation and divestiture of the Cellulose Fibers businesses. |
TIMBERLANDS
HOW WE DID IN 2017
We report sales volume and annual production data for our Timberlands segment in Our Business/What We Do/Timberlands.
Net Sales and Net Contribution to Earnings for Timberlands
| DOLLAR AMOUNTS IN MILLIONS | |||||||||||||||
| AMOUNT OF CHANGE | |||||||||||||||
| 2017 | 2016 | 2015 | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||
| Net sales to unaffiliated customers: | |||||||||||||||
| Delivered logs(1): | |||||||||||||||
| West | $ | 915 | $ | 865 | $ | 830 | $ | 50 | $ | 35 | |||||
| South | 616 | 566 | 241 | 50 | 325 | ||||||||||
| North | 95 | 91 | — | 4 | 91 | ||||||||||
| Other | 59 | 38 | 24 | 21 | 14 | ||||||||||
| Total | 1,685 | 1,560 | 1,095 | 125 | 465 | ||||||||||
| Stumpage and pay-as-cut timber | 73 | 85 | 37 | (12 | ) | 48 | |||||||||
| Uruguay operations(2) | 63 | 79 | 87 | (16 | ) | (8 | ) | ||||||||
| Recreational and other lease revenue | 59 | 44 | 25 | 15 | 19 | ||||||||||
| Other products(3) | 62 | 37 | 29 | 25 | 8 | ||||||||||
| Subtotal sales to unaffiliated customers | 1,942 | 1,805 | 1,273 | 137 | 532 | ||||||||||
| Intersegment sales: | |||||||||||||||
| United States | 520 | 590 | 559 | (70 | ) | 31 | |||||||||
| Other | 242 | 250 | 271 | (8 | ) | (21 | ) | ||||||||
| Subtotal intersegment sales | 762 | 840 | 830 | (78 | ) | 10 | |||||||||
| Total | $ | 2,704 | $ | 2,645 | $ | 2,103 | $ | 59 | $ | 542 | |||||
| Costs of products sold | $ | 2,043 | $ | 2,054 | $ | 1,566 | $ | (11 | ) | $ | 488 | ||||
| Operating income and Net contribution to earnings | $ | 532 | $ | 499 | $ | 470 | $ | 33 | $ | 29 | |||||
| (1) The Western region includes Oregon and Washington. The Southern region includes Alabama, Arkansas, Georgia, Florida, Louisiana, Mississippi, North Carolina, Oklahoma, South Carolina, Texas and Virginia. The Northern region includes Maine, Michigan, Montana, New Hampshire, Vermont, West Virginia and Wisconsin. Other includes our Canadian operations and the timberlands of the Twin Creeks Venture that we managed. (Our management agreement for the Twin Creeks Venture began in April 2016 and terminated in December 2017. For additional information see Note 8: Related Parties in Notes to Consolidated Financial Statements.) (2) Sales from our former Uruguayan operations included plywood and hardwood lumber. Our Uruguayan operations were divested on September 1, 2017. Refer to Note 3: Discontinued Operations and Other Divestitures in the Notes to Consolidated Financial Statements for further information on this divestiture. (3) Other products sales include sales of seeds and seedlings from our nursery operations and chips. |
COMPARING 2017 WITH 2016
Net Sales — Unaffiliated Customers
Net sales to unaffiliated customers increased $137 million — 8 percent — primarily due to:
| • | a $50 million increase in Southern log sales attributable to 12 percent increase in delivered logs sales volumes, partially offset by a 3 percent decrease in Southern log prices; |
| • | a $50 million increase in Western log sales attributable to a 12 percent increase in Western log prices, partially offset by a 6 percent decrease in delivered logs sales volumes; |
| • | a $25 million increase in Other products, primarily attributable to increased chips sales to unaffiliated customers (prior to our 2016 divestitures of our Cellulose Fibers businesses, chips sales were primarily intersegment sales); and |
| • | a $21 million increase in Other delivered logs, primarily due to a 55 percent increase in delivered logs sales volumes. |
These increases were partially offset by a $16 million decrease in our Uruguayan operations, primarily attributable to the divestiture that occurred during third quarter 2017. Refer to Note 3: Discontinued Operations and Other Divestitures in the Notes to Consolidated Financial Statements.
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 41
Intersegment Sales
Intersegment sales decreased $78 million — 9 percent — due to a decrease in chip and log intersegment sales, which were previously sold to our former Cellulose Fibers business segment. The businesses within this segment were divested during the second half of 2016. Refer to Note 3: Discontinued Operations and Other Divestitures in the Notes to Consolidated Financial Statements for further information on these divestitures.
Costs of Products Sold
Costs of products sold decreased $11 million — 1 percent — primarily due to:
| • | a $23 million decrease due to the divestiture of our Uruguayan operations in third quarter 2017. Refer to Note 3: Discontinued Operations and Other Divestitures in the Notes to Consolidated Financial Statements for further details. |
| • | a $16 million decrease in the West, attributable to a decrease in delivered logs sales volumes. |
These decreases were partially offset by a $19 million increase in Canada primarily attributable to an increase in delivered logs sales volumes.
Operating Income and Net Contribution to Earnings
Net contribution to earnings increased $33 million — 7 percent — primarily due to:
| • | a $99 million gain recorded in fourth quarter 2017 as a result of the sale of land in our Southern timberlands region to Twin Creeks (refer to Note 8: Related Parties in the Notes to Consolidated Financial Statements for further details), and |
| • | a $70 million increase in gross margin, as explained above. |
These increases were partially offset by a $147 million noncash impairment charge recognized in relation to the divestiture of our Uruguayan operations. Refer to Note 17: Charges for integration and restructuring, closures, and asset impairments in the Notes to Consolidated Financial Statements for further details of this impairment.
COMPARING 2016 WITH 2015
Compared to 2015, the changes to the results of operations for our Timberlands segment during 2016 are primarily attributable to the addition of approximately 6.3 million acres of Plum Creek timberlands, which produced over 18 million tons of harvest volume in 2015. The merger resulted in the expansion of our Southern timberlands from 4.0 million acres to 7.4 million acres — an 85 percent increase — and our Western timberlands from 2.6 to 3.0 million acres — a 15 percent increase. The merger also added 2.5 million acres across Maine, Michigan, Montana, New Hampshire, Vermont, West Virginia and Wisconsin, which we refer to collectively as our Northern timberlands. Increases to sales volume are primarily attributable to the significant increases in the overall size of and harvests from our timberlands holdings by region, particularly in the South and North regions.
The composition of our sales volume by region was also altered by the merger, as the South and North regions, which historically had lower average sales realizations compared to the West, comprise a greater portion of our overall sales subsequent to the merger. Additionally, within the South the acquired timberlands altered the overall sales mix, as lower realization pulpwood sales increased and higher realization grade logs decreased as a percentage of total sales volume, resulting in lower average sales realizations overall for the region in 2016 compared with 2015.
As a result of applying acquisition accounting to our Timber and timberland assets acquired as described in Note 4: Merger with Plum Creek in Notes to Consolidated Financial Statements, depletion rates increased significantly in 2016 compared to 2015. When combined with increased sales volume, these higher depletion rates drove significant increases in our costs of products sold in 2016 compared to 2015.
Net Sales — Unaffiliated Customers
Net sales to unaffiliated customers increased $532 million — 42 percent — primarily due to:
| • | a $325 million increase in Southern log sales as a result of a 146 percent increase in delivered logs sales volume primarily attributable to adding acquired Plum Creek operations, partially offset by a 5 percent decrease in average sales realizations of delivered logs due to mix of sawlogs and pulp logs; |
| • | a $91 million increase in Northern log sales attributable entirely to operations acquired upon our merger with Plum Creek; and |
| • | a $35 million increase in Western log sales as a result of a 6 percent increase in delivered logs sales volume attributable to adding acquired Plum Creek operations, partially offset by a 2 percent decrease in average sales realizations for delivered logs; |
| • | a $48 million increase in stumpage and pay-as-cut timber, which is primarily attributable to adding stumpage sales from acquired Plum Creek timberlands in the South; and |
| • | a $19 million increase in recreational and other lease revenue due entirely to the acquired Plum Creek leases. |
Intersegment Sales
Intersegment sales increased $10 million — 1 percent — due to a $31 million increase in intersegment sales in the United States. This increase is attributable to adding intersegment log sales volume for the Montana operations acquired from Plum Creek. This increase was partially offset by a decrease in average intersegment sales realizations.
The increase in the United States intersegment sales was partially offset by a $21 million decrease in intersegment sales in Canada. This decrease is attributable to lower log and chip sales volume to our former Cellulose Fibers segment as a result of divesting from our pulp mill in Grande Prairie, Alberta. There was also a slight decrease in average intersegment sales realizations compared to 2015.
Costs of Products Sold
Costs of products sold increased $488 million — 31 percent — primarily due to a 78 percent increase in sales volume attributable to the operations acquired in our merger with Plum Creek. Additionally, per unit costs increased due to higher depletion rates in the South and West attributable to acquired Plum Creek timberlands, which were measured at fair value as of the merger date.
Operating Income and Net Contribution to Earnings
Net contribution to earnings increased $29 million — 6 percent — primarily attributable to the changes in net sales and costs of products sold as explained above.
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 42
REAL ESTATE, ENERGY AND NATURAL RESOURCES
HOW WE DID IN 2017
We report acres sold and average price per acre for our Real Estate, Energy and Natural Resources segment in Our Business/What We Do/Real Estate, Energy and Natural Resources.
Net Sales and Net Contribution to Earnings for Real Estate, Energy and Natural Resources
| DOLLAR AMOUNTS IN MILLIONS | |||||||||||||||
| AMOUNT OF CHANGE | |||||||||||||||
| 2017 | 2016 | 2015 | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||
| Net sales to unaffiliated buyers: | |||||||||||||||
| Real estate | $ | 208 | $ | 172 | $ | 75 | $ | 36 | $ | 97 | |||||
| Energy and natural resources | 72 | 54 | 26 | 18 | 28 | ||||||||||
| Subtotal sales to unaffiliated buyers | 280 | 226 | 101 | 54 | 125 | ||||||||||
| Intersegment sales | 1 | 1 | — | — | 1 | ||||||||||
| Total | $ | 281 | $ | 227 | $ | 101 | $ | 54 | $ | 126 | |||||
| Cost of products sold | $ | 110 | $ | 134 | $ | 20 | $ | (24 | ) | $ | 114 | ||||
| Operating income | $ | 145 | $ | 53 | $ | 79 | $ | 92 | $ | (26 | ) | ||||
| Equity earnings (loss) from joint venture | 1 | 2 | — | (1 | ) | 2 | |||||||||
| Net contribution to earnings | $ | 146 | $ | 55 | $ | 79 | $ | 91 | $ | (24 | ) |
The timing of real estate sales is a function of many factors, including:
| • | the general state of the economy, |
| • | demand in local real estate markets, |
| • | the ability to obtain entitlements, |
| • | the ability of buyers to obtain financing, |
| • | the number of competing properties listed for sale, |
| • | the seasonal nature of sales (particularly in the northern states), |
| • | the plans of adjacent landowners, |
| • | our expectations of future price appreciation, |
| • | the timing of harvesting activities, and |
| • | the availability of government and not-for-profit funding (especially for conservation sales). |
In any period, the average sales price per acre will vary based on the location and physical characteristics of parcels sold.
COMPARING 2017 WITH 2016
Net Sales — Unaffiliated Buyers
Net sales to unaffiliated buyers increased $54 million — 24 percent — primarily due to:
| • | a $36 million increase in Net real estate sales primarily attributable to an 18 percent increase in volume of timberlands acres sold. |
| • | an $18 million increase in Net energy and natural resources sales primarily attributable to the increased operations acquired during our merger with Plum Creek. Our 2017 operations include a full twelve months of combined operations as compared to ten months of combined operations in 2016. The increase is further attributable to increases in royalties. |
Costs of Products Sold
Costs of products sold decreased $24 million — 18 percent — primarily due to the mix of properties sold in 2017 compared to 2016.
Net Contribution to Earnings
Net contribution to earnings increased $91 million — 165 percent — primarily due to increased gross margin discussed above. Additionally, our 2016 results include a $15 million asset impairment charge recorded for development projects. No comparable impairment charges were recorded within this segment during 2017.
COMPARING 2016 WITH 2015
Land acquired as a result of our merger with Plum Creek generally carried a higher per acre cost basis compared to our other acreage as a result of measuring acquired land at fair value via acquisition accounting as of the February 19, 2016, merger date. As a result, our costs of timberlands varied period-to-period based on the sales mix between acquired Plum Creek acreage and acreage owned by Weyerhaeuser prior to the merger.
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 43
Net Sales — Unaffiliated Buyers
Net sales to unaffiliated buyers increased $125 million — 124 percent — attributable to the following developments:
| • | Net real estate sales increased $97 million attributable to increases in volume of timberlands acres sold. This increase was partially offset by a decrease in average price realized per acre due to mix of properties sold. |
| • | Net energy and natural resources sales increased $28 million due primarily to increased sales volumes attributable to the operations acquired with our merger with Plum Creek. |
Costs of Products Sold
Costs of products sold increased $114 million — 570 percent — due primarily to:
| • | increased real estate and ENR sales volume, as explained above; |
| • | higher basis of real estate sold resulting from measuring acquired Plum Creek properties at fair value as of the February 19, 2016, merger date; and |
| • | an $11 million increase in commissions and closing costs that corresponds with the increased volume of transactions. |
Net Contribution to Earnings
Net contribution to earnings decreased $24 million — 30 percent — primarily attributable to increased general and administrative expenses of $20 million. The increase in general and administrative expenses is the result of creating a standalone business segment separate from Timberlands and dedicating more staff to the expanded land and natural resource footprint.
WOOD PRODUCTS
HOW WE DID IN 2017
We report sales volume and annual production data for our Wood Products segment in Our Business/What We Do/Wood Products.
Net Sales and Net Contribution to Earnings for Wood Products
| DOLLAR AMOUNTS IN MILLIONS | |||||||||||||||
| AMOUNT OF CHANGE | |||||||||||||||
| 2017 | 2016 | 2015 | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||
| Net sales: | |||||||||||||||
| Structural lumber | $ | 2,058 | $ | 1,839 | $ | 1,741 | $ | 219 | $ | 98 | |||||
| Engineered solid section | 500 | 450 | 428 | 50 | 22 | ||||||||||
| Engineered I-joists | 336 | 290 | 284 | 46 | 6 | ||||||||||
| Oriented strand board | 904 | 707 | 595 | 197 | 112 | ||||||||||
| Softwood plywood | 176 | 174 | 129 | 2 | 45 | ||||||||||
| Medium density fiberboard | 183 | 158 | — | 25 | 158 | ||||||||||
| Other products produced (1) | 276 | 201 | 189 | 75 | 12 | ||||||||||
| Complementary building products | 541 | 515 | 506 | 26 | 9 | ||||||||||
| Total | $ | 4,974 | $ | 4,334 | $ | 3,872 | $ | 640 | $ | 462 | |||||
| Costs of products sold | $ | 3,880 | $ | 3,688 | $ | 3,487 | $ | 192 | $ | 201 | |||||
| Operating income and Net contribution to earnings | $ | 569 | $ | 512 | $ | 258 | $ | 57 | $ | 254 | |||||
| (1) Includes wood chips and other byproducts. |
COMPARING 2017 WITH 2016
Net Sales
Net sales increased $640 million — 15 percent — primarily due to:
| • | a $219 million increase in structural lumber sales, attributable to a 13 percent increase in average sales realizations, partially offset by a 1 percent decrease in sales volumes; |
| • | a $197 million increase in oriented strand board sales, attributable to a 26 percent increase in average sales realizations as well as a 1 percent increase in sales volumes; |
| • | a $75 million increase in other products produced, primarily attributable to increased chip sales. Chips were previously sold to our former Cellulose Fibers segment and were therefore considered intersegment sales until the sale of our Cellulose Fibers businesses which occurred in the second half of 2016. Upon completion of these divestitures, chips sold to those businesses were considered sales to unaffiliated customers. (Refer to Note 3: Discontinued Operations and Other Divestitures in the Notes to Consolidated Financial Statements for further details regarding these divestitures.); |
| • | a $50 million increase in engineered solid section, primarily attributable to an 8 percent increase in sales volumes as well as a 3 percent increase in average sales realizations; and |
| • | a $46 million increase in engineered I-joists, primarily attributable to a 13 percent increase in sales volume as well as a 3 percent increase in average sales realizations. |
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 44
Costs of Products Sold
Costs of products sold increased $192 million — 5 percent — primarily attributable to an overall increase in sales volumes, as discussed above. This increase was offset by the mix of products sold during 2017 compared to 2016.
Operating Income and Net Contribution to Earnings
Operating income and Net contribution to earnings increased $57 million — 11 percent — primarily due to increased gross margin, as discussed above. This was partially offset by:
| • | The $290 million addition of "Charges for product remediation" in 2017, as there were no similar charges during 2016 (refer to Note 18: Charges for Product Remediation in the Notes to Consolidated Financial Statements for further information); |
| • | A $68 million decrease in intersegment sales in 2017 compared to 2016, which is primarily attributable to decreased intersegment chip sales. Prior to our divestitures of our former Cellulose Fibers business, which occurred in the second half of 2016, chips sold to these businesses were considered intersegment sales. Upon completion of these divestitures, chips sold to our former Cellulose Fibers businesses were considered sales to unaffiliated customers. |
| • | A $7 million increase in "Other operating costs, net," related to countervailing and anti-dumping duties. Refer to Softwood Lumber Agreement for further information regarding these regulations. |
| • | A $6 million impairment on nonstrategic assets recognized during third quarter 2017. Refer to Note 17: Charges for Integration and Restructuring, Closures and Asset Impairments in the Notes to Consolidated Financial Statements for further detail. |
COMPARING 2016 WITH 2015
Upon our merger with Plum Creek, we acquired five manufacturing facilities in Montana. The sales and net contribution to earnings of these facilities as of the merger date are included in the results of our Wood Products segment. The results of the plywood facilities are reported in softwood plywood and the lumber facilities are reported in structural lumber.
The Medium Density Fiberboard (MDF) facility supplies high-quality MDF to a wide range of customers throughout North America. Some of the more common uses for our MDF include furniture and cabinet components, architectural moldings, doors, store fixtures, core material for hardwood plywood, face material for softwood plywood, commercial wall paneling and substrate for laminate flooring.
We permanently closed two of the five acquired Plum Creek mills, the lumber facility and softwood plywood facility in Columbia Falls, Montana, during third quarter 2016. The closure of these facilities allows us to align the available log supply with our manufacturing capacity, including adding shifts at our Kalispell, Montana facilities, to position our Montana operations for long-term success.
Refer to Note 4: Merger with Plum Creek in Notes to Consolidated Financial Statements for further information regarding our merger with Plum Creek.
Net Sales
Net sales increased $462 million — 12 percent — primarily due to:
| • | a $158 million increase in medium density fiberboard sales generated from operations acquired in our merger with Plum Creek; |
| • | a $112 million increase in oriented strand board sales, attributable primarily to a 21 percent increase in average sales realizations; |
| • | a $98 million increase in lumber sales, attributable to a 3 percent increase in average sales realizations and a 3 percent increase in sales volume; and |
| • | a $45 million increase in plywood sales, attributable to a 9 percent increase in average sales realizations and a 26 percent increase in sales volume, with the volume increase due in part to acquired Plum Creek operations. |
Costs of Products Sold
Costs of products sold increased $201 million — 6 percent — primarily due to increased sales volume across most product lines and from added volumes produced and sold by the manufacturing operations acquired from our merger with Plum Creek. This increase is partially offset by lower log costs and lower manufacturing costs per unit.
Operating Income and Net Contribution to Earnings
Net contribution to earnings increased $254 million — 98 percent — primarily attributable to the changes in net sales and costs of products sold, as explained above.
UNALLOCATED ITEMS
Unallocated Items are gains or charges from continuing operations not related to or allocated to an individual operating segment. They include a portion of items such as: share-based compensation, pension and postretirement costs, foreign exchange transaction gains and losses associated with financing, and the elimination of intersegment profit in inventory, equity earnings from our Timberland Venture and the LIFO reserve. As a result of reclassifying our former Cellulose Fibers segment as discontinued operations, Unallocated Items also includes retained indirect corporate overhead costs previously allocated to the former segment.
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 45
Net Contribution to Earnings for Unallocated Items
| DOLLAR AMOUNTS IN MILLIONS | |||||||||||||||
| AMOUNT OF CHANGE | |||||||||||||||
| 2017 | 2016 | 2015 | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||
| Unallocated corporate function expenses | $ | (73 | ) | $ | (87 | ) | $ | (64 | ) | $ | 14 | $ | (23 | ) | |
| Unallocated share-based compensation | (9 | ) | (3 | ) | 6 | (6 | ) | (9 | ) | ||||||
| Unallocated pension service costs | (4 | ) | (5 | ) | (3 | ) | 1 | (2 | ) | ||||||
| Foreign exchange gains (losses) | 1 | 6 | (46 | ) | (5 | ) | 52 | ||||||||
| Elimination of intersegment profit in inventory and LIFO | (20 | ) | (18 | ) | 8 | (2 | ) | (26 | ) | ||||||
| Gain (loss) from sales of nonstrategic assets | 9 | 50 | 6 | (41 | ) | 44 | |||||||||
| Charges for integration and restructuring, closures and asset impairments: | |||||||||||||||
| Plum Creek merger-and integration-related costs | (34 | ) | (146 | ) | (14 | ) | 112 | (132 | ) | ||||||
| Other restructuring, closures, and asset impairments | — | (2 | ) | (15 | ) | 2 | 13 | ||||||||
| Other | 15 | (37 | ) | (41 | ) | 52 | 4 | ||||||||
| Operating income (loss) | $ | (115 | ) | $ | (242 | ) | $ | (163 | ) | $ | 127 | $ | (79 | ) | |
| Equity earnings from joint venture(1) | — | 20 | — | (20 | ) | 20 | |||||||||
| Non-operating pension and other postretirement benefit (costs) credits | (62 | ) | 48 | 14 | (110 | ) | 34 | ||||||||
| Interest income and other | 39 | 43 | 36 | (4 | ) | 7 | |||||||||
| Net contribution to earnings | $ | (138 | ) | $ | (131 | ) | $ | (113 | ) | $ | (7 | ) | $ | (18 | ) |
| (1) 2016 includes equity earnings from our Timberland Venture, which effective August 31, 2016, is consolidated as a wholly-owned subsidiary. |
Unallocated Items in 2017 include:
| • | an increase in expense related to "Non-operating pension and other postretirement benefits (costs) credits" due to a decrease in the expected return on our plan assets as well as an increase in the amortization of actuarial losses — $110 million; |
| • | a benefit in Other primarily related to environmental remediation insurance recoveries received in 2017 — $42 million; and |
| • | decreased charges recognized in 2017 related to our merger with Plum Creek (refer to Note 17: Charges for Integration and Restructuring, Closures and Asset Impairments in Notes to Consolidated Financial Statements) — $112 million. |
Unallocated Items in 2016 include:
| • | charges recognized in 2016 related to our merger with Plum Creek (refer to Note 17: Charges for Integration and Restructuring, Closures and Asset Impairments in Notes to Consolidated Financial Statements) — $146 million; |
| • | an increase in unallocated corporate function expenses primarily as a result of retaining costs allocated to our former Cellulose Fibers segment — $23 million; and |
| • | a gain related to the sale of our Federal Way, Washington headquarters campus, which is recorded in "Other operating costs (income), net" in our Consolidated Statement of Operations – $36 million. |
Unallocated Items in 2015 include:
| • | $13 million noncash impairment charge recognized in first quarter 2015 related to a nonstrategic asset that was sold in second quarter 2015 which is recorded in "Charges for integration and restructuring, closures and asset impairments" in our Consolidated Statement of Operations. See Note 17: Charges for Integration and Restructuring, Closures and Asset Impairments in the Notes to Consolidated Financial Statements for more information. |
| • | $14 million Plum Creek merger-related costs which are recorded in "Charges for integration and restructuring, closures and asset impairments" in our Consolidated Statement of Operations. |
INTEREST EXPENSE
Our net interest expense incurred for the last three years was:
| • | $393 million in 2017, |
| • | $431 million in 2016 and |
| • | $341 million in 2015. |
The primary factor driving the $38 million decrease in interest expense in 2017 as compared to 2016 is the decrease in our average indebtedness throughout the year.
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 46
INCOME TAXES
As a REIT, we generally are not subject to federal corporate level income taxes on REIT taxable income that is distributed to shareholders. Historical distributions to shareholders, including amounts and tax characteristics, for the years ended December 31 are summarized in the table below.
| AMOUNTS PER SHARE | |||||||||
| 2017 | 2016 | 2015 | |||||||
| Preference - capital gain distribution | $ | — | $ | 1.59 | $ | 3.19 | |||
| Common - capital gain distribution | $ | 1.25 | $ | 1.24 | $ | 1.20 |
The table below summarizes the items of tax preference for alternative minimum tax (AMT) purposes which have been apportioned to shareholders for the years ended December 31.
| AMOUNTS PER SHARE | |||||||||
| 2017 | 2016 | 2015 | |||||||
| Preference - AMT | $ | — | $ | 0.0120 | $ | — | |||
| Common - AMT | $ | 0.0097 | $ | 0.0094 | $ | — |
We are required to pay corporate income taxes on earnings of our TRSs, which includes our Wood Products segment and portions of our Timberlands and Real Estate & ENR segments' earnings. Our provision for income taxes is primarily driven by earnings generated by our TRSs. Overall performance results for our business segments can be found in Results of Operations/Timberlands, Results of Operations/Real Estate, Energy and Natural Resources, and Results of Operations/Wood Products.
On December 22, 2017, H.R. 1, commonly known as the Tax Cuts and Jobs Act (the "Tax Act"), was enacted. The Tax Act contains significant changes to corporate taxation, including the reduction of the corporate tax rate from 35 percent to 21 percent, increased deductions for capital spending and limitations on interest expense deductions. The Tax Act does not affect our REIT status or the provisions that allow us to pay capital gain dividends to our shareholders.
As a result of the reduction in the corporate tax rate, we have revalued our deferred tax assets and liabilities and have recorded a tax expense of $74 million during 2017, which reduced our net deferred tax asset.
For 2018, we expect our effective tax rate will be between 11 percent and 13 percent. The estimated range is based on current assumptions with respect to our earnings and the Tax Act. Our actual effective tax rate in 2018 may differ. The reduced effective tax rate is expected to result in overall lower tax expense beginning in 2018.
Our provision (benefit) for income taxes for our continuing operations over the last three years was:
| • | $134 million in 2017, |
| • | $89 million in 2016 and |
| • | $(58) million in 2015. |
During 2017, we recorded a $22 million tax benefit related to the repatriation of Canadian earnings.
During 2016, we recorded a $24 million tax charge related to the repatriation of Canadian earnings.
During 2015, we recorded a $13 million tax benefit for the expiration of the company’s built-in-gains tax period due to a change in tax law in the fourth quarter 2015.
See also Note 20: Income Taxes in Notes to Consolidated Financial Statements, which outlines the major components related to our income tax provision.
| LIQUIDITY AND CAPITAL RESOURCES |
We are committed to maintaining an appropriate capital structure that enables us to:
| • | protect the interests of our shareholders and lenders and |
| • | have access to major financial markets. |
CASH FROM OPERATIONS
Consolidated net cash provided by our operations was:
| • | $1,201 million in 2017, |
| • | $735 million in 2016 (includes continuing and discontinued operations) and |
| • | $1,075 million in 2015 (includes continuing and discontinued operations). |
COMPARING 2017 WITH 2016
Net cash provided by our operations increased $466 million, primarily due to:
| • | increased cash flows from business segments of $499 million; |
| • | a decrease in cash paid for income taxes of $316 million, which is primarily attributable to taxes paid in connection with our divestitures of our former Cellulose Fibers businesses during 2016; and |
| • | a decrease in cash paid for interest of $65 million corresponding with our decreased average indebtedness during 2017 compared to 2016. |
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 47
These items were partially offset by:
| • | decreased operating cash flows from discontinued operations of $196 million; and |
| • | an increase of $192 million in cash used for product remediation efforts (refer to Note 18: Charges for Product Remediation in the Notes to Consolidated Financial Statements). |
Also see Performance Measures for our Adjusted EBITDA by segment.
COMPARING 2016 WITH 2015
Net cash provided by our continuing and discontinued operations decreased $340 million, primarily due to:
| • | an increase in cash paid for income taxes of $471 million largely due to taxes paid in connection with our Cellulose Fibers businesses; |
| • | decreased operating cash flows from discontinued operations of $233 million; |
| • | an increase in cash paid for interest of $99 million corresponding with our increased average indebtedness; and |
| • | cash payments made in 2016 related to the Plum Creek merger of $154 million, comprised of: |
| ◦ | termination benefits — $33 million; |
| ◦ | investment banking and other professional services fees — $52 million; |
| ◦ | settlement of Value Management Awards — $6 million; |
| ◦ | pension and postretirement benefits — $38 million; and |
| ◦ | other merger-related costs — $14 million. |
Pension Contributions and Benefit Payments Made and Expected
During 2017, we:
| • | contributed $25 million for our Canadian registered plan in accordance with minimum funding rules and respective provincial regulations; |
| • | contributed to or made benefit payments for our Canadian nonregistered pension plans of $2 million; |
| • | made benefit payments of $31 million for our U.S. nonqualified pension plans; and |
| • | made benefit payments of $20 million for our U.S. and Canadian other postretirement plans. |
There was no minimum required contribution for our U.S. qualified plan for 2017, nor were any contributions made to this plan in 2017.
During 2018, based on estimated year-end assets and projections of plan liabilities, we expect to:
| • | be required to contribute approximately $23 million for our Canadian registered plan; |
| • | be required to contribute or make benefit payments for our Canadian nonregistered plans of $4 million; |
| • | make benefit payments of $19 million for our U.S. nonqualified pension plans; and |
| • | make benefit payments of $19 million for our U.S. and Canadian other postretirement plans. |
We do not anticipate being required to make a contribution to our U.S. qualified pension plan for 2018.
INVESTING IN OUR BUSINESS
Cash from investing activities includes:
| • | acquisitions of property, equipment, timberlands and reforestation; |
| • | investments in or distribution from equity affiliates; |
| • | proceeds from sale of assets and operations; and |
| • | purchases and redemptions of short-term investments. |
Consolidated net cash provided by (used in) investing activities was:
| • | $367 million in 2017, |
| • | $2,559 million in 2016 (includes continuing and discontinued operations) and |
| • | $(487) million in 2015 (includes continuing and discontinued operations). |
COMPARING 2017 WITH 2016
Net cash from investing activities decreased $2.2 billion primarily due to:
| • | a $2.1 billion decrease in net proceeds from the disposition of discontinued and other operations, primarily attributable to the proceeds received from the divestitures of our Cellulose Fibers businesses in 2016 — $2.5 billion — compared to the proceeds received for the divestiture of our Uruguayan operations —$403 million (refer to Note 3: Discontinued Operations and Other Divestitures in the Notes to Consolidated Financial Statements for further details); |
| • | a decrease of $440 million in proceeds received for our contribution of timberlands to Twin Creeks Venture in 2016 (refer to Note 8: Related Parties in the Notes to Consolidated Financial Statements for further details); and |
| • | a decrease of $78 million in proceeds from sales of nonstrategic assets. |
This activity was partially offset by:
| • | $311 million in combined proceeds from the sale of land in our Southern timberlands region to Twin Creeks as well as the redemption of our ownership interest in Twin Creeks, both of which occurred during fourth quarter 2017 (refer to Note 8: Related Parties in the Notes to Consolidated Financial Statements for further details); |
| • | a $91 million decrease in capital expenditures primarily attributable to the divestiture of our Cellulose Fibers business in 2016. |
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 48
COMPARING 2016 WITH 2015
Net cash from investing activities changed $3.0 billion to an inflow in 2016 as compared with an outflow in 2015, primarily due to:
| • | net proceeds from the divestitures of our Cellulose Fibers businesses in 2016 — $2.5 billion; |
| • | proceeds received for our contribution of timberlands to the Twin Creeks Venture in 2016 — $440 million; |
| • | proceeds from sales of nonstrategic assets — $104 million; and |
| • | distributions received from joint ventures during 2016 — $46 million. |
Three-Year Summary of Capital Spending by Business Segment
| DOLLAR AMOUNTS IN MILLIONS | |||||||||
| 2017 | 2016 | 2015 | |||||||
| Timberlands | $ | 115 | $ | 116 | $ | 75 | |||
| Real Estate & ENR | 2 | 1 | — | ||||||
| Wood Products | 299 | 297 | 287 | ||||||
| Unallocated Items | 3 | 11 | 3 | ||||||
| Discontinued operations | — | 85 | 118 | ||||||
| Total | $ | 419 | $ | 510 | $ | 483 |
We expect our net capital expenditures for 2018 to be $420 million, which is comparable to 2017 capital spend. The amount we spend on capital expenditures could change due to:
| • | future economic conditions, |
| • | environmental regulations, |
| • | changes in the composition of our business, |
| • | weather and |
| • | timing of equipment purchases. |
FINANCING
Cash from financing activities includes:
| • | issuances and payments of debt, |
| • | borrowings and payments under revolving lines of credit, |
| • | proceeds from stock offerings and option exercises and |
| • | payments for cash dividends and repurchasing stock. |
Consolidated net cash used in financing activities was:
| • | $1,420 million in 2017, |
| • | $3,630 million in 2016 (includes continuing and discontinued operations) and |
| • | $1,156 million in 2015 (includes continuing and discontinued operations). |
COMPARING 2017 WITH 2016
Net cash used in financing activities decreased $2,210 million in 2017, primarily due to the following:
| • | a decrease of $2,003 million related to cash used to repurchase common shares during 2016; and |
| • | a decrease of $1,592 million in cash used for payments on long-term debt. |
This activity was partially offset by a $1,473 million decrease in cash received from the issuance of new long-term debt.
COMPARING 2016 WITH 2015
Net cash used in financing activities increased $2,474 million in 2016, primarily due to:
| • | a $1,485 million increase in repurchase shares; |
| • | payment of $720 million of the debt assumed in our merger with Plum Creek on the merger date; and |
| • | a $313 million increase in dividends paid to common shareholders. |
LONG-TERM DEBT
Our consolidated long-term debt (including current portion) was:
| • | $6.0 billion as of December 31, 2017, |
| • | $6.6 billion as of December 31, 2016, and |
| • | $4.8 billion as of December 31, 2015. |
The decrease in our long-term debt during 2017 is attributable to the following activity:
| • | We prepaid a $550 million variable-rate term loan during July 2017, which was originally set to mature in 2020 (2020 term loan). The 2020 term loan was prepaid using available cash of $325 million as well as borrowing proceeds from a new $225 million variable-rate term loan set to mature in 2026. |
| • | We paid our $281 million 6.95 percent debenture during August 2017. |
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 49
The increase in our long-term debt during 2016 is attributable to the following activity:
| • | We assumed $3.4 billion of long-term debt during our merger with Plum Creek. Immediately following the merger, we paid $720 million of the debt assumed. (Refer to Note 4: Merger with Plum Creek in Notes to Consolidated Financial Statements for further information about our merger). |
| • | As part of our Cellulose Fibers Pulp business divestiture, $88 million of long-term debt was assumed by International Paper. (Refer to Note 3: Discontinued Operations and Other Divestitures in Notes to Consolidated Financial Statements for further information about our Cellulose Fibers divestitures). |
We have $62 million of long-term debt scheduled to mature during first quarter 2018.
See Note 12: Long-Term Debt in the Notes to Consolidated Financial Statements for more information about the long-term debt discussed above.
Refer to Note 8: Related Parties in the Notes to Consolidated Financial Statements for information regarding the nonrecourse debt held by our Variable Interest Entities (VIEs).
2016 TERM LOAN PAYMENT AND EXTINGUISHMENT
During February 2016, and subsequent to completion of the Plum Creek merger, we entered into a $600 million 18-month senior unsecured term loan maturing in August 2017. Borrowings were at LIBOR plus 1.05 percent. The $600 million outstanding under this facility was repaid in full and terminated during fourth quarter 2016.
During March 2016, we entered into a $1.9 billion 18-month senior unsecured term loan maturing in September 2017. Borrowings were at LIBOR plus 1.05 percent. The remaining $1.1 billion outstanding under this facility was repaid in full and terminated during fourth quarter 2016.
REVOLVING CREDIT FACILITIES
During March 2017, we entered into a new $1.5 billion five-year senior unsecured revolving credit facility that expires in March 2022. This replaced a $1 billion senior unsecured revolving credit facility that was set to expire September 2018. The entire amount is available to Weyerhaeuser Company. Borrowings are at LIBOR plus a spread or at other interest rates mutually agreed upon between the borrower and the lending banks. As of December 31, 2017 and December 31, 2016, there were no borrowings outstanding under the facility and we were in compliance with the credit facility covenants.
Debt covenants:
As of December 31, 2017, Weyerhaeuser Company:
| • | had no borrowings outstanding under our credit facility and |
| • | was in compliance with the credit facility covenants. |
Weyerhaeuser Company Covenants:
Key covenants related to Weyerhaeuser Company include the requirement to maintain:
| • | a minimum total adjusted shareholders' equity of $3.0 billion; and |
| • | a defined funded debt ratio of 65 percent or less. |
Weyerhaeuser Company’s total adjusted shareholders' equity is comprised of:
| • | total Weyerhaeuser shareholders’ equity, |
| • | excluding accumulated comprehensive income (loss), |
| • | minus Weyerhaeuser Company’s investment in our unrestricted subsidiaries. |
Total Weyerhaeuser Company capitalization is comprised of:
| • | total Weyerhaeuser Company debt |
| • | plus total adjusted shareholders' equity. |
As of December 31, 2017, Weyerhaeuser Company had:
| • | a defined total adjusted shareholders' equity of $10.4 billion and |
| • | a defined debt-to-total-capital ratio of 36.65 percent. |
Debt agreements that were assumed by Weyerhaeuser in the merger with Plum Creek were amended to materially conform key covenants with the covenants described above.
When calculating compliance in accordance with financial debt covenants as of December 31, 2016, we excluded the impact of our pension and other postretirement plans recorded within cumulative other comprehensive income from adjusted shareholders' interest (equity). The excluded amount at December 31, 2016, was $1,698 million, which is equal to the cumulative actuarial losses and prior service costs for our pension and postretirement plans. When calculating compliance in accordance with financial debt covenants as of December 31, 2017, we excluded the full amount of cumulative other comprehensive loss of $1,562 million. See Note 15: Shareholders' Interest in the Notes to Consolidated Financial Statements.
There are no other significant financial debt covenants related to our third-party debt. See Note 11: Lines of Credit in the Notes to Consolidated Financial Statements for more information.
CREDIT RATINGS
Upon completion of our merger with Plum Creek on February 19, 2016, S&P changed our long-term issuer credit ratings from BBB to BBB-. However, on May 9, 2017, S&P upgraded our long-term issuer credit ratings from BBB- back to BBB.
On April 14, 2015, Moody's Investors Service upgraded our long-term issuer credit ratings from Baa3 to Baa2. There was no change to our Moody's rating as a result of completing the merger with Plum Creek.
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 50
OPTION EXERCISES
Our cash proceeds from the exercise of stock options were:
| • | $128 million in 2017, |
| • | $61 million in 2016 and |
| • | $34 million in 2015. |
Our average stock price was $33.61, $30.01 and $31.67 in 2017, 2016 and 2015, respectively.
DIVIDENDS
We paid cash dividends on common shares of:
| • | $941 million in 2017, |
| • | $932 million in 2016 and |
| • | $619 million in 2015. |
Changes in the amount of dividends we paid were primarily due to:
| • | an increase in our quarterly dividend from 31 cents per share to 32 cents per share in November 2017; |
| • | an increase in our quarterly dividend from 29 cents per share to 31 cents per share in August 2015; and |
| • | an increase in the number of common shares outstanding during 2016, which was primarily attributable to the 278,886,704 shares issued as consideration in our merger with Plum Creek on February 19, 2016, offset by our subsequent repurchase of 67,816,810 shares between March 2016 and July 2016. |
We paid cash dividends on preference shares of $22 million in 2016 and $44 million in 2015. As all preference shares were converted to common shares on July 1, 2016, we did not pay any cash dividends on preference shares during 2017. See Note 15: Shareholders' Interest in the Notes to Consolidated Financial Statements for more information.
Our dividends declared on preference shares were 79.69 cents per share in:
| • | February and May 2016; and |
| • | February, May, August and October 2015. |
On February 9, 2018, our board of directors declared a dividend of 32 cents per share, payable on March 23, 2018, to shareholders of record at the close of business March 2, 2018.
STOCK REPURCHASES
On August 13, 2014, our board of directors approved a stock repurchase program under which we were authorized to repurchase up to $700 million of outstanding shares (the 2014 Repurchase Program). The 2014 Repurchase Program replaced the prior 2011 stock repurchase program. During 2014, we repurchased 6,062,993 shares of common stock for $203 million under the 2014 Repurchase Program. During 2015 we completed the 2014 Repurchase Program by repurchasing 15,471,962 shares of common stock for $497 million. All common stock purchases under the stock repurchase program were made in open-market transactions.
On August 27, 2015, our board of directors approved a new share repurchase program of up to $500 million of outstanding shares (the 2015 Repurchase Program), commencing upon completion of the 2014 Repurchase Program. During 2015, we repurchased 717,464 shares of common stock for $22 million under the 2015 Repurchase Program. As of December 31, 2015, we had remaining authorization of $478 million for future stock repurchases. All common stock purchases under the stock repurchase program were made in open-market transactions.
The 2016 Share Repurchase Authorization was approved in November 2015 by our Board of Directors and authorized management to repurchase up to $2.5 billion of outstanding shares subsequent to the closing of our merger with Plum Creek (the 2016 Repurchase Program). This new authorization replaced the August 2015 share repurchase authorization. During 2016, we repurchased 67,816,810 shares of common stock for $2 billion under the 2016 Repurchase Program. We did not repurchase any shares of common stock during 2017. As of December 31, 2017, we had remaining authorization of $500 million for future stock repurchases. All common stock purchases under the stock repurchase program were made in open-market transactions. We had 755,223 thousand shares of common stock outstanding as of December 31, 2017.
OUR CONTRACTUAL OBLIGATIONS AND COMMERCIAL COMMITMENTS
More details about our contractual obligations and commercial commitments are in Note 9: Pension and Other Postretirement Benefit Plans, Note 12: Long-Term Debt, Note 14: Legal Proceedings, Commitments and Contingencies and Note 20: Income Taxes in the Notes to Consolidated Financial Statements.
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 51
Significant Contractual Obligations as of December 31, 2017
| DOLLAR AMOUNTS IN MILLIONS | |||||||||||||||
| PAYMENTS DUE BY PERIOD | |||||||||||||||
| TOTAL | LESS THAN 1 YEAR | 1–3 YEARS | 3–5 YEARS | MORE THAN 5 YEARS | |||||||||||
| Long-term debt obligations, including current portion(1) (Note 12) | $ | 5,956 | $ | 62 | $ | 500 | $ | 719 | $ | 4,675 | |||||
| Interest(2) | 3,023 | 362 | 678 | 586 | 1,397 | ||||||||||
| Operating lease obligations | 324 | 40 | 67 | 56 | 161 | ||||||||||
| Purchase obligations(3) | 53 | 50 | 3 | — | — | ||||||||||
| Employee-related obligations(4) | 416 | 140 | 50 | 32 | 89 | ||||||||||
| Liabilities related to unrecognized tax benefits (Note 20)(5) | 4 | — | — | — | — | ||||||||||
| Total | $ | 9,776 | $ | 654 | $ | 1,298 | $ | 1,393 | $ | 6,322 | |||||
| (1) Does not include nonrecourse debt held by our Variable Interest Entities (VIEs). See Note 8: Related Parties in the Notes to Consolidated Financial Statements for further information on our VIEs and the related nonrecourse debt. (2) Amounts presented for interest payments assume that all long-term debt obligations outstanding as of December 31, 2017, will remain outstanding until maturity, and interest rates on variable-rate debt in effect as of December 31, 2017, will remain in effect until maturity. (3) Purchase obligations include agreements to purchase goods or services that are enforceable and legally binding on the company and that specify all significant terms, including: fixed or minimum quantities to be purchased; fixed, minimum or variable price provisions; and the approximate timing of the transaction. Purchase obligations exclude arrangements that the company can cancel without penalty. (4) The timing of certain of these payments will be triggered by retirements or other events. These payments can include workers' compensation, deferred compensation and banked vacation, among other obligations. When the timing of payment is uncertain, the amounts are included in the total column only. Minimum pension funding is required by established funding standards and estimates are not made beyond 2018. Estimated payments of contractually obligated postretirement benefits are not included due to the uncertainty of payment timing. (5) We have recognized total liabilities related to unrecognized tax benefits of $4 million as of December 31, 2017. The timing of payments related to these obligations is uncertain; however, none of this amount is expected to be paid within the next year. |
| OFF-BALANCE SHEET ARRANGEMENTS |
Off-balance sheet arrangements have not had — and are not reasonably likely to have — a material effect on our current or future financial condition, results of operations or cash flows. Note 8: Related Parties and Note 11: Lines of Credit in the Notes to Consolidated Financial Statements contain our disclosures of:
| • | surety bonds, |
| • | letters of credit and guarantees and |
| • | information regarding variable interest entities. |
| ENVIRONMENTAL MATTERS, LEGAL PROCEEDINGS AND OTHER CONTINGENCIES |
See Note 14: Legal Proceedings, Commitments and Contingencies in the Notes to Consolidated Financial Statements.
| ACCOUNTING MATTERS |
CRITICAL ACCOUNTING POLICIES
In the preparation of our financial statements we follow established accounting policies and make estimates that affect both the amounts and timing of the recording of assets, liabilities, revenues and expenses. Some of these estimates require judgments about matters that are inherently uncertain. Accounting policies whose application may have a significant effect on the reported results of operations and financial position are considered critical accounting policies.
In accounting, we base our judgments and estimates on:
| • | historical experience and |
| • | assumptions we believe are appropriate and reasonable under current circumstances. |
Actual results, however, may differ from the estimated amounts we have recorded.
Our most critical accounting policies relate to our:
| • | pension and postretirement benefit plans; |
| • | potential impairments of long-lived assets; |
| • | legal, environmental and product liability reserves; |
| • | timber depletion; and |
| • | business combinations. |
Details about our other significant accounting policies — what we use and how we estimate — are in Note 1: Summary of Significant Accounting Policies in the Notes to Consolidated Financial Statements.
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 52
PENSION AND POSTRETIREMENT BENEFIT PLANS
We sponsor several pension and postretirement benefit plans for our employees. Key assumptions we use in accounting for the plans include our:
| • | expected long-term rate of return on plan assets and |
| • | discount rates. |
At the end of every year, we review our assumptions with external advisers and make adjustments as appropriate. We use these assumptions to calculate liability information as of yearend and pension and post retirement expense for the following year. Actual experience that differs from our assumptions or any changes in our assumptions could have a significant effect on our financial position, results of operations and cash flows.
Other factors that affect our accounting for the plans include:
| • | actual pension fund performance, |
| • | level of lump sum distributions, |
| • | plan changes and amendments, |
| • | portfolio changes and restructuring, |
| • | anticipated trends in health care costs, |
| • | assumed increases in salaries and |
| • | mortality rates. |
This section provides more information about our:
| • | expected long-term rate of return and |
| • | discount rates. |
Expected Long-Term Rate of Return on Plan Assets
Plan assets are assets of the pension plan trusts that fund the benefits provided under the pension plans. The expected long-term rate of return is our estimate of the long-term rate of return that our plan assets will earn. Our expected long-term rate of return is important in determining the net periodic benefit or cost we recognize for our plans.
Over the 33 years it has been in place, our U.S. pension trust investment strategy has achieved a 13.7 percent net compound annual return rate.
After considering available information at the end of 2016, we determined that it was appropriate to reduce our assumption of long-term rate of return on plan assets used in determining net periodic benefit cost from 9.0 percent for the year ended December 31, 2016, to 8.0 percent for the year ended December 31, 2017. Based on the information available at the end of 2017, we determined that it is appropriate to continue to use the 8.0 percent return on plan assets assumption during 2018.
Factors we considered include:
| • | the net compounded annual return of over 8 percent achieved by our U.S. pension trust investment strategy the past 5 years and |
| • | current and expected valuation levels in the global equity and credit markets. |
Our expected long-term rate of return is important in determining the net periodic benefit or cost we recognize for our plans. Every 50 basis point decrease in our expected long-term rate of return would increase expense or reduce a credit by approximately:
| • | $22 million for our U.S. qualified pension plans and |
| • | $5 million for our Canadian registered pension plans. |
The actual return on plan assets in any given year may vary from our expected long-term rate of return. Actual returns on plan assets affect the funded status of the plans. Differences between actual returns on plan assets and the expected long-term rate of return are reflected as adjustments to cumulative other comprehensive income (loss), a component of total equity.
Discount Rates
Our discount rates as of December 31, 2017, are:
| • | 3.7 percent for our U.S. pension plans — compared with 4.3 percent at December 31, 2016; |
| • | 3.5 percent for our U.S. postretirement plans — compared with 3.7 percent at December 31, 2016; |
| • | 3.5 percent for our Canadian pension plans — compared with 3.7 percent at December 31, 2016; and |
| • | 3.4 percent for our Canadian postretirement plans — compared with 3.6 percent at December 31, 2016. |
We review our discount rates annually and revise them as needed. The discount rates are selected at the measurement date by matching current spot rates of high-quality corporate bonds with maturities similar to the timing of expected cash outflows for benefits.
Pension and postretirement benefit expenses for 2018 will be based on the 3.7 percent and 3.5 percent assumed discount rates for U.S. plans and 3.5 percent and 3.4 percent assumed discount rates for the Canadian plans.
Our discount rates are important in determining the cost of our plans. A 50 basis point decrease in our discount rate would increase expense or reduce a credit by approximately:
| • | $34 million for our U.S. qualified pension plans and |
| • | $4 million for our Canadian registered pension plans. |
LONG-LIVED ASSETS
We review the carrying value of our long-lived assets whenever events or changes in circumstances indicate that the carrying value of the assets may not be recoverable through future operations. The carrying value is the amount assigned to long-lived assets in our financial statements.
An impairment occurs when the carrying value of long-lived assets will not be recovered from future cash flows and is more than fair market value. Fair market value is the estimated amount we would receive if we were to sell the assets.
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 53
In determining fair market value and whether impairment has occurred, we are required to estimate:
| • | future cash flows, |
| • | residual values and |
| • | fair values of the assets. |
Key assumptions we use in developing the estimates include:
| • | probability of alternative outcomes, |
| • | product pricing, |
| • | raw material costs, |
| • | product sales and |
| • | discount rate. |
CONTINGENT LIABILITIES
We are subject to lawsuits, investigations and other claims related to environmental, product and other matters, and are required to assess the likelihood of any adverse judgments or outcomes to these matters, as well as potential ranges of probable losses.
We record contingent liabilities when:
| • | it becomes probable that we will have to make payments and |
| • | the amount of loss can be reasonably estimated. |
Assessing probability of loss and estimating probable losses requires analysis of multiple factors, including:
| • | historical experience, |
| • | evaluations of relevant legal and environmental regulations, |
| • | judgments about the potential actions of third party claimants and courts, and |
| • | consideration of potential environmental remediation methods. |
In addition to contingent liabilities recorded for probable losses, we disclose contingent liabilities when there is a reasonable possibility that an ultimate loss may occur.
While we do our best in developing our projections, recorded contingent liabilities are based on the best information available and actual losses in any future period are inherently uncertain. If estimated probable future losses or actual losses exceed our recorded liability for such claims, we would record additional charges. These exposures and proceedings can be significant and the ultimate negative outcomes could be material to our operating results or cash flow in any given quarter or year. See Note 14: Legal Proceedings, Commitments and Contingencies in the Notes to Consolidated Financial Statements for more information.
TIMBER DEPLETION
We record depletion, the costs attributed to timber harvested, as trees are harvested.
To calculate our depletion rates, which are updated annually, we:
| • | take the total carrying cost of the timber and |
| • | divide by the total timber volume estimated to be harvested during the harvest cycle. |
Estimating the volume of timber available for harvest over the harvest cycle requires consideration of the following factors:
| • | effects of fertilizer and pesticide applications, |
| • | changes in environmental regulations and other regulatory restrictions, |
| • | limits on harvesting certain timberlands, |
| • | changes in harvest plans, |
| • | scientific advancement in seedling and growing technology; and |
| • | changes in weather patterns. |
In addition, the duration of the harvest cycle varies by geographic region and species of timber.
Depletion rate calculations do not include estimates for:
| • | future silviculture or sustainable forest management costs associated with existing stands, |
| • | future reforestation costs associated with a stand's final harvest; and |
| • | future volume in connection with the replanting of a stand subsequent to its final harvest. |
A 5 percent decrease in our estimate of future harvest volumes would have:
| • | increased depletion expense by $12 million for 2017 and |
| • | increased depletion expense by $13 million for 2016. |
BUSINESS COMBINATIONS
We recognize identifiable assets acquired and liabilities assumed at their acquisition date fair value. Goodwill, if any, as of the acquisition date is measured as the excess of consideration transferred over the net of the acquisition date fair values of the assets acquired and the liabilities assumed. While we use our best estimates and assumptions for the purchase price allocation process to value assets acquired and liabilities assumed at the acquisition date, our estimates are inherently uncertain and subject to refinement. As a result, during the measurement period, which may be up to one year from the acquisition date, we record adjustments to the assets acquired and liabilities assumed, with the corresponding offset to any goodwill previously recorded (or to earnings in the event that no goodwill was previously recorded) to the extent that we identify adjustments to the preliminary purchase price allocation. Beginning January 1, 2016, we adopted ASU 2015-16, which eliminates the requirements to retrospectively apply measurement period adjustments to the preliminary purchase price allocation and revise comparative information on the income statement and balance sheet for any prior periods affected. We will recognize measurement period adjustments and any resulting effect on earnings during the period in which the adjustment is identified. Upon the conclusion of the measurement period or final
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 54
determination of the values of assets acquired or liabilities assumed, whichever comes first, any subsequent adjustments are recorded to our consolidated statement of operations.
PROSPECTIVE ACCOUNTING PRONOUNCEMENTS
A summary of prospective accounting pronouncements is in Note 1: Summary of Significant Accounting Policies in the Notes to Consolidated Financial Statements.
| PERFORMANCE MEASURES |
We use Adjusted Earnings before Interest, Taxes, Depreciation, Depletion and Amortization (Adjusted EBITDA) as a key performance measure to evaluate the performance of the consolidated company and our business segments. This measure should not be considered in isolation from and is not intended to represent an alternative to our results reported in accordance with U.S. generally accepted accounting principles (U.S. GAAP). However, we believe Adjusted EBITDA provides meaningful supplemental information for our investors about our operating performance, better facilitates period to period comparisons, and is widely used by analysts, lenders, rating agencies and other interested parties. Our definition of Adjusted EBITDA may be different from similarly titled measures reported by other companies. Adjusted EBITDA, as we define it, is operating income from continuing operations adjusted for depreciation, depletion, amortization, basis of real estate sold, pension and postretirement costs not allocated to business segments (primarily interest cost, expected return on plan assets, amortization of actuarial loss and amortization of prior service cost/credit), and special items. Adjusted EBITDA excludes results from joint ventures.
Adjusted EBITDA by Segment
| DOLLAR AMOUNTS IN MILLIONS | |||||||||
| 2017 | 2016 | 2015 | |||||||
| Timberlands | $ | 936 | $ | 865 | $ | 678 | |||
| Real Estate & ENR | 241 | 189 | 98 | ||||||
| Wood Products | 1,017 | 641 | 372 | ||||||
| 2,194 | 1,695 | 1,148 | |||||||
| Unallocated Items | (114 | ) | (112 | ) | (123 | ) | |||
| Total | $ | 2,080 | $ | 1,583 | $ | 1,025 |
We reconcile Adjusted EBITDA to net earnings for the consolidated company and to operating income for the business segments, as those are the most directly comparable U.S. GAAP measures for each.
The table below reconciles Adjusted EBITDA by segment to net earnings during the year ended 2017:
| DOLLAR AMOUNTS IN MILLIONS | |||||||||||||||
| TIMBERLANDS | REAL ESTATE & ENR | WOOD PRODUCTS | UNALLOCATED ITEMS | TOTAL | |||||||||||
| Net earnings | $ | 582 | |||||||||||||
| Earnings from discontinued operations, net of taxes | — | ||||||||||||||
| Interest expense, net of capitalized interest | 393 | ||||||||||||||
| Income taxes | 134 | ||||||||||||||
| Net contribution to earnings | $ | 532 | $ | 146 | $ | 569 | $ | (138 | ) | $ | 1,109 | ||||
| Equity earnings from joint ventures | — | (1 | ) | — | — | (1 | ) | ||||||||
| Non-operating pension and other postretirement benefit costs (credits) | — | — | — | 62 | 62 | ||||||||||
| Interest income and other | — | — | — | (39 | ) | (39 | ) | ||||||||
| Operating income | 532 | 145 | 569 | (115 | ) | 1,131 | |||||||||
| Depreciation, depletion and amortization | 356 | 15 | 145 | 5 | 521 | ||||||||||
| Basis of real estate sold | — | 81 | — | — | 81 | ||||||||||
| Unallocated pension service costs | — | — | — | 4 | 4 | ||||||||||
| Special items(1)(2)(3) | 48 | — | 303 | (8 | ) | 343 | |||||||||
| Adjusted EBITDA | $ | 936 | $ | 241 | $ | 1,017 | $ | (114 | ) | $ | 2,080 | ||||
| (1) Pretax special items included in Timberlands consists of: a $147 million noncash impairment charge of the Uruguayan operations a $99 million gain on sale of land in our Southern timberlands region. (2) Pretax special items included in Wood Products consists of: $290 million charge for product remediation, $7 million for countervailing and antidumping duties on Canadian softwood lumber that the Company sold in the United States, and a $6 million impairment charge on a nonstrategic asset. (3) Pretax special items included in Unallocated Items consist of: $42 million for environmental remediation insurance recoveries and $34 million for Plum Creek merger-related costs. |
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 55
The table below reconciles Adjusted EBITDA by segment to net earnings during the year ended 2016:
| DOLLAR AMOUNTS IN MILLIONS | |||||||||||||||
| TIMBERLANDS | REAL ESTATE & ENR | WOOD PRODUCTS | UNALLOCATED ITEMS | TOTAL | |||||||||||
| Net earnings | $ | 1,027 | |||||||||||||
| Earnings from discontinued operations, net of taxes | (612 | ) | |||||||||||||
| Interest expense, net of capitalized interest | 431 | ||||||||||||||
| Income taxes | 89 | ||||||||||||||
| Net contribution to earnings | $ | 499 | $ | 55 | $ | 512 | $ | (131 | ) | $ | 935 | ||||
| Equity earnings from joint ventures | — | (2 | ) | — | (20 | ) | (22 | ) | |||||||
| Non-operating pension and other postretirement benefit costs (credits) | — | — | — | (48 | ) | (48 | ) | ||||||||
| Interest income and other | — | — | — | (43 | ) | (43 | ) | ||||||||
| Operating income | 499 | 53 | 512 | (242 | ) | 822 | |||||||||
| Depreciation, depletion and amortization | 366 | 13 | 129 | 4 | 512 | ||||||||||
| Basis of real estate sold | — | 109 | — | — | 109 | ||||||||||
| Unallocated pension service costs | — | — | — | 5 | 5 | ||||||||||
| Special items(1)(2) | — | 14 | — | 121 | 135 | ||||||||||
| Adjusted EBITDA | $ | 865 | $ | 189 | $ | 641 | $ | (112 | ) | $ | 1,583 | ||||
| (1) Special items included in Real Estate & ENR relate to an asset impairment charge recorded for development projects. (2) Special items included in Unallocated Items consist of: $146 million Plum Creek merger-related costs, $36 million gain on sale of nonstrategic assets and $11 million of legal expense. |
The table below reconciles Adjusted EBITDA by segment to net earnings during the year ended 2015:
| DOLLAR AMOUNTS IN MILLIONS | |||||||||||||||
| TIMBERLANDS | REAL ESTATE & ENR | WOOD PRODUCTS | UNALLOCATED ITEMS | TOTAL | |||||||||||
| Net earnings | $ | 506 | |||||||||||||
| Earnings from discontinued operations, net of taxes | (95 | ) | |||||||||||||
| Interest expense, net of capitalized interest | 341 | ||||||||||||||
| Income taxes | (58 | ) | |||||||||||||
| Net contribution to earnings | $ | 470 | $ | 79 | $ | 258 | $ | (113 | ) | $ | 694 | ||||
| Equity earnings from joint ventures | — | — | — | — | — | ||||||||||
| Non-operating pension and other postretirement benefit costs (credits) | — | — | — | (14 | ) | (14 | ) | ||||||||
| Interest income and other | — | — | — | (36 | ) | (36 | ) | ||||||||
| Operating income | 470 | 79 | 258 | (163 | ) | 644 | |||||||||
| Depreciation, depletion and amortization | 208 | 1 | 106 | 10 | 325 | ||||||||||
| Basis of real estate sold | — | 18 | — | — | 18 | ||||||||||
| Unallocated pension service costs | — | — | — | 3 | 3 | ||||||||||
| Special items(1)(2) | — | — | 8 | 27 | 35 | ||||||||||
| Adjusted EBITDA | $ | 678 | $ | 98 | $ | 372 | $ | (123 | ) | $ | 1,025 | ||||
| (1) Special items included in Wood Products are pretax restructuring charges related to the closure of four distribution centers. (2) Special items included in Unallocated Items consist of a $13 million noncash impairment charge related to a nonstrategic asset that was sold in the second quarter and $14 million of Plum Creek merger-related costs. |
WEYERHAEUSER COMPANY > 2017 ANNUAL REPORT AND FORM 10-K 56
Previous: Item 6. SELECTED FINANCIAL DATA · Next: Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK