 filings.tools
AES (AES) 10-K risk factor changes: FY2022 vs FY2021
The 2022-12-31 10-K against the 2021-12-31 one, compared heading by heading and sentence by sentence.
Item 1A67 rewritten43 added27 removed442 unchanged
All filing items2,308 rewritten1,050 added840 removed4,389 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 1,050 added, 840 removed, 2,308 rewritten and 4,389 unchanged across 19 items that differ.
Sentences by item
22 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2022; struck-through words were in FY2021. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
67 rewritten, 43 added, 27 removed, 442 unchanged
The categories of risk we have identified in Item 1A.—*[Risk [removed: Factors](#if7b552d0c82e4d75af26724d7276acc2_58)*] [added: Factors](#i84f31ef528bc41899c5480059e42eda9_58)*] include risks associated with our operations, governmental regulation and laws, our indebtedness and financial condition.
These risk factors should be read in conjunction with Item 7*.—[Management's Discussion and Analysis of Financial Condition and Results of [removed: Operations](#if7b552d0c82e4d75af26724d7276acc2_97)*] [added: Operations](#i84f31ef528bc41899c5480059e42eda9_100)*] in this Form 10-K and the Consolidated Financial Statements and related notes included elsewhere in this Form 10-K.
- changes in the availability of our generation facilities or distribution systems due to increases in scheduled and unscheduled plant outages, equipment failure, failure of transmission systems, labor disputes, disruptions in fuel supply, poor hydrologic and wind conditions, inability to comply with regulatory or permit requirements, or catastrophic events such as fires, floods, storms, hurricanes, earthquakes, dam failures, tsunamis, explosions, terrorist acts, [removed: cyber attacks] [added: vandalism, cyber-attacks] or other similar occurrences; and
| [removed: 57] [added: 59] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
[removed: Limitations,] [added: Limitations] or interruptions in this infrastructure or at the facilities of our subsidiaries, including as a result of third parties intentionally or unintentionally disrupting this infrastructure or the facilities of our subsidiaries, could impede their ability to produce electricity.
See Item 3.— *[Legal [removed: Proceedings](#if7b552d0c82e4d75af26724d7276acc2_67)*] [added: Proceedings](#i84f31ef528bc41899c5480059e42eda9_67)*] below.
| [removed: 58] [added: 60] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
The open market wholesale prices for electricity can be volatile and generally reflect the variable cost of the source generation which could include renewable sources at near zero pricing or [removed: thermal sources subject to fluctuating cost of fuels such as coal, natural gas or oil derivative fuels in addition to other factors described below.]
This, combined with changes in oil, gas, and coal pricing, has led to increasingly volatile electricity markets across our [added: markets.]
| [removed: 59] [added: 61] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
The COVID-19 pandemic has severely impacted global economic [removed: activity,] [added: activity in recent years,] including electricity and energy consumption.
- deterioration of economic conditions, demand and other related factors resulting in impairments to [removed: goodwill or] long-lived assets; and
| [removed: 60] [added: 62] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
The impact of the COVID-19 pandemic also depends on factors, including the effectiveness and timing of [removed: vaccine development and distribution efforts,] [added: updated vaccines to address new variants,] the development of more virulent COVID-19 variants as well as third-party actions taken to contain its spread and mitigate its public health effects.
[removed: The] [added: A resurgence or material worsening of the] COVID-19 pandemic [removed: presents] [added: could present] material uncertainty that could adversely affect our generation facilities, transmission and distribution systems, development projects, energy storage sales by Fluence, and results of operations, financial condition and cash flows.
We may not have adequate risk mitigation [removed: and/or] [added: or] insurance coverage for liabilities.
[removed: Furthermore,] through AGIC, AES’ captive insurance company, we take certain insurance risk on our businesses.
| [removed: 61] [added: 63] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
We also may encounter challenges in integrating and realizing the expected benefits of these acquisitions as well as integration or other one-time costs that are greater [removed: than expected.]
| [removed: 62] [added: 64] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
[added: The evolution of competitive] electricity markets and the development of highly efficient gas-fired power plants and renewables such as wind and solar have also caused, and could continue to cause, price pressure in certain power markets where we sell or intend to sell power.
Such an attack, by hacking, malware or other means, may interrupt our operations, cause property damage, affect our ability to control [added: our infrastructure assets, cause the release of sensitive customer information or limit communications with third parties.]
| [removed: 63] [added: 65] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
- require extensive repair and restoration costs for additional security measures to avert future attacks; [removed: and]
- impair our reputation and limit our competitiveness for future [removed: opportunities.][added: opportunities; and]
[removed: In addition,] we are dependent upon hydrological conditions prevailing from time to time in the broad geographic regions in which our hydroelectric generation facilities are located.
To the extent that hydrological conditions result in droughts or other conditions negatively affect our hydroelectric generation business, such as has happened in Panama in [removed: 2019,] [added: 2019 and Brazil in 2021,] our results of operations can be materially adversely affected.
| [removed: 64] [added: 66] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
We are in various stages of developing and constructing [removed: power plants and] renewables [removed: projects.][added: projects and power plants.]
Successful completion of the development of these projects depends upon overcoming substantial risks, including risks relating to siting, financing, engineering and construction, permitting, [added: interconnection and transmission,] governmental approvals, commissioning delays, supply chain related disruptions to our access to materials, or the potential for termination of the power sales contract as a result of a failure to meet certain milestones.
We believe that capitalized costs for projects under development are recoverable; however, there can be no assurance that any individual project [added: will] reach commercial operation.
While we have certain rights to appoint representatives to the Fluence Board of Directors, the interests of the Fluence [added: shareholders, as represented by the Fluence Board of Directors, may not align with our interests or the interests of our securityholders.]
| [removed: 65] [added: 67] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
Customer growth and customer usage in our utilities businesses are affected by external factors, including mandated energy efficiency measures, demand side management requirements, and economic and demographic [removed: conditions, such as population changes, job and income growth, housing starts, new business formation and the overall level of economic activity.]
| [removed: 66] [added: 68] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
We have [removed: 32] [added: 28] defined benefit plans, five at U.S. subsidiaries and the remaining plans at foreign subsidiaries, which cover substantially all of the employees at these subsidiaries.
See Item 7.—*[Management's Discussion and Analysis—Critical Accounting Policies and Estimates—Pension and Other Postretirement [removed: Plans](#if7b552d0c82e4d75af26724d7276acc2_238)*] [added: Plans](#i84f31ef528bc41899c5480059e42eda9_256)*] and Note 15—*[Benefit [removed: Plans](#if7b552d0c82e4d75af26724d7276acc2_310)*] [added: Plans](#i84f31ef528bc41899c5480059e42eda9_331)*] included in Item 8.—*[Financial Statements and Supplementary [removed: Data](#if7b552d0c82e4d75af26724d7276acc2_247)*.][added: Data](#i84f31ef528bc41899c5480059e42eda9_265)*.]
Impairment of [removed: goodwill or] long-lived assets would negatively impact our consolidated results of operations and net worth.
[removed: We may be required to evaluate the potential] [added: Long-lived assets are initially recorded at cost or fair value, are depreciated over their estimated useful lives, and are evaluated for] impairment [removed: of goodwill outside of the required annual evaluation process if we experience situations,] [added: only when impairment indicators are present,] such [removed: as:] [added: as] deterioration in general economic conditions or our operating or regulatory environment; increased competitive environment; lower forecasted revenue; increase in fuel costs, particularly costs that we are unable to pass through to customers; increase in environmental compliance costs; negative or declining cash flows; loss of a key contract or customer, particularly when we are unable to replace it on equally favorable terms; developments in our strategy; divestiture of a significant component of our business; or adverse actions or assessments by a regulator.
Any impairment of [removed: goodwill or] long-lived assets could have a material adverse effect on our business, financial condition, results of operations, and prospects.
In addition, our battery storage operations also involve risks associated with lithium-ion batteries.
On rare occasions, lithium-ion batteries can rapidly release the energy they contain by venting smoke and flames in a manner that can ignite nearby materials as well as other lithium-ion batteries.
While more recent design developments for our storage projects seek to minimize the impact of such events, these events are inherent risks of our battery storage operations.
There can be no assurance that project financing will be available or that, once secured, will provide similar terms or flexibility as would be expected from a commercial lender.
thermal sources subject to fluctuating cost of fuels such as coal, natural gas or oil derivative fuels in addition to other factors described below.
Further, China's Zero COVID strategy contributed to a significant decrease in GDP growth in 2022.
The impact of the recent loosening of that strategy is uncertain at this time.
Furthermore,
In addition, the U.S. Department of Commerce’s investigation into the antidumping and countervailing duties circumvention claim on solar cells and panels supplied from Malaysia, Vietnam, Thailand, and Cambodia has reached a preliminary determination that circumvention occurred.
Additionally, Commerce issued a preliminary determination that circumvention would not be deemed to occur for any solar cells and panels imported from the four countries if the wafers were manufactured outside of China or if no more than two out of six specifically
identified components were produced in China.
These preliminary determinations could be modified and final determinations from Commerce are expected in May 2023.
If the final determinations result in additional taxes, tariffs, duties, or other assessments on renewable energy or the equipment necessary to generate or deliver it, such as antidumping and countervailing duty rates, such developments could impede the realization of our U.S. renewables strategy by resulting in, among other items, lack of a satisfactory market for the development and/or financing of our U.S. renewable energy projects, abandoning the development of certain U.S. renewable energy projects, a loss of our investments in the projects, and/or reduced project returns.
Further, in the U.S., the tax credits associated with certain renewables projects are earned when the project is placed in service.
Delays in executing our renewables projects can result in delays in recognizing those tax credits and adversely impact our short-term financial results.
Any of the above factors could have a material adverse effect on our business, financial condition, results of operations and prospects.
Objections of or challenges by local communities or interest groups may delay or impede permitting for our development projects.
than expected.
In particular, there has been an increased focus on the U.S. energy grid believed to be related to the Russia/Ukraine conflict.
In addition,
As of December 31, 2022, Fluence continues to report that a material weakness in its internal control over revenue recognition and related inventory has not yet been remediated.
Such material weakness can impact the reliability of the Fluence financial information that we may include as part of our financial information.
conditions, such as population changes, job and income growth, housing starts, new business formation and the overall level of economic activity.
On January 19, 2021, the D.C. Circuit vacated and remanded to the EPA the ACE Rule, but withheld issuance of the mandate that would effectuate its decision.
On February 22, 2021, the D.C. Circuit granted EPA's unopposed motion for a partial stay of the issuance of the mandate on vacating the repeal of the CPP.
On March 5, 2021, the D.C. Circuit issued the partial mandate effectuating the vacatur of the ACE Rule.
In effect, the CPP did not take effect while the EPA is addressing the remand of the ACE rule by promulgating a new Section 111(d) rule to regulate greenhouse gases from existing electric generating units.
On October 29, 2021, the U.S. Supreme Court granted petitions to review the decision by the D.C. Circuit to vacate the ACE Rule.
On June 30, 2022, Supreme Court reversed the judgment of the D.C. Circuit Court and remanded for further proceedings consistent with its opinion.
The opinion held that the “generation shifting” approach in the CPP exceeded the authority granted to EPA by Congress under Section 111(d) of the CAA.
As a result of the June 30, 2022 Supreme Court decision, on October 27, 2022, the D.C. Circuit recalled its March 5, 2021 partial mandate and issued a new partial mandate holding pending challenges to the ACE Rule in abeyance while EPA develops a replacement rule.
The impact of the results of further proceedings and potential future greenhouse gas emissions regulations remains uncertain, but it could be material.
The impact of the results of such litigation and potential future greenhouse gas emissions regulations remains uncertain, but it could be material.
However, there can be no assurance that we will effectively pass such costs onto the contract counterparties or
For example, in the third quarter of 2022, the Inflation Reduction Act (the “IRA”) was signed into law in the United States.
The IRA includes provisions that are expected to benefit the U.S. clean energy industry, including increases, extensions and/or new tax credits for onshore and offshore wind, solar, storage and hydrogen projects.
We expect that the extension of the current solar investment tax credits ("ITCs"), as well as higher credits available for projects that satisfy wage and apprenticeship requirements, will increase demand for our renewables products.
In the U.S., the IRA includes a 15% corporate alternative minimum tax based on adjusted financial statement income.
We are currently evaluating the applicability and effect of the new law and additional guidance issued in the fourth quarter of 2022.
With respect to international tax reform, in the fourth quarter of 2022, the European Commission adopted an amended Directive on Pillar 2 establishing a global minimum tax at a 15% rate.
There can be no assurance that project financing will be available.
markets.
The evolution of competitive
our infrastructure assets, cause the release of sensitive customer information or limit communications with third parties.
shareholders, as represented by the Fluence Board of Directors, may not align with our interests or the interests of our securityholders.
As of December 31, 2021, the Company had approximately $1.2 billion of goodwill, which represented approximately 4% of our total assets.
Goodwill is not amortized, but is evaluated for impairment at least annually, or more frequently if impairment indicators are present.
These types of events and the resulting analyses could result in goodwill impairment.
Additionally, goodwill may be impaired if our acquisitions do not perform as expected.
Long-lived assets are initially recorded at fair value, are amortized or depreciated over their estimated useful lives, and are evaluated for impairment only when impairment indicators, similar to those described above for goodwill, are present.
The estimated annual CO2 emissions from fossil fuel-fired electric power generation facilities of the Company's subsidiaries that are in construction or development are approximately 4 million metric tonnes (ownership adjusted).
On January 19, 2021, the D.C. Circuit vacated and remanded to EPA the ACE Rule although the parties have the opportunity to request a rehearing at the D.C. Circuit or seek a review of the decision by the U.S. Supreme Court.
The impact of this decision and potential new or revised rules from the current Administration remains uncertain.
In addition, while revenues would be
For example, in the third quarter of 2021, both the United States Senate and the United States House of Representatives passed $3.5 trillion budget resolutions as a first step to the budget reconciliation process that could include U.S. corporate and international tax reforms.
As part of the reconciliation process, the House Ways and Means Committee marked up a version of the “Build Back Better Act”.
The Build Back Better Act included U.S. corporate and international tax reform proposals that would increase the U.S. corporate income tax rate, modify the Global Intangible Low Taxed Income rules, create additional interest deduction limitations and provide clean energy incentives, among others.
The Company believes it would benefit
from the clean energy initiatives, though the tax implications may be unfavorable in the short term.
As of the filing date, the Build Back Better Act had not been voted on in the United States Senate.
With respect to international tax reform, in the third quarter of 2021,132 member countries of the OECD “Inclusive Framework” group released a statement announcing a coordinated framework that would reallocate taxing rights over the profits of multinational corporations and establish a global minimum tax at a 15% rate.
On December 20, 2021 the OECD released a set of Model Rules related to the so-called Pillar 2 global minimum tax known as the Global Anti-Base Erosion (GloBE).
On December 22, 2021, the European Commission proposed a draft Directive establishing a global minimum level of taxation.
The Subject to Tax Rule was excluded from the draft Directive.
These Rules, collectively, comprise the main facets of the GloBE.
Implementation of the framework would require multilateral agreement and/or country specific legislative action, including in the U.S.
result of foreign governments restricting the repatriation of funds or the conversion of currencies.
An excerpt. Shown here: 40 of 67 rewritten, 40 of 43 added and all 27 removed. The counts are complete. For every sentence, read Item 1A. RISK FACTORS in the FY2022 filing and the FY2021 filing.
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
429 rewritten, 215 added, 214 removed, 549 unchanged
In [removed: 2021,] [added: 2022,] AES delivered on its strategic and financial objectives.
We completed construction or the acquisition of [removed: 2.1] [added: 1.9] GW of renewables [removed: generation] and [added: energy storage, and] signed long-term PPAs for an additional [removed: 5] [added: 5.2] GW of new [removed: renewables.][added: renewable energy.]
See *Overview of our Strategy* included in Item [removed: 1.—*[Business](#if7b552d0c82e4d75af26724d7276acc2_19)*] [added: 1.—*[Business](#i84f31ef528bc41899c5480059e42eda9_19)*] of this Form 10-K for further information.
Compared with last year, diluted [removed: earnings] [added: loss] per share from continuing operations [removed: decreased $0.68,] [added: increased $0.20,] from [removed: $0.06] [added: $0.62] to [removed: a loss of $0.62.][added: $0.82.]
This [removed: decrease] [added: loss increase] reflects the [removed: loss] [added: prior year gains] on [removed: deconsolidation] [added: remeasurement] of [removed: Alto Maipo] [added: our interest] in [added: sPower's development platform and] the [removed: current period,] [added: Fluence capital raise,] higher [removed: current year impairments, and] [added: income tax expense,] lower contributions from [removed: Brazil due to the prior year revision of the GSF liability and drier hydrology; partially offset by higher margins at] our US and Utilities SBU [removed: including new renewables, Southland Energy, and Southland, lower Parent Company interest expense] due to [added: the recognition of previously deferred power purchase costs and impacts of outages, the prior year impact of] realized gains on de-designated interest rate swaps [added: at the Parent Company, higher interest expense,] and lower [added: capitalized] interest [removed: rates, gains on Fluence capital raisings, a gain] [added: at construction projects in Chile; partially offset by the prior year loss] on [removed: remeasurement] [added: deconsolidation] of [removed: our interest in sPower's development platform,] [added: Alto Maipo,] and [removed: lower income tax expense.][added: higher margins from our MCAC SBU due to favorable LNG transactions.]
| [removed: 82] [added: 84] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
| Years Ended December 31, | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | [removed: 2019] [added: 2020] | | | | | | % Change [removed: 2021] [added: 2022] vs. [removed: 2020] [added: 2021] | | | | | | % Change [removed: 2020] [added: 2021] vs. [removed: 2019] [added: 2020] | | |
| US and Utilities SBU | | | $ | [removed: 4,335] [added: 5,013] | | | | | $ | [removed: 3,918] [added: 4,335] | | | | | $ | [removed: 4,058] [added: 3,918] | | | | | [removed: 11] [added: 16] | | % | | | | [removed: \-3] [added: 11] | | % |
| South America SBU | | | [removed: 3,541] [added: 3,539] | | | | | | [removed: 3,159] [added: 3,541] | | | | | | [removed: 3,208] [added: 3,159] | | | | | | [removed: 12] [added: —] | | % | | | | [removed: \-2] [added: 12] | | % |
| MCAC SBU | | | [removed: 2,157] [added: 2,868] | | | | | | [removed: 1,766] [added: 2,157] | | | | | | [removed: 1,882] [added: 1,766] | | | | | | [removed: 22] [added: 33] | | % | | | | [removed: \-6] [added: 22] | | % |
| Eurasia SBU | | | [removed: 1,123] [added: 1,217] | | | | | | [removed: 828] [added: 1,123] | | | | | | [removed: 1,047] [added: 828] | | | | | | [removed: 36] [added: 8] | | % | | | | [removed: \-21] [added: 36] | | % |
| Corporate and Other | | | [removed: 116] [added: 119] | | | | | | [removed: 231] [added: 116] | | | | | | [removed: 46] [added: 231] | | | | | | [removed: \-50] [added: 3] | | % | | | | [removed: NM] [added: \-50] | | [added: %] |
| Eliminations | | | [removed: (131)] [added: (139)] | | | | | | [removed: (242)] [added: (131)] | | | | | | [removed: (52)] [added: (242)] | | | | | | [removed: \-46] [added: 6] | | % | | | | [removed: NM] [added: \-46] | | [added: %] |
| Total Revenue | | | [removed: 11,141] [added: 12,617] | | | | | | [removed: 9,660] [added: 11,141] | | | | | | [removed: 10,189] [added: 9,660] | | | | | | [removed: 15] [added: 13] | | % | | | | [removed: \-5] [added: 15] | | % |
| US and Utilities SBU | | | [removed: 792] [added: 564] | | | | | | [removed: 638] [added: 792] | | | | | | [removed: 754] [added: 638] | | | | | | [removed: 24] [added: \-29] | | % | | | | [removed: \-15] [added: 24] | | % |
| South America SBU | | | [removed: 1,069] [added: 823] | | | | | | [removed: 1,243] [added: 1,069] | | | | | | [removed: 873] [added: 1,243] | | | | | | [removed: \-14] [added: \-23] | | % | | | | [removed: 42] [added: \-14] | | % |
| MCAC SBU | | | [removed: 521] [added: 820] | | | | | | [removed: 559] [added: 521] | | | | | | [removed: 487] [added: 559] | | | | | | [removed: \-7] [added: 57] | | % | | | | [removed: 15] [added: \-7] | | % |
| Eurasia SBU | | | [removed: 216] [added: 236] | | | | | | [removed: 186] [added: 216] | | | | | | [removed: 188] [added: 186] | | | | | | [removed: 16] [added: 9] | | % | | | | [removed: \-1] [added: 16] | | % |
| Corporate and Other | | | [removed: 158] [added: 175] | | | | | | [removed: 120] [added: 158] | | | | | | [removed: 39] [added: 120] | | | | | | [removed: 32] [added: 11] | | % | | | | [removed: NM] [added: 32] | | [added: %] |
| Eliminations | | | [removed: (45)] [added: (70)] | | | | | | [removed: (53)] [added: (45)] | | | | | | [removed: 8] [added: (53)] | | | | | | [removed: \-15] [added: 56] | | % | | | | [removed: NM] [added: \-15] | | [added: %] |
| Total Operating Margin | | | [removed: 2,711] [added: 2,548] | | | | | | [removed: 2,693] [added: 2,711] | | | | | | [removed: 2,349] [added: 2,693] | | | | | | [removed: 1] [added: \-6] | | % | | | | [removed: 15] [added: 1] | | % |
| General and administrative expenses | | | [removed: (166)] [added: (207)] | | | | | | [removed: (165)] [added: (166)] | | | | | | [removed: (196)] [added: (165)] | | | | | | [removed: 1] [added: 25] | | % | | | | [removed: \-16] [added: 1] | | % |
| Interest expense | | | [removed: (911)] [added: (1,117)] | | | | | | [removed: (1,038)] [added: (911)] | | | | | | [removed: (1,050)] [added: (1,038)] | | | | | | [removed: \-12] [added: 23] | | % | | | | [removed: \-1] [added: \-12] | | % |
| Interest income | | | [removed: 298] [added: 389] | | | | | | [removed: 268] [added: 298] | | | | | | [removed: 318] [added: 268] | | | | | | [removed: 11] [added: 31] | | % | | | | [removed: \-16] [added: 11] | | % |
| Loss on extinguishment of debt | | | [removed: (78)] [added: (15)] | | | | | | [removed: (186)] [added: (78)] | | | | | | [removed: (169)] [added: (186)] | | | | | | [removed: \-58] [added: \-81] | | % | | | | [removed: 10] [added: \-58] | | % |
| Other expense | | | [removed: (60)] [added: (68)] | | | | | | [removed: (53)] [added: (60)] | | | | | | [removed: (80)] [added: (53)] | | | | | | 13 | | % | | | | [removed: \-34] [added: 13] | | % |
| Other income | | | [removed: 410] [added: 102] | | | | | | [removed: 75] [added: 410] | | | | | | [removed: 145] [added: 75] | | | | | | [removed: NM] [added: \-75] | | [added: %] | | | | [removed: \-48] [added: NM] | | [removed: %] |
| [removed: Gain (loss)] [added: Loss] on disposal and sale of business interests | | | [removed: (1,683)] [added: (9)] | | | | | | [removed: (95)] [added: (1,683)] | | | | | | [removed: 28] [added: (95)] | | | | | | [removed: NM] [added: \-99] | | [added: %] | | | | NM | | |
| Asset impairment expense | | | [removed: (1,575)] [added: (763)] | | | | | | [removed: (864)] [added: (1,575)] | | | | | | [removed: (185)] [added: (864)] | | | | | | [removed: 82] [added: \-52] | | % | | | | [removed: NM] [added: 82] | | [added: %] |
| Foreign currency transaction gains (losses) | | | [removed: (10)] [added: (77)] | | | | | | [removed: 55] [added: (10)] | | | | | | [removed: (67)] [added: 55] | | | | | | NM | | | | | | NM | | |
| Other non-operating expense | | | [removed: —] [added: (175)] | | | | | | [removed: (202)] [added: —] | | | | | | [removed: (92)] [added: (202)] | | | | | | [removed: \-100] [added: NM] | | [removed: %] | | | | [removed: NM] [added: \-100] | | [added: %] |
| Income tax benefit (expense) | | | [removed: 133] [added: (265)] | | | | | | [removed: (216)] [added: 133] | | | | | | [removed: (352)] [added: (216)] | | | | | | NM | | | | | | [removed: \-39] [added: NM] | | [removed: %] |
| Net equity in losses of affiliates | | | [removed: (24)] [added: (71)] | | | | | | [removed: (123)] [added: (24)] | | | | | | [removed: (172)] [added: (123)] | | | | | | [removed: \-80] [added: NM] | | [removed: %] | | | | [removed: \-28] [added: \-80] | | % |
| INCOME (LOSS) FROM CONTINUING OPERATIONS | | | [removed: (955)] [added: (505)] | | | | | | [removed: 149] [added: (955)] | | | | | | [removed: 477] [added: 149] | | | | | | [removed: NM] [added: \-47] | | [added: %] | | | | [removed: \-69] [added: NM] | | [removed: %] |
| Gain from disposal of discontinued businesses, net of income tax expense of [removed: $1,] $0, [added: $1,] and $0, respectively | | | [removed: 4] [added: —] | | | | | | [removed: 3] [added: 4] | | | | | | [removed: 1] [added: 3] | | | | | | [removed: 33] [added: \-100] | | % | | | | [removed: NM] [added: 33] | | [added: %] |
| NET INCOME (LOSS) | | | [removed: (951)] [added: (505)] | | | | | | [removed: 152] [added: (951)] | | | | | | [removed: 478] [added: 152] | | | | | | [removed: NM] [added: \-47] | | [added: %] | | | | [removed: \-68] [added: NM] | | [removed: %] |
| Less: [removed: Loss] [added: Net loss] (income) [removed: from continuing operations] attributable to noncontrolling interests and redeemable stock of subsidiaries | | | [removed: 542] [added: (41)] | | | | | | [removed: (106)] [added: 542] | | | | | | [removed: (175)] [added: (106)] | | | | | | NM | | | | | | [removed: \-39] [added: NM] | | [removed: %] |
| NET INCOME (LOSS) ATTRIBUTABLE TO THE AES CORPORATION | | | $ | [removed: (409)] [added: (546)] | | | | | $ | [removed: 46] [added: (409)] | | | | | $ | [removed: 303] [added: 46] | | | | | [removed: NM] [added: 33] | | [added: %] | | | | [removed: \-85] [added: NM] | | [removed: %] |
| Income (loss) from continuing operations, net of tax | | | $ | [removed: (413)] [added: (546)] | | | | | $ | [removed: 43] [added: (413)] | | | | | $ | [removed: 302] [added: 43] | | | | | [removed: NM] [added: 32] | | [added: %] | | | | [removed: \-86] [added: NM] | | [removed: %] |
| Income from discontinued operations, net of tax | | | [removed: 4] [added: —] | | | | | | [removed: 3] [added: 4] | | | | | | [removed: 1] [added: 3] | | | | | | [removed: 33] [added: \-100] | | % | | | | [removed: NM] [added: 33] | | [added: %] |
Adjusted EPS, a non-GAAP measure, increased $0.15, from $1.52 to $1.67, mainly driven by higher contributions from our MCAC SBU due to favorable LNG transactions and from our South America SBU due to higher margins and increased ownership in AES Andes, partially offset by lower contributions from our US and Utilities SBU due to the recognition of previously deferred power purchase costs and impacts of outages, the prior year impact of realized gains on de-designated interest rate swaps at the Parent Company, and higher interest expense.
| Goodwill impairment expense | | | (777) | | | | | | — | | | | | | — | | | | | | NM | | | | | | — | | % |
| NET INCOME (LOSS) ATTRIBUTABLE TO THE AES CORPORATION | | | $ | (546) | | | | | $ | (409) | | | | | $ | 46 | | | | | 33 | | % | | | | NM | | |
*Consolidated Revenue* *—* Revenue increased $1.5 billion, or 13%, in 2022 compared to 2021, driven by:
- $711 million at MCAC driven by favorable LNG transactions in Panama and the Dominican Republic; higher contract sales due to increased demand and higher prices in the Dominican Republic; higher spot sales due to better hydrology in Panama; and higher pass-through fuel costs in Mexico; partially offset by the impact from the sale of Itabo in April 2021;
- $678 million at US and Utilities driven by higher prices at AES Indiana and AES Ohio due to increases in riders to collect fuel and purchased power costs from customers, as well as increased demand and favorable weather; higher sales at AES Clean Energy due to the supply agreement with Google, the prior year acquisition of New York Wind and the commencement of renewable projects; higher spot sales at Southland; and higher pass-through energy prices in El Salvador; partially offset by an increase in unrealized derivative losses at Southland and Southland Energy and a decrease at AES Hawaii due to closure of the plant in August 2022; and
- $94 million at Eurasia mainly driven by higher energy prices and generation in Bulgaria, higher electricity prices at St. Nikola, and recognition of construction revenue at Mong Duong due to a reduction in expected completion costs for ash pond 2; partially offset by unfavorable FX impact.
- $228 million at US and Utilities mainly driven by an increase in unrealized derivative losses at Southland Energy; recognition of previously deferred purchased power costs at AES Ohio and a charge resulting from a regulatory settlement at AES Indiana; the impact from outages and closure of the plant at AES Hawaii; lower availability and higher maintenance costs at AES Puerto Rico due to forced outages and a higher heat rate; and an increase in costs associated with growing the business at AES Clean Energy; partially offset by higher retail margin at AES Indiana due to higher volumes from favorable weather; and higher sales at AES Clean Energy due to the supply agreement with Google, the prior year acquisition of New York Wind, and the commencement of renewables projects.
These unfavorable impacts were partially offset by increases of:
- $299 million at MCAC primarily driven by an increase in Panama and the Dominican Republic due to favorable LNG transactions; higher contract sales due to higher prices and favorable hydrology in Panama and increased demand and higher prices in the Dominican Republic; partially offset by the impact from the sale of Itabo in April 2021; and
*•*$20 million at Eurasia mainly driven by recognition of construction revenue at Mong Duong due to a reduction in expected completion costs for ash pond 2; and by higher electricity prices at St. Nikola in Bulgaria; partially offset by unfavorable FX impact and higher maintenance costs.
volume and generation at AES Brasil, partially due to the acquisition of Ventus and Cubico I; partially offset by unfavorable FX impact and by the prior period recovery of previously expensed payments from customers in Chile; and
General and administrative expenses increased $41 million, or 25%, to $207 million in 2022 compared to $166 million in 2021, primarily due to increased business development activity and people costs.
Interest expense increased $206 million, or 23%, to $1.1 billion in 2022, compared to $911 million in 2021, primarily due to the prior year impact of realized gains on de-designated interest rate swaps, lower capitalized interest at construction projects in Chile, and increased borrowings in South America and at the Parent Company.
Interest income increased $91 million, or 31%, to $389 million in 2022, compared to $298 million in 2021 primarily due to an increase in short-term investments at AES Brasil and Argentina, higher CAMMESA interest rates on receivables in Argentina, and increase in sales-type lease receivables at the Alamitos Energy Center.
Loss on extinguishment of debt decreased $63 million, or 81%, to $15 million in 2022, compared to $78 million in 2021.
These decreases were partially offset in 2021 by the losses mentioned above.
Other income decreased $308 million to $102 million in 2022, compared to $410 million in 2021 primarily due to the prior year gain on remeasurement of our equity interest in the sPower development platform to its acquisition-date fair value, recognized as part of the merger to form AES Clean Energy Development, prior year legal arbitration at Alto Maipo, and the prior year gain on remeasurement of contingent consideration at AES Clean Energy; partially offset by the current year gain on remeasurement of our existing investment in 5B, which is accounted for using the measurement alternative, and insurance proceeds primarily associated with property damage at TermoAndes.
Other expense increased $8 million, or 13%, to $68 million in 2022, compared to $60 million in 2021, primarily due to current year costs related to the disposition of AES Gilbert, including the recognition of an allowance on the sales-type lease receivable; partially offset by lower losses recognized at commencement of sales-type leases due to the prior year loss at AES Renewable Holdings.
Loss on disposal and sale of business interests increased $1.6 billion to $1.7 billion in 2021, compared to $95 million in 2020, primarily due to the changes at Alto Maipo and Fluence referenced in the paragraph above.
Goodwill impairment expense
Goodwill impairment expense was $777 million in 2022, due to a $644 million impairment at AES Andes and a $133 million impairment at AES El Salvador.
This was due to the Company seeing increases in inputs utilized to derive the discount rate applied in our goodwill impairment analysis, such as higher interest rates and country risk premiums in certain markets.
These changes to the inputs of our discount rate have negatively impacted our annual goodwill impairment test as of October 1, 2022.
There was no goodwill impairment expense in 2021 or 2020.
Asset impairment expense decreased $812 million to $763 million in 2022, compared to $1.6 billion in 2021.
This was partially offset by the $468 million impairment of Maritza's coal-fired plant due to Bulgaria's commitment to cease electricity generation using coal as a fuel source beyond 2038, the $193 million impairment at TEG TEP in Mexico, and a $76 million impairment of Amman East and IPP4 in Jordan.
This increase was primarily due to 2021 impairments at AES Andes totaling $804 million, a $475 million impairment at Puerto Rico, impairments at the Buffalo Gap wind generation facilities totaling $193 million, and a $67 million impairment at the Mountain View I & II wind facilities.
The Company recognized net foreign currency transaction losses of $77 million in 2022, primarily driven by the depreciation of the Argentine peso, partially offset by realized foreign currency derivative gains in South America due to the depreciating Colombian peso.
Other non-operating expense was $175 million in 2022 due to the other-than-temporary impairment of the sPower equity method investment.
The impairment analysis was triggered by the signing of a purchase and sale agreement which, at the time, implied an expected loss upon sale of the Company's indirect interest in a portfolio of sPower's operating assets ("OpCo B").
The transaction closed on February 28, 2023.
sPower primarily holds operating assets where the tax credits associated with underlying projects have already been allocated to tax equity partners.
The application of HLBV accounting increases the carrying value of these investments, as earnings are initially disproportionately allocated to the sponsor entity.
Since sPower does not have any ongoing development or other value creation activities following the transfer of these activities to AES Clean Energy Development, the impairment adjusts the carrying value to the fair market value of the operating assets.
There was no other non-operating expense in 2021.
Income tax expense was $265 million in 2022, compared to income tax benefit of $133 million in 2021.
The 2022 effective tax rate was impacted by the current year nondeductible goodwill impairments at AES Andes and AES El Salvador, as well as the current year asset impairment of the Maritza coal-fired plant.
These impacts were partially offset by favorable LNG transactions at certain MCAC businesses and inflationary and foreign currency impacts at certain Argentine businesses recognized in 2022.
See Note 9—*Goodwill and Other Intangible Assets* included in Item 8.—*Financial Statements and Supplementary Data* of this Form 10-K for details of the goodwill impairments.
Fluence completed its IPO and began trading in November 2021.
Adjusted EPS, a non-GAAP measure, increased $0.08, from $1.44 to $1.52, mainly reflecting higher contributions from our US and Utilities SBU, including new renewables and Southland Energy, higher generation at Chivor due to the life extension project completed in the prior year and better hydrology, and lower Parent Company interest expense due to realized gains on de-designated interest rate swaps and lower interest rates; partially offset by a higher adjusted tax rate, lower contributions from Brazil due to the prior year revision of the GSF liability and drier hydrology, the prior year impacts of a gain on sale of land in the U.S., incremental capitalized interest in Chile, and recovery of previously expensed payments from customers in Chile; and the impact of the inclusion of shares underlying the purchase contract component of our March 2021 equity units issuance.
*Consolidated Revenue* *—* Revenue decreased $529 million, or 5%, in 2020 compared to 2019, driven by:
- $219 million in Eurasia driven by the sale of the Northern Ireland businesses in June 2019 and lower generation in Vietnam;
- $140 million in US and Utilities mainly driven by a decrease in energy pass-through rates and lower demand due to the COVID-19 pandemic in El Salvador, lower regulated rates as a result of the changes in AES Ohio's ESP, lower retail sales demand at AES Indiana and DPL primarily due to milder weather and COVID-19 pandemic impacts, and decreased capacity sales, at Southland due to unit retirements, and at DPL due to the sale and closure of generation facilities.
These decreases were partially offset by increased capacity sales at Southland Energy due to the commencement of the PPAs;
- $116 million in MCAC mainly driven by lower generation and volume pass-through fuel revenue in Mexico, the disconnection of the Estrella del Mar I power barge from the grid in Panama, and lower market prices,
spot sales and demand in both the Dominican Republic and at the Colon combined cycle facility in Panama.
- $370 million in South America primarily due to the drivers discussed above, as well as a $184 million favorable revision to the GSF liability at Tietê related to the passage of a regulation providing concession extensions to hydro plants as compensation for prior period non-hydrological risk charges incorrectly assessed by the regulator; and
- $72 million in MCAC mostly due to higher availability at Changuinola due to the tunnel lining upgrade in 2019, improved hydrology in Panama, and higher LNG sales in the Dominican Republic, partially offset by prior year insurance recoveries associated with the lightning incident at the Andres facility in 2018, current year outage due to Andres steam turbine failure, and the disconnection of the Estrella del Mar I power barge from the grid in Panama.
These favorable impacts were partially offset by a decrease of $116 million in US and Utilities mostly due to lower regulated rates as a result of the changes in AES Ohio's ESP, lower retail sales demand at DPL and AES Indiana primarily due to milder weather and COVID-19 pandemic impacts, lower capacity sales due to the retirement of units at Southland, a favorable revision to the ARO at DPL, and cost recoveries from DPL's joint owners of Stuart and Killen in 2019, partially offset by increased capacity sales at Southland Energy due to the commencement of the PPAs, and lower depreciation expense at Southland due to the extension of the water board permits.
General and administrative expenses decreased $31 million, or 16%, to $165 million for 2020 compared to $196 million for 2019, primarily due to a higher reallocation of information technology costs to the SBUs and lower professional fees, partially offset by higher development costs.
Interest expense decreased $12 million, or 1%, to $1,038 million for 2020, compared to $1,050 million for 2019 primarily due to incremental capitalized interest in Chile and lower interest rates due to refinancing at the Parent Company, partially offset by lower capitalized interest due to the commencement of operations at the Alamitos and Huntington Beach facilities in February 2020.
Interest income decreased $50 million, or 16%, to $268 million for 2020, compared to $318 million for 2019 primarily due to the decrease of the LIBOR rate on receivables in Argentina, a lower loan receivable balance at Mong Duong, and a lower average interest rate at AES Brasil.
Loss on extinguishment of debt increased $17 million, or 10% to $186 million for 2020, compared to $169 million for 2019.
This increase was primarily due to the increases mentioned above partially offset by losses of $45 million at DPL, $31 million at Mong Duong, $29 million at AES Andes, $28 million at Colon, and $24 million at Cochrane in 2019 resulting from the redemption or refinancing of senior notes.
Other income decreased $70 million, or 48% to $75 million for 2020, compared to $145 million for 2019 primarily due to 2019 gains on insurance recoveries associated with property damage at the Andres facility and upgrading the tunnel lining at Changuinola, partially offset by the 2020 gain on sale of Redondo Beach land at Southland.
Other expense decreased $27 million, or 34% to $53 million for 2020, compared to $80 million for 2019 primarily due to 2019 losses recognized at commencement of sales-type leases at AES Renewable Holdings, the 2019 loss on disposal of assets at Changuinola associated with upgrading the tunnel lining, and lower defined benefit plan costs at AES Indiana in 2020, partially offset by a loss on sale of Stabilization Fund receivables in Chile and compliance with an arbitration decision in 2020.
Loss on disposal and sale of business interests was $95 million for 2020, primarily due to the loss on sale of Uruguaiana and the loss on the settlement of the arbitration related to the sale of Kazakhstan HPPs, partially offset by the gain on sale of OPGC; as compared to a gain of $28 million for 2019, primarily due to the gain on sale of a portion of our interest in sPower's operating assets, the gain on the merger of Simple Energy to form Uplight, and the gain on transfer of Stuart and Killen, partially offset by the loss on sale of Kilroot and Ballylumford.
Asset impairment expense increased $679 million to $864 million for 2020, compared to $185 million for 2019.
This increase was primarily driven by a $781 million impairment related to certain coal-fired plants at AES Andes and a $30 million impairment of the Estrella del Mar I power barge in Panama, compared to a $115 million impairment at Kilroot and Ballylumford upon meeting the held-for-sale criteria in 2019.
| | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
There were no other non-operating expenses during the year ended December 31, 2021.
Income tax expense decreased $136 million to $216 million in 2020 as compared to $352 million for 2019.
Further, the 2019 rate was impacted by the nondeductible losses on the sale of the Company's entire 100% interest in the Kilroot coal and oil-fired plant and energy storage facility and the Ballylumford gas-fired plant in the United Kingdom and associated asset impairments.
Further impacting the 2019 effective tax rate were the effects of the Argentine peso devaluation to tax expense, as well as to pretax income for nondeductible unrealized losses on foreign currency derivatives related to government receivables in Argentina.
A future
Net equity in losses of affiliates decreased $49 million, or 28%, to $123 million in 2020, compared to $172 million in 2019.
This was primarily driven by a $31 million increase in earnings due to lower long-lived asset impairments at Guacolda, AES Andes' 50%-owned equity affiliate, during 2020 as compared to 2019.
- Lower earnings in Chile due to long-lived asset impairments at AES Andes, partially offset by net gains from early contract terminations at Angamos and lower interest expense due to incremental capitalized interest;
- Lower earnings in Colombia due to drier hydrology and a life extension project at the Chivor hydroelectric plant;
- Prior year insurance recoveries net of outages at Andres; and
- Higher earnings in Brazil due to the favorable revision of the GSF liability; and
- Prior year losses on extinguishment of debt at Mong Duong and Colon.
Net income attributable to The AES Corporation decreased $257 million, or 85% to $46 million in 2020, compared to $303 million in 2019.
- Net impact of current and prior year other-than-temporary impairments of OPGC;
- Higher losses on extinguishment of debt in the current year, primarily due to major refinancings at the Parent Company;
- Lower margins at our US and Utilities SBU;
- Losses on sale of Uruguaiana and the Kazakhstan HPPs as a result of the final arbitration decision; and
An excerpt. Shown here: 40 of 429 rewritten, 40 of 215 added and 40 of 214 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2022 filing and the FY2021 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
12 rewritten, 5 added, 4 removed, 70 unchanged
For further information regarding market risk, see Item 1A.—*[Risk [removed: Factors](#if7b552d0c82e4d75af26724d7276acc2_58)*,] [added: Factors](#i84f31ef528bc41899c5480059e42eda9_58)*,] *Fluctuations in currency exchange rates may impact our financial results and position*; *Wholesale power prices may experience significant volatility in our markets which could impact our operations and opportunities for future growth;* *We may not be adequately hedged against our exposure to changes in commodity prices or interest rates; and Certain of our businesses are sensitive to variations in weather and hydrology* of this [removed: 2021] [added: 2022] Form 10-K.
Although we prefer to hedge our exposure to the impact of market fluctuations in the price of electricity, fuels, and environmental credits, some of our generation businesses operate under short-term [removed: sales] [added: sales, have contracted electricity obligations greater than supply] or [added: operate] under contract sales that leave an unhedged exposure on some of our capacity or through imperfect fuel pass-throughs.
For [removed: 2022,] [added: 2023,] we project pre-tax earnings exposure on a 10% (uncorrelated) move in commodity prices to be approximately a $5 million gain for [removed: power and oil,] [added: power,] a [removed: $5] [added: $10] million loss for [removed: coal,] [added: oil,] and a [removed: $15] [added: $5] million loss for [added: coal and] natural gas.
[added: In aggregate, the Company's downside exposure occurs] with lower power, lower oil, higher natural gas, and higher coal prices.
Due to variation of timing and amount between cash distributions and earnings exposure, the hedge impact may not fully cover the earnings exposure on [removed: a realized basis, which could result in greater volatility in earnings.]
The largest foreign exchange risks [removed: over a 12-month forward-looking period] [added: for 2023] stem from the following currencies: Brazilian [removed: real, Colombian peso,] [added: real] and Euro.
As of December 31, [removed: 2021,] [added: 2022,] assuming a 10% USD appreciation, cash distributions attributable to foreign subsidiaries exposed to movement in the exchange rate [added: of the Brazilian real] are projected to be impacted by less than [removed: $(5)] [added: a $10] million [removed: for Brazilian real and] [added: gain, a] less than $5 million [removed: each] [added: gain] for [added: the] Colombian peso and [added: a less than $5 million loss for the] Euro.
These numbers have been produced by applying a one-time 10% USD appreciation to forecasted exposed cash distributions for [removed: 2022] [added: 2023] coming from the respective subsidiaries exposed to the currencies listed above, net of the impact of outstanding hedges and holding all other variables constant.
We are exposed to risk resulting from changes in interest rates as a result of our issuance of [removed: variable-rate] [added: variable] and fixed-rate debt, as well as interest rate swap, cap, floor, and option agreements.
Depending on whether a plant's capacity payments or revenue stream is fixed or varies with inflation, we partially hedge against interest rate fluctuations by arranging [removed: fixed-] [added: fixed-rate] or variable-rate financing.
As of December 31, [removed: 2021,] [added: 2022,] the portfolio's pre-tax earnings exposure for [removed: 2022] [added: 2023] to a one-time 100-basis-point increase in interest rates for our Argentine peso, Brazilian real, Chilean peso, Colombian peso, Euro, and USD denominated debt would be [removed: approximately $20] [added: less than $55] million on interest expense for the debt denominated in these currencies.
| 122 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
At Southland, our existing once-through cooling generation units (“Legacy Assets”) are permitted to operate through the end of 2023.
Our exposure to certain of these currencies may be material.
| 123 \| 2022 Annual Report | | | | | |
a realized basis, which could result in greater volatility in earnings.
| 124 \| 2022 Annual Report | | | | | |
In aggregate, the Company's downside exposure occurs
| 120 \| 2021 Annual Report | | | | | |
At Southland, our existing once-through cooling generation units (“Legacy Assets”) have been requested to continue operating beyond their current retirement date and have been approved for an extended permit for between one and three years.
| 121 \| 2021 Annual Report | | | | | |
Item 1. BUSINESS
422 rewritten, 277 added, 200 removed, 934 unchanged
Additional items that may have an impact on our businesses are discussed in Item 1A.—*[Risk [removed: Factors](#if7b552d0c82e4d75af26724d7276acc2_58)*] [added: Factors](#i84f31ef528bc41899c5480059e42eda9_58)*] and Item 3.—*[Legal [removed: Proceedings](#if7b552d0c82e4d75af26724d7276acc2_67)*.][added: Proceedings](#i84f31ef528bc41899c5480059e42eda9_67)*.]
| 5 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
[removed: 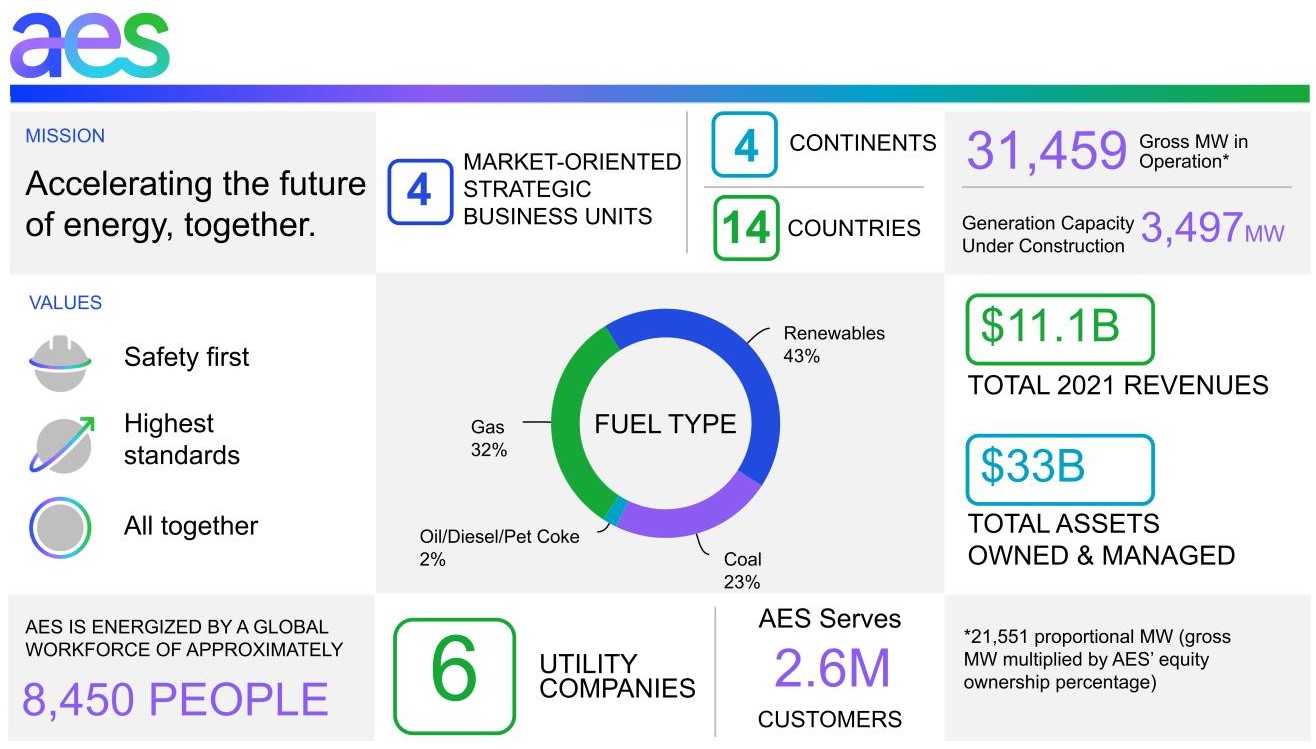][added: 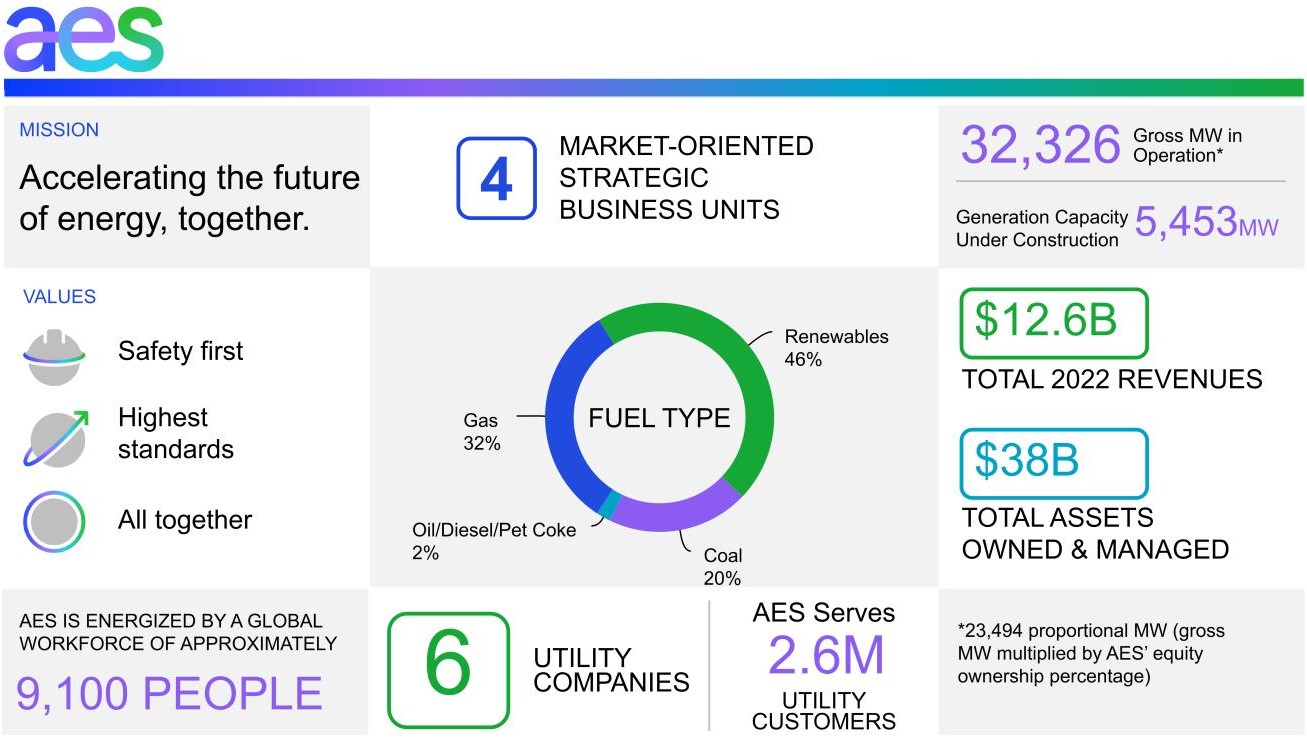]
AES is an industry leader in developing and [removed: growing] [added: operating] the solutions that will enable the transition to [added: zero and] low-carbon sources of energy and achievement of the Paris Agreement's goal of net-zero emissions by 2050.
In [removed: 2021,] [added: 2022,] we signed long-term contracts for [removed: approximately 5] [added: 5.2] GW of renewable power, bringing our backlog of projects — those with signed contracts, but which are not yet in operation — to [removed: 9.2] [added: 12.2] GW.
Central to our renewables growth strategy is a focus on customer collaboration and co-creation, which helps us develop unique solutions [removed: based on] [added: tailored to a] specific [removed: customer] [added: customer's] needs.
This approach has led to the co-creation of several first-of-its-kind industry innovations, including [removed: an agreement] [added: agreements] to supply 24/7 carbon-free energy for [removed: Google's data centers in Virginia, ensuring that the energy powering those] [added: global] data [removed: centers will be 90% carbon-free when measured on an hourly basis.][added: center companies.]
| 6 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
[removed: One way in which we are serving the] mining industry is through our Green Blend offering, in which we work to integrate renewable energy with thermal power during select hours of the day, reducing overall thermal generation and lowering emissions.
At AES Indiana, for example, we are working to retire [removed: an additional 415 MW of conventional] [added: its remaining coal] generation by [removed: 2023,] [added: the end of 2025,] while adding new [removed: solar] [added: renewables] and [removed: energy storage] [added: natural gas] to the grid.
We massively expanded our pipeline of development projects, which grew [removed: 70% to more than] [added: from] 55 GW [removed: at] [added: in January 2022 to 64 GW as of] the end of [removed: 2021,] [added: 2022,] both through acquisitions and increased investment in development activities, such as securing land or advancing permitting and interconnection processes.
AES Next works to identify new and innovative [added: technologies and] business [removed: ventures] [added: opportunities] that provide [added: or support] leading-edge [removed: and] greener energy solutions.
[removed: 2021] [added: 2022] Strategic Highlights
[removed: - We] [added: *•*We] signed [removed: 4,965] [added: 5,153] MW of renewables and energy storage under long-term PPAs, [removed: including:][added: including 2,553 MW of solar, wind and energy storage in the United States.]
We currently own and/or operate a generation portfolio of [removed: 31,459] [added: 32,326] MW, including generation from our integrated utility, AES Indiana.
| 7 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
[removed: These] contracts also help us to fund a significant portion of the total capital cost of the project through long-term non-recourse project-level financing.
| 8 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
For further information regarding commodity price risk please see Item 7A.—*[Quantitative and Qualitative Disclosures about Market [removed: Risk](#if7b552d0c82e4d75af26724d7276acc2_244)*] [added: Risk](#i84f31ef528bc41899c5480059e42eda9_262)*] in this Form 10-K.
[removed: 43%] [added: 46%] of the capacity of our generation plants are fueled by renewables, including hydro, solar, wind, energy storage, biomass and landfill gas, which do not have significant fuel costs.
[removed: A few exceptions to this are AES Andes in Chile, where we purchase imported gas from third parties, and] [added: With the exception of] our plants in the Dominican Republic and Panama, where we import LNG to utilize in the local [added: market, we use gas from local suppliers in each] market.
[removed: 23%] [added: 20%] of the capacity of our generation fleet is coal-fired.
At our non-U.S. generation plants, and at our [removed: plants] [added: plant] in [removed: Hawaii and] Puerto Rico, we source coal [removed: internationally.][added: from a mix of sources from the international market and in the local jurisdictions.]
[removed: Across our fleet,] [added: To the extent possible,] we utilize our global sourcing program to maximize the purchasing power of our fuel procurement.
AES' six utility businesses distribute power to 2.6 million [removed: people] [added: customers] and AES' two utilities in the U.S. also include generation capacity totaling [removed: 3,720] [added: 3,495] MW.
The asset base on which the utility is permitted a return is determined by the regulator, within the framework of applicable local laws, and is [added: based on the amount of assets that are considered used and useful in serving customers.]
| 9 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
[removed: Components of the tariff that are directly passed through to the] customer are usually adjusted through a summary regulatory process or an existing formula-based mechanism.
| 10 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
The Adjusted PTC by SBU for the year ended December 31, [removed: 2021] [added: 2022] is shown below.
See Item 7.—*[Management's Discussion and Analysis of Financial Condition and Results of Operations—SBU Performance [removed: Analysis](#if7b552d0c82e4d75af26724d7276acc2_157)*] [added: Analysis](#i84f31ef528bc41899c5480059e42eda9_160)*] of this Form 10-K for reconciliation and definitions of Adjusted PTC.
[removed: ][added: 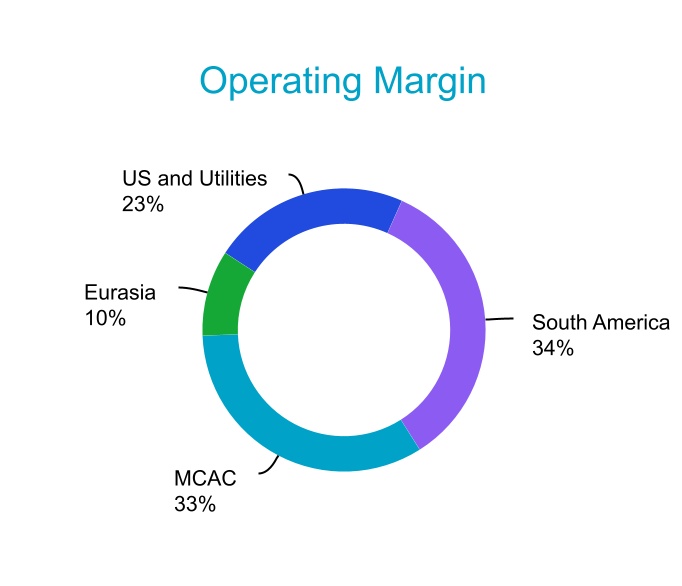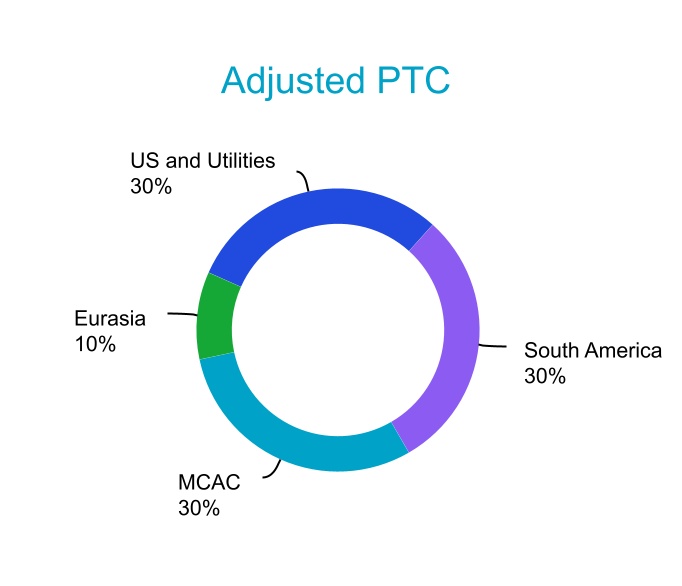]
See Item 7.—*[Management's Discussion and Analysis of Financial Condition and Results of [removed: Operations](#if7b552d0c82e4d75af26724d7276acc2_97)*] [added: Operations](#i84f31ef528bc41899c5480059e42eda9_100)*] and Note 18—*[Segment and Geographic [removed: Information](#if7b552d0c82e4d75af26724d7276acc2_319)*] [added: Information](#i84f31ef528bc41899c5480059e42eda9_340)*] included in Item 8.—*[Financial Statements and Supplementary [removed: Data](#if7b552d0c82e4d75af26724d7276acc2_247)*] [added: Data](#i84f31ef528bc41899c5480059e42eda9_265)*] of this Form 10-K for further discussion of the Company's segment structure.
| 11 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
[removed: 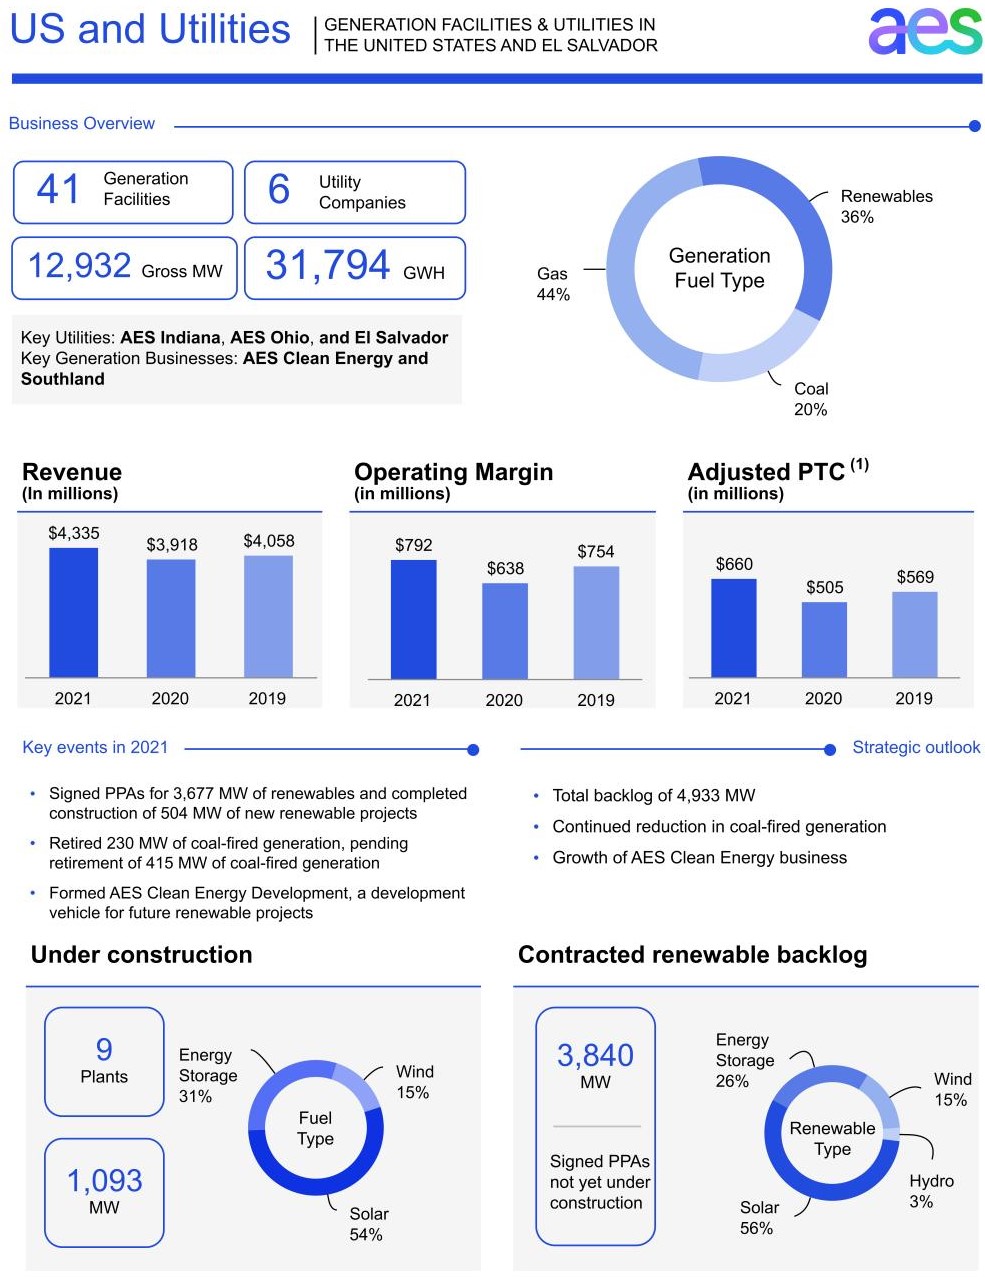][added: 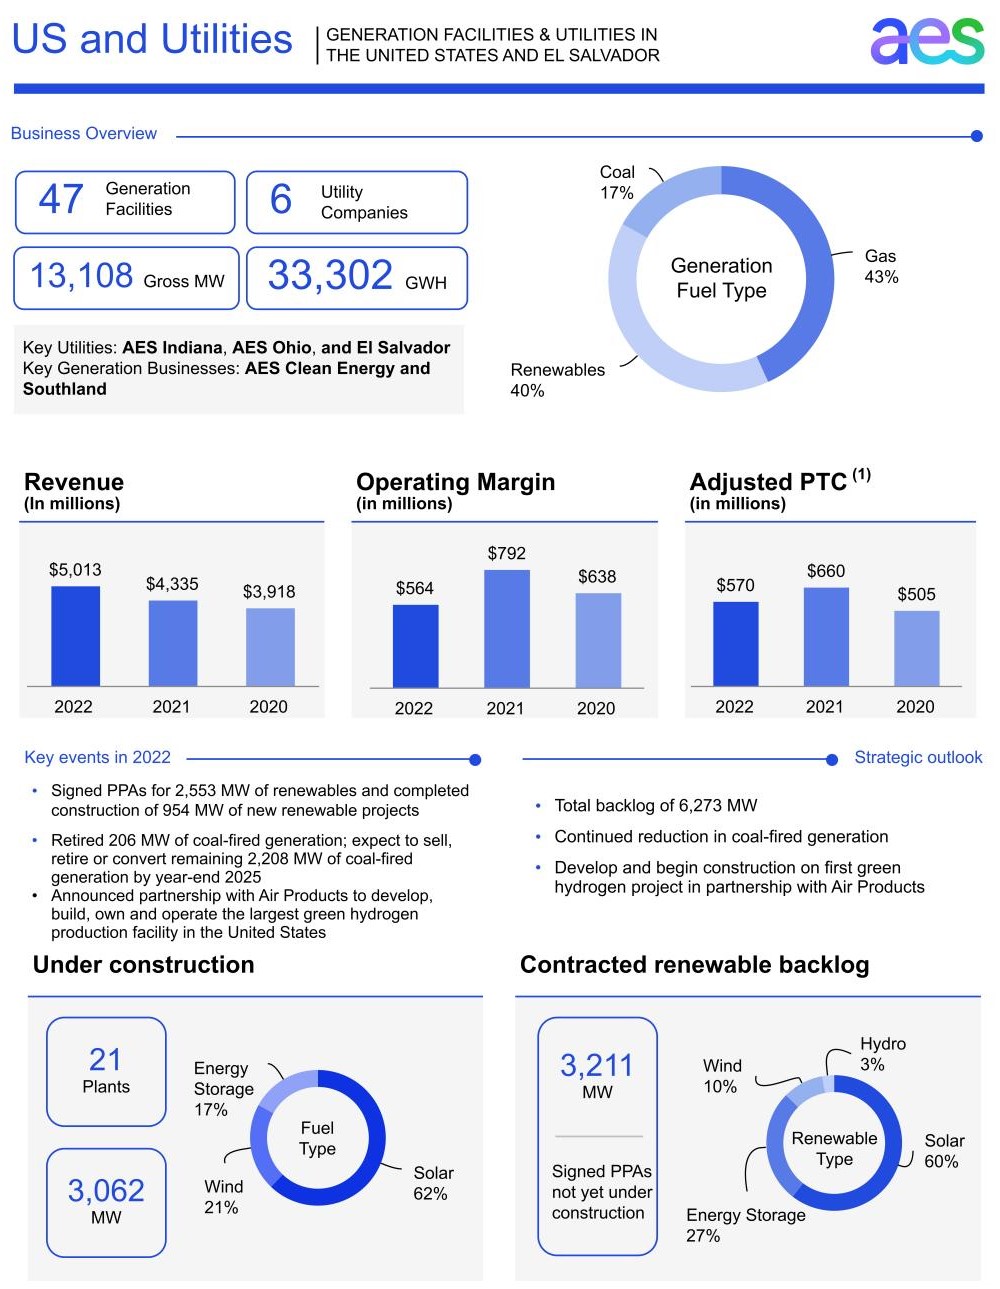]
| (1) Non-GAAP measure. See Item 7.—*[Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#if7b552d0c82e4d75af26724d7276acc2_97)—SBU] [added: Operations](#i84f31ef528bc41899c5480059e42eda9_100)—SBU] Performance Analysis—Non-GAAP Measures* for reconciliation and definition. | | | | | |
| 12 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
Our US and Utilities SBU has [removed: 41] [added: 47] generation facilities, two utilities in the United States, and four utilities in El Salvador.
*Generation* — Operating installed capacity of our US and Utilities SBU totals [removed: 12,932] [added: 13,108] MW.
| 13 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
The focus of our strategy continues to be on partnering with large companies that are looking to transition to carbon-free sources of electricity.
As an indication of our success, in 2022 we were recognized by BNEF as the #1 global clean energy developer for corporations.
Our unique capabilities in developing tailored energy solutions, enabled us to partner with Air Products to announce our plans to develop, build, own, and operate the largest green hydrogen production facility to date in the United States.
One way in which we are serving the
A substantial portion of our expected capital expenditures through 2025 will be related to the development of renewable projects.
- We completed the construction or acquisition of operating projects totaling 1,943 MW in the United States, Brazil, the Dominican Republic, Chile and Colombia, primarily wind, solar and energy storage.
- Our backlog, which includes projects with signed contracts, but which are not yet operational, is now 12,179 MW, consisting of:
◦5,453 MW under construction; and
◦6,726 MW with signed PPAs, but that are not yet under construction.
- We announced a partnership with Air Products to develop, build, own and operate the largest green hydrogen production facility to date in the United States.
◦Includes approximately 1.4 GW of wind and solar generation, along with electrolyzer capacity capable of producing over 200 metric tons per day (MT/D) of green hydrogen.
- The Company expects to announce certain internal management changes which will result in modifications to its financial reporting segments.
The financial performance of our renewables business is also impacted by our ability to complete construction projects and earn U.S. renewable tax credits.
These
Components of the tariff that are directly passed through to the
| Skipjack (2) (3) | | | | | | US-VA | | | | | | Solar | | | | | | 175 | | | | | | 75 | | % | | | | 2022 | | | | | | 2036 | | | | | | Exelon Generation Company | | |
| Central Line (sPower OpCo B (1)) | | | | | | US-AZ | | | | | | Solar | | | | | | 100 | | | | | | 50 | | % | | | | 2022 | | | | | | 2039 | | | | | | Salt River Project Agricultural Improvement & Power District | | |
| Big Island Waikoloa (3) (4) | | | | | | US-HI | | | | | | Solar | | | | | | 25 | | | | | | 100 | | % | | | | 2022 | | | | | | | | | | | | | | |
| Community Energy (2) | | | | | | US-Various | | | | | | Solar | | | | | | 14 | | | | | | 75 | | % | | | | 2022 | | | | | | 2023-2043 | | | | | | Various | | |
| | | | | | | | | | | | | | | | | | | 9,613 | | | | | | | | | | | | | | | | | | | | | | | | | | |
(2)Owned by AES Clean Energy Development ("ACED").
(4)Owned by AES Renewable Holdings.
(5)On December 1, 2022, Southland Energy sold an additional 14.9% ownership interest in the Southland Energy assets.
Following the sale, AES holds 50.1% of Southland Energy's interest and this business continues to be consolidated by AES.
(6)Facility experienced a fire event in April 2022 which rendered the asset currently inoperable.
| AES Ohio (1) | | | | | | US-OH | | | | | | 536,000 | | | | | | 13,875 | | | | | | | | | | | | | | | | | | 100 | | % | | | | 2011 | | |
| | | | | | | | | | | | | 2,603,000 | | | | | | 33,302 | | | | | | | | | | | | | | | | | | | | | | | | | | |
AES Indiana plans to convert the remaining two coal units at Petersburg to natural gas by the end of 2025.
| Cement City (1) | | | | | | US-MI | | | | | | Solar | | | | | | 20 | | | | | | 75 | | % | | | | 1H 2023 | | |
| Big Island Waikoloa (2) | | | | | | US-HI | | | | | | Solar | | | | | | 5 | | | | | | 100 | | % | | | | 1H 2023 | | |
| West Oahu Solar (2) | | | | | | US-HI | | | | | | Solar | | | | | | 13 | | | | | | 100 | | % | | | | 1H 2023 | | |
| | | | | | | Energy Storage | | | | | | 13 | | | | | | | | | | | | | | | | | | | | |
| High Mesa (1) | | | | | | US-CO | | | | | | Solar | | | | | | 10 | | | | | | 75 | | % | | | | 1H 2023 | | |
| | | | | | | Energy Storage | | | | | | 10 | | | | | | | | | | | | | | | | | | | | |
| Meanguera del Golfo | | | | | | El Salvador | | | | | | Solar | | | | | | 1 | | | | | | 100 | | % | | | | 1H 2023 | | |
| | | | | | | Energy Storage | | | | | | 4 | | | | | | | | | | | | | | | | | | | | |
| Great Cove 1&2 (1) | | | | | | US-PA | | | | | | Solar | | | | | | 220 | | | | | | 75 | | % | | | | 2H 2023 | | |
| Chevelon Butte (1) | | | | | | US-AZ | | | | | | Wind | | | | | | 238 | | | | | | 75 | | % | | | | 2H 2023 | | |
| McFarland Phase 1 (1) | | | | | | US-AZ | | | | | | Solar | | | | | | 200 | | | | | | 75 | | % | | | | 2H 2023 | | |
| | | | | | | Energy Storage | | | | | | 100 | | | | | | | | | | | | | | | | | | | | |
At the core of AES' strategy is a dual focus on: (1) growing our portfolio of low-carbon products and solutions; and (2) working to develop and incubate new solutions and business models which will help drive change in the industry in the future.
In 2021, we signed a total of approximately 2 GW of other innovative structures with various customers on a bilateral basis.
AES Next identifies upcoming trends in the industry and opportunities for innovation.
From there, we either develop capabilities in house or make strategic investments in third-party ventures, targeting those in which we see benefit to our overall portfolio and where we believe AES can add value.
*•*We completed construction or the acquisition of 2,079 MW of renewables and energy storage, primarily including:
◦1,129 MW of solar, wind and energy storage in the U.S.;
◦859 MW of hydro, wind, energy storage and solar in Chile, Brazil, and Colombia; and
◦91 MW of solar in Panama and the Dominican Republic
◦3,677 MW of wind, solar, energy storage, and hydro in the U.S. and El Salvador;
◦799 MW of wind in Brazil;
◦334 MW of wind, energy storage, and solar in Chile and Colombia; and
◦155 MW of solar in Panama and the Dominican Republic
- Our backlog of 9,239 MW includes:
◦3,497 MW under construction and coming online through 2024; and
◦5,742 MW of renewables signed under long-term PPAs
- Fluence completed its Initial Public Offering ("IPO") in November 2021, and following the IPO, our ownership interest is approximately 34%
Generally, we use gas from local suppliers in each market.
based on the amount of assets that are considered used and useful in serving customers.
| Hawaii (4) | | | | | | US-HI | | | | | | Coal | | | | | | 206 | | | | | | 100 | | % | | | | 1992 | | | | | | 2022 | | | | | | Hawaiian Electric Co. | | |
| Laurel Mountain | | | | | | US-WV | | | | | | Wind | | | | | | 98 | | | | | | 100 | | % | | | | 2011 | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | 9,212 | | | | | | | | | | | | | | | | | | | | | | | | | | |
(2)AES was entitled to 100% of earnings or losses until March 1, 2021, and any distributions related thereto.
(4)In November 2020, announced expected retirement in 2022.
| DPL (1) | | | | | | US-OH | | | | | | 534,000 | | | | | | 13,837 | | | | | | | | | | | | | | | | | | 100 | | % | | | | 2011 | | |
| | | | | | | | | | | | | 2,563,000 | | | | | | 31,794 | | | | | | | | | | | | | | | | | | | | | | | | | | |
AES Indiana issued an all-source Request for Proposal in December 2019 in order to competitively procure replacement capacity.
| AES Clean Energy (AES Renewable Holdings) | | | | | | US-Various | | | | | | Solar | | | | | | 247 | | | | | | 100 | | % | | | | 1H 2022 | | |
| Skipjack (AES Clean Energy) | | | | | | US-VA | | | | | | Solar | | | | | | 175 | | | | | | 75 | | % | | | | 1H 2022 | | |
| Mountain View Repowering (AES Clean Energy) | | | | | | US-CA | | | | | | Wind | | | | | | 66 | | | | | | 75 | | % | | | | 2H 2022 | | |
| Antelope Expansion 1B (AES Clean Energy/sPower) | | | | | | US-CA | | | | | | Solar | | | | | | 18 | | | | | | 50 | | % | | | | 1H 2022 | | |
| | | | | | | | | | | | | | | | | | | 1,093 | | | | | | | | | | | | | | |
The total
The IRP includes the retirement of approximately 630 MW of coal-fired generation by 2023.
Based on extensive modeling, AES Indiana determined that the cost of operating Petersburg Units 1 and 2 exceeds the value customers receive compared to alternative resources.
Retirement of these units allows the company to cost-effectively diversify the portfolio and transition to lower cost and cleaner resources while maintaining a reliable system.
AES Indiana retired 230 MW Petersburg Unit 1 on May 31, 2021 and has plans to retire 415 MW Petersburg Unit 2 in 2023, which will result in 630 MW of total retired economic capacity at this station.
AES Indiana issued an all-source Request for Proposal in December 2019, in order to competitively procure replacement capacity by June 1, 2023, which is the first year AES Indiana is expected to have a capacity shortfall.
Modeling indicated that a combination of wind, solar, storage, and energy efficiency would be the lowest reasonable cost option for the replacement capacity, but AES Indiana continues to assess the type, size, and location of resources in the bids it received.
On November 30, 2020, AES Ohio filed a new Distribution Rate Case Application proposing a revenue increase of $121 million per year and incorporating DIR investments that were planned and approved in the last rate case but not yet included in distribution rates, other distribution investments since September 2015, investments necessitated by the tornados that occurred on Memorial Day in 2019, and other proposed increases.
The rate case also includes a proposal for increased tree-trimming expenses and certain customer demand-side management programs and recovery of prior-approved regulatory assets for tree trimming, uncollectible expenses and rate case expense.
An excerpt. Shown here: 40 of 422 rewritten, 40 of 277 added and 40 of 200 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2022 filing and the FY2021 filing.
Item 3. LEGAL PROCEEDINGS
25 rewritten, 42 added, 49 removed, 69 unchanged
It is reasonably possible, however, that some matters could be decided unfavorably to the Company and could require the Company to pay damages or make expenditures in amounts that could be material, but cannot be estimated as of December 31, [removed: 2021.][added: 2022.]
[removed: GRIDCO appeared to be seeking approximately $189 million in damages, plus] undisclosed penalties and interest, but a detailed alleged damage analysis was not filed by GRIDCO.
In June 2007, a 2-to-1 majority of the arbitral tribunal rendered its award rejecting GRIDCO's claims and holding that none of the respondents, the Company, AES ODPL, or Jyoti, had [added: any liability to GRIDCO.]
| [removed: 74] [added: 76] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
The removal and remediation costs are estimated to be approximately [removed: R$10] [added: R$15] million to [removed: R$41] [added: R$60] million [removed: ($2] [added: ($3] million to [removed: $7] [added: $11] million), and there could be additional costs which cannot be estimated at this time.
In addition, in February 2016, AES Indiana received an NOV from the EPA alleging violations of [removed: NSR] [added: New Source Review] and other CAA regulations, the Indiana SIP, and the Title V operating permit at Petersburg Station.
On August 31, 2020, AES Indiana reached a settlement with the EPA, the DOJ and [removed: IDEM,] [added: the Indiana Department of Environmental Management (“IDEM”),] resolving these purported violations of the CAA at Petersburg Station.
The settlement agreement, in the form of a proposed judicial consent decree, was approved and entered by the U.S. District Court for the Southern District of Indiana on March 23, 2021, and includes, among other items, the following requirements: annual caps on NOx and SO2 emissions and more stringent emissions limits than AES Indiana's current Title V air permit; payment of civil penalties totaling $1.5 million; a $5 million environmental mitigation project consisting of the construction and operation of a new, non-emitting source of generation at the site; expenditure of $0.3 million on a state-only environmentally beneficial project to preserve [removed: local, ecologically-significant lands; and retirement of Units 1 and 2 prior to July 1, 2023.]
If AES Indiana does not meet the retirement obligation, it must install a Selective Non-Catalytic Reduction System [added: ("SNCR")] on Unit 4.
On May 26, 2020, CCC staff sent AES a [removed: Notice of Violation (NOV)] [added: NOV] directing AES to submit a Coastal Development Permit (“CDP”) application for the removal of the water pumps within the alleged wetlands.
AES has submitted the CDP to the permitting authority, the City of Redondo Beach (“the City”), with respect to [removed: AES’s] [added: AES’] plans to disable or remove the pumps.
On October 14, 2020, the City deemed the CDP application to be complete and indicated a public hearing will be required, at which [added: time AES must present additional information and analysis on the pumps within the alleged wetlands and the onsite electrical vaults.]
| [removed: 75] [added: 77] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
[removed: Each of Alto Maipo, AES Andes, and the] [added: The] Company believes [added: that] it has meritorious [removed: claims and/or] defenses [added: to the claims asserted against it] and will [removed: pursue its interests vigorously;] [added: defend itself vigorously in these proceedings;] however, there can be no assurances that [removed: each] [added: it] will be successful in its efforts.
In October 2017, the Maritime Prosecution Office from Valparaíso issued a ruling alleging responsibility by AES Andes for the presence of coal waste on Ventanas beach, and proposed a fine before the Maritime [removed: Governor.][added: Governor, of approximately $395,000.]
In May 2021, AES Andes was notified of an amended Opinion of the Maritime Prosecution Office which extends the alleged liability to a third party and [added: reduces the proposed fine to AES Andes to approximately $372,000.]
| [removed: 76] [added: 78] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
AES Andes believes that it has meritorious defenses to the allegations; however, there are no assurances [removed: that] it will be [removed: successful in defending this action.][added: successful.]
The lawsuit does not identify, or provide any supporting information concerning, the alleged injuries of the claimants [removed: individually.][added: individually, nor does the lawsuit provide any information supporting the demand for damages or explaining how the quantum was derived.]
CFE makes allegations that AES Mérida III is in breach of its obligations under a power and capacity purchase agreement [removed: ("Contract")] [added: (“Contract”)] between the two parties, which allegations [removed: relate] [added: related] to CFE’s own failure to provide fuel within the specifications of the Contract.
CFE seeks to recover approximately [removed: $190] [added: $200] million in payments made to AES [removed: Merida] [added: Mérida] under the Contract as well as approximately [removed: $431] [added: $480] million in alleged damages for having to acquire [removed: power from alternative sources in the Yucatan Peninsula.]
Closing arguments [removed: are scheduled for] [added: were heard in] May 2022.
AES Mérida believes that it has meritorious defenses and claims and will assert them vigorously in [removed: the arbitration;] [added: this dispute;] however, there can be no assurances that it will be successful in its efforts.
| [removed: 77] [added: 79] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
[added: The lawsuit generally alleges] that the CCRs caused personal injuries and deaths and demands over $600 million in alleged damages.
GRIDCO appeared to be seeking approximately $189 million in damages, plus
In October 2015, AES Indiana received an NOV alleging violations of the Clean Air Act (“CAA”), the Indiana State Implementation Plan (“SIP”), and the Title V operating permit related to alleged particulate and opacity violations at Petersburg Station Unit 3.
local, ecologically-significant lands; and retirement of Units 1 and 2 prior to July 1, 2023.
In April 2022, Puerto Ventanas requested that the Maritime Authority join this proceeding with a parallel proceeding; however, the request was rejected.
In May 2022, the General Director of the Maritime Territory and Merchant Marine of the Chilean Navy rejected AES Andes’ appeal and imposed a fine of $341,363.
AES Andes will continue with administrative appeals.
Preliminary hearings have taken place and are ongoing.
On January 17, 2023, the SMA approved street paving measures, or alternatively a program providing heaters for community members, as the means to satisfy the air emissions offsets in the approved Compliance Plan.
power from alternative sources in the Yucatan Peninsula.
In November 2022, the arbitration Tribunal issued its decision in the case, rejecting CFE’s claims for damages and granting AES Mérida a net amount of damages on AES Mérida’s counterclaims.
It is unclear whether CFE will comply with the decision or will attempt to challenge it.
On May 12, 2021, the Mexican Federal Attorney for Environmental Protection (the “Authority”) initiated an environmental audit at the Termoelectrica del Golfo (“TEG”) and Termoelectrica del Peñoles (“TEP”) thermal generating facilities.
On July 15, 2022, TEG was notified of the resolution issued by the Authority, which alleges breaches of air emission regulations, including failure to submit reports.
The resolution imposes a fine of $8,467,360 pesos (approximately USD $400,000).
The facility filed a nullity judgment to challenge the resolution, and on September 8, 2022, a provisional injunction was granted by the Tribunal, subject to TEG’s presentation of a warranty, which could include a corporate guaranty or bail.
The provisional injunction temporarily suspends the obligation to pay the fine while the Tribunal considers a definitive injunction, and potentially, a sentence dismissing the fine.
On December 2, 2022, TEG presented a bail as guarantee for the injunction, which was rejected by the local tax authority.
TEG challenged the tax authority's denial through an amparo claim on January 10, 2023.
No resolution for TEP’s audit has been issued, and on September 9, 2022, TEP filed an amparo claim challenging the inaction of the Authority on the environmental audit.
The amparo claim was admitted on October 17, 2022.
On July 25, 2022, AES Puerto Rico, LP (“AES-PR”) received from the EPA an NOV alleging certain violations of the CAA at AES-PR’s coal-fired power facility in Guayama, Puerto Rico.
The NOV alleges AES-PR exceeded an emission limit and did not continuously operate certain monitoring equipment, conduct certain analyses and testing, maintain complete records, and submit certain reports as required by the EPA’s Mercury and Air Toxics Standards.
The NOV further alleges AES-PR did not comply fully with the facility’s Title V operating permit.
AES-PR is engaging in discussions with the EPA about the NOV.
AES-PR will defend its interests, but we cannot predict the outcome of this matter at this time.
However, settlements and litigated outcomes of CAA claims alleged against other coal-fired power plants have required companies to pay civil penalties and undertake remedial measures.
In April 2022, the Superintendency of the Environment (the "SMA") notified AES Andes of certain alleged breaches associated with the construction of the Mesamávida wind project, initiating a sanctioning process.
The alleged charges include untimely implementation of road improvement measures and road use schedules and the failure to identify all noise receptors closest to the first construction phases of the project.
On June 23, 2022, the SMA addressed the charges to Energía Eólica Mesamávida SpA.
On June 28, 2022, Energía Eólica Mesamávida SpA submitted a proposed compliance program, with an estimated cost of $4.3 million, which was subsequently approved by the SMA.
On November 9, 2022, opponents to the project submitted before the Third Environmental Court a judicial action challenging the approval of this compliance program.
If the third-party appeal is successful or if the SMA determines there is an unsatisfactory execution of this compliance program, fines are possible.
AES Andes believes that it has meritorious defenses to the third-party challenge and will defend itself vigorously in these proceedings; however, there can be no assurances that it will be successful in its efforts.
In September 2022, the SMA initiated sanctioning proceedings against the Cochrane Power Station on four alleged charges, including one instance of noncompliance categorized as “serious” with the Environmental Qualification Resolution (RCA).
The allegations included structural and monitoring deficiencies, as well as an unauthorized underwater outfall discharging from the facility.
On December 12, 2022, AES Andes submitted a
proposed compliance program to the SMA, with an estimated cost of approximately $340,000, which is currently under review.
Fines are possible if the SMA does not approve the compliance program or if the SMA determines that the compliance program was not executed to its satisfaction.
On January 26, 2023, the SMA notified Alto Maipo SpA of four alleged charges relating to the Alto Maipo facility, all which are categorized by the SMA as “serious.” The alleged charges include untimely completion of intake works and insufficient capture by the provisional works, irrigation water outlet and canal contemplated by an agreement with local communities; non-compliance with the details of the forest management plans and intervention in unauthorized areas; construction of a road in a restricted paleontological area; and unlawful moving of fauna.
The Alto Maipo project intends to submit a compliance program for consideration by the SMA.
any liability to GRIDCO.
In February 2017, the EPA issued a NOV for DPL Stuart Station, alleging violations of opacity in 2016.
On May 31, 2018, Stuart Station was retired, and on December 20, 2019, it was transferred to an unaffiliated third-party purchaser, along with the associated environmental liabilities.
In October 2015, AES Indiana received a similar NOV alleging violations at Petersburg Station.
time AES must present additional information and analysis on the pumps within the alleged wetlands and the onsite electrical vaults.
In January 2017, the Superintendencia del Medio Ambiente (“SMA”) issued a Formulation of Charges asserting that Alto Maipo is in violation of certain conditions of the Environmental Approval Resolution (“RCA”) governing the construction of Alto Maipo’s hydropower project, for, among other things, operating vehicles at unauthorized times and failing to mitigate the impact of water infiltration during tunnel construction (“Infiltration Water”).
In February 2017, Alto Maipo submitted a compliance plan (“Compliance Plan”) to the SMA which, if approved by the agency, would resolve the matter without materially impacting construction of the project.
In April 2018, the SMA approved the Compliance Plan (“April 2018 Approval”).
Among other things, the Compliance Plan as approved by the SMA requires Alto Maipo to obtain from the Environmental Evaluation Service (“SEA”) a definitive interpretation of the RCA’s provisions concerning the authorized times to operate certain vehicles.
A number of lawsuits have been filed in relation to the April 2018 Approval.
These lawsuits were consolidated into one process in the Second Environmental Tribunal of Santiago ("Tribunal").
In October 2021, the Tribunal issued a ruling in favor of Alto Maipo and the SMA, upholding the validity of the Compliance Plan and dismissing all consolidated lawsuits.
This ruling was appealed.
The appeal is now in the Chilean Supreme Court, which is considering whether to accept the appeal.
Further, in January 2022, Alto Maipo received the definitive interpretation of the RCA´s provisions concerning the authorized times to operate certain vehicles.
Accordingly, Alto Maipo intends to request that the Compliance Plan be declared fulfilled and formally closed.
If the Compliance Plan is ultimately declared to be fulfilled and closed, and if the above-referenced appeal is dismissed, the Formulation of Charges will be discharged without penalty.
Otherwise, Alto Maipo could be subject to penalties, and the project could be negatively impacted.
Alto Maipo will pursue its interests vigorously in these matters; however, there can be no assurances that it will be successful in its efforts.
In June 2017, Alto Maipo terminated one of its contractors, Constructora Nuevo Maipo S.A. (“CNM”), given CNM’s stoppage of tunneling works, its failure to produce a completion plan, and its other breaches of contract.
Also, Alto Maipo drew $73 million under letters of credit (“LC Funds”) in connection with its termination of CNM.
Alto Maipo initiated arbitration against CNM to recover excess completion costs and other damages totaling at least $236 million (net of the LC Funds) relating to CNM’s breaches (“First Arbitration”).
CNM denied liability and sought a declaration that its termination was wrongful, damages allegedly resulting from that termination, and other relief.
CNM alleged that it was entitled to damages ranging from $70 million to $170 million (which included the LC Funds) plus interest and costs, based on various scenarios.
Alto Maipo contested these submissions.
The evidentiary hearing in the First Arbitration took place May 20-31, 2019, and closing arguments were heard June 9-10, 2020.
Also, in August 2018, CNM purported to initiate a separate arbitration against AES Andes and the Company (“Second Arbitration”).
In the Second Arbitration, CNM sought to pierce Alto Maipo’s corporate veil and appeared to seek an award holding AES Andes and the Company jointly and severally liable to pay any alleged net amounts that are found to be due to CNM in the First Arbitration or otherwise.
The Second Arbitration was consolidated into the First Arbitration.
In October 2021, the Tribunal issued a final and enforceable Partial Award in favor of Alto Maipo.
The Tribunal held, among other things, that Alto Maipo properly terminated the relevant tunneling contract and that Alto Maipo’s draw of the LC Funds was proper.
Also, the Tribunal determined that Alto Maipo was entitled to be paid additional damages of nearly $107 million (net after offsets) and that interest would accrue on the total amount of damages awarded until paid by CNM.
The Tribunal also dismissed the Second Arbitration as moot.
The Tribunal reserved for further proceedings, the issues of the interest to be paid by CNM and, as to all parties, the award of legal fees and costs.
To date, CNM has not paid the damages awarded to Alto Maipo.
Instead, CNM has made an application for an immaterial correction to the Partial Award.
CNM has also filed an application to revise the Partial Award seeking to reduce the net damages awarded to AM to approximately $42 million.
Alto Maipo will contest the application for revision.
In the meantime, the Tribunal has established the schedule for the next phase of the proceedings relating to interest, fees, and costs.
An evidentiary stage was concluded and then re-opened by order of the Maritime Governor on February 5, 2019 to allow AES Andes an opportunity to present reports and other evidence to challenge the grounds of the ruling.
An excerpt. Shown here: all 25 rewritten, 40 of 42 added and 40 of 49 removed. The counts are complete. For every sentence, read Item 3. LEGAL PROCEEDINGS in the FY2022 filing and the FY2021 filing.
Cover and table of contents
64 rewritten, 24 added, 20 removed, 306 unchanged
For the Fiscal Year Ended December 31, [removed: 2021][added: 2022]
[removed: ][added: ]
The aggregate market value of the voting and non-voting common equity held by non-affiliates on June 30, [removed: 2021,] [added: 2022,] the last business day of the Registrant's most recently completed second fiscal quarter (based on the closing sale price of [removed: $26.07] [added: $21.01] of the Registrant's Common Stock, as reported by the New York Stock Exchange on such date) was approximately [removed: $17.37] [added: $14.03] billion.
The number of shares outstanding of Registrant's Common Stock, par value $0.01 per share, on February [removed: 24, 2022] [added: 27, 2023] was [removed: 667,395,142.][added: 668,824,617.]
Portions of Registrant's Proxy Statement for its [removed: 2022] [added: 2023] annual meeting of stockholders are incorporated by reference in Parts II and III
The AES Corporation Fiscal Year [removed: 2021] [added: 2022] Form 10-K
| [Glossary of [removed: Terms](#if7b552d0c82e4d75af26724d7276acc2_7)] [added: Terms](#i84f31ef528bc41899c5480059e42eda9_7)] | | | [removed: [1](#if7b552d0c82e4d75af26724d7276acc2_10)] [added: [1](#i84f31ef528bc41899c5480059e42eda9_10)] | | |
| [ITEM 1. [removed: BUSINESS](#if7b552d0c82e4d75af26724d7276acc2_19)] [added: BUSINESS](#i84f31ef528bc41899c5480059e42eda9_19)] | | | [removed: [4](#if7b552d0c82e4d75af26724d7276acc2_19)] [added: [4](#i84f31ef528bc41899c5480059e42eda9_19)] | | |
| [ITEM 1A. RISK [removed: FACTORS](#if7b552d0c82e4d75af26724d7276acc2_58)] [added: FACTORS](#i84f31ef528bc41899c5480059e42eda9_58)] | | | [removed: [56](#if7b552d0c82e4d75af26724d7276acc2_58)] [added: [58](#i84f31ef528bc41899c5480059e42eda9_58)] | | |
| [ITEM 1B. UNRESOLVED STAFF [removed: COMMENTS](#if7b552d0c82e4d75af26724d7276acc2_61)] [added: COMMENTS](#i84f31ef528bc41899c5480059e42eda9_61)] | | | [removed: [73](#if7b552d0c82e4d75af26724d7276acc2_61)] [added: [75](#i84f31ef528bc41899c5480059e42eda9_61)] | | |
| [ITEM 2. [removed: PROPERTIES](#if7b552d0c82e4d75af26724d7276acc2_64)] [added: PROPERTIES](#i84f31ef528bc41899c5480059e42eda9_64)] | | | [removed: [73](#if7b552d0c82e4d75af26724d7276acc2_64)] [added: [75](#i84f31ef528bc41899c5480059e42eda9_64)] | | |
| [ITEM 3. LEGAL [removed: PROCEEDINGS](#if7b552d0c82e4d75af26724d7276acc2_67)] [added: PROCEEDINGS](#i84f31ef528bc41899c5480059e42eda9_67)] | | | [removed: [73](#if7b552d0c82e4d75af26724d7276acc2_67)] [added: [75](#i84f31ef528bc41899c5480059e42eda9_67)] | | |
| [ITEM 4. MINE SAFETY [removed: DISCLOSURES](#if7b552d0c82e4d75af26724d7276acc2_70)] [added: DISCLOSURES](#i84f31ef528bc41899c5480059e42eda9_70)] | | | [removed: [77](#if7b552d0c82e4d75af26724d7276acc2_70)] [added: [79](#i84f31ef528bc41899c5480059e42eda9_70)] | | |
| [ITEM 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY [removed: SECURITIES](#if7b552d0c82e4d75af26724d7276acc2_76)] [added: SECURITIES](#i84f31ef528bc41899c5480059e42eda9_76)] | | | [removed: [78](#if7b552d0c82e4d75af26724d7276acc2_76)] [added: [80](#i84f31ef528bc41899c5480059e42eda9_76)] | | |
| [ITEM 6. SELECTED FINANCIAL [removed: DATA](#if7b552d0c82e4d75af26724d7276acc2_94)] [added: DATA](#i84f31ef528bc41899c5480059e42eda9_97)] | | | [removed: [79](#if7b552d0c82e4d75af26724d7276acc2_94)] [added: [81](#i84f31ef528bc41899c5480059e42eda9_97)] | | |
| [ITEM 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF [removed: OPERATIONS](#if7b552d0c82e4d75af26724d7276acc2_97)] [added: OPERATIONS](#i84f31ef528bc41899c5480059e42eda9_100)] | | | [removed: [81](#if7b552d0c82e4d75af26724d7276acc2_97)] [added: [83](#i84f31ef528bc41899c5480059e42eda9_100)] | | |
| [Review of Consolidated Results of [removed: Operations](#if7b552d0c82e4d75af26724d7276acc2_103)] [added: Operations](#i84f31ef528bc41899c5480059e42eda9_106)] | | | [removed: [82](#if7b552d0c82e4d75af26724d7276acc2_103)] [added: [84](#i84f31ef528bc41899c5480059e42eda9_106)] | | |
| [SBU Performance [removed: Analysis](#if7b552d0c82e4d75af26724d7276acc2_157)] [added: Analysis](#i84f31ef528bc41899c5480059e42eda9_160)] | | | [removed: [90](#if7b552d0c82e4d75af26724d7276acc2_157)] [added: [93](#i84f31ef528bc41899c5480059e42eda9_160)] | | |
| [Key Trends and [removed: Uncertainties](#if7b552d0c82e4d75af26724d7276acc2_172)] [added: Uncertainties](#i84f31ef528bc41899c5480059e42eda9_175)] | | | [removed: [99](#if7b552d0c82e4d75af26724d7276acc2_172)] [added: [101](#i84f31ef528bc41899c5480059e42eda9_175)] | | |
| [Capital Resources and [removed: Liquidity](#if7b552d0c82e4d75af26724d7276acc2_208)] [added: Liquidity](#i84f31ef528bc41899c5480059e42eda9_226)] | | | [removed: [104](#if7b552d0c82e4d75af26724d7276acc2_208)] [added: [105](#i84f31ef528bc41899c5480059e42eda9_226)] | | |
| [Critical Accounting Policies and [removed: Estimates](#if7b552d0c82e4d75af26724d7276acc2_238)] [added: Estimates](#i84f31ef528bc41899c5480059e42eda9_256)] | | | [removed: [115](#if7b552d0c82e4d75af26724d7276acc2_238)] [added: [117](#i84f31ef528bc41899c5480059e42eda9_256)] | | |
| [ITEM 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET [removed: RISK](#if7b552d0c82e4d75af26724d7276acc2_244)] [added: RISK](#i84f31ef528bc41899c5480059e42eda9_262)] | | | [removed: [119](#if7b552d0c82e4d75af26724d7276acc2_244)] [added: [121](#i84f31ef528bc41899c5480059e42eda9_262)] | | |
| [ITEM 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY [removed: DATA](#if7b552d0c82e4d75af26724d7276acc2_247)] [added: DATA](#i84f31ef528bc41899c5480059e42eda9_265)] | | | [removed: [122](#if7b552d0c82e4d75af26724d7276acc2_247)] [added: [124](#i84f31ef528bc41899c5480059e42eda9_265)] | | |
| [Consolidated Statements of Comprehensive Income [removed: (Loss)](#if7b552d0c82e4d75af26724d7276acc2_256)] [added: (Loss)](#i84f31ef528bc41899c5480059e42eda9_277)] | | | [removed: [129](#if7b552d0c82e4d75af26724d7276acc2_256)] [added: [130](#i84f31ef528bc41899c5480059e42eda9_277)] | | |
| [Consolidated Statements of Changes in [removed: Equity](#if7b552d0c82e4d75af26724d7276acc2_259)] [added: Equity](#i84f31ef528bc41899c5480059e42eda9_280)] | | | [removed: [130](#if7b552d0c82e4d75af26724d7276acc2_259)] [added: [131](#i84f31ef528bc41899c5480059e42eda9_280)] | | |
| [Consolidated Statements of Cash [removed: Flows](#if7b552d0c82e4d75af26724d7276acc2_262)] [added: Flows](#i84f31ef528bc41899c5480059e42eda9_283)] | | | [removed: [131](#if7b552d0c82e4d75af26724d7276acc2_262)] [added: [132](#i84f31ef528bc41899c5480059e42eda9_283)] | | |
| [Note 1 - General and Summary of Significant Accounting [removed: Policies](#if7b552d0c82e4d75af26724d7276acc2_268)] [added: Policies](#i84f31ef528bc41899c5480059e42eda9_289)] | | | [removed: [132](#if7b552d0c82e4d75af26724d7276acc2_268)] [added: [133](#i84f31ef528bc41899c5480059e42eda9_289)] | | |
| [Note 2 - [removed: Inventory](#if7b552d0c82e4d75af26724d7276acc2_271)] [added: Inventory](#i84f31ef528bc41899c5480059e42eda9_292)] | | | [removed: [145](#if7b552d0c82e4d75af26724d7276acc2_271)] [added: [145](#i84f31ef528bc41899c5480059e42eda9_292)] | | |
| [Note 3 - Property, Plant and [removed: Equipment](#if7b552d0c82e4d75af26724d7276acc2_274)] [added: Equipment](#i84f31ef528bc41899c5480059e42eda9_295)] | | | [removed: [145](#if7b552d0c82e4d75af26724d7276acc2_274)] [added: [145](#i84f31ef528bc41899c5480059e42eda9_295)] | | |
| [Note 4 - Asset Retirement [removed: Obligation](#if7b552d0c82e4d75af26724d7276acc2_277)s] [added: Obligation](#i84f31ef528bc41899c5480059e42eda9_298)s] | | | [removed: [145](#if7b552d0c82e4d75af26724d7276acc2_277)] [added: [146](#i84f31ef528bc41899c5480059e42eda9_298)] | | |
| [Note 6 - Derivative Instruments and Hedging [removed: Activities](#if7b552d0c82e4d75af26724d7276acc2_283)] [added: Activities](#i84f31ef528bc41899c5480059e42eda9_304)] | | | [removed: [152](#if7b552d0c82e4d75af26724d7276acc2_283)] [added: [152](#i84f31ef528bc41899c5480059e42eda9_304)] | | |
| [Note 7 - Financing [removed: Receivables](#if7b552d0c82e4d75af26724d7276acc2_286)] [added: Receivables](#i84f31ef528bc41899c5480059e42eda9_307)] | | | [removed: [153](#if7b552d0c82e4d75af26724d7276acc2_286)] [added: [153](#i84f31ef528bc41899c5480059e42eda9_307)] | | |
| [Note 8 - Investments in and Advances to [removed: Affiliates](#if7b552d0c82e4d75af26724d7276acc2_289)] [added: Affiliates](#i84f31ef528bc41899c5480059e42eda9_310)] | | | [removed: [154](#if7b552d0c82e4d75af26724d7276acc2_289)] [added: [154](#i84f31ef528bc41899c5480059e42eda9_310)] | | |
| [Note 9 - Goodwill and Other Intangible [removed: Assets](#if7b552d0c82e4d75af26724d7276acc2_292)] [added: Assets](#i84f31ef528bc41899c5480059e42eda9_313)] | | | [removed: [157](#if7b552d0c82e4d75af26724d7276acc2_292)] [added: [156](#i84f31ef528bc41899c5480059e42eda9_313)] | | |
| [Note 10 - Regulatory Assets and [removed: Liabilities](#if7b552d0c82e4d75af26724d7276acc2_295)] [added: Liabilities](#i84f31ef528bc41899c5480059e42eda9_316)] | | | [removed: [158](#if7b552d0c82e4d75af26724d7276acc2_295)] [added: [158](#i84f31ef528bc41899c5480059e42eda9_316)] | | |
| [Note 11 - [removed: Debt](#if7b552d0c82e4d75af26724d7276acc2_298)] [added: Debt](#i84f31ef528bc41899c5480059e42eda9_319)] | | | [removed: [159](#if7b552d0c82e4d75af26724d7276acc2_298)] [added: [159](#i84f31ef528bc41899c5480059e42eda9_319)] | | |
| [Note 16 - Redeemable Stock of [removed: Subsidiaries](#if7b552d0c82e4d75af26724d7276acc2_313)] [added: Subsidiaries](#i84f31ef528bc41899c5480059e42eda9_334)] | | | [removed: [170](#if7b552d0c82e4d75af26724d7276acc2_313)] [added: [171](#i84f31ef528bc41899c5480059e42eda9_334)] | | |
| [Note 18 - Segments and Geographic [removed: Information](#if7b552d0c82e4d75af26724d7276acc2_319)] [added: Information](#i84f31ef528bc41899c5480059e42eda9_340)] | | | [removed: [175](#if7b552d0c82e4d75af26724d7276acc2_319)] [added: [177](#i84f31ef528bc41899c5480059e42eda9_340)] | | |
| [Note 19 - Share-Based [removed: Compensation](#if7b552d0c82e4d75af26724d7276acc2_322)] [added: Compensation](#i84f31ef528bc41899c5480059e42eda9_343)] | | | [removed: [177](#if7b552d0c82e4d75af26724d7276acc2_322)] [added: [179](#i84f31ef528bc41899c5480059e42eda9_343)] | | |
| [Note 21 - Other Income and [removed: Expense](#if7b552d0c82e4d75af26724d7276acc2_328)] [added: Expense](#i84f31ef528bc41899c5480059e42eda9_349)] | | | [removed: [180](#if7b552d0c82e4d75af26724d7276acc2_328)] [added: [182](#i84f31ef528bc41899c5480059e42eda9_349)] | | |
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements.
Indicate by check mark whether any of those error corrections are restatement that required a recovery analysis of incentive-based compensation received by any of the registrant's executive officers during the relevant recovery period pursuant to §240.10D-1(b).
| [PART I](#i84f31ef528bc41899c5480059e42eda9_13) | | | [3](#i84f31ef528bc41899c5480059e42eda9_13) | | |
| [PART II](#i84f31ef528bc41899c5480059e42eda9_73) | | | [80](#i84f31ef528bc41899c5480059e42eda9_73) | | |
| [Executive Summary](#i84f31ef528bc41899c5480059e42eda9_103) | | | [83](#i84f31ef528bc41899c5480059e42eda9_103) | | |
| [Consolidated Balance Sheets](#i84f31ef528bc41899c5480059e42eda9_271) | | | [128](#i84f31ef528bc41899c5480059e42eda9_271) | | |
| [Consolidated Statements of Operations](#i84f31ef528bc41899c5480059e42eda9_274) | | | [129](#i84f31ef528bc41899c5480059e42eda9_274) | | |
| [Note 5 - Fair Value](#i84f31ef528bc41899c5480059e42eda9_301) | | | [147](#i84f31ef528bc41899c5480059e42eda9_301) | | |
| [Note 12 - Commitments](#i84f31ef528bc41899c5480059e42eda9_322) | | | [164](#i84f31ef528bc41899c5480059e42eda9_322) | | |
| [Note 13 - Contingencies](#i84f31ef528bc41899c5480059e42eda9_325) | | | [164](#i84f31ef528bc41899c5480059e42eda9_325) | | |
| [Note 14 - Leases](#i84f31ef528bc41899c5480059e42eda9_328) | | | [165](#i84f31ef528bc41899c5480059e42eda9_328) | | |
| [Note 15 - Benefit Plans](#i84f31ef528bc41899c5480059e42eda9_331) | | | [167](#i84f31ef528bc41899c5480059e42eda9_331) | | |
| [Note 17 - Equity](#i84f31ef528bc41899c5480059e42eda9_337) | | | [172](#i84f31ef528bc41899c5480059e42eda9_337) | | |
| [Note 20 - Revenue](#i84f31ef528bc41899c5480059e42eda9_346) | | | [181](#i84f31ef528bc41899c5480059e42eda9_346) | | |
| [Note 23 - Income Taxes](#i84f31ef528bc41899c5480059e42eda9_355) | | | [185](#i84f31ef528bc41899c5480059e42eda9_355) | | |
| [Note 25 - Acquisitions](#i84f31ef528bc41899c5480059e42eda9_364) | | | [190](#i84f31ef528bc41899c5480059e42eda9_364) | | |
| [Note 30 - Subsequent Events](#i84f31ef528bc41899c5480059e42eda9_379) | | | [198](#i84f31ef528bc41899c5480059e42eda9_379) | | |
| [PART III](#i84f31ef528bc41899c5480059e42eda9_394) | | | [202](#i84f31ef528bc41899c5480059e42eda9_394) | | |
| [SIGNATURES](#i84f31ef528bc41899c5480059e42eda9_418) | | | [207](#i84f31ef528bc41899c5480059e42eda9_418) | | |
| ACED | | | AES Clean Energy Development, LLC | | |
| | | | | | |
| | | | | | |
| | | | | | |
- our ability to execute on our strategies or achieve expectations related to environmental, social, and governance matters;
| [PART I](#if7b552d0c82e4d75af26724d7276acc2_13) | | | [3](#if7b552d0c82e4d75af26724d7276acc2_13) | | |
| [PART II](#if7b552d0c82e4d75af26724d7276acc2_73) | | | [78](#if7b552d0c82e4d75af26724d7276acc2_73) | | |
| [Executive Summary](#if7b552d0c82e4d75af26724d7276acc2_100) | | | [81](#if7b552d0c82e4d75af26724d7276acc2_100) | | |
| [Consolidated Balance Sheets](#if7b552d0c82e4d75af26724d7276acc2_250) | | | [127](#if7b552d0c82e4d75af26724d7276acc2_250) | | |
| [Consolidated Statements of Operations](#if7b552d0c82e4d75af26724d7276acc2_253) | | | [128](#if7b552d0c82e4d75af26724d7276acc2_253) | | |
| [Note 5 - Fair Value](#if7b552d0c82e4d75af26724d7276acc2_280) | | | [146](#if7b552d0c82e4d75af26724d7276acc2_280) | | |
| [Note 12 - Commitments](#if7b552d0c82e4d75af26724d7276acc2_301) | | | [163](#if7b552d0c82e4d75af26724d7276acc2_301) | | |
| [Note 13 - Contingencies](#if7b552d0c82e4d75af26724d7276acc2_304) | | | [163](#if7b552d0c82e4d75af26724d7276acc2_304) | | |
| [Note 14 - Leases](#if7b552d0c82e4d75af26724d7276acc2_307) | | | [164](#if7b552d0c82e4d75af26724d7276acc2_307) | | |
| [Note 15 - Benefit Plans](#if7b552d0c82e4d75af26724d7276acc2_310) | | | [166](#if7b552d0c82e4d75af26724d7276acc2_310) | | |
| [Note 17 - Equity](#if7b552d0c82e4d75af26724d7276acc2_316) | | | [171](#if7b552d0c82e4d75af26724d7276acc2_316) | | |
| [Note 20 - Revenue](#if7b552d0c82e4d75af26724d7276acc2_325) | | | [179](#if7b552d0c82e4d75af26724d7276acc2_325) | | |
| [Note 23 - Income Taxes](#if7b552d0c82e4d75af26724d7276acc2_334) | | | [182](#if7b552d0c82e4d75af26724d7276acc2_334) | | |
| [Note 25 - Acquisitions](#if7b552d0c82e4d75af26724d7276acc2_343) | | | [188](#if7b552d0c82e4d75af26724d7276acc2_343) | | |
| [Note 30 - Subsequent Events](#if7b552d0c82e4d75af26724d7276acc2_358) | | | [195](#if7b552d0c82e4d75af26724d7276acc2_358) | | |
| [PART III](#if7b552d0c82e4d75af26724d7276acc2_370) | | | [201](#if7b552d0c82e4d75af26724d7276acc2_370) | | |
| [SIGNATURES](#if7b552d0c82e4d75af26724d7276acc2_394) | | | [206](#if7b552d0c82e4d75af26724d7276acc2_394) | | |
| IDEM | | | Indiana Department of Environmental Management | | |
| QIA | | | Qatar Investment Authority | | |
| SEET | | | Significantly Excessive Earnings Test | | |
An excerpt. Shown here: 40 of 64 rewritten, all 24 added and all 20 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2022 filing and the FY2021 filing.
Item 2. PROPERTIES
1 rewritten, 0 added, 0 removed, 3 unchanged
With a few exceptions, our facilities, which are described in Item [removed: 1*—[Business](#if7b552d0c82e4d75af26724d7276acc2_19)*] [added: 1*—[Business](#i84f31ef528bc41899c5480059e42eda9_19)*] of this Form 10-K, are subject to mortgages or other liens or encumbrances as part of the project's related finance facility.
Item 4. MINE SAFETY DISCLOSURES
1 rewritten, 0 added, 0 removed, 4 unchanged
| [removed: 78] [added: 80] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
Item 5. MARKET FOR REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
10 rewritten, 0 added, 0 removed, 28 unchanged
The cumulative repurchases from the commencement of the Stock Repurchase Program in July 2010 through December 31, [removed: 2021] [added: 2022] totaled 154.3 million shares for a total cost of $1.9 billion, at an average price per share of $12.12 (including a nominal amount of commissions).
As of December 31, [removed: 2021,] [added: 2022,] $264 million remained available for repurchase under the Stock Repurchase Program.
No repurchases were made by The AES Corporation of its common stock in [added: 2022,] 2021, [removed: 2020,] and [removed: 2019.][added: 2020.]
| Commencing the fourth quarter of | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | [removed: 2019] [added: 2020] | | |
| Cash dividend | | | | | | [removed: $0.1580] [added: $0.1659] | | | | | | [removed: $0.1505] [added: $0.1580] | | | | | | [removed: $0.1433] [added: $0.1505] | | |
The fourth quarter [removed: 2021] [added: 2022] cash dividend is to be paid in the first quarter of [removed: 2022.][added: 2023.]
See the information contained under Item 12.—*[Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters—Securities Authorized for Issuance under Equity Compensation [removed: Plans](#if7b552d0c82e4d75af26724d7276acc2_379)*] [added: Plans](#i84f31ef528bc41899c5480059e42eda9_403)*] of this Form 10-K.
As of February [removed: 24, 2022,] [added: 27, 2023,] there were approximately [removed: 3,612] [added: 3,508] record holders of our common stock.
| [removed: 79] [added: 81] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
[removed: ][added: 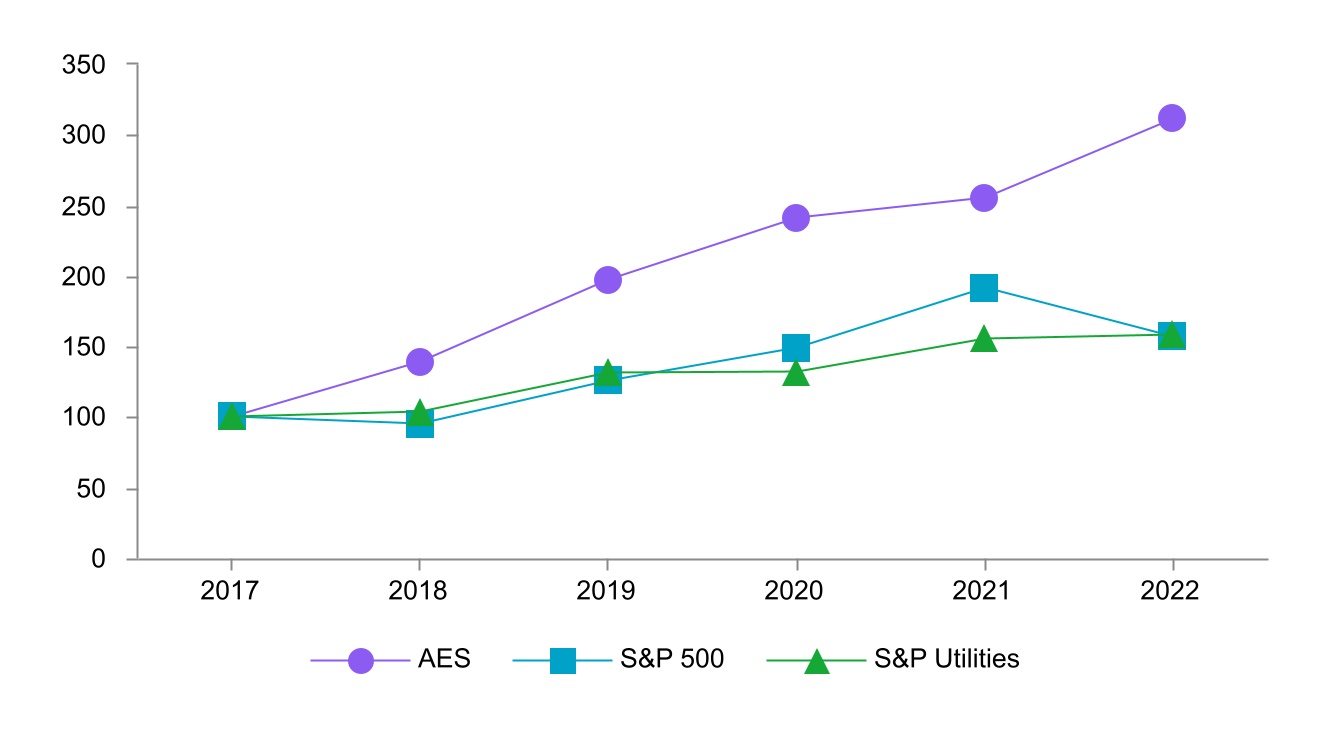]
Item 6. SELECTED FINANCIAL DATA
32 rewritten, 1 added, 0 removed, 19 unchanged
This data should be read together with Item 7.—*[Management's Discussion and Analysis of Financial Condition and Results of [removed: Operations](#if7b552d0c82e4d75af26724d7276acc2_97)*] [added: Operations](#i84f31ef528bc41899c5480059e42eda9_100)*] and the Consolidated Financial Statements and the notes thereto included in Item 8.—*[Financial Statements and Supplementary [removed: Data](#if7b552d0c82e4d75af26724d7276acc2_247)*] [added: Data](#i84f31ef528bc41899c5480059e42eda9_265)*] of this Form 10-K.
The selected financial data for each of the years in the five year period ended December 31, [removed: 2021] [added: 2022] have been derived from our audited Consolidated Financial Statements.
Please refer to the Notes to the Consolidated Financial Statements included in Item 8.—*[Financial Statements and Supplementary [removed: Data](#if7b552d0c82e4d75af26724d7276acc2_247)*] [added: Data](#i84f31ef528bc41899c5480059e42eda9_265)*] of this Form 10-K for further explanation of the effect of such activities.
Please also refer to Item 1A.—*[Risk [removed: Factors](#if7b552d0c82e4d75af26724d7276acc2_58)*] [added: Factors](#i84f31ef528bc41899c5480059e42eda9_58)*] of this Form 10-K and Note 27—*[Risks and [removed: Uncertainties](#if7b552d0c82e4d75af26724d7276acc2_349)*] [added: Uncertainties](#i84f31ef528bc41899c5480059e42eda9_370)*] to the Consolidated Financial Statements included in Item 8.—*[Financial Statements and Supplementary [removed: Data](#if7b552d0c82e4d75af26724d7276acc2_247)*] [added: Data](#i84f31ef528bc41899c5480059e42eda9_265)*] of this Form 10-K for certain risks and uncertainties that may cause the data reflected herein not to be indicative of our future financial condition or results of operations.
| [removed: 80] [added: 82] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
| | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | [removed: 2019] [added: 2020] | | | | | | [removed: 2018] [added: 2019] | | | | | | [removed: 2017] [added: 2018] | | |
| Revenue | | | $ | [removed: 11,141] [added: 12,617] | | | | | $ | [removed: 9,660] [added: 11,141] | | | | | $ | [removed: 10,189] [added: 9,660] | | | | | $ | [removed: 10,736] [added: 10,189] | | | | | $ | [removed: 10,530] [added: 10,736] | |
| Income (loss) from continuing operations (1) | | | [removed: (955)] [added: (505)] | | | | | | [removed: 149] [added: (955)] | | | | | | [removed: 477] [added: 149] | | | | | | [removed: 1,349] [added: 477] | | | | | | [removed: (148)] [added: 1,349] | | |
| Income (loss) from continuing operations attributable to The AES Corporation, net of tax | | | [removed: (413)] [added: (546)] | | | | | | [removed: 43] [added: (413)] | | | | | | [removed: 302] [added: 43] | | | | | | [removed: 985] [added: 302] | | | | | | [removed: (507)] [added: 985] | | |
| Income [removed: (loss)] from discontinued operations attributable to The AES Corporation, net of tax (2) | | | [removed: 4] [added: —] | | | | | | [removed: 3] [added: 4] | | | | | | [removed: 1] [added: 3] | | | | | | [removed: 218] [added: 1] | | | | | | [removed: (654)] [added: 218] | | |
| Net income (loss) attributable to The AES Corporation | | | $ | [removed: (409)] [added: (546)] | | | | | $ | [removed: 46] [added: (409)] | | | | | $ | [removed: 303] [added: 46] | | | | | $ | [removed: 1,203] [added: 303] | | | | | $ | [removed: (1,161)] [added: 1,203] | |
| Income (loss) from continuing operations attributable to The AES Corporation common stockholders, net of tax | | | $ | [removed: (0.62)] [added: (0.82)] | | | | | $ | [removed: 0.06] [added: (0.62)] | | | | | $ | [removed: 0.46] [added: 0.06] | | | | | $ | [removed: 1.49] [added: 0.46] | | | | | $ | [removed: (0.77)] [added: 1.49] | |
| Income [removed: (loss)] from discontinued operations attributable to The AES Corporation common stockholders, net of tax | | | [removed: 0.01] [added: —] | | | | | | 0.01 | | | | | | [removed: —] [added: 0.01] | | | | | | [removed: 0.33] [added: —] | | | | | | [removed: (0.99)] [added: 0.33] | | |
| Net income (loss) attributable to The AES Corporation common stockholders | | | $ | [removed: (0.61)] [added: (0.82)] | | | | | $ | [removed: 0.07] [added: (0.61)] | | | | | $ | [removed: 0.46] [added: 0.07] | | | | | $ | [removed: 1.82] [added: 0.46] | | | | | $ | [removed: (1.76)] [added: 1.82] | |
| Income (loss) from continuing operations attributable to The AES Corporation common stockholders, net of tax | | | $ | [removed: (0.62)] [added: (0.82)] | | | | | $ | [removed: 0.06] [added: (0.62)] | | | | | $ | [removed: 0.45] [added: 0.06] | | | | | $ | [removed: 1.48] [added: 0.45] | | | | | $ | [removed: (0.77)] [added: 1.48] | |
| Net income (loss) attributable to The AES Corporation common stockholders | | | $ | [removed: (0.61)] [added: (0.82)] | | | | | $ | [removed: 0.07] [added: (0.61)] | | | | | $ | [removed: 0.45] [added: 0.07] | | | | | $ | [removed: 1.81] [added: 0.45] | | | | | $ | [removed: (1.76)] [added: 1.81] | |
| Dividends Declared Per Common Share | | | $ | [removed: 0.61] [added: 0.64] | | | | | $ | [removed: 0.58] [added: 0.61] | | | | | $ | [removed: 0.55] [added: 0.58] | | | | | $ | [removed: 0.53] [added: 0.55] | | | | | $ | [removed: 0.49] [added: 0.53] | |
| Net cash provided by operating activities | | | $ | [removed: 1,902] [added: 2,715] | | | | | $ | [removed: 2,755] [added: 1,902] | | | | | $ | [removed: 2,466] [added: 2,755] | | | | | $ | [removed: 2,343] [added: 2,466] | | | | | $ | [removed: 2,504] [added: 2,343] | |
| Net cash used in investing activities | | | [removed: (3,051)] [added: (5,836)] | | | | | | [removed: (2,295)] [added: (3,051)] | | | | | | [removed: (2,721)] [added: (2,295)] | | | | | | [removed: (505)] [added: (2,721)] | | | | | | [removed: (2,599)] [added: (505)] | | |
| Net cash provided by (used in) financing activities | | | [removed: 797] [added: 3,758] | | | | | | [removed: (78)] [added: 797] | | | | | | [removed: (86)] [added: (78)] | | | | | | [removed: (1,643)] [added: (86)] | | | | | | [removed: 43] [added: (1,643)] | | |
| Total increase (decrease) in cash, cash equivalents and restricted cash | | | [removed: (343)] [added: 603] | | | | | | [removed: 255] [added: (343)] | | | | | | [removed: (431)] [added: 255] | | | | | | [removed: 215] [added: (431)] | | | | | | [removed: (172)] [added: 215] | | |
| Cash, cash equivalents and restricted cash, ending | | | [removed: 1,484] [added: 2,087] | | | | | | [removed: 1,827] [added: 1,484] | | | | | | [removed: 1,572] [added: 1,827] | | | | | | [removed: 2,003] [added: 1,572] | | | | | | [removed: 1,788] [added: 2,003] | | |
| Total assets | | | $ | [removed: 32,963] [added: 38,363] | | | | | $ | [removed: 34,603] [added: 32,963] | | | | | $ | [removed: 33,648] [added: 34,603] | | | | | $ | [removed: 32,521] [added: 33,648] | | | | | $ | [removed: 33,112] [added: 32,521] | |
| Non-recourse debt (noncurrent) | | | [removed: 13,603] [added: 17,846] | | | | | | [removed: 15,005] [added: 13,603] | | | | | | [removed: 14,914] [added: 15,005] | | | | | | [removed: 13,986] [added: 14,914] | | | | | | [removed: 13,176] [added: 13,986] | | |
| Recourse debt (noncurrent) | | | [removed: 3,729] [added: 3,894] | | | | | | [removed: 3,446] [added: 3,729] | | | | | | [removed: 3,391] [added: 3,446] | | | | | | [removed: 3,650] [added: 3,391] | | | | | | [removed: 4,625] [added: 3,650] | | |
| Redeemable stock of subsidiaries | | | [removed: 1,257] [added: 1,321] | | | | | | [removed: 872] [added: 1,257] | | | | | | [removed: 888] [added: 872] | | | | | | [removed: 879] [added: 888] | | | | | | [removed: 837] [added: 879] | | |
| Accumulated deficit | | | [removed: (1,089)] [added: (1,635)] | | | | | | [removed: (680)] [added: (1,089)] | | | | | | [removed: (692)] [added: (680)] | | | | | | [removed: (1,005)] [added: (692)] | | | | | | [removed: (2,276)] [added: (1,005)] | | |
| The AES Corporation stockholders' equity | | | [removed: 2,798] [added: 2,437] | | | | | | [removed: 2,634] [added: 2,798] | | | | | | [removed: 2,996] [added: 2,634] | | | | | | [removed: 3,208] [added: 2,996] | | | | | | [removed: 2,465] [added: 3,208] | | |
(1)Includes pre-tax losses on sales of business interests of [added: $9 million,] $1.7 billion, [removed: $95 million,] and [removed: $52] [added: $95] million for the years ended December 31, [added: 2022,] 2021, [removed: 2020,] and [removed: 2017,] [added: 2020,] respectively, and pre-tax gains of $28 million and $984 million for the years ended December 31, 2019, and 2018, respectively*;* pre-tax impairment expense of [added: $1.5 billion,] $1.6 billion, $864 million, $185 million, [removed: $208 million,] and [removed: $537] [added: $208] million for the years ended December 31, [added: 2022,] 2021, 2020, 2019, [removed: 2018,] and [removed: 2017,] [added: 2018,] respectively; other-than-temporary impairment of equity method investments of [added: $175 million,] $202 million, $92 million, and $147 million for the years ended December 31, [added: 2022,] 2020, 2019, and 2018, respectively; income tax [removed: expense of $194 million and $675 million related to the one-time transition tax on foreign earnings, income tax] benefit of $176 million related to the reversal of uncertain tax positions effectively settled upon the closure of the Company's 2017 U.S. tax return exam for the year ended December 31, [removed: 2021,] [added: 2021] and income tax [removed: benefit] [added: expense] of [removed: $77] [added: $194] million [added: related to the one-time transition tax on foreign earnings] and [removed: expense] [added: income tax benefit] of [removed: $39] [added: $77] million related to the remeasurement of deferred tax assets and liabilities to the lower corporate tax rate for the [removed: years] [added: year] ended December 31, [removed: 2018 and 2017, respectively;] [added: 2018;] and net equity in losses of affiliates, primarily at Guacolda, of $123 million, and $172 million, for the years ended December 31, 2020 and 2019, respectively.
See Note 24—*[Held-for-Sale and [removed: Dispositions](#if7b552d0c82e4d75af26724d7276acc2_340),*] [added: Dispositions](#i84f31ef528bc41899c5480059e42eda9_361),*] Note 22—*[Asset Impairment [removed: Expense](#if7b552d0c82e4d75af26724d7276acc2_331),*] [added: Expense](#i84f31ef528bc41899c5480059e42eda9_352),*] Note [added: 9 —*[Goodwill and Other Intangible Assets](#i84f31ef528bc41899c5480059e42eda9_313),* Note] 8—*[Investments in and Advances to [removed: Affiliates](#if7b552d0c82e4d75af26724d7276acc2_289)*] [added: Affiliates](#i84f31ef528bc41899c5480059e42eda9_310)*] and Note 23—*[Income [removed: Taxes](#if7b552d0c82e4d75af26724d7276acc2_334)*] [added: Taxes](#i84f31ef528bc41899c5480059e42eda9_355)*] included in Item 8.—*[Financial Statements and Supplementary [removed: Data](#if7b552d0c82e4d75af26724d7276acc2_247)*] [added: Data](#i84f31ef528bc41899c5480059e42eda9_265)*] of this Form 10-K for further information.
(2)Includes gain on sale of $199 million [removed: and loss on deconsolidation of $611 million] related to Eletropaulo for the [removed: years] [added: year] ended December 31, [removed: 2018 and 2017, respectively.][added: 2018.]
| [removed: 81] [added: 83] \| [removed: 2021] [added: 2022] Annual Report | | | | | |
| Income from discontinued operations attributable to The AES Corporation common stockholders, net of tax | | | — | | | | | | 0.01 | | | | | | 0.01 | | | | | | — | | | | | | 0.33 | | |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
1,103 rewritten, 406 added, 285 removed, 1,703 unchanged
We have audited the accompanying consolidated balance sheets of The AES Corporation (the Company) as of December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] the related consolidated statements of operations, comprehensive income (loss), changes in equity and cash flows for each of the three years in the period ended December 31, [removed: 2021,] [added: 2022,] and the related notes and the financial statement schedule listed in the Index at Item 15(a) (collectively referred to as the “consolidated financial statements”).
In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2021,] [added: 2022,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in Internal Control *—* Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) and our report dated [removed: February 28, 2022,] [added: March 1, 2023,] expressed an unqualified opinion thereon.
| *How We Addressed the Matter in Our Audit* | | | | | | We obtained an understanding, evaluated the design and tested the operating effectiveness of controls over the [removed: Company’s] [added: Company's] goodwill impairment review [added: and testing] process [removed: at] [added: for] the AES Andes [added: and AES El Salvador] reporting [removed: unit.] [added: units.] For example, we tested controls over management’s review of the valuation [removed: model,] [added: models,] the significant assumptions [removed: used to develop the estimates,] [added: described above,] and the completeness and accuracy of the data used in the valuations. To test the estimated fair value [removed: of] [added: for] the [removed: Company’s] AES Andes [added: and AES El Salvador] reporting [removed: unit,] [added: units,] we performed audit procedures that included, among others, assessing the methodologies used to develop the [removed: estimate of] [added: estimated] fair [removed: value,] [added: values,] testing the significant assumptions discussed above, and [removed: testing] [added: evaluating] the completeness and accuracy of the underlying data used by the Company in its analyses. We compared the significant assumptions used by management to current industry and economic [removed: trends as well as historical results.] [added: trends.] We assessed the historical accuracy of management’s estimates and performed sensitivity analyses of significant assumptions to evaluate the changes in the fair value of the reporting [removed: unit] [added: units] that would result from changes in the assumptions. We also involved valuation specialists to assist in our evaluation of the overall methodologies and the discount [removed: rate] [added: rates] used in the fair value estimate. | | |
| | | | | | | [removed: Identification and Valuation of Long-Lived] [added: Long-lived] Asset Impairments and Re-evaluation of Useful Lives | | |
| *Description of the Matter* | | | | | | At December 31, [removed: 2021,] [added: 2022,] the Company's [added: net] property, plant and equipment [removed: had an aggregate net carrying value of approximately $19,906] [added: was $23,039] million. As [removed: disclosed] [added: discussed] in Note 1 to the consolidated financial statements, when circumstances indicate [added: that] the carrying amount of long-lived assets in a held-for-use asset group may not be recoverable, the Company evaluates the assets for potential [removed: impairment and re-evaluates the remaining useful life. These] [added: impairment. Events or changes in] circumstances [added: that] may [added: necessitate a recoverability evaluation] include, but are not limited to, [added: adverse] changes in the regulatory environment, [removed: demand,] [added: unfavorable changes in] power prices or fuel costs, [added: increased competition due to additional capacity in the grid,] technological advancements, [removed: physical deterioration,] [added: declining trends in demand,] or an expectation it is more likely than not that the asset will be disposed of before the end of its [added: previously estimated] useful life. [removed: In 2021,] [added: If the carrying amount of the assets exceeds the undiscounted cash flows, an impairment is recognized for the amount by which the carrying amount of the asset group exceeds its fair value. The Company’s useful life estimates are continually evaluated for appropriateness] as [removed: disclosed] [added: changes] in [removed: Footnote] [added: the relevant factors arise, including when a long-lived asset group is tested for recoverability. As discussed in Note] 22 to the consolidated financial statements, the Company recognized a total asset impairment expense of [removed: $1,575 million, primarily] [added: $661 million] related to the [removed: Company’s Puerto Rico, Ventanas 3 & 4] [added: Maritza] and [removed: Angamos] [added: the TEG TEP] asset [removed: groups.] [added: groups in 2022.] | | |
| 125 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
| *How We Addressed the Matter in Our Audit* | | | | | | We obtained an understanding, evaluated the design and tested the operating effectiveness of the Company’s controls over the identification of impairment indicators, [removed: estimation] [added: re-evaluation] of [added: estimated] useful [removed: lives (including any changes if necessary)] [added: lives,] and [added: the] valuation of the [added: Maritza and TEG TEP] long-lived asset impairments. For example, we tested management’s monitoring controls over [removed: businesses that have had been affected] [added: the evaluation of events] or [removed: are expected] [added: changes in circumstances that would require an asset] to be [removed: affected by the circumstances above. Our testing] [added: tested for recoverability. We] also [removed: included] [added: tested] management’s review controls of the valuation [removed: model,] [added: models used in] the [added: impairment analyses, the] significant assumptions used to develop the estimates, and the completeness and accuracy of the data used in the valuations. [removed: Our] [added: To test the Company's identification of impairment indicators and re-evaluation of useful lives, our] audit procedures included, among others, making inquiries of [removed: management (including] [added: management, including] personnel in [removed: operations)] [added: operations,] to understand changes in the [removed: businesses, reading industry journals] [added: businesses] and [removed: publications to independently identify changes in the regulatory environments or the geographic areas] [added: management’s strategic plans,] and [removed: evaluating] [added: evaluate] whether management has considered [added: any] identified [removed: changes, if any. We considered businesses for which current power prices are significantly less than contractual prices within Power Purchase Agreements (PPAs) that are also near expiration.] [added: changes in their analysis.] We [removed: also considered] [added: evaluated] the [removed: Company’s ability to re-contract certain] [added: results] of [removed: its] [added: earnings and the projected cash flows for significant] coal generation assets [removed: upon the expiration of] [added: and assessed whether there has been] a [removed: PPA, given] [added: deterioration in earnings or projected losses that would represent an impairment indicator. We also evaluated conditions and trends in] the [removed: most recent legislative] [added: industry for the underlying economies, including any sale] or [added: disposition activities, and evaluated any adverse changes in the] regulatory [removed: changes.] [added: environment or the geographic areas to test the completeness and accuracy of the company's evaluation of potential impairment indicators.] We evaluated the Company’s [removed: analysis of the] useful [removed: lives of] [added: life estimates, in particular for] its [added: significant] coal generation assets, considering the existing [removed: PPAs] [added: Power Purchase Agreements (PPAs)] and the [removed: Company’s ability to use] [added: market for] the [added: use of these] assets subsequent to the expiration of [removed: a PPA,] [added: existing PPAs,] based on [removed: any regulatory or market changes. For projects that were still under construction, we compared] the [removed: Company's actual progress to their budgets, inspected engineering reports when considered appropriate, and considered project overruns. We reviewed disaggregated financial results for deterioration in earnings performance compared to prior periods, negative cash flows from operations, and working capital deficiencies and assessed whether these would represent impairment indicators, when applicable. We also considered and assessed conditions and trends in the industry and the underlying economies] [added: regulatory] and [removed: evaluated sale or disposition activities. When testing] [added: market conditions. To test] the impairment analyses for [removed: AES Puerto Rico, Ventanas] [added: the Maritza] and [removed: Angamos,] [added: TEG TEP asset groups,] our audit procedures included, among others, [removed: obtaining an understanding of management’s strategic view of the plants given the regulatory changes, evaluating management’s assessment of the lowest level of identifiable cash flows,] assessing the appropriateness of [added: valuation] methodologies, testing the significant assumptions discussed [removed: above] [added: above,] and testing the completeness and accuracy of the underlying data used by the Company in its analyses. We compared the significant assumptions used by management to current industry and economic [removed: trends, latest regulations] [added: trends] as well as historical results. We [removed: assessed the historical accuracy of management’s estimates and] performed sensitivity analyses of [added: certain] significant assumptions to evaluate the changes in the fair value of the asset groups that would result from changes in the assumptions. We also involved valuation specialists to assist in our evaluation of the overall [added: valuation] methodology and the discount [removed: rate] [added: rates] used in the fair value [removed: estimate.] [added: estimates.] | | |
| 126 \| [removed: 2021] [added: 2022] Annual Report | | | | | |
December 31, [removed: 2021] [added: 2022] and [removed: 2020][added: 2021]
| | | | [added: 2022 | | | | | |] 2021 | | | | | | 2020 | | |
| Cash and cash equivalents | | | $ | [removed: 943] [added: 1,374] | | | | | $ | [removed: 1,089] [added: 943] | |
| Restricted cash | | | [removed: 304] [added: 536] | | | | | | [removed: 297] [added: 304] | | |
| Short-term investments | | | [removed: 232] [added: 730] | | | | | | [removed: 335] [added: 232] | | |
| Accounts receivable, net of allowance for doubtful accounts of $5 and [removed: $13,] [added: $5,] respectively | | | [removed: 1,418] [added: 1,799] | | | | | | [removed: 1,300] [added: 1,418] | | |
| Inventory | | | [removed: 604] [added: 1,055] | | | | | | [removed: 461] [added: 604] | | |
| Prepaid expenses | | | [removed: 142] [added: 98] | | | | | | [removed: 102] [added: 142] | | |
| Other current assets | | | [removed: 897] [added: 802] | | | | | | [removed: 726] [added: (2)] | | | [added: | | | 800 | | |]
| Current held-for-sale assets | | | [removed: 816] [added: 518] | | | | | | [removed: 1,104] [added: 816] | | |
| Total current assets | | | [removed: 5,356] [added: 7,643] | | | | | | [removed: 5,414] [added: 5,356] | | |
| Land | | | [removed: 426] [added: 470] | | | | | | [removed: 417] [added: 426] | | |
| Electric generation, distribution assets and other | | | [removed: 25,552] [added: 26,599] | | | | | | [removed: 26,707] [added: 25,552] | | |
| Accumulated depreciation | | | [removed: (8,486)] [added: (8,651)] | | | | | | [removed: (8,472)] [added: (8,486)] | | |
| Construction in progress | | | [removed: 2,414] [added: 4,621] | | | | | | [removed: 4,174] [added: 2,414] | | |
| Property, plant and equipment, net | | | [removed: 19,906] [added: 23,039] | | | | | | [removed: 22,826] [added: 19,906] | | |
| Investments in and advances to affiliates | | | [removed: 1,080] [added: 952] | | | | | | [removed: 835] [added: 1,080] | | |
| Debt service reserves and other deposits | | | [removed: 237] [added: 177] | | | | | | [removed: 441] [added: 237] | | |
| Goodwill | | | [removed: 1,177] [added: 362] | | | | | | [removed: 1,061] [added: 1,177] | | |
| Other intangible assets, net of accumulated amortization of [removed: $385] [added: $434] and [removed: $330,] [added: $385,] respectively | | | [removed: 1,450] [added: 1,841] | | | | | | [removed: 827] [added: 1,450] | | |
| Deferred income taxes | | | [removed: 409] [added: 319] | | | | | | [removed: 288] [added: 409] | | |
| Other noncurrent assets, net of allowance of [removed: $23] [added: $51] and [removed: $21,] [added: $23,] respectively | | | [removed: 2,188] [added: 2,979] | | | | | | [removed: 1,660] [added: 2,188] | | |
| Noncurrent held-for-sale assets | | | [removed: 1,160] [added: —] | | | | | | [removed: 1,251] [added: 1,160] | | |
| Total other assets | | | [removed: 7,701] [added: 7,681] | | | | | | [removed: 6,363] [added: 7,701] | | |
| TOTAL ASSETS | | | $ | [removed: 32,963] [added: 38,363] | | | | | $ | [removed: 34,603] [added: 32,963] | |
| Accounts payable | | | $ | [removed: 1,153] [added: 1,730] | | | | | $ | [removed: 1,156] [added: 1,153] | |
| Accrued interest | | | [removed: 182] [added: 249] | | | | | | [removed: 191] [added: 182] | | |
| Accrued non-income taxes | | | [removed: 266] [added: 249] | | | | | | [removed: 257] [added: 266] | | |
| Accrued and other liabilities | | | [removed: 1,120] [added: 2,151] | | | | | | [removed: 1,223] [added: 1,205] | | |
| Non-recourse debt, including [removed: $302] [added: $416] and [removed: $336,] [added: $302,] respectively, related to variable interest entities | | | [removed: 1,367] [added: 1,758] | | | | | | [removed: 1,430] [added: 1,367] | | |
| Current held-for-sale liabilities | | | [removed: 559] [added: 354] | | | | | | [removed: 667] [added: 559] | | |
| | | | | | | Goodwill Impairment Test for AES Andes and AES El Salvador Reporting Units | | |
| *Description of the Matter* | | | | | | At December 31, 2022, the Company’s goodwill balance was $362 million. As discussed in Note 1 to the consolidated financial statements, the Company’s goodwill is tested for impairment at least annually. If goodwill is determined to be impaired, an impairment loss is measured at the amount by which the reporting unit’s carrying amount exceeds its fair value, not to exceed the carrying amount of goodwill. The Company performed a quantitative impairment test for the AES Andes and AES El Salvador reporting units and utilized the income approach to determine the estimated fair value of these reporting units. As discussed in Note 9 to the consolidated financial statements, the estimated fair value was less than the carrying amount for both of these reporting units and as a result the Company recognized impairment expense of $777 million during the fourth quarter of 2022. Auditing the Company’s annual goodwill impairment tests for the AES Andes and AES El Salvador reporting units required judgment to evaluate the effects of macroeconomic and industry conditions and involved a high degree of subjectivity due to the significant estimation required to determine the fair value of these reporting units. In particular, the fair value estimates of the reporting units involve the use of significant unobservable inputs and are sensitive to changes in significant assumptions, such as the interest rates and country risk premiums, which are inputs used to determine the discount rates. | | |
| 127 \| 2022 Annual Report | | | | | |
| | | | | | | Auditing the Company's identification of impairment indicators and re-evaluation of useful lives was complex and highly judgmental because of the many geographic, regulatory, and economic environments in which the Company operates. Also, due to the wide variety of events or changes in circumstances that may indicate that an asset group is not recoverable or that may result in a change in useful life, auditing the Company’s identification of impairment indicators and re-evaluation of useful lives involved a high degree of subjectivity, particularly given the Company’s decarbonization initiatives and shift towards clean energy platforms. In addition, auditing the Company’s valuation of long-lived assets used in the Maritza and TEG TEP impairment analyses involved significant judgment due to the significant unobservable inputs used in the estimation of the asset groups’ fair value. In particular, the significant assumptions for the income approach used to determine the fair value of the asset groups included the Company’s projections of revenue growth and discount rates, which are forward-looking assumptions and could be affected by future industry, market, and economic conditions. | | |
| Other current assets, net of CECL allowance of $2 and $0, respectively | | | 1,533 | | | | | | 897 | | |
| Loan receivable, net of allowance of $26 | | | 1,051 | | | | | | — | | |
| Goodwill impairment expense | | | (777) | | | | | | — | | | | | | — | | |
| Adjustments to redemption value of redeemable stock of subsidiaries (2) | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | (4) | | | | | | — | | | | | | — | | | | | | — | | |
| Adjustments to redemption value of redeemable stock of subsidiaries (2) | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | (4) | | | | | | — | | | | | | — | | | | | | — | | |
| Net income (loss) | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | (546) | | | | | | — | | | | | | 128 | | |
| Issuance of preferred shares in subsidiaries | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 60 | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Balance at December 31, 2022 | | | 1.0 | | | | | | $ | 838 | | | | | 818.8 | | | | | | $ | 8 | | | | | 150.0 | | | | | | $ | (1,822) | | | | | $ | 6,688 | | | | | $ | (1,635) | | | | | $ | (1,640) | | | | | $ | 2,067 | |
(3) Includes a $13 million reclass from *Additional paid-in capital* to *Preferred stock* to reflect the retrospective adoption of ASU 2020-06.
For further information, see Note 1—*[G](#i84f31ef528bc41899c5480059e42eda9_289)[e](#i84f31ef528bc41899c5480059e42eda9_289)[n](#i84f31ef528bc41899c5480059e42eda9_289)[e](#i84f31ef528bc41899c5480059e42eda9_289)[r](#i84f31ef528bc41899c5480059e42eda9_289)[a](#i84f31ef528bc41899c5480059e42eda9_289)[l](#i84f31ef528bc41899c5480059e42eda9_289) [](#i84f31ef528bc41899c5480059e42eda9_289)[a](#i84f31ef528bc41899c5480059e42eda9_289)[n](#i84f31ef528bc41899c5480059e42eda9_289)[d](#i84f31ef528bc41899c5480059e42eda9_289) [](#i84f31ef528bc41899c5480059e42eda9_289)[S](#i84f31ef528bc41899c5480059e42eda9_289)[u](#i84f31ef528bc41899c5480059e42eda9_289)[m](#i84f31ef528bc41899c5480059e42eda9_289)[m](#i84f31ef528bc41899c5480059e42eda9_289)[a](#i84f31ef528bc41899c5480059e42eda9_289)[r](#i84f31ef528bc41899c5480059e42eda9_289)[y](#i84f31ef528bc41899c5480059e42eda9_289) [](#i84f31ef528bc41899c5480059e42eda9_289)[o](#i84f31ef528bc41899c5480059e42eda9_289)[f](#i84f31ef528bc41899c5480059e42eda9_289) [](#i84f31ef528bc41899c5480059e42eda9_289)[S](#i84f31ef528bc41899c5480059e42eda9_289)[i](#i84f31ef528bc41899c5480059e42eda9_289)[g](#i84f31ef528bc41899c5480059e42eda9_289)[n](#i84f31ef528bc41899c5480059e42eda9_289)[i](#i84f31ef528bc41899c5480059e42eda9_289)[f](#i84f31ef528bc41899c5480059e42eda9_289)[i](#i84f31ef528bc41899c5480059e42eda9_289)[c](#i84f31ef528bc41899c5480059e42eda9_289)[a](#i84f31ef528bc41899c5480059e42eda9_289)[n](#i84f31ef528bc41899c5480059e42eda9_289)[t](#i84f31ef528bc41899c5480059e42eda9_289) [](#i84f31ef528bc41899c5480059e42eda9_289)[A](#i84f31ef528bc41899c5480059e42eda9_289)[ccounting Policies](#i84f31ef528bc41899c5480059e42eda9_289)*.
| Purchases under supplier financing arrangements | | | 1,042 | | | | | | 91 | | | | | | 72 | | |
| Repayments of obligations under supplier financing arrangements | | | (432) | | | | | | (35) | | | | | | (96) | | |
When the equity instrument is not probable of becoming redeemable, no adjustment to the carrying value is recognized.
When an impairment is observed, any excess of the carrying amount over its estimated fair value is recognized as impairment
| Cash and cash equivalents | | | $ | 1,374 | | | | | $ | 943 | |
| Restricted cash | | | 536 | | | | | | 304 | | |
| Debt service reserves and other deposits | | | 177 | | | | | | 237 | | |
Other accrued liabilities includes $662 million related to supplier financing arrangements, of which $296 million has a Parent Company guarantee; interest incurred for these arrangements is recorded on the Consolidated Statements of Operations within *Interest expense* or, if eligible for capitalization, to *Property, plant and equipment, net* on the Consolidated Balance Sheets.
The Company has elected an accounting policy not to consider the effects of being subject to the corporate alternative minimum tax in future periods when assessing the realizability of our deferred tax assets, carryforwards, and tax credits.
Any effect on the realization of deferred tax assets will be recognized in the period they arise.
the fiscal period.
transferred.
The objective of
(2)Increase in CECL reserve balance for regulatory receivables in Argentina.
(3)Lease receivable credit losses allowance at Southland Energy (AES Gilbert).
| 2022-04,Liabilities - Supplier Finance Programs (Topic 450-50): Disclosure of Supplier Finance Program Obligations | | | This update is to provide additional information and disclosures about an entity’s use of supplier finance programs to see how these programs will affect an entity’s working capital, liquidity, and cash flows. Entities that use supplier finance programs as the buyer party should disclose (1) the key terms of the payment terms and assets pledged as security or other forms of guarantees provided and (2) the unpaid amount outstanding, a description of where those obligations are presented on the balance sheet, and a rollforward of those obligations during the annual period. In each interim reporting period, the buyer must disclose the unpaid amount outstanding at the end of the interim period. | | | For fiscal years beginning after December 15, 2022, including interim periods within those fiscal years, except for the amendment on rollforward information, which is effective for fiscal years beginning after December 15, 2023. | | | The ASU only requires disclosures related to the Company's supplier finance programs and does not affect the recognition, measurement, or presentation of supplier finance program obligations on the balance sheet or cash flow statement. The Company expects to adopt the new disclosure requirements in the first quarter of 2023, except for the annual requirement to disclose rollforward information, which the Company expects to adopt and present prospectively beginning in the 2024 annual financial statements. | | |
The increase at Southland Energy is mostly due to additional liabilities incurred related to a demolition obligation at Alamitos.
The increase at AES Clean Energy is mostly due to additional liabilities incurred as a result of new development projects.
The increase at AES Indiana is primarily due to an upward revision of estimated cash flows at the Petersburg, Eagle Valley, and Harding Street plants.
The
increase at AES Brasil is primarily due to the initial recognition of asset retirement obligations as a result of the Cubico II acquisition.
The CVA for potential
Nonperformance risk includes, but may not be limited
| Balance at January 1 | | | $ | (6) | | | | | $ | — | | | | | $ | 108 | | | | | $ | (1) | | | | | $ | 101 | |
| | | | | | | |
| --- | --- | --- | --- | --- | --- | --- |
| 123 \| 2021 Annual Report | | | | | |
| 124 \| 2021 Annual Report | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | Goodwill Impairment Evaluation of the AES Andes Reporting Unit | | |
| *Description of the Matter* | | | | | | At December 31, 2021, the Company’s goodwill balance was $1,177 million, of which $644 million relates to the AES Andes reporting unit. As disclosed in Note 1 to the consolidated financial statements, the Company’s goodwill is tested for impairment at least annually at the reporting unit level. The goodwill impairment test at the AES Andes reporting unit involves the use of significant unobservable inputs to determine the fair value of the reporting unit. This estimate of fair value is compared to the carrying value of the reporting unit to determine whether goodwill is impaired. Auditing the Company's measurement of the fair value of the AES Andes reporting unit involved a high degree of subjectivity given the lack of observable inputs to estimate the reporting unit’s fair value. Key inputs that had a significant impact on the valuation included the prospective financial information (including the estimated growth in renewable projects, forward electricity prices and developments in the Chilean capacity market) and the discount rate, which were forward-looking and based upon expectations about future economic and market conditions. | | |
| | | | | | | Auditing the Company's identification and evaluation of impairment indicators involved significant auditor judgment considering the many geographic, regulatory, and economic environments in which the Company operates. Similarly, auditing the Company’s re-evaluation of useful lives required a high degree of subjectivity, particularly as it related to the Company’s coal generation assets given the Company’s decarbonization initiatives and the potential risks associated with climate change that have led to increased regulation and other actions. These audit procedures required an evaluation of a wide variety of circumstances for potential changes in useful lives or impairment indicators. In addition, auditing the Company’s valuation of long-lived asset impairments involved significant judgment related to the estimation of the asset groups’ fair value. There was a high degree of subjectivity given the lack of observable inputs to estimate the fair value. Key inputs that had a significant impact on the valuation included the prospective financial information (including the expected retirement dates of the plants and the probabilities assigned to the different scenarios) and the discount rate, which were forward-looking and based upon expectations about future economic and market conditions. | | |
| | | | | | | Accounting for the Merger of sPower and Distributed Energy Development Platforms | | |
| *Description of the Matter* | | | | | | As disclosed in Footnote 25 to the consolidated financial statements, the Company completed the merger of the sPower and AES Renewable Holdings development platforms to form AES Clean Energy Development in 2021. As part of the transaction, AES acquired an additional 25% ownership interest in the sPower development platform in exchange for a 25% ownership interest in specifically identified development entities of AES Renewable Holdings, certain future exit rights in the new partnership, and $7 million of cash. The acquisition of the sPower development platform was accounted for as a step acquisition as a result of the Company’s previously held interest. The sPower development assets were remeasured at their acquisition-date fair values resulting in a $214 million gain. The Company also recorded goodwill of $45 million representing the difference between the fair value of the consideration transferred and the fair value of the identifiable assets acquired and liabilities assumed. Auditing the Company’s accounting for the merger was complex due to the significant estimation in management’s determination of the fair value of the non-cash consideration transferred as well as the acquired assets. Specifically, the fair value of the sPower development pipeline and the intangible assets associated with the contracted and uncontracted projects acquired from sPower involved significant estimation uncertainty. The estimation uncertainty was primarily related to underlying assumptions about the future performance of the development projects or other unobservable inputs. The Company used a discounted cash flow model to measure the fair value of the development pipeline and acquired intangible assets. The significant assumptions used included discount rates and certain assumptions that form the basis of the forecasted results (e.g., pipeline capacity, developer profit, probability of project completion and expected timing of completion). These significant assumptions were forward looking and could be affected by future economic and market conditions. | | |
| *How We Addressed the Matter in Our Audit* | | | | | | We obtained an understanding, evaluated the design and tested the operating effectiveness of controls over the Company’s accounting for the step acquisition. For example, we tested controls over the recognition and measurement of the consideration transferred and intangible assets acquired, including management’s review of the valuation models, the significant assumptions used to develop the estimates, and the completeness and accuracy of the data used in the valuations. To test the estimated fair value of the development pipeline and intangible assets, we performed audit procedures that included, among others, evaluating the Company's selection of the valuation methodology, evaluating the methods and significant assumptions used by the Company's valuation specialist, and evaluating the completeness and accuracy of the underlying data supporting the significant assumptions and estimates. For example, we compared the significant assumptions used by management to third-party industry data, the Company’s budgets and forecasts as well as historical results. We also involved valuation specialists to assist in our evaluation of the overall methodology and the discount rates used in the fair value estimate. | | |
February 28, 2022
| | | | | | | | | | | | |
| Deferred income | | | 85 | | | | | | 438 | | |
| Balance at December 31, 2018 | | | — | | | | | | $ | — | | | | | 817.2 | | | | | | $ | 8 | | | | | 154.9 | | | | | | $ | (1,878) | | | | | $ | 8,154 | | | | | $ | (1,005) | | | | | $ | (2,071) | | | | | $ | 2,396 | |
| Net income | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 303 | | | | | | — | | | | | | 182 | | |
| Cumulative effect of a change in accounting principle (1) | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | 10 | | | | | | (4) | | | | | | — | | |
| Fair value adjustment (2) | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | (6) | | | | | | — | | | | | | — | | | | | | — | | |
| Fair value adjustment (2) | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | — | | | | | | (4) | | | | | | — | | | | | | — | | | | | | — | | |
| Refinancing of non-recourse debt at Mong Duong | | | — | | | | | | — | | | | | | 1,081 | | |
| Partial reinvestment of consideration from the sPower transaction | | | — | | | | | | — | | | | | | 58 | | |
Further, the allocation of income and dividends, as well as the adjustment to fair value, is classified outside permanent equity.
separately from continuing operations to distinguish the financial impact of disposal transactions from ongoing operations.
substantially complete liquidation of the investment in a foreign entity.
Performance obligations for capacity and ancillary services (such as operations and maintenance and dispatch services) are satisfied over time as the Company stands ready to perform under the terms of the contract.
basis over the lease term.
Upon commencement of the lease, the book value of the leased asset is removed from the balance sheet and a net investment in sales-type lease is recognized based on the present value of fixed payments under the contract and the residual value of the underlying asset.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
_____________________________
(2)Mong Duong loan receivable credit losses allowance was reclassified to held-for-sale assets on the Consolidated Balance Sheet as of December 31, 2020.
| 2016-13, 2018-19, 2019-04, 2019-05, 2019-10, 2019-11, 2020-02, 2020-03, Financial Instruments — Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments | | | See discussion of the ASU below. | | | January 1, 2020 | | | See impact upon adoption of the standard below. | | |
| 2016-02, 2018-01, 2018-10, 2018-11, 2018-20, 2019-01, Leases (Topic 842) | | | ASC 842 was adopted by sPower on January 1, 2020. sPower was not required to adopt ASC 842 using the public adoption date, as sPower is an equity method investee that meets the definition of a public business entity only by virtue of the inclusion of its summarized financial information in the Company’s SEC filings. | | | January 1, 2020 | | | The adoption of this standard resulted in a $4 million decrease to accumulated deficit attributable to the AES Corporation stockholders’ equity. | | |
| Other current assets (1) | | | 802 | | | | | | (2) | | | | | | 800 | | |
(1)*Other current assets* include the short-term portion of the Mong Duong loan receivable, which was reclassified to *Current held-for-sale assets* on the Consolidated Balance Sheet as of December 31, 2021.
operations of the plant, which are under the Company’s control until the end of the BOT contract.
| | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Sale of plants | | | | | | — | | | | | | (13) | | |
The increase at Chile is mostly due to the initial recognition of the ARO at the Andes Solar 2b plant.
An excerpt. Shown here: 40 of 1,103 rewritten, 40 of 406 added and 40 of 285 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2022 filing and the FY2021 filing.
Item 9A. CONTROLS AND PROCEDURES
9 rewritten, 2 added, 13 removed, 33 unchanged
Based upon this evaluation, the CEO and CFO concluded that as of December 31, [removed: 2021,] [added: 2022,] our disclosure controls and procedures were effective.
Management assessed the effectiveness of our internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
Based on this assessment, management believes that the Company maintained effective internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
The effectiveness of the Company's internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] has been audited by Ernst & Young LLP, an independent registered public accounting firm, as stated in their report, which appears herein.
There were no changes that occurred during the quarter ended December 31, [removed: 2021] [added: 2022] that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
We have audited The AES Corporation’s internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in Internal Control *—* Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission (2013 framework) (the COSO criteria).
In our opinion, The AES Corporation (the Company) maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated balance sheets of the Company as of December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] the related consolidated statements of operations, comprehensive income (loss), changes in equity, and cash flows for each of the three years in the period ended December 31, [removed: 2021,] [added: 2022,] and the related notes and [added: the] financial statement schedule listed in the Index at Item [removed: 15(a),] [added: 15(a)] and our report dated [removed: February 28, 2022] [added: March 1, 2023] expressed an unqualified opinion thereon.
200 | [removed: 2021] [added: 2022] Annual Report
March 1, 2023
201 | 2022 Annual Report
In February 2021, the Company substantially completed the merger of the sPower and AES Renewable Holdings development platforms to form AES Clean Energy Development (“Clean Energy”).
As a result, assets acquired and liabilities assumed in the merger have been included in AES’ Consolidated Balance Sheet as of December 31, 2021.
Clean Energy’s total assets and total revenue represented 4% and 1% of AES’ consolidated total assets and revenues, respectively, as of December 31, 2021.
Clean Energy’s net loss of $69 million for the period February 1, 2021 through December 31, 2021 was included in AES’ Consolidated Statement of Operations for the year ended December 31, 2021.
Legacy sPower entities continue to be accounted for as an equity method investment.
As permitted by SEC guidance, newly acquired Clean Energy businesses have been excluded from management’s formal evaluation of the effectiveness of AES’ disclosure controls and procedures due to the timing of the acquisitions.
197 | 2021 Annual Report
198 | 2021 Annual Report
As indicated in the accompanying Item 9A, *[Management’s Report on Internal Control over Financial Reporting](#if7b552d0c82e4d75af26724d7276acc2_364)*, management’s assessment of and conclusion on the effectiveness of internal control over financial reporting did not include the internal controls of the acquired businesses as part of the merger of the sPower and AES Renewable Holdings development platforms to form AES Clean Energy Development (Clean Energy), which is included in the 2021 consolidated financial statements of the Company and constituted 4% and 1% of total assets and revenue, respectively, as of December 31, 2021.
Clean Energy’s net loss of $69 million for the period February 1, 2021 through December 31, 2021 was included in the Company’s consolidated statement of operations for the year then ended.
Our audit of internal control over financial reporting of the Company also did not include an evaluation of the internal control over financial reporting of Clean Energy.
199 | 2021 Annual Report
February 28, 2022
Item 9C. DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS
0 rewritten, 1 added, 1 removed, 2 unchanged
202 | 2022 Annual Report
201 | 2021 Annual Report
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
2 rewritten, 0 added, 0 removed, 4 unchanged
The following information is incorporated by reference from the Registrant's Proxy Statement for the Registrant's [removed: 2022] [added: 2023] Annual Meeting of Stockholders which the Registrant expects will be filed on or around March 7, [removed: 2022] [added: 2023] (the [removed: "2022] [added: "2023] Proxy Statement"):
The other information required by this Item, to the extent not included above, will be contained in our [removed: 2022] [added: 2023] Proxy Statement and is herein incorporated by reference.
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 0 added, 0 removed, 2 unchanged
The information required by Item 402 of Regulation S-K will be contained in the [removed: 2022] [added: 2023] Proxy Statement under "Director Compensation" and "Executive Compensation" (excluding the information under the caption “Report of the Compensation Committee”) and is incorporated herein by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
5 rewritten, 3 added, 3 removed, 18 unchanged
See the information contained under the heading *Security Ownership of Certain Beneficial Owners, Directors, and Executive Officers* of the [removed: 2022] [added: 2023] Proxy Statement, which information is incorporated herein by reference.
The following table provides information about shares of AES common stock that may be issued under AES' equity compensation plans, as of December 31, [removed: 2021:][added: 2022:]
Securities Authorized for Issuance under Equity Compensation Plans (As of December 31, [removed: 2021)][added: 2022)]
The weighted average exercise price of Options outstanding under this plan included in Column (b) is [removed: $12.83] [added: $13.70] (excluding performance stock units, restricted stock units and director stock units), with [removed: 12,137,212] [added: 10,314,146] shares available for future issuance.
(2)Includes [removed: 2,386,991] [added: 3,189,316] (of which [removed: 354,091] [added: 544,386] are vested and [removed: 2,032,900] [added: 2,644,930] are unvested) shares underlying PSU and RSU awards (assuming [removed: 2019, 2020 and] [added: 2020,] 2021 [added: and 2022] PSUs [removed: median] [added: maximum] performance), [removed: 1,592,092] [added: 1,641,814] shares underlying Director stock unit awards, and [removed: 1,579,327] [added: 795,256] shares issuable upon the exercise of Stock Option grants, for an aggregate number of [removed: 5,558,410] [added: 5,626,386] shares.
| Equity compensation plans approved by security holders (1) | | | 5,626,386 | | | (2) | | | $ | 13.70 | | | | | 10,314,146 | | |
| Total | | | 5,626,386 | | | | | | $ | 13.70 | | | | | 10,314,146 | | |
203 | 2022 Annual Report
| Equity compensation plans approved by security holders (1) | | | 5,558,410 | | | (2) | | | $ | 12.83 | | | | | 12,137,212 | | |
| Total | | | 5,558,410 | | | | | | $ | 12.83 | | | | | 12,137,212 | | |
202 | 2021 Annual Report
Item 13. CERTAIN RELATIONSHIPS AND RELATED PARTY TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 0 removed, 0 unchanged
The information regarding related party transactions required by this item will be included in the [removed: 2022] [added: 2023] Proxy Statement found under the headings *Related Person Policies and Procedures* and *Board and Committee Governance* and are incorporated herein by reference.
Item 14. PRINCIPAL ACCOUNTANT FEES AND SERVICES
1 rewritten, 1 added, 1 removed, 1 unchanged
The information required by this Item 14 will be included in the [removed: 2022] [added: 2023] Proxy Statement under the headings *Information Regarding The Independent Registered Public Accounting Firm, Audit Fees, Audit Related Fees, and Pre-Approval Policies and Procedures* and is incorporated herein by reference.
204 | 2022 Annual Report
203 | 2021 Annual Report
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULE
123 rewritten, 30 added, 23 removed, 199 unchanged
| [Consolidated Statements of Operations for the years ended December 31, [removed: 2021, 2020 and 2019](#if7b552d0c82e4d75af26724d7276acc2_253)] [added: 202](#i84f31ef528bc41899c5480059e42eda9_274)[2](#i84f31ef528bc41899c5480059e42eda9_274)[, 202](#i84f31ef528bc41899c5480059e42eda9_274)[1](#i84f31ef528bc41899c5480059e42eda9_274) [and 2](#i84f31ef528bc41899c5480059e42eda9_274)[02](#i84f31ef528bc41899c5480059e42eda9_274)[0](#i84f31ef528bc41899c5480059e42eda9_274)] | | | | | | [removed: [128](#if7b552d0c82e4d75af26724d7276acc2_253)] [added: [129](#i84f31ef528bc41899c5480059e42eda9_274)] | | |
| [Consolidated Statements of Comprehensive Income (Loss) for the years ended December 31, [removed: 2021, 2020 and 2019](#if7b552d0c82e4d75af26724d7276acc2_256)] [added: 202](#i84f31ef528bc41899c5480059e42eda9_277)[2](#i84f31ef528bc41899c5480059e42eda9_277)[, 202](#i84f31ef528bc41899c5480059e42eda9_277)[1](#i84f31ef528bc41899c5480059e42eda9_277) [and 2](#i84f31ef528bc41899c5480059e42eda9_277)[02](#i84f31ef528bc41899c5480059e42eda9_277)[0](#i84f31ef528bc41899c5480059e42eda9_277)] | | | | | | [removed: [129](#if7b552d0c82e4d75af26724d7276acc2_256)] [added: [130](#i84f31ef528bc41899c5480059e42eda9_277)] | | |
| [Consolidated Statements of Changes in Equity for the years ended December 31, [removed: 2021, 2020 and 2019](#if7b552d0c82e4d75af26724d7276acc2_259)] [added: 202](#i84f31ef528bc41899c5480059e42eda9_280)[2](#i84f31ef528bc41899c5480059e42eda9_280)[, 202](#i84f31ef528bc41899c5480059e42eda9_280)[1](#i84f31ef528bc41899c5480059e42eda9_280) [and 2](#i84f31ef528bc41899c5480059e42eda9_280)[02](#i84f31ef528bc41899c5480059e42eda9_280)[0](#i84f31ef528bc41899c5480059e42eda9_280)] | | | | | | [removed: [130](#if7b552d0c82e4d75af26724d7276acc2_259)] [added: [131](#i84f31ef528bc41899c5480059e42eda9_280)] | | |
| [Consolidated Statements of Cash Flows for the years ended December 31, [removed: 2021, 2020 and 2019](#if7b552d0c82e4d75af26724d7276acc2_262)] [added: 202](#i84f31ef528bc41899c5480059e42eda9_283)[2](#i84f31ef528bc41899c5480059e42eda9_283)[, 202](#i84f31ef528bc41899c5480059e42eda9_283)[1](#i84f31ef528bc41899c5480059e42eda9_283) [and 2](#i84f31ef528bc41899c5480059e42eda9_283)[02](#i84f31ef528bc41899c5480059e42eda9_283)[0](#i84f31ef528bc41899c5480059e42eda9_283)] | | | | | | [removed: [131](#if7b552d0c82e4d75af26724d7276acc2_262)] [added: [132](#i84f31ef528bc41899c5480059e42eda9_283)] | | |
| [Notes to Consolidated Financial [removed: Statements](#if7b552d0c82e4d75af26724d7276acc2_265)] [added: Statements](#i84f31ef528bc41899c5480059e42eda9_286)] | | | | | | [removed: [132](#if7b552d0c82e4d75af26724d7276acc2_265)] [added: [133](#i84f31ef528bc41899c5480059e42eda9_286)] | | |
| 4 | | | | | | There are numerous instruments defining the rights of holders of long-term indebtedness of the Registrant and its consolidated subsidiaries, none of which exceeds ten percent of the total assets of the Registrant and its subsidiaries on a consolidated basis. The Registrant hereby agrees to furnish a copy of any of such agreements to the Commission upon request. Since these documents are not required filings under Item 601 of Regulation S-K, the Company has elected to file certain of these documents as Exhibits [removed: 4.(a)—4.(j).] [added: 4.(a)—4.(n).] | | |
| 4.(h) | | | | | | [Description of the Registrant's Securities is incorporated herein by reference to Exhibit 4.(k) of the Company's Form 10-K for the year ended December 31, [removed: 2020.](https://www.sec.gov/Archives/edgar/data/874761/000087476121000015/aes1231202010-kexhibit4k.htm)[is](https://www.sec.gov/Archives/edgar/data/874761/000087476121000015/aes1231202010-kexhibit4k.htm) [incorporated](https://www.sec.gov/Archives/edgar/data/874761/000087476121000015/aes1231202010-kexhibit4k.htm) [herein by](https://www.sec.gov/Archives/edgar/data/874761/000087476121000015/aes1231202010-kexhibit4k.htm) [reference] [added: 2020.is incorporated herein by reference] to [removed: E](https://www.sec.gov/Archives/edgar/data/874761/000087476121000015/aes1231202010-kexhibit4k.htm)[xhibit] [added: Exhibit] 4.(k) of the Company's Form 10-K for the year ended [removed: Decem](https://www.sec.gov/Archives/edgar/data/874761/000087476121000015/aes1231202010-kexhibit4k.htm)[ber] [added: December] 31, 2020.](https://www.sec.gov/Archives/edgar/data/874761/000087476121000015/aes1231202010-kexhibit4k.htm) | | |
[removed: 204] [added: S-1] | [removed: 2021] [added: 2022] Annual Report
205 | [removed: 2021] [added: 2022] Annual Report
| 10.26 | | | | | | [Separation Agreement by and between The AES Corporation and Lisa Krueger dated January 25, 2022 [removed: filed herewith](https://www.sec.gov/Archives/edgar/data/874761/000087476122000022/aes1231202110-kexhibit1026.htm).] [added: is incorporated herein by reference to Exhibit 10.26 of the Company's Form 10-K for the period ended December 31, 2021.](https://www.sec.gov/Archives/edgar/data/874761/000087476122000022/aes1231202110-kexhibit1026.htm)] | | |
| 10.27 | | | | | | [Consultant Agreement by and between The AES Corporation and Lisa Krueger dated January 25, 2022 [removed: filed herewith.](https://www.sec.gov/Archives/edgar/data/874761/000087476122000022/aes1231202110-kexhibit1027.htm)] [added: is incorporated herein by reference to Exhibit 10.27 of the Company's Form 10-K for the period ended December 31, 2021.](https://www.sec.gov/Archives/edgar/data/874761/000087476122000022/aes1231202110-kexhibit1027.htm)] | | |
| 21.1 | | | | | | [Subsidiaries of The AES Corporation (filed [removed: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476122000022/aes1231202110-kexhibit211.htm)] [added: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476123000010/aes1231202210-kexhibit211.htm)] | | |
| 23.1 | | | | | | [Consent of Independent Registered Public Accounting Firm, Ernst & Young LLP (filed [removed: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476122000022/aes1231202110-kexhibit231.htm)] [added: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476123000010/aes1231202210-kexhibit231.htm)] | | |
| 24 | | | | | | [Powers of Attorney (filed [removed: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476122000022/aes1231202110-kexhibit24.htm)] [added: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476123000010/aes1231202210-kexhibit24.htm)] | | |
| 31.1 | | | | | | [Rule 13a-14(a)/15d-14(a) Certification of Andrés Gluski (filed [removed: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476122000022/aes1231202110-kexhibit311.htm)] [added: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476123000010/aes1231202210-kexhibit311.htm)] | | |
| 31.2 | | | | | | [Rule 13a-14(a)/15d-14(a) Certification of Stephen Coughlin (filed [removed: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476122000022/aes1231202110-kexhibit312.htm)] [added: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476123000010/aes1231202210-kexhibit312.htm)] | | |
| 32.1 | | | | | | [Section 1350 Certification of Andrés Gluski (filed [removed: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476122000022/aes1231202110-kexhibit321.htm)] [added: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476123000010/aes1231202210-kexhibit321.htm)] | | |
| 32.2 | | | | | | [Section 1350 Certification of Stephen Coughlin (filed [removed: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476122000022/aes1231202110-kexhibit322.htm)] [added: herewith).](https://www.sec.gov/Archives/edgar/data/874761/000087476123000010/aes1231202210-kexhibit322.htm)] | | |
| 101 | | | | | | The AES Corporation Annual Report on Form 10-K for the year ended December 31, [removed: 2020,] [added: 2022,] formatted in Inline XBRL (Inline Extensible Business Reporting Language): (i) the Cover Page, (ii) Consolidated Balance Sheets, (iii) Consolidated Statements of Operations, (iv) Consolidated Statements of Comprehensive Income (Loss), (v) Consolidated Statements of Changes in Equity, (vi) Consolidated Statements of Cash Flows, and (vii) Notes to Consolidated Financial Statements. The instance document does not appear in the Interactive Data File because its XBRL tags are embedded within the Inline XBRL document. | | |
206 | [removed: 2021] [added: 2022] Annual Report
| Date: | | | [removed: February 28, 2022] [added: March 1, 2023] | | | By: | | | | | | /s/ ANDRÉS GLUSKI | | |
| /s/ SHERRY L. KOHAN | | | | | | [added: Senior] Vice President and [removed: Controller] [added: Chief Accounting Officer] (Principal Accounting Officer) | | | | | | | | |
[removed: S-1] [added: S-2] | [removed: 2021] [added: 2022] Annual Report
| [Schedule I—Condensed Financial Information of [removed: Registrant](#if7b552d0c82e4d75af26724d7276acc2_400)] [added: Registrant](#i84f31ef528bc41899c5480059e42eda9_424)] | | | [removed: S-[2](#if7b552d0c82e4d75af26724d7276acc2_400)] [added: S-[2](#i84f31ef528bc41899c5480059e42eda9_424)] | | |
[removed: S-2] [added: S-3] | [removed: 2021] [added: 2022] Annual Report
DECEMBER 31, [removed: 2021] [added: 2022] AND [removed: 2020][added: 2021]
| | | | [added: 2022] | | | [added: | | |] 2021 | | | | | | 2020 | | |
| Cash and cash equivalents | | | | | | $ | [removed: 40] [added: 24] | | | | | $ | [removed: 70] [added: 40] | |
| Accounts and notes receivable from subsidiaries | | | | | | [removed: 231] [added: 169] | | | | | | [removed: 188] [added: 231] | | |
| Prepaid expenses and other current assets | | | | | | [removed: 50] [added: 47] | | | | | | [removed: 55] [added: 50] | | |
| Total current assets | | | | | | [removed: 321] [added: 240] | | | | | | [removed: 313] [added: 321] | | |
| Investment in and advances to subsidiaries and affiliates | | | | | | [removed: 7,159] [added: 7,204] | | | | | | [removed: 6,426] [added: 7,159] | | |
| Cost | | | | | | [removed: 29] [added: 16] | | | | | | 29 | | |
| Accumulated depreciation | | | | | | [removed: (23)] [added: (10)] | | | | | | [removed: (22)] [added: (23)] | | |
| Office equipment, net | | | | | | 6 | | | | | | [removed: 7] [added: 6] | | |
| Deferred financing costs, net of accumulated amortization of [removed: $7] [added: $9] and [removed: $6,] [added: $7,] respectively | | | | | | [removed: 6] [added: 8] | | | | | | [removed: 4] [added: 6] | | |
| Other assets | | | | | | [removed: 33] [added: 117] | | | | | | [removed: 20] [added: 33] | | |
| Total other assets | | | | | | [removed: 39] [added: 125] | | | | | | [removed: 49] [added: 39] | | |
| Total assets | | | | | | $ | [removed: 7,525] [added: 7,575] | | | | | $ | [removed: 6,795] [added: 7,525] | |
| Accounts payable | | | | | | $ | [removed: 17] [added: 33] | | | | | $ | [removed: 15] [added: 17] | |
| [Consolidated Balance Sheets as of December 31, 202](#i84f31ef528bc41899c5480059e42eda9_271)[2](#i84f31ef528bc41899c5480059e42eda9_271) [and 20](#i84f31ef528bc41899c5480059e42eda9_271)[21](#i84f31ef528bc41899c5480059e42eda9_271) | | | | | | [128](#i84f31ef528bc41899c5480059e42eda9_271) | | |
| [Schedules](#i84f31ef528bc41899c5480059e42eda9_421) | | | | | | S-2-S-7 | | |
| 10.30 | | | | | | [Form of Director and Officer Indemnification Agreement](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1030.htm) [is incorporated herein by reference to Exhibit 10.30 of the Company](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1030.htm)['s Form 10-Q for the period ended September 30, 20](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1030.htm)[22](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1030.htm). | | |
| 10.31 | | | | | | [Amendment No. 1 to the Credit Agreement dated as of August 23, 2022 among The AES Corporation, a Delaware corporation, the lenders listed on the signature pages thereof, and Citibank, N.A., as Administrative Agent](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1031.htm) [](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1031.htm)[is incorporated herein by reference to Exhibit 10.31 of the Company's Form 10-Q for the period ended September 30, 20](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1031.htm)[22](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1031.htm). | | |
| 10.32 | | | | | | [Term Loan Agreement dated as of September 30, 2022 among The AES Corporation as Borrower, the banks named herein as Banks, and Sumitomo Mitsui Banking Corporation as Administrative Agent](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1032.htm) [is incorporated](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1032.htm) [herein](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1032.htm) [by reference to Exhibit 10.3](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1032.htm)[2](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1032.htm) [of](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1032.htm) [the Company's Form 10-Q f](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1032.htm)[or the period ended September 30, 20](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1032.htm)[22](https://www.sec.gov/Archives/edgar/data/874761/000087476122000073/aes0930202210-qexhibit1032.htm). | | |
| Andrés Gluski | | | | | | | | | March 1, 2023 | | | | | |
| Janet G. Davidson | | | | | | | | | March 1, 2023 | | | | | |
| Tarun Khanna | | | | | | | | | March 1, 2023 | | | | | |
| Holly K. Koeppel | | | | | | | | | March 1, 2023 | | | | | |
| Julia M. Laulis | | | | | | | | | March 1, 2023 | | | | | |
| James H. Miller | | | | | | | | | March 1, 2023 | | | | | |
| Alain Monié | | | | | | | | | March 1, 2023 | | | | | |
| John B. Morse | | | | | | | | | March 1, 2023 | | | | | |
| Moises Naim | | | | | | | | | March 1, 2023 | | | | | |
| Teresa M. Sebastian | | | | | | | | | March 1, 2023 | | | | | |
| Maura Shaughnessy | | | | | | | | | March 1, 2023 | | | | | |
| Stephen Coughlin | | | | | | | | | March 1, 2023 | | | | | |
| Sherry L. Kohan | | | | | | | | | March 1, 2023 | | | | | |
| *By: | | | /s/ PAUL L. FREEDMAN | | | | | | March 1, 2023 | | |
| Debt | | | | | | 3,894 | | | | | | 3,729 | | |
| | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | |
YEARS ENDED DECEMBER 31, 2022, 2021, AND 2020
| | | | | | | | | | | | | | | | | | |
YEARS ENDED DECEMBER 31, 2022, 2021, AND 2020
| For the Years Ended December 31, | | | | | | 2022 | | | | | | 2021 | | | | | | 2020 | | |
| | | | | | | | | | | | | | | | | | | | | |
| Senior Variable Rate Term Loan | | | | | | SOFR + 1.125% | | | | | | 2024 | | | | | | 200 | | | | | | — | | |
| 2026 | | | 800 | | |
| 2027 | | | 325 | | |
| [Consolidated Balance Sheets as of December 31, 2021 and 2020](#if7b552d0c82e4d75af26724d7276acc2_250) | | | | | | [127](#if7b552d0c82e4d75af26724d7276acc2_250) | | |
| [Schedules](#if7b552d0c82e4d75af26724d7276acc2_397) | | | | | | S-2-S-7 | | |
| Andrés Gluski | | | | | | | | | February 28, 2022 | | | | | |
| Janet G. Davidson | | | | | | | | | February 28, 2022 | | | | | |
| Tarun Khanna | | | | | | | | | February 28, 2022 | | | | | |
| Holly K. Koeppel | | | | | | | | | February 28, 2022 | | | | | |
| Julia M. Laulis | | | | | | | | | February 28, 2022 | | | | | |
| James H. Miller | | | | | | | | | February 28, 2022 | | | | | |
| Alain Monié | | | | | | | | | February 28, 2022 | | | | | |
| John B. Morse | | | | | | | | | February 28, 2022 | | | | | |
| Moises Naim | | | | | | | | | February 28, 2022 | | | | | |
| Teresa M. Sebastian | | | | | | | | | February 28, 2022 | | | | | |
| Maura Shaughnessy | | | | | | | | | February 28, 2022 | | | | | |
| Stephen Coughlin | | | | | | | | | February 28, 2022 | | | | | |
| Sherry L. Kohan | | | | | | | | | February 28, 2022 | | | | | |
| *By: | | | /s/ PAUL L. FREEDMAN | | | | | | February 28, 2022 | | |
| Deferred income taxes | | | | | | — | | | | | | 25 | | |
| Senior notes payable | | | | | | 3,729 | | | | | | 3,430 | | |
| Accounts and notes payable to subsidiaries | | | | | | — | | | | | | 28 | | |
| | | | 2021 | | | | | | 2020 | | | | | | 2019 | | |
| Change in pension adjustments due to net actuarial gain (loss) for the period, net of income tax (expense) benefit of $(9), $4 and $6, respectively | | | 23 | | | | | | (12) | | | | | | (16) | | |
| Effect of exchange rate changes on cash | | | | | | — | | | | | | — | | | | | | (1) | | |
| 2026 | | | 1,165 | | |
An excerpt. Shown here: 40 of 123 rewritten, all 30 added and all 23 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULE in the FY2022 filing and the FY2021 filing.