 filings.tools
Item 7. Management’s Discussion And Analysis Of Financial Condition And Results Of Operations
280K characters. Original on sec.gov · Markdown
Item 7. Management’s Discussion And Analysis Of Financial Condition And Results Of Operations
Ares Management, L.P. is a Delaware limited partnership formed on November 15, 2013. Unless the context otherwise requires, references to “we,” “us,” “our,” “the Partnership” and “the Company” are intended to mean the business and operations of Ares Management, L.P. and its consolidated subsidiaries. The following discussion analyzes the financial condition and results of operations of the Partnership . “Consolidated Funds” refers collectively to certain Ares‑affiliated funds, related co‑ investment entities and certain CLOs that are required under generally accepted accounting principles in the United States (“GAAP”) to be consolidated in our consolidated financial statements included in this Annual Report on Form 10‑K. Additional terms used by the Company are defined in the Glossary and throughout the Management's Discussion and Analysis in this Annual Report on Form 10-K.
The following discussion and analysis should be read in conjunction with the audited, consolidated financial statements of Ares Management, L.P. and the related notes included in this Annual Report on Form 10‑K.
Amounts and percentages presented throughout our discussion and analysis of financial condition and results of operations may reflect rounded results in thousands (unless otherwise indicated) and consequently, totals may not appear to sum.
Our Business
We are a leading global alternative asset manager that operates through three distinct but complementary investment groups, which are our reportable segments. In 2017, we reclassified certain expenses from OMG to our operating segments. We have presented our reportable segments for the years ended December 31, 2016 and 2015 to conform to the year ended December 31, 2017 presentation.
Our three operating segments are:
| • | Credit Group: Our Credit Group is a leading manager of credit strategies across the non-investment grade credit universe in the U.S. and Europe, with approximately $71.7 billion of assets under management and 139 funds as of December 31, 2017. The Credit Group offers a range of credit strategies across the liquid and illiquid spectrum, including syndicated loans, high yield bonds, credit opportunities, structured credit investments and U.S. and European direct lending. The Credit Group provides solutions for traditional fixed income investors seeking to access the syndicated loans and high yield bond markets and capitalizes on opportunities across traded corporate credit. It additionally provides investors access to directly originated fixed- and floating-rate credit assets and the ability to capitalize on illiquidity premiums across the credit spectrum. The Credit Group’s syndicated loans strategy focuses on liquid, traded non-investment grade secured loans to corporate borrowers. The high yield bond strategy seeks to deliver a diversified portfolio of liquid, traded non-investment grade corporate bonds, including secured, unsecured and subordinated debt instruments. Credit opportunities is a “go anywhere” strategy seeking to capitalize on market inefficiencies and relative value opportunities across the capital structure. The structured credit strategy invests across the capital structures of syndicated collateralized loan obligation vehicles (CLOs) and in directly-originated asset-backed instruments comprised of diversified portfolios of consumer and commercial assets. We are one of the largest self-originating direct lenders to the U.S. and European middle markets, providing one-stop financing solutions for small-to-medium sized companies, which the Company believes are increasingly underserved by traditional lenders. We provide investors access to these capabilities through several vehicles, including commingled funds, separately managed accounts and a publicly traded vehicle. The Credit Group conducts its U.S. corporate lending activities primarily through ARCC, the largest business development company as of December 31, 2017, by both market capitalization and total assets. In addition, the Credit Group manages a commercial finance business that provides asset-based and cash flow loans to small and middle-market companies, as well as asset-based facilities to specialty finance companies. The Credit Group’s European direct lending platform is one of the most significant participants in the European middle-market, focusing on self-originated investments in illiquid middle-market credits. |
| • | Private Equity Group: Our Private Equity Group has approximately $24.5 billion of assets under management as of December 31, 2017, broadly categorizing its investment strategies as corporate private equity, U.S. power and energy infrastructure and special situations. As of December 31, 2017, the group managed five corporate private equity commingled funds focused on North America and Europe and two focused on greater China, five commingled funds and six related co-investment vehicles focused on U.S. power and energy infrastructure and three special situations funds. In its North American and European flexible capital strategy, the Company targets opportunistic majority or shared-control investments in businesses with strong franchises and attractive growth opportunities in North America and Europe. The U.S. power and energy infrastructure strategy targets U.S. energy infrastructure-related assets across the power generation, transmission and midstream sectors, seeking attractive risk-adjusted equity returns with current cash flow and capital |
appreciation. The special situations strategy seeks to invest opportunistically across a broad spectrum of distressed or mispriced investments, including corporate debt, rescue capital, private asset-backed investments, post-reorganization securities and non-performing portfolios.
| • | Real Estate Group: Our Real Estate Group manages comprehensive public and private equity and debt strategies, with approximately $10.2 billion of assets under management across 42 funds as of December 31, 2017. Real Estate equity strategies focus on applying hands-on value creation initiatives to mismanaged and capital-starved assets, as well as new development, ultimately selling stabilized assets back into the market. The Real Estate Group manages both a value-add strategy and an opportunistic strategy. The value-add strategy seeks to create value by buying assets at attractive valuations and through active asset management of income-producing properties across the U.S. and Western Europe. The opportunistic strategy focuses on manufacturing core assets through development, redevelopment and fixing distressed capital structures across major property types in the U.S. and Europe. The Company’s debt strategies leverage the Real Estate Group’s diverse sources of capital to directly originate and manage commercial mortgage investments on properties that range from stabilized to requiring hands-on value creation. In addition to managing private debt funds, the Real Estate Group makes debt investments through a publicly traded commercial mortgage REIT, ACRE. |
The Operations Management Group (“OMG”) consists of five shared resource groups to support our operating segments by providing infrastructure and administrative support in the areas of accounting/finance, operations/information technology, business development/corporate strategy, legal/compliance and human resources. Additionally, the OMG provides services to certain of our investment companies and partnerships, which reimburse the OMG for expenses equal to the cost of services provided. The OMG’s expenses are not allocated to our three reportable segments but we consider the cost structure of the OMG when evaluating our financial performance.
The focus of our business model is to provide our investment management capabilities through various funds and products that meet the needs of a wide range of institutional and retail investors. Our revenues consist primarily of management fees and performance fees, as well as investment income and administrative expense reimbursements. Management fees are generally based on a defined percentage of average fair value of assets, total commitments, invested capital, net asset value, net investment income or par value of the investment portfolios we manage. Performance fees are based on certain specific hurdle rates as defined in the funds' applicable investment management or partnership agreements and represent either an incentive fee or carried interest. Other income (expense) represents the investment income, realized gains (losses) and unrealized appreciation (depreciation) resulting from the investments of the Company and the Consolidated Funds, as well as interest expense. We provide administrative services to certain of our affiliated funds that are presented within administrative, transaction and other fees for GAAP reporting, but are presented net of respective expenses for segment reporting purposes. We also receive transaction fees from certain affiliated funds for activities related to fund transactions, such as loan originations. In accordance with GAAP, we are required to consolidate those funds in which we hold a significant economic interest and substantive control rights. However, for segment reporting purposes, we present revenues and expenses on a combined segment basis, which shows the results of our reportable segments without giving effect to the consolidation of the funds. Accordingly, our segment revenues consist of management fees, other income, realized and unrealized performance fees, and net investment income. Our segment expenses consist of compensation and benefits, net of administrative fees, general, administrative and other expenses, net of administrative fees, as well as realized and unrealized performance fee compensation.
Trends Affecting Our Business
We believe that our disciplined investment philosophy across our three distinct but complementary investment groups contributes to the stability of our firm’s performance throughout market cycles. Additionally, as approximately 72% of our assets under management were in funds with a contractual life of three years or more and approximately 42% were in funds with a contractual life of seven years or more as of December 31, 2017, our funds have a stable base of committed capital enabling us to invest in assets with a long term focus over different points in a market cycle and to take advantage of market volatility. However, our results of operations, including the fair value of our AUM, are affected by a variety of factors, including conditions in the global financial markets and the economic and political environments, particularly in the United States and Western Europe.
December 2017 marked a modestly positive end to the year for credit markets as improving economic conditions, rising corporate earnings, accommodative monetary policy and falling inflation expectations supported investor sentiment. Despite sector specific gains experienced in November, credit spreads generally continued to tighten throughout the fourth quarter of 2017. In response to compressing yields, investors generally sought higher yielding risk assets globally. Similar to 2016, market participants were rewarded for a “risk-on” posture and as a result, the ICE BofAML High Yield Master II Index returned 7.48% for 2017, primarily driven by the CCC portion of the index which returned 10.59% during the year. The leveraged loan market experienced similar return patterns with the Credit Suisse Leveraged Loan Index delivering a 4.25% total return for the full year, led by a 7.45% return for the lower tier segment of the market. Against a backdrop of improving macroeconomic and corporate fundamentals as
well as enthusiasm over tax reform in the U.S., equities (measured by the S&P 500 Index) continued to reach record highs throughout the year and outperformed most asset classes with a year-to-date return of 21.83%.
European markets continued to show notable stability during the fourth quarter of 2017 as improving growth prospects and increased appetite for risk in the region seemed to offset geopolitical and monetary policy concerns. As a result, the ICE BofAML European High Yield Index and the Credit Suisse Western European Leveraged Loan Index delivered strong performance for the year-to-date period, returning 6.74% and 5.32% during 2017, respectively. Economic growth in Europe showed signs of strength as gross domestic product readings consistently beat expectations and the unemployment rate dipped to lows not seen since January 2009.
Notwithstanding the potential opportunities represented by market volatility, future earnings, cash flows and distributions are affected by a range of factors, including realizations of our funds’ investments, which are subject to significant fluctuations from period to period.
In 2018, some of the considerations informing our strategic decisions include:
| • | Our ability to fundraise and increase AUM and fee paying AUM. During the year ended December 31, 2017, we raised $16.7 billion, both in commingled and separately managed accounts, and continued to expand our investor base, raising capital from over 65 different funds and approximately 146 institutional investors, including 78 direct institutional investors that were new to Ares. Our fundraising efforts helped drive AUM growth of approximately 11.8% for 2017. During 2018, we expect that our fundraising will come from a combination of our existing and new strategies primarily in the U.S and Europe. During the year ended December 31, 2017, we earned approximately 1.1% on our FPAUM, which was consistent with 2016. As of December 31, 2017, we also had $15.0 billion of AUM not yet earning fees, which represents approximately $164.4 million in annual potential management fee revenue. Of the $164.4 million, $126.1 million relates to $11.8 billion of AUM available for future deployment. Our pipeline of potential fees, coupled with our future fundraising opportunities, gives us the potential to increase our management fees in 2018. |
| • | Our ability to attract new capital and investors with our broad multi‑asset class product offering. Our ability to attract new capital and investors in our funds is driven, in part, by the extent to which they continue to see the alternative asset management industry generally, and our investment products specifically, as an attractive vehicle for capital appreciation. We continually seek to create avenues to meet our investors’ evolving needs by offering an expansive range of investment funds, developing new products and creating managed accounts and other investment vehicles tailored to our investors’ goals. We continue to expand our distribution channels, seeking to meet the needs of insurance companies, as well as the needs of traditional institutional investors, such as pension funds, sovereign wealth funds, and endowments. If market volatility persists or increases, investors may seek absolute return strategies that seek to mitigate volatility. We offer a variety of investment strategies depending upon investors’ risk tolerance and expected returns. |
| • | Our disciplined investment approach and successful deployment of capital. Our ability to maintain and grow our revenue base is dependent upon our ability to successfully deploy the capital that our investors have committed to our investment funds. Greater competition, high valuations, cost of credit and other general market conditions have affected and may continue to affect our ability to identify and execute attractive investments. Under our disciplined investment approach, we deploy capital only when we have sourced a suitable investment opportunity at an attractive price. During the year ended December 31, 2017, we deployed $16.4 billion of gross capital across our three investment groups compared to approximately $10.2 billion deployed in 2016. As of December 31, 2017, we had $25.1 billion of capital available for investment and we remain well-positioned to invest our assets opportunistically. |
| • | Our ability to invest capital and generate returns through market cycles. The strength of our investment performance affects investors’ willingness to commit capital to our funds. The flexibility of the capital we are able to attract is one of the main drivers of the growth of our AUM and the management fees we earn. Current market conditions and a changing regulatory environment have created opportunities for Ares’ businesses, particularly in the Credit Group’s direct lending funds, and in the Private Equity's special situations funds, which utilize flexible investment mandates to manage portfolios through market cycles. As market conditions shift and default risk and interest rate risk come under greater focus, having the ability to move up and down the capital structure enables both our Credit and Private Equity Groups to reduce risk and enhance returns. Similarly, given our broad capabilities in leveraged loans, such flexibility enables our Credit Group to reduce sensitivities to changing interest rates by increasing allocations to floating rate syndicated loans. On a market value basis, more than 75% of the debt assets within our Credit Group are floating rate instruments, which we believe helps mitigate volatility associated with changes in interest rates. |
| • | Our ability to continue to achieve stable distributions to investors. Our fee related earnings represented approximately 80% of our distributable earnings for the year ended December 31, 2017. We believe that the high percentage of fee related earnings (versus performance related earnings) in our distributable earnings provides greater stability for our distributions relative to some peers. During 2017, we experienced higher relative distributable earnings compared to 2016 primarily driven by higher realized performance related earnings within the Private Equity Group, mostly as a result of market appreciation in a retail portfolio company following its initial public offering. In addition, we have historically experienced and expect to continue to experience higher realizations within our Credit Group funds during the second half compared to the first half of the year, as certain Credit Group funds, including ARCC, pay incentive fees annually when hurdles are exceeded, which are typically realized during the last six months of the year. |
See “Item 1A. Risk Factors” included in this Annual Report on Form 10‑K for a discussion of the risks to which our businesses are subject.
The Election for Ares Management, L.P. to be Taxed as a Corporation
We have filed an election with the Internal Revenue Service (“IRS”) to be treated as a corporation for U.S. federal income tax purposes (collectively, the “Tax Election”), with an effective date of March 1, 2018 (the “Effective Date”). Although we will be treated as a corporation for U.S. federal income tax purposes, we will remain a limited partnership under state law. In connection with the Tax Election, effective March 1, 2018, we have amended and restated our partnership agreement to, among other things, reflect our new tax classification and change the name of our common units and preferred units to common shares and preferred shares, respectively. The terms of such common shares and preferred shares, and the associated rights, otherwise remain unchanged. See “Item 1A. Risk Factors–Our common shareholders do not elect our general partner or, except in limited circumstances, vote on our general partner’s directors and have limited ability to influence decisions regarding our businesses.”
Asset managers structured as pass-through entities for income tax purposes have historically traded at substantial discounts to asset managers taxed as corporations. Further, we believe that our pass-through tax structure has historically limited our investor universe due to complexities related to this structure. The Tax Election is intended to simplify our tax structure and expand our eligible investor universe and, in turn, enhance our liquidity and trading volume, which may, among other things, provide us with a more liquid and attractive currency for potential strategic transactions to further long term growth. Moreover, we historically have paid corporate level taxes on our fee related earnings, which has averaged over 80% of total fee income since our initial public offering. This, combined with a reduction in the statutory federal corporate tax rate from 35% to 21%, also presented compelling reasons to make the Tax Election in 2018.
Shareholders will receive a final Schedule K-1 reflecting their allocable share of the partnership’s items for the period beginning January 1, 2018 and ending on the day immediately before the Effective Date. On and after the Effective Date, public common shareholders will not have current income tax obligations arising from their investment in Ares Management, L.P. other than on the receipt of distributions treated as dividends for tax purposes, which will be reported on Form 1099-DIV. This change reduces the legal and tax preparation costs associated with Schedule K-1 preparation and simplifies a shareholder’s tax reporting obligations.
We expect that neither Ares Management, L.P. nor its shareholders will recognize a material amount of gain or loss as a result of the Tax Election.
On the Effective Date, the aggregate tax basis of the shares held by a shareholder will equal the aggregate tax basis in such shares immediately before the Effective Date (reduced by the shareholder’s allocable share of our liabilities) and increased by the gain, if any, recognized by such shareholder as a result of the Tax Election. We believe that a shareholder’s holding period in the shares will generally be long-term. There is no assurance, however, that such treatment will be respected by the IRS.
The foregoing discussion is based on our expectation that all the relevant tax requirements for non-recognition treatment will have been met. There is no assurance, however, that such treatment will be respected by the IRS.
The rules governing the U.S. federal income tax treatment of the Tax Election are complex and their application to non-U.S. shareholders, in particular, is unclear. Accordingly, shareholders should consult their tax advisors regarding the tax treatment of the Tax Election in light of their particular situation.
Differences in Taxation of Partnerships and Corporations and Their Owners
An entity treated as a partnership for U.S. federal income tax purposes is not a taxable entity and generally incurs no U.S. federal income tax liability. Instead, each partner is required to take into account its share of items of income, gain, loss and deduction of the partnership in computing its U.S. federal income tax liability, regardless of whether distributions are made to it by the partnership. Distributions by an entity treated as a partnership to a partner are generally not taxable to the partnership or the partner and instead reduce a partner’s adjusted basis in its partnership interest.
An entity treated as a corporation for U.S. federal income tax purposes is a taxable entity and generally pays U.S. federal income tax on its taxable income. The maximum U.S. federal tax rate imposed on the net income of an entity treated as a corporation was recently changed from 35% to 21% for taxable years beginning after December 31, 2017. Such rate may be further changed in the future. An owner of an entity treated as a corporation generally is not taxed on any income earned by the entity until the entity distributes to it either cash or property. A distribution from an entity treated as a corporation is generally treated as a dividend to the extent it is paid from current or accumulated earnings and profits. We expect any dividends made to individuals and certain other qualifying owners to constitute “qualified dividend” income that is generally taxed at a favorable, lower tax rate than the ordinary income tax rate, if the requisite holding periods have been met. If the distribution exceeds current and accumulated
earnings and profits, the excess is treated as a nontaxable return of capital, reducing the owner’s tax basis in the stock to the extent of the owner’s tax basis in that stock. Any remaining excess is treated as capital gain. Because entities treated as corporations are taxed on their own taxable income, and because owners of such entities are taxed on any dividends distributed from such entities, there are two levels of potential tax upon income earned by entities treated as corporations.
Following the Effective Date, our shareholders (including holders of Series A Preferred Shares) will be subject to the tax treatment applicable to owners of entities that are treated as corporations described above.
The foregoing description addresses only certain U.S. federal income tax consequences of the Tax Election applicable to shareholders generally. We do not provide tax advice and nothing herein should be considered as such. Each shareholder should consult its tax advisor concerning the particular U.S. federal income, U.S. federal estate or gift, state, local, foreign and other tax consequences of the Tax Election to it.
2017 Tax Cuts and Jobs Act
On December 22, 2017, the Tax Cuts and Jobs Act was enacted into law creating significant and material updates to the Internal Revenue Code. The most significant change is a decrease of the corporate tax rate from 35% to 21%. The reduction in the corporate tax rate is effective for tax years beginning on or after January 1, 2018. We estimated the tax effects of the Tax Cuts and Jobs Act in our fourth quarter tax provision in accordance with our understanding of the changes and guidance available as of the date of this filing. The result was a $0.7 million income tax benefit in the fourth quarter of 2017, the period of enactment of the new tax law. The provisional amount relates to the remeasurement of certain deferred tax assets and liabilities based on the new rates at which they are expected to be reversed. Other significant changes are also included in the Tax Cuts and Jobs Act and will continue to be analyzed.
On December 22, 2017, the SEC issued Staff Accounting Bulletin (“SAB”) 118 to address the application of U.S. GAAP in regards to the change in tax law for registrants that do not have all of the necessary information available to analyze and calculate the accounting impact for the tax effects of the Tax Cuts and Jobs Act. Under SAB 118, we determined that approximately $0.7 million of deferred tax benefit should be recorded as a result of the remeasurement of certain deferred tax assets and liabilities that are impacted by the reduction in the U.S. federal tax rate at December 31, 2017. Additional work is necessary for a more detailed analysis on the tax effects of all aspects of the Tax Cuts and Jobs Act. Any subsequent adjustments to these amounts will be recorded to tax expense in the quarter that the required analysis is completed.
ARCC and American Capital, Ltd. Merger Agreement
On January 3, 2017, ARCC completed its acquisition of American Capital, Ltd. ("ACAS") pursuant to a definitive merger agreement entered into in May 2016 (the "ARCC-ACAS Transaction"). To support the ARCC-ACAS Transaction, we, through our subsidiary Ares Capital Management LLC, which serves as the investment adviser to ARCC, provided $275.2 million of cash consideration to ACAS shareholders upon the closing of the ARCC-ACAS Transaction in accordance with the terms and conditions of the merger agreement. In addition, we agreed to waive up to $10 million per quarter of ARCC's Part I Fees for ten calendar quarters, which began in the second quarter of 2017. We received a favorable private letter ruling from the IRS in the second quarter of 2017 which supports the full deductibility of the $275.2 million support payment in the 2017 tax year.
Consolidation and Deconsolidation of Ares Funds
Pursuant to GAAP, we consolidate the Consolidated Funds into our financial results as presented in this Annual Report on Form 10‑K. These funds represented approximately 6.4% of our AUM as of December 31, 2017, 3.0% of our management fees and 0.8% of our performance fees for the year ended December 31, 2017. As of December 31, 2017, 2016 and 2015, we consolidated 10, 7 and 5 CLOs, respectively, and 9 private funds. As of December 31, 2017, five of the CLOs were consolidated through risk retention vehicles.
The consolidation of these funds had the impact of increasing interest and other income of Consolidated Funds, interest expense of Consolidated Funds, net realized and unrealized gain (loss) on investment of Consolidated Funds and net income attributable to redeemable interests in Consolidated Funds, among others, for the years ended December 31, 2017, 2016 and 2015. Also, the consolidation of these funds typically has the impact of decreasing management and performance fees to the extent such fees were eliminated upon consolidation. For the actual impact that consolidation had on our results, see the Consolidating Schedules within Note 19, “Consolidation”, to our consolidated financial statements included in this Annual Report on Form 10-K.
The assets and liabilities of our Consolidated Funds are held within separate legal entities and, as a result, the liabilities of our Consolidated Funds are non-recourse to us. Generally, the consolidation of our Consolidated Funds has a significant gross-up effect on our assets, liabilities and cash flows but has no net effect on the net income attributable to us. The net economic ownership interests of our Consolidated Funds, to which we have no economic rights, are reflected as non‑controlling interests in the Consolidated Funds in our consolidated financial statements.
We generally deconsolidate funds we advise and CLOs when we are no longer deemed to have a controlling interest in the entity. During the year ended December 31, 2017, there were two Consolidated Funds liquidated or dissolved and no non-VIEs experienced a significant change in ownership or control that resulted in deconsolidation during the period.
The performance of our Consolidated Funds is not necessarily consistent with, or representative of, the combined performance trends of all of our funds.
Managing Business Performance
Non‑GAAP Financial Measures
We use the following non-GAAP measures to assess and track our performance:
| • | Economic Net Income (ENI) |
| • | Fee Related Earnings (FRE) |
| • | Performance Related Earnings (PRE) |
| • | Realized Income (RI) |
| • | Distributable Earnings (DE) |
These non‑GAAP financial measures supplement and should be considered in addition to and not in lieu of the results of operations, which are discussed further under “—Components of Consolidated Results of Operations” and are prepared in accordance with GAAP. For the specific components and calculations of these non-GAAP measures, as well as a reconciliation of these measures to the most comparable measure in accordance with GAAP, see Note 18, “Segment Reporting,” to our consolidated financial statements included in this Annual Report on Form 10‑K.
Operating Metrics
We monitor certain operating metrics that are common to the alternative asset management industry, which are discussed below.
Assets Under Management
Assets under management refers to the assets we manage. We view AUM as a metric to measure our investment and fundraising performance as it reflects assets generally at fair value plus available uncalled capital. For our funds other than CLOs, our AUM equals the sum of the following:
| • | net asset value (“NAV”) of such funds; |
| • | the drawn and undrawn debt (at the fund‑level including amounts subject to restrictions); and |
| • | uncalled committed capital (including commitments to funds that have yet to commence their investment periods). |
NAV refers to the fair value of all the assets of a fund less the fair value of all liabilities of the fund.
For CLOs, our AUM is equal to subordinated notes (equity) plus all drawn and undrawn debt tranches.
The tables below provide the period-to-period rollforwards of our total AUM by segment for the years ended December 31, 2017, 2016 and 2015 (in millions):
| Credit Group | Private Equity Group | Real Estate Group | Total AUM | ||||||||||||
| Balance at 12/31/2016 | $ | 60,466 | $ | 25,041 | $ | 9,752 | $ | 95,259 | |||||||
| Acquisitions | 3,605 | — | — | 3,605 | |||||||||||
| Net new par/equity commitments | 8,670 | 356 | 800 | 9,826 | |||||||||||
| Net new debt commitments | 5,989 | — | 509 | 6,498 | |||||||||||
| Distributions | (10,852 | ) | (3,014 | ) | (1,599 | ) | (15,465 | ) | |||||||
| Change in fund value | 3,854 | 2,147 | 767 | 6,768 | |||||||||||
| Balance at 12/31/2017 | $ | 71,732 | $ | 24,530 | $ | 10,229 | $ | 106,491 | |||||||
| Average AUM(1) | $ | 67,071 | $ | 24,914 | $ | 10,261 | $ | 102,246 |
| Credit Group | Private Equity Group | Real Estate Group | Total AUM | ||||||||||||
| Balance at 12/31/2015 | $ | 60,386 | $ | 22,978 | $ | 10,268 | $ | 93,632 | |||||||
| Net new par/equity commitments | 5,453 | 2,314 | 840 | 8,607 | |||||||||||
| Net new debt commitments | 5,030 | — | 225 | 5,255 | |||||||||||
| Distributions | (11,968 | ) | (2,519 | ) | (1,813 | ) | (16,300 | ) | |||||||
| Change in fund value | 1,565 | 2,268 | 232 | 4,065 | |||||||||||
| Balance at 12/31/2016 | $ | 60,466 | $ | 25,041 | $ | 9,752 | $ | 95,259 | |||||||
| Average AUM(1) | $ | 60,297 | $ | 24,553 | $ | 10,144 | $ | 94,994 |
| Credit Group | Private Equity Group | Real Estate Group | Total AUM | ||||||||||||
| Balance at 12/31/2014 | $ | 59,099 | $ | 12,087 | $ | 10,575 | $ | 81,761 | |||||||
| Acquisitions | — | 4,581 | — | 4,581 | |||||||||||
| Net new par/equity commitments | 7,316 | 6,700 | 1,328 | 15,344 | |||||||||||
| Net new debt commitments | 6,554 | — | 105 | 6,659 | |||||||||||
| Distributions | (11,949 | ) | (1,081 | ) | (2,072 | ) | (15,102 | ) | |||||||
| Change in fund value | (634 | ) | 691 | 332 | 389 | ||||||||||
| Balance at 12/31/2015 | $ | 60,386 | $ | 22,978 | $ | 10,268 | $ | 93,632 | |||||||
| Average AUM(1) | $ | 60,975 | $ | 17,115 | $ | 10,182 | $ | 88,272 |
(1) Represents a five-point average of quarter-end balances for each period.
Please refer to “— Results of Operations by Segment” for a more detailed presentation of AUM by segment for each of the periods presented.
The graphs below presents our Incentive Generating AUM and Incentive Eligible AUM by segment as of December 31, 2017, 2016 and 2015 (in millions):
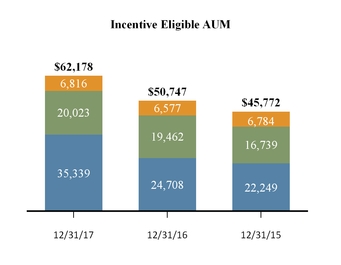
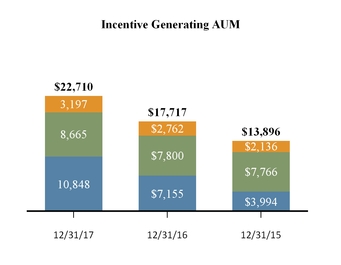
| Credit | Private Equity | Real Estate |
As of December 31, 2017, 2016 and 2015, our available capital, which we refer to as dry powder, was $25.1 billion, $23.2 billion and $22.4 billion, respectively, primarily attributable to our funds in the Credit Group and the Private Equity Group.
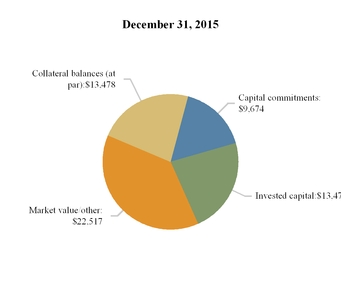
Fee Paying Assets Under Management
The following components generally comprise our FPAUM:
| • | The amount of limited partner capital commitments for certain closed-end funds within the reinvestment period in the Credit Group, funds in the Private Equity Group and certain private funds in the Real Estate Group; |
| • | The amount of limited partner invested capital for the aforementioned closed-end funds beyond the reinvestment period as well as the structured assets funds in the Credit Group, certain managed accounts within their reinvestment period, the mezzanine fund in the Credit Group, European commingled funds in the Credit Group and co-invest vehicles in the Real Estate Group; |
| • | The gross amount of aggregate collateral balance, for CLOs, at par, adjusted for defaulted or discounted collateral; and |
| • | The portfolio value, gross asset value or NAV, adjusted in certain instances for cash or certain accrued expenses, for the remaining funds in the Credit Group, ARCC, certain managed accounts in the Credit Group and certain debt funds in the Real Estate Group. |
The tables below provide the period‑to‑period rollforwards of our total FPAUM by segment for the years ended December 31, 2017, 2016 and 2015 (in millions):
| Credit Group | Private Equity Group | Real Estate Group | Total | ||||||||||||
| FPAUM Balance at 12/31/2016 | $ | 42,709 | $ | 11,314 | $ | 6,540 | $ | 60,563 | |||||||
| Acquisitions | 2,789 | — | — | 2,789 | |||||||||||
| Commitments | 5,060 | 7,955 | 665 | 13,680 | |||||||||||
| Subscriptions/deployment/increase in leverage | 5,094 | 1,122 | 582 | 6,798 | |||||||||||
| Redemptions/distributions/decrease in leverage | (8,733 | ) | (1,606 | ) | (841 | ) | (11,180 | ) | |||||||
| Change in fund value | 2,322 | (375 | ) | 183 | 2,130 | ||||||||||
| Change in fee basis | 209 | (1,552 | ) | (940 | ) | (2,283 | ) | ||||||||
| FPAUM Balance at 12/31/2017 | $ | 49,450 | $ | 16,858 | $ | 6,189 | $ | 72,497 | |||||||
| Average FPAUM(1) | $ | 46,598 | $ | 15,886 | $ | 6,547 | $ | 69,031 |
| Credit Group | Private Equity Group | Real Estate Group | Total | ||||||||||||
| FPAUM Balance at 12/31/2015 | $ | 39,925 | $ | 12,462 | $ | 6,757 | $ | 59,144 | |||||||
| Commitments | 3,631 | 159 | 462 | 4,252 | |||||||||||
| Subscriptions/deployment/increase in leverage | 3,712 | 93 | 630 | 4,435 | |||||||||||
| Redemptions/distributions/decrease in leverage | (5,815 | ) | (665 | ) | (1,019 | ) | (7,499 | ) | |||||||
| Change in fund value | 1,316 | (168 | ) | (58 | ) | 1,090 | |||||||||
| Change in fee basis | (60 | ) | (567 | ) | (232 | ) | (859 | ) | |||||||
| FPAUM Balance at 12/31/2016 | $ | 42,709 | $ | 11,314 | $ | 6,540 | $ | 60,563 | |||||||
| Average FPAUM(1) | $ | 40,938 | $ | 11,800 | $ | 6,669 | $ | 59,407 |
| Credit Group | Private Equity Group | Real Estate Group | Total | ||||||||||||
| FPAUM Balance at 12/31/2014 | $ | 37,274 | $ | 7,702 | $ | 6,118 | $ | 51,094 | |||||||
| Acquisitions | — | 4,046 | — | 4,046 | |||||||||||
| Commitments | 4,117 | 523 | 988 | 5,628 | |||||||||||
| Subscriptions/deployment/increase in leverage | 4,139 | 691 | 803 | 5,633 | |||||||||||
| Redemptions/distributions/decrease in leverage | (5,242 | ) | (414 | ) | (797 | ) | (6,453 | ) | |||||||
| Change in fund value | (57 | ) | (31 | ) | (68 | ) | (156 | ) | |||||||
| Change in fee basis | (306 | ) | (55 | ) | (287 | ) | (648 | ) | |||||||
| FPAUM Balance at 12/31/2015 | $ | 39,925 | $ | 12,462 | $ | 6,757 | $ | 59,144 | |||||||
| Average FPAUM(1) | $ | 38,328 | $ | 11,155 | $ | 6,208 | $ | 55,691 |
(1) Represents a five-point average of quarter-end balances for each period.
Please refer to “— Results of Operations by Segment” for detailed information by segment of the activity affecting total FPAUM for each of the periods presented.
The charts below present FPAUM by its fee basis as of December 31, 2017, 2016 and 2015 (in millions):
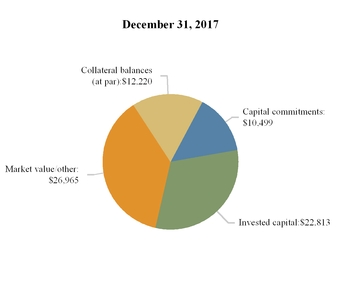
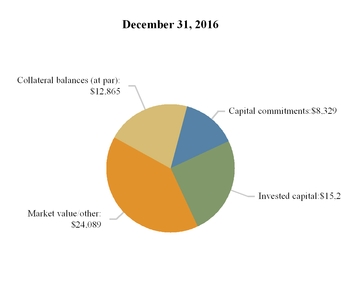
| FPAUM: $72,497 | FPAUM: $60,563 |
| FPAUM: $59,144 |
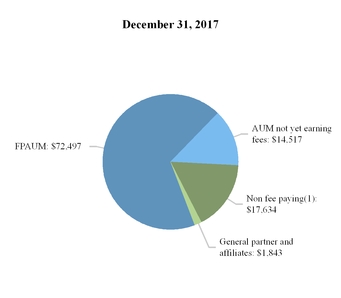
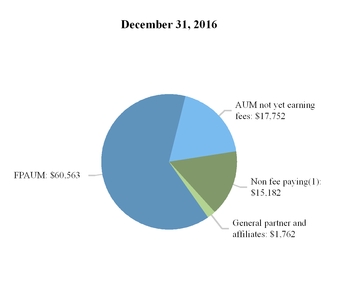
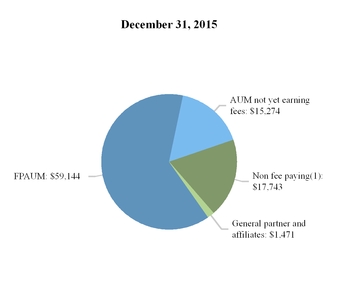
The components of our AUM, including the portion that is FPAUM, are presented below as of December 31, 2017, 2016 and 2015 (in millions):
| AUM: $106,491 | AUM: $95,259 |
| AUM: $93,632 |
(1) Includes $5.7 billion, $6.4 billion and $9.9 billion of AUM of funds from which we indirectly earn management fees as of December 31, 2017, 2016 and 2015, respectively.
Fund Performance Metrics
Fund performance information for our investment funds that are considered to be “significant funds” is included throughout this discussion with analysis to facilitate an understanding of our results of operations for the periods presented. Our significant funds include those that contributed at least 1% of our total management fees for the year ended December 31, 2017 or comprised at least 1% of the Company’s total FPAUM as of December 31, 2017, and for which we have sole discretion for investment decisions within the fund. In addition to management fees, each of our significant funds may generate performance fees upon the achievement of performance hurdles. The fund performance information reflected in this discussion and analysis is not indicative of our overall performance. An investment in Ares is not an investment in any of our funds. Past performance is not indicative of future results. As with any investment there is always the potential for gains as well as the possibility of losses. There can be no assurance that any of these funds or our other existing and future funds will achieve similar returns.
Components of Consolidated Results of Operations
Revenues
Management Fees. Management fees are generally based on a defined percentage of average fair value of assets, total commitments, invested capital, NAV, net investment income or par value of the investment portfolios managed by us. The fees are generally based on a quarterly measurement period and amounts can be paid in advance or in arrears depending on each specific fund. Management fees also include ARCC Part I Fees, a quarterly fee on investment income from ARCC, our publicly traded business development company registered under the Investment Company Act, which is managed by our subsidiary. ARCC Part I Fees are equal to 20% of ARCC's net investment income (before ARCC Part I Fees and incentive fees payable based on ARCC’s net capital gains), subject to a fixed “hurdle rate” of 1.75% per quarter, or 7.0% per annum. No fee is earned until ARCC’s net investment income exceeds a 1.75% hurdle rate, with a “catch up” provision such that we receive 20% of ARCC’s net investment income from the first dollar earned. ARCC Part I Fees are classified as management fees as they are predictable and are recurring in nature, are not subject to contingent repayment and are generally cash-settled each quarter. Management fees are recognized as revenue in the period advisory services are rendered, subject to our assessment of collectability. Additional details regarding our management fees are presented below:
Credit Group:
| • | Syndicated loans and high yield bonds: Typical management fees range from 0.35% to 0.65% of par plus cash or NAV. The syndicated loan funds have an average management contract term of 13.1 years as of December 31, 2017 and the fee ranges generally remain unchanged at the close of the re-investment period. The funds in the high-yield strategy generally represent open-ended managed accounts, which typically do not include investment period termination or management contract expiration dates. |
| • | Credit opportunities and structured credit: Typical management fees range from 0.45% to 1.50% of NAV, gross asset value, committed capital or invested capital. The funds in the credit opportunities strategy generally include open-ended or managed account structures, which typically do not have investment period termination or management contract expiration dates. The funds in the structured credit strategy include a publicly-traded closed-end fund, which does not include investment period termination or management contract termination dates. The funds in these strategies (excluding ARDC) had an average management contract term of 8.0 years as of December 31, 2017. |
| • | U.S and E.U. direct lending: Typical management fees range from 0.50% to 1.50% of invested capital, NAV or total assets. Following the expiration or termination of the investment period, the fee basis for certain closed-end funds and managed accounts in this strategy generally change to the aggregate cost or market value of the portfolio investments. In addition, management fees include the ARCC Part I Fees. Management fees on the lower end of the typical fee range are generally accompanied by transaction based fees. The funds in this strategy (excluding ARCC) had an average management contract term of 8.6 years as of December 31, 2017. |
Private Equity Group:
| • | Private Equity funds: Typical management fees range from 1.50% to 2.00% of total capital commitments during the investment period. The management fees for corporate private equity funds generally step down to between 0.75% and 1.25% of the aggregate adjusted cost of unrealized portfolio investments following the earlier to occur of: (i) the expiration or termination of the investment period or (ii) the launch of a successor fund. The power and energy and infrastructure funds generally step down the fee base to the aggregated adjusted cost of unrealized portfolio investments, while retaining the same fee rate, following the expiration or termination of the investment period. The funds in this strategy had an average management contract term of 11.1 years as of December 31, 2017. |
| • | Special situations funds: Typical management fees range from 1.00% to 1.50% of the lesser of the aggregate cost basis of unrealized portfolio investments or committed capital. The funds in this strategy are comprised of closed-end funds, with investment period termination or management contract termination dates. The special situation funds also include managed accounts, which generally do not include investment period termination or management contract termination dates. The funds in this strategy had an average management contract term of 8.8 years as of December 31, 2017. |
Real Estate Group:
Real Estate funds: Typical management fees range from 0.50% to 1.50% of invested capital, stockholders’ equity or total capital commitments. Following the expiration or termination of the investment period, the basis on which
management fees are earned for certain closed-end funds, managed accounts and co-investment vehicles in this strategy, which pay fees based on committed capital, change from committed capital to invested capital with no change in the management fee rate. The funds in this strategy (excluding ACRE) had an average management contract term of 11.2 years as of December 31, 2017.
In some instances, we may not record management fees that we have earned when a fund does not have sufficient liquidity to pay management fees or may be restricted by certain covenants from making payment. Management fees are not recorded until collectability is assured, which may include meeting certain performance conditions. We refer to these fees as deferred management fees. In future periods, the amount of deferred management fees that we will record typically increases with the length of time the fees were deferred. No material management fees earned were deferred as of December 31, 2017, 2016 and 2015.
As of the reporting date, accrued but unpaid management fees, net of management fee reductions and management fee offsets, are included under management fees receivable on the consolidated statements of financial condition. See Note 12, “Related Party Transactions,” to our consolidated financial statements included in this Annual Report on Form 10‑K for more information.
Performance Fees. Performance fees are based on certain specific hurdle rates as defined in the applicable investment management or partnership agreements of the funds that we manage. Performance fees are recorded on an accrual basis to the extent such amounts are contractually due. The investment returns of most of our funds may be volatile. Performance fees are assessed as a percentage of the investment return of the funds. The performance fee measurement period varies by type of fund and is typically indicative of when realizations are likely to occur. The performance fees from certain Credit Group; credit opportunities funds, structured credit funds and ARCC Part II Fees are measured and realized on an annual basis, typically in the second half of the year. The performance fees from our Credit Group syndicated loans funds, high yield bonds, credit opportunities funds, structured credit funds, managed accounts and Private Equity Group funds are generally measured on an as-if liquidated basis, assuming that the fund was liquidated based on the measurement date net asset value. The performance fees are earned based on cumulative return hurdles and realizations occur as the fund is liquidating. The performance fees for our CLOs are earned based on yearly return hurdles and realizations occur periodically based on the management agreement. For U.S. and E.U. direct lending Credit Group funds, performance fees are measured and distributed on an annual basis. Private Equity Group funds may also distribute performance fees as individual investment realizations occur. For Real Estate Group funds, performance fees are measured at the liquidation of the fund and distributions of performance fees do not occur until all capital is returned to investors. Further, Real Estate Group, Private Equity Group, Credit Group syndicated credit and certain high yield bonds funds may make annual tax distributions based on the tax obligation at year-end and may be greater than the performance fees that were recognized during the year.
Credit Group:
| • | Syndicated loans and high yield bonds: Typical performance fees represent 15% to 20% of each incentive eligible fund’s profits, subject to a preferred return of approximately 12% per annum. |
| • | Credit opportunities and structured credit: Typical performance fees represent 10% to 20% of each incentive eligible fund’s profits, subject to a preferred return of approximately 5% to 8% per annum. |
| • | U.S. and E.U. direct lending: Typical performance fees represent 10% to 20% of each incentive eligible fund’s profits, or cumulative realized capital gains (net of losses and unrealized capital depreciation), and are subject to a preferred return rate of approximately 5% to 8% per annum. |
Private Equity Group:
| • | Private Equity funds: Performance fees represent 20% of each incentive eligible fund’s profits, subject to a preferred return of approximately 8% per annum. |
| • | Special situations funds: Performance fees represent 20% of each incentive eligible fund’s profits, subject to a preferred return of approximately 8% per annum. |
Real Estate Group:
| • | Real estate funds: Typical performance fees represent 10% to 20% of each incentive eligible fund’s profits, subject to a preferred return of approximately 8% to 10% per annum. |
We may be liable to certain funds for previously realized performance fees if the fund’s investment values decline below certain return hurdles, which vary from fund to fund. As of December 31, 2017, 2016 and 2015, if the funds were liquidated at their fair values at that date, there would have been no contingent repayment obligation or liability. When the fair value of a fund’s investment remains constant or falls below certain return hurdles, previously recognized performance fees are reversed. In all cases, each fund is considered separately in evaluating carried interest and potential contingent repayment obligations. For any given period, performance fees could therefore be negative; however, cumulative performance fees can never be negative over the life of a fund. If upon a hypothetical liquidation of a fund’s investments at the then-current fair values previously recognized and distributed performance fees would be required to be returned, a liability would be established in our financial statements for the potential contingent repayment obligation that may differ from the amount of revenue that we reverse. At December 31, 2017, 2016 and 2015, if we assumed all existing investments were valued at $0, the total amount of performance fees subject to contingent repayment obligations, net of tax, would have been approximately $476.1 million, $418.3 million and $322.2 million, respectively, of which approximately $370.0 million, $323.9 million and $247.9 million, respectively, would have been reimbursable by professionals who have received such performance fees.
We are entitled to receive incentive fees from certain funds when the return on investment exceeds previous calendar year-end or date of investment high-watermarks. Some of our funds pay annual incentive fees or allocations equal to 10% to 20% of the fund’s profit for the year, subject to a high-watermark. The high-watermark is the highest historical NAV attributable to a fund investor’s account on which incentive fees were paid and represents the measuring floor for all future incentive fees. In these arrangements, incentive fees are recognized when the performance benchmark has been achieved based on the fund’s then-current fair value and are included in performance fees in our consolidated statement of operations. These incentive fees are a component of performance fees in our consolidated financial statements and are treated as accrued until paid.
For any given period, performance fee revenue in our consolidated statement of operations may include reversals of previously recognized performance fees due to a decrease in the value of a particular fund that results in a decrease of cumulative performance fees earned to date. Since many of our fund return hurdles are cumulative, previously recognized fees also may be reversed in a period of appreciation that is lower than the particular fund’s hurdle rate.
Administrative, Transaction and Other Fees. Other fees primarily include revenue from administrative services provided to certain of our affiliated funds that are paid to us, and revenues associated with Real Estate Group activities such as development and construction. In addition, we may receive fees from certain affiliated funds for activities related to fund transactions, such as loan originations. These fees are recognized as revenue in the period the transaction related services are rendered.
Expenses
Compensation and Benefits. Compensation generally includes salaries, bonuses, health and welfare benefits, equity-based compensation, and ARCC Part I Fee incentive compensation expenses. Compensation cost relating to the issuance of restricted units and options is measured at fair value at the grant date, reduced for actual forfeitures, and expensed over the vesting period on a straight-line basis. Phantom equity unit awards are re-measured at the end of each reporting period. Bonuses are accrued for the service period to which they relate. Compensation and benefits expenses are typically correlated to the operating performance of our segments, which is used to determine incentive based compensation for each segment. Our senior partners receive distributions based on their equity interests and are not paid an annual salary or bonus.
Performance Fee Compensation. Performance fee compensation includes compensation directly related to segment performance fees, which generally consists of percentage interests that we grant to our professionals. Depending on the nature of each fund, the performance fee participation is generally structured as a fixed percentage or as an annual award. The liability is calculated based upon the changes to realized and unrealized performance fees but not payable until the performance fees are realized. We have an obligation to pay our professionals a portion of the performance fees earned from certain funds, including performance fees from Consolidated Funds that are eliminated in consolidation.
Although changes in performance fee compensation are directly correlated with changes in performance fees reported within our segment results, this correlation does not always exist when our results are reported on a fully consolidated basis in accordance with GAAP. This discrepancy is caused by the fact that performance fees earned from our Consolidated Funds are eliminated upon consolidation while performance fee compensation is not eliminated.
General, Administrative and Other Expenses. General and administrative expenses include costs primarily related to placement fees, professional services, occupancy and equipment expenses, depreciation and amortization expenses, travel and related expenses, communication and information services and other general operating items. These expenses are not borne by fund investors.
Expenses of Consolidated Funds. Consolidated Funds’ expenses consist primarily of costs incurred by our Consolidated Funds, including professional fees, research expenses, trustee fees, travel expenses and other costs associated with administering these funds and with launching new products.
Other Income (Expense)
Interest and Dividend Income. Interest and dividend income consists of interest income and dividend income primarily generated from investments in products that we manage. Interest and dividend income are recognized on an accrual basis to the extent that such amounts are expected to be collected.
Interest Expense. Interest expense includes interest related to our Credit Facility, which has a variable interest rate based upon a credit spread that is adjusted with changes to corporate credit ratings, to our senior notes, which have a fixed coupon rate, and to our term loans.
Other Income (Expense), Net. Other income (expense), net consists of transaction gain (loss) and other non-operating and non‑investment related activity, such as loss on disposal of assets and gain (loss) due to the change in fair value of our contingent consideration liabilities.
Net Realized and Unrealized Gain (Loss) on Investments. Net gain (loss) from investment activities include realized and unrealized gains and losses from our investment portfolio. A realized gain (loss) is recognized when we redeem all or a portion of our investment or when we receive a distribution of capital. Unrealized gains (losses) on investments result from appreciation (depreciation) in the fair value of our investments, as well as reversals of previously recorded unrealized appreciation (depreciation) at the time the gain (loss) on an investment becomes realized.
Interest and Other Income of Consolidated Funds. Interest and other income of Consolidated Funds primarily includes interest and dividend income generated from the underlying investment securities incurred under the Consolidated CLOs' and Consolidated Funds' debt facilities.
Interest Expense of Consolidated Funds. Interest expense primarily consists of interest related to our Consolidated CLOs’ loans payable and, to a lesser extent, revolving credit lines, term loans and notes of other Consolidated Funds.
Net Realized and Unrealized Gain (Loss) on Investments of Consolidated Funds. Net gain (loss) from investment activities of our Consolidated Funds include realized and unrealized gains and losses resulting from their investment portfolios. Realized gains (losses) arise from dispositions of investments held by our Consolidated Funds. Unrealized gains (losses) are recorded to reflect appreciation (depreciation) of investments held by the Consolidated Funds due to periodic changes in fair value of the investments, as well as reversals of previously recorded unrealized appreciation (depreciation) of investments upon disposition, when the gain (loss) on an investment becomes realized.
Income Taxes. Prior to the effectiveness of the Tax Election, a substantial portion of our earnings flows through to our owners without being subject to federal income tax at the entity level. A portion of our operations is conducted through domestic corporations that are subject to corporate level taxes and for which we record current and deferred income taxes at the prevailing rates in the various jurisdictions in which these entities operate. The majority of our Consolidated Funds are not subject to income tax as the funds’ investors are responsible for reporting their share of income or loss. To the extent required by federal, state and foreign income tax laws and regulations, certain funds may incur income tax liabilities.
Income taxes are accounted for using the liability method of accounting. Under this method, deferred tax assets and liabilities are recognized for the expected future tax consequences of differences between the carrying amounts of assets and liabilities and their respective tax basis, using tax rates in effect for the year in which the differences are expected to reverse. The effect on deferred assets and liabilities of a change in tax rates is recognized in income in the period when the change is enacted. Deferred tax assets are reduced by a valuation allowance when it is more likely than not that some portion or all of the deferred tax assets will not be realized.
Non-Controlling and Redeemable Interests. Net income attributable to non-controlling and redeemable interests in Consolidated Funds represents the ownership interests that third parties hold in entities that are consolidated into our consolidated financial statements.
Net income attributable to non-controlling interests and redeemable interests in Ares Operating Group entities represents the results attributable to various minority, non-control oriented strategic investment partners based on the proportional daily average ownership in Ares Operating Group entities.
Results of Operations
Consolidated Results of Operations
The following table and discussion sets forth information regarding our consolidated results of operations for the years ended December 31, 2017, 2016 and 2015. We consolidate funds where we are deemed to hold a controlling financial interest. The Consolidated Funds are not necessarily the same entities in each year presented due to changes in ownership, changes in limited partners' rights, and the creation and termination of funds. The consolidation of these funds had no effect on net income attributable to us for the periods presented.
| For the Years Ended December 31, | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||||||||||||||
| 2017 | 2016 | 2015 | Favorable (Unfavorable) | Favorable (Unfavorable) | |||||||||||||||||||||
| $ Change | % Change | $ Change | % Change | ||||||||||||||||||||||
| Revenues | (Dollars in thousands) | ||||||||||||||||||||||||
| Management fees (includes ARCC Part I Fees of $105,467, $121,181, and $121,491 for the years ended December 31, 2017, 2016 and 2015, respectively) | $ | 722,419 | $ | 642,068 | $ | 634,399 | $ | 80,351 | 13 | % | $ | 7,669 | 1 | % | |||||||||||
| Performance fees | 636,674 | 517,852 | 150,615 | 118,822 | 23 | % | 367,237 | 244 | % | ||||||||||||||||
| Administrative, transaction and other fees | 56,406 | 39,285 | 29,428 | 17,121 | 44 | % | 9,857 | 33 | % | ||||||||||||||||
| Total revenues | 1,415,499 | 1,199,205 | 814,442 | 216,294 | 18 | % | 384,763 | 47 | % | ||||||||||||||||
| Expenses | |||||||||||||||||||||||||
| Compensation and benefits | 514,109 | 447,725 | 414,454 | (66,384 | ) | (15 | )% | (33,271 | ) | (8 | )% | ||||||||||||||
| Performance fee compensation | 479,722 | 387,846 | 111,683 | (91,876 | ) | (24 | )% | (276,163 | ) | (247 | )% | ||||||||||||||
| General, administrative and other expenses | 196,730 | 159,776 | 224,798 | (36,954 | ) | (23 | )% | 65,022 | 29 | % | |||||||||||||||
| Transaction support expense | 275,177 | — | — | (275,177 | ) | NM | — | NM | |||||||||||||||||
| Expenses of Consolidated Funds | 39,020 | 21,073 | 18,105 | (17,947 | ) | (85 | )% | (2,968 | ) | (16 | )% | ||||||||||||||
| Total expenses | 1,504,758 | 1,016,420 | 769,040 | (488,338 | ) | (48 | )% | (247,380 | ) | (32 | )% | ||||||||||||||
| Other income (expense) | |||||||||||||||||||||||||
| Net realized and unrealized gain on investments | 67,034 | 28,251 | 17,009 | 38,783 | 137 | % | 11,242 | 66 | % | ||||||||||||||||
| Interest and dividend income | 12,715 | 23,781 | 14,045 | (11,066 | ) | (47 | )% | 9,736 | 69 | % | |||||||||||||||
| Interest expense | (21,219 | ) | (17,981 | ) | (18,949 | ) | (3,238 | ) | (18 | )% | 968 | 5 | % | ||||||||||||
| Debt extinguishment expense | — | — | (11,641 | ) | — | NM | 11,641 | NM | |||||||||||||||||
| Other income, net | 19,470 | 35,650 | 21,680 | (16,180 | ) | (45 | )% | 13,970 | 64 | % | |||||||||||||||
| Net realized and unrealized gain (loss) on investments of Consolidated Funds | 100,124 | (2,057 | ) | (24,616 | ) | 102,181 | NM | 22,559 | NM | ||||||||||||||||
| Interest and other income of Consolidated Funds | 187,721 | 138,943 | 117,373 | 48,778 | 35 | % | 21,570 | 18 | % | ||||||||||||||||
| Interest expense of Consolidated Funds | (126,727 | ) | (91,452 | ) | (78,819 | ) | (35,275 | ) | (39 | )% | (12,633 | ) | (16 | )% | |||||||||||
| Total other income | 239,118 | 115,135 | 36,082 | 123,983 | 108 | % | 79,053 | 219 | % | ||||||||||||||||
| Income before taxes | 149,859 | 297,920 | 81,484 | (148,061 | ) | (50 | )% | 216,436 | 266 | % | |||||||||||||||
| Income tax expense (benefit) | (23,052 | ) | 11,019 | 19,064 | 34,071 | NM | 8,045 | 42 | % | ||||||||||||||||
| Net income | 172,911 | 286,901 | 62,420 | (113,990 | ) | (40 | )% | 224,481 | NM | ||||||||||||||||
| Less: Net income (loss) attributable to non-controlling interests in Consolidated Funds | 60,818 | 3,386 | (5,686 | ) | 57,432 | NM | 9,072 | NM | |||||||||||||||||
| Less: Net income attributable to redeemable interests in Ares Operating Group entities | — | 456 | 338 | (456 | ) | NM | 118 | 35 | % | ||||||||||||||||
| Less: Net income attributable to non-controlling interests in Ares Operating Group entities | 35,915 | 171,251 | 48,390 | (135,336 | ) | (79 | )% | 122,861 | 254 | % | |||||||||||||||
| Net income attributable to Ares Management, L.P. | 76,178 | 111,808 | 19,378 | (35,630 | ) | (32 | )% | 92,430 | NM | ||||||||||||||||
| Less: Preferred equity distributions paid | 21,700 | 12,176 | — | (9,524 | ) | (78 | )% | 12,176 | NM | ||||||||||||||||
| Net income attributable to Ares Management, L.P. common unitholders | $ | 54,478 | $ | 99,632 | $ | 19,378 | (45,154 | ) | (45 | )% | 80,254 | NM |
NM - Not Meaningful
The following two sections discuss the year-over-year fluctuations of our consolidated results of operations for 2017 compared to 2016, as well as 2016 compared to 2015. Additional details behind the fluctuations attributable to a particular segment are included in "—Results of Operations by Segment" for each of the segments.
Year Ended December 31, 2017 Compared to Year Ended December 31, 2016
Revenues
Management Fees. Total management fees increased by $80.4 million, or 13%, to $722.4 million, after giving effect to an increase in management fees of $5.0 million that were eliminated upon consolidation, for the year ended December 31, 2017 compared to year ended December 31, 2016. Segment management fees attributable to the Private Equity Group and Credit Group increased by $50.7 million and $36.8 million, respectively, and segment management fees attributable to the Real Estate Group decreased by $2.1 million compared to the year ended December 31, 2016. For more detail regarding the fluctuations of management fees within each of the segments see "—Results of Operations by Segment."
Performance Fees. Performance fees increased by $118.8 million, or 23%, to $636.7 million, after giving effect to an increase in performance fees of $4.0 million that were eliminated upon consolidation, for the year ended December 31, 2017 compared to year ended December 31, 2016. Segment performance fees attributable to the Real Estate Group, Private Equity Group and Credit Group increased by $61.0 million, $60.2 million and $1.0 million, respectively, compared to the year ended December 31, 2016. For more detail regarding the fluctuations of performance fees within each of the segments see "—Results of Operations by Segment."
Administrative, Transaction and Other Fees. Administrative, transaction and other fees increased by $17.1 million, or 44%, to $56.4 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase was primarily due to a $9.7 million increase in fees associated with certain funds within the U.S. and E.U. direct lending groups, from which we earned transaction fees of $18.2 million for the year ended December 31, 2017 compared to $8.5 million for the year ended December 31, 2016. We began to recognize transaction-based fees from certain direct lending funds in the fourth quarter of 2016. These fees will change with the level of deployed capital and the number of new funds, however we do not earn this fee from each fund. In addition, administrative fees included $30.7 million of compensation and benefits expense reimbursements for the year ended December 31, 2017, of which $7.7 million related to temporary employees that were assisting with the integration of ACAS into ARCC. Comparatively, administrative fee reimbursements offsetting compensation and benefits was $23.9 million for the year ended December 31, 2016.
Expenses
Compensation and Benefits. Compensation and benefits expenses increased by $66.4 million, or 15%, to $514.1 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase was due to an increase in headcount, including an additional $16.8 million attributable to employees hired in connection with ARCC's acquisition of ACAS, of which $7.7 million related to temporary employees assisting with the integration. In addition, equity compensation increased $21.6 million due to restricted stock units granted as part of a one-time grant to certain employees in the current year.
Performance Fee Compensation. Performance fee compensation increased by $91.9 million, or 24%, to $479.7 million for the year ended December 31, 2017 compared to year ended December 31, 2016. The change in performance fee compensation expense directly correlates with the change in our performance fees before giving effect to the performance fees earned from our Consolidated Funds that are eliminated upon consolidation.
General, Administrative and Other Expenses. General, administrative and other expenses increased by $37.0 million, or 23%, to $196.7 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase was attributable to an increase of placement fees of $13.3 million primarily due to the fundraising on two funds within our Credit Group during the current year. We incurred expenses of $4.4 million in connection with the operations of a new joint venture distribution platform. The platform will be used to raise capital for registered investment companies through independent brokerage networks. The first such fund, a direct lending closed end fund, was launched in 2017. Diligence related costs associated with potential acquisitions and capital transactions increased by $4.0 million. Also impacting the year ended December 31, 2017 was a $2.5 million one-time non-income tax expense. The remaining portion of the increase in expense was a result of additional occupancy-related and support costs associated with an increase in headcount. Total headcount increased by 8%, to more than 1,000 employees as of December 31, 2017 compared to total headcount as of December 31, 2016.
Transaction Support Expense. Transaction support expense represents a one-time payment of $275.2 million that we made, through our subsidiary Ares Capital Management LLC, to ACAS shareholders during the first quarter of 2017 upon the closing of ARCC’s acquisition of ACAS. In connection with this acquisition, our AUM increased by $3.6 billion and FPAUM increased by $2.8 billion at closing. No similar expenses were incurred in the year ended December 31, 2016.
Expenses of Consolidated Funds. Expenses of the Consolidated Funds increased by $17.9 million, or 85%, to $39.0 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase was primarily due to increased organizational and offering costs incurred to launch four new funds that we began consolidating in 2017 compared to organizational and offering costs incurred to launch two new funds that we began consolidating in 2016.
Other Income (Expense)
When evaluating the changes in other income (expense), we separately analyze the other income (expense) generated by the Company from the investment returns generated by our Consolidated Funds.
Net Realized and Unrealized Gain on Investments. Net gain on investments of the Company increased by $38.8 million to $67.0 million for the year ended December 31, 2017 compared to $28.3 million for the year ended December 31, 2016. The increase was primarily attributable to ACOF III, which had increases in net returns of $32.2 million for the year ended 2017 due to market appreciation in one of its portfolio companies that completed its initial public offering.
Interest and Dividend Income. Investment and dividend income of the Company decreased by $11.1 million from $23.8 million for the year ended December 31, 2016 to $12.7 million for the year ended December 31, 2017. The decrease was driven by a $14.2 million decrease in interest and dividend income received from our investment in ACOF III for the year ended December 31, 2017 compared to the year ended December 31, 2016. Recapitalization of portfolio companies within ACOF III caused increased disbursements during the year ended December 31, 2016 that did not recur in 2017. The decrease was offset by an increase of $2.1 million of interest income compared to the year ended December 31, 2016 from investments in our syndicated loan strategies, which increased as a result of our compliance with risk retention requirements.
Interest Expense. Interest expense increased by $3.2 million to $21.2 million for the year ended December 31, 2017 compared to $18.0 million for the year ended December 31, 2016. The increase in interest expense was primarily due to CLO term loan balance increasing from $61.1 million as of December 31, 2016 to $160.9 million as of December 31, 2017. CLO term loans entered in 2017 were in connection with risk retention requirements.
Other Income (Expense), Net. Other income of the Company decreased by $16.2 million, or 45%, to $19.5 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The decrease was primarily due to gains of $16.2 million for the year ended December 31, 2016 compared to losses of $1.7 million from the revaluation of certain assets and liabilities denominated in foreign currencies. In 2016, the Brexit vote caused exchange rate fluctuations that resulted in the strengthening of the U.S. dollar against foreign currencies in which we conduct business, primarily the British pounds sterling and the Euro. That strengthening of the U.S. dollar against these foreign currencies resulted in gains in 2016. In 2017, a portion of these gains reversed as the British pounds sterling and the Euro strengthened against the U.S. dollar. The impact was partially mitigated by reductions in liabilities denominated in foreign currencies during 2017.
Net Realized and Unrealized Gain (Loss) on Investments of Consolidated Funds. Net gain (loss) on investments of the Consolidated Funds increased $102.2 million from a net investment loss of $2.1 million for the year ended December 31, 2016 to a net investment gain of $100.1 million for the year ended December 31, 2017. The increase was driven by unrealized appreciation on certain investments of $38.5 million in an Asian corporate private equity fund and an increase in net realized and unrealized gains of $47.1 million in an E.U. direct lending fund due to the strengthening Euro for the year ended December 31, 2017 compared to the year ended December 31, 2016. The remaining portion of the increase was primarily attributable to the impact of unrealized gains from investments in funds we began consolidating in 2017.
Interest and Other Income of Consolidated Funds. Interest income and other income of the Consolidated Funds increased by $48.8 million, or 35%, to $187.7 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase was primarily driven by $28.8 million of interest income from funds we began consolidating in 2017 in addition to the impact of a full year of interest income from funds we began consolidating late in 2016. Also contributing to the increase was income from an Asian corporate private equity investment. These increases were offset by a decrease in interest income from the liquidation of a Consolidated Fund during the year ended December 31, 2017.
Interest Expense of Consolidated Funds. Interest expense of the Consolidated Funds increased by $35.3 million, or 39%, to $126.7 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase was driven
by interest expense from new borrowing arrangements for four new funds combined with a full year of interest expense from two new funds that we began consolidating in 2016.
Income Tax Expense (Benefit). Not all Company and Consolidated Fund entities are subject to taxes. As a result, income taxes may not move in tandem with income before taxes. Specifically, the Company’s investment income and performance fees, prior to the effectiveness of the Tax Election, are generally not subject to income tax.
Income tax benefit was $23.1 million for the year ended December 31, 2017 compared to income tax expense of $11.0 million for the year ended December 31, 2016. The tax benefit for the year ended December 31, 2017 was largely driven by the pre-tax losses recognized by AHI, a U.S. taxable entity, resulting from the $275.2 million transaction support payment made in connection with ARCC's acquisition of ACAS.
Non-Controlling and Redeemable Interests. Net income attributable to non-controlling and redeemable interests in Ares Operating Group entities represents results attributable to the owners of AOG Units that are not held by Ares Management, L.P. and is allocated based on the weighted average daily ownership of the AOG unitholders. The former owners of Indicus Advisors, LLP (“Indicus”), a company we acquired in 2011, exercised the put option on their redeemable interest during the third quarter of 2016, at which time the redeemable interest in Ares Operating Group entities ceased to exist.
Net income attributable to non-controlling and redeemable interests in Ares Operating Group entities decreased $135.3 million, from $171.3 million for the year ended December 31, 2016 to $35.9 million for the year ended December 31, 2017. Net income attributable to non-controlling interests decreased by a higher percentage than net income of the Company for the comparative period due to the the tax benefits recognized by AHI being solely attributable to the Company. The weighted average daily ownership for non-controlling and redeemable AOG unitholders was 61.4% for the year ended December 31, 2017 compared to 62.0% for the year ended December 31, 2016.
Year Ended December 31, 2016 Compared to Year Ended December 31, 2015
Revenues
Management Fees. Total management fees increased by $7.7 million, or 1%, to $642.1 million for the year ended December 31, 2016 compared to year ended December 31, 2015. The increase is primarily due to strong deployment of capital and new funds launched within the U.S. and E.U. direct lending strategy during the year ended December 31, 2016. The increase was partially offset by a decline in Private Equity Group management fees, due to an extension of ACOF II's term that included fee waivers beginning in the first quarter of 2016. Management fees from the Real Estate Group remained relatively flat year over year.
Performance Fees. Performance fees increased by $367.2 million, or 244%, to $517.9 million for the year ended December 31, 2016 compared to year ended December 31, 2015. The Private Equity Group had an increase in performance fees of $303.7 million compared to the year ended December 31, 2015 due primarily to increases of $203.3 million and $70.4 million in performance fees attributable to Ares Corporate Opportunities Fund IV, L.P. ("ACOF IV") and Ares Corporate Opportunities Fund III (“ACOF III”), respectively, due to stronger performance of the underlying portfolio companies. In addition, the Credit Group and Real Estate Group experienced increases in performance fees of $54.6 million and $8.8 million, respectively, over the prior year.
Administrative, Transaction and Other Fees. Administrative, transaction and other fees increased by $9.9 million, or 33%, to $39.3 million for the year ended December 31, 2016 compared to the year ended December 31, 2015, primarily due to an increase in fees associated with certain illiquid credit funds within the Credit Group, from which we earned transaction fees of approximately $8.5 million for the year ended December 31, 2016. Transaction fees based on loan originations were a new source of revenue in 2016 that we expect to continue in future periods.
Expenses
Compensation and Benefits. Compensation and benefits expenses increased by $33.3 million, or 8%, to $447.7 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase was primarily due to an increase in headcount, which drove increases in incentive based compensation and salary and benefit expenses. The employee headcount of OMG increased as part of an effort to reduce our reliance on professional service providers by internalizing certain corporate support functions.
Performance Fee Compensation. Performance fee compensation increased by $276.2 million, or 247%, to $387.8 million for the year ended December 31, 2016 compared to year ended December 31, 2015. The change in performance fee compensation expense directly correlates with the change in our performance fees before giving effect to the performance fees earned from our Consolidated Funds that are eliminated upon consolidation.
General, Administrative and Other Expenses. General, administrative and other expenses decreased by $65.0 million, or 29%, to $159.8 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The decrease was primarily due to $35.9 million of costs incurred in 2015 associated with discontinued merger efforts that did not recur in 2016. Depreciation and amortization expenses also decreased $19.6 million, including a $5.9 million reduction of accelerated amortization, due to certain intangible assets becoming fully amortized in 2015. Additionally, professional fees decreased $5.0 million primarily due to costs associated with the initial adoption of Sarbanes-Oxley in the prior year.
Expenses of Consolidated Funds. Expenses of the Consolidated Funds increased by $3.0 million, or 16%, to $21.1 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase was primarily due to organizational and offering costs incurred to launch new funds in 2016. The increase was partially offset by a reduction in professional fee expenses of the funds in 2016.
Other Income (Expense)
When evaluating the changes in other income (expense), we separately analyze the other income generated by the Company from the investment returns generated by our Consolidated Funds.
Net Realized and Unrealized Gain (Loss) on Investments. Net gain on investments of the Company increased by $11.2 million to $28.3 million for the year ended December 31, 2016 compared to $17.0 million for the year ended December 31, 2015. The increase is primarily attributable to our special situations funds and syndicated loan funds, which had net losses of $16.9 million and $0.5 million, respectively, in 2015 and net gains of $5.7 million and $6.2 million, respectively, in the current year. Partially offsetting these increases, was a $20.0 million realized loss in 2016 related to our minority interest equity method investment in Deimos Management Holdings LLC due to the winding down of its operations.
Interest and Dividend Income. Interest and dividend income of the Company increased by $9.7 million, or 69%, to $23.8 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase was primarily due to a $10.7 million increase in dividends and interest income from our investments in the Private Equity Group funds, including a $10.0 million increase in dividends and interest income from our investment in ACOF III for the year ended December 31, 2016 compared to the prior year period.
Interest Expense. Interest expense of the Company decreased by $1.0 million, or 5%, to $18.0 million for the year ended December 31, 2016 compared to year ended December 31, 2015. The decrease in interest expense was caused by the repayment of notes in connection with terminating a merger agreement in 2015.
Other Income (Expense), Net. Other income of the Company increased by $14.0 million, or 64%, to $35.7 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase was due to $16.2 million of transaction gains from the revaluation of certain assets and liabilities denominated in foreign currencies as a result of the strengthening U.S. dollar for the year ended December 31, 2016 compared to a net transaction loss of $0.3 million for the year ended December 31, 2015. Partially offsetting this increase, was a decrease in the gain recognized as a result of the revaluation of our contingent consideration liability related to the Energy Investors Funds ("EIF") acquisition. Due to lower than expected commitment period management fee revenue, we reduced our contingent consideration liability in each year, resulting in gains of $17.8 million and $21.1 million recognized during the years ended December 31, 2016 and 2015, respectively.
Net Realized and Unrealized Gain (Loss) on Investments of Consolidated Funds. Net loss on investments of the Consolidated Funds decreased $22.6 million from a net investment loss of $24.6 million for the year ended December 31, 2015 to a net investment loss of $2.1 million for the year ended December 31, 2016. The decrease is primarily driven by an increase in valuation of the underlying investments in one of our Credit Group's Consolidated Funds.
Interest and Other Income of Consolidated Funds. Interest income and other income of Consolidated Funds increased by $21.6 million, or 18%, to $138.9 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase is primarily driven by additional dividend income received by certain Consolidated Funds in our Credit Group.
Interest Expense of Consolidated Funds. Interest expense of Consolidated Funds increased by $12.6 million, or 16%, to $91.5 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase was driven by interest expense from the two new funds that we began consolidating in 2016.
Income Tax Expense (Benefit). Not all Company and Consolidated Fund entities are subject to taxes. As a result, income taxes may not move in tandem with income before taxes. Specifically, the Company’s investment income and performance fees, prior to the effectiveness of the Tax Election, are generally not subject to income tax.
Income tax expense was $11.0 million for the year ended December 31, 2016 compared to $19.1 million for the year ended December 31, 2015. The decrease was primarily attributable to the recognition of a deferred tax benefit resulting from an agreement between Ares Management, L.P. and a subsidiary whereby the subsidiary will remit cash for shares awarded under its Equity Incentive Plan, ultimately providing for a difference between taxable income and GAAP income that was recorded as a reduction to the income tax provision.
Non-Controlling and Redeemable Interests. Net income attributable to non-controlling and redeemable interests in Ares Operating Group entities represents results attributable to the owners of Ares Operating Group Units ("AOG Units") that are not held by Ares Management, L.P. and is allocated based on the weighted average daily ownership of the AOG unitholders. The former owners of Indicus Advisors, LLP (“Indicus”), a company we acquired in 2011, exercised the put option on their redeemable interest during the third quarter of 2016, at which time the redeemable interest in Ares Operating Group entities ceased to exist.
Net income attributable to non-controlling and redeemable interests in Ares Operating Group entities increased $123.0 million, from $48.4 million for the year ended December 31, 2015 to $171.3 million for the year ended December 31, 2016. The weighted average daily ownership for non-controlling and redeemable AOG unitholders was 62.0% for the year ended December 31, 2016 compared to 62.1% for the year ended December 31, 2015.
Segment Analysis
Under GAAP, we are required to consolidate entities where we have both significant economics and the power to direct the activities of the entity that impact economic performance. For more information regarding consolidation principles, see Note 2, “Summary of Significant Accounting Policies,” to our consolidated financial statements included in this Annual Report on Form 10‑K.
For segment reporting purposes, revenues and expenses are presented on a basis before giving effect to the results of our Consolidated Funds. As a result, segment revenues from management fees, performance fees and investment income are greater than those presented on a consolidated basis in accordance with GAAP because revenues recognized from Consolidated Funds are eliminated in consolidation. Furthermore, expenses and the effects of other income (expense) are different than related amounts presented on a consolidated basis in accordance with GAAP due to the exclusion of the results of Consolidated Funds.
Discussed below are our results of operations for each of our three reportable segments. In addition to the three segments, we separately discuss the OMG. This information is used by our management to make operating decisions, assess performance and allocate resources.
ENI and Other Measures
The following table sets forth FRE, PRE, ENI, RI and DE by segment basis for the years ended December 31, 2017, 2016 and 2015. FRE, PRE, ENI, RI and DE are non‑GAAP financial measures our management uses when making resource deployment decisions and in assessing performance of our segments. (For definitions of each of these non-GAAP financial measures and how they are being used by management see the Glossary).
| Year Ended December 31, | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||||||||||||||
| 2017 | 2016 | 2015 | Favorable (Unfavorable) | Favorable (Unfavorable) | |||||||||||||||||||||
| $ Change | % Change | $ Change | % Change | ||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||
| Fee related earnings: | |||||||||||||||||||||||||
| Credit Group | $ | 276,966 | $ | 243,177 | $ | 228,599 | $ | 33,789 | 14 | % | $ | 14,578 | 6 | % | |||||||||||
| Private Equity Group | 113,863 | 73,379 | 81,004 | 40,484 | 55 | % | (7,625 | ) | (9 | )% | |||||||||||||||
| Real Estate Group | 14,862 | 16,157 | 10,426 | (1,295 | ) | (8 | )% | 5,731 | 55 | % | |||||||||||||||
| Operations Management Group | (188,701 | ) | (160,363 | ) | (143,037 | ) | (28,338 | ) | (18 | )% | (17,326 | ) | (12 | )% | |||||||||||
| Fee related earnings | $ | 216,990 | $ | 172,350 | $ | 176,992 | 44,640 | 26 | % | (4,642 | ) | (3 | )% | ||||||||||||
| Performance related earnings: | |||||||||||||||||||||||||
| Credit Group | $ | 36,618 | $ | 70,691 | $ | 9,688 | (34,073 | ) | (48 | )% | 61,003 | NM | |||||||||||||
| Private Equity Group | 156,796 | 113,571 | 12,670 | 43,225 | 38 | % | 100,901 | NM | |||||||||||||||||
| Real Estate Group | 45,475 | 19,752 | 17,778 | 25,723 | 130 | % | 1,974 | 11 | % | ||||||||||||||||
| Operations Management Group | 11,828 | (19,381 | ) | (750 | ) | 31,209 | 161 | % | (18,631 | ) | NM | ||||||||||||||
| Performance related earnings | $ | 250,717 | $ | 184,633 | $ | 39,386 | 66,084 | 36 | % | 145,247 | NM | ||||||||||||||
| Economic net income: | |||||||||||||||||||||||||
| Credit Group | $ | 313,584 | $ | 313,868 | $ | 238,287 | (284 | ) | < 1 % | 75,581 | 32 | % | |||||||||||||
| Private Equity Group | 270,659 | 186,950 | 93,674 | 83,709 | 45 | % | 93,276 | 100 | % | ||||||||||||||||
| Real Estate Group | 60,337 | 35,909 | 28,204 | 24,428 | 68 | % | 7,705 | 27 | % | ||||||||||||||||
| Operations Management Group | (176,873 | ) | (179,744 | ) | (143,787 | ) | 2,871 | 2 | % | (35,957 | ) | (25 | )% | ||||||||||||
| Economic net income | $ | 467,707 | $ | 356,983 | $ | 216,378 | 110,724 | 31 | % | 140,605 | 65 | % | |||||||||||||
| Realized income: | |||||||||||||||||||||||||
| Credit Group | $ | 293,724 | $ | 301,706 | $ | 288,700 | (7,982 | ) | (3 | )% | 13,006 | 5 | % | ||||||||||||
| Private Equity Group | 192,814 | 149,544 | 93,668 | 43,270 | 29 | % | 55,876 | 60 | % | ||||||||||||||||
| Real Estate Group | 24,527 | 26,611 | 20,056 | (2,084 | ) | (8 | )% | 6,555 | 33 | % | |||||||||||||||
| Operations Management Group | (185,625 | ) | (177,533 | ) | (143,839 | ) | (8,092 | ) | (5 | )% | (33,694 | ) | (23 | )% | |||||||||||
| Realized income | $ | 325,440 | $ | 300,328 | $ | 258,585 | 25,112 | 8 | % | 41,743 | 16 | % | |||||||||||||
| Distributable earnings: | |||||||||||||||||||||||||
| Credit Group | $ | 268,737 | $ | 294,814 | $ | 279,630 | (26,077 | ) | (9 | )% | 15,184 | 5 | % | ||||||||||||
| Private Equity Group | 187,733 | 144,140 | 88,767 | 43,593 | 30 | % | 55,373 | 62 | % | ||||||||||||||||
| Real Estate Group | 19,189 | 21,594 | 14,831 | (2,405 | ) | (11 | )% | 6,763 | 46 | % | |||||||||||||||
| Operations Management Group | (204,024 | ) | (196,242 | ) | (152,639 | ) | (7,782 | ) | (4 | )% | (43,603 | ) | (29 | )% | |||||||||||
| Distributable earnings | $ | 271,635 | $ | 264,306 | $ | 230,589 | 7,329 | 3 | % | 33,717 | 15 | % |
NM - Not Meaningful
Reconciliation of Certain Non-GAAP Measures to Consolidated GAAP Financial Measures
Income before provision for income taxes is the GAAP financial measure most comparable to ENI, RI, FRE, PRE and DE. The following table presents the reconciliation of income before taxes as reported in the Condensed Consolidated Statements of Operations to ENI, RI, FRE, PRE and DE (in thousands):
| For the Year Ended December 31, | ||||||||||||
| 2017 | 2016 | 2015 | ||||||||||
| Economic net income | ||||||||||||
| Income before taxes | $ | 149,859 | $ | 297,920 | $ | 81,484 | ||||||
| Adjustments: | ||||||||||||
| Amortization of intangibles | 17,850 | 26,638 | 46,227 | |||||||||
| Depreciation expense | 12,631 | 8,215 | 6,942 | |||||||||
| Equity compensation expenses | 69,711 | 39,065 | 32,244 | |||||||||
| Acquisition and merger-related expenses | 259,899 | (16,902 | ) | 34,864 | ||||||||
| Placement fees and underwriting costs | 19,765 | 6,424 | 8,825 | |||||||||
| Offering costs | 688 | — | — | |||||||||
| Other non-cash (income) expense | (1,730 | ) | (1,728 | ) | 110 | |||||||
| Expense of non-controlling interests in consolidated subsidiaries | 1,739 | — | — | |||||||||
| (Income) loss before taxes of non-controlling interests in Consolidated Funds, net of eliminations | (62,705 | ) | (2,649 | ) | 5,682 | |||||||
| Economic net income | 467,707 | 356,983 | 216,378 | |||||||||
| Unconsolidated performance fees income - unrealized | (325,915 | ) | (228,472 | ) | (31,647 | ) | ||||||
| Unconsolidated performance fee compensation - unrealized | 237,392 | 189,582 | 46,492 | |||||||||
| Unconsolidated net investment (income) loss - unrealized | (53,744 | ) | (17,765 | ) | 27,362 | |||||||
| Realized income | 325,440 | 300,328 | 258,585 | |||||||||
| Unconsolidated performance fees income - realized | (317,787 | ) | (292,998 | ) | (121,948 | ) | ||||||
| Unconsolidated performance fee compensation - realized | 242,330 | 198,264 | 65,191 | |||||||||
| Unconsolidated net investment (income) loss | (32,993 | ) | (33,244 | ) | (24,836 | ) | ||||||
| Fee related earnings | 216,990 | 172,350 | 176,992 | |||||||||
| Unconsolidated performance fees—realized | 317,787 | 292,998 | 121,948 | |||||||||
| Unconsolidated performance fee compensation—realized | (242,330 | ) | (198,264 | ) | (65,191 | ) | ||||||
| Unconsolidated investment and other income realized, net | 32,987 | 33,244 | 24,836 | |||||||||
| Adjustments: | ||||||||||||
| One-time acquisition costs | (4,878 | ) | (841 | ) | (2,916 | ) | ||||||
| Dividend equivalent | (14,997 | ) | (5,323 | ) | (3,337 | ) | ||||||
| Non-cash items | 576 | 870 | (758 | ) | ||||||||
| Income tax expense | (4,857 | ) | (16,089 | ) | (5,208 | ) | ||||||
| Placement fees and underwriting costs | (16,324 | ) | (6,424 | ) | (8,825 | ) | ||||||
| Depreciation | (12,631 | ) | (8,215 | ) | (6,952 | ) | ||||||
| Offering costs | (688 | ) | — | — | ||||||||
| Distributable earnings | $ | 271,635 | $ | 264,306 | $ | 230,589 | ||||||
| Performance related earnings | ||||||||||||
| Economic net income | $ | 467,707 | $ | 356,983 | $ | 216,378 | ||||||
| Less: fee related earnings | (216,990 | ) | (172,350 | ) | (176,992 | ) | ||||||
| Performance related earnings | $ | 250,717 | $ | 184,633 | $ | 39,386 |
The following table reconciles unconsolidated performance fee income to our consolidated GAAP performance fee income (in thousands):
| For the Year Ended December 31, | ||||||||||||
| 2017 | 2016 | 2015 | ||||||||||
| Unconsolidated performance fee income - realized | $ | 317,787 | $ | 292,998 | $ | 121,948 | ||||||
| Performance fee income - realized earned from Consolidated Funds | (8,089 | ) | — | (1,769 | ) | |||||||
| Performance fee - realized reclass(1) | (2,721 | ) | (7,367 | ) | (6,472 | ) | ||||||
| Performance fee income - realized | 306,977 | 285,631 | 113,707 | |||||||||
| Unconsolidated performance fee income - unrealized | 325,915 | 228,472 | 31,647 | |||||||||
| Performance fee income - unrealized earned from Consolidated Funds | 2,997 | (1,139 | ) | 6,187 | ||||||||
| Performance fee - unrealized reclass(1) | 785 | 4,888 | (926 | ) | ||||||||
| Performance fee income - unrealized | 329,697 | 232,221 | 36,908 | |||||||||
| Total GAAP performance fee income | $ | 636,674 | $ | 517,852 | $ | 150,615 |
(1) Related to performance fees for AREA Sponsor Holdings LLC. Changes in value of this investment are reflected within other (income) expense in the Company’s Condensed Consolidated Statements of Operations.
The following table reconciles unconsolidated other income to our consolidated GAAP other income (in thousands):
| For the Year Ended December 31, | ||||||||||||
| 2017 | 2016 | 2015 | ||||||||||
| Unconsolidated net investment income | $ | 86,737 | $ | 51,009 | $ | (2,526 | ) | |||||
| Net investment income from Consolidated Funds | 129,223 | 42,244 | 25,702 | |||||||||
| Performance fee - reclass(1) | 1,936 | 2,479 | 7,398 | |||||||||
| Change in value of contingent consideration | 20,156 | 17,675 | 21,064 | |||||||||
| Other non-cash expense | 1,730 | 1,728 | (110 | ) | ||||||||
| Merger related expense | — | — | (15,446 | ) | ||||||||
| Offering costs | (688 | ) | — | — | ||||||||
| Other income of non-controlling interests in consolidated subsidiaries | 24 | — | — | |||||||||
| Total GAAP other income | $ | 239,118 | $ | 115,135 | $ | 36,082 |
(1) Related to performance fees for AREA Sponsor Holdings LLC. Changes in value of this investment are reflected within other (income) expense in the Company’s Condensed Consolidated Statements of Operations.
Results of Operations by Segment
Credit Group
The following table sets forth certain statement of operations data and certain other data of our Credit Group segment for the periods presented.
| For the Years Ended December 31, | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||||||||||||||
| 2017 | 2016 | 2015 | Favorable (Unfavorable) | Favorable (Unfavorable) | |||||||||||||||||||||
| $ Change | % Change | $ Change | % Change | ||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||
| Management fees (includes ARCC Part I Fees of $105,467, $121,181, and $121,491 for the years ended December 31, 2017, 2016 and 2015, respectively) | $ | 481,466 | $ | 444,664 | $ | 432,769 | $ | 36,802 | 8 | % | $ | 11,895 | 3 | % | |||||||||||
| Other fees | 20,830 | 9,953 | 414 | 10,877 | 109 | % | 9,539 | NM | |||||||||||||||||
| Compensation and benefits | (192,022 | ) | (182,901 | ) | (174,262 | ) | (9,121 | ) | (5 | )% | (8,639 | ) | (5 | )% | |||||||||||
| General, administrative and other expenses | (33,308 | ) | (28,539 | ) | (30,322 | ) | (4,769 | ) | (17 | )% | 1,783 | 6 | % | ||||||||||||
| Fee Related Earnings | 276,966 | 243,177 | 228,599 | 33,789 | 14 | % | 14,578 | 6 | % | ||||||||||||||||
| Performance fees-realized | 21,087 | 51,435 | 87,583 | (30,348 | ) | (59 | )% | (36,148 | ) | (41 | )% | ||||||||||||||
| Performance fees-unrealized | 54,196 | 22,851 | (71,341 | ) | 31,345 | 137 | % | 94,192 | NM | ||||||||||||||||
| Performance fee compensation-realized | (9,218 | ) | (11,772 | ) | (44,110 | ) | 2,554 | 22 | % | 32,338 | 73 | % | |||||||||||||
| Performance fee compensation-unrealized | (35,284 | ) | (26,109 | ) | 36,659 | (9,175 | ) | (35 | )% | (62,768 | ) | NM | |||||||||||||
| Net performance fees | 30,781 | 36,405 | 8,791 | (5,624 | ) | (15 | )% | 27,614 | NM | ||||||||||||||||
| Investment income-realized | 7,102 | 4,928 | 13,274 | 2,174 | 44 | % | (8,346 | ) | (63 | )% | |||||||||||||||
| Investment income (loss)-unrealized | 5,480 | 11,848 | (15,731 | ) | (6,368 | ) | (54 | )% | 27,579 | NM | |||||||||||||||
| Interest and other investment income | 5,660 | 26,119 | 10,429 | (20,459 | ) | (78 | )% | 15,690 | 150 | % | |||||||||||||||
| Interest expense | (12,405 | ) | (8,609 | ) | (7,075 | ) | (3,796 | ) | (44 | )% | (1,534 | ) | (22 | )% | |||||||||||
| Net investment income | 5,837 | 34,286 | 897 | (28,449 | ) | (83 | )% | 33,389 | NM | ||||||||||||||||
| Performance related earnings | 36,618 | 70,691 | 9,688 | (34,073 | ) | (48 | )% | 61,003 | NM | ||||||||||||||||
| Economic net income | $ | 313,584 | $ | 313,868 | $ | 238,287 | (284 | ) | < 1% | 75,581 | 32 | % | |||||||||||||
| Realized income | $ | 293,724 | $ | 301,706 | $ | 288,700 | (7,982 | ) | (3 | )% | 13,006 | 5 | % | ||||||||||||
| Distributable earnings | $ | 268,737 | $ | 294,814 | $ | 279,630 | (26,077 | ) | (9 | )% | 15,184 | 5 | % |
NM - Not meaningful
Accrued performance fees for the Credit Group are comprised of the following:
| As of December 31, | |||||||
| 2017 | 2016 | ||||||
| (Dollars in thousands) | |||||||
| CLOs | $ | 451 | $ | 8,182 | |||
| CSF | 28,158 | 26,416 | |||||
| ACE II | 24,090 | 16,427 | |||||
| ACE III | 43,595 | 11,541 | |||||
| Other credit funds | 72,210 | 42,386 | |||||
| Total Credit Group | $ | 168,504 | $ | 104,952 |
Net performance fee revenues for the Credit Group are comprised of the following:
| Year Ended December 31, 2017 | Year Ended December 31, 2016 | Year Ended December 31, 2015 | |||||||||||||||||||||||||||||||||
| Realized | Unrealized | Net | Realized | Unrealized | Net | Realized | Unrealized | Net | |||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| CLOs | $ | 7,615 | $ | (7,850 | ) | $ | (235 | ) | $ | 31,347 | $ | (18,379 | ) | $ | 12,968 | $ | 16,942 | $ | (14,413 | ) | $ | 2,529 | |||||||||||||
| CSF | — | 1,742 | 1,742 | — | 16,341 | 16,341 | 60,000 | (84,265 | ) | (24,265 | ) | ||||||||||||||||||||||||
| ARCC | — | — | — | — | — | — | (417 | ) | — | (417 | ) | ||||||||||||||||||||||||
| ACE II | 3,201 | 6,543 | 9,744 | 12,124 | (8,110 | ) | 4,014 | 1,916 | 19,659 | 21,575 | |||||||||||||||||||||||||
| ACE III | — | 29,557 | 29,557 | — | 12,035 | 12,035 | — | — | — | ||||||||||||||||||||||||||
| Other credit funds | 10,271 | 24,204 | 34,475 | 7,964 | 20,964 | 28,928 | 9,142 | 7,678 | 16,820 | ||||||||||||||||||||||||||
| Total Credit Group | $ | 21,087 | $ | 54,196 | $ | 75,283 | $ | 51,435 | $ | 22,851 | $ | 74,286 | $ | 87,583 | $ | (71,341 | ) | $ | 16,242 |
The following tables present the components of the change in performance fees - unrealized for the Credit Group:
| Year Ended December 31, 2017 | Year Ended December 31, 2016 | ||||||||||||||||||||||||||||||
| Performance Fees - Realized | Increases | Decreases | Performance Fees - Unrealized | Performance Fees - Realized | Increases | Decreases | Performance Fees - Unrealized | ||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||
| CLOs | $ | (7,615 | ) | $ | 282 | $ | (517 | ) | $ | (7,850 | ) | $ | (31,347 | ) | $ | 13,234 | $ | (266 | ) | $ | (18,379 | ) | |||||||||
| CSF | — | 1,742 | — | 1,742 | — | 16,341 | — | 16,341 | |||||||||||||||||||||||
| ACE II | (3,201 | ) | 9,744 | — | 6,543 | (12,124 | ) | 4,014 | — | (8,110 | ) | ||||||||||||||||||||
| ACE III | — | 29,557 | — | 29,557 | — | 12,035 | — | 12,035 | |||||||||||||||||||||||
| Other credit funds | (10,271 | ) | 38,236 | (3,761 | ) | 24,204 | (7,964 | ) | 30,666 | (1,738 | ) | 20,964 | |||||||||||||||||||
| Total Credit Group | $ | (21,087 | ) | $ | 79,561 | $ | (4,278 | ) | $ | 54,196 | $ | (51,435 | ) | $ | 76,290 | $ | (2,004 | ) | $ | 22,851 |
| Year Ended December 31, 2015 | |||||||||||||||
| Performance Fees - Realized | Increases | Decreases | Performance Fees - Unrealized | ||||||||||||
| (Dollars in thousands) | |||||||||||||||
| CLOs | $ | (16,942 | ) | $ | 4,119 | $ | (1,590 | ) | $ | (14,413 | ) | ||||
| CSF | (60,000 | ) | — | (24,265 | ) | (84,265 | ) | ||||||||
| ARCC | 417 | — | (417 | ) | — | ||||||||||
| ACE II | (1,916 | ) | 21,575 | — | 19,659 | ||||||||||
| Other credit funds | (9,142 | ) | 18,786 | (1,966 | ) | 7,678 | |||||||||
| Total Credit Group | $ | (87,583 | ) | $ | 44,480 | $ | (28,238 | ) | $ | (71,341 | ) |
Credit Group—Year Ended December 31, 2017 Compared to Year Ended December 31, 2016
Fee Related Earnings:
Fee related earnings increased $33.8 million, or 14%, to $277.0 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. Fee related earnings were impacted by fluctuations of the following components:
Management Fees. Total management fees increased by $36.8 million, or 8%, to $481.5 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. ARCC's acquisition of ACAS in the first quarter of 2017 increased FPAUM by approximately $2.8 billion at the time of acquisition, which drove an increase of $34.3 million in management fees generated by ARCC in 2017. Conversely, ARCC Part I Fees decreased $15.7 million due primarily to the $10 million per quarter ARCC Part I Fee waiver, which became effective in the second quarter of 2017 and totaled $30.0 million for 2017. Direct lending funds generated additional management fees of $25.5 million from capital deployment in existing funds during the year ended December 31, 2017, $10.3 million of which was attributable to Ares Capital Europe III, L.P. (“ACE III”). We also earned $16.8 million of management fees from 34 new funds that launched at various points throughout 2017. The aforementioned increases were offset by a decrease of $17.9 million in management fees from 23 funds liquidated during the year ended December 31, 2017.
The effective management fee rate decreased by 0.05% from 1.06% for the year ended December 31, 2016, to 1.01% for the year ended December 31, 2017. ARCC Part I Fees' contribution towards the total effective management fee rate of the Credit Group decreased from 0.29% for the year ended December 31, 2016 to 0.22% for the year ended December 31, 2017. The decrease in effective management fee rate was primarily due to the impact of the ARCC Part I fee waiver, offset partially by new direct lending funds with higher effective fee rates replacing run-off assets with lower fees rates.
Other Fees. Other fees increased by $10.9 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase resulted from a full year of transaction fees based on the increased volume and the amount of loans funded from certain U.S. direct lending funds.
Compensation and Benefits. Compensation and benefits expenses increased by $9.1 million, or 5%, to $192.0 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. Compensation and benefits expenses increased for the year ended December 31, 2017 primarily due to additional headcount and increase of incentive compensation with segment performance compared to the year ended December 31, 2016. Compensation costs related to employees hired in connection with the ARCC-ACAS Transaction was $6.7 million for the year ended December 31, 2017. This increase in expense was offset by a $9.3 million decrease in ARCC Part I compensation during 2017, due to the decrease in ARCC Part I Fee revenue. Compensation and benefits expenses represented 39.9% of management fees for the year ended December 31, 2017 compared to 41.1% for the year ended December 31, 2016.
General, Administrative and Other Expenses. General, administrative and other expenses increased by $4.8 million, or 17%, to $33.3 million for the year ended December 31, 2017. The increase in the current year was attributable to $4.4 million of costs incurred from operating expenses from a joint venture distribution platform. The platform will be used to raise capital for registered investment companies through independent brokerage networks. The first such fund, a direct lending closed end fund, was launched in 2017.
Performance Related Earnings:
Performance related earnings decreased $34.1 million to $36.6 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. Performance related earnings were impacted by fluctuations of the following components:
Net Performance Fees. Net performance fees include realized and unrealized performance fees, net of realized and unrealized performance fee compensation. The impact of reversals of previously recognized performance fee revenue and the corresponding performance fee compensation expense is reflected as a reduction in unrealized performance fees and unrealized performance fee compensation.
Net performance fees decreased by $5.6 million to $30.8 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The decrease in the current year was driven by decreased performance fees primarily from our syndicated loans strategy, which benefited from a broad-based credit market rally in the prior year. These decreases were partially offset by a $23.3 million increase in gross performance fees earned from Ares Capital Europe II, L.P. (“ACE II”) and Ares Capital Europe III, L.P. (“ACE III”) for the December 31, 2017 compared to the year ended December 31, 2016, which generated returns in excess of their hurdle rates on an increased capital base.
Net Investment Income. Net investment income decreased by $28.4 million to $5.8 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The decrease in the current year was primarily attributable to the revaluation of certain assets and liabilities denominated in foreign currencies, which resulted in losses of $4.5 million for the year ended December 31, 2017 compared to gains of $16.0 million for the year ended December 31, 2016. In 2016, the Brexit vote caused exchange rate fluctuations that resulted in the strengthening of the U.S. dollar against foreign currencies in which we conduct business, primarily the British pounds sterling and the Euro. That strengthening of the U.S. dollar against these foreign currencies resulted in gains in 2016. In 2017, a portion of these gains reversed as the British pounds sterling and the Euro strengthened against the U.S. dollar. The impact was partially mitigated by reductions in liabilities denominated in foreign currencies during 2017. Interest expense also increased $3.8 million for the year ended December 31, 2017 compared to the year ended December 31, 2016 as a result of term loans that were entered into in connection with new CLOs.
Realized Income:
Realized income decreased $8.0 million, or 3%, to $293.7 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The decrease was primarily driven by lower net realized performance fees and net realized investment income as a result of the wind down of legacy CLOs. These decreases were partially offset by an increase in FRE of $33.8 million for the year ended December 31, 2017 compared to the year ended December 31, 2016.
Economic Net Income:
Economic net income is comprised of fee related earnings and performance related earnings. Economic net income decreased $0.3 million to $313.6 million for the year ended December 31, 2017 compared to the year ended December 31, 2016 as a result of the fluctuations described above.
Distributable Earnings:
DE decreased $26.1 million, or 9%, to $268.7 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The decrease in DE was due to decreases of $14.0 million in net realized investment and other income and of $27.8 million in net realized performance fees for the year ended December 31, 2017, as described above. Increases in non-core expenses of $18.1 million for the year ended December 31, 2017 compared to the year ended December 31, 2016 also contributed to the decrease of DE. The primary drivers for the increase in non-core expenses were placement fees of $8.5 million related to two new fund launches and to dividend equivalent payments of $8.1 million made on unvested restricted stock. These decreases were partially offset by an increase in FRE of $33.8 million for the year ended December 31, 2017 compared to the year ended December 31, 2016.
Credit Group—Year Ended December 31, 2016 Compared to Year Ended December 31, 2015
Fee Related Earnings:
Fee related earnings increased $14.6 million, or 6%, to $243.2 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. Fee related earnings were impacted by fluctuations of the following components:
Management Fees. Total management fees increased by $11.9 million, or 3%, to $444.7 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase in management fees was primarily driven by the launch of 11 funds subsequent to December 31, 2015 that increased fees by $11.9 million.
Management fees of the Credit Group include quarterly fees on the net investment income from ARCC (ARCC Part I Fees). Total ARCC management fees for the years ended December 31, 2016 and 2015 were $258.2 million and $255.8 million, respectively, of which $121.2 million and $121.5 million, respectively, were related to ARCC Part I Fees.
The effective management fee rate decreased by 0.07% from 1.13% for the year ended December 31, 2015, to 1.06% for the year ended December 31, 2016. ARCC Part I Fees contributed 0.29% and 0.32% towards the total effective management fee rate of the Credit Group for the years ended December 31, 2016 and 2015, respectively.
Other Fees. Other fees increased by $9.5 million for the year ended December 31, 2016 compared to the year ended December 31, 2015, resulting from the introduction of a transaction fee earned from a new fund based on underwriting and originating activities.
Compensation and Benefits. Compensation and benefits expenses increased by $8.6 million, or 5%, to $182.9 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. Compensation and benefits expenses increased during the year ended December 31, 2016 primarily due to an increase in headcount, which drove increases in incentive based compensation and salary and benefit expenses. In addition, salary and benefits expenses increased in the current year due to merit based increases. Compensation and benefits expenses represented 41.1% of management fees for the year ended December 31, 2016 compared to 40.3% for the year ended December 31, 2015.
General, Administrative and Other Expenses. General, administrative and other expenses decreased by $1.8 million, or 6%, to $28.5 million for the year ended December 31, 2016, remaining relatively consistent with the year ended December 31, 2015.
Performance Related Earnings:
Performance related earnings increased $61.0 million to $70.7 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. Performance related earnings were impacted by fluctuations of the following components:
Net Performance Fees. Net performance fees include realized and unrealized performance fees, net of realized and unrealized performance fee compensation. The impact of reversals of previously recognized performance fee revenue and the corresponding performance fee compensation expense is reflected as a reduction in unrealized performance fees and unrealized performance fee compensation.
Net performance fees increased by $27.6 million to $36.4 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase in performance fees for the year ended December 31, 2016 was primarily driven by market appreciation in credit opportunities, U.S. direct lending and syndicated loans strategies as a result of strengthening credit markets. Additionally, net performance fees increased as a result of realizations from several CLOs in excess of unrealized amounts previously recognized during the year ended December 31, 2016 as compared to the year ended December 31, 2015.
Net Investment Income (Loss). Net investment income increased by $33.4 million to $34.3 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase was driven by overall improvements in the credit markets that resulted in unrealized market appreciation of $10.0 million and $4.2 million on investments in our syndicated loan funds and U.S. direct lending funds, respectively, offset by unrealized depreciation of $0.8 million on investments in our E.U. direct lending funds for the year ended December 31, 2016. In comparison, our investments in syndicated loan funds and U.S. direct lending funds experienced unrealized losses of $14.6 million and $0.4 million, respectively, for the year ended December 31, 2015. Additionally, $16.0 million of transaction gains from the revaluation of certain assets and liabilities denominated in foreign currencies is included in interest and other investment income for the year ended December 31, 2016 compared to transaction losses of $0.5 million for the year ended December 31, 2015.
Realized Income:
Realized income increased $13.0 million, or 5%, to $301.7 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase was due to increases of $14.6 million and $2.2 million in FRE and net realized investment and other income, respectively, offset by a decrease in net realized performance fees of $3.8 million.
Economic Net Income:
Economic net income is comprised of fee related earnings and performance related earnings. Economic net income increased $75.6 million, or 32%, to $313.9 million for the year ended December 31, 2016 compared to the year ended December 31, 2015 as a result of the fluctuations described above.
Distributable Earnings:
DE increased $15.2 million, or 5%, to $294.8 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. DE was positively impacted by increases in FRE of $14.6 million and an increase of $2.2 million in net realized investment and other income. The increases were partially offset by a decrease in net realized performance fees of $3.8 million.
Credit Group—Assets Under Management
The tables below provide the period‑to‑period rollforwards of AUM for the Credit Group for the years ended December 31, 2017, 2016 and 2015 (in millions):
| Syndicated Loans | High Yield | Credit Opportunities | Structured Credit | U.S. Direct Lending(1) | E.U. Direct Lending | Total Credit Group | |||||||||||||||||||||
| Balance at 12/31/2016 | $ | 17,260 | $ | 4,978 | $ | 3,304 | $ | 4,254 | $ | 21,110 | $ | 9,560 | $ | 60,466 | |||||||||||||
| Acquisitions | — | — | — | — | 3,605 | — | 3,605 | ||||||||||||||||||||
| Net new par/ equity commitments | 731 | 558 | (6 | ) | 356 | 6,167 | 864 | 8,670 | |||||||||||||||||||
| Net new debt commitments | 3,536 | — | — | — | 1,882 | 571 | 5,989 | ||||||||||||||||||||
| Distributions | (5,426 | ) | (1,224 | ) | (146 | ) | (173 | ) | (3,011 | ) | (872 | ) | (10,852 | ) | |||||||||||||
| Change in fund value | 429 | 318 | 181 | 354 | 887 | 1,685 | 3,854 | ||||||||||||||||||||
| Balance at 12/31/2017 | $ | 16,530 | $ | 4,630 | $ | 3,333 | $ | 4,791 | $ | 30,640 | $ | 11,808 | $ | 71,732 | |||||||||||||
| Average AUM(2) | $ | 16,861 | $ | 4,685 | $ | 3,343 | $ | 4,482 | $ | 26,957 | $ | 10,743 | $ | 67,071 |
| Syndicated Loans | High Yield | Credit Opportunities | Structured Credit | U.S. Direct Lending(1) | E.U. Direct Lending | Total Credit Group | |||||||||||||||||||||
| Balance at 12/31/2015 | $ | 17,617 | $ | 3,303 | $ | 3,715 | $ | 3,103 | $ | 23,592 | $ | 9,056 | $ | 60,386 | |||||||||||||
| Net new par/ equity commitments | 624 | 1,664 | 281 | 905 | 751 | 1,228 | 5,453 | ||||||||||||||||||||
| Net new debt commitments | 2,287 | — | — | — | 2,411 | 332 | 5,030 | ||||||||||||||||||||
| Distributions | (3,410 | ) | (459 | ) | (923 | ) | (106 | ) | (6,269 | ) | (801 | ) | (11,968 | ) | |||||||||||||
| Change in fund value | 142 | 470 | 231 | 352 | 625 | (255 | ) | 1,565 | |||||||||||||||||||
| Balance at 12/31/2016 | $ | 17,260 | $ | 4,978 | $ | 3,304 | $ | 4,254 | $ | 21,110 | $ | 9,560 | $ | 60,466 | |||||||||||||
| Average AUM(2) | $ | 17,162 | $ | 4,217 | $ | 3,365 | $ | 3,743 | $ | 22,299 | $ | 9,511 | $ | 60,297 |
| Syndicated Loans | High Yield | Credit Opportunities | Structured Credit | U.S. Direct Lending | E.U. Direct Lending | Total Credit Group | |||||||||||||||||||||
| Balance at 12/31/2014 | $ | 20,175 | $ | 3,076 | $ | 5,479 | $ | 1,719 | $ | 23,115 | $ | 5,535 | $ | 59,099 | |||||||||||||
| Net new par/ equity commitments | (13 | ) | 502 | 14 | 1,716 | 1,537 | 3,560 | 7,316 | |||||||||||||||||||
| Net new debt commitments | 2,949 | — | 302 | — | 2,051 | 1,252 | 6,554 | ||||||||||||||||||||
| Distributions | (4,949 | ) | (213 | ) | (1,915 | ) | (201 | ) | (3,654 | ) | (1,017 | ) | (11,949 | ) | |||||||||||||
| Change in fund value | (545 | ) | (62 | ) | (165 | ) | (131 | ) | 543 | (274 | ) | (634 | ) | ||||||||||||||
| Balance at 12/31/2015 | $ | 17,617 | $ | 3,303 | $ | 3,715 | $ | 3,103 | $ | 23,592 | $ | 9,056 | $ | 60,386 | |||||||||||||
| Average AUM(2) | $ | 19,605 | $ | 3,281 | $ | 4,533 | $ | 2,804 | $ | 24,179 | $ | 6,573 | $ | 60,975 |
(1) Distributions of $3.0 billion and $6.3 billion in 2017 and 2016, respectively, includes $1.6 billion and $4.8 billion reduction in leverage, respectively, related to the paydown associated with the Senior Secured Loan Program (the "SSLP").
(2) Represents a five-point average of quarter-end balances for each period.
Credit Group—Fee Paying AUM
The tables below provides the period‑to‑period rollforwards of fee paying AUM for the Credit Group for the years ended December 31, 2017, 2016 and 2015 (in millions):
| Syndicated Loans | High Yield | Credit Opportunities | Structured Credit | U.S. Direct Lending | E.U. Direct Lending | Total Credit Group | |||||||||||||||||||||
| FPAUM Balance at 12/31/2016 | $ | 15,998 | $ | 4,978 | $ | 2,705 | $ | 3,128 | $ | 11,292 | $ | 4,608 | $ | 42,709 | |||||||||||||
| Acquisitions | — | — | — | — | 2,789 | — | 2,789 | ||||||||||||||||||||
| Commitments | 4,116 | 495 | 4 | 273 | 172 | — | 5,060 | ||||||||||||||||||||
| Subscriptions/deployment/increase in leverage | — | 77 | 65 | 325 | 2,998 | 1,629 | 5,094 | ||||||||||||||||||||
| Redemptions/distributions/decrease in leverage | (5,240 | ) | (1,238 | ) | (137 | ) | (587 | ) | (948 | ) | (583 | ) | (8,733 | ) | |||||||||||||
| Change in fund value | 377 | 317 | 172 | 295 | 566 | 595 | 2,322 | ||||||||||||||||||||
| Change in fee basis | — | — | — | — | — | 209 | 209 | ||||||||||||||||||||
| FPAUM Balance at 12/31/2017 | $ | 15,251 | $ | 4,629 | $ | 2,809 | $ | 3,434 | $ | 16,869 | $ | 6,458 | $ | 49,450 | |||||||||||||
| Average FPAUM(1) | $ | 15,550 | $ | 4,685 | $ | 2,788 | $ | 3,316 | $ | 14,627 | $ | 5,632 | $ | 46,598 |
| Syndicated Loans | High Yield | Credit Opportunities | Structured Credit | U.S. Direct Lending | E.U. Direct Lending | Total Credit Group | |||||||||||||||||||||
| FPAUM Balance at 12/31/2015 | $ | 17,180 | $ | 3,303 | $ | 2,606 | $ | 2,558 | $ | 10,187 | $ | 4,091 | $ | 39,925 | |||||||||||||
| Commitments | 1,985 | 1,537 | 62 | 7 | 40 | — | 3,631 | ||||||||||||||||||||
| Subscriptions/deployment/increase in leverage | 24 | 127 | 366 | 379 | 1,423 | 1,393 | 3,712 | ||||||||||||||||||||
| Redemptions/distributions/decrease in leverage | (3,239 | ) | (459 | ) | (492 | ) | (112 | ) | (928 | ) | (585 | ) | (5,815 | ) | |||||||||||||
| Change in fund value | 48 | 470 | 223 | 296 | 570 | (291 | ) | 1,316 | |||||||||||||||||||
| Change in fee basis | — | — | (60 | ) | — | — | — | (60 | ) | ||||||||||||||||||
| FPAUM Balance at 12/31/2016 | $ | 15,998 | $ | 4,978 | $ | 2,705 | $ | 3,128 | $ | 11,292 | $ | 4,608 | $ | 42,709 | |||||||||||||
| Average FPAUM(1) | $ | 16,234 | $ | 4,217 | $ | 2,569 | $ | 2,805 | $ | 10,640 | $ | 4,473 | $ | 40,938 |
| Syndicated Loans | High Yield | Credit Opportunities | Structured Credit | U.S. Direct Lending | E.U. Direct Lending | Total Credit Group | |||||||||||||||||||||
| FPAUM Balance at 12/31/2014 | $ | 16,236 | $ | 3,075 | $ | 3,943 | $ | 1,602 | $ | 9,400 | $ | 3,018 | $ | 37,274 | |||||||||||||
| Commitments | 3,284 | 341 | 60 | 11 | 421 | — | 4,117 | ||||||||||||||||||||
| Subscriptions/deployment/increase in leverage | 122 | 97 | 164 | 1,102 | 1,088 | 1,566 | 4,139 | ||||||||||||||||||||
| Redemptions/distributions/decrease in leverage | (2,252 | ) | (213 | ) | (882 | ) | (218 | ) | (1,254 | ) | (423 | ) | (5,242 | ) | |||||||||||||
| Change in fund value | (281 | ) | (123 | ) | (283 | ) | (53 | ) | 793 | (110 | ) | (57 | ) | ||||||||||||||
| Change in fee basis | 71 | 126 | (396 | ) | 114 | (261 | ) | 40 | (306 | ) | |||||||||||||||||
| FPAUM Balance at 12/31/2015 | $ | 17,180 | $ | 3,303 | $ | 2,606 | $ | 2,558 | $ | 10,187 | $ | 4,091 | $ | 39,925 | |||||||||||||
| Average FPAUM(1) | $ | 16,533 | $ | 3,256 | $ | 3,290 | $ | 2,261 | $ | 9,525 | $ | 3,463 | $ | 38,328 |
(1) Represents a five-point average of quarter-end balances for each period.
The charts below present FPAUM for the Credit Group by its fee basis as of December 31, 2017, 2016 and 2015 (in millions):
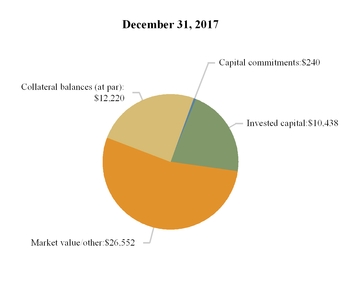
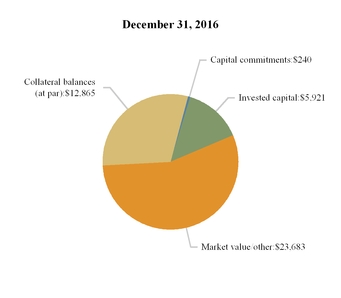
| FPAUM: $49,450 | FPAUM: $42,709 |
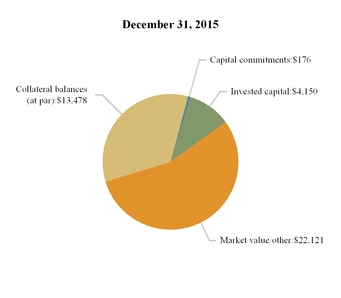
| FPAUM: $39,925 |
The components of our AUM, including the portion that is FPAUM, for the Credit Group are presented below as of December 31, 2017, 2016 and 2015 (in millions):

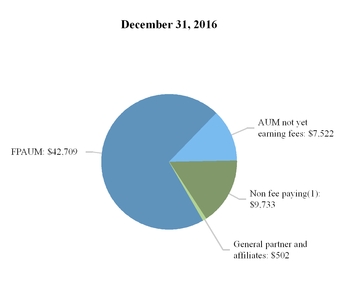
| AUM: $71,732 | AUM: $60,466 |
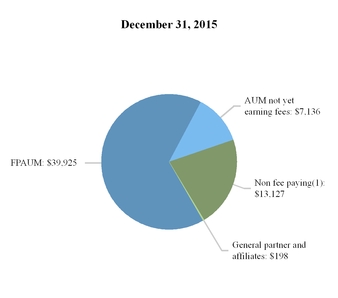
| AUM: $60,386 |
(1) Includes $5.7 billion, $6.4 billion and $9.9 billion of AUM of funds from which we indirectly earn management fees as of December 31, 2017, 2016 and 2015, respectively.
Credit Group—Fund Performance Metrics as of December 31, 2017
The Credit Group managed 139 funds as of December 31, 2017. ARCC contributed approximately 58% of the Credit Group’s total management fees for the year ended December 31, 2017. In addition to ARCC, we have six significant funds which contributed approximately 9% of the Credit Group’s management fees for the year ended December 31, 2017. Our significant funds that are not drawdown funds are ARCC; one sub-advised fund; Ares ELIS XI, Ltd. ("ELIS XI"), a 2013 vintage separately managed account focused on syndicated loans in the United States; and two separately managed accounts over which we exercise sole investment discretion. Our significant drawdown funds are Ares Capital Europe II, L.P. (“ACE II”), a 2013 vintage commingled fund; and ACE III, a 2015 vintage commingled fund, both of which focus on direct lending to European middle market companies. We do not present fund performance metrics for significant funds with less than two years of historical information, except for those significant funds which pay management fees on invested capital, in which case performance is shown at the earlier of (i) the one year anniversary of the fund's first investment and (ii) such time the fund is 50% or more invested.
The following table presents the performance data for our significant funds in the Credit Group that are not drawdown funds:
| As of December 31, 2017 | |||||||||||||||||||
| Returns(%)(1) | |||||||||||||||||||
| Year of | AUM | Fourth Quarter | Year-To-Date | Since Inception(2) | |||||||||||||||
| Fund | Inception | (in millions) | Gross | Net | Gross | Net | Gross | Net | Investment Strategy | ||||||||||
| ARCC(3) | 2004 | $ | 14,520 | N/A | 3.3 | N/A | 10.8 | N/A | 11.8 | U.S. Direct Lending | |||||||||
| Sub-advised Client A(4) | 2007 | $ | 723 | 0.6 | 0.5 | 8.1 | 7.7 | 8.0 | 7.6 | High Yield | |||||||||
| ELIS XI(4) | 2013 | $ | 716 | 1.1 | 1.0 | 4.9 | 4.4 | 3.6 | 3.1 | Syndicated Loans | |||||||||
| Separately Managed Account Client A(4) | 2015 | $ | 1,155 | 2.4 | 2.3 | 11.2 | 10.7 | 7.1 | 6.6 | Structured Credit | |||||||||
| Separately Managed Account Client B(4) | 2016 | $ | 830 | 0.7 | 0.6 | 7.0 | 6.7 | 6.7 | 6.3 | High Yield |
| (1) | Returns are time-weighted rates of return and include the reinvestment of income and other earnings from securities or other investments and reflect the deduction of all trading expenses. |
| (2) | Since inception returns are annualized. |
| (3) | Net returns are calculated using the fund's NAV and assume dividends are reinvested at the closest quarter-end NAV to the relevant quarterly ex-dividend dates. Additional information related to ARCC can be found in its financial statements filed with the SEC, which are not part of this report. |
| (4) | Gross returns do not reflect the deduction of management fees or any other expenses. Net returns are calculated by subtracting the applicable management fee from the gross returns on a monthly basis. |
The following table presents the performance data of our significant drawdown funds:
| As of December 31, 2017 (Dollars in millions) | |||||||||||||||||||||||||||||||||||
| Year of Inception | AUM | Original Capital Commitments | Cumulative Invested Capital | Realized Proceeds(1) | Unrealized Value(2) | Total Value | MoIC | IRR(%) | |||||||||||||||||||||||||||
| Fund | Gross(3) | Net(4) | Gross(5) | Net(6) | Investment Strategy | ||||||||||||||||||||||||||||||
| ACE II(7) | 2013 | $ | 1,509 | $ | 1,216 | $ | 977 | $ | 458 | $ | 796 | $ | 1,254 | 1.4x | 1.3x | 10.2 | 7.5 | E.U. Direct Lending | |||||||||||||||||
| ACE III(8) | 2015 | $ | 5,184 | $ | 2,822 | $ | 1,951 | $ | 102 | $ | 2,099 | $ | 2,201 | 1.2x | 1.1x | 17.5 | 13.1 | E.U. Direct Lending |
| (1) | Realized proceeds represent the sum of all cash distributions to all partners and if applicable, exclude tax and incentive distributions made to the general partner. |
| (2) | Unrealized value represents the fund's NAV reduced by the accrued performance fees, if applicable. There can be no assurance that unrealized values will be realized at the valuations indicated. |
| (3) | The gross multiple of invested capital (“MoIC”) is calculated at the fund-level and is based on the interests of the fee-paying limited partners and if applicable, excludes interests attributable to the non-fee paying limited partners and/or the general partner which does not pay management fees or performance fees. The gross MoIC is before giving effect to management fees, performance fees as applicable and other expenses. |
| (4) | The net MoIC is calculated at the fund-level and is based on the interests of the fee-paying limited partners and if applicable, excludes those interests attributable to the non-fee paying limited partners and/or the general partner which does not pay management fees or performance fees. The net MoIC is after giving effect to management fees, performance fees as applicable and other expenses. |
| (5) | The gross IRR is an annualized since inception gross internal rate of return of cash flows to and from the fund and the fund’s residual value at the end of the measurement period. Gross IRR reflects returns to the fee-paying limited partners and if applicable, excludes interests attributable to the non-fee paying limited partners and/or the general partner which does not pay management fees or performance fees. |
The cash flow dates used in the gross IRR calculation are based on the actual dates of the cash flows. Gross IRRs are calculated before giving effect to management fees, performance fees as applicable, and other expenses.
| (6) | The net IRR is an annualized since inception net internal rate of return of cash flows to and from the fund and the fund’s residual value at the end of the measurement period. Net IRRs reflect returns to the fee-paying limited partners and if applicable, exclude interests attributable to the non-fee paying limited partners and/or the general partner who does not pay management fees or performance fees. The cash flow dates used in the net IRR calculations are based on the actual dates of the cash flows. The net IRRs are calculated after giving effect to management fees, performance fees as applicable, and other expenses. The funds may utilize a credit facility during the investment period and for general cash management purposes. Net fund-level IRRs would have been lower had such fund called capital from its limited partners instead of utilizing the credit facility. |
| (7) | ACE II is made up of two feeder funds, one denominated in U.S. dollars and one denominated in Euros. The gross and net IRR and gross and net MoIC presented in the chart are for the U.S. dollar denominated feeder fund as that is the larger of the two feeders. The gross and net IRR for the Euro denominated feeder fund are 12.5% and 9.4%, respectively. The gross and net MoIC for the Euro denominated feeder fund are 1.5x and 1.3x, respectively. Original capital commitments are converted to U.S. dollars at the prevailing exchange rate at the time of the fund's closing. All other values for ACE II are for the combined fund and are converted to U.S. dollars at the prevailing quarter-end exchange rate. The variance between the gross and net MoICs and the net IRRs for the U.S. dollar denominated and Euro denominated feeder funds is driven by the U.S. GAAP mark-to-market reporting of the foreign currency hedging program in the U.S. dollar denominated feeder fund. The feeder fund will be holding the foreign currency hedges until maturity, and therefore is expected to ultimately recognize a gain while mitigating the currency risk associated with the initial principal investments. |
| (8) | ACE III is made up of two feeder funds, one denominated in U.S. dollars and one denominated in Euros. The gross and net MoIC presented in the chart are for the Euro denominated feeder fund as that is the larger of the two feeders. The gross and net IRR for the U.S. dollar denominated feeder fund are 17.5% and 12.8%, respectively. The gross and net MoIC for the U.S. dollar denominated feeder fund are 1.2x and 1.1x, respectively. Original capital commitments are converted to U.S. dollars at the prevailing exchange rate at the time of the fund's closing. All other values for ACE III are for the combined fund and are converted to U.S. dollars at the prevailing quarter-end exchange rate. |
Private Equity Group
The following table sets forth certain statement of operations data and certain other data of our Private Equity Group segment for the periods presented.
| For the Years Ended December 31, | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||||||||||||||
| 2017 | 2016 | 2015 | Favorable (Unfavorable) | Favorable (Unfavorable) | |||||||||||||||||||||
| $ Change | % Change | $ Change | % Change | ||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||
| Management fees | $ | 198,498 | $ | 147,790 | $ | 152,104 | $ | 50,708 | 34 | % | $ | (4,314 | ) | (3 | )% | ||||||||||
| Other fees | 1,495 | 1,544 | 1,406 | (49 | ) | (3 | )% | 138 | 10 | % | |||||||||||||||
| Compensation and benefits | (68,569 | ) | (61,276 | ) | (56,859 | ) | (7,293 | ) | (12 | )% | (4,417 | ) | (8 | )% | |||||||||||
| General, administrative and other expenses | (17,561 | ) | (14,679 | ) | (15,647 | ) | (2,882 | ) | (20 | )% | 968 | 6 | % | ||||||||||||
| Fee Related Earnings | 113,863 | 73,379 | 81,004 | 40,484 | 55 | % | (7,625 | ) | (9 | )% | |||||||||||||||
| Performance fees-realized | 287,092 | 230,162 | 24,849 | 56,930 | 25 | % | 205,313 | NM | |||||||||||||||||
| Performance fees-unrealized | 191,559 | 188,287 | 87,809 | 3,272 | 2 | % | 100,478 | 114 | % | ||||||||||||||||
| Performance fee compensation-realized | (228,774 | ) | (184,072 | ) | (19,255 | ) | (44,702 | ) | (24 | )% | (164,817 | ) | NM | ||||||||||||
| Performance fee compensation-unrealized | (153,148 | ) | (149,956 | ) | (74,598 | ) | (3,192 | ) | (2 | )% | (75,358 | ) | (101 | )% | |||||||||||
| Net performance fees | 96,729 | 84,421 | 18,805 | 12,308 | 15 | % | 65,616 | NM | |||||||||||||||||
| Investment income-realized | 22,625 | 18,773 | 6,840 | 3,852 | 21 | % | 11,933 | 174 | % | ||||||||||||||||
| Investment income (loss)-unrealized | 38,754 | (613 | ) | (13,205 | ) | 39,367 | NM | 12,592 | (95 | )% | |||||||||||||||
| Interest and other investment income | 3,906 | 16,579 | 6,166 | (12,673 | ) | (76 | )% | 10,413 | 169 | % | |||||||||||||||
| Interest expense | (5,218 | ) | (5,589 | ) | (5,936 | ) | 371 | 7 | % | 347 | 6 | % | |||||||||||||
| Net investment income (loss) | 60,067 | 29,150 | (6,135 | ) | 30,917 | 106 | % | 35,285 | NM | ||||||||||||||||
| Performance related earnings | 156,796 | 113,571 | 12,670 | 43,225 | 38 | % | 100,901 | NM | |||||||||||||||||
| Economic net income | $ | 270,659 | $ | 186,950 | $ | 93,674 | 83,709 | 45 | % | 93,276 | 100 | % | |||||||||||||
| Realized income | $ | 192,814 | $ | 149,544 | $ | 93,668 | 43,270 | 29 | % | 55,876 | 60 | % | |||||||||||||
| Distributable earnings | $ | 187,733 | $ | 144,140 | $ | 88,767 | 43,593 | 30 | % | 55,373 | 62 | % |
NM - Not meaningful
Accrued performance fees for the Private Equity Group are comprised of the following:
| As of December 31, | |||||||
| 2017 | 2016 | ||||||
| (Dollars in thousands) | |||||||
| ACOF III | $ | 570,578 | $ | 342,958 | |||
| ACOF IV | 217,354 | 234,207 | |||||
| EIF V | 16,215 | 16,510 | |||||
| Other funds | 11,260 | 30,174 | |||||
| Total Private Equity Group | $ | 815,407 | $ | 623,849 |
Net performance fee revenues for the Private Equity Group are comprised of the following:
| Year Ended December 31, 2017 | Year Ended December 31, 2016 | Year Ended December 31, 2015 | |||||||||||||||||||||||||||||||||
| Realized | Unrealized | Net | Realized | Unrealized | Net | Realized | Unrealized | Net | |||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| ACOF III | $ | 58,946 | $ | 227,620 | $ | 286,566 | $ | 161,216 | $ | 4,574 | $ | 165,790 | $ | 4,925 | $ | 90,420 | $ | 95,345 | |||||||||||||||||
| ACOF IV | 223,479 | (16,852 | ) | 206,627 | 41,807 | 181,571 | 223,378 | 10,545 | 9,512 | 20,057 | |||||||||||||||||||||||||
| EIF V | — | (294 | ) | (294 | ) | — | 16,510 | 16,510 | — | — | — | ||||||||||||||||||||||||
| Other funds | 4,667 | (18,915 | ) | (14,248 | ) | 27,139 | (14,368 | ) | 12,771 | 9,379 | (12,123 | ) | (2,744 | ) | |||||||||||||||||||||
| Total Private Equity Group | $ | 287,092 | $ | 191,559 | $ | 478,651 | $ | 230,162 | $ | 188,287 | $ | 418,449 | $ | 24,849 | $ | 87,809 | $ | 112,658 |
The following tables present the components of the change in performance fees - unrealized for the Private Equity Group:
| Year Ended December 31, 2017 | Year Ended December 31, 2016 | ||||||||||||||||||||||||||||||
| Performance Fees - Realized | Increases | Decreases | Performance Fees - Unrealized | Performance Fees - Realized | Increases | Decreases | Performance Fees - Unrealized | ||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||
| ACOF III | $ | (58,946 | ) | $ | 286,566 | $ | — | $ | 227,620 | $ | (161,216 | ) | $ | 165,790 | $ | — | $ | 4,574 | |||||||||||||
| ACOF IV | (223,479 | ) | 206,627 | — | (16,852 | ) | (41,807 | ) | 223,378 | — | 181,571 | ||||||||||||||||||||
| EIF V | — | — | (294 | ) | (294 | ) | — | 16,510 | — | 16,510 | |||||||||||||||||||||
| Other funds | (4,667 | ) | 1,016 | (15,264 | ) | (18,915 | ) | (27,139 | ) | 15,697 | (2,926 | ) | (14,368 | ) | |||||||||||||||||
| Total Private Equity Group | $ | (287,092 | ) | $ | 494,209 | $ | (15,558 | ) | $ | 191,559 | $ | (230,162 | ) | $ | 421,375 | $ | (2,926 | ) | $ | 188,287 |
| Year Ended December 31, 2015 | |||||||||||||||
| Performance Fees - Realized | Increases | Decreases | Performance Fees - Unrealized | ||||||||||||
| (Dollars in thousands) | |||||||||||||||
| ACOF III | $ | (4,925 | ) | $ | 95,345 | $ | — | $ | 90,420 | ||||||
| ACOF IV | (10,545 | ) | 20,057 | — | 9,512 | ||||||||||
| Other funds | (9,379 | ) | 10,260 | (13,004 | ) | (12,123 | ) | ||||||||
| Total Private Equity Group | $ | (24,849 | ) | $ | 125,662 | $ | (13,004 | ) | $ | 87,809 |
Private Equity Group—Year Ended December 31, 2017 Compared to Year Ended December 31, 2016
Fee Related Earnings:
Fee related earnings increased $40.5 million, or 55%, to $113.9 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. Fee related earnings were impacted by fluctuations of the following components:
Management Fees. Total management fees increased by $50.7 million, or 34%, to $198.5 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase was primarily attributable to ACOF V, which began generating fees in March 2017 totaling $90.8 million for the year ended December 31, 2017. In addition, Ares Energy Investors Fund V, L.P. ("EIF V") held its final close in the second quarter of 2017, generating additional management fees of $8.9 million for the year ended December 31, 2017. Management fees generated by EIF V for the year ended December 31, 2017 included $5.8 million of one-time catch-up fees. Partially offsetting these increases were management fees generated by Ares Corporate Opportunities Fund IV, L.P. (“ACOF IV”), which decreased by $37.1 million due to a reduced fee rate and change in fee basis in connection with the launch of ACOF V. Additionally, management fees attributable to certain U.S. power and energy infrastructure funds decreased $9.4 million as a result of portfolio realizations, which reduced the fee bases of the funds.
The effective management fee rate decreased from 1.26% for the year ended December 31, 2016 to 1.20% for the year ended December 31, 2017, excluding the effect of one-time catch-up fees. The decreases in the effective management fee rate resulted from the reduced fee rate at ACOF IV and were partially offset by ACOF V management fees.
Compensation and Benefits. Compensation and benefits expenses increased by $7.3 million, or 12%, to $68.6 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase was primarily due to increases in salary and benefits expenses as a result of additional headcount needed to support ACOF V's capital deployment, as well as merit based increases. Compensation and benefits expenses represented 34.5% of management fees for the year ended December 31, 2017 compared to 41.5% for the year ended December 31, 2016.
General, Administrative and Other Expenses. General, administrative and other expenses increased by $2.9 million, or 20%, to $17.6 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase in the current year was primarily attributable to an increase in recruiting fees of $1.7 million and other business support costs driven by increased headcount.
Performance Related Earnings:
Performance related earnings increased $43.2 million to $156.8 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. Performance related earnings were impacted by fluctuations of the following components:
Net Performance Fees. Net performance fees include realized and unrealized performance fees, net of realized and unrealized performance fee compensation. The impact of reversals of previously recognized performance fee revenue and the corresponding performance fee compensation expense is reflected as a reduction in unrealized performance fees and unrealized performance fee compensation.
Net performance fees increased by $12.3 million to $96.7 million for the year ended December 31, 2017 compared to $84.4 million for the year ended December 31, 2016. The increase in net performance fees was primarily driven by significant market appreciation in one of ACOF III's retail portfolio companies following its initial public offering.
Net Investment Income (Loss). Net investment income increased by $30.9 million to $60.1 million for the year ended December 31, 2017. The increase was primarily attributable to ACOF III, which had an increase of $32.2 million in net realized and unrealized gains for the year ended December 31, 2017 primarily due to market appreciation in one of its retail portfolio companies that completed its initial public offering in the current year.
Realized Income:
Realized income increased $43.3 million, or 29%, to $192.8 million for the year ended December 31, 2017 compared to the year ended December 31, 2016, primarily driven by increases in net realized performance fees of $12.2 million and FRE of $40.5 million. The increases were partially offset by a $9.4 million decrease in net realized investment and other income.
Economic Net Income:
Economic net income is comprised of fee related earnings and performance related earnings. Economic net income increased $83.7 million, or 45%, to $270.7 million for the year ended December 31, 2017 compared to the year ended December 31, 2016 as a result of the fluctuations described above.
Distributable Earnings:
DE increased $43.6 million, or 30%, to $187.7 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. DE was positively impacted by increases in net realized performance fees of $12.2 million and FRE of $40.5 million. The increases were partially offset by a $9.4 million decrease in net realized investment and other income.
Private Equity Group—Year Ended December 31, 2016 Compared to Year Ended December 31, 2015
Fee Related Earnings:
Fee related earnings decreased $7.6 million, or 9%, to $73.4 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. Fee related earnings were impacted by fluctuations of the following components:
Management Fees. Total management fees decreased by $4.3 million, or 3%, to $147.8 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The decrease was primarily attributable to the absence of management fees from Ares Corporate Opportunities Fund II, L.P. (“ACOF II”) in the current year, from which we generated $3.8 million of fees in the year ended December 31, 2015. In connection with an extension of ACOF II’s term for one year, we agreed to waive management fees starting in the first quarter of 2016. The effective management fee rate decreased by 0.01% from 1.27% for the year ended December 31, 2015, to 1.26% for the year ended December 31, 2016.
Compensation and Benefits. Compensation and benefits expenses increased by $4.4 million, or 8%, to $61.3 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase is primarily due to an increase in salary and benefits expenses, which were higher due to merit based increases and an increase in headcount in anticipation of ACOF V capital deployment. Additionally, incentive based compensation increased in the current year. Compensation and benefits expenses represented 41.5% of management fees for the year ended December 31, 2016 compared to 37.4% for the year ended December 31, 2015.
General, Administrative and Other Expenses. General, administrative and other expenses decreased by $1.0 million, or 6%, to $14.7 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The decrease was due to the timing of various services delivered over both years. We expect general, administrative and other expenses to increase in 2017 as capital is deployed in ACOF V.
Performance Related Earnings:
Performance related earnings increased $100.9 million to $113.6 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. Performance related earnings were impacted by fluctuations of the following components:
Net Performance Fees. Net performance fees include realized and unrealized performance fees, net of realized and unrealized performance fee compensation. The impact of reversals of previously recognized performance fee revenue and the corresponding performance fee compensation expense is reflected as a reduction in unrealized performance fees and unrealized performance fee compensation.
Net performance fees increased by $65.6 million to $84.4 million for the year ended December 31, 2016 compared to $18.8 million for the year ended December 31, 2015. The increase in net performance fees for the year ended December 31, 2016 was primarily driven by increases in the valuation of certain underlying portfolio companies within certain of our Private Equity Group’s funds.
Net Investment Income (Loss). Net investment income (loss) increased by $35.3 million from a net investment loss of $6.1 million for the year ended December 31, 2015 to net investment income of $29.2 million for the year ended December 31, 2016. Net investment income of $29.2 million for the year ended December 31, 2016 was primarily comprised of $15.6 million and $12.6 million of dividends and net realized gains from sales of ACOF III portfolio companies, respectively. In comparison, there was a $6.1 million net investment loss for the year ended December 31, 2015, primarily as a result of net realized and unrealized losses of $17.9 million and $9.8 million on certain investments in the special situations funds and an Asian corporate
private equity fund, respectively. These losses were offset by unrealized gains of $21.2 million on certain investments in North America and Europe driven by unrealized appreciation of the fair values of certain underlying investments.
Realized Income:
Realized income increased $55.9 million, or 60%, to $149.5 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase was due to increases in net realized performance fees and net realized investment and other income of $40.5 million and $23.0 million, respectively, partially offset by a $7.6 million decrease in FRE.
Economic Net Income:
Economic net income is comprised of fee related earnings and performance related earnings. Economic net income increased $93.3 million, or 100%, to $187.0 million for the year ended December 31, 2016 compared to the year ended December 31, 2015 as a result of the fluctuations described above.
Distributable Earnings:
DE increased $55.4 million, or 62%, to $144.1 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. DE was positively impacted by increases in net realized performance fees and net realized investment and other income of $40.5 million and $23.0 million, respectively. The increases were partially offset by a $7.6 million decrease in FRE.
Private Equity Group—Assets Under Management
The tables below provide the period‑to‑period rollforwards of AUM for the Private Equity Group for the years ended December 31, 2017, 2016 and 2015 (in millions):
| Corporate Private Equity | Private Equity - EIF | Special Situations | Total Private Equity Group | ||||||||||||
| Balance at 12/31/2016 | $ | 18,162 | $ | 5,143 | $ | 1,736 | $ | 25,041 | |||||||
| Net new equity commitments | 56 | 300 | — | 356 | |||||||||||
| Distributions | (2,130 | ) | (697 | ) | (187 | ) | (3,014 | ) | |||||||
| Change in fund value | 2,469 | (323 | ) | 1 | 2,147 | ||||||||||
| Balance at 12/31/2017 | $ | 18,557 | $ | 4,423 | $ | 1,550 | $ | 24,530 | |||||||
| Average AUM(3) | $ | 18,591 | $ | 4,697 | $ | 1,626 | $ | 24,914 |
| Corporate Private Equity(1) | Private Equity - EIF | Special Situations | Total Private Equity Group | ||||||||||||
| Balance at 12/31/2015 | $ | 15,908 | $ | 5,207 | $ | 1,863 | $ | 22,978 | |||||||
| Net new equity commitments | 2,184 | 130 | — | 2,314 | |||||||||||
| Distributions | (1,886 | ) | (372 | ) | (261 | ) | (2,519 | ) | |||||||
| Change in fund value | 1,956 | 178 | 134 | 2,268 | |||||||||||
| Balance at 12/31/2016 | $ | 18,162 | $ | 5,143 | $ | 1,736 | $ | 25,041 | |||||||
| Average AUM(3) | $ | 17,651 | $ | 5,102 | $ | 1,800 | $ | 24,553 |
| Corporate Private Equity(2) | Private Equity - EIF | Special Situations | Total Private Equity Group | ||||||||||||
| Balance at 12/31/2014 | $ | 10,135 | $ | — | $ | 1,952 | $ | 12,087 | |||||||
| Acquisitions | — | 4,581 | — | 4,581 | |||||||||||
| Net new equity commitments | 5,696 | 594 | 410 | 6,700 | |||||||||||
| Distributions | (728 | ) | (292 | ) | (61 | ) | (1,081 | ) | |||||||
| Change in fund value | 805 | 324 | (438 | ) | 691 | ||||||||||
| Balance at 12/31/2015 | $ | 15,908 | $ | 5,207 | $ | 1,863 | $ | 22,978 | |||||||
| Average AUM(3) | $ | 11,366 | $ | 3,717 | $ | 2,032 | $ | 17,115 |
| (1) | Net new equity commitments in 2016 includes $2.1 billion of commitments to ACOF V. |
| (2) | Net new equity commitments in 2015 represents commitments to ACOF V. |
| (3) | Represents a five-point average of quarter-end balances for each period. |
Private Equity Group—Fee Paying AUM
The tables below provide the period‑to‑period rollforwards of fee paying AUM, for the Private Equity Group for the years ended December 31, 2017, 2016 and 2015 (in millions):
| Corporate Private Equity | Private Equity - EIF | Special Situations | Total Private Equity Group | ||||||||||||
| FPAUM Balance at 12/31/2016 | $ | 6,454 | $ | 4,232 | $ | 628 | $ | 11,314 | |||||||
| Commitments | 7,655 | 300 | — | 7,955 | |||||||||||
| Subscriptions/deployment/increase in leverage | 478 | 230 | 414 | 1,122 | |||||||||||
| Redemptions/distributions/decrease in leverage | (966 | ) | (392 | ) | (248 | ) | (1,606 | ) | |||||||
| Change in fund value | 4 | (351 | ) | (28 | ) | (375 | ) | ||||||||
| Change in fee basis | (1,552 | ) | — | — | (1,552 | ) | |||||||||
| FPAUM Balance at 12/31/2017 | $ | 12,073 | $ | 4,019 | $ | 766 | $ | 16,858 | |||||||
| Average FPAUM(1) | $ | 11,157 | $ | 4,047 | $ | 682 | $ | 15,886 |
| Corporate Private Equity | Private Equity - EIF | Special Situations | Total Private Equity Group | ||||||||||||
| FPAUM Balance at 12/31/2015 | $ | 6,957 | $ | 4,454 | $ | 1,051 | $ | 12,462 | |||||||
| Commitments | 29 | 130 | — | 159 | |||||||||||
| Subscriptions/deployment/increase in leverage | 52 | 45 | (4 | ) | 93 | ||||||||||
| Redemptions/distributions/decrease in leverage | (288 | ) | (46 | ) | (331 | ) | (665 | ) | |||||||
| Change in fund value | — | (80 | ) | (88 | ) | (168 | ) | ||||||||
| Change in fee basis | (296 | ) | (271 | ) | — | (567 | ) | ||||||||
| FPAUM Balance at 12/31/2016 | $ | 6,454 | $ | 4,232 | $ | 628 | $ | 11,314 | |||||||
| Average FPAUM(1) | $ | 6,652 | $ | 4,306 | $ | 842 | $ | 11,800 |
| Corporate Private Equity | Private Equity - EIF | Special Situations | Total Private Equity Group | ||||||||||||
| FPAUM Balance at 12/31/2014 | $ | 7,172 | $ | — | $ | 530 | $ | 7,702 | |||||||
| Acquisitions | — | 4,046 | — | 4,046 | |||||||||||
| Commitments | — | 523 | — | 523 | |||||||||||
| Subscriptions/deployment/increase in leverage | 39 | 134 | 518 | 691 | |||||||||||
| Redemptions/distributions/decrease in leverage | (149 | ) | (247 | ) | (18 | ) | (414 | ) | |||||||
| Change in fund value | — | (2 | ) | (29 | ) | (31 | ) | ||||||||
| Change in fee basis | (105 | ) | — | 50 | (55 | ) | |||||||||
| FPAUM Balance at 12/31/2015 | $ | 6,957 | $ | 4,454 | $ | 1,051 | $ | 12,462 | |||||||
| Average FPAUM(1) | $ | 7,031 | $ | 3,265 | $ | 859 | $ | 11,155 |
(1) Represents a five-point average of quarter-end balances for each period.
The charts below present FPAUM for the Private Equity Group by its fee basis as of December 31, 2017, 2016 and 2015 (in millions):
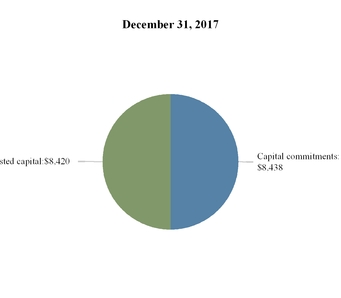
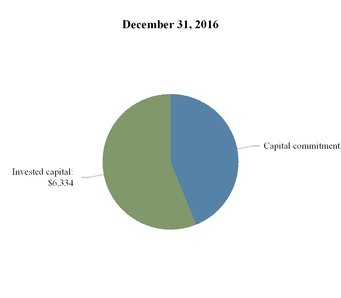
| FPAUM: $16,858 | FPAUM: $11,314 |
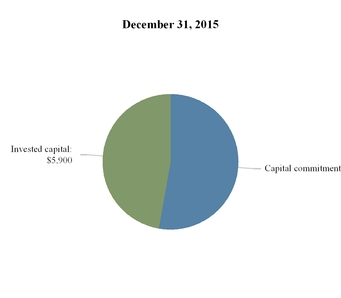
| FPAUM: $12,462 |
The components of our AUM, including the portion that is FPAUM, for the Private Equity Group are presented below as of December 31, 2017, 2016 and 2015 (in millions):
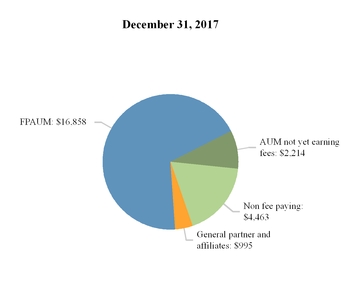
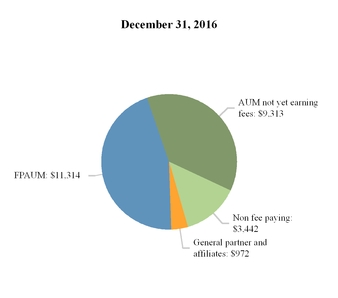
| AUM: $24,530 | AUM: $25,041 |
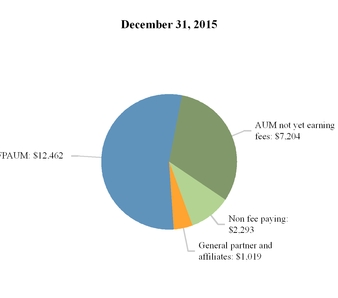
| AUM: $22,978 |
Private Equity Group—Fund Performance Metrics as of December 31, 2017
The Private Equity Group managed 21 commingled funds and related co-investment vehicles as of December 31, 2017. Our significant funds combined for approximately 93% of the Private Equity Group’s management fees for the year ended December 31, 2017. Our Corporate Private Equity funds focus on majority or shared-control investments, principally in under-capitalized companies in North America, Europe and Asia. ACOF III and ACOF IV are in harvest mode, meaning they are generally not seeking to deploy capital into new investment opportunities, while ACOF V is in deployment mode. Each of our U.S. power and energy infrastructure funds focuses on generating long-term, stable cash-flowing investments in the power generation, transmission and midstream energy sector. USPF III and USPF IV are in harvest mode, while EIF V is in deployment mode. We do not present fund performance metrics for significant funds with less than two years of historical information, except for those significant funds which pay management fees on invested capital, in which case performance is shown at the earlier of (i) the one year anniversary of the fund's first investment and (ii) such time the fund is 50% or more invested.
The following table presents the performance data for our significant funds in the Private Equity Group, all of which are drawdown funds:
| As of December 31, 2017 (Dollars in millions) | |||||||||||||||||||||||||||||||||||
| Year of Inception | AUM | Original Capital Commitments | Cumulative Invested Capital | Realized Proceeds(1) | Unrealized Value(2) | Total Value | MoIC | IRR(%) | |||||||||||||||||||||||||||
| Fund | Gross(3) | Net(4) | Gross(5) | Net(6) | Investment Strategy | ||||||||||||||||||||||||||||||
| USPF III | 2007 | $ | 824 | $ | 1,350 | $ | 1,808 | $ | 1,764 | $ | 814 | $ | 2,578 | 1.4x | 1.4x | 7.8 | 5.1 | U.S. Power and Energy Infrastructure | |||||||||||||||||
| ACOF III | 2008 | $ | 4,548 | $ | 3,510 | $ | 3,867 | $ | 6,181 | $ | 4,220 | $ | 10,401 | 2.7x | 2.3x | 31.3 | 23.4 | Corporate Private Equity | |||||||||||||||||
| USPF IV | 2010 | $ | 1,827 | $ | 1,688 | $ | 1,846 | $ | 809 | $ | 1,639 | $ | 2,448 | 1.3x | 1.2x | 10.1 | 6.5 | U.S. Power and Energy Infrastructure | |||||||||||||||||
| ACOF IV | 2012 | $ | 5,479 | $ | 4,700 | $ | 3,836 | $ | 2,492 | $ | 4,313 | $ | 6,805 | 1.8x | 1.5x | 23.6 | 16.1 | Corporate Private Equity | |||||||||||||||||
| EIF V (7) | 2015 | $ | 882 | $ | 801 | $ | 313 | $ | 77 | $ | 371 | $ | 448 | 1.4x | 1.6x | NA | NA | U.S. Power and Energy Infrastructure | |||||||||||||||||
| ACOF V | 2017 | $ | 7,798 | $ | 7,850 | $ | 1,415 | $ | 14 | $ | 1,483 | $ | 1,497 | 1.1x | 1.0x | NA | NA | Corporate Private Equity |
| (1) | Realized proceeds represent the sum of all cash dividends, interest income, other fees and cash proceeds from realizations of interests in portfolio investments. |
| (2) | Unrealized value represents the fair market value of remaining investments. There can be no assurance that unrealized investments will be realized at the valuations indicated. |
| (3) | The gross MoIC is calculated at the investment-level and is based on the interests of all partners. The gross MoIC is before giving effect to management fees, performance fees as applicable and other expenses. |
| (4) | The net MoIC for the U.S. power and energy infrastructure funds is calculated at the fund-level. The net MoIC for the corporate private equity funds is calculated at the investment-level. For all funds, the net MoIC is based on the interests of the fee-paying limited partners and if applicable, excludes those interests attributable to the non-fee paying limited partners and/or the general partner who does not pay management fees or performance fees. The net MoIC is after giving effect to management fees, performance fees as applicable and other expenses. |
| (5) | The gross IRR is an annualized since inception gross internal rate of return of cash flows to and from investments and the residual value of the investments at the end of the measurement period. Gross IRRs reflect returns to all partners. Cash flows used in the gross IRR calculation are assumed to occur at month-end. The gross IRRs are calculated before giving effect to management fees, performance fees as applicable, and other expenses. |
| (6) | The net IRR for the U.S. power and energy infrastructure funds is an annualized since inception net internal rate of return of cash flows to and from the fund and the fund’s residual value at the end of the measurement period. The cash flow dates used in the net IRR calculations are based on the actual dates of the cash flows. The net IRR for the corporate private equity funds is an annualized since inception net internal rate of return of cash flows to and from investments and the residual value of the investments at the end of the measurement period. The funds may utilize a credit facility during the investment period and for general cash management purposes. Net fund-level IRRs would have been lower had such fund called capital from its limited partners instead of utilizing the credit facility. Cash flows used in the net IRR calculations are assumed to occur at month end. For all funds, the net IRRs are calculated after giving effect to management fees, performance fees as applicable, and other expenses and exclude commitments by the general partner and Schedule I investors who do not pay either management fees or carried interest. Including the timing on contribution and distributions to and from the corporate private equity funds, net investor IRRs since inception for ACOF III is 22.7% and for ACOF IV is 15.2%. |
| (7) | The Gross MoIC is lower than the Net MoIC due to the fund's utilization of a credit facility to fund an investment that is currently under construction and not generating cash flow. |
Real Estate Group
The following table sets forth certain statement of operations data and certain other data of our Real Estate Group segment for the periods presented.
| For the Years Ended December 31, | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||||||||||||||
| 2017 | 2016 | 2015 | Favorable (Unfavorable) | Favorable (Unfavorable) | |||||||||||||||||||||
| $ Change | % Change | $ Change | % Change | ||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||
| Management fees | $ | 64,861 | $ | 66,997 | $ | 66,045 | $ | (2,136 | ) | (3 | )% | $ | 952 | 1 | % | ||||||||||
| Other fees | 106 | 854 | 2,779 | (748 | ) | (88 | )% | (1,925 | ) | (69 | )% | ||||||||||||||
| Compensation and benefits | (39,586 | ) | (41,091 | ) | (42,632 | ) | 1,505 | 4 | % | 1,541 | 4 | % | |||||||||||||
| General, administrative and other expenses | (10,519 | ) | (10,603 | ) | (15,766 | ) | 84 | 1 | % | 5,163 | 33 | % | |||||||||||||
| Fee Related Earnings | 14,862 | 16,157 | 10,426 | (1,295 | ) | (8 | )% | 5,731 | 55 | % | |||||||||||||||
| Performance fees-realized | 9,608 | 11,401 | 9,516 | (1,793 | ) | (16 | )% | 1,885 | 20 | % | |||||||||||||||
| Performance fees-unrealized | 80,160 | 17,334 | 15,179 | 62,826 | NM | 2,155 | 14 | % | |||||||||||||||||
| Performance fee compensation-realized | (4,338 | ) | (2,420 | ) | (1,826 | ) | (1,918 | ) | (79 | )% | (594 | ) | (33 | )% | |||||||||||
| Performance fee compensation-unrealized | (48,960 | ) | (13,517 | ) | (8,553 | ) | (35,443 | ) | (262 | )% | (4,964 | ) | (58 | )% | |||||||||||
| Net performance fees | 36,470 | 12,798 | 14,316 | 23,672 | 185 | % | (1,518 | ) | (11 | )% | |||||||||||||||
| Investment income-realized | 5,534 | 931 | 2,658 | 4,603 | NM | (1,727 | ) | (65 | )% | ||||||||||||||||
| Investment income-unrealized | 2,626 | 5,418 | 1,522 | (2,792 | ) | (52 | )% | 3,896 | 256 | % | |||||||||||||||
| Interest and other investment income | 2,495 | 1,661 | 259 | 834 | 50 | % | 1,402 | NM | |||||||||||||||||
| Interest expense | (1,650 | ) | (1,056 | ) | (977 | ) | (594 | ) | (56 | )% | (79 | ) | (8 | )% | |||||||||||
| Net investment income | 9,005 | 6,954 | 3,462 | 2,051 | 29 | % | 3,492 | 101 | % | ||||||||||||||||
| Performance related earnings | 45,475 | 19,752 | 17,778 | 25,723 | 130 | % | 1,974 | 11 | % | ||||||||||||||||
| Economic net income | $ | 60,337 | $ | 35,909 | $ | 28,204 | 24,428 | 68 | % | 7,705 | 27 | % | |||||||||||||
| Realized income | $ | 24,527 | $ | 26,611 | $ | 20,056 | (2,084,000 | ) | (8 | )% | 6,555,000 | 33 | % | ||||||||||||
| Distributable earnings | $ | 19,189 | $ | 21,594 | $ | 14,831 | (2,405 | ) | (11 | )% | 6,763 | 46 | % |
NM - Not Meaningful
Accrued performance fees for the Real Estate Group are comprised of the following:
| As of December 31, | |||||||
| 2017 | 2016 | ||||||
| (Dollars in thousands) | |||||||
| US VIII | 32,940 | 12,575 | |||||
| EF IV | 50,801 | 4,052 | |||||
| Other real estate funds | 37,528 | 22,001 | |||||
| Subtotal | 121,269 | 38,628 | |||||
| Other fee generating funds(1) | 15,362 | 16,675 | |||||
| Total Real Estate Group | $ | 136,631 | $ | 55,303 |
| (1) | Relates to investment income from AREA Sponsor Holdings LLC that is reclassified for segment reporting to align with the character of the underlying income generated. |
Net performance fee revenues for the Real Estate Group are comprised of the following:
| Year Ended December 31, 2017 | Year Ended December 31, 2016 | Year Ended December 31, 2015 | |||||||||||||||||||||||||||||||||
| Realized | Unrealized | Net | Realized | Unrealized | Net | Realized | Unrealized | Net | |||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| US VIII | — | 20,366 | 20,366 | — | 9,482 | 9,482 | — | 2,393 | 2,393 | ||||||||||||||||||||||||||
| EF IV | — | 46,750 | 46,750 | — | 4,052 | 4,052 | — | — | — | ||||||||||||||||||||||||||
| Other real estate funds | 6,887 | 13,830 | 20,717 | 4,034 | 8,688 | 12,722 | 3,044 | 11,862 | 14,906 | ||||||||||||||||||||||||||
| Subtotal | 6,887 | 80,946 | 87,833 | 4,034 | 22,222 | 26,256 | 3,044 | 14,255 | 17,299 | ||||||||||||||||||||||||||
| Other fee generating funds(1) | 2,721 | (786 | ) | 1,935 | 7,367 | (4,888 | ) | 2,479 | 6,472 | 924 | 7,396 | ||||||||||||||||||||||||
| Total Real Estate Group | $ | 9,608 | $ | 80,160 | $ | 89,768 | $ | 11,401 | $ | 17,334 | $ | 28,735 | $ | 9,516 | $ | 15,179 | $ | 24,695 |
| (1) | Relates to investment income from AREA Sponsor Holdings LLC that is reclassified for segment reporting to align with the character of the underlying income generated. |
The following tables present the components of the change in performance fees - unrealized for the Real Estate Group:
| Year Ended December 31, 2017 | Year Ended December 31, 2016 | ||||||||||||||||||||||||||||||
| Performance Fees - Realized | Increases | Decreases | Performance Fees - Unrealized | Performance Fees - Realized | Increases | Decreases | Performance Fees - Unrealized | ||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||
| US VIII | — | 20,366 | — | 20,366 | — | 9,482 | — | 9,482 | |||||||||||||||||||||||
| EF IV | — | 46,750 | — | 46,750 | — | 4,052 | — | 4,052 | |||||||||||||||||||||||
| Other real estate funds | (6,887 | ) | 21,441 | (724 | ) | 13,830 | (4,034 | ) | 13,456 | (734 | ) | 8,688 | |||||||||||||||||||
| Subtotal | (6,887 | ) | 88,557 | (724 | ) | 80,946 | (4,034 | ) | 26,990 | (734 | ) | 22,222 | |||||||||||||||||||
| Other fee generating funds(1) | (2,721 | ) | 2,769 | (834 | ) | (786 | ) | (7,367 | ) | 4,093 | (1,614 | ) | (4,888 | ) | |||||||||||||||||
| Total Real Estate Group | $ | (9,608 | ) | $ | 91,326 | $ | (1,558 | ) | $ | 80,160 | $ | (11,401 | ) | $ | 31,083 | $ | (2,348 | ) | $ | 17,334 |
| Year Ended December 31, 2015 | |||||||||||||||
| Performance Fees - Realized | Increases | Decreases | Performance Fees - Unrealized | ||||||||||||
| (Dollars in thousands) | |||||||||||||||
| US VIII | — | 2,393 | — | 2,393 | |||||||||||
| EF IV | — | — | — | — | |||||||||||
| Other real estate funds | (3,044 | ) | 14,906 | — | 11,862 | ||||||||||
| Subtotal | (3,044 | ) | 17,299 | — | 14,255 | ||||||||||
| Other fee generating funds(1) | (6,472 | ) | 7,527 | (131 | ) | 924 | |||||||||
| Total Real Estate Group | $ | (9,516 | ) | $ | 24,826 | $ | (131 | ) | $ | 15,179 |
| (1) | Relates to investment income from AREA Sponsor Holdings LLC that is reclassified for segment reporting to align with the character of the underlying income generated. |
Real Estate Group—Year Ended December 31, 2017 Compared to Year Ended December 31, 2016
Fee Related Earnings:
Fee related earnings decreased $1.3 million, or 8%, to $14.9 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. Fee related earnings were impacted by fluctuations of the following components:
Management Fees. Total management fees decreased by $2.1 million, or 3%, to $64.9 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The decrease was primarily attributable to a 2% decline in average fee paying AUM for the year ended December 31, 2017 compared to the year ended December 31, 2016. Ares Real Estate Fund VIII ("US VIII") and Ares European Real Estate Fund IV ("EF IV") had decreases in management fees of $1.1 million and $1.3 million, respectively, for the year ended December 31, 2017 compared to the year ended December 31, 2016 due to a change in the fee basis in connection with the launch of a successor fund and the end of the investment period, respectively. The winding down of one of our U.S. Real Estate Equity funds resulted in a reduction in management fees of $2.1 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. Partially offsetting these decreases were $2.4 million of management fees contributed by one of our U.S. Real Estate Equity funds that began generating fees in the year ended December 31, 2017.
The effective management fee rate, excluding the effect of one-time catch-up fees, remained consistent at 0.98% for the years ended December 31, 2017 and 2016.
Compensation and Benefits. Compensation and benefits expenses decreased by $1.5 million, or 4%, to $39.6 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The decrease was due to a reorganization of the group's management team that occurred in the latter half of 2016. Compensation and benefits expenses represented 61.0% of management fees for the year ended December 31, 2017 compared to 61.3% for the year ended December 31, 2016.
Performance Related Earnings:
Performance related earnings increased by $25.7 million to $45.5 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. Performance related earnings were impacted by fluctuations of the following components:
Net Performance Fees. Net performance fees include realized and unrealized performance fees, net of realized and unrealized performance fee compensation. The impact of reversals of previously recognized performance fee revenue and the corresponding performance fee compensation expense is reflected as a reduction in unrealized performance fees and performance fee compensation.
Net performance fees increased by $23.7 million to $36.5 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase in net performance fees for the current year periods was primarily driven by favorable real estate market fundamentals in both the U.S. and Europe that have resulted in appreciation across the portfolio of properties in our funds, primarily driven by net performance fees attributable to EF IV and US VIII, which collectively increased $21.4 million for the year ended December 31, 2017 compared to the year ended December 31, 2016.
Net Investment Income. Net investment income increased by $2.1 million to $9.0 million for the year ended December 31, 2017 compared to $7.0 million for the year ended December 31, 2016. The increase was driven by our investments in both U.S. and E.U. equity funds, which collectively experienced an increase in net gains for the year ended December 31, 2017 compared to the year ended December 31, 2016.
Realized Income:
Realized income decreased $2.1 million, or 8%, to $24.5 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The decrease was due to decreases in FRE of $1.3 million and net realized performance fees of $3.7 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. These decreases were partially offset by an increase in net realized investment and other income of $2.9 million for the year ended December 31, 2017 compared to the year ended December 31, 2016.
Economic Net Income:
Economic net income is comprised of fee related earnings and performance related earnings. Economic net income increased $24.4 million, or 68%, to $60.3 million for the year ended December 31, 2017 compared to the year ended December 31, 2016 as a result of the fluctuations described above.
Distributable Earnings:
DE decreased $2.4 million, or 11%, to $19.2 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The decrease in DE was due to decreases in FRE of $1.3 million and net realized performance fees of $3.7 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The decrease in DE was partially offset by an increase in net realized investment and other income of $2.9 million for the year ended December 31, 2017 compared to the year ended December 31, 2016.
Real Estate Group—Year Ended December 31, 2016 Compared to Year Ended December 31, 2015
Fee Related Earnings:
Fee related earnings increased $5.7 million, or 55%, to $16.2 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. Fee related earnings were impacted by fluctuations of the following components:
Management Fees. Total management fees increased by $1.0 million, or 1%, to $67.0 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The increase is primarily attributable to the launch of Ares European Property Enhancement Program II, L.P. ("EPEP II"), which began generating fees in 2016. The effective management fee rate decreased from 1.02% for the year ended December 31, 2015, to 0.98% for the year ended December 31, 2016. For certain U.S. equity funds, we earn a portion of our management fees on the cost basis of the unrealized investments and a portion on the unfunded commitments to the funds. The decrease in the management fee rates is a result of additional capital raised for those funds that earn a portion of their fees on unfunded commitments, increasing our fee-earning base, however at a lower rate. We expect management fees and the effective rate to increase as capital is deployed.
Compensation and Benefits. Compensation and benefits expenses decreased by $1.5 million, or 4%, to $41.1 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The decrease was primarily a result of a reduction in headcount, including a reorganization of the group's management team. Compensation and benefits expenses represented 61.3% of management fees for the year ended December 31, 2016 compared to 64.5% for the year ended December 31, 2015.
General, Administrative and Other Expenses. General, administrative and other expenses decreased by $5.2 million, or 33%, to $10.6 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. Cost reduction measures resulted in lower travel related expenses, professional services expenses and occupancy expenses compared to the prior year.
Performance Related Earnings:
Performance related earnings increased by $2.0 million to $19.8 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. Performance related earnings were impacted by fluctuations of the following components:
Net Performance Fees. Net performance fees include realized and unrealized performance fees, net of realized and unrealized performance fee compensation. The impact of reversals of previously recognized performance fee revenue and the corresponding performance fee compensation expense is reflected as a reduction in unrealized performance fees and performance fee compensation.
Net performance fees decreased by $1.5 million, or 11%, to $12.8 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The decrease in net performance fees for the year ended December 31, 2016 was primarily driven by an increase in performance fee compensation expense as a percentage of performance fees. Other incentive fee generating funds, while generating positive returns, experienced diminishing returns in comparison to the prior year. The decrease was offset by funds generating performance fees for the first time, including Ares European Real Estate Fund IV (“EU IV”), which generated $1.6 million net performance fees in 2016.
Net Investment Income (Loss). Net investment income increased by $3.5 million to $7.0 million for the year ended December 31, 2016 compared to $3.5 million for the year ended December 31, 2015. The increase in net investment income was primarily due to increases in valuations of the underlying assets. Our investments in U.S. and E.U. equity funds experienced unrealized market appreciation of $4.6 million and $1.4 million, respectively, for the year ended December 31, 2016 compared to $1.4 million and $0.1 million, respectively, for the year ended December 31, 2015. Of the $4.6 million of unrealized gains in our investments in U.S. equity funds for the year ended December 31, 2016, $2.4 million is attributable to our investment in a U.S. real estate fund.
Realized Income:
Realized income increased $6.6 million, or 33%, to $26.6 million for the year ended December 31, 2016 compared to the year ended December 31, 2015, primarily due to an increase in FRE of $5.7 million and an increase of $1.3 million in net realized performance fees.
Economic Net Income:
Economic net income is comprised of fee related earnings and performance related earnings. Economic net income increased $7.7 million, or 27%, to $35.9 million for the year ended December 31, 2016 compared to the year ended December 31, 2015 as a result of the fluctuations described above.
Distributable Earnings:
DE increased $6.8 million, or 46%, to $21.6 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. DE was positively impacted by an increase in FRE of $5.7 million and an increase of $1.3 million in net realized performance fees.
Real Estate Group—Assets Under Management
The tables below provide the period‑to‑period rollforwards of AUM for the Real Estate Group for the years ended December 31, 2017, 2016 and 2015 (in millions):
| Real Estate Equity - U.S. | Real Estate Equity - E.U. | Real Estate Debt | Total Real Estate Group | ||||||||||||
| Balance at 12/31/2016 | $ | 4,106 | $ | 3,100 | $ | 2,546 | $ | 9,752 | |||||||
| Net new equity commitments | 800 | — | — | 800 | |||||||||||
| Net new debt commitments | — | — | 509 | 509 | |||||||||||
| Distributions | (659 | ) | (801 | ) | (139 | ) | (1,599 | ) | |||||||
| Change in fund value | 331 | 405 | 31 | 767 | |||||||||||
| Balance at 12/31/2017 | $ | 4,578 | $ | 2,704 | $ | 2,947 | $ | 10,229 | |||||||
| Average AUM | $ | 4,459 | $ | 2,956 | $ | 2,846 | $ | 10,261 |
| Real Estate Equity - U.S. | Real Estate Equity - E.U. | Real Estate Debt | Total Real Estate Group | ||||||||||||
| Balance at 12/31/2015 | $ | 4,617 | $ | 3,059 | $ | 2,592 | $ | 10,268 | |||||||
| Net new equity commitments | 355 | 470 | 15 | 840 | |||||||||||
| Net new debt commitments | — | — | 225 | 225 | |||||||||||
| Distributions | (1,125 | ) | (357 | ) | (331 | ) | (1,813 | ) | |||||||
| Change in fund value | 259 | (72 | ) | 45 | 232 | ||||||||||
| Balance at 12/31/2016 | $ | 4,106 | $ | 3,100 | $ | 2,546 | $ | 9,752 | |||||||
| Average AUM | $ | 4,444 | $ | 3,143 | $ | 2,557 | $ | 10,144 |
| Real Estate Equity - U.S. | Real Estate Equity - E.U. | Real Estate Debt | Total Real Estate Group | ||||||||||||
| Balance at 12/31/2014 | $ | 4,595 | $ | 2,961 | $ | 3,019 | $ | 10,575 | |||||||
| Net new equity commitments | 732 | 755 | (159 | ) | 1,328 | ||||||||||
| Net new debt commitments | — | — | 105 | 105 | |||||||||||
| Distributions | (1,037 | ) | (619 | ) | (416 | ) | (2,072 | ) | |||||||
| Change in fund value | 327 | (38 | ) | 43 | 332 | ||||||||||
| Balance at 12/31/2015 | $ | 4,617 | $ | 3,059 | $ | 2,592 | $ | 10,268 | |||||||
| Average AUM | $ | 4,505 | $ | 2,983 | $ | 2,694 | $ | 10,182 |
(1) Represents a five-point average of quarter-end balances for each period.
Real Estate Group—Fee Paying AUM
The tables below provide the period‑to‑period rollforwards of fee paying AUM, for the Real Estate Group for the years ended December 31, 2017, 2016 and 2015 (in millions):
| Real Estate Equity - U.S. | Real Estate Equity - E.U. | Real Estate Debt | Total Real Estate Group | ||||||||||||
| FPAUM Balance at 12/31/2016 | $ | 2,891 | $ | 2,531 | $ | 1,118 | $ | 6,540 | |||||||
| Commitments | 665 | — | — | 665 | |||||||||||
| Subscriptions/deployment/increase in leverage | 441 | 138 | 3 | 582 | |||||||||||
| Redemptions/distributions/decrease in leverage | (510 | ) | (236 | ) | (95 | ) | (841 | ) | |||||||
| Change in fund value | — | 146 | 37 | 183 | |||||||||||
| Change in fee basis | (425 | ) | (515 | ) | — | (940 | ) | ||||||||
| FPAUM Balance at 12/31/2017 | $ | 3,062 | $ | 2,064 | $ | 1,063 | $ | 6,189 | |||||||
| Average FPAUM(1) | $ | 3,017 | $ | 2,429 | $ | 1,101 | $ | 6,547 |
| Real Estate Equity - U.S. | Real Estate Equity - E.U. | Real Estate Debt | Total Real Estate Group | ||||||||||||
| FPAUM Balance at 12/31/2015 | $ | 3,205 | $ | 2,554 | $ | 998 | $ | 6,757 | |||||||
| Commitments | 97 | 365 | — | 462 | |||||||||||
| Subscriptions/deployment/increase in leverage | 397 | 63 | 170 | 630 | |||||||||||
| Redemptions/distributions/decrease in leverage | (842 | ) | (87 | ) | (90 | ) | (1,019 | ) | |||||||
| Change in fund value | 34 | (132 | ) | 40 | (58 | ) | |||||||||
| Change in fee basis | — | (232 | ) | — | (232 | ) | |||||||||
| FPAUM Balance at 12/31/2016 | $ | 2,891 | $ | 2,531 | $ | 1,118 | $ | 6,540 | |||||||
| Average FPAUM(1) | $ | 3,011 | $ | 2,581 | $ | 1,077 | $ | 6,669 |
| Real Estate Equity - U.S. | Real Estate Equity - E.U. | Real Estate Debt | Total Real Estate Group | ||||||||||||
| FPAUM Balance at 12/31/2014 | $ | 3,028 | $ | 2,697 | $ | 393 | $ | 6,118 | |||||||
| Commitments | 357 | 548 | 83 | 988 | |||||||||||
| Subscriptions/deployment/increase in leverage | 260 | 8 | 535 | 803 | |||||||||||
| Redemptions/distributions/decrease in leverage | (347 | ) | (385 | ) | (65 | ) | (797 | ) | |||||||
| Change in fund value | — | (99 | ) | 31 | (68 | ) | |||||||||
| Change in fee basis | (93 | ) | (215 | ) | 21 | (287 | ) | ||||||||
| FPAUM Balance at 12/31/2015 | $ | 3,205 | $ | 2,554 | $ | 998 | $ | 6,757 | |||||||
| Average FPAUM(1) | $ | 2,998 | $ | 2,517 | $ | 693 | $ | 6,208 |
(1) Represents a five-point average of quarter-end balances for each period.
The charts below present FPAUM for the Real Estate Group by its fee basis as of December 31, 2017, 2016 and 2015 (in millions):
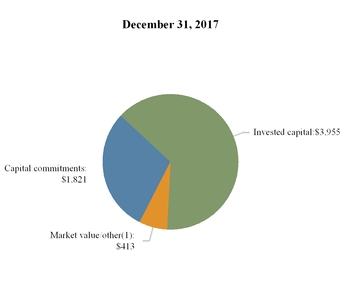
| FPAUM: $6,189 | FPAUM: $6,540 |
| FPAUM: $6,757 |
| (1) | Market value/other includes ACRE fee paying AUM, which is based on ACRE’s stockholders’ equity. |
The components of our AUM, including the portion that is FPAUM, for the Real Estate Group are presented below as of December 31, 2017, 2016 and 2015 (in millions):
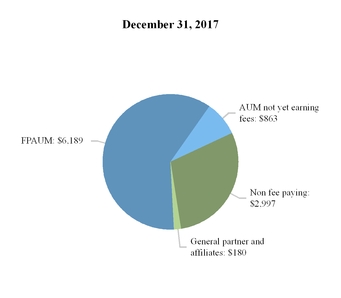
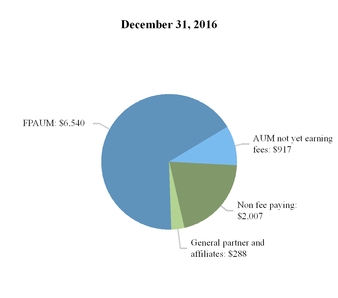
| AUM: $10,229 | AUM: $9,752 |
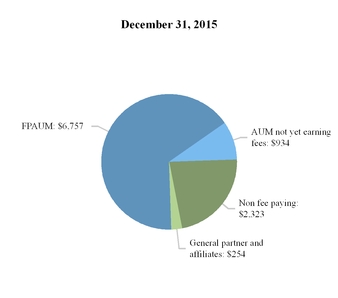
| AUM: $10,268 |
Real Estate Group—Fund Performance Metrics as of December 31, 2017
The Real Estate Group managed 42 funds as of December 31, 2017. Our two significant funds in the Real Estate Group combined for approximately 31% of the Real Estate Group’s management fees for the year ended December 31, 2017: EF IV, a commingled fund focused on real estate assets located in Europe, primarily in the United Kingdom, France and Germany; and EPEP II, a commingled fund focused on Europe. We do not present fund performance metrics for significant funds with less than two years of historical information, except for those significant funds which pay management fees on invested capital, in which case performance is shown at the earlier of (i) the one year anniversary of the fund's first investment and (ii) such time the fund is 50% or more invested.
The following table presents the performance data for our significant funds in the Real Estate Group, both of which are drawdown funds:
| As of December 31, 2017 (Dollars in millions) | |||||||||||||||||||||||||||||||||||
| Year of Inception | AUM | Original Capital Commitments | Cumulative Invested Capital | Realized Proceeds(1) | Unrealized Value(2) | Total Value | MoIC | IRR(%) | |||||||||||||||||||||||||||
| Fund | Gross(3) | Net(4) | Gross(5) | Net(6) | Investment Strategy | ||||||||||||||||||||||||||||||
| EF IV (7) | 2014 | $ | 1,022 | $ | 1,302 | $ | 1,057 | $ | 434 | $ | 1,008 | $ | 1,442 | 1.4x | 1.2x | 20.6 | 12.9 | E.U. Real Estate Equity | |||||||||||||||||
| EPEP II (8) | 2015 | $ | 698 | $ | 747 | $ | 298 | $ | 143 | $ | 226 | $ | 369 | 1.2x | 1.1x | NA | NA | E.U. Real Estate Equity |
| (1) | Realized proceeds include distributions of operating income, sales and financing proceeds received. |
| (2) | Unrealized value represents the fair market value of remaining investments. There can be no assurance that unrealized investments will be realized at the valuations indicated. |
| (3) | The gross MoIC is calculated at the investment level and is based on the interests of all partners. The gross MoIC for all funds is before giving effect to management fees, performance fees as applicable and other expenses. |
| (4) | The net MoIC is calculated at the fund-level and is based on the interests of the fee-paying partners and, if applicable, excludes interests attributable to the non fee-paying partners and/or the general partner who does not pay management fees or performance fees or has such fees rebated outside of the fund. The net MoIC is after giving effect to management fees, performance fees as applicable and other expenses. |
| (5) | The gross IRR is an annualized since inception gross internal rate of return of cash flows to and from investments and the residual value of the investments at the end of the measurement period. Gross IRRs reflect returns to all partners. Cash flows used in the gross IRR calculation are assumed to occur at quarter-end. The gross IRRs are calculated before giving effect to management fees, performance fees as applicable, and other expenses. |
| (6) | The net IRR is an annualized since inception net internal rate of return of cash flows to and from the fund and the fund’s residual value at the end of the measurement period. Net IRRs reflect returns to the fee-paying partners and, if applicable, excludes interests attributable to the non fee-paying partners and/or the general partner who does not pay management fees or performance fees or has such fees rebated outside of the fund. The cash flow dates used in the net IRR calculation are based on the actual dates of the cash flows. The net IRRs are calculated after giving effect to management fees, performance fees as applicable, and other expenses. The funds may utilize a credit facility during the investment period and for general cash management purposes. Net fund-level IRRs would have been lower had such fund called capital from its limited partners instead of utilizing the credit facility. |
| (7) | EF IV is made up of two parallel funds, one denominated in U.S. dollars and one denominated in Euros. The gross and net MoIC and gross and net IRRs presented in the chart are for the U.S. dollar denominated parallel fund as that is the larger of the two funds. The gross and net IRRs for the Euro denominated parallel fund are 20.8% and 14.2%, respectively. The gross and net MoIC for the Euro denominated parallel fund are 1.4x and 1.2x, respectively. Original capital commitments are converted to U.S. dollars at the prevailing exchange rate at the time of fund's closing. All other values for EF IV are for the combined fund and are converted to U.S. dollars at the prevailing quarter-end exchange rate. |
| (8) | EPEP II is made up of dual currency investors and Euro currency investors. The gross and net MoIC presented in the chart are for dual currency investors as dual currency investors represent the largest group of investors in the fund. Multiples exclude foreign currency gains and losses since dual currency investors fund capital contributions and receive distributions in local deal currency (GBP or EUR) and therefore, do not realize foreign currency gains or losses. The gross and net MoIC for the Euro currency investors, which include foreign currency gains and losses, are 1.2x and 1.1x, respectively. Original capital commitments are converted to U.S. dollars at the prevailing exchange rate at the time of fund's closing. All other values for EPEP II are for the combined fund and are converted to U.S. dollars at the prevailing quarter-end exchange rate. |
Operations Management Group
The following table sets forth certain statement of operations data and certain other data of the OMG on a segment basis for the periods presented.
| For the Years Ended December 31, | 2017 vs. 2016 | 2016 vs. 2015 | |||||||||||||||||||||||
| 2017 | 2016 | 2015 | Favorable (Unfavorable) | Favorable (Unfavorable) | |||||||||||||||||||||
| $ Change | % Change | $ Change | % Change | ||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||
| Compensation and benefits | $ | (113,558 | ) | $ | (99,447 | ) | $ | (86,869 | ) | $ | (14,111 | ) | (14 | )% | $ | (12,578 | ) | (14 | )% | ||||||
| General, administrative and other expenses | (75,143 | ) | (60,916 | ) | (56,168 | ) | (14,227 | ) | (23 | )% | (4,748 | ) | (8 | )% | |||||||||||
| Fee Related Earnings | (188,701 | ) | (160,363 | ) | (143,037 | ) | (28,338 | ) | (18 | )% | (17,326 | ) | (12 | )% | |||||||||||
| Investment income (loss)-realized | 3,880 | (14,606 | ) | (23 | ) | 18,486 | NM | (14,583 | ) | NM | |||||||||||||||
| Investment income (loss)-unrealized | 8,627 | (2,197 | ) | 52 | 10,824 | NM | (2,249 | ) | NM | ||||||||||||||||
| Interest and other investment income | 1,267 | 149 | 379 | 1,118 | NM | (230 | ) | (61 | )% | ||||||||||||||||
| Interest expense | (1,946 | ) | (2,727 | ) | (1,158 | ) | 781 | 29 | % | (1,569 | ) | (135 | )% | ||||||||||||
| Net investment income (loss) | 11,828 | (19,381 | ) | (750 | ) | 31,209 | NM | (18,631 | ) | NM | |||||||||||||||
| Performance related earnings | 11,828 | (19,381 | ) | (750 | ) | 31,209 | NM | (18,631 | ) | NM | |||||||||||||||
| Economic net income | $ | (176,873 | ) | $ | (179,744 | ) | $ | (143,787 | ) | 2,871 | 2 | % | (35,957 | ) | (25 | )% | |||||||||
| Realized income | $ | (185,625 | ) | $ | (177,533 | ) | $ | (143,839 | ) | (8,092 | ) | (5 | )% | (33,694 | ) | (23 | )% | ||||||||
| Distributable earnings | $ | (204,024 | ) | $ | (196,242 | ) | $ | (152,639 | ) | (7,782 | ) | (4 | )% | (43,603 | ) | (29 | )% |
NM - Not Meaningful
Operations Management Group—Year Ended December 31, 2017 Compared to Year Ended December 31, 2016
Fee Related Earnings:
Fee related earnings decreased $28.3 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. Fee related earnings were impacted by fluctuations of the following components:
Compensation and Benefits. Compensation and benefits expenses increased by $14.1 million, or 14%, to $113.6 million for the year ended December 31, 2017 compared to the year ended December 31, 2016, primarily due to additional headcount and merit based increases. Additional headcount was partially driven by employees hired to support several information technology initiatives and the expansion of our business development platform in order to more effectively raise additional investor commitments for our planned and newly launched funds. Employees hired in connection with ARCC's acquisition of ACAS also contributed to the growth in headcount, ACAS-related compensation expense, net of administrative fee reimbursements, for the year ended December 31, 2017 was $3.4 million.
General, Administrative and Other Expenses. General, administrative and other expenses increased by $14.2 million, or 23%, to $75.1 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The increase in the current year was due to several information technology initiatives to support system implementations, increased occupancy costs from growing headcount and business support costs associated with our expanding business platform during 2017. Also impacting the year ended December 31, 2017 was a $2.5 million one-time non-income tax paid during year ended December 31, 2017.
Performance Related Earnings:
Net Investment Income (Loss). Net investment income increased from a net investment loss of $19.4 million for the year ended December 31, 2016 to net investment income of $11.8 million for the year ended December 31, 2017. In 2016, we realized a $20.0 million loss on our minority interest equity method investment in Deimos Management Holdings LLC due to the winding down of its operations. In addition, our other fund investments in non-core investment strategies experienced an increase in net realized and unrealized gains of $9.8 million for the year ended December 31, 2017 compared to the year ended December 31, 2016.
Realized income:
Realized income decreased by $8.1 million, or 5%, to $185.6 million for the year ended December 31, 2017 compared to the year ended December 31, 2016. The decrease was primarily due to a decrease in FRE of $28.3 million, partially offset by an increase in net realized investment and other income of $20.2 million.
Economic Net Income:
Economic net income is comprised of fee related earnings and performance related earnings. Economic net income increased $2.9 million, or 2%, for the year ended December 31, 2017 compared to the year ended December 31, 2016 as a result of the fluctuations described above.
Distributable Earnings:
DE decreased $7.8 million, or 4%, for the year ended December 31, 2017 compared to the year ended December 31, 2016. DE decreased primarily due to a decrease in FRE of $28.3 million. The decrease was partially offset by an increase in net realized investment and other income of $20.2 million.
Operations Management Group—Year Ended December 31, 2016 Compared to Year Ended December 31, 2015
Fee Related Earnings:
Fee related earnings decreased $17.3 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. Fee related earnings were impacted by fluctuations of the following components:
Compensation and Benefits. Compensation and benefits expenses increased by $12.6 million, or 14%, to $99.4 million for the year ended December 31, 2016 compared to the year ended December 31, 2015, primarily due to increases in headcount as part of an effort to reduce our reliance on professional service providers by internalizing certain corporate support functions. In addition, incentive-based compensation increased for the year ended December 31, 2016 compared to the year ended December 31, 2015. Administrative fees, which are presented as a reduction to compensation and benefits expense, increased by $2.4 million for the year ended December 31, 2016, partially offsetting the increase in compensation and benefits expenses in the current year period.
General, Administrative and Other Expenses. General, administrative and other expenses increased by $4.7 million, or 8%, to $60.9 million for year ended December 31, 2016 compared to the year ended December 31, 2015. In 2016 we realigned certain general, administrative and other expenses with our operating activities, resulting in an increase in occupancy expenses recognized within OMG. Administrative fees, which are also presented as a reduction to general, administrative and other expenses, decreased by $1.9 million in for the year ended December 31, 2016, resulting in a net increase in general, administrative and other expenses compared to the prior year. Conversely, professional services expenses decreased due to cost containment initiatives during the current year.
Performance Related Earnings:
Performance related earnings decreased $18.6 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. Performance related earnings were impacted by the fluctuation in net investment loss:
Net Investment Loss. Net investment losses were $19.4 million and $0.8 million for the years ended December 31, 2016 and 2015, respectively. Prior to the fourth quarter of 2015, there was no investment activity within OMG. During the year ended December 31, 2016, we realized a $20.0 million loss on our minority interest, equity method investment in Deimos Management Holdings LLC due to the winding down of its operations. The realized loss was partially offset by net realized gains of $5.5 million from other fund investments in non-core investment strategies. Additionally, interest expense of $2.7 million was allocated to OMG, contributing to the net investment loss for the year ended December 31, 2016.
Realized income:
Realized income decreased by $33.7 million, or 23%, to $177.5 million for the year ended December 31, 2016 compared to the year ended December 31, 2015. The decrease was due to a decrease of $17.3 million in FRE and an increase of net realized
investment and other losses of $16.4 million for the year ended December 31, 2016 compared to the year ended December 31, 2015.
Economic Net Income:
Economic net income is comprised of fee related earnings and performance related earnings. Economic net income decreased $35.9 million, or 25%, for the year ended December 31, 2016 compared to the year ended December 31, 2015 as a result of the fluctuations described above.
Distributable Earnings:
DE decreased $43.6 million, or 29%, for the year ended December 31, 2016 compared to the year ended December 31, 2015. DE was negatively impacted by a decrease of $17.3 million in FRE. In addition, net realized investment and other losses increased $16.4 million for the year ended December 31, 2016.
Liquidity and Capital Resources
Sources and Uses of Liquidity
Our sources of liquidity are (1) cash on hand, (2) net working capital, (3) cash from operations, including management fees, which are collected monthly, quarterly or semi‑annually, net realized performance fees, which are unpredictable as to amount and timing, (4) fund distributions related to our investments that are also unpredictable as to amount and timing and (5) net borrowing provided by the Credit Facility. As of December 31, 2017, our cash and cash equivalents were $118.9 million, including investments in money market funds, and we had $210.0 million of borrowings outstanding under the Credit Facility. The ability to draw from the Credit Facility is subject to a leverage covenant. We believe that these sources of liquidity will be sufficient to fund our working capital requirements and to meet our commitments in the ordinary course of business for the foreseeable future.
We expect that our primary liquidity needs will continue to be to (1) provide capital to facilitate the growth of our existing investment management businesses, (2) fund our investment commitments, (3) provide capital to facilitate our expansion into businesses that are complementary to our existing investment management businesses, (4) pay operating expenses, including cash compensation to our employees and payments under the tax receivable agreement (“TRA”), (5) fund capital expenditures, (6) service our debt, (7) pay income taxes and (8) make distributions to our common and preferred shareholders in accordance with our distribution policy.
In the normal course of business, we have made distributions to our existing owners, including distributions sourced from investment income and performance fees. If cash flow from operations were insufficient to fund distributions over a sustained period of time, we expect that we would suspend paying such distributions. Unless quarterly distributions have been declared and paid (or declared and set apart for payment) on the preferred shares, we may not declare or pay or set apart payment for distributions on any common shares during the period. Dividends on the preferred shares are not cumulative and the preferred shares are not convertible into common shares or any other security.
Net realized performance fees also provide a source of liquidity. Performance fees are realized when a portfolio investment is profitably disposed of and the fund’s cumulative returns are in excess of the preferred return or hurdle rate. Performance fees are typically realized at the end of each fund’s measurement period when investment performance exceeds a stated benchmark or hurdle rate.
Our gross accrued performance fees by segment as of December 31, 2017 are set forth in the table below. The company did not record any contingent repayment obligation on accrued performance fees as of December 31, 2017.
| As of December 31, 2017 | |||||||||||
| Accrued Performance Fees | Eliminations(1) | Consolidated Accrued Performance Fees | |||||||||
| Segment | (Dollars in thousands) | ||||||||||
| Credit Group | $ | 168,504 | $ | (5,333 | ) | $ | 163,171 | ||||
| Private Equity Group | 815,407 | 815,407 | |||||||||
| Real Estate Group | 121,269 | — | 121,269 | ||||||||
| Total | $ | 1,105,180 | $ | (5,333 | ) | $ | 1,099,847 |
| (1) | Amounts represent accrued performance fees earned from Consolidated Funds that are eliminated in consolidation. |
Our consolidated financial statements reflect the cash flows of our operating businesses as well as the results of our Consolidated Funds. The assets of our Consolidated Funds, on a gross basis, are significantly larger than the assets of our operating businesses and therefore have a substantial effect on our reported cash flows. The primary cash flow activities of our Consolidated Funds include: (1) raising capital from third-party investors, which is reflected as non-controlling interests of our Consolidated Funds when required to be consolidated into our consolidated financial statements, (2) financing certain investments by issuing debt, (3) purchasing and selling investment securities, (4) generating cash through the realization of certain investments, (5) collecting interest and dividend income and (6) distributing cash to investors. Our Consolidated Funds are treated as investment companies for financial accounting purposes under GAAP; therefore, the character and classification of all Consolidated Fund transactions are presented as cash flows from operations. Liquidity available at our consolidated funds is typically not available for corporate liquidity needs, and debt of the consolidated funds is non–recourse to the company except to the extent of the Company's investment in the fund.
Cash Flows
The significant captions and amounts from our consolidated financial statements, which include the effects of our Consolidated Funds and CLOs in accordance with GAAP, are summarized below. Negative amounts represent a net outflow, or use of cash.
| Year Ended December 31, | |||||||||||
| 2017 | 2016 | 2015 | |||||||||
| (Dollars in millions) | |||||||||||
| Statements of cash flows data | |||||||||||
| Net cash used in operating activities | $ | (1,863 | ) | $ | (626 | ) | $ | (528 | ) | ||
| Net cash used in investing activities | (33 | ) | (12 | ) | (75 | ) | |||||
| Net cash provided by financing activities | 1,655 | 881 | 582 | ||||||||
| Effect of foreign exchange rate change | 17 | (22 | ) | (6 | ) | ||||||
| Net change in cash and cash equivalents | $ | (224 | ) | $ | 221 | $ | (27 | ) |
Operating Activities
Our net cash flows used in operating activities were $1.9 billion, $625.7 million and $528.0 million for the years ended December 31, 2017, 2016 and 2015, respectively. The changes in cash used in operating activities for the comparative periods was primarily driven by net investment activity in our Consolidated Funds related to new funds that we began consolidating in 2017 and 2016, respectively. For the years ended December 31, 2017, 2016 and 2015, net purchases from investments by our Consolidated Funds were $1.8 billion, $765.5 million and $593.3 million, respectively. The change for the year ended December 31, 2017 compared to the year ended December 31, 2016 was also attributable to a change in the timing of annual bonus payments to employees for the year ended December 31, 2017. Employee bonuses earned in 2017 were paid in December 2017, while a majority of employee bonuses earned in 2016 were were paid in January 2017, resulting in an $114.3 million increase in net cash used in operating activities for the year ended December 31, 2017 compared to the year ended December 31, 2016.
Our increasing working capital needs reflect the growth of our business, while the capital requirements needed to support fund-related activities vary based upon the specific investment activities being conducted during such period. The movements within our Consolidated Funds do not adversely impact our liquidity or earnings trends. We believe that our ability to generate cash from revenues, as well as the capacity under the Credit Facility, provides us with the necessary liquidity to manage short-term fluctuations in working capital and to meet our short-term commitments.
Investing Activities
Our investing activities generally reflect cash used for certain acquisitions and purchases of fixed assets. Purchases of fixed assets were $33.2 million, $11.9 million and $10.7 million for the years ended December 31, 2017, 2016 and 2015, respectively. The increase in fixed asset purchases in 2017 largely relates to furniture, fixtures, equipment and leasehold improvements related to a new office location in Los Angeles. In connection with certain business combinations and acquisitions, we record the fair value of management contracts and other finite-lived assets as intangible assets. During the year ended December 31, 2015, we used $64.4 million of cash, net of cash acquired, to complete the EIF acquisition.
Financing Activities
Net cash flows provided by financing activities was $1.7 billion, $880.8 million and $581.5 million for the years ended December 31, 2017, 2016 and 2015 respectively. For the year ended December 31, 2017, financing activities represented a source of cash primarily from net borrowings on debt facilities of the Company and our Consolidated funds. For the year ended December 31, 2016, net cash inflows were primarily due to net proceeds from preferred stock issuances and net borrowings on debt facilities of the Consolidated funds, which were partially offset by net repayments on the Company's debt facilities and a $40 million payment made in connection with our 2011 acquisition of Indicus Advisors, LLP. For the year ended December 31, 2015, net cash inflows were primarily due to net borrowings on debt facilities of the Company and our Consolidated funds.
Net borrowings from our debt obligations were $310.4 million for the year ended December 31, 2017 compared to net repayments on our debt obligations of $84.0 million for the year ended December 31, 2016 and net borrowings of $133.4 million for the year ended December 31, 2015. In the current year, net borrowings under the Credit Facility were used to support earlier payments of annual bonuses and net borrowings from new Term Loans that were issued to support purchases of CLOs that we manage within our risk retention vehicles.
Our Consolidated Funds had net proceeds from debt obligations of $1.5 billion, $905.0 million and $662.9 million for the years ended December 31, 2017, 2016 and 2015, respectively. The increase in net borrowing activity in 2017 for the Consolidated Funds is related to the launch of four new CLOs.
Proceeds from the issuance of preferred equity offering, net of issuance costs, resulted in a cash inflow of $298.8 million for the year ended December 31, 2016.
Distributions to our AOG unitholders and common shareholders were $261.7 million, $200.7 million and $217.8 million for the years ended December 31, 2017, 2016 and 2015, respectively. The changes in distributions are consistent with the changes in distributable earnings. For our Consolidated Funds, net contributions were $128.3 million, $14.5 million and $2.8 million for the years ended December 31, 2017, 2016 and 2015, respectively. The increase was driven by the funding activities of additional funds consolidated in 2017.
Capital Resources
The following table summarizes the Company's debt obligations (in thousands):
| As of December 31, 2017 | As of December 31, 2016 | |||||||||||||||||||
| Debt Origination Date | Maturity | Original Borrowing Amount | Carrying Value | Interest Rate | Carrying Value | Interest Rate | ||||||||||||||
| Credit Facility(1) | Revolver | 2/24/2022 | N/A | $ | 210,000 | 3.09 | % | $ | — | — | % | |||||||||
| Senior Notes(2) | 10/8/2014 | 10/8/2024 | $ | 250,000 | 245,308 | 4.21 | % | 244,684 | 4.21 | % | ||||||||||
| 2015 Term Loan(3) | 9/2/2015 | 7/29/2026 | $ | 35,205 | 35,037 | 2.86 | % | 35,063 | 2.74 | % | ||||||||||
| 2016 Term Loan(4) | 12/21/2016 | 1/15/2029 | $ | 26,376 | 25,948 | 3.08 | % | 26,037 | N/A | |||||||||||
| 2017 Term Loan A(4) | 3/22/2017 | 1/22/2028 | $ | 17,600 | 17,407 | 2.90 | % | N/A | N/A | |||||||||||
| 2017 Term Loan B(4) | 5/10/2017 | 10/15/2029 | $ | 35,198 | 35,062 | 2.90 | % | N/A | N/A | |||||||||||
| 2017 Term Loan C(4) | 6/22/2017 | 7/30/2029 | $ | 17,211 | 17,078 | 2.88 | % | N/A | N/A | |||||||||||
| 2017 Term Loan D(4) | 11/16/2017 | 10/15/2030 | $ | 30,450 | 30,336 | 2.77 | % | N/A | N/A | |||||||||||
| Total debt obligations | $ | 616,176 | $ | 305,784 |
| (1) | The AOG entities are borrowers under the Credit Facility, which, as amended in February 2017 and increased in September 2017, provides a $1.065 billion revolving line of credit. It has a variable interest rate based on LIBOR or a base rate plus an applicable margin with an unused commitment fee paid quarterly, which is subject to change with the Company’s underlying credit agency rating. As of December 31, 2017, base rate loans bear interest calculated based on the base rate plus 0.50% and the LIBOR rate loans bear interest calculated based on LIBOR plus 1.50%. The unused commitment fee is 0.20% per annum. There is a base rate and LIBOR floor of zero. |
| (2) | The Senior Notes were issued in October 2014 by Ares Finance Co. LLC (“AFC”), a subsidiary of the Company, at 98.268% of the face amount with interest paid semi-annually. The Company may redeem the Senior Notes prior to maturity, subject to the terms of the indenture. |
| (3) | The 2015 Term Loan was entered into in August 2015 by a subsidiary of the Company that acts as a manager to a CLO. The 2015 Term Loan is secured by collateral in the form of CLO senior tranches owned by the Company. To the extent the assets are not sufficient to cover the Term Loan, there is no further recourse to the Company to fund or repay the remaining balance. Interest is paid quarterly, and the Company also pays a fee of 0.025% of a maximum investment amount. |
| (4) | The 2016 and 2017 Term Loans ("Term Loans") were entered into by a subsidiary of the Company that acts as a manager to a CLO. The Term Loans are secured by collateral in the form of CLO senior tranches and subordinated notes owned by the Company. Collateral associated with one of the Term Loans may be used to satisfy outstanding liabilities of another term loan should the collateral fall short. To the extent the assets associated with these Term Loans are not sufficient, there is no further recourse to the Company to fund or repay the remaining balance. Interest is paid quarterly, and the Company also pays a fee of 0.03% of a maximum investment amount. |
As of December 31, 2017, we were in compliance with all covenants under the Credit Facility, Senior Notes and Term Loan obligations.
On February 24, 2017, we amended our Credit Facility to, among other things, increase the size of the Credit Facility from $1.03 billion to $1.04 billion and extend the maturity date from April 2019 to February 2022. Under the amended terms of the amended Credit Facility, based on our current credit agency ratings, the stated interest rate is LIBOR plus 1.50% with an unused commitment fee of 0.20%.
In September 2017, we increased our Credit Facility to $1.065 billion from $1.04 billion. The $25 million increase resulted from the exercise of the facility’s accordion feature and the addition of a new bank to the facility. No other terms of the revolving credit facility were impacted by the increase.
We intend to use a portion of our available liquidity to make cash distributions to our preferred and common shareholders on a quarterly basis in accordance with our distribution policies. Our ability to make cash distributions to our preferred and common shareholders is dependent on a myriad of factors, including among others: general economic and business conditions; our strategic plans and prospects; our business and investment opportunities; timing of capital calls by our funds in support of our commitments; our financial condition and operating results; working capital requirements and other anticipated cash needs; contractual restrictions and obligations; legal, tax and regulatory restrictions; restrictions on the payment of distributions by our subsidiaries to us and other relevant factors.
In conjunction with the Tax Election, we have adopted a new distribution policy that will reduce volatility of the quarterly distributions and become more closely aligned with our core management fee business. For further detail on the impact of the Tax Election on our distribution policy, see "Item 5. Market For Registrant’s Common Equity, Related Stockholder Matters And Issuer Purchases Of Equity Securities - Distribution Policy for Common Shares Prior to Effectiveness of Tax Election & Distribution Policy for Common Shares Following Effectiveness of Tax Election."
We are required to maintain minimum net capital balances for regulatory purposes for our United Kingdom subsidiary and for our subsidiary that operates as a broker‑dealer. These net capital requirements are met in part by retaining cash, cash‑equivalents and investment securities. As a result, we may be restricted in our ability to transfer cash between different operating entities and jurisdictions. As of December 31, 2017, we were required to maintain approximately $24.5 million in liquid net assets within these subsidiaries to meet regulatory net capital and capital adequacy requirements. We remain in compliance with all regulatory requirements.
Holders of AOG Units, subject to the terms of the exchange agreement, may exchange their AOG Units for Ares Management, L.P. common shares on a one-for-one basis. These exchanges are expected to result in increases in the tax basis of the tangible and intangible assets of Ares Management, L.P. that otherwise would not have been available. These increases in tax basis may increase (for tax purposes) depreciation and amortization and therefore reduce the amount of tax that we would otherwise be required to pay in the future. We entered into the TRA with the TRA recipients that provides for the payment by us to the TRA Recipients of 85% of the amount of cash savings, if any, in U.S. federal, state, local and foreign income tax or franchise tax that we actually realize as a result of these increases in tax basis and of certain other tax benefits related to entering into the TRA, including tax benefits attributable to payments under the TRA and interest accrued thereon. Future payments under the TRA in respect of subsequent exchanges are expected to be substantial. As of December 31, 2017, there have been a limited number of exchanges of AOG Units for Ares Management, L.P. common shares.
Preferred Equity
As of December 31, 2017 and 2016, the Company had 12,400,000 shares of Series A Preferred Shares (the “Preferred Equity”) outstanding. When, as and if declared by the Company’s board of directors, distributions on the Preferred Equity are paid quarterly at a rate per annum equal to 7.00%. The Preferred Equity may be redeemable at our option, in whole or in part, at any time on or after June 30, 2021, at a price of $25.00 per share.
Cash distributions to our common shareholders may be impacted by any corporate tax liability owed by us and Ares Holdings, Inc. (“AHI”), the wholly owned U.S. corporate subsidiary of the Company. In connection with the Preferred Equity issuance, the Ares Operating Group issued mirror preferred units (“GP Mirror Units”) paying the same 7.00% rate per annum to wholly owned subsidiaries of the Company including AHI. Although income allocated in respect of distributions on the GP Mirror Units may be subject to tax, cash distributions to our preferred shareholders will not be reduced on account of any income taxes owed by us. As a result, the amounts ultimately distributed by us to our common shareholders may be reduced by any corporate taxes imposed on us or AHI.
Exercise of Indicus Put Option
Upon acquisition of Indicus in November 2011, certain former owners of Indicus (“Indicus Owners”) were provided a fixed put option on their equity interest in the Company at an aggregate strike price of $40 million to be exercised during 2016 (“Put Option”). In August 2016, the Indicus Owners exercised their Put Option and, in November 2016, we paid these Indicus Owners a total of $40 million to settle the put option in exchange for redemption of their equity interests in the Company.
Critical Accounting Estimates
We prepare our consolidated financial statements in accordance with GAAP. In applying many of these accounting principles, we need to make assumptions, estimates or judgments that affect the reported amounts of assets, liabilities, revenues and expenses in our consolidated financial statements. We base our estimates and judgments on historical experience and other assumptions that we believe are reasonable under the circumstances. These assumptions, estimates or judgments, however, are both subjective and subject to change, and actual results may differ from our assumptions and estimates. If actual amounts are ultimately different from our estimates, the revisions are included in our results of operations for the period in which the actual amounts become known. We believe the following critical accounting policies could potentially produce materially different results if we were to change the underlying assumptions, estimates or judgments. See “—Components of Consolidated Results of Operations” and Note 2, “Summary of Significant Accounting Policies,” to our consolidated financial statements included in this Annual Report on Form 10‑K for a summary of our significant accounting estimates.
Principles of Consolidation
We consolidate entities based on either a variable interest model or voting interest model. As such, for entities that are determined to be variable interest entities (“VIEs”), we consolidate those entities where we have both significant economics and the power to direct the activities of the entity that impact economic performance. For limited partnerships and similar entities evaluated under the voting interest model, we do not consolidate those entities for which we act as the general partner. However, the Company continues to consolidate entities in which it holds majority voting interest.
The consolidation guidance requires qualitative and quantitative analysis to determine whether our involvement, through holding interests directly or indirectly in the entity or contractually through other variable interests (e.g., management and performance related fees), would give us a controlling financial interest. This analysis requires judgment. These judgments include: (1) determining whether the equity investment at risk is sufficient to permit the entity to finance its activities without additional subordinated financial support, (2) evaluating whether the equity holders, as a group, can make decisions that have a significant effect on the success of the entity, (3) determining whether two or more parties’ equity interests should be aggregated, (4) determining whether the equity investors have proportionate voting rights to their obligations to absorb losses or rights to receive returns from an entity and (5) evaluating the nature of relationships and activities of the parties involved in determining which party within a related‑party group is most closely associated with a VIE and hence would be deemed the primary beneficiary.
The holders of the consolidated VIEs’ liabilities do not have recourse to us other than to the assets of the consolidated VIEs. The assets and liabilities of the consolidated VIEs are comprised primarily of investments and loans payable, respectively.
Fair Value Measurement
GAAP establishes a hierarchal disclosure framework prioritizing the inputs used in measuring financial instruments at fair value into three levels based on their market observability. Market price observability is affected by a number of factors, including the type of instrument and the characteristics specific to the instrument. Financial instruments with readily available quoted prices from an active market or where fair value can be measured based on actively quoted prices generally have a higher degree of market price observability and a lesser degree of judgment inherent in measuring fair value.
Financial assets and liabilities measured and reported at fair value are classified as follows:
| • | Level I—Quoted prices in active markets for identical instruments. |
| • | Level II—Quoted prices for similar instruments in active markets; quoted prices for identical or similar instruments in inactive markets; and model‑derived valuations with directly or indirectly observable significant inputs. Level II inputs include prices in markets with few transactions, non-current prices, prices for which little public information exists or prices that vary substantially over time or among brokered market makers. Other inputs include interest rates, yield curves, volatilities, prepayment risks, loss severities, credit risks and default rates. |
| • | Level III—Valuations that rely on one or more significant unobservable inputs. These inputs reflect the Company’s assessment of the assumptions that market participants would use to value the instrument based on the best information available. |
In some instances, an instrument may fall into multiple levels of the fair value hierarchy. In such instances, the instrument’s level within the fair value hierarchy is based on the lowest of the three levels (with Level III being the lowest) that is significant to the fair value measurement. Our assessment of the significance of an input requires judgment and considers factors specific to
the instrument. See Note 6, “Fair Value,” to our consolidated financial statements included in this Annual Report on Form 10‑K for a summary of our valuation of investments and other financial instruments by fair value hierarchy levels.
Equity-Based Compensation
We recognize expense related to equity-based compensation in which we receive services from our professionals in exchange for (a) equity instruments of the Company, (b) derivatives based on the Company’s common shares, or (c) liabilities that are based on the fair value of the Company’s equity instruments. Equity-based compensation expense represents expenses associated with restricted units, options and phantom units granted under the Ares Management, L.P. 2014 Equity Incentive Plan.
Total compensation expense related to equity-based awards expected to be recognized in all future periods is determined based on the fair value of the respective equity-based award on the grant date, and is recognized on a straight-line basis over the requisite service period, where applicable. Compensation expense for a liability award is recognized each reporting period until the liability is settled. The fair value of liability award is remeasured at the end of each reporting period through settlement.
The Company recognizes forfeitures in the period they occur as a reversal of previously recognized compensation expense. The reduction in compensation expense is determined based on the specific awards forfeited during that period and could impact the expense for that period.
We record deferred tax assets for equity-based compensation transactions that result in deductions on our income tax returns based on the amount of equity-based compensation recognized and the statutory tax rate in the jurisdiction in which we will receive a tax deduction.
Restricted Shares
Certain restricted shares are subject to a lock up provision that expires on the fifth anniversary of the IPO. We used Finnerty’s average strike‑price put option model to estimate the discount associated with this lack of marketability to be applied on the closing price of common shares on the grant date, using the following key assumptions:
| Expected volatility factor(1) | 20% to 28 % |
| Average length of holding period restriction (in years) | 2.4 year |
| Weighted average expected dividend yield | 5.0% |
| (1) | Expected volatility is based on the Company's guideline companies' expected volatility. |
Options
We estimated the fair value of the options as of the grant date using the Black- Scholes option pricing model. Aggregate intrinsic value represents the value of the Company’s closing share price on the last trading day of the period in excess of the weighted-average exercise price multiplied by the number of options exercisable or expected to vest. The Company did not grant new options during the years ended December 31, 2017 and December 31, 2016. The fair value of each option granted during the year ended December 31, 2015 was measured on the date of grant using the Black-Scholes option-pricing model and the following weighted average assumptions:
| Risk-free interest rate | 1.71% to 1.80% |
| Weighted average expected dividend yield | 5.00% |
| Expected volatility factor(1) | 35.00% to 36.00% |
| Expected life in years | 6.66 to 7.49 |
| (1) | Expected volatility is based on comparable companies using daily stock prices. |
The fair value of an award is affected by the Company’s share price on the date of grant as well as other assumptions including the estimated volatility of the Company’s share price over the term of the awards and the estimated period of time that management expects employees to hold their share options. The estimated period of time that management expects employees to hold their options was estimated as the midpoint between the vesting date and maturity date.
Phantom Shares
Each phantom share represents an unfunded, unsecured right of the holder to receive an amount in cash per phantom share equal to the average closing price of a common share for the 15 trading days immediately prior to, and the 15 trading days immediately following, the vesting dates. The fair value of the awards is remeasured at each reporting period based on the most recent closing price of common shares.
Income Taxes
Prior to the effectiveness of the Tax Election, a substantial portion of our earnings flow through to our owners without being subject to federal income tax at the entity level. A portion of our operations is conducted through a domestic corporation that is subject to corporate level taxes and for which we record current and deferred income taxes at the prevailing rates in the various jurisdictions in which these entities operate.
We use the liability method of accounting for deferred income taxes pursuant to GAAP. Under this method, deferred tax assets and liabilities are recognized for the future tax consequences attributable to temporary differences between the carrying value of existing assets and liabilities and their respective tax bases. Deferred tax assets and liabilities are measured using the statutory tax rates expected to be applied in the periods in which those temporary differences are settled. The effect of a change in tax rates on deferred tax assets and liabilities is recognized in the period of the change. A valuation allowance is recorded on our net deferred tax assets when it is more likely than not that such assets will not be realized. When evaluating the realizability of our deferred tax assets, all evidence, both positive and negative, is evaluated. Items considered in this analysis include the ability to carry back losses, the reversal of temporary differences, tax planning strategies and expectations of future earnings.
Under GAAP, the amount of tax benefit to be recognized is the amount of benefit that is “more likely than not” to be sustained upon examination. We analyze our tax filing positions in all of the U.S. federal, state, local and foreign tax jurisdictions where we are required to file income tax returns, as well as for all open tax years in these jurisdictions. If, based on this analysis, we determine that uncertainties in tax positions exist, a liability is established, which is included in accounts payable, accrued expenses and other liabilities in our consolidated financial statements. We recognize accrued interest and penalties related to unrecognized tax positions in the provision for income taxes.
Tax laws are complex and subject to different interpretations by the taxpayer and respective governmental taxing authorities. Significant judgment is required in determining tax expense and in evaluating tax positions, including evaluating uncertainties under GAAP. We review our tax positions quarterly and adjust our tax balances as new information becomes available.
See Note 20, “Subsequent Events,” to our consolidated financial statements included in this Annual Report on Form 10‑K for changes made to our tax status in 2018.
Business Combinations
We account for business combinations using the acquisition method of accounting, under which the purchase price of the acquisition is allocated to the fair value of each asset acquired and liability assumed as of the acquisition date. Contingent consideration obligations are recognized as of the acquisition date at fair value based on the probability that contingency will be realized.
Management’s determination of fair value of assets acquired and liabilities assumed at the acquisition date, as well as contingent consideration, are based on the best information available in the circumstances and may incorporate management’s own assumptions and involves a significant degree of judgment. While we use our best estimates and assumptions to accurately value assets acquired and liabilities assumed at the acquisition date as well as contingent consideration, where applicable, estimates are then inherently uncertain and subject to refinement. As a result, during the measurement period, which may be up to one year from the acquisition date, the Company records adjustments to the assets acquired and liabilities assumed with the corresponding offset to goodwill. Upon the conclusion of the measurement period or final determination of the values of assets acquired or liabilities assumed, whichever comes first, any subsequent adjustments are recorded to the consolidated statements of operations.
For a given acquisition, management may identify certain pre-acquisition contingencies as of the acquisition date and may extend the review and evaluation of these pre‑acquisition contingencies throughout the measurement period to obtain sufficient information to assess whether management includes these contingencies as a part of the fair value estimates of assets acquired and liabilities assumed and, if so, to determine their estimated amounts. If management cannot reasonably determine the fair value of a pre- acquisition contingency by the end of the measurement period, which is generally the case given the nature of such matters, the Company will recognize an asset or a liability for such pre-acquisition contingency if: (i) it is probable that an asset
existed or a liability had been incurred at the acquisition date and (ii) the amount of the asset or liability can be reasonably estimated. Subsequent to the measurement period, changes in the estimates of such contingencies will affect earnings and could have a material effect on the consolidated statements of operations and financial position.
Intangible Assets and Goodwill
Our intangible assets generally consist of contractual rights to earn future management fees and incentive fees from investment funds we acquire. Finite-lived intangibles are amortized on a straight-line basis over their estimated useful lives, which range from approximately 1 to 13.5 years and are reviewed for impairment whenever events or changes in circumstances indicate that the carrying amount of the asset may not be recoverable.
Goodwill represents the excess of cost over the identifiable net assets of businesses acquired and is recorded in the functional currency of the acquired entity. Goodwill is tested annually for impairment. If, after assessing qualitative factors, we believe that it is more likely than not that the fair value of the reporting unit is less than its carrying value, we will use a two-step process to evaluate impairment. The first step compares the fair value of the reporting unit with its carrying amount, including goodwill. The second step, used to measure the amount of any potential impairment, compares the implied fair value of the reporting unit with the carrying amount of goodwill.
The assessment requires us to make judgments and involves the use of significant estimates and assumptions. These estimates and assumptions include long-term growth rates and margins used to calculate projected future cash flows, risk-adjusted discount rates based on our weighted average cost of capital and future economic and market conditions. These estimates and assumptions have to be made for each reporting unit evaluated for impairment. Our estimates for market growth, our market share and costs are based on historical data, various internal estimates and certain external sources, and are based on assumptions that are consistent with the plans and estimates we are using to manage the underlying business. If future forecasts are revised, they may indicate or require future impairment charges. We base our fair value estimates on assumptions we believe to be reasonable but that are unpredictable and inherently uncertain. Actual future results may differ from those estimates.
Recent Accounting Pronouncements
Information regarding recent accounting pronouncements and their impact on the Company can be found in Note 2, “Summary of Significant Accounting Policies,” in the “Notes to the Consolidated Financial Statements” included in this Annual Report on Form 10‑K for a summary of our significant accounting estimates.
Off‑Balance Sheet Arrangements
In the normal course of business, we engage in off‑balance sheet arrangements, including transactions in derivatives, guarantees, commitments, indemnifications and potential contingent repayment obligations.
Contractual Obligations, Commitments and Contingencies
The following table sets forth information relating to our contractual obligations of the Company and of the Consolidated Funds as of December 31, 2017:
| Ares Obligations | Less than 1 year | 1 - 3 years | 4 - 5 years | Thereafter | Total | |||||||||||||||
| (Dollars in thousands) | ||||||||||||||||||||
| The Company: | ||||||||||||||||||||
| Operating lease obligations(1) | $ | 26,849 | $ | 48,283 | $ | 37,177 | $ | 51,969 | $ | 164,278 | ||||||||||
| Debt obligations payable(2) | — | — | — | 406,176 | 406,176 | |||||||||||||||
| Interest obligations on debt(3) | 20,244 | 40,488 | 36,489 | 51,473 | 148,694 | |||||||||||||||
| Credit Facility(4) | — | — | 210,000 | — | 210,000 | |||||||||||||||
| Capital commitments(5) | 285,695 | — | — | — | 285,695 | |||||||||||||||
| Subtotal | 332,788 | 88,771 | 283,666 | 509,618 | 1,214,843 | |||||||||||||||
| Consolidated Funds: | ||||||||||||||||||||
| Debt obligations payable | 119,542 | 5,714 | — | 5,215,824 | 5,341,080 | |||||||||||||||
| Interest obligations on debt(3) | 130,969 | 260,350 | 259,782 | 687,693 | 1,338,794 | |||||||||||||||
| Capital commitments of Consolidated Funds(6) | 28,021 | — | — | — | 28,021 | |||||||||||||||
| Total | $ | 611,320 | $ | 354,835 | $ | 543,448 | $ | 6,413,135 | $ | 7,922,738 |
| (1) | The table includes future minimum commitments for our operating leases. Office space is leased under agreements with expirations ranging from month‑to‑month contracts to lease commitments through 2027. Rent expense includes only base contractual rent. |
| (2) | Debt obligations include $245.3 million senior notes and $160.9 million of term loan. |
| (3) | Interest obligations include interest accrued on outstanding indebtedness. |
| (4) | Represent outstanding balance under the Credit Facility |
| (5) | Represent commitments to invest in certain investment products, primarily in funds managed by us. These amounts are generally due on demand and are therefore presented as obligations payable in the less than one year. |
| (6) | Represents commitments by Consolidated Funds to fund certain investments. These amounts are generally due on demand and are therefore presented as obligations payable in the less than one year. |
In connection with the initial public offering, we entered into a TRA with the TRA Recipients that requires us to pay them 85% of any tax savings realized by Ares Management, L.P.’s and its wholly owned subsidiaries that are taxable as corporations for U.S. federal income tax purposes from any step‑up in tax basis resulting from an exchange of Ares Operating Group Units for Ares Management, L.P. common shares or, at our option, for cash. Because the timing of amounts to be paid under the tax receivable agreement cannot be determined, this contractual commitment has not been presented in the table above. The tax savings achieved may not ensure that we have sufficient cash available to pay this liability, and we may be required to incur additional debt to satisfy this liability.
Indemnifications
Consistent with standard business practices in the normal course of business, we enter into contracts that contain indemnities for our affiliates, persons acting on our behalf or such affiliates and third parties. The terms of the indemnities vary from contract to contract and the maximum exposure under these arrangements, if any, cannot be determined and has not been recorded in our consolidated financial statements. As of December 31, 2017, we have not had prior claims or losses pursuant to these contracts and expect the risk of loss to be remote.
Capital Commitments
As of December 31, 2017 and December 31, 2016, we had aggregate unfunded commitments of $285.7 million and $535.3 million, respectively, including commitments to both non-consolidated funds and Consolidated Funds. Total unfunded commitments included $16.5 million and $89.2 million in commitments to funds not managed by us as of December 31, 2017 and December 31, 2016, respectively.
ARCC Fee Waiver
In conjunction with the ARCC-ACAS Transaction, we agreed to waive up to $10 million per quarter of ARCC's Part I Fees for ten calendar quarters, which began in the second quarter of 2017. ARCC Part I Fees will only be waived to the extent they are paid. If Part I Fees are less than $10 million in any single quarter, the shortfall will not carryover to the subsequent quarters.
As of December 31, 2017, there are seven remaining quarters as part of the fee waiver agreement, with a maximum of $70 million in potential waivers. ARCC Part I Fees are shown net of the fee waiver.
Contingent Obligations
Generally, if at the termination of a fund (and increasingly at interim points in the life of a fund), the fund has not achieved investment returns that (in most cases) exceed the preferred return threshold or (in all cases) the general partner receives net profits over the life of the fund in excess of its allocable share under the applicable partnership agreement, the Company will be obligated to repay carried interest that was received by the Company in excess of the amounts to which the Company is entitled. This contingent obligation is normally reduced by income taxes paid by the Company related to its carried interest.
The partnership documents governing our funds generally include a contingent repayment provision that, if triggered, may give rise to a contingent obligation that may require the general partner to return amounts to the fund for distribution to investors. Therefore, performance fees, generally, are subject to reversal in the event that the funds incur future losses. These losses are limited to the extent of the cumulative performance fees recognized in income to date. Due in part to our investment performance and the fact that our performance fees are generally determined on a liquidation basis, as of December 31, 2017 and December 31, 2016, if the funds were liquidated at their fair values, there would have been no contingent repayment obligation or liability. There can be no assurance that we will not incur a contingent repayment obligation in the future. If all of the existing investments were deemed worthless, the amount of cumulative revenues that has been recognized would be reversed. We believe that the possibility of all of the existing investments becoming worthless is remote. At December 31, 2017, 2016 and 2015, had we assumed all existing investments were worthless, the amount of carried interest, net of tax, subject to contingent repayment would have been approximately $476.1 million, $418.3 million and $322.2 million, respectively, of which approximately $370.0 million, $323.9 million and $247.9 million, respectively, would be reimbursable to the Company by certain professionals.
Performance fees are also affected by changes in the fair values of the underlying investments in the funds that we advise. Valuations, on an unrealized basis, can be significantly affected by a variety of external factors including, but not limited to, bond yields and industry trading multiples.
Our senior professionals and other professionals who have received carried interest distributions are responsible for funding their proportionate share of any contingent repayment obligations. However, the governing agreements of certain of our funds provide that if a current or former professional from such funds does not fund his or her respective share, then we may have to fund additional amounts beyond what we received in carried interest, although we will generally retain the right to pursue any remedies that we have under such governing agreements against those carried interest recipients who fail to fund their obligations.
Additionally, at the end of the life of the funds there could be a payment due to a fund by us if we have recognized more performance fees than was ultimately earned. The general partner obligation amount, if any, will depend on final realized values of investments at the end of the life of the fund.
Previous: Item 6. Selected Financial Data · Next: Item 7A. Quantitative and Qualitative Disclosures About Market Risk