 filings.tools
Brown & Brown (BRO) 10-K risk factor changes: FY2012 vs FY2011
The 2012-12-31 10-K against the 2011-12-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A0 rewritten257 added0 removed0 unchanged
All filing items352 rewritten1,899 added1,502 removed618 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: the parser did not find an Item 1A in both filings.
- Sentence by sentence, 1,899 added, 1,502 removed, 352 rewritten and 618 unchanged across 21 items that differ.
- New this year: Item 1A. Risk Factors; Item 1. Business.; Item 3. Legal Proceedings.; Item 1B. Unresolved Staff Comments.; Item 2. Properties.; Item 8. Financial Statements and Supplementary Data..
Sentences by item
21 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2012; struck-through words were in FY2011. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
0 rewritten, 257 added, 0 removed, 0 unchanged
New section this year
| --- | --- |
WE CANNOT ACCURATELY FORECAST OUR COMMISSION REVENUES BECAUSE OUR COMMISSIONS DEPEND ON PREMIUM RATES CHARGED BY INSURANCE COMPANIES, WHICH HISTORICALLY HAVE VARIED AND, AS A RESULT, HAVE BEEN DIFFICULT TO PREDICT.
We are primarily engaged in the insurance agency, wholesale brokerage, and insurance programs business, and derive revenues principally from commissions paid by insurance companies.
Commissions are based upon a percentage of premiums paid by customers for insurance products.
The amount of such commissions is therefore highly dependent on premium rates charged by insurance companies.
We do not determine insurance premiums.
Premium rates are determined by insurance companies based on a fluctuating market.
Historically, property and casualty premiums have been cyclical in nature and have varied widely based on market conditions.
As traditional risk-bearing insurance companies continue to outsource the production of premium revenue to non-affiliated brokers or agents such as us, those insurance companies may seek to further reduce their expenses by reducing the commission rates payable to those insurance agents or brokers.
The reduction of these commission rates, along with general volatility and/or declines in premiums, may significantly affect our profitability.
Because we do not determine the timing or extent of premium pricing changes, we cannot accurately forecast our commission revenues, including whether they will significantly decline.
As a result, we may have to adjust our budgets for future acquisitions, capital expenditures, dividend payments, loan repayments and other expenditures to account for unexpected changes in revenues, and any decreases in premium rates may adversely affect the results of our operations.
CURRENT U.S. ECONOMIC CONDITIONS AND THE SHIFT AWAY FROM TRADITIONAL INSURANCE MARKETS MAY CONTINUE TO ADVERSLY AFFECT OUR BUSINESS.
Since late 2007, global consumer confidence has eroded amidst concerns over declining asset values, volatility in energy costs, geopolitical issues, the availability and cost of credit, high unemployment, and the stability and solvency of financial institutions, financial markets, businesses, and sovereign nations.
These concerns have slowed economic growth and resulted in a recession in the United States.
Economic conditions have had a negative impact on our results of operations during the years since 2008 due to reduced customer demand.
If these economic conditions worsen, a number of negative effects on our business could result, including declines in values of insurable exposure units, declines in insurance premium rates, and the financial insolvency, or reduced ability to pay, of certain of our customers.
Any of these effects could decrease our net revenues and profitability.
In addition, there has been an increase in alternative insurance markets, such as self-insurance, captives, risk retention groups and non-insurance capital markets.
While we compete in these segments on a fee-for-service basis, we cannot be certain that such alternative markets will provide the same level of profitability as traditional insurance markets.
OUR GROWTH STRATEGY DEPENDS IN PART ON THE ACQUISITION OF OTHER INSURANCE INTERMEDIARIES, WHICH MAY NOT BE AVAILABLE ON ACCEPTABLE TERMS IN THE FUTURE AND WHICH, IF CONSUMMATED, MAY NOT BE ADVANTAGEOUS TO US.
Our growth strategy includes the acquisition of other insurance intermediaries.
Our ability to successfully identify suitable acquisition candidates, complete acquisitions, integrate acquired businesses into our operations, and expand into new markets requires us to implement and improve our operations and our financial and management information systems.
Integrated, acquired businesses may not achieve levels of revenues, profitability, or productivity comparable to our existing operations, or otherwise perform as expected.
In addition, we compete for acquisition and expansion opportunities with firms and banks that have substantially greater resources than we do.
Acquisitions also involve a number of special risks, such as: diversion of management’s attention; difficulties in the integration of acquired operations and retention of personnel; entry into unfamiliar markets; unanticipated problems or legal liabilities; estimation of the acquisition earn-out payable; and tax and accounting issues, some or all of which could have a material adverse effect on the results of our operations, financial condition and cash flows.
##### [Table of Contents](#toc)
WE COULD INCUR SUBSTANTIAL LOSSES FROM OUR CASH AND INVESTMENT ACCOUNTS IF ONE OF THE FINANCIAL INSTITUTIONS THAT WE USE FAILS OR IS TAKEN OVER BY THE U.S. FEDERAL DEPOSIT INSURANCE CORPORATION (“FDIC”).
Traditionally, we have maintained cash and investment balances, including restricted cash held in premium trust accounts, at various depository institutions in amounts that are significantly in excess of the limits insured by the FDIC.
While we began in the Fall of 2008 re-focusing our investment and cash management strategy by moving more of our cash into non-interest bearing accounts (which were FDIC-insured until December 31, 2012, and not subject to any limits) and money market accounts (a portion of which became FDIC insured in the Fall of 2008), we still maintain cash and investment balances in excess of the current limits insured by FDIC.
As the credit crisis persists, the financial strength of some depository institutions has diminished and this trend may continue.
If one or more of the depository institutions with which we maintain significant cash balances were to fail, our ability to access these funds might be temporarily or permanently limited, and we could face material liquidity problems and potential material financial losses.
OUR BUSINESS, AND THEREFORE OUR RESULTS OF OPERATIONS AND FINANCIAL CONDITION, MAY BE ADVERSELY AFFECTED BY THE FURTHER DISRUPTION IN THE U.S.-BASED CREDIT MARKETS AND BY FURTHER INSTABILITY OF FINANCIAL SYSTEMS.
The disruption in the U.S.-based credit markets, the repricing of credit risk and the deterioration of the financial and real estate markets over the past few years have created increasingly difficult conditions for financial institutions and certain insurance companies.
These conditions include significant losses, greater volatility, significantly less liquidity, widening of credit spreads and a lack of price transparency in certain markets.
While these conditions have somewhat abated since the Fall of 2008, it is difficult to predict when these conditions will completely end and the extent to which our markets, products and business will be adversely affected.
The unprecedented disruptions in the credit and financial markets had a significant material adverse impact on a number of financial institutions and limited access to capital and credit for many companies.
Although we are not currently experiencing any limitation of access to our revolving credit facility (which matures in 2016) and are not aware of any issues impacting the ability or willingness of our lenders under such facility to honor their commitments to extend us credit, the failure of a lender could adversely affect our ability to borrow on that facility, which over time could negatively impact our ability to consummate significant acquisitions or make other significant capital expenditures.
Continued adverse conditions in the credit markets in future years could adversely affect the availability and terms of future borrowings or renewals or refinancings.
We also have a significant amount of trade accounts receivable from some insurance companies with which we place insurance.
An excerpt. Shown here: all 0 rewritten, 40 of 257 added and all 0 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2012 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations.
238 rewritten, 135 added, 127 removed, 287 unchanged
As an insurance intermediary, our principal sources of [removed: revenues] [added: revenue] are commissions paid by insurance companies and, to a lesser extent, fees paid directly by customers.
Commission revenues generally represent a percentage of the premium paid by an insured and are materially affected by fluctuations in both premium rate levels charged by insurance companies and the insureds’ underlying “insurable exposure units,” which are units that insurance companies use to measure or express insurance exposed to risk (such as property values, [added: or] sales and payroll levels) to determine what premium to charge the insured.
For example, level rates of inflation or a [removed: continuing] general decline in economic activity could limit increases in the values of insurable exposure units.
As of January [removed: 2012,] [added: 2013,] our senior leadership group included eight executive officers with regional responsibility for oversight of designated operations within the [removed: Company] [added: Company,] and four regional vice presidents in our Retail Division [removed: that] [added: and one regional vice president in our Wholesale Brokerage Division who] report directly to one of our executive officers.
Our revenues grew from $95.6 million in 1993 to [removed: $1.014] [added: $1.2] billion in [removed: 2011,] [added: 2012,] reflecting a compound annual growth rate of [removed: 14.0%.][added: 14.2%.]
In the same [added: 19 year] period, we increased net income from $8.0 million to [removed: $164.0] [added: $184.0] million in [removed: 2011,] [added: 2012,] a compound annual growth rate of [removed: 18.3%.][added: 17.9%.]
The [removed: past five] years [removed: have] [added: 2007 through 2011] posed significant challenges for us and for our industry in the form of a prevailing decline in insurance premium rates, commonly referred to as a “soft [removed: market;”] [added: market” and] increased significant governmental involvement in the Florida insurance marketplace [removed: since 2007, resulting] [added: which resulted] in a substantial loss of revenues for [removed: us; and, beginning in the second half of 2008 and throughout 2011, increased pressure on the values of insurable exposure units as the consequence of the general weakening of the economy in the United States.][added: us.]
[removed: From] [added: As a result, from] the first quarter of 2007 through the fourth quarter of 2011 we experienced negative internal revenue growth each quarter.
[added: Part of the decline in 2007 was the result of the increased governmental involvement in the Florida insurance marketplace, as described below in “The Florida Insurance Overview.”] In 2010 and 2011, continued declining exposure units had a greater negative impact on our commissions and fees revenues than declining insurance premium rates.
We also earn “profit-sharing contingent commissions,” which are profit-sharing commissions based primarily on underwriting results, but [added: which] may also reflect considerations for volume, growth and/or retention.
Over the last three years, profit-sharing contingent commissions have averaged approximately [removed: 5.0%] [added: 4.8%] of the previous year’s total commissions and fees revenue.
The term “core commissions and fees” excludes profit-sharing contingent commissions and [added: GSCs, and] therefore represents the revenues earned directly from specific insurance policies sold, and specific fee-based services rendered.
In contrast, the term “core organic commissions and fees” is our core commissions and fees less (i) the core commissions and fees earned for the first twelve months by [removed: a newly acquired] [added: newly-acquired] operations and (ii) divested business (core commissions and fees generated from offices, books of business or niches sold or terminated during the comparable period).
Core organic commissions and fees can reflect either “positive” growth with a net increase in revenues, or “negative” [added: growth] with a net decrease in revenues.
Since [removed: these] GSCs are not subject to the uncertainty of loss ratios, they are accrued throughout the year based on actual premiums written.
As of December 31, [removed: 2011,] [added: 2012,] we accrued and earned [removed: $12.1] [added: $9.1] million from GSCs during [removed: 2011,] [added: 2012,] most of which will be collected in the first quarter of [removed: 2012.][added: 2013.]
For the twelve-month periods ended December 31, [removed: 2010] [added: 2011] and [removed: 2009,] [added: 2010,] we earned [removed: $13.4] [added: $12.1] million and [removed: $15.9] [added: $13.4] million, respectively, from GSCs.
Fee revenues are generated primarily by: (1) our Services Division, which provides insurance-related services, including third-party claims administration and comprehensive medical utilization management services in both the workers’ compensation and all-lines liability arenas, as well as Medicare set-aside services, [removed: and] Social Security disability and Medicare benefits advocacy services, and [added: catastrophe claims adjusting services, and] (2) our National Programs and Wholesale Brokerage Divisions, which earn fees primarily for the issuance of insurance policies on behalf of insurance companies.
Fee revenues, as a percentage of our total commissions and fees, represented [removed: 16.4%] [added: 21.7%] in [removed: 2011, 14.6%] [added: 2012, 16.4%] in [removed: 2010] [added: 2011] and [removed: 13.3%] [added: 14.6%] in [removed: 2009.][added: 2010.]
As a result of the bank liquidity and solvency issues in the United States in the last quarter of 2008, we moved substantial amounts of our cash into non-interest bearing checking accounts so that they would be fully insured by the Federal [removed: Depository] [added: Deposit] Insurance Corporation (“FDIC”) or into money-market investment funds (a portion of which is FDIC insured) of SunTrust and Wells Fargo, two large national banks.
Many states have established “Residual Markets,” which are governmental or quasi-governmental insurance facilities that [added: are intended to] provide coverage to individuals and/or businesses that cannot buy insurance in the private marketplace, i.e., “insurers of last resort.” These facilities can be designed to cover any type of risk or exposure; however, the exposures most commonly subject to such facilities are automobile or high-risk property exposures.
Consequently, these operations lost significant amounts of [removed: revenues] [added: revenue] to Citizens.
From 2008 through [removed: 2011,] [added: 2012,] Citizens’ impact was not as dramatic as it had been in 2007; FIU’s core commissions and fees decreased [removed: 16.8%] [added: 19.7%] during this [removed: 2008 to 2011] [added: four-year] period.
Citizens continued to be competitive against the excess and surplus lines insurers, and therefore Citizens negatively affected the revenues of our Florida-based wholesale brokerage operations, such as Hull & Company, Inc., from 2007 through [removed: 2011,] [added: 2012,] although the impact has been decreasing each year.
Citizens’ impact on our Florida [removed: Retail Division] [added: retail offices] was less severe than on our National Programs and Wholesale Brokerage [removed: Divisions] [added: Division operations] because our retail offices have the ability to place business with Citizens, although at slightly lower commission rates and with greater difficulty than [removed: is the case] with other insurance companies.
Citizens raised its insurance rates again in 2011 and [added: 2012, and] is expected to continue to increase its insurance rates in [removed: 2012.][added: 2013.]
Our commission revenues from Citizens for [removed: 2011, 2010] [added: 2012, 2011] and [removed: 2009] [added: 2010] were approximately [removed: $7.8] [added: $6.4] million, [removed: $8.3] [added: $7.8] million, and [removed: $8.7] [added: $8.3] million, respectively.
If, as expected, Citizens continues to attempt to reduce its insured exposures, the financial impact of Citizens on our business should continue to be reduced in [removed: 2012.][added: 2013.]
The net [removed: lost revenues] [added: growth in core organic commissions and fees] of [removed: $23.3] [added: $24.9] million is a significant improvement from the comparable net lost revenues of [removed: $42.7] [added: $21.5] million and [removed: $46.5] [added: $40.1] million in [removed: 2010] [added: 2011] and [removed: 2009,] [added: 2010,] respectively.
This improvement is principally attributable to [removed: the slowing of the rates of decline in both exposure units and] [added: rising] insurance premium [removed: rates.][added: rates, and increasing insurance exposure units as a result of a gradually improving U. S. economy.]
[removed: Even though we continue to experience negative growth in our core organic commissions and fees, we] [added: We] have [added: also] succeeded in acquiring insurance operations that we believe [removed: are] [added: may be of] incrementally higher quality in each of the last three years.
We completed [removed: 38] [added: 20] acquisitions in [removed: 2011, which represents an increase over] [added: 2012, compared with] the [removed: 33] [added: 38] and [removed: 11] [added: 33] acquisitions made in [removed: 2010] [added: 2011] and [removed: 2009,] [added: 2010,] respectively.
[removed: The] [added: However, the] estimated annualized revenues from the [removed: 2011] [added: 2012] acquisitions [added: (excluding acquired books of business (customer accounts))] were [removed: $88.7] [added: $149.6] million, [removed: which is up from] [added: an increase over] the [removed: $70.6] [added: $88.7] million and [removed: $26.5] [added: $70.6] million that we acquired in [removed: 2010] [added: 2011] and [removed: 2009,] [added: 2010,] respectively.
Income before income taxes in [removed: 2011] [added: 2012] increased over [removed: 2010] [added: 2011] by [removed: 1.7%,] [added: 12.7%,] or [removed: $4.4] [added: $34.3] million, to [removed: $270.5] [added: $304.8] million.
However, that net increase of [removed: $4.4] [added: $34.3] million includes [removed: $14.4] [added: $44.2] million of income before income taxes related to new acquisitions that were stand-alone offices, and therefore, income before income taxes from those offices that existed in [added: the] same time periods of [removed: 2011] [added: 2012] and [removed: 2010] [added: 2011] (including the new acquisitions that “folded in” to those offices) decreased by [removed: only $9.9] [added: $10.0] million.
[removed: Additionally, $4.2 million of the net $9.9 million decrease in income before income taxes from those offices that existed in same periods of 2011 and 2010, was due to the increased non-cash] [added: Non-cash] stock-based compensation [removed: which related to] [added: increased 63.5%, or $4.3 million, in 2011 as a result of] new grants under our [removed: Stock Incentive Plan (“SIP”)] [added: SIP] that will vest in six to ten years, subject to [removed: grantees] [added: the] achievement of certain performance [removed: criteria,] [added: criteria by grantees,] and the achievement of consolidated EPS growth at certain levels by us, over a five-year measurement period ending December 31, 2015.
From 1993 through [removed: 2011,] [added: 2012,] we acquired [removed: 420] [added: 440] insurance intermediary operations, excluding acquired books of business (customer accounts).
| | | Number of Acquisitions | | | | | | | | Estimated Annual | | | | Net Cash | | | | Notes | | | | [added: Other | | | |] Liabilities | | | | Recorded Earn-out | | | | Aggregate Purchase | | |
| | | Asset | | | | Stock | | | | Revenues | | | | Paid | | | | Issued | | | | [added: Payable | | | |] Assumed | | | | Payable | | | | Price | | |
| 2011 | | | 37 | | | | 1 | | | $ | 88.7 | | | $ | 167.4 | | | $ | 1.2 | | | $ | [added: — | | | $ |] 15.7 | | | $ | 30.5 | | | $ | 214.8 | |
In October 2012, Kathy Colangelo was promoted to be Regional Vice President of our Wholesale Brokerage Division.
We increased revenues every year from 1993 to 2012, with the exception of 2009, when our revenues dropped 1.0%.
Additionally, beginning in the second half of 2008 and throughout 2011, there was a general decline in insurable exposure units as the consequence of the general weakening of the economy in the United States.
Beginning in the first quarter of 2012, many insurance premium rates began to slightly increase.
Additionally, in the second quarter of 2012, the general declines in insurable exposure units started to flatten and these exposures units subsequently began to gradually increase during the year.
As a result, we recorded positive internal revenue growth for each quarter of 2012 for each of our four divisions with two exceptions; the first quarter for the Retail Division and the third quarter for the National Programs Division, in which declines of only 0.7% and 3.3%, respectively, were experienced.
For 2012, our consolidated internal revenue growth rate was 2.6%.
In the event that the gradual increases in insurance premium rates and insurable exposure units that occurred in 2012 continue in 2013, we should continue to see positive quarterly internal growth rates in 2013.
The term “core commissions and fees” excludes profit-sharing contingent commissions and guaranteed supplemental commissions, and therefore represents the revenues earned directly from specific insurance policies sold, and specific fee-based services rendered.
Effective January 1, 2013, the FDIC ceased providing insurance guarantees on non-interest bearing checking accounts.
2012 was an important transition year.
After five years of experiencing negative internal growth in our core organic commissions and fees revenue as a direct result of the general weakness of the economy, we achieved a 2.6% positive internal revenue growth in 2012, which reflects a net growth of $24.9 million in core organic commissions and fees.
The net decrease of $10.0 million related primarily to: (1) $5.4 million from a change in estimated acquisition earn-out payables, (2) $1.9 million of increased interest expense related to the Arrowhead acquisition, (3) $1.7 million in increased non-cash stock-based compensation primarily due to new grants issued, and (4) $6.8 million earned by our Retail Division commissioned producers as a result of a special one-time bonus program for those whose 2012 production exceeded their 2011 production by at least 5%.
Therefore, excluding these items, income before income taxes from those offices that existed in the same time periods of 2012 and 2011 (including the new acquisitions that “folded in” to those offices) increased by only $5.8 million.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 2012 | | | 19 | | | | 1 | | | $ | 149.6 | | | $ | 483.9 | | | $ | 0.1 | | | $ | 25.4 | | | $ | 136.7 | | | $ | 21.5 | | | $ | 667.6 | |
Commission revenues related to installment billings at the Company’s subsidiary, Arrowhead, are recorded on the later of the effective date of the policy or the first installment billing.
Additionally, there have been no impairments recorded for amortizable intangible assets for the years ended December 31, 2012, 2011 and 2010.
| Core commissions and fees | | $ | 1,136,252 | | | | 19.5 | % | | $ | 950,685 | | | | 5.8 | % | | $ | 898,833 | |
| Guaranteed supplemental commissions | | | 9,146 | | | | (24.3 | )% | | | 12,079 | | | | (9.5 | )% | | | 13,352 | |
Profit-sharing contingent commissions and GSCs decreased $2.4 million or 4.4% in 2012 to $52.8 million, due primarily to $4.1 million and $1.2 million reductions in profit-sharing contingent commissions and GSCs in our Retail and Wholesale Brokerage Divisions, respectively; but these reductions were partially offset by a $3.2 million increase in our National Programs Division.
Core commissions and fees revenue increased $185.6 million on a net basis, of which approximately $171.4 million represented core commissions and fees from acquisitions that had no comparable revenues in 2011.
After taking into account divested business of $10.7 million, the remaining net increase of $24.9 million, representing net new business, reflects a 2.6% internal growth rate for core organic commissions and fees.
The employee compensation and benefit increases from these offices were primarily related to increases in staff and management salaries of $3.2 million, new salaried producers of $1.3 million, profit center bonuses of $1.4 million, health insurance costs of $1.8 million, employee 401(k)/profit-sharing contributions of $0.7 million and bonus incentives of $8.1 million primarily due to $6.8 million earned by our Retail Division commissioned producers as a result of a special one-time bonus program for those whose 2012 production exceeded their 2011 production by at least 5%.
Of the $3.0 million decrease, $2.7 million
related to reductions in office rents and related expenses, $2.2 million related to a reduction in legal expenses and $2.0 million related to lower insurance costs.
These cost savings were partially offset by increases of $1.3 million in consulting and inspection services, $1.1 million for litigation reserves, and $1.0 million in employee sales meetings.
Depreciation increased 24.1% in 2012, and decreased 2.0% in 2011.
The increase in 2012 was due primarily to the addition of fixed assets as a result of recent acquisitions.
The decrease in 2011 was the result of certain fixed assets becoming fully depreciated.
Interest expense increased $2.0 million, or 13.9%, in 2012, and decreased $0.3 million, or 2.3%, in 2011.
The 2012 increase was due primarily to the additional debt borrowed in connection with our acquisition of Arrowhead, and the 2011 decrease was due primarily to loan principal reductions.
| | | | | | | | | | | | | |
| | | 2012 | | | | 2011 | | | | | | | | | | | | | | | | | | | | | | |
| Retail(1) | | $ | 618,562 | | | $ | 571,129 | | | $ | 47,433 | | | | 8.3 | % | | $ | 38,734 | | | $ | 8,699 | | | | 1.5 | % |
| National Programs | | | 233,261 | | | | 148,841 | | | | 84,420 | | | | 56.7 | % | | | 83,281 | | | | 1,139 | | | | 0.8 | % |
| Wholesale Brokerage | | | 168,182 | | | | 155,151 | | | | 13,031 | | | | 8.4 | % | | | 3,598 | | | | 9,433 | | | | 6.1 | % |
| Services | | | 116,247 | | | | 64,875 | | | | 51,372 | | | | 79.2 | % | | | 45,783 | | | | 5,589 | | | | 8.6 | % |
| Total core commissions and fees | | $ | 1,136,252 | | | $ | 939,996 | | | $ | 196,256 | | | | 20.9 | % | | $ | 171,396 | | | $ | 24,860 | | | | 2.6 | % |
In February 2011, Anthony M.
Grippa, Thomas Keith Huval and Richard A.
Knudson, Jr. were promoted to be Regional Vice Presidents.
In April 2011, Nick Dereszynski was also promoted to be a Regional Vice President.
Additionally, in January, 2012, Anthony Strianese was promoted to be a Regional President, and Chris L.
Walker was promoted to be a Regional Executive Vice President.
We increased revenues every year from 1993 to 2008.
In 2009, our revenues dropped to $967.9 million, then increased 0.6% to $973.5 million and 4.1% to $1.014 billion in 2010 and 2011, respectively.
This was due primarily to the “soft market,” and, beginning in the second half of 2008 and throughout 2011, the decline in insurable exposure units, which further reduced our commissions and fees revenue.
Part of the decline in 2007 was the result of the increased governmental involvement in the Florida insurance marketplace, as described below in “The Florida Insurance Overview.” One industry segment that was hit especially hard during these years was the home-building industry in southern California and, to a lesser extent in Nevada, Arizona and Florida.
We had a wholesale brokerage operation that focused on placing property and casualty insurance products for that home-building segment.
The revenues from this operation were significantly adversely impacted during 2007 through 2009 by these national economic trends, and by 2010 these revenues were insignificant.
While insurance premium rates continued to decline for most lines of coverage during 2011, the rate of decline slowed, and in some cases increased for certain lines of coverages such as coastal property.
For the first time in the last five years, we are observing some upward pressure on general insurance premium rates.
For 2012, we believe that there may be a modest and gradual increase in many insurance premium rates.
Although we do not anticipate any significant increases in exposure units during 2012, we believe that the 2012 decline will be less than recent years and this lack of decline may enable us to begin to experience positive internal growth of our commissions and fees revenue at some point in 2012.
Even though our negative internal growth of our commissions and fees revenue improved over each sequential quarter for the third and fourth quarters of 2011, we do not believe that trend will necessarily continue in the first half of 2012 due to persisting inconsistencies in the insurance premium rate environment.
For the fifth consecutive year, we experienced negative internal growth of our commissions and fees revenue as a direct result of the general weakness of the economy since the second half of 2008 and the continuing “soft market.” Our core organic commissions and fees revenue which excludes the effect of recent acquisitions, profit-sharing contingencies and sales of books of business over the last twelve months, reflects a negative internal growth rate of (2.6)%, or $23.3 million of net lost revenues.
In fact, total revenues in 2011 increased 4.1% over 2010 due to the revenues from new acquisitions and the increase in other income.
The trend of increased acquisitions over the last three years continues into 2012 with our acquisition of Arrowhead, which is a national insurance program manager and one of the largest managing general agents (“MGA”) in the property and casualty insurance industry with estimated 2011 revenues of approximately $107.5 million.
This net decrease of $9.9 million reflects $16.8 million of reduced total revenues but offset by $6.9 million of continued cost savings and broad-based operational efficiencies.
Acquisition activity slowed in 2009 in part because potential sellers were unhappy with reduced agency valuations that were the consequence of lower revenues and operating profits due to the continuing “soft market” and decreasing exposure units, and therefore opted to defer the sales of their insurance agencies.
The economic outlook in 2011 and 2010 improved slightly over 2009 and as a result, certain sellers viewed 2011 and 2010 as a better time in which to join our organization, and consequently, we were able to close a greater number of acquisitions.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 2009 | | | 11 | | | | — | | | $ | 26.5 | | | $ | 40.4 | | | $ | 6.9 | | | $ | 1.8 | | | $ | 7.2 | | | $ | 56.3 | |
| | | | | | | | | | | | | | | | | | | | | |
| Core commissions and fees | | $ | 962,764 | | | | 5.5 | % | | $ | 912,185 | | | | (0.5 | )% | | $ | 917,226 | |
Profit-sharing contingent commissions increased $7.1 million to $54.7 million in 2010, with the increase primarily due to the performance of our National Programs Division.
The 2010 decrease of 4.7% in core organic commissions and fees revenue represents $42.7 million of net lost core commissions and fees revenue, of which $7.6 million was attributable to retail, wholesale brokerage and services operations based in Florida, while $21.8 million related to non-Florida retail, wholesale brokerage and services operations.
The remaining $13.3 million of net lost core commissions and fees revenue related to our National Programs Division, of which $10.7 million represented net lost business at Proctor Financial, Inc., our subsidiary which provides lender-placed insurance (“Proctor”).
The declines in core organic commissions and fees during 2010 were nearly offset by the addition of $39.2 million of core commission and fee revenues from acquired operations.
The employee compensation and benefit reductions from these offices were primarily related to reductions in staff and management salaries and bonuses of $12.6 million, off-set by an increase in compensation of new producers of $3.2 million for new salaried producers and $0.8 million for new commissioned producers, and an increase of $1.1 million in group health insurance costs.
Non-cash stock-based compensation decreased 7.0% or $0.5 million in 2010 as compared to 2009, as a result of headcount reductions.
Of the $9.9 million decrease, $3.2 million related to reduced net legal fees, $2.5 million related to reductions in office rent expense, and the remaining $4.2 million related to broad-based reductions in to travel and entertainment expenses, bad debt expenses, supplies, and postage and delivery expenses.
Of the $3.2 million reduction in net legal fees, $3.8 million related to a reimbursement by an insurance carrier of previously incurred legal costs.
Depreciation decreased 2.0% in 2011, and 4.5% in 2010.
The decreases in 2011 and 2010 were due primarily to certain fixed assets reaching their fully depreciated levels in those years.
Interest expense decreased $0.3 million, or 2.3%, in 2011, and $0.1 million, or 0.9%, in 2010 primarily as a result of principal reductions during those years.
| | | | $00000000 | | | | $00000000 | | | | $00000000 | |
An excerpt. Shown here: 40 of 238 rewritten, 40 of 135 added and 40 of 127 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations. in the FY2012 filing and the FY2011 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk.
2 rewritten, 0 added, 895 removed, 7 unchanged
The fair values of our cash and cash equivalents, restricted cash and investments, and certificates of deposit at December 31, [removed: 2011] [added: 2012] and [removed: 2010] [added: 2011] approximated their respective carrying values due to their short-term duration and, therefore, such market risk is not considered to be material.
In addition, we generally dispose of [removed: any significant] equity securities received in conjunction with an acquisition shortly after the acquisition date.
| --- | --- |
##### [Table of Contents](#toc)
| ITEM | 8. Financial Statements and Supplementary Data. |
Index to Consolidated Financial Statements
| | | | | |
| --- | --- | --- | --- | --- |
| | | Page No. | | |
| [Consolidated Statements of Income for the years ended December 31, 2011, 2010 and 2009](#tx233092_27) | | | 42 | |
| [Consolidated Balance Sheets as of December 31, 2011 and 2010](#tx233092_28) | | | 43 | |
| [Consolidated Statements of Shareholders’ Equity for the years ended December 31, 2011, 2010 and 2009](#tx233092_29) | | | 44 | |
| [Consolidated Statements of Cash Flows for the years ended December 31, 2011, 2010 and 2009](#tx233092_30) | | | 45 | |
| [Notes to Consolidated Financial Statements for the years ended December 31, 2011, 2010 and 2009](#tx233092_31) | | | 46 | |
| [Note 1: Summary of Significant Accounting Policies](#tx233092_32) | | | 46 | |
| [Note 2: Business Combinations](#tx233092_33) | | | 49 | |
| [Note 3: Goodwill](#tx233092_34) | | | 53 | |
| [Note 4: Amortizable Intangible Assets](#tx233092_35) | | | 53 | |
| [Note 5: Investments](#tx233092_36) | | | 54 | |
| [Note 6: Fixed Assets](#tx233092_37) | | | 54 | |
| [Note 7: Accrued Expenses and Other Liabilities](#tx233092_38) | | | 54 | |
| [Note 8: Long-Term Debt](#tx233092_39) | | | 55 | |
| [Note 9: Income Taxes](#tx233092_40) | | | 56 | |
| [Note 10: Employee Savings Plan](#tx233092_41) | | | 58 | |
| [Note 11: Stock-Based Compensation](#tx233092_42) | | | 58 | |
| [Note 12: Supplemental Disclosures of Cash Flow Information](#tx233092_43) | | | 61 | |
| [Note 13: Commitments and Contingencies](#tx233092_44) | | | 62 | |
| [Note 14: Quarterly Operating Results (Unaudited)](#tx233092_45) | | | 63 | |
| [Note 15: Segment Information](#tx233092_46) | | | 63 | |
| [Note 16: Subsequent Events](#tx233092_47) | | | 64 | |
| [Reports of Independent Registered Public Accounting Firm](#tx233092_48) | | | 66 | |
| [Management’s Report on Internal Control Over Financial Reporting](#tx233092_49) | | | 68 | |
BROWN & BROWN, INC.
CONSOLIDATED STATEMENTS OF
INCOME
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | Year Ended December 31, | | | | | | | | | | |
| _(in thousands, except per share data)_ | | 2011 | | | | 2010 | | | | 2009 | | |
| REVENUES | | | | | | | | | | | | |
| Commissions and fees | | $ | 1,005,962 | | | $ | 966,917 | | | $ | 964,863 | |
| Investment income | | | 1,267 | | | | 1,326 | | | | 1,161 | |
An excerpt. Shown here: all 2 rewritten, all 0 added and 40 of 895 removed. The counts are complete. For every sentence, read Item 7A. Quantitative and Qualitative Disclosures About Market Risk. in the FY2012 filing and the FY2011 filing.
Item 1. Business.
0 rewritten, 242 added, 0 removed, 0 unchanged
New section this year
| --- | --- |
General
We are a diversified insurance agency, wholesale brokerage, insurance programs and service organization with origins dating from 1939, headquartered in Daytona Beach and Tampa, Florida.
We market and sell to our customers insurance products and services, primarily in the property, casualty and employee benefits areas.
As an agent and broker, we do not assume underwriting risks.
Instead, we provide our customers with quality, non-investment insurance contracts, as well as other targeted, customized risk management products and services.
We are compensated for our services primarily by commissions paid by insurance companies and by fees paid by customers for certain services.
Commissions are usually a percentage of the premium paid by the insured.
Commission rates generally depend upon the type of insurance, the particular insurance company and the nature of the services provided by us.
In some cases, we share commissions with other agents or brokers who have acted jointly with us in a transaction.
We may also receive from an insurance company a “profit-sharing contingent commission,” which is a profit-sharing commission based primarily on underwriting results, but may also contain considerations for volume, growth and/or retention.
Fee revenues are generated primarily by: (1) our Services Division, which provides insurance-related services, including third-party claims administration and comprehensive medical utilization management services in both the workers’ compensation and all-lines liability arenas, as well as Medicare set-aside services, Social Security disability and Medicare benefits advocacy services, and catastrophe claims adjusting services, and (2) our National Programs and Wholesale Brokerage Divisions, which earn fees primarily for the issuing of insurance policies on behalf of insurance carriers.
The amount of our revenues from commissions and fees is a function of, among other factors, continued new business production, retention of existing customers, acquisitions and fluctuations in insurance premium rates and “insurable exposure units,” which are units that insurance companies use to measure or express insurance exposed to risk (such as property values, sales and payroll levels).
As of December 31, 2012, our activities were conducted in 218 locations in 37 states as follows and one office in London, England:
| | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Florida | | | 41 | | | Virginia | | | 5 | | | Missouri | | | 2 | |
| California | | | 20 | | | Connecticut | | | 4 | | | New Hampshire | | | 2 | |
| Washington | | | 16 | | | Kentucky | | | 4 | | | North Carolina | | | 2 | |
| New York | | | 15 | | | Massachusetts | | | 4 | | | Delaware | | | 1 | |
| Texas | | | 13 | | | Michigan | | | 4 | | | Hawaii | | | 1 | |
| New Jersey | | | 11 | | | Arkansas | | | 3 | | | Montana | | | 1 | |
| Georgia | | | 9 | | | Minnesota | | | 3 | | | Nevada | | | 1 | |
| Pennsylvania | | | 7 | | | New Mexico | | | 3 | | | Ohio | | | 1 | |
| Louisiana | | | 7 | | | Oregon | | | 3 | | | Utah | | | 1 | |
| Colorado | | | 6 | | | Tennessee | | | 3 | | | West Virginia | | | 1 | |
| Illinois | | | 6 | | | South Carolina | | | 3 | | | Wisconsin | | | 1 | |
| Indiana | | | 5 | | | Arizona | | | 2 | | | | | | | |
| Oklahoma | | | 5 | | | Kansas | | | 2 | | | | | | | |
##### [Table of Contents](#toc)
Industry Overview
Premium pricing within the property and casualty insurance underwriting (risk-bearing) industry has historically been cyclical, displaying a high degree of volatility based on prevailing economic and competitive conditions.
From the mid-1980s through 1999, the property and casualty insurance industry experienced a “soft market” during which the underwriting capacity of insurance companies expanded, stimulating an increase in competition and a decrease in premium rates and related commissions.
The dampening effect of this softness in rates on our revenues was somewhat offset by our acquisitions and new business production.
As a result of increasing “loss ratios” (the comparison of incurred losses plus adjustment expenses against earned premiums) of insurance companies through 1999, premium rates generally increased beginning in the first quarter of 2000 and continuing into 2003.
During 2003, increases in premium rates began to moderate and, in certain lines of insurance, premium rates decreased.
In 2004, as general premium rates continued to moderate, the insurance industry experienced the worst hurricane season since 1992 (when Hurricane Andrew hit south Florida).
The insured losses from the 2004 hurricane season were absorbed relatively easily by the insurance industry and the general insurance premium rates continued to soften during 2005.
During the third quarter of 2005, the insurance industry experienced the worst hurricane season ever recorded.
As a result of the significant losses incurred by insurance companies from these hurricanes, insurance premium rates in 2006 increased on coastal property, primarily in the southeastern region of the United States.
An excerpt. Shown here: all 0 rewritten, 40 of 242 added and all 0 removed. The counts are complete. For every sentence, read Item 1. Business. in the FY2012 filing.
Item 3. Legal Proceedings.
0 rewritten, 2 added, 0 removed, 0 unchanged
New section this year
| --- | --- |
See Note 13 to the Consolidated Financial Statements for information regarding our legal proceedings.
Cover and table of contents
34 rewritten, 3 added, 441 removed, 112 unchanged
For the fiscal year ended December 31, [removed: 2011][added: 2012]
| Florida | | [removed: ] [added: ] | | 59-0864469 |
| [removed: COMMON] [added: COMMON] STOCK, $0.10 PAR [removed: VALUE] [added: VALUE] | | [removed: NEW] [added: NEW] YORK STOCK [removed: EXCHANGE] [added: EXCHANGE] |
The aggregate market value of the voting common stock held by non-affiliates of the registrant, computed by reference to the price at which the stock was last sold on June 30, [removed: 2011] [added: 2012] (the last business day of the registrant’s most recently completed second fiscal quarter) was [removed: $2,989,330,854.][added: $3,200,673,955.]
The number of outstanding shares of the registrant’s Common Stock, $0.10 par value, as of February 20, [removed: 2012] [added: 2013] was [removed: 143,352,216][added: 143,943,521.]
Portions of Brown & Brown, Inc.’s Proxy Statement for the [removed: 2012] [added: 2013] Annual Meeting of Shareholders are incorporated by reference into Part III of this Report.
| [removed: [Part I](#tx233092_1)] [added: Part I] | | | | | | |
| Item 1. | | [removed: [Business](#tx233092_2)] [added: [Business](#tx441942_1)] | | | [removed: 4] [added: 2] | |
| Item 1A. | | [Risk [removed: Factors](#tx233092_3)] [added: Factors](#tx441942_2)] | | | [removed: 9] [added: 10] | |
| Item 1B. | | [Unresolved Staff [removed: Comments](#tx233092_4)] [added: Comments](#tx441942_3)] | | | [removed: 17] [added: 18] | |
| Item 2. | | [removed: [Properties](#tx233092_5)] [added: [Properties](#tx441942_4)] | | | [removed: 17] [added: 18] | |
| Item 3. | | [Legal [removed: Proceedings](#tx233092_6)] [added: Proceedings](#tx441942_5)] | | | [removed: 18] [added: 19] | |
| Item 4. | | [Mine Safety [removed: Disclosures](#tx233092_7)] [added: Disclosures](#tx441942_6)] | | | [removed: 18] [added: 19] | |
| [removed: [Part II](#tx233092_8)] [added: Part II] | | | | | | |
| Item 5. | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#tx233092_9)] [added: Securities](#tx441942_7)] | | | 19 | |
| Item 6. | | [Selected Financial [removed: Data](#tx233092_10)] [added: Data](#tx441942_8)] | | | 22 | |
| Item 7. | | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#tx233092_11)] [added: Operations](#tx441942_9)] | | | 23 | |
| Item 7A. | | [Quantitative and Qualitative Disclosures about Market [removed: Risk](#tx233092_12)] [added: Risk](#tx441942_10)] | | | 40 | |
| Item 8. | | [Financial Statements and Supplementary [removed: Data](#tx233092_13)] [added: Data](#tx441942_11)] | | | 41 | |
| Item 9. | | [Changes in and Disagreements With Accountants on Accounting and Financial [removed: Disclosure](#tx233092_14)] [added: Disclosure](#tx441942_12)] | | | [removed: 69] [added: 72] | |
| Item 9A. | | [Controls and [removed: Procedures](#tx233092_15)] [added: Procedures](#tx441942_13)] | | | [removed: 69] [added: 72] | |
| Item 9B. | | [Other [removed: Information](#tx233092_16)] [added: Information](#tx441942_14)] | | | [removed: 70] [added: 72] | |
| [removed: [Part III](#tx233092_17)] [added: Part III] | | | | | | |
| Item 10. | | [Directors, Executive Officers and Corporate [removed: Governance](#tx233092_18)] [added: Governance](#tx441942_15)] | | | [removed: 70] [added: 73] | |
| Item 11. | | [Executive [removed: Compensation](#tx233092_19)] [added: Compensation](#tx441942_16)] | | | [removed: 70] [added: 73] | |
| Item 12. | | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#tx233092_20)] [added: Matters](#tx441942_17)] | | | [removed: 70] [added: 73] | |
| Item 13. | | [Certain Relationships and Related Transactions, and Director [removed: Independence](#tx233092_21)] [added: Independence](#tx441942_18)] | | | [removed: 70] [added: 73] | |
| Item 14. | | [Principal Accounting Fees and [removed: Services](#tx233092_22)] [added: Services](#tx441942_19)] | | | [removed: 70] [added: 73] | |
| [removed: [Part IV](#tx233092_23)] [added: Part IV] | | | | | | |
| Item 15. | | [Exhibits, Financial Statement [removed: Schedules](#tx233092_24)] [added: Schedules](#tx441942_20)] | | | [removed: 71] [added: 74] | |
| [Exhibit [removed: Index](#tx233092_26)] [added: Index](#tx441942_22)] | | | | | | |
| | • | | The occurrence of adverse economic conditions, an adverse regulatory climate, or a disaster in California, Florida, Georgia, Indiana, [removed: Louisiana,] Massachusetts, Michigan, New Jersey, New York, Pennsylvania, Texas and Washington, because a significant portion of business written by Brown & Brown is for customers located in these states; |
| | • | | Our ability to forecast liquidity needs through at least the end of [removed: 2012;] [added: 2013;] |
| | • | | The inherent uncertainty in making estimates, judgments, and assumptions in the preparation of financial statements in accordance with generally accepted accounting principles in the United States of America [removed: (“GAAP”);] [added: (“U.S. GAAP”);] |
10-K 1 d441942d10k.htm FORM 10-K
FOR THE FISCAL YEAR ENDED DECEMBER 31, 2012
| [Signatures](#tx441942_21) | | | | | 77 | |
10-K 1 d233092d10k.htm FORM10K
##### [Table of Contents](#toc)
| --- | --- |
| [Signatures](#tx233092_25) | | | | | 74 | |
| --- | --- | --- | --- |
| ITEM | 1. Business. |
General
We are a diversified insurance agency, wholesale brokerage, insurance programs and service organization with origins dating from 1939, headquartered in Daytona Beach and Tampa, Florida.
We market and sell to our customers insurance products and services, primarily in the property, casualty and employee benefits areas.
As an agent and broker, we do not assume underwriting risks.
Instead, we provide our customers with quality, non-investment insurance contracts, as well as other targeted, customized risk management products and services.
We are compensated for our services primarily by commissions paid by insurance companies and by fees paid by customers for certain services.
Commissions are usually a percentage of the premium paid by the insured.
Commission rates generally depend upon the type of insurance, the particular insurance company and the nature of the services provided by us.
In some cases, we share commissions with other agents or brokers who have acted jointly with us in a transaction.
We may also receive from an insurance company a “profit-sharing contingent commission,” which is a profit-sharing commission based primarily on underwriting results, but may also contain considerations for volume, growth and/or retention.
Fee revenues are generated primarily by: (1) our Services Division, which provides insurance-related services, including third-party claims administration and comprehensive medical utilization management services in both the workers’ compensation and all-lines liability arenas, as well as Medicare set-aside services and Social Security disability and Medicare benefits advocacy services, and (2) our National Programs and Wholesale Brokerage Divisions, which earn fees primarily for the issuing of insurance policies on behalf of insurance carriers.
The amount of our revenues from commissions and fees is a function of, among other factors, continued new business production, retention of existing customers, acquisitions and fluctuations in insurance premium rates and “insurable exposure units,” which are units that insurance companies use to measure or express insurance exposed to risk (such as property values, sales and payroll levels).
As of December 31, 2011, our activities were conducted in 230 locations in 36 states as follows and one office in London, England:
| | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Florida | | | 42 | | | Oklahoma | | | 5 | | | South Carolina | | | 3 | |
| Texas | | | 17 | | | Connecticut | | | 4 | | | North Carolina | | | 2 | |
| New York | | | 15 | | | Massachusetts | | | 4 | | | Wisconsin | | | 2 | |
| Washington | | | 15 | | | Michigan | | | 4 | | | Delaware | | | 1 | |
| California | | | 14 | | | Tennessee | | | 4 | | | Hawaii | | | 1 | |
| New Jersey | | | 12 | | | Virginia | | | 4 | | | Kansas | | | 1 | |
| Georgia | | | 10 | | | Arizona | | | 3 | | | Missouri | | | 1 | |
| Pennsylvania | | | 10 | | | Arkansas | | | 3 | | | Nevada | | | 1 | |
| Louisiana | | | 9 | | | Minnesota | | | 3 | | | Ohio | | | 1 | |
| Colorado | | | 7 | | | Montana | | | 3 | | | West Virginia | | | 1 | |
| Indiana | | | 7 | | | New Hampshire | | | 3 | | | | | | | |
| Illinois | | | 6 | | | New Mexico | | | 3 | | | | | | | |
| Kentucky | | | 6 | | | Oregon | | | 3 | | | | | | | |
Arrowhead Acquisition
On January 9, 2012, we completed the acquisition of Arrowhead General Insurance Agency, Inc. (“Arrowhead”), a national insurance program manager and one of the largest managing general agents (“MGA”) in the property and casualty insurance industry, pursuant to a merger agreement dated December 15, 2011 (the “Merger Agreement”).
Under the Merger Agreement, the total cash purchase price of $395.0 million is subject to adjustments for options to purchase shares of Arrowhead’s common stock, working capital, sharing of net operating tax losses, Arrowhead’s preferred stock units, transaction expenses, and closing debt.
In addition, within 60 days following the third anniversary of the acquisition’s closing date, we will pay to certain persons who were Arrowhead equityholders as of the closing date additional earn-out payments equal, collectively, to $5.0 million, subject to certain adjustments based on the” cumulative EBITDA” of Arrowhead and all of its subsidiaries, as calculated under the Merger Agreement, during the final year of the three-year period following the acquisition’s closing date.
Industry Overview
Premium pricing within the property and casualty insurance underwriting (risk-bearing) industry has historically been cyclical, displaying a high degree of volatility based on prevailing economic and competitive conditions.
An excerpt. Shown here: all 34 rewritten, all 3 added and 40 of 441 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2012 filing and the FY2011 filing.
Item 1B. Unresolved Staff Comments.
0 rewritten, 2 added, 0 removed, 0 unchanged
New section this year
| --- | --- |
None.
Item 2. Properties.
0 rewritten, 14 added, 0 removed, 0 unchanged
New section this year
| --- | --- |
We lease our executive offices, which are located at 220 South Ridgewood Avenue, Daytona Beach, Florida 32114, and 655 N.
Franklin St, Suite 1900, Tampa, Florida 33602.
We lease offices at each of our 219 locations, with the exception of Dansville and Jamestown, New York, where we own the buildings in which our offices are located.
We also own an airplane hanger in Daytona Beach, Florida.
There are no outstanding mortgages on our owned properties.
Our operating leases expire on various dates.
These leases generally contain renewal options and rent escalation clauses based on increases in the lessors’ operating expenses and other charges.
We expect that most leases will be renewed or replaced upon expiration.
We believe that our facilities are suitable and adequate for present purposes, and that the productive capacity in such facilities is substantially being utilized.
From time to time, we may have unused space and seek to sublet such space to third parties, depending on the demand for office space in the locations involved.
In the future, we may need to purchase, build or lease additional facilities to meet the requirements projected in our long-term business plan.
See Note 13 to the Consolidated Financial Statements for additional information on our lease commitments.
##### [Table of Contents](#toc)
Item 4. Mine Safety Disclosures.
0 rewritten, 1 added, 1 removed, 2 unchanged
| --- | --- |
##### [Table of Contents](#toc)
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
19 rewritten, 15 added, 16 removed, 41 unchanged
| | | High | | | | Low | | | | [removed: Cash Dividends Per Common Share] [added: Cash Dividends Per Common Share] | | |
On February [removed: 22, 2012,] [added: 20, 2013,] there were [removed: 143,352,216] [added: 143,943,521] shares of our common stock outstanding, held by approximately [removed: 1,270] [added: 1,200] shareholders of record.
We did not repurchase any shares of our common stock under the repurchase [removed: plan during the fourth quarter of 2011.][added: plan.]
The following table sets forth information as of December 31, [removed: 2011,] [added: 2012,] with respect to compensation plans under which the Company’s equity securities are authorized for issuance:
| Plan Category | | Number of securities [removed: to be] [added: to be] issued upon exercise [removed: of outstanding options, warrants] [added: of outstanding options, warrants] and rights (a)(1) | | | | [removed: Weighted-average exercise] [added: Weighted-average exercise] price [removed: of outstanding options, warrants] [added: of outstanding options, warrants] and rights (b)(2) | | | | Number of [removed: securities remaining] [added: securities remaining] available [removed: for future] [added: for future] issuance [removed: under equity] [added: under equity] compensation [removed: plans (excluding securities reflected] [added: plans (excluding securities reflected] in column (a)) (c)(3) | | |
| Brown & Brown, Inc. 2000 Incentive Stock Option Plan | | | [removed: 1,384,537] [added: 738,792] | | | $ | [removed: 17.58] [added: 18.39] | | | | — | |
| Brown & Brown, Inc. 2010 Stock Incentive Plan | | | N/A | | | | N/A | | | | [removed: 4,718,044] [added: 4,455,517] | |
| Brown & Brown, Inc. 1990 Employee Stock Purchase Plan | | | N/A | | | | N/A | | | | [removed: 2,297,258] [added: 1,734,510] | |
| (1) | In addition to the number of securities listed in this column, [removed: 3,382,677] [added: 2,431,913] shares are issuable upon the vesting of restricted stock granted under the Brown & Brown, Inc. [removed: Stock] Performance [added: Stock] Plan and the Brown & Brown, Inc. 2010 Stock Incentive Plan, which represents the maximum number of shares that can vest based on the achievement of certain performance criteria. |
| (3) | All of the shares available for future issuance under the Brown & Brown, Inc. 2000 Incentive Stock Option Plan, the Brown & Brown, Inc. [removed: Stock] Performance [added: Stock] Plan, and the Brown & Brown, Inc. 2010 Stock Incentive Plan may be issued in connection with options, warrants, rights, restricted stock, or other stock-based awards. |
We did not sell any unregistered securities during [removed: 2011.][added: 2012.]
The following table presents information with respect to our purchases of our common stock during the three months ended December 31, [removed: 2011.][added: 2012.]
| Period | | Total Number [removed: of Shares] [added: of Shares] Purchased(1) | | | | Average Price [removed: Paid per] [added: Paid per] Share | | | | Total Number [removed: of Shares Purchased as] [added: of Shares Purchased as] Part [removed: of Publicly Announced Plans] [added: of Publicly Announced Plans] or Programs | | | | Approximate [removed: Dollar Value] [added: Dollar Value] of Shares [removed: that May] [added: that May] Yet [removed: Be Purchased] [added: Be Purchased] Under [removed: the Plans] [added: the Plans] or Programs | | |
| (1) | All of the shares reported above as purchased are attributable to shares withheld for employees’ payroll taxes and withholding taxes pertaining to the vesting of restricted shares awarded under our Performance Stock [added: Plan and Incentive Stock Option] Plan. |
The returns of each company have been weighted according to such companies’ respective stock market capitalizations as of December 31, [removed: 2006] [added: 2007] for the purposes of arriving at a peer group average.
The total return calculations are based upon an assumed $100 investment on December 31, [removed: 2006,] [added: 2007,] with all dividends reinvested.
[removed: 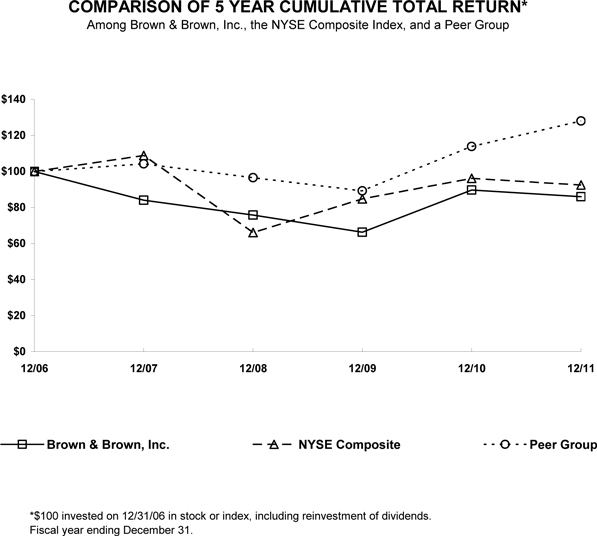][added: 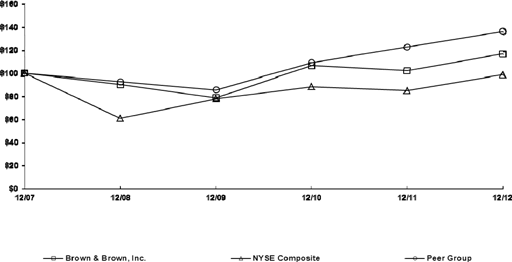]
| | | [removed: FISCAL YEAR] [added: YEAR] ENDING | | | | | | | | | | | | | | | | | | | | | | |
| COMPANY/INDEX/MARKET | | [removed: 12/31/2006] [added: 12/31/2007] | | | | [removed: 12/30/2007] [added: 12/31/2008] | | | | [removed: 12/29/2008] [added: 12/31/2009] | | | | [removed: 12/31/2009] [added: 12/31/2010] | | | | [removed: 12/31/2010] [added: 12/31/2011] | | | | [removed: 12/31/2011] [added: 12/31/2012] | | |
| 2012 | | | | | | | | | | | | |
| First Quarter | | $ | 25.00 | | | $ | 21.85 | | | $ | 0.085 | |
| Second Quarter | | $ | 27.32 | | | $ | 23.42 | | | $ | 0.085 | |
| Third Quarter | | $ | 28.17 | | | $ | 24.71 | | | $ | 0.085 | |
| Fourth Quarter | | $ | 27.31 | | | $ | 24.88 | | | $ | 0.09 | |
| Total | | | 738,792 | | | $ | 18.39 | | | | 6,190,027 | |
| October 1, 2012 to October 31, 2012 | | | — | | | $ | — | | | | — | | | $ | — | |
| November 1, 2012 to November 30, 2012 | | | 323 | | | $ | 26.08 | | | | — | | | $ | — | |
| December 1, 2012 to December 31, 2012 | | | 585,815 | | | $ | 25.86 | | | | — | | | $ | — | |
| Total | | | 586,138 | | | $ | 25.86 | | | | — | | | $ | — | |
COMPARISON OF 5 YEAR CUMULATIVE TOTAL RETURN
Among Brown & Brown, Inc., the NYSE Composite Index, and a Peer Group
| Brown & Brown, Inc. | | $ | 100.00 | | | $ | 90.20 | | | $ | 78.80 | | | $ | 106.63 | | | $ | 102.28 | | | $ | 116.65 | |
| NYSE Composite Index | | $ | 100.00 | | | $ | 60.74 | | | $ | 77.92 | | | $ | 88.36 | | | $ | 84.96 | | | $ | 98.55 | |
| Peer Group | | $ | 100.00 | | | $ | 92.58 | | | $ | 85.59 | | | $ | 109.22 | | | $ | 122.80 | | | $ | 136.25 | |
| --- | --- |
| 2010 | | | | | | | | | | | | |
| First Quarter | | $ | 18.10 | | | $ | 16.32 | | | $ | 0.0775 | |
| Second Quarter | | $ | 20.45 | | | $ | 17.65 | (1) | | $ | 0.0775 | |
| Third Quarter | | $ | 20.53 | | | $ | 18.85 | | | $ | 0.0775 | |
| Fourth Quarter | | $ | 24.39 | | | $ | 19.88 | | | $ | 0.08 | |
| (1) | Excluding the official closing stock price of $8.04 on May 6, 2010, the date of the NYSE “Flash Crash.” |
We are under no commitment or obligation to repurchase any particular amount of our common stock under the plan, and we may suspend the repurchase plan at any time at our discretion.
| Total | | | 1,384,537 | | | $ | 17.58 | | | | 7,015,302 | |
| October 1, 2011 to October 31, 2011 | | | 4,204 | | | $ | 21.35 | | | | — | | | $ | — | |
| November 1, 2011 to November 30, 2011 | | | 505 | | | $ | 21.46 | | | | — | | | $ | — | |
| December 1, 2011 to December 31, 2011 | | | 17,734 | | | $ | 21.82 | | | | — | | | $ | — | |
| Total | | | 22,443 | | | $ | 21.73 | | | | — | | | $ | — | |
| Brown & Brown, Inc. | | $ | 100.00 | | | $ | 84.10 | | | $ | 75.86 | | | $ | 66.27 | | | $ | 89.68 | | | $ | 86.01 | |
| NYSE Composite Index | | $ | 100.00 | | | $ | 108.87 | | | $ | 66.13 | | | $ | 84.83 | | | $ | 96.19 | | | $ | 92.50 | |
| Peer Group | | $ | 100.00 | | | $ | 104.28 | | | $ | 96.54 | | | $ | 89.25 | | | $ | 113.89 | | | $ | 128.05 | |
Item 6. Selected Financial Data.
31 rewritten, 1 added, 4 removed, 21 unchanged
The following selected Consolidated Financial Data for each of the five fiscal years in the period ended December 31, [removed: 2011] [added: 2012] have been derived from our Consolidated Financial Statements.
| | [removed: 2011] [added: 2012] | | | | [removed: 2010] [added: 2011] | | | | [removed: 2009] [added: 2010] | | | | [removed: 2008] [added: 2009] | | | | [removed: 2007] [added: 2008] | | | |
| Commissions and fees | | $ | [removed: 1,005,962] [added: 1,189,081] | | | $ | [removed: 966,917] [added: 1,005,962] | | | $ | [removed: 964,863] [added: 966,917] | | | $ | [removed: 965,983] [added: 964,863] | | | $ | [removed: 914,650] [added: 965,983] | |
| Investment income | | | [removed: 1,267] [added: 797] | | | | [removed: 1,326] [added: 1,267] | | | | [removed: 1,161] [added: 1,326] | | | | [removed: 6,079] [added: 1,161] | | | | [removed: 30,494] [added: 6,079] | [removed: (1)] |
| Other income, net | | | [removed: 6,313] [added: 10,154] | | | | [removed: 5,249] [added: 6,313] | | | | [removed: 1,853] [added: 5,249] | | | | [removed: 5,492] [added: 1,853] | | | | [removed: 14,523] [added: 5,492] | |
| Total revenues | | | [removed: 1,013,542] [added: 1,200,032] | | | | [removed: 973,492] [added: 1,013,542] | | | | [removed: 967,877] [added: 973,492] | | | | [removed: 977,554] [added: 967,877] | | | | [removed: 959,667] [added: 977,554] | |
| Employee compensation and benefits | | | [removed: 508,675] [added: 608,506] | | | | [removed: 487,820] [added: 508,675] | | | | [removed: 484,680] [added: 487,820] | | | | [removed: 485,783] [added: 484,680] | | | | [removed: 444,101] [added: 485,783] | |
| Non-cash stock-based compensation | | | [removed: 11,194] [added: 15,865] | | | | [removed: 6,845] [added: 11,194] | | | | [removed: 7,358] [added: 6,845] | | | | [removed: 7,314] [added: 7,358] | | | | [removed: 5,667] [added: 7,314] | |
| Other operating expenses | | | [removed: 144,079] [added: 174,389] | | | | [removed: 135,851] [added: 144,079] | | | | [removed: 143,389] [added: 135,851] | | | | [removed: 137,352] [added: 143,389] | | | | [removed: 131,371] [added: 137,352] | |
| Amortization | | | [removed: 54,755] [added: 63,573] | | | | [removed: 51,442] [added: 54,755] | | | | [removed: 49,857] [added: 51,442] | | | | [removed: 46,631] [added: 49,857] | | | | [removed: 40,436] [added: 46,631] | |
| Depreciation | | | [removed: 12,392] [added: 15,373] | | | | [removed: 12,639] [added: 12,392] | | | | [removed: 13,240] [added: 12,639] | | | | [removed: 13,286] [added: 13,240] | | | | [removed: 12,763] [added: 13,286] | |
| Interest | | | [removed: 14,132] [added: 16,097] | | | | [removed: 14,471] [added: 14,132] | | | | [removed: 14,599] [added: 14,471] | | | | [removed: 14,690] [added: 14,599] | | | | [removed: 13,802] [added: 14,690] | |
| Change in estimated acquisition earn-out payables | | | [removed: (2,206] [added: 1,418] | [removed: )] | | | [removed: (1,674] [added: (2,206] | ) | | | [removed: —] [added: (1,674] | [added: )] | | | — | | | | — | |
| Total expenses | | | [removed: 743,021] [added: 895,221] | | | | [removed: 707,394] [added: 743,021] | | | | [removed: 713,123] [added: 707,394] | | | | [removed: 705,056] [added: 713,123] | | | | [removed: 648,140] [added: 705,056] | |
| Income before income taxes | | | [removed: 270,521] [added: 304,811] | | | | [removed: 266,098] [added: 270,521] | | | | [removed: 254,754] [added: 266,098] | | | | [removed: 272,498] [added: 254,754] | | | | [removed: 311,527] [added: 272,498] | |
| Income taxes | | | [removed: 106,526] [added: 120,766] | | | | [removed: 104,346] [added: 106,526] | | | | [removed: 101,460] [added: 104,346] | | | | [removed: 106,374] [added: 101,460] | | | | [removed: 120,568] [added: 106,374] | |
| Net income | | $ | [removed: 163,995] [added: 184,045] | | | $ | [removed: 161,752] [added: 163,995] | | | $ | [removed: 153,294] [added: 161,752] | | | $ | [removed: 166,124] [added: 153,294] | | | $ | [removed: 190,959] [added: 166,124] | |
| Net income per share — diluted | | $ | [removed: 1.13] [added: 1.26] | | | $ | [removed: 1.12] [added: 1.13] | | | $ | [removed: 1.08] [added: 1.12] | | | $ | [removed: 1.17] [added: 1.08] | | | $ | [removed: 1.35] [added: 1.17] | |
| Weighted average number of shares outstanding — diluted | | | [removed: 140,264] [added: 142,010] | | | | [removed: 139,318] [added: 140,264] | | | | [removed: 137,507] [added: 139,318] | | | | [removed: 136,884] [added: 137,507] | | | | [removed: 136,357] [added: 136,884] | |
| Dividends declared per share | | $ | [removed: 0.3250] [added: 0.3450] | | | $ | [removed: 0.3125] [added: 0.3250] | | | $ | [removed: 0.3025] [added: 0.3125] | | | $ | [removed: 0.2850] [added: 0.3025] | | | $ | [removed: 0.2500] [added: 0.2850] | |
| Total assets | | $ | [removed: 2,607,011] [added: 3,128,058] | | | $ | [removed: 2,400,814] [added: 2,607,011] | | | $ | [removed: 2,224,226] [added: 2,400,814] | | | $ | [removed: 2,119,580] [added: 2,224,226] | | | $ | [removed: 1,960,659] [added: 2,119,580] | |
| Long-term debt | | $ | [removed: 250,033] [added: 450,000] | | | $ | [removed: 250,067] [added: 250,033] | | | $ | [removed: 250,209] [added: 250,067] | | | $ | [removed: 253,616] [added: 250,209] | | | $ | [removed: 227,707] [added: 253,616] | |
| Total shareholders’ equity [removed: (2)] | | $ | [removed: 1,643,963] [added: 1,807,333] | | | $ | [removed: 1,506,344] [added: 1,643,963] | | | $ | [removed: 1,369,874] [added: 1,506,344] | | | $ | [removed: 1,241,741] [added: 1,369,874] | | | $ | [removed: 1,097,458] [added: 1,241,741] | |
| Total shares outstanding at year-end | | | [removed: 143,352] [added: 143,878] | | | | [removed: 142,795] [added: 143,352] | | | | [removed: 142,076] [added: 142,795] | | | | [removed: 141,544] [added: 142,076] | | | | [removed: 140,673] [added: 141,544] | |
| Number of full-time equivalent employees at year-end | | | [removed: 5,557] [added: 6,438] | | | | [removed: 5,286] [added: 5,557] | | | | [removed: 5,206] [added: 5,286] | | | | [removed: 5,398] [added: 5,206] | | | | [removed: 5,047] [added: 5,398] | |
| Total revenues per average number of employees [removed: (3)] [added: (1)] | | $ | [removed: 186,949] [added: 191,729] | [added: (2)] | | $ | [removed: 185,568] [added: 186,949] | | | $ | [removed: 182,549] [added: 185,568] | | | $ | [removed: 187,181] [added: 182,549] | | | $ | [removed: 196,251] [added: 187,181] | |
| Stock price at year-end | | $ | [removed: 22.63] [added: 25.46] | | | $ | [removed: 23.94] [added: 22.63] | | | $ | [removed: 17.97] [added: 23.94] | | | $ | [removed: 20.90] [added: 17.97] | | | $ | [removed: 23.50] [added: 20.90] | |
| Stock price earnings multiple at year-end [removed: (4)] [added: (3)] | | | [removed: 20.03] [added: 20.21] | | | | [removed: 21.38] [added: 20.03] | | | | [removed: 16.64] [added: 21.38] | | | | [removed: 17.86] [added: 16.64] | | | | [removed: 17.41] [added: 17.86] | |
| Return on beginning shareholders’ equity [removed: (5)] [added: (4)] | | | 11 | % | | | [removed: 12] [added: 11] | % | | | 12 | % | | | [removed: 15] [added: 12] | % | | | [removed: 21] [added: 15] | % |
| [removed: (3)] [added: (1)] | Represents total revenues divided by the average of the number of full-time equivalent employees at the beginning of the year and the number of full-time equivalent employees at the end of the year. |
| [removed: (5)] [added: (3)] | Stock price at year-end divided by net income per share-diluted. |
| (2) | Of the 881 increase in the number of full-time equivalent employees from 2011 to 2012, 523 employees related to the January 9, 2012 acquisition of Arrowhead, and therefore, are considered to be full-time equivalent as of January 1, 2012. Thus, the average number of full-time equivalent employees for 2012 is considered to be 6,259. |
| --- | --- |
| | | | | | | | | | | | | | | | | | | | | |
| (1) | Includes an $18,664 gain on the sale of our investment in Rock-Tenn Company. |
| (2) | Shareholders’ equity as of December 31, 2011, 2010, 2009, 2008, and 2007 included $7, $7, $5, $13, and $13, respectively, as a result of the Company’s accounting for certain equity securities and interest rate swap agreement. |
Item 8. Financial Statements and Supplementary Data.
0 rewritten, 1,201 added, 0 removed, 0 unchanged
New section this year
| --- | --- |
Index to Consolidated Financial Statements
| | | | | |
| --- | --- | --- | --- | --- |
| | | Page No. | | |
| [Consolidated Statements of Income for the years ended December 31, 2012, 2011 and 2010](#tx441942_23) | | | 42 | |
| [Consolidated Balance Sheets as of December 31, 2012 and 2011](#tx441942_24) | | | 43 | |
| [Consolidated Statements of Shareholders’ Equity for the years ended December 31, 2012, 2011 and 2010](#tx441942_25) | | | 44 | |
| [Consolidated Statements of Cash Flows for the years ended December 31, 2012, 2011 and 2010](#tx441942_26) | | | 45 | |
| [Notes to Consolidated Financial Statements for the years ended December 31, 2012, 2011 and 2010](#tx441942_27) | | | 46 | |
| [Note 1: Summary of Significant Accounting Policies](#tx441942_28) | | | 46 | |
| [Note 2: Business Combinations](#tx441942_29) | | | 49 | |
| [Note 3: Goodwill](#tx441942_30) | | | 56 | |
| [Note 4: Amortizable Intangible Assets](#tx441942_31) | | | 57 | |
| [Note 5: Investments](#tx441942_32) | | | 57 | |
| [Note 6: Fixed Assets](#tx441942_33) | | | 58 | |
| [Note 7: Accrued Expenses and Other Liabilities](#tx441942_34) | | | 58 | |
| [Note 8: Long-Term Debt](#tx441942_35) | | | 58 | |
| [Note 9: Income Taxes](#tx441942_36) | | | 60 | |
| [Note 10: Employee Savings Plan](#tx441942_37) | | | 62 | |
| [Note 11: Stock-Based Compensation](#tx441942_38) | | | 62 | |
| [Note 12: Supplemental Disclosures of Cash Flow Information](#tx441942_39) | | | 66 | |
| [Note 13: Commitments and Contingencies](#tx441942_40) | | | 66 | |
| [Note 14: Quarterly Operating Results (Unaudited)](#tx441942_41) | | | 67 | |
| [Note 15: Segment Information](#tx441942_42) | | | 68 | |
| | | | | |
| [Reports of Independent Registered Public Accounting Firm](#tx441942_43) | | | 69 | |
| [Management’s Report on Internal Control Over Financial Reporting](#tx441942_44) | | | 71 | |
##### [Table of Contents](#toc)
BROWN & BROWN, INC.
CONSOLIDATED STATEMENTS OF INCOME
| | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | Year Ended December 31, | | | | | | | | | | |
| _(in thousands, except per share data)_ | | 2012 | | | | 2011 | | | | 2010 | | |
| REVENUES | | | | | | | | | | | | |
| Commissions and fees | | $ | 1,189,081 | | | $ | 1,005,962 | | | $ | 966,917 | |
| Investment income | | | 797 | | | | 1,267 | | | | 1,326 | |
| Other income, net | | | 10,154 | | | | 6,313 | | | | 5,249 | |
| | | | | | | | | | | | | |
An excerpt. Shown here: all 0 rewritten, 40 of 1,201 added and all 0 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data. in the FY2012 filing.
Item 9. Changes in and Disagreements With Accountants on Accounting and Financial Disclosure.
1 rewritten, 0 added, 0 removed, 1 unchanged
There were no changes in or disagreements with accountants on accounting and financial disclosure in [removed: 2011.][added: 2012.]
Item 9A. Controls and Procedures.
2 rewritten, 6 added, 2 removed, 18 unchanged
We carried out an evaluation required by Rules 13a-15 and 15d-15 under the Exchange Act (the “Evaluation”), under the supervision and with the participation of our Chief Executive Officer (“CEO”) and Chief Financial Officer (“CFO”), of the effectiveness of our disclosure controls and procedures as defined in Rule 13a-15 and 15d-15 under the Exchange Act (“Disclosure Controls”) as of December 31, [removed: 2011.][added: 2012.]
There has not been any change in our internal control over financial reporting identified in connection with the Evaluation that occurred during the quarter ended December 31, [removed: 2011] [added: 2012] that has materially affected, or is reasonably likely to materially affect, those controls.
In conducting Brown & Brown’s evaluation of the effectiveness of its internal controls over financial reporting, Brown & Brown has excluded the following acquisitions completed by Brown & Brown during 2012: Arrowhead General Insurance Agency Superholding Corporation, Richard W.
Endlar Insurance Agency, Inc., Texas Security General Insurance Agency, Inc., Edgren Hecker & Lemmon Insurance, Inc. and Rowlands & Barranca Agency, Inc. (collectively the “2012 Excluded Acquisitions”), which were acquired during 2012 and whose financial statements constitute 0.2% and 19.0% of net and total assets, respectively, 10.1% of revenues, and 10.4% of net income of the consolidated financial statement amounts as of and for the year ended December 31, 2012.
Management’s Report on Internal Control Over Financial Reporting
We assessed the effectiveness of our internal control over financial reporting as of December 31, 2012.
Management’s report on internal control over financial reporting as of December 31, 2012 is incorporated herein at Item 8.
Deloitte & Touche LLP, an independent registered public accounting firm, issued an audit report on the effectiveness of our internal control over financial reporting as of December 31, 2012, which is incorporated herein at Item 8.
In conducting Brown & Brown’s evaluation of the effectiveness of its internal controls over financial reporting, Brown & Brown has excluded the following acquisitions completed by Brown & Brown during 2011: Balcos Insurance, Inc., United Benefit Services Insurance Agency LLC et al., Fitzharris Agency, Inc. et al, Public Employee Benefits Solution, LLC, Sitzmann, Morris & Lavis Insurance Agency, Inc. et al., Snapper Shuler Kenner, Inc. et al, Industry Consulting Group, Inc. and Colonial Claims Corporation et al (collectively the “2011 Excluded Acquisitions”), which were acquired during 2011 and whose financial statements constitute 6.7% and 5.5% of net and total assets, respectively, 1.8% of revenues, and 2.7% of net income of the consolidated financial statement amounts as of and for the year ended December 31, 2011.
##### [Table of Contents](#toc)
Item 9B. Other Information.
0 rewritten, 1 added, 0 removed, 3 unchanged
##### [Table of Contents](#toc)
Item 10. Directors, Executive Officers and Corporate Governance.
3 rewritten, 0 added, 0 removed, 1 unchanged
The information required by this item regarding directors and executive officers is incorporated herein by reference to our definitive Proxy Statement to be filed with the SEC in connection with the Annual Meeting of Shareholders to be held in [removed: 2012] [added: 2013] (the [removed: “2012] [added: “2013] Proxy Statement”) under the headings “Management” and “Section 16(a) Beneficial Ownership Reporting.” We have adopted a code of ethics that applies to our principal executive officer, principal financial officer, and controller.
A copy of our Code of Ethics for our Chief Executive Officer and our Senior Financial Officers and a copy of our Code of Business Conduct and Ethics applicable to all employees are posted on our Internet website, at www.bbinsurance.com, and are also available upon written request directed to Corporate Secretary, Brown & Brown, Inc., [removed: 3101 West Martin Luther King Jr. Blvd.,] [added: 655 North Franklin St.,] Suite [removed: 400,] [added: 1900,] Tampa, Florida [removed: 33607,] [added: 33602,] or by telephone request to (813) 222-4277.
Any [added: approved] amendments to, or waiver [removed: from,] [added: of,] any provision of the Code of Business Conduct and Ethics will be posted on our website at the above address.
Item 11. Executive Compensation.
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required by this item is incorporated herein by reference to the [removed: 2012] [added: 2013] Proxy Statement under the heading “Executive Compensation.”
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
1 rewritten, 1 added, 0 removed, 1 unchanged
The information required by this item is incorporated herein by reference to the [removed: 2012] [added: 2013] Proxy Statement under the heading “Security Ownership of Management and Certain Beneficial Owners.”
Information regarding equity compensation plans required by this item is included in Item 5 of Part II of this report and is incorporated into this item by reference.
Item 13. Certain Relationships and Related Transactions, and Director Independence.
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required by this item is incorporated herein by reference to the [removed: 2012] [added: 2013] Proxy Statement under the heading “Management — Certain Relationships and Related Transactions.”
Item 14. Principal Accounting Fees and Services.
1 rewritten, 0 added, 0 removed, 3 unchanged
The information required by this item is incorporated herein by reference to the [removed: 2012] [added: 2013] Proxy Statement under the heading “Fees Paid to Deloitte & Touche LLP.”
Item 15. Exhibits and Financial Statement Schedules.
18 rewritten, 18 added, 16 removed, 119 unchanged
| 10.1(a) | | Lease of the Registrant for office space at 220 South Ridgewood Avenue, Daytona Beach, Florida dated August 15, 1987 (incorporated by reference to Exhibit 10a(3) to Form 10-K for the year ended December 31, 1993), as amended by Letter Agreement dated June 26, 1995; First Amendment to Lease dated August 2, 1999; Second Amendment to Lease dated December 11, 2001; Third Amendment to Lease dated August 8, 2002; Fourth Amendment to Lease dated October 26, 2004 (incorporated by reference to Exhibit 10.2(a) to Form 10-K for the year ended December 31, 2005); Fifth Amendment to Lease dated 2006 (incorporated by reference to Exhibit 10.1(a) to Form 10-K for the year ended December 31, 2010); [removed: and] Sixth Amendment to Lease dated August 17, 2009 (incorporated by reference to Exhibit 10.1(a) to Form 10-K for the year ended December 31, [removed: 2010).] [added: 2010); Seventh Amendment to Lease dated March 25, 2011; Eighth Amendment to Lease dated April 16, 2012; and Ninth Amendment to Lease dated December 5, 2012.] |
| 10.4(d) | | [removed: Separation Agreement and Release] [added: Employment Agreement,] dated [removed: January 12, 2011] [added: as of November 7, 1997,] between the Registrant and [removed: Thomas E. Riley] [added: J. Scott Penny] (incorporated by reference to Exhibit [removed: 10.1] [added: 10.4(e)] to Form [removed: 8-K filed January 19,] [added: 10-K for the year ended December 31,] 2011). |
| [removed: 10.4(e)] [added: 10.4(g)] | | Employment Agreement, dated as of [removed: November 7,] [added: October 27,] 1997, between the Registrant and [removed: J. Scott Penny.] [added: Charles H. Lydecker.] |
| [removed: 10.4(f)] [added: 10.4(e)] | | Employment Agreement, dated as of January 12, 1998, between the Registrant and C. Roy Bridges, as amended by the amendment effective May 10, 2011 (incorporated by reference to Exhibit 10.4 to Form 10-Q for the quarter ended March 31, 2011). |
| [removed: 10.4(g)] [added: 10.4(f)] | | Performance Cash Incentive Award Agreement between the Registrant and C. Roy Bridges dated May 10, 2011 (incorporated by reference to Exhibit 10.3 to Form 10-Q for the quarter ended March 31, 2011). |
| 10.9 | | [removed: First Amendment to] Amended and Restated Revolving and Term Loan [added: Credit] Agreement dated [removed: and effective July 15, 2004,] [added: as of January 9, 2012] by and between the Registrant and SunTrust Bank (incorporated by reference to Exhibit [removed: 4.2] [added: 10.17] to Form [removed: 10-Q] [added: 10-K] for the [removed: quarter] [added: year] ended [removed: June 30, 2004).] [added: December 31, 2011).] |
| [removed: 10.10] [added: 10.12] | | [removed: Amended and Restated Revolving and] Term Loan Agreement dated as of January [removed: 3, 2001] [added: 26, 2012] by and [removed: among] [added: between] the Registrant and [removed: SunTrust Bank] [added: JPMorgan Chase Bank, N.A] (incorporated by reference to Exhibit [removed: 4a] [added: 10.20] to Form 10-K for the year ended December 31, [removed: 2000).] [added: 2011).] |
| [removed: 10.12] [added: 10.11] | | [removed: Second Amendment to Amended and Restated Revolving and Term Loan] [added: Letter] Agreement dated [removed: as of December 22, 2006] [added: January 9, 2012] by and between [removed: the] Registrant and [removed: SunTrust Bank] [added: JPMorgan Chase Bank, N.A] (incorporated by reference to Exhibit [removed: 10.15] [added: 10.19] to Form 10-K for the year ended December 31, [removed: 2006).] [added: 2011).] |
| [removed: 10.13] [added: 10.10] | | [removed: Third Amendment to Amended and Restated Revolving and Term Loan Agreement] [added: Promissory Note] dated [removed: as of] January [removed: 30, 2007] [added: 9, 2012,] by and between [removed: the] Registrant and [removed: SunTrust Bank] [added: JPMorgan Chase Bank, N.A] (incorporated by reference to Exhibit [removed: 10.17] [added: 10.18] to Form 10-K for the year ended December 31, [removed: 2006).] [added: 2011).] |
| [removed: 10.15] [added: 10.8] | | Form of Performance-Based Stock Grant Agreement under 2010 Stock Incentive Plan (incorporated by reference to Exhibit 10.16 to Form 10-K for the year ended December 31, 2010). |
| [removed: 10.16] [added: 10.13] | | Merger Agreement, dated December 15, 2011, among the Registrant, Pacific Merger Corp., a [removed: wholly owned] [added: wholly-owned] subsidiary of the Registrant, Arrowhead General Insurance Agency Superholding Corporation, and Spectrum Equity Investors V, L.P. [added: (incorporated by reference to Exhibit 10.16 to Form 10-K for the year ended December 31, 2011).] |
| 31.1 | | Rule 13a-14(a)/15d-14(a) Certification by the [removed: Acting] Chief Executive Officer of the Registrant. |
| 32.1 | | Section 1350 Certification by the [removed: Acting] Chief Executive Officer of the Registrant. |
| | | | | | | [removed: _Acting Chief] [added: _Chief] Executive Officer_ |
| /s/ J. [removed: Hyatt] [added: Powell] Brown | | [removed: Chairman of the Board and Acting] President and Chief Executive Officer (Principal Executive Officer) | | [removed: February 29, 2012] [added: March 1, 2013] |
| /s/ Cory T. Walker | | Sr. Vice President, Treasurer and Chief Financial Officer (Principal Financial and Accounting Officer) | | [removed: February 29, 2012] [added: March 1, 2013] |
| Timothy R.M. Main | | [added: Director] | | [added: March 1, 2013] |
| | | Laurel L. Grammig [added: Attorney-in-Fact] |
| 10.1(b) | | Lease Agreement for office space at 655 N. Franklin St., Suite 1900, Tampa, Florida, dated March 27, 2012 and effective August 17, 2012, between TWC Fifty-Eight, Ltd., as landlord and the Registrant, as tenant. |
| 10.4(h) | | Employment Agreement, dated as of June 1, 2009, between the Registrant and Anthony Strianese. |
| Date: March 1, 2013 | | | | By: | | /s/ J. Powell Brown |
| | | | | | | J. Powell Brown |
| * | | Chairman of the Board | | March 1, 2013 |
| * | | Director | | March 1, 2013 |
| * | | Director | | March 1, 2013 |
| * | | Director | | March 1, 2013 |
| * | | Director | | March 1, 2013 |
| * | | Director | | March 1, 2013 |
| * | | | | |
| * | | Director | | March 1, 2013 |
| H. Palmer Proctor, Jr. | | | | |
| * | | Director | | March 1, 2013 |
| | | | | |
| * | | Director | | March 1, 2013 |
| | | | | |
| * | | Director | | March 1, 2013 |
| | | |
| 10.1(b) | | Lease Agreement for office space at 3101 W. Martin Luther King, Jr. Blvd., Tampa, Florida, dated July 1, 2004 and effective May 9, 2005, between Highwoods/Florida Holdings, L.P., as landlord and the Registrant, as tenant (incorporated by reference to Exhibit 10.2(b) to Form 10-K for the year ended December 31, 2005). |
| 10.8 | | Note Purchase Agreement, dated as of July 15, 2004, among the Registrant and the listed purchasers of the 5.57% Series A Senior Notes due September 15, 2011 and 6.08% Series B Senior Notes due July 15, 2014 (incorporated by reference to Exhibit 4.1 to Form 10-Q for the quarter ended June 30, 2004). |
| 10.11 | | Master Shelf and Note Purchase Agreement Dated as of December 22, 2006, by and among the Registrant and Prudential Investment Management, Inc. and certain Prudential affiliates as purchasers of the 5.66% Series C Senior Notes due December 22, 2016 (incorporated by reference to Exhibit 10.14 to Form 10-K for the year ended December 31, 2006). |
| 10.11(a) | | Letter Amendment dated September 30, 2009, to the Master Shelf and Note Purchase Agreement (incorporated by reference to Exhibit 10.1 to Form 8-K filed October 5, 2009). |
| 10.11(b) | | Confirmation of Acceptance dated January 21, 2011 (incorporated by reference to Exhibit 10.1 to Form 8-K filed January 27, 2011). |
| 10.14 | | Amended and Restated Revolving Loan Agreement dated as of June 3, 2008 by and between the Registrant and SunTrust Bank (incorporated by reference to Exhibit 10.19 to Form 8-K filed June 18, 2008). |
| 10.17 | | Amended and Restated Revolving and Term Loan Credit Agreement dated as of January 9, 2012 by and between the Registrant and SunTrust Bank. |
| 10.18 | | Promissory Note dated January 9, 2012, by and between Registrant and JPMorgan Chase Bank, N.A. |
| 10.19 | | Letter Agreement dated January 9, 2012 by and between Registrant and JPMorgan Chase Bank, N.A. |
| 10.20 | | Term Loan Agreement dated as of January 26, 2012 by and between the Registrant and JPMorgan Chase Bank, N.A. |
| Date: February 29, 2012 | | | | By: | | /s/ J. Hyatt Brown |
| | | | | | | J. Hyatt Brown |
| | | President and Chief Executive Officer; Director (currently on temporary leave of absence) | | February 29, 2012 |
| * | | Director | | February 29, 2012 |
| | | Attorney-in-Fact |