 filings.tools
Copart (CPRT) 10-K risk factor changes: FY2013 vs FY2012
The 2013-07-31 10-K against the 2012-07-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A58 rewritten20 added10 removed253 unchanged
All filing items691 rewritten364 added393 removed1,742 unchanged
Summary
counted, not written
- Item 1A lists 32 risk factor headings: 2 new, 5 reworded and 25 unchanged since FY2012. 2 headings from FY2012 no longer appear.
- Sentence by sentence, 364 added, 393 removed, 691 rewritten and 1,742 unchanged across 17 items that differ.
New Item 1A headings (2)
- Our operations and acquisitions in certain foreign areas expose us to political, regulatory, economic and reputational risks.
- Adverse U.S. and international economic conditions may negatively affect our business, operating results, or financial condition.
Removed Item 1A headings (2)
- Volatility in the capital and credit markets may negatively affect our business, operating results, or financial condition.
- Fluctuations in the U.S. unemployment rates could result in declines in revenue from processing insurance vehicles.
Reworded Item 1A headings (5)
- Our expansion into markets outside North America, including recent expansions in
[removed: Europe][added: Europe, Brazil] and the Middle East, expose us to risks arising from operating in international markets. Any failure to successfully integrate businesses acquired outside of North America into our operations could have an adverse effect on our consolidated results of operations, financial position or cash flows. - We face risks associated with the implementation of our salvage auction model in markets that may not operate on the same terms as the North American market. For example,
[removed: the U.K. market operates][added: certain markets operate] on a principal rather than agent basis, which[removed: has tended to][added: may] have an adverse impact on our gross margin percentages and[removed: has exposed][added: expose] us to inventory risks that we do not experience in North America. - If we experience problems with our [added: subhaulers and] trucking fleet operations, our business could be harmed.
- We are partially self-insured for certain losses and if our estimates of the cost of future claims differ from actual trends, our results of
[removed: our]operations could be harmed. - If the interest rate
[removed: swap][added: swaps] entered into in connection with our credit facility[removed: proves][added: prove] ineffective, it could result in volatility in our operating results, including potential losses, which could have a material adverse effect on our[removed: consolidated]results of operations and cash flows.
A heading is new when no FY2012 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
21 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2013; struck-through words were in FY2012. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
58 rewritten, 20 added, 10 removed, 253 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
No single customer accounted for more than 10% of our revenue during the fiscal year ended July 31, [removed: 2012.][added: 2013.]
Our expansion into markets outside North America, including recent expansions in [removed: Europe] [added: Europe, Brazil] and the Middle East, expose us to risks arising from operating in international markets.
We first expanded our operations outside North America in 2007 with a significant acquisition in the United [removed: Kingdom,] [added: Kingdom (the U.K.),] and we continue to evaluate acquisitions and other opportunities outside North America.
In August 2012, we announced our acquisition of a company in the United Arab [removed: Emirates.][added: Emirates (the U.A.E.), in November 2012, we announced our acquisitions of companies in Brazil and Germany and in June 2013, we announced our acquisition of a company in Spain.]
Among other things, we will ultimately deploy our proprietary auction technologies at all of our foreign operations and we cannot predict whether this deployment will be successful [removed: or will result in increases in the revenues or operating efficiencies of any acquired companies relative to their historic operating performance.]
In addition, certain acquisitions in the [removed: United Kingdom] [added: U.K.] may be reviewed by the Office of Fair Trade (OFT) and/or Competition Commission (U.K. Regulators).
For example, [removed: the U.K. market operates] [added: certain markets operate] on a principal rather than agent basis, which [removed: has tended to] [added: may] have an adverse impact on our gross margin percentages and [removed: has exposed] [added: expose] us to inventory risks that we do not experience in North America.
For example, [removed: the U.K. market operates primarily] [added: new markets may operate either wholly or partially] on the principal model, in which [removed: we take title to vehicles,] [added: the vehicle is purchased then resold for our own account,] rather than the agency model employed in North America, in which we act as a sales agent for the legal owner of vehicles.
[removed: As a result, our operations in the U.K. have had and will continue to] [added: Consequently, new acquisitions may] have an adverse impact on our consolidated gross margin percentages.
[removed: Operating] [added: Further, operating] on a principal basis exposes us to inventory risks, including losses from theft, damage, and obsolescence.
In other markets, insurers have traditionally been less [added: involved in the disposition of salvage vehicles.]
As we expand into markets outside North America and the [removed: United Kingdom,] [added: U.K.,] we cannot predict whether markets will readily [removed: adapt to] [added: adopt] our strategy of online auctions of automobiles sourced principally through vehicle insurers.
If the implementation of our new Enterprise Resource Planning [removed: (“ERP”)] [added: (ERP)] system is not executed efficiently and effectively, our business, financial position, and our consolidated operating results could be adversely affected.
We are in the process of converting our primary management information system to a new standard ERP system, which will occur in phases through [removed: 2013] [added: 2014] and [removed: 2014.][added: 2015.]
Although we have not been the victim of cyber attacks or other cyber incidents that have had a material impact on our consolidated operating results or financial position, we have from time to time experienced [removed: cybersecurity] [added: cyber security] breaches such as computer viruses and similar [removed: information technology violations in the ordinary course of business.]
If these systems are compromised, become inoperable for extended periods of time or cease to function properly, we may have to make a significant investment to fix or replace them and our ability to provide many of our electronic and online solutions to our customers may be [removed: impaired.][added: impaired, which would have a material adverse effect on our consolidated operating results and financial position.]
[removed: If that were] [added: Failure by us and our subsidiaries] to [removed: occur, it] [added: comply with these laws] could [added: subject us to civil and criminal penalties that could] have a material adverse effect on our consolidated operating results and financial position.
For example, Hurricanes [removed: Katrina and] [added: Katrina,] Rita [added: and Sandy] had, in certain quarters, an adverse effect on our operating results, in part because of yard capacity constraints in the Gulf Coast [removed: area.][added: area and in the northeastern coast of the United States, respectively.]
We may not be able to reach agreements to purchase independent storage facilities in markets where we have limited excess capacity, and zoning restrictions or difficulties obtaining use permits may limit our ability to expand our [added: capacity through acquisitions of new land.]
Our inability to control or manage these growth factors effectively could have a material adverse effect on our consolidated results of [removed: operations,] [added: operations and] financial [removed: position or cash flows.][added: position.]
Any significant impairment of our intellectual property rights, or any inability to protect our intellectual property rights, could have a material adverse effect on our consolidated results of [removed: operations,] [added: operations and] financial [removed: position or cash flows.][added: position.]
Litigation and any other intellectual property claims, whether with or without merit, can be time-consuming, expensive to litigate and settle, and can divert [added: management resources and attention from our core business.]
If we experience problems with our [added: subhaulers and] trucking fleet operations, our business could be harmed.
We rely solely upon independent subhaulers to pick up and deliver vehicles to and from our North American [added: and Brazilian] storage facilities.
We are partially self-insured for certain losses and if our estimates of the cost of future claims differ from actual trends, our results of [removed: our] operations could be harmed.
Further, we [removed: rely on] [added: utilize] independent actuaries to assist us in establishing the proper amount of reserves for anticipated payouts associated with these self-insured exposures.
Our executive officers, directors and their affiliates beneficially own, in the aggregate, [removed: 16%] [added: 19%] of our common stock as of July 31, [removed: 2012.][added: 2013.]
If they were to act together, these stockholders would have significant influence over most matters requiring approval by stockholders, including the election of directors, any amendments to our [removed: articles] [added: certificate] of incorporation and certain significant corporate transactions, including potential merger or acquisition transactions.
Our board of directors is authorized to create and issue from time to time, without stockholder approval, up to an aggregate of 5,000,000 shares of undesignated preferred stock, the terms of which may be established and shares of which may be issued without stockholder approval, and which may include rights superior to [added: the rights of the holders of common stock.]
[removed: These provisions could also discourage proxy contests and make it more] difficult for [removed: you and other] stockholders to elect directors of [removed: your] [added: their] choosing and cause us to take other corporate actions [removed: you] [added: the stockholders] desire.
These costs are amortized over the estimated useful life of the software beginning with its introduction or [removed: roll out.][added: roll-out.]
During periods of mild weather conditions, our ability to increase our revenues and improve our operating results and related growth will be increasingly dependent on our ability to obtain additional vehicle sellers and to compete [removed: more effectively in the market, each of which is subject to the other risks and uncertainties described in these sections.]
For example, during the fiscal year ended July 31, [removed: 2006,] [added: 2006 and during fiscal year 2013,] we recognized substantial additional costs associated with the impact of Hurricanes Katrina and Rita in Gulf Coast [removed: states.][added: states and Hurricane Sandy in the northeastern coast of the United States, respectively.]
These additional costs, characterized as “abnormal” under ASC 330, _Inventory,_ [removed: were recognized during the fiscal year ended July 31, 2006,] and included the additional subhauling, payroll, equipment and facilities expenses directly related to the operating conditions created by the hurricanes.
There can be no assurance that the existence of other local, regional or national contracts entered into by our competitors will not have a material adverse effect on our business or our expansion [added: plans.]
While most vehicle sellers have abandoned or reduced efforts to sell salvage vehicles directly without the use of service providers such as us, there can be no assurance that this trend will continue, which could adversely affect our market share, consolidated results of operations and financial [removed: condition.][added: position.]
We could incur substantial expenditures for preventative, investigative or remedial action and could be exposed to liability arising from our operations, contamination [added: by previous users of certain of our acquired facilities, or the disposal of our waste at off-site locations.]
[removed: Volatility in the capital] [added: Adverse U.S.] and [removed: credit markets] [added: international economic conditions] may negatively affect our business, operating results, or financial condition.
The capital and credit markets have [added: historically] experienced extreme volatility and disruption, which has [removed: led] [added: in the past and may in the future lead] to [removed: an] economic [removed: downturn] [added: downturns] in the U.S. and abroad.
As a result of [removed: the] [added: any] economic downturn, the number of miles driven may decrease, which may lead to fewer accident claims, a reduction of vehicle repairs, and fewer salvage vehicles.
or will result in increases in the revenues or operating efficiencies of any acquired companies relative to their historic operating performance.
Our operations and acquisitions in certain foreign areas expose us to political, regulatory, economic and reputational risks.
Although we have implemented policies, procedures and training designed to ensure compliance with anti-bribery laws, trade controls and economic sanctions, and similar regulations, our employees or agents may take actions in violation of our policies.
We may incur costs or other penalties in the event that any such violations occur, which could have an adverse effect on our business and reputation.
In addition, some of our recent acquisitions have required us to integrate non-U.S. companies which had not, until our acquisition, been subject to U.S. law.
In many countries outside of the United States, particularly in those with developing economies, it may be common for persons to engage in business practices prohibited by laws and regulations applicable to us, such as the U.S. Foreign Corrupt Practices Act (FCPA) or similar local anti-bribery laws.
These laws generally prohibit companies and their employees or agents from making improper payments to government officials for the purpose of obtaining or retaining business.
Any failure of new markets to adopt our business model could adversely affect our consolidated results of operations and financial position.
information technology violations in the ordinary course of business.
For example, in fiscal 2013, we acquired five new facilities in Sao Paulo, Brazil, one facility in the U.A.E., one facility in Ettlingen, Germany, one facility in Cordoba, Spain, and 43 facilities in North America.
Furthermore, promising acquisitions are difficult to identify and complete for a number of reasons, including competition among prospective buyers, the availability of affordable financing in the capital markets and the need to satisfy applicable closing conditions and obtain antitrust and other regulatory approvals on acceptable terms.
In addition, certain of the acquisition agreements by which we have acquired companies require the former owners to indemnify us against certain liabilities related to the operation of the company before we acquired it.
In most of these agreements, however, the liability of the former owners is limited and certain former owners may be unable to meet their indemnification responsibilities.
We cannot assure that these indemnification provisions will protect us fully or at all, and as a result we may face unexpected liabilities that adversely affect our financial statements.
Any failure to continue to successfully identify and complete acquisitions and develop new facilities could have a material adverse effect on our consolidated results of operations and financial position.
These provisions could also discourage proxy contests and make it more
more effectively in the market, each of which is subject to the other risks and uncertainties described in these sections.
These adverse economic conditions and events may have a negative effect on our business, consolidated results of operations and financial position.
We cannot accurately predict the amount or timing of any impairment of assets.
The second
| --- | --- | --- |
| • | | ensuring compliance with applicable legislation and regulations that affect our international operations, including applicable anticorruption legislation in the United States and United Kingdom and export control and sanctions laws; and |
involved in the disposition of salvage vehicles.
capacity through acquisitions of new land.
management resources and attention from our core business.
the rights of the holders of common stock.
plans.
by previous users of certain of our acquired facilities, or the disposal of our waste at off-site locations.
Fluctuations in the U.S. unemployment rates could result in declines in revenue from processing insurance vehicles.
Disposition generally is either the repair or disposal of the vehicle.
An excerpt. Shown here: 40 of 58 rewritten, all 20 added and all 10 removed. The counts are complete. For every sentence, read Item 1A. Risk Factors in the FY2013 filing and the FY2012 filing.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
107 rewritten, 91 added, 73 removed, 249 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
_This Annual Report on Form 10-K, including the information incorporated by reference herein, contains forward-looking statements within the meaning of Section 27A of the Securities [removed: Act,] [added: Act of 1933, as amended (the Securities Act),] and Section 21E of the [added: Securities] Exchange [removed: Act.][added: Act of 1934, as amended (the Exchange Act).]
We encourage investors to review these factors carefully together with the other matters referred to herein, as well as in the other documents we file with the [added: Securities and Exchange Commission or] SEC.
[removed: The Company] [added: We] may from time to time make additional written and oral forward-looking statements, including statements contained in [removed: the Company’s] [added: our] filings with the SEC.
[removed: The Company does] [added: We do] not undertake to update any forward-looking statement that may be made from time to time by [added: us] or on [removed: behalf of the Company._][added: our behalf._]
_Although we believe that, based on information currently available to [removed: the Company] [added: us] and [removed: its] [added: our] management, the expectations reflected in the forward-looking statements are reasonable, we cannot guarantee future results, levels of activity, performance or achievements.
You should not place undue reliance on these forward-looking [removed: statements._][added: statements.]
We sell [added: the vehicles] principally to licensed vehicle dismantlers, rebuilders, repair licensees, used vehicle dealers and [removed: exporters; however] [added: exporters and,] at certain locations, [removed: we sell directly] to the general public.
The majority of the vehicles sold on behalf of [removed: the] insurance companies are either damaged vehicles deemed a total loss or not economically repairable by the insurance companies or are recovered stolen vehicles for which an insurance settlement with the vehicle owner has already been made.
We offer vehicle sellers a full range of services that expedite each stage of the [removed: salvage] vehicle sales [removed: process and] [added: process,] minimize administrative and processing [removed: costs.][added: costs and maximize the ultimate sales price.]
In the [removed: United States] [added: U.S.] and [removed: Canada, or North America,] [added: Canada (North America), the U.A.E. and Brazil] we sell vehicles primarily as an agent and derive revenue primarily from fees paid by vehicle sellers and vehicle buyers as well as related fees for services such as towing and storage.
In the [removed: United Kingdom, or] U.K., [removed: a significant portion of our business is conducted] [added: we operate both] on a principal basis, purchasing [added: the] salvage vehicles outright from [added: the] insurance companies and reselling the vehicles for our own [removed: account.][added: account, and as an agent.]
[removed: Revenues from sellers are generally generated either on a fixed fee contract basis where we collect a fixed amount for selling each vehicle] regardless of the selling price of the vehicle or, under our Percentage Incentive Program, or [removed: PIP program,] [added: PIP,] where our fees are generally based on a predetermined percentage of the vehicle sales price.
Under the consignment programs, only the fees associated with vehicle processing are recorded in revenue, not the actual [added: sales price (gross proceeds).]
Transportation revenue includes charges to sellers for towing vehicles under certain [removed: contracts.][added: contracts and towing charges assessed to buyers for delivering vehicles.]
Operating costs consist primarily of operating personnel (which includes yard management, clerical and yard employees), rent, contract vehicle towing, insurance, fuel, equipment maintenance and repair, and costs of vehicles [removed: we] sold under purchase contracts.
We have experienced significant growth in facilities as we have acquired [removed: nine] [added: 55] facilities and established [removed: three] [added: four] new facilities since the beginning of fiscal [removed: 2010] [added: 2011] through July 31, [removed: 2012.][added: 2013.]
We believe that these acquisitions and openings strengthen our coverage as we have [removed: 155] facilities located in North [removed: America and] [added: America,] the [removed: U.K. as of July 31, 2012] [added: U.K., the U.A.E., Germany, Spain,] and [added: Brazil, and] are able to provide national coverage for our sellers.
The following table sets forth facilities that we have acquired or opened from August 1, [removed: 2009] [added: 2010] through July 31, [removed: 2012:][added: 2013:]
| Homestead, Florida | | | | Greenfield | | | | September 2010 | | | | [removed: Southern Florida] [added: United States] | | |
| Hartford City, Indiana | | | | Acquisition | | | | March 2011 | | | | [removed: Central Indiana] [added: United States] | | |
| Atlanta, Georgia | | | | Greenfield | | | | August 2011 | | | | [removed: Northern Georgia] [added: United States] | | |
The period-to-period comparability of our consolidated operating results and financial [removed: condition] [added: position] is affected by business acquisitions, new openings, weather and product introductions during such periods.
In addition to growth through [added: business] acquisitions, we seek to increase revenues and profitability by, among other things, (i) acquiring and developing additional vehicle storage facilities in key [removed: markets,] [added: markets;] (ii) pursuing national and regional vehicle seller [removed: agreements,] [added: agreements;] (iii) expanding our service offerings to sellers and [removed: members,] [added: members;] and (iv) expanding the application of VB2 into new markets.
Vehicle Sales. We have [removed: assumed] certain contracts [removed: through our U.K. acquisitions that require us to] [added: with insurance companies in which we] act as a principal, purchasing vehicles [removed: from the insurance companies] and reselling them for our own account.
The detrimental impact on recorded vehicle sales revenue due to the change in the [removed: GBP] [added: British pound] to [removed: USD] [added: U.S. dollar] exchange rate was $1.4 million.
Yard Operation Expenses. Yard operation expenses [added: excluding depreciation and amortization and impairment,] were [removed: $377.6] [added: $344.6] million during fiscal 2012 compared to [removed: $374.1] [added: $337.1] million for fiscal 2011, an increase of [removed: $3.5] [added: $7.5] million, or [removed: 0.9%,] [added: 2.2%,] above fiscal 2011.
There was a detrimental impact on yard operating expenses due to the change in the [removed: GBP] [added: British pound] to [removed: USD] [added: U.S. dollar] exchange rate of $0.5 million.
The beneficial impact on the cost of sales due to the change in the [removed: GBP] [added: British pound] to [removed: USD] [added: U.S. dollar] exchange rate was $1.0 million.
The beneficial impact on general and administrative expenses due to the change in the [removed: GBP] [added: British pound] to [removed: USD] [added: U.S. dollar] exchange rate was $0.1 million.
[removed: General] [added: Included in general] and administrative [added: costs were] depreciation and amortization expenses [added: which] were $15.1 million and $8.7 million for the fiscal years ended July 31, 2012 and 2011, respectively.
During the year ended July 31, 2012, we recorded an impairment of $8.8 million associated with the [removed: write down] [added: write-down] to fair market value of certain assets, primarily real estate, computer hardware and our fleet of private aircraft which have been removed from operations and, if not disposed [removed: of during the year,] [added: of,] are reflected in assets held for sale on the balance sheet.
Service Revenues. Service revenues were [removed: $713.1] [added: $849.7] million during fiscal [removed: 2011] [added: 2013] compared to [removed: $634.6] [added: $757.3] million for fiscal [removed: 2010,] [added: 2012,] an increase of [removed: $78.5] [added: $92.4] million, or [removed: 12.4%,] [added: 12.2%,] above fiscal [removed: 2010.][added: 2012.]
Vehicle sales revenues were [removed: $159.2] [added: $196.7] million during fiscal [removed: 2011] [added: 2013] compared to [removed: $138.3] [added: $166.9] million for fiscal [removed: 2010,] [added: 2012,] an increase of [removed: $20.9] [added: $29.8] million, or [removed: 15.1%,] [added: 17.9%,] above fiscal [removed: 2010.][added: 2012.]
Included in yard operation costs were depreciation and amortization expenses which were [removed: $37.0] [added: $40.8] million and [removed: $34.9] [added: $33.0] million for the fiscal years ended July 31, [removed: 2011] [added: 2013] and [removed: 2010,] [added: 2012,] respectively.
Cost of Vehicle Sales. The cost of vehicles sold was [removed: $125.2] [added: $167.2] million during fiscal [removed: 2011] [added: 2013] compared to [removed: $104.7] [added: $137.0] million for fiscal [removed: 2010,] [added: 2012,] an increase of [removed: $20.5] [added: $30.2] million, or [removed: 19.6%.][added: 22.0%.]
General and Administrative Expenses. General and administrative expenses, excluding depreciation and [removed: amortization,] [added: amortization and impairment,] were [removed: $98.9] [added: $122.0] million for fiscal [removed: 2011] [added: 2013] compared to [removed: $100.6] [added: $99.4] million for fiscal [removed: 2010, a decrease] [added: 2012, an increase] of [removed: $1.7] [added: $22.6] million, or [removed: 1.7%.][added: 22.7%.]
[removed: Depreciation] [added: Included in general] and [added: administrative costs were depreciation and] amortization expenses [added: which] were [removed: $8.7] [added: $16.0] million and [removed: $8.3] [added: $15.1] million for the fiscal years ended July 31, [removed: 2011] [added: 2013] and [removed: 2010,] [added: 2012,] respectively.
Interest expense [removed: increased $3.9] [added: decreased $1.1] million as a result of [removed: increased borrowing under the new credit facility] [added: principal payments of long-term debt,] which is further described in the Notes to Consolidated Financial Statements — _Note 9.
Other income, net, increased [removed: $1.7] [added: $0.8] million due primarily to the gain on sale of assets.
Income Taxes. Our effective income tax rates for fiscal [removed: 2011] [added: 2013] and [removed: 2010] [added: 2012] were [removed: 36.9%] [added: 35.0%] and [removed: 36.7%,] [added: 34.5%,] respectively.
In addition, historical information should not be considered an indicator of future performance._
We are a leading provider of online auctions and vehicle remarketing services in the United States (U.S.), Canada, the United Kingdom (U.K.), and Brazil.
We also provide vehicle remarketing service in the United Arab Emirates (U.A.E.), Germany and Spain.
In Germany and Spain, we derive revenue from sales listing fees for listing vehicles on behalf of many insurance companies.
Revenues from sellers are generally generated either on a fixed fee contract basis where we collect a fixed amount for selling each vehicle
| Burlington, North Carolina | | | | Greenfield | | | | July 2012 | | | | United States | | |
| Webster, New Hampshire | | | | Greenfield | | | | September 2012 | | | | United States | | |
| Gainesville, Georgia | | | | Acquisition | | | | May 2013 | | | | United States | | |
| Davison, Michigan | | | | Acquisition | | | | May 2013 | | | | United States | | |
| Ionia, Michigan | | | | Acquisition | | | | May 2013 | | | | United States | | |
| Kincheloe, Michigan | | | | Acquisition | | | | May 2013 | | | | United States | | |
| Salvage Parent, Inc.* | | | | Acquisition | | | | May 2013 | | | | United States | | |
| Dubai, U.A.E. . | | | | Acquisition | | | | August 2012 | | | | United Arab Emirates | | |
| Embu, Brazil | | | | Acquisition | | | | November 2012 | | | | Brazil | | |
| Pirapora, Brazil | | | | Acquisition | | | | November 2012 | | | | Brazil | | |
| Osasco, Brazil | | | | Acquisition | | | | November 2012 | | | | Brazil | | |
| Castelo Branco, Brazil | | | | Acquisition | | | | November 2012 | | | | Brazil | | |
| Locations | | | | Acquisition or Greenfield | | | | Date | | | | Geographic Service Area | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Vila Jaguara, Brazil | | | | Acquisition | | | | November 2012 | | | | Brazil | | |
| Ettlingen, Germany | | | | Acquisition | | | | November 2012 | | | | Germany | | |
| Cordoba, Spain | | | | Acquisition | | | | June 2013 | | | | Spain | | |
| * | | Salvage Parent, Inc. conducts business primarily as Quad City Salvage Auction, Crashed Toys, and Desert View Auto Auctions. Combined, these businesses operate at 39 locations in 14 states. |
_Fiscal 2013 Compared to Fiscal 2012_
| | | | | 2013 | | | | Percentage of Revenue | | | | 2012 | | | | Percentage of Revenue | | |
| Service revenues | | | | $ | 849,667 | | | | 81 | % | | $ | 757,272 | | | | 82 | % |
| Vehicle sales | | | | | 196,719 | | | | 19 | % | | | 166,919 | | | | 18 | % |
| | | | | $ | 1,046,386 | | | | 100 | % | | $ | 924,191 | | | | 100 | % |
The growth came from (i) our international expansion during the year into Germany, Spain, the United Arab Emirates and Brazil which represented $10.1 million; (ii) the acquisition of Salvage Parent, Inc. which closed on May 30, 2013 and represents $8.0 million; (iii) growth in the U.K. of $2.9 million driven by increased revenue per car; and, (iv) growth in North America of $71.4 million.
The growth in North America was driven primarily by increased volume as revenue per car remained relatively flat.
The increase in volume came from (i) Hurricane Sandy, as the major storm produced an extraordinary volume of flood damaged vehicles; (ii) market share gains as we saw the full year impact of the exclusive provider contract entered into with a major insurance company at the end of fiscal 2012; and, (iii) what we believe to be a general increase in the overall salvage market as we believe there has been an increase in salvage frequency.
Salvage frequency is the percentage of cars involved in accidents which the insurance companies salvage rather than repair.
Trends in salvage frequency are driven by the relationship between repairs costs, used car values and auction returns.
The increase in salvage frequency was driven, we believe, by the decline in used cars values relative to repair costs.
Used car values are determined by many factors including the used car supply, which is tied directly to new car sales, and the
average age of cars on the road.
New cars sales grew on a year over year basis increasing the supply of used cars and the average age of a car on the road continued to grow.
These factors, among others, lead to a decline in used car values on a year over year basis.
During the same period the average cost to repair a car increased.
The factors that influence repair costs, used car pricing and auction returns are many and varied and we cannot predict their movements.
sales price (gross proceeds).
Transportation revenue also includes towing charges assessed to buyers for delivering vehicles.
During fiscal 2004 and fiscal 2008, we converted all of our North American and U.K. sales, respectively, to an Internet-based auction-style model using our VB2 Internet sales technology which employs a two-step bidding process.
The first step, called the preliminary bid, allows members to submit bids up to one hour before a real time virtual auction begins.
The second step allows members to bid against each other, and the high bidder from the preliminary bidding process, in a real-time process over the Internet.
| Bristol, England | | | | Acquisition | | | | January 2010 | | | | United Kingdom | | |
| Bedford, England | | | | Acquisition | | | | January 2010 | | | | United Kingdom | | |
| Colchester, England | | | | Acquisition | | | | January 2010 | | | | United Kingdom | | |
| Gainsborough, England | | | | Acquisition | | | | *January 2010 | | | | United Kingdom | | |
| Luton, England | | | | Acquisition | | | | January 2010 | | | | United Kingdom | | |
| Scranton, Pennsylvania | | | | Greenfield | | | | February 2010 | | | | Central Pennsylvania | | |
| * | | Closed in fiscal 2010 |
In January 2010, the Company completed the acquisition of D Hales Limited (D Hales) which operated five locations in the United Kingdom.
In fiscal 2011, we acquired John Hewitt and Sons, Limited (Hewitt) which operated one location in the United Kingdom.
These acquisitions were undertaken because of their strategic fit with our business in the United Kingdom.
In August 2012, we acquired Ride Safely Middle East Auction, LLC located in Dubai, UAE.
The growth in the average selling price per unit was primarily due to: (i) the increase in commodity pricing, particularly the per ton price for crushed car bodies, which has an impact on the ultimate selling price of vehicles sold for scrap and vehicles sold for dismantling and (ii) in the U.K., the continuing beneficial impact of VB2 which we introduced to the U.K. in 2008 and which expands our buyer base by opening vehicle sales to buyers worldwide.
_Fiscal 2011 Compared to Fiscal 2010_
| | | | | 2011 | | | | Percentage of Revenue | | | | 2010 | | | | Percentage of Revenue | | |
| Service revenues | | | | $ | 713,093 | | | | 82 | % | | $ | 634,606 | | | | 82 | % |
| Vehicle sales | | | | | 159,153 | | | | 18 | % | | | 138,273 | | | | 18 | % |
| | | | | $ | 872,246 | | | | 100 | % | | $ | 772,879 | | | | 100 | % |
Growth in unit volume generated $62.1 million in additional service revenue relative to fiscal 2010 and was driven primarily by growth in the number of units sold on behalf of franchise and independent car dealerships, new and expanded contracts with insurance companies and the migration from the principal model to the agency model in the U.K. Growth in the average revenue per car sold generated $1.0 million in additional revenue over fiscal 2010 as higher scrap metal and used car pricing led to a general increase in the average selling price, and was offset by growth in the percentage of volume processed from suppliers with below average revenue per car.
The higher revenue per car sold was driven by the average selling price per vehicle as over 50% of our service revenue is tied in some manner to the ultimate selling price of the vehicle.
We believe the increase in the average selling price was primarily impacted by: (i) the year over year increase in commodity pricing as we believe that commodity pricing, particularly the per ton price for crushed car bodies, has an impact on the ultimate selling price of vehicles sold for scrap and vehicles sold for dismantling; (ii) the general increase in used car pricing, which we believe has an impact on the average selling price of vehicles which are repaired and retailed or purchased by the end user and (iii) in the U.K., the continuing beneficial impact of VB2 which we introduced to the U.K. in 2008 and which expands our buyer base by opening vehicle sales to buyers worldwide.
We cannot determine the impact of the movement of these factors, nor can we predict their future movement.
Further, we cannot determine which vehicles are sold to the end user or for scrap, dismantling, retailing or export.
Accordingly, we cannot quantify the specific impact that commodity pricing, used car pricing, and the introduction of VB2 had on the selling price of vehicles and ultimately on service revenue.
The average dollar to pound exchange rate was 1.60 dollars to the pound and 1.57 dollars to the pound for fiscal 2011 and fiscal 2010, respectively, and led to an increase in service revenue of $0.9 million.
In addition, on August 1, 2010, we adopted Accounting Standards Update (ASU) 2009-13_, Revenue Recognition (Topic 605): Multiple-Deliverable Revenue Arrangements_ (ASU 2009-13).
Consequently, we recognized in the period earned certain revenues, primarily towing fees, titling fees and other enhancement service fees, which were previously deferred until the period the car associated with those revenues was sold.
As a result of this change, we recognized $14.4 million in additional revenue for the fiscal year ended July 31, 2011, which would have otherwise been recognized in future periods.
The increase in vehicle sales revenue was due to the growth in the average selling price of vehicles which resulted in increased revenue of $19.1 million.
We cannot determine which vehicles are sold directly to the end user or for scrap, dismantling, retailing, or export and, accordingly, cannot quantify the specific impact of commodity pricing nor can we isolate the impact that VB2 had on the ultimate selling price of vehicles sold in the U.K. The
decline in volume resulted primarily from the migration of certain contracts in the U.K. from the principal model to the agency model and resulted in a reduction in vehicle sales revenue of $0.8 million.
The beneficial impact on recorded vehicle sales revenue due to the change in the GBP to USD exchange rate was $2.1 million.
Yard Operation Expenses. Yard operation expenses were $374.1 million during fiscal 2011 compared to $320.2 million for fiscal 2010, an increase of $53.9 million, or 16.8%, above fiscal 2010.
The increase was driven primarily by (i) the growth in volume of units processed, (ii) the adoption of ASU 2009-13, (iii) increase in subhauling costs due to the growth in diesel prices on a year over year basis, and (iv) the general growth in program costs associated with new business segments.
There was a detrimental impact on yard operating expenses due to the change in the GBP to USD exchange rate of $0.8 million.
On August 1, 2010 we adopted ASU 2009-13.
An excerpt. Shown here: 40 of 107 rewritten, 40 of 91 added and 40 of 73 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2013 filing and the FY2012 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
12 rewritten, 3 added, 0 removed, 13 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
To achieve this objective in the current uncertain global financial markets, as of July 31, [removed: 2012,] [added: 2013,] all of our total cash and cash equivalents were held in bank deposits and money market funds.
As of July 31, [removed: 2012,] [added: 2013,] we held no direct investments in auction rate securities, collateralized debt obligations, structured investment vehicles or mortgaged-backed securities.
Based on the average cash balance held during the twelve months ended July 31, [removed: 2012,] [added: 2013,] a 10% change in our interest yield would not materially affect our operating results.
Our total borrowings under the Credit Facility were [removed: $443.8] [added: $368.8] million as of July 31, [removed: 2012.][added: 2013.]
We have entered into two interest rate swaps to exchange our variable interest rate payments commitment for fixed interest rate payments on the Term Loan [removed: balance.][added: balance to mitigate the interest expense risk.]
Fluctuations in [removed: the] foreign currencies create volatility in our reported results of operations because we are required to consolidate the results of operations of our foreign currency denominated subsidiaries.
International net revenues result from transactions by our [removed: Canadian] [added: Canadian, U.K., U.A.E., Brazilian, Spain] and [removed: U.K.] [added: German] operations and are typically denominated in the local currency of each country.
These operations also incur a majority of their expenses in the local currency, the Canadian [removed: dollar and] [added: dollar,] the British [removed: pound.][added: pound, the U.A.E. dirham, the Brazilian real and the Euro.]
[removed: A hypothetical uniform 10% strengthening or weakening in the value of the] U.S. dollar relative to the Canadian [removed: dollar and] [added: dollar,] British [removed: pound] [added: pound, U.A.E. dirham, Brazilian real or Euro] in which our revenues and profits are denominated would result in a decrease/increase to revenue of [removed: $19.9] [added: $22.8] million for the twelve months ended July 31, [removed: 2012.][added: 2013.]
Fluctuations in [removed: the] foreign currencies create volatility in our reported consolidated financial position because we are required to remeasure substantially all assets and liabilities held by our foreign subsidiaries at the current exchange rate at the close of the accounting period.
At July 31, [removed: 2012,] [added: 2013,] the cumulative effect of foreign exchange rate fluctuations on our consolidated financial position was a net translation loss of [removed: $34.9] [added: $45.4] million.
A 10% strengthening or weakening in the value of the U.S. dollar relative to the Canadian [removed: dollar or the] [added: dollar,] British [removed: pound] [added: pound, U.A.E. dirham, Brazilian real or Euro] will not have a material effect on our consolidated financial position.
We do not hold or issue financial instruments for trading purposes.
Based on the average Credit Facility balance held during the year ended July 31, 2013, a 10% change in our interest rate would not materially affect our operating results.
A hypothetical uniform 10% strengthening or weakening in the value of the
Item 1. Business
37 rewritten, 30 added, 51 removed, 303 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
CopartTM, VB2TM, CopartDirectTM, BID4UTM, CoPartfinderTM, [removed: OutbidTM and] [added: OutbidTM,] CI & [removed: DesignTM] [added: DesignTM, Cars with HeartTM, and Crashedtoys.comTM,] are trademarks of Copart, Inc. This Form 10-K also includes other trademarks of Copart and of other companies.
We are a leading provider of online auctions and vehicle remarketing services in the United States (U.S.), [removed: Canada and] [added: Canada,] the United Kingdom [removed: (U.K.).][added: (U.K.), and Brazil.]
We provide vehicle sellers with a full range of services to process and sell vehicles [added: primarily] over the Internet through our Virtual Bidding Second Generation Internet auction-style sales technology, which we refer to as VB2.
[removed: We then sell the vehicles] principally to licensed vehicle dismantlers, rebuilders, repair licensees, used vehicle dealers and exporters and, at certain locations, to the general public.
[added: The majority of the vehicles sold on behalf of insurance companies] are either damaged vehicles deemed a total loss or not economically repairable by the insurance companies or are recovered stolen vehicles for which an insurance settlement with the vehicle owner has already been made.
In the U.S. and Canada (North America), [added: Brazil and the U.A.E.] we sell vehicles primarily as an agent and derive revenue primarily from fees paid by vehicle sellers and vehicle buyers as well as related fees for services such as towing and storage.
In the U.K., we operate both on a principal basis, purchasing the salvage [removed: vehicle] [added: vehicles] outright from the insurance companies and reselling the [removed: vehicle] [added: vehicles] for our own account, and as an agent.
For fiscal [removed: 2012,] [added: 2013,] sales of North American vehicles, on a unit basis, to members registered outside the state where the vehicle is located accounted for [removed: 51.1%] [added: 52.6%] of total vehicles sold; [removed: 28.7%] [added: 29.0%] of vehicles were sold to out of state members and [removed: 22.4%] [added: 23.6%] were sold to out of country members, based on registration.
For fiscal [removed: 2012,] [added: 2013,] sales of U.K. vehicles, on a unit basis, to members registered outside the country where the vehicle is located accounted for [removed: 18.1%] [added: 19.0%] of total vehicles sold.
For fiscal [removed: 2012,] [added: 2013,] which ended July 31, [removed: 2012,] [added: 2013,] our revenues were [removed: $924.2] [added: $1,046.4] million and our operating income was [removed: $286.4] [added: $283.0] million.
In fiscal 2012, in North America, we acquired two new facilities located in Calgary and Edmonton, [removed: Canada.][added: Canada and we opened two new facilities in Atlanta, Georgia and Burlington, North Carolina.]
Automobile manufacturers [removed: are incorporating] [added: continuously incorporate] new standard features, including unibody construction utilizing exotic metals, passenger safety cages with surrounding crumple zones to absorb impacts, plastic and ceramic components, airbags, [removed: xenon lights,] [added: adaptive headlights,] computer systems, [removed: heated seats,] [added: advanced cameras, collision warning systems,] and navigation systems.
Advance charges paid on behalf of the vehicle seller are either recovered upon sale of the [removed: vehicle or] [added: vehicle,] invoiced separately to the [added: seller or deducted from the net proceeds due to the] seller.
The vehicle is then sold either at a live auction or, in our case, on VB2 typically within [removed: 7] [added: seven] days.
The following table sets forth facilities that we have acquired or opened from August 1, [removed: 2009] [added: 2010] through July 31, [removed: 2012:][added: 2013:]
| Homestead, Florida | | | | Greenfield | | | | September 2010 | | | | [removed: Southern Florida] [added: United States] | | |
| Hartford City, Indiana | | | | Acquisition | | | | March 2011 | | | | [removed: Central Indiana] [added: United States] | | |
| Atlanta, Georgia | | | | Greenfield | | | | August 2011 | | | | [removed: Northern Georgia] [added: United States] | | |
[removed: __Expand] [added: _Expand] Our Service Offerings to Sellers and [removed: Members__][added: Members_]
Since our inception in 1982, we have expanded from a single facility in Vallejo, California to an integrated network of [removed: 155] facilities located in the United States, [removed: Canada and] [added: Canada,] the [removed: U.K. as of July 31, 2012.][added: U.K., the U.A.E., Brazil, Germany and Spain.]
Since becoming a public company in 1994, we have completed [removed: the acquisition] [added: acquisitions] of [removed: 83] facilities in North America, [removed: U.K. and] [added: U.K.,] the [removed: U.A.E. As part of our acquisition] [added: U.A.E., Brazil, Germany] and [removed: integration strategy, we seek to:][added: Spain.]
We offer Copart [added: ProQuote and Enhanced] ProQuote, [removed: a] proprietary [removed: service] [added: services] that [removed: assists] [added: assist] sellers in the vehicle claims evaluation process by providing online salvage value estimates, which help sellers determine whether to repair a particular vehicle or deem it a total loss.
We offer some of our major insurance company [removed: sellers] [added: sellers,] office and yard space to house vehicle inspection stations on-site at our facilities.
We have [removed: 77] [added: over 90] vehicle inspection stations at our facilities.
The preliminary bidding step is an open bid format similar to [removed: eBay.][added: eBay®.]
We have [removed: engaged agents] [added: a dedicated group of employees] in North America that target these dealers and work with them throughout the sales process.
No single customer accounted for more than 10% of our revenues in fiscal [removed: 2012, 2011] [added: 2013, 2012] and [removed: 2010.][added: 2011.]
[removed: Of] [added: We obtained 82% of] the total number of vehicles processed during fiscal years [removed: 2012, 2011 and 2010, we obtained 82%, 82%] [added: 2013, 2012] and [removed: 80%, respectively,] [added: 2011,] from insurance company sellers.
We market our services to vehicle sellers through an in-house sales force [removed: and independent agents] that utilize a variety of sales techniques, including targeted mailing of our sales literature, telemarketing, follow-up personal sales calls, Internet search engines, employee referrals, tow shop referrals, participation in trade shows and vehicle and insurance industry conventions.
We market our services to [added: franchise and independent dealerships as well as] the general public under [added: CopartDirect by utilizing an in-house sales force.]
[removed: We may, when appropriate, provide] vehicle sellers with detailed analysis of the net return on vehicles and a proposal setting forth ways in which we believe that we can improve net returns on vehicles and reduce administrative costs and expenses.
We have implemented our proprietary business operating software at [removed: all] [added: the majority] of our storage facilities.
We are planning to convert to a new standard Enterprise Resource Planning [removed: (“ERP”)] [added: (ERP)] system.
Implementation of the new ERP system is scheduled to occur in phases through fiscal [removed: 2013] [added: 2014] and [removed: 2014.][added: 2015.]
As of July 31, [removed: 2012,] [added: 2013,] we had [removed: 2,981] [added: 3,875] full-time employees, of whom [removed: 663] [added: 1,055] were engaged in general and administrative functions and [removed: 2,318] [added: 2,820] were engaged in yard operations.
We believe that we are in [removed: compliance] [added: compliance,] in all material [removed: respects] [added: respects,] with applicable regulatory requirements.
In seeking to limit access to sensitive information to the greatest practical extent, we routinely enter into confidentiality and assignment of [removed: invention agreements with each of our employees and consultants and nondisclosure agreements with our key customers and vendors.]
We also provide vehicle remarketing services in the United Arab Emirates (U.A.E.), Germany and Spain.
We sell the vehicles
In Germany and Spain, we derive revenue from sales listing fees for listing vehicles on behalf of many insurance companies.
In the U.K. we acquired one facility located in Birmingham, England.
In fiscal 2013, we acquired five new facilities in Sao Paulo, Brazil, one facility in Dubai, United Arab Emirates (U.A.E.), one facility in Ettlingen, Germany, one facility in Cordoba, Spain, and 43 facilities in North America and we opened a new facility in Webster, New Hampshire.
| Burlington, North Carolina | | | | Greenfield | | | | July 2012 | | | | United States | | |
| Webster, New Hampshire | | | | Greenfield | | | | September 2012 | | | | United States | | |
| Gainesville, Georgia | | | | Acquisition | | | | May 2013 | | | | United States | | |
| Davison, Michigan | | | | Acquisition | | | | May 2013 | | | | United States | | |
| Ionia, Michigan | | | | Acquisition | | | | May 2013 | | | | United States | | |
| Kincheloe, Michigan | | | | Acquisition | | | | May 2013 | | | | United States | | |
| Salvage Parent, Inc.* | | | | Acquisition | | | | May 2013 | | | | United States | | |
| Dubai, U.A.E. | | | | Acquisition | | | | August 2012 | | | | United Arab Emirates | | |
| Embu, Brazil | | | | Acquisition | | | | November 2012 | | | | Brazil | | |
| Pirapora, Brazil | | | | Acquisition | | | | November 2012 | | | | Brazil | | |
| Osasco, Brazil | | | | Acquisition | | | | November 2012 | | | | Brazil | | |
| Castelo Branco, Brazil | | | | Acquisition | | | | November 2012 | | | | Brazil | | |
| Vila Jaguara, Brazil | | | | Acquisition | | | | November 2012 | | | | Brazil | | |
| Ettlingen, Germany | | | | Acquisition | | | | November 2012 | | | | Germany | | |
| Cordoba, Spain | | | | Acquisition | | | | June 2013 | | | | Spain | | |
| * | | Salvage Parent, Inc. conducts business primarily as Quad City Salvage Auction, Crashed Toys, and Desert View Auto Auctions. Combined, these businesses operate at 39 locations in 14 states. |
| • | | A mobile application, which allows members to search, bid, create watchlists, join auctions and bid from anywhere; |
As part of our acquisition and integration strategy, we seek to:
| --- | --- | --- |
We may, when appropriate, provide
Employees per geographic region are as follows:
| North America | | | | United Kingdom | | | | Other | | | | Total Employees | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 3,010 | | | | 682 | | | | 183 | | | | 3,875 | | |
invention agreements with each of our employees and consultants and nondisclosure agreements with our key customers and vendors.
The majority of the vehicles sold on behalf of insurance companies
On June 14, 2007, we entered the U.K. salvage market through the acquisition of Universal Salvage Plc (Universal).
In fiscal 2008, we made the following additional acquisitions: Century Salvage Sales Limited (Century) on August 1, 2007; AG Watson Auto Salvage & Motors Spares Limited (AG Watson) on February 29, 2008; and Simpson Bros.
Holdings Limited (Simpson) on April 4, 2008.
In fiscal 2010, we acquired D Hales Limited (D Hales) on January 22, 2010.
In fiscal 2011, we acquired John Hewitt and Sons, Limited (Hewitt) on March 11, 2011.
Universal, Century, AG Watson, D Hales and Hewitt were all leading providers of vehicle auctions and services to the motor insurance and automotive industries.
Simpson was primarily an auto dismantler and was acquired primarily for its real estate holdings.
In fiscal 2012, we made no acquisitions in the U.K.
In fiscal 2008, we initiated two new programs using VB2, (i) Copart Dealer Services (CDS), by which we sell dealer-trade-ins and (ii) CopartDirect, whereby we offer to purchase the cars directly from the public and sell them on our own behalf.
Our goal through these two programs was to expand VB2’s application beyond traditional salvage in order to expand our customer base.
CDS targets franchise and independent dealerships while CopartDirect targets the general public.
In fiscal 2009, we opened our website to the public, initiated our Registered Broker program by which the public can purchase vehicles through a member, and initiated our Market Maker program by which members can open Copart storefronts with Internet kiosks that enable the general public to browse and view our inventory and purchase vehicles from us through the Market Maker.
In fiscal 2010, we initiated two additional programs using VB2: (i) 2nd chance bidding, which allows the second highest bidder of a vehicle the opportunity to purchase the vehicle for the seller’s current minimum bid after the high bidder declines and (ii) Night Cap Sales, which provides sellers an additional opportunity to have members bid on their vehicles, increasing exposure and minimizing cycle time.
As of July 31, 2012, we had a total of 155 facilities, comprised of 136 in the U.S., 4 in Canada and 15 in the U.K.
In August 2012, we acquired Ride Safely Middle East Auction, LLC located in Dubai, United Arab Emirates (UAE), our first acquisition outside of North America and the U.K.
| Bristol, England | | | | Acquisition | | | | January 2010 | | | | United Kingdom | | |
| Bedford, England | | | | Acquisition | | | | January 2010 | | | | United Kingdom | | |
| Colchester, England | | | | Acquisition | | | | January 2010 | | | | United Kingdom | | |
| Gainsborough, England | | | | Acquisition | | | | *January 2010 | | | | United Kingdom | | |
| Luton, England | | | | Acquisition | | | | January 2010 | | | | United Kingdom | | |
| Scranton, Pennsylvania | | | | Greenfield | | | | February 2010 | | | | Central Pennsylvania | | |
| * | | Closed in fiscal 2010 |
CopartDirect by utilizing an in-house sales force and we market our services to franchise and independent dealerships through a group of independent agents.
As of July 31, 2012, we had 2,408 and 573 employees located in North America and the U.K., respectively.
In connection with the acquisition of the Dallas, Texas storage facility in 1994, we set aside $3.0 million to cover the costs of environmental remediation, stabilization and related consulting expenses for a six-acre portion of the facility that contained elevated levels of lead due to the activities of the former operators.
We began the stabilization process in 1996 and completed it in 1999.
We paid all remediation and related costs from the $3.0 million fund and, in accordance with the acquisition agreement, distributed the remainder of the fund to the seller of the Dallas facility, less $0.2 million which was held back to cover the costs of obtaining the no-further-action letter.
In September 2002, our environmental engineering consultant issued a report, which concludes that the soil stabilization has effectively stabilized the lead-impacted soil, and that the concrete cap should prevent impact to storm water and subsequent surface water impact.
Our consultant thereafter submitted an Operations and Maintenance Plan (Plan) to the Texas Commission on Environmental Quality (TCEQ) providing for a two-year inspection and maintenance plan for the concrete cap, and a two-year ground and surface water monitoring plan.
In January of 2003, the TCEQ approved the Plan, subject to the additions of upstream (background) surface water samples from the intermittent stream adjacent to the facility and documentation of any repairs to the concrete cap during the post closure-monitoring period.
The first semi-annual water sampling was conducted in April 2003, which reflected that the lead-impacted, stabilized soil is not impacting the ground and/or surface water.
The second round of semi-annual water samples collected in October and November 2003 reported concentration of lead in one storm water and one surface water sample in excess of the established upstream criteria for lead.
In correspondence, which we received in July 2004, the TCEQ approved with comment our water monitoring report dated February 24, 2004.
The TCEQ instructed us to continue with post-closure monitoring and maintenance activities and submit the next report in accordance with the approved schedules.
In February 2005, a report from our environmental engineering consultant was transmitted to the TCEQ containing the results of annual monitoring activities consisting of two (2) semi-annual sampling events which occurred in April/June 2004 and October/November 2004.
Laboratory analytical results indicated no lead concentrations exceeding the target concentration level set in the Corrective Measures Study for the site, but some results were in excess of Texas surface water quality standards.
Our environmental engineering consultant concluded in the February 2005 report to the TCEQ that it is unlikely that lead concentrations detected in the storm water runoff samples are attributable to the lead impacted soils.
Based on the results of the 2004 samplings, we requested that no further action be
taken and that a closure letter be issued by the TCEQ.
An excerpt. Shown here: all 37 rewritten, all 30 added and 40 of 51 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2013 filing and the FY2012 filing.
Cover and table of contents
14 rewritten, 1 added, 4 removed, 60 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
SECURITIES AND EXCHANGE [removed: COMMISSION][added: COMMISSION]
Washington, D.C. [removed: 20549][added: 20549]
Form [removed: 10-K][added: 10-K]
| \[X\] | | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 For the fiscal year ended: July 31, [removed: 2012] [added: 2013] |
Copart, [removed: Inc.][added: Inc.]
[removed: (Exact] [added: | (Exact] name of registrant as specified in its charter) [added: | | | | | | | |]
Yes o No [removed: R][added: þ]
The aggregate market value of the voting and non-voting Common Stock held by non-affiliates of the registrant as of January 31, [removed: 2012] [added: 2013] (the last business day of the registrant’s most recently completed second fiscal quarter) was [removed: $2,504,602,111] [added: $3,808,774,974] based upon the closing sales price reported for such date on the NASDAQ Global Select Market (formerly the NASDAQ National Market).
At September [removed: 28, 2012,] [added: 30, 2013,] registrant had [removed: 124,093,869] [added: 125,515,179] outstanding shares of Common Stock.
Portions of our definitive Proxy Statement for the [removed: 2012] [added: 2013] Annual Meeting of Stockholders, also referred to in this Annual Report on Form 10-K as our Proxy Statement, which will be filed with the Securities and Exchange Commission, or SEC, pursuant to Regulation 14A within 120 days after the registrant’s fiscal year end of July 31, [removed: 2012,] [added: 2013,] have been incorporated by reference in Part III hereof.
for the Fiscal Year Ended July 31, [removed: 2012][added: 2013]
| | | | | Governmental Regulations | | | | | [removed: 13] [added: 12] | |
| | | | | Intellectual Property and Proprietary Rights | | | | | [removed: 13] [added: 12] | |
Risk Factors [removed: 14][added: 13]
10-K 1 d30512.htm 10-K
10-K 1 d29549.htm 10-K
Item 4. Mine Safety Disclosures 25
16 rewritten, 0 added, 0 removed, 30 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
Selected Financial Data [removed: 30][added: 29]
Management’s Discussion and Analysis of Financial Condition and Results of Operations [removed: 31][added: 30]
Changes in and Disagreements With Accountants on Accounting and Financial Disclosure [removed: 47][added: 46]
Controls and Procedures [removed: 47][added: 46]
Other Information [removed: 50][added: 49]
| PART III | | | | | | | | | [removed: 51] [added: 50] | |
Directors, Executive Officers of the Registrant and Corporate Governance [removed: 51][added: 50]
Executive Compensation [removed: 51][added: 50]
Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters [removed: 52][added: 51]
Certain Relationships and Related Transactions, and Director Independence [removed: 52][added: 51]
Principal Accountant Fees and Services [removed: 52][added: 51]
| PART IV | | | | | | | | | [removed: 53] [added: 52] | |
Exhibits and Financial Statement Schedules [removed: 53][added: 52]
_This Annual Report on Form 10-K for the fiscal year ended July 31, [removed: 2012,] [added: 2013,] or this Form 10-K, including the information incorporated by reference herein, contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended (the Securities Act), and Section 21E of the Securities Exchange Act of 1934, as amended (the Exchange Act).
We may from time to time make additional written and oral forward-looking statements, including statements contained in [removed: the Company’s] [added: our] filings with the SEC.
We do not undertake to update any forward-looking statement that may be made from time to time by or on behalf of [removed: the Company._][added: us._]
Item 2. Properties
3 rewritten, 2 added, 2 removed, 5 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
This facility consists of approximately 53,000 square feet of [removed: leased] office space under a lease which expires in fiscal 2024.
[removed: We also] [added: In Brazil, we] own or lease [removed: an additional 155] [added: five] operating facilities.
In the U.S., we have facilities in every state except Delaware, [removed: New Hampshire,] North Dakota, Rhode Island, South Dakota, Vermont and Wyoming.
In the U.A.E., we lease one operating facility.
In Germany and Spain we operate online platforms.
In addition, we own approximately 10,000 square feet of office space near the previous corporate headquarters in Fairfield, California which houses certain corporate departments that are not currently moving to the Dallas, Texas headquarters.
In August 2012, we acquired a facility in Dubai, UAE.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
20 rewritten, 17 added, 23 removed, 59 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
As of July 31, [removed: 2012,] [added: 2013,] we had [removed: 1,617] [added: 1,415] stockholders of record.
On July 31, [removed: 2012,] [added: 2013,] the last reported sale price of our common stock on the NASDAQ Global Select Market was [removed: $23.76] [added: $32.51] per share.
| [removed: Fiscal] [added: Fiscal] Year 2012 | | | | High | | | | Low | | |
| [removed: Fiscal] [added: Fiscal] Year [removed: 2011] [added: 2013] | | | | High | | | | Low | | |
[removed: In fiscal 2012,] [added: On September 22, 2011,] our Board of Directors approved a 40 million share increase in the stock repurchase program, bringing the total current authorization to 98 million shares.
For the fiscal year ended July 31, [removed: 2010,] [added: 2013,] we repurchased [removed: 242,502] [added: 500,000] shares of our common stock at a weighted average price of [removed: $18.38.][added: $27.77.]
As of July 31, [removed: 2012,] [added: 2013,] the total number of shares repurchased under the program was [removed: 49,786,782] [added: 50,286,782] and [removed: 48,213,218] [added: 47,713,218] shares were available for repurchase under our program.
Our directors and executive officers were expressly prohibited from participating in the tender offer by our board of directors under our [removed: Securities] [added: Insider] Trading Policy.
[removed: The] shares accepted for purchase are comprised of the 21,052,630 shares we offered to purchase and an additional 3,291,546 shares purchased pursuant to our right to purchase additional shares up to 2% of our outstanding shares.
The dilutive earnings per share impact of all repurchased shares on the weighted average number of common shares outstanding for the year ended July 31, [removed: 2012] [added: 2013] is [removed: $0.04.][added: less than $0.01.]
| May 1, [removed: 2012] [added: 2013] through May 31, [removed: 2012] [added: 2013] | | | | | — | | | | — | | | | — | | | | [removed: 51,013,218] [added: 47,713,218] | |
| [removed: June 1, 2012 through June 30, 2012] [added: Fourth Quarter] | | | | | 2,800,000 | | | $ | 23.22 | | | | 2,800,000 | | | | 48,213,218 | |
| July 1, [removed: 2012] [added: 2013] through July 31, [removed: 2012] [added: 2013] | | | | | — | | | | — | | | | — | | | | [removed: 48,213,218] [added: 47,713,218] | |
In the [removed: first] [added: first, second and third quarters of fiscal year 2012 and the second] quarter of fiscal year [removed: 2010, Mr. Jay Adair, Chief Executive Officer (and then President),] [added: 2013 certain executive officers] exercised stock options through cashless exercises.
We remitted [removed: $2.6] [added: $0.6] million, [removed: $4.2] [added: $2.6] million and [removed: $7.4] [added: $4.2] million, in fiscal [removed: 2012, 2011] [added: 2013, 2012] and [removed: 2010,] [added: 2011,] respectively, to the proper taxing authorities in satisfaction of the employees’ minimum statutory withholding requirements.
| FY 2012—Q3 | | | | | 322,520 | | | $ | 10.74 | | | | [removed: 131,298] [added: 131,299] | | | | [removed: 85,684] [added: 85,683] | | | | 105,538 | | | $ | 26.38 | | | $ | 2,260 | |
There were no issuances of unregistered securities in the quarter ended July 31, [removed: 2012.][added: 2013.]
The following is a line graph comparing the cumulative total return to stockholders of our common stock at July 31, [removed: 2012] [added: 2013] since July 31, [removed: 2007,] [added: 2008,] to the cumulative total return over such period of (i) the NASDAQ Composite Index, (ii) the NASDAQ Industrial Index, and (iii) the NASDAQ Q-50 (NXTQ).
[removed: ][added: 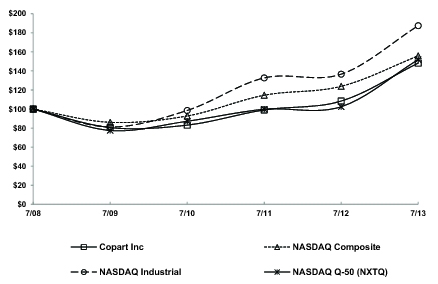]
| * | | Assumes that $100.00 was invested on July 31, [removed: 2007] [added: 2008] in our common stock, in the NASDAQ Composite Index, the NASDAQ Industrial Index and the NASDAQ Q-50 (NXTQ), and that all dividends were reinvested. No dividends have been declared on our common stock. Stockholder returns over the indicated period should not be considered indicative of future stockholder returns. |
As of July 31, 2013, there were 125,494,995 shares outstanding.
| Fourth Quarter | | | | | 38.26 | | | | 30.11 | |
| Third Quarter | | | | | 36.93 | | | | 31.30 | |
| Second Quarter | | | | | 37.47 | | | | 28.39 | |
| First Quarter | | | | | 28.98 | | | | 23.28 | |
The
| _Fiscal 2013_ | | | | | | | | | | | | | | | | | | |
| First Quarter | | | | | 500,000 | | | $ | 27.77 | | | | 500,000 | | | | 47,713,218 | |
| Second Quarter | | | | | — | | | | — | | | | — | | | | 47,713,218 | |
| Third Quarter | | | | | — | | | | — | | | | — | | | | 47,713,218 | |
| June 1, 2013 through June 30, 2013 | | | | | — | | | | — | | | | — | | | | 47,713,218 | |
| FY 2013—Q2 | | | | | 73,228 | | | $ | 8.89 | | | | 18,127 | | | | 17,461 | | | | 37,640 | | | $ | 35.91 | | | $ | 627 | |
| | | | | 7/08 | | | | 7/09 | | | | 7/10 | | | | 7/11 | | | | 7/12 | | | | 7/13 | | |
| Copart, Inc. | | | | $ | 100.00 | | | $ | 80.51 | | | $ | 83.08 | | | $ | 99.07 | | | $ | 108.34 | | | $ | 148.24 | |
| NASDAQ Composite | | | | $ | 100.00 | | | $ | 86.02 | | | $ | 92.70 | | | $ | 114.49 | | | $ | 123.84 | | | $ | 155.80 | |
| NASDAQ Industrial | | | | $ | 100.00 | | | $ | 81.18 | | | $ | 98.49 | | | $ | 132.68 | | | $ | 136.59 | | | $ | 187.49 | |
| NASDAQ Q-50 (NXTQ) | | | | $ | 100.00 | | | $ | 77.47 | | | $ | 87.18 | | | $ | 99.77 | | | $ | 102.40 | | | $ | 151.88 | |
As of July 31, 2012, there were 124,393,700 shares outstanding.
Throughout this report, share and per share amounts have been adjusted as appropriate to reflect the two-for-one stock split effected in the form of a stock dividend distributed after close of trading on March 28, 2012.
| Fourth Quarter | | | | | 23.99 | | | | 21.52 | |
| Third Quarter | | | | | 22.82 | | | | 19.74 | |
| Second Quarter | | | | | 20.44 | | | | 16.50 | |
| First Quarter | | | | | 18.37 | | | | 15.64 | |
| _Fiscal 2010 _ | | | | | | | | | | | | | | | | | | |
| First Quarter | | | | | — | | | | — | | | | — | | | | 30,701,062 | |
| Second Quarter | | | | | — | | | | — | | | | — | | | | 30,701,062 | |
| Third Quarter | | | | | — | | | | — | | | | — | | | | 30,701,062 | |
| Fourth Quarter | | | | | 242,502 | | | $ | 18.38 | | | | 242,502 | | | | 30,458,560 | |
In the fourth quarter of fiscal year 2010, Mr. Willis J.
Johnson, Chairman of the Board, exercised stock options through a cashless exercise.
In the first, second and third quarters of fiscal year 2012 certain executive officers exercised stock options through cashless exercises.
| Period | | | | Options Exercised | | | | Exercise Price | | | | Shares Net Settled for Exercise | | | | Shares Withheld for Taxes(1) | | | | Net Shares to Employee | | | | Share Price for Withholding | | | | Tax Withholding (in 000’s) | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| FY 2010—Q1 | | | | | 647,262 | | | $ | 6.52 | | | | 228,708 | | | | 191,492 | | | | 227,062 | | | $ | 18.45 | | | $ | 3,533 | |
| FY 2010—Q4 | | | | | 700,000 | | | $ | 6.46 | | | | 245,844 | | | | 211,654 | | | | 242,502 | | | $ | 18.38 | | | $ | 3,890 | |
| | | | | 7/07 | | | | 7/08 | | | | 7/09 | | | | 7/10 | | | | 7/11 | | | | 7/12 | | |
| Copart, Inc. | | | | $ | 100.00 | | | $ | 155.86 | | | $ | 125.48 | | | $ | 129.50 | | | $ | 154.41 | | | $ | 168.87 | |
| NASDAQ Composite | | | | $ | 100.00 | | | $ | 87.14 | | | $ | 82.39 | | | $ | 92.16 | | | $ | 113.03 | | | $ | 117.69 | |
| NASDAQ Industrial | | | | $ | 100.00 | | | $ | 85.75 | | | $ | 68.73 | | | $ | 83.86 | | | $ | 110.22 | | | $ | 111.19 | |
| NASDAQ Q-50 (NXTQ) | | | | $ | 100.00 | | | $ | 90.75 | | | $ | 106.56 | | | $ | 118.10 | | | $ | 155.37 | | | $ | 166.78 | |
Item 6. Selected Financial Data
25 rewritten, 1 added, 2 removed, 9 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
The following selected consolidated statements of income data for the years ended July 31, [removed: 2012, 2011] [added: 2013, 2012] and [removed: 2010] [added: 2011] and the consolidated balance data at July 31, [removed: 2012] [added: 2013] and [removed: 2011,] [added: 2012,] are derived from the audited consolidated financial statements appearing elsewhere in this Annual Report on Form 10-K.
The following selected consolidated statements of income data for the years ended July 31, [removed: 2009] [added: 2010] and [removed: 2008] [added: 2009] and the consolidated balance sheet data at July 31, [removed: 2010, 2009] [added: 2011, 2010] and [removed: 2008,] [added: 2009,] are derived from the audited consolidated financial statements that are not included in this Annual Report on Form 10-K.
[added: | * | |] As a result of the adoption of Accounting Standards Update [removed: 2009—13,] [added: 2009–13,] _Revenue Arrangements with Multiple Deliverables_, for the year ended July 31, 2011, we accelerated recognition of $14.4 million in service revenue and $13.5 million in related yard operation expenses. [added: |]
| | | | | [removed: 2012] [added: 2013] | | | | [removed: 2011] [added: 2012] | | | | [removed: 2010] [added: 2011*] | | | | [removed: 2009] [added: 2010] | | | | [removed: 2008] [added: 2009] | | | |
| | | | | (in thousands, except per [removed: share and other data)] [added: share)] | | | | | | | | | | | | | | | | | | | |
| Revenues | | | | $ | [removed: 924,191] [added: 1,046,386] | | | $ | [removed: 872,246] [added: 924,191] | | | $ | [removed: 772,879] [added: 872,246] | | | $ | [removed: 743,082] [added: 772,879] | | | $ | [removed: 784,848] [added: 743,082] | | |
| Operating income | | | | | [removed: 286,353] [added: 282,992] | | | | [removed: 265,290] [added: 286,353] | | | | [removed: 239,070] [added: 265,290] | | | | [removed: 225,325] [added: 239,070] | | | | [removed: 237,917] [added: 225,325] | | |
| Income from continuing operations before income taxes | | | | | [removed: 278,056] [added: 276,872] | | | | [removed: 263,877] [added: 278,056] | | | | [removed: 239,495] [added: 263,877] | | | | [removed: 227,732] [added: 239,495] | | | | [removed: 249,650] [added: 227,732] | | |
| Income tax expense | | | | | [removed: (95,937] [added: (96,847] | ) | | | [removed: (97,502] [added: (95,937] | ) | | | [removed: (87,868] [added: (97,502] | ) | | | [removed: (88,186] [added: (87,868] | ) | | | [removed: (92,718] [added: (88,186] | ) | |
| Income from continuing operations | | | | | [removed: 182,119] [added: 180,025] | | | | [removed: 166,375] [added: 182,119] | | | | [removed: 151,627] [added: 166,375] | | | | [removed: 139,546] [added: 151,627] | | | | [removed: 156,932] [added: 139,546] | | |
| Income from discontinued operations, net of income tax effects | | | | | — | | | | — | | | | — | | | | [removed: 1,557] [added: —] | | | | [removed: —] [added: 1,557] | | |
| Net income | | | | | [removed: 182,119] [added: 180,025] | | | | [removed: 166,375] [added: 182,119] | | | | [removed: 151,627] [added: 166,375] | | | | [removed: 141,103] [added: 151,627] | | | | [removed: 156,932] [added: 141,103] | | |
| Income from continuing operations | | | | $ | [removed: 1.42] [added: 1.44] | | | $ | [removed: 1.10] [added: 1.42] | | | $ | [removed: 0.90] [added: 1.10] | | | $ | [removed: 0.84] [added: 0.90] | | | $ | [removed: 0.90] [added: 0.84] | | |
| Discontinued operations | | | | | — | | | | — | | | | — | | | | [removed: 0.01] [added: —] | | | | [removed: —] [added: 0.01] | | |
| Net income per share | | | | $ | [removed: 1.42] [added: 1.44] | | | $ | [removed: 1.10] [added: 1.42] | | | $ | [removed: 0.90] [added: 1.10] | | | $ | [removed: 0.85] [added: 0.90] | | | $ | [removed: 0.90] [added: 0.85] | | |
| Weighted average shares | | | | | [removed: 128,120] [added: 124,912] | | | | [removed: 151,298] [added: 128,120] | | | | [removed: 168,330] [added: 151,298] | | | | [removed: 167,074] [added: 168,330] | | | | [removed: 174,824] [added: 167,074] | | |
| Income from continuing operations | | | | $ | 1.39 | | | $ | [removed: 1.08] [added: 1.39] | | | $ | [removed: 0.89] [added: 1.08] | | | $ | [removed: 0.82] [added: 0.89] | | | $ | [removed: 0.87] [added: 0.82] | | |
| Discontinued operations | | | | | — | | | | — | | | | — | | | | [removed: 0.01] [added: —] | | | | [removed: —] [added: 0.01] | | |
| Net income per share | | | | $ | 1.39 | | | $ | [removed: 1.08] [added: 1.39] | | | $ | [removed: 0.89] [added: 1.08] | | | $ | [removed: 0.83] [added: 0.89] | | | $ | [removed: 0.87] [added: 0.83] | | |
| Weighted average shares | | | | | [removed: 131,428] [added: 129,781] | | | | [removed: 153,352] [added: 131,428] | | | | [removed: 170,054] [added: 153,352] | | | | [removed: 169,860] [added: 170,054] | | | | [removed: 179,716] [added: 169,860] | | |
| Cash, cash equivalents and short-term investments | | | | $ | [removed: 140,112] [added: 63,631] | | | $ | [removed: 74,009] [added: 140,112] | | | $ | [removed: 268,188] [added: 74,009] | | | $ | [removed: 162,691] [added: 268,188] | | | $ | [removed: 38,954] [added: 162,691] | | |
| Working capital | | | | | [removed: 134,908] [added: 67,893] | | | | [removed: 75,242] [added: 134,908] | | | | [removed: 330,191] [added: 75,242] | | | | [removed: 212,349] [added: 330,191] | | | | [removed: 84,501] [added: 212,349] | | |
| Total assets | | | | | [removed: 1,155,066] [added: 1,334,481] | | | | [removed: 1,084,436] [added: 1,154,000] | | | | [removed: 1,228,812] [added: 1,084,436] | | | | [removed: 1,058,032] [added: 1,228,812] | | | | [removed: 956,247] [added: 1,058,032] | | |
| Total debt | | | | | [removed: 444,120] [added: 372,457] | | | | [removed: 375,756] [added: 444,120] | | | | [removed: 975] [added: 375,756] | | | | [removed: 1,457] [added: 975] | | | | [removed: 2,240] [added: 1,457] | | |
| Stockholders’ equity | | | | | [removed: 561,117] [added: 762,401] | | | | [removed: 555,172] [added: 561,117] | | | | [removed: 1,087,234] [added: 555,172] | | | | [removed: 921,459] [added: 1,087,234] | | | | [removed: 798,996] [added: 921,459] | | |
| --- | --- | --- |
| Other Data | | | | | | | | | | | | | | | | | | | | | | | |
| Number of storage facilities | | | | | 155 | | | | 153 | | | | 152 | | | | 147 | | | | 143 | | |
Item 9A. Controls and Procedures
8 rewritten, 1 added, 2 removed, 41 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
We conducted an evaluation of the effectiveness of the design and operation of our disclosure controls and procedures [removed: (as] [added: _(_as] defined in Rules 13a-15(e) and 15d-15(e) under the Exchange Act), or Disclosure Controls, as of the end of the period covered by this Annual Report on Form 10-K.
Management assessed our internal control over financial reporting as of July 31, [removed: 2012,] [added: 2013,] the end of our fiscal year.
Management based its assessment on criteria established in Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway [removed: Commission.][added: Commission (1992 Framework).]
[added: The certifications of our principal executive officer] and principal financial officer attached as Exhibits 31.1 and 31.2 to this report include, in paragraph 4 of such certifications, information concerning our disclosure controls and procedures and internal controls over financial reporting.
Our independent registered public accounting firm, Ernst & Young LLP, independently assessed the effectiveness of our internal control over financial reporting as of July 31, [removed: 2012.][added: 2013.]
We have audited Copart, Inc.’s internal control over financial reporting as of July 31, [removed: 2012,] [added: 2013,] based on criteria established in Internal Control—Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission [added: (1992 Framework)] (the COSO criteria).
In our opinion, Copart, Inc. maintained, in all material respects, effective internal control over financial reporting as of July 31, [removed: 2012,] [added: 2013,] based on the COSO criteria.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated balance sheets of Copart, Inc. as of July 31, [removed: 2012] [added: 2013] and [removed: 2011,] [added: 2012,] and the related consolidated statements of income, comprehensive income, stockholders’ equity, and cash flows for each of the three years in the period ended July 31, [removed: 2012] [added: 2013] of Copart, Inc. and our report dated [removed: October 1, 2012] [added: September 30, 2013] expressed an unqualified opinion thereon.
September 30, 2013
The certifications of our principal executive officer
October 1, 2012
Item 9B. Other Information
1 rewritten, 1 added, 3 removed, 2 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
Certain information required by Part III is omitted from this Annual Report on Form 10-K because we intend to file a definitive proxy statement for our [removed: 2012] [added: 2013] Annual Meeting of Stockholders (the Proxy Statement) not later than 120 days after the end of the fiscal year covered by this Annual Report on Form 10-K, and certain information to be included therein is incorporated herein by reference.
None.
An updated form of indemnification agreement applicable to our directors and certain of our officers was approved in January 2012.
The form was intended to update the current form for our reincorporation into Delaware and general developments in corporate law since the adoption of our original form of indemnification agreement and was done as part of our ordinary course of corporate governance matters.
A copy of the form of agreement is attached as Exhibit 10.17 to this Report on Form 10-K.
Item 10. Directors, Executive Officers of the Registrant and Corporate Governance
3 rewritten, 0 added, 0 removed, 13 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
Information required by this item concerning our Board of Directors, the members of our Audit Committee, our Audit Committee Financial Expert, and compliance with Section 16(a) of the Securities Exchange Act of 1934 is incorporated by reference to the sections entitled “Proposal Number One Election of Directors,” “Corporate Governance and Board of Directors” and “Related Person Transactions and Section 16(a) Beneficial Ownership Compliance” in our Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2012] [added: 2013] fiscal year end).
Information required by this item concerning our Executive Officers is incorporated by reference to the section entitled “Executive Officers” in our Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2012] [added: 2013] fiscal year end).
Information required by this item with respect to material changes to the procedures by which our stockholders may recommend nominees to our Board of Directors is incorporated herein by reference from the information provided under the heading “Corporate Governance and Board of Directors,” subheading “Director Nomination Process,” of our Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2012] [added: 2013] fiscal year end).
Item 11. Executive Compensation
1 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
The information required by this item is incorporated herein by reference from the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2012] [added: 2013] fiscal year end) under the heading “Executive Compensation,” “Compensation of Non-Employee Directors,” and “Corporate Governance and Board of Directors.”
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
1 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
The information required by this item is incorporated herein by reference from the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2012] [added: 2013] fiscal year end) under the headings “Security Ownership” and “Execution Compensation,” subheading “Equity Compensation Plan Information.”
Item 13. Certain Relationships and Related Transactions, and Director Independence
1 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
The information required by this item is incorporated herein by reference from the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2012] [added: 2013] fiscal year end) under the heading “Related Person Transactions and Section 16(a) Beneficial Ownership Compliance,” “Corporate Governance and Board of Directors,” and “Proposal Number One Election of Directors.”
Item 14. Principal Accountant Fees and Services
2 rewritten, 0 added, 1 removed, 1 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
The information required by this item is incorporated herein by reference from the section captioned “Proposal Three — Ratification of Appointment of Independent Registered Public Accounting Firm” in the Proxy Statement (to be filed with the Securities and Exchange Commission within 120 days of our July 31, [removed: 2012] [added: 2013] fiscal year end).
PART [removed: IV][added: IV]
Item 15. Exhibits and Financial Statement Schedules
382 rewritten, 197 added, 222 removed, 685 unchanged
Read the full itemFY2013 item · filed September 30, 2013FY2012 item · filed October 1, 2012
| (a) 1. | | | | _Financial [removed: Statements:_Index] [added: Statements:_ Index] to Consolidated Financial Statements | | | | | | |
| | | | | Report of Independent Registered Public Accounting Firm | | | | | [removed: 59] [added: 58] | |
| | | | | Consolidated Balance Sheets at July 31, [removed: 2012] [added: 2013] and [removed: 2011] [added: 2012] | | | | | [removed: 60] [added: 59] | |
| | | | | Consolidated Statements of Income for the years ended July 31, [removed: 2012, 2011] [added: 2013, 2012] and [removed: 2010] [added: 2011] | | | | | [removed: 61] [added: 60] | |
| | | | | Consolidated Statements of Comprehensive Income for the years ended July 31, [removed: 2012, 2011] [added: 2013, 2012] and [removed: 2010] [added: 2011] | | | | | [removed: 62] [added: 61] | |
| | | | | Consolidated Statements of Stockholders’ Equity for the years ended July 31, [removed: 2012, 2011] [added: 2013, 2012] and [removed: 2010] [added: 2011] | | | | | [removed: 63] [added: 62] | |
| | | | | Consolidated Statements of Cash Flows for the years ended July 31, [removed: 2012, 2011] [added: 2013, 2012] and [removed: 2010] [added: 2011] | | | | | [removed: 64] [added: 63] | |
| | | | | Notes to Consolidated Financial Statements | | | | | [removed: 65] [added: 64] | |
| 2. | | | | _Financial Statement [removed: Schedules:_All] [added: Schedules:_ All] schedules are omitted because they are not applicable or the required information is shown in the consolidated financial statements or notes [removed: thereto] [added: thereto.] | | | | | | |
| 3. | | | | [removed: _Exhibits:_The] [added: _Exhibits:_ The] following Exhibits are filed as part of, or incorporated by reference into this [removed: report.] [added: report.] | | | | | | |
| 4.3 | | | | Amendment to Preferred Stock Rights Agreement, as of January 10, [removed: 2012,] [added: 2013,] between the Registrant and Computershare Trust Company, N.A. (formerly Equiserve Trust Company, N.A.) | | | | 8/A-12G/A (File No. 000-23255), Exhibit 4.3 | | | | January 10, 2012 | | | |
| 10.14 | | | | Executive Officer Employment Agreement between the Registrant and [removed: Greg A. Tucker,] [added: Vincent Phillips,] dated [removed: October 29, 2008] [added: April 12, 2010] | | | | Current Report on Form 8-K (File No. 000-23255), Exhibit No. [removed: 10.3] [added: 10.4] | | | | December 15, 2010 | | | |
| [removed: 10.16] [added: 10.15] | | | | Standard Industrial/Commercial single tenant lease-net dated January 3, 2011 between Partnership HealthPlan of California and the Registrant | | | | Annual Report on Form 10-K (File No. 000-23254), Exhibit No. 10.21 | | | | September 28, 2011 | | | |
| [removed: 10.17*] [added: 10.16*] | | | | Form of Indemnification Agreement signed by executive officers and directors | | | | [removed: —] [added: Annual Report on Form 10-K (File No. 000-23255), Exhibit No. 10.17] | | | | [removed: Filed herewith] [added: October 1, 2012] | | | |
| [removed: 10.18] [added: 10.17] | | | | Standard Industrial/Commercial single tenant lease-net dated February 3, [removed: 2012] [added: 2013] between Garden Centura, L.P. and the Registrant | | | | [removed: —] [added: Annual Report on Form 10-K (File No. 000-23255), Exhibit No. 10.18] | | | | [removed: Filed herewith] [added: October 1, 2012] | | | |
| [removed: 101.INS(2)] [added: 101.INS] | | | | XBRL Instance Document | | | | | | | | | | | |
| [removed: 101.SCH(2)] [added: 101.SCH] | | | | XBRL Taxonomy Extension Schema Document | | | | | | | | | | | |
| [removed: 101.CAL(2)] [added: 101.CAL] | | | | XBRL Taxonomy Extension Calculation Linkbase Document | | | | | | | | | | | |
| [removed: 101.DEF(2)] [added: 101.DEF] | | | | XBRL Extension Definition | | | | | | | | | | | |
| [removed: 101.LAB(2)] [added: 101.LAB] | | | | XBRL Taxonomy Extension Label Linkbase Document | | | | | | | | | | | |
| [removed: 101.PRE(2)] [added: 101.PRE] | | | | XBRL Taxonomy Extension Presentation Linkbase Document | | | | | | | | | | | |
| (1) | | | | In accordance with Item 601(b)(32)(ii) of Regulation S-K and SEC Release No. 33-8238 and 34-47986, Final Rule: Management’s Reports on Internal Control Over Financial Reporting and Certification of Disclosure in Exchange Act Periodic Reports, the certifications furnished in Exhibits 32.1 and 32.2 hereto are deemed to accompany this Form [removed: 10-Q] [added: 10-K] and will not be deemed “filed” for purposes of Section 18 of the Exchange Act. Such certifications will not be deemed to be incorporated by reference into any filings under the Securities Act or the Exchange Act, except to the extent that the registrant specifically incorporates it by reference. | | | | | | | | | | |
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the [removed: undersigned,] [added: undersigned] thereunto duly authorized.
| /s/ A. JAYSON ADAIRA. Jayson Adair | | | | Chief Executive Officer (Principal Executive Officer and Director) | | | | [removed: October 1, 2012] [added: September 30, 2013] | | |
| /s/ WILLIAM E. FRANKLINWilliam E. Franklin | | | | Senior Vice President of Finance and Chief Financial Officer (Principal Financial and Accounting Officer) | | | | [removed: October 1, 2012] [added: September 30, 2013] | | |
| /s/ WILLIS J. JOHNSONWillis J. Johnson | | | | Chairman of the Board | | | | [removed: October 1, 2012] [added: September 30, 2013] | | |
| /s/ JAMES E. MEEKSJames E. Meeks | | | | Director | | | | [removed: October 1, 2012] [added: September 30, 2013] | | |
| /s/ STEVEN D. COHANSteven D. Cohan | | | | Director | | | | [removed: October 1, 2012] [added: September 30, 2013] | | |
| /s/ DANIEL ENGLANDERDaniel Englander | | | | Director | | | | [removed: October 1, 2012] [added: September 30, 2013] | | |
| /s/ THOMAS N. TRYFOROSThomas N. Tryforos | | | | Director | | | | [removed: October 1, 2012] [added: September 30, 2013] | | |
| /s/ MATT BLUNTMatt Blunt | | | | Director | | | | [removed: October 1, 2012] [added: September 30, 2013] | | |
| /s/ VINCENT W. MITZVincent W. Mitz | | | | President and Director | | | | [removed: October 1, 2012] [added: September 30, 2013] | | |
We have audited the accompanying consolidated balance sheets of Copart, Inc. as of July 31, [removed: 2012] [added: 2013] and [removed: 2011,] [added: 2012,] and the related consolidated statements of income, comprehensive income, stockholders’ equity, and cash flows for each of the three years in the period ended July 31, [removed: 2012.][added: 2013.]
In our opinion, the financial statements referred to above present fairly, in all material respects, the consolidated financial position of Copart, Inc. at July 31, [removed: 2012] [added: 2013] and [removed: 2011,] [added: 2012,] and the consolidated results of its operations and its cash flows for each of the three years in the period ended July 31, [removed: 2012,] [added: 2013,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), Copart, Inc.’s internal control over financial reporting as of July 31, [removed: 2012,] [added: 2013,] based on criteria established in Internal Control-Integrated Framework issued by the Committee of Sponsoring Organizations of the Treadway Commission [added: (1992 Framework)] and our report dated [removed: October 1, 2012] [added: September 30, 2013] expressed an unqualified opinion thereon.
[removed: (in] [added: (in] thousands, except share [removed: amounts)][added: amounts)]
| | | | | July 31, [removed: 2012] [added: 2013] | | | | July 31, [removed: 2011 |] [added: 2012] | | | | [added: July 31, 2011] | | |
| ASSETS | | | | | | | | | | | | [removed: | | | |]
| Current assets: | | | | | | | | | | | | [removed: | | | |]
| Cash and cash equivalents | | | | $ | [removed: 140,112] [added: 63,631] | | | $ | [removed: 74,009 | | | |] [added: 140,112] | | |
| 10.18 | | | | Executive Officer Employment Agreement between the Registrant and John Lindle, dated June 1, 2013 | | | | — | | | | Filed herewith | | | |
September 30, 2013
September 30, 2013
September 30, 2013
| Accounts receivable, net | | | | | 182,714 | | | | 137,900 | | |
| Total current assets | | | | | 306,452 | | | | 321,227 | | |
| Total assets | | | | $ | 1,334,481 | | | $ | 1,154,000 | | |
| | | | | | | | | | | | |
| Bank overdraft | | | | | 16,291 | | | | — | | |
| Total current liabilities | | | | | 238,559 | | | | 186,319 | | |
| Total liabilities | | | | | 572,080 | | | | 592,883 | | |
| | | | | | | | | | | | |
| Total liabilities and stockholders’ equity | | | | $ | 1,334,481 | | | $ | 1,154,000 | | |
| Unrealized gain (loss) on interest rate swaps, net of tax effects of $(1,647), $1,045, and $0 | | | | | 2,993 | | | | (1,749 | ) | | | — | | |
| Reclassification adjustment of interest rate swaps to net income, net of tax effects of $874, $717, and $0 | | | | | (1,624 | ) | | | (1,361 | ) | | | — | | |
| Net income | | | | | — | | | | — | | | | — | | | | — | | | | 180,025 | | | | 180,025 | |
| Exercise of stock options, net of repurchased shares | | | | | 1,516,534 | | | | 1 | | | | 21,370 | | | | — | | | | (943 | ) | | | 20,428 | |
| Shares repurchased | | | | | (500,000 | ) | | | — | | | | (2,622 | ) | | | — | | | | (11,263 | ) | | | (13,885 | ) |
| Balances at July 31, 2013 | | | | | 125,494,995 | | | $ | 13 | | | $ | 368,769 | | | $ | (47,161 | ) | | $ | 440,780 | | | $ | 762,401 | |
| Accounts receivable | | | | | (31,171 | ) | | | (16,004 | ) | | | (12,506 | ) | |
| Change in bank overdraft | | | | | 16,291 | | | | — | | | | — | | |
Significant intercompany transactions and balances have been eliminated in consolidation.
In Germany and Spain, the Company derives revenue from sales listing fees for listing vehicles on behalf of insurance companies.
criteria for separate units of accounting.
The Company applies the provisions of accounting guidance for subsequent measurement of inventory to our vehicle pooling costs.
The provision requires that items such as idle facility expense, double freight and re-handling costs be recognized as current period charges regardless of whether they meet the criteria of “abnormal” as provided in the guidance.
In addition, the guidance requires that the allocation of fixed production overhead to the costs of conversion be based on the normal capacity of production facilities.
In early November 2012, Hurricane Sandy hit the northeastern coast of the United States.
As a result of the extensive flooding that it caused, the Company expended additional costs for (i) temporary storage facilities; (ii) premiums for subhaulers as they were reassigned from other regions; and (iii) labor costs incurred for overtime, travel and lodging due to the reassignment of employees to the affected region.
These costs, which are characterized as “abnormal” under ASC 330, _Inventory_, were expensed as incurred and not included in inventory.
At July 31, 2013, the incremental salvage vehicles received as a result of Hurricane Sandy have been sold.
The Company records foreign currency translation adjustments from the process of translating the functional currency of the financial statements of its foreign subsidiaries into the U.S. dollar reporting currency.
The Company recognizes, within yard operation expenses, the costs of pre-sale services, including towing, title processing, and preparation and storage, at the time the related services are provided.
_Bank Overdraft_
As a result of maintaining a consolidated cash management system, the Company utilizes controlled disbursement bank accounts.
These accounts are funded as checks are presented for payment, not when checks are issued.
The resulting bank overdraft position is included in current liabilities.
transportation and other equipment; 3 to 10 years for office furniture and equipment; and 15 to 40 years or the lease term, whichever is shorter, for buildings and improvements.
The impairment test consists of a comparison of the fair value of the intangible asset with its carrying amount.
In February 2013, the FASB issued ASU 2013-02, “_Reporting Amounts Reclassified Out of Accumulated Other Comprehensive Income_,” which amends ASC 220, “_Comprehensive Income_.” The amended guidance requires entities to provide information about the amounts reclassified out of accumulated other comprehensive income by component.
| --- | --- | --- |
| 10.15 | | | | Executive Officer Employment Agreement between the Registrant and Vincent Phillips, dated April 12, 2010 | | | | Current Report on Form 8-K (File No. 000-23255), Exhibit No. 10.4 | | | | December 15, 2010 | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| (2) | | | | XBRL information is furnished and not filed or a part of a registration statement or prospectus for purposes of sections 11 or 12 of the Securities Exchange Act of 1933, as amended, is deemed not filed for purposes of section 18 of the Securities Exchange Act of 1934, as amended, and otherwise is not subject to liability under these sections. | | | | | | | | | | |
| * | | Management contract, plan or arrangement |
| --- | --- | --- |
October 1, 2012
October 1, 2012
As discussed in Note 1 to the consolidated financial statements, effective August 1, 2010, the Company adopted on a prospective basis Auditing Standards Update 2009 -13, _Revenue Arrangements with Multiple Deliverables_.
October 1, 2012
COPART, INC.
| Accounts receivable, net | | | | | 138,966 | | | | 122,859 | | | | | | |
| Total current assets | | | | | 322,293 | | | | 241,868 | | | | | | |
| Total assets | | | | $ | 1,155,066 | | | $ | 1,084,436 | | | | | | |
| | | | | | | | | | | | | | | | |
| Other current liabilities | | | | | 785 | | | | 4,929 | | | | | | |
| Total current liabilities | | | | | 187,385 | | | | 166,626 | | | | | | |
| Total liabilities | | | | | 593,949 | | | | 529,264 | | | | | | |
| | | | | | | | | | | | | | | | |
| Total liabilities and stockholders’ equity | | | | $ | 1,155,066 | | | $ | 1,084,436 | | | | | | |
| Balances at July 31, 2009 | | | | | 167,877,628 | | | $ | 17 | | | $ | 334,423 | | | $ | (27,082 | ) | | $ | 614,101 | | | $ | 921,459 | |
| Net income | | | | | — | | | | — | | | | — | | | | — | | | | 151,627 | | | | 151,627 | |
| Exercise of stock options, net of repurchased shares | | | | | 954,930 | | | | — | | | | 5,351 | | | | — | | | | (7,315 | ) | | | (1,964 | ) |
| Shares repurchased | | | | | (242,502 | ) | | | — | | | | (512 | ) | | | — | | | | (3,945 | ) | | | (4,457 | ) |
| Accounts receivable | | | | | (16,202 | ) | | | (12,865 | ) | | | 2,436 | | |
| Issuance of notes receivable | | | | | — | | | | — | | | | (1,300 | ) | |
| --- | --- | --- |
As a result of the Reincorporation, for the year ended July 31, 2012, the Company reclassified $12,000 to common stock, par value to reflect the change in par value from no par to $.0001 per share.
On March 8, 2012, the Company’s board of directors approved a two-for-one stock split effected in the form of a stock dividend.
The additional shares resulting from the stock split were distributed after the closing of trading on March 28, 2012 to stockholders of record on March 23, 2012.
The stock dividend increased the number of shares of common stock outstanding and all per share amounts have been adjusted for the stock dividend.
Copart Canada was incorporated in January 2003 and Copart Europe was incorporated in June 2007.
NOTES TO CONSOLIDATED FINANCIAL STATEMENTS (Continued)
technology and vehicle delivery, loading, title processing, preparation and storage.
As a result of this adoption, for the year ended July 31, 2011, the Company accelerated recognition of $14.4 million in service revenue and $13.5 million in related yard operation expenses.
The impact on net income and earnings per share was not material.
The functional currency of the Company is the U.S. dollar.
respectively, as they are the primary currencies within the economic environment in which each subsidiary operates.
On August 1, 2010, the Company adopted ASU 2009-13.
An excerpt. Shown here: 40 of 382 rewritten, 40 of 197 added and 40 of 222 removed. The counts are complete. For every sentence, read Item 15. Exhibits and Financial Statement Schedules in the FY2013 filing and the FY2012 filing.