 filings.tools
Item 1. Business
67K characters. Original on sec.gov · Markdown
Item 1. Business
Through its three lines of business of small commercial, middle & large commercial, and global specialty, Commercial Lines offers its products and services to businesses in the United States ("U.S.") and internationally. Commercial Lines generally consists of products written for small businesses and middle market companies as well as national and multi-national accounts, largely distributed through retail agents and brokers, wholesale agents and global and specialty reinsurance brokers. The majority of Commercial Lines written premium is generated by small commercial and middle market, which provide coverage options and customized pricing based on the policyholder’s individual risk characteristics. Small commercial and middle market lines within middle & large commercial are generally referred to as standard commercial lines.
Small commercial provides coverages for small businesses, which the Company generally considers to be businesses with an annual payroll under $12, revenues under $25 and property values less than $20 per location. Within small commercial, both property and general liability coverages are offered under a single package policy, marketed under the Spectrum name. Through Maxum Specialty Insurance Group ("Maxum"), small commercial also provides excess and surplus lines coverage to small businesses including umbrella, general liability, property and other coverages.
Middle & large commercial business provides insurance coverages to medium-sized and national accounts businesses, which are companies whose payroll, revenue and property values exceed the small business definition. In addition to offering standard commercial lines products, middle & large commercial includes program business which provides tailored programs, primarily to customers with common risk characteristics. On national accounts, a significant portion of the business is written through large deductible programs. Other programs written within middle & large commercial are retrospectively-rated where the premiums are adjustable based on loss experience. Also within middle & large commercial, the Company writes captive programs business, which provides tailored programs to those seeking a loss sensitive solution where premiums are adjustable based on loss experience.
Global specialty provides a variety of customized insurance products, including property, liability, marine, professional liability, bond and accident and health reinsurance. On May 23, 2019, the Company' acquired Navigators Group, a global specialty insurer. The vast majority of the business written by our Navigators Group insurance subsidiaries is reported in the global specialty business unit. Revenues and earnings of the Navigators Group business are included in operating results of the Company's Commercial Lines segment since the acquisition date. For discussion of this transaction, see Note 2- Business Acquisitions of Notes to Consolidated Financial Statements.
Marketing and Distribution
Commercial Lines provides insurance products and services through the Company’s regional offices, branches and sales and policyholder service centers throughout the United States and overseas, principally in Europe. The products are marketed and distributed using independent retail agents and brokers, wholesale agents and global and specialty reinsurance brokers. As the sole corporate member of Lloyd's Syndicate 1221 ("Lloyd's Syndicate"), the Company has the exclusive right to underwrite
business up to an approved level of premium in the Lloyd’s of London (“Lloyd’s”) market.
In the United States, the independent agent and broker distribution channel is consolidating and this trend is expected to continue. This will likely result in a larger proportion of written premium being concentrated among fewer agents and brokers. In addition, the Company offers insurance products to customers of payroll service providers through its relationships with major national payroll companies in the United States and to members of affinity organizations.
Competition
Small Commercial
In small commercial, The Hartford competes against large national carriers, regional carriers and direct writers. Competitors include stock companies, mutual companies and other underwriting organizations. The small commercial market remains highly competitive and fragmented as carriers seek to differentiate themselves through product expansion, price reduction, enhanced service and leading technology. Larger carriers such as The Hartford continually advance their pricing sophistication and ease of doing business with agents and customers through the use of technology, analytics and other capabilities that improve the process of evaluating a risk, quoting new business and servicing customers. The Company also continuously enhances digital capabilities as customers and distributors demand more access and convenience, and expands product and underwriting capabilities to accommodate both larger accounts and a broader risk appetite. Existing competitors and new entrants, including start-up and non-traditional carriers, are actively looking to expand sales of business insurance products to small businesses through increasing their underwriting appetite, deepening their relationships with distribution partners, and through on-line and direct-to-consumer marketing.
Middle & Large Commercial
Middle & large commercial business is considered “high touch” and involves individual underwriting and pricing decisions. Competition in this market includes stock companies, mutual companies, alternative risk sharing groups and other underwriting organizations. The pricing of middle market and national accounts is prone to significant volatility over time due to changes in individual account characteristics and exposure, as well as legislative and macro-economic forces. National and regional carriers participate in the middle & large commercial insurance sector, resulting in a competitive environment where pricing and policy terms are critical to securing new business and retaining existing accounts. Within this competitive environment, The Hartford is working to deepen its product and underwriting capabilities, leverage its sales and underwriting talent and expand its use of data analytics to make risk selection and pricing decisions. In product development and related areas such as claims and risk engineering, the Company is extending its capabilities in industry verticals, such as energy, construction, technology and life sciences. Through business partners, the Company offers business insurance coverages to exporters and other U.S. companies with a physical presence overseas. The Hartford’s middle & large commercial business will leverage the investments in product, underwriting, and technology to better match price to individual risk as the firm pursues responsible growth strategies to deliver target returns.
Part I - Item 1. Business
For specialty casualty businesses within middle & large commercial, pricing competition continues to be significant, particularly for the larger individual accounts. As a means to mitigate the cost of insurance on larger accounts, more insureds may opt for the loss-sensitive products offered in our national accounts segment, including retrospectively rated contracts, in lieu of guaranteed cost policies. Under a retrospectively-rated contract, the ultimate premium collected from the insured is adjusted based on how incurred losses for the policy year develop over time, subject to a minimum and maximum premium.
Global Specialty
Global specialty competes against multi-national insurance and reinsurance companies, writing marine, property, excess casualty, professional liability, bond and assumed reinsurance. Global specialty also includes excess and surplus lines written through Maxum, including umbrella, general liability, property and other coverages. Due to adverse loss experience over the past couple of years, particularly in ocean marine, property, excess casualty and international professional liability lines, pricing has increased across the industry in response to those loss cost trends. Nonetheless, the market continues to be highly competitive.
In the bond business, favorable underwriting results in recent years has led to increased competition for market share.
In professional liability, international, large and medium-sized businesses are in differing competitive environments. Large public director & officers coverage, specifically excess layers, is under significant competitive price pressure. The middle market private management liability segment is in a more stable competitive and pricing environment.
Lloyd's syndicate and London market business has been under financial stress in recent years due to a perceived lack of adequate premium pricing and an excessive focus on growth at the expense of underwriting discipline in those markets, combined with a significant increase in the level of catastrophe activity. As such, syndicates and London market carriers, including The Hartford, are taking pricing and underwriting actions to improve profitability. Lloyd's of London ("Lloyd's"), which is regulated by the Financial Conduct Authority and Prudential Regulatory Authority in the U.K., has been implementing changes to improve performance of the syndicates including a more rigorous approach to the approval of syndicate business plans. Additionally Lloyd’s have also introduced recent changes which require that members limit the amount of tier 2 capital (e.g. letters of credit) that can be used to meet syndicate solvency capital requirements.
| PERSONAL LINES |
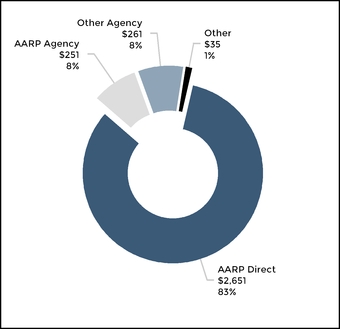
2019 Earned Premiums of $3,198 by Line of Business
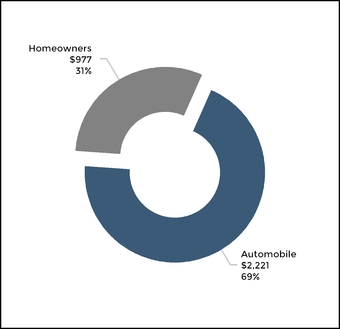
2019 Earned Premiums of $3,198 by Product
Part I - Item 1. Business
Principal Products and Services
| Automobile | Covers damage to an individual insured’s own vehicle due to collision or other perils and is referred to as automobile physical damage. In addition to first party automobile physical damage, automobile insurance covers liability for bodily injuries and property damage suffered by third parties and losses caused by uninsured or underinsured motorists. Also, under no-fault laws, policies written in some states provide first party personal injury protection. Some of the Company’s personal automobile insurance policies also offer personal umbrella liability coverage for an additional premium. |
| Homeowners | Insures against losses to residences and contents from fire, wind and other perils. Homeowners insurance includes owned dwellings, rental properties and coverage for tenants. The policies may provide other coverages, including loss related to recreation vehicles or watercraft, identity theft and personal items such as jewelry. |
Personal Lines provides automobile, homeowners and personal umbrella coverages to individuals across the United States, including a program designed exclusively for members of AARP (“AARP Program”). The Hartford's automobile and homeowners products provide coverage options and pricing tailored to a customer's individual risk. The Hartford has individual customer relationships with AARP Program policyholders and, as a group, they represent a significant portion of the total Personal Lines' business. Business sold to AARP members, either direct or through independent agents, amounted to earned premiums of $2.9 billion, $3.0 billion and $3.2 billion in 2019, 2018 and 2017, respectively.
During 2019, Personal Lines continued to refine its automobile and home product offerings marketed under the Open Road Auto and Home Advantage names. Overall rate levels, price segmentation, rating factors and underwriting procedures were examined and updated to reflect the company’s actual experience with these products. Personal Lines works with carrier partners to provide risk protection options for AARP members with needs beyond the company’s current product offering.
Marketing and Distribution
Personal Lines reaches diverse customers through multiple distribution channels, including direct-to-consumer and independent agents. In direct-to-consumer, Personal Lines markets its products through a mix of media, including direct mail, digital marketing, television as well as digital and print advertising. Through the agency channel, Personal Lines provides products and services to customers through a network of independent agents in the standard personal lines market, primarily serving mature, preferred consumers. These independent agents are not employees of the Company.
Personal Lines has made significant investments in offering direct and agency-based customers the opportunity to interact with the company online, including via mobile devices. In addition, its technology platform for telephone sales centers enables sales representatives to provide an enhanced experience for direct-to-consumer customers, positioning the Company to offer unique capabilities to AARP’s member base.
Most of Personal Lines' sales are associated with its exclusive licensing arrangement with AARP, with the current agreement in place through January 1, 2023, to market automobile, homeowners and personal umbrella coverages to AARP's approximately 37 million members, primarily direct but also through independent agents. This relationship with AARP, which has been in place since 1984, provides Personal Lines with an important competitive advantage given the increase in the
population of those over age 50 and the strength of the AARP brand. In most states, auto and home policies issued to AARP members include a lifetime continuation agreement endorsement, providing that the policies will be renewed as long as certain terms are met, such as timely payment of premium and maintaining a driver’s license in good standing.
In addition to selling to AARP members, Personal Lines offers its automobile and homeowners products to non-AARP customers, primarily through the independent agent channel within select underwriting markets where we believe we have a competitive advantage. Personal Lines leverages its agency channel to target AARP members and other customer segments that value the advice of an independent agent and recognize the differentiated experience the Company provides. In particular, the Company has taken action to distinguish its brand and improve profitability in the independent agent channel with fewer and more highly partnered agents.
Competition
The personal lines automobile and homeowners insurance markets are highly competitive. Personal lines insurance is written by insurance companies of varying sizes that compete principally on the basis of price, product, service, including claims handling, the insurer's ratings and brand recognition. Companies with strong ratings, recognized brands, direct sales capability and economies of scale will have a competitive advantage. In recent years, insurers have increased their advertising in the direct-to-consumer market, in an effort to gain new business and retain profitable business. The growth of direct-to-consumer sales, including through new entrants to the marketplace, continues to outpace sales in the agency distribution channel.
Insurers that distribute products principally through agency channels compete by offering commissions and additional incentives to attract new business. To distinguish themselves in the marketplace, top tier insurers are offering on-line and self-service capabilities that make it easier for agents and consumers to do business with the insurer. A large majority of agents have been using “comparative rater” tools that allow the agent to compare premium quotes among several insurance companies. The use of comparative rater tools increases price competition. Insurers that are able to capitalize on their brand and reputation, differentiate their products and deliver strong customer service are more likely to be successful in this market.
The use of data mining and predictive modeling is used by more and more carriers to target the most profitable business, and carriers have further segmented their pricing plans to expand market share in what they believe to be the most profitable segments. The Company continues to invest in capabilities to better utilize data and analytics, and thereby, refine and manage
Part I - Item 1. Business
underwriting and pricing.
Also, new automobile technology advancements, including lane departure warnings, backup cameras, automatic braking and active collision alerts, are being deployed rapidly and are
expected to improve driver safety and reduce the likelihood of vehicle collisions. However, these features include expensive parts, potentially increasing average claim severity.
| PROPERTY & CASUALTY OTHER OPERATIONS |
Property & Casualty Other Operations includes certain property and casualty operations, managed by the Company, that have discontinued writing new business and includes substantially all of the Company's pre-1986 asbestos and environmental ("A&E") exposures. For a discussion of coverages provided under policies
written with exposure to A&E prior to 1986, reported within the P&C Other Operations segment (“Run-off A&E”), run-off assumed reinsurance and all other non-A&E exposures, see Part II, Item 7, MD&A - Critical Accounting Estimates, Property & Casualty Insurance Product Reserves.
| GROUP BENEFITS |
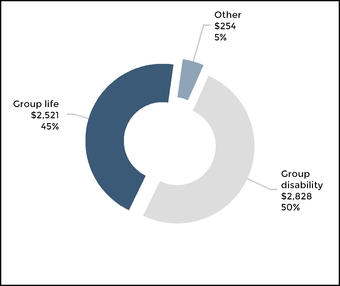
2019 Premiums and Fee Income of $5,603
Principal Products and Services
| Group Life | Typically is term life insurance provided in the form of yearly renewable term life insurance. Other life coverages in this category include accidental death and dismemberment and travel accident insurance. |
| Group Disability | Typically comprised of short-term disability, long-term disability, and family leave coverage that pays a percentage of an employee’s salary for a period of time if they are ill or injured and cannot perform the duties of their job or absent from work to care for a family member. Short-term and long-term disability policies have elimination periods that must be satisfied prior to benefit payments. The Company also earns fee income from leave management services and the administration of underwriting, enrollment and claims processing for employer self-funded plans. |
| Other Products | Includes other group coverages such as retiree health insurance, critical illness, accident, hospital indemnity and participant accident coverages. |
Group insurance typically covers an entire group of people under a single contract, most typically the employees of a single employer or members of an association.
Group Benefits provides group life, disability and other group coverages to members of employer groups, associations and affinity groups through direct insurance policies and provides reinsurance to other insurance companies. In addition to employer paid coverages, the segment offers voluntary product
coverages which are offered through employee payroll deductions. Group Benefits also offers disability underwriting, administration, and claims processing to self-funded employer plans. In addition, the segment offers a single-company leave management solution, which integrates work absence data from the insurer’s short-term and long-term group disability and workers’ compensation insurance business with its leave management administration services.
Part I - Item 1. Business
Group Benefits generally offers term insurance policies, allowing for the adjustment of rates or policy terms in order to minimize the adverse effect of market trends, loss costs, declining interest rates and other factors. Policies are typically sold with one, two or three-year rate guarantees depending upon the product and market segment.
On November 1, 2017, the Company's group benefits subsidiary, Hartford Life and Accident Insurance Company ("HLA") acquired Aetna's U.S. group life and disability business through a reinsurance transaction. Revenues and earnings of the Aetna U.S. group life and disability business are included in operating results of the Company's Group Benefits segment since the acquisition date. For discussion of this transaction, see Note 2- Business Acquisitions of Notes to Consolidated Financial Statements.
Marketing and Distribution
The Group Benefits distribution network is managed through a regional sales office system to distribute its group insurance products and services through a variety of distribution outlets including brokers, consultants, third-party administrators and trade associations. Additionally, the segment has relationships with several private exchanges which offer its products to employer groups.
The acquisition of Aetna's U.S. group life and disability business in 2017 further enhanced Group Benefit's distribution footprint by increasing its sales force. The acquisition also provided Group Benefits an exclusive, multi year collaboration to sell it's group life and disability products through Aetna's medical sales team.
Competition
Group Benefits competes with numerous insurance companies and financial intermediaries marketing insurance products. In
order to differentiate itself, Group Benefits uses its risk management expertise and economies of scale to derive a competitive advantage. Competitive factors include the extent of products offered, price, the quality of customer and claims handling services, and the Company's relationship with third-party distributors and private exchanges. Active price competition continues in the marketplace, resulting in multi-year rate guarantees being offered to customers. Top tier insurers in the marketplace also offer on-line and self-service capabilities to third party distributors and consumers. The relatively large size and underwriting capacity of the Group Benefits business provides a competitive advantage over smaller competitors.
Group Benefits' acquisition of Aetna's U.S. group life and disability business further increased its market presence and competitive capabilities through the addition of industry-leading digital technology and an integrated absence management and claims platform.
Additionally, as employers continue to focus on reducing the cost of employee benefits, we expect more companies to offer voluntary products paid for by employees. Competitive factors affecting the sale of voluntary products include the breadth of products, product education, enrollment capabilities and overall customer service.
The Company has expanded its employer group product offerings, including the voluntary product suite, encompassing coverages for short term absences from work, critical illness and accident coverages. The Company's enhanced enrollment and marketing tools, such as My Tomorrow©, are providing additional opportunities to educate individual participants about supplementary benefits and deepen their knowledge about product selection.
| HARTFORD FUNDS |
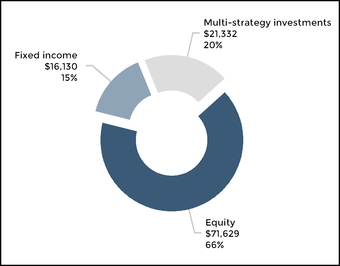
**Hartford Funds Segment Assets Under Management ("AUM") of $**126,958 as of December 31, 2019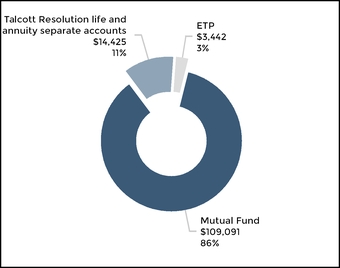
Mutual Fund AUM as of December 31, 2019
Part I - Item 1. Business
Principal Products and Services
| Mutual Funds | Includes approximately 70 actively managed mutual funds across a variety of asset classes including domestic and international equity, fixed income, and multi-strategy investments, principally subadvised by two unaffiliated institutional asset management firms that have comprehensive global investment capabilities. |
| ETP | Includes a suite of exchange-traded products (“ETP”) traded on the New York Stock Exchange that is comprised of multi-factor and actively managed fixed income exchange-traded funds ("ETF"). Multi-factor ETF’s are designed to track indices using both active and passive investment techniques that strive to improve performance relative to traditional capitalization weighted indices. |
| Talcott Resolution life and annuity separate accounts | Relates to assets of the life and annuity business sold in May 2018 that are still managed by the Company's Hartford Funds segment. |
The Hartford Funds segment provides investment management, administration, product distribution and related services to investors through a diverse set of investment products in domestic and international markets. Hartford Funds' comprehensive range of products and services assist clients in achieving their desired investment objectives. AUM are separated into three distinct categories referred to as mutual funds, ETP and Talcott Resolution life and annuity separate accounts, which relate to the life and annuity business sold in May 2018. The Hartford Funds segment will continue to manage the mutual fund assets of Talcott Resolution, though these assets are expected to continue to decline over time.
Marketing and Distribution
Our funds and ETPs are sold through national and regional broker-dealer organizations, independent financial advisers, defined contribution plans, financial consultants, bank trust
groups and registered investment advisers. Our distribution team is organized to sell primarily in the United States. The investment products for Talcott Resolution are not actively distributed.
Competition
The investment management industry is mature and highly competitive. Firms are differentiated by investment performance, range of products offered, brand recognition, financial strength, proprietary distribution channels, quality of service and level of fees charged relative to quality of investment products. The Hartford Funds segment competes with a large number of asset management firms and other financial institutions and differentiates itself through superior fund performance, product breadth, strong distribution and competitive fees. In recent years demand for lower cost passive investment strategies has outpaced demand for actively managed strategies and has taken market share from active managers.
| CORPORATE |
The Company includes in the Corporate category investment management fees and expenses related to managing third party business, including management of the invested assets of Talcott Resolution, reserves for run-off structured settlement and terminal funding agreement liabilities, capital raising activities (including equity financing, debt financing and related interest expense), transaction expenses incurred in connection with an acquisition, purchase accounting adjustments related to goodwill and other expenses not allocated to the reporting segments.
Additionally, included in the Corporate category are discontinued operations from the Company's life and annuity business sold in May 2018 and a 9.7% ownership interest in the legal entity that acquired this business. The operating results of the life and annuity business are included in discontinued operations for all periods prior to the closing date.
Part I - Item 1. Business
RESERVES
Total Reserves as of December 31, 2019 [1]

| [1] | Includes reserves for future policy benefits and other policyholder funds and benefits payable of $635 and $755*, respectively, of which* $411 and $459*, respectively, relate to the Group Benefits segment with the remainder related to run-off structured settlement and terminal funding agreements within Corporate.* |
The reserve for unpaid losses and loss adjustment expenses includes a liability for unpaid losses, including those that have been incurred but not yet reported, as well as estimates of all expenses associated with processing and settling these insurance claims, including reserves related to both Property & Casualty and Group Benefits.
Total Property & Casualty Reserves as of December 31, 2019
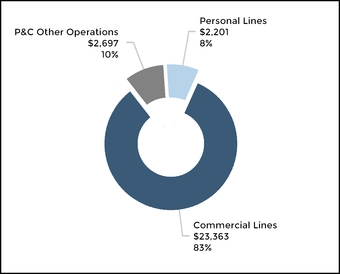
Further discussion of The Hartford’s property and casualty insurance product reserves, including run-off asbestos and environmental claims reserves within P&C Other Operations, may be found in Part II, Item 7, MD&A — Critical Accounting Estimates — Property and Casualty Insurance Product Reserves. Additional discussion may be found in Notes to Consolidated Financial Statements, including in the Company’s accounting policies for insurance product reserves within Note 1 - Basis of Presentation and Significant Accounting Policies and in Note 11 - Reserve for Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements.
Total Group Benefits Reserves as of December 31, 2019 [1]
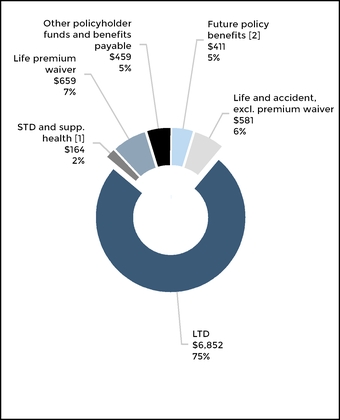
[1]Includes $118 of short-term disability reserves and $46 of supplemental health reserves.
[2]Includes $294 of paid up life reserves and policy reserves on life policies, $105 of reserves for conversions to individual life and $12 of other reserves.
Other policyholder funds and benefits payable represent deposits from policyholders where the company does not have insurance risk but is subject to investment risk. Reserves for future policy benefits represent life-contingent reserves for which the company is subject to insurance and investment risk.
Discussion of The Hartford's Group Benefits long-term disability reserves may be found in Part II, Item 7, MD&A — Critical Accounting Estimates — Group Benefits Long-term Disability ("LTD") Reserves, Net of Reinsurance. Additional discussion may be found in Note 11 - Reserve for Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements.
Part I - Item 1. Business
UNDERWRITING FOR P&C AND GROUP BENEFITS
The Company underwrites the risks it insures in order to manage exposure to loss through favorable risk selection and diversification. Risk modeling is used to manage, within specified limits, the aggregate exposure taken in each line of business and across the Company. For property and casualty business, aggregate exposure limits are set by geographic zone and peril. Products are priced according to the risk characteristics of the insured’s exposures. Rates charged for Personal Lines products are filed with the states in which we write business. Rates for Commercial Lines products are also filed with the states but the premium charged may be modified based on the insured’s relative risk profile and workers’ compensation policies may be subject to modification based on prior loss experience. Pricing for Group Benefits products, including long-term disability and life insurance, is also based on an underwriting of the risks and a projection of estimated losses, including consideration of investment income.
Pricing adequacy depends on a number of factors, including the ability to obtain regulatory approval for rate changes, proper evaluation of underwriting risks, the ability to project future loss cost frequency and severity based on historical loss experience adjusted for known trends, the Company’s response to rate actions taken by competitors, its expense levels and expectations about regulatory and legal developments. The Company seeks to price its insurance policies such that insurance premiums and future net investment income earned on premiums received will cover underwriting expenses and the ultimate cost of paying claims reported on the policies and provide for a profit margin. For many of its insurance products, the Company is required to obtain approval for its premium rates from state insurance departments and the Lloyd's Syndicate's ability to write business is subject to Lloyd's approval for its premium capacity each year.
Geographic Distribution of Earned Premium (% of total)
| Location | Commercial Lines | Personal Lines | Group Benefits | Total | ||||
| California | 8 | % | 2 | % | 3 | % | 13 | % |
| New York | 5 | % | 1 | % | 2 | % | 8 | % |
| Texas | 4 | % | 1 | % | 2 | % | 7 | % |
| Florida | 2 | % | 1 | % | 2 | % | 5 | % |
| All other [1] | 30 | % | 14 | % | 23 | % | 67 | % |
| Total | 49 | % | 19 | % | 32 | % | 100 | % |
| [1] | No other single state or country accounted for 5% or more of the Company's consolidated earned premium written in 2019*.* |
CLAIMS ADMINISTRATION FOR P&C AND GROUP BENEFITS
Claims administration includes the functions associated with the receipt of initial loss notices, claims adjudication and estimates, legal representation for insureds where appropriate, establishment of case reserves, payment of losses and notification to reinsurers. These activities are performed by approximately 7,100 claim professionals located in 50 states, Washington D.C and 5 international locations, organized to meet the specific claim service needs for our various product offerings. Our combined workers’ compensation and Group Benefits units enable us to leverage synergies for improved outcomes.
Claim payments for benefit, loss and loss adjustment expenses are the largest expenditure for the Company.
REINSURANCE
For discussion of reinsurance, see Part II, Item 7, MD&A — Enterprise Risk Management and Note 8 - Reinsurance of Notes to Consolidated Financial Statements.
INVESTMENT OPERATIONS
Hartford Investment Management Company (“HIMCO”) is an SEC registered investment advisor and manages the Company's investment operations. HIMCO provides customized investment strategies for The Hartford's investment portfolio, as well as for The Hartford's pension plan and institutional clients. In connection with the life and annuity business sold in May 2018, HIMCO entered into an agreement for an initial five year term to manage the invested assets of Talcott Resolution.
As of December 31, 2019 and 2018, the fair value of HIMCO’s total assets under management was approximately $98.0 billion and $89.6 billion, respectively, including $42.4 billion and $40.2 billion, respectively, that were held in HIMCO managed third party accounts and $4.1 billion and $3.6 billion, respectively, that support the Company's pension and other post-retirement benefit plans.
Management of The Hartford's Investment Portfolio
HIMCO manages the Company's investment portfolios to maximize economic value and generate the returns necessary to support The Hartford’s various product obligations, within internally established objectives, guidelines and risk tolerances. The portfolio objectives and guidelines are developed based upon the asset/liability profile, including duration, convexity and other characteristics within specified risk tolerances. The risk tolerances considered include, but are not limited to, asset sector,
Part I - Item 1. Business
credit issuer allocation limits, and maximum portfolio limits for below investment grade holdings. The Company attempts to minimize adverse impacts to the portfolio and the Company’s results of operations from changes in economic conditions through asset diversification, asset allocation limits, asset/liability duration matching and the use of derivatives. For further discussion of HIMCO’s portfolio management approach, see Part II, Item 7, MD&A — Enterprise Risk Management.
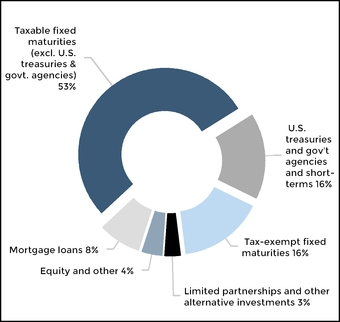
The Hartford's Investment Portfolio of $53.0 billion as of December 31, 2019
ENTERPRISE RISK MANAGEMENT
The Company has insurance, operational and financial risks. For discussion on how The Hartford manages these risks, see Part II, Item 7, MD&A - Enterprise Risk Management.
REGULATION
State and Foreign Insurance Laws
State insurance laws are intended to supervise and regulate insurers with the goal of protecting policyholders and ensuring the solvency of the insurers. As such, the insurance laws and regulations grant broad authority to state insurance departments (“Departments”) to oversee and regulate the business of insurance. The Departments monitor the financial stability of an insurer by requiring insurers to maintain certain solvency standards and minimum capital and surplus requirements; invested asset requirements; state deposits of securities; guaranty fund premiums; restrictions on the size of risks which may be insured under a single policy; and adequate reserves and other necessary provisions for unearned premiums, unpaid losses and loss adjustment expenses and other liabilities, both reported and unreported. In addition, the Departments perform periodic
market and financial examinations of insurers and require insurers to file annual and other reports on the financial condition of the companies. Policyholder protection is also regulated by the Departments through licensing of insurers, sales employees, agents and brokers and others; approval of premium rates and policy forms; claims administration requirements; and maintenance of minimum rates for accumulation of surrender values.
Many states also have laws regulating insurance holding company systems. These laws require insurance companies, which are formed and chartered in the state ( “Domestic Insurers”), to register with the state department of insurance (referred to as their “domestic state or regulator”) and file information concerning the operations of companies within the holding company system that may materially affect the operations, management or financial condition of the insurers within the system. Insurance holding company regulations principally relate to (i) state insurance approval of the acquisition of Domestic Insurers, (ii) prior review or approval of certain transactions between the domestic insurer and its affiliates, and (iii) regulation of dividends made by the domestic insurer. All transactions within a holding company system affecting Domestic Insurers must be determined to be fair and equitable.
The NAIC, the organization that works to promote standardization of best practices and assists state insurance regulatory authorities and insurers, conducted the “Solvency Modernization Initiative” (the “Solvency Initiative”). The effort focused on reviewing the U.S. financial regulatory system and financial regulation affecting insurance companies including capital requirements, corporate governance and risk management, group supervision, statutory accounting and financial reporting and reinsurance. As a result of the Solvency Initiative, the NAIC adopted model regulations, adopted by the Company’s lead regulator of Connecticut, requiring insurers to file disclosures annually on their risk management and corporate governance practices under the Corporate Governance Annual Disclosure Model Act, Risk Management and Own Risk and Solvency Assessment Model Act (ORSA) and Holding Company Act Enterprise Risk Report.
The extent of financial services regulation on business outside the United States varies significantly among the countries in which The Hartford operates. Some countries have minimal regulatory requirements, while others regulate financial services providers extensively. Foreign financial services providers in certain countries are faced with greater restrictions than domestic competitors domiciled in that particular jurisdiction. In addition, an insurance company underwriting risks through the Lloyd’s of London market (“Lloyd’s") utilizes a special vehicle (the “Syndicate”) and is required to comply with Lloyd’s capital requirements. Lloyd’s determines the amount of capital, known as Funds at Lloyd’s (“FAL”), that each Syndicate has to provide in order to support the amount and the level of risk (as determined by Lloyd’s) of the business which the Syndicate is expected to underwrite. Under Solvency II, insurers are required to hold a sufficient level of capital. Syndicates seeking to utilize letters of credit or other third party guarantees to meet Solvency II requirements must first obtain approval from the Prudential Regulation Authority.
Part I - Item 1. Business
Federal and State Securities and Financial Regulation Laws
The Company sells and distributes its mutual funds through a broker dealer subsidiary, and is subject to regulation promulgated and enforced by the Financial Industry Regulatory Authority, the SEC and/or, in some instances, state securities administrators. Other subsidiaries operate as investment advisers registered with the SEC under the Investment Advisers’ Act of 1940, as amended, and are registered as investment advisers under certain state laws, as applicable. Because federal and state laws and regulations are primarily intended to protect investors in securities markets, they generally grant regulators broad rulemaking and enforcement authority. Some of these regulations include, among other things, regulations impacting sales methods, trading practices, suitability of investments, use and safekeeping of customers’ funds, corporate governance, capital, recordkeeping, and reporting requirements.
Failure to comply with federal and state laws and regulations may result in fines, the issuance of cease-and-desist orders or suspension, termination or limitation of the activities of our operations and/or our employees.
INTELLECTUAL PROPERTY
We rely on a combination of contractual rights and copyright, trademark, patent and trade secret laws to establish and protect our intellectual property.
We have a trademark portfolio that we consider important in the marketing of our products and services, including, among others, the trademarks of The Hartford name, the Stag Logo and the
combination of these two trademarks. The duration of trademark registrations may be renewed indefinitely subject to country-specific use and registration requirements. We regard our trademarks as highly valuable assets in marketing our products and services and vigorously seek to protect them against infringement. In addition, we own a number of patents and patent applications relating to on-line quoting, insurance related processing, insurance telematics, proprietary interface platforms, and other matters, some of which may be important to our business operations. Patents are of varying duration depending on filing date, and will typically expire at the end of their natural term.
EMPLOYEES
The Hartford has approximately 19,500 employees as of December 31, 2019.
AVAILABLE INFORMATION
The Company’s Internet address is www.thehartford.com. Our annual report on Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K, and amendments to those reports are available, without charge, on the investor relations section of our website, https://ir.thehartford.com, as soon as reasonably practicable after they are filed electronically with the SEC. Reports filed with the SEC may be viewed at www.sec.gov. References in this report to our website address are provided only as a convenience and do not constitute, and should not be viewed as, an incorporation by reference of the information contained on, or available through, the website. Therefore, such information should not be considered part of this report.
Item 1A. RISK FACTORS
In deciding whether to invest in The Hartford, you should carefully consider the following risks, any of which could have a material adverse effect on our business, financial condition, results of operation or liquidity and could also impact the trading price of our securities. These risks are not exclusive, and additional risks to which we are subject include, but are not limited to, the factors mentioned under “Forward-Looking Statements” above and the risks of our businesses described elsewhere in this Annual Report on Form 10-K.
The following risk factors have been organized by category for ease of use, however many of the risks may have impacts in more than one category. The occurrence of certain of them may, in turn, cause the emergence or exacerbate the effect of others. Such a combination could materially increase the severity of the impact of these risks on our business, results of operations, financial condition or liquidity.
Risks Relating to Economic, Political and Global Market Conditions
Unfavorable economic, political and global market conditions may adversely impact our business and results of operations.
The Company’s investment portfolio and insurance liabilities are sensitive to changes in economic, political and global capital market conditions, such as the effect of a weak economy and changes in credit spreads, equity prices, interest rates, inflation, foreign currency exchange rates, and shifts in demand and supply of U.S. dollars. Weak economic conditions, such as high unemployment, low labor force participation, lower family income, a weak real estate market, lower business investment and lower consumer spending may adversely affect the demand for insurance and financial products and lower the Company’s
Part I - Item 1A. Risk Factors
profitability in some cases. In addition, a deterioration in global economic conditions and/or geopolitical conditions, including due to military action, trade wars, tariffs or other actions with respect to international trade agreements or policies, has the potential to, among other things, reduce demand for our products, reduce exposures we insure, drive higher inflation that could increase the Company’s loss costs and result in increased incidence of claims, particularly for workers’ compensation and disability claims. The Company’s investment portfolio includes limited partnerships and other alternative investments and equity securities for which changes in value are reported in earnings. These investments may be adversely impacted by economic volatility, including real estate market deterioration, which could impact our net investment returns and result in an adverse impact on operating results.
Below are several key factors impacted by changes in economic, political, and global market conditions and their potential effect on the Company’s business and results of operations:
| • | Credit Spread Risk - Credit spread exposure is reflected in the market prices of fixed income instruments where lower rated securities generally trade at a higher credit spread. If issuer credit spreads increase or widen, the market value of our investment portfolio may decline. If the credit spread widening is significant and occurs over an extended period of time, the Company may recognize other-than-temporary impairments, resulting in decreased earnings. If credit spreads tighten, significantly, the Company’s net investment income associated with new purchases of fixed maturities may be reduced. In addition, the value of credit derivatives under which the Company assumes exposure or purchases protection are impacted by changes in credit spreads, with losses occurring when credit spreads widen for assumed exposure or when credit spreads tighten if credit protection has been purchased. |
| • | Equity Markets Risk - A decline in equity markets may result in unrealized capital losses on investments in equity securities recorded against net income and lower earnings from Hartford Funds where fee income is earned based upon the fair value of the assets under management. Equity markets are unpredictable. During 2018 and 2019, the equity markets were more volatile than in prior periods, which could be indicative of a greater risk of a decline. For additional information on equity market sensitivity, see Part II, Item 7, MD&A - Enterprise Risk Management, Financial Risk- Equity Risk. |
| • | Interest Rate Risk - Global economic conditions may result in the persistence of a low interest rate environment which would continue to pressure our net investment income and could result in lower margins on certain products. For additional information on interest rate sensitivity, see Part II, Item 7, MD&A - Enterprise Risk Management, Financial Risk - Interest Rate Risk |
New and renewal business for our property and casualty and group benefits products is priced considering prevailing interest rates. As interest rates decline, in order to achieve the same economic return, we would have to increase product prices to offset the lower anticipated investment income earned on invested premiums. Conversely, as interest rates rise, pricing targets will tend to decrease to reflect higher anticipated investment income. Our ability to
effectively react to such changes in interest rates may affect our competitiveness in the marketplace, and in turn, could reduce written premium and earnings. For additional information on interest rate sensitivity, see Part II, Item 7, MD&A - Enterprise Risk Management, Financial Risk - Interest Rate Risk.
In addition, due to the long-term nature of the liabilities within our Group Benefits operations, particularly for long-term disability, declines in interest rates over an extended period of time would result in our having to reinvest at lower yields. On the other hand, a rise in interest rates, in the absence of other countervailing changes, would reduce the market value of our investment portfolio. A decline in market value of invested assets due to an increase in interest rates could also limit our ability to realize tax benefits from recognized capital losses.
| • | Inflation Risk - Inflation is a risk to our property and casualty business because, in many cases, claims are paid out many years after a policy is written and premium is collected for the risk. Accordingly, a greater than expected increase in inflation related to the cost of medical services and repairs over the claim settlement period can result in higher claim costs than what was estimated at the time the policy was written. Inflation can also affect consumer spending and business investment which can reduce the demand for our products and services. |
| • | Foreign Currency Exchange Rate - Changes in foreign currency exchange rates may impact our non-U.S. dollar denominated investments and foreign subsidiaries. As the Company has expanded its international operations, exposure to exchange rate fluctuations has increased. We hold cash and fixed maturity securities denominated in foreign currencies, including British Pounds and Canadian dollars, among others, and also have other assets and liabilities denominated in foreign currencies such as premiums receivable and loss reserves. While the Company predominately uses asset-liability matching, including the use of derivatives, to hedge certain of these exposures to fluctuations in foreign currency exchange rates, these actions do not eliminate the risk that changes in the exchange rates of foreign currencies to the U.S. dollar could result in financial loss to the Company, including realized or unrealized capital losses resulting from currency revaluation and increases to regulatory capital requirements for foreign subsidiaries that have net assets that are not denominated in their local currency. For additional information on foreign exchange risk, see Part II, Item 7, MD&A - Enterprise Risk Management, Financial Risk. |
Concentration of our investment portfolio increases the potential for significant losses.
The concentration of our investment portfolios in any particular industry, collateral type, group of related industries or geographic sector could have an adverse effect on our investment portfolios and consequently on our business, financial condition, results of operations, and liquidity. Events or developments that have a negative impact on any particular industry, collateral type, group of related industries or geographic region may have a greater adverse effect on our investment portfolio to the extent that the portfolio is concentrated rather than diversified.
Part I - Item 1A. Risk Factors
Further, if issuers of securities or loans we hold are acquired, merge or otherwise consolidate with other issuers of securities or loans held by the Company, our investment portfolio’s credit concentration risk to issuers could increase for a period of time, until the Company is able to sell securities to get back in compliance with the established investment credit policies.
Changing climate and weather patterns may adversely affect our business, financial condition and results of operation.
Climate change presents risks to us as an insurer, investor and employer. Climate models indicate that rising temperatures will likely result in rising sea levels over the decades to come and may increase the frequency and intensity of natural catastrophes and severe weather events. Extreme weather events such as abnormally high temperatures may result in increased losses associated with our property, auto, workers’ compensation and group benefits businesses. Changing climate patterns may also increase the duration, frequency and intensity of heat/cold waves, which may result in increased claims for property damage, business interruption and losses under workers’ compensation, group disability and group life coverages. Precipitation patterns across the U.S. are projected to change, which if realized, may increase risks of flash floods and wildfires. Additionally, there may be an impact on the demand, price and availability of automobile and homeowners insurance, and there is a risk of higher reinsurance costs or more limited availability of reinsurance coverage. Changes in climate conditions may also cause our underlying modeling data to not adequately reflect frequency and severity, limiting our ability to effectively evaluate and manage risks of catastrophes and severe weather events. Among other impacts, this could result in not charging enough premiums or not obtaining timely state approvals for rate increases to cover the risks we insure. We may also experience significant interruptions to the Company’s systems and operations that hinder our ability to sell and service business, manage claims and operate our business.
In addition, climate change-related risks may adversely impact the value of the securities that we hold. The effects of climate change could also lead to increased credit risk of other counterparties we transact business with, including reinsurers. Rising sea levels may lead to decreases in real estate values in coastal areas, reducing premium and demand for commercial property and homeowners insurance and adversely impacting the value of our real estate-related investments. Additionally, government policies or regulations to slow climate change, such as emission controls or technology mandates, may have an adverse impact on sectors such as utilities, transportation and manufacturing, affecting demand for our products and our investments in these sectors.
Changes in security asset prices may impact the value of our fixed income, real estate and commercial mortgage investments, resulting in realized or unrealized losses on our invested assets. Our decision to invest in certain securities and loans may also be impacted by changes in climate patterns due to:
| • | changes in supply/demand characteristics for fuel (e.g., coal, oil, natural gas) |
| • | advances in low-carbon technology and renewable energy development and |
| • | effects of extreme weather events on the physical and operational exposure of industries and issuers |
Because there is significant variability associated with the impacts of climate change, we cannot predict how physical, legal, regulatory and social responses may impact our business.
The discontinuance of LIBOR may adversely affect the value of certain investments we hold and floating rate securities we have issued, and any other assets or liabilities whose value may be tied to LIBOR.
LIBOR is an indicative measure of the average interest rate at which major global banks could borrow from one another. LIBOR is used as a benchmark or reference rate in certain derivatives and floating rate fixed maturities that are part of our investment portfolio, as well as two classes of junior subordinated debentures that we have issued and are currently outstanding.
In July 2017, the U.K. Financial Conduct Authority announced that by the end of 2021, it intends to stop persuading or compelling banks to report information used to set LIBOR, which could result in LIBOR no longer being published after 2021 or a determination by regulators that LIBOR is no longer representative of its underlying market. Since 2017, actions by regulators have resulted in efforts to establish alternative reference rates to LIBOR in several major currencies. The Alternative Reference Rate Committee, a group of private-market participants convened by the Federal Reserve Board and the Federal Reserve Bank of New York, has recommended the Secured Overnight Funding Rate (“SOFR”) as its preferred alternative rate for U.S. dollar LIBOR. SOFR is a measure of the cost of borrowing cash overnight, collateralized by U.S. Treasury securities, and is based on directly observable U.S. Treasury-backed repurchase transactions. The Federal Reserve Bank of New York began publishing daily SOFR in April 2018. Development of broadly accepted methodologies for transitioning from LIBOR, an unsecured forward-looking rate, to SOFR, a secured rate based on historical transactions, is ongoing.
The Company continues to monitor and assess the potential impacts of the discontinuation of LIBOR, which will vary depending on (1) existing contract language to determine a LIBOR replacement rate, referred to as “fallback provisions”, in individual contracts and (2) whether, how, and when industry participants develop and widely adopt new reference rates and fallback provisions for both existing and new products or instruments. At this time, it is not possible to predict how markets will respond to these new rates and the effect that the discontinuation of LIBOR might have on new or existing financial instruments. If LIBOR ceases to exist or is found by regulators to no longer be representative, outstanding contracts with interest rates tied to LIBOR may be adversely affected and impact our results of operations through a reduction in value of some of our LIBOR referenced floating rate investments, an increase in the interest we pay on our outstanding junior subordinated debentures, or an adverse impact to hedge effectiveness of derivatives or availability of hedge accounting. Additionally, any discontinuation of or transition from LIBOR may impact pricing, valuation and risk analytic processes and hedging strategies.
For additional information on the Company’s financial instruments that are tied to LIBOR, see Part II, Item 7, Management's Discussion and Analysis of Financial Condition
Part I - Item 1A. Risk Factors
and Results of Operation, Enterprise Risk Management, Financial Risk.
The withdrawal of the U.K. from the E.U. may adversely affect our business, financial condition and results of operation.
In June 2016, the U.K voted in a national referendum to withdraw from the E.U. (“Brexit”) and formal negotiations on the separation process, including the final exit date, have been ongoing and extended various times. The U.K. officially departed from the E.U. on January 31, 2020, with the existing trade agreement (between the E.U. and U.K.) in effect until its expiration date on December 31, 2020.
Prolonged uncertainty relating to the terms of the U.K.’s withdrawal, could, among other outcomes, cause significant volatility in global financial markets, currency exchange rate fluctuations and asset valuations, and disrupt the U.K. market and the E.U. markets by increasing restrictions on the trade and free movement of goods, services and people between the U.K. and the E.U. The withdrawal could also lead to legal uncertainty and potentially divergent national laws and regulations as the U.K. determines which E.U. laws to replace or replicate.
As a result of the acquisition of Navigators Group, we have international operations in the U.K. and E.U. While Navigators Group has implemented measures to sell business in the E.U. independently of its U.K. insurance companies, either through its own Belgium insurance subsidiary or by having its Lloyd's Syndicate write business through the Lloyd’s subsidiary in Belgium, Brexit may cause disruptions throughout the U.K. and E.U. Should we seek to access the E.U. market through our U.K. insurance companies, that will depend on general trade and services agreements made by the U.K. with the E.U. or on specific arrangements made by our U.K. insurance companies to retain access to the E.U. market. In addition, the ability to access the E.U. market through our Lloyd's Syndicate depends on Lloyd's being able to comply with E.U. regulations through its Belgium subsidiary. The consequence of making such specific arrangements may increase our cost of doing business.
The consequences of U.K.’s withdrawal from the E.U. in the long term are unknown and not quantifiable at this time. However, given the lack of comparable precedent, any effects of a withdrawal may adversely affect our business, financial condition and results of operations.
Insurance Industry and Product Related Risks
Unfavorable loss development may adversely affect our business, financial condition, results of operations and liquidity.
We establish property and casualty loss reserves to cover our estimated liability for the payment of all unpaid losses and loss expenses incurred with respect to premiums earned on our policies. Loss reserves are estimates of what we expect the ultimate settlement and administration of claims will cost, less what has been paid to date. These estimates are based upon actuarial projections and on our assessment of currently available data, as well as estimates of claims severity and frequency, legal
theories of liability and other factors. For risks due to evolving changes in social, economic and environmental conditions, see the Risk Factor, “Unexpected and unintended claim and coverage issues under our insurance contracts may adversely impact our financial performance.”
Loss reserve estimates are refined periodically as experience develops and claims are reported and settled, potentially resulting in increases to our reserves. Increases in reserves would be recognized as an expense during the periods in which these determinations are made, thereby adversely affecting our results of operations for those periods. In addition, since reserve estimates of aggregate loss costs for prior years are used in pricing our insurance products, inaccurate reserves can lead to our products not being priced adequately to cover actual losses and related loss expenses in order to generate a profit.
We continue to receive A&E claims, the vast majority of which relate to policies written before 1986. Estimating the ultimate gross reserves needed for unpaid losses and related expenses for asbestos and environmental claims is particularly difficult for insurers and reinsurers. The actuarial tools and other techniques used to estimate the ultimate cost of more traditional insurance exposures tend to be less precise when used to estimate reserves for some A&E exposures.
Moreover, the assumptions used to estimate gross reserves for A&E claims, such as claim frequency over time, average severity, and how various policy provisions will be interpreted, are subject to significant uncertainty. It is also not possible to predict changes in the legal and legislative environment and their effect on the future development of A&E claims. These factors, among others, make the variability of gross reserves estimates for these longer-tailed exposures significantly greater than for other more traditional exposures.
Effective December 31, 2016, the Company entered into an agreement with National Indemnity Company (“NICO”), a subsidiary of Berkshire Hathaway Inc. (“Berkshire”) whereby the Company is reinsured for subsequent adverse development on substantially all of its net A&E reserves up to an aggregate net limit of $1.5 billion. We remain directly liable to claimants and if the reinsurer does not fulfill its obligations under the agreement or if future adverse development exceeds the $1.5 billion aggregate limit, we may need to increase our recorded net reserves which could have a material adverse effect on our financial condition, results of operations and liquidity. For additional information related to risks associated with the adverse development cover, see Note 11 - Reserve for Unpaid Losses and Loss Adjustment Expenses of Notes to Consolidated Financial Statements.
We are vulnerable to losses from catastrophes, both natural and man-made.
Our insurance operations expose us to claims arising out of catastrophes. Catastrophes can be caused by various unpredictable natural events, including, among others, earthquakes, hurricanes, hailstorms, severe winter weather, wind storms, fires, tornadoes, and pandemics. Catastrophes can also be man-made, such as terrorist attacks, cyber-attacks, explosions or infrastructure failures.
The geographic distribution of our business subjects us to catastrophe exposure for events occurring in a number of areas, including, but not limited to: hurricanes in Florida, the Gulf Coast,
Previous: Cover and table of contents · Next: Item 1A. Risk Factors