 filings.tools
Kimco Realty (KIM) 10-K risk factor changes: FY2016 vs FY2015
The 2016-12-31 10-K against the 2015-12-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A26 rewritten17 added35 removed207 unchanged
All filing items1,288 rewritten1,007 added1,019 removed1,484 unchanged
Summary
counted, not written
- Item 1A lists 21 risk factor headings: 4 new, 3 reworded and 14 unchanged since FY2015. 3 headings from FY2015 no longer appear.
- Sentence by sentence, 1,007 added, 1,019 removed, 1,288 rewritten and 1,484 unchanged across 14 items that differ.
- New this year: Item 16. Form 10-K Summary.
New Item 1A headings (4)
- To maintain our REIT status, we may be forced to borrow funds during unfavorable market conditions, and the unavailability of such capital on favorable terms at the desired times, or at all, may cause us to curtail our investment activities and/or to dispose of assets at inopportune times, which could adversely affect our financial condition, results of operations, cash flow and per share trading price of our common stock.
- The tax imposed on REITs engaging in “prohibited transactions” may limit our ability to engage in transactions which would be treated as sales for federal income tax purposes.
- Construction and development projects are subject to risks that materially increase the costs of completion.
- We have completed, or have nearly completed, our efforts to exit our investments in Mexico, South America and Canada, however, we cannot predict the impact of laws and regulations affecting these international operations, including the United States Foreign Corrupt Practices Act, or the potential that we may face regulatory sanctions.
Removed Item 1A headings (3)
- To maintain our REIT status, we may be forced to borrow funds on a short-term basis during unfavorable market conditions.
- We have certain international operations, which may be affected by economic, political and other risks associated with international operations, and this could adversely affect our business.
- We cannot predict the impact of laws and regulations affecting our international operations nor the potential that we may face regulatory sanctions.
Reworded Item 1A headings (3)
- Loss of our tax status as a
[removed: real estate investment trust][added: REIT] or changes in federal tax laws, regulations, administrative interpretations or court decisions relating to[removed: real estate investment trusts][added: REITs] could have significant adverse consequences to us and the value of our securities. - Unsuccessful
[removed: ground-up][added: real estate under] development activities or a slowdown in[removed: ground-up][added: real estate under] development activities could have a direct impact on our growth, results of operations and cash flows. - We may not be able to recover our investments in
[removed: marketable securities,]mortgage receivables or other investments, which may result in significant losses to us.
A heading is new when no FY2015 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
22 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2016; struck-through words were in FY2015. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
26 rewritten, 17 added, 35 removed, 207 unchanged
Loss of our tax status as [removed: a real estate investment trust] [added: a REIT] or changes in federal tax laws, regulations, administrative interpretations or court decisions relating to [removed: real estate investment trusts] [added: REITs] could have significant adverse consequences to us and the value of our securities.
New legislation, regulations, administrative interpretations or court decisions could significantly [added: and negatively] change the tax laws with respect to qualification as a REIT, the federal income tax consequences of such qualification or the desirability of an investment in a REIT relative to other investments.
| | ● | we would not be allowed a deduction for [removed: distributions] [added: dividends] to stockholders in computing our taxable income and we would be subject to federal income tax at regular corporate rates; |
As a result of all these factors, our failure to qualify as a REIT or [added: new legislation] changes in federal tax laws with respect to qualification as a REIT or the tax consequences of such qualification could also impair our ability to expand our business or raise capital and materially adversely affect the value of our securities.
To qualify as a REIT, we generally must distribute to our stockholders at least 90% of our [removed: REIT] [added: net] taxable income each year, excluding [added: net] capital gains, and we will be subject to regular corporate income taxes on the amount we distribute that is less than 100% of our net taxable income each [removed: year.][added: year, including capital gains.]
Assuming we continue to satisfy these [removed: distributions] [added: distribution] requirements with cash, we may need to borrow funds to meet the REIT distribution requirements [added: and avoid the payment of income and excise taxes] even if the then prevailing market conditions are not favorable for these borrowings.
These borrowing needs could result from differences in timing between the actual receipt of cash and inclusion of income for federal income tax purposes, or the effect of non-deductible capital expenditures, the creation of [added: cash] reserves or required debt or amortization payments.
The economic performance and value of our properties is subject to all of the risks associated with owning and operating real estate, [removed: including:][added: including but not limited to:]
Retailers at our properties may face increasing competition from other retailers, e-commerce, outlet malls, discount shopping clubs, [removed: catalog companies,] direct mail, telemarketing or home shopping networks, all of which could (i) reduce rents payable to us; (ii) reduce our ability to attract and retain tenants at our properties; or (iii) lead to increased vacancy rates at our properties.
At any [removed: time] [added: time,] our [removed: tenants, particularly small local stores,] [added: tenants] may experience a downturn in their business that may significantly weaken their financial condition.
A tenant [removed: or lease guarantor] bankruptcy could delay our efforts to collect past due balances under the relevant leases and could ultimately preclude collection of these sums.
Therefore, we may not be able to vary our portfolio in response to economic or other conditions promptly or on terms favorable to us within a [removed: time frame] [added: timeframe] that we would need.
We may [removed: acquire or] [added: acquire or] develop properties or acquire other real estate related [removed: companies, and] [added: companies, and] this may create risks.
[removed: Unsuccessful ground-up development] [added: Unsuccessful real estate under development] activities or a slowdown [removed: in ground-up development] [added: in real estate under development] activities could have a direct impact on our growth, results of operations and cash flows.
[removed: Property ground-up] [added: Real estate under] development is a component of our operating and investment strategy.
We intend to continue pursuing select [removed: ground-up] [added: real estate under] development opportunities for long-term investment and construction of retail and/or mixed use properties as opportunities arise.
Our [removed: ground-up] [added: real estate under] development and construction activities include the following risks:
| | ● | [removed: We] [added: we] may abandon [removed: ground-up] [added: real estate under] development opportunities after expending resources and could lose all or part of our investment in such opportunities, including loss of deposits or failure to recover expenses already incurred; |
Additionally, new [removed: ground-up] [added: real estate under] development activities typically require substantial time and attention from management, and the time frame required for development, construction and lease-up of these properties could require several years to realize any significant cash return.
The co-venturer or partner may fail to provide capital or fulfill its obligations, which may result in certain liabilities to us for guarantees and other [removed: commitments, conflicts arising between us and our partners and the difficulty of managing and resolving such conflicts, and the difficulty of managing or otherwise monitoring such business arrangements.][added: commitment.]
We [added: have completed, or have nearly completed, our efforts to exit our investments in Mexico, South America and Canada, however, we] cannot predict the impact of laws and regulations affecting [removed: our] [added: these] international [removed: operations nor] [added: operations, including] the [added: United States Foreign Corrupt Practices Act, or the] potential that we may face regulatory sanctions.
Our international operations [added: have] included properties in Canada, Mexico, Chile, Brazil and Peru and are subject to a variety of United States and foreign laws and regulations, including the United States Foreign Corrupt Practices Act [removed: (“FCPA”).][added: (“FCPA”) and foreign tax laws and regulations.]
In addition, we cannot predict the [removed: nature, scope or effect of future regulatory requirements to which our international operations might be subject, the] manner in which [removed: existing] [added: such] laws [added: or regulations] might be administered or interpreted, or [added: when, or] the potential that we may face regulatory [removed: sanctions.][added: sanctions or tax audits as a result of our international operations.]
We [removed: are cooperating] [added: have cooperated, and will continue to cooperate,] with the SEC [removed: investigation] and [removed: a parallel investigation by] the U.S. Department of Justice [removed: (“DOJ”).][added: (“DOJ”), which is conducting a parallel investigation.]
We may not be able to recover our investments in [removed: marketable securities, mortgage] [added: mortgage] receivables or other investments, which may result in significant losses to us.
In these [removed: instances] [added: instances,] we may need to protect a particular investment by making payments to maintain the current status of a prior lien or discharge it entirely.
We believe that we are organized and operate in a manner that has allowed us to qualify and will allow us to remain qualified as a REIT under the Code.
The rules dealing with federal income taxation are constantly under review by persons involved in the legislative process and by the IRS and U.S. Department of the Treasury.
We cannot predict how changes in the tax laws might affect our investors or us.
To maintain our REIT status, we may be forced to borrow funds during unfavorable market conditions, and the unavailability of such capital on favorable terms at the desired times, or at all, may cause us to curtail our investment activities and/or to dispose of assets at inopportune times, which could adversely affect our financial condition, results of operations, cash flow and per share trading price of our common stock.
These sources, however, may not be available on favorable terms or at all.
Our access to third-party sources of capital depends on a number of factors, including the market's perception of our growth potential, our current debt levels, the market price of our common stock, and our current and potential future earnings.
We cannot assure you that we will have access to such capital on favorable terms at the desired times, or at all, which may cause us to curtail our investment activities and/or to dispose of assets at inopportune times, and could adversely affect our financial condition, results of operations, cash flow and per share trading price of our common stock.
The tax imposed on REITs engaging in “prohibited transactions” may limit our ability to engage in transactions which would be treated as sales for federal income tax purposes.
A REIT's net income from prohibited transactions is subject to a 100% penalty tax.
In general, prohibited transactions are sales or other dispositions of property, other than foreclosure property, held primarily for sale to customers in the ordinary course of business.
Although we do not intend to hold any properties that would be characterized as held for sale to customers in the ordinary course of our business, unless a sale or disposition qualifies under certain statutory safe harbors, such characterization is a factual determination and no guarantee can be given that the IRS would agree with our characterization of our properties or that we will always be able to make use of the available safe harbors.
Construction and development projects are subject to risks that materially increase the costs of completion.
In the event that we decide to develop and construct new properties or redevelop existing properties, we will be subject to risks and uncertainties associated with construction and development.
These risks include, but are not limited to, risks related to obtaining all necessary zoning, land-use, building occupancy and other governmental permits and authorizations, risks related to the environmental concerns of government entities or community groups, risks related to changes in economic and market conditions between development commencement and stabilization, risks related to construction labor disruptions, adverse weather, acts of God or shortages of materials which could cause construction delays and risks related to increases in the cost of labor and materials which could cause construction costs to be greater than projected and adversely impact the amount of our development fees or our results of operations or financial condition.
Conflicts arising between us and our partners may be difficult to manage and/or resolve and it could be difficult to manage or otherwise monitor the existing business arrangements.
Although we have completely, or have nearly completed, our efforts to exit our investments in Mexico, South America and Canada, we cannot assure you that our past or any current international operations will continue to be found to be in compliance with such laws or regulations.
At this point, we are unable to predict the duration, scope or result of the SEC or DOJ investigations.
We believe that we have operated so as to qualify as a REIT under the Code and that our current organization and method of operation comply with the rules and regulations promulgated under the Code to enable us to continue to qualify as a REIT.
| --- | --- | --- |
To maintain our REIT status, we may be forced to borrow funds on a short-term basis during unfavorable market conditions.
We have certain international operations, which may be affected by economic, political and other risks associated with international operations, and this could adversely affect our business.
The risks we face in international business operations include, but are not limited to:
| | ● | currency risks, including currency fluctuations; |
| | ● | unexpected changes in legislative and regulatory requirements, including changes in applicable laws and regulations in the United States that affect foreign operations; |
| | ● | potential adverse tax burdens; |
| | ● | burdens of complying with different accounting and permitting standards, labor laws and a wide variety of foreign laws; |
| | ● | obstacles to the repatriation of earnings and cash; |
| | ● | regional, national and local political uncertainty; |
| | ● | economic slowdown and/or downturn in foreign markets; |
| | ● | difficulties in staffing and managing international operations; |
| | ● | difficulty in administering and enforcing corporate policies, which may be different than the normal business practices of local cultures; and |
| | ● | reduced protection for intellectual property in some countries. |
Each of these risks might impact our cash flow or impair our ability to borrow funds, which ultimately could adversely affect our business, financial condition, operating results and cash flows.
In order to operate internationally, we must overcome cultural and language barriers and assimilate different business practices.
In addition, we are required to create compensation programs, employment policies and other administrative programs that comply with laws of multiple countries.
We also must communicate and monitor standards and directives in our international locations.
Our failure to successfully manage our geographically diverse operations could impair our ability to react quickly to changing business and market conditions and to enforce compliance with standards and procedures.
Since a portion of our revenues are generated internationally, we must devote an appropriate level of resources to managing our international operations.
Our future success will be influenced by our ability to anticipate and effectively manage these and other risks associated with our international operations.
Any of these factors could, however, materially adversely affect our international operations and, consequently, our financial condition, results of operations and cash flows.
We have policies and procedures designed to promote compliance with the FCPA and other anti-corruption laws, but we cannot assure you that we will continue to be found to be operating in compliance with, or be able to detect violations of, any such laws or regulations.
We cannot assure you that our employees will adhere to our Code of Conduct or any other of our policies, applicable anti-corruption laws, including the FCPA, or other legal requirements.
Failure to comply or violations of any applicable policies, anti-corruption laws, or other legal requirements may subject us to legal, regulatory or other sanctions, including criminal and civil penalties and other remedial measures.
Our investments in marketable securities are subject to specific risks relating to the particular issuer of the securities, including the financial condition and business outlook of the issuer, which may result in significant losses to us.
Marketable securities are generally unsecured and may also be subordinated to other obligations of the issuer.
As a result, investments in marketable securities are subject to risks of:
| | ● | limited liquidity in the secondary trading market; |
| | ● | substantial market price volatility, resulting from changes in prevailing interest rates; |
| | ● | subordination to the prior claims of banks and other senior lenders to the issuer; |
| | ● | the possibility that earnings of the issuer may be insufficient to meet its debt service and distribution obligations; and |
| | ● | the declining creditworthiness and potential for insolvency of the issuer during periods of rising interest rates and economic downturn. |
These risks may adversely affect the value of outstanding marketable securities and the ability of the issuers to make distribution payments.
Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations
197 rewritten, 110 added, 101 removed, 226 unchanged
As of December 31, [removed: 2015,] [added: 2016,] the Company had interests in [removed: 605] [added: 525] shopping center [removed: properties,] [added: properties] aggregating [removed: 96.0] [added: 85.4] million square feet of GLA located in [removed: 38] [added: 34] states, Puerto Rico and Canada.
In addition, the Company had [removed: 446] [added: 384] other property interests, primarily through the Company’s preferred equity investments and other real estate investments, totaling [removed: 7.3] [added: 6.3] million square feet of GLA.
[added: The Company’s strategy is to be the premier owner and operator of open-air shopping centers through investments primarily in the U.S.] To achieve this strategy the Company is (i) continuing to transform the quality of its portfolio by disposing of lesser quality assets and acquiring larger higher quality properties in key markets identified by the Company, [added: for which substantial progress has been achieved as of the end of 2016,] (ii) simplifying its business [removed: by] [added: by:] (a) reducing the number of joint venture investments and (b) exiting Mexico, South America and Canada, for which the exit of South America has been [removed: completed and] [added: completed,] Mexico has been substantially [removed: completed,] [added: completed and the Company essentially sold all operating properties in Canada,] (iii) pursuing redevelopment opportunities within its portfolio to increase overall value and (iv) selectively acquiring land parcels in our key markets for [removed: ground-up] [added: real estate] development [removed: projects, consisting of retail and/or mixed use centers,] [added: projects] for long-term investment.
The following highlights the Company’s significant transactions, events and results that occurred during the year ended December 31, [removed: 2015:][added: 2016:]
[added: Financial and] Portfolio Information:
[removed: | | ● | Net] [added: Provision for] income [removed: available to common shareholders] [added: taxes, net] increased [removed: by $465.5] [added: $12.3] million to [removed: $831.2] [added: $72.5] million for the year ended December 31, [removed: 2015,] [added: 2016,] as compared to [removed: $365.7] [added: $60.2] million for the corresponding period in [removed: 2014. |][added: 2015.]
| | ● | Funds from operations (“FFO”) [removed: increased from $596.2] [added: decreased to $555.7] million or [removed: $1.45] [added: $1.32] per diluted share for the year ended December 31, [removed: 2014, to] [added: 2016 from] $643.2 million or $1.56 per diluted share for the year ended December 31, [removed: 2015] [added: 2015,] (see additional disclosure on FFO beginning on page 30). |
| | ● | FFO as adjusted increased [removed: from $576.9] [added: to $629.4] million or [removed: $1.40] [added: $1.50] per diluted share for the year ended December 31, [removed: 2014, to] [added: 2016 from] $603.4 million or $1.46 per diluted share for the year ended December 31, [removed: 2015] [added: 2015,] (see additional disclosure on FFO beginning on page 30). |
| | ● | U.S. same property net operating income (“U.S. [removed: Same Property] [added: same property] NOI”) increased [removed: 3.1%] [added: 2.8%] for the year ended December 31, [removed: 2015,] [added: 2016,] as compared to the corresponding period in [removed: 2014] [added: 2015] (see additional disclosure on U.S. [removed: Same Property] [added: same property] NOI beginning on page 32). |
| | ● | Executed [removed: 1,016] [added: 935] new leases, renewals and options totaling approximately [removed: 6.5] [added: 6.8] million square feet in the [removed: Combined Shopping Center] [added: Consolidated Operating] Portfolio. |
Acquisition Activity (see Footnotes [removed: 3] [added: 3, 4] and [removed: 7] [added: 8] of the Notes to Consolidated Financial Statements included in this Form 10-K):
| | ● | Acquired [removed: 48 shopping center properties, nine out-parcels] [added: 12 consolidated operating properties] and [removed: three land parcels] [added: two out-parcels] comprising an aggregate [removed: 7.5] [added: 2.7] million square feet of GLA, for an aggregate purchase price of [removed: $1.8 billion] [added: $645.6 million] including the assumption of [removed: $807.6] [added: $284.7] million of non-recourse mortgage debt encumbering [removed: 38] [added: 10] of the properties. The Company acquired [removed: 43] [added: nine] of these properties for an aggregate [removed: sales] [added: purchase] price of [removed: $1.6 billion] [added: $505.9 million] from joint ventures in which the Company previously held noncontrolling ownership interests and recognized an aggregate gain on change in control of interests of [removed: $149.2] [added: $57.4] million from the fair value adjustment. |
Disposition Activity (see [removed: Footnotes 4, 5, and 6] [added: Footnote 5] of the Notes to Consolidated Financial Statements included in this Form 10-K):
| | ● | During [removed: 2015,] [added: 2016,] the Company disposed of [removed: 90] [added: 30] consolidated operating properties and [removed: eight] [added: two] out-parcels, [removed: including its remaining property] in [removed: Chile, in] separate transactions, for an aggregate sales price of [removed: $543.9] [added: $378.7] million. These transactions resulted in [added: (i)] an aggregate [removed: net] gain of [removed: $125.8] [added: $86.8] million, after income tax expense, [removed: foreign currency translation loss of $19.6 million related to the sale of the remaining Chile property] and [added: (ii)] aggregate impairment charges of [removed: $10.2] [added: $37.2] million, [added: which were taken prior to sale,] before income tax [removed: expense] [added: benefit] of [removed: $2.3] [added: $10.0] million. |
[removed: | | ● | During January 2015, the] [added: The] Company [removed: entered into] [added: had] a [removed: new] $650.0 million unsecured term loan (“Term [removed: Loan”)] [added: Loan’)] which [removed: has an initial maturity date] [added: was scheduled to mature] in January [removed: 2017 (with] [added: 2017, with] three one-year extension options at the Company’s [removed: discretion)] [added: discretion,] and [removed: accrues] [added: accrued] interest at a spread [removed: (currently 95] [added: (95] basis [removed: points)] [added: points at December 31, 2016)] to LIBOR or at the Company’s option at a base rate as defined per the agreement [removed: (1.37%] [added: (1.60%] at December 31, [removed: 2015). The proceeds from the Term Loan were used to repay the Company’s $400.0 million term loan, which was scheduled to mature in April 2015 (with two additional one-year extension options) and bore interest at LIBOR plus 105 basis points, and for general corporate purposes. |][added: 2016).]
[removed: | | ● | Also during 2015,] [added: During 2016,] the Company [added: (i) assumed $289.0 million of individual non-recourse mortgage debt relating to the acquisition of 10 properties, including $4.3 million associated with fair value debt adjustments and (ii)] paid off [removed: $557.0] [added: $703.0] million of mortgage debt (including fair market value adjustment of [removed: $1.4] [added: $2.1] million) that encumbered [removed: 27] [added: 47] operating properties. [removed: |]
Base rental revenues from rental [removed: property] [added: properties] are recognized on a straight-line basis over the terms of the related leases.
If, up to one year from the acquisition date, information regarding fair value of the assets acquired and liabilities assumed is received and estimates are refined, appropriate [removed: adjustments, if material,] [added: adjustments] are [removed: made to] [added: recognized in] the [removed: purchase price allocation on a retrospective basis.][added: reporting period in which the adjustment is identified.]
| Buildings and building improvements [added: (in years)] | | 15 to 50 [removed: years] |
_Realizability of Deferred Tax [removed: Assets_ _and] [added: Assets and] Uncertain Tax Positions_
Changes in the recognition or measurement of uncertain tax positions could result in material increases or decreases in the Company’s income tax expense in the period in which a change is made, which could have a material impact on operating results (see Footnote [removed: 21] [added: 22] of the Notes to Consolidated Financial Statements included in this Form 10-K).
| Revenues from rental properties (1) | | $ | 1,144.5 | | | $ | 958.9 | | | $ | 185.6 | | | | [removed: 19.4] [added: 19.4%] | [removed: %] |
| Rent | | $ | 12.3 | | | $ | 14.3 | | | $ | (2.0 | ) | | | [removed: (14.0] [added: (14.0%)] | [removed: )%] |
| Real estate taxes | | | 147.2 | | | | 124.7 | | | | 22.5 | | | | [removed: 18.0] [added: 18.0%] | [removed: %] |
| Operating and maintenance | | | 145.0 | | | | 119.7 | | | | 25.3 | | | | [removed: 21.1] [added: 21.1%] | [removed: %] |
| | | $ | 304.5 | | | $ | 258.7 | | | $ | 45.8 | | | | [removed: 17.7] [added: 17.7%] | [removed: %] |
| Depreciation and amortization (3) | | $ | 344.5 | | | $ | 258.1 | | | $ | 86.4 | | | | [removed: 33.5] [added: 33.5%] | [removed: %] |
| (1) | Revenues from rental [removed: property] [added: properties] increased primarily from the combined effect of (i) the acquisition of operating properties during 2015 and 2014, providing incremental revenues for the year ended December 31, 2015, of $179.9 million, as compared to the corresponding period in [removed: 2014,] [added: 2014 and] (ii) the completion of certain redevelopment projects, tenant buyouts and net growth in the current portfolio, providing incremental revenues for the year ended December 31, 2015, of $23.5 million, as compared to the corresponding period in 2014, partially offset by (iii) a decrease in revenues of $17.8 million from properties sold during 2015 and 2014. |
During the year ended December 31, [removed: 2014,] [added: 2015,] the Company recognized impairment charges of [removed: $217.8 million, of which $178.0] [added: $45.5] million, before [added: noncontrolling interests and] income [removed: tax benefits] [added: taxes,] of [removed: $1.7 million,] [added: which $0.1 million] is included in discontinued operations.
The adjustments to property carrying values [added: for 2016 and 2015] were recognized in connection with the Company’s efforts to market [added: for sale] certain properties and management’s assessment as to the likelihood and timing of such potential transactions and the anticipated hold period for such properties.
For additional disclosure, see Footnote [removed: 15] [added: 16] of the Notes to Consolidated Financial Statements included in this Form 10-K.
This increase is primarily due to (i) an increase in foreign tax expense of $33.6 million primarily resulting from the sale of certain Canadian investments during 2015, as compared to 2014 and (ii) an increase in tax expense of $4.3 million relating to equity in income recognized in connection with the Company’s [removed: Albertson’s] [added: Albertsons] investment during 2015, as compared to 2014.
During [removed: 2014,] [added: 2015,] the Company acquired [removed: 34] [added: 43] properties from joint ventures in which the Company had noncontrolling interests.
The Company recorded [removed: an aggregate] [added: a] net gain on change in control of interests of [removed: $107.2] [added: $149.2] million related to the fair value adjustment associated with its [removed: original ownership of] [added: previously held equity interests in] these properties.
During [removed: 2014,] [added: 2016,] the Company disposed of [removed: 90] [added: 30] consolidated operating [removed: properties,] [added: properties and two out-parcels,] in separate transactions, for an aggregate sales price of [removed: $833.5 million, including 27 operating properties in Latin America.][added: $378.7 million.]
These transactions, which are included in Discontinued Operations on the Company’s Consolidated Statements of Income, resulted in (i) an aggregate gain of $203.3 million, before income taxes of $12.0 [removed: million] [added: million,] (ii) the release of a cumulative foreign currency translation loss of $92.9 million relating to the substantial liquidation of the Company’s investment in Mexico and (iii) aggregate impairment charges of $85.1 million before income tax benefits of $1.7 million.
_Comparison [removed: 20__14_] [added: 201__6_] _to [removed: 20__13_][added: 201__5_]
| (1) | Revenues from rental [removed: property] [added: properties] increased primarily from the combined effect of (i) the acquisition of operating properties during [removed: 2014] [added: 2016] and [removed: 2013,] [added: 2015,] providing incremental revenues for the year ended December 31, [removed: 2014,] [added: 2016,] of [removed: $110.1] [added: $57.4] million, as compared to the corresponding period in [removed: 2013] [added: 2015] and (ii) [removed: an overall increase in] the [removed: consolidated shopping center portfolio occupancy to 95.7% at December 31, 2014, as compared to 94.0% at December 31, 2013, the] completion of certain redevelopment projects, tenant buyouts and net growth in the current portfolio, providing incremental revenues for the year ended December 31, [removed: 2014,] [added: 2016,] of [removed: $23.6] [added: $17.4] million, as compared to the corresponding period in [removed: 2013.] [added: 2015, partially offset by (iii) a decrease in revenues of $66.9 million from properties sold during 2016 and 2015.] |
| (2) | Rental property expenses include (i) rent expense relating to ground lease payments for which the Company is the lessee, (ii) real estate tax expense for consolidated properties for which the Company has a controlling ownership interest and (iii) operating and maintenance expense, which consists of property related costs including repairs and maintenance costs, roof repair, landscaping, parking lot repair, snow removal, utilities, property insurance costs, security and various other property related expenses. Rental property expenses [removed: increased] [added: decreased $6.0 million] for the year ended December 31, [removed: 2014,] [added: 2016,] as compared to the corresponding period in [removed: 2013,] [added: 2015,] primarily due to [removed: acquisitions] [added: the disposition] of properties during [removed: 2014 and 2013, resulting in (i) an increase in real estate taxes of $16.0 million, (ii) an increase in repairs] [added: 2016] and [removed: maintenance costs of $6.8 million, (iii) an increase in snow removal costs of $3.4 million, (iv) an increase in property services of $3.7 million, (v) an increase in utilities expense] [added: 2015, partially offset by the acquisition] of [removed: $1.8 million] [added: properties during 2016] and [removed: (vi) an increase in insurance expense of $3.9 million, due to an increase in insurance claims.] [added: 2015.] |
| (3) | Depreciation and amortization increased for the year ended December 31, [removed: 2014,] [added: 2016,] as compared to the corresponding period in [removed: 2013,] [added: 2015,] primarily due to operating property acquisitions during [removed: 2014] [added: 2016] and [removed: 2013.] [added: 2015 and write-offs relating to the Company’s redevelopment projects in 2016, partially offset by property dispositions.] |
As part of the Company’s strategy each property is evaluated for its highest and best use, which may include residential and mixed-use components.
| | ● | Net income available to common shareholders was $332.6 million, or $0.79 per diluted share for the year ended December 31, 2016, as compared to $831.2 million, or $2.00 per diluted share for the corresponding period in 2015. This change was primarily attributable to lower gains on sales of operating properties (including joint ventures) of $378.9 million, net of tax and $49.9 million of higher impairments attributable to the sale or pending disposition of operating properties in 2016 (see “Results of Operations” for additional detail). |
| | ● | The Company’s consolidated operating portfolio occupancy at December 31, 2016 was 95.2%. |
| | ● | The Company acquired from its partner the remaining ownership interest in a development project that was held in a joint venture for a gross purchase price of $84.2 million. Additionally, during the year ended December 31, 2016, the Company acquired additional land parcels related to two existing development projects for $13.8 million. |
| 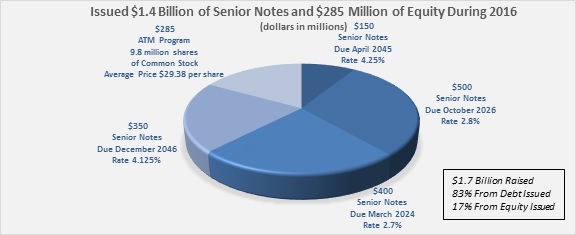 |
| --- |
During the years ended December 31, 2016 and 2015, the Company repaid the following notes (dollars in millions):
| Type | Date Paid | Maturity Date | | | | Amount Repaid (USD) | | | | Interest Rate | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Canadian Notes Payable | Aug-16 | Apr-18 | \- | Aug-20 | | $ | 270.9 | | | 3.855% | \- | 5.99% | |
| Senior Unsecured Note | Aug-16 | | May-17 | | | $ | 290.9 | | | | 5.70% | | |
| Medium Term Notes | Mar-16 | | Mar-16 | | | $ | 300.0 | | | | 5.783% | | |
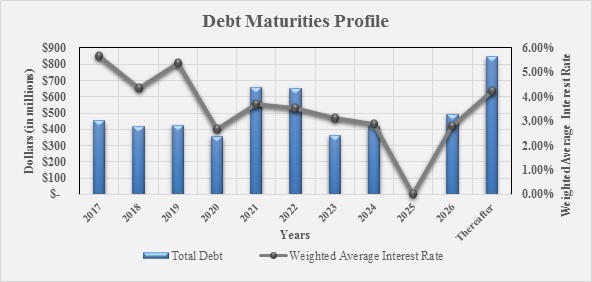
As a result of the above activity the Company was able to extend its debt maturity profile, including extension options, as of December 31, 2016 as follows:
|  |
| --- |
The Company has elected to early adopt ASU 2017-01, Business Combinations (Topic 805): Clarifying the Definition of a Business at the beginning of its fiscal year ended December 31, 2017, including its interim periods within the year, and will appropriately apply the guidance to its prospective asset acquisitions of operating properties, which includes the capitalization of acquisition costs.
From time to time the joint ventures will obtain unsecured debt, which may be guaranteed by the joint venture.
The Company’s reported net earnings are directly affected by management’s judgement in determining a valuation allowance.
| | | 2016 | | | | 2015 | | | | Change | | | | % change | | |
| Revenues from rental properties (1) | | $ | 1,152.4 | | | $ | 1,144.5 | | | $ | 7.9 | | | | 0.7% | |
| Rent | | $ | 11.0 | | | $ | 12.3 | | | $ | (1.3 | ) | | | (10.6%) | |
| Real estate taxes | | | 146.6 | | | | 147.2 | | | | (0.6 | ) | | | (0.4%) | |
| Operating and maintenance | | | 140.9 | | | | 145.0 | | | | (4.1 | ) | | | (2.8%) | |
| | | $ | 298.5 | | | $ | 304.5 | | | $ | (6.0 | ) | | | (2.0%) | |
| Depreciation and amortization (3) | | $ | 355.3 | | | $ | 344.5 | | | $ | 10.8 | | | | 3.1% | |
Management and other fee income decreased $3.9 million to $18.4 million for the year ended December 31, 2016, as compared to $22.3 million for the corresponding period in 2015.
This decrease is primarily attributable to (i) the sale of properties within various joint venture investments and the acquisition of partnership interests in joint ventures by the Company during 2016 and 2015, and (ii) the recognition of enhancement fee income related to the Company’s prior investment in InTown Suites of $1.2 million during 2015.
During the year ended December 31, 2016, the Company recognized impairment charges related solely to adjustments to property carrying values of $93.3 million for which the Company’s estimated fair value was primarily based on third party appraisals and third party offers through signed contracts, letters of intent or discounted cash flow models.
The 2015 impairment charges consisted of (i) $30.3 million related to adjustments to property carrying values, (ii) $9.0 million relating to a cost method investment, (iii) $5.3 million related to certain investments in other real estate investments and (iv) $0.8 million related to marketable debt securities investments.
This decrease is primarily due to the sale of certain marketable securities during the year ended December 31, 2015, which resulted in an aggregate gain of $39.9 million.
During the year ended December 31, 2016, the Company incurred early extinguishment of debt charges aggregating $45.7 million in connection with the optional make-whole provisions of unsecured notes that were repaid prior to maturity and prepayment penalties on a mortgage encumbering 10 operating properties, which the Company also paid prior to the scheduled maturity date.
See “Liquidity and Capital Resources” for additional details.
This increase is primarily due to (i) an increase in the Company’s valuation allowance of $63.5 million as a result of the Company’s merger of its taxable REIT subsidiary into a wholly owned LLC of the Company, partially offset by (ii) a decrease in foreign tax expense of $26.1 million primarily relating to fewer sales of unconsolidated properties within the Company’s Canadian portfolio which were subject to foreign taxes at a consolidated reporting entity level during 2016, as compared to 2015, (iii) an increase in tax benefit of $13.4 million related to impairment charges recognized during 2016, as compared to 2015, (iv) a decrease of $4.5 million in tax expense related to gains recognized during 2015, as compared to 2016, (v) a decrease of $3.0 million in tax expense on operations due to fewer properties in the taxable REIT subsidiary as a result of the TRS Merger, (vi) a decrease of $2.0 million resulting from the favorable settlement of a tax audit during 2016 and (vii) a decrease in tax expense of $2.0 million relating to equity income recognized in connection with the Company’s Albertsons investment during 2015.
This decrease is primarily due to (i) a decrease in gains of $248.1 million resulting from fewer sales of properties and interests within various joint venture investments, including the Company’s Canadian Portfolio, during 2016, as compared to 2015 and (ii) lower equity in income of $26.0 million resulting from the sales of properties within various joint venture investments and the acquisition of partnership interests in joint ventures by the Company during 2016 and 2015, partially offset by (iii) a decrease in impairment charges of $7.2 million recognized during 2016, as compared to 2015.
These transactions resulted in an aggregate gain of $86.8 million, after income tax expense, and aggregate impairment charges of $37.2 million which were taken prior to sale, before income tax benefit of $10.0 million.
For additional disclosure, see Footnote 16 of the Notes to Consolidated Financial Statements included in this Form 10-K.
These transactions resulted in an aggregate gain of $143.6 million, after income tax expense, and aggregate impairment charges of $10.2 million, before income tax expense of $2.3 million.
Additionally, during 2015, the Company disposed of its remaining operating property in Chile for a sales price of $51.3 million.
This transaction resulted in the release of a cumulative foreign currency translation loss of $19.6 million due to the Company’s liquidation of its investment in Chile, partially offset by a gain on sale of $1.8 million, after income tax expense.
| | | 2016 | | | | 2015 | | |
The Company’s strategy is to be the premier owner and operator of open-air shopping centers through investments primarily in the U.S..
| --- | --- | --- |
| | ● | U.S. pro-rata occupancy rose from 95.7% at December 31, 2014, to 95.8% at December 31, 2015. |
| | ● | Additionally, during the year ended December 31, 2015, the Company acquired $20.7 million in land related to two existing development projects which will be held as long-term investments. The Company anticipates completing these projects over the next four years. |
| | ● | During March 2015, the Company issued $350.0 million of 30-year Senior Unsecured Notes at an interest rate of 4.25% payable semi-annually in arrears which are scheduled to mature in April 2045. |
| | ● | During October 2015, the Company issued $500.0 million of seven-year Senior Unsecured Notes at an interest rate of 3.40% payable semi-annually in arrears which are scheduled to mature in November 2022. |
| | ● | During November 2015, the Company redeemed all of its outstanding 7,000,000 depositary shares of the Company’s 6.90% Class H Cumulative Redeemable Preferred Stock (the “Class H Preferred Stock”) resulting in an aggregate payment of $175.0 million. In connection with this redemption the Company recorded a non-cash charge of $5.8 million resulting from the difference between the redemption amount and the carrying amount of the Class H Preferred Stock on the Company’s Consolidated Balance Sheets. |
| | ● | During 2015, the Company repaid (i) its $100.0 million 4.904% medium term notes, which matured in February 2015, (ii) its $100.0 million 5.250% senior unsecured notes, which matured in September 2015 and (iii) its $150.0 million 5.584% medium term notes, which matured in November 2015. |
The Company believes, when evaluating deferred tax assets within its taxable REIT subsidiaries, special consideration should be given to the unique relationship between the Company as a REIT and its taxable REIT subsidiaries.
This relationship exists primarily to protect the REIT’s qualification under the Code by permitting, within certain limits, the REIT to engage in certain business activities in which the REIT cannot directly participate.
As such, the REIT controls which and when investments are held in, or distributed or sold from, its taxable REIT subsidiaries.
This relationship distinguishes a REIT and taxable REIT subsidiary from an enterprise that operates as a single, consolidated corporate taxpayer.
The Company primarily utilizes a projection of pre-tax book income and taxable income as positive evidence to overcome any negative evidence.
Although items of income and expense utilized in the projection are objectively verifiable there is also significant judgment used in determining the duration and timing of events that would impact the projection.
Based upon the Company’s analysis of positive and negative evidence the Company will make a determination of the need for a valuation allowance against its deferred tax assets.
If future income projections do not occur as forecasted, the Company will reevaluate the need for a valuation allowance.
In addition, the Company can employ additional strategies to realize its deferred tax assets, including transferring a greater portion of its property management business to the TRS and sale of certain built-in gain assets.
These impairment charges consist of (i) $118.4 million related to adjustments to property carrying values, (ii) the release of a cumulative foreign currency translation loss of $92.9 million relating to the substantial liquidation of the Company’s investment in Mexico, (iii) $4.8 million related to a cost method investment and (iv) $1.6 million related to a preferred equity investment.
Certain of the calculations to determine fair value utilized unobservable inputs and as such are classified as Level 3 of the fair value hierarchy.
| | | 2014 | | | | 2013 | | | | Change | | | | % change | | |
| Revenues from rental properties (1) | | $ | 958.9 | | | $ | 825.2 | | | $ | 133.7 | | | | 16.2 | % |
| Rent | | $ | 14.3 | | | $ | 13.3 | | | $ | 1.0 | | | | 7.5 | % |
| Real estate taxes | | | 124.7 | | | | 108.7 | | | | 16.0 | | | | 14.7 | % |
| Operating and maintenance | | | 119.7 | | | | 99.4 | | | | 20.3 | | | | 20.4 | % |
| | | $ | 258.7 | | | $ | 221.4 | | | $ | 37.3 | | | | 16.8 | % |
| Depreciation and amortization (3) | | $ | 258.1 | | | $ | 224.7 | | | $ | 33.4 | | | | 14.9 | % |
This decrease is primarily due to a decrease in professional fees of $3.4 million in connection with the Company’s response to a subpoena from the Enforcement Division of the SEC and a parallel investigation by the DOJ in connection with the investigation of Wal-Mart Stores, Inc. with respect to the Foreign Corrupt Practices Act (see Item 3) and a decrease in personnel related costs of $1.8 million for the year ended December 31, 2014, as compared to the corresponding period in 2013.
During the second quarter ended June 30, 2014, the Company implemented a plan to accelerate its disposition of certain properties.
This plan effectively shortened the Company’s anticipated hold period for these properties and as a result the Company recognized impairment charges on various operating properties.
During the year ended December 31, 2013, the Company recognized impairment charges of $190.2 million of which $158.0 million, before noncontrolling interests and income tax, is included in discontinued operations.
These impairment charges consist of (i) $175.6 million related to adjustments to property carrying values, (ii) $10.4 million related to a cost method investment, (iii) $1.0 million related to certain joint venture investments and (iv) $3.2 million related to a preferred equity investment.
This decrease is primarily due to (i) a decrease in realized gains of $12.1 million resulting from the sale of certain marketable securities during the year ended December 31, 2013, (ii) a decrease in excess cash distributions related to cost method investments of $2.8 million for the year ended December 31, 2013 and (iii) a decrease in dividend income of $1.2 million resulting from the sale of certain marketable securities during the year ended December 31, 2013.
This change is primarily due to a decrease in gains from land sales of $8.0 million and an increase in acquisition related costs of $1.4 million related to an increase in acquisitions during 2014 as compared to 2013.
This change is primarily due to (i) a decrease in foreign tax expense of $9.5 million primarily relating to the sale of certain unconsolidated properties during 2013 within the Company’s Latin American portfolio which were subject to foreign taxes at a consolidated reporting entity level offset by an increase in other foreign uncertain tax positions of $5.5 million, (ii) a decrease in tax provision of $9.1 million relating to a change in control gain recognized during the year ended December 31, 2013, (iii) a decrease in tax provision of $3.4 million related to gains on land sales during 2013, and (iv) a decrease in tax provision of $2.4 million related to gains on sale of certain marketable securities during 2013, partially offset by (v) a partial release of the deferred tax valuation allowance of $8.7 million during the year ended December 31, 2013 related to the Company’s FNC Realty Corp. (“FNC”) portfolio based on the Company’s estimated future earnings of FNC and (vi) a decrease in tax benefit of $4.3 million relating to equity losses recognized in connection with the Company’s Albertson’s investment.
Equity in income of joint ventures, net decreased $49.1 million to $159.6 million for the year ended December 31, 2014, as compared to $208.7 million for the corresponding period in 2013.
This decrease is primarily the result of (i) the release of a cumulative foreign currency translation loss of $47.3 million relating to the substantial liquidation of the Company’s investment in Mexico, (ii) a decrease in gains of $21.7 million resulting from the sale of properties within various joint venture investments and interests in joint ventures primarily located in Latin America during 2013, (iii) a decrease in equity in income of $1.4 million due to the sale of the InTown portfolio in 2013 and (iv) a decrease of equity in income of $7.5 million related to the sale of various joint ventures within the Company’s Latin American portfolio during 2014, partially offset by (v) an increase in equity in income of $15.6 million primarily resulting from a cash distribution received in excess of the Company’s carrying basis during 2014, and (vi) a decrease in impairment charges of $8.2 million relating to various joint venture properties primarily located in Mexico taken during the year ended 2013, as compared to 2014.
Equity in income from other real estate investments, net increased $6.9 million to $38.0 million for the year ended December 31, 2014, as compared to $31.1 million for the corresponding period in 2013.
These transactions, which are included in Discontinued operations on the Company’s Consolidated Statements of Income, resulted in an aggregate gain of $25.4 million and impairment charges of $61.9 million, before income tax.
Additionally, during 2013, the Company sold eight consolidated properties in its Latin American portfolio for an aggregate sales price of $115.4 million.
These transactions, which are included in Discontinued operations on the Company’s Consolidated Statements of Income, resulted in an aggregate gain of $23.3 million, before income taxes, and aggregate impairment charges of $26.9 million (including the release of a cumulative foreign currency translation loss of $7.8 million associated with the sale of the Company’s interest in two properties within Brazil, which represents a full liquidation of the Company’s investment in Brazil), before income taxes.
An excerpt. Shown here: 40 of 197 rewritten, 40 of 110 added and 40 of 101 removed. The counts are complete. For every sentence, read Item 7. Management's Discussion and Analysis of Financial Condition and Results of Operations in the FY2016 filing and the FY2015 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
17 rewritten, 8 added, 14 removed, 14 unchanged
The following table presents the Company’s aggregate fixed rate and variable rate [removed: domestic and foreign] debt obligations outstanding, including fair market value adjustments and unamortized deferred financing costs, as of December 31, [removed: 2015,] [added: 2016,] with corresponding weighted-average interest rates sorted by maturity date.
| | | [removed: 2016 | | | |] 2017 | | | | 2018 | | | | 2019 | | | | 2020 | | | | [added: 2021 | | | |] Thereafter | | | | Total | | | | Fair Value | | |
| [removed: U.S. Dollar Denominated Secured Debt] [added: Secured Debt] | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Average Interest Rate | | | \- | | | | [removed: \-] [added: 3.37] | [added: %] | | | [removed: 2.55] [added: 1.91] | % | | | \- | | | | \- | | | | \- | | | | [removed: 2.55] [added: 2.15] | % | | | | |
| [removed: Unsecured Debt] [added: Unsecured Debt] | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Average Interest Rate | | | [removed: 5.78] [added: \-] | [removed: %] | | | [removed: 5.70] [added: 4.30] | % | | | [removed: 4.30] [added: 6.88] | % | | | [removed: 6.88] [added: \-] | [removed: %] | | | [removed: \-] [added: 3.20] | [added: %] | | | [removed: 3.46] [added: 3.40] | % | | | [removed: 4.37] [added: 3.73] | % | | | | |
| Average Interest Rate | | | [removed: \-] [added: 1.60] | [added: %] | | | [removed: 1.37] [added: 1.67] | % | | | \- | | | | \- | | | | \- | | | | \- | | | | [removed: 1.37] [added: 1.61] | % | | | | |
Based on the Company’s variable-rate debt balances, interest expense would have increased by [removed: $6.8] [added: $3.9] million [removed: in 2015] [added: for the year ended December 31, 2016,] if short-term interest rates were 1.0% higher.
The following table presents the Company’s foreign investments and respective [removed: cumulative] [added: cumulated] translation [removed: adjustment] [added: adjustments] (“CTA”) as of December 31, [removed: 2015.][added: 2016.]
Investment amounts are shown in their respective local currencies and the U.S. dollar [removed: equivalents and] [added: equivalents,] CTA balances are shown in U.S. dollars:
| Country | | Local Currency | | | | [removed: U.S. Dollars] [added: U.S. Dollars] | | | | CTA Gain | | |
| Mexican real estate investments (MXN) | | | [removed: 272.2] [added: 181.4] | | | $ | [removed: 18.7] [added: 14.3] | | | $ | \- | |
| Canadian real estate investments (CAD) | | | [removed: 291.9] [added: 47.5] | | | $ | [removed: 210.0] [added: 35.3] | | | $ | [removed: 6.6] [added: 6.3] | |
[removed: Currency fluctuations between local currency and the U.S. dollar during the period in which the Company held its investment result in a CTA, which] [added: This CTA] is recorded as a component of Accumulated other comprehensive income (“AOCI”) on the Company’s Consolidated Balance Sheets.
The Company’s aggregate CTA [removed: net] gain balance at December 31, [removed: 2015,] [added: 2016,] is [removed: $6.6] [added: $6.3] million.
Under [removed: U.S.] GAAP, the Company is required to release CTA balances into earnings when the Company has substantially liquidated its investment in a foreign entity.
The response to this Item 8 is included in our audited [added: Consolidated Financial Statements and] Notes to Consolidated Financial Statements, which are contained in Part IV Item 15 of this Form 10-K.
The instruments’ actual cash flow amounts are in millions.
| Fixed Rate | | $ | 451.5 | | | $ | 96.2 | | | $ | 2.7 | | | $ | 103.9 | | | $ | 161.3 | | | $ | 204.1 | | | $ | 1,019.7 | | | $ | 1,022.2 | |
| Average Interest Rate | | | 5.68 | % | | | 4.72 | % | | | 5.29 | % | | | 5.39 | % | | | 5.39 | % | | | 4.46 | % | | | 5.27 | % | | | | |
| Variable Rate | | $ | \- | | | $ | 19.4 | | | $ | 100.0 | | | $ | \- | | | $ | \- | | | $ | \- | | | $ | 119.4 | | | $ | 118.8 | |
| Fixed Rate | | $ | \- | | | $ | 299.5 | | | $ | 299.2 | | | $ | \- | | | $ | 496.8 | | | $ | 2,559.1 | | | $ | 3,654.6 | | | $ | 3,618.3 | |
| Variable Rate | | $ | 250.0 | | | $ | 22.7 | | | $ | \- | | | $ | \- | | | $ | \- | | | $ | \- | | | $ | 272.7 | | | $ | 272.5 | |
Currency fluctuations between local currency and the U.S. dollar, for investments for which the Company has determined that the local currency is the functional currency, for the period in which the Company held its investment result in a CTA.
The Company may, in the near term, substantially liquidate its remaining investment in Canada, which will require the then unrealized gain on foreign currency translation to be recognized as earnings.
The information is presented in U.S. dollar equivalents, which is the Company’s reporting currency.
The instruments’ actual cash flows are denominated in U.S. dollars and Canadian dollars (CAD) as indicated by geographic description (amounts are USD equivalent in millions).
| Fixed Rate | | $ | 476.6 | | | $ | 574.9 | | | $ | 100.0 | | | $ | 3.1 | | | $ | 107.6 | | | $ | 317.9 | | | $ | 1,580.1 | | | $ | 1,594.8 | |
| Average Interest Rate | | | 6.26 | % | | | 5.80 | % | | | 4.76 | % | | | 5.29 | % | | | 5.43 | % | | | 4.98 | % | | | 5.69 | % | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Variable Rate | | $ | \- | | | $ | \- | | | $ | 34.9 | | | $ | \- | | | $ | \- | | | $ | \- | | | $ | 34.9 | | | $ | 35.0 | |
| Fixed Rate | | $ | 299.9 | | | $ | 290.5 | | | $ | 294.9 | | | $ | 298.9 | | | $ | \- | | | $ | 1,677.5 | | | $ | 2,861.7 | | | $ | 2,896.2 | |
| Variable Rate | | $ | \- | | | $ | 648.8 | | | $ | \- | | | $ | \- | | | $ | \- | | | $ | \- | | | $ | 648.8 | | | $ | 655.6 | |
| CAD Denominated Unsecured Debt | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Fixed Rate | | $ | \- | | | $ | \- | | | $ | 107.6 | | | $ | \- | | | $ | 143.2 | | | $ | \- | | | $ | 250.8 | | | $ | 268.4 | |
| Average Interest Rate | | | \- | | | | \- | | | | 5.99 | % | | | \- | | | | 3.86 | % | | | \- | | | | 4.77 | % | | | | |
The foreign currency exchange risk has been partially mitigated, but not eliminated, through the use of local currency denominated debt.
During 2015, the Company sold its remaining property in Chile.
As a result of liquidating its investments in Chile, the Company recognized a loss from foreign currency translation in the aggregate amount of $18.8 million during the year ended December 31, 2015.
Item 1. Business
20 rewritten, 19 added, 11 removed, 50 unchanged
As of December 31, [removed: 2015,] [added: 2016,] the Company had interests in [removed: 605] [added: 525] shopping center properties (the “Combined Shopping Center Portfolio”), aggregating [removed: 96.0] [added: 85.4] million square feet of gross leasable area (“GLA”), located in [removed: 38] [added: 34] states, Puerto Rico and Canada.
In addition, the Company had [removed: 446] [added: 384] other property interests, primarily through the Company’s preferred equity investments and other real estate investments, totaling [removed: 7.3] [added: 6.3] million square feet of GLA.
As of December 31, [removed: 2015,] [added: 2016,] a total of [removed: 546] [added: 551] persons were employed by the Company.
On the Company’s Web site you can obtain, free of charge, a copy of [removed: our] [added: this] Form 10-K, quarterly reports on Form 10-Q, current reports on Form 8-K and amendments to those reports filed or furnished pursuant to Section 13(a) or 15(d) of the Exchange Act of 1934, as amended, as soon as reasonably practicable, after we file such material electronically with, or furnish it to, the SEC.
The Company’s initial growth resulted primarily from [removed: ground-up] [added: real estate under] development and the construction of shopping centers.
The Company continued its geographic expansion with investments in Canada, Puerto Rico, Mexico, Chile, Brazil and Peru; [removed: however] [added: however,] during 2013, based upon a perceived change in market conditions, the Company began its efforts to exit its investments in Mexico and South America.
[removed: By the fourth quarter] [added: As] of [removed: 2015,] [added: December 31, 2016,] the Company had [added: essentially sold all of its operating properties in Canada,] substantially liquidated its investments in Mexico and had completely exited South America by liquidating its investments in Chile, Brazil and Peru.
| Mexico | | $ | [removed: 1.9] [added: 0.6] | | | $ | [removed: 29.4] [added: 1.9] | | | $ | [removed: 49.5] [added: 29.4] | |
| Peru | | $ | \- | | | $ | [removed: 0.1] [added: \-] | | | $ | [removed: 0.4] [added: 0.1] | |
| Chile | | $ | [removed: 6.7] [added: \-] | | | $ | [removed: 8.1] [added: 6.7] | | | $ | [removed: 9.2] [added: 8.1] | |
| Mexico (Mexican Pesos “MXN”) | | | [removed: 28.2] [added: 11.3] | | | | [removed: 382.3] [added: 28.2] | | | | [removed: 673.8] [added: 382.3] | |
| Peru (Peruvian Nuevo Sol) | | | \- | | | | [removed: 0.4] [added: \-] | | | | [removed: 1.2] [added: 0.4] | |
| Chile (Chilean Pesos “CLP”) | | | [removed: 4,264.9] [added: \-] | | | | [removed: 4,485.9] [added: 4,264.9] | | | | [removed: 4,464.7] [added: 4,485.9] | |
| [removed: Mexico (2014 includes] [added: | (3) | Included in] the [added: year ended December 31, 2014 is the] release of cumulative foreign currency translation adjustment [removed: “CTA”) | | $ | (1.6 | ) | | $ | (3.7 | ) | | $ | 98.1 |] [added: (“CTA”) of $47.3 million in equity losses.] |
| Chile (CLP) | | | \- | | | | [removed: (55.3] [added: \-] | [removed: )] | | | [removed: 2,141.2] [added: (55.3] | [added: )] |
[removed: The Company, through its taxable REIT subsidiaries (“TRS”), as permitted by the Tax Relief Extension Act of 1999, has previously engaged in various retail] [added: These activities have included (i) ground-up] real estate [removed: related opportunities, including (i)ground-up] [added: under] development of open-air shopping centers and the subsequent sale thereof upon completion, (ii) retail real estate management and disposition services, which primarily focused on leasing and disposition strategies for real estate property interests of both healthy and distressed retailers and (iii) the Company’s investment in AB Acquisition, LLC, which consists of grocers Safeway, Albertsons, Vons and other banners (collectively “Albertsons”).
[added: The Company’s strategy is to be the premier owner and operator of open-air shopping centers through investments primarily in the U.S.] To achieve this strategy the Company is (i) continuing to transform the quality of its portfolio by disposing of lesser quality assets and acquiring larger higher quality properties in key markets identified by the Company, [added: for which substantial progress has been achieved as of the end of 2016,] (ii) simplifying its business [removed: by] [added: by:] (a) reducing the number of joint venture investments and (b) exiting Mexico, South America and Canada, for which the exit of South America has been [removed: completed and] [added: completed,] Mexico has been substantially [removed: completed,] [added: completed and the Company essentially sold all operating properties in Canada,] (iii) pursuing redevelopment opportunities within its portfolio to increase overall value and (iv) selectively acquiring land parcels [added: in our key markets] for [removed: ground-up] [added: real estate] development [removed: projects, consisting of retail and/or mixed use centers,] [added: projects] for long-term investment.
The Company's open-air shopping center properties are designed to attract local area customers and are typically anchored by a national or regional discount department store, [removed: supermarket] [added: grocery store] or drugstore tenant offering day-to-day necessities rather than high-priced luxury items.
As of December 31, [removed: 2015,] [added: 2016,] no single open-air shopping center accounted for more than [removed: 1.8%] [added: 1.9%] of the Company's annualized base rental revenues, including the proportionate share of base rental revenues from properties in which the Company has less than a 100% economic interest, or more than 1.5% of the Company’s total shopping center GLA.
At December 31, [removed: 2015,] [added: 2016,] the Company’s five largest tenants were TJX Companies, The Home Depot, [added: Ahold Delhaize,] Bed Bath & [removed: Beyond, Royal Ahold] [added: Beyond] and Albertsons which represented [removed: 3.2%,] [added: 3.4%,] 2.4%, 2.1%, [removed: 1.9%] [added: 2.0%] and [removed: 1.9%,] [added: 1.8%,] respectively, of the Company’s annualized base rental revenues, including the proportionate share of base rental revenues from properties in which the Company has less than a 100% economic interest.
| | | 2016 | | | | 2015 | | | | 2014 | | |
| Canada (1) | | $ | 152.6 | | | $ | 409.1 | | | $ | 49.3 | |
| Mexico (2) (3) | | $ | (3.6 | ) | | $ | (1.6 | ) | | $ | (3.7 | ) |
| Chile (4) | | $ | \- | | | $ | 0.9 | | | $ | (0.1 | ) |
| Canada (Canadian dollars “CAD”) (1) | | | 199.5 | | | | 540.1 | | | | 54.6 | |
| Mexico (MXN) | | | 29.2 | | | | (24.0 | ) | | | 550.8 | |
| | (1) | Includes gains of $141.9 million (CAD 185.9 million) and $373.8 million (CAD 439.9 million) on disposition of equity interests for the years ended December 31, 2016 and 2015, respectively. |
| --- | --- | --- |
| | (2) | Includes equity losses of $5.2 million, equity losses of $0.8 million, and equity income of $0.4 million for the years ended December 31, 2016, 2015 and 2014, respectively, related to foreign investments for which the reporting currency is denominated in USD and not subject to foreign translation exposure. |
| --- | --- | --- |
| --- | --- | --- |
| | (4) | Included in the year ended December 31, 2015 is the release of CTA of $0.8 million in equity income. |
| --- | --- | --- |
The Company maintains certain subsidiaries which made joint elections with the Company to be treated as taxable REIT subsidiaries (“TRSs”), which permit the Company to engage in certain business activities which the REIT may not conduct directly.
A TRS is subject to federal and state income taxes on its income, and the Company includes a provision for taxes in its consolidated financial statements.
Effective August 1, 2016, the Company merged Kimco Realty Services Inc. ("KRS"), a TRS, into a wholly-owned Limited Liability Company (“LLC”) of the Company (the “Merger”) and no longer operates KRS as a TRS.
The Company analyzed the individual assets of KRS and determined that substantially all of KRS’s assets constitute real estate assets and investments that can be directly owned by the Company without adversely affecting the Company’s status as a REIT, including its investment in Albertsons.
Any non-REIT qualifying assets or activities were transferred to a newly formed TRS.
As part of the Company’s strategy each property is evaluated for its highest and best use, which may include residential and mixed-use components.
The Company believes its portfolio of open-air shopping center properties is the largest (measured by GLA) currently held by any publicly traded REIT.
| | | 2015 | | | | 2014 | | | | 2013 | | |
| Brazil | | $ | \- | | | $ | \- | | | $ | 3.2 | |
| Brazil (Brazilian Real) | | | \- | | | | \- | | | | 6.8 | |
| | | | | | | | | | | | | |
| Canada (2015 includes gains of $373.8 million on disposition of equity interests) | | $ | 409.1 | | | $ | 49.3 | | | $ | 46.6 | |
| Chile (2015 includes the release of CTA) | | $ | 0.9 | | | $ | (0.1 | ) | | $ | 4.2 | |
| Canada (Canadian dollars) (2015 includes gains of CAD $439.9 million on disposition of equity interests) | | | 540.1 | | | | 54.6 | | | | 48.0 | |
| Mexico (MXN) (2014 includes the release of CTA) | | | (24.0 | ) | | | (550.8 | ) | | | 232.3 | |
The Company may consider other investments through its TRS should suitable opportunities arise.
The Company’s strategy is to be the premier owner and operator of open-air shopping centers through investments primarily in the U.S..
Item 3. Legal Proceedings
2 rewritten, 0 added, 0 removed, 2 unchanged
The Company [removed: is cooperating] [added: has cooperated, and will continue to cooperate,] with the SEC and the U.S. Department of Justice (“DOJ”), which is conducting a parallel investigation.
At this point, we are unable to predict the duration, scope or result of the SEC or DOJ [removed: investigation.][added: investigations.]
Cover and table of contents
35 rewritten, 5 added, 4 removed, 78 unchanged
10-K 1 [removed: kim20151231_10k.htm] [added: kim20161231_10k.htm] FORM 10-K [Table [removed: Of] [added: of] Contents](#TOC)
For the fiscal year ended December 31, [removed: 2015][added: 2016]
| [removed: |] Maryland | | 13-2744380 | [removed: |]
| [removed: |] (State or other jurisdiction of incorporation or organization) | | (I.R.S. Employer Identification No.) | [removed: |]
| [added: Title of each class] | | Name of each exchange on |
| [removed: Title of each class] | | which registered |
| [removed: |] Large accelerated filer | ☑ | Accelerated filer | ☐ |
| [removed: |] Non-accelerated filer | ☐ | Smaller reporting company | ☐ |
| [removed: |] (Do not check if a smaller reporting company.) | | | |
The aggregate market value of the voting and non-voting common equity held by non-affiliates of the registrant was approximately [removed: $9.0] [added: $12.8] billion based upon the closing price on the New York Stock Exchange for such equity on June 30, [removed: 2015.][added: 2016.]
As of February [removed: 11, 2016,] [added: 22, 2017,] the registrant had [removed: 413,710,579] [added: 425,629,020] shares of common stock outstanding.
Part III incorporates certain information by reference to the Registrant's definitive proxy statement to be filed with respect to the Annual Meeting of Stockholders expected to be held on April [removed: 26, 2016.][added: 25, 2017.]
| [added: |] PART I | | [removed: |]
| 1A. | [Risk [removed: Factors](#BKMK133)] [added: Factors](#BKMK18593)] | [removed: 5] [added: 6] |
| 1B. | [Unresolved Staff [removed: Comments](#BKMK134)] [added: Comments](#BKMK18594)] | [removed: 11] [added: 12] |
| 3. | [Legal [removed: Proceedings](#BKMK136)] [added: Proceedings](#BKMK18596)] | 13 |
| 4. | [Mine Safety [removed: Disclosures](#BKMK137)] [added: Disclosures](#BKMK18597)] | 13 |
| [added: |] PART II | | [removed: |]
| 5. | [Market for Registrant's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#BKMK138)] [added: Securities](#BKMK18598)] | 14 |
| 6. | [Selected Financial [removed: Data](#BKMK139)] [added: Data](#BKMK18599)] | 16 |
| 7. | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#BKMK140)] [added: Operations](#BKMK18600)] | 17 |
| 7A. | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#BKMK141)] [added: Risk](#BKMK18601)] | 33 |
| 8. | [Financial Statements and Supplementary [removed: Data](#BKMK142)] [added: Data](#BKMK18602)] | [removed: 34] [added: 33] |
| 9. | [Changes in and Disagreements With Accountants on Accounting and Financial [removed: Disclosure](#BKMK143)] [added: Disclosure](#BKMK18603)] | [removed: 34] [added: 33] |
| 9A. | [Controls and [removed: Procedures](#BKMK144)] [added: Procedures](#BKMK18604)] | [removed: 34] [added: 33] |
| 9B. | [Other [removed: Information](#BKMK145)] [added: Information](#BKMK18605)] | 34 |
| [added: |] PART III | | [removed: |]
| 10. | [Directors, Executive Officers and Corporate [removed: Governance](#BKMK146)] [added: Governance](#BKMK18606)] | 34 |
| 11. | [Executive [removed: Compensation](#BKMK147)] [added: Compensation](#BKMK18607)] | [removed: 35] [added: 34] |
| 12. | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#BKMK148)] [added: Matters](#BKMK18608)] | [removed: 35] [added: 34] |
| 13. | [Certain Relationships and Related Transactions, and Director [removed: Independence](#BKMK149)] [added: Independence](#BKMK18609)] | [removed: 35] [added: 34] |
| 14. | [Principal Accounting Fees and [removed: Services](#BKMK150)] [added: Services](#BKMK18610)] | [removed: 35] [added: 34] |
| [added: |] PART IV | | [removed: |]
| 15. | [Exhibits, Financial Statement [removed: Schedules](#BKMK151)] [added: Schedules](#BKMK18611)] | 35 |
Factors which may cause actual results to differ materially from current expectations include, but are not limited to (i) general adverse economic and local real estate conditions, (ii) the inability of major tenants to continue paying their rent obligations due to bankruptcy, insolvency or a general downturn in their business, (iii) financing risks, such as the inability to obtain equity, debt or other sources of financing or refinancing on favorable terms to the Company, (iv) the Company’s ability to raise capital by selling its assets, (v) changes in governmental laws and regulations, (vi) the level and volatility of interest rates and foreign currency exchange rates and managements’ ability to estimate the impact thereof, (vii) risks related to the Company’s international operations, (viii) the availability of suitable acquisition, disposition, development and redevelopment [removed: opportunities ,] [added: opportunities,] and risks related to acquisitions not performing in accordance with our expectations, (ix) valuation and risks related to the Company’s joint venture and preferred equity investments, (x) valuation of marketable securities and other investments, (xi) increases in operating costs, (xii) changes in the dividend policy for the Company’s common stock, (xiii) the reduction in the Company’s income in the event of multiple lease terminations by tenants or a failure by multiple tenants to occupy their premises in a shopping center, (xiv) impairment charges, (xv) unanticipated changes in the Company’s intention or ability to prepay certain debt prior to maturity and/or hold certain securities until maturity and (xvi) the risks and uncertainties identified under Item 1A, “Risk Factors” and elsewhere in this Form 10-K and in the Company’s other filings with the Securities and Exchange Commission (“SEC”).
| --- | --- | --- | --- |
| --- | --- | --- |
| 1. | [Business](#BKMK18592) | 3 |
| 2. | [Properties](#BKMK18595) | 12 |
| 16. | [Form 10-K Summary](#BKMK18612) | 35 |
| --- | --- | --- | --- | --- |
| | | |
| 1. | [Business](#BKMK132) | 3 |
| 2. | [Properties](#BKMK135) | 11 |
Item 2. Properties
23 rewritten, 14 added, 13 removed, 19 unchanged
_Real Estate Portfolio__._ As of December 31, [removed: 2015,] [added: 2016,] the Company had interests in [removed: 605] [added: 525] shopping center properties aggregating [removed: 96.0] [added: 85.4] million square feet of GLA located in [removed: 38] [added: 34] states, Puerto Rico and Canada.
In addition, the Company had [removed: 446] [added: 384] other property interests, primarily through the Company’s preferred equity investments and other real estate investments, totaling [removed: 7.3] [added: 6.3] million square feet of GLA.
As of December 31, [removed: 2015,] [added: 2016,] the Company’s Combined Shopping Center Portfolio was [removed: 95.0%] [added: 95.4%] leased.
The Company's open-air shopping center properties, which are generally owned and operated through subsidiaries or joint ventures, had an average size of [removed: 158,686] [added: 162,618] square feet as of December 31, [removed: 2015.][added: 2016.]
During [removed: 2015,] [added: 2016,] the Company [removed: capitalized $156.0] [added: expended $143.5] million in connection with these property improvements and expensed to operations [removed: $38.5] [added: $34.3] million.
The Company's open-air shopping centers are usually "anchored" by a national or regional discount department store, [removed: supermarket] [added: grocery store] or drugstore.
Some of the major national and regional companies that are tenants in the Company's shopping center properties include TJX Companies, The Home Depot, [added: Ahold Delhaize,] Bed Bath & Beyond, [removed: Royal Ahold,] Albertsons, [removed: Wal-Mart,] [added: Ross Stores, Petsmart,] Kohl’s, [removed: Petsmart] [added: Wal-Mart] and [removed: Ross Stores.][added: Whole Foods.]
Minimum base rental revenues and operating expense reimbursements accounted for 98% and other revenues, including percentage rents, accounted for 2% of the Company's total revenues from rental [removed: property] [added: properties] for the year ended December 31, [removed: 2015.][added: 2016.]
Approximately [removed: 31.1%] [added: 29.8%] of the Company's leases of consolidated properties also contain provisions requiring the payment of additional rent calculated as a percentage of tenants’ gross sales above predetermined thresholds.
Percentage rents accounted for less than 1% of the Company's revenues from rental [removed: property] [added: properties] for the year ended December 31, [removed: 2015.][added: 2016.]
As of December 31, [removed: 2015,] [added: 2016,] the Company’s consolidated operating portfolio, comprised of [removed: 60.5] [added: 59.2] million square feet of GLA, was [removed: 95.7%] [added: 95.2%] leased.
For the period January 1, [removed: 2015] [added: 2016] to December 31, [removed: 2015,] [added: 2016,] the Company increased the average base rent per leased square foot, which includes the impact of tenant concessions, in its U.S. consolidated portfolio of open-air shopping centers from [removed: $13.50] [added: $14.36] to [removed: $14.36,] [added: $14.99,] an increase of [removed: $0.86.][added: $0.63.]
This increase primarily consists of (i) a [removed: $0.24] [added: $0.10] increase relating to acquisitions, (ii) a [removed: $0.40] [added: $0.19] increase relating to dispositions, and (iii) a [removed: $0.22] [added: $0.34] increase relating to new leases signed net of leases vacated and rent step-ups within the portfolio.
The Company has a total of [removed: 6,164] [added: 6,120] leases in the U.S. consolidated operating portfolio.
| [removed: Year Ending December 31,] [added: Year Ending December 31,] | | [removed: Number of Leases Expiring] | [added: Number of Leases Expiring] | | | [removed: Square Feet Expiring] | [added: Square Feet Expiring] | | | [removed: Total] [added: | Total] Annual [removed: Base Rent Expiring] [added: Base Rent Expiring] | | | | [removed: %] [added: %] of [removed: Gross Annual Rent] [added: Gross Annual Rent] | | |
[added: | |] (1) [added: |] Leases currently under month to month lease or in process of renewal [added: |]
During [removed: 2015,] [added: 2016,] the Company executed [removed: 1,016] [added: 935] leases totaling over [removed: 6.5] [added: 6.8] million square feet in the Company’s consolidated operating portfolio comprised of [removed: 388] [added: 344] new leases and [removed: 628] [added: 591] renewals and options.
The leasing costs associated with these leases are estimated to aggregate [removed: $54.2] [added: $58.4] million or [removed: $25.38] [added: $29.81] per square foot.
These costs include [removed: $42.8] [added: $46.4] million of tenant improvements and [removed: $11.4] [added: $12.0] million of leasing commissions.
The average rent per square foot on new leases was [removed: $17.63] [added: $18.85] and on renewals and options was [removed: $15.76.][added: $14.97.]
The Company has interests in [removed: 46] [added: 44] consolidated shopping center properties [removed: and interests in 20 shopping center properties in unconsolidated joint ventures] that are subject to long-term ground leases where a third party owns and has leased the underlying land to the Company [removed: (or an affiliated joint venture)] to construct and/or operate a shopping center.
The Company [removed: or the joint venture] pays rent for the use of the land and generally is responsible for all costs and expenses associated with the building and improvements.
At the end of these long-term leases, unless extended, the land together with all improvements [removed: revert] [added: reverts] to the landowner.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| (1) | | | | 168 | | | | 484 | | | $ | 9,892 | | | | 1.2 | % |
| 2017 | | | | 717 | | | | 4,075 | | | $ | 68,822 | | | | 8.2 | % |
| 2018 | | | | 894 | | | | 6,309 | | | $ | 98,788 | | | | 11.7 | % |
| 2019 | | | | 903 | | | | 6,653 | | | $ | 100,430 | | | | 11.9 | % |
| 2020 | | | | 819 | | | | 6,101 | | | $ | 94,589 | | | | 11.2 | % |
| 2021 | | | | 793 | | | | 6,745 | | | $ | 98,678 | | | | 11.7 | % |
| 2022 | | | | 518 | | | | 5,280 | | | $ | 74,069 | | | | 8.8 | % |
| 2023 | | | | 273 | | | | 3,425 | | | $ | 47,962 | | | | 5.7 | % |
| 2024 | | | | 237 | | | | 2,954 | | | $ | 47,138 | | | | 5.6 | % |
| 2025 | | | | 225 | | | | 2,168 | | | $ | 35,144 | | | | 4.2 | % |
| 2026 | | | | 234 | | | | 3,735 | | | $ | 49,768 | | | | 5.9 | % |
| 2027 | | | | 156 | | | | 3,033 | | | $ | 40,761 | | | | 4.8 | % |
| --- | --- | --- |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| (1) | | | 173 | | | | 460 | | | $ | 8,874 | | | | 1.1 | % |
| 2016 | | | 656 | | | | 3,822 | | | $ | 56,298 | | | | 6.8 | % |
| 2017 | | | 1,002 | | | | 7,756 | | | $ | 116,803 | | | | 14.1 | % |
| 2018 | | | 903 | | | | 6,507 | | | $ | 98,617 | | | | 11.9 | % |
| 2019 | | | 849 | | | | 6,724 | | | $ | 98,130 | | | | 11.8 | % |
| 2020 | | | 808 | | | | 6,331 | | | $ | 93,771 | | | | 11.3 | % |
| 2021 | | | 451 | | | | 4,985 | | | $ | 65,220 | | | | 7.9 | % |
| 2022 | | | 267 | | | | 3,016 | | | $ | 41,558 | | | | 5.0 | % |
| 2023 | | | 248 | | | | 3,218 | | | $ | 44,222 | | | | 5.3 | % |
| 2024 | | | 232 | | | | 3,004 | | | $ | 47,022 | | | | 5.7 | % |
| 2025 | | | 229 | | | | 2,203 | | | $ | 34,715 | | | | 4.2 | % |
| 2026 | | | 141 | | | | 3,283 | | | $ | 39,242 | | | | 4.7 | % |
Item 5. Market for the Registrant's Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
20 rewritten, 21 added, 20 removed, 21 unchanged
| | | Stock Price | | | | | | | | | | | [added: |]
| Period | | High | | | | Low | | | | Dividends | | | [added: |]
| [removed: 2014:] [added: 2016:] | | | | | | | | | | | | | [added: |]
| First Quarter | | $ | 28.54 | | | $ | 25.20 | | | $ | 0.24 | | [added: |]
| Second Quarter | | $ | 27.06 | | | $ | 22.48 | | | $ | 0.24 | | [added: |]
| Third Quarter | | $ | 25.70 | | | $ | 22.07 | | | $ | 0.24 | | [added: |]
| Fourth Quarter | | $ | 27.33 | | | $ | 23.98 | | | $ | 0.255 | [removed: (b)] [added: (a)] | [added: |]
| | (a) | Paid on January 15, [removed: 2015,] [added: 2016] to stockholders of record on January [removed: 2, 2015.] [added: 4, 2016.] |
| | (b) | Paid on January 15, [removed: 2016,] [added: 2017] to stockholders of record on January [removed: 4, 2016.] [added: 3, 2017.] |
Holders: The number of holders of record of the Company's common stock, par value $0.01 per share, was [removed: 2,412] [added: 2,292] as of January 31, [removed: 2016.][added: 2017.]
The [removed: Company has determined that the] $0.96 dividend per common share paid during 2015 [removed: represented] [added: consisted of] 100% capital gain to its stockholders.
The [removed: $0.90] [added: Company has determined that the $1.02] dividend per common share paid during [removed: 2014 represented 36%] [added: 2016 consisted of 62%] ordinary income, [removed: a 36%] [added: an 8%] return of capital and [removed: 28%] [added: 30%] capital gain to its stockholders.
See "Management's Discussion and Analysis of Financial Condition and Results of Operations" and Footnotes [removed: 12, 13] [added: 13, 14] and [removed: 16] [added: 17] of the Notes to Consolidated Financial Statements included in this Form 10-K.
Issuer Purchases of Equity [removed: Securities] [added: Securities:] During the year ended December 31, [removed: 2015,] [added: 2016,] the Company repurchased [removed: 179,696] [added: 257,477] shares in connection with common shares surrendered or deemed surrendered to the Company to satisfy statutory minimum tax withholding obligations in connection with the vesting of restricted stock awards under the Company’s equity-based compensation plans.
The Company expended approximately [removed: $4.8] [added: $6.9] million to repurchase these shares.
| Period | | | | Total Number of Shares Purchased | | | | Average Price Paid per Share | | | | Total Number [removed: of Shares Purchased as] [added: of Shares Purchased as] Part of [removed: Publicly Announced Plans or] [added: Publicly Announced Plans or] Programs | | | | Approximate [removed: Dollar Value] [added: Dollar Value] of Shares [removed: that May] [added: that May] Yet [removed: Be Purchased] [added: Be Purchased] Under [removed: the Plans] [added: the Plans] or Programs (in millions) | | |
| [removed: March 1, 2015 | – | March 31, 2015 | | | \-] [added: 2015:] | | | [removed: $] | [removed: \-] | | | | [removed: \-] | | | | [removed: \-] | |
Total Stockholder Return [removed: Performance] [added: Performance:] The following performance chart compares, over the five years ended December 31, [removed: 2015,] [added: 2016,] the cumulative total stockholder return on the Company’s common stock with the cumulative total return of the S&P 500 Index and the cumulative total return of the NAREIT Equity REIT Total Return Index (the "NAREIT Equity Index") prepared and published by the National Association of Real Estate Investment Trusts ("NAREIT").
Stockholder return performance, presented quarterly for the five years ended December 31, [removed: 2015,] [added: 2016,] is not necessarily indicative of future results.
| [removed: ] [added: 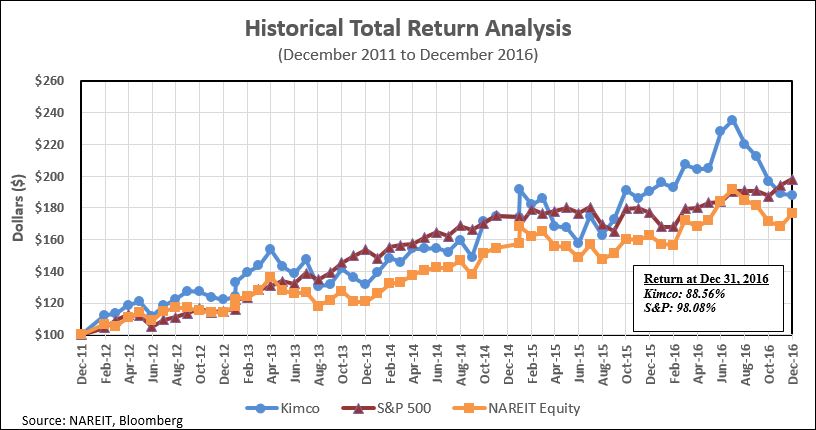] |
Market Information:
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| First Quarter | | $ | 29.11 | | | $ | 24.75 | | | $ | 0.255 | | |
| Second Quarter | | $ | 31.38 | | | $ | 26.79 | | | $ | 0.255 | | |
| Third Quarter | | $ | 32.24 | | | $ | 28.34 | | | $ | 0.255 | | |
| Fourth Quarter | | $ | 29.23 | | | $ | 24.35 | | | $ | 0.27 | (b) | |
Recent Sales of Unregister Securities:
None.
| January 1, 2016 | – | January 31, 2016 | | | 35,768 | | | $ | 26.46 | | | | \- | | | $ | \- | |
| February 1, 2016 | – | February 29, 2016 | | | 186,476 | | | $ | 26.37 | | | | \- | | | | \- | |
| March 1, 2016 | – | March 31, 2016 | | | 621 | | | $ | 27.78 | | | | \- | | | | \- | |
| April 1, 2016 | – | April 30, 2016 | | | \- | | | $ | \- | | | | \- | | | | \- | |
| May 1, 2016 | – | May 31, 2016 | | | 16,069 | | | $ | 28.61 | | | | \- | | | | \- | |
| June 1, 2016 | – | June 30, 2016 | | | 1,110 | | | $ | 29.66 | | | | \- | | | | \- | |
| July 1, 2016 | – | July 31, 2016 | | | \- | | | $ | \- | | | | \- | | | | \- | |
| August 1, 2016 | – | August 31, 2016 | | | 11,858 | | | $ | 31.27 | | | | \- | | | | \- | |
| September 1, 2016 | – | September 30, 2016 | | | 2,056 | | | $ | 28.64 | | | | \- | | | | \- | |
| October 1, 2016 | – | October 31, 2016 | | | 3,519 | | | $ | 27.71 | | | | \- | | | | \- | |
| November 1, 2016 | – | November 30, 2016 | | | \- | | | $ | \- | | | | \- | | | | \- | |
| December 1, 2016 | – | December 31, 2016 | | | \- | | | $ | \- | | | | \- | | | | \- | |
| Total | | | | | 257,477 | | | $ | 26.80 | | | | \- | | | $ | \- | |
Market Information There were no common stock offerings completed by the Company during the three-year period ended December 31, 2015.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| First Quarter | | $ | 22.70 | | | $ | 19.61 | | | $ | 0.225 | |
| Second Quarter | | $ | 23.63 | | | $ | 21.41 | | | $ | 0.225 | |
| Third Quarter | | $ | 23.82 | | | $ | 21.54 | | | $ | 0.225 | |
| Fourth Quarter | | $ | 26.04 | | | $ | 21.56 | | | $ | 0.24 | (a) |
| | | | | | | | | | | | | |
| 2015: | | | | | | | | | | | | |
| January 1, 2015 | – | January 31, 2015 | | | 6,251 | | | $ | 26.32 | | | | \- | | | $ | \- | |
| February 1, 2015 | – | February 28, 2015 | | | 159,743 | | | $ | 26.82 | | | | \- | | | | \- | |
| April 1, 2015 | – | April 30, 2015 | | | \- | | | $ | \- | | | | \- | | | | \- | |
| May 1, 2015 | – | May 31, 2015 | | | 754 | | | $ | 24.49 | | | | \- | | | | \- | |
| June 1, 2015 | – | June 30, 2015 | | | \- | | | $ | \- | | | | \- | | | | \- | |
| July 1, 2015 | – | July 31, 2015 | | | 366 | | | $ | 22.90 | | | | \- | | | | \- | |
| August 1, 2015 | – | August 31, 2015 | | | 11,858 | | | $ | 24.85 | | | | \- | | | | \- | |
| September 1, 2015 | – | September 30, 2015 | | | \- | | | $ | \- | | | | \- | | | | \- | |
| October 1, 2015 | – | October 31, 2015 | | | 724 | | | $ | 26.32 | | | | \- | | | | \- | |
| November 1, 2015 | – | November 30, 2015 | | | \- | | | $ | \- | | | | \- | | | | \- | |
| December 1, 2015 | – | December 31, 2015 | | | \- | | | $ | \- | | | | \- | | | | \- | |
| Total | | | | | 179,696 | | | $ | 26.65 | | | | \- | | | $ | \- | |
Item 6. Selected Financial Data
25 rewritten, 3 added, 5 removed, 14 unchanged
| | | [removed: 2015] [added: 2016] | | | | [added: 2015] | [removed: 2014(2)] | | | [added: 2014] | [removed: 2013(2)] | | | [added: 2013] | [removed: 2012(2)] | | | [added: 2012(2)] | [removed: 2011(2)] | |
| Revenues from rental properties (1) | | $ | [removed: 1,144,474] [added: 1,152,401] | | | $ | [removed: 958,888] [added: 1,144,474] | | | $ | [removed: 825,210] [added: 958,888] | | | $ | [removed: 755,851] [added: 825,210] | | | $ | [removed: 698,211] [added: 755,851] | |
| Interest expense [removed: (3)] [added: (2)] | | $ | [removed: 218,891] [added: 192,549] | | | $ | [removed: 203,759] [added: 218,891] | | | $ | [removed: 212,240] [added: 203,759] | | | $ | [removed: 223,736] [added: 212,240] | | | $ | [removed: 219,599] [added: 223,736] | |
| Depreciation and amortization [removed: (3)] [added: (2)] | | $ | [removed: 344,527] [added: 355,320] | | | $ | [removed: 258,074] [added: 344,527] | | | $ | [removed: 224,713] [added: 258,074] | | | $ | [removed: 214,827] [added: 224,713] | | | $ | [removed: 197,956] [added: 214,827] | |
| Provision for income taxes, net [removed: (4)] [added: (3)] | | $ | [removed: 67,325] [added: 78,583] | | | $ | [removed: 22,438] [added: 67,325] | | | $ | [removed: 32,654] [added: 22,438] | | | $ | [removed: 15,603] [added: 32,654] | | | $ | [removed: 24,928] [added: 15,603] | |
| Impairment charges [removed: (5)] [added: (4)] | | $ | [removed: 45,383] [added: 93,266] | | | $ | [removed: 39,808] [added: 45,383] | | | $ | [removed: 32,247] [added: 39,808] | | | $ | [removed: 10,289] [added: 32,247] | | | $ | [removed: 13,077] [added: 10,289] | |
| Income from continuing operations [removed: (6)] [added: (5)] | | $ | [removed: 894,190] [added: 378,850] | | | $ | [removed: 375,133] [added: 894,190] | | | $ | [removed: 276,884] [added: 375,133] | | | $ | [removed: 172,760] [added: 276,884] | | | $ | [removed: 100,059] [added: 172,760] | |
| Basic | | $ | [removed: 2.01] [added: 0.79] | | | $ | [removed: 0.77] [added: 2.01] | | | $ | [removed: 0.53] [added: 0.77] | | | $ | [removed: 0.19] [added: 0.53] | | | $ | [removed: 0.10] [added: 0.19] | |
| Diluted | | $ | [removed: 2.00] [added: 0.79] | | | $ | [removed: 0.77] [added: 2.00] | | | $ | [removed: 0.53] [added: 0.77] | | | $ | [removed: 0.19] [added: 0.53] | | | $ | [removed: 0.10] [added: 0.19] | |
| Basic | | | [removed: 411,319] [added: 418,402] | | | | [removed: 409,088] [added: 411,319] | | | | [removed: 407,631] [added: 409,088] | | | | [removed: 405,997] [added: 407,631] | | | | [removed: 406,530] [added: 405,997] | |
| Diluted | | | [removed: 412,851] [added: 419,709] | | | | [removed: 411,038] [added: 412,851] | | | | [removed: 408,614] [added: 411,038] | | | | [removed: 406,689] [added: 408,614] | | | | [removed: 407,669] [added: 406,689] | |
| Cash dividends declared per common share | | $ | [removed: 0.975] [added: 1.035] | | | $ | [removed: 0.915] [added: 0.975] | | | $ | [removed: 0.855] [added: 0.915] | | | $ | [removed: 0.78] [added: 0.855] | | | $ | [removed: 0.73] [added: 0.78] | |
| | | [removed: 2015] [added: 2016] | | | | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | | | [removed: 2012] [added: 2013] | | | | [removed: 2011] [added: 2012] | | |
| Real estate, before accumulated depreciation | | $ | [removed: 11,568,809] [added: 12,008,075] | | | $ | [removed: 10,018,226] [added: 11,568,809] | | | $ | [removed: 9,123,344] [added: 10,018,226] | | | $ | [removed: 8,947,287] [added: 9,123,344] | | | $ | [removed: 8,771,257] [added: 8,947,287] | |
| Total assets [removed: (7)] | | $ | [removed: 11,344,171] [added: 11,230,600] | | | $ | [removed: 10,261,400] [added: 11,344,171] | | | $ | [removed: 9,644,247] [added: 10,261,400] | | | $ | [removed: 9,731,928] [added: 9,644,247] | | | $ | [removed: 9,604,026] [added: 9,731,928] | |
| Total debt [removed: (7)] | | $ | [removed: 5,376,310] [added: 5,066,368] | | | $ | [removed: 4,595,970] [added: 5,376,310] | | | $ | [removed: 4,202,018] [added: 4,595,970] | | | $ | [removed: 4,176,011] [added: 4,202,018] | | | $ | [removed: 4,089,649] [added: 4,176,011] | |
| Total stockholders' equity | | $ | [removed: 5,046,300] [added: 5,256,139] | | | $ | [removed: 4,774,785] [added: 5,046,300] | | | $ | [removed: 4,632,417] [added: 4,774,785] | | | $ | [removed: 4,765,160] [added: 4,632,417] | | | $ | [removed: 4,686,386] [added: 4,765,160] | |
| Cash flow provided by operations | | $ | [removed: 493,701] [added: 592,096] | | | $ | [removed: 629,343] [added: 493,701] | | | $ | [removed: 570,035] [added: 629,343] | | | $ | [removed: 479,054] [added: 570,035] | | | $ | [removed: 448,613] [added: 479,054] | |
| Cash flow provided by/(used for) investing activities | | $ | [removed: 21,365] [added: 165,383] | | | $ | [removed: 126,705] [added: 21,365] | | | $ | [removed: 72,235] [added: 126,705] | | | $ | [removed: (51,000] [added: 72,235] | [removed: )] | | $ | [removed: (20,760] [added: (51,000] | ) |
| Cash flow used for financing activities | | $ | [removed: (512,854] [added: (804,527] | ) | | $ | [removed: (717,494] [added: (512,854] | ) | | $ | [removed: (635,377] [added: (717,494] | ) | | $ | [removed: (399,061] [added: (635,377] | ) | | $ | [removed: (440,125] [added: (399,061] | ) |
[removed: |] (1) [removed: |] Does not include revenues (i) from rental [removed: property] [added: properties] relating to unconsolidated joint [removed: ventures, (ii) relating to the investment in retail store leases] [added: ventures] and [removed: (iii)] [added: (ii)] from properties included in discontinued operations. [removed: |]
[removed: | (3) |] [added: (2)] Does not include amounts reflected in discontinued operations. [removed: |]
[removed: | (4) | Does not include amounts reflected in discontinued operations.] Amounts include income taxes related to gain on [removed: transfer/sale] [added: sale] of operating properties. [removed: |]
[removed: | (5) |] [added: (4)] Amounts exclude noncontrolling interests and amounts reflected in discontinued operations. [removed: |]
[removed: | (6) |] [added: (5)] Amounts include gain on [removed: transfer/sale] [added: sale] of operating properties, net of tax and net [added: of] income attributable to noncontrolling interests. [removed: |]
| Early extinguishment of debt charges | | $ | 45,674 | | | $ | \- | | | $ | \- | | | $ | \- | | | $ | \- | |
| Gain on sale of operating properties, net (2) | | $ | 92,823 | | | $ | 132,908 | | | $ | 618 | | | $ | 2,798 | | | $ | 8,475 | |
(3) Does not include amounts reflected in discontinued operations.
| Gain on sale of development properties | | $ | \- | | | $ | \- | | | $ | \- | | | $ | \- | | | $ | 12,074 | |
| Gain on sale of operating properties, net, net of tax (3) | | $ | 125,813 | | | $ | 389 | | | $ | 1,432 | | | $ | 4,299 | | | $ | 108 | |
| --- | --- |
| (2) | Amounts have been adjusted to reflect the impact of operating properties sold during the years ended December 31, 2014, 2013, 2012 and 2011, which are reflected in discontinued operations in the Consolidated Statements of Income. |
| (7) | Beginning in its fiscal year 2015, the Company elected to early adopt Accounting Standards Update (“ASU”) 2015-03 and ASU 2015-15 and appropriately retrospectively applied the guidance to its Notes Payable and Mortgages Payable to all periods presented. Unamortized debt issuance costs are included in Total debt for all periods presented (previously included in Other assets on the Company’s Consolidated Balance Sheets). |
Item 9A. Controls and Procedures
3 rewritten, 0 added, 0 removed, 7 unchanged
There have not been any changes in the Company’s internal control over financial reporting (as such term is defined in Rules 13a-15(f) and 15d-15(f) under the Exchange Act) during the fourth fiscal quarter ended December 31, [removed: 2015,] [added: 2016,] that have materially affected, or are reasonably likely to materially affect, the Company’s internal control over financial reporting.
Based on our evaluation under the framework in _Internal Control_ _\-_ _Integrated Framework_ _(2013)_, our management concluded that our internal control over financial reporting was effective as of December 31, [removed: 2015.][added: 2016.]
The effectiveness of our internal control over financial reporting as of December 31, [removed: 2015,] [added: 2016,] has been audited by PricewaterhouseCoopers LLP, an independent registered public accounting firm, as stated in their report which is included herein.
Item 10. Directors, Executive Officers and Corporate Governance
1 rewritten, 0 added, 0 removed, 3 unchanged
The information required by this item is incorporated by reference to “Proposal 1—Election of Directors,” “Corporate Governance,” “Committees of the Board of Directors,” “Executive Officers” and “Other Matters” in our definitive proxy statement to be filed with respect to the Annual Meeting of Stockholders expected to be held on April [removed: 26, 2016] [added: 25, 2017] (“Proxy Statement”).
Item 15. Exhibits, Financial Statement Schedules
12 rewritten, 0 added, 91 removed, 19 unchanged
| | | | [removed: Form10-K] [added: Form 10-K] Report Page |
| | [Report of Independent Registered Public Accounting [removed: Firm](#BKMK164)] [added: Firm](#BKMK18633)] | | 40 |
| | [Consolidated Balance Sheets as of December 31, [removed: 2015] [added: 2016] and [removed: 2014](#BKMK165)] [added: 2015](#BKMK18634)] | | 41 |
| | [Consolidated Statements of Income for the years ended December 31, [removed: 2015, 2014] [added: 2016, 2015] and [removed: 2013](#BKMK166)] [added: 2014](#BKMK18635)] | | 42 |
| | [Consolidated Statements of Comprehensive Income for the years ended December 31, [removed: 2015, 2014] [added: 2016, 2015] and [removed: 2013](#BKMK167)] [added: 2014](#BKMK18636)] | | 43 |
| | [Consolidated Statements of Changes in Equity for the years ended December 31, [removed: 2015, 2014] [added: 2016, 2015] and [removed: 2013](#BKMK168)] [added: 2014](#BKMK18637)] | | 44 |
| | [Consolidated Statements of Cash Flows for the years ended December 31, [removed: 2015, 2014] [added: 2016, 2015] and [removed: 2013](#BKMK169)] [added: 2014](#BKMK18638)] | | 45 |
| | [Notes to Consolidated Financial [removed: Statements](#BKMK170)] [added: Statements](#BKMK18640)] | | 46 |
| | [Schedule [removed: II](#BKMK171) -] [added: II -](#BKMK18641)] | Valuation and Qualifying Accounts | [removed: 92] [added: 87] |
| | [Schedule [removed: III](#BKMK172) -] [added: III -](#BKMK18642)] | Real Estate and Accumulated Depreciation | [removed: 93] [added: 88] |
| | [Schedule [removed: IV](#BKMK173) -] [added: IV -](#BKMK18643)] | Mortgage Loans on Real Estate | [removed: 95] [added: 90] |
| | [The exhibits listed on the accompanying Index to Exhibits are filed as part of this [removed: report.](#BKMK163)] [added: report.](#BKMK18644)] | | 36 |
| --- | --- | --- | --- |
| | | | |
INDEX TO EXHIBITS
| | | | Incorporated by Reference | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Exhibit Number | Exhibit Description | | Form | | File No. | | Date of Filing | | Exhibit Number | | | Filed/ Furnished Herewith | | Page Number | |
| 3.1(a) | Articles of Restatement of Kimco Realty Corporation, dated January 14, 2011 | | 10-K | | 1-10899 | | 02/28/11 | | 3.1(a) | | | | | | |
| 3.1(b) | Amendment to Articles of Restatement of Kimco Realty Corporation dated May 8, 2014 | | 10-K | | 1-10899 | | 02/27/15 | | 3.1(b) | | | | | | |
| 3.1(c) | Articles Supplementary of Kimco Realty Corporation dated November 8, 2010 | | 10-K | | 1-10899 | | 02/28/11 | | 3.1(b) | | | | | | |
| 3.1(d) | Articles Supplementary of Kimco Realty Corporation, dated March 12, 2012 | | 8-A12B | | 1-10899 | | 03/13/12 | | 3.2 | | | | | | |
| 3.1(e) | Articles Supplementary of Kimco Realty Corporation, dated July 17, 2012 | | 8-A12B | | 1-10899 | | 07/18/12 | | 3.2 | | | | | | |
| 3.1(f) | Articles Supplementary of Kimco Realty Corporation, dated November 30, 2012 | | 8-A12B | | 1-10899 | | 12/03/12 | | 3.2 | | | | | | |
| 3.2 | Amended and Restated By-laws of Kimco Realty Corporation, dated February 25, 2009 | | 10-K | | 1-10899 | | 02/27/09 | | 3.2 | | | | | | |
| 4.1 | Agreement of Kimco Realty Corporation pursuant to Item 601(b)(4)(iii)(A) of Regulation S-K | | S-11 | | 333-42588 | | 09/11/91 | | 4.1 | | | | | | |
| 4.2 | Form of Certificate of Designations for the Preferred Stock | | S-3 | | 333-67552 | | 09/10/93 | | 4(d) | | | | | | |
| 4.3 | Indenture dated September 1, 1993, between Kimco Realty Corporation and Bank of New York (as successor to IBJ Schroder Bank and Trust Company) | | S-3 | | 333-67552 | | 09/10/93 | | 4(a) | | | | | | |
| 4.4 | First Supplemental Indenture, dated August 4, 1994, between Kimco Realty Corporation and Bank of New York (as successor to IBJ Schroder Bank and Trust Company) | | 10-K | | 1-10899 | | 03/28/96 | | 4.6 | | | | | | |
| 4.5 | Second Supplemental Indenture, dated April 7, 1995, between Kimco Realty Corporation and Bank of New York (as successor to IBJ Schroder Bank and Trust Company) | | 8-K | | 1-10899 | | 04/07/95 | | 4(a) | | | | | | |
| 4.6 | Indenture dated April 21, 2005, between Kimco North Trust III, Kimco Realty Corporation, as guarantor and BNY Trust Company of Canada, as trustee | | 8-K | | 1-10899 | | 04/25/05 | | 4.1 | | | | | | |
| 4.7 | Third Supplemental Indenture, dated June 2, 2006, between Kimco Realty Corporation, and The Bank of New York, as trustee | | 8-K | | 1-10899 | | 06/05/06 | | 4.1 | | | | | | |
| 4.8 | First Supplemental Indenture, dated October 31, 2006, among Kimco Realty Corporation, Pan Pacific Retail Properties, Inc. and Bank of New York Trust Company, N.A., as trustee | | 8-K | | 1-10899 | | 11/03/06 | | 4.2 | | | | | | |
| 4.9 | Fifth Supplemental Indenture, dated October 31, 2006, among Kimco Realty Corporation, Pan Pacific Retail Properties, Inc. and Bank of New York Trust Company, N.A., as trustee | | 8-K | | 1-10899 | | 11/03/06 | | 4.1 | | | | | | |
| 4.10 | First Supplemental Indenture, dated June 2, 2006, among Kimco North Trust III, Kimco Realty Corporation, as guarantor and BNY Trust Company of Canada, as trustee | | 10-K | | 1-10899 | | 02/28/07 | | 4.12 | | | | | | |
| 4.11 | Second Supplemental Indenture, dated August 16, 2006, among Kimco North Trust III, Kimco Realty Corporation, as guarantor and BNY Trust Company of Canada, as trustee | | 10-K | | 1-10899 | | 02/28/07 | | 4.13 | | | | | | |
| 4.12 | Fourth Supplemental Indenture, dated April 26, 2007, between Kimco Realty Corporation and The Bank of New York, as trustee | | 8-K | | 1-10899 | | 04/26/07 | | 1.3 | | | | | | |
| 4.13 | Fifth Supplemental Indenture, dated September 24, 2009, between Kimco Realty Corporation and The Bank of New York Mellon, as trustee | | 8-K | | 1-10899 | | 09/24/09 | | 4.1 | | | | | | |
| 4.14 | Third Supplemental Indenture, dated April 13, 2010, among Kimco North Trust III, Kimco Realty Corporation, as guarantor and BNY Trust Company of Canada, as trustee | | 10-Q | | 1-10899 | | 05/07/10 | | 99.2 | | | | | | |
| | | Incorporated by Reference | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- |
| Exhibit Number | Exhibit Description | Form | File No. | Date of Filing | Exhibit Number | Filed/ Furnished Herewith | Page Number |
| 4.15 | Sixth Supplemental Indenture, dated May 23, 2013, between Kimco Realty Corporation and The Bank of New York Mellon, as trustee | 8-K | 1-10899 | 05/23/13 | 4.1 | | |
| 4.16 | Fourth Supplemental Indenture, dated July 22, 2013, among Kimco North Trust III, Kimco Realty Corporation, as guarantor and BNY Trust Company of Canada, as trustee | 10-Q | 1-10899 | 08/02/13 | 99.2 | | |
| 4.17 | Seventh Supplemental Indenture, dated April 24, 2014, between Kimco Realty Corporation and The Bank of New York Mellon, as trustee | 8-K | 1-10899 | 04/24/14 | 4.1 | | |
| 10.1 | Amended and Restated Stock Option Plan | 10-K | 1-10899 | 03/28/95 | 10.3 | | |
| 10.2 | Second Amended and Restated 1998 Equity Participation Plan of Kimco Realty Corporation (restated February 25, 2009) | 10-K | 1-10899 | 02/27/09 | 10.9 | | |
| 10.3 | Form of Indemnification Agreement | 10-K | 1-10899 | 02/27/09 | 99.1 | | |
| 10.4 | Agency Agreement, dated July 17, 2013, by and among Kimco North Trust III, Kimco Realty Corporation and Scotia Capital Inc., RBC Dominion Securities Inc., CIBC World Markets Inc. and National Bank Financial Inc. | 10-Q | 1-10899 | 08/02/13 | 99.1 | | |
| 10.5 | Kimco Realty Corporation Executive Severance Plan, dated March 15, 2010 | 8-K | 1-10899 | 03/19/10 | 10.5 | | |
| 10.6 | Kimco Realty Corporation 2010 Equity Participation Plan | 8-K | 1-10899 | 03/19/10 | 10.7 | | |
| 10.7 | Form of Performance Share Award Grant Notice and Performance Share Award Agreement | 8-K | 1-10899 | 03/19/10 | 10.8 | | |
An excerpt. Shown here: all 12 rewritten, all 0 added and 40 of 91 removed. The counts are complete. For every sentence, read Item 15. Exhibits, Financial Statement Schedules in the FY2016 filing and the FY2015 filing.
Item 16. Form 10-K Summary
0 rewritten, 101 added, 0 removed, 0 unchanged
New section this year
None
INDEX TO EXHIBITS
| | | | Incorporated by Reference | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Exhibit Number | Exhibit Description | | Form | | File No. | | Date of Filing | | Exhibit Number | | | Filed/ Furnished Herewith | | Page Number | |
| 3.1(a) | Articles of Restatement of Kimco Realty Corporation, dated January 14, 2011 | | 10-K | | 1-10899 | | 02/28/11 | | 3.1(a) | | | | | | |
| 3.1(b) | Amendment to Articles of Restatement of Kimco Realty Corporation, dated May 8, 2014 | | | | | | | | | | | * | | 91 | |
| 3.1(c) | Articles Supplementary of Kimco Realty Corporation, dated November 8, 2010 | | 10-K | | 1-10899 | | 02/28/11 | | 3.1(b) | | | | | | |
| 3.1(d) | Articles Supplementary of Kimco Realty Corporation, dated March 12, 2012 | | 8-A12B | | 1-10899 | | 03/13/12 | | 3.2 | | | | | | |
| 3.1(e) | Articles Supplementary of Kimco Realty Corporation, dated July 17, 2012 | | 8-A12B | | 1-10899 | | 07/18/12 | | 3.2 | | | | | | |
| 3.1(f) | Articles Supplementary of Kimco Realty Corporation, dated November 30, 2012 | | 8-A12B | | 1-10899 | | 12/03/12 | | 3.2 | | | | | | |
| 3.2 | Amended and Restated Bylaws of Kimco Realty Corporation, dated February 25, 2009 | | 10-K | | 1-10899 | | 02/27/09 | | 3.2 | | | | | | |
| 4.1 | Agreement of Kimco Realty Corporation pursuant to Item 601(b)(4)(iii)(A) of Regulation S-K | | S-11 | | 333-42588 | | 09/11/91 | | 4.1 | | | | | | |
| 4.2 | Form of Certificate of Designations for the Preferred Stock | | S-3 | | 333-67552 | | 09/10/93 | | 4(d) | | | | | | |
| 4.3 | Indenture dated September 1, 1993, between Kimco Realty Corporation and Bank of New York (as successor to IBJ Schroder Bank and Trust Company) | | S-3 | | 333-67552 | | 09/10/93 | | 4(a) | | | | | | |
| 4.4 | First Supplemental Indenture, dated August 4, 1994, between Kimco Realty Corporation and Bank of New York (as successor to IBJ Schroder Bank and Trust Company) | | 10-K | | 1-10899 | | 03/28/96 | | 4.6 | | | | | | |
| 4.5 | Second Supplemental Indenture, dated April 7, 1995, between Kimco Realty Corporation and Bank of New York (as successor to IBJ Schroder Bank and Trust Company) | | 8-K | | 1-10899 | | 04/07/95 | | 4(a) | | | | | | |
| 4.6 | Third Supplemental Indenture, dated June 2, 2006, between Kimco Realty Corporation and The Bank of New York, as trustee | | 8-K | | 1-10899 | | 06/05/06 | | 4.1 | | | | | | |
| 4.7 | Fourth Supplemental Indenture, dated April 26, 2007, between Kimco Realty Corporation and The Bank of New York, as trustee | | 8-K | | 1-10899 | | 04/26/07 | | 1.3 | | | | | | |
| 4.8 | Fifth Supplemental Indenture, dated September 24, 2009, between Kimco Realty Corporation and The Bank of New York Mellon, as trustee | | 8-K | | 1-10899 | | 09/24/09 | | 4.1 | | | | | | |
| 4.9 | Sixth Supplemental Indenture, dated May 23, 2013, between Kimco Realty Corporation and The Bank of New York Mellon, as trustee | | 8-K | | 1-10899 | | 05/23/13 | | 4.1 | | | | | | |
| 4.10 | Seventh Supplemental Indenture, dated April 24, 2014, between Kimco Realty Corporation and The Bank of New York Mellon, as trustee | | 8-K | | 1-10899 | | 04/24/14 | | 4.1 | | | | | | |
| 10.1 | Amended and Restated Stock Option Plan | | 10-K | | 1-10899 | | 03/28/95 | | 10.3 | | | | | | |
| 10.2 | Second Amended and Restated 1998 Equity Participation Plan of Kimco Realty Corporation (restated February 25, 2009) | | 10-K | | 1-10899 | | 02/27/09 | | 10.9 | | | | | | |
| 10.3 | Form of Indemnification Agreement | | 10-K | | 1-10899 | | 02/27/09 | | 99.1 | | | | | | |
| 10.4 | Agency Agreement, dated July 17, 2013, by and among Kimco North Trust III, Kimco Realty Corporation and Scotia Capital Inc., RBC Dominion Securities Inc., CIBC World Markets Inc. and National Bank Financial Inc. | | 10-Q | | 1-10899 | | 08/02/13 | | 99.1 | | | | | | |
| 10.5 | Kimco Realty Corporation Executive Severance Plan, dated March 15, 2010 | | 8-K | | 1-10899 | | 03/19/10 | | 10.5 | | | | | | |
| 10.6 | Restated Kimco Realty Corporation 2010 Equity Participation Plan | | \- | | \- | | \- | | \- | | | * | | 93 | |
| 10.7 | Form of Performance Share Award Grant Notice and Performance Share Award Agreement | | 8-K | | 1-10899 | | 03/19/10 | | 10.8 | | | | | | |
| 10.8 | First Amendment to the Kimco Realty Corporation Executive Severance Plan, dated March 20, 2012 | | 10-Q | | 1-10899 | | 05/10/12 | | 10.3 | | | | | | |
| | | Incorporated by Reference | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- |
| Exhibit Number | Exhibit Description | Form | File No. | Date of Filing | Exhibit Number | Filed/ Furnished Herewith | Page Number |
| 10.9 | $1.75 Billion Amended and Restated Credit Agreement, dated March 17, 2014, among Kimco Realty Corporation, the subsidiaries of Kimco party thereto, the lenders party thereto, and JPMorgan Chase Bank, N.A., as administrative agent | 8-K | 1-10899 | 03/20/14 | 10.1 | | |
| 10.10 | $2.25 Billion Amended and Restated Credit Agreement, dated February 1, 2017, among Kimco Realty Corporation, the subsidiaries of Kimco party thereto, the lenders party thereto, and JPMorgan Chase Bank, N.A., as administrative agent | 8-K | 1-10899 | 02/02/17 | 10.1 | | |
| 10.11 | Credit Agreement, dated January 30, 2015, among Kimco Realty Corporation and each of the parties named therein | 8-K | 1-10899 | 02/05/15 | 10.1 | | |
| 10.12 | Consulting Agreement, dated June 11, 2015, between Kimco Realty Corporation and David B. Henry | 8-K | 1-10899 | 06/12/15 | 10.1 | | |
| 12.1 | Computation of Ratio of Earnings to Fixed Charges | — | — | — | — | * | 116 |
| 12.2 | Computation of Ratio of Earnings to Combined Fixed Charges and Preferred Stock Dividends | — | — | — | — | * | 117 |
| 21.1 | Significant Subsidiaries of the Company | — | — | — | — | * | 118 |
An excerpt. Shown here: all 0 rewritten, 40 of 101 added and all 0 removed. The counts are complete. For every sentence, read Item 16. Form 10-K Summary in the FY2016 filing.
Item 8. , ITEM 15 (a) (1) and (2)
907 rewritten, 709 added, 725 removed, 813 unchanged
| [Report of Independent Registered Public Accounting [removed: Firm](#BKMK184)] [added: Firm](#BKMK18633)] | | 40 |
| [Consolidated Balance Sheets as of December 31, [removed: 2015] [added: 2016] and [removed: 2014](#BKMK185)] [added: 2015](#BKMK18634)] | | 41 |
| [Consolidated Statements of Income for the years ended December 31, [removed: 2015, 2014] [added: 2016, 2015] and [removed: 2013](#BKMK186)] [added: 2014](#BKMK18635)] | | 42 |
| [Consolidated Statements of Comprehensive Income for the years ended December 31, [removed: 2015, 2014] [added: 2016, 2015] and [removed: 2013](#BKMK187)] [added: 2014](#BKMK18636)] | | 43 |
| [Consolidated Statements of Changes in Equity for the years ended December 31, [removed: 2015, 2014] [added: 2016, 2015] and [removed: 2013](#BKMK188)] [added: 2014](#BKMK18637)] | | 44 |
| [Consolidated Statements of Cash Flows for the years ended December 31, [removed: 2015, 2014] [added: 2016, 2015] and [removed: 2013](#BKMK189)] [added: 2014](#BKMK18638)] | | 45 |
| [Notes to Consolidated Financial [removed: Statements](#BKMK190)] [added: Statements](#BKMK18640)] | | 46 |
| II. | [Valuation and Qualifying [removed: Accounts](#BKMK191)] [added: Accounts](#BKMK18641)] | [removed: 92] [added: 87] |
| III. | [Real Estate and Accumulated [removed: Depreciation](#BKMK192)] [added: Depreciation](#BKMK18642)] | [removed: 93] [added: 88] |
| IV. | [Mortgage Loans on Real [removed: Estate](#BKMK193)] [added: Estate](#BKMK18643)] | [removed: 95] [added: 90] |
In our opinion, the consolidated financial statements listed in the index appearing under Item 15(a)(1) present fairly, in all material respects, the financial position of Kimco Realty Corporation and its subsidiaries [removed: (the "Company")] at December 31, [removed: 2015] [added: 2016] and [removed: 2014,] [added: 2015,] and the results of their operations and their cash flows for each of the three years in the period ended December 31, [removed: 2015] [added: 2016] in conformity with accounting principles generally accepted in the United States of America.
Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2015,] [added: 2016,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
| | | December 31, [removed: 2015] [added: 2016] | | | | December 31, [removed: 2014] [added: 2015] | | |
| Land | | $ | [removed: 2,728,257] [added: 2,845,186] | | | $ | [removed: 2,365,800] [added: 2,728,257] | |
| Building and improvements | | | [removed: 8,661,362] [added: 8,827,861] | | | | [removed: 7,520,095] [added: 8,661,362] | |
| Less: accumulated depreciation and amortization | | | [removed: (2,115,320] [added: (2,278,292] | ) | | | [removed: (1,955,406] [added: (2,115,320] | ) |
| Real estate under development | | | [removed: 179,190] [added: 335,028] | | | | [removed: 132,331] [added: 179,190] | |
| Real estate, net | | | [removed: 9,453,489] [added: 9,729,783] | | | | [removed: 8,062,820] [added: 9,453,489] | |
| Investments and advances in real estate joint ventures | | | [removed: 742,559] [added: 504,209] | | | | [removed: 1,037,218] [added: 742,559] | |
| Other real estate investments | | | [removed: 215,836] [added: 209,146] | | | | [removed: 266,157] [added: 215,836] | |
| Mortgages and other financing receivables | | | [removed: 23,824] [added: 23,197] | | | | [removed: 74,013] [added: 23,824] | |
| Cash and cash [removed: equivalents] [added: equivalents, beginning of year] | | | 189,534 | | | | 187,322 | | [added: | | 148,768 | |]
| Marketable securities | | | [removed: 7,565] [added: 8,101] | | | | [removed: 90,235] [added: 7,565] | |
| Accounts and notes receivable, net | | | [removed: 175,252] [added: 181,823] | | | | [removed: 172,386] [added: 175,252] | |
| Deferred charges and prepaid expenses | | | [removed: 152,349] [added: 147,694] | | | | [removed: 158,302] [added: 152,349] | |
| Other assets | | | [removed: 383,763] [added: 284,161] | | | | [removed: 212,947] [added: 383,763] | |
| Total assets | | $ | [removed: 11,344,171] [added: 11,230,600] | | | $ | [removed: 10,261,400] [added: 11,344,171] | |
| Notes payable | | $ | [removed: 3,761,328] [added: 3,927,251] | | | $ | [removed: 3,171,742] [added: 3,761,328] | |
| Mortgages payable | | | [removed: 1,614,982] [added: 1,139,117] | | | | [removed: 1,424,228] [added: 1,614,982] | |
| Accounts payable and accrued expenses | | | [removed: 150,059] [added: 145,751] | | | | [removed: 129,509] [added: 150,059] | |
| Dividends payable | | | [removed: 115,182] [added: 124,517] | | | | [removed: 111,143] [added: 115,182] | |
| Other liabilities | | | [removed: 433,960] [added: 404,137] | | | | [removed: 431,533] [added: 433,960] | |
| Total liabilities | | | [removed: 6,075,511] [added: 5,740,773] | | | | [removed: 5,268,155] [added: 6,075,511] | |
| Redeemable noncontrolling interests | | | [removed: 86,709] [added: 86,953] | | | | [removed: 91,480] [added: 86,709] | |
| Preferred stock, $1.00 par value, authorized 6,029,100 [removed: and 5,959,100] shares, [removed: respectively,] 32,000 [removed: and 102,000] shares issued and outstanding (in [removed: series), respectively Aggregate liquidation preference $800,000 and $975,000, respectively] [added: series)] | | | [removed: 32] | | | | [removed: 102] | |
| Common stock, $.01 par value, authorized 750,000,000 shares issued and outstanding [removed: 413,430,756] [added: 425,034,113] and [removed: 411,819,818] [added: 413,430,756] shares, respectively | | | [removed: 4,134] [added: 4,250] | | | | [removed: 4,118] [added: 4,134] | |
| Paid-in capital | | | [removed: 5,608,881] [added: 5,922,958] | | | | [removed: 5,732,021] [added: 5,608,881] | |
| Cumulative distributions in excess of net income | | | [removed: (572,335] [added: (676,867] | ) | | | [removed: (1,006,578] [added: (572,335] | ) |
| Accumulated other comprehensive income | | | [removed: 5,588] [added: 5,766] | | | | [removed: 45,122] [added: 5,588] | |
| Total stockholders' equity | | | [removed: 5,046,300] [added: 5,256,139] | | | | [removed: 4,774,785] [added: 5,046,300] | |
| | | Form 10-K Page |
February 24, 2017
| | | | 11,673,047 | | | | 11,389,619 | |
| | | | 9,394,755 | | | | 9,274,299 | |
| Cash and cash equivalents | | | 142,486 | | | | 189,534 | |
| | | | | | | | | |
| Aggregate liquidation preference $800,000 | | | 32 | | | | 32 | |
| Early extinguishment of debt charges | | | (45,674 | ) | | | \- | | | | \- | |
| | | Cumulative | | | | Accumulated | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Net income | | | 378,850 | | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | 378,850 | | | | 7,288 | | | | 386,138 | |
| Change in unrealized loss on interest rate swaps | | | \- | | | | 451 | | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | 451 | | | | \- | | | | 451 | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Issuance of common stock | | | \- | | | | \- | | | | \- | | | | \- | | | | 10,711 | | | | 107 | | | | 286,314 | | | | 286,421 | | | | \- | | | | 286,421 | |
| Surrender of restricted stock | | | \- | | | | \- | | | | \- | | | | \- | | | | (276 | ) | | | (3 | ) | | | (7,005 | ) | | | (7,008 | ) | | | \- | | | | (7,008 | ) |
| Balance, December 31, 2016 | | $ | (676,867 | ) | | $ | 5,766 | | | | 32 | | | $ | 32 | | | | 425,034 | | | $ | 4,250 | | | $ | 5,922,958 | | | $ | 5,256,139 | | | $ | 146,735 | | | $ | 5,402,874 | |
| Net income | | $ | 386,138 | | | $ | 900,143 | | | $ | 435,880 | |
| Deferred taxes | | | 55,068 | | | | 4,498 | | | | 15,128 | |
| Early extinguishment of debt charges | | | 45,674 | | | | \- | | | | \- | |
| Change in Canadian withholding tax receivable | | | 23,571 | | | | (37,040 | ) | | | \- | |
| Payment of early extinguishment of debt charges | | | (45,674 | ) | | | \- | | | | \- | |
| Change in tenants' security deposits | | | 1,367 | | | | 2,116 | | | | \- | |
The Company elected status as a Real Estate Investment Trust (“REIT”) for federal income tax purposes beginning in its taxable year January 1, 1992 and operates in a manner that enables the Company to maintain its status as a REIT.
Effective August 1, 2016, the Company merged Kimco Realty Services Inc. ("KRS"), a TRS, into a wholly-owned Limited Liability Company (“LLC”) of the Company (the “Merger”) and no longer operates KRS as a TRS.
The Company analyzed the individual assets of KRS and determined that substantially all of KRS’s assets constitute real estate assets and investments that can be directly owned by the Company without adversely affecting the Company’s status as a REIT.
Any non-REIT qualifying assets or activities were transferred to a newly formed TRS (see Footnote 22 of the Notes to Consolidated Financial Statements).
The Company has elected to early adopt ASU 2017-01, Business Combinations (Topic 805): Clarifying the Definition of a Business at the beginning of its fiscal year ended December 31, 2017, including its interim periods within the year, and will appropriately apply the guidance to its prospective asset acquisitions of operating properties, which includes the capitalization of acquisition costs.
| --- | --- | --- | --- | --- | --- | --- |
The Company ceases cost capitalization when the property is held available for occupancy and placed into service.
However, the Company may continue to capitalize costs even though a project is substantially completed if construction is still ongoing at the site.
As of December 31, 2016, the Company did not guaranty any unsecured joint venture debt.
Most states, where the Company holds investments in real estate, conform to the federal rules recognizing REITs.
Certain subsidiaries of the Company have made a joint election with the Company to be treated as TRSs.
| Gain on sale of operating properties, net, net of tax | | | 86,785 | | | | 125,813 | | | | 389 | |
| Net income attributable to noncontrolling interests | | | (7,288 | ) | | | (6,028 | ) | | | (11,879 | ) |
| Preferred stock redemption charges | | | \- | | | | (5,816 | ) | | | \- | |
| | | | | | | | | | | | | |
| | | | | | | | | | | | | |
| Weighted average common shares outstanding – basic | | | 418,402 | | | | 411,319 | | | | 409,088 | |
| | | | | | | | | | | | | |
| Income from discontinued operations | | | \- | | | | \- | | | | 0.12 | |
| | | Form10-K Page |
| --- | --- | --- |
As discussed in Note 1 to the consolidated financial statements, the Company adopted accounting standards update (“ASU”) No. 2014-08, “Reporting Discontinued Operations and Disclosures of Disposals of Components of an Entity”, which changed the criteria for reporting discontinued operations in 2015.
February 26, 2016
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | 11,389,619 | | | | 9,885,895 | |
| | | | 9,274,299 | | | | 7,930,489 | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Balance, January 1, 2013 | | $ | (824,008 | ) | | | (66,182 | ) | | | 102 | | | $ | 102 | | | | 407,782 | | | $ | 4,078 | | | $ | 5,651,170 | | | $ | 4,765,160 | | | $ | 167,320 | | | $ | 4,932,480 | |
| Net income | | | 236,281 | | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | 236,281 | | | | 5,072 | | | | 241,353 | |
| Class H Depositary Share, $1.5000 per | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Issuance of common stock | | | \- | | | | \- | | | | \- | | | | \- | | | | 560 | | | | 5 | | | | 9,208 | | | | 9,213 | | | | \- | | | | 9,213 | |
| Surrender of restricted stock | | | \- | | | | \- | | | | \- | | | | \- | | | | (247 | ) | | | (2 | ) | | | (3,889 | ) | | | (3,891 | ) | | | \- | | | | (3,891 | ) |
| Acquisition of noncontrolling interests | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | (8,894 | ) | | | (8,894 | ) | | | (20,096 | ) | | | (28,990 | ) |
| Cash and cash equivalents, beginning of year | | | 187,322 | | | | 148,768 | | | | 141,875 | |
| --- | --- |
The Company is also subject to local taxes on certain non-U.S. investments.
| Effect of dilutive securities(a): | | | | | | | | | | | | |
(a) The effect of the assumed conversion of certain convertible units had an anti-dilutive effect upon the calculation of Income from continuing operations per share.
Accordingly, the impact of such conversions has not been included in the determination of diluted earnings per share calculations.
Additionally, there were 5,300,680, 7,137,120 and 10,950,388, stock options that were not dilutive as of December 31, 2015, 2014 and 2013, respectively.
The ASU is expected to impact the Company’s consolidated financial statements as the Company has certain operating and land lease arrangements for which it is the lessee.
In September 2015, the FASB issued ASU 2015-16, Simplifying the Accounting for Measurement-Period Adjustments (“ASU 2015-16”), which eliminates the requirement to restate prior period financial statements for measurement period adjustments.
The new guidance requires that the cumulative impact of a measurement period adjustment (including the impact on prior periods) be recognized in the reporting period in which the adjustment is identified.
Early adoption is permitted.
In April 2015, the FASB issued ASU 2015-03, Interest - Imputation of Interest (Topic 835): Simplifying the Presentation of Debt Issuance Costs (“ASU 2015-03”).
The amendments in ASU 2015-03 require that debt issuance costs related to a recognized debt liability be presented in the balance sheet as a direct deduction from the carrying amount of that debt liability, consistent with debt discounts.
The recognition and measurement guidance for debt issuance costs are not affected by the amendments in this update.
The amendments in ASU 2015-03 are effective for fiscal years beginning after December 15, 2015.
In August 2015, the FASB issued ASU 2015-15: Presentation and Subsequent Measurement of Debt Issuance Costs Associated with Line-of-Credit Arrangements (“ASU 2015-15”) providing guidance regarding the presentation and subsequent measurement of debt issuance costs related to line-of-credit arrangements.
Given the absence of authoritative guidance on this matter, the SEC staff has stated that it would not object to an entity deferring and presenting debt issuance costs as an asset and subsequently amortizing the deferred debt issuance costs ratably over the term of the line-of-credit arrangement, regardless of whether there are any outstanding borrowings on that line-of-credit arrangement.
Beginning in its fiscal year 2015, the Company elected to early adopt ASU 2015-03 and ASU 2015-15 and retrospectively applied the guidance to its Notes Payable and Mortgages Payable for all periods presented.
Unamortized debt issuance costs of $31.4 million and $3.2 million are included in Notes Payable and Mortgages Payable, respectively, as of December 31, 2015, and $20.5 million and $3.9 million of unamortized debt issuance costs are included in Notes Payable and Mortgages Payable, respectively, as of December 31, 2014 (previously included in Other assets on the Company’s Consolidated Balance Sheets).
ASU 2015-02 will be effective for periods beginning after December 15, 2015.
Early adoption is permitted, including adoption in an interim period.
The Company is currently in the process of evaluating the impact the adoption of ASU 2014-09 will have on the Company’s financial position or results of operations.
In April 2014, the FASB issued ASU 2014-08, Presentation of Financial Statements (Topic 205) and Property, Plant, and Equipment (Topic 360): Reporting Discontinued Operations and Disclosures of Disposals of Components of an Entity (“ASU 2014-08”).
The amendments in ASU 2014-08 change the criteria for determining which disposals can be presented as discontinued operations and modifies related disclosure requirements.
The amendments in ASU 2014-08 are effective for fiscal years beginning after December 15, 2014.
An excerpt. Shown here: 40 of 907 rewritten, 40 of 709 added and 40 of 725 removed. The counts are complete. For every sentence, read Item 8. , ITEM 15 (a) (1) and (2) in the FY2016 filing and the FY2015 filing.