 filings.tools
Prologis (PLD) 10-K risk factor changes: FY2021 vs FY2020
The 2021-12-31 10-K against the 2020-12-31 one, compared heading by heading and sentence by sentence.
Item 1A35 rewritten22 added17 removed277 unchanged
All filing items1,377 rewritten590 added713 removed2,170 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 590 added, 713 removed, 1,377 rewritten and 2,170 unchanged across 19 items that differ.
- New this year: Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections.
Sentences by item
23 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2021; struck-through words were in FY2020. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
35 rewritten, 22 added, 17 removed, 277 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
We conduct a significant portion of our business and employ a substantial number of people outside of the U.S. During [removed: 2020,] [added: 2021,] we generated approximately [removed: $484] [added: $620] million or [removed: 10.9%] [added: 13.0%] of our consolidated revenues from operations outside the U.S. Circumstances and developments related to international operations that could negatively affect us include, but are not limited to, the following factors:
| • | unexpected changes in regulatory [added: and environmental] requirements, taxes, tariffs, trade wars and laws within the countries in which we operate; |
| • | the impact of regional or country-specific business cycles and economic instability, including government [removed: shutdowns, uncertainty in the U.K., or further] [added: shutdowns and] withdrawals from the European Union or other international trade alliances or agreements; |
Our properties are also subject to various federal, state and local regulatory requirements, such as the Americans with Disabilities Act and state and local [removed: fire] [added: fire, life-safety, energy] and [removed: life-safety] [added: greenhouse gas emissions] requirements.
At December 31, [removed: 2020,] [added: 2021,] approximately [removed: $8.6] [added: $9.1] billion or [removed: 15.3%] [added: 15.6%] of our total consolidated assets were invested in a currency other than the U.S. dollar, principally the British pound sterling, [added: Canadian dollar,] euro and Japanese yen.
Our hedging of foreign currency and interest rate risk may not effectively limit our exposure to [removed: other] [added: these] risks.
At December 31, [removed: 2020, 30.9%] [added: 2021, 30.7%] of our consolidated operating properties or [removed: $13.6] [added: $13.8] billion (based on consolidated gross book value, or investment before depreciation) were located in California (Central Valley, San Francisco Bay Area and Southern California markets), [added: which represented 25.9% of the aggregate square footage of our operating properties and 33.0% of our consolidated operating property NOI.]
Of these markets, no single market contributed more than 10% of our total consolidated investment before [removed: depreciation.][added: depreciation in operating properties.]
Our O&M portfolio, which includes our [removed: wholly-owned] [added: consolidated] properties and properties [removed: included in] [added: owned by] our [added: unconsolidated] co-investment ventures, has concentrations of properties in the same markets mentioned above, as well as in markets in [added: China,] France, Japan, Mexico and the U.K., and are subject to the economic conditions in those markets.
We may decide to sell or contribute properties to certain of our [removed: unconsolidated] co-investment ventures or sell properties to third parties to generate proceeds to fund our capital deployment activities.
The [removed: unconsolidated] co-investment ventures or third parties who might acquire our properties may need to have access to debt and equity capital, in the private and public markets, in order to acquire properties from us.
| • | governmental [added: and environmental] regulations and the associated potential liability under, and changes in, environmental, zoning, usage, tax, tariffs and other laws. |
At December 31, [removed: 2020,] [added: 2021,] our top 10 customers accounted for [removed: 16.3%] [added: 16.7%] of our consolidated [added: NER and 14.0% of our O&M] NER.
We may acquire properties and companies that [removed: involves] [added: involve] risks [removed: which] [added: that] could adversely affect our business and financial condition.
Our real estate development and redevelopment strategy is focused on monetizing land [added: and redevelopment sites] in the future through development of logistics facilities to hold for long-term [removed: investment,] [added: investment and for] contribution or sale to a co-investment venture or third party, depending on market conditions, our liquidity needs and other factors.
| • | we may have construction costs [added: or additional environmental regulation costs] that exceed our estimates and projects may not be completed, delivered or stabilized as planned due to defects or other issues; |
We are subject to risks and liabilities in connection with forming [added: and attracting third-party investment in] co-investment ventures, investing in new or existing co-investment ventures, [removed: attracting third-party investment] and managing properties through co-investment ventures.
At December 31, [removed: 2020,] [added: 2021,] we had investments in co-investment ventures, both public and private, that owned operating properties with a gross book value of approximately [removed: $49] [added: $54] billion.
| • | our partners might have economic or other business interests or goals that are inconsistent with our business interests or goals that would affect our ability to operate the [removed: property;] [added: venture;] |
| • | our relationships with our partners are generally contractual in nature and may be terminated or dissolved under the terms of the agreements, and in such event, we may not continue to [removed: manage or] invest in [added: or manage] the assets underlying such relationships resulting in [removed: reduced fee revenues or we may elect to acquire the properties in order to maintain an investment in the portfolio; and] |
The terms of our various credit agreements, including our credit [removed: facilities,] [added: facilities and term loans,] the indentures under which [added: certain of] our senior notes [removed: and term loans] are issued and other note agreements, require us to comply with a number of customary financial covenants, such as maintaining debt service coverage ratios, leverage [removed: ratios,] [added: ratios and] fixed charge coverage [removed: ratios and other operating covenants including maintaining insurance][added: ratios.]
At December 31, [removed: 2020,] [added: 2021,] our credit ratings [added: were A3] from Moody’s [added: with a stable outlook] and [added: A- from] S&P [removed: were A3 and A-, respectively, both] with [removed: stable] [added: a positive] outlook.
[removed: The Financial Conduct Authority (“FCA”),] [added: Transition to an alternative reference rate due to] the [removed: authority that regulates] [added: cessation of] the London Inter-bank Offered Rate [removed: (“LIBOR”), announced that it intends to stop compelling banks to submit rates for the calculation of LIBOR after 2021 which will require transition to an alternative reference rate that] [added: (“LIBOR”)] could have a negative impact on our required debt payments and the value of our related debt and derivative financial instruments.
[removed: As a result, in the U.S., the] [added: The] Federal Reserve Board and the Federal Reserve Bank of New York identified the Secured Overnight Financing Rate (“SOFR”) as its preferred alternative rate for USD LIBOR for debt and derivative financial instruments.
This [removed: change] [added: extended cessation date for USD LIBOR-indexed rates] would allow most legacy USD LIBOR contracts to mature before disruptions occur in the USD LIBOR market, without the need to transition those contracts to SOFR.
We anticipate managing the transition [added: from USD LIBOR] to [removed: a preferred alternative rate] [added: SOFR] using the language set out in our agreements and through potentially modifying our debt and derivative instruments, however future market conditions may not allow immediate implementation of desired modifications and we may incur significant associated costs in doing so.
We will continue to monitor and evaluate the potential impact on our debt payments and value of our related debt and derivative financial [removed: instruments, however, we are not able to predict when IBOR-indexed rates will cease to be available.][added: instruments.]
The impact of the COVID-19 outbreak on our business, that of our [removed: unconsolidated] co-investment ventures, and our customers for the long-term continues to be uncertain.
Given the ongoing and dynamic nature of these circumstances, we cannot predict the extent to which the continuation of the COVID-19 pandemic may impact our [removed: business,] [added: business and operating results and that of our co-investment ventures,] but its impact may include the following:
| • | Our ability to recover our investments in real estate assets may be impacted by current market conditions; [removed: and] |
Despite system redundancy, the implementation of security measures and the existence of a disaster recovery plan for our internal and hosted information technology systems, our systems are vulnerable to damages from any number of sources, including energy blackouts, natural disasters, terrorism, war, telecommunication failures and cyber security attacks, such as [removed: computer viruses] [added: malware, ransomware,] or unauthorized access.
We may [removed: also] incur additional costs to remedy damages caused by such disruptions.
[added: While management continually reviews the effectiveness of our disclosure controls and] procedures and internal control over financial reporting, there can be no guarantee that our internal control over financial reporting will be effective in accomplishing all control objectives all of the time.
We are exposed to the potential impacts of future climate [removed: change,] [added: change and could be required to implement new or stricter regulations,] which may result in unanticipated losses that could affect our business and financial condition.
[removed: However, we] [added: We] may be adversely impacted as a real estate developer in the future by potential impacts to the supply chain or stricter energy efficiency standards or greenhouse gas regulations for the commercial building sectors.
For the year ended December 31, 2021, $422 million or 12.1% of our total consolidated segment NOI was denominated in a currency other than the U.S. dollar.
See Note 17 to the Consolidated Financial Statements in Item 8.
Financial Statements and Supplementary Data for more information on these amounts.
In addition, we occasionally use interest rate swap contracts to manage interest rate risk and limit the impact of future interest rate changes on earnings and cash flows.
| | a decrease in our assets under management and a reduction in fee revenues. This may also require us to acquire the properties in order to maintain an investment in the portfolio; and |
We have also made investments in early and growth-stage companies that are focused on emerging technology.
These companies may not be successful at raising additional capital or generating cash flows to sustain operations, which could result in the impairment of our investment.
In addition, through Prologis Essentials we are investing in the development of new business lines that are complementary to our core business.
These business lines may not be successful and may include risks that are different than investing in our core real estate business.
In March 2021, the Financial Conduct Authority (“FCA”) formally announced that the publication of LIBOR was ending and confirmed that USD LIBOR-indexed rates would cease to be published after June 30, 2023.
Certain interbank offered rates (“IBOR”) ceased on December 31, 2021.
For discussion on the transition of these rates see Note 2 to the Consolidated Financial Statements in Item 8.
Financial Statements and Supplementary Data.
At December 31, 2021, only the available USD commitments on our global senior credit facilities were indexed to USD LIBOR.
Our global senior credit facility agreements contain provisions that reference a comparable or successor rate to the extent USD LIBOR rates are no longer available and no mandatory prepayment or redemption provisions would be triggered in that instance.
| • | Increases in material costs as a result of labor shortages and supply chain disruptions may make the development of properties more costly than we originally budgeted; and |
| --- | --- |
| --- | --- |
Third-party security events at vendors, sub-processors, and service providers could also impact our data and operations via unauthorized access to information or disruption of services which may ultimately result in financial losses.
Despite training, detection systems and response procedures, an increase in email attacks (phishing and business email compromise) may create disruption to our business and financial risk.
Although security incidents have had an insignificant financial impact on our operating results, the growing frequency of attempts may lead to increased costs to protect the company and respond to any events, including additional personnel, consultants and protection technologies.
Additionally, remediation costs for security events may not be covered by our insurance.
For the year ended December 31, 2020, $289 million or 8.9% of our total consolidated segment NOI, as disclosed in Note 17 to the Consolidated Financial Statements in Item 8.
Financial Statements and Supplementary Data, was denominated in a currency other than the U.S. dollar.
which represented 26.2% of the aggregate square footage of our operating properties and 27.1% of our NOI.
coverage.
In July 2017, the FCA announced it intended to stop compelling banks to submit rates for the calculation of LIBOR after 2021.
In November 2020, the Federal Reserve Board along with various independent groups announced the potential for certain USD LIBOR tenors to continue to be published until June 2023.
The expected transition of GBP LIBOR and Yen LIBOR at the end of 2021 was not impacted by this announcement.
Additionally, other global regulators have undertaken reference rate reform initiatives to identify a preferred alternative rate for other interbank offered rates (“IBORs”).
We refer to these rates collectively as “IBOR-indexed”.
At December 31, 2020 we had variable rate debt of $2.0 billion, excluding borrowings that are hedged through interest rate swap agreements.
Our loan documents contain provisions that contemplate alternative methods to determine the base rate applicable to our IBOR-indexed debt to the extent IBOR-indexed rates are not available.
Additionally, no mandatory prepayment or redemption provisions would be triggered under our loan documents in the event that the IBOR-indexed rates are not available.
If a contract is not transitioned to a preferred alternative rate and IBOR-indexed rates are discontinued, the impact on our debt and derivative financial instruments is likely to vary by contract.
If IBOR-indexed rates are discontinued or if the methods of calculating the rates change, interest rates on our current or future indebtedness may be adversely affected.
While we currently expect IBOR-indexed rates to be available until the end of 2021, it is possible that they will become unavailable prior to that time.
While management continually reviews the effectiveness of our disclosure controls and
We do not currently consider ourselves to be exposed to regulatory risks related to climate change, as the operation of our buildings typically does not generate a significant amount of greenhouse gas emissions.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
221 rewritten, 74 added, 128 removed, 314 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
A discussion regarding our financial condition and results of operations for [removed: 2020] [added: 2021] compared to [removed: 2019] [added: 2020] is presented below.
Information on [removed: 2018] [added: 2019] is included in graphs only to show year over year trends in our results of operations and operating metrics.
Our financial condition for [removed: 2018 and] [added: 2019,] results of operations for [removed: 2018 and] 2019 [added: and 2020] compared to [removed: 2018] [added: 2019 and details on the IPT Transaction and LPT Transaction referenced throughout this document] can be found under Item 7.
Management’s Discussion and Analysis of Financial Condition and Results of Operations, which is incorporated by reference herein to our Annual Report on [Form [removed: 10-K](https://www.sec.gov/ix?doc=/Archives/edgar/data/1045609/000156459020004096/pld-10k_20191231.htm)] [added: 10-K](https://www.sec.gov/ix?doc=/Archives/edgar/data/1045609/000156459021005312/pld-10k_20201231.htm)] for the fiscal year ended December 31, [removed: 2019,] [added: 2020,] filed with the SEC on February 11, [removed: 2020,] [added: 2021,] and is available on the SEC’s website at www.sec.gov and our Investor Relations website at www.ir.prologis.com.
[removed: | • |] We earned promotes aggregating [removed: $241] [added: $98] million [removed: ($164] [added: ($43] million net of related expenses), primarily [removed: in June] [added: during the fourth quarter of 2021] from [added: one of] our unconsolidated co-investment [removed: venture] [added: ventures] in [removed: the U.S. |][added: Europe.]
[removed: | • |] We generated net proceeds of [removed: $3.0] [added: $5.2] billion and realized net gains of [removed: $717 million,] [added: $1.6 billion,] principally from the contribution of properties to our unconsolidated co-investment ventures in [removed: the U.S., Europe, Mexico] [added: Japan, Europe] and [removed: Japan] [added: the U.S.] and dispositions to third [removed: parties in the U.S. and Europe, including a majority of the U.K. portfolio acquired in the Liberty Transaction. |][added: parties.]
[removed: | • | Additionally, we] [added: We] completed the following consolidated financing activities that included the issuance of [removed: $6.2] [added: $2.9] billion and redemption of [removed: $3.0] [added: $1.5] billion of senior notes, with aggregate principal [added: amounts] in U.S. dollars. [removed: This resulted in extending our weighted average remaining maturity to 10 years and lowering our weighted average effective interest rate to approximately 1.9% (principal in millions): |]
| | [removed: Initial Borrowing] [added: Issuance] Date | | Borrowing Currency | | | | USD (1) | | | | Interest Rate (2) | | | | Term (3) | | | | Maturity Dates |
| | (2) | The [added: weighted average] interest rate represents the fixed or variable interest [removed: rate] [added: rates of the related debt] at the issuance or redemption [removed: date of the related debt.] [added: date.] |
| | (3) | The [removed: issuance date and redemption date] weighted average term [removed: represent] [added: represents] the remaining maturity in years on the related debt at the issuance or redemption [removed: date, respectively.] [added: date.] |
At December 31, [removed: 2020,] [added: 2021,] we had total available liquidity of [removed: $4.8] [added: $5.0] billion, principally due to [removed: current] aggregate availability under our credit facilities of [removed: $3.9] [added: $4.4] billion and unrestricted cash balances of [removed: $598] [added: $556] million.
Each segment’s NOI is reconciled to [removed: a] line [removed: item] [added: items] in the Consolidated Financial Statements [added: as provided] in [removed: their respective segment discussions] [added: the related discussion] below.
| Real Estate Operations – NOI | | $ | [removed: 2,820] [added: 3,105] | | | $ | [removed: 2,091] [added: 2,820] | |
| Strategic Capital – NOI | | | [removed: 419] [added: 384] | | | | [removed: 307] [added: 419] | |
| General and administrative expenses | | | [removed: (275] [added: (294] | ) | | | [removed: (266] [added: (275] | ) |
| Depreciation and amortization expenses | | | [removed: (1,562] [added: (1,578] | ) | | | [removed: (1,140] [added: (1,562] | ) |
| Operating income before gains on real estate transactions, net | | | [removed: 1,402] [added: 1,617] | | | | [removed: 992] [added: 1,402] | |
| Gains on dispositions of development properties and land, net | | | [removed: 465] [added: 817] | | | | [removed: 468] [added: 465] | |
| Gains on other dispositions of investments in real estate, net | | | [removed: 252] [added: 773] | | | | [removed: 390] [added: 252] | |
| Operating income | | $ | [removed: 2,119] [added: 3,207] | | | $ | [removed: 1,850] [added: 2,119] | |
We allocate the costs of our property management and leasing functions to the Real Estate Operations segment through *Rental Expenses* [removed: and the Strategic Capital segment through *Strategic Capital Expenses* based on the square footage of the relative portfolios.]
Below are the components of Real Estate Operations [removed: revenues, expenses and NOI (in millions),] [added: NOI,] derived directly from [added: line items in] the Consolidated Financial [removed: Statements.][added: Statements (in millions):]
| Rental revenues | | $ | [removed: 3,791] [added: 4,148] | | | $ | [removed: 2,832] [added: 3,791] | |
| Development management and other revenues | | | [removed: 11] [added: 20] | | | | [removed: 6] [added: 11] | |
| Rental expenses | | | [removed: (952] [added: (1,041] | ) | | | [removed: (734] [added: (952] | ) |
| Other expenses | | | [removed: (30] [added: (22] | ) | | | [removed: (13] [added: (30] | ) |
| Real Estate Operations – NOI | | $ | [removed: 2,820] [added: 3,105] | | | $ | [removed: 2,091] [added: 2,820] | |
The change in Real Estate Operations [added: (“REO”)] NOI in [removed: 2020] [added: 2021] compared to [removed: 2019] [added: 2020 of approximately $285 million] was impacted by the following [removed: items (dollars in] [added: activities (in] millions):
[removed: 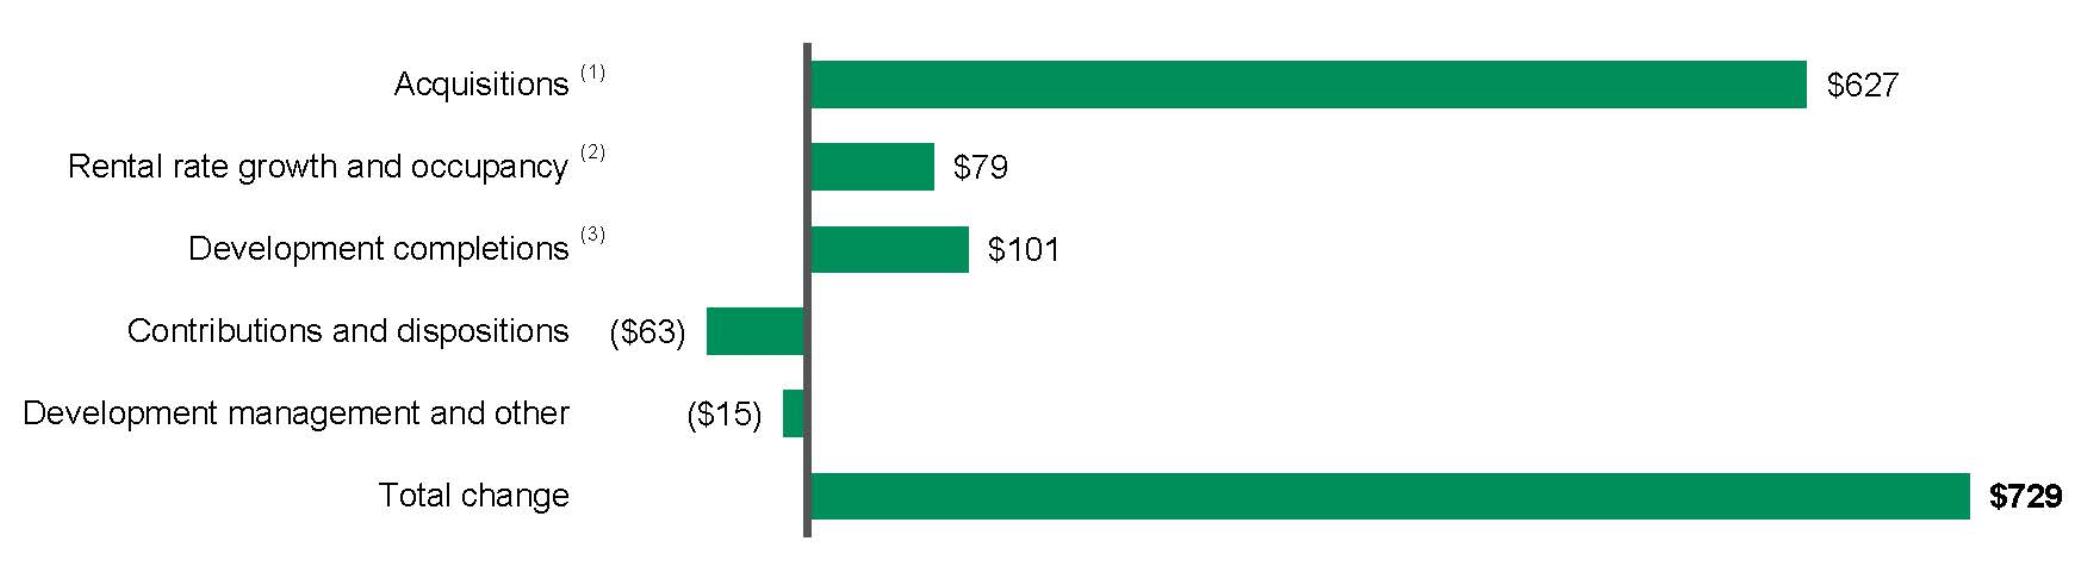][added: ]
| [removed: (2)] [added: (1)] | During both [removed: years,] [added: periods,] we experienced positive rental rate growth. Rental rate growth is a combination of higher rental rates on rollover of leases (or rent change) and contractual rent increases on existing leases. If a lease has a contractual rent increase driven by a metric that is not known at the time the lease commences, such as the consumer price index or a similar metric, the rent increase is not included in rent leveling and [removed: therefore,] [added: therefore] impacts the rental revenue we recognize. [added: Significant rent change during both periods continues to be a key driver in increasing rental income.] See below for key metrics on rent change on rollover and occupancy for the consolidated operating portfolio. |
| (3) | We calculate changes in NOI from development completions period over period by comparing the change in NOI generated on the pool of developments that completed on or after January 1, [removed: 2019] [added: 2020] through December 31, [removed: 2020.] [added: 2021.] |
[removed: 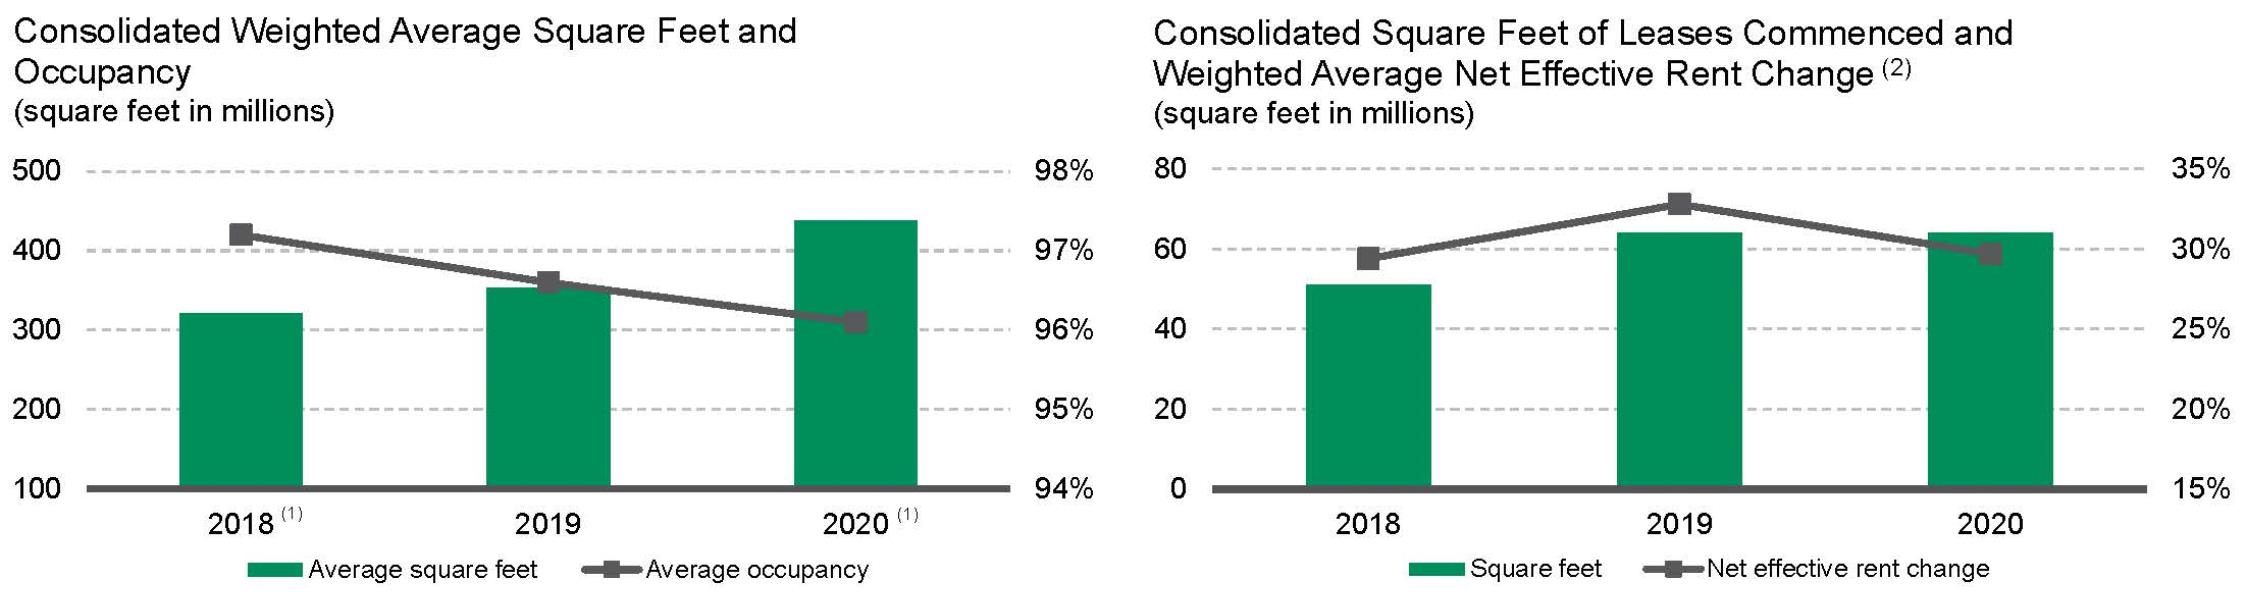][added: 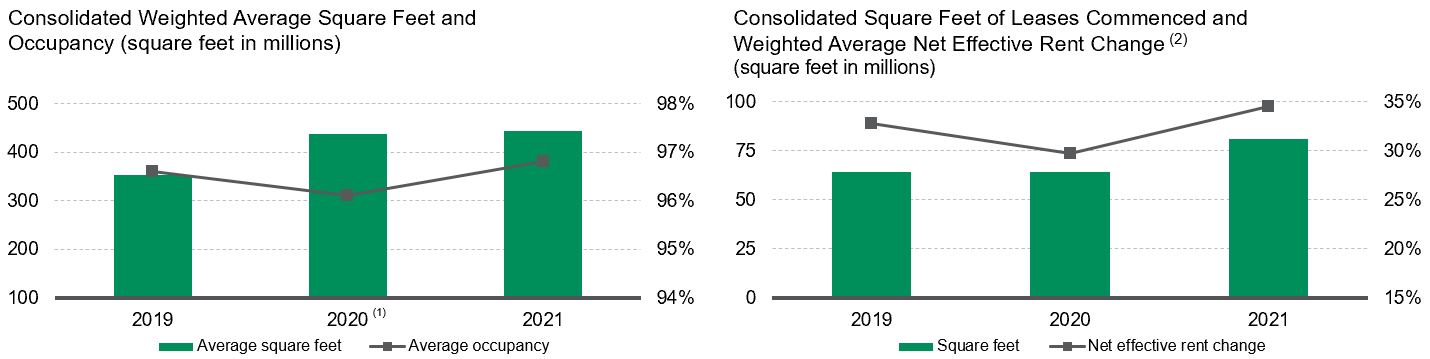]
| Number of new development projects during the period | | | [removed: 42] [added: 78] | | | | [removed: 74] [added: 42] | |
| Square feet | | | [removed: 14] [added: 26] | | | | [removed: 25] [added: 14] | |
| TEI | | $ | [removed: 1,997] [added: 3,478] | | | $ | [removed: 2,741] [added: 1,997] | |
| Percentage of build-to-suits based on TEI | | | [removed: 40.0] [added: 46.2] | % | | | [removed: 44.0] [added: 40.0] | % |
| Number of development projects stabilized during the period | | | [removed: 66] [added: 62] | | | | [removed: 72] [added: 66] | |
| Square feet | | | [removed: 23] [added: 19] | | | | [removed: 26] [added: 23] | |
| TEI | | $ | [removed: 2,451] [added: 2,329] | | | $ | [removed: 2,422] [added: 2,451] | |
| Percentage of build-to-suits based on TEI | | | [removed: 48.9] [added: 42.7] | % | | | [removed: 36.9] [added: 48.9] | % |
Summary of 2021
Our financial condition and operating results were strong during 2021.
E-commerce continues to grow well above its historical average and demand for space is robust based on our proprietary data.
As demand surges, having the right logistics real estate in the right location is mission critical for our customers, which is evident with our O&M occupancy at 97.7% at December 31, 2021.
Leasing activity accelerated for our portfolio during 2021.
Our outlook for 2022 is equally as promising as we expect increases in market rents and asset valuations to drive our operating results as well as our execution of profitable deployment activities.
In December 2021, UKLV sold its operating properties to our unconsolidated co-investment ventures, PELF and PELP, and its land to us.
This resulted in a consolidated weighted average remaining maturity of 10 years and lowered our weighted average effective interest rate to 1.6% at December 31, 2021 (principal in millions):
| | February | | € | 1,350 | | | $ | 1,639 | | | 0.7% | | | | | 14.3 | | | February 2032 – 2041 |
| | February | | $ | 400 | | | $ | 400 | | | 1.6% | | | | | 10.1 | | | March 2031 |
| | June | | ¥ | 65,000 | | | $ | 587 | | | 0.8% | | | | | 15.4 | | | June 2028 – 2061 |
| | December | | £ | 215 | | | $ | 285 | | | 2.0% | | | | | 17.7 | | | December 2033 – 2041 |
| | Total | | | | | | $ | 2,911 | | | 1.0% | | | | | 14.2 | | | |
| | March | | € | 600 | | | $ | 716 | | | 3.4% | | | | | 3.0 | | | February 2024 |
| | March | | $ | 750 | | | $ | 750 | | | 3.8% | | | | | 4.7 | | | November 2025 |
| | Total | | | | | | $ | 1,466 | | | 3.6% | | | | | 3.8 | | | |
In April 2021, we increased our available liquidity by entering into a second global senior credit facility with an available borrowing capacity of $1.0 billion and we terminated the $500 million multi-currency term loan.
| | | 2021 | | | | 2020 | | |
and the Strategic Capital segment through *Strategic Capital Expenses* based on the square footage of the relative portfolios.
| | | 2021 | | | | 2020 | | |
| (2) | One of the drivers of the increase in NOI in 2021, compared to 2020, was the Liberty Transaction on February 4, 2020. In the transaction we acquired 519 industrial operating properties, aggregating 100 million square feet, and increased our consolidated investments in real estate by approximately $13 billion. |
| (1) | In 2020, we completed the Liberty Transaction. |
| | | 2021 | | | | 2020 | | |
| Estimated value creation | | $ | 1,284 | | | $ | 932 | |
| (2) | Estimated weighted average margin is calculated on development properties as estimated value creation, less estimated closing costs and taxes, if any, on properties expected to be sold or contributed, divided by TEI. |
While construction costs increased during 2021, we continue to maintain high margins as a result of lower capitalization rates and higher market rents.
Our current investment in the development portfolio was $2.7 billion and we expect our development activities to increase in 2022.
Our capital expenditures continue to increase year over year as we grow the consolidated operating portfolio through development stabilizations and acquisitions.
We plan to continue allocating capital in 2022 to renovate and modernize our operating portfolio, including the addition of sustainable and efficient building features.
For further details regarding the key property information and summarized financial condition and operating results of our unconsolidated co-investment ventures, refer to Note 5 to the Consolidated Financial Statements.
| | | 2021 | | | | 2020 | | |
| | | 2021 | | | | 2020 | | | | 2021 | | | | 2020 | | | | 2021 | | | | 2020 | | | | 2021 | | | | 2020 | | | | 2021 | | | | 2020 | | | |
G&A expenses increased in 2021 as compared to 2020, due to higher compensation expenses based largely on our outperformance and the increase in our share price.
For discussion on our long-term incentive plans refer to the proxy statement for our 2021 annual meeting of stockholders.
| | | 2021 | | | | 2020 | | |
The change in depreciation and amortization expenses in 2021 compared to 2020 of approximately $16 million was impacted by the following activities (in millions):
Gains on the disposition of development properties and land were $817 million and $465 million for 2021 and 2020, respectively, and primarily included gains from the contribution of properties we developed to our unconsolidated co-investment ventures in Japan, the U.S. and Europe.
Gains on other dispositions of investments in real estate were $773 million and $252 million for 2021 and 2020, respectively, which included sales of operating properties, including certain non-strategic assets acquired in the Liberty Transaction and the IPT Transaction, the contribution of operating properties to our unconsolidated co-investment venture in the U.S. and the sale of our ownership interest in other unconsolidated ventures.
Value-added properties are properties we have either acquired at a discount and believe we could provide greater returns post-stabilization or properties we expect to repurpose to a higher and better use.
| | 2021 | | | | | | | | | | | | 2020 | | | | | | | | | | |
Summary of 2020
Our financial condition and operating results remain strong in the COVID-19 environment and, in combination with the demand we see in our proprietary data, the pace of rent collections and dialogue with our customers, our outlook continues to improve in the first quarter of 2021.
However, with the continued uncertainty across the globe until we put COVID-19 behind us, we cannot predict the impact on our business, future financial condition, and operating results.
We experienced minimal impacts from the current environment on our O&M portfolio operating fundamentals in 2020.
This is the result of the high quality and location of our real estate portfolio, our customer base, favorable market fundamentals in the logistics real estate sector and significant in-place-to-market rent spreads.
E-commerce continues to grow well above its historical average and customers that serve essential daily needs are thriving.
Customers that have been negatively impacted by the current economy represent a minimal percentage of our annual rent.
Leasing activity remained strong for the O&M portfolio throughout 2020 with the commencement of 150 million square feet of leases with an average term of 66 months, including 37 million square feet in the fourth quarter.
Rent change in our O&M portfolio was 21.3% during 2020 and 23.8% in the fourth quarter.
We expect market rents to continue to increase in 2021.
The average number of days from lease proposal to commencement decreased since 2019 as some customers have increased the pace of activity.
We received requests from certain customers for rent concessions during 2020 and for those granted, we deferred the rental payments to a later period in 2020 or 2021.
The deferral of rental payments did not impact revenue recognized from those leases.
During 2020, on an O&M basis we deferred $45 million of rental payments which represented less than 1% of our total O&M annualized rental revenue.
At January 25, 2021, we had collected $33 million, or 98%, of the deferred payments due at December 31st, with the remainder due in 2021.
Although COVID-19 continues to have a minimal impact on our rent collections and bad debt is trending lower than we initially anticipated, we may experience an increase in bad debt.
Our capital deployment and disposition activities have continued throughout this time and we expect the volume of these activities to accelerate in 2021.
By the fourth quarter of 2020, we restarted the majority of the speculative development projects that we suspended in the first quarter.
Our business continuity, communication plans and technology are allowing all functions of our business to work smoothly during this time.
Generally, our employees have continued working remotely or in certain locations in our offices under protocols to keep a safe working environment.
We have not had any lay-offs and we have extended financial assistance to employees in need.
Our local property and leasing teams have continued to maintain our properties and work with our customers to help them navigate the new environment while following established measures to help keep them and our customers safe.
In addition, we are providing assistance across the globe in the form of direct cash grants, supplies and donation of over one million square feet through our Space for Good program.
In 2020, through the Prologis Foundation, we pledged $5 million to COVID-19 relief organizations and $1 million in support of racial equality causes.
We completed the following significant activities in 2020 as described in the Notes to the Consolidated Financial Statements:
| • | In January, our U.S. co-investment ventures, USLV and USLF, acquired the wholly owned real estate assets of IPT for $2.0 billion each, including the assumption and repayment of debt. As USLV is a consolidated co-investment venture, our Results of Operations section includes a discussion of the acquired properties. USLF is an unconsolidated co-investment venture and therefore the acquisition is included in the discussion of our O&M Operating Portfolio. |
| --- | --- |
| • | In February, we completed the Liberty Transaction for $13.0 billion through the issuance of equity and the assumption of debt. We assumed $2.8 billion of debt with a weighted average stated interest rate of 3.8%. We paid down $1.8 billion of the assumed debt with senior notes we issued at lower rates in February 2020, as detailed below. |
| --- | --- |
| --- | --- |
| --- | --- |
| --- | --- |
| | February (4) | | € | 1,350 | | | $ | 1,485 | | | 0.6% | | | | 10.7 | | | | February 2022 – 2035 |
| | February | | $ | 2,200 | | | $ | 2,200 | | | 2.4% | | | | | 15.0 | | | April 2027 – 2050 |
| | February | | £ | 250 | | | $ | 322 | | | 1.9% | | | | | 15.8 | | | February 2035 |
| | June (4) | | ¥ | 41,200 | | | $ | 386 | | | 1.0% | | | | | 12.4 | | | June 2027 – 2050 |
| | August (4) | | $ | 1,250 | | | $ | 1,250 | | | 1.6% | | | | | 18.2 | | | October 2030 – 2050 |
| | September | | ¥ | 19,700 | | | $ | 187 | | | 1.0% | | | | | 14.1 | | | September 2032 – 2040 |
| | December | | € | 300 | | | $ | 365 | | | 0.0% | | | | | 2.0 | | | December 2022 |
| | January | | € | 400 | | | $ | 446 | | | 0.0% | | | | 0.1 | | | | January 2020 |
An excerpt. Shown here: 40 of 221 rewritten, 40 of 74 added and 40 of 128 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2021 filing and the FY2020 filing.
Item 7A. Quantitative and Qualitative Disclosures About Market Risk
15 rewritten, 6 added, 7 removed, 24 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
Our sensitivity analysis estimates the exposure to market risk sensitive instruments assuming a hypothetical 10% adverse change in foreign currency exchange rates or interest rates at December 31, [removed: 2020.][added: 2021.]
Additionally, we hedge our foreign currency risk by entering into derivative financial [added: instruments that we designate as net investment hedges, as these amounts offset the translation adjustments on the underlying net assets of our foreign investments.]
At December 31, [removed: 2020,] [added: 2021,] after consideration of our ability to borrow in the foreign currencies in which we invest and also derivative and nonderivative financial instruments as discussed in Note 15 to the Consolidated Financial Statements, we had minimal net equity denominated in a currency other than the U.S. dollar.
For the year ended December 31, [removed: 2020, $442] [added: 2021, $573] million or [removed: 10.0%] [added: 12.0%] of our total consolidated revenue was denominated in foreign currencies.
We have forward contracts that were not designated as hedges, denominated principally in British pound sterling, Canadian dollar, euro and Japanese yen, and have an aggregate notional amount of [removed: $1.2] [added: $1.7] billion to mitigate risk associated with the translation of the future earnings of our subsidiaries denominated in these currencies.
[removed: Although the impact to net earnings is mitigated through higher] translated U.S. dollar earnings from these currencies, a weakening of the U.S. dollar against these currencies by 10% could result in a [removed: $116] [added: $166] million cash payment on settlement of these contracts.
At December 31, [removed: 2020, $14.9] [added: 2021, $15.9] billion of our debt bore interest at fixed rates and therefore the fair value of these instruments was affected by changes in market interest rates.
At December 31, [removed: 2020, $2.0] [added: 2021, $1.9] billion of our debt bore interest at variable rates.
The following table summarizes the future repayment of debt and scheduled principal payments at December 31, [removed: 2020] [added: 2021] (dollars in millions):
| | [removed: 2021] [added: 2022] | | | | [removed: 2022] [added: 2023] | | | | [removed: 2023] [added: 2024] | | | | [removed: 2024] [added: 2025] | | | | Thereafter | | | | Total | | | | Fair Value | | |
| Senior notes | | [removed: \-] [added: 340] | | | | [removed: 368] [added: \-] | | | | \- | | | | \- | | | | \- | | | | [removed: 368] [added: 340] | | | | [removed: 370] [added: 340] | |
| (1) | At December 31, [removed: 2020,] [added: 2021,] we had [added: one] interest rate swap [removed: agreements] [added: agreement] to fix €150 million ($165 million) of our floating rate euro senior notes [removed: and $250 million of our multi-currency term loan, both of] which [removed: were] [added: is] included in fixed rate debt. |
| (2) | The [added: weighted average] interest rates represent the effective interest rates (including amortization of [removed: the] debt issuance costs and [removed: the] noncash premiums and discounts) at December 31, [removed: 2020] [added: 2021] for the debt outstanding. |
At December 31, [removed: 2020,] [added: 2021,] the weighted average effective interest rate on our variable rate debt was 0.5%.
On the basis of our sensitivity analysis, a 10% increase in interest rates on our average outstanding variable rate debt balances would result in additional annual interest expense of $1 million for the year ended December 31, [removed: 2020,] [added: 2021,] which equates to a change in interest rates of 5 basis points on our average outstanding variable rate debt balances and [added: less than] 1 basis point on our average total debt portfolio balances.
Although the impact to net earnings is mitigated through higher
| Fixed rate debt (1) | $ | 646 | | | $ | 36 | | | $ | 136 | | | $ | 188 | | | $ | 14,858 | | | $ | 15,864 | | | $ | 15,995 | |
| Weighted average interest rate (2) | | \-0.1 | % | | | 4.4 | % | | | 7.6 | % | | | 3.1 | % | | | 1.7 | % | | | 1.7 | % | | | | |
| Credit facilities | $ | \- | | | $ | 266 | | | $ | 225 | | | $ | \- | | | $ | \- | | | $ | 491 | | | $ | 491 | |
| Term loans | | \- | | | | 134 | | | | \- | | | | \- | | | | 956 | | | | 1,090 | | | | 1,090 | |
| Total variable rate debt | $ | 340 | | | $ | 400 | | | $ | 225 | | | $ | \- | | | $ | 956 | | | $ | 1,921 | | | $ | 1,921 | |
instruments that we designate as net investment hedges, as these amounts offset the translation adjustments on the underlying net assets of our foreign investments.
| Fixed rate debt (1) | $ | 271 | | | $ | 196 | | | $ | 34 | | | $ | 869 | | | $ | 13,505 | | | $ | 14,875 | | | $ | 16,034 | |
| Weighted average interest rate (2) | | 1.8 | % | | | 0.6 | % | | | 4.5 | % | | | 4.2 | % | | | 2.0 | % | | | 2.1 | % | | | | |
| Credit facilities | $ | \- | | | $ | \- | | | $ | 172 | | | $ | \- | | | $ | \- | | | $ | 172 | | | $ | 172 | |
| Secured mortgage debt | | 105 | | | | 63 | | | | \- | | | | 136 | | | | \- | | | | 304 | | | | 304 | |
| Term loans | | \- | | | | \- | | | | 134 | | | | \- | | | | 1,067 | | | | 1,201 | | | | 1,204 | |
| Total variable rate debt | $ | 105 | | | $ | 431 | | | $ | 306 | | | $ | 136 | | | $ | 1,067 | | | $ | 2,045 | | | $ | 2,050 | |
Item 1. Business
66 rewritten, 83 added, 74 removed, 96 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
We believe the current organization and method of operation [removed: will] enable Prologis, Inc. to maintain its status as a REIT.
We operate and manage our business on an owned and managed (“O&M”) basis and therefore evaluate the operating performance of the properties [removed: in] [added: for] our O&M portfolio, which includes our consolidated properties and properties owned by our unconsolidated co-investment [removed: ventures, which we manage.][added: ventures.]
We make operating decisions based on our total O&M portfolio, as we manage the properties [removed: similarly regardless of] [added: without regard to their] ownership.
We [added: also] evaluate our results based on our proportionate economic ownership of each property included in the O&M portfolio (“our share”) to reflect our share of the financial results of the O&M portfolio.
Management’s Discussion and Analysis of Financial Condition and Results of Operations for a reconciliation of *Net Earnings Attributable to Common [removed: Stockholders*] [added: Stockholders/Unitholders*] in the Consolidated Statements of Income to our FFO measures and a reconciliation of NOI to *Operating Income,* the most directly comparable GAAP measures.
Our corporate headquarters is located at Pier 1, Bay 1, San Francisco, California 94111, and our other principal office locations are in Amsterdam, Denver, [removed: Luxembourg,] Mexico City, Shanghai, Singapore and Tokyo.
Our [removed: local] teams actively manage our [removed: portfolio, which encompasses] [added: portfolio to provide comprehensive real estate services, including] leasing, property management, [removed: capital deployment] [added: development, acquisitions] and [removed: opportunistic] dispositions.
Our [removed: disposition activities] [added: property dispositions] allow us to recycle capital and [removed: largely self-fund] [added: contribute to self-funding] our development and acquisition activities.
Our portfolio [removed: is focused] [added: focuses] on the world’s most vibrant centers of commerce and our scale [added: across these locations] allows us to respond to our customers’ [removed: needs for the highest-quality buildings across these locations.][added: diverse logistics requirements.]
[removed: This positioning] [added: The location of our global portfolio] gives us the unique ability to provide our customers with the right real estate solutions for their supply chains that, in turn, allows them to meet [removed: end\-consumer] [added: end-consumer] delivery expectations.
At December 31, [removed: 2020,] [added: 2021,] we owned or had investments [removed: in properties,] [added: in,] on a wholly-owned basis or through ventures, [removed: in the following geographies (dollars in billions, based] [added: properties and development projects (based] on gross book value and total expected investment [removed: (as defined below) and square feet] [added: at completion, respectively)] in [removed: millions):][added: the following geographies:]
[removed: ][added: 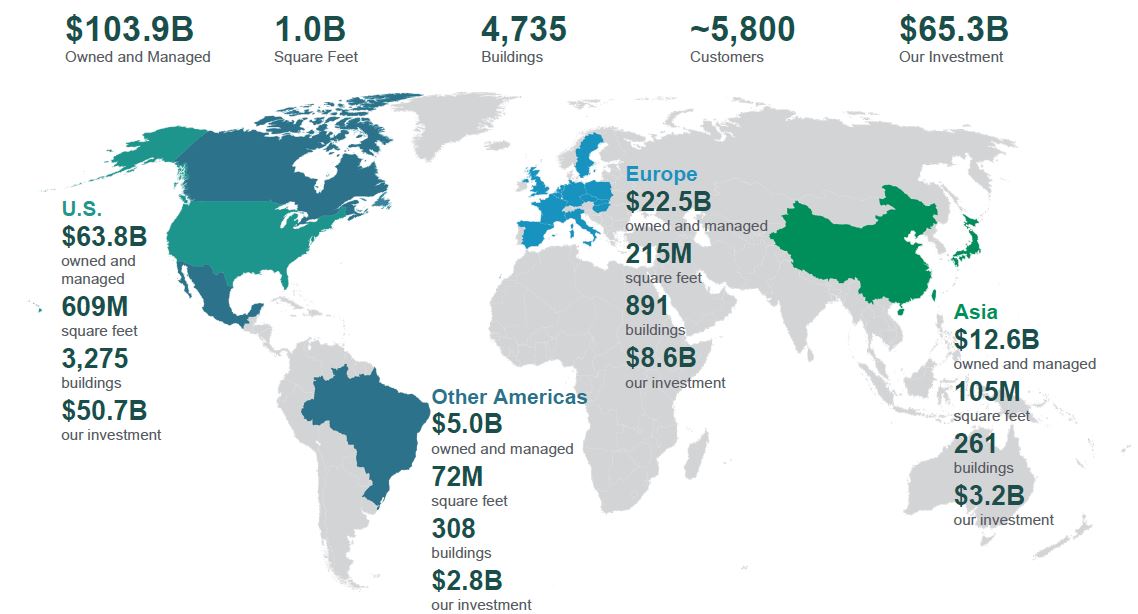]
Throughout this discussion, we reflect amounts in [removed: U.S. dollars,] [added: the United States (“U.S.”) dollar,] our reporting currency.
Included in these amounts are consolidated and unconsolidated investments denominated in foreign currencies, principally the British pound sterling, [added: Canadian dollar,] euro and Japanese yen that are impacted by fluctuations in exchange rates when translated to U.S. dollars.
[removed: 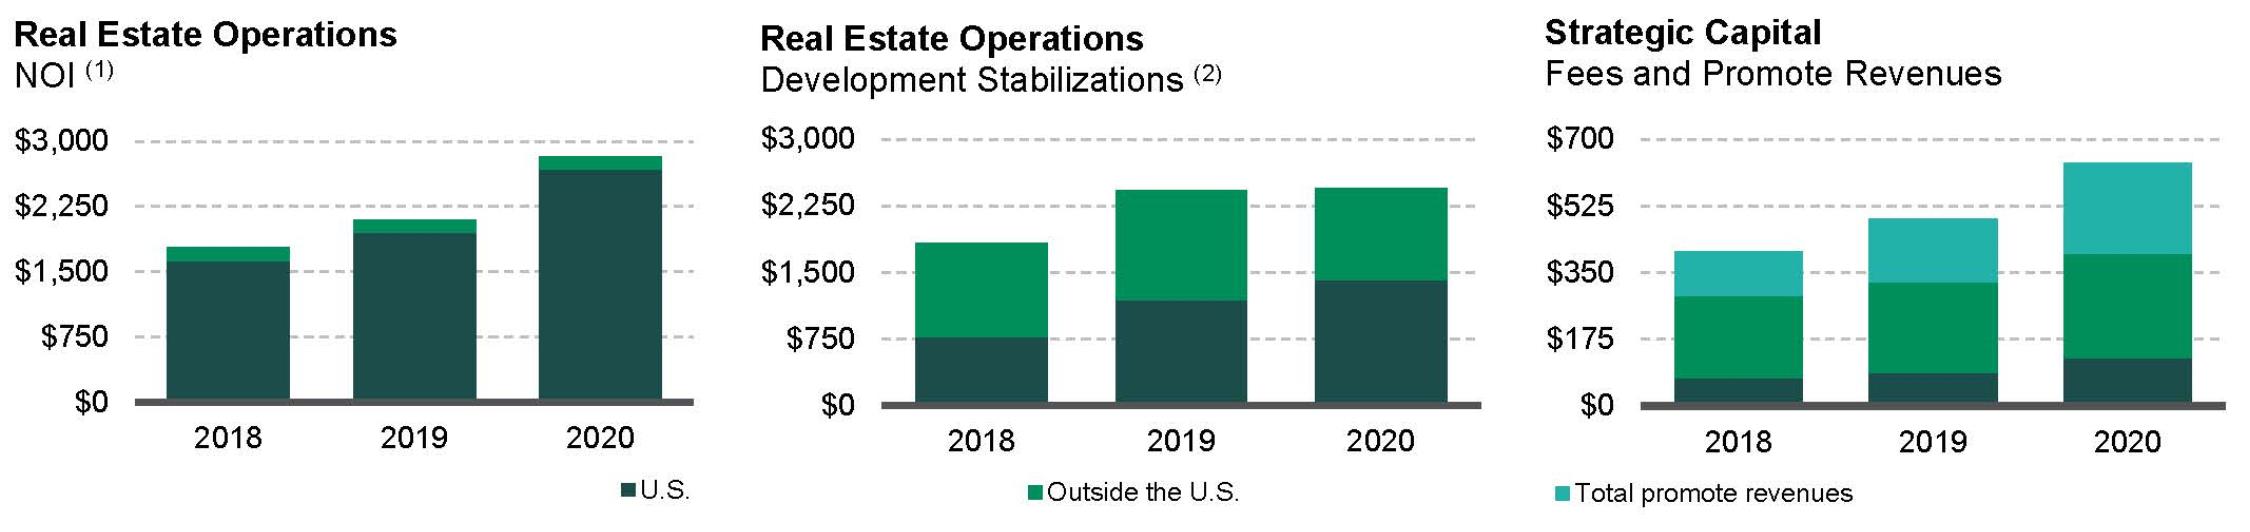][added: ]
| (1) | NOI from Real Estate Operations is calculated directly from our Consolidated Financial Statements as *Rental Revenues* and *Development Management and Other Revenues* less *Rental Expenses* and *Other Expenses.* [added: NOI from Strategic Capital is calculated directly from our Consolidated Financial Statements as *Strategic Capital* *Revenues* less *Strategic Capital* *Expenses.*] |
| (2) | A developed property moves into the operating portfolio when it meets our definition of stabilization, which is the earlier of [added: when a property that was developed has been completed for] one [removed: year after] [added: year, is contributed to a co-investment venture following] completion or [added: is] 90% [removed: occupancy.] [added: occupied.] Amounts represent our total expected investment (“TEI”), which includes the estimated cost of [removed: development,] [added: development or expansion,] land, construction and leasing costs. |
Rental operations comprise the largest component of our operating segments and generally contribute 85% to 90% of our consolidated revenues, earnings and [removed: funds from operations (“FFO”).][added: FFO.]
[removed: A majority] [added: Substantially all] of our consolidated rental revenue, NOI and cash flows are generated in the U.S.
Given the scarcity of modern logistics facilities in our target markets, our development business provides [removed: us] the opportunity to build [removed: what] [added: to] our [removed: customers need.][added: customers’ current and future requirements and deepen our market presence.]
We believe we have a competitive advantage due to (i) the strategic locations of our [added: global] land bank and redevelopment sites; (ii) the development expertise of our local teams; [removed: and] (iii) the depth of our customer [removed: relationships.][added: relationships and (iv) our ability to integrate sustainable design features and practices, as detailed in our Environmental Stewardship, Social Responsibility and Governance section below, that result in cost-savings and operational efficiencies for our customers.]
Based on our current estimates, our consolidated land, including [removed: options,] [added: options and Covered Land Plays,] has the potential to support the development of [removed: $11.8] [added: $22.2] billion [added: ($26.4 billion on an O&M basis)] of TEI of new logistics space.
Our strategic capital segment allows us to partner with many of the world’s largest institutional [removed: investors and capitalize our business through private equity, principally perpetual open-ended or long-term ventures.][added: investors.]
We [removed: also access capital in this segment] [added: capitalize our business] through [added: private equity, principally perpetual open-ended or long-term ventures, and] two publicly traded vehicles: Nippon Prologis REIT, Inc. in Japan and FIBRA Prologis in Mexico.
We align our interests with our partners by holding significant ownership interests in all of our [removed: 9] [added: eight] unconsolidated co-investment ventures (ranging from 15% to [removed: 50%), which allows us to reduce our exposure to foreign currency movements for investments outside the U.S.][added: 50%).]
This segment produces [removed: stable,] [added: durable,] long-term cash flows and generally contributes 10% to 15% of our recurring consolidated revenues, earnings and FFO.
We generate strategic capital revenues from our unconsolidated co-investment ventures, principally through asset [added: management] and property management services.
We earn additional revenues by providing leasing, acquisition, [removed: construction,] [added: construction management,] development and disposition services.
In certain ventures, we also have the ability to earn revenues through incentive fees (“promotes” or “promote revenues”) periodically during the life of a venture or upon [removed: liquidation.][added: liquidation based primarily on the appreciation of the portfolio.]
We believe the quality and scale of our global portfolio, [added: our ability to build out] the [added: global land bank, our strategic capital business, the] expertise of our team, the depth of our customer relationships and the strength of our balance sheet [removed: give] [added: are differentiators that allow] us [removed: unique competitive advantages] to [removed: grow] [added: drive growth in] revenues, NOI, earnings, FFO and cash flows.
[removed: 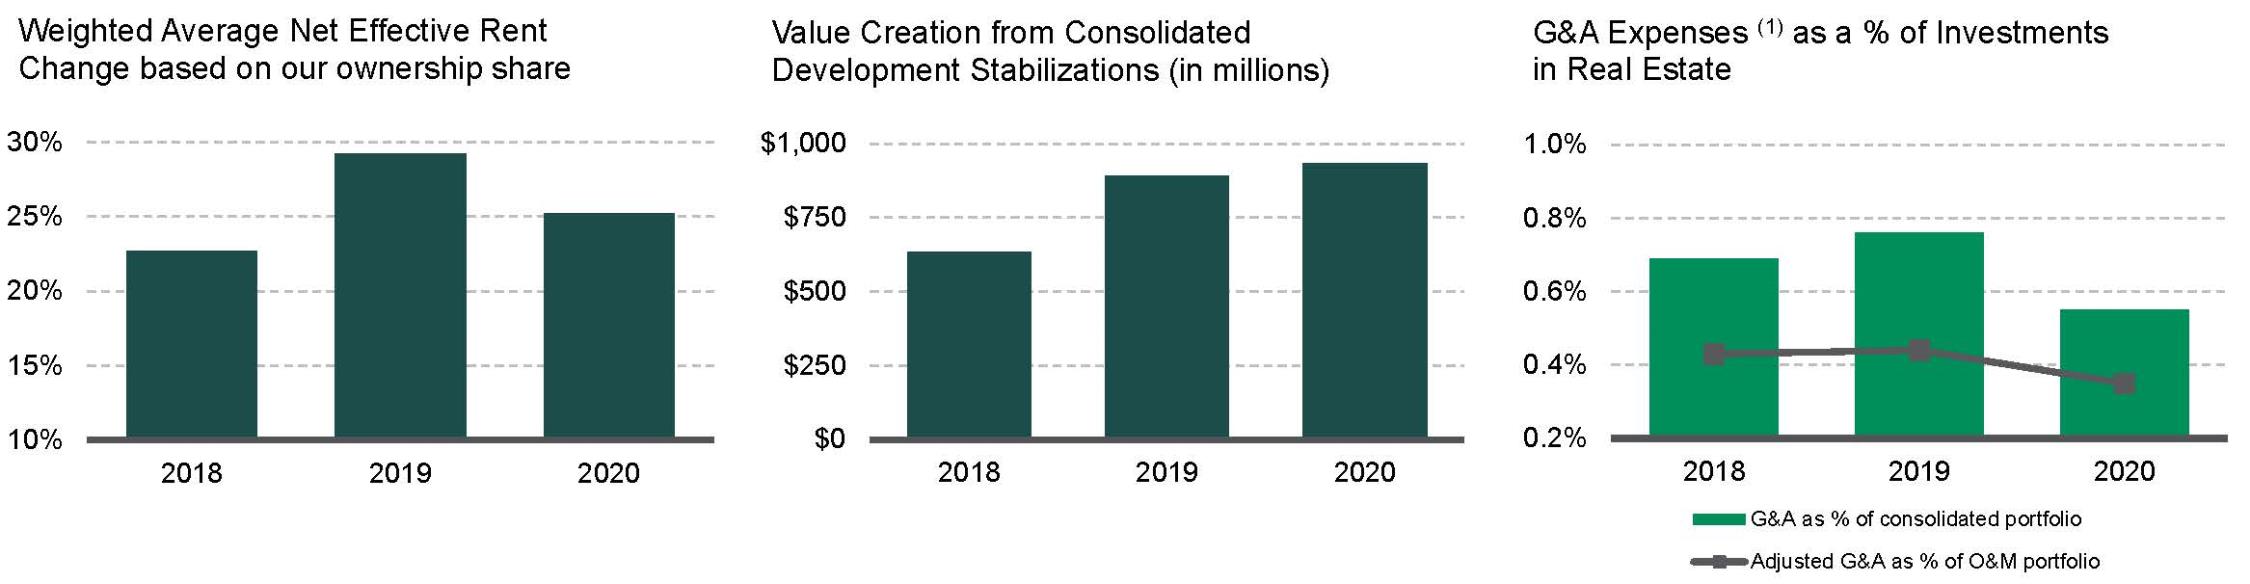][added: ]
| • | Rent Growth. [removed: Despite the COVID-19 pandemic and the current economic environment, we] [added: We] expect rents in our markets to [added: continue to] increase due to [added: the] demand for the location and quality of our properties. In addition, due to strong market rent growth over the last several years, our in-place leases have considerable upside [removed: potential.] [added: potential to drive future incremental organic NOI growth.] We estimate that [removed: the rental rates of] our [removed: leases are 13% below current] [added: net effective lease mark-to-market is approximately 36%, which represents the growth rate from in-place rents to] market [added: rents based] on [removed: the basis of] our weighted average ownership [added: of the O&M portfolio] at December 31, [removed: 2020.] [added: 2021.] Therefore, even if market rent growth is [removed: flat, a] [added: flat in the future, we expect our] lease [removed: renewal will likely] [added: renewals to] translate into [removed: increased] [added: significant increases in] future rental income, on a consolidated basis or through the earnings we recognize from our unconsolidated co-investment ventures based on our ownership. We have experienced positive rent change on rollover (comparing the net effective rent (“NER”) of the new lease to the prior lease for the same space) in every quarter since 2013. [removed: We expect this trend to continue for several more years due to our current in-place rents being below market. We also expect future growth in market rents to further contribute to increased rental income.] |
| • | Economies of Scale from Growth. We [removed: use adjusted G&A expenses as a percentage of the O&M portfolio to measure and evaluate our overhead costs. We] have scalable systems and infrastructure in place to grow both our consolidated and O&M portfolios with limited incremental G&A expense. We believe we can continue to grow NOI and strategic capital revenues organically and through accretive development and acquisition activity while further reducing G&A as a percentage of our investments in real estate. [added: We use adjusted G&A expenses as a percentage of the O&M portfolio (based on gross book value) to measure and evaluate our overhead costs.] As [removed: noted] [added: shown] in the graph above, the acquisitions of [removed: the] Liberty [added: Property Trust] and [removed: IPT portfolios] [added: Liberty Property Limited Partnership (collectively “Liberty” or the “Liberty Transaction”) and Industrial Property Trust Inc. (“IPT” or the “IPT Transaction”) in 2020] are key examples of this effort, where we increased our investments in real estate in the O&M portfolio by over 20% [removed: in the first quarter of 2020] and had minimal increases to G&A expenses, [removed: which results] [added: resulting] in lower G&A expenses as a percentage of [removed: the] investments in real estate. |
Real estate ownership is highly fragmented, and we [removed: therefore] face competition from many owners and operators.
We [removed: may] face competition regarding our capital deployment activities, including [removed: local, regional and] [added: regional,] national [added: and global] operators or developers.
Despite the [removed: competition we may face,] [added: competition,] our [removed: strategic focus] [added: global reach and local market knowledge] over the years has given us distinct competitive advantages, including the following:
| • | [removed: an investment in ESG practices that enhances asset values while improving sustainability performance, including the] development of logistics facilities with sustainable design features that meet customer needs for high-quality [removed: buildings;] [added: buildings while enabling them to make progress on their own sustainability objectives;] |
| • | the ability to leverage [removed: our] [added: the] organizational scale and structure [added: of our 1.0 billion square foot O&M portfolio] to provide a single point of contact for our [removed: focus] [added: multi-market] customers to address their needs through our in-house global customer [added: led] solutions team; |
| • | relationships and successful track record with current and prospective investors in our strategic capital [removed: business;] [added: business that is comprised of 95% perpetual long-term ventures and two publicly traded vehicles;] |
| • | a strong balance sheet and credit ratings, coupled with significant [removed: liquidity and] [added: liquidity,] borrowing [removed: capacity.] [added: capacity and long-term fixed debt with low rates.] |
With the broadening of e-commerce adoption driving requirements for increased warehouse space to store inventory, surging customer demand has continued to outpace supply.
We believe this demand surge is driven by three primary factors: (i) overall consumption growth; (ii) customer supply chains still re-positioning to address the significant shift to e-commerce, as well as preparing for higher growth and service expectations; and (iii) our customers’ desire for more supply chain resiliency.
With inventory-to-sales ratios below pre-pandemic levels, our customers not only need to restock for this shortfall, but build an additional safety stock.
We believe these forces have placed a premium on speed-to-market and flexibility, driving demand for years to come.
The scale of our 1.0 billion square foot portfolio allows us to help our customers in a multitude of unique ways.
We continue to focus on differentiated ways to meet our customers’ needs through our Prologis Essentials business.
This program includes product and service solutions for our customers’ operations, workforce, energy, transportation and data and analytic needs.
Our integrated suite of solutions allows our customers to benefit from our global scale, strategic partnerships with vendors and local expertise to obtain services and products more efficiently.
We use our proprietary data and analytics to provide our customers actionable insights on everything from inventory, shipping, security, communications management and dock visibility.
Prologis Essentials has a strong sustainability component to its suite of services, which supports our customers’ progress toward their sustainability goals.
This includes new development and redevelopment of buildings to specifications that align with leading sustainable building standards and implementation of energy solutions such as solar power and LED lighting.
As we explore additional ways to deliver revenue-generating sustainability solutions, we created a new senior leadership role in 2021 – chief sustainability and energy officer.
We also are anticipating the introduction of electric vehicle (“EV”) fleets in logistics and are making long-term investments in our portfolio and talent to be well prepared for the future of EV trucking and logistics.
For leases that commenced during 2021 within the consolidated operating portfolio, the weighted average lease term was 62 months.
This structure allows us to reduce our exposure to foreign currency movements for investments outside the U.S.
Asset management fees are primarily driven by the real estate valuation of the respective ventures.
Most of the strategic capital revenues are generated outside the U.S.
| • | Value Creation from Development. A successful development and redevelopment program requires maintaining control of well-located land and redevelopment sites and sourcing a future pipeline through acquisition opportunities, including our innovative approach with Covered Land Plays, which are income generating assets acquired with the intention to redevelop for higher and better use as industrial properties. The global nature of our development program is a wide landscape of opportunities to pursue based on our judgement of market conditions, opportunities and risks. We believe that the carrying value of our global land bank is meaningfully below its current fair value. Due to the strategic nature of our global land bank, development expertise of our teams and strength of our customer relationships, we expect to create value as we build new properties. |
We are able to maintain strong margins despite rising construction costs, as we experienced in 2021, due to our procurement activities that mitigate a portion of the inflationary increases, as well as rising market rents.
We measure the estimated value creation of a development project as the margin above our TEI.
As properties stabilize, we expect to realize the value creation principally through contributions to unconsolidated co-investment ventures and increases in the NOI of the consolidated portfolio.
Our current investment in the development portfolio was $2.7 billion and we expect our development activities to increase in 2022.
| • | Strategic Capital Advantages. We continue to successfully raise capital to propel the long-term growth of the co-investment ventures while maintaining our substantial investments in these vehicles. At December 31, 2021, the gross book value of the operating portfolio held by our eight unconsolidated co-investment ventures was $45.3 billion across 456 million square feet. During 2021, the valuations of the real estate portfolios owned by the unconsolidated co-investment ventures increased significantly, resulting in higher asset management fees. We expect that continued market rent growth will result in an increase in the asset valuations of the unconsolidated co-investment ventures, which will drive significant returns to the investors and increase the potential for earning promote revenues over the next couple of years. Our Strategic Capital business generates durable fee streams, with asset management fees marked to fair values each quarter, all while requiring minimal capital other than our investment in the venture. |
| • | Balance Sheet Strength. We continue to seek and execute on opportunities to refinance debt at historically low rates. Our financing activities over the last three years resulted in extending our consolidated weighted average remaining maturity from 6 to 10 years and lowering our weighted average effective interest rate from 2.7% to 1.6% at January 1, 2019 and December 31, 2021, respectively. At December 31, 2021, we had total available liquidity of $5.0 billion and continue to maintain low leverage as a percentage of our real estate investments and our market capitalization. As a result of our low leverage, available liquidity and investment capacity in the co-investment ventures, we have significant capacity to capitalize on value-added investment opportunities that will translate into future earnings growth. |
| • | Staying “Ahead of What’s Next™”. We are focused on creating value beyond real estate by enhancing our customers’ experience, leveraging our scale to deliver the best value through our procurement activities and constantly innovating through data analytics and digitization efforts. Our Prologis Essentials business supports our customers’ through service and product offerings, including innovative solutions to operations, transport, technology, energy, and labor challenges that can make our customers’ decision process easier and their enterprise more efficient. Additionally, we invest in sustainable logistics building design features and practices, such as the addition of solar panels, LED lighting and EV charging, that also allows us to assist our customers with their sustainability performance. |
| • | long-term relationships with customers served by our customer experience team that allows us to proactively and promptly respond to their needs across our global platform; |
| • | the access our customers have to Prologis Essentials integrated suite of solutions; |
| • | a strategically located, global land bank and redevelopment sites that have the potential to support the development of $26.4 billion of TEI of new logistics space on an O&M basis; |
| • | local teams with the expertise, experience and relationships to lease our properties and deploy capital advantageously; |
| • | a market intelligence team that allows us to track business conditions in real time, proactively pursue market opportunities and disruptions alike, and develop revenue-generating capabilities to strengthen our operational excellence; |
| • | an investment in technology and talent to support our sustainability objectives, including expanding our efforts around renewable energy; |
| • | Prologis Ventures, our corporate venture capital group, and Prologis Labs, our initiative for testing new technologies alongside our customers, together track the leading edge of innovation within real estate and the supply chain, creating important capabilities that connect Prologis with the C-suites of our customers; and |
| --- | --- |

| --- | --- |
| | Consolidated - Real Estate Operations | | | | | | | | | Owned and Managed | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| 1. Amazon | | 7.0 | | | | 24 | | | 1. Amazon | | 4.8 | | | | 33 | |
| 2. FedEx | | 2.1 | | | | 7 | | | 2. Geodis | | 1.4 | | | | 15 | |
| 4. Geodis | | 1.1 | | | | 5 | | | 4. DHL | | 1.2 | | | | 11 | |
The majority of our properties in the United States (“U.S.”) are wholly owned, while our international properties are primarily held in our co-investment ventures, which has the benefit of mitigating our exposure to foreign currency movements.
There is an emergence of two new structural demand drivers for our real estate: (i) the need for more inventory as supply chains emphasize resilience over efficiency and (ii) the acceleration of e-commerce adoption.
As service time increasingly moves to the forefront of the global supply chain, it drives demand for logistics real estate close to the end\-consumer.
As we look to the future of logistics real estate, we are focused on solving our customers’ pain points, innovating in pursuit of creative solutions and operational excellence.
We are listening and responding to our customers’ needs for skilled labor through initiatives to create community workforce programs to develop their talent pool, utilize our proprietary data and analytics to ensure efficient distribution solutions and negotiate better pricing on common products and services that our customers need.
Our customers turn to us because they know that a strategic partnership with Prologis is a competitive advantage.
We accomplish all of this by employing individuals who continue to grow, embrace change and draw strength from inclusion and diversity.
2020 Significant Events
On January 8, 2020, our two U.S. co-investment ventures, Prologis U.S. Logistics Venture, LLC (“USLV”) and Prologis Targeted U.S. Logistics Fund (“USLF”), acquired the wholly-owned real estate assets of Industrial Property Trust Inc. (“IPT”) for approximately $2.0 billion each, which we refer to as the “IPT Transaction” and is detailed in Notes 4, 5, 8 and 11 to the Consolidated Financial Statements.
The portfolio included 235 properties, aggregating 37 million square feet and were highly complementary to our U.S. portfolio in terms of product quality, location and growth potential.
Our aggregate investment in the IPT Transaction was $1.6 billion.
On February 4, 2020, we acquired Liberty Property Trust and Liberty Property Limited Partnership (collectively “Liberty”) through a merger transaction that we refer to as the “Liberty Transaction” and is detailed in Note 3 to the Consolidated Financial Statements.
The Liberty portfolio was primarily comprised of logistics real estate assets, including 519 operating properties, aggregating 100 million square feet and were highly complementary to our U.S. portfolio in terms of product quality, location and growth potential.
The portfolio also included properties under development, land for future development and office properties.
The acquisition expanded our presence in target markets such as Lehigh Valley, Chicago, Houston, Central Pennsylvania, New Jersey and Southern California.
The total acquisition price, including transaction costs, was approximately $13 billion and was funded through the issuance of equity and the assumption of debt.
As a result of the closely aligned portfolios and similar business strategy, we integrated the IPT and Liberty properties while adding minimal property management and general and administrative expenses, further scaling our operations.
On a combined basis, there were 42 million square feet of non-strategic industrial properties with a gross book value of approximately $3 billion acquired in both the Liberty Transaction and the IPT Transaction that we do not intend to operate long-term.
Depending on the expected hold period, these assets were either classified as *Assets Held for Sale or Contribution* or other real estate investments within *Investments in Real Estate Properties* at the time of acquisition in the Consolidated Balance Sheets.
Since acquisition some of these non-strategic industrial properties have been sold.
In early 2020, COVID-19 was characterized as a global pandemic by the World Health Organization.
The COVID-19 outbreak has disrupted financial markets and global, national and local economies since this time.
Our operating results have remained strong in the COVID-19 environment and our business has been resilient.
We expect operating conditions in our portfolio to continue to strengthen in 2021.
However, with the continued uncertainty across the globe, we cannot predict the impact on our business, future financial condition or operating results.
For discussion on current operating results and our operational and financial outlook, as well as our response to help protect employees and customers, see the Summary of 2020 section in Item 7.
Management’s Discussion and Analysis of Financial Condition and Results of Operations.
We develop properties to meet these needs, deepen our market presence and maintain a modern portfolio.
In addition to our land portfolio, we have also made investments in other properties that have the potential to be redeveloped to increase value.
Most of the strategic capital revenues are generated outside the U.S. NOI in this segment is calculated directly from our Consolidated Financial Statements as *Strategic Capital Revenues* less *Strategic Capital Expenses* and excludes property-related NOI.
| • | Value Creation from Development. A successful development and redevelopment program involves maintaining control of well-located and entitled land and redevelopment sites. We believe that the carrying value of our land bank is below its current fair value. Due to the strategic nature of our land bank, development expertise of our teams and strength of our customer relationships, we expect to create value as we build new properties. We measure the estimated value creation of a development project as the margin above our anticipated cost to develop. As properties under development stabilize, we expect to realize the value creation principally through contributions to the unconsolidated co-investment ventures and increases in the NOI of our operating portfolio. |
| • | Balance Sheet Strength. Through the acquisitions of Liberty and IPT and execution of several opportunistic debt refinancings at historically low rates, we further enhanced our financial position during 2020 while maintaining low leverage. At December 31, 2020, we had total available liquidity of $4.8 billion. As a result of our low leverage and available liquidity, we have significant capacity to capitalize on value-added investment opportunities that will translate into future earnings growth. |
| • | Staying “Ahead of What’s Next™”. We are working on initiatives to create value beyond the real estate by enhancing our customers’ experience, utilizing our scale to streamline our procurement activities and negotiating better pricing on products and services for us and our customers, as well as delivering improvements to our business through innovation, data analytics and |
| | digitization efforts. Underlying our future strategy for growth is our ongoing commitment to, and initiatives in, environmental stewardship, social responsibility and governance (“ESG”). |
| • | established relationships with customers served by our experienced and responsive local and regional teams; |
| • | proven property management and leasing expertise; |
| • | a strategically located land bank and redevelopment sites; |
| • | local teams with development expertise; and |
In order to provide for a customer-centric location strategy, we have invested in properties located within infill and urban areas in our largest global markets with same day and next day access to the consumer population, these are our Last Touch® and city distribution facilities, respectively.
| --- | --- | --- | --- | --- | --- | --- | --- |
An excerpt. Shown here: 40 of 66 rewritten, 40 of 83 added and 40 of 74 removed. The counts are complete. For every sentence, read Item 1. Business in the FY2021 filing and the FY2020 filing.
Cover and table of contents
49 rewritten, 4 added, 2 removed, 106 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
For the fiscal year ended December 31, [removed: 2020][added: 2021]
[removed: ][added: ]
[removed: (Registrant’s] [added: (Registrants’] telephone number, including area code)
Based on the closing price of Prologis, Inc.’s common stock on June 30, [removed: 2020,] [added: 2021,] the aggregate market value of the voting common equity held by nonaffiliates of Prologis, Inc. was [removed: $68,586,769,164.][added: $87,997,816,686.]
The number of shares of Prologis, Inc.’s common stock outstanding at February [removed: 5, 2021,] [added: 7, 2022,] was approximately [removed: 739,500,000.][added: 740,000,000.]
This report combines the annual reports on Form 10-K for the year ended December 31, [removed: 2020,] [added: 2021,] of Prologis, Inc. and Prologis, L.P. Unless stated otherwise or the context otherwise requires, references to “Prologis, Inc.” or the “Parent” mean Prologis, Inc. and its consolidated subsidiaries; and references to “Prologis, L.P.” or the “Operating Partnership” or the “OP” mean Prologis, L.P., and its consolidated subsidiaries.
At December 31, [removed: 2020,] [added: 2021,] the Parent owned [removed: 97.35%] [added: 97.32%] common general partnership interest in the OP and [removed: 100%] [added: substantially all] of the preferred units in the OP.
The remaining [removed: 2.65%] [added: 2.68%] common limited partnership interests are owned by unaffiliated investors and certain current and former directors and officers of the Parent.
| | | [Code of Ethics and Business Conduct](#CODE_ETHICS) | | [removed: 9] [added: 11] |
| | | [Environmental Stewardship, Social Responsibility and Governance](#ESG) | | [removed: 9] [added: 11] |
| | | [Environmental Matters](#ENVIRON2) | | [removed: 10] [added: 12] |
| | | [Governmental Matters](#GovMatters) | | [removed: 10] [added: 12] |
| | | [Insurance Coverage](#INSURANCE) | | [removed: 10] [added: 12] |
| 1A. | | [Risk Factors](#ITEM_1A_RISK_FACTORS) | | [removed: 10] [added: 12] |
| 1B. | | [Unresolved Staff Comments](#ITEM_1B_UNRESOLVED_STAFF_COMMENTS) | | [removed: 19] [added: 21] |
| 2. | | [Properties](#ITEM_2_PROPERTIES) | | [removed: 19] [added: 21] |
| | | [Geographic Distribution](#GEOGRAPHIC) | | [removed: 19] [added: 21] |
| | | [Lease Expirations](#LEASEEX) | | [removed: 22] [added: 24] |
| | | [Co-Investment Ventures](#COINVT) | | [removed: 23] [added: 25] |
| 3. | | [Legal Proceedings](#ITEM_3_LEGAL_PROCEEDINGS) | | [removed: 23] [added: 25] |
| 4. | | [Mine Safety Disclosures](#ITEM_4_MINE_SAFETY_DISCLOSURES) | | [removed: 23] [added: 25] |
| 5. | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities](#ITEM_5_MARKET_FOR_REGISTRANTS_COMMON_EQU) | | [removed: 23] [added: 25] |
| | | [Market Information and Holders](#MKTINFO) | | [removed: 23] [added: 25] |
| | | [Preferred Stock Dividends](#PREFERRED) | | [removed: 24] [added: 26] |
| | | [removed: [Sale] [added: [Sales] of Unregistered Securities](#SALESUNREGISTER) | | [removed: 24] [added: 26] |
| | | [Purchases of Equity [removed: Securities](#PURUNREGISTER)] [added: Securities](#PURCHASESOFEQUITYSECURITIES)] | | [removed: 25] [added: 27] |
| | | [Securities Authorized for Issuance Under Equity Compensation [removed: Plans](#SECURITIESAUTHO)] [added: Plans](#SECURITIESAUTHORI)] | | [removed: 25] [added: 27] |
| | | [Other Stockholder Matters](#OTHERSTOCK) | | [removed: 25] [added: 27] |
| 7. | | [Management’s Discussion and Analysis of Financial Condition and Results of Operations](#ITEM_7_MANAGEMENTS_DISCUSSION_ANALYSIS_F) | | [removed: 25] [added: 27] |
| | | [Management’s Overview](#MGTOVER) | | [removed: 26] [added: 27] |
| | | [Results of Operations](#RESULTS) | | [removed: 27] [added: 28] |
| | | [Environmental Matters](#ENVIRO_MATTERS) | | [removed: 36] [added: 37] |
| | | [Liquidity and Capital Resources](#LIQANDCAP) | | [removed: 36] [added: 37] |
| | | [Critical Accounting Policies](#Critical) | | [removed: 40] [added: 41] |
| | | [New Accounting Pronouncements](#NewAccountingPro) | | [removed: 41] [added: 42] |
| | | [Funds from Operations Attributable to Common Stockholders/Unitholders](#FFO) | | [removed: 41] [added: 42] |
| 7A. | | [Quantitative and Qualitative Disclosures About Market Risk](#ITEM7AMKT) | | [removed: 43] [added: 44] |
| 8. | | [Financial Statements and Supplementary Data](#ITEM_8_FINANCIAL_STATEMENTS_SUPPLEMENTAR) | | [removed: 44] [added: 45] |
| 9. | | [Changes in and Disagreements with Accountants on Accounting and Financial Disclosure](#ITEM_9_CHANGES_IN_DISAGREEMENTS_WITH_ACC) | | [removed: 44] [added: 45] |
| 9A. | | [Controls and Procedures](#ITEM_9A_CONTROLS_PROCEDURES) | | [removed: 44] [added: 45] |
(Former name, former address and former fiscal year, if changed since last report)
Auditor Name: KPMG LLP Auditor Location: Denver, CO Auditor Firm ID: 185
| 6. | | [\[Reserved\]](#ITEM_6_RESERVED) | | 27 |
| 9C. | | [Disclosure Regarding Foreign Jurisdictions that Prevent Inspections](#ITEM_9C_FR_PREVENT_INSPECTIONS) | | 47 |
| Prologis, L.P. | | 3.375% Notes due 2024 | | PLD/24 | | New York Stock Exchange |
| 6. | | [Selected Financial Data](#ITEM_6_SELECTED_FINANCIAL_DATA) | | 25 |
An excerpt. Shown here: 40 of 49 rewritten, all 4 added and all 2 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2021 filing and the FY2020 filing.
Item 2. Properties
45 rewritten, 66 added, 64 removed, 61 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
[removed: The O&M portfolio includes the properties we consolidate and the properties owned by our unconsolidated co-investment] [added: investment] ventures reflected at 100% of the amount included in the ventures’ financial statements as calculated on a GAAP basis, not our proportionate share.
Included in the operating property information below for our consolidated operating properties are [removed: 482] [added: 497] buildings owned primarily by one co-investment venture that we consolidate but of which we own less than 100% of the equity.
No individual property or market amounted to 10% or more of our consolidated total assets at December 31, [removed: 2020,] [added: 2021,] or generated revenue equal to 10% or more of our consolidated total revenues for the year ended December 31, [removed: 2020,] [added: 2021,] with the exception of the Southern California market.
| Baltimore/Washington D.C. | | | [removed: 10] [added: 41] | | | [added: *] | [removed: 1,210] | | | | [removed: 12] [added: 18] | | | [added: *] | [removed: 14] | | | | [removed: 1,603] [added: 13] | |
| Dallas/Ft. Worth | | | [removed: 31] [added: 32] | | | | [removed: 2,205] [added: 2,281] | | | | 8 | | | | [removed: 38] [added: 39] | | | | [removed: 2,732] [added: 2,872] | |
| New Jersey/New York City | | | [removed: 32] [added: 18] | | | | [removed: 3,798] [added: 1] | | | | [removed: 45] [added: 56] | | | [added: *] | [removed: 41] | | | | [removed: 5,059] [added: 124] | |
| San Francisco Bay Area | | | [removed: 21] [added: \-] | | | | [removed: 2,909] [added: \-] | | | | [removed: 9] [added: \-] | | | [added: *] | [removed: 26] | | | | [removed: 3,562] [added: 42] | |
| Germany | | [removed: *] | [added: 26] | | | | [removed: 18] [added: 1] | | | | [removed: \-] [added: 12] | | | | [removed: 25] [added: 1] | | | | [removed: 2,397] [added: 96] | |
| Remaining Countries – Europe (8 countries) [removed: (3)] | | | [removed: 3] [added: 780] | | | | [removed: 178] [added: 16] | | | | [removed: \-] [added: 158] | | | | [removed: 82] [added: 2] | | | | [removed: 6,675] [added: 178] | |
| Value-added properties (5) | | | [removed: 5] [added: 3] | | | | [removed: 594] [added: 626] | | | | \- | | | | [removed: 9] [added: 5] | | | | [removed: 983] [added: 968] | |
| Baltimore/Washington D.C. | | | [removed: 41] [added: 11] | | | | [removed: 1] [added: 1,269] | | | | [removed: 16] [added: 12] | | | | [removed: 1] [added: 15] | | | | [removed: 120] [added: 1,667] | |
| Central PA | | | 29 | | | [added: *] | [removed: 1] | | | | 8 | | | | \- | | | | \- | |
| Dallas/Ft. Worth | | | [removed: 108] [added: 351] | | | | [removed: 2] [added: 5] | | | | [removed: 25] [added: 140] | | | | [removed: 1] [added: 2] | | | | [removed: 98] [added: 173] | |
| Lehigh Valley | | | 208 | | | | 2 | | | | [removed: 82] [added: 77] | | | | [removed: 2] [added: 1] | | | | [removed: 197] [added: 101] | |
| New Jersey/New York City | | | [removed: 26] [added: 33] | | | | [removed: 1] [added: 3,869] | | | | [removed: 34] [added: 44] | | | | [removed: 1] [added: 41] | | | | [removed: 16] [added: 5,144] | |
| San Francisco Bay Area | | | [removed: \-] [added: 20] | | | | [removed: \-] [added: 2,951] | | | | [removed: \-] [added: 9] | | | [removed: *] | [added: 25] | | | | [removed: 96] [added: 3,611] | |
| Germany | | | [removed: 66] [added: 1] | | | | [removed: 2] [added: 78] | | | [added: \-] | [removed: 39] | | | [removed: *] | [added: 26] | | | | [removed: 76] [added: 2,387] | |
| Netherlands | | [added: *] | [removed: 31] | | | | [removed: 1] [added: 12] | | | [added: \-] | [removed: 15] | | | | [removed: 1] [added: 24] | | | | [removed: 98] [added: 2,261] | |
| Subtotal Asia | | | [removed: 76] [added: 74] | | | | [removed: 4] [added: 5] | | | | [removed: 119] [added: 92] | | | | 7 | | | | [removed: 1,320] [added: 1,127] | |
| Total land and development portfolio | | | [removed: 5,304] [added: 6,227] | | | | [removed: 94] [added: 108] | | | $ | [removed: 1,606] [added: 2,520] | | | | [removed: 28] [added: 35] | | | $ | [removed: 3,769] [added: 4,717] | |
| (1) | Certain of our consolidated properties are pledged as security under secured mortgage debt and assessment bonds. For purposes of this table, the total principal balance of a debt issuance that is secured by a pool of properties is allocated among the properties in the pool based on each property’s investment balance. In addition to the amounts reflected here, we also have [removed: $101] [added: $10] million of encumbrances related to one [removed: prestabilized property] [added: land parcel] included in the consolidated [removed: development] [added: land] portfolio. |
| (4) | Included in our consolidated operating properties are properties that we consider to be held for contribution and are presented within *Assets Held for Sale or Contribution* in the Consolidated Balance Sheets. We include these properties in our operating portfolio as they are expected to be contributed to our co-investment ventures and remain in our O&M operating portfolio. At December 31, [removed: 2020,] [added: 2021,] we had investments in real estate properties that were expected to be contributed to our unconsolidated co-investment ventures totaling [removed: $454] [added: $535] million and aggregating [removed: 5] [added: 4] million square feet. See Note 6 to the Consolidated Financial Statements in Item 8. Financial Statements and Supplementary Data for further information on our *Assets Held for Sale or Contribution.* |
| (7) | TEI is based on current projections and is subject to change. [removed: In the first quarter of 2020, we suspended several recently started speculative development projects for the short-term. Most of the suspended projects were restarted by the fourth quarter of 2020. At December 31, 2020, the outstanding suspended development projects had a TEI of $82 million and remain within our consolidated development portfolio.] As noted in the table below, our current investment in [removed: our active development portfolio, excluding suspended] [added: the] development [removed: projects,] [added: portfolio] was [removed: $1.9] [added: $2.7] billion, leaving approximately [removed: $1.8] [added: $2.0] billion of additional required investment. At December 31, [removed: 2020,] [added: 2021,] based on TEI, approximately [removed: 17%] [added: 18%] of the properties in the development portfolio were completed but not [added: yet stabilized, 71% of the properties were expected to be completed before December 31, 2022, and the remaining properties were expected to be completed before October 2023.] |
The following table summarizes our investment in consolidated real estate properties at December 31, [removed: 2020] [added: 2021] (in millions):
| Operating properties, excluding assets held for sale or contribution | | $ | [removed: 43,508] [added: 44,454] | |
| Development portfolio, including cost of land | | | [removed: 1,882] [added: 2,729] | |
| Other real estate investments (1) | | | [removed: 3,388] [added: 3,302] | |
| Total consolidated real estate properties | | $ | [removed: 50,384] [added: 53,005] | |
| (1) | Included in other real estate investments were: (i) non-strategic real estate assets acquired [removed: in the Liberty Transaction] that we do not intend to operate long-term; (ii) [removed: land parcels we own and lease to third parties; (iii)] real estate assets that we intend to redevelop into industrial properties; [added: (iii) land parcels we own] and [added: lease to third parties; and] (iv) costs associated with potential acquisitions and future development projects, including purchase options on land. |
We generally lease our properties on a long-term basis (the average term for leases commenced, including new leases and renewals, in [removed: 2020] [added: 2021] was [removed: 64] [added: 62] months).
The following table summarizes the lease expirations of our consolidated operating portfolio for leases in place at December 31, [removed: 2020] [added: 2021] (dollars and square feet in millions):
| | | Number of Leases | | | | Occupied Square Feet | | | | Dollars | | | | % of Total | | | | Dollars Per Square Foot [removed: (1)] | | |
| Month to month | | | [removed: 121] [added: 93] | | | | [removed: 4] [added: 3] | | | | | | | | | | | | | |
Included in our O&M portfolio are consolidated and unconsolidated co-investment ventures that hold investments in real estate properties, primarily logistics [removed: facilities] [added: facilities,] that we also manage.
The following table summarizes our consolidated and unconsolidated co-investment ventures at December 31, [removed: 2020] [added: 2021] (in millions):
| Prologis U.S. Logistics Venture (“USLV”) | | | [removed: 78] [added: 77] | | | $ | [removed: 7,772] [added: 7,927] | | | $ | 12 | | | $ | [removed: 21] [added: 6] | |
| Prologis Targeted U.S. Logistics Fund (“USLF”) | | | [removed: 117] [added: 122] | | | $ | [removed: 10,987] [added: 12,199] | | | $ | [removed: 43] [added: \-] | | | $ | [removed: 37] [added: 288] | |
| FIBRA Prologis | | | [removed: 40] [added: 43] | | | | [removed: 2,549] [added: 2,763] | | | | [removed: 6] [added: \-] | | | | [removed: 6] [added: 27] | |
| Prologis Brazil Logistics Venture ("PBLV") and other joint ventures | | | [removed: 11] [added: 13] | | | | [removed: 507] [added: 641] | | | | [removed: 47] [added: 46] | | | | [removed: 188] [added: 185] | |
| Subtotal Other Americas | | | [removed: 51] [added: 56] | | | | [removed: 3,056] [added: 3,404] | | | | [removed: 53] [added: 46] | | | | [removed: 194] [added: 212] | |
The O&M portfolio includes the properties we consolidate and the properties owned by our unconsolidated co-
| Atlanta | | | 25 | | | $ | 1,629 | | | $ | 13 | | | | 31 | | | $ | 2,084 | |
| Central PA | | | 15 | | | | 1,308 | | | | \- | | | | 17 | | | | 1,428 | |
| Central Valley | | | 17 | | | | 1,326 | | | | 9 | | | | 19 | | | | 1,461 | |
| Chicago | | | 39 | | | | 3,248 | | | | 8 | | | | 55 | | | | 4,724 | |
| Houston | | | 24 | | | | 2,518 | | | | 4 | | | | 31 | | | | 3,034 | |
| Lehigh Valley | | | 25 | | | | 3,107 | | | | \- | | | | 28 | | | | 3,386 | |
| Orlando | | | 10 | | | | 1,022 | | | | 70 | | | | 11 | | | | 1,120 | |
| Seattle | | | 14 | | | | 2,066 | | | | \- | | | | 22 | | | | 2,932 | |
| South Florida | | | 12 | | | | 1,614 | | | | 28 | | | | 19 | | | | 2,471 | |
| Southern California | | | 77 | | | | 9,181 | | | | 14 | | | | 97 | | | | 11,515 | |
| Remaining Markets – U.S. (15 markets) (2) | | | 76 | | | | 5,500 | | | | 38 | | | | 102 | | | | 7,485 | |
| Subtotal U.S. | | | 430 | | | | 42,889 | | | | 257 | | | | 552 | | | | 54,934 | |
| Brazil | | \- | | | | \- | | | | \- | | | | | 13 | | | | 641 | |
| Canada | | | 10 | | | | 833 | | | | 150 | | | | 10 | | | | 833 | |
| Mexico | | * | | | | | 28 | | | \- | | | | | 43 | | | | 2,765 | |
| Subtotal Other Americas | | | 10 | | | | 861 | | | | 150 | | | | 66 | | | | 4,239 | |
| France | | | 1 | | | | 93 | | | \- | | | | | 33 | | | | 2,913 | |
| U.K. | | * | | | | | 69 | | | \- | | | | | 28 | | | | 5,351 | |
| Remaining Countries – Europe (8 countries) (3) | | | 2 | | | | 117 | | | \- | | | | | 90 | | | | 7,064 | |
| Subtotal Europe | | | 4 | | | | 369 | | | | \- | | | | 201 | | | | 19,976 | |
| China | | \- | | | | \- | | | | \- | | | | | 42 | | | | 3,098 | |
| Japan | | * | | | | | 26 | | | \- | | | | | 40 | | | | 7,201 | |
| Singapore | | | 1 | | | | 141 | | | \- | | | | | 1 | | | | 141 | |
| Subtotal Asia | | | 1 | | | | 167 | | | | \- | | | | 83 | | | | 10,440 | |
| Total operating portfolio (4) | | | 445 | | | | 44,286 | | | | 407 | | | | 902 | | | | 89,589 | |
| Total operating properties | | | 448 | | | $ | 44,912 | | | $ | 407 | | | | 907 | | | $ | 90,557 | |
| Atlanta | | | 221 | | | | 3 | | | $ | 34 | | | | 3 | | | $ | 191 | |
| Central Valley | | | 770 | | | | 14 | | | | 158 | | | | 2 | | | | 272 | |
| Chicago | | | 134 | | | | 2 | | | | 43 | | | | 2 | | | | 292 | |
| Houston | | | 163 | | | | 2 | | | | 39 | | | * | | | | | 99 | |
| Orlando | | | 100 | | | | 1 | | | | 27 | | | | 1 | | | | 106 | |
| Seattle | | | 158 | | | | 2 | | | | 116 | | | * | | | | | 77 | |
| South Florida | | | 150 | | | | 2 | | | | 134 | | | | 1 | | | | 154 | |
| Southern California | | | 536 | | | | 10 | | | | 400 | | | | 3 | | | | 468 | |
| Remaining Markets – U.S. (15 markets) | | | 814 | | | | 12 | | | | 281 | | | | 4 | | | | 368 | |
| Subtotal U.S. | | | 3,693 | | | | 56 | | | | 1,531 | | | | 19 | | | | 2,480 | |
| Brazil | | | 263 | | | | 5 | | | | 52 | | | | \- | | | | \- | |
| Canada | | | 167 | | | | 3 | | | | 125 | | | | 1 | | | | 54 | |
| Mexico | | | 681 | | | | 12 | | | | 94 | | | | 1 | | | | 103 | |
| Atlanta | | | 24 | | | $ | 1,549 | | | $ | 14 | | | | 30 | | | $ | 1,996 | |
| Central PA | | | 16 | | | | 1,309 | | | | \- | | | | 17 | | | | 1,403 | |
| Central Valley | | | 17 | | | | 1,306 | | | | 10 | | | | 19 | | | | 1,440 | |
| Chicago | | | 39 | | | | 3,201 | | | | 9 | | | | 52 | | | | 4,359 | |
| Houston | | | 24 | | | | 2,454 | | | | 5 | | | | 30 | | | | 2,963 | |
| Lehigh Valley | | | 24 | | | | 2,951 | | | | \- | | | | 27 | | | | 3,228 | |
| Seattle | | | 13 | | | | 2,016 | | | | \- | | | | 22 | | | | 2,873 | |
| South Florida | | | 13 | | | | 1,677 | | | | 29 | | | | 18 | | | | 2,220 | |
| Southern California | | | 78 | | | | 9,151 | | | | 16 | | | | 97 | | | | 11,227 | |
| Remaining Markets – U.S. (15 markets) (2) | | | 80 | | | | 5,728 | | | | 39 | | | | 107 | | | | 7,630 | |
| Subtotal U.S. | | | 422 | | | | 41,464 | | | | 196 | | | | 538 | | | | 52,295 | |
| Brazil | | | \- | | | | \- | | | | \- | | | | 10 | | | | 506 | |
| Canada | | | 10 | | | | 882 | | | | 153 | | | | 10 | | | | 882 | |
| Mexico | | | 1 | | | | 53 | | | | \- | | | | 41 | | | | 2,597 | |
| Subtotal Other Americas | | | 11 | | | | 935 | | | | 153 | | | | 61 | | | | 3,985 | |
| France | | | 1 | | | | 92 | | | | \- | | | | 32 | | | | 2,861 | |
| Netherlands | | * | | | | | 19 | | | | \- | | | | 23 | | | | 2,314 | |
| U.K. | | | 1 | | | | 103 | | | | \- | | | | 26 | | | | 4,031 | |
| Subtotal Europe | | | 5 | | | | 410 | | | | \- | | | | 188 | | | | 18,278 | |
| China | | | \- | | | | \- | | | | \- | | | | 32 | | | | 2,504 | |
| Japan | | | 2 | | | | 348 | | | | 199 | | | | 37 | | | | 7,179 | |
| Singapore | | | 1 | | | | 144 | | | | \- | | | | 1 | | | | 144 | |
| Subtotal Asia | | | 3 | | | | 492 | | | | 199 | | | | 70 | | | | 9,827 | |
| Total operating portfolio (4) | | | 441 | | | | 43,301 | | | | 548 | | | | 857 | | | | 84,385 | |
| Total operating properties | | | 446 | | | $ | 43,895 | | | $ | 548 | | | | 866 | | | $ | 85,368 | |
| Atlanta | | | 344 | | | | 3 | | | $ | 34 | | | * | | | | $ | 17 | |
| Central Valley | | | 934 | | | | 16 | | | | 185 | | | | 1 | | | | 80 | |
| Chicago | | | 182 | | | | 3 | | | | 64 | | | | 1 | | | | 36 | |
| Houston | | | 197 | | | | 3 | | | | 44 | | | * | | | | | 13 | |
| Seattle | | | 41 | | | | 1 | | | | 67 | | | * | | | | | 62 | |
| South Florida | | | 183 | | | | 3 | | | | 148 | | | * | | | | | 24 | |
| Southern California | | | 116 | | | | 2 | | | | 108 | | | * | | | | | 62 | |
| Remaining Markets – U.S. (15 markets) | | | 620 | | | | 9 | | | | 106 | | | | 6 | | | | 633 | |
| Subtotal U.S. | | | 3,029 | | | | 47 | | | | 921 | | | | 13 | | | | 1,454 | |
| Brazil | | | 196 | | | | 4 | | | | 16 | | | | \- | | | | \- | |
| Canada | | | 162 | | | | 3 | | | | 89 | | | * | | | | | 72 | |
| Mexico | | | 414 | | | | 7 | | | | 76 | | | | 1 | | | | 44 | |
| Subtotal Other Americas | | | 772 | | | | 14 | | | | 181 | | | | 1 | | | | 116 | |
| France | | | 263 | | | | 5 | | | | 28 | | | | 1 | | | | 126 | |
| U.K. | | | 198 | | | | 4 | | | | 120 | | | | 2 | | | | 328 | |
An excerpt. Shown here: 40 of 45 rewritten, 40 of 66 added and 40 of 64 removed. The counts are complete. For every sentence, read Item 2. Properties in the FY2021 filing and the FY2020 filing.
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
6 rewritten, 2 added, 27 removed, 15 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
The following line graph compares the change in Prologis, Inc. cumulative total stockholder’s return on shares of its common stock from December 31, [removed: 2015,] [added: 2016,] to the cumulative total return of the S&P 500 Stock Index and the Financial Times and Stock Exchange NAREIT Equity REITs Index from December 31, [removed: 2015,] [added: 2016,] to December 31, [removed: 2020.][added: 2021.]
The graph assumes an initial investment of $100 in our common [added: stock and each of the indices on December 31, 2016, and, as required by the SEC, the reinvestment of all dividends.]
[removed: 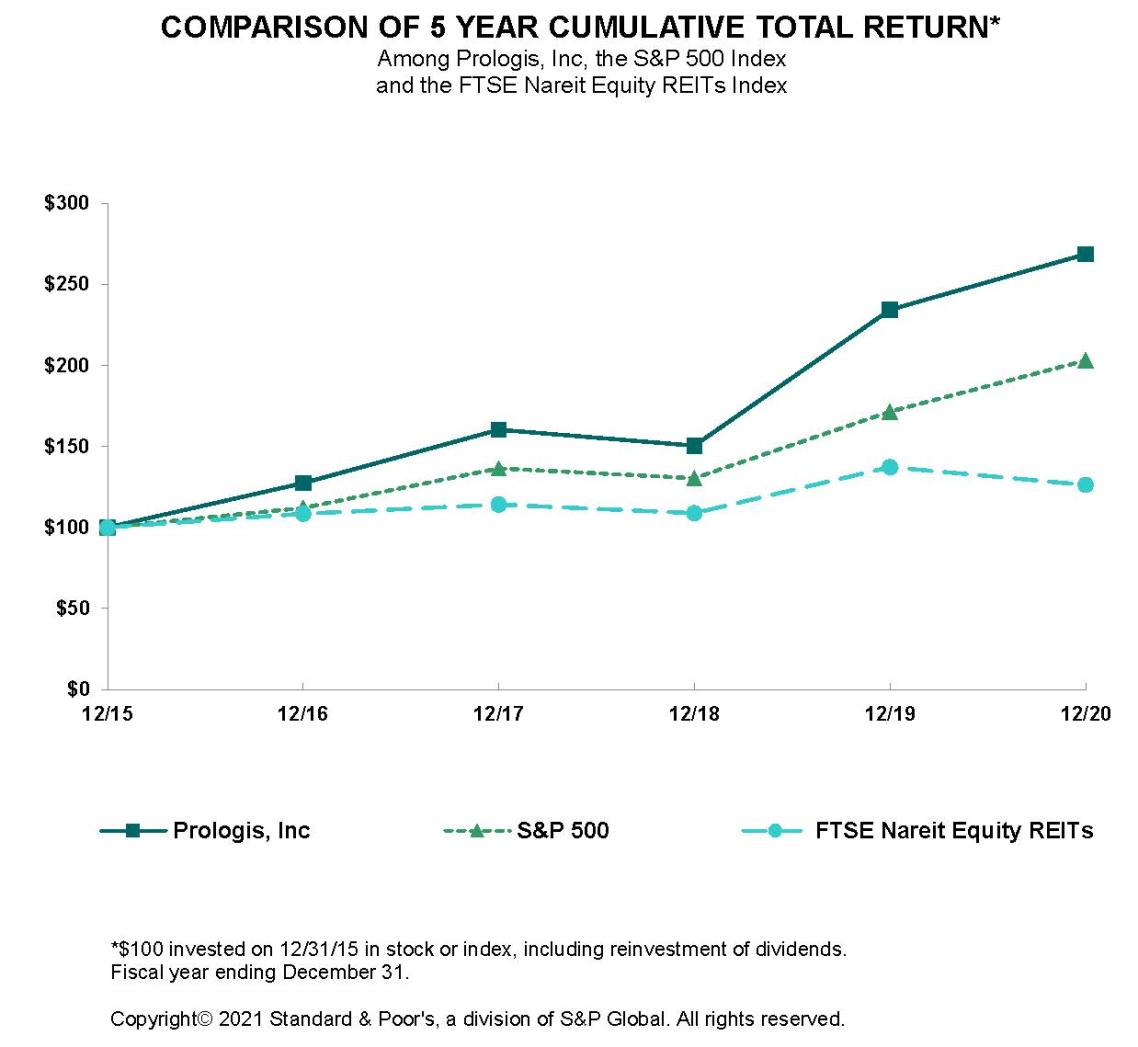][added: 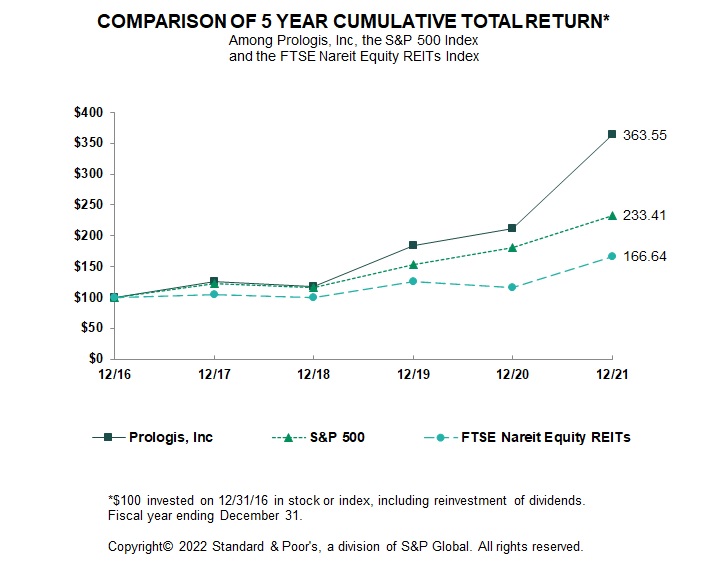]
At December 31, [removed: 2020 and 2019,] [added: 2021,] we had 1.3 million [removed: and 1.4 million] shares of the Series Q preferred [removed: stock, respectively,] [added: stock] with a liquidation preference of $50 per share that will be redeemable at our option on or after November 13, 2026.
Dividends payable per share [removed: were] [added: was] $4.27 for the [removed: years] [added: year] ended December 31, [removed: 2020 and 2019.][added: 2021.]
Further information relative to our equity compensation plans will be provided in our [removed: 2021] [added: 2022] Proxy Statement or in an amendment filed on Form 10-K/A.
During 2021, we issued 0.8 million shares of common stock of Prologis, Inc. in connection with the redemption of common units of Prologis, L.P. and issued 1.0 million common units in Prologis, L.P. in connection with the acquisition of additional ownership interest in an unconsolidated other venture from our partner in reliance on the exemption from registration requirements of the Securities Act of 1933, as amended, afforded by Section 4(a)(2) thereof.
During 2021, we did not purchase any common stock of Prologis, Inc. in connection with our share purchase program.
stock and each of the indices on December 31, 2015, and, as required by the SEC, the reinvestment of all dividends.
During 2020, we issued 0.7 million shares of common stock of Prologis, Inc. in connection with the redemption of common units of Prologis, L.P. and 0.5 million common units of Prologis, L.P. in connection with the acquisition of properties (see Note 11 to the Consolidated Financial Statements in Item 8.
Financial Statements and Supplementary Data) in reliance on the exemption from registration requirements of the Securities Act of 1933, as amended, afforded by Section 4(a)(2) thereof.
The table below sets forth the information with respect to purchases by Prologis, Inc. of its common stock during the year ended December 31, 2020:
| Period | Total Number of Shares Purchased (1) | | | | Average Price Paid per Share (2) | | | | Total Number of Shares Purchased as Part of Publicly Announced Plan (3) | | | | Approximate Dollar Value of Shares that May Yet Be Purchased Under the Plan (in millions) (4) | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| January 1 – January 31 | | \- | | | $ | \- | | | | \- | | | $ | \- | |
| February 1 – February 29 | | \- | | | | \- | | | | \- | | | | \- | |
| March 1 – March 31 | | 539,000 | | | | 64.66 | | | | 539,000 | | | | 965 | |
| April 1 – April 30 | | \- | | | | \- | | | | \- | | | | \- | |
| May 1 – May 31 | | \- | | | | \- | | | | \- | | | | \- | |
| June 1 – June 30 | | \- | | | | \- | | | | \- | | | | \- | |
| July 1 – July 31 | | \- | | | | \- | | | | \- | | | | \- | |
| August 1 – August 31 | | \- | | | | \- | | | | \- | | | | \- | |
| September 1 – September 30 | | \- | | | | \- | | | | \- | | | | \- | |
| October 1 – October 31 | | \- | | | | \- | | | | \- | | | | \- | |
| November 1 – November 30 | | \- | | | | \- | | | | \- | | | | \- | |
| December 1 – December 31 | | \- | | | | \- | | | | \- | | | | \- | |
| Total | | 539,000 | | | $ | 64.66 | | | | 539,000 | | | $ | 965 | |
| (1) | In March 2020, the Board of Directors authorized a new share purchase program to repurchase up to $1.0 billion of common stock on the open market or in privately negotiated transactions. This column primarily represents open market share repurchases. |
| --- | --- |
| (2) | Average price paid per share is a weighted average calculation using the aggregate price, excluding commissions and fees. |
| --- | --- |
| (3) | The aggregate value of shares purchased in the year ended December 31, 2020 as part of the publicly announced plan was $35 million. |
| --- | --- |
| (4) | As of February 5, 2021, $965 million in share repurchase authorization remained. There is no scheduled expiration date for the program, but the program may be discontinued at any time. |
| --- | --- |
Item 6. [Reserved]
0 rewritten, 0 added, 1 removed, 0 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
None.
Item 8. Financial Statements and Supplementary Data
1 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
The Consolidated Balance Sheets of Prologis, Inc. and Prologis, L.P. at December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] the Consolidated Statements of Income of Prologis, Inc. and Prologis, L.P., the Consolidated Statements of Comprehensive Income of Prologis, Inc. and Prologis, L.P., the Consolidated Statements of Equity of Prologis, Inc., the Consolidated Statements of Capital of Prologis, L.P. and the Consolidated Statements of Cash Flows of Prologis, Inc. and Prologis, L.P. for each of the years in the three-year period ended December 31, [removed: 2020,] [added: 2021,] Notes to Consolidated Financial Statements and Schedule III — Real Estate and Accumulated Depreciation, together with the reports of KPMG LLP, independent registered public accounting firm, are included under Item 15 of this report and are incorporated herein by reference.
Item 9A. Controls and Procedures
13 rewritten, 0 added, 2 removed, 18 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
Prologis, Inc. carried out an evaluation under the supervision and with the participation of management, including the Chief Executive Officer and Chief Financial Officer, of the effectiveness of the disclosure controls and procedures (as defined in Rule 13a-15(e) under the Securities and Exchange Act of 1934 (the “Exchange Act”)) at December 31, [removed: 2020.][added: 2021.]
[added: Based on this evaluation, the Chief Executive] Officer and the Chief Financial Officer have concluded that the disclosure controls and procedures are effective to ensure that information required to be disclosed by us in reports that we file or submit under the Exchange Act is recorded, processed, summarized and reported within the time periods specified in the SEC rules and forms.
Subsequent to December 31, [removed: 2020,] [added: 2021,] there were no significant changes in the internal controls or in other factors that could significantly affect these controls, including any corrective actions with regard to significant deficiencies and material weaknesses.
There [removed: has] [added: have not] been [removed: no change] [added: any changes] in [removed: our] [added: Prologis, Inc.’s] internal control over financial reporting (as [removed: such term is] defined in Rules 13a-15(f) and 15(d)-15(f) under the Exchange Act) that occurred during the quarter ended December 31, [removed: 2020,] [added: 2021,] that [removed: has] [added: have] materially affected, or [removed: is] [added: are] reasonably likely to materially affect, [removed: our] [added: Prologis, Inc.’s] internal control over financial reporting.
Under the supervision and with the participation of management, including the Chief Executive Officer and Chief Financial Officer, an evaluation of the effectiveness of the internal control over financial reporting was conducted at December 31, [removed: 2020,] [added: 2021,] based on the criteria described in “Internal Control — Integrated Framework” (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
Based on this assessment, management determined that, at December 31, [removed: 2020,] [added: 2021,] the internal control over financial reporting was effective.
Our internal control over financial reporting at December 31, [removed: 2020,] [added: 2021,] has been audited by KPMG LLP, an independent registered public accounting firm, as stated in their attestation report, which is included herein.
Prologis, L.P. carried out an evaluation under the supervision and with the participation of management, including the Chief Executive Officer and Chief Financial Officer, of the effectiveness of the disclosure controls and procedures (as defined in Rule 13a-15(e) under the Exchange Act) at December 31, [removed: 2020.][added: 2021.]
Subsequent to December 31, [removed: 2020,] [added: 2021,] there were no significant changes in the internal controls or in other factors that could significantly affect these controls, including any corrective actions with regard to significant deficiencies and material weaknesses.
There [removed: has] [added: have not] been [removed: no change] [added: any changes] in [removed: our] [added: Prologis, L.P.’s] internal control over financial reporting (as [removed: such term is] defined in Rules 13a-15(f) and 15(d)-15(f) under the Exchange Act) that occurred during the quarter ended December 31, [removed: 2020,] [added: 2021,] that [removed: has] [added: have] materially affected, or [removed: is] [added: are] reasonably likely to materially affect, [removed: our] [added: Prologis, L.P.’s] internal control over financial reporting.
Under the supervision and with the participation of management, including the Chief Executive Officer and Chief Financial Officer, an evaluation of the effectiveness of the internal control over financial reporting was conducted at December 31, [removed: 2020,] [added: 2021,] based on the criteria described in “Internal Control — Integrated Framework” (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
Based on this assessment, management determined that, at December 31, [removed: 2020,] [added: 2021,] the internal control over financial reporting was effective.
[added: The internal control over financial reporting is a process] designed to provide reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with GAAP.
Based on this evaluation, the Chief Executive
The internal control over financial reporting is a process
Item 9B. Other Information
0 rewritten, 0 added, 1 removed, 1 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
PART III
Item 9C. Disclosure Regarding Foreign Jurisdictions that Prevent Inspections
0 rewritten, 2 added, 0 removed, 0 unchanged
New section this year
Read the full itemFY2021 item · filed February 9, 2022
Not Applicable.
PART III
Item 10. Directors, Executive Officers and Corporate Governance
1 rewritten, 0 added, 0 removed, 0 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
The information required by this item is incorporated herein by reference to, including relevant sections in our [removed: 2021] [added: 2022] Proxy Statement, under the captions entitled Board of Directors and Corporate Governance; Executive Officers; Executive Compensation; Director Compensation; Security Ownership; Equity Compensation Plans and Additional Information or will be provided in an amendment filed on Form 10-K/A.
Item 11. Executive Compensation
1 rewritten, 0 added, 0 removed, 0 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
The information required by this item is incorporated herein by reference to the relevant sections in our [removed: 2021] [added: 2022] Proxy Statement, under the captions entitled Board of Directors and Corporate Governance; Executive Officers; Executive Compensation and Director Compensation or will be provided in an amendment filed on Form 10-K/A.
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
1 rewritten, 0 added, 0 removed, 0 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
The information required by this item is incorporated herein by reference to the relevant sections in our [removed: 2021] [added: 2022] Proxy Statement, under the captions entitled Security Ownership and Equity Compensation Plans or will be provided in an amendment filed on Form 10-K/A.
Item 13. Certain Relationships and Related Transactions, and Director Independence
1 rewritten, 0 added, 0 removed, 0 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
The information required by this item is incorporated herein by reference to the relevant sections in our [removed: 2021] [added: 2022] Proxy Statement, under the caption entitled Board of Directors and Corporate Governance or will be provided in an amendment filed on Form 10-K/A.
Item 14. Principal Accounting Fees and Services
1 rewritten, 0 added, 0 removed, 1 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
The information required by this item is incorporated herein by reference to the relevant sections in our [removed: 2021] [added: 2022] Proxy Statement, under the caption entitled Audit Matters or will be provided in an amendment filed on Form 10-K/A.
Item 15. Exhibits, Financial Statements and Schedules
3 rewritten, 0 added, 0 removed, 8 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
See Index to the Consolidated Financial Statements and Schedule III on page [removed: 48] [added: 49] of this report, which is incorporated herein by reference.
(b) Exhibits: The Exhibits required by Item 601 of Regulation S-K are listed in the Index to the Exhibits on pages [removed: 103] [added: 102] to 112 of this report, which is incorporated herein by reference.
(c) Financial Statements: See Index to the Consolidated Financial Statements and Schedule III on page [removed: 48] [added: 49] of this report, which is incorporated by reference.
Item 16. Form 10-K Summary
918 rewritten, 331 added, 390 removed, 1,242 unchanged
Read the full itemFY2021 item · filed February 9, 2022FY2020 item · filed February 11, 2021
| [Reports of Independent Registered Public Accounting Firm](#Report_1) | [removed: 49] [added: 50] |
| [Consolidated Balance Sheets](#B_S_1) | [removed: 52] [added: 53] |
| [Consolidated Statements of Income](#S_O_1) | [removed: 53] [added: 54] |
| [Consolidated Statements of Comprehensive Income](#S_C_I_1) | [removed: 54] [added: 55] |
| [Consolidated Statements of Equity](#S_E_1) | [removed: 55] [added: 56] |
| [Consolidated Statements of Cash Flows](#S_C_F_1) | [removed: 56] [added: 57] |
| [Consolidated Balance Sheets](#B_S_2) | [removed: 57] [added: 58] |
| [Consolidated Statements of Income](#S_O_2) | [removed: 58] [added: 59] |
| [Consolidated Statements of Comprehensive Income](#S_C_I_2) | [removed: 59] [added: 60] |
| [Consolidated Statements of Capital](#S_C_2) | [removed: 60] [added: 61] |
| [Consolidated Statements of Cash Flows](#S_C_F_2) | [removed: 61] [added: 62] |
| [Notes to the Consolidated Financial Statements](#NOTES_TO_CONSOLIDATED_FINANCIAL_STATEMEN) | [removed: 62] [added: 63] |
| [Note 1. Description of the Business](#NoteOne) | [removed: 62] [added: 63] |
| [Note 2. Summary of Significant Accounting Policies](#NoteTwo) | [removed: 62] [added: 63] |
| [Note 3. [removed: Acquisitions](#NoteThree)] [added: Liberty Transaction](#NoteThree)] | [removed: 69] [added: 70] |
| [Note 9. Stockholders' Equity of Prologis, Inc.](#NoteTen) | [removed: 81] [added: 80] |
| [Note 14. Earnings Per Common Share or Unit](#EPS) | [removed: 89] [added: 88] |
| [Note 15. Financial Instruments and Fair Value Measurements](#NoteSixteen) | [removed: 90] [added: 89] |
| [Note 16. Commitments and Contingencies](#NoteSeventeen) | [removed: 93] [added: 92] |
| [Note 17. Business Segments](#NoteEighteen) | [removed: 94] [added: 93] |
| [Note 18. Supplemental Cash Flow Information](#NoteNineteen) | [removed: 96] [added: 95] |
| [Note 19. Selected Quarterly Financial Data (Unaudited)](#NoteTwenty) | [removed: 98] [added: 97] |
| [Schedule III — Real Estate and Accumulated Depreciation](#SCHEDULE_III_REAL_ESTATE_ACCUMULATED_DEP) | [removed: 100] [added: 99] |
We have audited the accompanying consolidated balance sheets of Prologis, Inc. and subsidiaries (the Company) as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] the related consolidated statements of income, comprehensive income, equity, and cash flows for each of the years in the three-year period ended December 31, [removed: 2020,] [added: 2021,] and the related notes and financial statement schedule III (collectively, the consolidated financial statements).
In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] and the results of its operations and its cash flows for each of the years in the three-year period ended December 31, [removed: 2020,] [added: 2021,] in conformity with U.S. generally accepted accounting principles.
We also have audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company’s internal control over financial reporting as of December 31, [removed: 2020,] [added: 2021,] based on criteria established in *Internal Control – Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission, and our report dated February [removed: 10, 2021] [added: 9, 2022] expressed an unqualified opinion on the effectiveness of the Company’s internal control over financial reporting.
Critical Audit [removed: Matters][added: Matter]
The critical audit [removed: matters] [added: matter] communicated below [removed: are matters] [added: is a matter] arising from the current period audit of the consolidated financial statements that [removed: were] [added: was] communicated or required to be communicated to the audit committee and that: (1) [removed: relate] [added: relates] to accounts or disclosures that are material to the consolidated financial statements and (2) involved our especially challenging, subjective, or complex judgments.
The communication of [added: a] critical audit [removed: matters] [added: matter] does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit [removed: matters] [added: matter] below, providing [added: a] separate [removed: opinions] [added: opinion] on the critical audit [removed: matters] [added: matter] or on the accounts or disclosures to which [removed: they relate.][added: it relates.]
As discussed in Notes 2 and 4, the Company had [removed: $43,508] [added: $44,454] million of operating properties as of December 31, [removed: 2020.][added: 2021.]
We evaluated the design and tested the operating effectiveness of certain internal controls [removed: over the Company’s recoverability of operating properties process including controls] related to determining the expected holding period [added: of operating properties] and any related changes.
We evaluated the Company’s expected holding period by inquiring of the Company regarding changes to the expected holding period, considering certain factors related to the current economic environment, reading minutes of the meetings of the Company’s Board of Directors, reading external communications with investors and analysts, and analyzing documents prepared by the Company regarding proposed real estate transactions and potential [removed: triggering events.][added: changes to the expected holding period.]
We have audited the accompanying consolidated balance sheets of Prologis, L.P. and subsidiaries (the Operating Partnership) as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] the related consolidated statements of income, comprehensive income, capital, and cash flows for each of the years in the [removed: three‑year] [added: three-year] period ended December 31, [removed: 2020,] [added: 2021,] and the related notes and financial statement schedule III (collectively, the consolidated financial statements).
In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Operating Partnership as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] and the results of its operations and its cash flows for each of the years in the [removed: three‑year] [added: three-year] period ended December 31, [removed: 2020,] [added: 2021,] in conformity with U.S. generally accepted accounting principles.
We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the [removed: Company] [added: Operating Partnership] in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
Critical Audit [removed: Matters][added: Matter]
The critical audit [removed: matters] [added: matter] communicated below [removed: are matters] [added: is a matter] arising from the current period audit of the consolidated financial statements that [removed: were] [added: was] communicated or required to be communicated to the audit committee and that: (1) [removed: relate] [added: relates] to accounts or disclosures that are material to the consolidated financial statements and (2) involved our especially challenging, subjective, or complex judgments.
The communication of [added: a] critical audit [removed: matters] [added: matter] does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit [removed: matters] [added: matter] below, providing [added: a] separate [removed: opinions] [added: opinion] on the critical audit [removed: matters] [added: matter] or on the accounts or disclosures to which [removed: they relate.][added: it relates.]
As discussed in Notes 2 and 4, the Operating Partnership had [removed: $43,508] [added: $44,454] million of operating properties as of December 31, [removed: 2020.][added: 2021.]
We evaluated the design and tested the operating effectiveness of certain internal controls [removed: over the Operating Partnership’s recoverability of operating properties process including controls] related to determining the expected holding period [added: of operating properties] and any related changes.
[Index to Item 15](#Index)
February 9, 2022
[Index to Item 15](#Index)
February 9, 2022
[Index to Item 15](#Index)
February 9, 2022
[Index to Item 15](#Index)
| | 2021 | | | | 2020 | | |
| Other assets | | 3,312,454 | | | | 2,949,009 | |
| Other liabilities | | 1,776,189 | | | | 1,747,977 | |
[Index to Item 15](#Index)
[Index to Item 15](#Index)
[Index to Item 15](#Index)
| Consolidated net earnings | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | 2,939,723 | | | | 208,867 | | | | 3,148,590 | |
| Effect of equity compensation plans | | \- | | | | (389 | ) | | | (4 | ) | | | 38,114 | | | | \- | | | | \- | | | | 78,062 | | | | 116,172 | |
| Redemption of noncontrolling interests | | \- | | | | 835 | | | | 8 | | | | 37,238 | | | | \- | | | | \- | | | | (190,482 | ) | | | (153,236 | ) |
| Consolidation of other venture | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | 25,759 | | | | 25,759 | |
| Acquisitions by noncontrolling interests | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | 130,416 | | | | 130,416 | |
| Foreign currency translation gains, net | | \- | | | | \- | | | | \- | | | | \- | | | | 298,413 | | | | \- | | | | 7,516 | | | | 305,929 | |
| Unrealized gains on derivative contracts, net | | \- | | | | \- | | | | \- | | | | \- | | | | 17,073 | | | | \- | | | | 469 | | | | 17,542 | |
| Dividends ($2.52 per common share) and other distributions | | \- | | | | \- | | | | \- | | | | (31 | ) | | | \- | | | | (1,872,861 | ) | | | (375,054 | ) | | | (2,247,946 | ) |
| Balance at December 31, 2021 | $ | 63,948 | | | | 739,827 | | | $ | 7,398 | | | $ | 35,561,608 | | | $ | (878,253 | ) | | $ | (1,327,828 | ) | | $ | 4,315,337 | | | $ | 37,742,210 | |
[Index to Item 15](#Index)
[Index to Item 15](#Index)
| | 2021 | | | | 2020 | | |
| Cash and cash equivalents | | 556,117 | | | | 598,086 | |
| Other assets | | 3,312,454 | | | | 2,949,009 | |
| Other liabilities | | 1,776,189 | | | | 1,747,977 | |
[Index to Item 15](#Index)
[Index to Item 15](#Index)
[Index to Item 15](#Index)
| Consolidated net earnings | | \- | | | | \- | | | | \- | | | | 2,939,723 | | | | \- | | | | 50,034 | | | | \- | | | | 31,758 | | | | 127,075 | | | | 3,148,590 | |
| Effect of equity compensation plans | | \- | | | | \- | | | | (389 | ) | | | 38,110 | | | | 1,286 | | | | 78,062 | | | | \- | | | | \- | | | | \- | | | | 116,172 | |
| Redemption of limited partnership units | | \- | | | | \- | | | | 835 | | | | 37,246 | | | | (2,105 | ) | | | (190,482 | ) | | | \- | | | | \- | | | | \- | | | | (153,236 | ) |
| Consolidation of other venture | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | 25,759 | | | | 25,759 | |
| Foreign currency translation gains (losses), net | | \- | | | | \- | | | | \- | | | | 298,413 | | | | \- | | | | 4,982 | | | | \- | | | | 3,226 | | | | (692 | ) | | | 305,929 | |
| Reallocation of capital | | \- | | | | \- | | | | \- | | | | (2,347 | ) | | | \- | | | | 133 | | | | \- | | | | 2,214 | | | | \- | | | | \- | |
| Distributions ($2.52 per common unit) and other | | \- | | | | \- | | | | \- | | | | (1,872,892 | ) | | | \- | | | | (40,287 | ) | | | \- | | | | (22,233 | ) | | | (312,534 | ) | | | (2,247,946 | ) |
| Balance at December 31, 2021 | | 1,279 | | | $ | 63,948 | | | | 739,827 | | | $ | 33,362,925 | | | | 12,354 | | | $ | 557,097 | | | | 8,595 | | | $ | 360,702 | | | $ | 3,397,538 | | | $ | 37,742,210 | |
[Index to Item 15](#Index)
| --- | --- |
Change in Accounting Principle
As discussed in Notes 2 and 4 to the consolidated financial statements, the Company has changed its method of accounting for leases as of January 1, 2019 due to the adoption of Accounting Standards Codification Topic 842, *Leases*.
Liberty Transaction
As discussed in Note 3 to the consolidated financial statements, on February 4, 2020 Prologis, Inc. and Prologis, L.P. acquired Liberty Property Trust and Liberty Property Limited Partnership (collectively the “Liberty Transaction”) for $13.0 billion and the transaction was accounted for as an asset acquisition.
In asset acquisitions, the Company measures the real estate assets acquired based on their cost or total consideration exchanged and any excess consideration is allocated to the real estate properties, excluding those identified as held for sale, on a relative fair value basis.
The components of the acquisition include an initial allocation to investments in real estate properties acquired based on fair value and an initial allocation of that fair value to buildings and land.
We identified the evaluation of the fair value allocated to investments in real estate properties acquired, including the allocation of the property fair value to land and building, in the Liberty Transaction as a critical audit matter.
Evaluating the fair value amounts estimated by the Company in the allocation, which have measurement uncertainty, required specialized skill and knowledge.
Specifically, testing significant assumptions of market rents and capitalization rates in relation to investments in real estate and testing the allocation of property fair value to land and building.
The following are the primary procedures we performed to address this critical audit matter.
We evaluated the design and tested the operating effectiveness of certain internal controls over the Company’s fair value estimation process for investments in real estate properties, land and building.
This included controls related to the determination of amounts allocated to land and building and significant assumptions used to estimate the fair value of investments in real estate properties.
For a selection of investments in real estate properties we involved valuation professionals with specialized skills and knowledge, who assisted in 1) comparing the Company’s determination of the fair value of investments in real estate properties to sales prices from available property sales, 2) comparing the Company’s significant assumptions used in the determination of the fair value of investments in real estate properties to available leasing information, industry research publications and inquiries of market participants, 3) comparing the Company’s determination of the fair value of land to sales prices from available land sales and 4) comparing the Company’s determination of fair value of building to developed ranges of estimates based on market data, such as industry guides used for developing replacement building values.
The following are the primary procedures we performed to address this critical audit matter.
February 10, 2021
Change in Accounting Principle
As discussed in Notes 2 and 4 to the consolidated financial statements, the Operating Partnership has changed its method of accounting for leases as of January 1, 2019 due to the adoption of Accounting Standards Codification Topic 842, *Leases*.
Liberty Transaction
As discussed in Note 3 to the consolidated financial statements, on February 4, 2020 Prologis, Inc. and Prologis, L.P. acquired Liberty Property Trust and Liberty Property Limited Partnership (collectively the “Liberty Transaction”) for $13.0 billion and the transaction was accounted for as an asset acquisition.
In asset acquisitions, the Operating Partnership measures the real estate assets acquired based on their cost or total consideration exchanged and any excess consideration is allocated to the real estate properties, excluding those identified as held for sale, on a relative fair value basis.
The components of the acquisition include an initial allocation to investments in real estate properties acquired based on fair value and an initial allocation of that fair value to buildings and land.
We identified the evaluation of the fair value allocated to investments in real estate properties acquired, including the allocation of the property fair value to land and building, in the Liberty Transaction as a critical audit matter.
Evaluating the fair value amounts estimated by the Operating Partnership in the allocation, which have measurement uncertainty, required specialized skill and knowledge.
Specifically, testing significant assumptions of market rents and capitalization rates in relation to investments in real estate and testing the allocation of property fair value to land and building.
We evaluated the design and tested the operating effectiveness of certain internal controls over the Operating Partnership’s fair value estimation process for investments in real estate properties, land and building.
This included controls related to the determination of amounts allocated to land and building and significant assumptions used to estimate the fair value of investments in real estate properties.
For a selection of investments in real estate properties we involved valuation professionals with specialized skills and knowledge, who assisted in 1) comparing the Operating Partnership’s determination of the fair value of investments in real estate properties to sales prices from available property sales, 2) comparing the Operating Partnership’s significant assumptions used in the determination of the fair value of investments in real estate properties to available leasing information, industry research publications and inquiries of market participants, 3) comparing the Operating Partnership’s determination of the fair value of land to sales prices from available land sales and 4) comparing the Operating Partnership’s determination of fair value of building to developed ranges of estimates based on market data, such as industry guides used for developing replacement building values.
February 10, 2021
February 10, 2021
| Other assets | | 2,456,208 | | | | 1,711,857 | |
| Other liabilities | | 1,261,005 | | | | 877,601 | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Balance at January 1, 2018 | $ | 68,948 | | | | 532,186 | | | $ | 5,322 | | | $ | 19,363,007 | | | $ | (901,658 | ) | | $ | (2,904,461 | ) | | $ | 3,074,583 | | | $ | 18,705,741 | |
| Consolidated net earnings | | \- | | | | \- | | | | \- | | | | \- | | | | \- | | | | 1,649,361 | | | | 173,599 | | | | 1,822,960 | |
| Effect of equity compensation plans | | \- | | | | 1,251 | | | | 12 | | | | 33,544 | | | | \- | | | | \- | | | | 52,219 | | | | 85,775 | |
| DCT Transaction, net of issuance costs | | \- | | | | 96,179 | | | | 962 | | | | 6,321,667 | | | | \- | | | | \- | | | | 298,092 | | | | 6,620,721 | |
| Redemption of noncontrolling interests | | \- | | | | \- | | | | \- | | | | (11,257 | ) | | | \- | | | | \- | | | | (64,663 | ) | | | (75,920 | ) |
| Foreign currency translation losses, net | | \- | | | | \- | | | | \- | | | | \- | | | | (181,728 | ) | | | \- | | | | (8,862 | ) | | | (190,590 | ) |
An excerpt. Shown here: 40 of 918 rewritten, 40 of 331 added and 40 of 390 removed. The counts are complete. For every sentence, read Item 16. Form 10-K Summary in the FY2021 filing and the FY2020 filing.