 filings.tools
PNC Financial Services Group (PNC) 10-K risk factor changes: FY2022 vs FY2021
The 2022-12-31 10-K against the 2021-12-31 one, compared heading by heading and sentence by sentence.
Item 1A207 rewritten66 added74 removed371 unchanged
All filing items2,681 rewritten1,029 added939 removed4,360 unchanged
Summary
counted, not written
- Item 1A lists 29 risk factor headings: 0 new, 6 reworded and 23 unchanged since FY2021. 1 heading from FY2021 no longer appears.
- Sentence by sentence, 1,029 added, 939 removed, 2,681 rewritten and 4,360 unchanged across 18 items that differ.
New Item 1A headings (0)
No risk factor heading in this filing is absent from FY2021.
Removed Item 1A headings (1)
- The COVID-19 pandemic has had and is likely to continue to have an adverse effect, possibly materially, on our overall business and financial performance.
Reworded Item 1A headings (6)
- The scheduled
[removed: discontinuance][added: cessation] of LIBOR presents risks to the financial instruments originated, held or serviced by PNC that use LIBOR as a reference rate. [removed: New customer privacy][added: Privacy] initiatives [added: have imposed and] will [added: continue to] impose additional operational burdens on PNC, [added: and they] may limit our ability to pursue desirable business initiatives and increase the risks associated with any future use of[removed: customer][added: personal] data.- Climate
[removed: change and societal responses to climate change][added: change-related risks] could adversely affect our business and performance, including indirectly through impacts on our customers. - Our use of technology is dependent on having the right to use
[removed: the][added: its] underlying intellectual property. - The concentration and mix of our
[removed: loan portfolio][added: assets] could increase the potential for significant [added: credit] losses. - Our asset and liability valuations and the determination of the amount of loss allowances and impairments taken on our assets are highly subjective.
[removed: Inaccurate][added: Our] estimates could materially impact our results of operations or financial position.
A heading is new when no FY2021 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
22 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2022; struck-through words were in FY2021. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
207 rewritten, 66 added, 74 removed, 371 unchanged
We discuss our principal risk management oversight and processes and, in appropriate places, related historical performance and other metrics in the Risk Management section [removed: included in Item 7] of this Report.
The following is a summary of the Risk Factors [removed: disclosure] in this Item 1A:
- The scheduled [removed: discontinuance] [added: cessation] of LIBOR presents risks to the financial instruments originated, held or serviced by PNC that use LIBOR as a reference rate.
- Climate [removed: change and societal responses to climate change] [added: change-related risks] could adversely affect our business and performance, including indirectly through impacts on our customers.
- We are subject to risks related to the use of technology which is critical to our ability to maintain or enhance the competitiveness of our businesses and is dependent on having the right to use [removed: the] [added: its] underlying intellectual property.
We could also suffer a material adverse impact from interruptions in the effective operation of our information systems and other technology, including as a result of [removed: third party] [added: third-party] breaches of data security either at PNC or at third parties handling PNC information.
- Our business and financial results are subject to risks associated with the creditworthiness of our customers and counterparties, the concentration and mix of our [removed: loan portfolio,] [added: assets,] market interest rates and movements in those rates and changes in the values of financial assets.
- We are subject to operational risks as a result of our dependence on the effectiveness and integrity of our employees and [added: internal systems and] on [removed: third party] [added: third-party] vendors, service providers and other counterparties over whom we do not have direct control.
- We are subject to risks related to growing our business by acquiring other financial services business from time to time as these [removed: acquisitions, including the acquisition of BBVA,] [added: acquisitions] present a number of risks and uncertainties related both to the acquisition transactions themselves and to the integration of the acquired businesses into PNC after closing.
The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* 15
[removed: -] Some of the legislation responsive to the [removed: outbreak, including] [added: COVID-19 pandemic (such as] the CARES Act and the Consolidated Appropriations [removed: Act, provides] [added: Act that provided] for certain commercial and consumer [removed: protections which have] [added: protections)] altered [removed: and may continue to alter] the profitability of the transactions in which we [removed: engage.][added: engage, and other laws related to employee benefits increased administrative, compensation and benefits costs to us.]
[removed: Further governmental action that is taken] [added: Other such laws may be enacted in response] to [removed: mitigate the economic effects of the pandemic, as well as additional compensation] [added: other extraordinary events beyond PNC’s control that have similar] or [removed: benefit actions taken by PNC,] [added: broader effects on us and] could adversely affect our financial condition and results of operations, possibly materially, in other ways that are not [added: now] known [removed: now.][added: to us.]
[removed: - We] [added: We] rely on [removed: our employees, third party vendors and] [added: third-party vendors,] service providers and other [removed: counterparties, both domestically and abroad,] [added: counterparties] to [added: help] support many aspects of our business.
[removed: These risks are also faced by many of] [added: Increases in costs or expenses impacting] our [removed: customers which could adversely affect their] [added: customers’] operations and financial [removed: performance and] [added: performance, such as the interest rates payable on their debt obligations, could] increase our credit risk or decrease the demand for our products and services.
16 The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K*
These conditions may not abate in the near [removed: term] [added: term,] and their continuation could materially adversely affect our operations and financial performance.
Such economic conditions also [added: have led and] may [added: continue to] lead to turmoil and volatility in financial markets, often with at least some financial asset categories losing value.
Any of these effects would likely have an adverse impact on our [removed: earnings,] [added: operations and financial performance,] with the significance of the impact generally depending on the nature and severity of the adverse economic conditions.
As a result, the direct impact on our business and [added: financial] performance from economic conditions outside the U.S. is not likely to be significant, although the impact would increase if we [removed: expand] [added: expanded] our foreign business more than nominally.
We are, however, susceptible to the risk that [removed: such] [added: foreign] economic conditions could negatively affect our business and financial performance.
Changes in law or governmental policy affecting the economy, business activity, or personal spending, investing or saving activities may cause consumers and businesses to alter [added: their] behavior in ways that impact demand for our products and services.
[removed: Moreover, a change in regulatory practices that increases] [added: For example,] the [added: increased] time frames [removed: to obtain] [added: and difficulty in obtaining] regulatory approvals for acquisitions and other activities [removed: or makes them more difficult to obtain] could affect our ability to make acquisitions or introduce new products and services.
The monetary policies of the Federal [removed: Reserve] [added: Reserve, including changes in the federal funds rate, open market operations and balance sheet management,] have a significant impact on interest rates, the value of financial instruments and other assets and liabilities, and overall financial market [removed: performance.][added: performance and volatility.]
These policies can thus affect the activities and results of operations of financial [removed: companies such as PNC.]
Although we may not accurately predict the nature or timing of future changes in monetary policies or the precise effects that they may have on our activities and financial results, we anticipate that the FOMC will [removed: raise] [added: increase] the federal funds rate by [removed: 0.25 percentage] [added: an additional 25 basis] points [removed: five times] in [removed: 2022 to reach a range of 1.25% to 1.50% by the end of the year, and then further increase the federal funds rate in 2023.][added: March.]
The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* 17
In addition, [removed: monetary policy] actions by governmental authorities in [removed: the European Union or] other [removed: countries] [added: countries, including with respect to monetary policy,] could [removed: have an] impact [removed: on] [added: financial markets and] global interest rates, which could affect rates in the U.S. as well as rates on instruments denominated in currencies other than the U.S. dollar, any of which could have [removed: one or more of the] potential effects on us [added: as] described above.
Some of the potential impacts on our business and results of governmental monetary policy are described in Risk Factors under the heading “Risks Related to the Business of Banking.” [removed: The Federal Reserve has lowered its benchmark rates to historically low levels as a result of the COVID-19 pandemic.]
As a result, we are subject to numerous laws and [removed: regulations involving both our business and organization,] [added: regulations,] with multiple regulators or agencies having supervisory or enforcement oversight over aspects of our [removed: business.][added: business activities.]
These laws, regulations and supervisory activities are intended to promote the safety and soundness of financial institutions, financial market stability, the transparency and liquidity of financial markets, [removed: and] consumer [removed: and investor] protection and [added: to] prevent money laundering and terrorist financing and are not primarily intended to protect PNC security holders.
The results of routine and non-routine supervisory or examination activities by our regulators, including actual or perceived compliance failures, could result in limitations on our ability to enter into certain transactions, engage in new activities, expand geographically, make acquisitions or obtain necessary regulatory approvals in connection [removed: therewith.][added: therewith, or otherwise require us to modify our businesses practices in a manner that materially impacts our financial condition or results of operations.]
We also rely on third parties who may expose us to compliance [removed: risk.]
A failure to comply with regulatory requirements or deficiencies in risk management practices could be incorporated in our confidential supervisory [removed: ratings] [added: ratings,] which could limit PNC’s ability to expand or require additional approvals before engaging in certain business activities.
Also see [added: the] Supervision and Regulation [removed: in Item 1] [added: section] of this Report for more information concerning the regulation of PNC, including those areas that have been receiving a high level of regulatory focus.
Note 20 Regulatory Matters [removed: in the Notes to Consolidated Financial Statements in Item 8 of this Report] also discusses some of the [removed: regulation] [added: regulations] applicable to us.
18 The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K*
The Federal Reserve can also impose additional limitations on capital distributions, such as the limitations on distributions imposed in response to the COVID-19 [removed: pandemic.][added: pandemic and the 2007-2008 financial crisis.]
Limitations on PNC’s ability to receive dividends from its subsidiaries, including PNC Bank, could have a material adverse effect on its liquidity and ability to pay dividends on and make repurchases of its capital [removed: stock.][added: stock, especially to the extent that PNC must first service any outstanding debt obligations.]
See the Supervision and Regulation section [removed: included in Item 1] of this Report.
[removed: As] [added: Generally, as] it is [removed: unclear, at this time,] [added: unclear] whether or how these initiatives will be implemented in the U.S., we are unable to estimate what potential impact such initiatives may have on us.
This may be further exacerbated by the expiration of pandemic-related government assistance in the U.S., which could lead to a decrease in economic activity and a deterioration in households’ finances, particularly if consumers also continue to face high inflation.
While the U.S. economy has generally improved since the onset of the COVID-19 pandemic, we now operate in an uncertain economic environment as a result of the impacts of the pandemic and responsive measures to manage it, high inflation, supply chain disruptions, changes in the labor markets, volatile energy prices and geopolitical tensions (including as a result of the Russia-Ukraine conflict).
As another example, we could experience an increase in credit losses as a result of structural and secular changes fostered by the pandemic for certain sectors of the economy.
In addition, the application of some laws may be uncertain, require significant judgment and be subject to differing interpretations.
Congress and the agencies that regulate us have changed and may continue to change the laws and policies that are applicable to us, including their interpretations of rules and guidelines, which has subjected and may continue to subject financial institutions like us to heightened levels of regulation and supervision and more stringent enforcement and potentially severe penalties.
As another example, tax laws and tax rates may be subject to significant change and an increase in our effective tax rates could adversely affect our business, results of operation and financial condition.
In addition, these changes may adversely impact our operations or financial condition as discussed in more detail in the Risk Factor headed “As a regulated financial services firm, we are subject to numerous governmental regulations and comprehensive oversight by a variety of regulatory agencies and enforcement authorities.
These regulations and the way they are implemented can have a significant impact on our businesses and operations and our ability to grow and expand.”
Divided control of the U.S. government may increase concern over the inability of Congress and the President to reach necessary agreements and make government shutdowns or defaults in government obligations more likely.
companies such as PNC.
The FOMC has increased its benchmark rates from a range of 0% to 0.25% from March 2020 through 2021 to 4.75% as of February 1, 2023 in an effort to reduce high rates of inflation.
This would bring the federal funds rate to a range of 4.75% to 5.00% by mid-March.
We expect a federal funds rate cut of 25 basis points in early 2024 as inflation moves toward the FOMC’s 2% long-term objective.
For example, under Dodd-Frank, the CFPB has broad authority to protect consumers from “unfair, deceptive and abusive acts or practices,” the definition of which is being clarified through heightened instances of CFPB enforcement actions and proceedings.
risk.
The Basel Committee continues to develop policies and standards for the prudential regulation of banks.
We expect the federal banking agencies to propose rules in 2023 to implement the capital- and liquidity-related final set of Basel III standards issued by the Basel Committee in December 2017.
However, we maintain a sizable book of owned and serviced LIBOR reference rate assets.
For more information on our LIBOR reference rate assets, see the Market Risk Management portion of the Risk Management section of this Report.
As announced by ICE Benchmark Administration Limited and the U.K. Financial Conduct Authority, as of June 30, 2023, the current form of USD LIBOR will no longer be available, and any alternative form of USD LIBOR published using a new methodology for rate calculation (*i.e.*, “synthetic LIBOR”) would not be a “representative” rate.
As a result, most USD LIBOR reference rate assets will require a replacement reference rate on or about that time.
That replacement reference rate will either be implemented consistent with contractual terms or by operation of law.
Currently, SOFR is the alternative reference rate replacing USD LIBOR for most types of transactions and, under recently enacted federal legislation addressing LIBOR cessation, is the replacement reference rate to be used for certain LIBOR contracts when LIBOR cessation occurs, including those that do not include terms for determining a replacement reference rate.
LIBOR and SOFR are based on different inputs.
To address differences between LIBOR and SOFR, certain industry-recommended LIBOR contract provisions that provide a mechanism to transition to a SOFR reference rate include the concept of an adjustment spread.
The adjustment spread is applied when a LIBOR-based contract moves to the SOFR replacement reference rate.
These recommended adjustment spreads are based on a five-year median look-back of the historical spot difference between the applicable LIBOR tenor and the applicable SOFR tenor and were fixed on March 5, 2021 as a result of announcements by ICE Benchmark Administration (the administrator of LIBOR) and the UK Financial Conduct Authority (the regulatory supervisor of the IBA) of the dates after which all LIBOR settings will either cease to be provided or will no longer be representative.
The same adjustment spreads will also be operational under current federal law.
Changing the reference rate to SOFR is highly likely to result in some value transfer between parties to instruments originally based on LIBOR, and we have experienced some value transfer in connection with instruments that have been amended away from LIBOR in anticipation of its cessation.
That value transfer arises because no reference rate will replicate LIBOR exactly, and, accordingly, any replacement reference rate will not behave identically to LIBOR over time.
Individuals whose personal information may be protected by law may include our customers, prospective customers, job applicants, employees and third parties.
This is particularly true as we continue to expand our business into new markets.
We are, or may become, subject to regularly evolving and developing data privacy and data security laws and regulations in other jurisdictions, including certain foreign jurisdictions even where our presence in such jurisdictions is minimal.
In addition, we could face reductions in creditworthiness on the part of some customers or in the value of assets securing loans.
We also have been and may continue to be subject to pressure from individuals or groups to cease doing business with certain companies or sectors because of concerns related to climate change.
We are currently subject to climate-related regulatory expectations and could be subject to additional regulatory restrictions or costs associated with providing products or services to certain companies or sectors.
Further, there is increased scrutiny of climate change-related policies, goals and disclosures, which could result in litigation and regulatory investigations and actions.
We may incur additional costs and require additional resources as we evolve our strategy, practices and related disclosures with respect to these matters.
Our ability to create, obtain, maintain and report on information in an accurate, timely and secure manner is a foundational component of our business.
Systems maintained by or for these other companies are generally subject to many of the same risks
- The COVID-19 pandemic has had and is likely to continue to have an adverse effect, possibly materially, on our overall business and financial performance.
Risks Related to the COVID-19 Pandemic
The COVID-19 pandemic has had and is likely to continue to have an adverse effect, possibly materially, on our overall business and financial performance.
The COVID-19 pandemic has resulted in widespread and continuing impacts on economic and financial conditions, our customers and our employees.
While economic conditions have improved since the first half of 2020, the recovery has been inconsistent across different geographic regions, sectors, companies and individuals and subject to setbacks as conditions related to the pandemic fluctuate.
There is still a great deal of uncertainty about the length and severity of the pandemic and the strength or reversal of the economic rebound.
While many of the impacts have subsided, including as a result of relaxation of responsive measures to manage the pandemic, future developments may lead to reimposed or new responsive measures that otherwise increase the negative economic impacts of the pandemic.
Accordingly, the pandemic and its consequences had and are likely to continue to have an adverse effect,
possibly materially, on our overall business and financial performance.
The following are examples of the most likely impacts on PNC:
- National macroeconomic indicators, forecasts and performance expectations have all steadily improved, which has had a beneficial impact on our credit risk, but uncertainty remains regarding lifetime losses of certain portions of our commercial and consumer portfolios.
For commercial borrowers, there are still lingering concerns around industries that have been affected by COVID-19 related restrictions and market changes.
For these industries, where unrestricted commerce has recently returned, the recovery will lag the broader economy.
Where restrictions persist or market changes have emerged, the impact and eventual level of recovery are less certain.
For consumer borrowers, payment behavior upon expiration of government stimulus, including recently expired enhanced unemployment benefits, is still difficult to predict.
As a result, there is a likelihood that certain of our commercial and consumer customers or counterparties will become delinquent on their loans or other obligations to us, which, in turn, will result in a higher level of non-performing loans and net charge-offs.
In addition, given the uncertainty about the length and severity of the pandemic and the strength or reversal of the economic rebound, our provision for credit losses may be more volatile period-to-period with a corresponding increase in period-to-period volatility in our net income.
- There has been and there is likely to continue to be a decrease in the demand for certain of our products and services which could be further exacerbated if customers lose confidence due to concerns regarding the economy, including as a result of inflationary pressures or supply chain disruptions.
- While customer deposits have grown, aiding our liquidity, future changes in behavior resulting in declining deposit balances would likely increase our funding costs and reduce our net interest income and liquidity resources.
These laws may be extended or increased in scope, and other laws may be enacted in response to the pandemic that have similar or broader effects on us.
- Other laws related to employee benefits and the treatment of employees have negatively impacted and may continue to negatively impact us by increasing administrative, compensation and benefits costs by, for example, mandating coverage of certain COVID-19 related testing without cost sharing or mandating additional paid or unpaid leave.
Reduced workforces which may be caused by, among other things, illness, quarantine, stay at home or other government mandates, decisions regarding mandatory vaccination, proof of vaccination or face covering requirements, difficulties transitioning back to an in-office environment or substantial changes in the labor market (including labor availability and wage inflation) could result in an adverse impact to our operations and financial performance.
Many of these risks are likely to persist after the pandemic as a result of permanent changes to the labor market.
- In support of our employees, customers and communities, we have taken and may continue to take steps beyond or in addition to those required by governmental or regulatory minimums which may further adversely impact our profitability.
For example, we have provided and may continue to provide additional relief or forbearance to customers, health and wellness benefits to employees (including significant company approved leave) or financial support for community initiatives to assist those in need because of the outbreak.
The actual or perceived failure to provide sufficient services, support or relief to those businesses or individuals in need or properly implement legislation responsive to the outbreak or our voluntary commitments could negatively impact our reputation with adverse consequences to our business.
In addition, such actual or perceived failure, or operational and other issues that arise in connection with the implementation of government-mandated or other financial assistance or relief programs present elevated levels of financial, legal and reputational risk, including fraud, governmental and regulatory inquiries, investigations and enforcement actions, as well as private lawsuits.
Participation by PNC in governmental programs, such as the CARES Act and the Consolidated Appropriations Act, including the PPP, also have exposed and may continue to expose us to governmental investigation and action or public scrutiny and criticism.
Refer to our other Risk Factors in this Item 1A for information regarding other factors that have and are likely to continue to affect our business and financial performance as a result of the pandemic.
Increases in costs or expenses impacting our customers’ operations and financial performance, such as the interest rate payable on their debt obligations, could increase our credit risk or decrease the demand for our products and services.
Recently, there has been
inflation at higher levels than seen in many decades, and significant supply chain constraints have increased costs and impacted operations for us and many of our customers.
As another example, declines in leisure recreation and travel because of the COVID-19 pandemic have adversely affected and may continue to adversely affect restaurants, casinos, hotels, convention centers, cruise lines, airlines and other travel/transportation companies.
In particular, the COVID-19 pandemic has led to economic issues of the types described here and presents the risk of further such impacts.
See the immediately preceding Risk Factor for a discussion of risks associated with the COVID-19 pandemic.
Changes in the U.S. presidential administration and Congress have led and will likely continue to lead to changes in law or policy, including the level of regulation and supervision of financial institutions.
For example, it is possible that Congress amends or repeals all or certain aspects of the Tax Cuts and Jobs Act of 2017 which could adversely affect us, including through a complete or partial repeal of the reduction in the statutory corporate income tax rate.
In addition, changes in key personnel at the agencies that regulate us, including the federal banking regulators, may result in differing interpretations of existing rules and guidelines and potentially more stringent enforcement and severe penalties.
See the Risk Factor headed “The COVID-19 pandemic has had and is likely to continue to have an adverse effect, possibly materially, on our overall business and financial performance.”
The Basel Committee continues to engage in capital- and liquidity-related initiatives.
An excerpt. Shown here: 40 of 207 rewritten, 40 of 66 added and 40 of 74 removed. The counts are complete. For every sentence, read Item 1A. RISK FACTORS in the FY2022 filing and the FY2021 filing.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (MD&A)
743 rewritten, 385 added, 338 removed, 777 unchanged
- Continuing to maintain [removed: and] [added: and, over time,] grow our deposit base as a low-cost stable funding source,
- The appropriateness of [removed: reserves needed for] critical accounting estimates and related contingencies, and
- Global and domestic economic conditions, including the length and extent of the economic impacts of the [added: COVID-19] pandemic, [added: and the actions taken to mitigate and manage it,]
[removed: 38] [added: 36] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K*
For additional information on the risks we face, see [added: Item 1A Risk Factors and] the Cautionary Statement Regarding Forward-Looking Information section in this Item [removed: 7 and Item 1A Risk Factors in this Report.][added: 7.]
Our results [added: of operations and balance sheets] for [removed: the twelve months ended December 31, 2021] [added: all periods presented in this Report] reflect the [removed: impact] [added: benefit] of [removed: BBVA's] [added: BBVA’s] acquired [removed: business operations] [added: businesses] for the period since the acquisition closed on June 1, 2021.
For additional information on the acquisition of BBVA, see Note 2 Acquisition and Divestiture [removed: Activity in the Notes to Consolidated Financial Statements included in Item 8 of this Report.][added: Activity.]
For additional details on the divestiture of our equity investment in BlackRock, see Note 2 Acquisition and Divestiture [removed: Activity in the Notes to Consolidated Financial Statements in Item 8 of this Report.][added: Activity.]
Net income [removed: from continuing operations] for [removed: 2021] [added: 2022] was [removed: $5.7] [added: $6.1] billion, or [removed: $12.70] [added: $13.85] per diluted common share, an increase of [removed: $2.7] [added: $0.4] billion compared to net income [removed: from continuing operations] of [removed: $3.0] [added: $5.7] billion, or [removed: $6.36] [added: $12.70] per diluted common share, for [removed: 2020.][added: 2021.]
The increase was [removed: primarily] driven by [removed: lower provision for credit losses in 2021 and] higher [removed: noninterest] [added: net interest] income, [removed: including the benefit of BBVA,] partially offset by [removed: expenses related to the BBVA acquisition] [added: a higher provision for credit losses, lower noninterest income] and [removed: increased business activity.][added: higher expenses.]
- Total revenue increased [removed: $2.3 billion] [added: $1.9 billion, or 10%,] to [removed: $19.2] [added: $21.1] billion.
[removed: Provision for credit losses was $3.2 billion] [added: Provision] for [removed: 2020.][added: (Recapture of) Credit Losses]
- Noninterest expense increased [removed: $2.7 billion, or 26%,] [added: $168 million] to [removed: $13.0] [added: $13.2] billion, reflecting [removed: expenses related to] the [added: addition of a full year of] BBVA [removed: acquisition] [added: operating expenses] and [removed: increased] [added: continued] business [removed: activity.][added: investment.]
The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [removed: 39][added: 37]
Our balance sheet was [removed: strong and] well positioned at December 31, [removed: 2021 and 2020.][added: 2022.]
- Total loans increased [removed: $46.4] [added: $37.7] billion, or [removed: 19%,] [added: 13%,] to [removed: $288.4] [added: $326.0] billion.
- PNC had [removed: $3.4] [added: $0.4] billion of PPP loans outstanding at December 31, [removed: 2021,] [added: 2022,] compared to [removed: $12.0] [added: $3.4] billion at December 31, [removed: 2020.][added: 2021.]
- Total consumer loans increased [removed: $20.5] [added: $5.7] billion, or [removed: 28%,] [added: 6%,] to [removed: $95.3] [added: $101.0] billion, primarily due to [removed: the addition of BBVA loans and increased originations of] [added: increases in] residential mortgages, [added: home equity and credit card,] partially offset by declines in the remaining [removed: PNC legacy] portfolios as paydowns outpaced new originations.
- Interest earning deposits with banks, primarily with the Federal Reserve Bank, decreased [removed: $10.9 billion to $74.3 billion primarily due] [added: $46.9 billion, or 63%] to [removed: increased] [added: $27.3 billion, reflecting higher loans outstanding, lower deposits and higher] securities [removed: purchases.][added: balances.]
- At December 31, [removed: 2021] [added: 2022] compared to December 31, [removed: 2020:][added: 2021:]
- The ACL related to loans, which consists of the ALLL and the allowance for unfunded lending related commitments, decreased to [removed: $5.5] [added: $5.4] billion, or [removed: 1.92%] [added: 1.67%] of total loans at December 31, [removed: 2021,] [added: 2022,] compared to [removed: $5.9] [added: $5.5] billion, or [removed: 2.46%] [added: 1.92%] of total loans at December 31, [removed: 2020.][added: 2021.]
- Net charge-offs of [removed: $657] [added: $563] million or [removed: 0.24%] [added: 0.18%] of average loans in [removed: 2021] [added: 2022] decreased [removed: 21%] [added: 14%] compared to net charge-offs of [removed: $832] [added: $657] million or [removed: 0.33%] [added: 0.24%] of average [removed: loans,] [added: loans] for [removed: 2020.][added: 2021.]
We maintained a strong capital position during [removed: 2021.][added: 2022.]
- The Basel III CET1 capital ratio decreased to [removed: 10.3%] [added: 9.1%] at December 31, [removed: 2021] [added: 2022] from [removed: 12.2%] [added: 10.3%] at December 31, [removed: 2020, primarily due to the BBVA acquisition.][added: 2021.]
CECL’s estimated impact on CET1 capital is defined as the change in retained earnings at adoption plus or minus 25% of the change in CECL ACL at the balance sheet date, excluding the [removed: initial] allowance for PCD [removed: loans from BBVA,] [added: loans,] compared to CECL ACL at [removed: transition.][added: adoption.]
- In [removed: 2021,] [added: 2022,] we returned [removed: $3.0] [added: $6.0] billion of capital to shareholders through dividends on common shares of [removed: $2.0] [added: $2.4] billion and repurchases of [removed: 5] [added: 21.2] million common shares for [removed: $1.0] [added: $3.6] billion.
- On January [removed: 5, 2022,] [added: 4, 2023,] the PNC Board of Directors declared a quarterly cash dividend on common stock of [removed: $1.25] [added: $1.50] per [removed: share paid on February 5, 2022.][added: share.]
[removed: 40] [added: 38] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K*
See the Liquidity and Capital Management portion of the Risk Management section of this Item 7 for more detail on our [removed: 2021] [added: 2022] capital and liquidity actions as well as our capital ratios.
These statements are based on our [removed: view] [added: views] that:
See [added: Item 1A Risk Factors and] the Cautionary Statement Regarding Forward-Looking Information section in this Item 7 [removed: and Item 1A Risk Factors in this Report] for other factors that could cause future events to differ, perhaps materially, from those anticipated in these forward-looking statements.
For the full year [removed: 2022,] [added: 2023,] compared to full year [removed: 2021,] [added: 2022,] we expect:
- Period-end loans to be up [removed: approximately 5%,][added: 2% to 4%,]
- The effective tax rate to be approximately [removed: 18%, and][added: 18%.]
For the first quarter of [removed: 2022,] [added: 2023,] compared to the fourth quarter of [removed: 2021,] [added: 2022,] we expect:
- Average [removed: loans, excluding PPP,] [added: loans] to be up [removed: approximately 1%] [added: 6%] to [removed: 2%,][added: 8%,]
- Net interest income to be down [removed: approximately] 1% to 2%,
- Fee income to be down [removed: 4%] [added: 3%] to [removed: 6%,][added: 5%,]
- Other noninterest income, excluding [removed: integration costs,] net securities [added: gains] and Visa activity, to be between [removed: $375] [added: $200] million and [removed: $425] [added: $250] million,
- Total revenue to decline approximately [removed: 3% to 5%,][added: 3%,]
- Leveraging technology to create efficiencies that help us better serve customers.
- Our ability to manage operational risks related to new products and services, changes in processes and procedures or the implementation of new technology.
- The effect of climate change on our business and performance, including indirectly through impacts on our customers,
Presentation of Noninterest Income
Effective for the first quarter of 2022, PNC updated the presentation of its noninterest income categorization to be based on product and service type, and accordingly, has changed the basis of presentation of its noninterest income revenue streams to: (i) Asset management and brokerage, (ii) Capital markets related, (iii) Card and cash management, (iv) Lending and deposit services, (v) Residential and commercial mortgage and (vi) Other noninterest income.
For a description of each updated noninterest income revenue stream, see Note 1 Accounting Policies.
Additionally, in the fourth quarter of 2022, PNC updated the name of the noninterest income line item “Capital markets related” to “Capital markets and advisory.” This update did not impact the components of the category.
All periods presented herein reflect these changes.
Selected Financial Data
The following tables include selected financial data which should be reviewed in conjunction with the Consolidated Financial Statements and Notes included in Item 8 of this Report as well as the other disclosures in this Report concerning our historical financial performance, our future prospects and the risks associated with our business and financial performance.
Table 1: Summary of Operations, Per Common Share Data and Performance Ratios
| | | | Year ended December 31 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Dollars in millions, except per share data | | | 2022 | | | | | | 2021 | | | | | | 2020 | | | | | | | | | | | | | | | | | |
| Summary of Operations | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Total revenue | | | 21,120 | | | | | | 19,211 | | | | | | 16,901 | | | | | | | | | | | | | | | | | |
| Income from continuing operations before income taxes and noncontrolling interests | | | 7,473 | | | | | | 6,988 | | | | | | 3,429 | | | | | | | | | | | | | | | | | |
| Income taxes from continuing operations | | | 1,360 | | | | | | 1,263 | | | | | | 426 | | | | | | | | | | | | | | | | | |
| Net income from continuing operations | | | 6,113 | | | | | | 5,725 | | | | | | 3,003 | | | | | | | | | | | | | | | | | |
| Income from discontinued operations before taxes | | | | | | | | | | | | | | | 5,777 | | | | | | | | | | | | | | | | | |
| Income taxes from discontinued operations | | | | | | | | | | | | | | | 1,222 | | | | | | | | | | | | | | | | | |
| Net income | | | $ | 6,113 | | | | | $ | 5,725 | | | | | $ | 7,558 | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Net income attributable to common shareholders | | | $ | 5,735 | | | | | $ | 5,436 | | | | | $ | 7,284 | | | | | | | | | | | | | | | | |
| Per Common Share | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Diluted earnings from continuing operations | | | $ | 13.85 | | | | | $ | 12.70 | | | | | $ | 6.36 | | | | | | | | | | | | | | | | |
| Diluted earnings from discontinued operations | | | | | | | | | | | | | | | $ | 10.60 | | | | | | | | | | | | | | | | |
| Total diluted earnings | | | $ | 13.85 | | | | | $ | 12.70 | | | | | $ | 16.96 | | | | | | | | | | | | | | | | |
| Book value per common share | | | $ | 99.93 | | | | | $ | 120.61 | | | | | $ | 119.11 | | | | | | | | | | | | | | | | |
| Tangible book value per common share (non-GAAP) (a) | | | $ | 72.12 | | | | | $ | 94.11 | | | | | $ | 97.43 | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Performance Ratios | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Net interest margin (non-GAAP) (b) | | | 2.65 | | % | | | | 2.29 | | % | | | | 2.53 | | % | | | | | | | | | | | | | | | |
| Return on: | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Average common shareholders’ equity | | | 13.52 | | % | | | | 10.78 | | % | | | | 15.21 | | % | | | | | | | | | | | | | | | |
- Leveraging technology to innovate and enhance products, services, security and processes.
- The integration of BBVA's businesses into PNC and PNC Bank.
PNC’s balance sheet at December 31, 2021 includes balances from BBVA.
- Net interest income increased $0.7 billion, or 7%, to $10.6 billion, including the benefit of BBVA.
- Net interest margin decreased to 2.29% for 2021 compared to 2.53% for 2020.
- Noninterest income increased $1.6 billion, or 23%, to $8.6 billion, primarily due to the benefit of BBVA and higher merger and acquisition advisory fees.
- Provision recapture was $0.8 billion in 2021, driven by portfolio changes, including improved credit quality and changes in portfolio composition, along with the impact from an improved economic environment, partially offset by the additional provision for credit losses related to the BBVA acquisition.
In comparison to December 31, 2020, changes in our balance sheet were primarily driven by the BBVA acquisition.
- Total assets increased $90.5 billion, or 19%, to $557.2 billion.
- Total commercial loans grew $25.9 billion, or 15%, to $193.1 billion, driven by BBVA loans and organic growth in PNC's corporate banking and business credit businesses, partially offset by PPP loan forgiveness.
- Investment securities increased $44.2 billion, or 50%, to $133.0 billion due to increased purchase activity and securities from BBVA.
- Total deposits increased $91.9 billion, or 25%, to $457.3 billion, reflecting deposits from BBVA and growth in consumer and commercial liquidity.
- Borrowed funds of $30.8 billion decreased $6.4 billion, or 17%, due to lower bank notes and senior debt and lower FHLB borrowings, reflecting the use of liquidity from deposit growth, which more than offset borrowed funds from BBVA.
We maintained solid credit quality metrics in 2021.
- Nonperforming assets of $2.5 billion increased $169 million, or 7%, due to nonperforming assets from BBVA, partially offset by lower PNC legacy nonperforming assets reflecting improved credit performance.
- Overall loan delinquencies of $2.0 billion increased $622 million, or 46%, as lower delinquencies in the PNC legacy portfolio were more than offset by delinquencies attributable to BBVA, including increases from BBVA conversion-related administrative and operational delays.
The decrease was primarily driven by impacts from portfolio changes and an improved economic environment, partially offset by the addition of reserves related to the BBVA acquisition.
Commercial loan net charge-offs increased $15 million and consumer loan net charge-offs decreased $190 million compared to 2020.
- Capital was impacted by our election of a five-year transition period for CECL’s estimated impact on CET1 capital.
The estimated CECL impact was added to CET1 capital through December 31, 2021 and will be phased-out over the following three years.
- Common shareholders' equity increased to $50.7 billion at December 31, 2021, compared to $50.5 billion at December 31, 2020.
- In June 2021, we announced the reinstatement of share repurchase programs with repurchases of up to $2.9 billion for the four-quarter period beginning in the third quarter of 2021.
- The U.S. economy continues to recover from the pandemic-caused recession in the first half of 2020.
Growth is likely to be softer in the first quarter of 2022 due to the omicron variant, and then pick up in the spring, remaining above the economy’s long-run average throughout this year.
Consumer spending growth will remain solid in 2022 due to good underlying fundamentals.
- Supply-chain difficulties, which weighed on growth in the second half of 2021, will gradually ease over the course of 2022.
Labor shortages will remain a constraint this year, although strong wage growth will support consumer spending.
- Inflation accelerated in the second half of 2021 to its fastest pace in decades due to strong demand but limited supplies coming out of the pandemic for some goods and services.
Inflation will slow in 2022 as supply and demand for these goods and services normalize, but also broaden throughout the economy due to wage growth.
Inflation will end 2022 above the Federal Reserve’s long-run objective of 2%.
- PNC expects the FOMC to raise the federal funds rate by 0.25 percentage points five times in 2022 to reach a range of 1.25% to 1.50% by the end of the year, and then further increase the federal funds rate in 2023.
The Federal Reserve will also end its purchases of long-term Treasuries and mortgage-backed securities in March 2022, and then start to reduce its balance sheet in mid-2022.
Full year guidance for 2022 includes the impact of twelve months of BBVA operations compared to seven months in 2021.
- Average loan growth of approximately 10%,
- Revenue growth to be 8% to 10% (we now expect revenue growth to be on the higher end of this range based on our revised projection of the number of increases to the federal funds rate in 2022),
- Expenses, excluding integration expense, to be up 4% to 6%,
- To generate positive operating leverage.
Additionally, as of year-end 2021, actions that will drive our $900 million of anticipated savings related to the BBVA acquisition have been substantially completed, and we expect the savings to be fully realized in 2022.
| | | | 2021 | | | | | | | | | | | | 2020 | | | | | | | | |
| Loans | | | 268,696 | | | 3.37 | | % | 9,060 | | | | | | 252,633 | | | 3.55 | | % | 8,979 | | |
An excerpt. Shown here: 40 of 743 rewritten, 40 of 385 added and 40 of 338 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (MD&A) in the FY2022 filing and the FY2021 filing.
Item 1. BUSINESS
100 rewritten, 26 added, 29 removed, 299 unchanged
[removed: We also have strategic international offices in four countries outside the U.S.] At December 31, [removed: 2021,] [added: 2022,] our consolidated total assets, total deposits and total shareholders’ equity were [removed: $557.2] [added: $557.3] billion, [removed: $457.3] [added: $436.3] billion and [removed: $55.7] [added: $45.8] billion, respectively.
Our results [added: of operations and balance sheets] for [removed: the twelve months ended December 31, 2021] [added: all periods presented in this Report] reflect the benefit of BBVA’s acquired [removed: business operations] [added: businesses] for the period since the acquisition closed on June 1, 2021.
For additional information on the acquisition of BBVA, see Note 2 Acquisition and Divestiture [removed: Activity in the Notes to Consolidated Financial Statements included in Item 8 of this Report.][added: Activity.]
For additional details on the divestiture of our equity investment in BlackRock, see Note 2 Acquisition and Divestiture [removed: Activity in the Notes to Consolidated Financial Statements in Item 8 of this Report.][added: Activity.]
Our corporate legal structure at December 31, [removed: 2021] [added: 2022] consisted of one domestic subsidiary bank, including its subsidiaries, and [removed: 54] [added: 59] active non-bank subsidiaries, in addition to various affordable housing investments and historic rehabilitation investments.
Our bank subsidiary is PNC Bank, a national bank [removed: headquartered] [added: chartered] in [removed: Pittsburgh, Pennsylvania.][added: Wilmington, Delaware.]
The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* 1
| Average Consolidated Balance Sheet And Net Interest Analysis | | | [removed: 187] [added: 190] | | |
| Analysis Of Year-To-Year Changes In Net Interest Income | | | [removed: 188] [added: 191] | | |
| Selected Loan Maturities And Interest Sensitivity | | | [removed: 190] [added: 192] | | |
| Credit Ratios | | | [removed: 66, 70] [added: 65, 69] and [removed: 71] [added: 70] | | |
| Allocation Of Allowance For Credit Losses | | | [removed: 70] [added: 69] | | |
| Average Amount And Average Rate Paid On Deposits | | | [removed: 187] [added: 190] | | |
| Uninsured Deposits and Time Deposits | | | [removed: 190] [added: 193] | | |
See Note 20 Regulatory Matters [removed: in the Notes to Consolidated Financial Statements in Item 8 of this Report] for additional information regarding our regulatory matters.
2 The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K*
Among the areas that have been receiving a high level of regulatory focus are compliance with the BSA and anti-money laundering laws, capital and liquidity management (including stress testing), the structure and effectiveness of enterprise risk management frameworks, the [removed: management of risks associated with the COVID-19 pandemic, the] protection of confidential customer information, [removed: cyber security,] [added: cybersecurity,] the oversight of arrangements with third-party vendors and suppliers, and compliance with fair lending and other consumer protection laws and regulations, including those governing retail sales practices, fee disclosures, unfair, deceptive or abusive acts or practices, collection practices, [removed: and] protections for military service members and individuals in [removed: bankruptcy.][added: bankruptcy, and the management of risks associated with the Paycheck Protection Program we participated in to help businesses mitigate the impact of the COVID-19 pandemic.]
See [removed: also] the additional information included as Risk Factors in Item 1A of this Report discussing the impact of financial regulatory initiatives on the regulatory environment for us and the financial services industry.
The agencies’ regulatory capital rules have undergone significant change since 2013, when the agencies adopted final rules to implement the Basel Committee’s international regulatory capital framework, known as “Basel III”, as well as certain provisions of [removed: the Dodd-Frank Act.][added: Dodd-Frank.]
[removed: In 2019, the] [added: The] federal banking agencies [removed: adopted rules to better] tailor the application of their capital, liquidity and enhanced prudential requirements for banking organizations to the asset size and risk profile (as measured by certain regulatory metrics) of the banking [removed: organization (the “2019 Tailoring Rules”).][added: organization.]
[removed: Effective January 1, 2020, the] [added: The] agencies’ capital and liquidity rules classify all BHCs with $100 billion or more in total assets into one of four categories (Category I, Category II, Category III and Category IV), with the most stringent capital and liquidity requirements applying to Category I firms and the least restrictive requirements applying to Category IV firms.
As of December 31, [removed: 2021,] [added: 2022,] PNC had cross-jurisdictional activities for these purposes of [removed: $21.4] [added: $24.1] billion.
CET1 capital is generally common stock, retained earnings, and qualifying minority [removed: interest] [added: interests] less required deductions.
Under the regulatory capital rules, PNC and PNC Bank must deduct investments in unconsolidated financial institutions, MSRs and deferred tax assets (in each case, net of associated deferred tax liabilities) from CET1 capital to the extent such [removed: items] [added: categories] individually [added: exceed 25% of the institution’s adjusted CET1 capital.]
The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* 3
As of December 31, [removed: 2021,] [added: 2022,] PNC and PNC Bank’s investments in unconsolidated financial institutions, MSRs and deferred tax assets did not exceed this threshold.
The agencies’ capital rules also permit banking organizations to elect to phase-in, on a straight-line basis over a three-year period, the day-one regulatory capital effects of implementing the Financial Accounting Standards Board’s ASU 2016-13 [removed: Financial Instruments] - [removed: Credit Losses (Topic 326), commonly referred to as the CECL standard.][added: *Financial Instruments*]
Separately, the [removed: federal banking agencies adopted a rule that permits] [added: rules permit] banking organizations that [removed: are] [added: were] subject to CECL during 2020 to delay CECL’s estimated impact on CET1 capital.
PNC and PNC Bank [removed: have] elected this five-year transition period effective March 31, 2020, which impacts the regulatory capital ratios disclosed in this Report.
See Note 1 Accounting Policies [removed: in the Notes to Consolidated Financial Statements in Item 8 of this Report] for more detail on [removed: the] CECL [removed: standard.][added: and the ACL.]
PNC and PNC Bank are required to use the standardized approach for determining [removed: a banking organization’s] risk-weighted assets for purposes of calculating the risk-based capital ratios.
Based on PNC’s performance under the Federal Reserve’s supervisory stress tests as part of CCAR [removed: 2021,] [added: 2022,] PNC’s SCB for the period from the fourth quarter of [removed: 2021] [added: 2022] through the third quarter of [removed: 2022] [added: 2023] was set at [removed: 2.5%.][added: 2.9%.]
PNC and PNC Bank must maintain risk-based capital above the minimum risk-based capital ratio requirements plus its SCB (in the case of PNC) or capital conservation buffer (in the case of PNC Bank) in order to avoid limitations on capital distributions, including dividends and repurchases of any Tier 1 capital instrument, such as common and qualifying preferred [removed: stock] [added: stock,] and certain discretionary incentive compensation payments.
As a result, [added: to avoid limitations on capital distributions and certain discretionary incentive compensation payments,] PNC [added: must maintain a CET1 capital ratio of at least 7.4%, a Tier 1 capital ratio of at least 8.9%,] and [added: a Total capital ratio of at least 10.9%, and] PNC Bank must maintain a CET1 capital ratio of at least 7.0%, a Tier 1 capital ratio of at least 8.5%, and a Total capital ratio of at least [removed: 10.5% to avoid limitations on capital distributions and certain discretionary incentive compensation payments.][added: 10.5%.]
For Category III banking organizations (such as PNC and PNC Bank), the Federal Reserve [added: and OCC] can supplement these higher SCB or capital conservation buffer levels above the regulatory minimums by a countercyclical capital buffer of up to an additional 2.5% of risk-weighted assets.
This buffer, which must be held in the form of CET1 capital, is currently set at zero in the U.S. A Federal Reserve policy statement establishes the framework and factors the Federal Reserve would use in setting and adjusting the amount of [added: the U.S. countercyclical capital buffer.]
4 The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K*
Banking organizations are required to maintain a minimum leverage ratio of Tier 1 capital to total assets of 4.0%, and Category III banking organizations must maintain a minimum supplementary leverage ratio of [removed: 3.0%.]
As of December 31, [removed: 2021,] [added: 2022,] the leverage and supplementary leverage ratios of PNC and PNC Bank were above the required minimum level.
However, it is possible that the agencies will consider applying one or more of these requirements in the future to [removed: a larger subset of] [added: additional] BHCs or insured depository institutions like PNC and PNC Bank.
We also have strategic international offices in Canada, China, Germany and the United Kingdom.
More than 99% of the assets of PNC are held in its domestic bank subsidiary, PNC Bank, a national banking association chartered and located in Wilmington, Delaware.
In September 2022, the federal banking agencies announced their intent to revise U.S. regulatory capital requirements to align them with the international standards finalized by the Basel Committee in December 2017, which include, among other items, changes to the standardized approach for credit risk, the credit valuation adjustment risk framework, operational risk framework and the leverage ratio framework.
These changes could increase capital requirements for U.S. banking organizations, including PNC.
*\- Credit Losses* (Topic 326), commonly referred to as the CECL standard.
3.0%.
In October 2022, the Federal Reserve and FDIC jointly issued an advance notice of proposed rulemaking to solicit input on potential changes to the resolution-related requirements applicable to large banking organizations like PNC that are not GSIBs, including a requirement to maintain loss-absorbing capacity at the bank or holding company in the form of long-term debt.
In May 2022, the federal banking agencies issued a notice of proposed rulemaking to amend the regulations implementing the CRA.
The proposal, among other things, would significantly expand the number of areas in which a bank is evaluated under the CRA, change the tests used to evaluate a bank in those areas, and expand the data a bank must collect and report.
We expect the federal banking agencies to finalize revisions to the regulations implementing the CRA in 2023, which may increase PNC Bank’s obligations and compliance costs necessary to achieve a “Satisfactory” or “Outstanding” rating.
In reviewing the merger of BHCs, the acquisition of banks or the acquisition of voting securities of a
PNC filed a targeted resolution plan in December 2021 and received feedback from the agencies in December 2022 that did not identify any shortcomings or deficiencies in PNC’s plan.
In addition to the proposed long-term debt requirements noted above, the Federal Reserve’s and FDIC’s October 2022 advance notice of proposed rulemaking solicited input on other potential changes to the resolution-related requirements applicable to large banking organizations like PNC that are not GSIBs.
The advance notice of proposed rulemaking solicited comments and posed specific questions on whether to impose GSIB-like resolution requirements on large banking organizations that are not GSIBs, including a “clean holding company” requirement that would prohibit top-tier holding companies from entering certain financial arrangements (such as short-term borrowing or derivative contracts), separability requirements, the Federal Reserve’s supervisory guidance on recovery planning, and certain disclosure requirements currently applicable to GSIBs.
Such requirements could, among other things, increase PNC’s borrowing costs, require the implementation of new operational capabilities, and require changes to PNC’s resolution strategies at the holding company level and bank level.
PNC Bank filed its resolution plan in December 2022 and is awaiting feedback from the FDIC.
supervisory role with respect to PNC Bank’s derivatives and foreign exchange businesses.
Additionally, our Corporate Diversity Council is co-chaired by our Chief Executive Officer and Chief Diversity Officer and includes senior leaders from across the organization.
The council is responsible for overseeing strategic corporate initiatives that impact the creation and sustainment of an inclusive corporate culture and a talented, diverse workforce.
December 31, 2022.
We support the transition to a low-carbon economy by striving to manage our physical footprint in a sustainable manner, incorporating climate-related risk considerations into our ERM framework, integrating responsible investing strategies into our investment and portfolio management practices, and helping clients finance their own sustainability goals.
These tenets have been incorporated into our Climate Action Strategy that was formalized at the start of 2022 to set us on a pathway to finance the transition to a low-carbon economy.
Our approach will be iterative and flexible, highlighting five main areas: employee engagement; long-term collaboration with stakeholders, external partners and industry groups; support for our customers’ transition plans; executing on our own operation sustainability goals; and portfolio alignment over time, emphasizing climate risk identification and management, and financed emissions calculations as initial work sets.
PNC’s recently established Climate Risk Committee specifically oversees the integration of climate-related risks into the ERM Framework.
Physical risks arise from risks associated with natural perils, such as hurricanes, fires, floods and drought.
investor.relations@pnc.com for copies of exhibits, including financial statement and schedule exhibits where applicable.
PNC's balance sheet at December 31, 2021 includes balances from BBVA.
New legislation, changes in rules promulgated by federal financial regulators, other federal and state regulatory authorities and self-regulatory organizations, or changes in the interpretation or enforcement of existing laws and rules, may directly affect the operations and profitability of our businesses.
We anticipate new legislative and regulatory initiatives over the next several years, focused specifically on banking and other financial services in which we are engaged.
Legislative and regulatory developments to date, as well as those that come in the future, have had and are likely to continue to have an impact on the conduct of our business.
The more detailed description of the significant regulations to which we are subject included in this Report is based on current laws and regulations and is subject to potentially material change.
exceed 25% of the institution’s adjusted CET1 capital.
Because PNC’s SCB is established as part of the CCAR process, and is based on PNC’s projected performance (as determined by the Federal Reserve) under the relevant supervisory severely adverse scenario (which can change, potentially materially, from stress test to stress test), PNC’s SCB may vary, potentially materially, over time and, thus, PNC may be required to maintain capital above these levels to avoid limitations on capital distributions and certain discretionary incentive compensation payments.
the U.S. countercyclical capital buffer.
At December 31, 2021, the LCR for PNC and PNC Bank exceeded the required minimum levels.
At December 31, 2021, the NSFR for PNC and PNC Bank exceeded the required minimum levels.
Source of Parent Company Liquidity and Dividends.
Notes to Consolidated Financial Statements in Item 8 of this Report.
The Federal Reserve is required to impose a maximum 15-to-1 debt to equity ratio on a BHC if the federal agencies that comprise the FSOC determine that the company poses a grave threat to the financial stability of the U.S. and that the imposition of such a debt-to-equity requirement would mitigate such risk.
The Federal Reserve also is required to establish early remediation requirements for BHCs with more than $250 billion in total assets and continues to work towards finalizing these requirements.
To date, the prohibitions under the final Volcker Rule regulations have not had a material effect on our businesses or revenue.
PNC filed a targeted resolution plan in December 2021.
PNC Bank’s next resolution plan is due in December 2022.
In addition, certain changes in the activities of a broker-dealer require approval from FINRA,
In regard to recruiting and retaining talent amid an ever-changing landscape, we have set an objective of making long-
term flexibility a differentiator for PNC.
Our flexible workforce model includes personnel in fully remote, fully on-site and hybrid (mix of remote/on-site) positions based on role and job responsibilities.
Our approach to flexibility will evolve as we learn and evaluate what works best for our employees and PNC.
PNC continues to recognize the impacts that the COVID-19 pandemic has had and will likely continue to have on our human capital.
We are monitoring the status of the pandemic nationally and locally and continue to prioritize the safety and well-being of our employees, while complying with all state and local health mandates and managing in accordance with Center for Disease Control guidelines.
Our various strategies and policies in place to promote the health and safety of our employees who need to be on-site to execute their job responsibilities continue to evolve.
PNC’s sustainability and climate change strategy is based on a four-pronged approach: (i) maintaining risk management controls that incorporate climate change considerations, (ii) managing our internal operations in a sustainable manner, (iii) helping our clients finance their sustainable operations and (iv) managing capital for our clients in responsible ways.
We adapt this approach based on best practices as we learn what works for PNC and our stakeholders.
PNC has also developed a carbon intensity score, which is a top-down assessment of the carbon intensity of our loan portfolio.
Aligning with qualitative assessments of carbon intensities within industries, the carbon intensity scores are primarily used as a high-level benchmarking and portfolio trend tool.
An excerpt. Shown here: 40 of 100 rewritten, all 26 added and all 29 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2022 filing and the FY2021 filing.
Item 3. LEGAL PROCEEDINGS
1 rewritten, 0 added, 0 removed, 0 unchanged
See the information set forth in Note 21 Legal [removed: Proceedings in the Notes to Consolidated Financial Statements in Item 8 of this Report,] [added: Proceedings,] which is incorporated here by reference.
Cover and table of contents
166 rewritten, 37 added, 34 removed, 125 unchanged
For the fiscal year ended December 31, [removed: 2021][added: 2022]
The aggregate market value of the registrant’s outstanding voting common stock held by nonaffiliates on June 30, [removed: 2021,] [added: 2022,] determined using the per share closing price on that date on the New York Stock Exchange of [removed: $190.76,] [added: $157.77,] was approximately [removed: $80.8] [added: $64.6] billion.
Number of shares of registrant’s common stock outstanding at February [removed: 4, 2022: 418,454,799][added: 3, 2023: 399,682,159]
Portions of the definitive Proxy Statement of The PNC Financial Services Group, Inc. to be filed pursuant to Regulation 14A for the [removed: 2022] [added: 2023] annual meeting of shareholders (Proxy Statement) are incorporated by reference into Part III of this Form 10-K.
Cross-Reference Index to [removed: 2021] [added: 2022] Form 10-K
| Item 1 | | | [removed: [Business.](#iaa6d7aa2f870454da9ce69c37ef5dad0_13)] [added: [Business.](#ib4bdc01166af494b81c4833469b4fe36_13)] | | | [removed: [1](#iaa6d7aa2f870454da9ce69c37ef5dad0_13)] [added: [1](#ib4bdc01166af494b81c4833469b4fe36_13)] | | |
| Item 1A | | | [Risk [removed: Factors.](#iaa6d7aa2f870454da9ce69c37ef5dad0_16)] [added: Factors.](#ib4bdc01166af494b81c4833469b4fe36_16)] | | | [removed: [15](#iaa6d7aa2f870454da9ce69c37ef5dad0_16)] [added: [15](#ib4bdc01166af494b81c4833469b4fe36_16)] | | |
| Item 1B | | | [Unresolved Staff [removed: Comments.](#iaa6d7aa2f870454da9ce69c37ef5dad0_19)] [added: Comments.](#ib4bdc01166af494b81c4833469b4fe36_19)] | | | [removed: [32](#iaa6d7aa2f870454da9ce69c37ef5dad0_19)] [added: [31](#ib4bdc01166af494b81c4833469b4fe36_19)] | | |
| Item 2 | | | [removed: [Properties.](#iaa6d7aa2f870454da9ce69c37ef5dad0_22)] [added: [Properties.](#ib4bdc01166af494b81c4833469b4fe36_22)] | | | [removed: [32](#iaa6d7aa2f870454da9ce69c37ef5dad0_22)] [added: [31](#ib4bdc01166af494b81c4833469b4fe36_22)] | | |
| Item 3 | | | [Legal [removed: Proceedings.](#iaa6d7aa2f870454da9ce69c37ef5dad0_25)] [added: Proceedings.](#ib4bdc01166af494b81c4833469b4fe36_25)] | | | [removed: [32](#iaa6d7aa2f870454da9ce69c37ef5dad0_25)] [added: [31](#ib4bdc01166af494b81c4833469b4fe36_25)] | | |
| Item 4 | | | [Mine Safety [removed: Disclosures.](#iaa6d7aa2f870454da9ce69c37ef5dad0_28)] [added: Disclosures.](#ib4bdc01166af494b81c4833469b4fe36_28)] | | | [removed: [32](#iaa6d7aa2f870454da9ce69c37ef5dad0_28)] [added: [31](#ib4bdc01166af494b81c4833469b4fe36_28)] | | |
| [Information about our Executive [removed: Officers](#iaa6d7aa2f870454da9ce69c37ef5dad0_31)] [added: Officers](#ib4bdc01166af494b81c4833469b4fe36_31)] | | | | | | [removed: [33](#iaa6d7aa2f870454da9ce69c37ef5dad0_31)] [added: [32](#ib4bdc01166af494b81c4833469b4fe36_31)] | | |
| Item 5 | | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities.](#iaa6d7aa2f870454da9ce69c37ef5dad0_37)] [added: Securities.](#ib4bdc01166af494b81c4833469b4fe36_37)] | | | [removed: [34](#iaa6d7aa2f870454da9ce69c37ef5dad0_37)] [added: [33](#ib4bdc01166af494b81c4833469b4fe36_37)] | | |
| | | | [Common Stock Performance [removed: Graph](#iaa6d7aa2f870454da9ce69c37ef5dad0_40)] [added: Graph](#ib4bdc01166af494b81c4833469b4fe36_40)] | | | [removed: [36](#iaa6d7aa2f870454da9ce69c37ef5dad0_40)] [added: [35](#ib4bdc01166af494b81c4833469b4fe36_40)] | | |
| Item 7 | | | [Management’s Discussion and Analysis of Financial Condition and Results of Operations [removed: (MD&A).](#iaa6d7aa2f870454da9ce69c37ef5dad0_46)] [added: (MD&A).](#ib4bdc01166af494b81c4833469b4fe36_46)] | | | [removed: [38](#iaa6d7aa2f870454da9ce69c37ef5dad0_46)] [added: [36](#ib4bdc01166af494b81c4833469b4fe36_46)] | | |
| | | | [Executive [removed: Summary](#iaa6d7aa2f870454da9ce69c37ef5dad0_49)] [added: Summary](#ib4bdc01166af494b81c4833469b4fe36_49)] | | | [removed: [38](#iaa6d7aa2f870454da9ce69c37ef5dad0_49)] [added: [36](#ib4bdc01166af494b81c4833469b4fe36_49)] | | |
| | | | [Consolidated Income Statement [removed: Review](#iaa6d7aa2f870454da9ce69c37ef5dad0_52)] [added: Review](#ib4bdc01166af494b81c4833469b4fe36_52)] | | | [removed: [42](#iaa6d7aa2f870454da9ce69c37ef5dad0_52)] [added: [42](#ib4bdc01166af494b81c4833469b4fe36_52)] | | |
| | | | [Consolidated Balance Sheet [removed: Review](#iaa6d7aa2f870454da9ce69c37ef5dad0_70)] [added: Review](#ib4bdc01166af494b81c4833469b4fe36_67)] | | | [removed: [45](#iaa6d7aa2f870454da9ce69c37ef5dad0_70)] [added: [44](#ib4bdc01166af494b81c4833469b4fe36_67)] | | |
| | | | [Business Segments [removed: Review](#iaa6d7aa2f870454da9ce69c37ef5dad0_88)] [added: Review](#ib4bdc01166af494b81c4833469b4fe36_85)] | | | [removed: [49](#iaa6d7aa2f870454da9ce69c37ef5dad0_88)] [added: [48](#ib4bdc01166af494b81c4833469b4fe36_85)] | | |
| | | | [Critical Accounting Estimates and [removed: Judgments](#iaa6d7aa2f870454da9ce69c37ef5dad0_190)] [added: Judgments](#ib4bdc01166af494b81c4833469b4fe36_187)] | | | [removed: [82](#iaa6d7aa2f870454da9ce69c37ef5dad0_190)] [added: [81](#ib4bdc01166af494b81c4833469b4fe36_187)] | | |
| | | | [Cautionary Statement Regarding Forward-Looking [removed: Information](#iaa6d7aa2f870454da9ce69c37ef5dad0_196)] [added: Information](#ib4bdc01166af494b81c4833469b4fe36_193)] | | | [removed: [84](#iaa6d7aa2f870454da9ce69c37ef5dad0_196)] [added: [84](#ib4bdc01166af494b81c4833469b4fe36_193)] | | |
| Item 7A | | | [Quantitative and Qualitative Disclosures about Market [removed: Risk](#iaa6d7aa2f870454da9ce69c37ef5dad0_199)] [added: Risk](#ib4bdc01166af494b81c4833469b4fe36_196)] | | | [removed: [86](#iaa6d7aa2f870454da9ce69c37ef5dad0_199)] [added: [85](#ib4bdc01166af494b81c4833469b4fe36_196)] | | |
| Item 8 | | | [Financial Statements and Supplementary [removed: Data](#iaa6d7aa2f870454da9ce69c37ef5dad0_202)] [added: Data](#ib4bdc01166af494b81c4833469b4fe36_199)] | | | [removed: [86](#iaa6d7aa2f870454da9ce69c37ef5dad0_202)] [added: [85](#ib4bdc01166af494b81c4833469b4fe36_199)] | | |
| | | | [Report of Independent Registered Public Accounting [removed: Firm](#iaa6d7aa2f870454da9ce69c37ef5dad0_205)] [added: Firm](#ib4bdc01166af494b81c4833469b4fe36_202)] | | | [removed: [87](#iaa6d7aa2f870454da9ce69c37ef5dad0_205)] [added: [86](#ib4bdc01166af494b81c4833469b4fe36_202)] | | |
| | | | [Consolidated [removed: Income Statement](#iaa6d7aa2f870454da9ce69c37ef5dad0_208)] [added: Statement of Comprehensive Income](#ib4bdc01166af494b81c4833469b4fe36_208)] | | | [removed: [90](#iaa6d7aa2f870454da9ce69c37ef5dad0_208)] [added: [89](#ib4bdc01166af494b81c4833469b4fe36_208)] | | |
| | | | [Consolidated Balance [removed: Sheet](#iaa6d7aa2f870454da9ce69c37ef5dad0_214)] [added: Sheet](#ib4bdc01166af494b81c4833469b4fe36_211)] | | | [removed: [92](#iaa6d7aa2f870454da9ce69c37ef5dad0_214)] [added: [90](#ib4bdc01166af494b81c4833469b4fe36_211)] | | |
| | | | [Consolidated Statement of Changes in [removed: Equity](#iaa6d7aa2f870454da9ce69c37ef5dad0_217)] [added: Equity](#ib4bdc01166af494b81c4833469b4fe36_214)] | | | [removed: [93](#iaa6d7aa2f870454da9ce69c37ef5dad0_217)] [added: [91](#ib4bdc01166af494b81c4833469b4fe36_214)] | | |
| | | | [Consolidated Statement of Cash [removed: Flows](#iaa6d7aa2f870454da9ce69c37ef5dad0_220)] [added: Flows](#ib4bdc01166af494b81c4833469b4fe36_220)] | | | [removed: [94](#iaa6d7aa2f870454da9ce69c37ef5dad0_220)] [added: [92](#ib4bdc01166af494b81c4833469b4fe36_220)] | | |
| | | | [Notes to [removed: Consolidated](#iaa6d7aa2f870454da9ce69c37ef5dad0_223) [Financial Statements](#iaa6d7aa2f870454da9ce69c37ef5dad0_223)] [added: Consolidated Financial Statements](#ib4bdc01166af494b81c4833469b4fe36_223)] | | | [removed: [96](#iaa6d7aa2f870454da9ce69c37ef5dad0_223)] [added: [94](#ib4bdc01166af494b81c4833469b4fe36_223)] | | |
| | | | [Note 1 Accounting [removed: Policies](#iaa6d7aa2f870454da9ce69c37ef5dad0_226)] [added: Policies](#ib4bdc01166af494b81c4833469b4fe36_226)] | | | [removed: [96](#iaa6d7aa2f870454da9ce69c37ef5dad0_226)] [added: [94](#ib4bdc01166af494b81c4833469b4fe36_226)] | | |
| | | | [Note 2 Acquisition and Divestiture [removed: Activity](#iaa6d7aa2f870454da9ce69c37ef5dad0_235)] [added: Activity](#ib4bdc01166af494b81c4833469b4fe36_229)] | | | [removed: [111](#iaa6d7aa2f870454da9ce69c37ef5dad0_235)] [added: [111](#ib4bdc01166af494b81c4833469b4fe36_229)] | | |
| | | | [Note 3 Investment [removed: Securities](#iaa6d7aa2f870454da9ce69c37ef5dad0_244)] [added: Securities](#ib4bdc01166af494b81c4833469b4fe36_256)] | | | [removed: [115](#iaa6d7aa2f870454da9ce69c37ef5dad0_244)] [added: [115](#ib4bdc01166af494b81c4833469b4fe36_256)] | | |
| | | | [Note 4 Loans and Related Allowance for Credit [removed: Losses](#iaa6d7aa2f870454da9ce69c37ef5dad0_265)] [added: Losses](#ib4bdc01166af494b81c4833469b4fe36_277)] | | | [removed: [118](#iaa6d7aa2f870454da9ce69c37ef5dad0_265)] [added: [118](#ib4bdc01166af494b81c4833469b4fe36_277)] | | |
| | | | [Note 5 Loan Sale and Servicing Activities and Variable Interest [removed: Entities](#iaa6d7aa2f870454da9ce69c37ef5dad0_298)] [added: Entities](#ib4bdc01166af494b81c4833469b4fe36_304)] | | | [removed: [130](#iaa6d7aa2f870454da9ce69c37ef5dad0_298)] [added: [129](#ib4bdc01166af494b81c4833469b4fe36_304)] | | |
Cross-Reference Index to [removed: 2021] [added: 2022] Form 10-K (continued)
| | | | [Note 6 Goodwill and Mortgage Servicing [removed: Rights](#iaa6d7aa2f870454da9ce69c37ef5dad0_310)] [added: Rights](#ib4bdc01166af494b81c4833469b4fe36_316)] | | | [removed: [133](#iaa6d7aa2f870454da9ce69c37ef5dad0_310)] [added: [132](#ib4bdc01166af494b81c4833469b4fe36_316)] | | |
| | | | [Note 8 Premises, Equipment and Leasehold [removed: Improvements](#iaa6d7aa2f870454da9ce69c37ef5dad0_355)] [added: Improvements](#ib4bdc01166af494b81c4833469b4fe36_358)] | | | [removed: [137](#iaa6d7aa2f870454da9ce69c37ef5dad0_355)] [added: [136](#ib4bdc01166af494b81c4833469b4fe36_358)] | | |
| | | | [Note 13 Other Comprehensive [removed: Income](#iaa6d7aa2f870454da9ce69c37ef5dad0_400)] [added: Income](#ib4bdc01166af494b81c4833469b4fe36_403)] | | | [removed: [143](#iaa6d7aa2f870454da9ce69c37ef5dad0_400)] [added: [143](#ib4bdc01166af494b81c4833469b4fe36_403)] | | |
| | | | [Note 14 Earnings Per [removed: Share](#iaa6d7aa2f870454da9ce69c37ef5dad0_409)] [added: Share](#ib4bdc01166af494b81c4833469b4fe36_412)] | | | [removed: [144](#iaa6d7aa2f870454da9ce69c37ef5dad0_409)] [added: [144](#ib4bdc01166af494b81c4833469b4fe36_412)] | | |
| | | | [Note 15 Fair [removed: Value](#iaa6d7aa2f870454da9ce69c37ef5dad0_415)] [added: Value](#ib4bdc01166af494b81c4833469b4fe36_418)] | | | [removed: [145](#iaa6d7aa2f870454da9ce69c37ef5dad0_415)] [added: [145](#ib4bdc01166af494b81c4833469b4fe36_418)] | | |
If securities are registered pursuant to Section 12(b) of the Act, indicate by check mark whether the financial statements of the registrant included in the filing reflect the correction of an error to previously issued financial statements.
Indicate by check mark whether any of those error corrections are restatements that required a recovery analysis of incentive-based compensation received by any of the registrant’s executive officers during the relevant recovery period pursuant to §240.10D-1(b).
| Item 6 | | | [Reserved](#ib4bdc01166af494b81c4833469b4fe36_43) | | | [35](#ib4bdc01166af494b81c4833469b4fe36_43) | | |
| | | | [Risk Management](#ib4bdc01166af494b81c4833469b4fe36_100) | | | [56](#ib4bdc01166af494b81c4833469b4fe36_100) | | |
| | | | [Consolidated Income Statement](#ib4bdc01166af494b81c4833469b4fe36_205) | | | [88](#ib4bdc01166af494b81c4833469b4fe36_205) | | |
| | | | [Note 7 Leases](#ib4bdc01166af494b81c4833469b4fe36_334) | | | [134](#ib4bdc01166af494b81c4833469b4fe36_334) | | |
| | | | [Note 9 Time Deposits](#ib4bdc01166af494b81c4833469b4fe36_367) | | | [137](#ib4bdc01166af494b81c4833469b4fe36_367) | | |
| | | | [Note 10 Borrowed Funds](#ib4bdc01166af494b81c4833469b4fe36_373) | | | [137](#ib4bdc01166af494b81c4833469b4fe36_373) | | |
| | | | [Note 11 Commitments](#ib4bdc01166af494b81c4833469b4fe36_382) | | | [139](#ib4bdc01166af494b81c4833469b4fe36_382) | | |
| | | | [Note 12 Equity](#ib4bdc01166af494b81c4833469b4fe36_388) | | | [140](#ib4bdc01166af494b81c4833469b4fe36_388) | | |
| | | | [Note 22 Parent Company](#ib4bdc01166af494b81c4833469b4fe36_535) | | | [179](#ib4bdc01166af494b81c4833469b4fe36_535) | | |
| | | | [Note 23 Segment Reporting](#ib4bdc01166af494b81c4833469b4fe36_550) | | | [182](#ib4bdc01166af494b81c4833469b4fe36_550) | | |
| | | | [Note 25 Subsequent Events](#ib4bdc01166af494b81c4833469b4fe36_568) | | | [188](#ib4bdc01166af494b81c4833469b4fe36_568) | | |
| | | | [Statistical Information (Unaudited)](#ib4bdc01166af494b81c4833469b4fe36_571) | | | [190](#ib4bdc01166af494b81c4833469b4fe36_571) | | |
| | | | [Glossary](#ib4bdc01166af494b81c4833469b4fe36_601) | | | [194](#ib4bdc01166af494b81c4833469b4fe36_601) | | |
| | | | [Acronyms](#ib4bdc01166af494b81c4833469b4fe36_607) | | | [198](#ib4bdc01166af494b81c4833469b4fe36_607) | | |
| [SIGNATURES](#ib4bdc01166af494b81c4833469b4fe36_649) | | | | | | [207](#ib4bdc01166af494b81c4833469b4fe36_649) | | |
Cross-Reference Index to 2022 Form 10-K (continued)
| 1 | | | [Summary of Operations, Per Common Share Data and Performance Ratios](#ib4bdc01166af494b81c4833469b4fe36_4893) | | | [38](#ib4bdc01166af494b81c4833469b4fe36_4893) | | |
| 2 | | | [Balance Sheet Highlights and Other Selected Ratios](#ib4bdc01166af494b81c4833469b4fe36_4869) | | | [38](#ib4bdc01166af494b81c4833469b4fe36_4920) | | |
| 8 | | | [Loans](#ib4bdc01166af494b81c4833469b4fe36_73) | | | [45](#ib4bdc01166af494b81c4833469b4fe36_73) | | |
| 15 | | | [Details of Loans](#ib4bdc01166af494b81c4833469b4fe36_106) | | | [60](#ib4bdc01166af494b81c4833469b4fe36_106) | | |
| 28 | | | [PNC Bank Notes Issued](#ib4bdc01166af494b81c4833469b4fe36_151) | | | [71](#ib4bdc01166af494b81c4833469b4fe36_151) | | |
| 31 | | | [Parent Company Notes Redeemed](#ib4bdc01166af494b81c4833469b4fe36_5054) | | | [73](#ib4bdc01166af494b81c4833469b4fe36_5054) | | |
Cross-Reference Index to 2022 Form 10-K (continued)
| 61 | | | [Non-Consolidated VIEs](#ib4bdc01166af494b81c4833469b4fe36_313) | | | [131](#ib4bdc01166af494b81c4833469b4fe36_313) | | |
| 62 | | | [Goodwill by Business Segment](#ib4bdc01166af494b81c4833469b4fe36_319) | | | [132](#ib4bdc01166af494b81c4833469b4fe36_319) | | |
| 67 | | | [Lessor Income](#ib4bdc01166af494b81c4833469b4fe36_337) | | | [134](#ib4bdc01166af494b81c4833469b4fe36_337) | | |
| 76 | | | [Time Deposits](#ib4bdc01166af494b81c4833469b4fe36_370) | | | [137](#ib4bdc01166af494b81c4833469b4fe36_370) | | |
| 77 | | | [Borrowed Funds](#ib4bdc01166af494b81c4833469b4fe36_376) | | | [137](#ib4bdc01166af494b81c4833469b4fe36_376) | | |
Cross-Reference Index to 2022 Form 10-K (continued)
| 115 | | | [Basel Regulatory Capital](#ib4bdc01166af494b81c4833469b4fe36_529) | | | [174](#ib4bdc01166af494b81c4833469b4fe36_529) | | |
| 116 | | | [Parent Company - Income Statement](#ib4bdc01166af494b81c4833469b4fe36_538) | | | [179](#ib4bdc01166af494b81c4833469b4fe36_538) | | |
| 117 | | | [Parent Company - Balance Sheet](#ib4bdc01166af494b81c4833469b4fe36_541) | | | [180](#ib4bdc01166af494b81c4833469b4fe36_541) | | |
| 119 | | | [Parent Company - Statement of Cash Flows](#ib4bdc01166af494b81c4833469b4fe36_547) | | | [181](#ib4bdc01166af494b81c4833469b4fe36_547) | | |
| 120 | | | [Results of Businesses](#ib4bdc01166af494b81c4833469b4fe36_553) | | | [183](#ib4bdc01166af494b81c4833469b4fe36_553) | | |
| 121 | | | [Noninterest Income by Business Segment and Reconciliation to Consolidated Noninterest Income](#ib4bdc01166af494b81c4833469b4fe36_559) | | | [185](#ib4bdc01166af494b81c4833469b4fe36_559) | | |
| Depositary Shares Each Representing a 1/4,000 Interest in a Share of Fixed-to- Floating Rate Non-Cumulative Perpetual Preferred Stock, Series P | | | PNC P | | | New York Stock Exchange | | |
| Item 6 | | | [Selected Financial Data](#iaa6d7aa2f870454da9ce69c37ef5dad0_43) | | | [37](#iaa6d7aa2f870454da9ce69c37ef5dad0_43) | | |
| | | | [Risk Management](#iaa6d7aa2f870454da9ce69c37ef5dad0_103) | | | [57](#iaa6d7aa2f870454da9ce69c37ef5dad0_103) | | |
| | | | [Consolidated Statement of Comprehensive Income](#iaa6d7aa2f870454da9ce69c37ef5dad0_211) | | | [91](#iaa6d7aa2f870454da9ce69c37ef5dad0_211) | | |
| | | | [Note 7 Leases](#iaa6d7aa2f870454da9ce69c37ef5dad0_328) | | | [135](#iaa6d7aa2f870454da9ce69c37ef5dad0_328) | | |
| | | | [Note 9 Time Deposits](#iaa6d7aa2f870454da9ce69c37ef5dad0_364) | | | [138](#iaa6d7aa2f870454da9ce69c37ef5dad0_364) | | |
| | | | [Note 10 Borrowed Funds](#iaa6d7aa2f870454da9ce69c37ef5dad0_370) | | | [138](#iaa6d7aa2f870454da9ce69c37ef5dad0_370) | | |
| | | | [Note 11 Commitments](#iaa6d7aa2f870454da9ce69c37ef5dad0_379) | | | [140](#iaa6d7aa2f870454da9ce69c37ef5dad0_379) | | |
| | | | [Note 12 Equity](#iaa6d7aa2f870454da9ce69c37ef5dad0_385) | | | [141](#iaa6d7aa2f870454da9ce69c37ef5dad0_385) | | |
| | | | [Note 22 Parent Company](#iaa6d7aa2f870454da9ce69c37ef5dad0_526) | | | [178](#iaa6d7aa2f870454da9ce69c37ef5dad0_526) | | |
| | | | [Note 23 Segment Reporting](#iaa6d7aa2f870454da9ce69c37ef5dad0_541) | | | [180](#iaa6d7aa2f870454da9ce69c37ef5dad0_541) | | |
| | | | [Note 25 Subsequent Events](#iaa6d7aa2f870454da9ce69c37ef5dad0_5143) | | | [186](#iaa6d7aa2f870454da9ce69c37ef5dad0_5143) | | |
| | | | [Statistical Information (Unaudited)](#iaa6d7aa2f870454da9ce69c37ef5dad0_559) | | | [187](#iaa6d7aa2f870454da9ce69c37ef5dad0_559) | | |
| | | | [Glossary](#iaa6d7aa2f870454da9ce69c37ef5dad0_601) | | | [191](#iaa6d7aa2f870454da9ce69c37ef5dad0_601) | | |
| | | | [Acronyms](#iaa6d7aa2f870454da9ce69c37ef5dad0_607) | | | [195](#iaa6d7aa2f870454da9ce69c37ef5dad0_607) | | |
| [SIGNATURES](#iaa6d7aa2f870454da9ce69c37ef5dad0_649) | | | | | | [204](#iaa6d7aa2f870454da9ce69c37ef5dad0_649) | | |
| 6 | | | [Loans](#iaa6d7aa2f870454da9ce69c37ef5dad0_76) | | | [46](#iaa6d7aa2f870454da9ce69c37ef5dad0_76) | | |
| 13 | | | [Details of Loans](#iaa6d7aa2f870454da9ce69c37ef5dad0_109) | | | [62](#iaa6d7aa2f870454da9ce69c37ef5dad0_109) | | |
| 28 | | | [Contractual Obligations](#iaa6d7aa2f870454da9ce69c37ef5dad0_163) | | | [74](#iaa6d7aa2f870454da9ce69c37ef5dad0_163) | | |
| 29 | | | [Other Commitments](#iaa6d7aa2f870454da9ce69c37ef5dad0_166) | | | [74](#iaa6d7aa2f870454da9ce69c37ef5dad0_166) | | |
| 57 | | | [Rollforward of Allowance for Loan and Lease Losses and Associated Loan Data](#iaa6d7aa2f870454da9ce69c37ef5dad0_295) | | | [129](#iaa6d7aa2f870454da9ce69c37ef5dad0_295) | | |
| 60 | | | [Non-Consolidated VIEs](#iaa6d7aa2f870454da9ce69c37ef5dad0_307) | | | [132](#iaa6d7aa2f870454da9ce69c37ef5dad0_307) | | |
| 61 | | | [Goodwill by Business Segment](#iaa6d7aa2f870454da9ce69c37ef5dad0_313) | | | [133](#iaa6d7aa2f870454da9ce69c37ef5dad0_313) | | |
| 66 | | | [Lessor Income](#iaa6d7aa2f870454da9ce69c37ef5dad0_331) | | | [135](#iaa6d7aa2f870454da9ce69c37ef5dad0_331) | | |
| 75 | | | [Time Deposits](#iaa6d7aa2f870454da9ce69c37ef5dad0_367) | | | [138](#iaa6d7aa2f870454da9ce69c37ef5dad0_367) | | |
| 76 | | | [Borrowed Funds](#iaa6d7aa2f870454da9ce69c37ef5dad0_373) | | | [138](#iaa6d7aa2f870454da9ce69c37ef5dad0_373) | | |
| 114 | | | [Basel Regulatory Capital](#iaa6d7aa2f870454da9ce69c37ef5dad0_520) | | | [173](#iaa6d7aa2f870454da9ce69c37ef5dad0_520) | | |
| 115 | | | [Parent Company - Income Statement](#iaa6d7aa2f870454da9ce69c37ef5dad0_529) | | | [178](#iaa6d7aa2f870454da9ce69c37ef5dad0_529) | | |
| 116 | | | [Parent Company - Balance Sheet](#iaa6d7aa2f870454da9ce69c37ef5dad0_532) | | | [179](#iaa6d7aa2f870454da9ce69c37ef5dad0_532) | | |
| 118 | | | [Parent Company - Statement of Cash Flows](#iaa6d7aa2f870454da9ce69c37ef5dad0_538) | | | [180](#iaa6d7aa2f870454da9ce69c37ef5dad0_538) | | |
| 119 | | | [Results of Businesses](#iaa6d7aa2f870454da9ce69c37ef5dad0_544) | | | [182](#iaa6d7aa2f870454da9ce69c37ef5dad0_544) | | |
| 120 | | | [Retail Banking Noninterest Income Disaggregation](#iaa6d7aa2f870454da9ce69c37ef5dad0_550) | | | [184](#iaa6d7aa2f870454da9ce69c37ef5dad0_550) | | |
| 121 | | | [Corporate & Institutional Banking Noninterest Income Disaggregation](#iaa6d7aa2f870454da9ce69c37ef5dad0_553) | | | [185](#iaa6d7aa2f870454da9ce69c37ef5dad0_553) | | |
| 122 | | | [Asset Management Group Noninterest Income Disaggregation](#iaa6d7aa2f870454da9ce69c37ef5dad0_556) | | | [185](#iaa6d7aa2f870454da9ce69c37ef5dad0_556) | | |
An excerpt. Shown here: 40 of 166 rewritten, all 37 added and all 34 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2022 filing and the FY2021 filing.
Item 2. PROPERTIES
1 rewritten, 0 added, 0 removed, 4 unchanged
We include here by reference the additional information regarding our properties in Note 7 Leases and Note 8 Premises, Equipment and Leasehold [removed: Improvements in the Notes to Consolidated Financial Statements in Item 8 of this Report.][added: Improvements.]
Item 4. MINE SAFETY DISCLOSURES
21 rewritten, 3 added, 2 removed, 58 unchanged
[removed: 32] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [added: 31]
Information regarding each of our executive officers as of February [removed: 18, 2022] [added: 20, 2023] is set forth below.
| Carole L. Brown | | | [removed: 57] [added: 58] | | | Executive Vice President and Head of Asset Management Group | | | 2019 | | |
| Richard K. Bynum | | | [removed: 51] [added: 52] | | | Executive Vice President and Chief Corporate Responsibility Officer | | | 2005 | | |
| William S. Demchak | | | [removed: 59] [added: 60] | | | Chairman, President and Chief Executive Officer (b) | | | 2002 | | |
| Kieran J. Fallon | | | [removed: 55] [added: 56] | | | Executive Vice President and Chief Risk Officer | | | 2011 | | |
| Deborah Guild | | | [removed: 53] [added: 54] | | | Executive Vice President, Chief Information Security Officer and Head of Enterprise Technology | | | 2013 | | |
| Michael J. Hannon | | | [removed: 65] [added: 66] | | | Executive Vice President and Chief Credit Officer | | | 1982 | | |
| Vicki C. Henn | | | [removed: 53] [added: 54] | | | Executive Vice President and Chief Human Resources Officer | | | 1994 | | |
| Gregory B. Jordan | | | [removed: 62] [added: 63] | | | Executive Vice President, General Counsel, Chief Administrative Officer and Head of Regulatory and Government Affairs | | | 2013 | | |
| Stacy M. Juchno | | | [removed: 46] [added: 47] | | | Executive Vice President and General Auditor | | | 2009 | | |
| Ganesh Krishnan | | | [removed: 46] [added: 47] | | | Executive Vice President and Enterprise Chief Information Officer | | | 2008 | | |
| [removed: Karen L. Larrimer] [added: Alexander E. C. Overstrom] | | | [removed: 59] [added: 39] | | | Executive Vice [removed: President, Chief Customer Officer] [added: President] and Head of Retail Banking | | | [removed: 1995] [added: 2014] | | |
| Michael P. Lyons | | | [removed: 51] [added: 52] | | | Executive Vice President and Head of Corporate & Institutional Banking | | | 2011 | | |
| E William Parsley, III | | | [removed: 56] [added: 57] | | | Executive Vice President and Chief Operating Officer | | | 2003 | | |
| Robert Q. Reilly | | | [removed: 57] [added: 58] | | | Executive Vice President and Chief Financial Officer | | | 1987 | | |
| Gregory H. Kozich | | | [removed: 58] [added: 59] | | | Senior Vice President and Controller | | | 2010 | | |
Biographical information for Mr. Demchak is included in “Election of Directors (Item 1)” in our proxy statement to be filed for the [removed: 2022] [added: 2023] annual meeting of shareholders.
Prior to her work for the City of Chicago, Ms. Brown had a more than 25-year career as [removed: one of the leading] [added: a] municipal finance investment [removed: bankers in the country.][added: banker.]
[added: 32] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [removed: 33]
[removed: Larrimer] [added: Alexander E. C. Overstrom] was appointed Executive Vice President [removed: in 2013] and [removed: became head] [added: Head] of Retail Banking in [removed: 2016.][added: July 2022.]
| | | | | | | | | | | | |
Previously, he held numerous management roles including Head of Small Business, Deputy Head of Retail Banking, Head of Merchant Services, and Chief Operating Officer of Corporate & Institutional Banking and Asset Management.
Prior to joining PNC in 2014, he worked in strategy and investment banking at Goldman Sachs.
Karen L.
She has also served as Chief Customer Officer since April 2014, prior to which she served as Chief Marketing Officer.
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
15 rewritten, 16 added, 22 removed, 27 unchanged
Our common stock is listed on the New York Stock Exchange and is traded under the symbol “PNC.” At the close of business on February [removed: 11, 2022,] [added: 10, 2023,] there were [removed: 46,767] [added: 44,958] common shareholders of record.
For further information concerning dividend restrictions and other factors that could limit our ability to pay dividends, as well as restrictions on loans, dividends or advances from bank subsidiaries to the parent company, see the Supervision and Regulation section in Item 1, Item 1A Risk [removed: Factors,] [added: Factors and] the Liquidity and Capital Management portion of the Risk Management section in Item 7, and Note 10 Borrowed Funds, Note 12 Equity and Note 20 Regulatory [removed: Matters in the Notes to Consolidated Financial Statements in Item 8 of this Report,] [added: Matters,] which we include here by reference.
[removed: 34] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [added: 33]
We include here by reference the information regarding our compensation plans under which PNC equity securities are authorized for issuance as of December 31, [removed: 2021] [added: 2022] in the table (with introductory paragraph and notes) in Item 12 of this Report.
Details of our repurchases of PNC common stock during the fourth quarter of [removed: 2021] [added: 2022] are included in the following table:
| [removed: 2021] [added: 2022] period | | | Total shares purchased (a) | | | Average price paid per share | | | Total shares purchased as part of publicly announced programs (b) | | | Maximum number of shares that may yet be purchased under the programs (b) | | |
Note 17 Employee Benefit Plans and Note 18 Stock Based Compensation Plans [removed: in the Notes to Consolidated Financial Statements in Item 8 of this Report] include additional information regarding our employee benefit and equity compensation plans that use PNC common stock.
A maximum amount of [removed: 70.1] [added: 49.0] million shares remained available for repurchase under the new stock program authorization at December 31, [removed: 2021.][added: 2022.]
[added: 34] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [removed: 35]
This graph shows the cumulative total shareholder return (*i.e.*, price change plus reinvestment of dividends) on our common stock during the five-year period ended December 31, [removed: 2021,] [added: 2022,] as compared with: (i) a selected peer group as set forth below and referred to as the “Peer [removed: Group;”] [added: Group”;] (ii) an overall stock market index, the S&P 500 Index; and (iii) a published industry index, the S&P 500 Banks.
The stock performance graph assumes that $100 was invested at market close on December 31, [removed: 2016] [added: 2017] for the five-year period and that dividends were reinvested.
[removed: 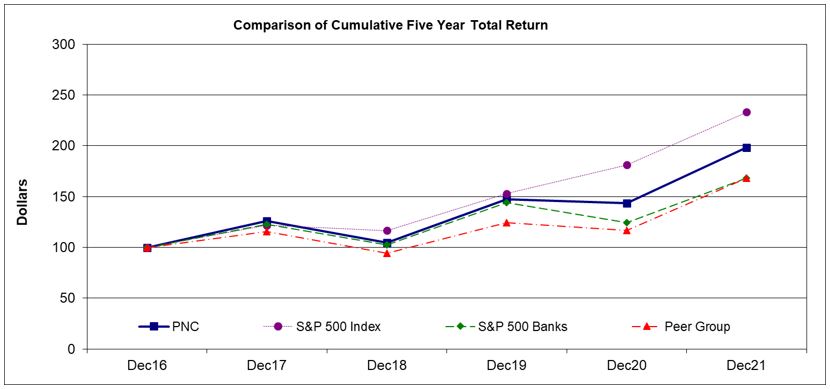][added: 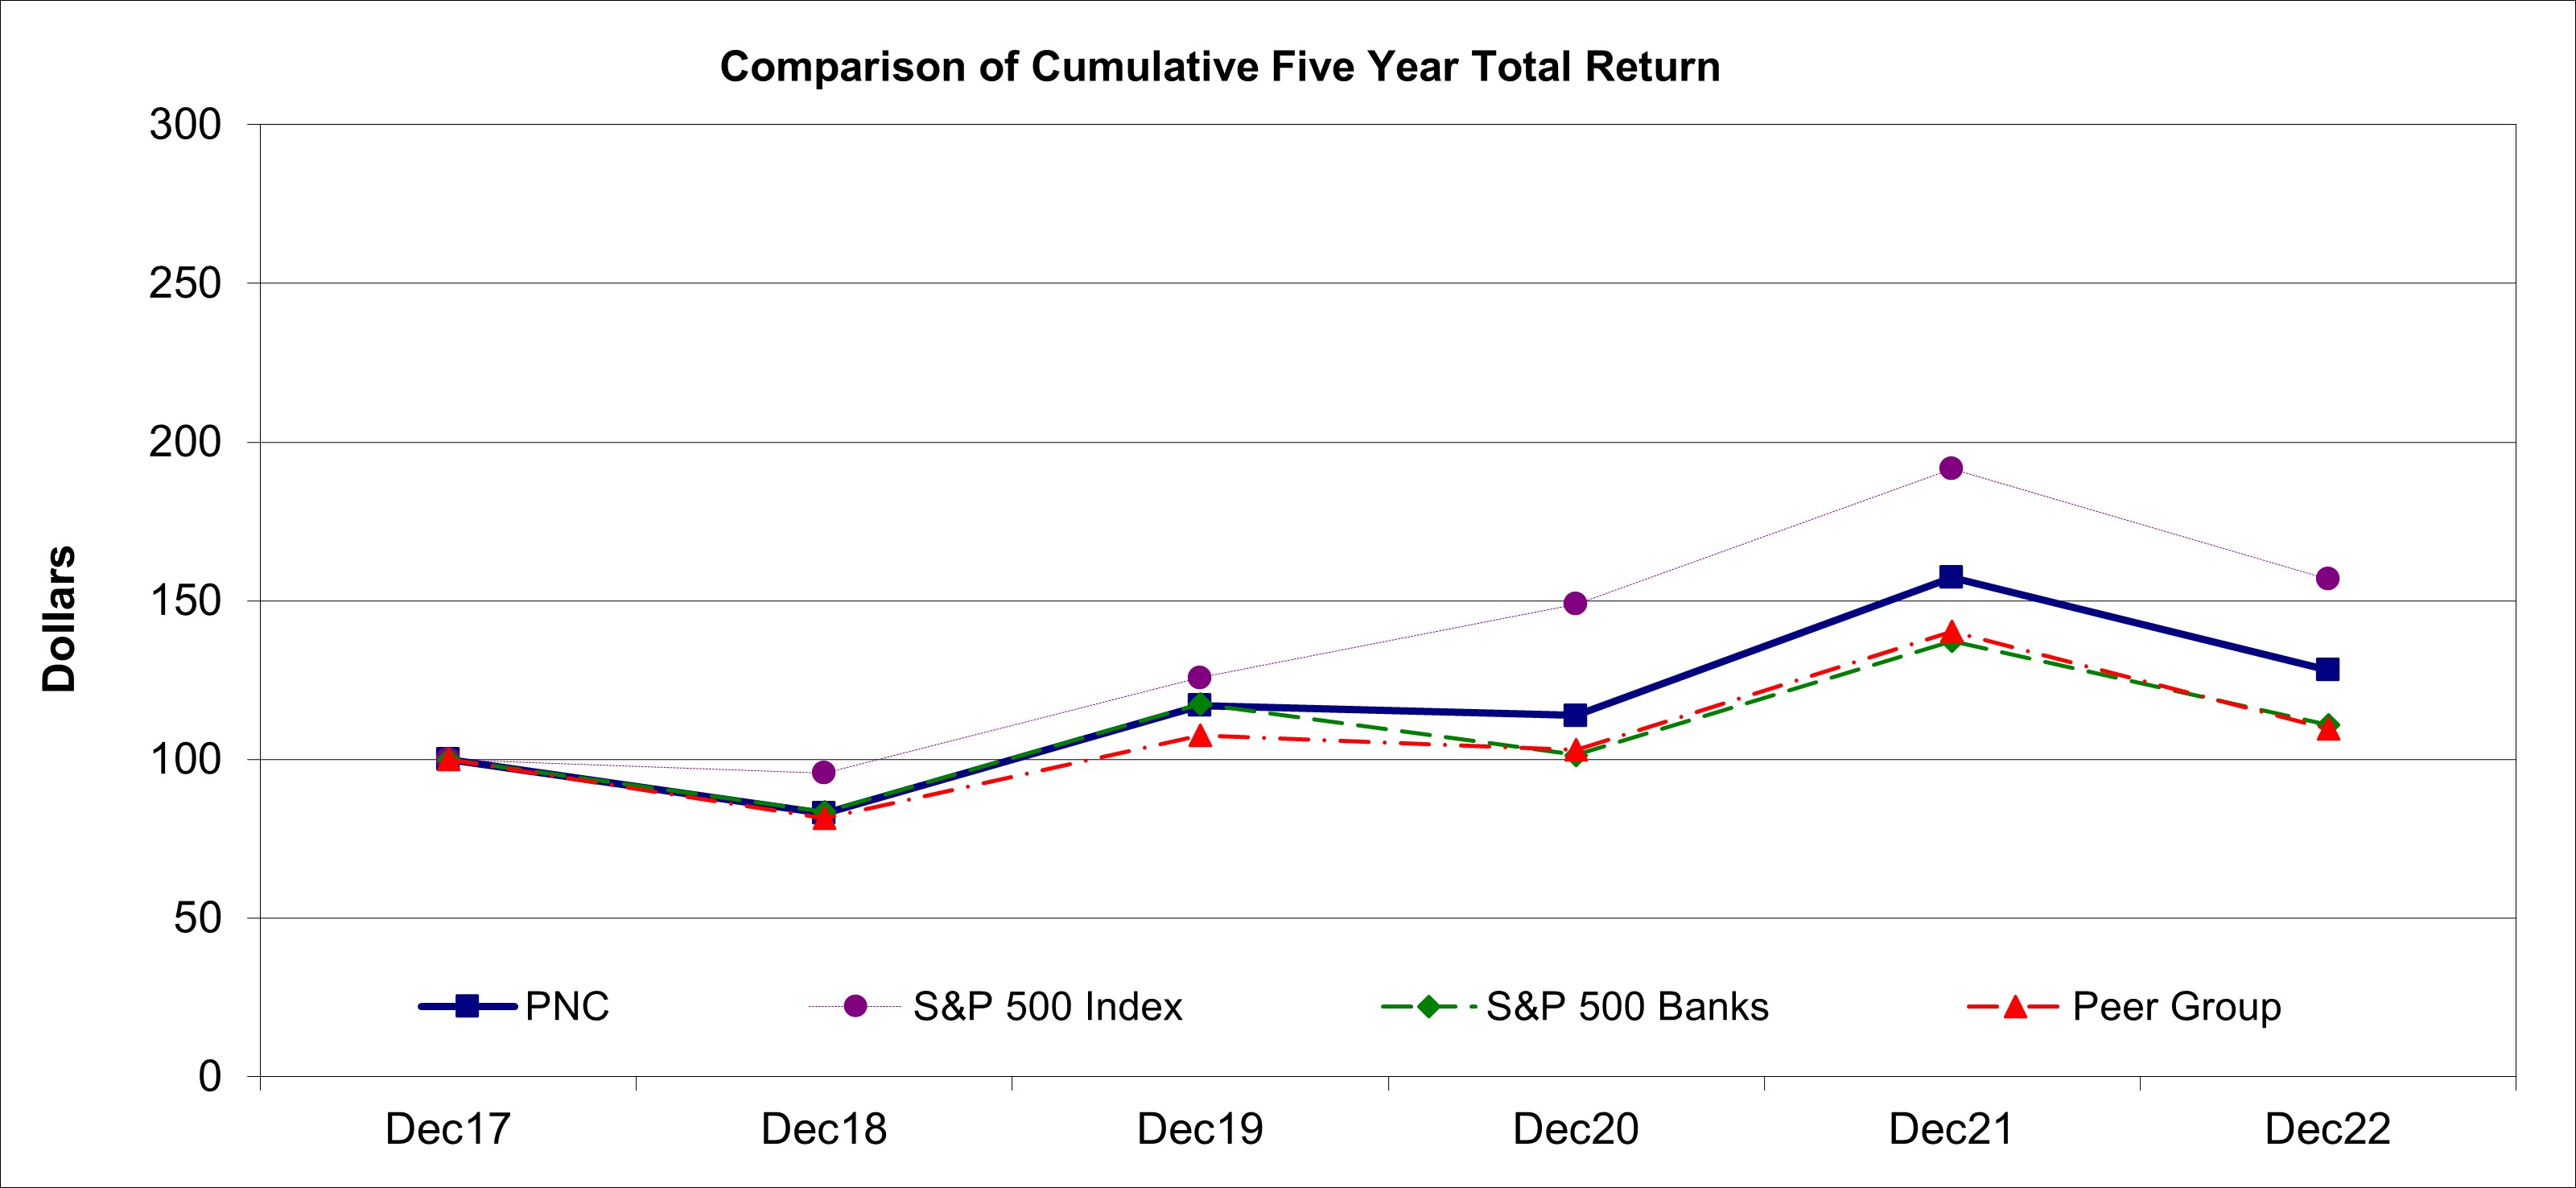]
| | | | Base Period | | | Assumes $100 investment at Close of Market on December 31, [removed: 2016] [added: 2017] Total Return = Price change plus reinvestment of dividends | | | | | | | | | | | | | | | 5-Year Compound Growth Rate | | |
| | | | Dec. [removed: 2016 | | | Dec.] 2017 | | | Dec. 2018 | | | Dec. 2019 | | | Dec. 2020 | | | Dec. 2021 | | | [added: Dec. 2022] | | | [added: | | |]
Each yearly point for the Peer Group is determined by calculating the cumulative total shareholder return for each company in the Peer Group from December 31, [removed: 2016] [added: 2017] to December 31 of that year, or the last business day of that year (End of Month Dividend Reinvestment Assumed) and then using the median of these returns as the yearly plot point.
Consistent with the SCB framework, which allows for capital return in amounts in excess of the SCB minimum levels, our Board of Directors has authorized a repurchase framework under the repurchase program approved on April 4, 2019 of up to 100 million common shares, of which approximately 49% were still available for repurchase at December 31, 2022.
Under this framework, PNC expects quarterly repurchases of up to $500 million with the ability to adjust those levels as conditions warrant.
PNC’s SCB for the four-quarter period beginning October 1, 2022 is 2.9%.
150 Royall Street, Suite 101
Canton, MA 02021
| October 1 – 31 | | | 1,534 | | | $ | 154.72 | | 1,523 | | | 51,280 | | |
| November 1 – 30 | | | 1,234 | | | $ | 161.33 | | 1,234 | | | 50,046 | | |
| December 1 – 31 | | | 1,052 | | | $ | 154.63 | | 1,052 | | | 48,994 | | |
| Total | | | 3,820 | | | $ | 156.83 | | 3,809 | | | | | |
(b)Consistent with the SCB framework, which allows for capital return in amounts in excess of the SCB minimum levels, our Board of Directors has authorized a repurchase framework under the repurchase program of up to 100 million common shares approved on April 4, 2019.
Under the SCB framework we repurchased 21.1 million shares in 2022 and 5.0 million shares in 2021.
| PNC | | | $ | 100 | | $ | 83.02 | | $ | 116.97 | | $ | 113.78 | | $ | 157.26 | | $ | 128.07 | | 5.07 | | % |
| S&P 500 Index | | | $ | 100 | | $ | 95.61 | | $ | 125.70 | | $ | 148.81 | | $ | 191.48 | | $ | 156.77 | | 9.41 | | % |
| S&P 500 Banks | | | $ | 100 | | $ | 83.56 | | $ | 117.52 | | $ | 101.35 | | $ | 137.28 | | $ | 110.91 | | 2.09 | | % |
| Peer Group | | | $ | 100 | | $ | 81.35 | | $ | 107.62 | | $ | 103.04 | | $ | 140.25 | | $ | 109.51 | | 1.83 | | % |
For Truist Financial Corporation, the preceding chart and table reflects historical BB&T Corporation data from December 2017 to December 2018 without inclusion of historical data from SunTrust Banks, Inc. This Peer Group was approved for 2022 by the Board’s Personnel and Compensation Committee, and the Committee has approved the same peer group for 2023.
In the first quarter of 2021, the Federal Reserve extended the special limitations on dividends and share repurchases by CCAR-participating BHCs that were put in place in 2020 as a result of ongoing economic uncertainty from COVID-19.
While these restrictions permitted share repurchases based on income, we refrained from repurchasing shares until the close of the BBVA transaction.
These restrictions ended on June 30, 2021 for firms with capital levels above those required by the 2021 stress-tests.
In June 2021, we announced the reinstatement of share repurchase programs with repurchases of up to $2.9 billion for the four-quarter period beginning in the third quarter of 2021.
462 South 4th Street, Suite 1600
Louisville, KY 40202
| October 1 – 31 | | | 671 | | | $ | 205.37 | | 658 | | | 72,390 | | |
| November 1 – 30 | | | 650 | | | $ | 204.98 | | 650 | | | 71,740 | | |
| December 1 – 31 | | | 1,612 | | | $ | 200.59 | | 1,612 | | | 70,128 | | |
| Total | | | 2,933 | | | $ | 202.66 | | | | | | | |
(b)On April 4, 2019, our Board of Directors approved the establishment of a new stock repurchase program authorization in the amount of 100 million shares of PNC common stock, effective July 1, 2019.
Under this authorization, repurchases may be made in open market or privately negotiated transactions, with the timing and exact amount of common stock repurchases depending on a number of factors including, among others, market and general economic conditions, regulatory capital considerations, alternative uses of capital, the potential impact on our credit ratings, and contractual and regulatory limitations, including the results of the supervisory assessment of capital adequacy and capital planning processes undertaken by the Federal Reserve as part of the CCAR process.
These restrictions ended on June 30, 2021 for firms with capital levels above those required by the 2021 stress tests.
Under these programs we repurchased 5.0 million shares in 2021 and 11.0 million shares in 2020.
| PNC | | | $ | 100 | | $ | 125.96 | | $ | 104.57 | | $ | 147.34 | | $ | 143.31 | | $ | 198.08 | | 14.65 | | % |
| S&P 500 Index | | | $ | 100 | | $ | 121.82 | | $ | 116.47 | | $ | 153.13 | | $ | 181.29 | | $ | 233.28 | | 18.46 | | % |
| S&P 500 Banks | | | $ | 100 | | $ | 122.55 | | $ | 102.41 | | $ | 144.02 | | $ | 124.21 | | $ | 168.23 | | 10.96 | | % |
| Peer Group | | | $ | 100 | | $ | 115.66 | | $ | 94.27 | | $ | 124.67 | | $ | 116.93 | | $ | 168.10 | | 10.95 | | % |
For Truist Financial Corporation, the preceding chart and table reflects historical BB&T Corporation data from December 2016 to December 2018.
Historical data for SunTrust Banks, Inc. is not included as a part of Truist Financial Corporation in the preceding chart and table.
This Peer Group was approved for 2021 by the Board of Directors’ Human Resources Committee, and the Committee has approved the same peer group for 2022.
36 The PNC Financial Services Group, Inc. – *2021 Form 10-K*
Item 6. RESERVED
1 rewritten, 0 added, 53 removed, 0 unchanged
The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [removed: 37][added: 35]
This Selected Financial Data should be reviewed in conjunction with the Consolidated Financial Statements and Notes included in
Item 8 of this Report as well as the other disclosures in this Report concerning our historical financial performance, our future
prospects and the risks associated with our business and financial performance.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | Year ended December 31 | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Dollars in millions, except per share data | | | 2021 | | | | | | 2020 | | | | | | 2019 | | | | | | | | | | | | | | | | | |
| Summary of Operations | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Net interest income | | | $ | 10,647 | | | | | $ | 9,946 | | | | | $ | 9,965 | | | | | | | | | | | | | | | | |
| Noninterest income | | | 8,564 | | | | | | 6,955 | | | | | | 6,874 | | | | | | | | | | | | | | | | | |
| Total revenue | | | 19,211 | | | | | | 16,901 | | | | | | 16,839 | | | | | | | | | | | | | | | | | |
| Provision for (recapture of) credit losses | | | (779) | | | | | | 3,175 | | | | | | 773 | | | | | | | | | | | | | | | | | |
| Noninterest expense | | | 13,002 | | | | | | 10,297 | | | | | | 10,574 | | | | | | | | | | | | | | | | | |
| Income from continuing operations before income taxes and noncontrolling interests | | | 6,988 | | | | | | 3,429 | | | | | | 5,492 | | | | | | | | | | | | | | | | | |
| Income taxes from continuing operations | | | 1,263 | | | | | | 426 | | | | | | 901 | | | | | | | | | | | | | | | | | |
| Net income from continuing operations | | | 5,725 | | | | | | 3,003 | | | | | | 4,591 | | | | | | | | | | | | | | | | | |
| Income from discontinued operations before taxes | | | | | | | | | 5,777 | | | | | | 988 | | | | | | | | | | | | | | | | | |
| Income taxes from discontinued operations | | | | | | | | | 1,222 | | | | | | 161 | | | | | | | | | | | | | | | | | |
| Net income from discontinued operations | | | | | | | | | 4,555 | | | | | | 827 | | | | | | | | | | | | | | | | | |
| Net income | | | $ | 5,725 | | | | | $ | 7,558 | | | | | $ | 5,418 | | | | | | | | | | | | | | | | |
| Net income attributable to common shareholders | | | $ | 5,436 | | | | | $ | 7,284 | | | | | $ | 5,129 | | | | | | | | | | | | | | | | |
| Per Common Share | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Diluted earnings from continuing operations | | | $ | 12.70 | | | | | $ | 6.36 | | | | | $ | 9.57 | | | | | | | | | | | | | | | | |
| Diluted earnings from discontinued operations | | | | | | | | | $ | 10.60 | | | | | $ | 1.82 | | | | | | | | | | | | | | | | |
| Total diluted earnings | | | $ | 12.70 | | | | | $ | 16.96 | | | | | $ | 11.39 | | | | | | | | | | | | | | | | |
| Book value per common share | | | $ | 120.61 | | | | | $ | 119.11 | | | | | $ | 104.59 | | | | | | | | | | | | | | | | |
| Tangible book value per common share (a) | | | $ | 94.11 | | | | | $ | 97.43 | | | | | $ | 83.30 | | | | | | | | | | | | | | | | |
| Performance Ratios | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Net interest margin (b) | | | 2.29 | | % | | | | 2.53 | | % | | | | 2.89 | | % | | | | | | | | | | | | | | | |
| Noninterest income to total revenue | | | 45 | | % | | | | 41 | | % | | | | 41 | | % | | | | | | | | | | | | | | | |
| Efficiency | | | 68 | | % | | | | 61 | | % | | | | 63 | | % | | | | | | | | | | | | | | | |
| Return on: | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Average common shareholders’ equity | | | 10.78 | | % | | | | 15.21 | | % | | | | 11.50 | | % | | | | | | | | | | | | | | | |
| Average assets | | | 1.09 | | % | | | | 1.68 | | % | | | | 1.35 | | % | | | | | | | | | | | | | | | |
(a)See explanation and reconciliation of this non-GAAP measure in Reconciliation of Tangible Book Value Per Common Share (Non-GAAP) Statistical Information (Unaudited) section in Item 8 of this Report.
(b)See explanation and reconciliation of this non-GAAP measure in Average Consolidated Balance Sheet and Net Interest Analysis and Reconciliation of Taxable-Equivalent Net Interest Income (Non-GAAP) Statistical Information (Unaudited) section in Item 8 of this Report.
| Dollars in millions, except as noted | | | 2021 | | | | | | 2020 | | | | | | | | | | | | | | | | | | | | | | | |
| Balance Sheet Highlights | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Assets | | | $ | 557,191 | | | | | $ | 466,679 | | | | | | | | | | | | | | | | | | | | | | |
| Loans | | | $ | 288,372 | | | | | $ | 241,928 | | | | | | | | | | | | | | | | | | | | | | |
An excerpt. Shown here: all 1 rewritten, all 0 added and 40 of 53 removed. The counts are complete. For every sentence, read Item 6. RESERVED in the FY2022 filing and the FY2021 filing.
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
1,359 rewritten, 482 added, 370 removed, 2,474 unchanged
| [Reports of Independent Registered Public Accounting [removed: Firm](#iaa6d7aa2f870454da9ce69c37ef5dad0_205)] [added: Firm](#ib4bdc01166af494b81c4833469b4fe36_202)] (PCAOB ID: 238) | | | | | | | | | | | | [removed: [87](#iaa6d7aa2f870454da9ce69c37ef5dad0_205)] [added: [86](#ib4bdc01166af494b81c4833469b4fe36_202)] | | |
| [Consolidated [removed: Income Statement](#iaa6d7aa2f870454da9ce69c37ef5dad0_208)] [added: Statement of Comprehensive Income](#ib4bdc01166af494b81c4833469b4fe36_208)] | | | | | | | | | | | | [removed: [90](#iaa6d7aa2f870454da9ce69c37ef5dad0_208)] [added: [89](#ib4bdc01166af494b81c4833469b4fe36_208)] | | |
| [Consolidated Balance [removed: Sheet](#iaa6d7aa2f870454da9ce69c37ef5dad0_214)] [added: Sheet](#ib4bdc01166af494b81c4833469b4fe36_211)] | | | | | | | | | | | | [removed: [92](#iaa6d7aa2f870454da9ce69c37ef5dad0_214)] [added: [90](#ib4bdc01166af494b81c4833469b4fe36_211)] | | |
| [Consolidated Statement of Changes in [removed: Equity](#iaa6d7aa2f870454da9ce69c37ef5dad0_217)] [added: Equity](#ib4bdc01166af494b81c4833469b4fe36_214)] | | | | | | | | | | | | [removed: [93](#iaa6d7aa2f870454da9ce69c37ef5dad0_217)] [added: [91](#ib4bdc01166af494b81c4833469b4fe36_214)] | | |
| [Consolidated Statement of Cash [removed: Flows](#iaa6d7aa2f870454da9ce69c37ef5dad0_220)] [added: Flows](#ib4bdc01166af494b81c4833469b4fe36_220)] | | | | | | | | | | | | [removed: [94](#iaa6d7aa2f870454da9ce69c37ef5dad0_220)] [added: [92](#ib4bdc01166af494b81c4833469b4fe36_220)] | | |
| [Notes to the Consolidated Financial [removed: Statements](#iaa6d7aa2f870454da9ce69c37ef5dad0_223)] [added: Statements](#ib4bdc01166af494b81c4833469b4fe36_223)] | | | | | | | | | | | | [removed: [96](#iaa6d7aa2f870454da9ce69c37ef5dad0_223)] [added: [94](#ib4bdc01166af494b81c4833469b4fe36_223)] | | |
[removed: 86] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [added: 85]
We have audited the accompanying consolidated balance sheet of The PNC Financial Services Group, Inc. and its subsidiaries (the “Company”) as of December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] and the related consolidated statements of income, [added: of] comprehensive income, [added: of] changes in equity and [added: of] cash flows for each of the three years in the period ended December 31, [removed: 2021,] [added: 2022,] including the related notes (collectively referred to as the “consolidated financial statements”).
We also have audited the Company’s internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in [removed: *Internal] [added: Internal] Control - Integrated [removed: Framework*] [added: Framework] (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2021] [added: 2022] and [removed: 2020,] [added: 2021,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2021] [added: 2022] in conformity with accounting principles generally accepted in the United States of America.
Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2021,] [added: 2022,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
[added: 86] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [removed: 87]
The critical audit [removed: matters] [added: matter] communicated below [removed: are matters] [added: is a matter] arising from the current period audit of the consolidated financial statements that [removed: were] [added: was] communicated or required to be communicated to the audit committee and that (i) [removed: relate] [added: relates] to accounts or disclosures that are material to the consolidated financial statements and (ii) involved our especially challenging, subjective, or complex judgments.
The communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit [removed: matters] [added: matter] below, providing [added: a] separate [removed: opinions] [added: opinion] on the critical audit [removed: matters] [added: matter] or on the accounts or disclosures to which [removed: they relate.][added: it relates.]
[removed: *Allowance] [added: Allowance] for Loans and Lease Losses – Commercial [removed: Loans*][added: Loans]
As described in Notes 1 and 4 to the consolidated financial statements, the allowance for loans and lease losses was approximately [removed: $4,868] [added: $4,741] million as of December 31, [removed: 2021,] [added: 2022,] of which [removed: $3,185] [added: $3,114] million relates to commercial loans.
For example, qualitative factors may include industry concentration and conditions, [removed: including the impacts of COVID-19 on highly impacted segments,] changes in market conditions, changes in the nature and volume of the Company’s portfolio, recent credit quality trends, recent loss experience in particular portfolios, recent macroeconomic factors, limitations of available input data, model imprecision, changes in lending policies, and other factors.
The principal considerations for our determination that performing procedures relating to the allowance for loan and lease losses for commercial loans is a critical audit matter are (i) the significant judgment and estimation by management in developing economic forecast scenarios of Real GDP and U.S. unemployment rate, determining weighting of each scenario, and estimating qualitative [removed: reserves related to the impacts of COVID-19 on certain highly impacted segments,] [added: reserves,] which in turn led to a high degree of auditor judgment, subjectivity and effort in performing procedures and in evaluating audit evidence related to management’s significant judgements and estimations and (ii) the audit effort involved professionals with specialized skill and knowledge.
[removed: For commercial loans, as disclosed by management, the fair] [added: Fair] value [removed: is] [added: for loans were] based on a discounted cash flow methodology that [removed: considers] [added: considered] credit loss and prepayment expectations, market interest rates and other market [removed: factors.][added: factors, such as liquidity, from the perspective of a market participant.]
[removed: 88] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [added: 87]
[added: 88] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [removed: 89]
| | | | [added: | | |] Year ended December 31 | | | [removed: | | | | | | | | | | | |]
| In millions, except per share data | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | [removed: 2019] [added: 2020] | | |
| Loans | | | $ | [removed: 9,007] [added: 11,795] | | | | | $ | [removed: 8,927] [added: 9,007] | | | | | $ | [removed: 10,525] [added: 8,927] | |
| Investment securities | | | [removed: 1,834] [added: 2,726] | | | | | | [removed: 2,041] [added: 1,834] | | | | | | [removed: 2,426] [added: 2,041] | | |
| Other | | | [removed: 293] [added: 915] | | | | | | [removed: 339] [added: 293] | | | | | | [removed: 811] [added: 339] | | |
| Total interest income | | | [removed: 11,134] [added: 15,436] | | | | | | [removed: 11,307] [added: 11,134] | | | | | | [removed: 13,762] [added: 11,307] | | |
| Deposits | | | [removed: 126] [added: 1,267] | | | | | | [removed: 643] [added: 126] | | | | | | [removed: 1,986] [added: 643] | | |
| Borrowed funds | | | [removed: 361] [added: 1,155] | | | | | | [removed: 718] [added: 361] | | | | | | [removed: 1,811] [added: 718] | | |
| Total interest expense | | | [removed: 487] [added: 2,422] | | | | | | [removed: 1,361] [added: 487] | | | | | | [removed: 3,797] [added: 1,361] | | |
| Net interest income | | | [removed: 10,647] [added: 13,014] | | | | | | [removed: 9,946] [added: 10,647] | | | | | | [removed: 9,965] [added: 9,946] | | |
| Asset management [added: fees] | | | [removed: 964] | | | | | | [removed: 836] | | | | | | [removed: 862] | | | [added: $ | 964 | |]
| Total noninterest income | | | [removed: 8,564] [added: 8,106] | | | | | | [removed: 6,955] [added: 8,564] | | | | | | [removed: 6,874] [added: 6,955] | | |
| Total revenue | | | [removed: 19,211] [added: 21,120] | | | | | | [removed: 16,901] [added: 19,211] | | | | | | [removed: 16,839] [added: 16,901] | | |
| Provision For (Recapture of) Credit Losses | | | [removed: (779)] [added: 477] | | | | | | [removed: 3,175] [added: (779)] | | | | | | [removed: 773] [added: 3,175] | | |
| Personnel | | | [removed: 7,141] [added: 7,244] | | | | | | [removed: 5,673] [added: 7,141] | | | | | | [removed: 5,647] [added: 5,673] | | |
| Occupancy | | | [removed: 940] [added: 992] | | | | | | [removed: 826] [added: 940] | | | | | | [removed: 834] [added: 826] | | |
| Equipment | | | [removed: 1,411] [added: 1,395] | | | | | | [removed: 1,176] [added: 1,411] | | | | | | [removed: 1,210] [added: 1,176] | | |
| Marketing | | | [removed: 319] [added: 355] | | | | | | [removed: 236] [added: 319] | | | | | | [removed: 301] [added: 236] | | |
| Other | | | [removed: 3,191] [added: 3,184] | | | | | | [removed: 2,386] [added: 3,191] | | | | | | [removed: 2,582] [added: 2,386] | | |
| [Consolidated Income Statement](#ib4bdc01166af494b81c4833469b4fe36_205) | | | | | | | | | | | | [88](#ib4bdc01166af494b81c4833469b4fe36_205) | | |
February 22, 2023
| Asset management and brokerage | | | 1,444 | | | | | | 1,438 | | | | | | 1,203 | | |
| Capital markets and advisory | | | 1,296 | | | | | | 1,577 | | | | | | 1,259 | | |
| Card and cash management | | | 2,633 | | | | | | 2,398 | | | | | | 1,913 | | |
| Lending and deposit services | | | 1,134 | | | | | | 1,102 | | | | | | 1,026 | | |
| Residential and commercial mortgage | | | 647 | | | | | | 850 | | | | | | 946 | | |
| Other | | | 952 | | | | | | 1,199 | | | | | | 608 | | |
| Senior debt | | | 16,657 | | | | | | 20,661 | | |
Comparable amounts at December 31, 2021 were less than $0.1 billion and zero.
| Net income | | | | | | | | | | | | | | | | | | 6,041 | | | | | | | | | | | | 72 | | | 6,113 | | |
| Preferred stock issuance (f) (g) | | | | | | | | | | | | 2,232 | | | | | | | | | | | | | | | | | | | | | 2,232 | | |
| Preferred stock redemption (h) | | | | | | | | | | | | (1,500) | | | | | | | | | | | | | | | | | | | | | (1,500) | | |
| Balance at December 31, 2022 (a) | | | 401 | | | | | | $ | 2,714 | | $ | 5,746 | | $ | 12,630 | | $ | 53,572 | | $ | (10,172) | | $ | (18,716) | | | | | $ | 38 | | $ | 45,812 | |
(f)On April 26, 2022, PNC issued 1,000,000 depositary shares each representing 1/100th ownership in a share of 6.000% fixed-rate reset non-cumulative perpetual preferred stock, Series U, with a par value of $1 per share.
(g)On August 19, 2022, PNC issued 1,250,000 depositary shares each representing 1/100th ownership in a share of 6.200% fixed-rate reset non-cumulative perpetual preferred stock, Series V, with a par value of $1 per share.
(h)On November 1, 2022, PNC redeemed all 15,000 shares of its Series P preferred stock, as well as all 60 million depositary shares each representing a fractional interest in such shares.
| (Continued from previous page) | | | | | | Year ended December 31 | | | | | | | | | | | | | | |
| Cash and due from banks and restricted cash at end of period | | | | | | $ | 7,043 | | | | | $ | 8,004 | | | | | $ | 7,017 | |
| Transfer from securities available for sale to securities held to maturity (a) | | | | | | $ | 88,605 | | | | | | | | | | | | | |
(a)During the year ended December 31, 2022, we transferred securities from available for sale to held to maturity in non-cash transactions.
The amount of $88.6 billion includes the aggregate fair value of the securities of $82.7 billion and aggregate net pretax unrealized losses of $5.9 billion included in AOCI at transfer.
Effective for the first quarter of 2022, PNC updated the presentation of its noninterest income categorization to be based on product and service type, and accordingly, has changed the basis of presentation of its noninterest income revenue streams to: (i) Asset management and brokerage, (ii) Capital markets related, (iii) Card and cash management, (iv) Lending and deposit services, (v) Residential and commercial mortgage and (vi) Other noninterest income.
Additionally, in the fourth quarter of 2022, PNC updated the name of the noninterest income line item “Capital markets related” to “Capital markets and advisory.” This update did not impact the components of the category.
A description of each revenue stream follows:
Asset management and brokerage includes revenue from our asset management and retail brokerage businesses.
Asset management services include investment management, custody, retirement planning, family planning, trust management and retirement administration.
Brokerage services offer retail customers a wide range of investment options, including mutual funds, annuities, stock, bonds and managed accounts.
Capital markets and advisory includes revenue from services and activities primarily related to merger and acquisition advisory, equity capital markets advisory, asset-backed financing, loan syndication, securities underwriting, credit valuation adjustments related to the derivatives portfolio and customer-related trading.
Card and cash management includes revenue primarily from debit and credit card activities, inclusive of credit card points and rewards, treasury management services and ATM fees.
Debit and credit card activities include interchange revenue and merchant service fees.
Treasury management services include cash and investment management, receivables and disbursement management, funds transfer, international payment and access to online/mobile information management and reporting.
Lending and deposit services includes revenue primarily related to service charges on deposits, loan commitment and usage fees, the issuance of standby letters of credit, operating lease income and long-term care and insurance products.
Residential and commercial mortgage includes the gain and loss on sale of mortgages, revenue related to our mortgage servicing responsibilities, mortgage servicing rights valuation adjustments and net gains on originations and sales of loans held for sale.
Other noninterest income is primarily composed of private equity revenue, net securities gains and losses, activity related to our equity investment in Visa and gains and losses on asset sales.
See Note 24 Fee-based Revenue from Contracts with Customers for additional details related to these revenue streams within the scope of ASC 606 - *Revenue from Contracts with Customers*.
The PNC Financial Services Group, Inc. – *2022 Form 10-K* 99
- Industry concentrations and conditions,
- Recent credit quality trends,
- Timing of available information.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| [Consolidated Statement of Comprehensive Income](#iaa6d7aa2f870454da9ce69c37ef5dad0_211) | | | | | | | | | | | | [91](#iaa6d7aa2f870454da9ce69c37ef5dad0_211) | | |
Addressing the matter involved performing procedures and evaluating audit evidence in connection with forming our overall opinion on the consolidated financial statements.
*Acquisition of BBVA USA Bancshares, Inc. - Fair Value of Commercial Loans Acquired*
As described in Note 2 to the consolidated financial statements, the Company acquired BBVA USA Bancshares, Inc. (“BBVA”) on June 1, 2021.
The transaction has been accounted for as a business combination and accordingly, the assets and liabilities from BBVA were recorded at fair value as of the acquisition date.
The fair value of loans acquired from BBVA was approximately $61,423 million as of June 1, 2021, of which $39,742 million were commercial loans.
The principal considerations for our determination that performing procedures relating to the fair value of commercial loans acquired is a critical audit matter are (i) the significant judgment and estimation by management in developing the credit loss expectations, prepayment expectations, and market interest rates used in the discounted cash flow methodology, which in turn led to a high degree of auditor judgment, subjectivity, and effort in performing procedures and in evaluating audit evidence obtained related to the
significant judgments and estimations by management, and (ii) the audit effort involved professionals with specialized skill and knowledge.
These procedures included testing the effectiveness of controls relating to the fair value of commercial loans acquired, including controls over the credit loss expectations, prepayment expectations, and market interest rates used in the discounted cash flow methodology.
These procedures also included, among others (i) the involvement of professionals with specialized skill and knowledge to assist in developing independent ranges of fair value for the commercial loans acquired, including the development of independent expectations for credit losses, prepayments, and market interest rates, (ii) comparing management’s estimate to the independently developed ranges, and (iii) testing the completeness and accuracy of the underlying loan data provided by management that was used to develop these expectations.
February 25, 2022
| | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Consumer services | | | 1,845 | | | | | | 1,484 | | | | | | 1,555 | | |
| Corporate services | | | 2,924 | | | | | | 2,167 | | | | | | 1,914 | | |
| Residential mortgage | | | 456 | | | | | | 604 | | | | | | 368 | | |
| Service charges on deposits | | | 535 | | | | | | 500 | | | | | | 702 | | |
| Other | | | 1,840 | | | | | | 1,364 | | | | | | 1,473 | | |
| | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Bank notes and senior debt | | | 20,661 | | | | | | 24,271 | | |
| Balance at December 31, 2018 (a) | | | 457 | | | | | | $ | 2,711 | | $ | 3,986 | | $ | 12,291 | | $ | 38,919 | | $ | (725) | | $ | (9,454) | | | | | $ | 42 | | $ | 47,770 | |
| Balance at January 1, 2019 (a) | | | 457 | | | | | | $ | 2,711 | | $ | 3,986 | | $ | 12,291 | | $ | 38,981 | | $ | (725) | | $ | (9,454) | | | | | $ | 42 | | $ | 47,832 | |
| Net income | | | | | | | | | | | | | | | | | | 5,369 | | | | | | | | | | | | 49 | | | 5,418 | | |
| Cumulative effect of ASU adoptions (d) | | | | | | | | | | | | | | | | | | (671) | | | | | | | | | | | | | | | (671) | | |
(b)Represents the impact of the adoption of ASU 2016-02 related primarily to deferred gains on previous sale-leaseback transactions.
| Net cash received from divestiture activity | | | | | | | | | | | | | | | | | | 75 | | |
| Right-of-use assets recognized at adoption of ASU 2016-02 | | | | | | | | | | | | | | | | | | $ | 2,004 | |
(a)Cash paid to acquire BBVA was $11,480 million.
The amount of $10,511 million represents the cash paid for the acquisition less $969 million in cash acquired.
Our balance sheet at December 31, 2021 includes balances from BBVA.
The CECL standard was applied prospectively to debt securities and, as a result, the amortized cost basis of investment securities for which OTTI had previously been recorded did not change upon adoption.
detailed in Note 15 Fair Value.
nonaccrual at the time of modification unless payment in full of principal or interest is not expected.
We maintain the ACL at an
The
- Industry concentrations and conditions, including the impacts of COVID-19 on highly impacted segments,
- Recent credit quality trends, including the impact of COVID-19 hardship related loan modifications,
- Timing of available information, including the performance of first lien positions.
An excerpt. Shown here: 40 of 1,359 rewritten, 40 of 482 added and 40 of 370 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2022 filing and the FY2021 filing.
Item 9A. CONTROLS AND PROCEDURES
5 rewritten, 1 added, 0 removed, 7 unchanged
We performed an evaluation under the supervision and with the participation of our management, including the Chairman, President and Chief Executive Officer and the Executive Vice President and Chief Financial Officer, of the effectiveness of PNC’s internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
Based on this assessment, management concluded that PNC maintained effective internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
PricewaterhouseCoopers LLP, the independent registered public accounting firm that audited our consolidated financial statements as of and for the year ended December 31, [removed: 2021] [added: 2022] included in this Report, has also audited the effectiveness of PNC’s internal control over financial reporting as of December 31, [removed: 2021.][added: 2022.]
As of December 31, [removed: 2021,] [added: 2022,] we performed an evaluation under the supervision and with the participation of our management, including the Chairman, President and Chief Executive Officer and the Executive Vice President and Chief Financial Officer, of the effectiveness of the design and operation of our disclosure controls and procedures and of changes in our internal control over financial reporting.
Based on that evaluation, our Chairman, President and Chief Executive Officer and our Executive Vice President and Chief Financial Officer concluded that our disclosure controls and procedures (as defined in Rule 13a-15(e) under the Securities and Exchange Act of 1934, as amended) were effective as of December 31, [removed: 2021,] [added: 2022,] and that there has been no change in PNC’s internal control over financial reporting that occurred during the fourth quarter of [removed: 2021] [added: 2022] that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
198 The PNC Financial Services Group, Inc. – *2022 Form 10-K*
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
3 rewritten, 0 added, 2 removed, 3 unchanged
Certain of the information regarding our directors (or nominees for director), executive officers and Audit Committee (and Audit Committee financial experts), required by this item is included under the captions “Election of Directors (Item 1),” and “Corporate Governance – Board committees – Audit Committee,” in our Proxy Statement to be filed for the [removed: 2022] [added: 2023] annual meeting of shareholders and is incorporated herein by reference.
Information regarding our compliance with Section 16(a) of the Securities Exchange Act of 1934 is included, to the extent necessary, under the caption “Delinquent Section 16(a) Reports” in our Proxy Statement to be filed for the [removed: 2022] [added: 2023] annual meeting of shareholders and is incorporated herein by reference.
Certain information regarding our PNC Code of Business Conduct and Ethics required by this item is included under the captions “Corporate Governance – Our Code of Business Conduct and Ethics” and “Director and Executive Officer Relationships – Code of Business Conduct and Ethics” in our Proxy Statement to be filed for the [removed: 2022] [added: 2023] annual meeting of shareholders and is incorporated [added: herein by reference.]
196 The PNC Financial Services Group, Inc. – *2021 Form 10-K*
herein by reference.
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 1 added, 0 removed, 1 unchanged
The information required by this item is included under the captions “Corporate Governance – Board committees – Human Resources Committee – Compensation committee interlocks and insider participation,” “Director Compensation,” “Compensation Discussion and Analysis,” “Compensation Committee Report,” “Compensation and Risk,” “Compensation Tables,” “Change in Control and Termination of Employment” and “CEO Pay Ratio” in our Proxy Statement to be filed for the [removed: 2022] [added: 2023] annual meeting of shareholders and is incorporated herein by reference.
The PNC Financial Services Group, Inc. – *2022 Form 10-K* 199
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
7 rewritten, 3 added, 3 removed, 9 unchanged
The information required by this item regarding security ownership of certain beneficial owners and management is included under the caption “Security Ownership of Management and Certain Beneficial Owners” in our Proxy Statement to be filed for the [removed: 2022] [added: 2023] annual meeting of shareholders and is incorporated herein by reference.
Information regarding our compensation plans under which PNC equity securities are authorized for issuance as of December 31, [removed: 2021] [added: 2022] is included in the table which follows.
[removed: Additional] [added: For additional] information regarding these [removed: plans is included in] [added: plans, see] Note 18 Stock Based Compensation [removed: Plans in the Notes to Consolidated Financial Statements in Item 8 of this Report.][added: Plans.]
(2) – Of this total, the following amounts relate to the 2016 Incentive Award Plan (2016 Incentive Plan), approved by shareholders on April 26, 2016: [removed: 3,579,373] [added: 3,338,653] are stock-payable restricted stock units (at a maximum share award level), [removed: 737,912] [added: 871,648] are performance share units (at maximum share award level) and [removed: 53,268] [added: 59,658] are deferred stock units (at a maximum share award level).
Also included in this total are the following amounts that relate to the 2006 Incentive Award Plan, as amended and restated (2006 Incentive Plan): [removed: 28,134] [added: 10,750] are stock options and [removed: 83,605] [added: 44,177] are stock-payable restricted stock units (at a maximum award level).
(3) – Includes [removed: 1,956,393] [added: 1,786,148] shares available for issuance under the Employee Stock Purchase Plan, of which [removed: 71,227] [added: 106,038] shares are subject to purchase during the purchase period ending December 31, [removed: 2021.][added: 2022.]
The amount available for awards under the 2016 Incentive Plan is [removed: 21,933,846.][added: 18,234,031.]
At December 31, 2022
| Equity compensation plans approved by security holders | | | | | | 4,324,886 | | | (2) | | | $ | 63.87 | | | | | 20,020,179 | | | (3) | | |
| Total | | | | | | 4,324,886 | | | | | | $ | 63.87 | | | | | 20,020,179 | | | | | |
At December 31, 2021
| Equity compensation plans approved by security holders | | | | | | 4,482,292 | | | (2) | | | $ | 63.04 | | | | | 23,890,239 | | | (3) | | |
| Total | | | | | | 4,482,292 | | | | | | $ | 63.04 | | | | | 23,890,239 | | | | | |
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 1 removed, 0 unchanged
The information required by this item is included under the captions “Director and Executive Officer Relationships – Director independence, – Transactions with directors, – Family relationships, and – Indemnification and advancement of costs” and “Related Person Transactions” in our Proxy Statement to be filed for the [removed: 2022] [added: 2023] annual meeting of shareholders and is incorporated herein by reference.
The PNC Financial Services Group, Inc. – *2021 Form 10-K* 197
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
1 rewritten, 1 added, 0 removed, 1 unchanged
The information required by this item is included under the caption “Ratification of Independent Registered Public Accounting [removed: Firm"] [added: Firm”] in our Proxy Statement to be filed for the [removed: 2022] [added: 2023] annual meeting of shareholders and is incorporated herein by reference.
200 The PNC Financial Services Group, Inc. – *2022 Form 10-K*
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
44 rewritten, 6 added, 9 removed, 172 unchanged
| 2.1.1 | | | | | | [removed: [Stock] [added: [Share] Purchase Agreement, dated as of November 15, 2020, between Banco Bilbao Vizcaya Argentaria, S.A. and The PNC Financial Services Group, Inc.](http://www.sec.gov/Archives/edgar/data/713676/000071367620000151/comet-sharepurchaseagr.htm) | | | | | | Incorporated herein by reference to Exhibit 2.1 of the Corporation’s Current Report on Form 8-K filed November 19, 2020 | | |
| 3.2 | | | | | | [Amended and Restated Bylaws of the Corporation effective February 10, [removed: 2022](https://www.sec.gov/Archives/edgar/data/713676/000071367622000011/pncfsgbylaws172022.htm)] [added: 2022](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/ex32corpbylaws172022fina.htm)] | | | | | | [removed: Incorporated herein by reference to Exhibit 3.1 of the Corporation's Current Report on Form 8-K filed February 11, 2022] [added: Filed herewith] | | |
[removed: 198] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [added: 201]
| [removed: 4.7] [added: 4.10] | | | | | | [Form of PNC Bank, National Association Subordinated Fixed Rate Global Bank Note issued prior to January 16, 2014](http://www.sec.gov/Archives/edgar/data/713676/000119312504187756/dex411.htm) | | | | | | Incorporated herein by reference to Exhibit 4.11 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2004 | | |
| [removed: 4.8.1] [added: 4.11.1] | | | | | | [Issuing and Paying Agency Agreement, dated January 16, 2014, between PNC Bank, National Association and PNC Bank, National Association, relating to the $25 billion Global Bank Note Program for the Issue of Senior and Subordinated Bank Notes](http://www.sec.gov/Archives/edgar/data/713676/000119312514077944/d634352dex425.htm) | | | | | | Incorporated herein by reference to Exhibit 4.25 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2013 | | |
| [removed: 4.8.2] [added: 4.11.2] | | | | | | [Amendment No. 1 to Issuing and Paying Agency Agreement, dated May 22, 2015, between PNC Bank, National Association and PNC Bank, National Association, relating to the $30 billion Global Bank Note Program for the Issue of Senior and Subordinated Bank Notes](http://www.sec.gov/Archives/edgar/data/713676/000119312515277885/d943118dex4212.htm) | | | | | | Incorporated herein by reference to Exhibit 4.21.2 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2015 | | |
| [removed: 4.8.3] [added: 4.11.3] | | | | | | [Amendment No. 2 to Issuing and Paying Agency Agreement, dated May 27, 2016, between PNC Bank, National Association and PNC Bank, National Association, relating to the $40 billion Global Bank Note Program for the Issue of Senior and Subordinated Bank Notes](http://www.sec.gov/Archives/edgar/data/713676/000119312516669661/d209081dex4203.htm) | | | | | | Incorporated herein by reference to Exhibit 4.20.3 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2016 | | |
| [removed: 4.9] [added: 4.12] | | | | | | [Forms of PNC Bank, National Association Senior Global Bank Notes issued after January 16, 2014 (included in Exhibit [removed: 4.](http://www.sec.gov/Archives/edgar/data/713676/000119312514077944/d634352dex425.htm)[8](http://www.sec.gov/Archives/edgar/data/713676/000119312514077944/d634352dex425.htm)[.1)](http://www.sec.gov/Archives/edgar/data/713676/000119312514077944/d634352dex425.htm)] [added: 4.11.1)](http://www.sec.gov/Archives/edgar/data/713676/000119312514077944/d634352dex425.htm)] | | | | | | Incorporated herein by reference to Exhibit 4.25 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2013 | | |
[added: 202] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [removed: 199]
| [removed: 4.10] [added: 4.13] | | | | | | [Forms of PNC Bank, National Association Subordinated Global Bank Notes issued on or after May 22, 2015 (included in Exhibit [removed: 4.](http://www.sec.gov/Archives/edgar/data/713676/000119312515277885/d943118dex4212.htm)[8](http://www.sec.gov/Archives/edgar/data/713676/000119312515277885/d943118dex4212.htm)[.2)](http://www.sec.gov/Archives/edgar/data/713676/000119312515277885/d943118dex4212.htm)] [added: 4.11.2)](http://www.sec.gov/Archives/edgar/data/713676/000119312515277885/d943118dex4212.htm)] | | | | | | Incorporated herein by reference to Exhibit 4.21.2 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2015 | | |
| [removed: 4.11] [added: 4.14] | | | | | | [Description of the [removed: Corporation's Securities](https://www.sec.gov/Archives/edgar/data/713676/000071367622000019/a2021ex4-11xdescriptiono.htm)] [added: Corporation’s Securities](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/exhibit414descriptionofs.htm)] | | | | | | Filed herewith | | |
| [removed: 10.2.1] [added: 10.6.3] | | | | | | [removed: [The Corporation’s ERISA Excess Pension] [added: [Amendment 2021-2 to the Corporation and Affiliates Deferred Compensation and Incentive] Plan, as amended and restated effective January 1, [removed: 2009](http://www.sec.gov/Archives/edgar/data/713676/000119312509042518/dex104.htm)] [added: 2020](http://www.sec.gov/Archives/edgar/data/713676/000071367622000019/a1063-conformedamendment.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.4] [added: 10.6.3] of the Corporation’s Annual Report on Form 10-K for the year ended December 31, [removed: 2008*] [added: 2021*] | | |
| [removed: 10.2.2] [added: 10.30.2] | | | | | | [Amendment [removed: 2009-1] to [removed: the Corporation’s ERISA Excess] [added: The National City Corporation 2004 Deferred Compensation] Plan, as amended and restated effective January 1, [removed: 2009](http://www.sec.gov/Archives/edgar/data/713676/000119312510052794/dex106.htm)] [added: 2005](http://www.sec.gov/Archives/edgar/data/713676/000119312511051725/dex1056.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.6] [added: 10.56] of the Corporation’s Annual Report on Form 10-K for the year ended December 31, [removed: 2009*] [added: 2010*] | | |
| [removed: 10.2.3] [added: 10.14] | | | | | | [removed: [Amendment 2011-1 to the Corporation’s ERISA Excess Pension Plan, as amended and restated] [added: [Certificate of Corporate Action for Grantor Trusts] effective [removed: January] [added: December] 1, [removed: 2009](http://www.sec.gov/Archives/edgar/data/713676/000119312512087345/d260760dex108.htm)] [added: 2021](http://www.sec.gov/Archives/edgar/data/713676/000071367622000019/a1014conformedexecutionv.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.8] [added: 10.14] of the Corporation’s Annual Report on Form 10-K for the year ended December 31, [removed: 2011*] [added: 2021*] | | |
| [removed: 10.2.4] [added: 10.16] | | | | | | [removed: [Amendment 2013-1 to the Corporation’s ERISA Excess Pension Plan, as amended] [added: [2013 forms of employee stock option] and [removed: restated effective January 1, 2009](http://www.sec.gov/Archives/edgar/data/713676/000119312514077944/d634352dex1024.htm)] [added: restricted share unit agreements](http://www.sec.gov/Archives/edgar/data/713676/000119312513085012/d446794dex1064.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.2.4] [added: 10.64] of the Corporation’s Annual Report on Form 10-K for the year ended December 31, [removed: 2013*] [added: 2012*] | | |
[removed: 200] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [added: 203]
| [removed: 10.6.3] [added: 10.2] | | | | | | [removed: [Amendment 2021-2 to the Corporation and Affiliates Deferred Compensation and Incentive] [added: [The Corporation’s ERISA Excess Pension] Plan, as amended and restated effective January 1, [removed: 2020](https://www.sec.gov/Archives/edgar/data/713676/000071367622000019/a1063-conformedamendment.htm)] [added: 2023](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/exhibit102erisaexcesspen.htm)] | | | | | | Filed herewith* | | |
| [removed: 10.16] [added: 10.17] | | | | | | [removed: [2012] [added: [Additional 2013] forms of employee stock option, [added: performance unit,] restricted stock and restricted share unit [removed: agreements](http://www.sec.gov/Archives/edgar/data/713676/000119312512222424/d323892dex1077.htm)] [added: agreements](http://www.sec.gov/Archives/edgar/data/713676/000119312513326063/d546718dex1082.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.77] [added: 10.82] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended [removed: March 31, 2012*] [added: June 30, 2013*] | | |
| [removed: 10.17] [added: 10.25] | | | | | | [removed: [Forms] [added: [2022 Form] of [removed: employee stock option, restricted stock and restricted share unit agreements with varied vesting, payment and other circumstances](http://www.sec.gov/Archives/edgar/data/713676/000119312512222424/d323892dex1078.htm)] [added: Restricted Share Units Award Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1035-2022formofrestric.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.78] [added: 10.35] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended [removed: March 31, 2012*] [added: June 30, 2022*] | | |
| [removed: 10.18] [added: 10.22] | | | | | | [removed: [2013 forms] [added: [2021 Form] of [removed: employee stock option and restricted share unit agreements](http://www.sec.gov/Archives/edgar/data/713676/000119312513085012/d446794dex1064.htm)] [added: Restricted Share Units Award Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367621000095/a1036-202110qcegrsufinal.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.64] [added: 10.36] of the Corporation’s Annual Report on Form 10-K for the year ended December 31, [removed: 2012*] [added: 2021*] | | |
| [removed: 10.19] [added: 10.27] | | | | | | [removed: [Additional 2013 forms] [added: [2022 Form] of [removed: employee stock option, performance unit, restricted stock and restricted share unit agreements](http://www.sec.gov/Archives/edgar/data/713676/000119312513326063/d546718dex1082.htm)] [added: Performance Restricted Share Units Award Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1037-2022formofperform.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.82] [added: 10.37] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, [removed: 2013*] [added: 2022*] | | |
[added: 204] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [removed: 201]
| [removed: 10.20] [added: 10.18] | | | | | | [removed: [2019] [added: [2020] Form of Performance Share Units Award [removed: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367619000073/a1045-201910qpsufinal.htm)] [added: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367620000115/pnc-06302020xex1039.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.45] [added: 10.39] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended [removed: September] [added: June] 30, [removed: 2019*] [added: 2020*] | | |
| [removed: 10.21] [added: 10.19] | | | | | | [removed: [2019] [added: [2020] Form of Restricted Share Units Award [removed: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367619000073/a1046-201910qcegrsufin.htm)] [added: Agreement](https://www.sec.gov/Archives/edgar/data/713676/000071367620000115/pnc-06302020xex1040.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.46] [added: 10.40] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended [removed: September] [added: June] 30, [removed: 2019*] [added: 2020*] | | |
| [removed: 10.22] [added: 10.26] | | | | | | [removed: [2019] [added: [2022] Form of Restricted Share Units Award Agreement [removed: -] [added: –] Senior Leader [removed: Program](http://www.sec.gov/Archives/edgar/data/713676/000071367619000073/a1047-201910qsection16.htm)] [added: Program](http://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1036-2022formofrestric.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.47] [added: 10.36] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended [removed: September] [added: June] 30, [removed: 2019*] [added: 2022*] | | |
| [removed: 10.23] [added: 10.24] | | | | | | [removed: [2020] [added: [2022] Form of Performance Share Units Award [removed: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367620000115/pnc-06302020xex1039.htm)] [added: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1034-2022formofperform.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.39] [added: 10.34] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, [removed: 2020*] [added: 2022*] | | |
| [removed: 10.24] [added: 10.20] | | | | | | [2020 Form of Restricted Share Units Award [removed: Agreement](https://www.sec.gov/Archives/edgar/data/713676/000071367620000115/pnc-06302020xex1040.htm)] [added: Agreement - Senior Leader Program](https://www.sec.gov/Archives/edgar/data/713676/000071367620000115/pnc-06312020xex1041.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.40] [added: 10.41] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2020* | | |
| [removed: 10.25] [added: 10.23] | | | | | | [removed: [2020] [added: [2021] Form of Restricted Share Units Award Agreement [removed: -] [added: –] Senior Leader [removed: Program](https://www.sec.gov/Archives/edgar/data/713676/000071367620000115/pnc-06312020xex1041.htm)] [added: Program](https://www.sec.gov/Archives/edgar/data/713676/000071367621000095/a1037-2021section16senio.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.41] [added: 10.37] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, [removed: 2020*] [added: 2021*] | | |
| [removed: 10.26] [added: 10.21] | | | | | | [2021 Form of Performance Share Units Award [removed: Agreement](https://www.sec.gov/Archives/edgar/data/713676/000071367622000019/ex1026-2021cegpsufinalfe.htm)] [added: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367622000019/ex1026-2021cegpsufinalfe.htm)] | | | | | | [removed: Filed herewith*] [added: Incorporated herein by reference to Exhibit 10.26 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2021*] | | |
| [removed: 10.27] [added: 10.28] | | | | | | [removed: [2021 Form] [added: [Form] of [removed: Restricted Share Units Award Agreement](https://www.sec.gov/Archives/edgar/data/713676/000071367621000095/a1036-202110qcegrsufinal.htm)] [added: Time Sharing Agreement between the Corporation and certain executives](http://www.sec.gov/Archives/edgar/data/713676/000071367622000047/ex1033-templatextimeshar.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.36] [added: 10.33] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended [removed: June 30, 2021*] [added: March 31, 2022*] | | |
| [removed: 10.30] [added: 10.29] | | | | | | [Form of change of control employment agreements](http://www.sec.gov/Archives/edgar/data/713676/000119312516683131/d241922dex1051.htm) | | | | | | Incorporated herein by reference to Exhibit 10.51 of the Corporation’s Current Report on Form 8-K filed August 16, 2016* | | |
| [removed: 10.31.1] [added: 10.30.1] | | | | | | [The National City Corporation 2004 Deferred Compensation Plan, as amended and restated effective January 1, 2005](http://www.sec.gov/Archives/edgar/data/69970/000095015206004116/l19873aexv10w35.txt) | | | | | | Incorporated herein by reference to Exhibit 10.35 of National City Corporation’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2006* | | |
| [removed: 10.32.1] [added: 10.31.1] | | | | | | [Distribution Agreement, dated January 16, 2014, between PNC Bank, National Association and the Dealers named therein, relating to the $25 billion Global Bank Note Program for the Issue of Senior and Subordinated Bank Notes](http://www.sec.gov/Archives/edgar/data/713676/000119312515070443/d836469dex1047.htm) | | | | | | Incorporated by reference to Exhibit 10.47 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2014 | | |
| [removed: 10.32.2] [added: 10.31.2] | | | | | | [Amendment No. 1 to Distribution Agreement, dated May 22, 2015, between PNC Bank, National Association and the Dealers named therein, relating to the $30 billion Global Bank Note Program for the Issue of Senior and Subordinated Bank Notes](http://www.sec.gov/Archives/edgar/data/713676/000119312515277885/d943118dex10472.htm) | | | | | | Incorporated herein by reference to Exhibit 10.47.2 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2015 | | |
[removed: 202] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [added: 205]
| [removed: 10.32.3] [added: 10.31.3] | | | | | | [Amendment No. 2 to Distribution Agreement, dated May 27, 2016, between PNC Bank, National Association and the Dealers named therein, relating to the $40 billion Global Bank Note Program for the Issue of Senior and Subordinated Bank Notes](http://www.sec.gov/Archives/edgar/data/713676/000119312516669661/d209081dex10483.htm) | | | | | | Incorporated herein by reference to Exhibit 10.48.3 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2016 | | |
| 21 | | | | | | [Schedule of Certain Subsidiaries of the [removed: Corporation](https://www.sec.gov/Archives/edgar/data/713676/000071367622000019/pnc-12312021xex21.htm)] [added: Corporation](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/pnc-12312022xex21.htm)] | | | | | | Filed herewith | | |
| 22 | | | | | | [Subsidiary Issuers of Guaranteed [removed: Securities](https://www.sec.gov/Archives/edgar/data/713676/000071367622000019/pnc-12302021xex22.htm)] [added: Securities](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/pnc-12312022xex22.htm)] | | | | | | Filed herewith | | |
| 23.1 | | | | | | [Consent of PricewaterhouseCoopers LLP, the Corporation’s Independent Registered Public Accounting [removed: Firm](https://www.sec.gov/Archives/edgar/data/713676/000071367622000019/a2021_pwcconsentletter.htm)] [added: Firm](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/exhibit231signed.htm)] | | | | | | Filed herewith | | |
| 24 | | | | | | [Powers of [removed: Attorney](https://www.sec.gov/Archives/edgar/data/713676/000071367622000019/a2021ex24powerofattorney.htm)] [added: Attorney](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/exhibit24.htm)] | | | | | | Filed herewith | | |
| 3.1.9 | | | | | | [Statement with Respect to Shares of the 6.000% Fixed-Rate Reset Non-Cumulative Perpetual Preferred Stock, Series U](http://www.sec.gov/Archives/edgar/data/713676/000071367622000039/exhibit31statementwithre.htm) | | | | | | Incorporated herein by reference to Exhibit 3.1 of the Corporation’s Current Report on Form 8-K filed April 26, 2022 | | |
| 3.1.10 | | | | | | [Statement with Respect to Shares of the 6.200% Fixed-Rate Reset Non-Cumulative Perpetual Preferred Stock, Series V](http://www.sec.gov/Archives/edgar/data/713676/000071367622000077/exhibit3.htm) | | | | | | Incorporated herein by reference to Exhibit 3.1 of the Corporation’s Current Report on Form 8-K filed August 19, 2022 | | |
| 3.1.11 | | | | | | [Statement with Respect to Shares of the 6.250% Fixed-Rate Reset Non-Cumulative Perpetual Preferred Stock, Series W](https://www.sec.gov/Archives/edgar/data/713676/000071367623000015/exhibit31.htm) | | | | | | Incorporated herein by reference to Exhibit 3.1 of the Corporation’s Current Report on Form 8-K filed February 7, 2023 | | |
| 4.7 | | | | | | [Deposit Agreement, dated as of April 26, 2022, between the Corporation, Computershare Trust Company, N.A. and Computershare Inc., as depositary, and the holders from time to time of the Depositary Receipts representing interests in the Series U preferred stock](http://www.sec.gov/Archives/edgar/data/713676/000071367622000039/exhibit41depositagreemen.htm) | | | | | | Incorporated herein by reference to Exhibit 4.1 of the Corporation’s Current Report on Form 8-K filed April 26, 2022 | | |
| 4.8 | | | | | | [Deposit Agreement, dated as of August 19, 2022, between the Corporation, Computershare Trust Company, N.A. and Computershare Inc., as depositary, and the holders from time to time of the Depositary Receipts representing interests in the Series V preferred stock](http://www.sec.gov/Archives/edgar/data/713676/000071367622000077/exhibit4.htm) | | | | | | Incorporated herein by reference to Exhibit 4.1 of the Corporation’s Current Report on Form 8-K filed August 19, 2022 | | |
| 4.9 | | | | | | [Deposit Agreement, dated as of February 7, 2023, between the Corporation, Computershare Trust Company, N.A. and Computershare Inc., as depositary, and the holders from time to time of the Depositary Receipts representing interests in the Series W preferred stock](http://www.sec.gov/Archives/edgar/data/713676/000071367623000015/exhibit41.htm) | | | | | | Incorporated herein by reference to Exhibit 4.1 of the Corporation’s Current Report on Form 8-K filed February 7, 2023 | | |
Audited consolidated financial statements of BlackRock, Inc. as of December 31, 2021 and 2020 and for each of the three years in the period ended December 31, 2021 are filed with this Report as Exhibit 99.1 and incorporated herein by reference.
| | | | | | | | | | | | | | | |
| 10.14 | | | | | | [Certificate of Corporate Action for Grantor Trusts effective December](https://www.sec.gov/Archives/edgar/data/713676/000071367622000019/a1014conformedexecutionv.htm) [1, 2021](https://www.sec.gov/Archives/edgar/data/713676/000071367622000019/a1014conformedexecutionv.htm) | | | | | | Filed herewith* | | |
| 10.28 | | | | | | [2021 Form of Restricted Share Units Award Agreement – Senior Leader Program](https://www.sec.gov/Archives/edgar/data/713676/000071367621000095/a1037-2021section16senio.htm) | | | | | | Incorporated herein by reference to Exhibit 10.37 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2021* | | |
| 10.29.1 | | | | | | [Time Sharing Agreement, dated as of November 15, 2017, by and between the Corporation and William S. Demchak](https://www.sec.gov/Archives/edgar/data/713676/000071367621000025/pnc-12312020xex10311.htm) | | | | | | Incorporated herein by reference to Exhibit 10.31.1 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2020* | | |
| 10.29.2 | | | | | | [Time Sharing Agreements Amendment and Termination Agreement, dated as of February 27, 2020, by and between the Corporation and William S. Demchak](https://www.sec.gov/Archives/edgar/data/713676/000071367621000025/pnc-12312020xex10312.htm) | | | | | | Incorporated herein by reference to Exhibit 10.31.2 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2020* | | |
| 10.31.2 | | | | | | [Amendment to The National City Corporation 2004 Deferred Compensation Plan, as amended and restated effective January 1, 2005](http://www.sec.gov/Archives/edgar/data/713676/000119312511051725/dex1056.htm) | | | | | | Incorporated herein by reference to Exhibit 10.56 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2010* | | |
| 23.2 | | | | | | [Consent of Deloitte & Touche LLP, Independent Registered Public Accounting Firm of BlackRock, Inc.](https://www.sec.gov/Archives/edgar/data/713676/000071367622000019/final2021pncconsent_vcle.htm) | | | | | | Filed herewith | | |
| 99.1 | | | | | | [Audited consolidated financial statements of BlackRock, Inc. as of December 31, 2021 and 2020 and for each of the three years ended December 31, 2021](https://www.sec.gov/Archives/edgar/data/713676/000071367622000019/pncex991blackrock_financ.htm) | | | | | | Filed herewith | | |
An excerpt. Shown here: 40 of 44 rewritten, all 6 added and all 9 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES in the FY2022 filing and the FY2021 filing.
Item 16. FORM 10-K SUMMARY
5 rewritten, 2 added, 2 removed, 27 unchanged
[added: 206] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [removed: 203]
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of The PNC Financial Services Group, Inc. and in the capacities indicated on February [removed: 25, 2022.][added: 22, 2023.]
| * Joseph Alvarado; [removed: Charles E. Bunch;] Debra A. Cafaro; Marjorie Rodgers Cheshire; Andrew T. Feldstein; Richard J. Harshman; Daniel R. Hesse; [added: Renu Khator,] Linda R. Medler, Robert A. Niblock, Martin Pfinsgraff; Bryan Salesky, Toni Townes-Whitley; Michael J. Ward | | | | | | Directors | | |
| | | | | | | [removed: Alicia Powell,] [added: Laura Gleason,] Attorney-in-Fact, pursuant to Powers of Attorney filed herewith | | |
[removed: 204] The PNC Financial Services Group, Inc. – [removed: *2021] [added: *2022] Form 10-K* [added: 207]
| | | | | | | February 22, 2023 | | |
| *By: | | | | | | /s/ Laura Gleason | | |
| | | | | | | February 25, 2022 | | |
| *By: | | | | | | /s/ Alicia Powell | | |