 filings.tools
PNC Financial Services Group (PNC) 10-K risk factor changes: FY2023 vs FY2022
The 2023-12-31 10-K against the 2022-12-31 one, compared heading by heading and sentence by sentence.
Item 1A115 rewritten50 added131 removed398 unchanged
All filing items2,727 rewritten1,175 added1,156 removed4,102 unchanged
Summary
counted, not written
- Item 1A lists 29 risk factor headings: 2 new, 5 reworded and 22 unchanged since FY2022. 2 headings from FY2022 no longer appear.
- Sentence by sentence, 1,175 added, 1,156 removed, 2,727 rewritten and 4,102 unchanged across 21 items that differ.
- New this year: Item 1C. CYBERSECURITY.
New Item 1A headings (2)
- Our ability to operate our business could be impaired if our liquidity is unexpectedly constrained.
- We are vulnerable to the risk of breaches of data security affecting the functioning of systems or the confidentiality of information that could adversely affect our customers and our business.
Removed Item 1A headings (2)
- The scheduled cessation of LIBOR presents risks to the financial instruments originated, held or serviced by PNC that use LIBOR as a reference rate.
- We are vulnerable to the risk of third-party breaches of data security affecting the functioning of systems or the confidentiality of information, either at PNC or at third parties handling PNC information.
Reworded Item 1A headings (5)
- As a regulated financial services firm, we are subject to numerous governmental regulations and comprehensive oversight by a variety of regulatory agencies and enforcement authorities. These regulations and
[removed: the way they are implemented][added: their implementation] can have a significant impact on our businesses and operations and our ability to grow and expand. - Privacy [added: and consumer data rights] initiatives have imposed and will continue to impose additional operational burdens on PNC, and they may limit our ability to pursue desirable business initiatives and increase the risks associated with any future use of personal data.
- There are risks resulting from the extensive use of
[removed: models][added: models, some of which use artificial intelligence (AI),] in our business. - We rely on third-party vendors, service providers and other counterparties to help support many aspects of our business. When we do so, our direct control of activities related to our business is reduced, which
[removed: could introduce][added: introduces] risk. - We grow our business in part by acquiring other financial services businesses from time to time. Sometimes these are businesses with technologies or other assets valuable to us even if they do not themselves provide financial services to customers.
[removed: These acquisitions][added: Acquisitions] present a number of risks and uncertainties related both to the acquisition transactions themselves and to the integration of the acquired businesses into PNC after closing.
A heading is new when no FY2022 heading matches it after ignoring case and punctuation, and reworded when it shares at least 60 percent of its words with one that went away. All current risk factor headings.
Sentences by item
23 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2023; struck-through words were in FY2022. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
115 rewritten, 50 added, 131 removed, 398 unchanged
[removed: - We are subject to risks related to growing our business by acquiring other financial services business from time to time as these acquisitions] [added: Acquisitions] present a number of risks and uncertainties related both to the acquisition transactions themselves and to the integration of the acquired businesses into PNC after [removed: closing.][added: closing.]
[removed: As a financial services company,] [added: Given the nature of] our [added: business, our] business and overall financial performance are affected to a significant extent by economic conditions, primarily in the U.S. [added: Declining or adverse economic conditions and adverse changes in investor, consumer and business sentiment generally result in reduced business activity, which may decrease the demand for our products and services or reduce the number of creditworthy borrowers.]
The ability of borrowers to repay loans is often weakened as a result of economic [removed: downturns and] [added: downturns,] higher inflation and unemployment.
This may be further exacerbated by [removed: the expiration of pandemic-related government assistance in the U.S., which could lead to] a [removed: decrease in economic activity and a] deterioration in households’ finances, particularly if consumers also continue to face high inflation.
In addition, [added: adverse economic conditions, including] periods of [removed: inflation] [added: inflation,] may [removed: affect certain of our costs] [added: limit the availability of,] or [removed: expenses (including increasing our cost of] [added: increase the costs of,] capital and [removed: labor),] [added: labor,] erode consumer and customer purchasing power, confidence and spending and may also reduce our tolerance for extending credit.
[added: 16] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 15]
We are, however, susceptible to the risk that foreign economic conditions [added: and geopolitical tensions] could negatively affect our business and financial performance.
In addition, the application of some laws may be uncertain, require significant judgment and be [removed: subject to differing interpretations.]
These regulations and [removed: the way they are implemented] [added: their implementation] can have a significant impact on our businesses and operations and our ability to grow and expand.”
Divided control of the U.S. government [removed: may increase] [added: increases] concern over the inability of Congress and the President to reach necessary agreements and make government shutdowns or defaults in government obligations more likely.
These policies can thus affect the activities and results of operations of financial [added: companies such as PNC.]
[removed: 16] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [added: 17]
These regulations and [removed: the way they are implemented] [added: their implementation] can have a significant impact on our businesses and operations and our ability to grow and expand.
Legislative or regulatory actions [removed: can] [added: have resulted and will likely continue to] result in increased compliance costs, reduced business opportunities, or [removed: new] requirements and limitations on how we conduct our business.
In particular, the financial services industry continues to face heightened scrutiny, [removed: particularly] [added: including] with respect to BSA and AML compliance [removed: requirements and] [added: requirements,] consumer compliance and protection [removed: matters.][added: matters (such as with respect to overdraft and other fees), and capital, liquidity and resolution planning in response to turmoil in the banking]
The results of [removed: routine and non-routine] supervisory or examination activities by our regulators, including actual or perceived compliance failures, could result in limitations on our ability to enter into certain transactions, engage in new activities, expand geographically, make acquisitions or obtain necessary regulatory approvals in connection therewith, or otherwise require us to modify our businesses practices in a manner that materially impacts our financial condition or results of operations.
Different approaches to regulation by different [removed: jurisdictions] [added: jurisdictions, including potentially conflicting state-level regulation,] could materially increase our compliance costs or risks of non-compliance.
We also rely on third parties who may expose us to compliance [added: risk.]
[added: 18] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 17]
Also see the Supervision and Regulation section of this Report [added: and Note 19 Regulatory Matters] for more information concerning the regulation of PNC, including those areas that have been receiving a high level of regulatory focus.
For example, downgrades could negatively impact our right to continue to service [removed: mortgages.][added: mortgages and hold related escrows and reserves.]
[removed: 18] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [added: 19]
For [removed: more] information on our [removed: LIBOR reference rate assets,] [added: liquidity management,] see the [removed: Market Risk] [added: Liquidity and Capital] Management portion of the Risk Management section of this Report.
[added: 20] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 19]
Privacy [added: and consumer data rights] initiatives have imposed and will continue to impose additional operational burdens on PNC, and they may limit our ability to pursue desirable business initiatives and increase the risks associated with any future use of personal data.
[removed: Recently,] [added: Over time,] there has been an increase in legislative and regulatory efforts to protect the privacy [added: and enhance the portability] of personal data, including enhanced data privacy laws regulating the use of health and biometric data.
These initiatives, among other things, limit how companies can use personal data and impose obligations on companies in their management of such [added: data, including requiring companies like PNC to make available to consumers and authorized third parties certain data relating to transactions and accounts and establishing obligations for accessing such] data.
There continues to be concern, including on the part of our regulators, regarding climate change and its impacts [removed: on virtually all aspects of life] over the short-, medium- and long-term horizons.
These concerns over the anticipated and unanticipated impacts of climate change (including physical risk and transition risk) have led and will continue to lead to governmental efforts [removed: around the world] to mitigate those impacts.
[removed: We and our customers] may face cost increases, asset value reductions, [added: the reduced availability of insurance,] operations disruptions and changes and the like because of climate change (including [removed: severe] [added: because of the increased frequency or severity of acute] weather [removed: events)] [added: events] and [added: long-term shifts in the climate) and] governmental actions or societal responses to climate change.
Changed consumer and business behavior because of climate change concerns creates transition risk for PNC arising from the process of adjusting to these [removed: concerns, including transitioning to a low-carbon economy.][added: concerns.]
We also have been and may continue to be subject to [added: conflicting] pressure from [removed: individuals or] [added: individuals,] groups [added: and/or governmental entities] to cease doing [removed: business] [added: business, or to maintain business,] with certain companies or [removed: sectors] [added: sectors, in particular those involved with fossil fuels,] because of concerns related to climate change.
We may [added: also] incur additional costs and require additional resources as we evolve our strategy, practices and related disclosures with respect to these matters.
[removed: 20] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [added: 21]
The Risk Factor headed “We are at risk for an adverse impact on our business due to damage to our reputation” further discusses risks associated with our management of [removed: environmental, social and governance] [added: these] matters, including related activist pressure.
Our risk management [added: needs to continue to evolve, or it] may not be effective in identifying, measuring, monitoring and controlling climate risk exposure, particularly given that the timing, nature and severity of the impacts of climate change may not be predictable.
As a result of these factors, the financial services industry [removed: is undergoing] [added: continues to undergo] rapid technological change with frequent introductions of new technology-driven products and services.
Examples include expanded use of cloud computing, artificial intelligence and machine learning, [removed: virtual and augmented reality,] biometric authentication, voice and natural language, data protection enhancements and increased online and mobile device interaction with customers, including innovative ways that customers can [added: view, access and aggregate financial data,] make payments or manage their accounts.
Over time, there have been and continue to be instances where technology used by PNC [removed: and other financial institutions] has been alleged to have infringed patents held by others, and, in some cases, [removed: we, as well as other financial institutions,] [added: we] have suffered related losses.
Effective management of our expanded [added: digital products and services, geographic footprint and continued] remote work environment heightens our need for secure, reliable and adequate information systems and technology.
For more information about how we manage risks, see the Risk Management section of this Report.
We operate in an uncertain economic environment due to structural and secular changes triggered by the pandemic for certain sectors of the economy combined with increased interest rates, inflation and geopolitical tensions.
For example, as remote work continues to be a feasible alternative to pre-pandemic in-office work arrangements, notable portions of available commercial real estate space remain underutilized.
This likely decreases demand for financial services in that sector and harms the creditworthiness of some of our office commercial real estate customers, as well as businesses whose customers have historically been office workers.
subject to differing interpretations.
Since 2022, the Federal Reserve’s quantitative tightening and increases in benchmark rates to reduce high rates of inflation has and may continue to adversely affect the value of financial instruments and other assets and liabilities, including securities and interest-bearing deposits, impact borrowers, increase market volatility and result in a flattening or inversion of the yield curve.
industry in early 2023.
In addition, heightened standards under proposed and recently finalized rules, such as those implementing the Community Reinvestment Act, may result in increased obligations and compliance costs, and may factor into our ability to expand and engage in new actions.
Federal law grants substantial supervisory and enforcement powers to federal banking regulators, and they have assumed an active oversight, examination and enforcement role across the financial services industry.
In July 2023, the Federal Reserve, OCC, and FDIC proposed for public comment a rule to implement the final components of the Basel III framework that would significantly revise the capital requirements for large banking organizations, including PNC and PNC Bank.
We expect the proposal, if finalized in its current form, would result in lower regulatory capital ratios for PNC and PNC Bank, which would likely increase the risk of some of the potential adverse effects described above.
Our ability to operate our business could be impaired if our liquidity is unexpectedly constrained.
Our liquidity could be impaired as a result of unanticipated outflows of cash or collateral, unexpected loss of consumer deposits or higher than anticipated draws on lending-related commitments, an inability to sell assets (or to sell assets at favorable times or prices), a default by a counterparty or other market participant, our inability to access other sources of liquidity, including through the capital markets due to unforeseen market dislocations or interruptions, or a lack of market or customer confidence in PNC or financial institutions in general.
Many of the above conditions and factors may be caused by events over which we have little or no control.
The increased speed with which information is disseminated, through official or social media, could increase the speed or severity of liquidity pressures caused by, for example, negative news about PNC’s or other financial institutions’ financial prospects or safety and soundness.
A negative impact on our liquidity would likely limit our ability to support our operations and fund outstanding liabilities as well as meet regulatory expectations, which would adversely affect our financial condition and results of operations.
We and our customers
Our stakeholders may disagree with these policies and goals or, conversely, believe that these policies and goals are, and our related progress in accomplishing such goals and implementing such policies is, insufficient.
This may lead to a decrease in demand for our products and services or damage to our reputation.
In addition, there are and will continue to be challenges related to capturing, verifying, analyzing and disclosing climate-related data that is subject to measurement uncertainties.
This effort has involved and is likely to continue to involve the expenditure of considerable amounts of funds and other resources, which could be constrained to the extent that sustained adverse economic conditions and other factors described elsewhere in these Risk Factors negatively impact our business or financial performance.
Where we rely on access to third-party intellectual property, it may not be available to us on commercially reasonably terms or at all.
For example, we are likely to be limited in our ability to identify and quickly resolve breaches and attacks that may impact our business the further removed an entity is from our business, such as when a breach or attack occurs at vendors of our vendors.
Under these agreements, we may
These types of phishing attacks have increased over time, and they have evolved to include other types of attacks like vishing (through voice messages) and smishing (through SMS text).
Similarly, attacks have been conducted through application program interfaces where cyber attackers seek to exploit the interfaces between mobile or web applications.
We have seen a higher volume
and complexity of attacks during times of increased geopolitical tensions.
For example, the recent resumption in federal student loan payments could impact a borrower’s ability to repay a loan, such as a mortgage, because of the financial pressure from student loan payments.
Either set of conditions is not likely to be sustained and may obscure actual current operations and financial performance.
The Risk Factor headed “There are risks resulting from the extensive use of models, some of which use artificial intelligence (AI), in our business” further discusses risks associated with estimating expected losses under CECL.
While there are limitations on the extent of total exposure to an individual consumer or business borrower, events adversely affecting some of our clients or counterparties, based on individual factors or the nature or location of their business, or asset classes or financial markets in which we are involved, could materially and adversely affect us.
Higher interest rates also have hindered and may continue to hinder the ability of borrowers to support interest payments on variable rate loans.
the financial markets or market volatility as well as developments specific to the asset or liability in question.
We increasingly use models related to how we do business with customers and for internal process automation that leverage AI/machine learning algorithms.
These models can be more predictive, but because of the complex way in which the many variables in AI/machine learning models interact, the results of these models are often less interpretable than traditional statistical models.
Other models are used to support decisions made regarding how we do business with customers.
Demand for our products and services could also suffer as many of the risks to PNC related to the economy and other external factors, including regulation, such as changes to tax laws and tax rates, could negatively impact consumers and businesses and their interest in or ability to use our products and services.
In some circumstances, our stakeholders have held and continue to hold conflicting views on the role PNC and other financial services companies should play in continuing to or refraining from financing certain sectors.
In some cases, we are subject to potentially conflicting proposed and enacted state and local laws affecting our industry that regulate the manner in which or whether we may finance or service certain clients, industries or sectors.
Our success is dependent on our ability to identify, understand and manage the risks presented by our business activities so that we can appropriately balance risk taking with revenue generation and profitability.
We discuss our principal risk management oversight and processes and, in appropriate places, related historical performance and other metrics in the Risk Management section of this Report.
Summary
The following is a summary of the Risk Factors in this Item 1A:
- Our business and financial performance are vulnerable to the impact of adverse economic conditions.
- The policies of the Federal Reserve and other governmental agencies and the impact of government legislation, regulation and policy and other political factors on the economy, interest rates, overall financial market performance and banking organizations could have an adverse effect on our business and financial performance and our ability to pay dividends or otherwise return capital to shareholders.
- A downgrade in our credit ratings could significantly impact our liquidity, funding costs and access to the capital markets.
- The scheduled cessation of LIBOR presents risks to the financial instruments originated, held or serviced by PNC that use LIBOR as a reference rate.
- Climate change-related risks could adversely affect our business and performance, including indirectly through impacts on our customers.
- We are subject to risks related to the use of technology which is critical to our ability to maintain or enhance the competitiveness of our businesses and is dependent on having the right to use its underlying intellectual property.
We could also suffer a material adverse impact from interruptions in the effective operation of our information systems and other technology, including as a result of third-party breaches of data security either at PNC or at third parties handling PNC information.
- Our business and financial results are subject to risks associated with the creditworthiness of our customers and counterparties, the concentration and mix of our assets, market interest rates and movements in those rates and changes in the values of financial assets.
- We are subject to risks related to the selection of accounting methods, inaccurate estimates and assumptions and to risks related to poorly designed and implemented models that are extensively used in our business.
- We operate in a highly competitive environment and our success depends on our ability to attract and retain customers and talented employees and we are at risk for an adverse impact on our business due to damage to our reputation.
- We are subject to operational risks as a result of our dependence on the effectiveness and integrity of our employees and internal systems and on third-party vendors, service providers and other counterparties over whom we do not have direct control.
Declining or adverse economic conditions and adverse changes in investor, consumer and business sentiment generally result in reduced business activity, which may decrease the demand for our products and services or reduce the number of creditworthy borrowers.
While the U.S. economy has generally improved since the onset of the COVID-19 pandemic, we now operate in an uncertain economic environment as a result of the impacts of the pandemic and responsive measures to manage it, high inflation, supply chain disruptions, changes in the labor markets, volatile energy prices and geopolitical tensions (including as a result of the Russia-Ukraine conflict).
For example, shifting consumer behavior with respect to retail purchases being made over the internet rather than in physical stores has negatively impacted performance by some retailers.
This likely decreases demand for financial services in that sector, possibly harming the creditworthiness of some shopping mall operators, retail companies and others with whom we do business.
As another example, we could experience an increase in credit losses as a result of structural and secular changes fostered by the pandemic for certain sectors of the economy.
In addition, remote work has adversely affected and may continue to adversely affect commercial real estate, as well as businesses whose customers have historically been office workers.
Affected companies have experienced and may continue to experience lower levels of business and possible declining creditworthiness.
Some of the legislation responsive to the COVID-19 pandemic (such as the CARES Act and the Consolidated Appropriations Act that provided for certain commercial and consumer protections) altered the profitability of the transactions in which we engage, and other laws related to employee benefits increased administrative, compensation and benefits costs to us.
Other such laws may be enacted in response to other extraordinary events beyond PNC’s control that have similar or broader effects on us and could adversely affect our financial condition and results of operations, possibly materially, in other ways that are not now known to us.
companies such as PNC.
The FOMC has increased its benchmark rates from a range of 0% to 0.25% from March 2020 through 2021 to 4.75% as of February 1, 2023 in an effort to reduce high rates of inflation.
Although we may not accurately predict the nature or timing of future changes in monetary policies or the precise effects that they may have on our activities and financial results, we anticipate that the FOMC will increase the federal funds rate by an additional 25 basis points in March.
This would bring the federal funds rate to a range of 4.75% to 5.00% by mid-March.
We expect a federal funds rate cut of 25 basis points in early 2024 as inflation moves toward the FOMC’s 2% long-term objective.
For example, under Dodd-Frank, the CFPB has broad authority to protect consumers from “unfair, deceptive and abusive acts or practices,” the definition of which is being clarified through heightened instances of CFPB enforcement actions and proceedings.
Federal law grants substantial supervisory and enforcement powers to federal banking regulators.
risk.
Note 20 Regulatory Matters also discusses some of the regulations applicable to us.
The Basel Committee continues to develop policies and standards for the prudential regulation of banks.
See the Supervision and Regulation section of this Report.
Generally, as it is unclear whether or how these initiatives will be implemented in the U.S., we are unable to estimate what potential impact such initiatives may have on us.
We expect the federal banking agencies to propose rules in 2023 to implement the capital- and liquidity-related final set of Basel III standards issued by the Basel Committee in December 2017.
For example, under the 2019 Tailoring Rules, certain BHCs are classified as Category I, Category II, Category III or Category IV firms.
While PNC and PNC Bank currently are Category III firms, if PNC or PNC Bank became a Category I or II institution, we would be subject to more stringent capital and liquidity standards, which would likely increase some of the potential adverse effects described above.
Future changes to the capital and liquidity rules to require PNC or PNC Bank to maintain more or higher quality capital or greater liquidity would also likely increase some of the potential adverse effects described above.
An excerpt. Shown here: 40 of 115 rewritten, 40 of 50 added and 40 of 131 removed. The counts are complete. For every sentence, read Item 1A. RISK FACTORS in the FY2023 filing and the FY2022 filing.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (MD&A)
717 rewritten, 327 added, 318 removed, 837 unchanged
Our capital and liquidity priorities are to support customers, fund business investments and return excess capital to shareholders, while maintaining appropriate capital [added: and liquidity] in light of economic conditions, the Basel III framework and other regulatory expectations.
- Actions we take within the capital and other financial [removed: markets.][added: markets,]
[removed: 36] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [added: 37]
[added: 38] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 37]
| Dollars in millions, except per share data | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | | | | | | | | | | | | | | | | |
| Net interest income | | | $ | [removed: 13,014] [added: 13,916] | | | | | $ | [removed: 10,647] [added: 13,014] | | | | | $ | [removed: 9,946] [added: 10,647] | | | | | | | | | | | | | | | | |
| Noninterest income | | | [removed: 8,106] [added: 7,574] | | | | | | [removed: 8,564] [added: 8,106] | | | | | | [removed: 6,955] [added: 8,564] | | | | | | | | | | | | | | | | | |
| Total revenue | | | [removed: 21,120] [added: 21,490] | | | | | | [removed: 19,211] [added: 21,120] | | | | | | [removed: 16,901] [added: 19,211] | | | | | | | | | | | | | | | | | |
| Provision for (recapture of) credit losses | | | [removed: 477] [added: 742] | | | | | | [removed: (779)] [added: 477] | | | | | | [removed: 3,175] [added: (779)] | | | | | | | | | | | | | | | | | |
| Noninterest expense | | | [removed: 13,170] [added: 14,012] | | | | | | [removed: 13,002] [added: 13,170] | | | | | | [removed: 10,297] [added: 13,002] | | | | | | | | | | | | | | | | | |
| Income [removed: from continuing operations] before income taxes and noncontrolling interests | | | [removed: 7,473] [added: 6,736] | | | | | | [removed: 6,988] [added: 7,473] | | | | | | [removed: 3,429] [added: 6,988] | | | | | | | | | | | | | | | | | |
| Income taxes [removed: from continuing operations] | | | [removed: 1,360] [added: 1,089] | | | | | | [removed: 1,263] [added: 1,360] | | | | | | [removed: 426] [added: 1,263] | | | | | | | | | | | | | | | | | |
| Net income [removed: from continuing operations] | | | [removed: 6,113] [added: $] | [added: 5,647] | | | | | [removed: 5,725] [added: $] | [added: 6,113] | | | | | [removed: 3,003] [added: $] | [added: 5,725] | | | | | | | | | | | | | | | | |
| Net income attributable to common shareholders | | | $ | [removed: 5,735] [added: 5,153] | | | | | $ | [removed: 5,436] [added: 5,735] | | | | | $ | [removed: 7,284] [added: 5,436] | | | | | | | | | | | | | | | | |
| Diluted earnings [removed: from continuing operations] | | | $ | [removed: 13.85] [added: 12.79] | | | | | $ | [removed: 12.70] [added: 13.85] | | | | | $ | [removed: 6.36] [added: 12.70] | | | | | | | | | | | | | | | | |
| Book value per common share | | | $ | [removed: 99.93] [added: 112.72] | | | | | $ | [removed: 120.61] [added: 99.93] | | | | | $ | [removed: 119.11] [added: 120.61] | | | | | | | | | | | | | | | | |
| Tangible book value per common share (non-GAAP) (a) | | | $ | [removed: 72.12] [added: 85.08] | | | | | $ | [removed: 94.11] [added: 72.12] | | | | | $ | [removed: 97.43] [added: 94.11] | | | | | | | | | | | | | | | | |
| Net interest margin (non-GAAP) (b) | | | [removed: 2.65] [added: 2.76] | | % | | | | [removed: 2.29] [added: 2.65] | | % | | | | [removed: 2.53] [added: 2.29] | | % | | | | | | | | | | | | | | | |
| Noninterest income to total revenue | | | [removed: 38] [added: 35] | | % | | | | [removed: 45] [added: 38] | | % | | | | [removed: 41] [added: 45] | | % | | | | | | | | | | | | | | | |
| Efficiency | | | [removed: 62] [added: 65] | | % | | | | [removed: 68] [added: 62] | | % | | | | [removed: 61] [added: 68] | | % | | | | | | | | | | | | | | | |
| Average common shareholders’ equity | | | [removed: 13.52] [added: 12.35] | | % | | | | [removed: 10.78] [added: 13.52] | | % | | | | [removed: 15.21] [added: 10.78] | | % | | | | | | | | | | | | | | | |
| Average assets | | | [removed: 1.11] [added: 1.01] | | % | | | | [removed: 1.09] [added: 1.11] | | % | | | | [removed: 1.68] [added: 1.09] | | % | | | | | | | | | | | | | | | |
(a)See explanation and reconciliation of this non-GAAP measure in [added: the] Reconciliation of Tangible Book Value Per Common Share (non-GAAP) Statistical Information (Unaudited) section in Item 8 of this Report.
(b)See explanation and reconciliation of this non-GAAP measure in [added: the] Average Consolidated Balance Sheet and Net Interest Analysis and Reconciliation of Taxable-Equivalent Net Interest Income (non-GAAP) Statistical Information (Unaudited) section in Item 8 of this Report.
| Dollars in millions, except as noted | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | | | | | | | | | | | | | | | | | | |
| Assets | | | $ | [removed: 557,263] [added: 561,580] | | | | | $ | [removed: 557,191] [added: 557,263] | | | | | | | | | | | | | | | | | | | | | | |
| Loans | | | $ | [removed: 326,025] [added: 321,508] | | | | | $ | [removed: 288,372] [added: 326,025] | | | | | | | | | | | | | | | | | | | | | | |
| Allowance for loan and lease losses | | | $ | [removed: 4,741] [added: 4,791] | | | | | $ | [removed: 4,868] [added: 4,741] | | | | | | | | | | | | | | | | | | | | | | |
| Interest-earning deposits with banks | | | $ | [removed: 27,320] [added: 43,804] | | | | | $ | [removed: 74,250] [added: 27,320] | | | | | | | | | | | | | | | | | | | | | | |
| Investment securities | | | $ | [removed: 139,334] [added: 132,569] | | | | | $ | [removed: 132,962] [added: 139,334] | | | | | | | | | | | | | | | | | | | | | | |
| Total deposits | | | $ | [removed: 436,282] [added: 421,418] | | | | | $ | [removed: 457,278] [added: 436,282] | | | | | | | | | | | | | | | | | | | | | | |
| Borrowed funds | | | $ | [removed: 58,713] [added: 72,737] | | | | | $ | [removed: 30,784] [added: 58,713] | | | | | | | | | | | | | | | | | | | | | | |
| Total shareholders’ equity | | | $ | [removed: 45,774] [added: 51,105] | | | | | $ | [removed: 55,695] [added: 45,774] | | | | | | | | | | | | | | | | | | | | | | |
| Common shareholders’ equity | | | $ | [removed: 40,028] [added: 44,864] | | | | | $ | [removed: 50,685] [added: 40,028] | | | | | | | | | | | | | | | | | | | | | | |
| Common equity Tier 1 | | | [removed: 9.1] [added: 9.9] | | % | | | | [removed: 10.3] [added: 9.1] | | % | | | | | | | | | | | | | | | | | | | | | |
| Dividend payout | | | [removed: 41.7] [added: 47.8] | | % | | | | [removed: 37.8] [added: 41.7] | | % | | | | | | | | | | | | | | | | | | | | | |
| Loans to deposits | | | [removed: 75] [added: 76] | | % | | | | [removed: 63] [added: 75] | | % | | | | | | | | | | | | | | | | | | | | | |
| Common shareholders’ equity to total assets | | | [removed: 7.2] [added: 8.0] | | % | | | | [removed: 9.1] [added: 7.2] | | % | | | | | | | | | | | | | | | | | | | | | |
| Average common shareholders’ equity to average assets | | | [removed: 7.7] [added: 7.5] | | % | | | | [removed: 9.6] [added: 7.7] | | % | | | | | | | | | | | | | | | | | | | | | |
[removed: 38] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [added: 39]
- Global and domestic economic conditions,
Signature Bank Portfolio Acquisition
On October 2, 2023, PNC acquired a portfolio of capital commitments facilities from Signature Bridge Bank, N.A. through an agreement with the FDIC as receiver of the former Signature Bank, New York.
The acquired portfolio represented approximately $16.0 billion in total commitments, including approximately $9.0 billion of funded loans, at the time of acquisition.
Workforce Reduction
During the fourth quarter of 2023, PNC implemented a workforce reduction that is expected to reduce 2024 personnel expense by approximately $325 million annually, on a pre-tax basis.
PNC incurred expenses of $150 million in the fourth quarter of 2023 in connection with this workforce reduction.
FDIC Special Assessment
In November 2023, the FDIC approved a final rule to implement a special assessment to recover the loss to the Deposit Insurance Fund associated with protecting uninsured depositors following the closures of Silicon Valley Bank and Signature Bank.
PNC
incurred an expense on a pre-tax basis of $515 million during the fourth quarter of 2023 representing the total estimated cost of the assessment.
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
The decrease also included negative Visa Class B derivative fair value adjustments of $279 million for 2023 compared to $40 million of negative adjustments for 2022.
- Provision for credit losses was $742 million in 2023, primarily driven by portfolio activity, including changes in credit quality related to the commercial real estate portfolio.
Provision for credit losses was $477 million in 2022.
- Noninterest expense increased $842 million, or 6%, to $14.0 billion, and included $515 million pertaining to the FDIC special assessment for the recovery of losses related to the closures of Silicon Valley Bank and Signature Bank as well as $150 million of workforce reduction charges.
- Total loans decreased $4.5 billion, to $321.5 billion.
- Total commercial loans decreased $5.5 billion, or 2%, to $219.6 billion, driven by lower utilization of loan commitments and paydowns outpacing new production, partially offset by the acquisition of capital commitment facilities from Signature Bridge Bank, N.A. on October 2, 2023.
- Investment securities decreased $6.8 billion, or 5%, to $132.6 billion, as limited purchase activity was more than offset by portfolio paydowns and maturities.
- Borrowed funds of $72.7 billion increased $14.0 billion, or 24%, due to parent company senior debt issuances and higher FHLB borrowings.
The slight increase in reserves was primarily driven by portfolio activity, including changes in credit quality related to the commercial real estate portfolio, partially offset by an updated economic outlook.
- Net charge-offs of $710 million or 0.22% of average loans in 2023 increased $147 million compared to net charge-offs of $563 million or 0.18% of average loans for 2022, reflecting higher commercial and consumer net loan charge-offs.
- Common shareholders’ equity increased $4.9 billion to $44.9 billion at December 31, 2023, due to the benefit of net income and an improvement in AOCI, partially offset by common dividends paid and common share repurchases.
In light of the Federal banking agencies proposed rules to adjust the Basel III capital framework, share repurchase activity is expected to remain modest during the first quarter of 2024.
PNC continues to evaluate the potential impact of the proposed rules and may adjust share repurchase activity depending on market and economic conditions, as well as other factors.
The estimated fully implemented ratios reflect the full impact of CECL and exclude the benefits of this transition provision.
The estimated CET1 fully implemented ratio was 9.8% at December 31, 2023 compared to 8.9% at December 31, 2022.
- PNC’s baseline forecast is for slower economic growth in 2024 as consumer spending growth slows and higher interest rates remain a drag on the economy.
The ongoing strength of the labor market will continue to support consumer spending.
Slowing inflation will allow for federal funds rate cuts starting in the late spring or early summer; this will support economic growth in the second half of 2024.
- GDP growth this year will be below trend at slightly above 1%, and the unemployment rate will increase modestly to somewhat above 4% by the end of 2024.
- PNC expects the federal funds rate to remain unchanged in the first part of 2024, between 5.25% and 5.50%, with federal funds rate cuts starting in May 2024 as inflation slows further.
PNC expects the federal funds rate to end 2024 between 4.25% and 4.50%.
- Spot loans to be up 3% to 4%,
- Noninterest income, excluding net securities gains and Visa activity, to be up 4% to 6%,
- Global and domestic economic conditions, including the length and extent of the economic impacts of the COVID-19 pandemic, and the actions taken to mitigate and manage it,
For additional information on the acquisition of BBVA, see Note 2 Acquisition and Divestiture Activity.
Discontinued Operations
In the second quarter of 2020, PNC divested its entire 22.4% equity investment in BlackRock.
Net proceeds from the sale were $14.2 billion with an after-tax gain on sale of $4.3 billion.
BlackRock’s historical results are reported as discontinued operations.
For additional details on the divestiture of our equity investment in BlackRock, see Note 2 Acquisition and Divestiture Activity.
| Income from discontinued operations before taxes | | | | | | | | | | | | | | | 5,777 | | | | | | | | | | | | | | | | | |
| Income taxes from discontinued operations | | | | | | | | | | | | | | | 1,222 | | | | | | | | | | | | | | | | | |
| Net income from discontinued operations | | | | | | | | | | | | | | | 4,555 | | | | | | | | | | | | | | | | | |
| Net income | | | $ | 6,113 | | | | | $ | 5,725 | | | | | $ | 7,558 | | | | | | | | | | | | | | | | |
| Diluted earnings from discontinued operations | | | | | | | | | | | | | | | $ | 10.60 | | | | | | | | | | | | | | | | |
| Total diluted earnings | | | $ | 13.85 | | | | | $ | 12.70 | | | | | $ | 16.96 | | | | | | | | | | | | | | | | |
- Provision for credit losses was $477 million in 2022, driven by our weakened economic outlook along with loan growth, partially offset by the impacts from the reassessment of pandemic-related risks and credit quality improvement in the portfolio.
Provision recapture was $779 million for 2021.
- Noninterest expense increased $168 million to $13.2 billion, reflecting the addition of a full year of BBVA operating expenses and continued business investment.
The increase was partially offset by lower integration expenses.
- Total assets were stable.
- Total loans increased $37.7 billion, or 13%, to $326.0 billion.
- Total commercial loans grew $32.0 billion, or 17%, to $225.0 billion, due to new production and higher utilization of loan commitments, partially offset by PPP loan forgiveness.
- PNC had $0.4 billion of PPP loans outstanding at December 31, 2022, compared to $3.4 billion at December 31, 2021.
- Investment securities increased $6.4 billion, or 5%, to $139.3 billion due to net purchases, primarily of agency residential mortgage-backed securities, partially offset by a decline in valuation driven by interest rates.
- Borrowed funds of $58.7 billion increased $27.9 billion, or 91%, due to higher FHLB borrowings, partially offset by lower senior debt.
The decrease was primarily driven by the reassessment of pandemic-related risks and improvements in credit quality, partially offset by our weakened economic outlook along with loan growth.
- Net charge-offs of $563 million or 0.18% of average loans in 2022 decreased 14% compared to net charge-offs of $657 million or 0.24% of average loans for 2021.
The decline was primarily driven by fewer commercial net charge-offs, partially offset by higher consumer net charge-offs due to a decrease in recoveries.
Net charge-offs in the comparative period included BBVA-related charge-offs resulting from required purchase accounting treatment.
- Common shareholders’ equity decreased to $40.0 billion at December 31, 2022, compared to $50.7 billion at December 31, 2021 as the benefit of net income was more than offset by a decrease in AOCI, reflecting the negative impact of higher interest rates on securities and swap values.
The decline was also attributable to share repurchases and common dividends paid.
◦The SCB framework allows for capital returns in amounts up to the level of capital in excess of the firm’s SCB plus the regulatory minimum level of capital.
Under this framework, PNC expects quarterly repurchases of up to $500 million with the ability to adjust those levels as conditions warrant.
The dividend, with a payment date of February 5, 2023, was paid on the next business day.
CECL’s estimated impact on CET1 capital is defined as the change in retained earnings at adoption plus or minus 25% of the change in CECL ACL at the balance sheet date, excluding the allowance for PCD loans, compared to CECL ACL at adoption.
The CET1 fully implemented ratio, which reflects the full impact of CECL and excludes the benefits of the optional five-year transition, was 8.9% at December 31, 2022 compared to 10.0% at December 31, 2021.
- The economy continues to expand in early 2023, but economic growth is slowing in response to the ongoing Federal Reserve monetary policy tightening to slow inflation.
This has led to large increases in both short- and long-term interest rates.
With much higher mortgage rates the housing market is already in contraction, with steep drops in existing home sales and single-family housing starts, and a modest decline in house prices.
Other sectors where interest rates play an outsized role, such as business investment and consumer spending on durable goods, will contract in 2023.
- PNC’s baseline outlook is for a recession starting in the second half of 2023, with real GDP contracting a modest 1% before recovery starts in early 2024 as the Federal Reserve lowers interest rates in response to a deteriorating labor market and slower inflation.
The unemployment rate will increase throughout 2023, peaking at above 5% in the first half of 2024.
An excerpt. Shown here: 40 of 717 rewritten, 40 of 327 added and 40 of 318 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS (MD&A) in the FY2023 filing and the FY2022 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
1 rewritten, 0 added, 0 removed, 0 unchanged
This information is set forth in the Risk Management section of Item 7 and in Note 1 Accounting Policies, Note [removed: 15] [added: 14] Fair Value and Note [removed: 16] [added: 15] Financial Derivatives in the Notes to Consolidated Financial Statements in Item 8 of this Report.
Item 1. BUSINESS
118 rewritten, 88 added, 38 removed, 269 unchanged
[added: We also have strategic international offices in four countries outside the U.S.] At December 31, [removed: 2022,] [added: 2023,] our consolidated total assets, total deposits and total shareholders’ equity were [removed: $557.3] [added: $561.6] billion, [removed: $436.3] [added: $421.4] billion and [removed: $45.8] [added: $51.1] billion, respectively.
Our corporate legal structure at December 31, [removed: 2022] [added: 2023] consisted of one domestic subsidiary bank, including its subsidiaries, and [removed: 59] [added: 54] active non-bank subsidiaries, in addition to various affordable housing investments and historic rehabilitation investments.
The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* 1
| Average Consolidated Balance Sheet [removed: And] [added: and] Net Interest Analysis | | | [removed: 190] [added: [180](#i697b5c6c53da4edd87b88055b5e4dfbe_583)] | | |
| Analysis [removed: Of] [added: of] Year-To-Year Changes [removed: In] [added: in] Net Interest Income | | | [removed: 191] [added: [181](#i697b5c6c53da4edd87b88055b5e4dfbe_586)] | | |
| Maturities [removed: And] [added: and] Weighted-Average Yield [removed: Of] [added: of] Securities | | | [removed: 117] [added: [110](#i697b5c6c53da4edd87b88055b5e4dfbe_277) and [180](#i697b5c6c53da4edd87b88055b5e4dfbe_583)] | | |
| Selected Loan Maturities [removed: And] [added: and] Interest Sensitivity | | | [removed: 192] [added: [183](#i697b5c6c53da4edd87b88055b5e4dfbe_598)] | | |
| Credit Ratios | | | [removed: 65, 69] [added: [63](#i697b5c6c53da4edd87b88055b5e4dfbe_133), [66](#i697b5c6c53da4edd87b88055b5e4dfbe_148)] and [removed: 70] [added: [67](#i697b5c6c53da4edd87b88055b5e4dfbe_151)] | | |
| Allocation [removed: Of] [added: of] Allowance [removed: For] [added: for] Credit Losses | | | [removed: 69] [added: [66](#i697b5c6c53da4edd87b88055b5e4dfbe_148)] | | |
| Average Amount [removed: And] [added: and] Average Rate Paid [removed: On] [added: on] Deposits | | | [removed: 190] [added: [180](#i697b5c6c53da4edd87b88055b5e4dfbe_583)] | | |
| Uninsured Deposits and Time Deposits | | | [removed: 193] [added: [183](#i697b5c6c53da4edd87b88055b5e4dfbe_601)] | | |
[removed: More than 99% of the assets of] PNC [removed: are held in] [added: primarily conducts] its [added: business through its] domestic bank subsidiary, PNC Bank, a national banking association chartered and located in Wilmington, Delaware.
See Note [removed: 20] [added: 19] Regulatory Matters for additional information regarding our regulatory matters.
In addition, we are subject to comprehensive supervision and examination [removed: by, among other] [added: by many] regulatory bodies, [added: including] the Federal Reserve and the OCC.
2 The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K*
Among the areas that have been receiving a high level of regulatory focus are compliance with the [removed: BSA and anti-money laundering] [added: BSA/AML] laws, capital and liquidity management (including [removed: stress testing),] [added: contingency, recovery, and resolution planning),] the structure and effectiveness of enterprise risk management [removed: frameworks,] [added: frameworks (including for climate-related risks),] the protection of confidential customer information, cybersecurity, the oversight of arrangements with third-party vendors and suppliers, [added: use of unapproved messaging applications by employees in regulated entities,] and compliance with fair lending and other consumer protection laws and regulations, including those governing retail sales practices, fee disclosures, unfair, deceptive or abusive acts or practices, collection practices, [added: and] protections for military service [removed: members and individuals in bankruptcy, and the management of risks associated with the Paycheck Protection Program we participated in to help businesses mitigate the impact of the COVID-19 pandemic.][added: members.]
The federal banking agencies [added: currently] tailor the application of their capital, liquidity and enhanced prudential requirements for banking organizations to the asset size and risk profile (as measured by certain regulatory metrics) of the banking organization.
As of December 31, [removed: 2022,] [added: 2023,] PNC had cross-jurisdictional activities for these purposes of [removed: $24.1] [added: $21.3] billion.
Under the [added: current] regulatory capital rules, PNC and PNC Bank must deduct investments in unconsolidated financial institutions, MSRs and deferred tax assets (in each case, net of associated deferred tax liabilities) from CET1 capital to the extent such categories individually exceed 25% of the institution’s adjusted CET1 capital.
As of December 31, [removed: 2022,] [added: 2023,] PNC and PNC Bank’s investments in unconsolidated financial institutions, MSRs and deferred tax assets did not exceed this threshold.
The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* 3
[removed: Separately, the] [added: The agencies’ capital] rules permit banking organizations that were subject to CECL during 2020 to delay CECL’s estimated impact on CET1 capital.
CECL’s estimated impact on CET1 capital is [added: defined as] the change in retained earnings at adoption plus or minus 25% of the change in CECL ACL at the balance sheet [removed: date] [added: date, excluding the allowance for PCD loans,] compared to CECL ACL at [removed: transition.][added: adoption.]
Banking organizations must maintain a minimum CET1 ratio of 4.5%, a Tier 1 capital ratio of 6.0%, and a Total capital ratio of 8.0%, in each case in relation to risk-weighted assets, to be considered “adequately capitalized.” [removed: In 2020, the Federal Reserve introduced a CET1 SCB for] BHCs subject to the Federal Reserve’s CCAR process, such as [removed: PNC.][added: PNC, are subject to a CET1 SCB.]
Based on PNC’s performance under the Federal Reserve’s supervisory stress tests as part of CCAR [removed: 2022,] [added: 2023,] PNC’s SCB for the [added: four-quarter] period [removed: from the fourth quarter of 2022 through] [added: beginning October 1, 2023 is] the [removed: third quarter] [added: regulatory minimum] of [removed: 2023 was set at 2.9%.][added: 2.5%.]
PNC and PNC Bank must maintain risk-based capital above the minimum risk-based capital ratio requirements plus its SCB (in the case of PNC) or capital conservation buffer (in the case of PNC Bank) in order to avoid limitations on capital distributions, including [added: paying] dividends and [added: executing] repurchases [added: or redemptions] of any Tier 1 capital instrument, such as common and qualifying preferred stock, and certain discretionary incentive compensation payments.
As a result, to avoid limitations on capital distributions and certain discretionary incentive compensation payments, PNC [removed: must maintain a CET1 capital ratio of at least 7.4%, a Tier 1 capital ratio of at least 8.9%,] and [removed: a Total capital ratio of at least 10.9%, and] PNC Bank must maintain a CET1 capital ratio of at least 7.0%, a Tier 1 capital ratio of at least 8.5%, and a Total capital ratio of at least 10.5%.
Total leverage exposure takes into account on-balance sheet assets as well as certain off-balance sheet items, including loan commitments and [removed: potential future exposure under derivative contracts.]
Banking organizations are required to maintain a minimum leverage ratio of Tier 1 capital to total assets of 4.0%, and Category III banking organizations must maintain a minimum supplementary leverage ratio of [added: 3.0%.]
4 The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K*
As of December 31, [removed: 2022,] [added: 2023,] the leverage and supplementary leverage ratios of PNC and PNC Bank were above the required minimum level.
PNC and PNC Bank are not [added: currently] subject to the additional CET1 capital surcharge, minimum long-term debt requirement, minimum total loss-absorbing capacity or enhanced supplementary leverage ratio requirements that apply to U.S. GSIBs.
However, it is possible that the agencies [removed: will consider applying] [added: may apply] one or more of these requirements in the future to additional BHCs or insured depository institutions like PNC and PNC Bank.
Failure to meet applicable capital requirements could subject a banking organization to a variety of enforcement remedies available to the federal banking agencies, including [removed: a limitation] [added: limitations] on [removed: the ability to pay dividends or repurchase shares,] [added: capital distributions,] the issuance of a capital directive to increase capital and, in severe cases, the termination of deposit insurance by the FDIC and the appointment of a conservator or receiver.
For example, PNC and PNC Bank must remain “well capitalized” for PNC to continue to take advantage of financial holding company [removed: status.][added: status as described below.]
At December 31, [removed: 2022,] [added: 2023,] PNC and PNC Bank exceeded the required ratios for classification as “well capitalized.” For additional discussion of capital adequacy requirements, including the levels of capital required to be considered “well capitalized,” see the Liquidity and Capital Management portion of the Risk Management section of this Report and Note [removed: 20] [added: 19] Regulatory Matters.
[removed: The Federal Reserve’s capital] plan [removed: rule provides that a BHC must resubmit a new capital plan] prior to the next annual submission date if, among other things, there has been or will be a material change in the BHC’s risk profile, financial condition or corporate structure since its last capital plan submission.
In connection with the [removed: 2023] [added: 2024] CCAR exercise, we must file our capital plan and stress testing results using financial data as of December 31, [removed: 2022,] [added: 2023,] with the Federal Reserve by April 5, [removed: 2023.][added: 2024.]
In June [removed: 2023,] [added: 2024,] we expect to receive PNC’s preliminary SCB for the [added: four-quarter] period [removed: from the fourth quarter of 2023 through the third quarter of] [added: beginning October 1,] 2024.
The Federal Reserve must provide firms their final SCB for this period by August 31, [removed: 2023,] [added: 2024,] which would reflect any changes made to the firm’s planned common stock dividends to remain in compliance with the firm’s SCB.
We offer a broad range of deposit, credit and fee-based products and services to serve our customers.
See Note 22 Segment Reporting for additional details regarding our products and services.
Presentation of Noninterest Income
Effective for the first quarter of 2022, PNC updated the presentation of its noninterest income categorization to be based on product and service type, and accordingly, has changed the basis of presentation of its noninterest income revenue streams to: (i) Asset management and brokerage, (ii) Capital markets related, (iii) Card and cash management, (iv) Lending and deposit services, (v) Residential and commercial mortgage and (vi) Other noninterest income.
For a description of each updated noninterest income revenue stream, see Note 1 Accounting Policies.
Additionally, in the fourth quarter of 2022, PNC updated the name of the noninterest income line item “Capital markets related” to “Capital markets and advisory.” This update did not impact the components of the category.
All periods presented herein reflect these changes.
Signature Bank Portfolio Acquisition
On October 2, 2023, PNC acquired a portfolio of capital commitments facilities from Signature Bridge Bank, N.A. through an agreement with the FDIC as receiver of the former Signature Bank, New York.
The acquired portfolio represented approximately $16.0 billion in total commitments, including approximately $9.0 billion of funded loans, at the time of acquisition.
On July 27, 2023, and as described in more detail below, the Federal Reserve, OCC, and FDIC proposed for public comment an interagency rule to implement the final components of the Basel III framework that would significantly revise the capital requirements for large banking organizations, including PNC and PNC Bank.
Under current rules, any of these no longer being the case, PNC and PNC Bank would become a Category I or II institution, and subject to more stringent capital and liquidity standards.
Some of the benefits of tailored application of capital, liquidity, and enhanced prudential requirements under current rules may be reversed if the agencies adopt, as proposed, certain rules issued in 2023 for comment as described further below.
PNC elected to delay the estimated impact of CECL on CET1 capital through December 31, 2021, followed by a three-year transition period.
Effective for the first quarter of 2022, PNC is now in the three-year transition period, and the full impact of the CECL standard is being phased-in to regulatory capital through December 31, 2024.
potential future exposure under derivative contracts.
In August 2023, the federal banking agencies proposed rules that would require Category II, III, and IV bank holding companies and banks to issue and maintain minimum amounts of long-term debt that satisfy certain requirements.
Additionally, Category II, III, and IV bank holding companies would be subject to “clean holding company” requirements, which would prohibit such companies from entering into certain financial arrangements and cap certain liabilities.
PNC, as a Category III holding company, and PNC Bank would be subject to the rules and would have a three-year phase-in period after any final rule to achieve compliance with the long-term debt requirements.
If the long-term debt rules were finalized in their current form, we would expect to achieve compliance through normal course funding.
The federal banking agencies issued a proposed rule in July 2023 to implement the final components of the Basel III framework.
The rule generally would align the regulatory capital elements and required deductions for Category III banking organizations, such as PNC and PNC Bank, with those currently applicable to Category I and II banking organizations and apply a new expanded risk-based approach for calculating risk-weighted assets (the “expanded risk-based approach”).
Among other impacts, PNC and PNC Bank would be required to recognize most elements of AOCI in regulatory capital and deduct from CET1 capital, among other items, MSRs, deferred tax assets, and investments in unconsolidated financial institutions that individually exceed 10% of CET1 capital or in the aggregate with other threshold items that exceed 15% of CET1 capital.
The new expanded risk-based approach to calculating risk-weighted assets would apply more granular and standardized risk-weighting methodologies for credit, operational, market, equity and credit valuation adjustment risks.
PNC and PNC Bank would be required to calculate their risk-based capital ratios under the existing standardized approach and the expanded risk-based approach and would be subject to the lower of the two resulting ratios for their risk-based capital minimum and buffer requirements, including the SCB.
The proposal indicates the effective date of the final rule would be July 1, 2025, with certain provisions having a three-year phase-in period, including the recognition of AOCI elements in regulatory capital and the increase in risk-weighted assets due to the expanded risk-based approach.
Based on our December 31, 2023 balance sheet, PNC and PNC Bank expect to remain above the current minimum capital and buffer requirements if the proposal were finalized in its current form.
The Federal Reserve’s capital plan rule provides that a BHC must resubmit a new capital
Until such
The final rule takes effect April 1, 2024, but the majority of its operative provisions are effective January 1, 2026, with the data reporting requirements effective January 1, 2027.
The Federal Reserve and the OCC have the ability to take enforcement action against PNC and PNC Bank, respectively, to prevent and remedy acts and practices that the agencies determine to be unfair or deceptive.
purposes of these regulations.
The Federal Reserve is required to establish standards under the statutory provision known as the “Durbin Amendment” for assessing whether the amount of any interchange fee received by a debit card issuer such as PNC Bank is reasonable and proportional to the cost incurred by the issuer, subject to certain adjustments.
The Federal Reserve implemented these standards through Regulation II, which limits the interchange fee an issuer may charge based on three components.
On October 25, 2023, the Federal Reserve proposed revisions to the three components of the interchange fee cap.
We expect the proposed rule, if finalized in its current form, would reduce PNC Bank’s interchange fee revenue.
The agencies have not yet published updated guidelines.
Following the bank failures in March 2023, the FDIC invoked the systemic risk exception to certain resolution-related and Deposit Insurance Fund restrictions in order to fully protect all depositors of the affected institutions, including uninsured deposits.
By law, any losses to the Deposit Insurance Fund to support uninsured depositors under the systemic risk exception must be recovered by one or more special assessments on insured depository institutions or depository institution holding companies, or both.
On November 16, 2023, the FDIC finalized a rule to implement the special assessment.
We also have strategic international offices in Canada, China, Germany and the United Kingdom.
For additional information on the acquisition of BBVA, see Note 2 Acquisition and Divestiture Activity.
Discontinued Operations
In the second quarter of 2020, PNC divested its entire 22.4% equity investment in BlackRock.
Net proceeds from the sale were $14.2 billion with an after-tax gain on sale of $4.3 billion.
BlackRock’s historical results are reported as discontinued operations.
For additional details on the divestiture of our equity investment in BlackRock, see Note 2 Acquisition and Divestiture Activity.
In September 2022, the federal banking agencies announced their intent to revise U.S. regulatory capital requirements to align them with the international standards finalized by the Basel Committee in December 2017, which include, among other items, changes to the standardized approach for credit risk, the credit valuation adjustment risk framework, operational risk framework and the leverage ratio framework.
These changes could increase capital requirements for U.S. banking organizations, including PNC.
PNC and PNC Bank would become a Category I or II institution, and subject to more stringent capital and liquidity standards, if PNC were at some point in the future to have $700 billion or more in total consolidated assets, be designated as a GSIB, or have $75 billion or more in cross-jurisdictional activity.
The agencies’ capital rules also permit banking organizations to elect to phase-in, on a straight-line basis over a three-year period, the day-one regulatory capital effects of implementing the Financial Accounting Standards Board’s ASU 2016-13 - *Financial Instruments*
*\- Credit Losses* (Topic 326), commonly referred to as the CECL standard.
PNC implemented the CECL standard effective January 1, 2020, but elected not to implement the phase-in of the day-one regulatory capital effects of the standard.
For institutions electing to utilize this CECL transition rule for regulatory capital, the estimated CECL impact was added to CET1 through December 31, 2021, and will be phased-out over the following three years.
PNC and PNC Bank elected this five-year transition period effective March 31, 2020, which impacts the regulatory capital ratios disclosed in this Report.
3.0%.
In October 2022, the Federal Reserve and FDIC jointly issued an advance notice of proposed rulemaking to solicit input on potential changes to the resolution-related requirements applicable to large banking organizations like PNC that are not GSIBs, including a requirement to maintain loss-absorbing capacity at the bank or holding company in the form of long-term debt.
A national bank’s financial subsidiary generally may not engage in a new financial activity authorized by the GLB Act, or acquire a company engaged in such a new financial activity, if the national bank or any of its insured depository institution affiliates received a CRA rating of less than Satisfactory.
In reviewing the merger of BHCs, the acquisition of banks or the acquisition of voting securities of a
PNC Bank is subject to certain enhanced deposit insurance recordkeeping requirements adopted by the FDIC, which are designed to assist the FDIC to promptly determine whether, or to what extent, a large bank’s deposits are covered by deposit insurance if the bank were to fail.
In addition to the proposed long-term debt requirements noted above, the Federal Reserve’s and FDIC’s October 2022 advance notice of proposed rulemaking solicited input on other potential changes to the resolution-related requirements applicable to large banking organizations like PNC that are not GSIBs.
The advance notice of proposed rulemaking solicited comments and posed specific questions on whether to impose GSIB-like resolution requirements on large banking organizations that are not GSIBs, including a “clean holding company” requirement that would prohibit top-tier holding companies from entering certain financial arrangements (such as short-term borrowing or derivative contracts), separability requirements, the Federal Reserve’s supervisory guidance on recovery planning, and certain disclosure requirements currently applicable to GSIBs.
Such requirements could, among other things, increase PNC’s borrowing costs, require the implementation of new operational capabilities, and require changes to PNC’s resolution strategies at the holding company level and bank level.
In January 2021, the FDIC lifted the moratorium that it had instituted on resolution plan filings by insured depository institutions.
The regulations could reduce the fees that we receive, require that we provide additional consumer disclosures, alter the way we provide our products and services, impair our ability to compete with other providers of financial products or services, or expose us to greater risk of private litigation or regulatory enforcement action.
The CFPB has engaged in rulemakings that affect, among other things, consumer remittance transfers, the qualified mortgage definition under the Truth in Lending Act, the Home Mortgage Disclosure Act, the Fair Debt Collection Practices Act, and payday, vehicle title, and certain high-cost installment loans and may establish, or modify, rules governing other aspects of consumer financial products or services in the future.
supervisory role with respect to PNC Bank’s derivatives and foreign exchange businesses.
- Other international money transfer businesses.
People of color represented approximately 35% of PNC’s workforce, including 26% of our employees in managerial roles, as of
December 31, 2022.
As part of building a pipeline of diverse talent, 73% of the early career development program participants in 2022 were diverse, including LGBTQ+, women, veterans, people of color and those with a disability.
SEC Reports and Corporate Governance Information
The SEC maintains a website at www.sec.gov that contains reports, including exhibits, proxy and information statements, and other information about issuers, like us, who file electronically with the SEC.
You can also inspect reports, proxy statements and other information about us at the offices of the New York Stock Exchange, 20 Broad Street, New York, New York 10005.
We make our Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, Current Reports on Form 8-K, and amendments to those reports filed with or furnished to the SEC pursuant to Section 13(a) or 15(d) of the Exchange Act available free of charge on our internet website as soon as reasonably practicable after we electronically file such material with, or furnish it to, the SEC.
Our corporate internet address is www.pnc.com, and you can find this information at www.pnc.com/secfilings.
investor.relations@pnc.com for copies of exhibits, including financial statement and schedule exhibits where applicable.
Shareholders who would like to request printed copies of the PNC Code of Business Conduct and Ethics or our Corporate Governance Guidelines or the charters of our Board’s Audit, Nominating and Governance, Human Resources, or Risk Committees (all of which are posted on our website at www.pnc.com/corporategovernance) may do so by sending their requests to our Corporate Secretary at The PNC Financial Services Group, Inc at The Tower at PNC Plaza, 300 Fifth Avenue, Pittsburgh, Pennsylvania 15222-2401.
An excerpt. Shown here: 40 of 118 rewritten, 40 of 88 added and all 38 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2023 filing and the FY2022 filing.
Item 3. LEGAL PROCEEDINGS
1 rewritten, 0 added, 0 removed, 0 unchanged
See the information set forth in Note [removed: 21] [added: 20] Legal Proceedings, which is incorporated here by reference.
Cover and table of contents
124 rewritten, 70 added, 75 removed, 126 unchanged
For the fiscal year ended December 31, [removed: 2022][added: 2023]
Indicate by check mark whether the registrant has submitted electronically every Interactive Data File required to be submitted pursuant to Rule 405 of Regulation S-T (§232.405 of this chapter) during the preceding 12 months (or for such shorter period that the registrant was required to submit such [added: files).]
The aggregate market value of the registrant’s outstanding voting common stock held by nonaffiliates on June 30, [removed: 2022,] [added: 2023,] determined using the per share closing price on that date on the New York Stock Exchange of [removed: $157.77,] [added: $125.95,] was approximately [removed: $64.6] [added: $50.0] billion.
Number of shares of registrant’s common stock outstanding at February [removed: 3, 2023: 399,682,159][added: 2, 2024: 397,808,112]
Portions of the definitive Proxy Statement of The PNC Financial Services Group, Inc. to be filed pursuant to Regulation 14A for the [removed: 2023] [added: 2024] annual meeting of shareholders (Proxy Statement) are incorporated by reference into Part III of this Form 10-K.
Cross-Reference Index to [removed: 2022] [added: 2023] Form 10-K
| Item 1B | | | [Unresolved Staff [removed: Comments.](#ib4bdc01166af494b81c4833469b4fe36_19)] [added: Comments](#i697b5c6c53da4edd87b88055b5e4dfbe_19)] | | | [removed: [31](#ib4bdc01166af494b81c4833469b4fe36_19)] [added: [31](#i697b5c6c53da4edd87b88055b5e4dfbe_19)] | | |
| Item 4 | | | [Mine Safety [removed: Disclosures.](#ib4bdc01166af494b81c4833469b4fe36_28)] [added: Disclosures](#i697b5c6c53da4edd87b88055b5e4dfbe_28)] | | | [removed: [31](#ib4bdc01166af494b81c4833469b4fe36_28)] [added: [33](#i697b5c6c53da4edd87b88055b5e4dfbe_28)] | | |
| [Information about our Executive [removed: Officers](#ib4bdc01166af494b81c4833469b4fe36_31)] [added: Officers](#i697b5c6c53da4edd87b88055b5e4dfbe_31)] | | | | | | [removed: [32](#ib4bdc01166af494b81c4833469b4fe36_31)] [added: [33](#i697b5c6c53da4edd87b88055b5e4dfbe_31)] | | |
| Item 5 | | | [Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities.](#ib4bdc01166af494b81c4833469b4fe36_37)] [added: Securities](#i697b5c6c53da4edd87b88055b5e4dfbe_37)] | | | [removed: [33](#ib4bdc01166af494b81c4833469b4fe36_37)] [added: [35](#i697b5c6c53da4edd87b88055b5e4dfbe_37)] | | |
| | | | [Common Stock Performance [removed: Graph](#ib4bdc01166af494b81c4833469b4fe36_40)] [added: Graph](#i697b5c6c53da4edd87b88055b5e4dfbe_40)] | | | [removed: [35](#ib4bdc01166af494b81c4833469b4fe36_40)] [added: [36](#i697b5c6c53da4edd87b88055b5e4dfbe_40)] | | |
| Item 6 | | | [removed: [Reserved](#ib4bdc01166af494b81c4833469b4fe36_43)] [added: [Reserved](#i697b5c6c53da4edd87b88055b5e4dfbe_43)] | | | [removed: [35](#ib4bdc01166af494b81c4833469b4fe36_43)] [added: [37](#i697b5c6c53da4edd87b88055b5e4dfbe_43)] | | |
| Item 7 | | | [Management’s Discussion and Analysis of Financial Condition and Results of Operations [removed: (MD&A).](#ib4bdc01166af494b81c4833469b4fe36_46)] [added: (MD&A)](#i697b5c6c53da4edd87b88055b5e4dfbe_46)] | | | [removed: [36](#ib4bdc01166af494b81c4833469b4fe36_46)] [added: [37](#i697b5c6c53da4edd87b88055b5e4dfbe_46)] | | |
| | | | [Executive [removed: Summary](#ib4bdc01166af494b81c4833469b4fe36_49)] [added: Summary](#i697b5c6c53da4edd87b88055b5e4dfbe_49)] | | | [removed: [36](#ib4bdc01166af494b81c4833469b4fe36_49)] [added: [37](#i697b5c6c53da4edd87b88055b5e4dfbe_49)] | | |
| | | | [Consolidated Income Statement [removed: Review](#ib4bdc01166af494b81c4833469b4fe36_52)] [added: Review](#i697b5c6c53da4edd87b88055b5e4dfbe_61)] | | | [removed: [42](#ib4bdc01166af494b81c4833469b4fe36_52)] [added: [42](#i697b5c6c53da4edd87b88055b5e4dfbe_61)] | | |
| | | | [Consolidated Balance Sheet [removed: Review](#ib4bdc01166af494b81c4833469b4fe36_67)] [added: Review](#i697b5c6c53da4edd87b88055b5e4dfbe_76)] | | | [removed: [44](#ib4bdc01166af494b81c4833469b4fe36_67)] [added: [45](#i697b5c6c53da4edd87b88055b5e4dfbe_76)] | | |
| | | | [Business Segments [removed: Review](#ib4bdc01166af494b81c4833469b4fe36_85)] [added: Review](#i697b5c6c53da4edd87b88055b5e4dfbe_94)] | | | [removed: [48](#ib4bdc01166af494b81c4833469b4fe36_85)] [added: [48](#i697b5c6c53da4edd87b88055b5e4dfbe_94)] | | |
| | | | [Critical Accounting Estimates and [removed: Judgments](#ib4bdc01166af494b81c4833469b4fe36_187)] [added: Judgments](#i697b5c6c53da4edd87b88055b5e4dfbe_193)] | | | [removed: [81](#ib4bdc01166af494b81c4833469b4fe36_187)] [added: [77](#i697b5c6c53da4edd87b88055b5e4dfbe_193)] | | |
| | | | [Cautionary Statement Regarding Forward-Looking [removed: Information](#ib4bdc01166af494b81c4833469b4fe36_193)] [added: Information](#i697b5c6c53da4edd87b88055b5e4dfbe_199)] | | | [removed: [84](#ib4bdc01166af494b81c4833469b4fe36_193)] [added: [81](#i697b5c6c53da4edd87b88055b5e4dfbe_199)] | | |
| Item 7A | | | [Quantitative and Qualitative Disclosures about Market [removed: Risk](#ib4bdc01166af494b81c4833469b4fe36_196)] [added: Risk](#i697b5c6c53da4edd87b88055b5e4dfbe_202)] | | | [removed: [85](#ib4bdc01166af494b81c4833469b4fe36_196)] [added: [82](#i697b5c6c53da4edd87b88055b5e4dfbe_202)] | | |
| Item 8 | | | [Financial Statements and Supplementary [removed: Data](#ib4bdc01166af494b81c4833469b4fe36_199)] [added: Data](#i697b5c6c53da4edd87b88055b5e4dfbe_205)] | | | [removed: [85](#ib4bdc01166af494b81c4833469b4fe36_199)] [added: [82](#i697b5c6c53da4edd87b88055b5e4dfbe_205)] | | |
| | | | [Report of Independent Registered Public Accounting [removed: Firm](#ib4bdc01166af494b81c4833469b4fe36_202)] [added: Firm](#i697b5c6c53da4edd87b88055b5e4dfbe_208)] | | | [removed: [86](#ib4bdc01166af494b81c4833469b4fe36_202)] [added: [83](#i697b5c6c53da4edd87b88055b5e4dfbe_208)] | | |
| | | | [Consolidated Income [removed: Statement](#ib4bdc01166af494b81c4833469b4fe36_205)] [added: Statement](#i697b5c6c53da4edd87b88055b5e4dfbe_211)] | | | [removed: [88](#ib4bdc01166af494b81c4833469b4fe36_205)] [added: [85](#i697b5c6c53da4edd87b88055b5e4dfbe_211)] | | |
| | | | [Consolidated Statement of Comprehensive [removed: Income](#ib4bdc01166af494b81c4833469b4fe36_208)] [added: Income](#i697b5c6c53da4edd87b88055b5e4dfbe_214)] | | | [removed: [89](#ib4bdc01166af494b81c4833469b4fe36_208)] [added: [86](#i697b5c6c53da4edd87b88055b5e4dfbe_214)] | | |
| | | | [Consolidated Balance [removed: Sheet](#ib4bdc01166af494b81c4833469b4fe36_211)] [added: Sheet](#i697b5c6c53da4edd87b88055b5e4dfbe_217)] | | | [removed: [90](#ib4bdc01166af494b81c4833469b4fe36_211)] [added: [87](#i697b5c6c53da4edd87b88055b5e4dfbe_217)] | | |
| | | | [Consolidated Statement of Changes in [removed: Equity](#ib4bdc01166af494b81c4833469b4fe36_214)] [added: Equity](#i697b5c6c53da4edd87b88055b5e4dfbe_220)] | | | [removed: [91](#ib4bdc01166af494b81c4833469b4fe36_214)] [added: [88](#i697b5c6c53da4edd87b88055b5e4dfbe_220)] | | |
| | | | [Consolidated Statement of Cash [removed: Flows](#ib4bdc01166af494b81c4833469b4fe36_220)] [added: Flows](#i697b5c6c53da4edd87b88055b5e4dfbe_226)] | | | [removed: [92](#ib4bdc01166af494b81c4833469b4fe36_220)] [added: [89](#i697b5c6c53da4edd87b88055b5e4dfbe_226)] | | |
| | | | [Notes to Consolidated Financial [removed: Statements](#ib4bdc01166af494b81c4833469b4fe36_223)] [added: Statements](#i697b5c6c53da4edd87b88055b5e4dfbe_229)] | | | [removed: [94](#ib4bdc01166af494b81c4833469b4fe36_223)] [added: [91](#i697b5c6c53da4edd87b88055b5e4dfbe_229)] | | |
| | | | [Note 1 Accounting [removed: Policies](#ib4bdc01166af494b81c4833469b4fe36_226)] [added: Policies](#i697b5c6c53da4edd87b88055b5e4dfbe_232)] | | | [removed: [94](#ib4bdc01166af494b81c4833469b4fe36_226)] [added: [91](#i697b5c6c53da4edd87b88055b5e4dfbe_232)] | | |
| | | | [removed: [Note 4 Loans] [added: [Note](#i697b5c6c53da4edd87b88055b5e4dfbe_283) [3](#i697b5c6c53da4edd87b88055b5e4dfbe_283) [Loans] and Related Allowance for Credit [removed: Losses](#ib4bdc01166af494b81c4833469b4fe36_277)] [added: Losses](#i697b5c6c53da4edd87b88055b5e4dfbe_283)] | | | [removed: [118](#ib4bdc01166af494b81c4833469b4fe36_277)] [added: [111](#i697b5c6c53da4edd87b88055b5e4dfbe_283)] | | |
| | | | [removed: [Note 5 Loan] [added: [Note](#i697b5c6c53da4edd87b88055b5e4dfbe_310) [4](#i697b5c6c53da4edd87b88055b5e4dfbe_310) [Loan] Sale and Servicing Activities and Variable Interest [removed: Entities](#ib4bdc01166af494b81c4833469b4fe36_304)] [added: Entities](#i697b5c6c53da4edd87b88055b5e4dfbe_310)] | | | [removed: [129](#ib4bdc01166af494b81c4833469b4fe36_304)] [added: [124](#i697b5c6c53da4edd87b88055b5e4dfbe_310)] | | |
Cross-Reference Index to [removed: 2022] [added: 2023] Form 10-K (continued)
| | | | [removed: [Note 6 Goodwill] [added: [Note](#i697b5c6c53da4edd87b88055b5e4dfbe_322) [5](#i697b5c6c53da4edd87b88055b5e4dfbe_322) [Goodwill] and Mortgage Servicing [removed: Rights](#ib4bdc01166af494b81c4833469b4fe36_316)] [added: Rights](#i697b5c6c53da4edd87b88055b5e4dfbe_322)] | | | [removed: [132](#ib4bdc01166af494b81c4833469b4fe36_316)] [added: [127](#i697b5c6c53da4edd87b88055b5e4dfbe_322)] | | |
| | | | [removed: [Note 8 Premises,] [added: [Note](#i697b5c6c53da4edd87b88055b5e4dfbe_364) [7](#i697b5c6c53da4edd87b88055b5e4dfbe_364) [Premises,] Equipment and Leasehold [removed: Improvements](#ib4bdc01166af494b81c4833469b4fe36_358)] [added: Improvements](#i697b5c6c53da4edd87b88055b5e4dfbe_364)] | | | [removed: [136](#ib4bdc01166af494b81c4833469b4fe36_358)] [added: [131](#i697b5c6c53da4edd87b88055b5e4dfbe_364)] | | |
| | | | [Note [removed: 13 Other] [added: 1](#i697b5c6c53da4edd87b88055b5e4dfbe_409)[2](#i697b5c6c53da4edd87b88055b5e4dfbe_409) [Other] Comprehensive [removed: Income](#ib4bdc01166af494b81c4833469b4fe36_403)] [added: Income](#i697b5c6c53da4edd87b88055b5e4dfbe_409)] | | | [removed: [143](#ib4bdc01166af494b81c4833469b4fe36_403)] [added: [138](#i697b5c6c53da4edd87b88055b5e4dfbe_409)] | | |
| | | | [Note [removed: 14 Earnings] [added: 1](#i697b5c6c53da4edd87b88055b5e4dfbe_418)[3](#i697b5c6c53da4edd87b88055b5e4dfbe_418) [Earnings] Per [removed: Share](#ib4bdc01166af494b81c4833469b4fe36_412)] [added: Share](#i697b5c6c53da4edd87b88055b5e4dfbe_418)] | | | [removed: [144](#ib4bdc01166af494b81c4833469b4fe36_412)] [added: [139](#i697b5c6c53da4edd87b88055b5e4dfbe_418)] | | |
| | | | [Note [removed: 17 Employee] [added: 1](#i697b5c6c53da4edd87b88055b5e4dfbe_475)[6](#i697b5c6c53da4edd87b88055b5e4dfbe_475) [Employee] Benefit [removed: Plans](#ib4bdc01166af494b81c4833469b4fe36_466)] [added: Plans](#i697b5c6c53da4edd87b88055b5e4dfbe_475)] | | | [removed: [164](#ib4bdc01166af494b81c4833469b4fe36_466)] [added: [158](#i697b5c6c53da4edd87b88055b5e4dfbe_475)] | | |
| | | | [Note [removed: 18 Stock] [added: 1](#i697b5c6c53da4edd87b88055b5e4dfbe_502)[7](#i697b5c6c53da4edd87b88055b5e4dfbe_502) [Stock] Based Compensation [removed: Plans](#ib4bdc01166af494b81c4833469b4fe36_493)] [added: Plans](#i697b5c6c53da4edd87b88055b5e4dfbe_502)] | | | [removed: [170](#ib4bdc01166af494b81c4833469b4fe36_493)] [added: [164](#i697b5c6c53da4edd87b88055b5e4dfbe_502)] | | |
| | | | [Note [removed: 24 Fee-based] [added: 2](#i697b5c6c53da4edd87b88055b5e4dfbe_565)[3](#i697b5c6c53da4edd87b88055b5e4dfbe_565) [Fee-based] Revenue from Contracts with [removed: Customers](#ib4bdc01166af494b81c4833469b4fe36_556)] [added: Customers](#i697b5c6c53da4edd87b88055b5e4dfbe_565)] | | | [removed: [184](#ib4bdc01166af494b81c4833469b4fe36_556)] [added: [175](#i697b5c6c53da4edd87b88055b5e4dfbe_565)] | | |
| Item 9 | | | [Changes in and Disagreements with Accountants on Accounting and Financial [removed: Disclosure.](#ib4bdc01166af494b81c4833469b4fe36_610)] [added: Disclosure](#i697b5c6c53da4edd87b88055b5e4dfbe_616)] | | | [removed: [198](#ib4bdc01166af494b81c4833469b4fe36_610)] [added: [188](#i697b5c6c53da4edd87b88055b5e4dfbe_616)] | | |
| Item 1 | | | [Business](#i697b5c6c53da4edd87b88055b5e4dfbe_13) | | | [1](#i697b5c6c53da4edd87b88055b5e4dfbe_13) | | |
| Item 1A | | | [Risk Factors](#i697b5c6c53da4edd87b88055b5e4dfbe_16) | | | [16](#i697b5c6c53da4edd87b88055b5e4dfbe_16) | | |
| Item 1C | | | [Cybersecurity](#i697b5c6c53da4edd87b88055b5e4dfbe_5133) | | | [31](#i697b5c6c53da4edd87b88055b5e4dfbe_5133) | | |
| Item 2 | | | [Properties](#i697b5c6c53da4edd87b88055b5e4dfbe_22) | | | [33](#i697b5c6c53da4edd87b88055b5e4dfbe_22) | | |
| Item 3 | | | [Legal Proceedings](#i697b5c6c53da4edd87b88055b5e4dfbe_25) | | | [33](#i697b5c6c53da4edd87b88055b5e4dfbe_25) | | |
| | | | [Risk Management](#i697b5c6c53da4edd87b88055b5e4dfbe_109) | | | [54](#i697b5c6c53da4edd87b88055b5e4dfbe_109) | | |
| | | | [Note 2 Investment Securities](#i697b5c6c53da4edd87b88055b5e4dfbe_262) | | | [108](#i697b5c6c53da4edd87b88055b5e4dfbe_262) | | |
| | | | [Note](#i697b5c6c53da4edd87b88055b5e4dfbe_340) [6](#i697b5c6c53da4edd87b88055b5e4dfbe_340) [Leases](#i697b5c6c53da4edd87b88055b5e4dfbe_340) | | | [130](#i697b5c6c53da4edd87b88055b5e4dfbe_340) | | |
| | | | [Note](#i697b5c6c53da4edd87b88055b5e4dfbe_373) [8](#i697b5c6c53da4edd87b88055b5e4dfbe_373) [](#i697b5c6c53da4edd87b88055b5e4dfbe_373)[Time Deposits](#i697b5c6c53da4edd87b88055b5e4dfbe_373) | | | [132](#i697b5c6c53da4edd87b88055b5e4dfbe_373) | | |
| | | | [Note](#i697b5c6c53da4edd87b88055b5e4dfbe_379) [9](#i697b5c6c53da4edd87b88055b5e4dfbe_379) [Borrowed Funds](#i697b5c6c53da4edd87b88055b5e4dfbe_379) | | | [132](#i697b5c6c53da4edd87b88055b5e4dfbe_379) | | |
| | | | [Note 1](#i697b5c6c53da4edd87b88055b5e4dfbe_388)[0](#i697b5c6c53da4edd87b88055b5e4dfbe_388) [Commitments](#i697b5c6c53da4edd87b88055b5e4dfbe_388) | | | [134](#i697b5c6c53da4edd87b88055b5e4dfbe_388) | | |
| | | | [Note 1](#i697b5c6c53da4edd87b88055b5e4dfbe_394)[1](#i697b5c6c53da4edd87b88055b5e4dfbe_394) [Equity](#i697b5c6c53da4edd87b88055b5e4dfbe_394) | | | [135](#i697b5c6c53da4edd87b88055b5e4dfbe_394) | | |
| | | | [Note 1](#i697b5c6c53da4edd87b88055b5e4dfbe_424)[4](#i697b5c6c53da4edd87b88055b5e4dfbe_424) [Fair Value](#i697b5c6c53da4edd87b88055b5e4dfbe_424) | | | [139](#i697b5c6c53da4edd87b88055b5e4dfbe_424) | | |
| | | | [Note 1](#i697b5c6c53da4edd87b88055b5e4dfbe_448)[5](#i697b5c6c53da4edd87b88055b5e4dfbe_448) [Financial Derivatives](#i697b5c6c53da4edd87b88055b5e4dfbe_448) | | | [152](#i697b5c6c53da4edd87b88055b5e4dfbe_448) | | |
| | | | [Note 1](#i697b5c6c53da4edd87b88055b5e4dfbe_511)[8](#i697b5c6c53da4edd87b88055b5e4dfbe_511) [Income Taxes](#i697b5c6c53da4edd87b88055b5e4dfbe_511) | | | [165](#i697b5c6c53da4edd87b88055b5e4dfbe_511) | | |
| | | | [Note](#i697b5c6c53da4edd87b88055b5e4dfbe_535) [19](#i697b5c6c53da4edd87b88055b5e4dfbe_535) [Regulatory Matters](#i697b5c6c53da4edd87b88055b5e4dfbe_535) | | | [167](#i697b5c6c53da4edd87b88055b5e4dfbe_535) | | |
| | | | [Note 2](#i697b5c6c53da4edd87b88055b5e4dfbe_541)[0](#i697b5c6c53da4edd87b88055b5e4dfbe_541) [Legal Proceedings](#i697b5c6c53da4edd87b88055b5e4dfbe_541) | | | [168](#i697b5c6c53da4edd87b88055b5e4dfbe_541) | | |
| | | | [Note 2](#i697b5c6c53da4edd87b88055b5e4dfbe_544)[1](#i697b5c6c53da4edd87b88055b5e4dfbe_544) [Parent Company](#i697b5c6c53da4edd87b88055b5e4dfbe_544) | | | [172](#i697b5c6c53da4edd87b88055b5e4dfbe_544) | | |
| | | | [Note 2](#i697b5c6c53da4edd87b88055b5e4dfbe_559)[2](#i697b5c6c53da4edd87b88055b5e4dfbe_559) [Segment Reporting](#i697b5c6c53da4edd87b88055b5e4dfbe_559) | | | [173](#i697b5c6c53da4edd87b88055b5e4dfbe_559) | | |
| | | | [Note 24 Subsequent Events](#i697b5c6c53da4edd87b88055b5e4dfbe_571) | | | [179](#i697b5c6c53da4edd87b88055b5e4dfbe_571) | | |
| | | | [Statistical Information (Unaudited)](#i697b5c6c53da4edd87b88055b5e4dfbe_577) | | | [180](#i697b5c6c53da4edd87b88055b5e4dfbe_577) | | |
| | | | [Glossary](#i697b5c6c53da4edd87b88055b5e4dfbe_607) | | | [184](#i697b5c6c53da4edd87b88055b5e4dfbe_607) | | |
| | | | [Defined Terms](#i697b5c6c53da4edd87b88055b5e4dfbe_610) | | | [184](#i697b5c6c53da4edd87b88055b5e4dfbe_610) | | |
| | | | [Acronyms](#i697b5c6c53da4edd87b88055b5e4dfbe_613) | | | [188](#i697b5c6c53da4edd87b88055b5e4dfbe_613) | | |
| Item 9A | | | [Controls and Procedures](#i697b5c6c53da4edd87b88055b5e4dfbe_619) | | | [188](#i697b5c6c53da4edd87b88055b5e4dfbe_619) | | |
| Item 9B | | | [Other Information](#i697b5c6c53da4edd87b88055b5e4dfbe_622) | | | [189](#i697b5c6c53da4edd87b88055b5e4dfbe_622) | | |
| Item 11 | | | [Executive Compensation](#i697b5c6c53da4edd87b88055b5e4dfbe_631) | | | [189](#i697b5c6c53da4edd87b88055b5e4dfbe_631) | | |
| Item 14 | | | [Principal Accounting Fees and Services](#i697b5c6c53da4edd87b88055b5e4dfbe_640) | | | [190](#i697b5c6c53da4edd87b88055b5e4dfbe_640) | | |
| Item 15 | | | [Exhibits, Financial Statement Schedules](#i697b5c6c53da4edd87b88055b5e4dfbe_646) | | | [191](#i697b5c6c53da4edd87b88055b5e4dfbe_646) | | |
| Item 16 | | | [Form 10-K Summary](#i697b5c6c53da4edd87b88055b5e4dfbe_652) | | | [196](#i697b5c6c53da4edd87b88055b5e4dfbe_652) | | |
| [SIGNATURES](#i697b5c6c53da4edd87b88055b5e4dfbe_655) | | | | | | [197](#i697b5c6c53da4edd87b88055b5e4dfbe_655) | | |
Cross-Reference Index to 2023 Form 10-K (continued)
| 8 | | | [Loans](#i697b5c6c53da4edd87b88055b5e4dfbe_82) | | | [46](#i697b5c6c53da4edd87b88055b5e4dfbe_82) | | |
| 15 | | | [Details of Loans](#i697b5c6c53da4edd87b88055b5e4dfbe_115) | | | [58](#i697b5c6c53da4edd87b88055b5e4dfbe_115) | | |
| 27 | | | [Primary Contingent Liquidity Sources](#i697b5c6c53da4edd87b88055b5e4dfbe_4910) | | | [69](#i697b5c6c53da4edd87b88055b5e4dfbe_4910) | | |
| 31 | | | [Net Interest Income Sensitivity Analysis](#i697b5c6c53da4edd87b88055b5e4dfbe_178) | | | [73](#i697b5c6c53da4edd87b88055b5e4dfbe_178) | | |
| 32 | | | [Economic Value of Equity Sensitivity Analysis](#i697b5c6c53da4edd87b88055b5e4dfbe_5126) | | | [74](#i697b5c6c53da4edd87b88055b5e4dfbe_5126) | | |
Cross-Reference Index to 2023 Form 10-K (continued)
| 35 | | | [Investment Securities Summary](#i697b5c6c53da4edd87b88055b5e4dfbe_265) | | | [108](#i697b5c6c53da4edd87b88055b5e4dfbe_265) | | |
| 40 | | | [Analysis of Loan Portfolio](#i697b5c6c53da4edd87b88055b5e4dfbe_286) | | | [112](#i697b5c6c53da4edd87b88055b5e4dfbe_286) | | |
files).
| Item 1 | | | [Business.](#ib4bdc01166af494b81c4833469b4fe36_13) | | | [1](#ib4bdc01166af494b81c4833469b4fe36_13) | | |
| Item 1A | | | [Risk Factors.](#ib4bdc01166af494b81c4833469b4fe36_16) | | | [15](#ib4bdc01166af494b81c4833469b4fe36_16) | | |
| Item 2 | | | [Properties.](#ib4bdc01166af494b81c4833469b4fe36_22) | | | [31](#ib4bdc01166af494b81c4833469b4fe36_22) | | |
| Item 3 | | | [Legal Proceedings.](#ib4bdc01166af494b81c4833469b4fe36_25) | | | [31](#ib4bdc01166af494b81c4833469b4fe36_25) | | |
| | | | [Risk Management](#ib4bdc01166af494b81c4833469b4fe36_100) | | | [56](#ib4bdc01166af494b81c4833469b4fe36_100) | | |
| | | | [Note 2 Acquisition and Divestiture Activity](#ib4bdc01166af494b81c4833469b4fe36_229) | | | [111](#ib4bdc01166af494b81c4833469b4fe36_229) | | |
| | | | [Note 3 Investment Securities](#ib4bdc01166af494b81c4833469b4fe36_256) | | | [115](#ib4bdc01166af494b81c4833469b4fe36_256) | | |
| | | | [Note 7 Leases](#ib4bdc01166af494b81c4833469b4fe36_334) | | | [134](#ib4bdc01166af494b81c4833469b4fe36_334) | | |
| | | | [Note 9 Time Deposits](#ib4bdc01166af494b81c4833469b4fe36_367) | | | [137](#ib4bdc01166af494b81c4833469b4fe36_367) | | |
| | | | [Note 10 Borrowed Funds](#ib4bdc01166af494b81c4833469b4fe36_373) | | | [137](#ib4bdc01166af494b81c4833469b4fe36_373) | | |
| | | | [Note 11 Commitments](#ib4bdc01166af494b81c4833469b4fe36_382) | | | [139](#ib4bdc01166af494b81c4833469b4fe36_382) | | |
| | | | [Note 12 Equity](#ib4bdc01166af494b81c4833469b4fe36_388) | | | [140](#ib4bdc01166af494b81c4833469b4fe36_388) | | |
| | | | [Note 15 Fair Value](#ib4bdc01166af494b81c4833469b4fe36_418) | | | [145](#ib4bdc01166af494b81c4833469b4fe36_418) | | |
| | | | [Note 16 Financial Derivatives](#ib4bdc01166af494b81c4833469b4fe36_442) | | | [158](#ib4bdc01166af494b81c4833469b4fe36_442) | | |
| | | | [Note 19 Income Taxes](#ib4bdc01166af494b81c4833469b4fe36_502) | | | [171](#ib4bdc01166af494b81c4833469b4fe36_502) | | |
| | | | [Note 20 Regulatory Matters](#ib4bdc01166af494b81c4833469b4fe36_526) | | | [173](#ib4bdc01166af494b81c4833469b4fe36_526) | | |
| | | | [Note 21 Legal Proceedings](#ib4bdc01166af494b81c4833469b4fe36_532) | | | [174](#ib4bdc01166af494b81c4833469b4fe36_532) | | |
| | | | [Note 22 Parent Company](#ib4bdc01166af494b81c4833469b4fe36_535) | | | [179](#ib4bdc01166af494b81c4833469b4fe36_535) | | |
| | | | [Note 23 Segment Reporting](#ib4bdc01166af494b81c4833469b4fe36_550) | | | [182](#ib4bdc01166af494b81c4833469b4fe36_550) | | |
| | | | [Note 25 Subsequent Events](#ib4bdc01166af494b81c4833469b4fe36_568) | | | [188](#ib4bdc01166af494b81c4833469b4fe36_568) | | |
| | | | [Statistical Information (Unaudited)](#ib4bdc01166af494b81c4833469b4fe36_571) | | | [190](#ib4bdc01166af494b81c4833469b4fe36_571) | | |
| | | | [Glossary](#ib4bdc01166af494b81c4833469b4fe36_601) | | | [194](#ib4bdc01166af494b81c4833469b4fe36_601) | | |
| | | | [Defined Terms](#ib4bdc01166af494b81c4833469b4fe36_604) | | | [194](#ib4bdc01166af494b81c4833469b4fe36_604) | | |
| | | | [Acronyms](#ib4bdc01166af494b81c4833469b4fe36_607) | | | [198](#ib4bdc01166af494b81c4833469b4fe36_607) | | |
| Item 9A | | | [Controls and Procedures.](#ib4bdc01166af494b81c4833469b4fe36_613) | | | [198](#ib4bdc01166af494b81c4833469b4fe36_613) | | |
| Item 9B | | | [Other Information.](#ib4bdc01166af494b81c4833469b4fe36_616) | | | [199](#ib4bdc01166af494b81c4833469b4fe36_616) | | |
| Item 11 | | | [Executive Compensation.](#ib4bdc01166af494b81c4833469b4fe36_625) | | | [199](#ib4bdc01166af494b81c4833469b4fe36_625) | | |
| Item 14 | | | [Principal Accounting Fees and Services.](#ib4bdc01166af494b81c4833469b4fe36_634) | | | [200](#ib4bdc01166af494b81c4833469b4fe36_634) | | |
| Item 15 | | | [Exhibits, Financial Statement Schedules.](#ib4bdc01166af494b81c4833469b4fe36_640) | | | [201](#ib4bdc01166af494b81c4833469b4fe36_640) | | |
| Item 16 | | | [Form 10-K Summary](#ib4bdc01166af494b81c4833469b4fe36_646) | | | [206](#ib4bdc01166af494b81c4833469b4fe36_646) | | |
| [SIGNATURES](#ib4bdc01166af494b81c4833469b4fe36_649) | | | | | | [207](#ib4bdc01166af494b81c4833469b4fe36_649) | | |
| 8 | | | [Loans](#ib4bdc01166af494b81c4833469b4fe36_73) | | | [45](#ib4bdc01166af494b81c4833469b4fe36_73) | | |
| 15 | | | [Details of Loans](#ib4bdc01166af494b81c4833469b4fe36_106) | | | [60](#ib4bdc01166af494b81c4833469b4fe36_106) | | |
| 24 | | | [Summary of Troubled Debt Restructurings](#ib4bdc01166af494b81c4833469b4fe36_136) | | | [67](#ib4bdc01166af494b81c4833469b4fe36_136) | | |
| 28 | | | [PNC Bank Notes Issued](#ib4bdc01166af494b81c4833469b4fe36_151) | | | [71](#ib4bdc01166af494b81c4833469b4fe36_151) | | |
| 29 | | | [PNC Bank Notes Redeemed](#ib4bdc01166af494b81c4833469b4fe36_154) | | | [72](#ib4bdc01166af494b81c4833469b4fe36_154) | | |
| 31 | | | [Parent Company Notes Redeemed](#ib4bdc01166af494b81c4833469b4fe36_5054) | | | [73](#ib4bdc01166af494b81c4833469b4fe36_5054) | | |
| 34 | | | [Interest Sensitivity Analysis](#ib4bdc01166af494b81c4833469b4fe36_172) | | | [76](#ib4bdc01166af494b81c4833469b4fe36_172) | | |
| 35 | | | [Net Interest Income Sensitivity to Alternative Rate Scenarios](#ib4bdc01166af494b81c4833469b4fe36_175) | | | [76](#ib4bdc01166af494b81c4833469b4fe36_175) | | |
An excerpt. Shown here: 40 of 124 rewritten, 40 of 70 added and 40 of 75 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2023 filing and the FY2022 filing.
Item 1C. CYBERSECURITY
0 rewritten, 43 added, 0 removed, 0 unchanged
New section this year
We manage our cybersecurity risk as an integral part of our enterprise risk management programs.
Accordingly, you should review the disclosure in this Item 1C in conjunction with the disclosure in the Risk Management section of this Report.
The PNC Financial Services Group, Inc. – *2023 Form 10-K* 31
Information Security Program
PNC’s approach to cyber risk management, oversight, and reporting is based on a well-structured information security program.
The program is responsible for protecting information assets to achieve business objectives in a secure manner and designed to keep customers’ information and their funds safe and available.
Program capabilities are built against industry guidance and a security framework to identify risks to sensitive information, protect that information and maintain an appropriate response and recovery capability to help ensure resilience against information security incidents.
PNC’s information security program is designed to ensure that PNC follows industry guidance and security frameworks for data protection, system development security, identity and access management, incident management, threat and vulnerability management, security operations management and third- and fourth-party security.
Our program is continuously enhanced by threat intelligence, new regulations, industry guidance and disruptive new technologies.
The program includes, among other things, annual security and privacy training for all PNC employees, phishing exercises, and informative articles and communications to raise employee awareness.
PNC actively monitors and responds to the overall cybersecurity threat landscape via active capabilities to share information and leverage intelligence, monitoring, and response capabilities across the security industry, which include cybersecurity threats, physical threats and fraud.
PNC’s intelligence and analysis capabilities collaborate to analyze events and trends for possible response.
We have not experienced any material cybersecurity threats that have impacted PNC’s business strategy, results of operations, or financial condition to date.
Notwithstanding our well-established approach regarding cybersecurity, we may not be successful in preventing or mitigating the impact of a cybersecurity incident that could have a material impact on our business, results of operations or financial condition.
See Item 1A Risk Factors of this Report for a discussion of cybersecurity risks.
Board Governance and Risk Oversight
PNC’s Board of Directors maintains governance and oversight of the risks posed by cybersecurity threats through the Board-level Technology and Risk Committees.
The Technology Committee meets no less than quarterly, and its purpose is to (i) assist the Board with the oversight of technology strategy and significant technology initiatives and programs, including those that can position the use of technology to drive strategic advantages and (ii) fulfill oversight responsibilities with respect to technology risk, information management, and security risks (including cyber security, cyber fraud, and physical security risks), and the adequacy of PNC’s business recovery, resiliency and contingency plans and test results.
The Technology Committee is informed of cyber threats and risks through multiple mechanisms.
PNC’s Chief Information Security Officer presents quarterly to the Technology Committee on such topics as threat intelligence and assessment reports, incident and event reporting from other institutions, governance and regulatory exam statuses, and the status of other key program deliverables, among other content.
The Risk Committee meets no less than quarterly and provides oversight of PNC’s ERM framework.
Cybersecurity risk is integrated into PNC’s overall ERM framework, and is represented as the Information Security domain, alongside seven other operational risk domains.
See the Risk Management section of this Report for more details on our ERM framework.
PNC’s inherent information security risks, the maturity and completeness of the control environment, and measurements against our risk appetite are presented quarterly to the Technology Committee by the firm’s Chief Technology Risk Officer.
Overall risks across the Enterprise Risk Framework are then reported quarterly to the Risk Committee by the Chief Risk Officer.
Communication to the Board occurs more frequently than quarterly, when dictated by incident and event management policies and procedures based on the criticality and urgency of the communication.
Role of Management
Management is directly involved in assessing and managing PNC’s risks from cybersecurity threats.
PNC uses a three-lines-of-defense model where cybersecurity risk is managed and assessed by the first line of defense, led by the Chief Information Security Officer and the Director of Technology and Security Risk Management, and the second line of defense which is led by the Chief Technology Risk Officer, who reports to the Chief Risk Officer.
The first and second lines of defense are examined internally by our third line of defense, Internal Audit.
The lines of defense model ensures appropriate oversight within the management structure.
See the Risk Governance and Oversight section of Risk Management for more details on each of our lines of defense.
In addition to the three lines of internal defense, PNC engages external consultants to assess and inform the program, as needed.
The Chief Information Security Officer’s organization includes managers who have led cybersecurity programs in other industries such as robotics and artificial intelligence, consulting, telecommunications, healthcare, and manufacturing, which brings together a multi-faceted approach to managing cybersecurity threats and risks.
The Information Security department leadership and personnel hold degrees in Information Security, Management Information Systems, Computer Science, Engineering Management and other professional majors.
They also hold multiple professional certifications inclusive of vendor-issued security credentials from CISCO,
32 The PNC Financial Services Group, Inc. – *2023 Form 10-K*
Microsoft and F5, and industry certifications including but not limited to: Certified Information Systems Security Professional issued by the International Information System Security Certification Consortium; the Cybersecurity and Infrastructure Security Agency and Certified Information Security Manager issued by the Information Systems Audit and Control Association; and the Certificate of Cloud Security Knowledge issued by the Cloud Security Association.
Cyber Risks Related to Third Parties
Risks from cybersecurity threats associated with its use of third-party service providers are addressed as part of the information security risk and third-party risk domains, and their management is integrated into the ERM Framework.
An excerpt. Shown here: all 0 rewritten, 40 of 43 added and all 0 removed. The counts are complete. For every sentence, read Item 1C. CYBERSECURITY in the FY2023 filing.
Item 2. PROPERTIES
1 rewritten, 0 added, 0 removed, 4 unchanged
We include here by reference the additional information regarding our properties in Note [removed: 7] [added: 6] Leases and Note [removed: 8] [added: 7] Premises, Equipment and Leasehold Improvements.
Item 4. MINE SAFETY DISCLOSURES
24 rewritten, 2 added, 4 removed, 54 unchanged
The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 31][added: 33]
Information regarding each of our executive officers as of February 20, [removed: 2023] [added: 2024] is set forth below.
| Carole L. Brown | | | [removed: 58] [added: 59] | | | Executive Vice President and Head of Asset Management Group | | | 2019 | | |
| Richard K. Bynum | | | [removed: 52] [added: 53] | | | Executive Vice President and Chief Corporate Responsibility Officer | | | 2005 | | |
| William S. Demchak | | | [removed: 60] [added: 61] | | | [removed: Chairman, President] [added: Chairman] and Chief Executive Officer (b) | | | 2002 | | |
| Kieran J. Fallon | | | [removed: 56] [added: 57] | | | Executive Vice President and Chief Risk Officer | | | 2011 | | |
| Deborah Guild | | | [removed: 54] [added: 55] | | | Executive Vice [removed: President, Chief Information Security Officer] [added: President] and Head of Enterprise Technology [added: and Security] | | | 2013 | | |
| [removed: Michael J. Hannon] [added: Robert Q. Reilly] | | | [removed: 66] [added: 59] | | | Executive Vice President and Chief [removed: Credit] [added: Financial] Officer | | | [removed: 1982] [added: 1987] | | |
| Vicki C. Henn | | | [removed: 54] [added: 55] | | | Executive Vice President and Chief Human Resources Officer | | | 1994 | | |
| Gregory B. Jordan | | | [removed: 63] [added: 64] | | | Executive Vice President, General [removed: Counsel,] [added: Counsel and] Chief Administrative Officer [removed: and Head of Regulatory and Government Affairs] | | | 2013 | | |
| Stacy M. Juchno | | | [removed: 47] [added: 48] | | | Executive Vice President and General Auditor | | | 2009 | | |
| Ganesh Krishnan | | | [removed: 47] [added: 48] | | | Executive Vice President and Enterprise Chief Information Officer | | | 2008 | | |
| Michael P. Lyons | | | [removed: 52] [added: 53] | | | [removed: Executive Vice] President and Head of Corporate & Institutional Banking | | | 2011 | | |
| Alexander E. C. Overstrom | | | [removed: 39] [added: 40] | | | Executive Vice President and Head of Retail Banking | | | 2014 | | |
| E William Parsley, III | | | [removed: 57] [added: 58] | | | Executive Vice President and Chief Operating Officer | | | 2003 | | |
| Gregory H. Kozich | | | [removed: 59] [added: 60] | | | Senior Vice President and Controller | | | 2010 | | |
Biographical information for Mr. Demchak is included in “Election of Directors (Item 1)” in our proxy statement to be filed for the [removed: 2023] [added: 2024] annual meeting of shareholders.
[removed: Prior to] joining PNC in 2019, she served as chief financial officer for the City of Chicago from May 2015 to May 2019.
Deborah Guild [removed: was appointed] [added: has served as] Executive Vice [removed: President, Chief Information Security Officer] [added: President] and Head of Enterprise Technology [removed: in November] [added: and Security since December] 2020.
[removed: Prior to her appointment, she was] [added: She previously served as] PNC’s Chief [added: Information] Security Officer, [added: Chief Security Officer,] and [removed: previously served as PNC’s] Chief Technology Officer.
[removed: 32] [added: 34] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K*
Ganesh Krishnan [removed: was appointed] [added: has served as] Executive Vice President and Enterprise Chief Information Officer [removed: in November] [added: since December] 2020.
[removed: Prior to being named to his current role, he] [added: He previously] served as Chief Information Officer for PNC’s Corporate & Institutional Banking business and Staff Service Technology starting in 2017.
Lyons [removed: has been an Executive Vice] [added: was appointed] President [removed: since 2011] [added: in February 2024] and is Head of Corporate & Institutional Banking.
Prior to
He previously served as an Executive Vice President since 2011.
| Robert Q. Reilly | | | 58 | | | Executive Vice President and Chief Financial Officer | | | 1987 | | |
Michael J.
Hannon has served as Executive Vice President since 2009, prior to which he was a Senior Vice President.
He has served as Chief Credit Officer since 2001 and was Interim Chief Risk Officer from December 2011 to February 2012.
Item 5. MARKET FOR REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
19 rewritten, 14 added, 11 removed, 28 unchanged
Our common stock is listed on the New York Stock Exchange and is traded under the symbol “PNC.” At the close of business on February [removed: 10, 2023,] [added: 9, 2024,] there were [removed: 44,958] [added: 43,059] common shareholders of record.
Consistent with the SCB framework, which allows for capital return in amounts in excess of the SCB minimum levels, our Board of Directors has authorized a repurchase framework under the [added: previously approved] repurchase program [removed: approved on April 4, 2019] of up to 100 million common shares, of which approximately [removed: 49%] [added: 45%] were still available for repurchase at December 31, [removed: 2022.][added: 2023.]
PNC’s SCB for the four-quarter period beginning October 1, [removed: 2022] [added: 2023] is [removed: 2.9%.][added: the regulatory minimum of 2.5%.]
For further information concerning dividend restrictions and other factors that could limit our ability to pay dividends, as well as restrictions on loans, dividends or advances from bank subsidiaries to the parent company, see the Supervision and Regulation section in Item 1, Item 1A Risk Factors and the Liquidity and Capital Management portion of the Risk Management section in Item 7, and Note [removed: 10] [added: 9] Borrowed Funds, Note [removed: 12] [added: 11] Equity and Note [removed: 20] [added: 19] Regulatory Matters, which we include here by reference.
The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 33][added: 35]
We include here by reference the information regarding our compensation plans under which PNC equity securities are authorized for issuance as of December 31, [removed: 2022] [added: 2023] in the table (with introductory paragraph and notes) in Item 12 of this Report.
Details of our repurchases of PNC common stock during the fourth quarter of [removed: 2022] [added: 2023] are included in the following [removed: table:][added: table.]
| [removed: 2022] [added: 2023] period [added: In thousands, except per share data] | | | Total shares purchased (a) | | | Average price paid per share | | | Total shares purchased as part of publicly announced programs (b) | | | Maximum number of shares that may yet be purchased under the programs (b) | | |
Note [removed: 17] [added: 16] Employee Benefit Plans and Note [removed: 18] [added: 17] Stock Based Compensation Plans include additional information regarding our employee benefit and equity compensation plans that use PNC common stock.
(b)Consistent with the SCB framework, which allows for capital return in amounts in excess of the SCB minimum levels, our Board of Directors has authorized a repurchase framework under the [added: previously approved] repurchase program of up to 100 million common [removed: shares approved on April 4, 2019.][added: shares, of which approximately 45 million shares, or 45% were still available for repurchase at December 31, 2023.]
Under the SCB framework we repurchased [removed: 21.1] [added: 4.0] million shares in [removed: 2022] [added: 2023] and [removed: 5.0] [added: 21.1] million shares in [removed: 2021.][added: 2022.]
[removed: 34] [added: 36] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K*
This graph shows the cumulative total shareholder return (*i.e.*, price change plus reinvestment of dividends) on our common stock during the five-year period ended December 31, [removed: 2022,] [added: 2023,] as compared with: (i) a selected peer group as set forth below and referred to as the “Peer Group”; (ii) an overall stock market index, the S&P 500 Index; and (iii) a published industry index, the S&P 500 Banks.
The stock performance graph assumes that $100 was invested at market close on December 31, [removed: 2017] [added: 2018] for the five-year period and that dividends were reinvested.
[removed: 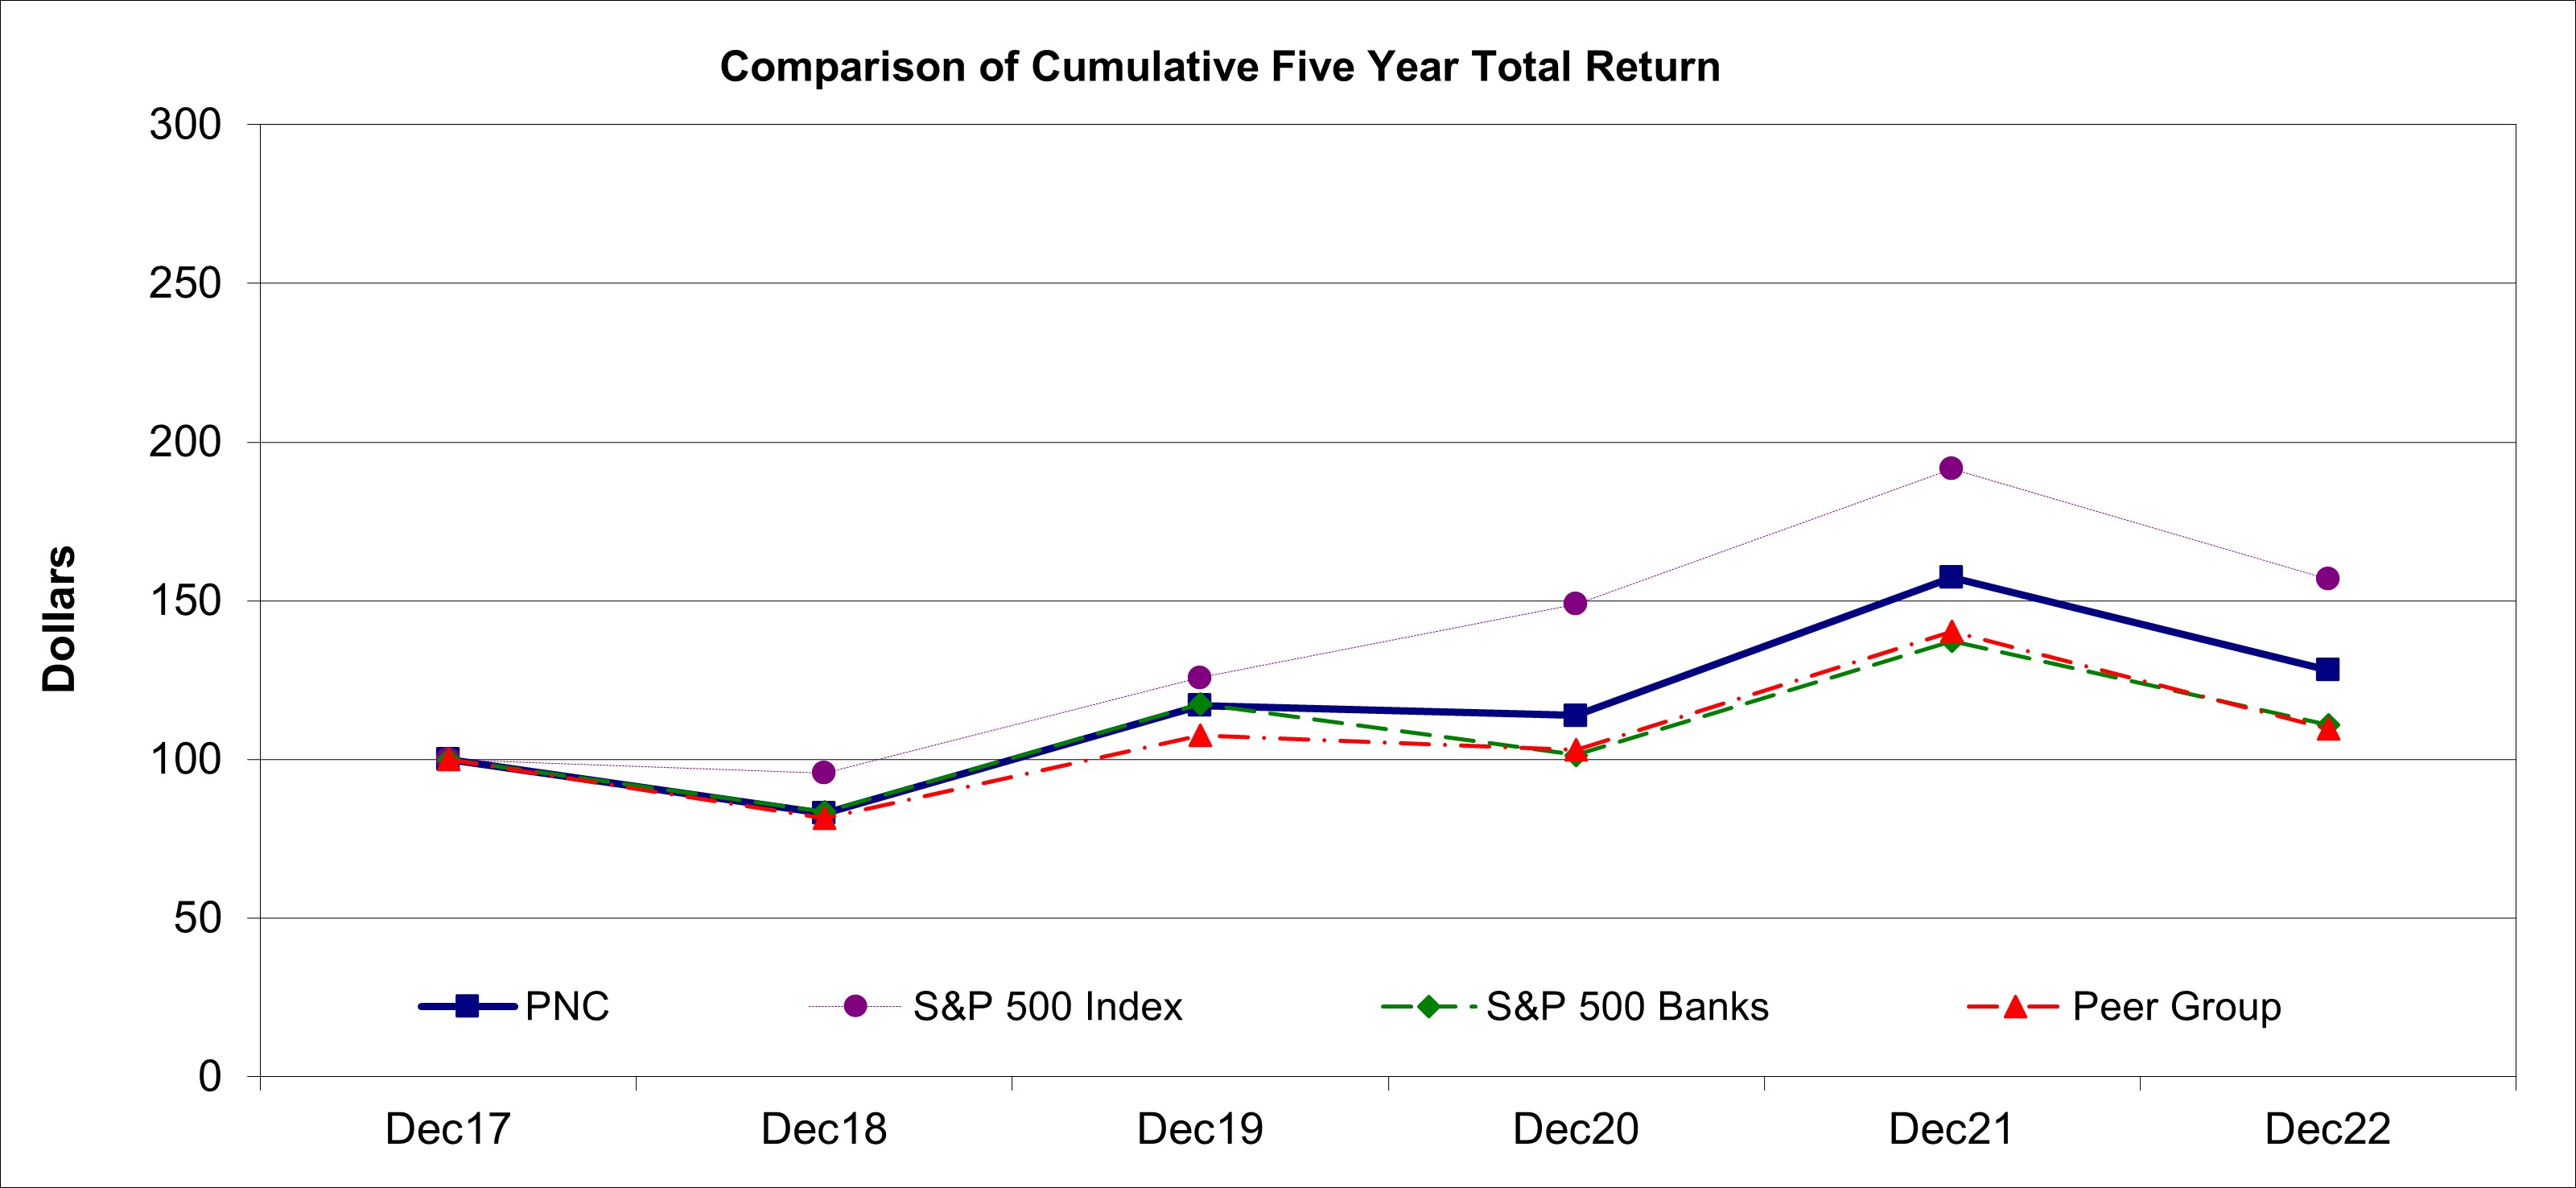][added: 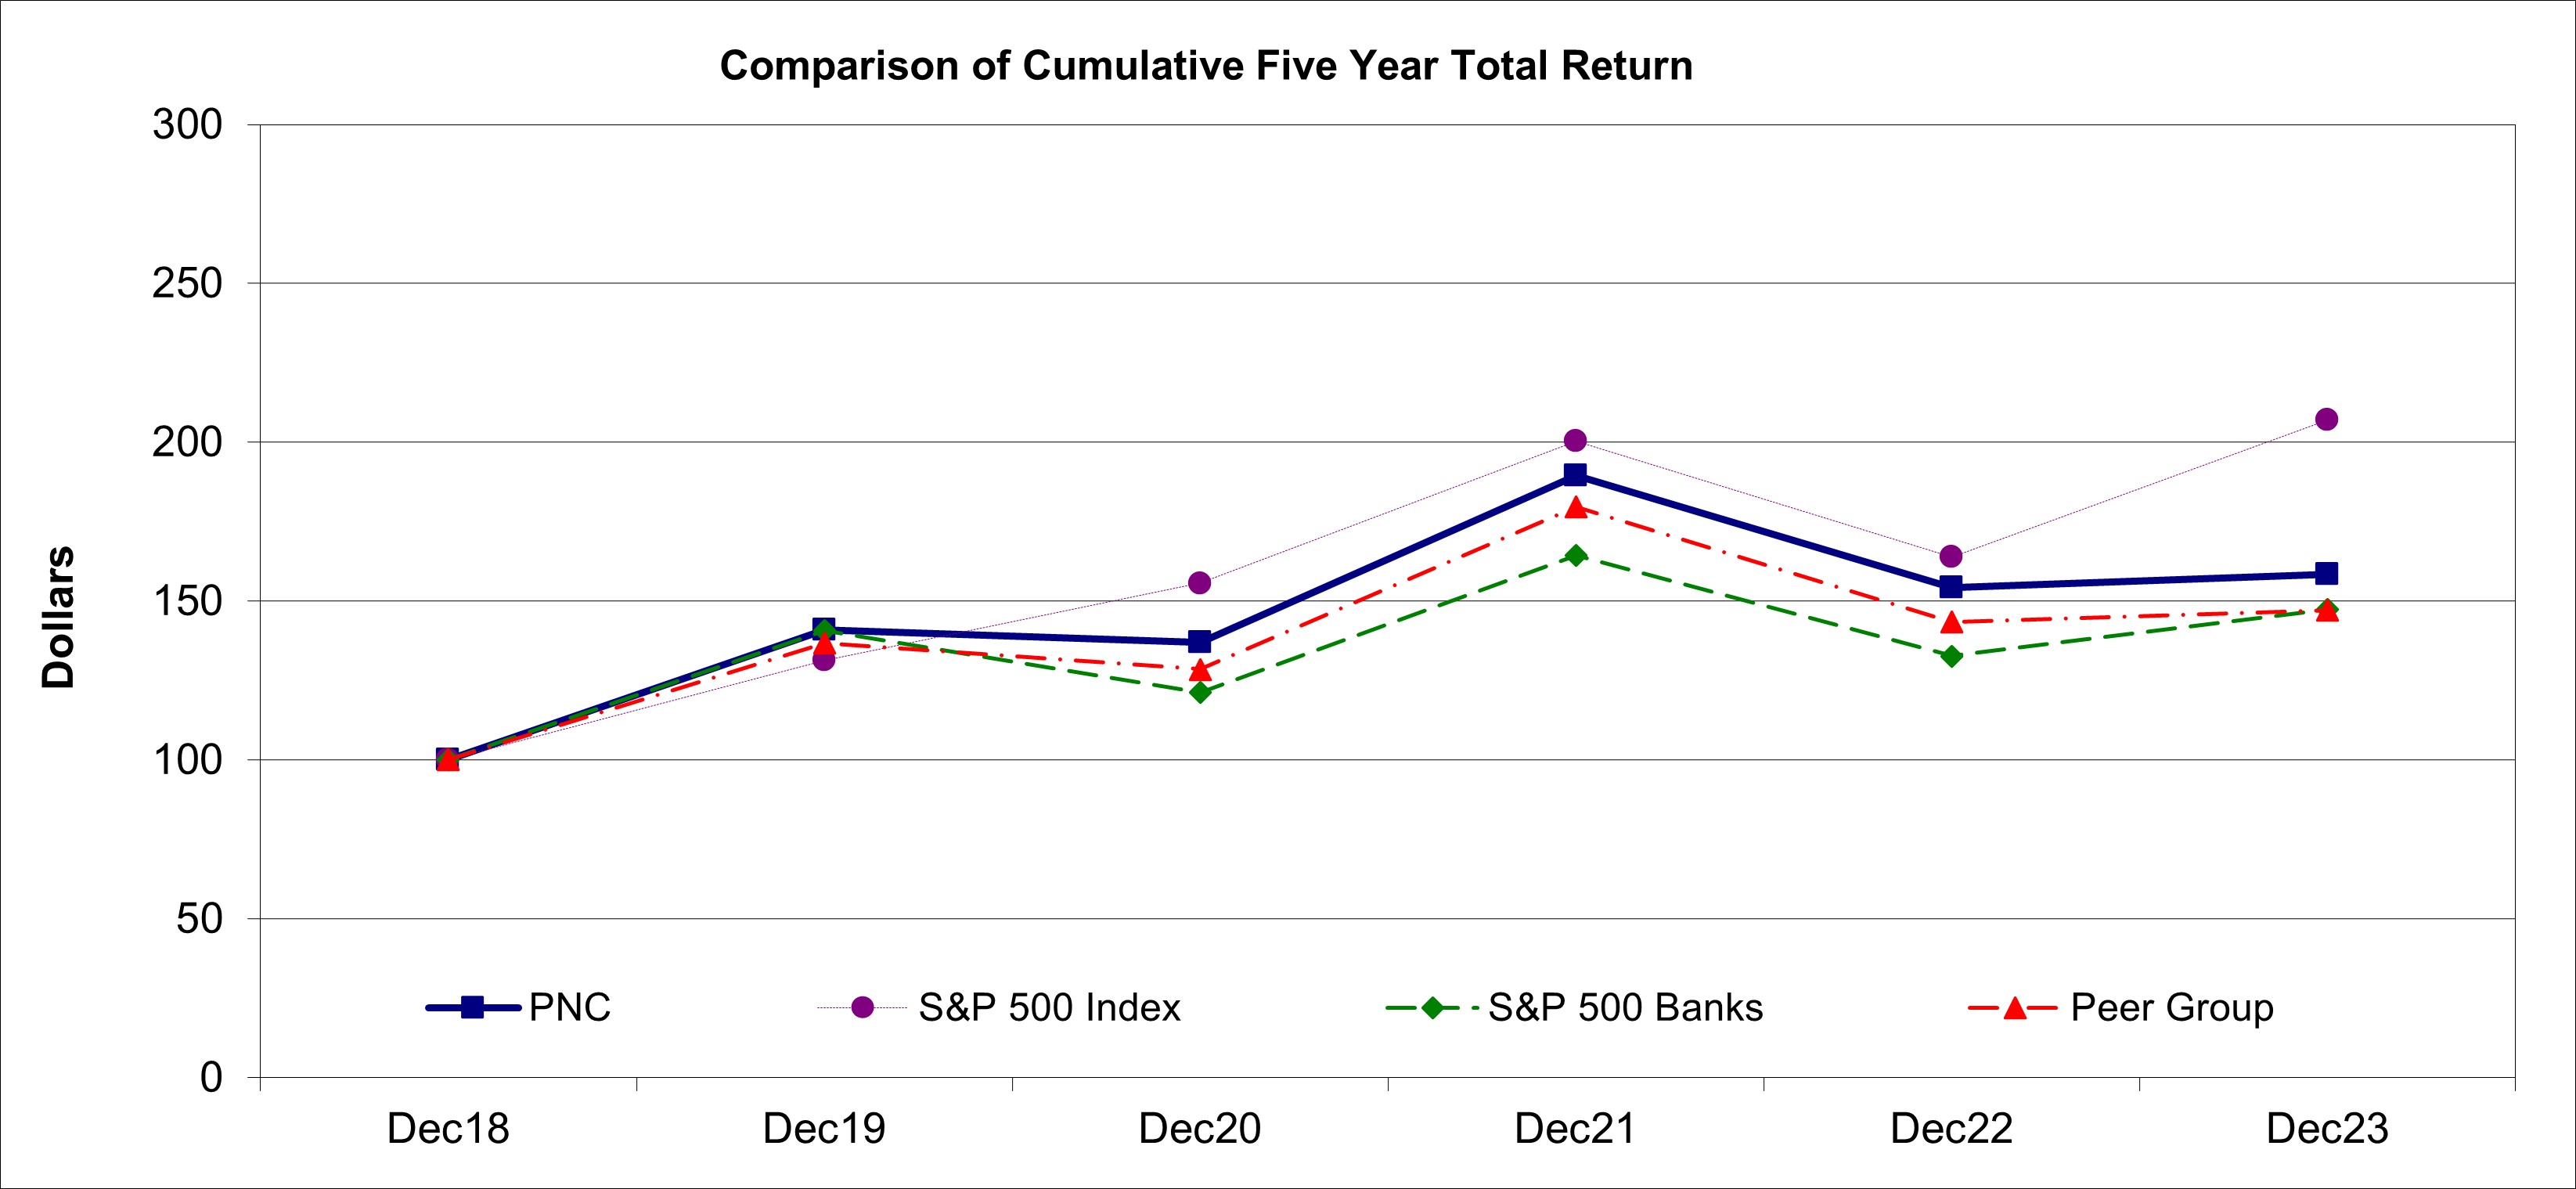]
| | | | Base Period | | | Assumes $100 investment at Close of Market on December 31, [removed: 2017] [added: 2018] Total Return = Price change plus reinvestment of dividends | | | | | | | | | | | | | | | 5-Year Compound Growth Rate | | |
| | | | Dec. [removed: 2017 | | | Dec.] 2018 | | | Dec. 2019 | | | Dec. 2020 | | | Dec. 2021 | | | Dec. 2022 | | | [added: Dec. 2023] | | | [added: | | |]
[removed: For Truist Financial Corporation, the preceding chart and table reflects historical BB&T Corporation] data [removed: from December 2017 to] [added: up until] December [removed: 2018] [added: 6, 2019,] without inclusion of historical data from SunTrust Banks, Inc. This Peer Group was approved for [removed: 2022] [added: 2023] by the Board’s Personnel and Compensation Committee, and the Committee has approved the same peer group for [removed: 2023.][added: 2024.]
Each yearly point for the Peer Group is determined by calculating the cumulative total shareholder return for each company in the Peer Group from December 31, [removed: 2017] [added: 2018] to December 31 of that year, or the last business day of that year (End of Month Dividend Reinvestment Assumed) and then using the median of these returns as the yearly plot point.
In light of the Federal banking agencies proposed rules to adjust the Basel III capital framework, share repurchase activity is expected to remain modest during the first quarter of 2024.
PNC continues to evaluate the potential impact of the proposed rules and may adjust share repurchase activity depending on market and economic conditions, as well as other factors.
| October 1 – 31 | | | 10 | | | $ | 118.13 | | | | | 45,500 | | |
| November 1 – 30 | | | 78 | | | $ | 128.58 | | 78 | | | 45,422 | | |
| December 1 – 31 | | | 437 | | | $ | 154.36 | | 437 | | | 44,985 | | |
| Total | | | 525 | | | $ | 149.83 | | 515 | | | | | |
In light of the Federal banking agencies proposed rules to adjust the Basel III capital framework, share repurchase activity is expected to remain modest during the first quarter of 2024.
PNC continues to evaluate the potential impact of the proposed rules and may adjust share repurchase activity depending on market and economic conditions, as well as other factors.
PNC’s SCB for the four-quarter period beginning October 1, 2023 is the regulatory minimum of 2.5%.
| PNC | | | $ | 100 | | $ | 140.89 | | $ | 137.04 | | $ | 189.42 | | $ | 154.26 | | $ | 158.41 | | 9.64 | | % |
| S&P 500 Index | | | $ | 100 | | $ | 131.47 | | $ | 155.65 | | $ | 200.29 | | $ | 163.98 | | $ | 207.04 | | 15.67 | | % |
| S&P 500 Banks | | | $ | 100 | | $ | 140.64 | | $ | 121.29 | | $ | 164.28 | | $ | 132.73 | | $ | 147.28 | | 8.05 | | % |
| Peer Group | | | $ | 100 | | $ | 136.89 | | $ | 128.54 | | $ | 179.63 | | $ | 143.33 | | $ | 147.08 | | 8.02 | | % |
For Truist Financial Corporation, the preceding chart and table reflects historical BB&T Corporation
Under this framework, PNC expects quarterly repurchases of up to $500 million with the ability to adjust those levels as conditions warrant.
| In thousands, except per share data | | | | | | | | | | | | | | |
| October 1 – 31 | | | 1,534 | | | $ | 154.72 | | 1,523 | | | 51,280 | | |
| November 1 – 30 | | | 1,234 | | | $ | 161.33 | | 1,234 | | | 50,046 | | |
| December 1 – 31 | | | 1,052 | | | $ | 154.63 | | 1,052 | | | 48,994 | | |
| Total | | | 3,820 | | | $ | 156.83 | | 3,809 | | | | | |
A maximum amount of 49.0 million shares remained available for repurchase under the new stock program authorization at December 31, 2022.
| PNC | | | $ | 100 | | $ | 83.02 | | $ | 116.97 | | $ | 113.78 | | $ | 157.26 | | $ | 128.07 | | 5.07 | | % |
| S&P 500 Index | | | $ | 100 | | $ | 95.61 | | $ | 125.70 | | $ | 148.81 | | $ | 191.48 | | $ | 156.77 | | 9.41 | | % |
| S&P 500 Banks | | | $ | 100 | | $ | 83.56 | | $ | 117.52 | | $ | 101.35 | | $ | 137.28 | | $ | 110.91 | | 2.09 | | % |
| Peer Group | | | $ | 100 | | $ | 81.35 | | $ | 107.62 | | $ | 103.04 | | $ | 140.25 | | $ | 109.51 | | 1.83 | | % |
Item 6. RESERVED
0 rewritten, 0 added, 1 removed, 0 unchanged
The PNC Financial Services Group, Inc. – *2022 Form 10-K* 35
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
1,534 rewritten, 573 added, 569 removed, 2,164 unchanged
| [Reports of Independent Registered Public Accounting [removed: Firm](#ib4bdc01166af494b81c4833469b4fe36_202)] [added: Firm](#i697b5c6c53da4edd87b88055b5e4dfbe_208)] (PCAOB ID: 238) | | | | | | | | | | | | [removed: [86](#ib4bdc01166af494b81c4833469b4fe36_202)] [added: [83](#i697b5c6c53da4edd87b88055b5e4dfbe_208)] | | |
| [Consolidated Income [removed: Statement](#ib4bdc01166af494b81c4833469b4fe36_205)] [added: Statement](#i697b5c6c53da4edd87b88055b5e4dfbe_211)] | | | | | | | | | | | | [removed: [88](#ib4bdc01166af494b81c4833469b4fe36_205)] [added: [85](#i697b5c6c53da4edd87b88055b5e4dfbe_211)] | | |
| [Consolidated Statement of Comprehensive [removed: Income](#ib4bdc01166af494b81c4833469b4fe36_208)] [added: Income](#i697b5c6c53da4edd87b88055b5e4dfbe_214)] | | | | | | | | | | | | [removed: [89](#ib4bdc01166af494b81c4833469b4fe36_208)] [added: [86](#i697b5c6c53da4edd87b88055b5e4dfbe_214)] | | |
| [Consolidated Balance [removed: Sheet](#ib4bdc01166af494b81c4833469b4fe36_211)] [added: Sheet](#i697b5c6c53da4edd87b88055b5e4dfbe_217)] | | | | | | | | | | | | [removed: [90](#ib4bdc01166af494b81c4833469b4fe36_211)] [added: [87](#i697b5c6c53da4edd87b88055b5e4dfbe_217)] | | |
| [Consolidated Statement of Changes in [removed: Equity](#ib4bdc01166af494b81c4833469b4fe36_214)] [added: Equity](#i697b5c6c53da4edd87b88055b5e4dfbe_220)] | | | | | | | | | | | | [removed: [91](#ib4bdc01166af494b81c4833469b4fe36_214)] [added: [88](#i697b5c6c53da4edd87b88055b5e4dfbe_220)] | | |
| [Consolidated Statement of Cash [removed: Flows](#ib4bdc01166af494b81c4833469b4fe36_220)] [added: Flows](#i697b5c6c53da4edd87b88055b5e4dfbe_226)] | | | | | | | | | | | | [removed: [92](#ib4bdc01166af494b81c4833469b4fe36_220)] [added: [89](#i697b5c6c53da4edd87b88055b5e4dfbe_226)] | | |
| [Notes to the Consolidated Financial [removed: Statements](#ib4bdc01166af494b81c4833469b4fe36_223)] [added: Statements](#i697b5c6c53da4edd87b88055b5e4dfbe_229)] | | | | | | | | | | | | [removed: [94](#ib4bdc01166af494b81c4833469b4fe36_223)] [added: [91](#i697b5c6c53da4edd87b88055b5e4dfbe_229)] | | |
[added: 82] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 85]
We have audited the accompanying consolidated balance sheet of The PNC Financial Services Group, Inc. and its subsidiaries (the “Company”) as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the related consolidated statements of income, of comprehensive income, of changes in equity and of cash flows for each of the three years in the period ended December 31, [removed: 2022,] [added: 2023,] including the related notes (collectively referred to as the “consolidated financial statements”).
We also have audited the [removed: Company’s] [added: Company's] internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2022] [added: 2023] and [removed: 2021,] [added: 2022,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2022] [added: 2023] in conformity with accounting principles generally accepted in the United States of America.
Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2022,] [added: 2023,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the COSO.
[removed: 86] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [added: 83]
[removed: The] communication of critical audit matters does not alter in any way our opinion on the consolidated financial statements, taken as a whole, and we are not, by communicating the critical audit matter below, providing a separate opinion on the critical audit matter or on the accounts or disclosures to which it relates.
[removed: Allowance] [added: *Allowance] for Loans and Lease Losses – Commercial [removed: Loans][added: Loans*]
As described in Notes 1 and [removed: 4] [added: 3] to the consolidated financial statements, the allowance for loans and lease losses was approximately [removed: $4,741] [added: $4,791] million as of December 31, [removed: 2022,] [added: 2023,] of which [removed: $3,114] [added: $3,259] million relates to commercial loans.
The principal considerations for our determination that performing procedures relating to the allowance for loan and lease losses for commercial loans is a critical audit matter are (i) the significant judgment and estimation by management in developing economic forecast scenarios of Real GDP and U.S. unemployment rate, determining weighting of each scenario, and estimating qualitative reserves, [removed: which in turn led to] [added: (ii)] a high degree of auditor judgment, subjectivity and effort in performing procedures and in evaluating audit evidence related to management’s significant judgements and [removed: estimations] [added: estimations,] and [removed: (ii)] [added: (iii)] the audit effort involved [added: the use of] professionals with specialized skill and knowledge.
[added: 84] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 87]
| In millions, except per share data | | | [removed: 2022] [added: 2023] | | | | | | [removed: 2021] [added: 2022] | | | | | | [removed: 2020] [added: 2021] | | |
| Loans | | | $ | [removed: 11,795] [added: 18,299] | | | | | $ | [removed: 9,007] [added: 11,795] | | | | | $ | [removed: 8,927] [added: 9,007] | |
| Investment securities | | | [removed: 2,726] [added: 3,545] | | | | | | [removed: 1,834] [added: 2,726] | | | | | | [removed: 2,041] [added: 1,834] | | |
| Other | | | [removed: 915] [added: 2,464] | | | | | | [removed: 293] [added: 915] | | | | | | [removed: 339] [added: 293] | | |
| Total interest income | | | [removed: 15,436] [added: 24,308] | | | | | | [removed: 11,134] [added: 15,436] | | | | | | [removed: 11,307] [added: 11,134] | | |
| Deposits | | | [removed: 1,267] [added: 6,609] | | | | | | [removed: 126] [added: 1,267] | | | | | | [removed: 643] [added: 126] | | |
| Borrowed funds | | | [removed: 1,155] [added: 3,783] | | | | | | [removed: 361] [added: 1,155] | | | | | | [removed: 718] [added: 361] | | |
| Total interest expense | | | [removed: 2,422] [added: 10,392] | | | | | | [removed: 487] [added: 2,422] | | | | | | [removed: 1,361] [added: 487] | | |
| Net interest income | | | [removed: 13,014] [added: 13,916] | | | | | | [removed: 10,647] [added: 13,014] | | | | | | [removed: 9,946] [added: 10,647] | | |
| Asset management and brokerage | | | [removed: 1,444] [added: 1,412] | | | | | | [removed: 1,438] [added: 1,444] | | | | | | [removed: 1,203] [added: 1,438] | | |
| Capital markets and advisory | | | [removed: 1,296] [added: 952] | | | | | | [removed: 1,577] [added: 1,296] | | | | | | [removed: 1,259] [added: 1,577] | | |
| Card and cash management | | | [removed: 2,633] [added: 2,733] | | | | | | [removed: 2,398] [added: 2,633] | | | | | | [removed: 1,913] [added: 2,398] | | |
| Lending and deposit services | | | [removed: 1,134] [added: 1,233] | | | | | | [removed: 1,102] [added: 1,134] | | | | | | [removed: 1,026] [added: 1,102] | | |
| Residential and commercial mortgage | | | [removed: 647] [added: 625] | | | | | | [removed: 850] [added: 647] | | | | | | [removed: 946] [added: 850] | | |
| Other | | | [removed: 952] [added: 619] | | | | | | [removed: 1,199] [added: 952] | | | | | | [removed: 608] [added: 1,199] | | |
| Total noninterest income | | | [removed: 8,106] [added: 7,574] | | | | | | [removed: 8,564] [added: 8,106] | | | | | | [removed: 6,955] [added: 8,564] | | |
| Total revenue | | | [removed: 21,120] [added: 21,490] | | | | | | [removed: 19,211] [added: 21,120] | | | | | | [removed: 16,901] [added: 19,211] | | |
| Provision For (Recapture of) Credit Losses | | | [removed: 477] [added: 742] | | | | | | [removed: (779)] [added: 477] | | | | | | [removed: 3,175] [added: (779)] | | |
| Personnel | | | [removed: 7,244] [added: 7,428] | | | | | | [removed: 7,141] [added: 7,244] | | | | | | [removed: 5,673] [added: 7,141] | | |
| Occupancy | | | [removed: 992] [added: 982] | | | | | | [removed: 940] [added: 992] | | | | | | [removed: 826] [added: 940] | | |
| Equipment | | | [removed: 1,395] [added: 1,411] | | | | | | [removed: 1,411] [added: 1,395] | | | | | | [removed: 1,176] [added: 1,411] | | |
| Marketing | | | [removed: 355] [added: 350] | | | | | | [removed: 319] [added: 355] | | | | | | [removed: 236] [added: 319] | | |
The
February 21, 2024
| Balance at January 1, 2023 (a) | | | 401 | | | | | | $ | 2,714 | | $ | 5,746 | | $ | 12,630 | | $ | 53,598 | | $ | (10,172) | | $ | (18,716) | | | | | $ | 38 | | $ | 45,838 | |
| Preferred stock issuance (h) | | | | | | | | | | | | 1,487 | | | | | | | | | | | | | | | | | | | | | 1,487 | | |
| Balance at December 31, 2023 (a) | | | 398 | | | | | | $ | 2,716 | | $ | 6,241 | | $ | 12,779 | | $ | 56,290 | | $ | (7,712) | | $ | (19,209) | | | | | $ | 36 | | $ | 51,141 | |
(g)Represents the cumulative effect of adopting ASU 2022-02.
| Other operating activities, net | | | | | | 1,197 | | | | | | 838 | | | | | | (258) | | |
| Other investing activities, net | | | | | | (1,950) | | | | | | (2,995) | | | | | | (2,682) | | |
| Adjustment to assets and liabilities related to partially financed investment exits | | | | | | $ | 834 | | | | | | | | | | | | | |
(a)During the year ended December 31, 2021, cash paid to acquire BBVA was $11,480 million.
The amount of $10,511 million represents the cash paid for the acquisition less $969 million in cash acquired.
PNC paid $11.5 billion in cash as consideration for the acquisition.
On October 8, 2021, BBVA USA merged into PNC Bank.
We do not consider contractual restrictions on the sale of an equity security when measuring fair value.
The CARES Act credit reporting rules, which required exceptions to this policy, expired in the third quarter of 2023.
Prior period amounts continue to be presented in accordance with the credit reporting rules under the CARES Act, which required certain loans modified due to pandemic-related hardships to not be reported as past due based on the contractual terms of the loan, even when borrowers may not have made payments on their loans during the modification period.
Amortized cost basis does not include accrued
On January 1, 2023, we adopted ASU 2022-02 *Financial Instruments—Credit Losses (Topic 326): Troubled Debt Restructurings and Vintage Disclosures* (ASU 2022-02), which eliminates the accounting guidance for TDRs and replaces TDRs with loan modifications to borrowers experiencing financial difficulty, or FDMs.
FDMs occur as a result of our loss mitigation activities.
A variety of solutions are offered to borrowers, including loan modifications that may result in principal forgiveness, interest rate reductions, term extensions, payment delays, repayment plans or combinations thereof:
- Interest rate reductions include modifications where the interest rate is reduced and/or interest is deferred.
- Term extensions extend the original contractual maturity date of the loan.
- Payment delays consist of modifications where we expect to collect contractual amounts due but that result in a delay in the receipt of payments specified under the original loan terms.
We generally consider payment delays to be insignificant when the delay is three months or less.
- Repayment plans are offered for some of our credit card and unsecured line of credit products, which provide for a reduced payment and interest rate for a specific period of time.
Additionally, modifications to borrowers experiencing financial difficulty also result from borrowers that have been discharged from personal liability through Chapter 7 bankruptcy and have not formally reaffirmed their obligations to us, and those that enter into trial modifications.
FDMs exclude loans held for sale and loans accounted for under the fair value option.
Our disclosed FDM population also excludes government insured or guaranteed education loans as loss mitigation activities for these loans are either required by law or they are considered separate from PNC’s loss mitigation treatments.
Commercial loans with an appraised value of collateral that exceeds the loan value, loans with guarantor support, and residential mortgage government insured or guaranteed loans are included in our disclosed population of FDMs when those loan modifications are granted to a borrower experiencing financial difficulty.
FDMs continue to be subject to our existing nonaccrual policies.
Expected losses or recoveries on FDMs have been factored into the ALLL estimates for each loan class under the methodologies described in this Note 1.
Additionally, for periods prior to 2023,
These nonperforming loans would also be charged off when the collateral has been repossessed.
If payment is received on a nonaccrual loan, generally the payment is first applied to the remaining principal balance.
For TDRs prior to the adoption of ASU 2022-02, payments were applied based upon their contractual terms unless the related loan was deemed non-performing.
Consumer loans modified due to a borrower experiencing financial difficulty are generally included in nonperforming and nonaccrual loans if they are not government insured or guaranteed.
Commercial loans modified due to a borrower experiencing financial difficulty may be included in nonperforming and nonaccrual loans, subject to the bank’s policies for nonperforming loans and leases.
FDMs may remain on accruing status if the bank expects to collect all contractual principal and interest due under the loan and the borrower remains current.
Collateral coverage, guarantor and/or sponsor support and debt service coverage are factors that may be considered in the accruing status of an FDM loan.
FDM loans classified as nonperforming and nonaccrual loans may return to accruing status after a reasonable period of time, generally six months, in which the loan performs under modified terms and meets other performance indicators.
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
*Change in Accounting Principle*
As discussed in Note 1 to the consolidated financial statements, the Company changed the manner in which it accounts for the allowance for credit losses in 2020.
February 22, 2023
| Income from discontinued operations before taxes | | | | | | | | | | | | | | | 5,777 | | |
| Income taxes from discontinued operations | | | | | | | | | | | | | | | 1,222 | | |
| Net income from discontinued operations | | | | | | | | | | | | | | | 4,555 | | |
| Basic earnings from continuing operations | | | $ | 13.86 | | | | | $ | 12.71 | | | | | $ | 6.37 | |
| Basic earnings from discontinued operations | | | | | | | | | | | | | | | 10.62 | | |
| Diluted earnings from continuing operations | | | $ | 13.85 | | | | | $ | 12.70 | | | | | $ | 6.36 | |
| Diluted earnings from discontinued operations | | | | | | | | | | | | | | | 10.60 | | |
| Net income from discontinued operations | | | | | | | | | | | | | | | 4,555 | | |
| Other comprehensive income from discontinued operations, before tax and net of reclassifications into Net income | | | | | | | | | | | | | | | 148 | | |
| Income tax expense from discontinued operations related to items of other comprehensive income | | | | | | | | | | | | | | | (33) | | |
| Other comprehensive income from discontinued operations, after tax and net of reclassifications into Net income | | | | | | | | | | | | | | | 115 | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
$0.1 billion at December 31, 2022 and Loans held for sale of $1.9 billion, Loans of $1.5 billion and Other assets of $0.1 billion at December 31, 2021.
| Balance at December 31, 2019 (a) | | | 433 | | | | | | $ | 2,712 | | $ | 3,993 | | $ | 12,376 | | $ | 42,215 | | $ | 799 | | $ | (12,781) | | | | | $ | 29 | | $ | 49,343 | |
| Balance at January 1, 2020 (a) | | | 433 | | | | | | $ | 2,712 | | $ | 3,993 | | $ | 12,376 | | $ | 41,544 | | $ | 799 | | $ | (12,781) | | | | | $ | 29 | | $ | 48,672 | |
| Net income | | | | | | | | | | | | | | | | | | 7,517 | | | | | | | | | | | | 41 | | | 7,558 | | |
(b)Represents the impact of the adoption of ASU 2016-13 - *Financial Instruments - Credit Losses*.
| Gain on sale of BlackRock | | | | | | | | | | | | | | | | | | (5,740) | | |
| Undistributed earnings of BlackRock | | | | | | | | | | | | | | | | | | (174) | | |
| Other | | | | | | 831 | | | | | | (194) | | | | | | 684 | | |
| Net proceeds from sale of BlackRock | | | | | | | | | | | | | | | | | | 14,225 | | |
| Other | | | | | | (2,995) | | | | | | (2,682) | | | | | | (1,264) | | |
| Federal Home Loan Bank borrowings | | | | | | | | | | | | (3,680) | | | | | | (15,601) | | |
| Net Cash Provided By Discontinued Operations | | | | | | | | | | | | | | | | | | 11,542 | | |
| Net Cash Provided (Used) By Continuing Operations | | | | | | (961) | | | | | | 987 | | | | | | (9,586) | | |
| Transfer from trading securities to investment securities | | | | | | | | | | | | | | | | | | $ | 289 | |
(a)During the year ended December 31, 2022, we transferred securities from available for sale to held to maturity in non-cash transactions.
The amount of $88.6 billion includes the aggregate fair value of the securities of $82.7 billion and aggregate net pretax unrealized losses of $5.9 billion included in AOCI at transfer.
Loans
PCD loans do not require additional considerations and thus are evaluated for inclusion in our TDR population.
Prior to the expiration of TDR relief on January 1, 2022, PNC elected not to apply a TDR designation to loans that were restructured due to a COVID-19 hardship pursuant to specific criteria under the CARES Act.
Since loans restructured due to a COVID-19 related hardship were not identified as TDRs, they were not placed on nonaccrual at the time of modification unless payment in full of principal or interest was not expected.
These loans continued to be subject to our existing nonaccrual policy.
| Education / Other consumer | | | | | | •Net charge-off and pay-down rates by vintage are used to estimate expected losses in lieu of discrete risk parameters | | | | | | | | |
| Education / Other consumer | | | •Net charge-off and pay-down rates by vintage are used to estimate expected losses in lieu of discrete risk parameters | | | | | | | | |
While our reserve methodologies strive to reflect all relevant credit risk factors, there continues to be uncertainty associated with, but not limited to, potential imprecision in the estimation process due to the inherent time lag of obtaining information and normal variations between expected and actual outcomes.
An excerpt. Shown here: 40 of 1,534 rewritten, 40 of 573 added and 40 of 569 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2023 filing and the FY2022 filing.
Item 9A. CONTROLS AND PROCEDURES
6 rewritten, 0 added, 0 removed, 7 unchanged
[removed: 198] [added: 188] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K*
We performed an evaluation under the supervision and with the participation of our management, including the Chairman, President and Chief Executive Officer and the Executive Vice President and Chief Financial Officer, of the effectiveness of PNC’s internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
Based on this assessment, management concluded that PNC maintained effective internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
PricewaterhouseCoopers LLP, the independent registered public accounting firm that audited our consolidated financial statements as of and for the year ended December 31, [removed: 2022] [added: 2023] included in this Report, has also audited the effectiveness of PNC’s internal control over financial reporting as of December 31, [removed: 2022.][added: 2023.]
As of December 31, [removed: 2022,] [added: 2023,] we performed an evaluation under the supervision and with the participation of our management, including the Chairman, President and Chief Executive Officer and the Executive Vice President and Chief Financial Officer, of the effectiveness of the design and operation of our disclosure controls and procedures and of changes in our internal control over financial reporting.
Based on that evaluation, our Chairman, President and Chief Executive Officer and our Executive Vice President and Chief Financial Officer concluded that our disclosure controls and procedures (as defined in Rule 13a-15(e) under the Securities and Exchange Act of 1934, as amended) were effective as of December 31, [removed: 2022,] [added: 2023,] and that there has been no change in PNC’s internal control over financial reporting that occurred during the fourth quarter of [removed: 2022] [added: 2023] that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. OTHER INFORMATION
0 rewritten, 2 added, 1 removed, 1 unchanged
Director or Executive Officer Rule 10b5-1 and Non-Rule 10b5-1 Trading Arrangements
During the three months ended December 31, 2023, none of PNC’s directors or executive officers adopted, terminated, or modified a Rule 10b5-1 trading arrangement or non-Rule 10b5-1 trading arrangement.
None.
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
3 rewritten, 0 added, 0 removed, 3 unchanged
Certain of the information regarding our directors (or nominees for director), executive officers and Audit Committee (and Audit Committee financial experts), required by this item is included under the captions [removed: “Election] [added: “Item 1 - Election] of [removed: Directors (Item 1),”] [added: Directors,”] and “Corporate Governance – Board committees – Audit Committee,” in our Proxy Statement to be filed for the [removed: 2023] [added: 2024] annual meeting of shareholders and is incorporated herein by reference.
Information regarding our compliance with Section 16(a) of the Securities Exchange Act of 1934 is included, to the extent necessary, under the caption “Delinquent Section 16(a) Reports” in our Proxy Statement to be filed for the [removed: 2023] [added: 2024] annual meeting of shareholders and is incorporated herein by reference.
Certain information regarding our PNC Code of Business Conduct and Ethics required by this item is included under the captions “Corporate Governance – Our Code of Business Conduct and Ethics” [removed: and “Director and Executive Officer Relationships – Code of Business Conduct and Ethics”] in our Proxy Statement to be filed for the [removed: 2023] [added: 2024] annual meeting of shareholders and is incorporated herein by reference.
Item 11. EXECUTIVE COMPENSATION
3 rewritten, 1 added, 0 removed, 0 unchanged
The information required by this item is included under the captions “Corporate Governance – Board committees – Human Resources Committee – Compensation committee interlocks and insider participation,” “Director Compensation,” “Compensation Discussion and Analysis,” “Compensation Committee Report,” “Compensation and Risk,” “Compensation Tables,” “Change in Control and Termination of Employment” and “CEO Pay Ratio” in our Proxy Statement to be filed for the [removed: 2023] [added: 2024] annual meeting of shareholders and is incorporated herein by reference.
In accordance with Item 407(e)(5) of Regulation S-K, the information set forth under the caption “Compensation Committee Report” in such Proxy Statement will be deemed to be furnished in this Report and will not be [removed: deemed to be incorporated by reference into any filing under the Securities Act or the Exchange Act as a result of furnishing the disclosure in this manner.]
The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 199][added: 189]
deemed to be incorporated by reference into any filing under the Securities Act or the Exchange Act as a result of furnishing the disclosure in this manner.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
10 rewritten, 3 added, 3 removed, 6 unchanged
The information required by this item regarding security ownership of certain beneficial owners and management is included under the caption “Security Ownership of Management and Certain Beneficial Owners” in our Proxy Statement to be filed for the [removed: 2023] [added: 2024] annual meeting of shareholders and is incorporated herein by reference.
Information regarding our compensation plans under which PNC equity securities are authorized for issuance as of December 31, [removed: 2022] [added: 2023] is included in the table which follows.
For additional information regarding these plans, see Note [removed: 18] [added: 17] Stock Based Compensation Plans.
| | | | | | | Number of securities to be issued upon exercise of outstanding options, warrants and rights | | | | | | [removed: Weighted-average exercise price of outstanding options, warrants and rights (1)] | | | | | | Number of securities remaining available for future issuance under equity compensation plans (excluding securities reflected in column (a)) | | | | | |
| Equity compensation plans approved by security holders | | | | | | [removed: 4,324,886] [added: 4,677,131] | | | [removed: (2)] [added: (1)] | | | [removed: $] | [removed: 63.87] | | | | | [removed: 20,020,179] [added: 15,393,550] | | | [removed: (3)] [added: (2)] | | |
[removed: (1) –] The [removed: weighted-average exercise price does not take into account] restricted stock units [removed: or] [added: and] incentive performance units [removed: because they] have no exercise price.
[removed: (2)] [added: (1)] – Of this total, the following amounts relate to the 2016 Incentive Award Plan (2016 Incentive Plan), approved by shareholders on April 26, 2016: [removed: 3,338,653] [added: 3,734,119] are stock-payable restricted stock units (at a maximum share award level), [removed: 871,648] [added: 857,867] are performance share units (at maximum share award level) and [removed: 59,658] [added: 65,431] are deferred stock units (at a maximum share award level).
Also included in this total are [removed: the following amounts] [added: 19,714 stock-payable restricted stock units (at a maximum award level)] that relate to the 2006 Incentive Award Plan, as amended and restated (2006 Incentive [removed: Plan): 10,750 are stock options and 44,177 are stock-payable restricted stock units (at a maximum award level).][added: Plan).]
[removed: (3)] [added: (2)] – Includes [removed: 1,786,148] [added: 1,542,918] shares available for issuance under the Employee Stock Purchase Plan, of which [removed: 106,038] [added: 104,213] shares are subject to purchase during the purchase period ending December 31, [removed: 2022.][added: 2023.]
The amount available for awards under the 2016 Incentive Plan is [removed: 18,234,031.][added: 13,850,632.]
At December 31, 2023
| | | | | | | (a) | | | | | | | | | | | | (b) | | | | | |
| Total | | | | | | 4,677,131 | | | | | | | | | | | | 15,393,550 | | | | | |
At December 31, 2022
| | | | | | | (a) | | | | | | (b) | | | | | | (c) | | | | | |
| Total | | | | | | 4,324,886 | | | | | | $ | 63.87 | | | | | 20,020,179 | | | | | |
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this item is included under the captions “Director and Executive Officer Relationships – Director independence, – Transactions with directors, – Family relationships, and – Indemnification and advancement of costs” and “Related Person Transactions” in our Proxy Statement to be filed for the [removed: 2023] [added: 2024] annual meeting of shareholders and is incorporated herein by reference.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
2 rewritten, 0 added, 0 removed, 1 unchanged
The information required by this item is included under the caption [removed: “Ratification] [added: “Item 2 - Ratification] of Independent Registered Public Accounting Firm” in our Proxy Statement to be filed for the [removed: 2023] [added: 2024] annual meeting of shareholders and is incorporated herein by reference.
[removed: 200] [added: 190] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K*
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
43 rewritten, 1 added, 4 removed, 174 unchanged
| 3.1.1 | | | | | | [Amended and Restated Articles of Incorporation of the Corporation, [added: as amended and] effective January 2, 2009](http://www.sec.gov/Archives/edgar/data/713676/000119312509042518/dex31.htm) | | | | | | Incorporated herein by reference to Exhibit 3.1 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2008 | | |
| 3.2 | | | | | | [Amended and Restated Bylaws of the Corporation effective February 10, [removed: 2022](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/ex32corpbylaws172022fina.htm)] [added: 2022](https://www.sec.gov/Archives/edgar/data/713676/000071367624000028/a32corpbylaws172022final.htm)] | | | | | | Filed herewith | | |
The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 201][added: 191]
[removed: 202] [added: 192] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K*
| 4.14 | | | | | | [Description of the Corporation’s [removed: Securities](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/exhibit414descriptionofs.htm)] [added: Securities](https://www.sec.gov/Archives/edgar/data/713676/000071367624000028/descriptionofsecuritiese.htm)] | | | | | | Filed herewith | | |
| 10.2 | | | | | | [The Corporation’s ERISA Excess Pension Plan, as amended and restated effective January 1, 2023](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/exhibit102erisaexcesspen.htm) | | | | | | [removed: Filed herewith*] [added: Incorporated by reference to Exhibit 10.2 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2022*] | | |
The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 203][added: 193]
| 10.7 | | | | | | [The PNC Financial Services Group, Inc. 2016 Incentive Award [removed: Plan](http://www.sec.gov/Archives/edgar/data/713676/000119312516567192/d172001dex991.htm)] [added: Plan](https://www.sec.gov/Archives/edgar/data/713676/000119312516567192/d172001dex991.htm)] | | | | | | Incorporated herein by reference to Exhibit 99.1 of the Corporation’s Form S-8 (File No. 333-210995) filed April 29, 2016* | | |
| [removed: 10.8.1] [added: 10.28.1] | | | | | | [The [removed: Corporation’s 2006 Incentive Award] [added: National City Corporation 2004 Deferred Compensation] Plan, as amended and restated effective [removed: as of March 11, 2011](http://www.sec.gov/Archives/edgar/data/713676/000119312511131571/dex1070.htm)] [added: January 1, 2005](http://www.sec.gov/Archives/edgar/data/69970/000095015206004116/l19873aexv10w35.txt)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.70] [added: 10.35] of [removed: the] [added: National City] Corporation’s Quarterly Report on Form 10-Q for the quarter ended March 31, [removed: 2011*] [added: 2006*] | | |
| [removed: 10.8.2] [added: 10.12] | | | | | | [removed: [Addendum to the Corporation’s 2006 Incentive Award Plan, effective as] [added: [Certificate] of [added: Corporate Action for Grantor Trusts effective] January [removed: 26, 2012](http://www.sec.gov/Archives/edgar/data/713676/000119312512087345/d260760dex1028.htm)] [added: 1, 2012](http://www.sec.gov/Archives/edgar/data/713676/000119312512087345/d260760dex1037.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.28] [added: 10.37] of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2011* | | |
| [removed: 10.9] [added: 10.8] | | | | | | [The Corporation’s Directors Deferred Compensation Plan, as amended and restated effective January 1, 2015](http://www.sec.gov/Archives/edgar/data/713676/000119312514398221/d786733dex1052.htm) | | | | | | Incorporated herein by reference to Exhibit 10.52 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2014* | | |
| [removed: 10.10] [added: 10.9] | | | | | | [The Corporation’s 2016 Incentive Award Plan Directors Deferred Stock Unit Program effective January 1, 2017](http://www.sec.gov/Archives/edgar/data/713676/000119312517062524/d300732dex1016.htm) | | | | | | Incorporated herein by reference to Exhibit 10.16 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2016* | | |
| [removed: 10.11] [added: 10.10] | | | | | | [Trust Agreement between the Corporation, as settlor, and Matrix Trust Company, as trustee](http://www.sec.gov/Archives/edgar/data/713676/000071367618000032/ex1015-matrixtrustagmt.htm) | | | | | | Incorporated herein by reference to Exhibit 10.15 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2017* | | |
| [removed: 10.12] [added: 10.11] | | | | | | [Trust Agreement between PNC Investment Corp., as settlor, and PNC Bank, National Association, as trustee](http://www.sec.gov/Archives/edgar/data/713676/000119312505217775/dex1034.htm) | | | | | | Incorporated herein by reference to Exhibit 10.34 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2005* | | |
| 10.13 | | | | | | [Certificate of Corporate Action for Grantor Trusts effective [removed: January] [added: December] 1, [removed: 2012](http://www.sec.gov/Archives/edgar/data/713676/000119312512087345/d260760dex1037.htm)] [added: 2021](http://www.sec.gov/Archives/edgar/data/713676/000071367622000019/a1014conformedexecutionv.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.37] [added: 10.14] of the Corporation’s Annual Report on Form 10-K for the year ended December 31, [removed: 2011*] [added: 2021*] | | |
| [removed: 10.14] [added: 10.15] | | | | | | [removed: [Certificate] [added: [2021 Form] of [removed: Corporate Action for Grantor Trusts effective December 1, 2021](http://www.sec.gov/Archives/edgar/data/713676/000071367622000019/a1014conformedexecutionv.htm)] [added: Performance Share Units Award Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367622000019/ex1026-2021cegpsufinalfe.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.14] [added: 10.26] of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2021* | | |
| [removed: 10.15] [added: 10.14] | | | | | | [The Corporation’s Employee Stock Purchase Plan, as amended and restated as of January 1, 2020](http://www.sec.gov/Archives/edgar/data/713676/000071367620000084/exhibit44pnc-esppplandocum.htm) | | | | | | Incorporated herein by reference to Exhibit 4.4 of the Corporation’s Form S-8 (File No. 333-238049) filed May 6, 2020* | | |
| 10.16 | | | | | | [removed: [2013 forms] [added: [2021 Form] of [removed: employee stock option and restricted share unit agreements](http://www.sec.gov/Archives/edgar/data/713676/000119312513085012/d446794dex1064.htm)] [added: Restricted Share Units Award Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367621000095/a1036-202110qcegrsufinal.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.64] [added: 10.36] of the Corporation’s Annual Report on Form 10-K for the year ended December 31, [removed: 2012*] [added: 2021*] | | |
| [removed: 10.17] [added: 10.21] | | | | | | [removed: [Additional 2013 forms] [added: [2022 Form] of [removed: employee stock option, performance unit, restricted stock and restricted share unit agreements](http://www.sec.gov/Archives/edgar/data/713676/000119312513326063/d546718dex1082.htm)] [added: Performance Restricted Share Units Award Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1037-2022formofperform.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.82] [added: 10.37] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, [removed: 2013*] [added: 2022*] | | |
[removed: 204] [added: 194] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K*
| 10.18 | | | | | | [removed: [2020] [added: [2022] Form of Performance Share Units Award [removed: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367620000115/pnc-06302020xex1039.htm)] [added: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1034-2022formofperform.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.39] [added: 10.34] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, [removed: 2020*] [added: 2022*] | | |
| 10.19 | | | | | | [removed: [2020] [added: [2022] Form of Restricted Share Units Award [removed: Agreement](https://www.sec.gov/Archives/edgar/data/713676/000071367620000115/pnc-06302020xex1040.htm)] [added: Agreement](https://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1035-2022formofrestric.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.40] [added: 10.35] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, [removed: 2020*] [added: 2022*] | | |
| 10.20 | | | | | | [removed: [2020] [added: [2022] Form of Restricted Share Units Award Agreement [removed: -] [added: –] Senior Leader [removed: Program](https://www.sec.gov/Archives/edgar/data/713676/000071367620000115/pnc-06312020xex1041.htm)] [added: Program](http://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1036-2022formofrestric.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.41] [added: 10.36] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, [removed: 2020*] [added: 2022*] | | |
| [removed: 10.21] [added: 10.22] | | | | | | [removed: [2021] [added: [2023] Form of Performance Share Units Award [removed: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367622000019/ex1026-2021cegpsufinalfe.htm)] [added: Agreement](https://www.sec.gov/Archives/edgar/data/713676/000071367623000058/a1033-23executiveperform.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.26] [added: 10.33] of the Corporation’s [removed: Annual] [added: Quarterly] Report on Form [removed: 10-K] [added: 10-Q] for the [removed: year] [added: quarter] ended [removed: December 31, 2021*] [added: June 30, 2023*] | | |
| [removed: 10.22] [added: 10.25] | | | | | | [removed: [2021] [added: [2023] Form of [added: Five-Year] Restricted Share Units Award [removed: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367621000095/a1036-202110qcegrsufinal.htm)] [added: Agreement](https://www.sec.gov/Archives/edgar/data/713676/000071367621000095/a1036-202110qcegrsufinal.htm)] | | | | | | Incorporated herein by reference to Exhibit 10.36 of the Corporation’s [removed: Annual] [added: Quarterly] Report on Form [removed: 10-K] [added: 10-Q] for the [removed: year] [added: quarter] ended [removed: December 31, 2021*] [added: June 30, 2023*] | | |
| [removed: 10.23] [added: 10.17] | | | | | | [2021 Form of Restricted Share Units Award Agreement – Senior Leader Program](https://www.sec.gov/Archives/edgar/data/713676/000071367621000095/a1037-2021section16senio.htm) | | | | | | Incorporated herein by reference to Exhibit 10.37 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2021* | | |
| [removed: 10.24] [added: 10.23] | | | | | | [removed: [2022] [added: [2023] Form of [removed: Performance] [added: Restricted] Share Units Award [removed: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1034-2022formofperform.htm)] [added: Agreement](https://www.sec.gov/Archives/edgar/data/713676/000071367623000058/a1034-23executiverestric.htm)] | | | | | | Incorporated herein by reference to Exhibit 10.34 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, [removed: 2022*] [added: 2023*] | | |
| [removed: 10.25] [added: 10.24] | | | | | | [removed: [2022] [added: [2023] Form of Restricted Share Units Award [removed: Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1035-2022formofrestric.htm)] [added: Agreement – Senior Leader Program](https://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1035-2022formofrestric.htm)] | | | | | | Incorporated herein by reference to Exhibit 10.35 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, [removed: 2022*] [added: 2023*] | | |
| 10.26 | | | | | | [removed: [2022 Form] [added: [Form] of [removed: Restricted Share Units Award] [added: Time Sharing] Agreement [removed: – Senior Leader Program](http://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1036-2022formofrestric.htm)] [added: between the Corporation and certain executives](https://www.sec.gov/Archives/edgar/data/713676/000071367622000047/ex1033-templatextimeshar.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.36] [added: 10.33] of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended [removed: June 30,] [added: March 31,] 2022* | | |
| [removed: 10.29] [added: 10.27] | | | | | | [Form of change of control employment [removed: agreements](http://www.sec.gov/Archives/edgar/data/713676/000119312516683131/d241922dex1051.htm)] [added: agreements](https://www.sec.gov/Archives/edgar/data/713676/000119312516683131/d241922dex1051.htm)] | | | | | | Incorporated herein by reference to Exhibit 10.51 of the Corporation’s Current Report on Form 8-K filed August 16, 2016* | | |
| [removed: 10.30.1] [added: 10.28.2] | | | | | | [removed: [The] [added: [Amendment to The] National City Corporation 2004 Deferred Compensation Plan, as amended and restated effective January 1, [removed: 2005](http://www.sec.gov/Archives/edgar/data/69970/000095015206004116/l19873aexv10w35.txt)] [added: 2005](http://www.sec.gov/Archives/edgar/data/713676/000119312511051725/dex1056.htm)] | | | | | | Incorporated herein by reference to Exhibit [removed: 10.35] [added: 10.56] of [removed: National City] [added: the] Corporation’s [removed: Quarterly] [added: Annual] Report on Form [removed: 10-Q] [added: 10-K] for the [removed: quarter] [added: year] ended [removed: March] [added: December] 31, [removed: 2006*] [added: 2010*] | | |
| [removed: 10.31.1] [added: 10.29.1] | | | | | | [Distribution Agreement, dated January 16, 2014, between PNC Bank, National Association and the Dealers named therein, relating to the $25 billion Global Bank Note Program for the Issue of Senior and Subordinated Bank Notes](http://www.sec.gov/Archives/edgar/data/713676/000119312515070443/d836469dex1047.htm) | | | | | | Incorporated by reference to Exhibit 10.47 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2014 | | |
| [removed: 10.31.2] [added: 10.29.2] | | | | | | [Amendment No. 1 to Distribution Agreement, dated May 22, 2015, between PNC Bank, National Association and the Dealers named therein, relating to the $30 billion Global Bank Note Program for the Issue of Senior and Subordinated Bank Notes](http://www.sec.gov/Archives/edgar/data/713676/000119312515277885/d943118dex10472.htm) | | | | | | Incorporated herein by reference to Exhibit 10.47.2 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2015 | | |
The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 205][added: 195]
| [removed: 10.31.3] [added: 10.29.3] | | | | | | [Amendment No. 2 to Distribution Agreement, dated May 27, 2016, between PNC Bank, National Association and the Dealers named therein, relating to the $40 billion Global Bank Note Program for the Issue of Senior and Subordinated Bank Notes](http://www.sec.gov/Archives/edgar/data/713676/000119312516669661/d209081dex10483.htm) | | | | | | Incorporated herein by reference to Exhibit 10.48.3 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2016 | | |
| 21 | | | | | | [Schedule of Certain Subsidiaries of the [removed: Corporation](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/pnc-12312022xex21.htm)] [added: Corporation](https://www.sec.gov/Archives/edgar/data/713676/000071367624000028/pnc-12312023xex21.htm)] | | | | | | Filed herewith | | |
| 22 | | | | | | [Subsidiary Issuers of Guaranteed [removed: Securities](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/pnc-12312022xex22.htm)] [added: Securities](https://www.sec.gov/Archives/edgar/data/713676/000071367624000028/pnc-12312023xex22.htm)] | | | | | | Filed herewith | | |
| 23.1 | | | | | | [Consent of PricewaterhouseCoopers LLP, the Corporation’s Independent Registered Public Accounting [removed: Firm](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/exhibit231signed.htm)] [added: Firm](https://www.sec.gov/Archives/edgar/data/713676/000071367624000028/consent.htm)] | | | | | | Filed herewith | | |
| 24 | | | | | | [Powers of [removed: Attorney](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/exhibit24.htm)] [added: Attorney](https://www.sec.gov/Archives/edgar/data/713676/000071367624000028/powerofattorney.htm)] | | | | | | Filed herewith | | |
| 31.1 | | | | | | [Certification of Chief Executive Officer pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/713676/000071367623000020/pnc-12312022xex311.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/713676/000071367624000028/pnc-12312023xex311.htm)] | | | | | | Filed herewith | | |
| 97 | | | | | | [Dodd-Frank Recoupment Policy effective October 2, 2023](https://www.sec.gov/Archives/edgar/data/713676/000071367624000028/exhibit97-doddxfrank.htm) | | | | | | Filed herewith | | |
| | | | | | | | | | | | | | | |
| 10.27 | | | | | | [2022 Form of Performance Restricted Share Units Award Agreement](http://www.sec.gov/Archives/edgar/data/713676/000071367622000072/ex1037-2022formofperform.htm) | | | | | | Incorporated herein by reference to Exhibit 10.37 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended June 30, 2022* | | |
| 10.28 | | | | | | [Form of Time Sharing Agreement between the Corporation and certain executives](http://www.sec.gov/Archives/edgar/data/713676/000071367622000047/ex1033-templatextimeshar.htm) | | | | | | Incorporated herein by reference to Exhibit 10.33 of the Corporation’s Quarterly Report on Form 10-Q for the quarter ended March 31, 2022* | | |
| 10.30.2 | | | | | | [Amendment to The National City Corporation 2004 Deferred Compensation Plan, as amended and restated effective January 1, 2005](http://www.sec.gov/Archives/edgar/data/713676/000119312511051725/dex1056.htm) | | | | | | Incorporated herein by reference to Exhibit 10.56 of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2010* | | |
An excerpt. Shown here: 40 of 43 rewritten, all 1 added and all 4 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES in the FY2023 filing and the FY2022 filing.
Item 16. FORM 10-K SUMMARY
5 rewritten, 1 added, 1 removed, 28 unchanged
[removed: 206] [added: 196] The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K*
Pursuant to the requirements of the Securities Exchange Act of 1934, this report has been signed below by the following persons on behalf of The PNC Financial Services Group, Inc. and in the capacities indicated on February [removed: 22, 2023.][added: 21, 2024.]
| /s/ William S. Demchak | | | | | | [removed: Chairman, President,] [added: Chairman and] Chief Executive Officer and Director | | |
| * Joseph Alvarado; Debra A. Cafaro; Marjorie Rodgers Cheshire; Andrew T. Feldstein; Richard J. Harshman; Daniel R. Hesse; Renu Khator, Linda R. Medler, Robert A. Niblock, Martin Pfinsgraff; Bryan [removed: Salesky, Toni Townes-Whitley; Michael J. Ward] [added: Salesky] | | | | | | Directors | | |
The PNC Financial Services Group, Inc. – [removed: *2022] [added: *2023] Form 10-K* [removed: 207][added: 197]
| | | | | | | February 21, 2024 | | |
| | | | | | | February 22, 2023 | | |