 filings.tools
Vulcan Materials (VMC) 10-K risk factor changes: FY2021 vs FY2020
The 2021-12-31 10-K against the 2020-12-31 one, compared heading by heading and sentence by sentence.
Item 1A24 rewritten6 added16 removed106 unchanged
All filing items999 rewritten1,165 added718 removed2,705 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 1,165 added, 718 removed, 999 rewritten and 2,705 unchanged across 20 items that differ.
Sentences by item
21 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2021; struck-through words were in FY2020. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
24 rewritten, 6 added, 16 removed, 106 unchanged
Due to risks and uncertainties, known and unknown, our past financial results may not be a reliable indicator of future [removed: performance] [added: performance,] and historical trends should not be used to anticipate results or trends in future periods.
[removed: Since] [added: Because] our business is dependent on spending in both the public and private sector construction markets, our profits are sensitive to the underlying national, regional, and local economic conditions.
A pandemic, epidemic or other public health emergency, such as the [removed: recent outbreak of the current] [added: ongoing] coronavirus (COVID-19) pandemic, could have a material adverse effect on our business, results of operations, financial condition and cash flows — Our operations expose us to risks associated with pandemics, epidemics or other public health emergencies, such as the COVID-19 pandemic.
[removed: The outbreak] [added: This pandemic] has resulted in governments around the world implementing or reimplementing strict measures to help control the spread of the virus, including quarantines, “shelter in place” and “stay at home” orders, travel restrictions, business curtailments, school closures, and other measures.
In addition, governments and central banks in several parts of the world have enacted fiscal and monetary stimulus measures to counteract the impacts of the COVID-19 [removed: pandemic,] [added: pandemic] and may take further action as circumstances warrant.
Consistent with federal guidelines and with state and local orders to date, we currently continue to operate across our [removed: footprint as an essential business.][added: footprint.]
The extent to which the COVID-19 outbreak impacts our business, results of operations, financial condition or cash flows will depend on future developments, which remain highly uncertain and cannot be predicted, including, but not limited to, the duration and geographic spread of the outbreak, its severity, the actions to contain the virus or treat its impact including the reimplementation of restrictions on economic activity following new outbreaks, the [added: availability, durability and efficacy of vaccines, the] long-term impacts of the virus on transportation revenues, government budgets and other funding priorities and the extent and pace at which normal economic and operating conditions can resume.
| Part I | [removed: 19] [added: 24] |
Changes in legal requirements and governmental policies concerning zoning, land use, environmental and other areas of the law may result in additional liabilities, a reduction in operating hours and additional capital expenditures — Our operations are affected by numerous federal, state and local laws and [removed: regulations] [added: regulations, including those] related to zoning, land use and environmental matters.
Stricter laws and regulations, or more stringent interpretations of existing laws or regulations, may impose new liabilities, taxes or tariffs on [removed: us,] [added: us;] reduce operating [removed: hours,] [added: hours;] require additional investment by us in pollution control [removed: equipment,] [added: equipment;] create restrictions on our [removed: products or] [added: products;] impede our access to reserves or [added: hamper the] opening [added: of] new or [removed: expanding] [added: expansion of] existing plants or facilities.
In [removed: 2020,] [added: 2021,] voters in local jurisdictions in Arizona, [removed: California, Florida,] Georgia, [removed: North Carolina, South Carolina,] Texas and Virginia, among others, approved bond and revenue-raising measures to provide additional resources for transportation projects.
However, given [added: the time to set up new federal programs,] varying state and local budgetary situations and the [removed: associated pressure on infrastructure spending,] [added: stages of projects,] we cannot be entirely assured of the existence, amount and timing of appropriations for future public infrastructure projects.
We face political and other [added: risks, including legal] risks [added: for failure to comply with the FCPA,] associated with our international operations, including our largest [added: aggregates] production facility located in Playa del Carmen, [removed: Mexico.][added: Mexico and our newly acquired aggregates production facility in British Columbia, Canada.]
These risks [added: have included and] may [added: in the future] include changes in international trade policies, such as the United States - Mexico - Canada Agreement (USMCA), imposition of duties, taxes or government royalties, arbitrary changes to permits, zoning classifications or operating agreements, or overt acts by foreign governments, including expropriations and other forms of takings of property.
| Part I | [removed: 20] [added: 25] |
Therefore, our earnings are highly sensitive to changes in product [removed: shipments] [added: shipment volumes] — Due to the high levels of fixed capital required for extracting and producing construction aggregates, our profits are negatively affected by significant decreases in [removed: shipments.][added: shipment volumes.]
While we have not identified any events or changes in circumstances since our annual impairment test on November 1, [removed: 2020] [added: 2021] that indicate the fair value of any of our reporting units is below its carrying value, a significant downturn in the construction industry may have a material effect on the fair value of our reporting units.
A deterioration in our credit ratings and/or the state of the capital markets could negatively impact the cost and/or availability of financing — We currently have [removed: $3.36] [added: $3.95] billion of debt with maturities between [removed: 2021] [added: 2022] and 2048.
[removed: Furthermore, we] [added: We] expect to finance acquisitions with a combination of cash flows from existing operations, additional debt and/or additional equity.
A deterioration in the state of the capital markets, regardless of our credit ratings, could impact our access [removed: to,] [added: to] and cost of, new debt or equity capital.
Disputes with organized labor could disrupt our business operations — Labor unions represent approximately [removed: 11%] [added: 16%] of our workforce.
A significant interruption of our information technology systems [removed: or the loss of confidential or other sensitive data could have a material adverse impact on our operations and financial results — Given our reliance on information technology] (our own and that of our service [removed: providers’] [added: providers] such as Amazon Web [removed: Services), a significant interruption in the availability of information technology] [added: Services)] or the loss of [removed: confidential, personal,] [added: confidential] or [removed: proprietary information] [added: other sensitive data] (whether our own, our employees’, our suppliers’, or our [removed: customers’), regardless of the cause,] [added: customers’)] could [removed: negatively] [added: have a material adverse] impact [added: on] our operations and financial [removed: results.][added: results — We have a dedicated information security team that executes, and updates as warranted based on emerging risk and new risk management technology, our information security program.]
Aggregates resources and reserves calculations are estimates [removed: only,] [added: only] and are subject to uncertainty due to factors including the inherent variability of the deposit and recoverability of saleable material in the mining process — The calculation of mineral resources and reserves are estimates and depend upon geological interpretation and statistical inferences or assumptions drawn from drilling and sampling analysis, which may prove to be unpredictable.
Subsequent developments in legal proceedings may affect our assessment and estimates of a loss [removed: contingency,] [added: contingency] and could result in an adverse effect on our financial position, results of operations or cash flows.
In November 2021, the federal Infrastructure Investment and Jobs Act (IIJA), which included a five year road, bridge and public transportation program reauthorization at record levels, was signed into law.
The highway programs, as well as funding for other aggregates-intensive public infrastructure, will provide assistance to state departments of transportation, federal, state and local agencies, and metro areas for several years to come.
Recently, the Mexican government has taken actions that adversely affect our operations in that country, including delays in issuing a historically routine three-year customs permit for our deep-water port.
Mexico instead issued a short-term customs permit that must be renewed after two months.
While we continue to negotiate with the Mexican authorities to reach an agreeable and mutually beneficial solution, failure by the Mexican government to issue future customs permits or its taking of any other measures that force us to cease our operations in Mexico would have an adverse effect on our ability to supply customers.
An increase in our effective tax rate could negatively affect our earnings and net cash provided by operating activities — Factors that may increase our future effective tax rate include, but are not limited to: governmental authorities increasing statutory income tax rates or eliminating deductions or credits; the mix of jurisdictions in which our earnings are taxed; changes in the valuation of our deferred tax assets and liabilities; the effect our stock price has with regard to excess tax benefits from share-based compensation; adjustments to estimated taxes upon finalization of various income tax returns; the resolution of issues arising from income tax audits with various tax authorities; and the interpretation of income tax laws and/or administrative practices.
In March 2020, the World Health Organization characterized COVID-19 as a pandemic, and the President of the United States declared the COVID-19 outbreak a national emergency.
| | |
| --- | --- |
The federal FAST Act, a five year, fully-funded road, bridge and public transportation authorization law, was extended for a year, and continues to provide assistance to state DOTs and metro areas while Congress contemplates new long-term highway and transit legislation in 2021.
In addition, failure to comply with the FCPA may result in legal claims against us.
Given our current credit metrics and ratings, together with other factors, we expect to refinance our nearer term debt maturities rather than repay them when due.
| Part I | 21 |
The phase-out of LIBOR, or the replacement of LIBOR with a different reference rate or modification of the method used to calculate LIBOR, may adversely affect interest rates — LIBOR is an interest rate benchmark used as a reference rate for a wide range of financial transactions.
In July 2017, the United Kingdom’s Financial Conduct Authority, which regulates LIBOR, announced that it intends to stop compelling banks to submit LIBOR rates after 2021.
It is unclear whether LIBOR will cease to exist at that time (and if so, what reference rate will replace it) or if new methods of calculating LIBOR will be established such that it continues to exist after 2021.
The Alternative Reference Rates Committee (ARRC) has proposed the Secured Overnight Financing Rate (SOFR) as the alternative to U.S. LIBOR.
ARRC has proposed a paced market transition plan to SOFR from LIBOR, and organizations are currently working on industry wide and company specific transition plans.
Uncertainty exists as to the transition process and broad acceptance of SOFR as the primary alternative to LIBOR.
We have two material debt instruments with LIBOR as a reference rate: 1) $500.0 million floating-rate notes due March 2021, and 2) $1,000.0 million line of credit (none outstanding at December 31, 2020) due September 2025.
At this time, we cannot predict the impact of a departure from LIBOR as a reference rate.
We have a dedicated information security team that executes, and updates as warranted based on emerging risk and new risk management technology, our information security program.
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
309 rewritten, 212 added, 137 removed, 664 unchanged
[removed: Management’s] [added: The objective of our management’s] discussion and analysis is [removed: intended] to help investors understand our operations and current business [removed: environment.][added: environment from the perspective of our management.]
The following generally includes a comparison of our results of operations and liquidity and capital resources for [removed: 2020] [added: 2021] and [removed: 2019.][added: 2020.]
For the discussion of changes from [removed: 2018 to] 2019 [added: to 2020] and other financial information related to [removed: 2018,] [added: 2019,] refer to Part II, Item 7.
Management’s Discussion and Analysis of Financial Condition and Results of Operations, of our Form 10-K for the year ended December 31, [removed: 2019] [added: 2020] filed with the Securities and Exchange Commission on February [removed: 26, 2020.][added: 25, 2021.]
FINANCIAL SUMMARY FOR [removed: 2020] [added: 2021] (compared to [removed: 2019)][added: 2020)]
Gross profit increased [removed: $25.6] [added: $91.9] million, or [removed: 2%,] [added: 7%,] to [removed: $1,281.5] [added: $1,373.4] million
Aggregates segment freight-adjusted revenues [removed: decreased $6.5] [added: increased $306.3] million, or [removed: less than 1%,] [added: 10%,] to [removed: $3,007.6] [added: $3,313.9] million
Freight-adjusted sales price increased [removed: 3.2%,] [added: 3.0%,] or [removed: $0.45] [added: $0.43] per ton to [removed: $14.44][added: $14.87]
[removed: Segment] [added: Aggregates segment] gross profit increased [removed: $12.5] [added: $136.5] million, or [removed: 1%,] [added: 12%,] to [removed: $1,159.2] [added: $1,295.7] million
Asphalt, Concrete and Calcium segment gross profit [removed: increased $13.1] [added: decreased $44.6] million, or [removed: 12%,] [added: 36%,] to [removed: $122.3] [added: $77.7] million, collectively
Selling, administrative and general (SAG) expenses [removed: decreased 3%] [added: increased 16%] to [removed: $359.8] [added: $417.6] million and [removed: decreased] [added: increased] 0.1 percentage [removed: points] [added: point] (10 basis points) as a percentage of total revenues
Operating earnings increased [removed: $18.3] [added: $115.1] million, or [removed: 2%,] [added: 13%,] to [removed: $895.7] [added: $1,010.8] million
[removed: Earnings] [added: | Earnings] from continuing operations before income taxes [removed: were $743.8 million compared to $757.7 million][added: | | | $ 873.8 | | | $ 743.8 | | | $ 757.7 | |]
Earnings [added: attributable to Vulcan] from continuing operations were [removed: $588.0 million, or $4.41] [added: $5.05] per diluted share, compared to [removed: $622.5 million, or $4.67 per diluted share][added: $4.41]
Discrete items in [removed: 2019] [added: 2021] include:
pretax charges of [removed: $10.8] [added: $1.5] million for [removed: property donation][added: divested operations]
pretax charges of [removed: $3.0] [added: $1.5] million [removed: for] [added: associated with] divested operations
pretax charges of [removed: $1.7] [added: $39.0] million associated with non-routine business development
pretax charges of [removed: $6.5] [added: $15.0] million for [added: managerial] restructuring
Adjusted (for the discrete pretax items noted above) earnings [added: attributable to Vulcan] from continuing operations were [removed: $4.68] [added: $5.04] per diluted share, compared to [removed: $4.70] [added: $4.68] per diluted share
Adjusted EBITDA was [removed: $1,323.5] [added: $1,451.3] million, an increase of [removed: $53.5] [added: $127.8] million, or [removed: 4%][added: 10%]
Returned capital to shareholders via dividends [removed: ($180.2] [added: of $196.4] million [removed: versus $164.0 million) and] [added: @ $1.48 per] share [removed: repurchases ($26.1 million] versus [removed: $2.6 million)][added: $180.2 million @ $1.36 per share]
| Part II | [removed: 32] [added: 67] |
Our weighted-average debt maturity was [removed: 13] [added: 11.3] years, and the effective weighted-average interest rate was [removed: 4.1%.][added: 3.68%.]
Our capital allocation priorities [removed: are,] [added: are] as follows:
During [removed: 2020,] [added: 2021,] we invested [removed: $239.3] [added: $281.7] million to replace or improve existing property, plant & equipment.
During [removed: 2020,] [added: 2021,] we invested [removed: $122.9] [added: $169.6] million in internal growth projects to secure new aggregates reserves, develop new production and/or distribution sites, enhance our distribution capabilities and support the targeted growth of our asphalt and concrete operations.
We closed two business acquisitions [added: (including U.S. Concrete)] during [removed: 2020] [added: 2021] for total consideration of [removed: $73.4] [added: $1,639.4] million.
During [removed: 2020,] [added: 2021,] we paid a dividend per share of [removed: $1.36] [added: $1.48] and paid total dividends of [removed: $180.2] [added: $196.4] million.
| Part II | [removed: 33] [added: 68] |
Management expectations for [removed: 2021] [added: 2022] include:
Interest expense of approximately [removed: $130] [added: $150] million
Depreciation, depletion, [removed: accretion] [added: accretion,] and amortization expense of approximately [removed: $400] [added: $540] million
An effective tax rate of [removed: approximately] 21% [added: to 22%]
Additionally, we expect to spend [removed: between $450] [added: $600] million [removed: and $475] [added: to $650] million on capital expenditures, including growth [added: and capacity-adding] projects.
| Part II | [removed: 34] [added: 69] |
Over time, we have strategically and systematically built one of the most valuable aggregates franchises in the [removed: U.S.,] [added: U.S.] with a footprint that is impossible to replicate.
We have a coast-to-coast footprint that serves [removed: 19] [added: 20] of the top 25 highest-growth metropolitan statistical areas (MSAs) and states where [removed: 73%] [added: 75%] of U.S. population growth from 2020 to 2030 is projected to occur.
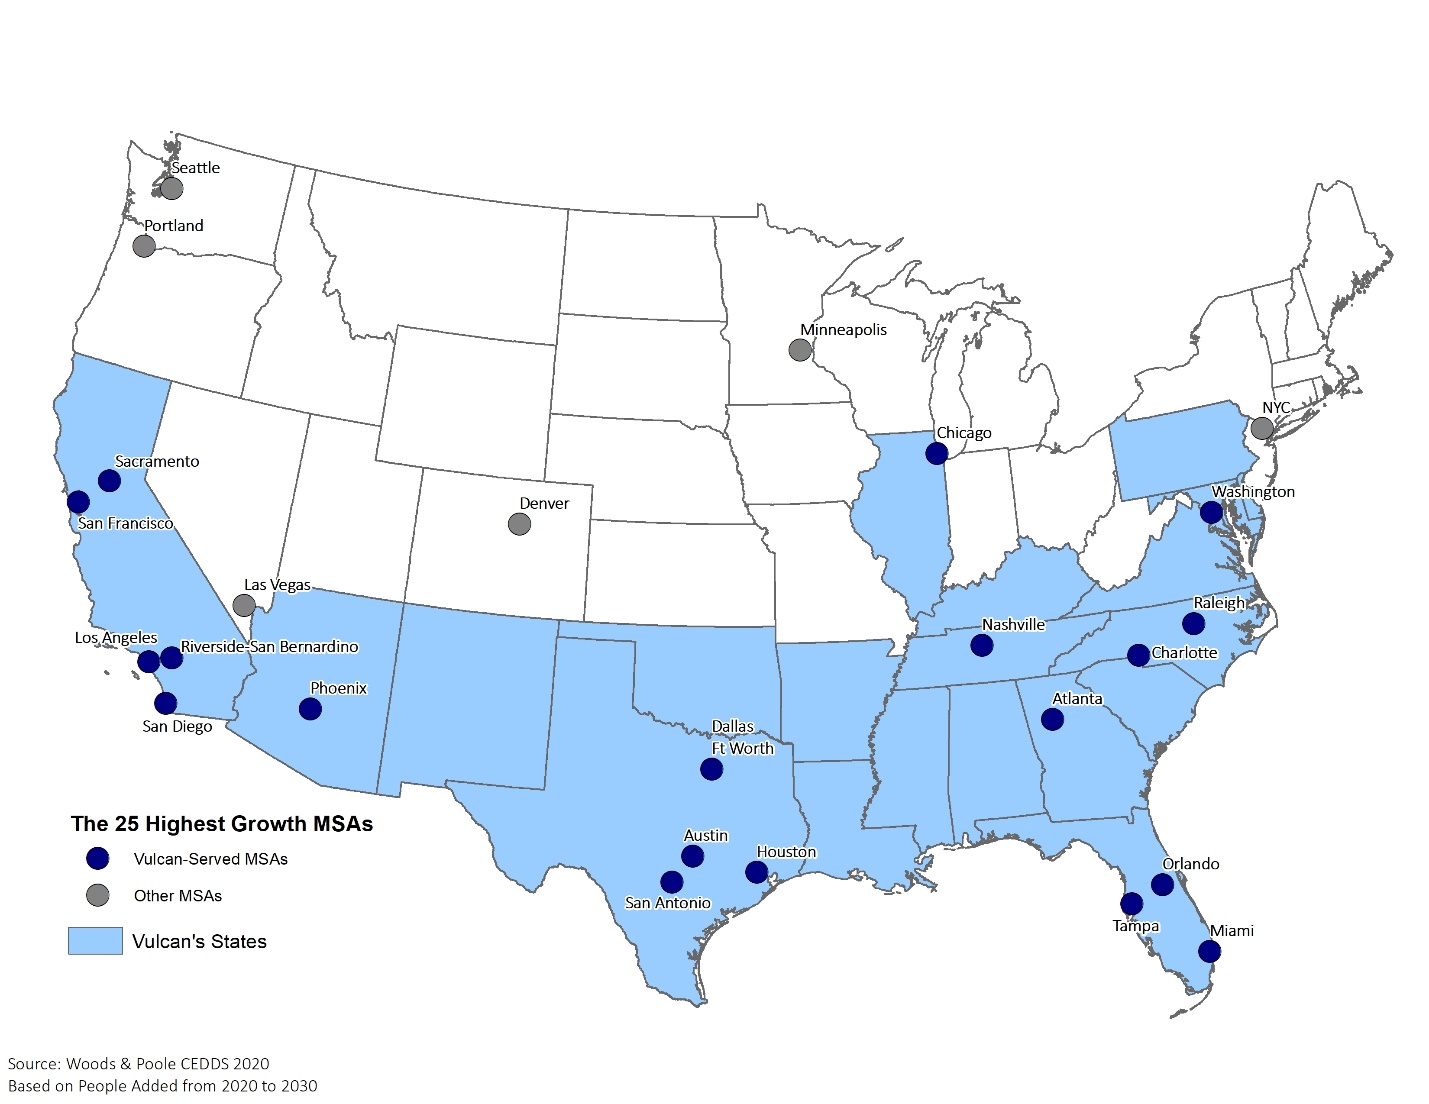][added: 7](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg016.jpg)]
*Source: Woods & Poole CEDDS [removed: 2020*][added: 2021*]
Total revenues increased $695.4 million, or 14%, to $5,552.2 million
Aggregates segment sales increased $400.7 million, or 10%, to $4,345.0 million
Shipments increased 7%, or 14.6 million tons, to 222.9 million tons
Same-store shipments increased 5%, or 10.2 million tons, to 218.5 million tons
Same-store freight-adjusted sales price also increased 3.0% to $14.87 per ton
Same-store unit profitability (as measured by gross profit per ton) increased 7% to $5.95 per ton
$13.7 million of tax charges related to an increase in the Alabama NOL carryforward valuation allowance
pretax net gain of $114.7 million related to the sale of a reclaimed quarry in Southern California
pretax charges of $13.4 million for COVID-19 pandemic direct incremental costs
pretax charge of $12.1 million for pension settlement
pretax interest charges of $9.4 million related to financing the acquisition of U.S. Concrete
Net earnings attributable to Vulcan were $670.8 million, an increase of $86.3 million, or 15%
Our teams finished the year strong, despite ongoing challenges from inflationary pressures and labor constraints.
We expanded our industry-leading unit profitability by continuing to focus on our operating disciplines and taking pricing actions where necessary to mitigate these headwinds.
We continue to make excellent progress integrating the U.S. Concrete operations into our business.
This acquisition extends our growth platform in certain existing markets as well as new geographies.
These results demonstrate our ability to execute on Vulcan’s four strategic disciplines — Operational Excellence, Strategic Sourcing, Commercial Excellence and Logistics Innovation (as outlined in Item 1 “Business” under the “Business Strategy” heading) — and enhance our operating leverage moving forward.
We are well positioned to capitalize on the positive demand trends we see developing in 2022 and beyond.
As demand and the pricing environment continue to strengthen, we expect healthy growth in unit profitability again in 2022.
Robust growth in aggregates pricing and continued focus on operational excellence will more than offset anticipated inflationary pressures.
In our asphalt business, we expect recent pricing efforts to begin to mitigate higher liquid asphalt costs and lead to gross profit margin improvement beginning in the second half of 2022.
In our concrete business, improvement in private nonresidential construction activity will help drive earnings growth in 2022.
At year end 2021, total debt to Adjusted EBITDA was 2.7x (2.5x on a net debt basis).
We remain committed to our stated long-term target leverage range of 2.0x to 2.5x total debt to Adjusted EBITDA.
Return on invested capital was 14.2% and we remain committed to driving further improvement through solid operating earnings growth coupled with disciplined capital management.
During August 2021, we closed on one such large business combination (U.S. Concrete) for $1,634.5 million.
During 2021, we made no share repurchases.
We carry considerable momentum into the new year.
Our markets are poised to outperform other parts of the country as demand continues to improve and our industry-leading unit profitability increases with each passing quarter.
We will continue to drive substantial value through the combination of our legacy business and the acquisition of U.S. Concrete.
Residential construction remains strong, and contract awards for private nonresidential buildings are growing again.
On the public side, infrastructure investment is moving forward, and we are well positioned in attractive growth markets where the need is greatest.
The recently enacted Infrastructure Investment and Jobs Act is certainly a positive for our industry; it will add to existing demand as well as elongate the cycle.
However, we do not expect it to have a significant impact in 2022.
That said, labor shortages and supply chain disruptions are expected to continue to limit shipment growth in 2022.
We expect the favorable pricing dynamics that improved throughout 2021 to be even better in 2022 and lead to attractive growth in aggregates unit profitability.
Growing our aggregates unit profitability consistently during the last two years of pandemic-related disruptions demonstrates the resiliency of our business and our ability to capitalize on any changes in the macro environment.
Net earnings attributable to Vulcan of between $800 to $890 million
Adjusted EBITDA of between $1,720 to $1,820 million
High single-digit growth in Aggregates cash gross profit per ton ($7.43 in 2021)
Total revenues decreased $72.3 million, or 1.5%, to $4,856.8 million
Aggregates segment sales decreased $46.0 million, or 1%, to $3,944.3 million
Shipments decreased 3%, or 7.2 million tons, to 208.3 million tons
pretax gains of $13.4 million for the sale of businesses and property donation
Net earnings were $584.5 million, a decrease of $33.2 million, or 5%
| | |
| --- | --- |
Our best-in-class aggregates business, along with the efforts and dedication of our employees, allowed us to overcome COVID-19 related disruptions in 2020.
As we saw in 2020, demand for our products can be subject to market fluctuations outside of our control.
We remain focused on the factors within our control, including our pricing and cost actions, both of which contributed to further improvement in our industry-leading unit margins in 2020.
Most impressive, we delivered year-over-year gains in aggregates unit profitability throughout each quarter in 2020.
Our ability to leverage our four strategic disciplines — Commercial and Operational Excellence, Logistics Innovation and Strategic Sourcing — enabled us to expand unit margins, deliver improved cash flows, and increase returns on invested capital.
Our team’s hard work along with our leading market positions and strong financial foundation will enable us to capitalize on an improving demand outlook in 2021.
Our operating plans are underpinned by our aforementioned four strategic disciplines, a healthy balance sheet, strong liquidity, and the engagement of our people.
2020 revenues were $4,856.8 million, 1% lower than the prior year, while gross profit margins expanded across each segment.
Effective cost management throughout the organization and aggregates price growth helped drive margin expansion.
Net earnings were $584.5 million and Adjusted EBITDA was a record $1,323.5 million.
At year end, total debt to 2020 Adjusted EBITDA was 2.5 times or 1.6 times on a net debt basis reflecting $1,198.0 million of cash on hand — approximately $500.0 million will be used to pay off certain debt maturities due in March 2021.
Return on invested capital increased 0.4 percentage points (40 basis points) from the prior year to 14.3%.
Operating cash flows were $1,070.4 million, up 9% versus the previous year.
Solid operating earnings growth coupled with disciplined capital management led to these results.
During the fourth quarter of 2020, we restarted planned growth projects that were put on hold in March 2020 as a result of the pandemic.
During 2020, we returned $26.1 million to our shareholders through share repurchases.
Construction employment gains in key markets are a positive signal that activity levels are recovering across our footprint, as compelling fundamentals in residential construction support growing demand in 2021.
Shipments into private nonresidential continue to benefit from growth in heavy industrial projects such as data centers and warehouses, while construction starts in other categories remain below the prior year.
Recent improvements in highway lettings and contract awards indicate growing confidence and visibility fueling advancement of planned projects, particularly in the second half of 2021.
The pricing environment remains positive and we continue to execute at a high level — positioning us well for 2021.
We are encouraged by the continued strength in residential construction activity, particularly single-family housing.
Our expectation is also supported by the recent improvement in highway awards and construction employment trends in key markets.
Data centers, distribution centers, and warehouses, which now comprise the largest share of new private nonresidential project awards, will continue to underpin demand in this end market.
We believe these leading indicators, along with sustaining a positive pricing environment, can be a catalyst for further recovery in construction activity during 2021.
Aggregates shipments down 2% to up 2% versus 2020
Aggregates freight-adjusted price increase of 2% to 4% from 2020
Collective Asphalt, Concrete and Calcium segment gross profit up mid-to high single digits
SAG expenses of $365 million to $375 million
Earnings from continuing operations of $4.80 to $5.40 per diluted share
Net earnings of $640 million to $720 million
Adjusted EBITDA of $1.340 billion to $1.440 billion
No major changes in COVID shelter-in-place restrictions
For support functions, we previously implemented remote work arrangements and restricted business travel effective mid-March 2020.
An excerpt. Shown here: 40 of 309 rewritten, 40 of 212 added and 40 of 137 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2021 filing and the FY2020 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
3 rewritten, 0 added, 0 removed, 17 unchanged
At December 31, [removed: 2020,] [added: 2021,] the estimated fair value of our long-term debt including current maturities was [removed: $3,959.0] [added: $4,423.7] million compared to a face value of [removed: $3,357.9] [added: $3,949.6] million.
The effect of a decline in interest rates of one percentage point would increase the fair value of our debt by approximately [removed: $414.9] [added: $380.9] million.
| Part II | [removed: 67] [added: 72] |
Item 1. BUSINESS
74 rewritten, 121 added, 36 removed, 307 unchanged
As of December 31, [removed: 2020,] [added: 2021,] we had [removed: 380] [added: 404] active aggregates facilities, [removed: 70] [added: 69] asphalt [added: facilities, 173 concrete] facilities and [removed: 46 concrete facilities.][added: 1 calcium facility.]
Our strategy and competitive advantage are based on our strength in [removed: aggregates] [added: aggregates,] which are used in most types of construction and in the production of asphalt mix and ready-mixed concrete.
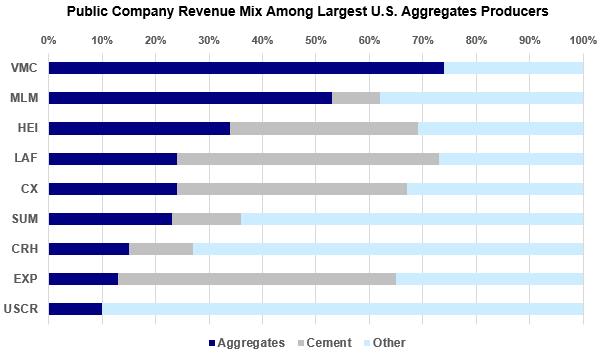][added: 5](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg001.jpg)]
*Source: [removed: 2019] [added: 2020] reported financial information and Company [removed: estimates*][added: estimates.]
Our [removed: 380] [added: 404] active aggregates facilities as of December 31, [removed: 2020] [added: 2021] provide opportunities to share and scale best practices across our operations and to procure equipment (fixed and mobile), parts, supplies and services in an efficient and cost-effective manner, both regionally and nationally.
We currently have [removed: 15.9] [added: 15.6] billion tons of [removed: permitted and] proven [removed: or] [added: and] probable aggregates reserves.
During the period 2020 - 2030, Moody's Analytics projects that [removed: 73%] [added: 75%] of the U.S. population growth, [removed: 70%] [added: 72%] of household formation and [removed: 61%] [added: 70%] of new jobs will occur in Vulcan-served states.
[added: Our coast-to-coast footprint serves 20 of the top 25 highest-growth metropolitan statistical areas in 22 states plus the U.S. Virgin Islands and Washington D.C.] The close proximity of our aggregates reserves and our production facilities to this projected population growth creates many opportunities to invest capital in high-return projects.
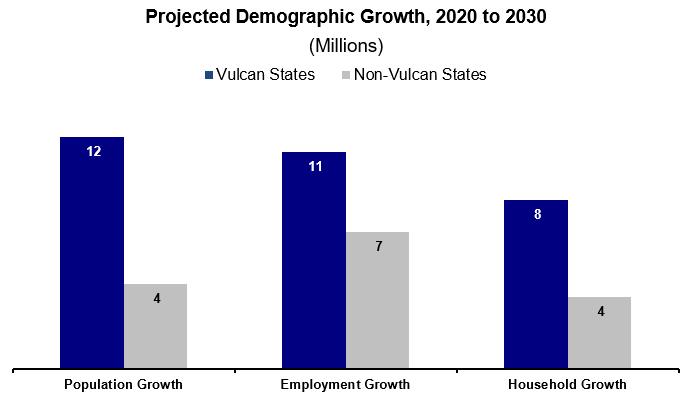][added: 8](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg002.jpg)]
*Source: Moody’s Analytics as of December 10, [removed: 2020*][added: 2021*]
Our top ten revenue producing states accounted for 88% of our [removed: 2020] [added: 2021] revenues while our top five accounted for 61%.
| | VULCAN’S TOP TEN REVENUE PRODUCING STATES IN [removed: 2020] [added: 2021] | | | | | | | | | | | |
| | 4. | [removed: Georgia] [added: Tennessee] | | | | 9. | | North Carolina | | | | |
[removed: For example, in 1999] [added: In 1999,] we acquired CalMat Co., thereby expanding our aggregates operations into California and Arizona and making us one of the nation’s leading producers of asphalt mix.
Additionally, throughout our [removed: history] [added: history,] we have completed many bolt-on aggregates [added: and downstream] acquisitions that have contributed significantly to our growth.
From [removed: 2018] [added: 2019] to [removed: 2020,] [added: 2021,] we invested over [removed: $300] [added: $1,758.1] million in acquisitions as outlined in Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.”
During [removed: 2020,] [added: 2021,] we reinvested [removed: $360.8] [added: $451.3] million into core operating & maintenance capital and internal growth capital, in addition to [removed: $384.1] [added: $362.2] million and [removed: $469.1] [added: $384.1] million reinvested in [removed: 2019] [added: 2020] and [removed: 2018,] [added: 2019,] respectively.
As illustrated below, our annual Return on Invested Capital (ROIC) [removed: increased 0.4] [added: decreased 0.1] percentage points [removed: (40] [added: (10] basis points) in [removed: 2020 as a 4% increase in Adjusted EBITDA (net earnings decreased 5% in 2020) was leveraged with disciplined capital management (average invested capital only increased 1%).][added: 2021.]
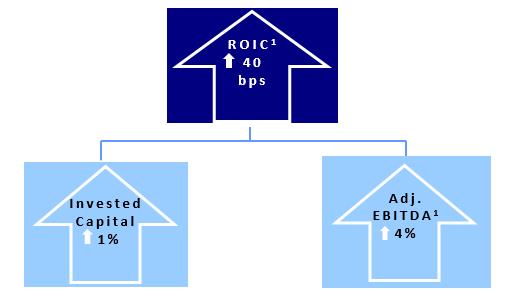][added: 12](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg003.jpg)]
Commercial Excellence — Clearly defined roles and responsibilities together with access to real time, forward-looking metrics [removed: leads] [added: lead] to our sales teams spending less time on non-selling activities and more time responding to our customers’ needs.
Logistics Innovation [removed: –] [added: —] Partnering with our customers (truck drivers and contractors) to provide a bundled logistics solution with digital shipping records and on-site, mobile visibility leads to streamlined scheduling, speed and accuracy of delivery, and efficient back-office processes.
With [removed: approximately] [added: more than] 240,000 acres in our land portfolio, a long-term holistic approach to preserving land and water is integral to sustaining our success.
[removed: And, our] [added: Our] community relations programs serve our neighbors while ensuring that we grow and thrive in the communities where we operate.
Our [removed: 2020] [added: 2021] total revenues and gross profit by segment are illustrated as follows (Calcium revenues and gross profit were less than one percent):
[removed: |] 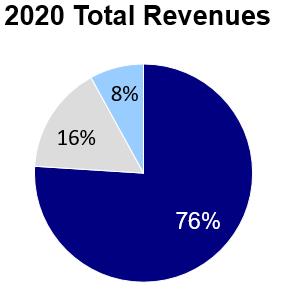 | 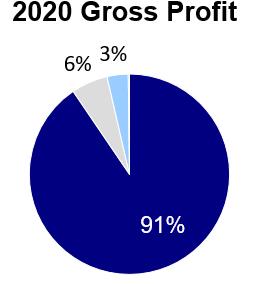 |][added: 17](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg004.jpg)]
| 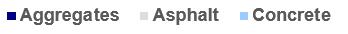] [added: 3](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg007.jpg)] | |
as a raw material used in combination with other resources to construct many of the items we rely on to sustain our quality of [removed: life] [added: life,] including:
Approximately [removed: 80%] [added: 82%] of our total aggregates shipments are delivered exclusively from the producing location to the customer by truck.
The remaining [removed: 3%] [added: 1%] of aggregates shipments are delivered directly to the customer by rail or water.
Highly fragmented industry: The U.S. aggregates industry is composed of over [removed: 5,000] [added: 5,500] companies that manage close to 11,000 operations.
The drivers underpinning long-term demand and sustained pricing growth remain firmly in [removed: place,] [added: place] in both the public and private sectors of the economy.
They include: population growth; gains in total employment (short-term disruption due to COVID-19 pandemic) and in household income and wages; a continuing increase in household formations; the growing need for additional housing stock and housing demand; a multi-year federal transportation law in place and continuing increases in transportation funding at state and local levels; stable state tax receipts; public investment in infrastructure that is still well below the long-term trend-line; and [removed: increasing] [added: a multi-year federal infrastructure investment law and continued] political awareness and [removed: acceptance of] [added: focus on] the need to invest in infrastructure.
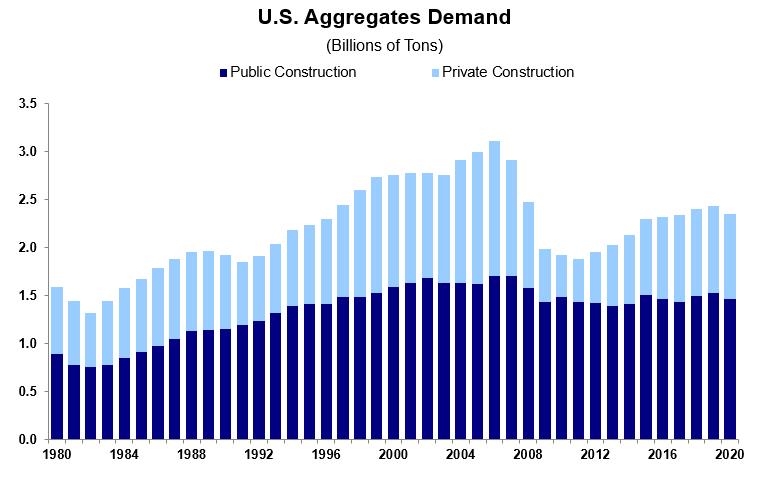][added: 13](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg008.jpg)]
Public sector construction includes spending by federal, [removed: state,] [added: state] and local governments for highways, bridges, buildings, airports, schools, prisons, sewer and waste disposal systems, water supply systems, dams, reservoirs and other public construction projects.
In [removed: 2020,] [added: 2021,] publicly-funded construction accounted for approximately [removed: 43%] [added: 42%] of our total aggregates shipments, and approximately [removed: 23%] [added: 22%] of our aggregates sales by volume were used in highway construction projects.
Since 2012, eleven Vulcan-served states representing [removed: over 87%] [added: 88%] of our [removed: 2020] [added: 2021] total revenues have averaged a 69% increase in their states’ revenues for highways.
Major transportation funding measures in Vulcan-served areas approved in [removed: 2020] [added: 2021] are estimated to result in [removed: $2.575] [added: $3.3] billion in revenues and bond proceeds primarily dedicated to roads, streets and bridges.
Across the [removed: United States,] [added: U.S.,] voters in [removed: 18] [added: 17] states approved [removed: 94%] [added: 87%] of [removed: 322] [added: 323] measures in [removed: 2020,] [added: 2021,] which will generate [removed: $14.1] [added: $7.6] billion in new and recurring transportation investment.
This [removed: represents a record high approval rate and] continues a trend in which voters have approved [removed: 83%] [added: 84%] of [removed: nearly 2,300] [added: 2,608] transportation investment ballot measures since 2010.
The long-term nature of the [removed: FAST Act] [added: highway program reauthorization in the IIJA] is important.
As of December 31, 2021, we had 404 active aggregates facilities as shown below.
While aggregates is our focus and primary business, as of December 31, 2021, we further served our customers through our 69 asphalt facilities and 173 concrete facilities located in Alabama, Arizona, California, Maryland, New Jersey, New Mexico, New York, Oklahoma, Pennsylvania, Tennessee, Texas, Virginia, the U.S. Virgin Islands, Washington D.C. and the Bahamas.
VMC excludes U.S. Concrete, which was acquired in August 2021.*
| | 2. | California | | | | 7. | | Alabama | | | | |
| | 3. | Georgia | | | | 8. | | Arizona | | | | |
In 2021, we acquired U.S. Concrete, enhancing and expanding our aggregates-led business in attractive growing metropolitan areas.
Through our 2021 acquisition of U.S. Concrete, we entered the Oklahoma, New Jersey, New York, Pennsylvania and U.S. Virgin Islands concrete markets and expanded our California, Texas and Washington D.C. concrete markets.
While Adjusted EBITDA increased 10% in 2021 (net earnings attributable to Vulcan increased 15% in 2021), invested capital also increased by 10%, primarily as a result of the U.S. Concrete acquisition.
We remain committed to driving improvement in our ROIC through solid operating earnings growth coupled with disciplined capital management.
As a result, aggregates gross profit per ton has improved from $5.32 in 2019 to $5.81 in 2021.
In 2021, we sold previously mined land in Southern California that we had reclaimed for commercial and retail development for net proceeds of $182.3 million resulting in a pretax net gain of $114.7 million.
Our leadership recognized decades ago the significance and importance of leadership in the Safety, Health and Environmental areas.
The Safety, Health and Environmental Affairs Committee of our Board of Directors, along with the full Board, has oversight responsibility for our environmental, safety and health programs and results.
Our Safety, Health & Environmental Management Committee, made up of the senior leadership team along with other key senior personnel from cross-functional operations and staff disciplines, has the ongoing management responsibility for all of our safety, health and environmental initiatives.
In 2021, we achieved an overall Mine Safety and Health Administration (MSHA) safety performance of 0.98 injuries per 200,000 employee hours worked, which is both industry-leading and considered world-class.
We leveraged our charitable foundation and company funds to support food banks, healthcare services, childhood education remote learning programs and other initiatives designed to lessen the difficulties experienced in many of our communities.
Our charitable foundation alone has provided more than $60 million in support over the past 20 years to essential charitable, civic and educational organizations that strengthen and enrich our communities.
Our environmental stewardship commitment is designed to protect plant and animal species and habitats, as well as the air we breathe, the water we use and the planet we all share.
In all parts of our company, from local operations to our corporate and regional offices to our international business and ocean-going shipping, we are focused on ensuring that our operations are efficient in ways that are economically and environmentally sustainable.
We are proud to maintain the third largest number of Certified Wildlife Habitat sites of any industrial company in the U.S. for 2021, in partnership with the international Wildlife Habitat Council.
For a discussion of our energy management and greenhouse gas emissions initiatives, see the Climate Change section later within this Item 1 under Other Business-Related Items.
Additionally, as a result of our 2021 acquisition of U.S. Concrete, we serve markets in California and Hawaii from our quarry in British Columbia, Canada by means of a long-term marine shipping agreement with CSL Americas.
We have over 20,000 customers in 22 states, the U.S. Virgin Islands, Washington D.C., the Bahamas, British Columbia (Canada), and Quintana Roo (Mexico).
Direct production costs of aggregates primarily include: a) wages and fringe benefits; b) depreciation, depletion, accretion and amortization of capital (or long-term) assets; c) operating parts and supplies; d) repair and maintenance; e) outside services and f) energy (primarily electricity and diesel).
Several states also index their gas taxes to a measure of inflation, including Alabama, California, Florida, Georgia, Illinois, Maryland and North Carolina.
federal highway funding: In November 2021, President Biden signed a historic, bi-partisan infrastructure bill, the Infrastructure Investment and Jobs Act (IIJA), into law.
The IIJA provides the largest increase in federal highway, road and bridge funding in more than six decades with a five-year reauthorization of Federal-Aid Highway Program funding.
The total Federal-Aid Highway Program obligation limitation under IIJA starts at $66.9 billion in FFY 2022 and increases to $72.1 billion in FFY 2026, for a total of nearly $350 billion.
These numbers include one-time additional funding for large road and bridge projects, such as $40 billion for bridge repair, replacement and rehabilitation.
Of the bridge money, approximately $16.5 billion is earmarked for projects in Vulcan-served states.
Importantly, building on improvements in the two prior reauthorization laws — The Fixing America’s Surface Transportation Act (FAST Act) and Moving Ahead for Progress in the 21st Century Act (MAP-21) — the IIJA further streamlines project delivery and environmental approval advancements.
Project financing remains an important additional component of overall surface transportation spending.
The IIJA expands access to private activity bonds for highway and intermodal projects, and sets the Transportation Infrastructure Finance & Innovation Act (TIFIA) program authorized at $250 million per year.
ADDITIONAL FEDERAL INFRASTUCTURE INVESTMENTS UNDER THE IIJA: The IIJA allocates a total of approximately $1.2 trillion in federal funds for infrastructure investment, including almost $550 billion in new spending.
A little more than half of the new money is dedicated to transportation sector projects.
Beyond highway infrastructure, Vulcan could benefit from IIJA-funded, aggregates-intensive infrastructure projects, such as railroads, airports, seaports, and drinking and wastewater systems.
We also provide construction paving services (included in our Asphalt segment) in Alabama, Tennessee and Texas.
We produce and sell ready-mixed concrete in California, Maryland, New Jersey, New York, Oklahoma, Pennsylvania, Texas, Virginia, the U.S. Virgin Islands, and Washington D.C. In August 2021, through our acquisition of U.S. Concrete, we entered the New Jersey, New York, Oklahoma, Pennsylvania and U.S. Virgin Islands concrete markets and expanded our service of the California, Texas and Washington D.C. concrete markets.
Ready-mixed concrete consists of cement and other cement-related materials (such as fly ash and slag), aggregates (crushed stone and sand), chemical admixtures and water and is measured in cubic yards.
Cement is the binding agent used to bind water, crushed stone and sand in the production of ready-mixed concrete.
Our coast-to-coast footprint serves 19 of the top 25 highest-growth metropolitan statistical areas in 20 states plus the District of Columbia.
| | 2. | California | | | | 7. | | Arizona | | | | |
| | 3. | Tennessee | | | | 8. | | Alabama | | | | |
For example, during 2019 we acquired aggregates operations that strengthened our position in Tennessee.
Additionally, throughout our history we have completed many bolt-on downstream acquisitions that have contributed significantly to our growth.
For example, during 2020 we acquired asphalt operations in Texas expanding our already strong presence in that market.
Our strategic priorities have given us the ability to leverage decisions we have made over the past few years.
We have over 23,000 customers in 20 states, the District of Columbia and Mexico.
federal highway funding: In December 2015, President Obama signed a new, long-term federal highway and transit authorization bill, Fixing America’s Surface Transportation Infrastructure Act (FAST Act), into law after the final legislation received strong, bipartisan support in both the House and the Senate.
The FAST Act provides multi-year funding to state and local governments in support of road, bridge, intermodal and public transportation projects.
President Trump signed a one-year extension of the FAST Act into law in 2020.
The FAST Act increases Federal-Aid Highway Program funding from $41 billion in the federal fiscal year (FFY) 2015 to $47 billion in FFY 2021.
The Bipartisan Budget Act of 2018 added approximately $2 billion per year to base highway programs in 2018 and 2019.
In addition, for FFY 2021, state departments of transportation were allocated $10 billion in emergency aid from the $900 billion Coronavirus Response and Relief Supplemental Appropriations Act, a COVID-19 relief measure passed by Congress in December 2020 as part of a final year-end legislative package.
The FAST Act also contains important policy changes.
To further accelerate the project delivery process, it augments the environmental review and permitting process reforms contained in the prior law, Moving Ahead for Progress in the 21st Century Act (MAP-21).
The FAST Act also provides assistance for states making investments in major capital projects — particularly freight projects.
Project financing remains an important additional component of overall surface transportation spending, with the Transportation Infrastructure Finance & Innovation Act (TIFIA) program authorized at $275 million (in line with the previous program outlays) and growing to $300 million by 2020.
The FAST Act also created a new National Surface Transportation and Innovative Finance Bureau to provide technical assistance to states seeking to pursue public-private partnerships and other financing arrangements for transportation projects.
The FAST Act extension expires on September 30, 2021.
Congress is in the process of developing policy and funding legislative proposals for FAST Act reauthorization.
It would not be atypical for additional extensions of current law to be required to provide Congress with adequate time to complete the reauthorization process.
Historically, there is minimal disruption to the flow of federal funding to state and local projects due to extensions.
In June 2018, we acquired additional asphalt mix operations and a construction paving business in Texas.
In March 2018, we entered the Alabama asphalt market through the acquisition of an aggregates, asphalt mix and construction paving business.
In March 2018, we exited the Georgia ready-mixed concrete market (we retained all real property which is leased to the buyer and obtained a long-term aggregates supply agreement).
LafargeHolcim
MDU Resources Group, Inc.
We estimate that capital expenditures for environmental control facilities in 2021 and 2022 will be $11.3 million and $7.5 million, respectively.
We do not anticipate any significant issues with any unions in 2021.
Today, approximately 38% of our workforce is diverse, and we have a number of initiatives to continue building a diverse and inclusive workforce.
We have more than doubled the number of diverse Division and Corporate officers since 2013.
The Wilshire 5000 M&S is a market capitalization weighted sector containing public equities of firms in the Materials and Services sector, which includes our company and approximately 1,300 other companies.
| Vulcan Materials Company | | | | | | $ 100.00 | | | $ 132.69 | | | $ 137.21 | | | $ 106.66 | | | $ 156.86 | | | $ 163.33 | |
| S&P 500 | | | | | | $ 100.00 | | | $ 111.96 | | | $ 136.40 | | | $ 130.43 | | | $ 171.48 | | | $ 203.03 | |
| Wilshire 5000 M&S | | | | | | $ 100.00 | | | $ 111.39 | | | $ 142.11 | | | $ 131.47 | | | $ 175.29 | | | $ 229.20 | |
An excerpt. Shown here: 40 of 74 rewritten, 40 of 121 added and all 36 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2021 filing and the FY2020 filing.
Item 3. LEGAL PROCEEDINGS
1 rewritten, 0 added, 0 removed, 6 unchanged
We were not subject to any penalties in [removed: 2020] [added: 2021] for failure to disclose transactions identified by the Internal Revenue Service as abusive under Internal Revenue Code Section 6707A.
Cover and table of contents
26 rewritten, 27 added, 2 removed, 74 unchanged
| þ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 For the Fiscal Year Ended December 31, [removed: 2020] [added: 2021] OR | | | | |
| Aggregate market value of voting and non-voting common stock held by non-affiliates as of June 30, [removed: 2020:] [added: 2021:] | [removed: $15,315,526,050] [added: $23,045,807,043] |
| Number of shares of common stock, $1.00 par value, outstanding as of February [removed: 12, 2021:] [added: 15, 2022:] | [removed: 132,547,092] [added: 132,792,275] |
| Portions of the registrant’s annual proxy statement for the annual meeting of its shareholders to be held on May [removed: 14, 2021,] [added: 13, 2022,] are incorporated by reference into Part III of this Annual Report on Form 10-K. | |
| VULCAN MATERIALS COMPANY ANNUAL REPORT ON FORM 10-k fISCAL YEAR ENDED DECEMBER 31, [removed: 2020] [added: 2021] CONTENTs | | | |
| | 1A | [Risk Factors](#PartI_Item1A) | [removed: 19] [added: 22] |
| | 1B | [Unresolved Staff Comments](#PartI_Item1B) | [removed: 24] [added: 26] |
| | 2 | [Properties](#PartI_Item2) | [removed: 25] [added: 27] |
| | 3 | [Legal Proceedings](#PartI_Item3) | [removed: 28] [added: 34] |
| | 4 | [Mine Safety Disclosures](#PartI_Item4) | [removed: 28] [added: 34] |
| | — | [Information about our Executive Officers](#Executive_Officers) | [removed: 29] [added: 35] |
| II | 5 | [Market for the Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities](#PartII_Item5) | [removed: 31] [added: 37] |
| | 7 | [Management’s Discussion and Analysis of Financial Condition and Results of Operations](#PartII_Item7) | [removed: 32] [added: 38] |
| | 7A | [Quantitative and Qualitative Disclosures about Market Risk](#PartII_Item7A) | [removed: 67] [added: 72] |
| | 8 | [Financial Statements and Supplementary Data](#PartII_Item8) | [removed: 68] [added: 73] |
| | 9 | [Changes in and Disagreements with Accountants on Accounting and Financial Disclosure](#PartII_Item9) | [removed: 123] [added: 129] |
| | 9A | [Controls and Procedures](#PartII_Item9A) | [removed: 123] [added: 129] |
| | 9B | [Other Information](#PartII_Item9B) | [removed: 125] [added: 131] |
| III | 10 | [Directors, Executive Officers and Corporate Governance](#PartIII_Item10) | [removed: 126] [added: 132] |
| | 11 | [Executive Compensation](#PartIII_Item11) | [removed: 126] [added: 132] |
| | 12 | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters](#PartIII_Item12) | [removed: 126] [added: 132] |
| | 13 | [Certain Relationships and Related Transactions, and Director Independence](#PartIII_Item13) | [removed: 126] [added: 132] |
| | 14 | [Principal Accounting Fees and Services](#PartIII_Item14) | [removed: 126] [added: 132] |
| IV | 15 | [Exhibits and Financial Statement Schedules](#PartIV_Item15) | [removed: 127] [added: 133] |
| | 16 | [Form 10-K Summary](#PartIV_Item16) | [removed: 132] [added: 138] |
a pandemic, epidemic or other public health emergency, such as the [removed: recent outbreak of] COVID-19 [added: outbreak]
st
| | 9C | [Disclosure Regarding Foreign Jurisdictions that Prevent Inspections](#PartII_Item9C) | 131 |
| | — | [Signatures](#Signatures) | 139 |
international business operations and relationships, including recent actions taken by the Mexican government with respect to our operations in that country
availability and cost of trucks, railcars, barges and ships, as well as their licensed operators, for transport of our materials
labor shortages and constraints
our mission
We are the company we are today thanks to the positive actions of our nearly 12,000 employees.
We believe that doing the right thing is good for our business, our environment and our society.
That’s our commitment.
*Our Mission*
*Provide quality products and services that consistently*
*exceed our customers’ expectations.
Be responsible stewards*
*with respect to safety and the environmental impact of our operations*
*and products.
Drive value and superior returns for our customers,*
*employees, communities and shareholders.*
We maintain the highest degree of respect for people — for their dignity, talents and interests.
We believe that empowering, mentoring, training and rewarding our people helps create a highly engaged workforce, happy people and sustainable, long-term value.
We act fairly and honorably to earn the respect and trust of all parties with whom we interact.
We hold ourselves to high ethical standards, including abiding by both the letter and spirit of the laws and regulations related to our business.
We are committed to excellence in all of our activities.
We value innovation.
We strive to maintain a position of leadership in all of our businesses.
DOING THE RIGHT THING, THE RIGHT WAY, AT THE RIGHT TIME.
IT’S THE VULCAN WAY.
| | — | [Signatures](#Signatures) | 133 |
the impact of a discontinuation of the London Interbank Offered Rate (LIBOR)
Item 1B. UNRESOLVED STAFF COMMENTS
1 rewritten, 0 added, 0 removed, 4 unchanged
| Part I | [removed: 24] [added: 26] |
Item 2. PROPERTIES
38 rewritten, 166 added, 31 removed, 33 unchanged
[removed: As the largest U.S. supplier of construction aggregates, we] [added: We principally] serve markets in [removed: twenty] [added: twenty-two] states, [added: the U.S. Virgin Islands,] Washington [removed: D.C.] [added: D.C.,] and the local [removed: market] [added: markets] surrounding our [removed: operation] [added: operations] in [added: British Columbia, Canada and Quintana Roo,] Mexico.
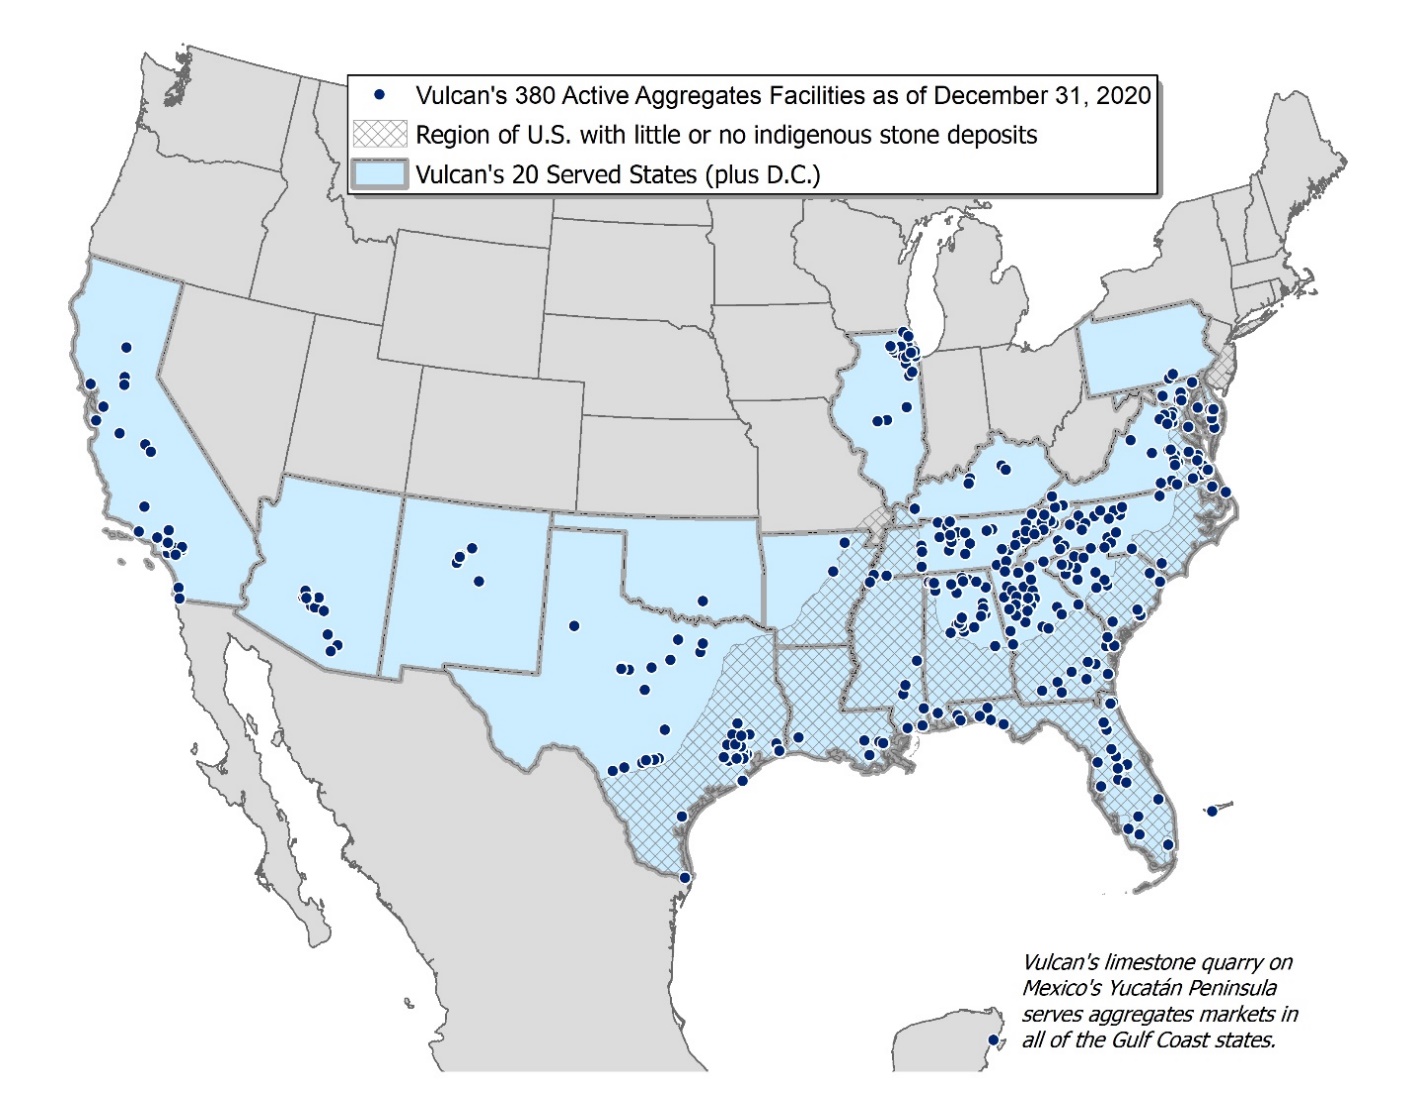][added: 31](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg015.jpg)]
Our current estimate of [removed: 15.9] [added: 15.6] billion tons of proven and probable aggregates reserves reflects a decrease of 0.3 billion tons from the prior year’s estimate.
Estimates of reserves are of recoverable stone, sand and gravel of suitable quality for economic extraction, based on drilling and studies by our geologists and engineers, recognizing reasonable economic and operating constraints as to maximum depth of overburden and stone excavation, and subject to permit or other [removed: restrictions,.][added: restrictions.]
[removed: Proven, or measured, reserves are] [added: Proven —] those reserves for which the quantity is computed from dimensions revealed by drill data, together with other direct and measurable observations, such as outcrops, trenches and quarry faces.
The grade and quality of those reserves are computed from the results of detailed sampling, and the sampling and measurement data are spaced so closely and the geologic character is so well defined that size, shape, depth and mineral content of reserves are well [removed: established.][added: established]
[removed: Probable, or indicated, reserves are] [added: Probable —] those reserves for which quantity, grade and quality are computed partly from specific measurements and partly from projections based on reasonable, though not drilled, geologic evidence.
The degree of assurance, although lower than that for proven reserves, is high enough to assume continuity between points of [removed: observation.][added: observation]
| Part I | [removed: 25] [added: 28] |
Reported proven and probable reserves include only quantities that are owned in fee or under [removed: lease,] [added: lease] and for which all appropriate zoning and permitting have been obtained through permit, contract or grandfathered status.
[removed: Leases, zoning, permits, reclamation plans] [added: Contractual] and [removed: other government or industry] [added: governmental] regulations [added: (for example, leases, zoning, permits and reclamation plans)] often set limits on the areas, depths and lengths of time allowed for mining, stipulate setbacks and slopes that must be left in place, and designate which areas may be used for surface facilities, berms, and overburden or waste storage, among other requirements and [removed: restrictions.][added: restrictions]
[removed: Technical] [added: Technical] and economic factors [removed: also] affect the estimates of reported reserves regardless of what might otherwise be considered proven or probable based on a geologic analysis.
For example, excessive overburden or weathered rock, rock quality issues, excessive mining depths, groundwater issues, overlying wetlands, endangered species habitats, and rights of way or easements may effectively limit the quantity of reserves considered proven and [removed: probable.][added: probable]
The table below presents, by division, the [removed: tons] [added: count] of [removed: proven and probable] [added: active] aggregates [removed: reserves] [added: facilities] as of December 31, [removed: 2020] [added: 2021] and the types of facilities operated.
| | | | [removed: *(millions] [added: *Count] of [removed: tons)* | | |] [added: Active Aggregates Operating Facilities*] | | | | | | | | | [removed: *Count of Aggregates Operating Facilities* *2*] | | | | | | | |
| | | | *Aggregates Reserves* | | | | | | | | | [removed: 2020] | | | | [removed: | |] *Sand [removed: and*] [added: &*] | | | | |
| *Division* *1* | | | [removed: *Proven* | |] [added: *Total Proven & Probable*] | [removed: *Probable*] | | | [removed: *Total*] [added: *Production*] | | | [removed: *Production*] [added: *Limestone*] | | | [removed: *Stone*] [added: *Granite*] | | | *Gravel* | | | [removed: *Sales Yards*] [added: *Other* *3*] | |
| Southern Gulf Coast | | | [removed: 1,804.1 | | | 52.4] [added: 25] | | | [removed: 1,856.5] [added: 0] | | | [removed: 23.1] [added: 25] | | | [removed: 24] [added: 22] | | | [removed: 0] [added: 3] | | | [removed: 19] [added: 50] | |
| *1* | *The divisions are defined by states/countries as follows:* *Central Division* — [removed: *Arkansas, Illinois,] [added: *Illinois,] Kentucky and Tennessee* *International Division* — [removed: *Mexico*] [added: *Quintana Roo (Mexico), the U.S. Virgin Islands and British Columbia (Canada)*] *Mideast Division* — *Delaware, Maryland, North Carolina, Pennsylvania, Virginia and Washington D.C.* *Mountain West Division* — *Arizona and New Mexico* *Southeast Division* — *Florida (excluding panhandle), Georgia and South Carolina* *Southern Gulf Coast Division* — *Alabama, [added: Arkansas,] Florida Panhandle, Louisiana and Mississippi* *Southwest Division* — *Oklahoma and Texas* *Western Division* — *California* [added: *U.S. Concrete* *— Aggregates facilities are located in* *New Jersey, New York, Oklahoma, and Texas. Excludes the U.S. Virgin Islands and British Columbia (Canada) which are included in the International Division*] | |
| [removed: *3*] [added: *4*] | *Includes a maximum of [removed: 314.2] [added: 300.3] million tons of reserves encumbered by volumetric production payments as defined in Note 2 “Revenues” in Item 8 “Financial Statements and Supplementary Data.”* | |
Of the [removed: 15.9] [added: 15.6] billion tons of aggregates reserves at December 31, [removed: 2020, 9.2] [added: 2021, 9.1] billion tons or 58% are located on owned land and [removed: 6.7] [added: 6.5] billion tons or 42% are located on leased land.
| Part I | [removed: 26] [added: 29] |
| [removed: *(millions of tons)*] | | | [removed: | | | | | | |] [added: *(millions of tons)*] | | | | | | | | | | |
| [removed: *Location (nearest major metropolitan area)* | | | | | | |] [added: *Location*] | | | *Proven* | | | *Probable* | | | *Total* | | | *Production* | |
As of December 31, [removed: 2020,] [added: 2021,] we operated a number of facilities producing asphalt mix, ready-mixed concrete and calcium in several of our divisions as reflected in the table below:
| | | | | | | | | | | | | | | | *Asphalt* *2* | | | *Concrete* [added: *3*] | | | *Calcium* [removed: *3*] [added: *4*] | |
| Mideast | | | [removed: | | |] [added: 33] | | | [added: 4] | | | [added: 37] | | | [removed: 0] [added: 24] | | | [removed: 36] [added: 19] | | | [removed: 0] [added: 80] | |
| Mountain West | | | [removed: | | |] [added: 2] | | | [added: 10] | | | [added: 12] | | | [removed: 21] [added: 2] | | | [removed: 0] [added: 4] | | | [removed: 0] [added: 18] | |
| Southwest | | | [removed: | | |] [added: 17] | | | [added: 0] | | | [added: 17] | | | [removed: 15] [added: 24] | | | [removed: 7] [added: 1] | | | [removed: 0] [added: 42] | |
| Western | | | [removed: | | |] [added: 7] | | | [added: 8] | | | [added: 15] | | | [removed: 22] [added: 1] | | | [removed: 3] [added: 11] | | | [removed: 0] [added: 27] | |
| Total | | | | | | | | | | | | | | | [removed: 70] [added: 69] | | | [removed: 46] [added: 173] | | | 1 | |
| [removed: *3*] [added: *4*] | *Comprised of a* *ground* *calcium [removed: plant.*] [added: plant in Brooksville, Florida.*] |
Our Calcium segment operates a quarry at Brooksville, Florida [removed: which] [added: that] provides feedstock for the ground calcium operation.
| [removed: *(millions of tons)*] | | | [removed: | | | | | | | | |] [added: *(millions of tons)*] | | | | | | | | | | |
Our [added: production stage, leased] Brooksville limestone quarry [removed: is mined and processed primarily as] [added: produces] a supplement for end-use products, such as animal feed and plastics.
The Brooksville limestone quarry has an average calcium carbonate (CaCO3) content of [removed: 98.0%.][added: 97%.]
The office space consists of approximately 184,410 square feet and is leased through December 31, [removed: 2023, with three five-year renewal periods thereafter.][added: 2038.]
The annual rental cost for the current term of the lease is approximately [removed: $3.7] [added: $3.8] million.
As the largest U.S. supplier of construction aggregates, we have mining properties across the U.S. and in the Bahamas, Canada and Mexico.
Our mining properties are categorized as follows: (1) Production Stage – properties with reported proven or probable reserves where we are actively mining aggregates, (2) Development Stage – properties with reported proven or probable reserves where we are not actively mining aggregates, and (3) Exploration Stage – properties with no reported reserves.
The following map illustrates the location of our 228 aggregates production stage properties and 71 development stage properties.
Our 34 aggregates exploration stage properties are excluded from this map.
Active aggregates facilities generally include one or more scale houses, office buildings, maintenance shops and processing plants.
Our aggregates resources and reserves are our foundation and fundamental to our success.
However, no individual mining property is individually material to our business.
As of December 31, 2021, we directly operated substantially all of our aggregates production facilities.
Our aggregates resources and reserves estimates are calculated in accordance with subpart 1300 of Regulation S-K under the Exchange Act.
Our proven and probable aggregates reserves may not be comparable to similar information regarding aggregates reserves disclosed in accordance with the guidance of other countries.
We conduct ongoing studies of our deposits to optimize economic values and to manage risk.
We revise our mine plans and estimates of proven and probable aggregates reserves as required and in accordance with the latest available studies.
Once mine plans are initially established, the ongoing viability of the plan is reviewed regularly with the benefit of hindsight.
Discussions between mine planning, operations, and management determine the need for adjustments, additional resources, drilling information, or other key information.
While construction aggregates reserves and resources are relatively consistent, conditions can change with time that require a newly tailored solution.
Examples of changes include fluctuations in physical or chemical parameters of the product, sales product shifts, overburden removal or placement management, structural changes, entitlement changes and land additions.
Our estimates of proven and probable aggregates reserves are prepared by and are the responsibility of our employees.
The methodology employed takes a systematic approach to collecting sufficient information to estimate the reserves and resources.
Each of our reserve and resource bearing properties is evaluated with supporting information to identify its geological, mining and economic viability.
The supporting information includes aerial photography, topography, geologic maps, aggregates rock quality information (including core drilling, hand samples, and bulk sample testing, and/or geophysical data), hydrology, archaeology, biology, property boundary information, zoning information, relevant municipal and environmental permitting information.
The information is collected by experienced mining engineers and geologists who determine the extent of a resource using a combination of methods including ordinary planimetric based measurements to computer aided design 3-dimensional models.
The results of the supporting information are reviewed by various levels of management, including our “qualified person” (as defined by subpart 1300).
This qualified person then verifies that the information adheres to regulatory mandated quantification methods.
The economic viability of our reserves is evaluated taking into account historical performance of relevant operations and sales forecasts, among other factors.
Measurements of our proven and probable aggregates reserves have inherent risks.
These risks include the accuracy and completeness of geologic information, the interpretation of the data, operational execution, market shifts, structural events and the uncertainty of uncovered material.
Management and the qualified person work together to assess these risks regularly and amend the reserves assessments with new information as appropriate.
New information can yield site changes that require capital expenditures or cause production performance changes that have financial impacts.
AGGREGATES RESOURCES
Mineral resources are defined as a concentration or occurrence of material of economic interest in or on the earth’s crust in such form, grade or quality, and quantity that there are reasonable prospects for its economic extraction.
Mineral resources are classified into three categories, in decreasing level of confidence, as follows:
Measured — based on conclusive geological evidence and sampling, meaning that evidence is sufficient to test and confirm geological and grade or quality continuity.
After applying modifying factors (as noted in the Aggregates Reserves section below), measured resources may be converted to either proven or probable reserves
Indicated — based on adequate geological evidence and sampling, meaning that evidence is sufficient to establish geological and grade or quality continuity with reasonable certainty.
After applying modifying factors, indicated resources may be converted to probable reserves
Inferred — based on limited geological evidence and sampling, meaning that evidence is only sufficient to establish that geological and grade or quality continuity is more likely than not.
Inferred resources may not be converted to reserves
Our reported aggregates resources do not include amounts that have been identified as mineral reserves.
Our 2021 measured, indicated and inferred aggregates resources are based on an initial assessment using an average sales price assumption ranging from $5.00 to $20.00 per ton depending on the location/market.
The table below presents, by division, the tons of measured, indicated and inferred aggregates resources and the percentage of aggregates resources by commodity as of December 31, 2021.
Our reserve estimates take into account these factors.
In addition, computations for reserves in-place are adjusted for estimates of unsaleable sizes and materials as well as pit and plant waste.
The 15.9 billion tons of estimated proven and probable aggregates reserves reported at the end of 2020 include reserves at inactive and greenfield (undeveloped) sites.
| | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Central | | | 2,301.3 | | | 820.4 | | | 3,121.7 | | | 32.7 | | | 55 | | | 5 | | | 8 | |
| International | | | 529.5 | | | 0.0 | | | 529.5 | | | 11.4 | | | 1 | | | 0 | | | 0 | |
| Mideast | | | 2,422.8 | | | 981.2 | | | 3,404.0 | | | 34.0 | | | 37 | | | 4 | | | 24 | |
| Mountain West | | | 216.1 | | | 112.8 | | | 328.9 | | | 8.7 | | | 2 | | | 13 | | | 2 | |
| Southeast 3 | | | 2,952.9 | | | 871.7 | | | 3,824.6 | | | 50.1 | | | 45 | | | 8 | | | 24 | |
| Southwest | | | 1,377.8 | | | 0.0 | | | 1,377.8 | | | 24.3 | | | 16 | | | 1 | | | 24 | |
| Western | | | 761.9 | | | 737.4 | | | 1,499.3 | | | 18.8 | | | 5 | | | 12 | | | 1 | |
| Total | | | 12,366.4 | | | 3,575.9 | | | 15,942.3 | | | 203.1 | | | 185 | | | 43 | | | 102 | |
| *2* | *In addition to the aggregates facilities included in the table above, we operated 50 recycled concrete plants which are not dependent on reserves.* | |
The following table lists our ten largest active aggregates facilities based on the total proven and probable reserves at the sites.
None of our aggregates facilities contributed more than 5% to our total revenues in 2020.
| | | | | | | | | | | *Reserves at 12/31/2020* | | | | | | | | | *2020* | |
| Playa del Carmen (Cancun), Mexico | | | | | | | | | | 529.5 | | | 0.0 | | | 529.5 | | | 11.4 | |
| Hanover (Harrisburg), Pennsylvania | | | | | | | | | | 221.5 | | | 236.4 | | | 457.9 | | | 2.0 | |
| McCook (Chicago), Illinois | | | | | | | | | | 96.8 | | | 266.5 | | | 363.3 | | | 4.4 | |
| Corona (Los Angeles), California | | | | | | | | | | 10.0 | | | 320.0 | | | 330.0 | | | 2.1 | |
| Gold Hill (Charlotte), North Carolina | | | | | | | | | | 146.7 | | | 121.2 | | | 267.9 | | | 0.9 | |
| Postell (Macon), Georgia | | | | | | | | | | 186.5 | | | 72.3 | | | 258.8 | | | 4.6 | |
| San Emidio (Bakersfield), California | | | | | | | | | | 28.5 | | | 221.5 | | | 250.0 | | | 0.9 | |
| Medina (San Antonio), Texas | | | | | | | | | | 244.6 | | | 0.0 | | | 244.6 | | | 2.8 | |
| Macon, Georgia | | | | | | | | | | 115.4 | | | 128.0 | | | 243.4 | | | 2.0 | |
| Norcross (Atlanta), Georgia | | | | | | | | | | 180.2 | | | 27.7 | | | 207.9 | | | 3.4 | |
| *1* | *International* *Division has no asphalt, concrete or* *calcium* *facilities.* |
| | | | | | | | | | | | | *Reserves at 12/31/2020* | | | | | | | | | *2020* | |
| *Location* | | | | | | | | | | | | *Proven* | | | *Probable* | | | *Total* | | | *Production* | |
| Brooksville | | | | | | | | | | | | 4.5 | | | 7.1 | | | 11.6 | | | 0.3 | |
An excerpt. Shown here: all 38 rewritten, 40 of 166 added and all 31 removed. The counts are complete. For every sentence, read Item 2. PROPERTIES in the FY2021 filing and the FY2020 filing.
Item 4. MINE SAFETY DISCLOSURES
22 rewritten, 6 added, 1 removed, 49 unchanged
| Part I | [removed: 28] [added: 34] |
The names, positions and ages, as of February 20, [removed: 2021,] [added: 2022,] of our executive officers are as follows:
| J. Thomas Hill | Chairman, President and Chief Executive Officer | [removed: 61] [added: 62] |
| Suzanne H. Wood | Senior Vice President and Chief Financial Officer | [removed: 60] [added: 61] |
| Stanley G. Bass | Chief Strategy Officer | [removed: 59] [added: 60] |
| Thompson S. Baker II | Chief Operating Officer | [removed: 62] [added: 63] |
| [removed: David P. Clement] [added: Ronnie Pruitt] | Senior Vice President, [removed: Mountain West] [added: U.S. Concrete,] and Western [added: and Southwest] Divisions | [removed: 60] [added: 51] |
| Denson N. Franklin III | Senior Vice President, General Counsel and Secretary | [removed: 57] [added: 58] |
| Jerry F. Perkins Jr. | Senior Vice President, Southern & Gulf Coast and [removed: Southwest Divisions] [added: Mountain West Divisions, Commercial Excellence] | [removed: 51] [added: 52] |
| Jason P. Teter | Senior Vice President, Mideast and Southeast Divisions | [removed: 46] [added: 47] |
| Randy L. Pigg | Vice President, Controller and Principal Accounting Officer | [removed: 48] [added: 49] |
Previously, he served as Executive Vice President and Chief Operating Officer from January 2014 to July 2014, and Senior Vice President [removed: –] [added: —] South Region from December 2011 to December 2013.
Bass was elected Chief Strategy Officer in [added: March 2021 after serving as Chief Growth Officer since] February [removed: 2021.][added: 2016.]
He served as Senior Vice President [removed: –] [added: —] Western and Mountain West Divisions from January 2015 to February 2016, and Senior Vice President [removed: –] [added: —] West Region from September 2013 to December 2014.
Prior to that, he served as Senior Vice President [removed: –] [added: —] Central and West Regions from February 2013 to September 2013 and Senior Vice President [removed: –] [added: —] Central Region from December 2011 to February 2013.
Prior to that, he served in a number of positions with Vulcan, including President [removed: –] [added: —] Florida Rock Division, before serving as Chief Executive Officer of FRP Holdings, Inc. from October 2010 to March 2017 and President and Chief Executive Officer of Patriot Transportation Holding, Inc. from December 2014 to March 2017.
[removed: Clement was appointed] [added: He previously served as] Senior Vice President of the [added: Central Division since August 2021 and, prior to that role, served as Senior Vice President of the] Mountain West and Western Divisions [removed: in] [added: since] March 2020.
| Part I | [removed: 29] [added: 35] |
Perkins Jr. was appointed Senior Vice President [removed: of the] Southern & Gulf Coast and [removed: Southwest Divisions] [added: Mountain West Divisions, Commercial Excellence] in [removed: March 2020.][added: September 2021.]
Prior to [removed: his current position,] [added: that role,] he was [removed: president] [added: President] of the Southern and Gulf Coast Division.
Prior to that, he served in a number of positions with Vulcan, including Manager Financial Research & Reporting and Finance Director [removed: –] [added: —] Central Region.
| Part I | [removed: 30] [added: 36] |
| David P. Clement | Senior Vice President, Central Division, Operations Support, Procurement & Environmental | 61 |
Clement was appointed Senior Vice President Central Division, Operations Support, Procurement & Environmental in September 2021.
He previously served as Senior Vice President of the Southern & Gulf Coast and Mountain West Divisions since August 2021 and, prior to that role, served as Senior Vice President of the Southern & Gulf Coast and Southwest Divisions since March 2020.
Ronnie Pruitt is Senior Vice President of U.S. Concrete and the Western and Southwest Divisions.
He joined Vulcan as part of Vulcan’s August 2021 acquisition of U.S. Concrete, Inc. He held various leadership roles at U.S. Concrete, including President and Chief Executive Officer from April 2020 to August 2021, President and Chief Operating Officer from April 2019 to April 2020, and Senior Vice President and Chief Operating Officer from October 2015 to April 2019.
Prior to joining U.S. Concrete in 2015, he served as the Vice President of Cement Sales of Martin Marietta Materials, Inc. and held various positions at Texas Industries, Inc.
Prior to that he served as Chief Growth Officer as of February 2016.
Item 5. MARKET FOR REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
5 rewritten, 1 added, 1 removed, 21 unchanged
As of February [removed: 12, 2021,] [added: 15, 2022,] the number of shareholders of record was [removed: 2,379.][added: 2,277.]
Purchases of our equity securities during the quarter ended December 31, [removed: 2020] [added: 2021] are summarized below.
| *1* | *In* *February 2017, our Board of Directors authorized us to purchase* *up to 10,000,000 shares of our common stock.* *As of December 31, [removed: 2020,] [added: 2021,] there were* *8,064,851* *shares remaining under this* *authorization. Depending upon market, business, legal and other conditions, we may purchase shares* *from time to time through* *the* *open market* *(including* *plans designed to comply with Rule 10b5-1 of the Securities Exchange Act of 1934) and/or through* *privately negotiated transactions.* *The authorization has no time limit, does not obligate us to purchase any specific number of shares, and may be suspended or discontinued at any time.* | |
We did not have any unregistered sales of equity securities during the fourth quarter of [removed: 2020.][added: 2021.]
| Part II | [removed: 31] [added: 37] |
| 2021 | | | | | | | | | | | |
| 2020 | | | | | | | | | | | |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
457 rewritten, 600 added, 479 removed, 1,267 unchanged
We have audited the accompanying consolidated balance sheets of Vulcan Materials Company and subsidiaries (the “Company”) as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] the related consolidated statements of comprehensive income, equity, and cash flows, for each of the three years in the period ended December 31, [removed: 2020,] [added: 2021,] and the related notes (collectively referred to as the “financial statements”).
In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2020] [added: 2021] and [removed: 2019,] [added: 2020,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2020,] [added: 2021,] in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, [removed: 2020,] [added: 2021,] based on the criteria established in *Internal Control* *—* *Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February 25, [removed: 2021] [added: 2022] expressed an unqualified opinion on the Company's internal control over financial reporting.
[removed: Critical] [added: *Critical] Audit [removed: Matter][added: Matter Description*]
The critical audit [removed: matter] [added: matters] communicated below [removed: is a matter] [added: are matters] arising from the current-period audit of the financial statements that [removed: was] [added: were] communicated or required to be communicated to the audit committee and that (1) [removed: relates] [added: relate] to accounts or disclosures that are material to the financial statements and (2) involved our especially challenging, subjective, or complex judgments.
The communication of critical audit matters does not alter in any way our opinion on the financial statements, taken as a whole, and we are not, by communicating the critical audit [removed: matter] [added: matters] below, providing [removed: a] separate [removed: opinion] [added: opinions] on the critical audit [removed: matter] [added: matters] or on the accounts or disclosures to which [removed: it relates.][added: they relate.]
| Part II | [removed: 68] [added: 123] |
The groundwater treatment system for the Hewitt Landfill on-site remediation [removed: reached mechanical completion during 2020.][added: is fully operational as of December 31, 2021.]
Due to these uncertainties, future amounts recorded related to the ultimate resolution of claims and assessments could [removed: be material in a given period] [added: cause actual losses] to [added: differ materially from accrued costs.We identified] the [removed: Company’s results of operations or cash flows.Evaluating] [added: Hewitt Landfill and NHOU (collectively] the [added: Hewitt Landfill Environmental Matter) as a critical audit matter because evaluating the] estimate of the liability and the extent and sufficiency of related disclosures is subjective in nature and as such requires [removed: significant audit] [added: an increased extent of] effort, involves especially subjective auditing [removed: judgements,] [added: judgments,] and requires the [removed: use] [added: involvement] of our environmental specialists.
Our audit procedures related to the uncertainty in the timing, recognition and disclosure of the Company’s responsibility and potential share of remediation costs, specifically as they relate to the Hewitt Landfill [removed: and NHOU (collectively the Hewitt Landfill] Environmental [removed: Matter)] [added: Matter] include the following, among others:
We tested the [added: operating] effectiveness of controls over the identification and evaluation of information available to assess potential responsibility or share of remediation costs for the Hewitt Landfill Environmental Matter, as well as controls over the adequacy of the related financial statement footnote disclosures.
| Part II | [removed: 69] [added: 124] |
| | [removed: 2020] [added: 2021] | | | [removed: *2019*] [added: *2020*] | | | [removed: *2018*] [added: *2019*] | |
| *in [removed: thousands,] [added: millions,] except per share data* | | | | | | | | |
| Gain on sale of property, plant & equipment and businesses | [removed: 3,997] [added: 120.1] | | | [removed: 23,752] [added: 4.0] | | | [removed: 14,944] [added: 23.8] | |
| Other operating expense, net | [removed: (29,975)] [added: (65.1)] | | | [removed: (31,647)] [added: (30.0)] | | | [removed: (34,805)] [added: (31.7)] | |
| Other nonoperating income (expense), net | [removed: (17,540)] [added: 10.7] | | | [removed: 9,243] [added: (17.5)] | | | [removed: 13,000] [added: 9.2] | |
| Earnings from continuing operations before income taxes | [removed: 743,798] [added: 873.8] | | | [removed: 757,701] [added: 743.8] | | | [removed: 623,290] [added: 757.7] | |
| Loss on discontinued operations, net of tax | [removed: (3,515)] [added: (3.3)] | | | [removed: (4,841)] [added: (3.5)] | | | [removed: (2,036)] [added: (4.8)] | |
| Deferred [removed: gain (loss)] [added: loss] on interest rate derivative | [removed: (14,679)] [added: 0.0] | | | [removed: 0] [added: (14.7)] | | | [removed: 2,496] [added: 0.0] | |
| Amortization of prior interest rate derivative loss | [removed: 1,689] [added: 1.5] | | | [removed: 227] [added: 1.7] | | | [removed: 226] [added: 0.2] | |
| Adjustment for funded status of benefit plans | [removed: 6,366] [added: 13.4] | | | [removed: (26,892)] [added: 6.4] | | | [removed: (207)] [added: (26.9)] | |
| Amortization of actuarial loss and prior service cost for benefit plans | [removed: 23,057] [added: 13.7] | | | [removed: 1,142] [added: 23.0] | | | [removed: 4,365] [added: 1.2] | |
| Other comprehensive income (loss) | [removed: 16,433] [added: 28.6] | | | [removed: (25,523)] [added: 16.4] | | | [removed: 6,880] [added: (25.5)] | |
| Basic earnings (loss) per share [added: attributable to Vulcan] | | | | | | | | |
| Continuing operations | $ [removed: 4.44] [added: 5.08] | | | $ [removed: 4.71] [added: 4.44] | | | $ [removed: 3.91] [added: 4.71] | |
| Discontinued operations | (0.03) | | | [removed: (0.04)] [added: (0.03)] | | | [removed: (0.01)] [added: (0.04)] | |
| Net earnings | $ [removed: 4.41] [added: 5.05] | | | $ [removed: 4.67] [added: 4.41] | | | $ [removed: 3.90] [added: 4.67] | |
| Diluted earnings (loss) per share [added: attributable to Vulcan] | | | | | | | | |
| Continuing operations | $ [removed: 4.41] [added: 5.05] | | | $ [removed: 4.67] [added: 4.41] | | | $ [removed: 3.87] [added: 4.67] | |
| Discontinued operations | [removed: (0.02)] [added: (0.03)] | | | [removed: (0.04)] [added: (0.02)] | | | [removed: (0.02)] [added: (0.04)] | |
| Net earnings | $ [removed: 4.39] [added: 5.02] | | | $ [removed: 4.63] [added: 4.39] | | | $ [removed: 3.85] [added: 4.63] | |
| Part II | [removed: 70] [added: 125] |
| | [removed: 2020] [added: 2021] | | | [added: *2020* | | |] *2019* | |
| Customers, less allowance for [removed: doubtful accounts] [added: credit losses] | | | | | |
| Other current assets | [removed: 74,270] | | | [removed: 76,396] [added: 8.6] | |
| Investments and long-term receivables | [removed: 34,301] [added: 34.1] | | | [removed: 60,709] [added: 34.3] | |
| Property, plant & equipment, net | [removed: 4,425,999] [added: 5,546.8] | | | [removed: 4,316,038] [added: 4,426.0] | |
| Operating lease right-of-use assets, net | [removed: 423,128] [added: 691.4] | | | [removed: 408,189] [added: 423.1] | |
| Other intangible assets, net | [removed: 1,123,544] [added: 1,749.0] | | | [removed: 1,091,475] [added: 1,123.5] | |
Critical Audit Matters
Acquisitions – U.S. Concrete - Refer to Note 19 to the consolidated financial statements
The Company completed the acquisition of U.S. Concrete, Inc. (“USCR”), a leading supplier of aggregates and ready-mixed concrete, for total consideration of $1.63 billion on August 26, 2021.
The Company accounted for the business combination under the acquisition method of accounting.
Accordingly, the purchase price was allocated to the assets acquired and liabilities assumed based on their respective fair values, resulting in recorded goodwill of approximately $525 million.
Management determined the fair value of acquired intangible assets and property, plant & equipment to be approximately $674 million and $1.11 billion, respectively.
Management estimated the fair value of the intangible assets and property, plant & equipment using techniques that required management to make significant estimates and assumptions including those related to future cash flows, current market pricing of similar assets, and the selection of discount rates.
We identified the acquisition of USCR as a critical audit matter because of the subjectivity inherent in the estimates and assumptions management made in the determination of fair value of the aforementioned acquired assets.
Performing audit procedures to evaluate the reasonableness of future cash flows, discount rates and market pricing inputs required a high degree of auditor judgment and an increased extent of effort, including the need to involve internal fair value specialists.
Our audit procedures related to the estimates of fair value, including future cash flows, consisted of the following, among others:
We tested the effectiveness of controls over the purchase price allocation, including management’s controls over forecasts of future cash flows and the selection of the discount rate utilized to value the amortizable intangible assets acquired.
We also tested the effectiveness of management’s controls over the selection of market pricing inputs for the valuation of property, plant & equipment assets.
With the assistance of internal fair value specialists, we:
Evaluated the reasonableness of the selected valuation methodologies and the application of those methodologies;
Tested the source information underlying the determination of the discount rates and tested the mathematical accuracy of the fair value models;
Compared market pricing inputs to applicable external market sources.
We evaluated the reasonableness of management’s forecasts of future cash flows by comparing the assumptions used in the projections to external market sources, historical data, and results from other areas of the audit.
*How the Critical Audit Matter Was Addressed in the Audit*
February 25, 2022
| Total revenues | $ 5,552.2 | | | $ 4,856.8 | | | $ 4,929.1 | |
| Cost of revenues | 4,178.8 | | | 3,575.3 | | | 3,673.2 | |
| Gross profit | 1,373.4 | | | 1,281.5 | | | 1,255.9 | |
| Selling, administrative and general expenses | 417.6 | | | 359.8 | | | 370.5 | |
| Operating earnings | 1,010.8 | | | 895.7 | | | 877.5 | |
| Interest income | 1.6 | | | 1.6 | | | 1.2 | |
| Interest expense | 149.3 | | | 136.0 | | | 130.2 | |
| Current | 133.5 | | | 93.9 | | | 58.9 | |
| Deferred | 66.6 | | | 61.9 | | | 76.3 | |
| Total income tax expense | 200.1 | | | 155.8 | | | 135.2 | |
| Earnings from continuing operations | 673.7 | | | 588.0 | | | 622.5 | |
| Net earnings | 670.4 | | | 584.5 | | | 617.7 | |
| Loss attributable to noncontrolling interest | 0.4 | | | 0.0 | | | 0.0 | |
| Net earnings attributable to Vulcan | $ 670.8 | | | $ 584.5 | | | $ 617.7 | |
| Comprehensive income | 699.0 | | | 600.9 | | | 592.2 | |
| Comprehensive loss attributable to noncontrolling interest | 0.4 | | | 0.0 | | | 0.0 | |
| Comprehensive income attributable to Vulcan | $ 699.4 | | | $ 600.9 | | | $ 592.2 | |
| Basic | 132.8 | | | 132.6 | | | 132.3 | |
| Assuming dilution | 133.5 | | | 133.2 | | | 133.4 | |
| *in millions* | | | | | |
| Cash and cash equivalents | $ 235.0 | | | $ 1,197.1 | |
February 25, 2021
| | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Total revenues | $ 4,856,826 | | | $ 4,929,103 | | | $ 4,382,869 | |
| Cost of revenues | 3,575,345 | | | 3,673,202 | | | 3,281,924 | |
| Gross profit | 1,281,481 | | | 1,255,901 | | | 1,100,945 | |
| Selling, administrative and general expenses | 359,772 | | | 370,548 | | | 333,371 | |
| Operating earnings | 895,731 | | | 877,458 | | | 747,713 | |
| Interest income | 1,567 | | | 1,155 | | | 554 | |
| Interest expense | 135,960 | | | 130,155 | | | 137,977 | |
| Current | 93,948 | | | 58,941 | | | 40,516 | |
| Deferred | 61,855 | | | 76,257 | | | 64,933 | |
| Total income tax expense | 155,803 | | | 135,198 | | | 105,449 | |
| Earnings from continuing operations | 587,995 | | | 622,503 | | | 517,841 | |
| Net earnings | $ 584,480 | | | $ 617,662 | | | $ 515,805 | |
| Comprehensive income | $ 600,913 | | | $ 592,139 | | | $ 522,685 | |
| Basic | 132,578 | | | 132,300 | | | 132,393 | |
| Assuming dilution | 133,245 | | | 133,385 | | | 133,926 | |
| *in thousands* | | | | | |
| Cash and cash equivalents | $ 1,197,068 | | | $ 271,589 | |
| Restricted cash | 945 | | | 2,917 | |
| 2020 — $2,551; 2019 — $3,125 | 512,945 | | | 532,012 | |
| Other | 43,352 | | | 38,104 | |
| Inventories | 448,585 | | | 458,308 | |
| Total current assets | 2,277,165 | | | 1,379,326 | |
| Goodwill | 3,172,112 | | | 3,167,061 | |
| Other noncurrent assets | 230,656 | | | 225,995 | |
| Total assets | $ 11,686,905 | | | $ 10,648,793 | |
| Accrued interest | 19,943 | | | 19,167 | |
| Other current liabilities | 147,779 | | | 153,984 | |
| Total current liabilities | 1,047,883 | | | 535,563 | |
| Long-term debt | 2,772,240 | | | 2,784,315 | |
| Deferred management incentive and other compensation | 26,787 | | | 22,856 | |
| Pension benefits | 107,195 | | | 142,363 | |
| Other postretirement benefits | 29,412 | | | 35,848 | |
| Asset retirement obligations | 283,163 | | | 210,323 | |
| Deferred revenue | 174,045 | | | 179,880 | |
| Operating lease liabilities | 399,582 | | | 388,042 | |
| Other noncurrent liabilities | 113,218 | | | 94,707 | |
| Total liabilities | $ 5,659,575 | | | $ 5,026,936 | |
An excerpt. Shown here: 40 of 457 rewritten, 40 of 600 added and 40 of 479 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2021 filing and the FY2020 filing.
Item 9A. CONTROLS AND PROCEDURES
8 rewritten, 9 added, 6 removed, 37 unchanged
Our Chief Executive Officer and Chief Financial Officer, with the participation of other management officials, evaluated the effectiveness of the design and operation of the disclosure controls and procedures as of December 31, [removed: 2020.][added: 2021.]
Based upon that evaluation, our Chief Executive Officer and Chief Financial Officer concluded that our disclosure controls and procedures were effective as of December 31, [removed: 2020.][added: 2021.]
[removed: No] [added: Excluding the U.S. Concrete acquisition noted below, no] material changes were made during the fourth quarter of [removed: 2020] [added: 2021] to our internal [removed: control] [added: controls] over financial reporting, nor have there been other factors that materially affect these controls.
Based on this evaluation, management concluded that our internal control over financial reporting was effective as of December 31, [removed: 2020.][added: 2021.]
Deloitte & Touche LLP, an independent registered public accounting firm, as auditors of our consolidated financial statements, has issued an attestation report on the effectiveness of our internal control over financial reporting as of December 31, [removed: 2020.][added: 2021.]
We have audited the internal control over financial reporting of Vulcan Materials Company and subsidiaries (the “Company”) as of December 31, [removed: 2020,] [added: 2021,] based on criteria established in *Internal Control* — *Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2020,] [added: 2021,] based on criteria established in *Internal Control* — *Integrated Framework (2013)* issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated financial statements as of and for the year ended December 31, [removed: 2020,] [added: 2021,] of the Company and our report dated February 25, [removed: 2021,] [added: 2022,] expressed an unqualified opinion on those financial statements.
We completed our acquisition of U.S. Concrete on August 26, 2021 and have not yet included U.S. Concrete in management’s assessment of the effectiveness of our internal controls over financial reporting.
We are currently integrating U.S. Concrete into our operations and internal control processes.
Accordingly, pursuant to the SEC’s general guidance that an assessment of a recently acquired business may be omitted from the scope of an assessment for one year following the acquisition, the scope of management’s assessment of the effectiveness of our disclosure controls and procedures does not include U.S. Concrete.
U.S. Concrete constituted approximately 10% of our total assets as of December 31, 2021 and approximately 8% of our total revenues for the year ended December 31, 2021.
| Part II | 129 |
As described in Item 9A, Controls and Procedures, management excluded from its assessment the internal control over financial reporting at U.S. Concrete, which was acquired on August 26, 2021, and whose financial statements constitute 10% of total assets and 8% of total revenues of the consolidated financial statement amounts as of and for the year ended December 31, 2021.
Accordingly, our audit did not include the internal control over financial reporting at U.S. Concrete.
| February 25, 2022 |
| Part II | 130 |
Due to the COVID-19 pandemic, we have implemented remote work arrangements for support functions and restricted business travel effective mid-March 2020.
To date, these arrangements have not materially affected our ability to maintain our business operations, including the operation of financial reporting systems, internal control over financial reporting, and disclosure controls and procedures.
We are continually assessing the potential effects of the pandemic on the design and operating effectiveness of our internal control over financial reporting and if necessary, will take appropriate actions.
| Part II | 123 |
| February 25, 2021 |
| Part II | 124 |
Item 9B. OTHER INFORMATION
0 rewritten, 4 added, 1 removed, 6 unchanged
ITEM 9C
DISCLOSURE REGARDING FOREIGN JURISDICTIONS THAT PREVENT INSPECTIONS
Not applicable.
| Part II | 131 |
| Part II | 125 |
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
2 rewritten, 0 added, 0 removed, 2 unchanged
On or about March [removed: 29, 2021,] [added: 28, 2022,] we expect to file a definitive proxy statement with the Securities and Exchange Commission pursuant to Regulation 14A (our [removed: “2021] [added: “2022] Proxy Statement”).
The information under the headings “Proposal 1 - Election of Directors,” “Corporate Governance – Policies,” “Corporate Governance – Director Nomination Process,” “Corporate Governance – Committees of the Board of Directors” and “Delinquent Section 16(a) Reports” (to the extent reported therein) included in our [removed: 2021] [added: 2022] Proxy Statement is incorporated herein by reference.
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 0 added, 0 removed, 1 unchanged
The information under the headings “Compensation Discussion and Analysis,” “Director Compensation,” “Executive Compensation,” “Corporate Governance – Compensation Committee Interlocks and Insider Participation,” and “Compensation Committee Report” included in our [removed: 2021] [added: 2022] Proxy Statement is incorporated herein by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED
1 rewritten, 0 added, 0 removed, 2 unchanged
The information under the headings “Security Ownership of Certain Beneficial Owners and Management,” and “Equity Compensation Plans” included in our [removed: 2021] [added: 2022] Proxy Statement is incorporated herein by reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 0 removed, 1 unchanged
The information under the headings “Corporate Governance – Director Independence,” and “Corporate Governance – Transactions with Related Persons” included in our [removed: 2021] [added: 2022] Proxy Statement is incorporated herein by reference.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
2 rewritten, 0 added, 0 removed, 5 unchanged
The information under the heading “Independent Registered Public Accounting Firm” included in our [removed: 2021] [added: 2022] Proxy Statement is incorporated herein by reference.
| Part III | [removed: 126] [added: 132] |
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
18 rewritten, 11 added, 6 removed, 82 unchanged
| | Report of Independent Registered Public Accounting Firm [added: (PCAOB ID 34)] | [removed: 68 - 69] [added: 73 – 75] | |
| | Consolidated Statements of Comprehensive Income | [removed: 70] [added: 76] | |
| | Consolidated Balance Sheets | [removed: 71] [added: 77] | |
| | Consolidated Statements of Cash Flows | [removed: 72] [added: 78] | |
| | Consolidated Statements of Equity | [removed: 73] [added: 79] | |
| | Notes to Consolidated Financial Statements | [removed: 74 -122] [added: 80 – 128] | |
| Exhibit 21 | | | [List of the Company's material subsidiaries as of December 31, [removed: 2020](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231xex21.htm)] [added: 202](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231xex21.htm)1] | | |
| Exhibit 23 | | | [Consent of Deloitte & Touche LLP, Independent Registered Public Accounting [removed: Firm](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231xex23.htm)] [added: Firm](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231xex23.htm)] | | |
| Exhibit 24 | | | [Powers of [removed: Attorney](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231xex24.htm)] [added: Attorney](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231xex24.htm)] | | |
| Exhibit 31(a) | | | [Certification of Chief Executive Officer pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231xex31.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231xex31.htm)] | | |
| Exhibit 31(b) | | | [Certification of Chief Financial Officer pursuant to Section 302 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231xex31.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231xex31.htm)] | | |
| Exhibit 32(a) | | | [Certification of Chief Executive Officer pursuant to Section 906 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231xex32.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231xex32.htm)] | | |
| Exhibit 32(b) | | | [Certification of Chief Financial Officer pursuant to Section 906 of the Sarbanes-Oxley Act of [removed: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231xex32.htm)] [added: 2002](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231xex32.htm)] | | |
| Exhibit 95 | | | [MSHA Citations and [removed: Litigation](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231xex95.htm)] [added: Litigation](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231xex95.htm)] | | |
| Exhibit 101 | | | The following financial information from this Annual Report on Form 10-K for the year ended December 31, [removed: 2020] [added: 2021] are formatted in iXBRL (Inline eXtensible Business Reporting Language): (i) the Consolidated Statements of Comprehensive Income, (ii) the Consolidated Balance Sheets, (iii) the Consolidated Statements of Cash Flows, (iv) the Consolidated Statements of Equity and (v) the Notes to Consolidated Financial Statements. | [added: | |]
| Exhibit 104 | | | Cover Page Interactive Data File – the cover page from this Annual Report on Form 10-K for the year ended December 31, [removed: 2020] [added: 2021] is formatted in iXBRL (contained in Exhibit 101). | [added: | |]
| *1* | *Incorporated by reference.* | | | [added: | |]
| *2* | *Management contract or compensatory plan.* | | | [added: | |]
| Exhibit 2(a) | | | [Agreement and Plan of Merger, dated as of June 6, 2021, by and among Vulcan Materials Company, Grizzly Merger Sub I, Inc. and U.S. Concrete, Inc., filed as Exhibit 2.1 to the Company’s Current Report on Form 8-K filed on June 7, 2021 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312521183727/d177818dex21.htm) | | |
| Part IV | 133 |
| Part IV | 134 |
| Part IV | 135 |
| Exhibit 10(hh) | | | [Credit Agreement, dated June 30, 2021, among Vulcan Materials Company, Truist Bank, as Administrative Agent, and the Lenders and other parties named therein, filed as Exhibit 10.1 to the Company’s Current Report on Form 8-K filed on July 1, 2021 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312521206349/d72908dex101.htm) | | |
| Exhibit 10(ii) | | | [First Amendment to Credit Agreement, dated June 30, 2021, among Vulcan Materials Company, Truist Bank, as Administrative Agent, and the Lenders and other parties named therein, filed as Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q filed on August 5, 2021 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600921000044/vmc-20210630xex10_2.htm) | | |
| Exhibit 10(jj) | | | [First Amendment to Credit Agreement, dated August 16, 2021, by and between Vulcan Materials Company and Truist Bank, as Administrative Agent, filed as Exhibit 10.1 to the Company’s Quarterly Report on Form 10-Q filed on November 5, 2021 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600921000050/vmc-20210930xex10_1.htm) | | |
| Exhibit 10(kk) | | | [Second Amendment to Credit Agreement, dated August 16, 2021, by and between Vulcan Materials Company and Truist Bank, as Administrative Agent, filed as Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q filed on November 5, 2021 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600921000050/vmc-20210930xex10_2.htm) | | |
| Part IV | 136 |
| --- | --- | --- | --- | --- | --- |
| Part IV | 137 |
| --- | --- | --- | --- |
| Part IV | 127 |
| Part IV | 128 |
| Part IV | 129 |
| Part IV | 130 |
| Part IV | 131 |
Item 16. FORM 10-K SUMMARY
6 rewritten, 2 added, 2 removed, 19 unchanged
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized on February 25, [removed: 2021.][added: 2022.]
| | ] [added: 1](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg038.jpg)] J. Thomas Hill Chairman, President and Chief Executive Officer |
| ] [added: 3](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg038.jpg)] J. Thomas Hill | Chairman, President and Chief Executive Officer (Principal Executive Officer) | February 25, [removed: 2021] [added: 2022] |
| ] [added: 4](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg039.jpg)] Suzanne H. Wood | Senior Vice President and Chief Financial Officer (Principal Financial Officer) | February 25, [removed: 2021] [added: 2022] |
| ] [added: 38](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg040.jpg)] Randy L. Pigg | Vice President, Controller (Principal Accounting Officer) | February 25, [removed: 2021] [added: 2022] |
| ] [added: 22](https://www.sec.gov/Archives/edgar/data/1396009/000139600922000010/vmc-20211231x10kg041.jpg)] Denson N. Franklin III Attorney-in-Fact | | February 25, [removed: 2021] [added: 2022] |
| Part IV | 138 |
| Part IV | 139 |
| Part IV | 132 |
| Part IV | 133 |