 filings.tools
Vulcan Materials (VMC) 10-K risk factor changes: FY2020 vs FY2019
The 2020-12-31 10-K against the 2019-12-31 one, compared heading by heading and sentence by sentence.
Item 1A19 rewritten20 added9 removed107 unchanged
All filing items1,164 rewritten595 added514 removed2,752 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 595 added, 514 removed, 1,164 rewritten and 2,752 unchanged across 21 items that differ.
- Not in this year's filing: Item 6. SELECTED FINANCIAL DATA.
Sentences by item
22 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2020; struck-through words were in FY2019. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
19 rewritten, 20 added, 9 removed, 107 unchanged
Our business is dependent on the construction industry and is subject to economic [removed: cycles —] [added: cycles —] Our products are principally sold to the U.S. construction industry.
In [removed: 2019,] [added: 2020,] voters in local jurisdictions in [added: Arizona,] California, [added: Florida,] Georgia, [removed: New Mexico,] North Carolina, [added: South Carolina,] Texas and Virginia, among others, approved bond and revenue-raising measures to provide additional resources for transportation projects.
The federal FAST Act, a five year, fully-funded road, bridge and public transportation authorization law, [removed: is providing] [added: was extended for a year, and continues to provide] assistance to state DOTs and metro [removed: areas.][added: areas while Congress contemplates new long-term highway and transit legislation in 2021.]
| Part I | [removed: 17] [added: 21] |
A number of our facilities are located in desert [removed: climates] [added: climates,] and while we have not experienced any significant shortages of energy or water in the past, we cannot guarantee that we will not in the future.
These risks may include changes in international trade policies, such as the United States [removed: —] [added: -] Mexico [removed: —] [added: -] Canada Agreement (USMCA), imposition of duties, taxes or government royalties, arbitrary changes to permits, zoning classifications or operating agreements, or overt acts by foreign governments, including expropriations and other forms of takings of property.
| Part I | [removed: 18] [added: 22] |
While we have not identified any events or changes in circumstances since our annual impairment test on November 1, [removed: 2019] [added: 2020] that indicate the fair value of any of our reporting units is below its carrying value, a significant downturn in the construction industry may have a material effect on the fair value of our reporting units.
A deterioration in our credit ratings and/or the state of the capital markets could negatively impact the cost and/or availability of financing — We currently have [removed: $2.85] [added: $3.36] billion of debt with maturities between [removed: 2020] [added: 2021] and 2048.
A deterioration in our credit ratings, regardless of the cause, could limit our debt financing options and increase the cost of such debt [removed: financing (whether for refinancing existing debt or financing acquisitions).][added: financing.]
The phase-out of LIBOR, or the replacement of LIBOR with a different reference rate or modification of the method used to calculate LIBOR, may adversely affect interest rates [removed: —] [added: —] LIBOR is an interest rate benchmark used as a reference rate for a wide range of financial [removed: transactions, including derivatives and loans.][added: transactions.]
It is unclear whether [removed: or not] LIBOR will cease to exist at that time (and if so, what reference rate will replace it) or if new methods of calculating LIBOR will be established such that it continues to exist after 2021.
The Alternative Reference Rates Committee (ARRC) has proposed [removed: that] the Secured Overnight Financing Rate (SOFR) [removed: is the rate that represents best practice] as the alternative to [removed: LIBOR for use in financial and other derivatives contracts that are currently indexed to United States dollar] [added: U.S.] LIBOR.
ARRC has proposed a paced market transition plan to SOFR from LIBOR, and organizations are currently working on industry wide and company specific transition [removed: plans as it relates to financial and other derivative contracts exposed to LIBOR.][added: plans.]
We have [removed: three] [added: two] material debt instruments with LIBOR as a reference [removed: rate, each of which matures before the end of 2021:] [added: rate:] 1) [removed: $250.0 million floating-rate notes due 2020, 2)] $500.0 million floating-rate notes due [added: March] 2021, and [removed: 3) $750.0] [added: 2) $1,000.0] million line of credit (none outstanding at December 31, [removed: 2019)] [added: 2020)] due [removed: 2021.][added: September 2025.]
[added: A significant interruption of our information technology systems or the loss of confidential or other sensitive data could have a material adverse impact on our operations and financial results —] Given our reliance on information technology (our own and [added: that of] our [removed: third-party providers’),] [added: service providers’ such as Amazon Web Services),] a significant interruption in the availability of information [removed: technology, regardless of the cause,] [added: technology] or the loss of confidential, personal, or proprietary information (whether our own, our employees’, our suppliers’, or our customers’), regardless of the cause, could negatively impact our [removed: operations.][added: operations and financial results.]
While we have invested in the protection of our data and information technology [removed: to reduce these risks] and routinely test the security of our information systems network, we cannot be assured that our efforts will prevent breakdowns or breaches in our systems that could adversely affect our business.
Variability in the supply and prices of these resources could materially affect our operating results from period to [removed: period] [added: period,] and rising costs could erode our profitability.
We cannot predict the outcome of these contingencies with certainty — We are involved in environmental investigations and cleanups at sites [added: that we own or owned,] where we operate or have operated [removed: in the past] or [added: where we] sent materials for recycling or [removed: disposal.][added: disposal, as well as related offsite investigations and cleanups.]
A pandemic, epidemic or other public health emergency, such as the recent outbreak of the current coronavirus (COVID-19) pandemic, could have a material adverse effect on our business, results of operations, financial condition and cash flows — Our operations expose us to risks associated with pandemics, epidemics or other public health emergencies, such as the COVID-19 pandemic.
In March 2020, the World Health Organization characterized COVID-19 as a pandemic, and the President of the United States declared the COVID-19 outbreak a national emergency.
The outbreak has resulted in governments around the world implementing or reimplementing strict measures to help control the spread of the virus, including quarantines, “shelter in place” and “stay at home” orders, travel restrictions, business curtailments, school closures, and other measures.
In addition, governments and central banks in several parts of the world have enacted fiscal and monetary stimulus measures to counteract the impacts of the COVID-19 pandemic, and may take further action as circumstances warrant.
Consistent with federal guidelines and with state and local orders to date, we currently continue to operate across our footprint as an essential business.
Notwithstanding our continued operations and an economic environment that has shown signs of improvement, the COVID-19 pandemic has had and may have further negative impacts on our operations, supply chain, transportation networks and customers, which may lower our revenues and EBITDA, including as a result of preventative and precautionary measures that we, other businesses and governments are taking.
The COVID-19 pandemic is a widespread public health crisis that is adversely affecting the economies and financial markets of many countries.
Any resulting economic downturn could adversely affect demand for our products and contribute to volatile supply and demand conditions affecting prices and volumes in the markets for our products and services.
The progression of this matter has and may continue to negatively impact our business or results of operations by affecting the health of our employees and through the temporary closure of our operating locations or those of our customers or suppliers.
The extent to which the COVID-19 outbreak impacts our business, results of operations, financial condition or cash flows will depend on future developments, which remain highly uncertain and cannot be predicted, including, but not limited to, the duration and geographic spread of the outbreak, its severity, the actions to contain the virus or treat its impact including the reimplementation of restrictions on economic activity following new outbreaks, the long-term impacts of the virus on transportation revenues, government budgets and other funding priorities and the extent and pace at which normal economic and operating conditions can resume.
There can be no assurance that we will not be impacted by adverse consequences that may be brought about by pandemics on global financial markets, which may reduce resources, share prices and financial liquidity and may severely limit the availability of financing capital.
In 2020, Virginia passed new long-term highway funding legislation and voters in Arkansas made permanent a ½ cent gas tax increase first approved in 2012.
At this time, we cannot predict the impact of a departure from LIBOR as a reference rate.
GENERAL RISK FACTORS
We have a dedicated information security team that executes, and updates as warranted based on emerging risk and new risk management technology, our information security program.
Aggregates resources and reserves calculations are estimates only, and are subject to uncertainty due to factors including the inherent variability of the deposit and recoverability of saleable material in the mining process — The calculation of mineral resources and reserves are estimates and depend upon geological interpretation and statistical inferences or assumptions drawn from drilling and sampling analysis, which may prove to be unpredictable.
Until mineral reserves are actually mined and processed, the quantity must be considered as an estimate only.
| | |
| --- | --- |
| Part I | 23 |
In 2019, two state legislatures in Vulcan-served areas — Alabama and Illinois — passed new long-term highway funding legislation.
At this time, we cannot predict the future impact of a departure from LIBOR as a reference rate; however, if future rates based upon the successor reference rate (or a new method of calculating LIBOR) are higher than LIBOR rates as currently determined, it may have a material adverse effect on our financial condition and results of operations.
OTHER RISKS
A significant interruption of our information technology systems or the loss of confidential or other sensitive data, including cybersecurity risks, could have a material adverse impact on our operations and financial results — As part of our regular review of potential risks, we maintain an information and operational technology risk management program that is primarily supervised by information technology management and reviewed by internal cross-functional stakeholders.
As part of this program, analyses of emerging cybersecurity threats as well as our plans and strategies to address them are regularly prepared and presented to senior management, the Audit Committee and the Board of Directors.
Management is not aware of a cybersecurity incident that has had a material adverse impact on our financial condition or results of operations; however, we could suffer material financial or other losses in the future and we are not able to predict the severity of these attacks.
The occurrence of a cyber-attack, breach, unauthorized access, misuse, computer virus or other malicious code or other cybersecurity event could jeopardize or result in the unauthorized disclosure, gathering, monitoring, misuse, corruption, loss or destruction of confidential and other information that belongs to us, our customers, our counterparties, or third-party providers that is processed and stored in, and transmitted through, our computer systems and networks.
The occurrence of such an event could also result in damage to our software, computers or systems, or otherwise cause interruptions or malfunctions in our, our customers’, our counterparties’ or third parties’ operations.
This could result in loss of customers and business opportunities, reputational damage, litigation, regulatory fines, penalties or intervention, reimbursement or other compensatory costs, or otherwise adversely affect our business, financial condition or results of operations.
Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
292 rewritten, 190 added, 153 removed, 655 unchanged
FINANCIAL SUMMARY FOR [removed: 2019] [added: 2020] (compared to [removed: 2018)][added: 2019)]
Gross profit increased [removed: $155.0] [added: $25.6] million, or [removed: 14%,] [added: 2%,] to [removed: $1,255.9] [added: $1,281.5] million
Aggregates segment freight-adjusted revenues [removed: increased $346.9] [added: decreased $6.5] million, or [removed: 13%,] [added: less than 1%,] to [removed: $3,014.2] [added: $3,007.6] million
Freight-adjusted sales price increased [removed: 6%,] [added: 3.2%,] or [removed: $0.74] [added: $0.45] per ton [added: to $14.44]
Segment gross profit increased [removed: $154.8] [added: $12.5] million, or [removed: 16%,] [added: 1%,] to [removed: $1,146.6] [added: $1,159.2] million
Asphalt, Concrete and Calcium segment gross profit increased [removed: $0.2] [added: $13.1] million, or [removed: 0%,] [added: 12%,] to [removed: $109.3] [added: $122.3] million, collectively
Selling, administrative and general (SAG) expenses [removed: increased 11%] [added: decreased 3%] to [removed: $370.5] [added: $359.8] million and decreased [removed: 0.10] [added: 0.1] percentage points (10 basis points) as a percentage of total revenues
Operating earnings increased [removed: $129.7] [added: $18.3] million, or [removed: 17%,] [added: 2%,] to [removed: $877.5] [added: $895.7] million
Earnings from continuing operations before income taxes were [removed: $757.7] [added: $743.8] million compared to [removed: $623.3] [added: $757.7] million
Earnings from continuing operations were [removed: $622.5] [added: $588.0] million, or [removed: $4.67] [added: $4.41] per diluted share, compared to [removed: $517.8] [added: $622.5] million, or [removed: $3.87] [added: $4.67] per diluted share
Discrete items in [removed: 2018] [added: 2020] include:
pretax gains of [removed: $2.9] [added: $13.4] million [removed: for] [added: related to] the sale of businesses [added: and property donation]
pretax charges of [removed: $18.5] [added: $6.9] million for divested operations
pretax charges of [removed: $5.2] [added: $7.3] million associated with non-routine business development
pretax charges of [removed: $6.2] [added: $1.3] million for restructuring
Adjusted (for the discrete pretax items noted above) earnings from continuing operations were [removed: $4.70] [added: $4.68] per diluted share, compared to [removed: $4.05] [added: $4.70] per diluted share
Adjusted EBITDA was [removed: $1,270.0] [added: $1,323.5] million, an increase of [removed: $138.3] [added: $53.5] million, or [removed: 12%][added: 4%]
Returned capital to shareholders via dividends [removed: ($164.0] [added: ($180.2] million versus [removed: $148.1] [added: $164.0] million) and share repurchases [removed: ($2.6] [added: ($26.1] million versus [removed: $134.0] [added: $2.6] million)
| Part II | [removed: 29] [added: 63] |
[added: |] Adjusted EBITDA [removed: increased 12% to $1,270.0 million.][added: | | | | | | $ 1,323.5 | | | $ 1,270.0 | |]
Our weighted-average debt maturity was [removed: 14 years] [added: 13 years,] and the [added: effective] weighted-average interest rate was [removed: 4.4%.][added: 4.1%.]
Our capital allocation priorities [removed: remain unchanged:][added: are, as follows:]
[removed: This amount included] [added: During 2020, we invested] $239.3 million [removed: of core operating and maintenance capital investments] to [removed: improve or] replace [added: or improve] existing property, plant & equipment.
[removed: In addition,] [added: During 2020,] we invested [removed: $165.0] [added: $122.9] million in internal growth projects to secure new aggregates reserves, develop new production [added: and/or distribution] sites, enhance our distribution capabilities and support the targeted growth of our asphalt and concrete operations.
We closed two business acquisitions during [removed: 2019] [added: 2020] for total consideration of [removed: $45.3] [added: $73.4] million.
During [removed: 2019,] [added: 2020,] we returned [removed: $166.6] [added: $26.1] million to our shareholders through [removed: dividends and] share repurchases.
| Part II | [removed: 30] [added: 64] |
Management expectations for [removed: 2020] [added: 2021] include:
Aggregates freight-adjusted price increase of [removed: 4%] [added: 2%] to [removed: 6%][added: 4% from 2020]
Collective Asphalt, Concrete and Calcium segment gross profit [removed: growth of 10% to 15%][added: up mid-to high single digits]
SAG expenses of [removed: approximately] $365 million [added: to $375 million]
Interest expense of approximately [removed: $125] [added: $130] million
Depreciation, depletion, accretion and amortization expense of approximately [removed: $385] [added: $400] million
An effective tax rate of approximately [removed: 20%][added: 21%]
Earnings from continuing operations of [removed: $5.20] [added: $4.80] to [removed: $5.80] [added: $5.40] per diluted share
Net earnings of [removed: $695] [added: $640] million to [removed: $775] [added: $720] million
Adjusted EBITDA of [removed: $1.385] [added: $1.340] billion to [removed: $1.485] [added: $1.440] billion
| Part II | [removed: 31] [added: 65] |
We have a coast-to-coast footprint that serves 19 of the top 25 highest-growth metropolitan [added: statistical] areas [added: (MSAs)] and states where [removed: 72%] [added: 73%] of U.S. population growth from 2020 to 2030 is projected to occur.
][added: 17](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg015.jpg)]
Management’s discussion and analysis is intended to help investors understand our operations and current business environment.
The following discussion should be read in conjunction with the consolidated financial statements and the accompanying notes contained in this Annual Report.
The following generally includes a comparison of our results of operations and liquidity and capital resources for 2020 and 2019.
For the discussion of changes from 2018 to 2019 and other financial information related to 2018, refer to Part II, Item 7.
Management’s Discussion and Analysis of Financial Condition and Results of Operations, of our Form 10-K for the year ended December 31, 2019 filed with the Securities and Exchange Commission on February 26, 2020.
Total revenues decreased $72.3 million, or 1.5%, to $4,856.8 million
Aggregates segment sales decreased $46.0 million, or 1%, to $3,944.3 million
Shipments decreased 3%, or 7.2 million tons, to 208.3 million tons
pretax charges of $10.2 million for COVID-19 pandemic direct incremental costs
Net earnings were $584.5 million, a decrease of $33.2 million, or 5%
Our best-in-class aggregates business, along with the efforts and dedication of our employees, allowed us to overcome COVID-19 related disruptions in 2020.
As we saw in 2020, demand for our products can be subject to market fluctuations outside of our control.
We remain focused on the factors within our control, including our pricing and cost actions, both of which contributed to further improvement in our industry-leading unit margins in 2020.
Most impressive, we delivered year-over-year gains in aggregates unit profitability throughout each quarter in 2020.
Our ability to leverage our four strategic disciplines — Commercial and Operational Excellence, Logistics Innovation and Strategic Sourcing — enabled us to expand unit margins, deliver improved cash flows, and increase returns on invested capital.
Our team’s hard work along with our leading market positions and strong financial foundation will enable us to capitalize on an improving demand outlook in 2021.
Our operating plans are underpinned by our aforementioned four strategic disciplines, a healthy balance sheet, strong liquidity, and the engagement of our people.
2020 revenues were $4,856.8 million, 1% lower than the prior year, while gross profit margins expanded across each segment.
Effective cost management throughout the organization and aggregates price growth helped drive margin expansion.
Net earnings were $584.5 million and Adjusted EBITDA was a record $1,323.5 million.
At year end, total debt to 2020 Adjusted EBITDA was 2.5 times or 1.6 times on a net debt basis reflecting $1,198.0 million of cash on hand — approximately $500.0 million will be used to pay off certain debt maturities due in March 2021.
Return on invested capital increased 0.4 percentage points (40 basis points) from the prior year to 14.3%.
Operating cash flows were $1,070.4 million, up 9% versus the previous year.
Solid operating earnings growth coupled with disciplined capital management led to these results.
Our balanced approach to capital allocation remains unchanged.
Through economic cycles we intend to balance reinvestment in our business, growth through acquisitions, and return of capital to shareholders while maintaining financial strength and flexibility evidenced by our strong balance sheet and investment-grade credit ratings.
This capital requirement expands and contracts as production and shipment levels change.
During the fourth quarter of 2020, we restarted planned growth projects that were put on hold in March 2020 as a result of the pandemic.
Our third priority is growing the dividend with a keen focus on sustainability through the economic cycle.
During 2020, we paid a dividend per share of $1.36 and paid total dividends of $180.2 million.
Construction employment gains in key markets are a positive signal that activity levels are recovering across our footprint, as compelling fundamentals in residential construction support growing demand in 2021.
Shipments into private nonresidential continue to benefit from growth in heavy industrial projects such as data centers and warehouses, while construction starts in other categories remain below the prior year.
Recent improvements in highway lettings and contract awards indicate growing confidence and visibility fueling advancement of planned projects, particularly in the second half of 2021.
The pricing environment remains positive and we continue to execute at a high level — positioning us well for 2021.
We are encouraged by the continued strength in residential construction activity, particularly single-family housing.
Our expectation is also supported by the recent improvement in highway awards and construction employment trends in key markets.
Data centers, distribution centers, and warehouses, which now comprise the largest share of new private nonresidential project awards, will continue to underpin demand in this end market.
We believe these leading indicators, along with sustaining a positive pricing environment, can be a catalyst for further recovery in construction activity during 2021.
Aggregates shipments down 2% to up 2% versus 2020
No major changes in COVID shelter-in-place restrictions
Total revenues increased $546.2 million, or 12%, to $4,929.1 million
Aggregates segment sales increased $476.6 million, or 14%, to $3,990.3 million
Shipments increased 7%, or 14.1 million tons, to 215.5 million tons
Same-store shipments increased 6%, or 12.2 million tons, to 213.5 million tons
Same-store freight-adjusted sales price increased 6%, or $0.74 per ton
$0.6 million of tax expense related to the Tax Cuts and Jobs Act (TCJA)
pretax interest charges of $7.4 million related to the January and March early debt retirements
pretax gains of $2.3 million for business interruption claims
Net earnings were $617.7 million, an increase of $101.9 million, or 20%
2019 marked another year of strong earnings growth and cash generation.
We are particularly proud of our people who worked hard to achieve these results while ensuring another year of world class safety performance.
Widespread improvements in pricing helped drive 8% growth in our industry-leading unit profitability (gross profit per ton) in aggregates and double-digit growth in Adjusted EBITDA.
Industry leadership in safety and pace-setting unit margins are both evidence of a strong and healthy business.
Going forward, our compounding unit margins and our disciplined capital allocation position us well to increase our cash flows and improve our return on invested capital.
Full year revenues were $4.9 billion, up 12% as compared to the prior year, and net earnings were $617.7 million, an increase of 20%.
At year end, total debt was $2.8 billion, or 2.2 times 2019 Adjusted EBITDA.
As the leading aggregates producer in the U.S., we are well positioned for continued top line growth, particularly as federal, state and local governments increase spending on public infrastructure construction, while demand for private sector projects gain momentum.
In addition, our keen focus on operational excellence, cost control and disciplined investment should enable us to enhance profitability and drive sustainable, long-term shareholder value.
We will continue to make disciplined investments in organic and acquisition-led growth, while continuing to emphasize capital returns and cost control.
We are completely focused on actions that improve returns to our shareholders.
We seek continuous, compounding improvement, generating big results through small actions.
deploying operating capital to sustain our franchise
maintaining the financial strength and flexibility needed through the cycle
strategic growth through mergers and acquisitions and internal development
returning excess cash to shareholders through a healthy mix of sustainable dividend growth and stock repurchases
Our capital allocation and investment-grade rating priorities remain unchanged.
For the full year, capital expenditures were $404.3 million.
We continue to pursue opportunities for value-creating acquisitions, swaps and greenfield investments.
We remain active in the pursuit of bolt-on acquisitions and other value-creating growth investments.
These acquisitions strengthened both our aggregates position in Tennessee and our ready-mixed concrete position in Virginia.
Demand in our markets will continue to benefit from higher levels of highway funding and continued growth in residential and nonresidential markets.
Residential construction should continue to strengthen after some softness in certain of our markets during the second half of 2019.
Private nonresidential construction activity should also improve as leading indicators point to positive growth in 2020.
Demand fundamentals, including population and employment growth, continue to support longer-term growth in residential and nonresidential construction.
We are seeing a positive pricing environment driven by shipment momentum in private demand and visibility of public demand.
This visibility to demand growth sets the stage for solid price improvement in 2020.
Price improvement coupled with our four strategic initiatives (operational excellence, strategic sourcing, commercial excellence and logistics innovation) should continue to increase unit profitability.
Aggregates shipments growth of 2% to 4%
Additionally, we expect to spend approximately $275 million on maintenance capital and $200 million for internal growth projects that are largely underway.
In summary, we expect another year of strong earnings growth in 2020.
An excerpt. Shown here: 40 of 292 rewritten, 40 of 190 added and 40 of 153 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT'S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2020 filing and the FY2019 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
3 rewritten, 0 added, 2 removed, 17 unchanged
At December 31, [removed: 2019,] [added: 2020,] the estimated fair value of our long-term debt including current maturities was [removed: $3,073.7] [added: $3,959.0] million compared to a face value of [removed: $2,846.4] [added: $3,357.9] million.
The effect of a decline in interest rates of one percentage point would increase the fair value of our debt by approximately [removed: $305.4] [added: $414.9] million.
| Part II | [removed: 63] [added: 67] |
Over time, our EBITDA and operating income are positively correlated to floating interest rates (as measured by 3-month LIBOR).
As such, our business serves as a natural hedge to rising interest rates, and floating-rate debt serves as a natural hedge against weaker operating results due to general economic weakness.
Item 1. BUSINESS
76 rewritten, 64 added, 27 removed, 277 unchanged
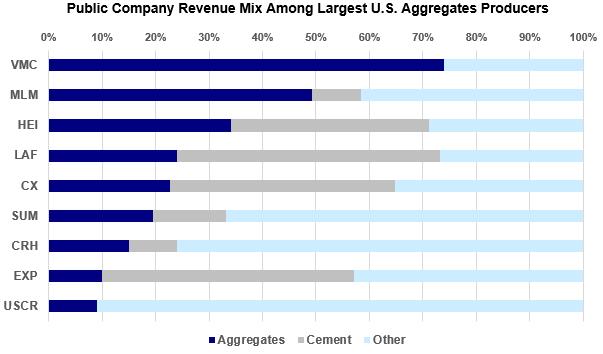
Vulcan Materials [removed: Company, a New Jersey corporation,] [added: Company] operates primarily in the U.S. and is the nation’s largest supplier of construction aggregates (primarily crushed stone, sand and [removed: gravel) and] [added: gravel),] a major producer of asphalt mix and ready-mixed [removed: concrete.][added: concrete, and a supplier of construction paving services.]
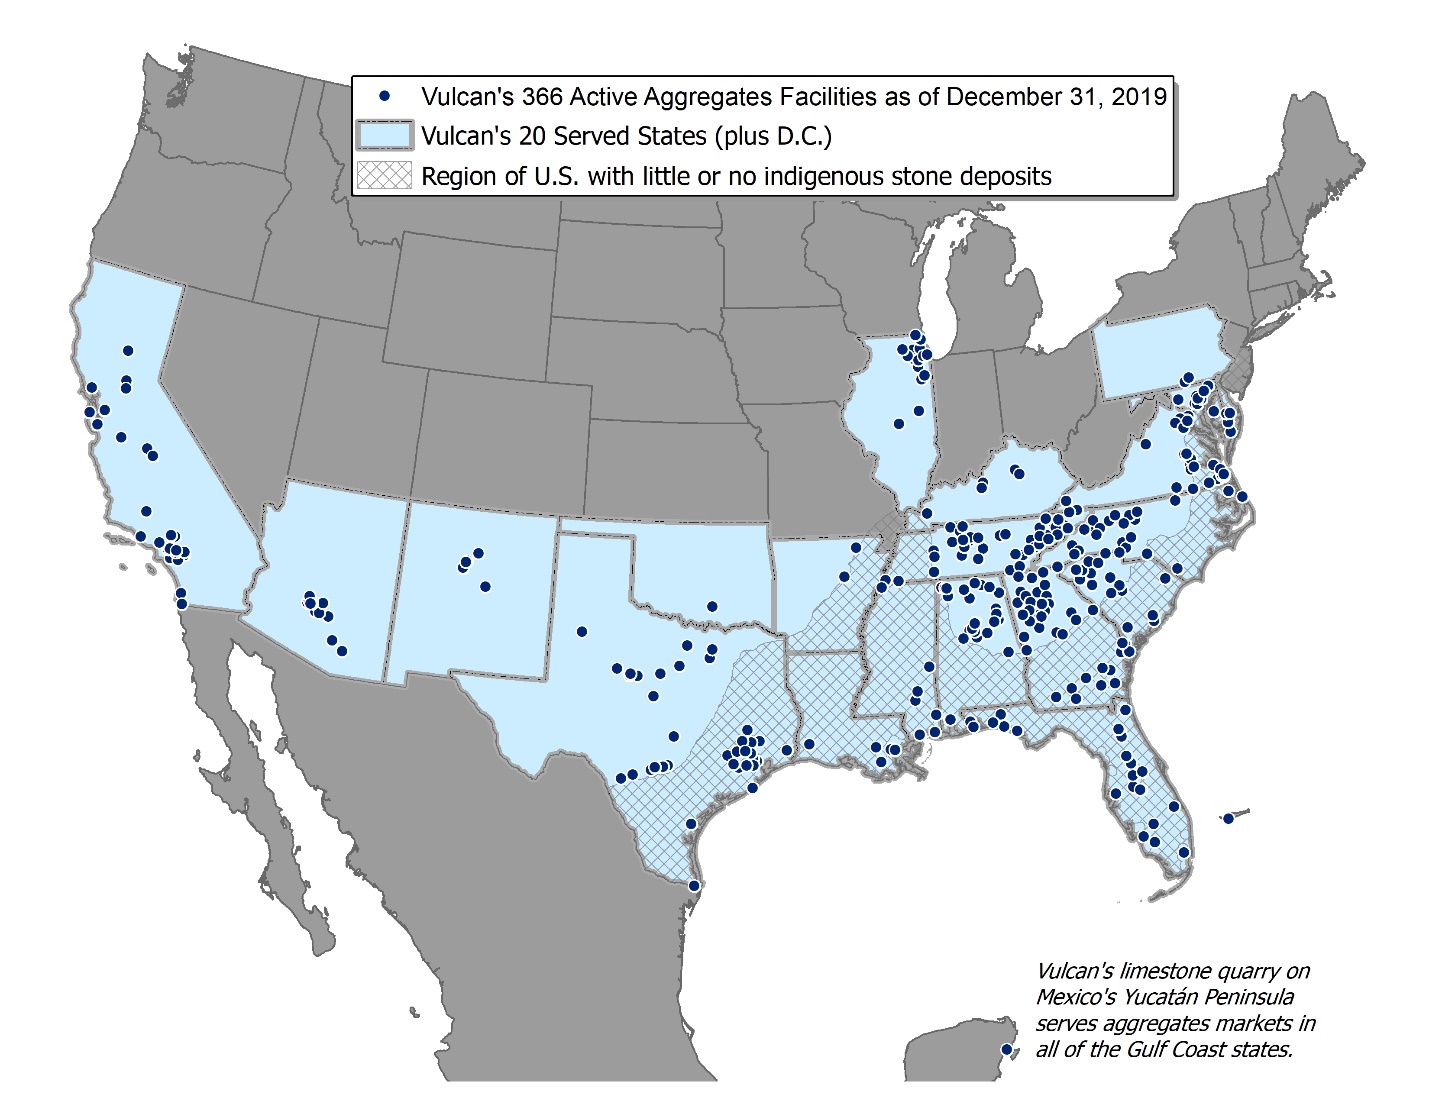
As of December 31, [removed: 2019,] [added: 2020,] we had [removed: 366] [added: 380] active aggregates facilities, 70 asphalt facilities and [removed: 53] [added: 46] concrete facilities.
Our strategy for long-term value creation is built on: (1) an aggregates\-focused business, (2) a disciplined approach to [removed: portfolio] [added: growth] management and capital allocation, (3) a focus on continuous compounding improvement in profitability, (4) a holistic approach to land management, and (5) our commitment to safety, health and the environment.
][added: 11](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg001.jpg)]
*Source: [removed: 2018] [added: 2019] reported financial information and Company estimates*
Aggregates are used in virtually all types of public and private construction, [removed: and] practically no substitutes for quality aggregates [removed: exist.][added: exist, and significant barriers to entry exist in most markets.]
[removed: nTAKE ADVANTAGE OF SIZE AND SCALE:] Our [removed: 366] [added: 380] active aggregates facilities as of December 31, [removed: 2019] [added: 2020] provide opportunities to [removed: standardize operating] [added: share and scale best] practices [added: across our operations] and [added: to] procure equipment (fixed and mobile), parts, supplies and services in an efficient and cost-effective manner, both regionally and nationally.
We currently have [removed: 16.2] [added: 15.9] billion tons of permitted and proven or probable aggregates reserves.
[removed: PORTFOLIO MANAGEMENT] [added: Growth management] AND CAPITAL ALLOCATION
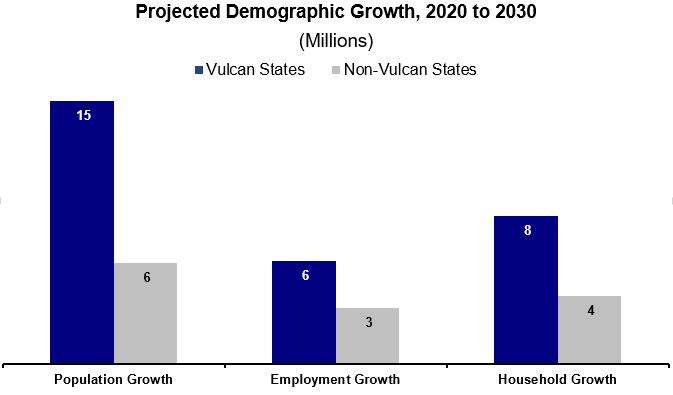
[added: growth management:] Demand for our products is dependent on construction activity and correlates positively with changes in population growth, household formation and employment.
During the period 2020 - 2030, Moody's Analytics projects that [removed: 72%] [added: 73%] of the U.S. population growth, [removed: 68%] [added: 70%] of household formation and [removed: 65%] [added: 61%] of new jobs will occur in Vulcan-served states.
][added: 41](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg002.jpg)]
*Source: Moody’s Analytics as of December [removed: 12, 2019*][added: 10, 2020*]
[removed: We] [added: As such, we] have pursued a strategy to increase our presence in U.S. metropolitan areas that are expected to grow the most rapidly and to divest assets that are no longer considered part of our long-term growth strategy.
Our coast-to-coast footprint serves 19 of the top 25 highest-growth [removed: U.S.] metropolitan [added: statistical] areas in 20 states plus the District of Columbia.
Our top ten revenue producing states accounted for [removed: 87%] [added: 88%] of our [removed: 2019] [added: 2020] revenues while our top five accounted for 61%.
| | VULCAN’S TOP TEN REVENUE PRODUCING STATES IN [removed: 2019] [added: 2020] | | | | | | | | | | | |
| | [removed: 3.] [added: 4.] | [removed: Virginia] [added: Georgia] | | | | [removed: 8.] [added: 9.] | | North Carolina | | | | |
| | [removed: 4.] [added: 3.] | Tennessee | | | | [removed: 9.] [added: 8.] | | Alabama | | | | |
| | 5. | [removed: Georgia] [added: Virginia] | | | | 10. | | South Carolina | | | | |
[removed: portfolio management:] Since becoming a public company in 1956, Vulcan has principally grown by mergers and acquisitions.
In 2007, we acquired Florida Rock Industries, [removed: Inc. This acquisition expanded] [added: Inc., expanding] our aggregates business in Florida and our aggregates and ready-mixed concrete businesses in other Mid-Atlantic and Southeastern states.
In 2017, we acquired Aggregates [removed: USA — this acquisition] [added: USA,] greatly [removed: expanded] [added: expanding] our ability to serve customers in Florida, Georgia and South Carolina.
[removed: capital allocation:] Our [removed: long-term strategy around capital allocation has] [added: strategic priorities have] given us the ability to leverage decisions we have made over the past few years.
During [removed: 2019,] [added: 2020,] we reinvested [removed: $384.1] [added: $360.8] million into core operating & maintenance capital and internal growth capital, in addition to [removed: $469.1] [added: $384.1] million and [removed: $459.6] [added: $469.1] million reinvested in [removed: 2018] [added: 2019] and [removed: 2017,] [added: 2018,] respectively.
Our focus on the following four strategic [removed: initiatives] [added: disciplines] has made us one of the most profitable public companies in the industry (as measured by aggregates gross profit per ton).
Strategic Sourcing — Leveraging common practices and innovation leads to more time in our plants and with our suppliers to [added: deliver the right parts and services at the right time and] optimize the total cost of [removed: ownership (right part at the right time).][added: ownership.]
We manage these [removed: initiatives] [added: disciplines] locally and align our talent and incentives accordingly.
Our products are used to build the roads, tunnels, bridges, railroads and airports that connect us, and to build the hospitals, schools, shopping centers, factories and places of worship that are essential to our [removed: lives] [added: lives, our communities] and the economy.
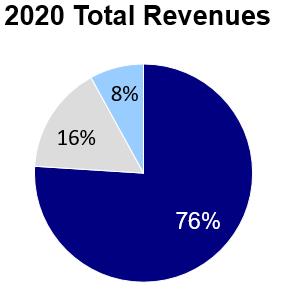
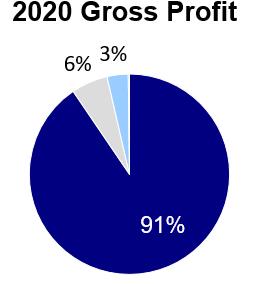
Our [removed: 2019] [added: 2020] total revenues and gross profit by segment are illustrated as follows (Calcium revenues and gross profit were less than one percent):
[removed: |] 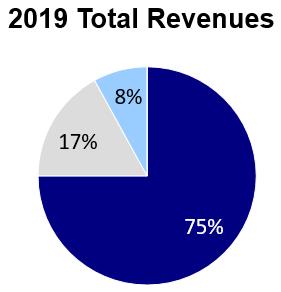 | 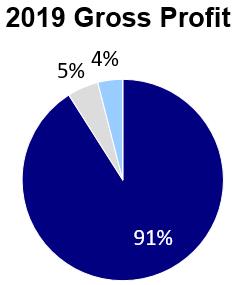 |][added: 43](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg003.jpg)]
| ] [added: 3](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg006.jpg)] | |
Highly fragmented industry: The U.S. aggregates industry is composed of over [removed: 5,800] [added: 5,000] companies that manage close to [removed: 10,000] [added: 11,000] operations.
We have over 23,000 customers in 20 states, the District of [removed: Columbia, Mexico] [added: Columbia] and [removed: the Bahamas.][added: Mexico.]
While short-term and medium-term demand for aggregates fluctuates with economic cycles, declines have historically been followed by strong [removed: recoveries, with each peak establishing a new historical high.][added: recoveries.]
The drivers underpinning [added: long-term] demand [removed: recovery —] and [removed: sustained, multi-year volume and] [added: sustained] pricing growth [removed: —] remain firmly in place, in both the public and private sectors of the economy.
They include: population growth; gains in total employment [added: (short-term disruption due to COVID-19 pandemic)] and in household income and wages; a continuing increase in household formations; the growing need for additional housing stock and housing demand; a multi-year federal transportation law in place and continuing increases in transportation funding at state and local levels; [removed: record] [added: stable] state tax receipts; public investment in infrastructure that is still well below the long-term [removed: trend-line,] [added: trend-line;] and increasing political awareness and acceptance of the need to invest in infrastructure.
Public sector construction activity has historically been more stable and less cyclical than privately-funded construction, and [added: it] generally requires more aggregates per dollar of construction spending.
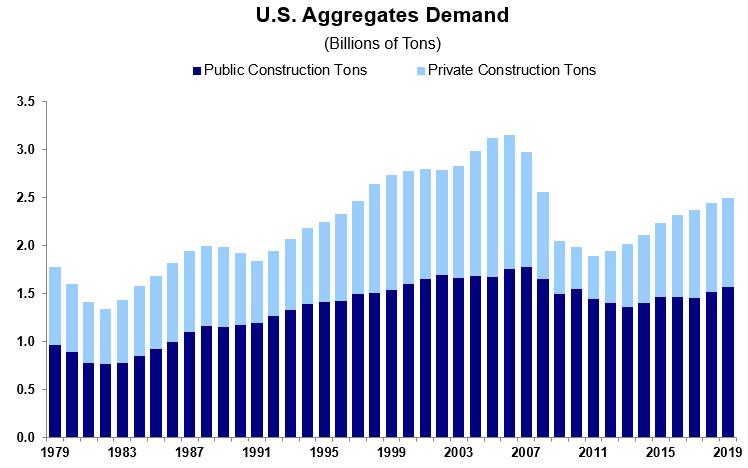][added: 54](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg007.jpg)]
In [removed: 2019,] [added: 2020,] publicly-funded construction accounted for approximately [removed: 44%] [added: 43%] of our total aggregates shipments, and approximately 23% of our aggregates sales by volume were used in highway construction projects.
nTAKE ADVANTAGE OF SIZE AND SCALE: While certain aspects of each aggregates operation are unique, such as its location within a local market and its particular geological characteristics, every operation uses a similar group of assets to produce saleable aggregates and provide customer service.
For example, during 2020 we acquired asphalt operations in Texas expanding our already strong presence in that market.
From 2018 to 2020, we invested over $300 million in acquisitions as outlined in Note 19 “Acquisitions and Divestitures” in Item 8 “Financial Statements and Supplementary Data.”
capital allocation: Our long-term capital allocation strategy is focused on the following priorities:
Operating Capital (maintain and grow the value of our franchise)
Growth Capital (including greenfields and acquisitions)
Dividend Growth (with a keen focus on sustainability)
Return Excess Cash to Shareholders (primarily via share repurchases)
As illustrated below, our annual Return on Invested Capital (ROIC) increased 0.4 percentage points (40 basis points) in 2020 as a 4% increase in Adjusted EBITDA (net earnings decreased 5% in 2020) was leveraged with disciplined capital management (average invested capital only increased 1%).
| *1* | *ROIC and Adjusted EBITDA are Non-GAAP financial measures. Non-GAAP financial measures are defined and reconciled within Item 7 under the caption Reconciliation of Non-GAAP Financial Measures.* |
|  |  |
Most recently, in 2020 the Virginia legislature raised its statewide gas tax, and voters in Arkansas renewed a ½ cent sales tax measure originally approved in 2012, to provide significant revenue for highway construction and maintenance through motor fuel tax increases.
President Trump signed a one-year extension of the FAST Act into law in 2020.
In addition, for FFY 2021, state departments of transportation were allocated $10 billion in emergency aid from the $900 billion Coronavirus Response and Relief Supplemental Appropriations Act, a COVID-19 relief measure passed by Congress in December 2020 as part of a final year-end legislative package.
FEDERAL WATER INFRASTRUCTURE: In December 2020, President Trump signed the Water Resources Development Act of 2020 (WRDA 2020) into law, enacting the fourth consecutive biennial authorization for the U.S. Army Corps of Engineers (Army Corps) since 2014.
The FFY 2021 appropriations for the Corps, also passed as part of the year-end legislative package, funds for the first time the Army Corps Water Infrastructure Financing Program (CWIFP), which was authorized in the Water Resources Reform and Development Act of 2014 (WRRDA 2014).
Modeled after the highly popular TIFIA program in the surface transportation sector, CWIFP will accelerate non-federal investments in water resources infrastructure by providing long-term, low-cost loans to creditworthy borrowers.
In October 2020, we strengthened our asphalt position in Texas by acquiring additional asphalt operations.
We are subject to a wide variety of federal, state and local laws and regulations in the communities where we conduct business.
Compliance with these laws and regulations often requires the time and effort of our employees, as well as financial resources.
The following describes certain significant regulations that may impact our business.
For additional information about our risks related to government regulations, see Item 1A “Risk Factors.”
HUMAN CAPITAL
Vulcan’s commitment to our people has played a key role in the ongoing success and growth of our company throughout our long history.
We are dedicated to fostering a culture of mutual respect, integrity, teamwork and trust among our workforce.
Our people share a competitive drive to be the best they can be and do the right thing, which benefits all our stakeholders.
Diversity and inclusion are important values at Vulcan.
Our continued investment in people and strong commitment to diversity and inclusion will help us attract, grow and retain the best talent possible.
In 2015, we escalated and formalized our efforts in this area with the launch of our Diversity and Inclusion Council to promote an open workplace where everyone, regardless of background, race, or other factors is free to contribute and grow.
In 2019, we signed the CEO Action for Diversity & InclusionTM pledge and we forged a long-term partnership with Historically Black Colleges and Universities (HBCUs) to support our future leaders in our communities and on our team.
As a result of our commitment to diversity and inclusion we have:
Cultivated a diverse talent pipeline of next generation leaders through our operations/sales trainee program
Expanded the diversity of our workforce at middle management and higher levels
Increased the number of female hires and promotions in senior leadership roles
Developed a five-year strategy through our Diversity and Inclusion Council
Built partnerships with HBCUs to recruit talented minority students for internships and management training roles
Today, approximately 38% of our workforce is diverse, and we have a number of initiatives to continue building a diverse and inclusive workforce.
We have more than doubled the number of diverse Division and Corporate officers since 2013.
Our Board of Directors is 36% diverse; and, we earned recognition in 2017 by *2020 Women on Boards* for having 20% or more of our board seats held by women.
We believe that learning is fundamental to every job and we encourage our people to expand and explore their capabilities for continued growth.
Each aggregates operation is also unique because of its location within a local market and its particular geological characteristics.
Every operation, however, uses a similar group of assets to produce saleable aggregates and provide customer service.
For example, during 2019 we expanded our Virginia ready-mixed concrete operations.
From 2017 to 2019, we invested over $1.1 billion in acquisitions, while further strengthening our portfolio through divestitures and swaps, including swapping our concrete operations in Arizona for asphalt operations in Arizona during 2017.
In 2019, Alabama and Illinois became the two most recent states in Vulcan’s footprint to raise significant revenue for highway construction and maintenance through motor fuel tax increases.
FEDERAL WATER INFRASTRUCTURE: In October 2018, President Trump signed America’s Water Infrastructure Act of 2018 (AWIA 2018) into law.
Included in AWIA 2018 are improvements to the Water Infrastructure Finance and Innovation Act (WIFIA) program, which was modeled after the highly popular TIFIA program in the surface transportation sector.
Created in the Water Resources Reform and Development Act of 2014 (WRRDA 2014), WIFIA allows for federal credit assistance to water resources projects in the form of low-cost loans, loan guarantees and lines of credit.
In addition to these regular authorizations, federal emergency supplemental appropriations were provided in 2018 in the Bipartisan Budget Act of 2018 for hurricane-affected areas in Florida, Louisiana, Texas and other states ($89.3 billion) and in the Additional Supplement Appropriations for Disaster Relief Act in 2019 ($19.9 billion).
A portion of these funds will be directed to long-term and short-term U.S. Army Corps of Engineers-supported flood control and other water resources construction projects as well as additional infrastructure projects that use aggregates and related materials.
In December 2017, we strengthened our asphalt position in Arizona by swapping ready-mixed concrete operations for an asphalt mix operation.
In January 2017, we entered the Tennessee asphalt market through the acquisition of several asphalt mix operations and a construction paving business.
As noted above, in December 2017 we exited the Arizona ready-mixed concrete market via a swap for an asphalt mix operation, continuing our strategy to focus on asphalt mix in that market.
In March 2017, we reentered the California ready-mixed concrete market through an acquisition.
The fair value of such obligations is capitalized and depreciated over the estimated useful life of the owned or leased site.
The liability is accreted through charges to operating expenses.
All reclamation obligations are reviewed at least annually.
For additional information about reclamation obligations (referred to in our financial statements as asset retirement obligations), see Notes 1 and 17 to the consolidated financial statements in Item 8 “Financial Statements and Supplementary Data.”
PATENTS AND TRADEMARKS
We do not own or have a license or other rights under any patents, registered trademarks or trade names that are material to any of our reporting segments.
OTHER INFORMATION ABOUT VULCAN
Vulcan is a New Jersey corporation incorporated on February 14, 2007, while its predecessor company was incorporated on September 27, 1956.
Our principal sources of energy are electricity, diesel fuel and natural gas.
We do not anticipate any difficulty in obtaining sources of energy required for operation of any of our reporting segments in 2020.
| Vulcan Materials Company | | | | | | $ 100.00 | | | $ 145.10 | | | $ 192.55 | | | $ 199.09 | | | $ 154.70 | | | $ 227.56 | |
| S&P 500 | | | | | | $ 100.00 | | | $ 101.40 | | | $ 113.57 | | | $ 138.33 | | | $ 132.24 | | | $ 173.89 | |
| Wilshire 5000 M&S | | | | | | $ 100.00 | | | $ 104.80 | | | $ 116.75 | | | $ 148.97 | | | $ 137.80 | | | $ 183.68 | |
An excerpt. Shown here: 40 of 76 rewritten, 40 of 64 added and all 27 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2020 filing and the FY2019 filing.
Item 3. LEGAL PROCEEDINGS
1 rewritten, 0 added, 0 removed, 6 unchanged
We were not subject to any penalties in [removed: 2019] [added: 2020] for failure to disclose transactions identified by the Internal Revenue Service as abusive under Internal Revenue Code Section 6707A.
Cover and table of contents
25 rewritten, 3 added, 2 removed, 74 unchanged
| þ | ANNUAL REPORT PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934 For the Fiscal Year Ended December 31, [removed: 2019] [added: 2020] OR | | | | |
| Aggregate market value of voting and non-voting common stock held by non-affiliates as of June [removed: 28, 2019:] [added: 30, 2020:] | [removed: $18,124,821,274] [added: $15,315,526,050] |
| Number of shares of common stock, $1.00 par value, outstanding as of February [removed: 13, 2020:] [added: 12, 2021:] | [removed: 132,394,732] [added: 132,547,092] |
| Portions of the registrant’s annual proxy statement for the annual meeting of its shareholders to be held on May [removed: 8, 2020,] [added: 14, 2021,] are incorporated by reference into Part III of this Annual Report on Form 10-K. | |
| VULCAN MATERIALS COMPANY ANNUAL REPORT ON FORM 10-k fISCAL YEAR ENDED DECEMBER 31, [removed: 2019] [added: 2020] CONTENTs | | | |
| | 1A | [Risk Factors](#PartI_Item1A) | [removed: 17] [added: 19] |
| | 1B | [Unresolved Staff Comments](#PartI_Item1B) | [removed: 21] [added: 24] |
| | 2 | [Properties](#PartI_Item2) | [removed: 22] [added: 25] |
| | 3 | [Legal Proceedings](#PartI_Item3) | [removed: 25] [added: 28] |
| | 4 | [Mine Safety Disclosures](#PartI_Item4) | [removed: 25] [added: 28] |
| | — | [Information about our Executive Officers](#Executive_Officers) | [removed: 26] [added: 29] |
| II | 5 | [Market for the Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities](#PartII_Item5) | [removed: 27] [added: 31] |
| | 7 | [Management’s Discussion and Analysis of Financial Condition and Results of Operations](#PartII_Item7) | [removed: 29] [added: 32] |
| | 7A | [Quantitative and Qualitative Disclosures about Market Risk](#PartII_Item7A) | [removed: 63] [added: 67] |
| | 8 | [Financial Statements and Supplementary Data](#PartII_Item8) | [removed: 64] [added: 68] |
| | 9 | [Changes in and Disagreements with Accountants on Accounting and Financial Disclosure](#PartII_Item9) | [removed: 119] [added: 123] |
| | 9A | [Controls and Procedures](#PartII_Item9A) | [removed: 119] [added: 123] |
| | 9B | [Other Information](#PartII_Item9B) | [removed: 121] [added: 125] |
| III | 10 | [Directors, Executive Officers and Corporate Governance](#PartIII_Item10) | [removed: 122] [added: 126] |
| | 11 | [Executive Compensation](#PartIII_Item11) | [removed: 122] [added: 126] |
| | 12 | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters](#PartIII_Item12) | [removed: 122] [added: 126] |
| | 13 | [Certain Relationships and Related Transactions, and Director Independence](#PartIII_Item13) | [removed: 122] [added: 126] |
| | 14 | [Principal Accounting Fees and Services](#PartIII_Item14) | [removed: 122] [added: 126] |
| IV | 15 | [Exhibits and Financial Statement Schedules](#PartIV_Item15) | [removed: 123] [added: 127] |
| | 16 | [Form 10-K Summary](#PartIV_Item16) | [removed: 128] [added: 132] |
| Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report. þ | | | | | |
| | — | [Signatures](#Signatures) | 133 |
a pandemic, epidemic or other public health emergency, such as the recent outbreak of COVID-19
| | 6 | [Selected Financial Data](#PartII_Item6) | 28 |
| | — | [Signatures](#Signatures) | 129 |
Item 1B. UNRESOLVED STAFF COMMENTS
1 rewritten, 0 added, 0 removed, 4 unchanged
| Part I | [removed: 21] [added: 24] |
Item 2. PROPERTIES
33 rewritten, 16 added, 15 removed, 57 unchanged
As the largest U.S. supplier of construction aggregates, we serve markets in twenty states, Washington D.C. and the local [removed: markets] [added: market] surrounding our [removed: operations] [added: operation] in [removed: Mexico and the Bahamas.][added: Mexico.]
][added: 31](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg014.jpg)]
Our current estimate of [removed: 16.2] [added: 15.9] billion tons of proven and probable aggregates reserves reflects a decrease of [removed: 0.1] [added: 0.3] billion tons from the prior year’s estimate.
Estimates of reserves are of recoverable stone, sand and gravel of suitable quality for economic extraction, based on drilling and studies by our geologists and engineers, recognizing reasonable economic and operating constraints as to maximum depth of overburden and stone excavation, and subject to permit or other [removed: restrictions.][added: restrictions,.]
| Part I | [removed: 22] [added: 25] |
The [removed: 16.2] [added: 15.9] billion tons of estimated proven and probable aggregates reserves reported at the end of [removed: 2019] [added: 2020] include reserves at inactive and greenfield (undeveloped) sites.
The table below presents, by division, the tons of proven and probable aggregates reserves as of December 31, [removed: 2019] [added: 2020] and the types of facilities operated.
| | | | *Aggregates Reserves* | | | | | | | | | [removed: 2019] [added: 2020] | | | | | | *Sand and* | | | | |
| *1* | *The divisions are defined by states/countries as follows:* *Central Division* — *Arkansas, Illinois, Kentucky and Tennessee* *International Division* — *Mexico* *Mideast Division* — *Delaware, Maryland, North Carolina, Pennsylvania, Virginia and Washington D.C.* *Mountain West Division* — *Arizona and New Mexico* *Southeast Division* — *Florida (excluding panhandle), [removed: Georgia, South Carolina] [added: Georgia] and [removed: the Bahamas*] [added: South Carolina*] *Southern Gulf Coast Division* — *Alabama, Florida Panhandle, Louisiana and Mississippi* *Southwest Division* — *Oklahoma and Texas* *Western Division* — *California* | |
| *2* | *In addition to [removed: the* *aggregates* *facilities] [added: the aggregates facilities] included in the table above, we [removed: operated* *46 recycled* *concrete] [added: operated 50 recycled concrete] plants which are not dependent on reserves.* | |
| *3* | *Includes a maximum [removed: of* *327.0* *million] [added: of 314.2 million] tons of reserves [removed: encumbered* *by volumetric] [added: encumbered by volumetric] production [removed: payments* *as] [added: payments as] defined in [removed: Note* *2* *“Revenues”] [added: Note 2 “Revenues”] in Item 8 “Financial Statements and Supplementary [removed: Data.”*] [added: Data.”*] | |
Of the [removed: 16.2] [added: 15.9] billion tons of aggregates reserves at December 31, [removed: 2019, 9.1] [added: 2020, 9.2] billion tons or [removed: 56%] [added: 58%] are located on owned land and [removed: 7.1] [added: 6.7] billion tons or [removed: 44%] [added: 42%] are located on leased land.
| Part I | [removed: 23] [added: 26] |
None of our aggregates [removed: facilities, other than Playa del Carmen,] [added: facilities] contributed more than 5% to our total revenues in [removed: 2019.][added: 2020.]
| Playa del Carmen (Cancun), Mexico | | | | | | | | | | [removed: 540.2] [added: 529.5] | | | 0.0 | | | [removed: 540.2] [added: 529.5] | | | [removed: 14.0] [added: 11.4] | |
| Hanover (Harrisburg), Pennsylvania | | | | | | | | | | [removed: 223.6] [added: 221.5] | | | 236.4 | | | [removed: 460.0] [added: 457.9] | | | [removed: 2.8] [added: 2.0] | |
| McCook (Chicago), Illinois | | | | | | | | | | [removed: 101.2] [added: 96.8] | | | 266.5 | | | [removed: 367.7] [added: 363.3] | | | [removed: 4.7] [added: 4.4] | |
| Postell (Macon), Georgia | | | | | | | | | | [removed: 190.9] [added: 186.5] | | | 72.3 | | | [removed: 263.2] [added: 258.8] | | | [removed: 4.5] [added: 4.6] | |
| San Emidio (Bakersfield), California | | | | | | | | | | [removed: 250.0] [added: 28.5] | | | [removed: 0.0] [added: 221.5] | | | 250.0 | | | [removed: 1.4] [added: 0.9] | |
| Medina (San Antonio), Texas | | | | | | | | | | [removed: 247.3] [added: 244.6] | | | 0.0 | | | [removed: 247.3] [added: 244.6] | | | [removed: 1.0] [added: 2.8] | |
| Norcross (Atlanta), Georgia | | | | | | | | | | [removed: 183.4] [added: 180.2] | | | 27.7 | | | [removed: 211.1] [added: 207.9] | | | [removed: 3.6] [added: 3.4] | |
As of December 31, [removed: 2019,] [added: 2020,] we operated a number of facilities producing asphalt mix, ready-mixed concrete and calcium in several of our divisions as reflected in the table below:
| | | | | | | | | | | | | | | | *Asphalt* *2* | | | *Concrete* [removed: *3*] | | | *Calcium* [removed: *4*] [added: *3*] | |
| Central | | | | | | | | | | | | | | | [removed: 11] [added: 10] | | | 0 | | | 0 | |
| Mideast | | | | | | | | | | | | | | | 0 | | | [removed: 39] [added: 36] | | | 0 | |
| Mountain West | | | | | | | | | | | | | | | [removed: 20] [added: 21] | | | [removed: 2] [added: 0] | | | 0 | |
| Southeast | | | | | | | | | | | | | | | 0 | | | [removed: 1] [added: 0] | | | 1 | |
| Western | | | | | | | | | | | | | | | 22 | | | [removed: 4] [added: 3] | | | 0 | |
| Total | | | | | | | | | | | | | | | 70 | | | [removed: 53] [added: 46] | | | 1 | |
| [removed: *4*] [added: *3*] | *Comprised of a* *ground* *calcium plant.* |
| Part I | [removed: 24] [added: 27] |
| Brooksville | | | | | | | | | | | | [removed: 4.8] [added: 4.5] | | | 7.1 | | | [removed: 11.9] [added: 11.6] | | | 0.3 | |
The Brooksville limestone quarry has an average calcium carbonate (CaCO3) content of [removed: 97%.][added: 98.0%.]
| Central | | | 2,301.3 | | | 820.4 | | | 3,121.7 | | | 32.7 | | | 55 | | | 5 | | | 8 | |
| International | | | 529.5 | | | 0.0 | | | 529.5 | | | 11.4 | | | 1 | | | 0 | | | 0 | |
| Mideast | | | 2,422.8 | | | 981.2 | | | 3,404.0 | | | 34.0 | | | 37 | | | 4 | | | 24 | |
| Mountain West | | | 216.1 | | | 112.8 | | | 328.9 | | | 8.7 | | | 2 | | | 13 | | | 2 | |
| Southeast 3 | | | 2,952.9 | | | 871.7 | | | 3,824.6 | | | 50.1 | | | 45 | | | 8 | | | 24 | |
| Southern Gulf Coast | | | 1,804.1 | | | 52.4 | | | 1,856.5 | | | 23.1 | | | 24 | | | 0 | | | 19 | |
| Southwest | | | 1,377.8 | | | 0.0 | | | 1,377.8 | | | 24.3 | | | 16 | | | 1 | | | 24 | |
| Western | | | 761.9 | | | 737.4 | | | 1,499.3 | | | 18.8 | | | 5 | | | 12 | | | 1 | |
| Total | | | 12,366.4 | | | 3,575.9 | | | 15,942.3 | | | 203.1 | | | 185 | | | 43 | | | 102 | |
| | | | | | | | | | | *Reserves at 12/31/2020* | | | | | | | | | *2020* | |
| Corona (Los Angeles), California | | | | | | | | | | 10.0 | | | 320.0 | | | 330.0 | | | 2.1 | |
| Gold Hill (Charlotte), North Carolina | | | | | | | | | | 146.7 | | | 121.2 | | | 267.9 | | | 0.9 | |
| Macon, Georgia | | | | | | | | | | 115.4 | | | 128.0 | | | 243.4 | | | 2.0 | |
The Brooksville quarry is not individually material to our business.
Calcium resources and reserves are outlined in the table below:
| | | | | | | | | | | | | *Reserves at 12/31/2020* | | | | | | | | | *2020* | |
| Central | | | 2,838.9 | | | 819.6 | | | 3,658.5 | | | 38.9 | | | 53 | | | 4 | | | 9 | |
| International | | | 540.2 | | | 0.0 | | | 540.2 | | | 14.0 | | | 1 | | | 0 | | | 0 | |
| Mideast | | | 2,464.5 | | | 981.3 | | | 3,445.8 | | | 39.4 | | | 34 | | | 3 | | | 24 | |
| Mountain West | | | 173.2 | | | 119.1 | | | 292.3 | | | 9.1 | | | 2 | | | 12 | | | 2 | |
| Southeast 3 | | | 3,007.0 | | | 874.1 | | | 3,881.1 | | | 52.6 | | | 44 | | | 9 | | | 22 | |
| Southern Gulf Coast | | | 1,376.2 | | | 45.0 | | | 1,421.2 | | | 18.0 | | | 23 | | | 0 | | | 19 | |
| Southwest | | | 1,406.6 | | | 0.0 | | | 1,406.6 | | | 23.9 | | | 15 | | | 1 | | | 22 | |
| Western | | | 1,017.1 | | | 489.7 | | | 1,506.8 | | | 21.1 | | | 6 | | | 13 | | | 2 | |
| Total | | | 12,823.7 | | | 3,328.8 | | | 16,152.5 | | | 217.0 | | | 178 | | | 42 | | | 100 | |
| | | | | | | | | | | *Reserves at 12/31/2019* | | | | | | | | | *2019* | |
| Corona (Los Angeles), California | | | | | | | | | | 12.5 | | | 319.5 | | | 332.0 | | | 2.2 | |
| Gold Hill (Charlotte), North Carolina | | | | | | | | | | 147.7 | | | 121.1 | | | 268.8 | | | 1.0 | |
| Macon, Georgia | | | | | | | | | | 117.4 | | | 128.0 | | | 245.4 | | | 1.9 | |
| *3* | *Southeast Division Concrete is comprised of* *a ready-mixed concrete plant in the Bahamas.* |
| | | | | | | | | | | | | *Reserves at 12/31/2019* | | | | | | | | | *2019* | |
Item 4. MINE SAFETY DISCLOSURES
11 rewritten, 24 added, 0 removed, 37 unchanged
| Part I | [removed: 25] [added: 28] |
The names, positions and ages, as of February 20, [removed: 2020,] [added: 2021,] of our executive officers are as follows:
| J. Thomas Hill | Chairman, President and Chief Executive Officer | [removed: 60] [added: 61] |
| Suzanne H. Wood | Senior Vice President and Chief Financial Officer | [removed: 59] [added: 60] |
| Stanley G. Bass | Chief [removed: Growth] [added: Strategy] Officer | [removed: 58] [added: 59] |
| Thompson S. Baker II | Chief Operating Officer | [removed: 61] [added: 62] |
| Denson N. Franklin III | Senior Vice President, General Counsel and Secretary | [removed: 56] [added: 57] |
| Randy L. Pigg | Vice President, Controller and Principal Accounting Officer | [removed: 47] [added: 48] |
She currently serves on the board of directors and [added: is chair of the] audit committee of RELX Group, a FTSE 50 global professional information and analytics company.
Bass was elected Chief [removed: Growth] [added: Strategy] Officer in February [removed: 2016.][added: 2021.]
| Part I | [removed: 26] [added: 29] |
| David P. Clement | Senior Vice President, Mountain West and Western Divisions | 60 |
| Jerry F. Perkins Jr. | Senior Vice President, Southern & Gulf Coast and Southwest Divisions | 51 |
| Jason P. Teter | Senior Vice President, Mideast and Southeast Divisions | 46 |
She also serves on the board of directors, audit committee and nominations committee of Ferguson plc, the FTSE 100 leading distributor of plumbing and heating products.
Prior to that he served as Chief Growth Officer as of February 2016.
David P.
Clement was appointed Senior Vice President of the Mountain West and Western Divisions in March 2020.
He first joined the organization as an operations management trainee in 1983 and progressed to the position of area production manager in 1993.
After spending a few years at Pioneer Mid-Atlantic and working as a consultant, he rejoined Vulcan in 2004 as vice president and general manager of the Midwest Division.
He has held the positions of vice president of operations for the Midwest Division, vice president and general manager of the Central Region, senior vice president of the Central Region, and most recently as president of the Central Division.
Jerry F.
Perkins Jr. was appointed Senior Vice President of the Southern & Gulf Coast and Southwest Divisions in March 2020.
Prior to his current position, he was president of the Southern and Gulf Coast Division.
He also served as general counsel and corporate secretary and held various legal leadership roles for Vulcan.
Before joining Vulcan in 2002, he worked as a certified public accountant (CPA) at a global accounting firm and was an attorney with Burr & Forman LLP in Birmingham, Alabama.
Jason P.
Teter was appointed Senior Vice President of the Mideast and Southeast Divisions in March 2020.
Prior to his current position, he was president of the Southeast Division.
He joined Vulcan in 2013 as vice president of business development.
He also served as vice president of finance for Vulcan and president of the Southern and Gulf Coast Division.
Before joining Vulcan, he spent ten years in various finance, business development and general management positions with Lafarge North America.
| | |
| --- | --- |
| Part I | 30 |
Item 5. MARKET FOR REGISTRANT'S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
5 rewritten, 4 added, 4 removed, 18 unchanged
As of February [removed: 13, 2020,] [added: 12, 2021,] the number of shareholders of record was [removed: 2,474.][added: 2,379.]
Purchases of our equity securities during the quarter ended December 31, [removed: 2019] [added: 2020] are summarized below.
| *1* | [removed: *On February 10,* *2017,] [added: *In* *February 2017,] our Board of Directors authorized us to [removed: purchase up to* *8,243,243] [added: purchase* *up to 10,000,000] shares of our common [removed: stock to refresh the number of shares we were authorized to purchase to* *10,000,000.*] [added: stock.*] *As of December 31, [removed: 2019,] [added: 2020,] there were* [removed: *8,279,189*] [added: *8,064,851*] *shares remaining [removed: under* *this authorization.] [added: under this* *authorization.] Depending upon market, business, legal and other conditions, we may purchase shares* *from time to time through* *the* *open market* *(including* *plans designed to comply with Rule 10b5-1 of the Securities Exchange Act of 1934) and/or through* *privately negotiated transactions.* *The authorization has no time limit, does not obligate us to purchase any specific number of shares, and may be suspended or discontinued at any time.* | |
We did not have any unregistered sales of equity securities during the fourth quarter of [removed: 2019.][added: 2020.]
| Part II | [removed: 27] [added: 31] |
| 2020 | | | | | | | | | | | |
| Oct 1 - Oct 31 | 0 | | | $ 0.00 | | | 0 | | | 8,064,851 | |
| Nov 1 - Nov 30 | 0 | | | $ 0.00 | | | 0 | | | 8,064,851 | |
| Dec 1 - Dec 31 | 0 | | | $ 0.00 | | | 0 | | | 8,064,851 | |
| 2019 | | | | | | | | | | | |
| Oct 1 - Oct 31 | 0 | | | $ 0.00 | | | 0 | | | 8,279,189 | |
| Nov 1 - Nov 30 | 0 | | | $ 0.00 | | | 0 | | | 8,279,189 | |
| Dec 1 - Dec 31 | 0 | | | $ 0.00 | | | 0 | | | 8,279,189 | |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
622 rewritten, 257 added, 244 removed, 1,382 unchanged
We have audited the accompanying consolidated balance sheets of Vulcan Materials Company and subsidiaries (the “Company”) as of December 31, [removed: 2019] [added: 2020] and [removed: 2018,] [added: 2019,] the related consolidated statements of comprehensive income, equity, and cash flows, for each of the three years in the period ended December 31, [removed: 2019,] [added: 2020,] and the related notes (collectively referred to as the “financial statements”).
In our opinion, the financial statements present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2019] [added: 2020] and [removed: 2018,] [added: 2019,] and the results of its operations and its cash flows for each of the three years in the period ended December 31, [removed: 2019,] [added: 2020,] in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the Company's internal control over financial reporting as of December 31, [removed: 2019,] [added: 2020,] based on the criteria established in *Internal Control* *—* *Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February [removed: 26, 2020] [added: 25, 2021] expressed an unqualified opinion on the Company's internal control over financial reporting.
| Part II | [removed: 64] [added: 119] |
Specific to the Hewitt Landfill Environmental Matter, management is engaged in groundwater testing, certain remedial procedures and ongoing dialogue with federal and local agencies such as the Environmental Protection Agency (EPA), Los Angeles Regional Water Quality Control Board (RWQCB) and the Los Angeles Department of Water and Power [removed: (LADWP).][added: (LADWP) as well as other interested parties.]
Due to these uncertainties, future amounts recorded related to the ultimate resolution of claims and assessments could be material in a given period to the Company’s results of operations or cash [removed: flows.][added: flows.Evaluating the estimate of the liability and the extent and sufficiency of related disclosures is subjective in nature and as such requires significant audit effort, involves especially subjective auditing judgements, and requires the use of our environmental specialists.]
| Part II | [removed: 65] [added: 120] |
| | [removed: 2019] [added: 2020] | | | [removed: *2018*] [added: *2019*] | | | [removed: *2017*] [added: *2018*] | |
| Total revenues | $ [removed: 4,929,103] [added: 4,856,826] | | | $ [removed: 4,382,869] [added: 4,929,103] | | | $ [removed: 3,890,296] [added: 4,382,869] | |
| Cost of revenues | [removed: 3,673,202] [added: 3,575,345] | | | [removed: 3,281,924] [added: 3,673,202] | | | [removed: 2,896,783] [added: 3,281,924] | |
| Gross profit | [removed: 1,255,901] [added: 1,281,481] | | | [removed: 1,100,945] [added: 1,255,901] | | | [removed: 993,513] [added: 1,100,945] | |
| Selling, administrative and general expenses | [removed: 370,548] [added: 359,772] | | | [removed: 333,371] [added: 370,548] | | | [removed: 324,972] [added: 333,371] | |
| Gain on sale of property, plant & equipment and businesses | [removed: 23,752] [added: 3,997] | | | [removed: 14,944] [added: 23,752] | | | [removed: 17,827] [added: 14,944] | |
| Other operating expense, net | [removed: (31,647)] [added: (29,975)] | | | [removed: (34,805)] [added: (31,647)] | | | [removed: (47,324)] [added: (34,805)] | |
| Operating earnings | [removed: 877,458] [added: 895,731] | | | [removed: 747,713] [added: 877,458] | | | [removed: 639,044] [added: 747,713] | |
| Other nonoperating [removed: income,] [added: income (expense),] net | [removed: 9,243] [added: (17,540)] | | | [removed: 13,000] [added: 9,243] | | | [removed: 13,357] [added: 13,000] | |
| Interest income | [removed: 1,155] [added: 1,567] | | | [removed: 554] [added: 1,155] | | | [removed: 4,437] [added: 554] | |
| Interest expense | [removed: 130,155] [added: 135,960] | | | [removed: 137,977] [added: 130,155] | | | [removed: 295,522] [added: 137,977] | |
| Earnings from continuing operations before income taxes | [removed: 757,701] [added: 743,798] | | | [removed: 623,290] [added: 757,701] | | | [removed: 361,316] [added: 623,290] | |
| Income tax expense [removed: (benefit)] | | | | | | | | |
| Current | [removed: 58,941] [added: 93,948] | | | [removed: 40,516] [added: 58,941] | | | [removed: 354] [added: 40,516] | |
| Deferred | [removed: 76,257] [added: 61,855] | | | [removed: 64,933] [added: 76,257] | | | [removed: (232,429)] [added: 64,933] | |
| Total income tax expense [removed: (benefit)] | [removed: 135,198] [added: 155,803] | | | [removed: 105,449] [added: 135,198] | | | [removed: (232,075)] [added: 105,449] | |
| Earnings from continuing operations | [removed: 622,503] [added: 587,995] | | | [removed: 517,841] [added: 622,503] | | | [removed: 593,391] [added: 517,841] | |
| [removed: Earnings (loss)] [added: Loss] on discontinued operations, net of tax | [removed: (4,841)] [added: (3,515)] | | | [removed: (2,036)] [added: (4,841)] | | | [removed: 7,794] [added: (2,036)] | |
| Net earnings | $ [removed: 617,662] [added: 584,480] | | | $ [removed: 515,805] [added: 617,662] | | | $ [removed: 601,185] [added: 515,805] | |
| Deferred gain [added: (loss)] on interest rate derivative | [removed: 0] [added: (14,679)] | | | [removed: 2,496] [added: 0] | | | [removed: 0] [added: 2,496] | |
| Amortization of prior interest rate derivative loss | [removed: 227] [added: 1,689] | | | [removed: 226] [added: 227] | | | [removed: 1,862] [added: 226] | |
| Adjustment for funded status of benefit plans | [removed: (26,892)] [added: 6,366] | | | [removed: (207)] [added: (26,892)] | | | [removed: (14,106)] [added: (207)] | |
| Amortization of actuarial loss and prior service cost for benefit plans | [removed: 1,142] [added: 23,057] | | | [removed: 4,365] [added: 1,142] | | | [removed: 2,154] [added: 4,365] | |
| Other comprehensive income (loss) | [removed: (25,523)] [added: 16,433] | | | [removed: 6,880] [added: (25,523)] | | | [removed: (10,090)] [added: 6,880] | |
| Comprehensive income | $ [removed: 592,139] [added: 600,913] | | | $ [removed: 522,685] [added: 592,139] | | | $ [removed: 591,095] [added: 522,685] | |
| Continuing operations | $ [removed: 4.71] [added: 4.44] | | | $ [removed: 3.91] [added: 4.71] | | | $ [removed: 4.48] [added: 3.91] | |
| Discontinued operations | [removed: (0.04)] [added: (0.03)] | | | [removed: (0.01)] [added: (0.04)] | | | [removed: 0.06] [added: (0.01)] | |
| Net earnings | $ [removed: 4.67] [added: 4.41] | | | $ [removed: 3.90] [added: 4.67] | | | $ [removed: 4.54] [added: 3.90] | |
| Continuing operations | $ [removed: 4.67] [added: 4.41] | | | $ [removed: 3.87] [added: 4.67] | | | $ [removed: 4.40] [added: 3.87] | |
| Discontinued operations | [removed: (0.04)] [added: (0.02)] | | | [removed: (0.02)] [added: (0.04)] | | | [removed: 0.06] [added: (0.02)] | |
| Net earnings | $ [removed: 4.63] [added: 4.39] | | | $ [removed: 3.85] [added: 4.63] | | | $ [removed: 4.46] [added: 3.85] | |
| Basic | [removed: 132,300] [added: 132,578] | | | [removed: 132,393] [added: 132,300] | | | [removed: 132,513] [added: 132,393] | |
| Assuming dilution | [removed: 133,385] [added: 133,245] | | | [removed: 133,926] [added: 133,385] | | | [removed: 134,878] [added: 133,926] | |
The groundwater treatment system for the Hewitt Landfill on-site remediation reached mechanical completion during 2020.
The incurred and anticipated costs have been fully accrued for based on facts and circumstances known to the Company at this time.
Obtaining an understanding of the change in estimate of remediation costs, as applicable, and performing procedures to evaluate the appropriateness and sufficiency of the estimate at year-end.
February 25, 2021
| | 2020 | | | *2019* | |
| Net earnings | $ 584,480 | | | $ 617,662 | | | $ 515,805 | |
| Other, net | (1,564) | | | (63) | | | 0 | |
| common stock | (214) | | (214) | | | 0 | | (25,918) | | 0 | | | (26,132) | |
| Other comprehensive income | 0 | | 0 | | | 0 | | 0 | | 16,433 | | | 16,433 | |
| Other | 0 | | 0 | | | 110 | | (110) | | 0 | | | 0 | |
| Balances at December 31, 2020 | 132,516 | | $ 132,516 | | | $ 2,802,012 | | $ 3,274,107 | | $ (181,305) | | | $ 6,027,330 | |
While we continue to operate as an essential business, the COVID-19 pandemic has impacted our industry and the economy, and it may have far-reaching impacts on many aspects of our operations, directly and indirectly, including with respect to its impacts on customer behaviors, business and manufacturing operations, our employees, and the market generally.
Events and changes in circumstances arising after December 31, 2020, including those resulting from the impacts of COVID-19, will be reflected in management’s estimates for future periods.
Allowance for doubtful accounts is based on our assessment of the collectability of customer accounts.
We regularly review the allowance by considering factors such as historical experience, credit quality, the age of the accounts receivable balances, and current economic conditions that may affect a customer’s ability to pay.
For assets sold or otherwise disposed of, the cost and related accumulated depreciation are removed, and any related gain or loss is reflected in income.
Except for equipment with monthly monitoring service where the service component accounts for a majority of the lease cost, the non-lease components of our lease agreements are not separated from the lease components.
| Amortization of finance leases | 1,616 | | | 29 | | | 472 | |
We may also enter into contracts that qualify for the normal purchases and normal sales (NPNS) exception.
When a contract meets the criteria to qualify as NPNS, we apply such exception.
Income recognition and realization related to NPNS contracts generally coincide with the physical delivery of the commodity.
For contracts qualifying for the NPNS exception, no recognition of the contract’s fair value in the consolidated financial statements is required until settlement of the contract as long as the transaction remains probable of occurring.
| *in thousands* | | | 2020 | | | *2019* | |
| *dollars in thousands* | 2020 | | | *2019* | |
| Discount rate | 0.30% | | | 1.63% | |
| 2021 | $ 22,436 | |
| 2022 | 16,453 | |
| 2023 | 11,492 | |
| 2024 | 6,857 | |
| 2025 | 3,751 | |
For additional information about claims and litigation, see Note 12 under the caption Litigation and Environmental Matters.
| SOSARs 1 | | $ 1,605 | | | 1.3 | |
| Restricted shares | | 8,362 | | | 1.7 | |
The plans were remeasured at November 30, 2020 to reflect settlement accounting (due to a voluntary lump-sum settlement offer to certain fully vested plan participants) for the CMG Hourly Pension Plan and the Vulcan Materials Company (VMC) Pension Plan (the Chemicals and Salaried Pension Plans were merged to form the VMC Pension Plan effective November 30, 2020).
In response to the COVID-19 pandemic, the Coronavirus Aid, Relief, and Economic Security Act (CARES Act) was signed into law in March 2020.
The CARES Act provides numerous tax relief provisions and stimulus measures.
A temporary favorable change to the prior year and current year limitations on interest deductions and a temporary suspension of certain payment requirements for the employer portion of Social Security taxes are the relief provisions that are expected to provide us the greatest benefit.
In the first quarter of 2020, an expected cash tax benefit of $13,301,000 was recorded to account for the favorable change to the prior year limitation on interest deductions.
| assuming dilution | 133,245 | | | 133,385 | | | 133,926 | |
Certain items previously reported in specific financial statement captions have been reclassified to conform to the 2020 presentation.
| | |
| --- | --- |
Cumulatively through December 31, 2019, the Company has incurred life-to-date expense of $37.3 million for the Hewitt Landfill on-site remediation, which is based on the facts and circumstances known to the Company at this time.
Evaluating the estimate of the liability and the extent and sufficiency of related disclosures is subjective in nature and as such requires significant audit effort, involves especially subjective auditing judgements, and requires the use of our environmental specialists.
Comparing, on a sample basis, management’s estimate of remediation costs to third party support.
February 26, 2020
| | | | | | |
| --- | --- | --- | --- | --- | --- |
| Balances at December 31, 2016 | 132,339 | | $ 132,339 | | | $ 2,807,995 | | $ 1,771,518 | | $ (139,376) | | | $ 4,572,476 | |
| Net earnings | 0 | | 0 | | | 0 | | 601,185 | | 0 | | | 601,185 | |
| common stock | (510) | | (510) | | | 0 | | (59,793) | | 0 | | | (60,303) | |
| Other comprehensive loss | 0 | | 0 | | | 0 | | 0 | | (10,090) | | | (10,090) | |
| Other | 0 | | 0 | | | 125 | | (127) | | 0 | | | (2) | |
The 2017 results also reflect insurance recoveries for past legal expenses associated with the Texas Brine matter (see Note 12).
Receivables are aged, and appropriate allowances for doubtful accounts and bad debt expense are recorded.
We elected the following practical expedients: (1) the practical expedient package which permits us to not reassess our prior conclusions about lease identification, lease classification, and initial direct costs; (2) to not separate the lease components from the non-lease components for all leases; (3) to apply a portfolio approach to our railcar and barge leases; (4) to not recognize ROU assets and lease liabilities for all pre-existing land easements not previously accounted for as leases; and (5) to not recognize ROU assets or lease liabilities for our short-term leases, including existing short-term leases of those assets in transition.
| Amortization of leaseholds | 29 | | | 472 | | | 608 | |
| Discount rate | 1.63% | | | 2.93% | |
| | | |
| --- | --- | --- |
| 2020 | $ 22,348 | |
| 2021 | 15,306 | |
| 2022 | 10,742 | |
| 2023 | 6,256 | |
| 2024 | 3,604 | |
| SOSARs 1 | | $ 2,168 | | | 1.2 | |
| Restricted shares | | 8,003 | | | 1.8 | |
As noted below in Accounting Standards Recently Adopted (Lease Accounting), we elected not to restate pre-2019 financials for the adoption of the new lease standard (ASU 2016-02).
LEASE ACCOUNTING During the first quarter of 2019, we adopted Accounting Standards Update (ASU) 2016-02, “Leases,” utilizing the comparatives transition option (we elected not to restate comparative periods) under ASC 840.
This ASU amends prior accounting standards for lease accounting and adds additional disclosures about leasing arrangements.
Under the new guidance, lessees are required to recognize lease right-of-use assets and lease liabilities on the balance sheet for all leases (excluding mineral leases) with terms longer than 12 months.
Leases are classified as either finance or operating, with classification affecting the pattern of expense recognition in the income statement and presentation of cash flow in the statement of cash flows.
Upon adoption, we recognized operating lease liabilities of $442,697,000, with corresponding right-of-use assets based on the present value of the remaining minimum rental payments under current leasing standards for existing operating leases.
See the caption Leases under this Note 1 for the practical expedients elected and other information.
Additionally, see Notes 7 and 16 for the required lease disclosures.
ASU 2018-14 is effective for fiscal years ending after December 15, 2020 and is to be applied retrospectively.
While we are still evaluating the impact of ASU 2018-14, it will not impact our consolidated financial statements as it only affects disclosure.
Thus, the adoption of this standard will have a minor impact on the notes to our consolidated financial statements, specifically, our benefit plans note.
CREDIT LOSSES In June 2016, the FASB issued ASU 2016-13, “Measurement of Credit Losses on Financial Instruments,” which amends guidance on the impairment of financial instruments.
ASU 2016-13 is effective for annual reporting periods beginning after December 15, 2019, and interim reporting periods within those annual reporting periods.
An excerpt. Shown here: 40 of 622 rewritten, 40 of 257 added and 40 of 244 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2020 filing and the FY2019 filing.
Item 9A. CONTROLS AND PROCEDURES
8 rewritten, 6 added, 3 removed, 37 unchanged
Our Chief Executive Officer and Chief Financial Officer, with the participation of other management officials, evaluated the effectiveness of the design and operation of the disclosure controls and procedures as of December 31, [removed: 2019.][added: 2020.]
Based upon that evaluation, our Chief Executive Officer and Chief Financial Officer concluded that our disclosure controls and procedures were effective as of December 31, [removed: 2019.][added: 2020.]
No material changes were made during the fourth quarter of [removed: 2019] [added: 2020] to our internal control over financial reporting, nor have there been other factors that materially affect these controls.
Based on this evaluation, management concluded that our internal control over financial reporting was effective as of December 31, [removed: 2019.][added: 2020.]
Deloitte & Touche LLP, an independent registered public accounting firm, as auditors of our consolidated financial statements, has issued an attestation report on the effectiveness of our internal control over financial reporting as of December 31, [removed: 2019.][added: 2020.]
We have audited the internal control over financial reporting of Vulcan Materials Company and subsidiaries (the “Company”) as of December 31, [removed: 2019,] [added: 2020,] based on criteria established in *Internal Control* — *Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission (COSO).
In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2019,] [added: 2020,] based on criteria established in *Internal Control* — *Integrated Framework (2013)* issued by COSO.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States) (PCAOB), the consolidated financial statements as of and for the year ended December 31, [removed: 2019,] [added: 2020,] of the Company and our report dated February [removed: 26, 2020,] [added: 25, 2021,] expressed an unqualified opinion on those financial statements.
Due to the COVID-19 pandemic, we have implemented remote work arrangements for support functions and restricted business travel effective mid-March 2020.
To date, these arrangements have not materially affected our ability to maintain our business operations, including the operation of financial reporting systems, internal control over financial reporting, and disclosure controls and procedures.
We are continually assessing the potential effects of the pandemic on the design and operating effectiveness of our internal control over financial reporting and if necessary, will take appropriate actions.
| Part II | 123 |
| February 25, 2021 |
| Part II | 124 |
| Part II | 119 |
| February 26, 2020 |
| Part II | 120 |
Item 9B. OTHER INFORMATION
0 rewritten, 1 added, 1 removed, 6 unchanged
| Part II | 125 |
| Part II | 121 |
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
2 rewritten, 0 added, 0 removed, 2 unchanged
On or about March [removed: 23, 2020,] [added: 29, 2021,] we expect to file a definitive proxy statement with the Securities and Exchange Commission pursuant to Regulation 14A (our [removed: “2020] [added: “2021] Proxy Statement”).
The information under the headings “Proposal 1 - Election of Directors,” “Corporate Governance – Policies,” “Corporate Governance – Director Nomination Process,” “Corporate Governance – Committees of the Board of Directors” and “Delinquent Section 16(a) Reports” (to the extent reported therein) included in our [removed: 2020] [added: 2021] Proxy Statement is incorporated herein by reference.
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 0 added, 0 removed, 1 unchanged
The information under the headings “Compensation Discussion and Analysis,” “Director Compensation,” “Executive Compensation,” “Corporate Governance – Compensation Committee Interlocks and Insider Participation,” and “Compensation Committee Report” included in our [removed: 2020] [added: 2021] Proxy Statement is incorporated herein by reference.
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED
1 rewritten, 0 added, 0 removed, 2 unchanged
The information under the headings “Security Ownership of Certain Beneficial Owners and Management,” and “Equity Compensation Plans” included in our [removed: 2020] [added: 2021] Proxy Statement is incorporated herein by reference.
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 0 removed, 1 unchanged
The information under the headings “Corporate Governance – Director Independence,” and “Corporate Governance – Transactions with Related Persons” included in our [removed: 2020] [added: 2021] Proxy Statement is incorporated herein by reference.
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
2 rewritten, 0 added, 0 removed, 5 unchanged
The information under the heading “Independent Registered Public Accounting Firm” included in our [removed: 2020] [added: 2021] Proxy Statement is incorporated herein by reference.
| Part III | [removed: 122] [added: 126] |
Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES
54 rewritten, 8 added, 10 removed, 44 unchanged
| | Report of Independent Registered Public Accounting Firm | [removed: 64] [added: 68] - [removed: 65] [added: 69] | |
| | Consolidated Statements of Comprehensive Income | [removed: 66] [added: 70] | |
| | Consolidated Balance Sheets | [removed: 67] [added: 71] | |
| | Consolidated Statements of Cash Flows | [removed: 68] [added: 72] | |
| | Consolidated Statements of Equity | [removed: 69] [added: 73] | |
| | Notes to Consolidated Financial Statements | [removed: 70 -118] [added: 74 -122] | |
| Exhibit 3(b) | | | [Amended and Restated By-Laws of the Company (as amended through [removed: February 14,] [added: March 23,] 2020) filed as Exhibit 3.1 to the Company’s Current Report on Form 8-K filed on [removed: February 19,] [added: March 25,] 2020 [removed: 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312520041389/d890219dex31.htm)] [added: 1](http://www.sec.gov/Archives/edgar/data/1396009/000156459020012874/vmc-ex31_15.htm)] | | |
| Exhibit [removed: 4(i)] [added: 4(k)] | | | Indenture, dated as of May 1, 1991, by and between Legacy Vulcan Corp. (formerly Vulcan Materials Company) and First Trust of New York (as successor trustee to Morgan Guaranty Trust Company of New York) filed as Exhibit 4 to the Form S-3 on May 2, 1991 (Registration No. 33-40284) 1 | | |
| Exhibit [removed: 4(j)] [added: 4(l)] | | | [Supplemental Indenture No. 1, dated as of November 16, 2007, among the Company, Legacy Vulcan Corp. and The Bank of New York, as Trustee, filed as Exhibit 4.1 to the Company’s Current Report on Form 8-K filed on November 21, 2007 1](http://www.sec.gov/Archives/edgar/data/1396009/000095012307015875/y427068kexv4w1.htm) | | |
| Exhibit [removed: 4(k)] [added: 4(m)] | | | [Supplemental Indenture No. 2, dated as of June 30, 2015, between Legacy Vulcan, LLC and The Bank of New York Mellon Trust Company, N.A., as Trustee, filed as Exhibit 4(a) to the Company’s Quarterly Report on Form 10-Q filed on August 5, 2015 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600915000030/vmc-20150630ex4a14b97ea.htm) | | |
| Exhibit [removed: 4(l)] [added: 4(n)] | | | [removed: [Term Loan Note,] [added: [Indenture,] dated [removed: December 17, 2017,] [added: as of February 23, 2018,] between Vulcan Materials Company and [removed: Bank of America, N.A.,] [added: Regions Bank, as Trustee,] filed as Exhibit [removed: 10.1] [added: 4.1] to the Company’s Current Report on Form 8-K filed on [removed: December 21, 2017 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312517376623/d423227dex101.htm)] [added: February 26, 2018 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312518057209/d539453dex41.htm)] | | |
| Exhibit [removed: 4(m)] [added: 10(c)] | | | [removed: [Guaranty] [added: [Credit] Agreement, dated [removed: December 21, 2017, by each of the parties identified therein] as [removed: Guarantors, each other subsidiary] of [added: September 10, 2020, among] Vulcan Materials [removed: Company that becomes a party thereto,] [added: Company, Truist Bank, as Administrative Agent,] and [removed: Bank of America, N.A.,] [added: the Lenders and other parties named therein,] filed as Exhibit [removed: 10.2] [added: 10.1] to the Company’s Current Report on Form 8-K filed on [removed: December 21, 2017 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312517376623/d423227dex102.htm)] [added: September 11, 2020 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312520244169/d944112dex101.htm)] | | |
| Exhibit [removed: 4(n)] [added: 4(i)] | | | [Eighth Supplemental Indenture, dated as of February 23, 2018, between Vulcan Materials Company and Regions Bank, as Trustee, filed as Exhibit 4.1 to the Company’s Current Report on Form 8-K filed on February 23, 2018 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312518056123/d514001dex41.htm) | | |
| Exhibit [removed: 4(o)] [added: 4(j)] | | | [removed: [Indenture,] [added: [Ninth Supplemental Indenture,] dated as of [removed: February 23, 2018,] [added: May 18, 2020,] between Vulcan Materials Company and Regions [removed: Bank,] [added: Bank] as Trustee, filed as Exhibit 4.1 to the Company’s Current Report on Form 8-K filed on [removed: February 26, 2018 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312518057209/d539453dex41.htm)] [added: May 18, 2020 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312520145154/d891796dex41.htm)] | | |
| Exhibit [removed: 4(q)] [added: 10(b)] | | | [removed: [First Amendment to] [added: [364-Day] Credit [removed: Agreement] [added: Agreement,] dated [removed: as of August 16, 2019,] [added: April 10, 2020,] among Vulcan Materials [removed: Company and SunTrust Bank] [added: Company, Truist Bank,] as Administrative Agent, and [added: the Lenders and] other parties named therein, filed as Exhibit 10.1 to the Company’s [removed: Quarterly] [added: Current] Report on Form [removed: 10-Q] [added: 8-K] filed on [removed: November 7, 2019 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600919000065/vmc-20190930xex10_1.htm)] [added: April 13, 2020 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312520105285/d916741dex101.htm)] | | |
| Exhibit [removed: 4(r)] [added: 4(o)] | | | [Description of [removed: Securities](https://www.sec.gov/Archives/edgar/data/1396009/000139600920000006/vmc-20191231xex4_r.htm)] [added: Securities, filed as Exhibit 4(r) to the Company’s Annual Report on Form 10-K filed on February 26, 2020 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600920000006/vmc-20191231xex4_r.htm)] | | |
| Exhibit [removed: 10(a)] [added: 10(l)] | | | [removed: [Credit] [added: [Form of Change of Control Employment] Agreement dated [removed: as of June 19, 2015 among the Company and SunTrust Bank as Administrative Agent, and other parties named therein] [added: January 1, 2016,] filed as Exhibit 10.1 to the [removed: Company’s] [added: Company's] Current Report on Form 8-K filed on [removed: June 25, 2015 1](http://www.sec.gov/Archives/edgar/data/1396009/000114420415038932/v414020_ex10-1.htm)] [added: January 7, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000114420416074571/v428515_ex10-1.htm)] | | |
| Exhibit [removed: 10(b)] [added: 10(r)] | | | [removed: [Credit Agreement dated as] [added: [Form] of [removed: December 21, 2016 among the Company and SunTrust Bank, as Administrative Agent, and the Lenders and other parties named therein] [added: Performance Share Unit Agreement] filed as Exhibit 10.1 to the [removed: Company’s] [added: Company's] Current Report on Form 8-K filed on [removed: December 22, 2016 1](http://www.sec.gov/Archives/edgar/data/1396009/000114420416141021/v455520_ex10-1.htm)] [added: March 11, 2010 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000114420410012797/v177024_ex10-1.htm)] | | |
| Exhibit [removed: 10(c)] [added: 10(d)] | | | [Unfunded Supplemental Benefit Plan for Salaried Employees, as amended, filed as Exhibit 10.4 to the Company's Current Report on Form 8-K filed on December 17, 2008 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w4.htm) | | |
| Exhibit [removed: 10(d)] [added: 10(e)] | | | [Amendment No. 1 to the Unfunded Supplemental Benefit Plan for Salaried Employees filed as Exhibit 10.1 to the Company’s Current Report on Form 8-K on January 7, 2014 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000114420414000953/v364833_ex10-1.htm) | | |
| Exhibit [removed: 10(e)] [added: 10(f)] | | | [Deferred Compensation Plan for Directors Who Are Not Employees of the Company, as amended, filed as Exhibit 10.5 to the Company's Current Report on Form 8-K filed on December 17, 2008 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w5.htm) | | |
| Exhibit [removed: 10(f)] [added: 10(g)] | | | [The 2006 Omnibus Long-Term Incentive Plan of the Company filed as Appendix C to Legacy Vulcan Corp.’s 2006 Proxy Statement on Schedule 14A filed on April 13, 2006 1,2](http://www.sec.gov/Archives/edgar/data/103973/000010397306000088/proxy2006.htm) | | |
| Exhibit [removed: 10(g)] [added: 10(h)] | | | [Amendment to the 2006 Omnibus Long-Term Incentive Plan of the Company filed as Appendix A to the Company’s 2011 Proxy Statement on Schedule 14A filed March 31, 2011 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000114420411019107/v216860-def14a.htm) | | |
| Exhibit [removed: 10(h)] [added: 10(i)] | | | [Amendment to the 2006 Omnibus Long-Term Incentive Plan of the Company dated February 9, 2012, filed as Exhibit 10(l) to the Company’s Annual Report on Form 10-K for the year ended December 31, 2011 filed on February 29, 2012 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000119312512089430/d257544dex10i.htm) | | |
| Exhibit [removed: 10(i)] [added: 10(j)] | | | [Restricted Stock Plan for Nonemployee Directors of the Company, as amended, filed as Exhibit 10.6 to the Company's Current Report on Form 8-K filed on December 17, 2008 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w6.htm) | | |
| Exhibit [removed: 10(j)] [added: 10(k)] | | | [Executive Deferred Compensation Plan, as amended, filed as Exhibit 10.1 to the Company's Current Report on Form 8-K filed on December 17, 2008 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w1.htm) | | |
| Exhibit [removed: 10(k)] [added: 10(s)] | | | [Form of [removed: Change of Control Employment] [added: Performance Share Unit] Agreement [removed: dated January 1, 2016,] [added: (2012)] filed as Exhibit 10.1 to the [removed: Company's] [added: Company’s] Current Report on Form 8-K filed on [removed: January 7, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000114420416074571/v428515_ex10-1.htm)] [added: February 14, 2012 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000114420412009141/v302778_ex10-1.htm)] | | |
| Exhibit [removed: 10(l)] [added: 10(m)] | | | [Vulcan Materials Company Change of Control Severance Plan for Senior Officers, effective January 1, 2016, filed as Exhibit 10(m) to the Company’s Annual Report on Form 10-K filed on February 25, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600916000044/vmc-20151231ex10ma03dee.htm) | | |
| Exhibit [removed: 10(m)] [added: 10(n)] | | | [Executive Incentive Plan of the Company, as amended, filed as Exhibit 10.2 to the Company's Current Report on Form 8-K filed on December 17, 2008 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w2.htm) | | |
| Exhibit [removed: 10(n)] [added: 10(o)] | | | [Supplemental Executive Retirement Agreement filed as Exhibit 10 to Legacy Vulcan Corp.’s Quarterly Report on Form 10-Q for the quarter ended September 30, 2001 filed on November 2, 2001 1,2](http://www.sec.gov/Archives/edgar/data/103973/000010397301500050/sera-dmj.htm) | | |
| Exhibit [removed: 10(o)] [added: 10(p)] | | | [Form of Stock Option Agreement filed as Exhibit 10(o) to Legacy Vulcan Corp.’s Report on Form 8-K filed on December 20, 2005 1,2](http://www.sec.gov/Archives/edgar/data/103973/000010397305000308/stockoptionagt.htm) | | |
| Exhibit [removed: 10(p)] [added: 10(q)] | | | [Form of Director Deferred Stock Unit Agreement filed as Exhibit 10.9 to the Company's Current Report on Form 8-K filed on December 17, 2008 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w9.htm) | | |
| Exhibit [removed: 10(q)] [added: 10(v)] | | | [Form of [removed: Performance Share] [added: Employee Deferred Stock] Unit [added: Amended] Agreement filed as Exhibit [removed: 10.1] [added: 10.7] to the Company's Current Report on Form 8-K filed on [removed: March 11, 2010 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000114420410012797/v177024_ex10-1.htm)] [added: December 17, 2008 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w7.htm)] | | |
| Exhibit [removed: 10(r)] [added: 10(dd)] | | | [Form of Performance Share Unit [added: Award] Agreement [removed: (2012)] [added: (2020) under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan,] filed as Exhibit 10.1 to the Company’s [removed: Current] [added: Quarterly] Report on Form [removed: 8-K] [added: 10-Q] filed on [removed: February 14, 2012 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000114420412009141/v302778_ex10-1.htm)] [added: May 6, 2020 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600920000015/vmc-20200331xex10_1.htm)] | | |
| Exhibit [removed: 10(s)] [added: 10(t)] | | | [Form of Stock-Only Stock Appreciation Rights Agreement filed as Exhibit 10(q) to Legacy Vulcan Corp.’s Report on Form 10-K filed on February 26, 2007 1,2](http://www.sec.gov/Archives/edgar/data/103973/000095014407001601/g05561exv10wxqy.htm) | | |
| Exhibit [removed: 10(t)] [added: 10(u)] | | | [Stock-Only Stock Appreciation Rights Agreement between the Company and John R. McPherson dated November 9, 2011, filed as Exhibit 10(a) to the Company’s Current Report on Form 8-K filed on November 15, 2011 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000114420411065033/v240795_ex10-a.htm) | | |
| Exhibit [removed: 10(u)] [added: 10(x)] | | | [Form of [removed: Employee] [added: Non-Employee Director] Deferred Stock Unit [removed: Amended] Agreement [added: under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan,] filed as Exhibit [removed: 10.7] [added: 10(y)] to the [removed: Company's Current] [added: Company’s Quarterly] Report on Form [removed: 8-K] [added: 10-Q] filed on [removed: December 17, 2008 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000095014408009390/g17056exv10w7.htm)] [added: August 3, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600916000071/vmc-20160630xex10_y.htm)] | | |
| Exhibit [removed: 10(v)] [added: 10(w)] | | | [Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 99 to the Company’s Registration Statement on Form S-8 (File No. 333-211349) filed on May 13, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000119312516590099/d155821dex99.htm) | | |
| Exhibit [removed: 10(w)] [added: 10(z)] | | | [Form of [removed: Non-Employee Director Deferred] [added: Restricted] Stock Unit [added: Award] Agreement under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit [removed: 10(y)] [added: 10(aa)] to the Company’s Quarterly Report on Form 10-Q filed on August 3, 2016 [removed: 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600916000071/vmc-20160630xex10_y.htm)] [added: 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600916000071/vmc-20160630xex10_aa.htm)] | | |
| Exhibit [removed: 10(x)] [added: 10(y)] | | | [Form of Stock-Only Stock Appreciation Rights Award Agreement under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 10(z) to the Company’s Quarterly Report on Form 10-Q filed on August 3, 2016 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600916000071/vmc-20160630xex10_z.htm) | | |
| Exhibit 10(a) | | | [Second Amendment to Credit Agreement, dated April 10, 2020, among Vulcan Materials Company, each of the Guarantors, the Lenders party thereto, and Truist Bank successor by merger to SunTrust Bank, as Administrative Agent, filed as Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q filed on August 5, 2020 1](http://www.sec.gov/Archives/edgar/data/1396009/000139600920000040/vmc-20200630xex10_2.htm) | | |
| Part IV | 128 |
| Part IV | 129 |
| Exhibit 10(ee) | | | [Form of Stock-Only Appreciation Rights Award Agreement (2020) under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan, filed as Exhibit 10.2 to the Company’s Quarterly Report on Form 10-Q filed on May 6, 2020 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600920000015/vmc-20200331xex10_2.htm) | | |
| Exhibit 10(gg) | | | [Form of Non-Employee Director Restricted Stock Unit Award Agreement under the Vulcan Materials Company 2016 Omnibus Long-Term Incentive Plan filed as Exhibit 10.3 to the Company’s Quarterly Report on Form 10-Q filed on August 5, 2020 1,2](http://www.sec.gov/Archives/edgar/data/1396009/000139600920000040/vmc-20200630xex10_3.htm) | | |
| Part IV | 130 |
| --- | --- | --- | --- |
| Part IV | 131 |
| --- | --- | --- | --- | --- | --- |
| Exhibit 2 | | | [Membership Interest Purchase Agreement, dated as of May 24, 2017, by and among Vulcan Construction Materials, LLC, Aggregates USA Holdings Sub, LLC, Aggregates USA, LLC, solely for limited purposes, SPO Partners II, L.P., and, solely for limited purposes, Vulcan Materials Company, filed as Exhibit 2.1 to the Company’s Current Report on Form 8-K filed on May 25, 2017 1, 3](http://www.sec.gov/Archives/edgar/data/1396009/000110465917035006/a17-14163_1ex2d1.htm) | | |
| Part IV | 123 |
| Exhibit 4(p) | | | [Registration Rights Agreement, dated as of February 23, 2018, between Vulcan Materials Company and Goldman Sachs & Co. LLC, U.S. Bancorp Investments, Inc. and Wells Fargo Securities, LLC, filed as Exhibit 4.2 to the Company’s Current Report on Form 8-K filed on February 26, 2018 1](http://www.sec.gov/Archives/edgar/data/1396009/000119312518057209/d539453dex42.htm) | | |
| Part IV | 124 |
| Part IV | 125 |
| Exhibit 10(aa) | | | [Separation Agreement, dated as of July 7, 2018, by and between John R. McPherson and Vulcan Materials Company, filed as Exhibit 10.1 to the Company’s Current Report on Form 8-K filed on July 10, 2018 1, 2](http://www.sec.gov/Archives/edgar/data/1396009/000089882218000048/separationagreement.htm) | | |
| Exhibit 10(dd) | | | [Letter Agreement, dated as of September 3, 2019, by and between Michael R. Mills and Vulcan Materials Company, filed as Exhibit 10.1 to the Company’s Current Report on Form 8-K filed on September 6, 2019 1.2](http://www.sec.gov/Archives/edgar/data/1396009/000119312519239381/d802728dex101.htm) | | |
| Part IV | 126 |
| *3* | *The schedules and exhibits to the Purchase Agreement have been omitted pursuant to Item 601(b)(2) of Regulation S-K.* | | | | |
An excerpt. Shown here: 40 of 54 rewritten, all 8 added and all 10 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS AND FINANCIAL STATEMENT SCHEDULES in the FY2020 filing and the FY2019 filing.
Item 16. FORM 10-K SUMMARY
7 rewritten, 2 added, 2 removed, 18 unchanged
Pursuant to the requirements of Section 13 or 15(d) of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized on February [removed: 26, 2020.][added: 25, 2021.]
| | ] [added: 1](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg037.jpg)] J. Thomas Hill Chairman, President and Chief Executive Officer |
| ] [added: 3](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg037.jpg)] J. Thomas Hill | Chairman, President and Chief Executive Officer (Principal Executive Officer) | February [removed: 26, 2020] [added: 25, 2021] |
| ] [added: 4](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg038.jpg)] Suzanne H. Wood | Senior Vice President and Chief Financial Officer (Principal Financial Officer) | February [removed: 26, 2020] [added: 25, 2021] |
| ] [added: 38](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg039.jpg)] Randy L. Pigg | Vice President, Controller (Principal Accounting Officer) | February [removed: 26, 2020] [added: 25, 2021] |
| The following directors: Melissa H. Anderson Thomas A. Fanning O. B. Grayson Hall, Jr. Cynthia L. Hostetler Richard T. O'Brien James T. Prokopanko Kathleen L. Quirk David P. Steiner Lee J. Styslinger, III [removed: D. Michael Wilson] [added: George Willis] | Director Director Director Director Director Director Director Director Director Director | |
| ] [added: 22](https://www.sec.gov/Archives/edgar/data/1396009/000139600921000009/vmc-20201231x10kg040.jpg)] Denson N. Franklin III Attorney-in-Fact | | February [removed: 26, 2020] [added: 25, 2021] |
| Part IV | 132 |
| Part IV | 133 |
| Part IV | 128 |
| Part IV | 129 |
Item 6. SELECTED FINANCIAL DATA
0 rewritten, 0 added, 42 removed, 0 unchanged
Dropped this year
SELECTED FINANCIAL DATA
The selected earnings data, per share data and balance sheet data for each of the five most recent years ended December 31 set forth below have been derived from our audited consolidated financial statements.
The following data should be read in conjunction with our consolidated financial statements and notes to consolidated financial statements in Item 8 “Financial Statements and Supplementary Data.”
| | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | | | | | | | | | | |
| | | | | 2019 | | | *2018* | | | *2017* | | | *2016* | | | *2015* | |
| *As of and for the years ended December 31* | | | | | | | | | | | | | | | | | |
| *in millions, except per share data* | | | | | | | | | | | | | | | | | |
| Total revenues | | | $ | 4,929.1 | | $ | 4,382.9 | | $ | 3,890.3 | | $ | 3,592.7 | | $ | 3,422.2 | |
| Gross profit | | | $ | 1,255.9 | | $ | 1,100.9 | | $ | 993.5 | | $ | 988.9 | | $ | 857.5 | |
| Gross profit margin | | | | 25.5% | | | 25.1% | | | 25.5% | | | 27.5% | | | 25.1% | |
| Earnings from continuing operations 1 | | | $ | 622.5 | | $ | 517.8 | | $ | 593.4 | | $ | 422.4 | | $ | 232.9 | |
| Earnings (loss) on discontinued operations, | | | | | | | | | | | | | | | | | |
| net of tax 2 | | | $ | (4.8) | | $ | (2.0) | | $ | 7.8 | | $ | (2.9) | | $ | (11.7) | |
| Net earnings | | | $ | 617.7 | | $ | 515.8 | | $ | 601.2 | | $ | 419.5 | | $ | 221.2 | |
| Basic earnings (loss) per share | | | | | | | | | | | | | | | | | |
| Continuing operations | | | $ | 4.71 | | $ | 3.91 | | $ | 4.48 | | $ | 3.17 | | $ | 1.75 | |
| Discontinued operations | | | | (0.04) | | | (0.01) | | | 0.06 | | | (0.02) | | | (0.09) | |
| Basic net earnings per share | | | $ | 4.67 | | $ | 3.90 | | $ | 4.54 | | $ | 3.15 | | $ | 1.66 | |
| Diluted earnings (loss) per share | | | | | | | | | | | | | | | | | |
| Continuing operations | | | $ | 4.67 | | $ | 3.87 | | $ | 4.40 | | $ | 3.11 | | $ | 1.72 | |
| Discontinued operations | | | | (0.04) | | | (0.02) | | | 0.06 | | | (0.02) | | | (0.08) | |
| Diluted net earnings per share | | | $ | 4.63 | | $ | 3.85 | | $ | 4.46 | | $ | 3.09 | | $ | 1.64 | |
| Cash and cash equivalents | | | $ | 271.6 | | $ | 40.0 | | $ | 141.6 | | $ | 259.0 | | $ | 284.1 | |
| Total assets 3 | | | $ | 10,648.8 | | $ | 9,832.1 | | $ | 9,504.9 | | $ | 8,471.5 | | $ | 8,301.6 | |
| Total liabilities 3 | | | $ | 5,026.9 | | $ | 4,629.2 | | $ | 4,536.0 | | $ | 3,899.0 | | $ | 3,847.4 | |
| Working capital | | | $ | 843.8 | | $ | 476.6 | | $ | 737.2 | | $ | 764.9 | | $ | 731.1 | |
| Current maturities and short-term debt | | | $ | 0.0 | | $ | 133.0 | | $ | 41.4 | | $ | 0.1 | | $ | 0.1 | |
| Long-term debt 4 | | | $ | 2,784.3 | | $ | 2,779.4 | | $ | 2,813.5 | | $ | 1,982.8 | | $ | 1,980.3 | |
| Equity | | | $ | 5,621.9 | | $ | 5,202.9 | | $ | 4,968.9 | | $ | 4,572.5 | | $ | 4,454.2 | |
| Cash dividends declared per share | | | $ | 1.24 | | $ | 1.12 | | $ | 1.00 | | $ | 0.80 | | $ | 0.40 | |
| | |
| --- | --- |
| *1* | *Earnings from continuing operations for* *2017 include pretax interest charges of $148.0 million referable to debt purchases and $297.0 million of discrete net tax benefits.* |
| *2* | *Discontinued operations include the results attributable to our former Chemicals business.* |
| *3* | *As a result of our first quarter 2019 adoption of ASU 2016-02 (see Note 1 “Summary of Significant Accounting Policies” in Item 8 “Financial Statements and Supplementary Data” under the caption New Accounting Standards), total assets* *and total liabilities* *as of December 31, 2019 included $408.2* *million* *and $418.0, respectively,* *of reported right-of-use assets* *and related liabilities. We elected not to restate comparative periods.* |
| *4* | *Long-term debt includes $250.0 million of floating-rate notes due June 2020 (see Note 6 “Debt”* *in Item 8 “Financial Statements and Supplementary Data”) as we intend to refinance these notes, and we have the ability to do so by borrowing on our line of credit.* |
| | |
| --- | --- |
An excerpt. Shown here: all 0 rewritten, all 0 added and 40 of 42 removed. The counts are complete. For every sentence, read Item 6. SELECTED FINANCIAL DATA in the FY2019 filing.