 filings.tools
Devon Energy (DVN) 10-K risk factor changes: FY2020 vs FY2019
The 2020-12-31 10-K against the 2019-12-31 one, compared heading by heading and sentence by sentence.
Item 1A27 rewritten33 added7 removed192 unchanged
All filing items1,094 rewritten787 added653 removed1,999 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 1 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 787 added, 653 removed, 1,094 rewritten and 1,999 unchanged across 17 items that differ.
Sentences by item
20 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2020; struck-through words were in FY2019. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. Risk Factors
27 rewritten, 33 added, 7 removed, 192 unchanged
The risks described below may not be the only risks we face, as our business and operations may also be subject to risks that we do not yet know of, or that we currently [removed: believe are immaterial.]
For example, over the last five years, [added: monthly] NYMEX WTI oil and NYMEX Henry Hub [added: gas] prices ranged from highs of over [removed: $75] [added: $67] per Bbl and $4.80 per MMBtu, respectively, to lows of under [removed: $27] [added: $30] per Bbl and [removed: $1.70] [added: $1.50] per MMBtu, respectively.
[removed: Our Operations] [added: Our Operations] Are Uncertain and Involve Substantial Costs and [removed: Risks][added: Risks]
[removed: Regulatory] [added: These] and [added: other regulatory and] public policy developments could, among other things, restrict production levels, [added: delay necessary permitting,] impose price controls, change environmental protection [removed: requirements] [added: requirements, impose restrictions on pipelines or other necessary infrastructure] and increase taxes, royalties and other amounts payable to governments or governmental agencies.
[added: Our operating and] other compliance costs could increase further if existing laws and regulations are revised or reinterpreted, or if new laws and regulations become applicable to our operations.
In addition, changes in public policy may indirectly impact our operations by, among other things, increasing the cost of supplies and equipment and [removed: fostering general economic uncertainty.]
Although we are unable to predict changes to existing laws and regulations, such changes could significantly impact our profitability, financial condition and liquidity, particularly changes related to [added: leasing and permitting on federal lands,] hydraulic fracturing, environmental matters more generally, seismic activity and income taxes, as discussed below.
The EPA also released a report in 2016 finding that certain aspects of hydraulic fracturing, such as water withdrawals and wastewater management practices, could result in impacts to water [removed: resources.][added: resources in certain circumstances.]
Beyond these regulatory efforts, various policy makers, regulatory agencies and political [removed: candidates] [added: leaders] at the federal, state and local levels have proposed implementing even further restrictions on hydraulic fracturing, including prohibiting the technology outright.
[removed: It] [added: While it] is [added: not] possible [removed: that] [added: at this time to predict the ultimate impact of these or] any [removed: such] [added: other future regulatory changes, any additional] restrictions [removed: may particularly target industry activity] [added: or prohibitions] on [added: our ability to operate on] federal [removed: lands, which] [added: lands] could adversely impact our [removed: operations] [added: business] in the Delaware and Powder River Basins, as well as other areas where we operate under federal leases.
[removed: As of December 31, 2019, approximately] [added: Post-merger, less than] 20% of our total leasehold resides on federal [removed: lands, and approximately 40% and 60% of our leasehold] [added: lands primarily located] in the Delaware and Powder River [removed: Basins, respectively, resides on federal lands.][added: Basins.]
These laws and regulations may, among other things, impose liability on us for the cost of remediating pollution that results from our [removed: operations.][added: operations or prior operations on assets we have acquired.]
Seismic Activity – Earthquakes in northern and central [removed: Oklahoma] [added: Oklahoma, southeastern New Mexico, western Texas] and elsewhere have prompted concerns about seismic activity and possible relationships with the oil and gas industry.
In the jurisdictions in which we [removed: operate,] [added: operate or previously operated,] income taxes are assessed on our earnings after consideration of all allowable deductions and credits.
[removed: Changes in the types of earnings that are subject to income tax,] [added: intangible drilling costs) and] the [removed: types] [added: timing] of [removed: costs that are considered allowable deductions] [added: such deductions,] or the rates assessed on our taxable earnings would all impact our income taxes and resulting operating cash flow.
[removed: Concerns] [added: Concerns] About Climate Change and Related Regulatory, Social and Market Actions May Adversely Affect Our [removed: Business][added: Business]
Policy makers [added: and regulators] at both the U.S. federal and state levels have [removed: introduced legislation] [added: already imposed, or stated intentions to impose, laws] and [removed: proposed new] regulations designed to quantify and limit the emission of greenhouse gases.
For example, both the EPA and the BLM have issued regulations for the control of methane emissions, which also include leak detection and repair requirements, for the oil and gas [removed: industry.][added: industry; although the methane specific requirements of some of these regulations have been repealed, similar or more stringent emissions requirements may be imposed by the Biden Administration.]
[removed: Nevertheless,] [added: In addition,] several states where we operate, including [removed: Wyoming and] [added: Wyoming,] New [removed: Mexico,] [added: Mexico and Texas,] have already imposed, or stated intentions to impose, laws or regulations designed to reduce methane emissions from oil and gas exploration and production activities.
With respect to more comprehensive regulation, policy makers and political [removed: candidates] [added: leaders] have made, or expressed support for, a variety of proposals, such as the development of cap-and-trade or carbon tax [removed: programs, as well as the more sweeping “green new deal” resolutions introduced in Congress in early 2019.][added: programs.]
Moreover, [removed: certain] [added: an increasing number of] financial institutions, funds and other sources of capital have begun restricting or eliminating their investment in oil and natural gas activities due to their concern regarding climate change.
As of December 31, [removed: 2019,] [added: 2020,] we had total indebtedness of $4.3 billion.
Our business has become increasingly dependent on digital technologies, and we anticipate expanding the use of [removed: technology] [added: these technologies] in our operations, including through artificial intelligence, process automation and data analytics.
Concurrent with [removed: this] [added: the] growing dependence on technology is greater sensitivity to cyber attack related activities, which have [removed: frequently] [added: increasingly] targeted our industry.
Cyber attackers often attempt to gain unauthorized access to digital systems for purposes of misappropriating [removed: sensitive] [added: confidential and proprietary] information, intellectual property or financial assets, corrupting data or causing operational disruptions as well as [removed: to prevent] [added: preventing] users from accessing systems or information [removed: and demand] [added: for the purpose of demanding] payment in order [added: for users] to regain access.
[removed: Midstream] [added: Midstream] Capacity Constraints and Interruptions Impact Commodity [removed: Sales][added: Sales]
[removed: Insurance] [added: Insurance] Does Not Cover All [removed: Risks][added: Risks]
believe are immaterial.
Our Business Has Been Adversely Impacted by the COVID-19 Pandemic, and We May Experience Continuing or Worsening Adverse Effects From This or Other Pandemics
The COVID-19 pandemic and related economic repercussions have created significant volatility, uncertainty and turmoil in the oil and gas industry.
This outbreak and the related responses of governmental authorities and others to limit the spread of the virus significantly reduced global economic activity, resulting in an unprecedented decline in the demand for oil and other commodities during 2020.
Combined with other factors, this decline in demand caused a swift and material deterioration in commodity prices in early 2020, which adversely impacted our results of operations for 2020 and contributed to our recognition of a material asset impairment to our oil and gas assets during the first quarter of 2020.
The negative effects of COVID-19 on economic prospects across the world have contributed to concerns for the potential of a prolonged economic slowdown and recession.
Any such downturns, or protracted periods of depressed commodity prices, could have significant adverse consequences for our financial condition and liquidity.
Moreover, any such downturns could also result in similar financial constraints for our non-operating partners, purchasers of our production and other counterparties, thereby increasing the risk that such counterparties default on their obligations to us.
Such defaults or more general supply chain disruptions due to the pandemic may also jeopardize the supply of materials, equipment or services for our operations.
The COVID-19 pandemic and related restrictions aimed at mitigating its spread have caused us to modify certain of our business practices, including limiting employee travel, encouraging work-from-home practices and other social distancing measures.
There is no certainty that these or any other future measures will be sufficient to mitigate the risks posed by the disease, including the risk of infection of key employees, and our ability to perform certain functions could be disrupted or otherwise impaired by these new
business practices.
For example, our reliance on technology has necessarily increased due to our encouragement of remote communications and other work-from-home practices, which could make us more vulnerable to cyber attacks.
The COVID-19 pandemic and its related effects continue to evolve.
The ultimate extent of the impact of the COVID-19 pandemic and any other future pandemic on our business will depend on future developments, including, but not limited to, the nature, duration and spread of the disease, the vaccination and other responsive actions to stop its spread or address its effects and the duration, timing and severity of the related consequences on commodity prices and the economy more generally, including any recession resulting from the pandemic.
Any extended period of depressed commodity prices or general economic disruption as a result of a pandemic would adversely affect our business, financial condition and results of operations.
For example, President Biden and certain members of his administration and Congress have expressed support for, and have taken steps to implement, efforts to transition the economy away from fossil fuels and to promote stricter environmental regulations, and such proposals could impose new and more onerous burdens on our industry and business.
fostering general economic uncertainty.
Federal Lands – President Biden and certain members of his administration have expressed support for, and have taken steps to implement, additional regulation of oil and gas leasing and permitting on federal lands.
Such proposals range from more onerous permitting requirements to an outright moratorium on new oil and gas leasing and permitting on federal lands.
For example, on January 20, 2021, the Acting Secretary of the Department of the Interior issued an order temporarily limiting the authority to approve certain fossil fuel authorizations on federal lands, including the approval of new leases and new drilling permits, to certain high-ranking officials within the Department of the Interior.
In addition, President Biden issued an executive order on January 27, 2021 directing the Secretary of the Interior to pause on entering new oil and gas leases on public lands to the extent possible and to launch a rigorous review of all existing leasing and permitting practices related to fossil fuel development on public lands.
Changes in the types of earnings that are subject to income tax, the types of costs that are considered allowable deductions (such as
In addition, President Biden has highlighted addressing climate change as a priority of his administration, and he previously released an energy plan calling for a number of sweeping changes to address climate change, including, among other measures, a national mobilization effort to achieve net-zero emissions for the U.S. economy by 2050, through increased use of renewable power, stricter fuel-efficiency standards and support for zero-emission vehicles.
President Biden issued a number of executive orders in January 2021 with the purpose of implementing certain of these changes, including the rejoining of the Paris Agreement, a call for the issuance of more stringent methane emissions regulations for oil and gas facilities and an order directing federal agencies to procure electric vehicles.
Although the full impact of these orders is uncertain at this time, the adoption and implementation of these or other initiatives may result in the restriction or cancellation of oil and natural gas activities, greater costs of compliance or consumption (thereby reducing demand for our products) or an impairment in our ability to continue our operations in an economic manner.
[Index to Financial Statements](#IndexToFinancialStatements)
We May Fail to Realize the Anticipated Benefits of the Merger
The ultimate success of the Merger will depend on, among other things, our ability to combine the legacy Devon and WPX businesses in a manner that realizes anticipated synergies and benefits.
If we are not able to successfully achieve these synergies, or the cost to achieve these synergies is greater than expected, then the anticipated benefits of the Merger may not be realized fully or at all or may take longer to realize than expected.
It is possible that the integration process could result in the loss of key employees, the loss of customers, the disruption of our ongoing businesses, inconsistencies in standards, controls, procedures and policies, unexpected integration issues, higher than expected integration costs and an overall post‑completion integration process that takes longer than originally anticipated.
Furthermore, our board of directors and management team consist of directors and employees from each of the legacy companies.
The integration of these individuals could require the reconciliation of differing priorities and strategic philosophies, which may not be successful or take longer than anticipated.
Our operating and
For example, changes in U.S. trade relations, particularly the imposition of tariffs by the U.S. and China, may increase the cost of materials we or our vendors use, thereby increasing our operating expense.
For example, certain candidates running to be elected President of the United States in 2020 have pledged to impose a ban on hydraulic fracturing.
Following the change in presidential administrations, however, the agencies have attempted to revise or rescind their previously issued methane standards.
Litigation concerning these methane regulations and subsequent attempts to revise or rescind them is ongoing.
As generally proposed, a cap-and-trade program would cap overall greenhouse gas emissions on an economy-wide basis and require major sources of greenhouse gas emissions or major fuel producers to acquire and surrender emission allowances, while a carbon tax could impose taxes based on emissions from our operations and downstream uses of our products.
The “green new deal” resolutions call for a 10-year national mobilization effort to, among other things, transition 100% of power demand in the U.S. to zero-emission sources and overhaul transportation systems in the U.S. to remove greenhouse gas emissions as much as is technologically feasible.
Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations
228 rewritten, 208 added, 311 removed, 308 unchanged
Financial Statements and Supplementary Data” of this [removed: report.][added: report for further discussion.]
Overview of [removed: 2019] [added: 2020] Results
[removed: | | • | Increased] [added: We previously increased] our quarterly [removed: common stock] dividend [removed: 12.5%] to $0.09 per share [removed: beginning in] [added: commencing with] the second quarter of 2019. [removed: |]
| [removed: ] [added: 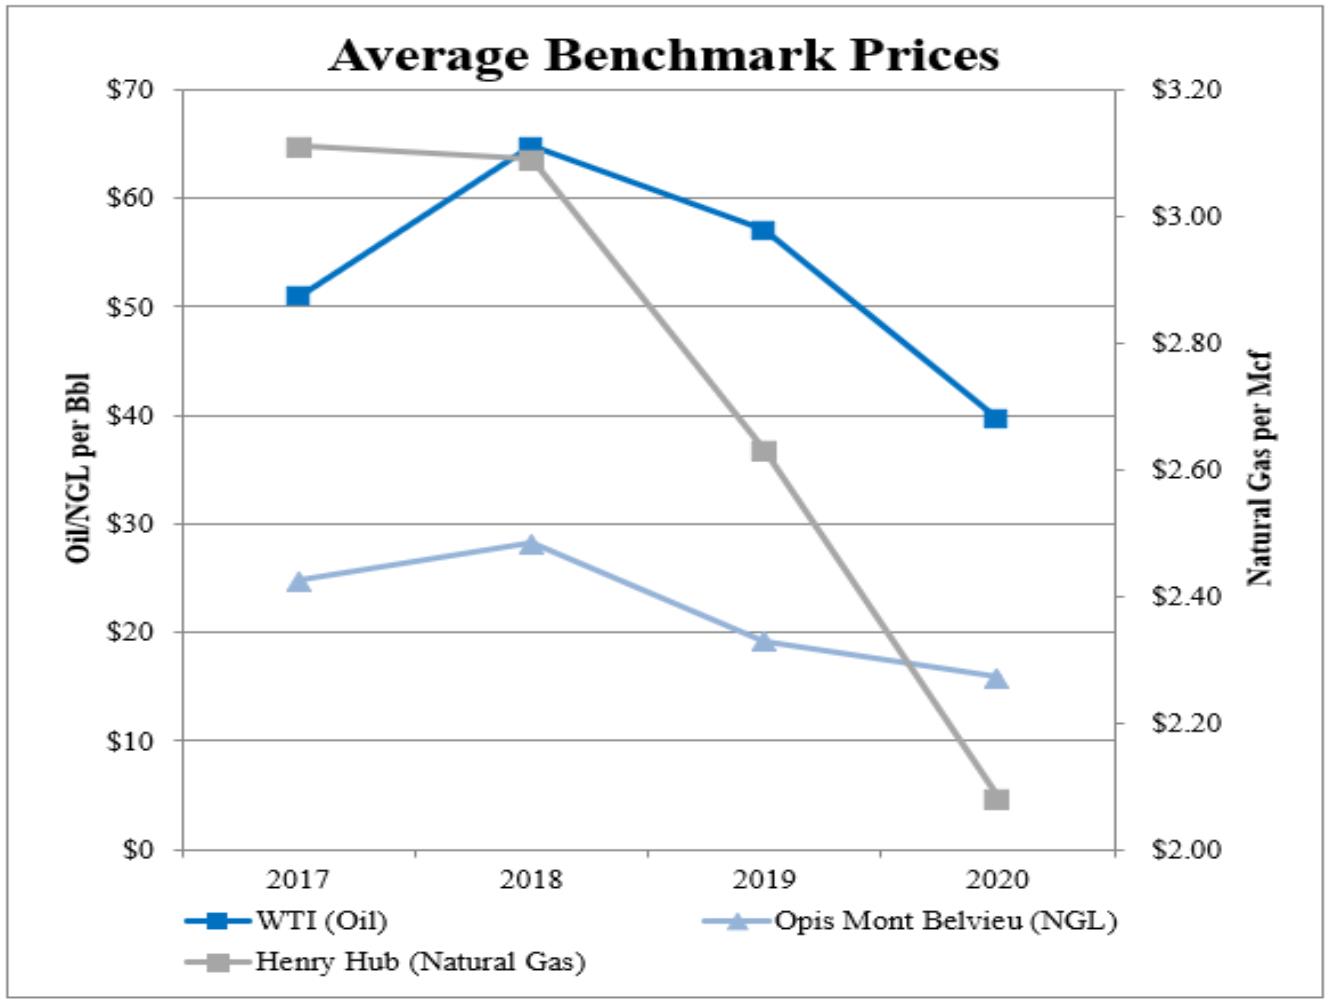] | | As presented in the graph at the left, our operating achievements are subject to the volatility of commodity prices. Over the last four years, NYMEX WTI oil and NYMEX Henry Hub [added: gas] prices ranged from average highs of $64.79 per Bbl and $3.11 per MMBtu, respectively, to average lows of [removed: $43.36] [added: $39.59] per Bbl and [removed: $2.46] [added: $2.08] per MMBtu, respectively. |
[removed: ][added: 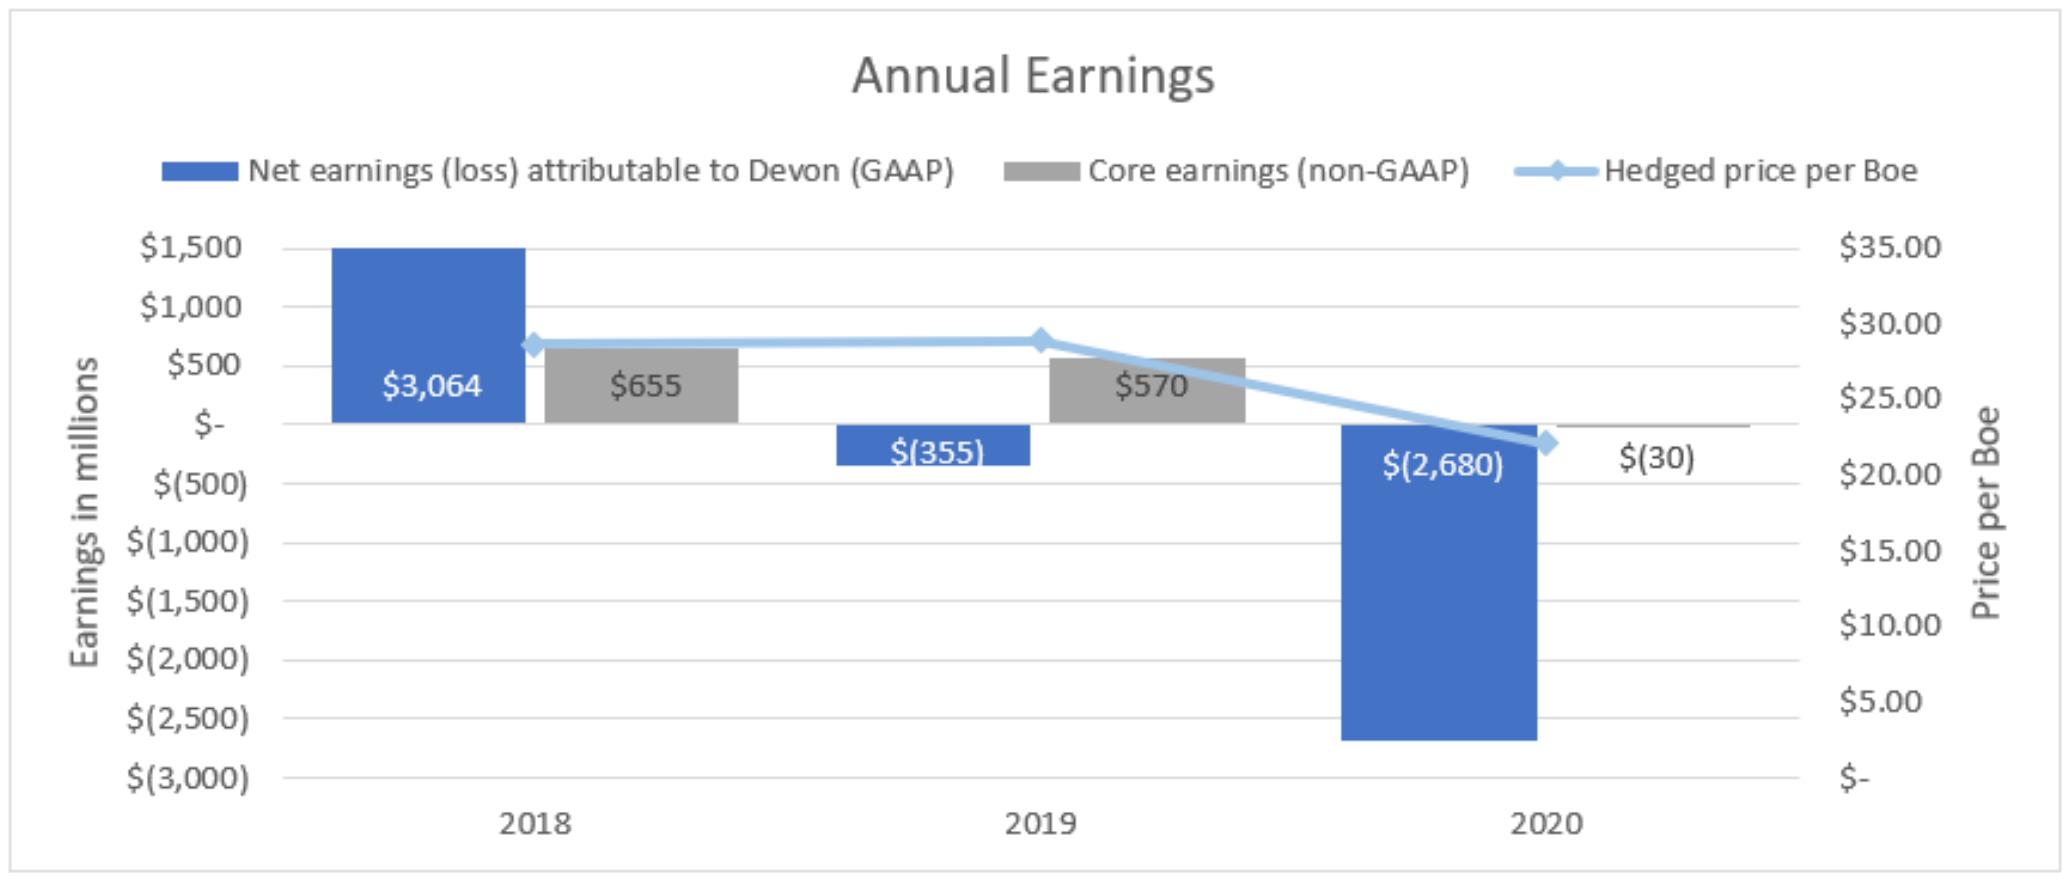]
Our net earnings in recent years have been significantly impacted by divestiture [removed: transactions] [added: transactions, asset impairments] and temporary, noncash adjustments to the value of our commodity hedges.
Net earnings in [removed: 2017] [added: 2020] included [removed: a $0.1] [added: $2.3] billion [removed: gain on] [added: of] asset [removed: dispositions from continuing operations] [added: impairments on our proved] and [added: unproved properties and] a [removed: $0.2] [added: $0.1] billion hedge valuation [removed: gain,] [added: loss,] both net of taxes.
[removed: 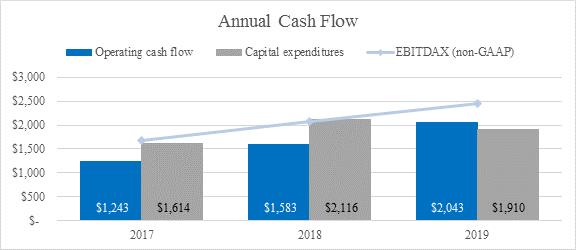][added: 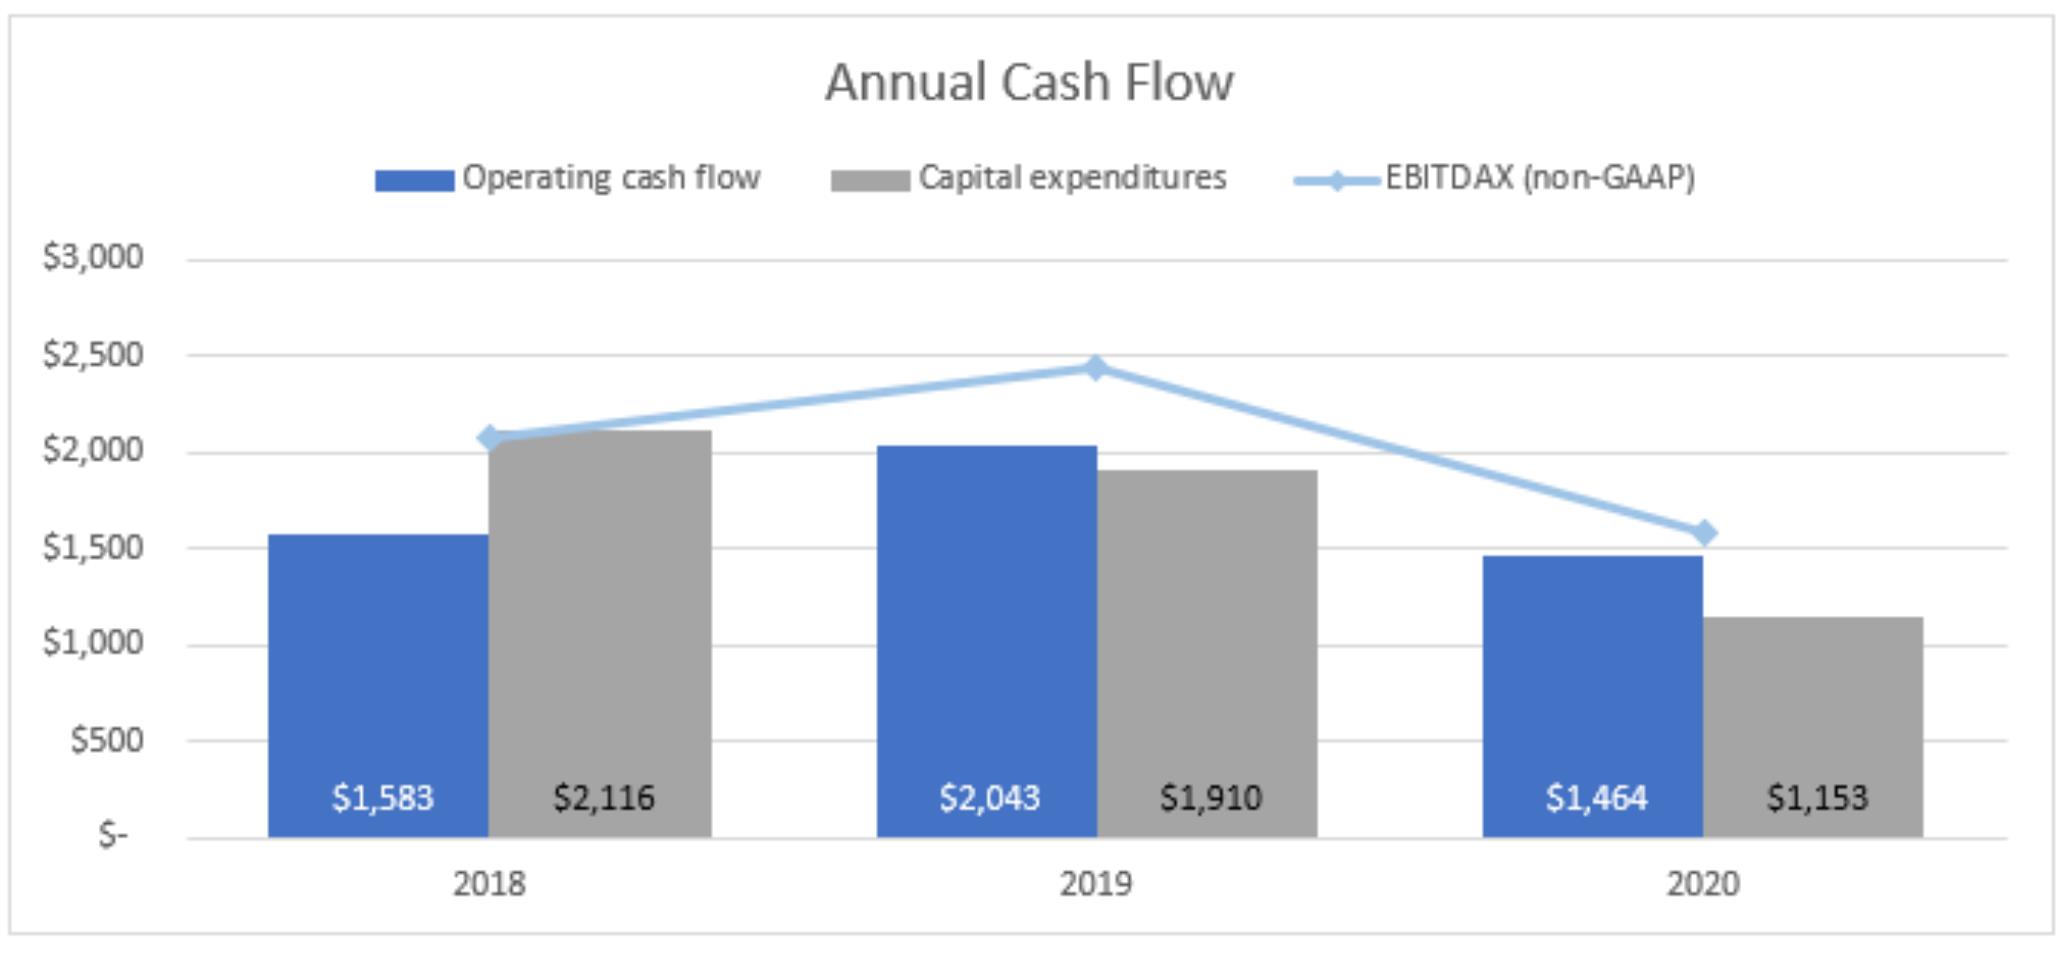]
[removed: Business] [added: Business] and Industry [removed: Outlook][added: Outlook]
[added: In 2020,] Devon marked its [removed: 48th] [added: 49th] anniversary in the oil and gas business and its [removed: 31st] [added: 32nd] year as a public [removed: company during 2019.][added: company.]
To mitigate our exposure to commodity [removed: price] [added: market] volatility and ensure our financial strength, we continue to execute a disciplined, risk-management hedging program.
We are [added: currently] adding [removed: 2020] [added: 2021 hedge] positions at desirable [removed: prices, and] [added: prices where post-merger] we currently have approximately [removed: 40%] [added: 50%] of our anticipated oil volumes and [removed: 25%] [added: 55%] of our anticipated gas volumes hedged.
[removed: Additionally, we] [added: We] are [added: also] actively adding attractive hedges for [removed: 2021.][added: 2022.]
Further insulating our cash flow, we continue to examine and, when appropriate, execute attractive regional basis swap hedges [removed: in an effort] to protect price realizations across our portfolio.
[removed: Accordingly,] [added: To achieve our 2021 capital program objectives that maximize free cash flow,] over [removed: half] [added: 70 percent] of [removed: the 2020] [added: our 2021] spend will be focused [removed: in] on our highest margin U.S. oil play, the Delaware Basin.
[removed: Results] [added: Results] of [removed: Operations][added: Operations]
The following [removed: graphs,] [added: graph,] discussion and analysis are intended to provide an understanding of our results of operations and current financial condition.
Analysis of the change in net earnings from continuing operations is shown below and analysis of the change in net earnings from discontinued operations is shown on page [removed: 33.][added: 35.]
[added: | | | 2020 | | | |] 2019 [removed: vs.] [added: | | | |] 2018 [added: | | |]
Our [removed: 2019] [added: 2020] net loss from continuing operations was [removed: $79 million and decreased $793 million] [added: $2.5 billion,] compared to [removed: 2018.][added: a net loss from continuing operations of $79 million for 2019.]
The graph below shows the change in net [removed: earnings] [added: loss] from [removed: 2018] [added: 2019] to [removed: 2019.][added: 2020.]
[removed: ][added: 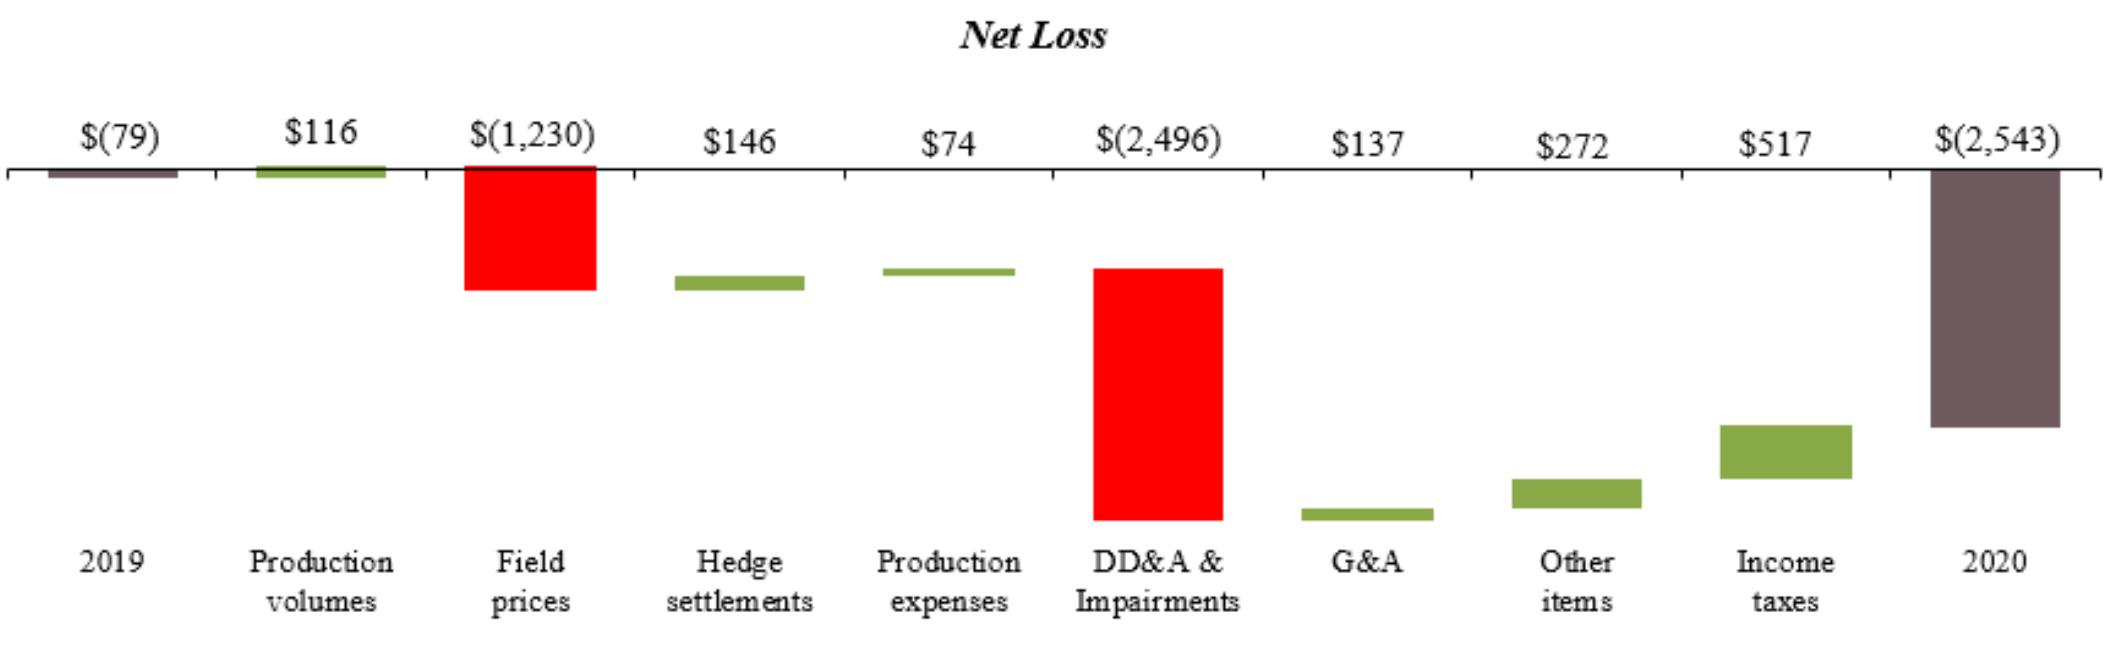]
[removed: Production Volumes][added: Production Volumes]
| | | [removed: 2019] [added: 2020] | | | | % of Total | | | | [removed: 2018] [added: 2019] | | | | Change | | |
| Delaware Basin | | | [removed: 70] [added: 85] | | | | [removed: 47] [added: 55] | % | | | [removed: 42] [added: 70] | | | | [removed: +67] [added: +21] | % |
| Powder River Basin | | | [removed: 17] [added: 19] | | | | [removed: 11] [added: 12] | % | | | [removed: 14] [added: 17] | | | | [removed: +26] [added: +11] | % |
| Eagle Ford | | | [removed: 23] [added: 24] | | | | [removed: 16] [added: 15] | % | | | [removed: 28] [added: 23] | | | | [removed: \- 17] [added: +1] | % |
| Other | | | [removed: 6] [added: 7] | | | | [removed: 4] [added: 5] | % | | | [removed: 5] [added: 9] | | | | [removed: +4] [added: \- 25] | % |
| Total | | | [removed: 150] [added: 155] | | | | 100 | % | | | [removed: 130] [added: 150] | | | | [removed: +15] [added: +3] | % |
| Delaware Basin | | | [removed: 177] [added: 248] | | | | [removed: 29] [added: 41] | % | | | [removed: 105] [added: 177] | | | | [removed: +68] [added: +40] | % |
| Powder River Basin | | | [removed: 24] [added: 23] | | | | 4 | % | | | [removed: 16] [added: 24] | | | | [removed: +55] [added: \- 3] | % |
| Eagle Ford | | | [removed: 79] [added: 77] | | | | 13 | % | | | 79 | | | | \- [removed: 0] [added: 3] | % |
| Other | | | [removed: 1] [added: 3] | | | | 0 | % | | | [removed: 1] [added: 5] | | | | \- [removed: 18] [added: 34] | % |
| Total | | | [removed: 599] [added: 603] | | | | 100 | % | | | [removed: 566] [added: 599] | | | | [removed: +6] [added: +1] | % |
| Delaware Basin | | | [removed: 27] [added: 37] | | | | [removed: 36] [added: 47] | % | | | [removed: 16] [added: 27] | | | | [removed: +74] [added: +35] | % |
| Powder River Basin | | | [removed: 2] [added: 3] | | | | 3 | % | | | [removed: 1] [added: 2] | | | | [removed: +53] [added: +17] | % |
| Eagle Ford | | | [removed: 11] [added: 10] | | | | 14 | % | | | [removed: 13] [added: 11] | | | | \- [removed: 15] [added: 5] | % |
| Other | | | 1 | | | | 1 | % | | | 1 | | | | [removed: +12] [added: \- 40] | % |
| Total | | | [removed: 77] [added: 78] | | | | 100 | % | | | [removed: 71] [added: 77] | | | | [removed: +9] [added: +1] | % |
| Delaware Basin | | | [removed: 127] [added: 163] | | | | [removed: 39] [added: 49] | % | | | [removed: 75] [added: 127] | | | | [removed: +69] [added: +28] | % |
The following discussion and analyses generally focus on 2020 and 2019 items and year-to-year comparisons between 2020 and 2019.
Discussions of 2018 items and year-to-year comparisons between 2019 and 2018 that are not included in this report can be found in “Management’s Discussion and Analysis of Financial Condition and Results or Operations” in Part II, Item 7 of our 2019 Annual Report on Form 10-K.
COVID – 19
A novel strain of coronavirus, SARS-CoV-2, causing a disease referred to as COVID-19, was reported to have surfaced in China in late 2019 and has subsequently spread worldwide, resulting in a global pandemic and health crisis.
Devon began actively monitoring COVID-19 in January 2020 and formally established a COVID-19 cross-functional planning team at the beginning of March.
The COVID-19 team is focused on two key priorities: the health and safety of our employees and contractors and the uninterrupted operation of our business.
| | • | Health and safety – The COVID-19 team has developed and implemented a number of safety measures, which have successfully kept our workforce healthy and safe. The COVID-19 team has established an informational campaign to provide employees an understanding of the virus risk factors and safety measures, as well as timely updates from governmental stay-at-home regulations. Expectations have also been set for employees to communicate immediately if they, or someone they have been in contact with, has experienced symptoms or tested positive for COVID-19. Other measures have included closing all of Devon’s office buildings and locations to the public, implementing social distancing and encouraging employees to work from home. Beginning in late March, more than 90% of the workforce assigned to Devon’s Oklahoma City Headquarters office were primarily working from home until the vast majority began a hybrid schedule of working from home and the office late in the second quarter. The COVID-19 team also strongly encourages employees to wear masks, reinforces social distancing measures and continues to perform targeted and routine intensive and deep cleaning of all Devon office locations. |
| | • | Uninterrupted operation of our business – Beyond workforce safety measures, the COVID-19 team has worked with government officials to ensure our business continues to be deemed an essential business or infrastructure. The COVID-19 team has ensured technology and resources are available for employees to execute their job duties while working from home and implemented further social distancing and contactless initiatives in our oil and gas field operations. The collective efforts of our COVID-19 team and our entire workforce have enabled us to avoid the need to implement COVID-19 containment or mitigation measures, which would require closure or suspension of any of our operations. |
This outbreak and the related responses of governmental authorities and others to limit the spread of the virus have significantly reduced global economic activity, resulting in an unprecedented decline in the demand for oil and other commodities.
This supply-and-demand imbalance was exacerbated by uncertainty regarding the future global supply of oil due to disputes between Russia and the members of OPEC in March 2020.
These factors caused a swift and material deterioration in commodity prices in early 2020, with NYMEX WTI oil prices falling from a high of over $60/Bbl at the beginning of the year to below $20/Bbl in April 2020.
By the end of 2020, NYMEX WTI oil prices recovered to approximately $50/Bbl, and we expect oil and other commodity prices to remain volatile for the foreseeable future.
Driven by the coronavirus pandemic, 2020 was a challenging year for the oil and gas industry and our business.
Social distancing restrictions, government lockdowns and individual behavior changes all reduced transportation needs, which negatively impacted the demand for oil.
The resulting drop in oil prices and cash generated from our operations necessitated a change in our plans.
We aggressively reduced our planned capital investment 45%, selectively curtailed production and initiated sustainable cost-reduction measures.
Despite these challenges, we continued to improve our capital efficiency and controllable costs per unit of production.
Importantly, we maintained competitive leverage and debt metrics.
These market forces led to opportunities for select companies in our industry to create shareholder value from mergers and acquisitions.
And, on September 26, 2020, we entered into the Merger Agreement, providing for an all-stock merger of equals with WPX which successfully closed on January 7, 2021.
The Merger has created a leading oil producer in the U.S., with an asset base underpinned by premium acreage in the economic core of the Delaware Basin.
This strategic combination accelerates our transition to a cash-return business model, including the implementation of a fixed plus variable dividend strategy.
As evidenced by our recent performance highlights below, we remain focused on building economic value by executing on our strategic priorities of disciplined oil volume growth while cutting operational and corporate costs, reducing reinvestment rates to maximize free cash flow, maintaining low leverage, delivering cash returns to our shareholders and pursuing ESG excellence.
As we capture synergies and other benefits from the Merger, we expect to improve across all these performance measures.
| | • | 2020 oil production totaled 155 MBbls/d, exceeding our plan by 5%. |
| | • | Operating costs continued to decline in 2020, led by a 29% and 6% decrease from 2019 for G&A and production expenses, respectively. |
| | • | Reduced workforce to reflect lower and sustainable capital investment program. |
| | • | Closed on the Barnett Shale transaction on October 1, 2020, receiving net proceeds of $490 million. |
| | • | Paid a special dividend of $0.26 per share for approximately $100 million on October 1, 2020. |
| | • | Remained focused on reducing methane emissions and greenhouse gas while also increasing water recycling. |
| | • | Exited 2020 with $5.2 billion of liquidity, including $2.2 billion of cash, with no near-term debt maturities. |
Despite our portfolio enhancements, aggressive cost reductions and operational advancements, our 2020 financial results were challenged by commodity prices and deterioration of the macro-economic environment resulting from the unprecedented COVID-19 pandemic.
Our earnings decreased from 2019 to 2020 due to a decline in overall commodity prices.
Led by a 31% decline in WTI from 2019 to 2020, our unhedged combined realized price decreased 31%, while our hedged price decreased 26%.
In response to this commodity price environment, we reduced our aggregate production and G&A expenses 13% compared to 2019.
EBITDAX, which excludes financial amounts related to discontinued operations, and operating cash flow continue to be impacted from the COVID-19 pandemic and declines in commodity prices.
As operating cash flow has declined, we reduced our 2020 capital expenditures by approximately $800 million, or 45% compared to the original capital budget.
As of December 31, 2020, we had $5.2 billion of liquidity comprised of $2.2 billion of cash and $3.0 billion of available credit under our Senior Credit Facility.
We had $4.3 billion of debt outstanding with no maturities until the end of 2025.
Post-merger, approximately 50% and 55% of our 2021 oil and gas production is hedged, respectively.
During 2019, we completed our transformation to a U.S. oil growth company with our exit from Canada and pending sale of the Barnett Shale.
These transactions accelerate efforts to focus exclusively on our resource-rich U.S. oil portfolio, which provides us with a strong foundation to grow returns, margin and profitability.
By operating under a disciplined returns-driven strategy focused on delivering strong operational results, financial strength and value to our shareholders and continuing our commitment to environmental, social and governance excellence, we completed our transformation to “New Devon” and made significant progress toward our cost reduction objectives as evidenced by these 2019 highlights:
| | • | Closed on the sale of our Canadian business for $2.6 billion ($3.4 billion Canadian dollars) in June 2019. |
| --- | --- | --- |
| | • | Announced the sale of our Barnett Shale assets for $770 million (expected closing in the second quarter of 2020). |
| | • | Completed workforce reduction and other cost reduction initiatives, reaching approximately $240 million of annualized G&A savings. |
| | • | Improved capital efficiency by reducing capital expenditures approximately 10% and increasing oil production 21% compared to 2018. |
| | • | Retired $1.7 billion of senior notes, reducing annualized financing costs by $60 million. |
| | • | Repurchased $4.8 billion of our total $5.8 billion share repurchase authorizations, representing an outstanding share count reduction of nearly 30% since the program’s inception. |
| | • | Increased Delaware Basin and Powder River Basin production over 60% in 2019 compared to 2018. |
| | • | Reduced methane emissions by nearly 20% over the last three years and established a target to further reduce methane intensity rates by 2025. |
| | • | Exited 2019 with $1.8 billion of cash, inclusive of $380 million restricted for discontinued operations, $3.0 billion of available credit under our Senior Credit Facility and have no debt maturities until 2025. |
EBITDAX, which excludes financial amounts related to discontinued operations, has been increasing over the past three years as a result of our New Devon production growth and cost reductions.
Regardless of cash flow fluctuations, we remain focused on managing our capital investment to generate free cash flow.
As operating cash flow has declined, we have adjusted our capital development plans accordingly.
As an established company with a strong leadership team, we have experience operating through periods of volatile commodity prices.
With our focused strategy and portfolio of quality assets, we are committed to navigating the current environment while safeguarding our long-term financial strength.
Market prices for crude oil and natural gas are inherently volatile.
In 2019, WTI oil prices averaged approximately $57.02/Bbl versus $64.79/Bbl in 2018.
Despite price support in the first half of 2019 driven by supply tightness and geopolitical tensions, 2019 WTI oil prices overall were negatively impacted by trade concerns and economic slowdown fears, even with strong supply and demand fundamentals.
Looking ahead, crude oil has experienced near term downward pressure as a result of softer demand from the growing impact of the coronavirus related crisis.
Positive factors that could reduce these recent negative factors and create more demand for crude oil are the extension of OPEC cuts through 2020, as well as the International Maritime Organization 2020 regulations.
Henry Hub gas prices averaged approximately $2.63/MMBtu in 2019 versus $3.09/MMBtu in 2018.
Mt.
Belvieu Blended Index NGL prices averaged approximately $19.22/Bbl in 2019 versus $28.31/Bbl in 2018.
Natural gas and NGL prices faced strong headwinds in 2019 due to U.S. supply growth far outpacing demand for both commodities domestically and internationally.
These factors continue to weigh on current natural gas and NGL prices.
As discussed in our [Critical Accounting Estimates](#Critical_Accounting_Estimates), our STACK assets are susceptible to a material asset impairment should prices decrease from current levels.
While such an impairment would materially impact our reported net earnings, it would not impact our operating cash flow or our current near-term drilling plans.
Throughout 2019, our operational efficiencies continued to accelerate.
Our improved cost structure expanded margins, and we ended the year ahead of our multi-year cost savings initiative plan.
As we carry our 2019 momentum into 2020, we will maintain our capital-efficiency focus and intensify our steadfast commitment to capital discipline.
Our returns-driven strategy will be underpinned by our continued efforts to improve our cost structure and grow higher-margin oil production.
As such, our 2020 capital program has been optimized for strong returns, high single-digit oil growth, free cash flow and enhanced per-share cash flow growth.
To achieve our 2020 capital program objectives, our capital allocation priorities are four-fold: maintain base production, fund dividends, invest in high-return growth projects and return excess cash to shareholders.
As the most active program in Devon’s portfolio, capital activity in the Delaware Basin will be diversified across five core areas.
Also accretive to our 2020 returns-focused capital program is our 2020 Rockies activity, where spend will be prioritized to our top-tier Powder River Basin development activity.
In total, our 2020 operating plan is expected to deliver U.S. oil growth of approximately 7.5% to 9.0% on a retained asset basis.
To facilitate the review, these numbers are being presented before consideration of earnings attributable to noncontrolling interests.
An excerpt. Shown here: 40 of 228 rewritten, 40 of 208 added and 40 of 311 removed. The counts are complete. For every sentence, read Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations in the FY2020 filing and the FY2019 filing.
Item 7A. Quantitative and Qualitative Disclosures about Market Risk
6 rewritten, 0 added, 0 removed, 19 unchanged
The key terms to our oil and gas derivative financial instruments as of December 31, [removed: 2019] [added: 2020] are presented in [Note 3](#Derivatives) in “Item 8.
At December 31, [removed: 2019,] [added: 2020,] a 10% change in the forward curves associated with our commodity derivative instruments would have changed our net [removed: asset] [added: liability] positions by approximately [removed: $115] [added: $118] million.
At December 31, [removed: 2019,] [added: 2020,] we had total debt of $4.3 billion.
Devon has certain Canadian dollar obligations associated with its divested Canadian operations which are to be paid with the cash restricted for [removed: discontinued operations.][added: retained obligations.]
A 10% unfavorable change in the Canadian-to-U.S. dollar exchange rate would not have materially impacted our December 31, [removed: 2019] [added: 2020] balance sheet for these items.
See [Note [removed: 18](#Discops)] [added: 19](#Discops)] in “Item 8.
Item 3. Legal Proceedings
0 rewritten, 0 added, 3 removed, 2 unchanged
On April 4, 2019, Devon Energy Production Company, L.P., a wholly-owned subsidiary of the Company (“DEPCO”), agreed to settle its previously disclosed negotiations with the EPA relating to certain alleged Clean Air Act violations at its Beaver Creek Gas Plant located near Riverton, Wyoming by executing an agreed order with the EPA.
The order included a penalty of $150,000 and was approved by the regional EPA judicial officer on June 12, 2019.
Moreover, in connection with the resolution of this matter with the EPA, DEPCO entered into a consent decree on May 9, 2019 with respect to the same matter with the Wyoming Department of Environmental Quality, which also included a separate penalty of $150,000.
Cover and table of contents
91 rewritten, 89 added, 37 removed, 354 unchanged
[removed: Form 10-K][added: FORM 10-K]
For the fiscal year ended December 31, [removed: 2019][added: 2020]
[removed: ][added: ]
The aggregate market value of the voting common stock held by non-affiliates of the registrant as of June [removed: 28, 2019] [added: 30, 2020] was approximately [removed: $11.6] [added: $4.3] billion, based upon the closing price of [removed: $28.52] [added: $11.34] per share as reported by the New York Stock Exchange on such date.
On February [removed: 5, 2020, 382.9] [added: 3, 2021, 673.1] million shares of common stock were outstanding.
[removed: DEVON] [added: DEVON] ENERGY [removed: CORPORATION][added: CORPORATION]
| [Item 1A. Risk Factors](#ITEM_1A_RISK_FACTORS) | | [removed: 13] [added: 14] |
| [Item 1B. Unresolved Staff Comments](#ITEM_1B_UNRESOLVED_STAFF_COMMENTS) | | [removed: 20] [added: 22] |
| [Item 3. Legal Proceedings](#ITEM_3_LEGAL_PROCEEDINGS) | | [removed: 20] [added: 22] |
| [Item 4. Mine Safety Disclosures](#ITEM_4_MINE_SAFETY_DISCLOSURES) | | [removed: 20] [added: 22] |
| [PART II](#PART_II) | | [removed: 21] [added: 23] |
| [Item 5. Market for Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities](#ITEM_5) | | [removed: 21] [added: 23] |
| [Item 6. Selected Financial Data](#ITEM_6_SELECTED_FINANCIAL_DATA) | | [removed: 23] [added: 25] |
| [Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations](#ITEM_7) | | [removed: 24] [added: 26] |
| [Item 7A. Quantitative and Qualitative Disclosures about Market Risk](#ITEM_7A) | | [removed: 46] [added: 48] |
| [Item 8. Financial Statements and Supplementary Data](#ITEM_8) | | [removed: 47] [added: 49] |
| [Item 9. Changes in and Disagreements with Accountants on Accounting and Financial Disclosure](#ITEM_9) | | [removed: 100] [added: 104] |
| [Item 9A. Controls and Procedures](#ITEM_9A_CONTROLS_PROCEDURE_S) | | [removed: 100] [added: 104] |
| [Item 9B. Other Information](#ITEM_9B_OR_INFORMATION) | | [removed: 100] [added: 104] |
| [PART III](#PART_III) | | [removed: 101] [added: 106] |
| [Item 10. Directors, Executive Officers and Corporate Governance](#ITEM_10) | | [removed: 101] [added: 106] |
| [Item 11. Executive Compensation](#ITEM_11_EXECUTIVE_COMPENSATION) | | [removed: 101] [added: 106] |
| [Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters](#ITEM_12) | | [removed: 101] [added: 106] |
| [Item 13. Certain Relationships and Related Transactions, and Director Independence](#ITEM_13) | | [removed: 101] [added: 106] |
| [Item 14. Principal Accountant Fees and Services](#ITEM_14) | | [removed: 101] [added: 106] |
| [Item 15. Exhibits and Financial Statement Schedules](#ITEM_15_EXHIBITS_FINANCIAL_STMTS_SCHED) | | [removed: 102] [added: 107] |
| [Item 16. Form 10-K Summary](#ITEM_16_Form10K_Summary) | | [removed: 107] [added: 116] |
[removed: INFORMATION] [added: INFORMATION] REGARDING FORWARD-LOOKING [removed: STATEMENTS][added: STATEMENTS]
Consequently, actual future results could differ materially [added: and adversely] from our expectations due to a number of factors, including, but not limited to:
| | • | our ability to successfully complete mergers, acquisitions and divestitures; [removed: and] |
We [removed: assume no] [added: do not undertake, and expressly disclaim, any] duty to update or revise our forward-looking statements based on new information, future events or otherwise.
Our operations are concentrated in various onshore areas in the U.S. In [removed: June 2019,] [added: October 2020,] we completed the sale of [removed: substantially all of] our [removed: oil and gas assets and operations in Canada.][added: Barnett Shale assets.]
As of December 31, [removed: 2019,] [added: 2020,] Devon and its consolidated subsidiaries had approximately [removed: 1,800 employees.][added: 1,400 employees, all located in the U.S.]
Proven and responsible operator – We operate our business with the interests of our stakeholders and our environmental, social and governance [removed: progress] [added: values] in mind.
[removed: A premier,] [added: Premier,] sustainable portfolio of assets – As discussed [added: later] in [removed: the next] [added: this] section of this Annual Report, we own a portfolio of assets located in the United States.
We also desire to own a portfolio of assets that can provide [removed: a] [added: sustainable] production [removed: growth platform] extending many years into the future.
Due to the strength of oil prices relative to natural gas, we have [removed: been positioning] [added: positioned] our portfolio to be more heavily weighted to U.S. oil assets in recent years.
As a result of these [removed: divestitures, we expect] [added: transactions,] our oil [removed: production growth,] [added: production,] price realizations and field-level margins will all improve, as we sharpen our focus on [removed: four] [added: five] U.S. oil [added: and liquids] plays located in the Delaware Basin, [removed: STACK,] Powder River [added: Basin, Anadarko Basin, Williston] Basin and Eagle Ford.
As a result of our divestment of substantially all of our oil and gas assets and operations in Canada, as well as the [removed: recently announced] divestiture of our Barnett Shale assets, amounts associated with these assets are presented as discontinued operations.
[removed: Therefore,] [added: The] financial and operational data, such as reserves, production, wells and acreage, provided in this document exclude amounts related to our Canadian and Barnett Shale assets unless otherwise noted.
Indicate by check mark whether the registrant has filed a report on and attestation to its management’s assessment of the effectiveness of its internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act (15 U.S.C. 7262(b)) by the registered public accounting firm that prepared or issued its audit report.
| [PART IV](#PART_IV) | | 107 |
| [Signatures](#SIGNATURES) | | 117 |
“Merger” means the merger of Merger Sub with and into WPX, with WPX continuing as the surviving corporation and a wholly-owned subsidiary of the Company, pursuant to the terms of the Merger Agreement.
“Merger Agreement” means that certain Agreement and Plan of Merger, dated September 26, 2020, by and among the Company, Merger Sub and WPX.
“Merger Sub” means East Merger Sub, Inc., a wholly-owned subsidiary of the Company.
“WPX” means WPX Energy, Inc.
| | • | risks relating to the COVID-19 pandemic or other future pandemics; |
| | • | risks related to the Merger, including the risk that we may not realize the anticipated benefits of the Merger or successfully integrate the two legacy businesses; and |
The forward-looking statements included in this filing speak only as of the date of this report, represent current reasonable management’s expectations as of the date of this filing and are subject to the risks and uncertainties identified above as well as those described elsewhere in this report and in other documents we file from time to time with the SEC.
We cannot guarantee the accuracy of our forward-looking statements, and readers are urged to carefully review and consider the various disclosures made in this report and in other documents we file from time to time with the SEC.
On January 7, 2021, Devon and WPX completed an all-stock merger of equals.
WPX is an oil and gas exploration and production company with assets in the Delaware Basin in Texas and New Mexico and the Williston Basin in North Dakota.
This merger enhances the scale of our operations, builds a leading position in the Delaware Basin and accelerates our cash-return business model that prioritizes free cash flow generation and the return of capital to shareholders.
In accordance with the Merger Agreement, WPX shareholders received a fixed exchange of 0.5165 shares of Devon common stock for each share of WPX common stock owned.
The combined company continues to operate under the name Devon.
During 2019, we sold our Canadian business, generating $2.6 billion in proceeds.
During 2020, we sold our Barnett Shale assets, generating proceeds of $490 million and contingent earnout payments to Devon of up to $260 million based upon future commodity prices, with upside participation beginning at a $2.75 Henry Hub natural gas price or a $50 WTI oil price.
On January 7, 2021, Devon and WPX completed an all-stock merger of equals.
WPX is an oil and gas exploration and production company with assets in the Delaware Basin in Texas and New Mexico and the Williston Basin in North Dakota.
With the WPX Merger and continuous improvement initiatives, we are building a scalable, multi-basin portfolio of U.S. oil assets and aggressively improving our cost structure to further expand margins.
Human Capital
Delivering strong operational and financial results in a safe, environmentally and socially responsible way requires the expertise and positive contributions of every Devon employee.
Consequently, our people are the Company’s most important resource and we seek to hire the best people who share our core values of doing the right thing, delivering results and being good team members and neighbors to our communities.
To develop our workforce, we focus on training, safety, wellness, inclusion, diversity and equality.
Employee Safety and Wellness
We prepare our workforce to work safely with comprehensive training and orientation, on-the-job guidance and tools, safety engagements, recognition and other resources.
Employees and contractors are expected to comply with safety rules and regulations and are accountable to stopping at-risk work, immediately reporting incidents and near-miss events and informing visitors of emergency alarms and evacuation plans.
To safeguard workers on our well sites and neighbors nearby, we plan, design, drill, complete and produce wells using proven best practices, technologies, tools and materials.
In response to the COVID-19 pandemic, we have developed and implemented a number of safety measures to help our employees manage their work and personal responsibilities, with a strong focus on employee well-being, health and safety.
Refer to “COVID-19” included in Item 7.
“Management’s Discussion and Analysis of Financial Condition and Results of Operations” for information on actions taken by Devon to protect and support its employees during the COVID-19 pandemic.
Beyond employee safety, Devon also prioritizes the physical, mental and financial wellness of our employees.
We offer competitive health and financial benefits with incentives designed to promote wellbeing.
For example, we encourage employees to take advantage of our wellness programs and activities by getting an annual physical exam or completing a financial wellness series at no cost to employees.
Employee Compensation, Benefits and Development
We strive to attract and retain high-performing individuals across our workforce.
One way we do this is by providing competitive compensation and benefits, including annual bonuses; a 401(k) savings plan with a Devon match; stock awards; medical, dental and vision health care coverage; health savings and dependent-care flexible spending accounts; maternity and parental leave for the birth or adoption of a child; an adoption assistance program; alternate work schedules; flexible work hours; part-time work options; telecommuting support; among other benefits.
Devon also looks to our core values to build the workforce we need.
We develop our employees’ knowledge and creativity and advance continual learning and career development through ongoing performance, training and development conversations.
| [PART IV](#PART_IV) | | 102 |
| [Signatures](#SIGNATURES) | | 108 |
“ASR” means an accelerated share-repurchase transaction with a financial institution to repurchase Devon’s common stock.
“FASB” means Financial Accounting Standards Board.
“OPIS” means Oil Price Information Service.
“Tax Reform Legislation” means Tax Cuts and Jobs Act.
| | • | risks related to environmental regulations; |
In December 2019, we announced the sale of our Barnett Shale assets.
During 2019, we completed our transition to a U.S. oil company.
We sold our Canadian business, generating $2.6 billion in proceeds, and announced the sale of our Barnett Shale assets for approximately $770 million, before purchase price adjustments.
Throughout 2019, we continued to achieve efficiency gains in various aspects of our business.
Our initial production rates from new wells continued to improve in our four U.S. oil plays and have exceeded the average of the top 40 U.S. producers since 2015 by more than 40%.
We continued to improve cycle times, incorporate production optimization strategies and other cost reduction initiatives, driving down breakeven costs across our portfolio of assets.
As we focus on a more streamlined portfolio of U.S. oil assets, we are aggressively pursuing an improved cost structure to further expand margins.
During 2019, we reduced our consolidated debt by $1.7 billion, primarily from proceeds from our divestitures.
We also raised our quarterly dividend 12.5% and repurchased 69 million shares of common stock under our share repurchase program.
As of December 31, 2019, we had three operated rigs targeting the Turner, Parkman, Teapot and Niobrara formations in northern Converse County, Wyoming of the Powder River Basin.
Our Eagle Ford assets generated substantial cash flow in 2019.
In 2020, we plan approximately $300 million of capital investment.
| STACK | | | 11 | | | | 114 | | | | 13 | | | | 43 | |
| STACK | | | 12 | | | | 121 | | | | 14 | | | | 45 | |
| 2017 | | | | | | | | | | | | | | | | |
| STACK | | | 9 | | | | 107 | | | | 11 | | | | 38 | |
| U.S. | | | 42 | | | | 189 | | | | 21 | | | | 95 | |
| STACK | | $ | 48.43 | | | $ | 2.40 | | | $ | 17.78 | | | $ | 4.72 | |
| Delaware Basin | | $ | 48.38 | | | $ | 2.43 | | | $ | 16.44 | | | $ | 8.19 | |
| U.S. | | $ | 49.41 | | | $ | 2.57 | | | $ | 16.74 | | | $ | 6.49 | |
| | (1) | As further discussed in [Note 1](#SummaryOfSignificantAccountingPolicies) in “Item 8. Financial Statements and Supplementary Data” of this report, starting in 2018 the presentation of certain processing arrangements changed from a net to a gross presentation, which resulted in an increase to our upstream revenues and production expenses with no impact to net earnings. These changes primarily related to our STACK properties. |
| 2017 | | | 145.8 | | | | — | | | | 44.0 | | | | — | | | | 189.8 | | | | — | | | | 189.8 | |
| U.S. | | | 7,739 | | | | 2,376 | | | | 3,138 | | | | 1,281 | | | | 10,877 | | | | 3,657 | |
As of December 31, 2019, there were no proved undeveloped reserves associated with our expiring acreage.
In 2019, we allowed approximately 0.1 million acres to expire.
| U.S. | | | 1,055 | | | | 576 | | | | 2,956 | | | | 1,272 | | | | 4,011 | | | | 1,848 | |
Customers
During 2019 and 2017, no purchaser accounted for over 10% of our consolidated sales revenue.
During 2018, we had one purchaser that accounted for approximately 11% of our consolidated sales revenue.
In addition, permitting activities on federal lands can sometimes be subject to delays.
An excerpt. Shown here: 40 of 91 rewritten, 40 of 89 added and all 37 removed. The counts are complete. For every sentence, read Cover and table of contents in the FY2020 filing and the FY2019 filing.
Item 5. Market for Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities
11 rewritten, 14 added, 8 removed, 14 unchanged
On February [removed: 5, 2020,] [added: 3, 2021,] there were [removed: 6,771] [added: 12,611] holders of record of our common stock.
Additional information on our dividends can be found in [Note [removed: 17](#StockholdersEquity)] [added: 18](#StockholdersEquity)] in “Item 8.
The following graph compares the cumulative TSR over a five-year period on Devon’s common stock with the cumulative total returns of the S&P 500 Index and [removed: a] peer [removed: group] [added: groups] of companies to which we compare our performance.
[removed: The] [added: In 2019, the] peer group [removed: includes] [added: included] Apache Corporation, Chesapeake Energy Corporation, [removed: Concho Resources, Inc.,] ConocoPhillips, Continental Resources, Inc., [removed: Encana Corporation,] EOG Resources, Inc., Hess Corporation, Marathon Oil Corporation, Murphy Oil Corporation, [removed: Noble Energy, Inc.,] Occidental Petroleum [removed: Corporation] [added: Corporation, Ovintiv, Inc.] and Pioneer Natural Resources Company.
The graph was prepared assuming $100 was invested on December 31, [removed: 2014] [added: 2015] in Devon’s common stock, the peer [removed: group] [added: groups] and the S&P 500 Index, and dividends have been reinvested subsequent to the initial investment.
[removed: This new] [added: In 2020, this] peer group was [removed: selected] [added: recalibrated] to better align with Devon’s go-forward size and [removed: operations] [added: operations,] in light of our strategic transformation in [removed: 2019.][added: 2019, and due to consolidation within the industry.]
[removed: 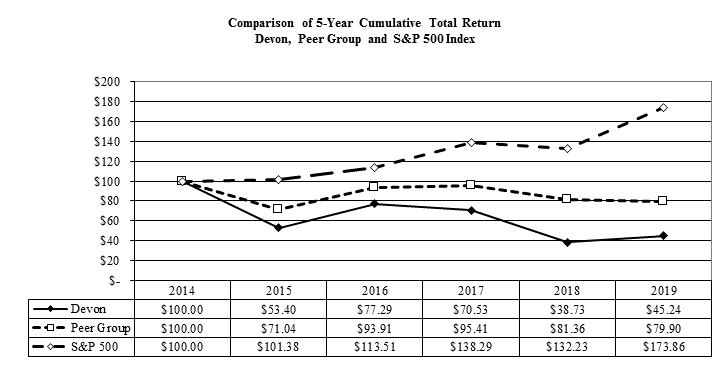][added: 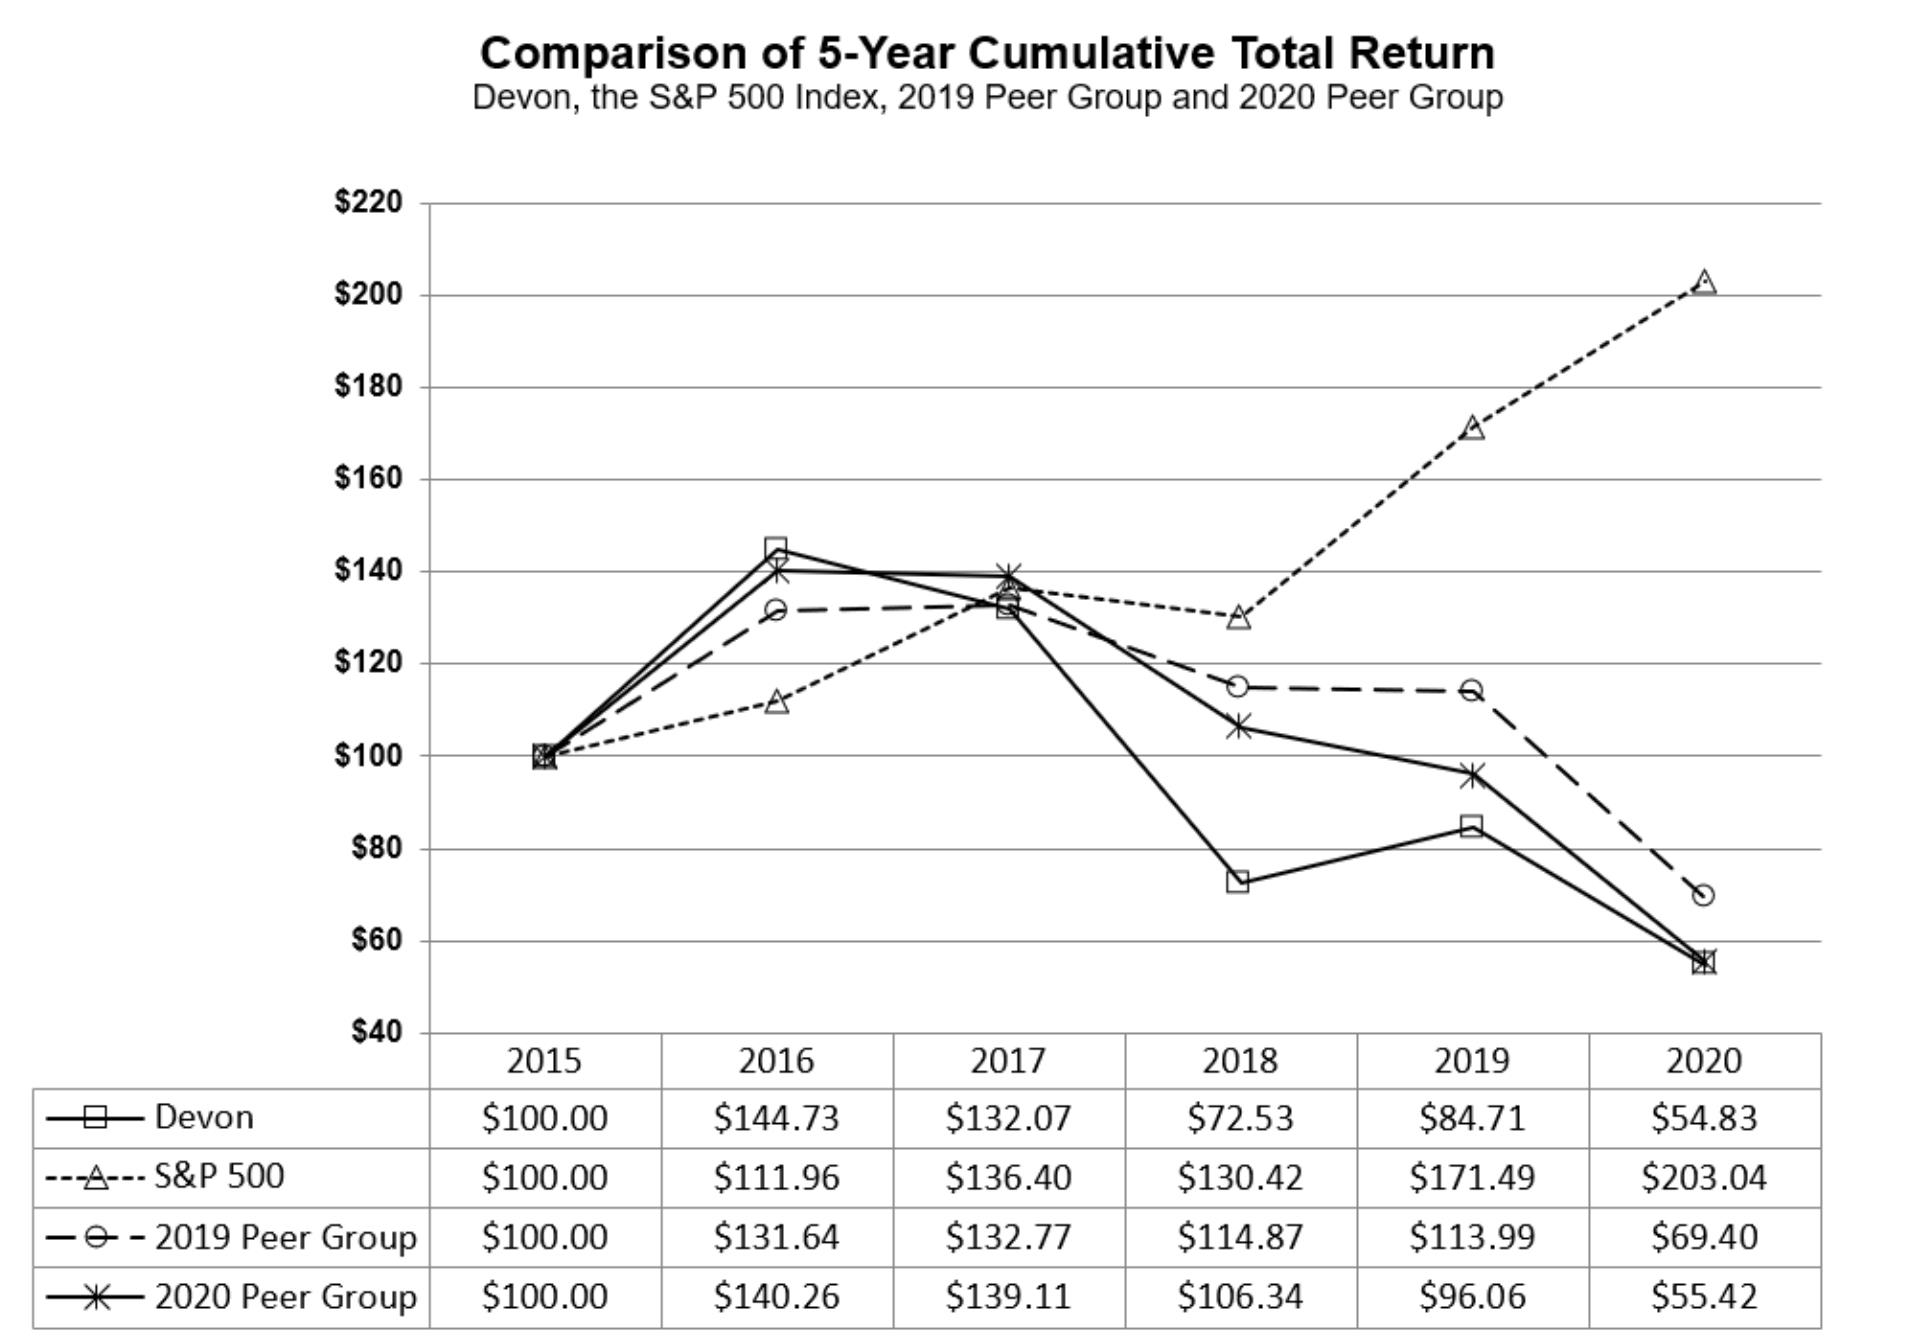]
The graph and information [removed: is] [added: are] included for historical comparative purposes only and should not be considered indicative of future stock performance.
The following table provides information regarding purchases of our common stock that were made by us during the fourth quarter of [removed: 2019] [added: 2020] (shares in thousands).
| | (1) | [removed: In addition to shares purchased under the share repurchase program described below, these] [added: These] amounts [removed: also included approximately 76,000] [added: reflect the] shares received by us from employees for the payment of personal income tax withholding on vesting transactions. |
Eligible employees purchased approximately [removed: 27,000] [added: 14,000] shares of our common stock in [removed: 2019,] [added: 2020,] at then-prevailing stock prices, that they held through their ownership in the Devon Stock Fund.
Following the closing of the Merger, Devon initiated a “fixed plus variable” dividend strategy.
Under this strategy, Devon plans to pay, on a quarterly basis, a fixed dividend amount and, potentially, a variable dividend amount, if any, to its stockholders.
The declaration and payment of any future dividend, whether fixed or variable, will remain at the full discretion of the Board of Directors and will depend on Devon’s financial results, cash requirements, future prospects, COVID-19 impacts and other factors deemed relevant by the Devon Board.
In determining the amount of the quarterly fixed dividend, the Board expects to consider a number of factors, including Devon’s financial condition, the commodity price environment and a general target of paying out approximately 10% of operating cash flow through the fixed dividend.
Any variable dividend amount will be determined on a quarterly basis and will equal up to 50% of “excess free cash flow,” which is a non-GAAP measure and is computed as operating cash flow (a GAAP measure) before balance sheet changes, less capital expenditures and the fixed dividend.
A number of factors will be considered when determining if a variable dividend payment will be made.
Devon expects that the most critical factors will consist of Devon’s financial condition, including its cash balances and leverage metrics, as well as the commodity price outlook.
The new 2020 peer group includes Apache Corporation, Chesapeake Energy Corporation, Cimarex Energy Co., Continental Resources, Inc., EOG Resources, Inc., Marathon Oil Corporation, Occidental Petroleum Corporation, Ovintiv, Inc. and Pioneer Natural Resources.
Anadarko Petroleum Corporation, Concho Resources, Inc. and Noble Energy, Inc. were previously included in these peer groups, but have been excluded as a result of being acquired as part of the continuing consolidation in the industry.
| October 1 - October 31 | | | 63 | | | $ | 8.98 | | | | — | | | $ | 962 | |
| November 1 - November 30 | | | 17 | | | $ | 14.41 | | | | — | | | $ | 962 | |
| December 1 - December 31 | | | 8 | | | $ | 14.93 | | | | — | | | $ | — | |
| Total | | | 88 | | | $ | 10.58 | | | | — | | | | | |
| | (2) | On December 17, 2019, we announced a $1.0 billion share repurchase program that expired on December 31, 2020. We repurchased 2.2 million common shares for $38 million, or $16.85 per share, under this share repurchase program. For additional information, see [Note 18](#StockholdersEquity) in “Item 8. Financial Statements and Supplementary Data” of this report. |
The declaration of future dividends is a business decision made by our Board of Directors, and will depend on Devon’s financial condition and other relevant factors.
Anadarko Petroleum Corporation was a part of this peer group prior to being acquired by Occidental Petroleum Corporation in 2019.
Commencing in 2020, Devon will use a recalibrated peer group for performance and compensation purposes.
| October 1 - October 31 | | | 4,285 | | | $ | 21.27 | | | | 4,244 | | | $ | 199 | |
| November 1 - November 30 | | | 218 | | | $ | 22.33 | | | | 192 | | | $ | 195 | |
| December 1 - December 31 | | | 9 | | | $ | 22.58 | | | | — | | | $ | 1,000 | |
| Total | | | 4,512 | | | $ | 21.32 | | | | 4,436 | | | | | |
| | (2) | On March 7, 2018, we announced a $1.0 billion share repurchase program. On June 6, 2018, we announced the expansion of this program to $4.0 billion. On February 19, 2019, we announced a further expansion to $5.0 billion with a December 31, 2019 expiration date. Of the $5.0 billion authorized amount, $4.8 billion was repurchased when the program expired on December 31, 2019. On December 17, 2019, we announced a new $1.0 billion share repurchase program with a December 31, 2020 expiration date. Under the new program, $800 million of the $1.0 billion authorization is conditioned upon the closing of the pending Barnett Shale divestiture. During 2019, we repurchased 68.6 million shares of common stock for $1.8 billion, or $26.62 per share. Future purchases under the program will be made in the open market, private transactions or through the use of ASR programs. |
Item 6. Selected Financial Data
0 rewritten, 1 added, 23 removed, 1 unchanged
Not applicable.
The financial information below should be read in conjunction with “Item 7.
Management’s Discussion and Analysis of Financial Condition and Results of Operations” and “Item 8.
Financial Statements and Supplementary Data” of this report.
| | | 2019 | | | | 2018 | | | | 2017 | | | | 2016 | | | | 2015 | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Statement of Earnings data: | | | | | | | | | | | | | | | | | | | | |
| Upstream revenues (1) | | $ | 3,355 | | | $ | 4,542 | | | $ | 2,988 | | | $ | 2,325 | | | $ | 4,082 | |
| Total revenues (1) | | $ | 6,220 | | | $ | 8,896 | | | $ | 6,501 | | | $ | 5,054 | | | $ | 7,547 | |
| Net earnings (loss) from continuing operations (2) | | $ | (79 | ) | | $ | 714 | | | $ | 33 | | | $ | (871 | ) | | $ | (7,989 | ) |
| Net earnings (loss) from continuing operations per share: | | | | | | | | | | | | | | | | | | | | |
| Basic (2) | | $ | (0.21 | ) | | $ | 1.43 | | | $ | 0.06 | | | $ | (1.72 | ) | | $ | (19.66 | ) |
| Diluted (2) | | $ | (0.21 | ) | | $ | 1.42 | | | $ | 0.06 | | | $ | (1.72 | ) | | $ | (19.66 | ) |
| Cash dividends per common share | | $ | 0.35 | | | $ | 0.30 | | | $ | 0.24 | | | $ | 0.42 | | | $ | 0.96 | |
| Balance Sheet data: | | | | | | | | | | | | | | | | | | | | |
| Total assets (3) | | $ | 13,717 | | | $ | 19,566 | | | $ | 30,241 | | | $ | 28,675 | | | $ | 29,673 | |
| Long-term debt (4) | | $ | 4,294 | | | $ | 4,292 | | | $ | 5,258 | | | $ | 5,359 | | | $ | 7,488 | |
| Stockholders' equity | | $ | 5,920 | | | $ | 9,186 | | | $ | 14,104 | | | $ | 12,722 | | | $ | 11,111 | |
| Common shares outstanding | | | 382 | | | | 450 | | | | 525 | | | | 523 | | | | 418 | |
| | (1) | In January 2018, Devon adopted ASC 606 – *Revenue from Contracts with Customers* using the modified retrospective method and has applied the standard to all existing contracts. The impact of adoption is further discussed in [Note 1](#SummaryOfSignificantAccountingPolicies) of “Item 8. Financial Statements and Supplementary Data” of this report. Prior periods have not been restated. |
| --- | --- | --- |
| | (2) | Material asset impairments and acquisition and divestiture activity had significant impacts on operating results and the carrying value of our oil and gas assets. Specifically, there were asset impairments of $0.3 billion, $0.2 billion, $0.5 billion and $10.3 billion in 2018, 2017, 2016 and 2015, respectively. More discussion on these items can be found in “Item 7. Management’s Discussion and Analysis of Financial Condition and Results of Operations” and in [Note 2](#Acquisitions_Divestitures) and [Note 5](#AssetImpairments) of “Item 8. Financial Statements and Supplementary Data” of this report. |
| | (3) | Amounts include assets related to our divested Canadian business and aggregate ownership interest in EnLink and the General Partner as well as our recently announced Barnett Shale assets that will be divested in 2020. For additional information, see [Note 18](#Discops) of “Item 8. Financial Statements and Supplementary Data” of this report. These divestitures resulted in the reclassification of the respective assets to assets associated with discontinued operations, which are included within this amount. |
| | (4) | Long-term debt balance excludes amounts that were classified as liabilities associated with discontinued operations in the respective periods related to the sale of Devon’s Canadian business and ownership interests in EnLink and the General Partner. See [Note 18](#Discops) of “Item 8. Financial Statements and Supplementary Data” of this report for additional details. |
Item 8. Financial Statements and Supplementary Data
653 rewritten, 319 added, 251 removed, 921 unchanged
| [Report of Independent Registered Public Accounting Firm](#Report_of_Independent_Registered_Public) | | [removed: 48] [added: 50] |
| [Consolidated Statements of Comprehensive Earnings](#Comprehensive_Statements) | | [removed: 51] [added: 54] |
| [Consolidated Statements of Cash Flows](#CONSOLIDATED_STATEMENTS_CASH_FLOWS) | | [removed: 52] [added: 55] |
| [Consolidated Balance Sheets](#CONSOLIDATED_BALANCE_SHEETS) | | [removed: 53] [added: 56] |
| [Consolidated Statements of Equity](#CONSOLIDATED_STATEMENTS_OF_STOCKHOLDERS) | | [removed: 54] [added: 57] |
| [Notes to Consolidated Financial Statements](#Note) | | [removed: 55] [added: 58] |
| [Note 1 – Summary of Significant Accounting Policies](#SummaryOfSignificantAccountingPolicies) | | [removed: 55] [added: 58] |
| [Note 2 – Divestitures](#Acquisitions_Divestitures) | | [removed: 65] [added: 67] |
| [Note 3 – Derivative Financial Instruments](#Derivatives) | | [removed: 66] [added: 69] |
| [Note 4 – Share-Based Compensation](#ShareBasedComp) | | [removed: 67] [added: 70] |
| [Note 5 – Asset Impairments](#AssetImpairments) | | [removed: 70] [added: 73] |
| [Note 6 – Restructuring and Transaction Costs](#Restructuring) | | [removed: 70] [added: 74] |
| [Note [removed: 7] [added: 8] – Income Taxes](#Income_Taxes) | | [removed: 71] [added: 75] |
| [Note [removed: 8] [added: 9] – Net Earnings (Loss) Per Share From Continuing Operations](#EPS) | | [removed: 74] [added: 80] |
| [Note [removed: 9] [added: 10] – Other Comprehensive Earnings](#N10_OR_COMPREHENSIVE_EARNINGS) | | [removed: 75] [added: 81] |
| [Note [removed: 10] [added: 11] – Supplemental Information to Statements of Cash Flows](#SupplementalCashFlow) | | [removed: 75] [added: 82] |
| [Note [removed: 11] [added: 12] – Accounts Receivable](#AccountsReceivable) | | [removed: 76] [added: 82] |
| [Note [removed: 12] [added: 13] – Property, Plant and Equipment](#N13_PROPERTY_PLANT_EQUIPMENT) | | [removed: 76] [added: 83] |
| [Note [removed: 13] [added: 14] – Debt and Related Expenses](#Debt) | | [removed: 77] [added: 84] |
| [Note [removed: 14] [added: 15] – Leases](#Leases) | | [removed: 79] [added: 85] |
| [Note [removed: 15] [added: 16] – Asset Retirement Obligations](#ARO) | | [removed: 81] [added: 87] |
| [Note [removed: 16] [added: 17] – Retirement Plans](#RetirementPlans) | | [removed: 82] [added: 88] |
| [Note [removed: 17] [added: 18] – Stockholders’ Equity](#StockholdersEquity) | | [removed: 85] [added: 91] |
| [Note [removed: 18] [added: 19] – Discontinued Operations and Assets Held For Sale](#Discops) | | [removed: 87] [added: 93] |
| [Note [removed: 19] [added: 20] – Commitments and Contingencies](#Commitments) | | [removed: 91] [added: 96] |
| [Note [removed: 20] [added: 21] – Fair Value Measurements](#FairValue) | | [removed: 93] [added: 98] |
| [Note [removed: 21] [added: 22] – Supplemental Information on Oil and Gas Operations (Unaudited)](#SupplementalOilAndGas) | | [removed: 94] [added: 99] |
We have audited the accompanying consolidated balance sheets of Devon Energy Corporation and subsidiaries (the Company) as of December 31, [removed: 2019] [added: 2020] and [removed: 2018,] [added: 2019,] the related consolidated statements of comprehensive earnings, equity, and cash flows for each of the years in the three-year period ended December 31, [removed: 2019,] [added: 2020,] and the related notes (collectively, the consolidated financial statements).
We also have audited the Company’s internal control over financial reporting as of December 31, [removed: 2019,] [added: 2020,] based on criteria established in *Internal Control – Integrated [removed: Framework* *(2013)*] [added: Framework (2013)*] issued by the Committee of Sponsoring Organizations of the Treadway Commission.
In our opinion, the consolidated financial statements referred to above present fairly, in all material respects, the financial position of the Company as of December 31, [removed: 2019] [added: 2020] and [removed: 2018,] [added: 2019,] and the results of its operations and its cash flows for each of the years in the three-year period ended December 31, [removed: 2019,] [added: 2020,] in conformity with U.S. generally accepted accounting principles.
Also in our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2019] [added: 2020] based on criteria established in *Internal Control – Integrated Framework (2013)* issued by the Committee of Sponsoring Organizations of the Treadway Commission.
[removed: Changes] [added: Change] in Accounting Principles
As discussed in Note [removed: 14] [added: 1] to the consolidated financial statements, the Company has changed its method of accounting for leases in 2019 due to the adoption of Accounting Standards Update 2016-02, *Leases (Topic [removed: 842)*.][added: 842).*]
[added: A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the] maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and dispositions of the assets of the company; (2) provide reasonable assurance that transactions are recorded as necessary to permit preparation of financial statements in accordance with generally accepted accounting principles, and that receipts and expenditures of the company are being made only in accordance with authorizations of management and directors of the company; and (3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use, or disposition of the company’s assets that could have a material effect on the financial statements.
[removed: Evaluation] [added: Estimate] of [removed: the estimate] [added: future cash flows] of proved and unproved oil and gas reserves used to assess the recoverability of the carrying value [added: and to estimate the fair value] of [added: certain] oil and gas properties [removed: in the STACK common operating field]
As discussed in Notes 1, 5, and [removed: 12] [added: 13] to the consolidated financial statements, the Company performs recoverability tests for the carrying value of its [removed: proved] oil and gas properties [removed: subject to amortization.][added: for each relevant asset group.]
The recoverability tests are performed [removed: on an annual basis or more often] if events and circumstances indicate that the carrying value of [removed: such properties] [added: the asset group] may not be recoverable.
The determination of the undiscounted cash flows [added: for the recoverability test and the determination of fair value for impairment] is [added: largely] driven by the underlying estimate of proved and unproved oil and gas reserves [removed: for oil and gas properties] as determined by the Company’s internal reservoir engineers.
[removed: Estimating common operating fields’] [added: To estimate the oil and gas properties’] future cash [removed: flows requires the expertise of] [added: flows, internal] reservoir engineers [removed: who] take into consideration the estimate of [added: risk-adjusted] future production quantities, future operating and capital cost assumptions, and projected oil and gas prices inclusive of market differentials.
We identified the [removed: evaluation of the] estimate of [added: future cash flows from] proved and unproved oil and gas reserves used to assess the recoverability of the carrying value [added: and to estimate the fair value] of [added: certain of] the [removed: STACK common operating field’s] [added: company’s] oil and gas properties as a critical audit matter.
| [Note 7 – Other, Net](#Other_Expenses) | | 75 |
| | | |
The Company estimates the undiscounted future net cash flows expected to be generated from the oil and gas properties and compares such future net cash flows to the carrying amount of the oil and gas property to determine if the carrying amount is recoverable.
When the carrying amount of an oil and gas property exceeds its estimated undiscounted future net cash flows, the carrying amount is impaired to its estimated fair value by applying a discount rate to the undiscounted future cash flows.
During the first quarter of 2020, the Company recorded an impairment of approximately $2.7 billion related to its Anadarko Basin and Rockies oil and gas properties.
There was a high degree of subjective auditor judgment in evaluating the key assumptions used to estimate the undiscounted and discounted future cash flows of the proved and unproved oil and gas properties.
The key assumptions used in these estimates were current and forecasted commodity prices, forecasted operating and capital costs, future production quantities, risk adjustment factors associated with the proved and unproved reserve volumes, and the discount rate applied to determine fair value.
We evaluated the professional qualifications of the Company’s internal reservoir engineers and the knowledge, skills, and ability of the Company’s internal reservoir engineers.
In addition, we involved valuation professionals with specialized skills and knowledge, who assisted in:
—Evaluating the discount rate by comparing it against a discount rate range that was independently developed using publicly available market data for comparable entities.
—Evaluating the forecasted commodity price assumptions by comparing to the median and average of forward price estimates from analysts and other industry sources.
— Evaluating the overall fair value of proved and unproved oil and gas properties by reconciling it to the Company’s market capitalization as of the measurement date.
The Company also periodically evaluates whether changes in the estimated proved oil and gas reserves for each common operating field have occurred that would require a change in the rate of depletion to be applied to the production realized.
We evaluated (1) the professional qualifications of the Company’s internal reservoir engineers as well as the external reservoir engineers and external engineering firm, (2) the knowledge, skills, and ability of the Company’s internal and external reservoir engineers, and (3) the relationship of the external reservoir engineers and external engineering firm to the Company.
Evaluation of potential impairment of goodwill for the U.S. reporting unit
As discussed in Note 1 to the consolidated financial statements, the total goodwill balance was approximately $753 million as of December 31, 2020.
During the completion of the first quarter qualitative goodwill impairment assessment, the Company determined an evaluation of goodwill for potential impairment was required for the U.S. reporting unit as a result of declines in the trading price of its common stock.
Evaluating goodwill for potential impairment involves comparing the fair value of the reporting unit to its carrying value.
If the fair value is less than the carrying value, an impairment charge will be recognized for the amount by which the carrying amount exceeds the fair value.
The fair value is estimated based upon valuation analysis involving the trading price of the Company’s outstanding equity shares, and consideration of a control premium determined by reviewing comparable companies and transactions.
A key assumption in the valuation analysis is the control premium, which is derived from the assessment of control premiums from comparable companies’ recent transactions.
In performing the evaluation of goodwill for impairment in the first quarter, the Company concluded that the fair value of the U.S. reporting unit exceeded the carrying value and therefore no impairment was recognized.
We identified the evaluation of potential impairment of goodwill for the U.S. reporting unit as a critical audit matter.
Specifically, a high degree of auditor judgment and specialized skills were required to evaluate the control premium used to estimate of the fair value of the reporting unit.
Changes to the control premium could have a significant effect on the Company’s estimate of the fair value of the U.S. reporting unit.
The following are the primary procedures we performed to address this critical audit matter.
We evaluated the design and tested the operating effectiveness of certain internal controls over the Company’s goodwill impairment process, including controls related to the control premium.
We performed a sensitivity analysis to determine the significant assumptions used to evaluate goodwill impairment, individually and in the aggregate, which required challenging auditor judgment.
We involved a valuation professional with specialized skills and knowledge, who assisted in:
—Evaluating the control premium used by comparing it to a control premium that was independently developed using publicly available market data
—Developing an estimate of the fair value of the reporting unit and comparing it to the Company’s fair value estimate.
February 17, 2021
| Other, net | | | (34 | ) | | | 4 | | | | (7 | ) |
| Net earnings (loss) | | $ | (2,671 | ) | | $ | (353 | ) | | $ | 3,224 | |
| Depreciation, depletion and amortization | | | 1,300 | | | | 1,497 | | | | 1,228 | |
| Asset impairments | | | 2,693 | | | | — | | | | 156 | |
| Income taxes receivable | | | 174 | | | | 47 | |
| | | (Unaudited) | | | | | | | | | | | | | | | | | | | | | | | | | | | | | | |
| Net earnings (loss) | | | — | | | | — | | | | — | | | | (2,680 | ) | | | — | | | | — | | | | 9 | | | | (2,671 | ) |
| Contributions from noncontrolling interests | | | — | | | | — | | | | — | | | | — | | | | — | | | | — | | | | 21 | | | | 21 | |
| --- | --- | --- |
| [Note 22 – Supplemental Quarterly Financial Information (Unaudited)](#QuarterlyFinancialInfo) | | 99 |
As discussed in Note 1 to the consolidated financial statements, the Company has changed its method of accounting for revenue in 2018 due to the adoption of Accounting Standards Codification 606, *Revenue from Contracts with Customers (ASC 606)*.
A company’s internal control over financial reporting includes those policies and procedures that (1) pertain to the
The STACK common operating field had a carrying value of $3.7 billion as of December 31, 2019.
Based on current and forecasted commodity prices and costs, production volumes and drilling plans, and the risk adjustment factors associated with the unproved reserve volumes, the STACK common operating field required more judgment to evaluate the estimate of both proved and unproved oil and gas reserves used in determining undiscounted future net cash flows for the asset group.
In addition, we assessed the competence, objectivity, and capabilities of the Company’s internal reservoir engineers and third-party reservoir engineers.
We have also evaluated the Company’s selected risk adjustment factors by evaluation of the proximity of the unproved reserves to proved producing reserves.
We analyzed the grouping of costs and proved oil and gas reserves by common operating field.
In addition, we assessed the competence, objectivity, and capabilities of the Company’s internal reservoir engineers and the Company’s external reservoir engineers.
We read and considered the report of the Company’s third-party reservoir engineers in connection with our evaluation of the Company’s reserve estimates.
February 19, 2020
| Upstream revenues | | $ | 3,355 | | | $ | 4,542 | | | $ | 2,988 | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- |
| | | | | | | | | |
| Cash restricted for discontinued operations | | | 380 | | | | — | |
| Short-term debt | | | — | | | | 162 | |
| Long-term liabilities associated with discontinued operations | | | 185 | | | | 2,454 | |
| Treasury stock, at cost, 1.0 million shares in 2018 | | | — | | | | (22 | ) |
| Balance as of December 31, 2016 | | | 523 | | | $ | 52 | | | $ | 7,237 | | | $ | (69 | ) | | $ | 1,054 | | | $ | — | | | $ | 4,448 | | | $ | 12,722 | |
| Net earnings | | | — | | | | — | | | | — | | | | 898 | | | | — | | | | — | | | | 180 | | | | 1,078 | |
| Subsidiary equity transactions | | | — | | | | — | | | | 14 | | | | — | | | | — | | | | — | | | | 576 | | | | 590 | |
| --- | --- |
aggregates its U.S. operating segments into one reporting segment due to the similar nature of its business.
With the reclassification of Devon’s Canadian operations to discontinued operations and assets and liabilities associated with discontinued operations, Devon now has one reporting segment, which is reflected in the consolidated financial statements.
Impact of ASC 606 Adoption
In January 2018, Devon adopted ASC 606 – *Revenue from Contracts with Customers (ASC 606)* using the modified retrospective method and applied the standard to all existing contracts at adoption.
ASC 606 supersedes previous revenue recognition requirements in ASC 605 and includes a five-step revenue recognition model to depict the transfer of goods or services to customers in an amount that reflects the consideration in exchange for those goods or services.
The changes to upstream revenues and production expenses were due to the conclusion that Devon represents the principal and controls a promised product before transferring it to the ultimate third party customer in accordance with the control model in ASC 606.
This was a change from previous conclusions reached for these agreements utilizing the principal versus agent indicators under ASC 605 where the assessment was focused on Devon passing title and not control to the processing entity and Devon ultimately receiving a net price from the third-party end customer.
As a result, Devon changed the presentation of revenues and expenses for these agreements.
Revenues related to these agreements are presented on a gross basis for amounts expected to be received from third-party customers through the marketing process.
Gathering, processing and transportation expenses related to these agreements, incurred prior to the transfer of control to the customer at the tailgate of the natural gas processing facilities, are presented as production expenses.
During 2018, these changes resulted in a $191 million increase to upstream revenues and production expenses with no impact to net earnings.
As a result of
the adoption of ASC 606, Devon’s marketing and midstream revenues and marketing and midstream expenses were not impacted.
a specified point or performance has occurred, control has transferred and collectability of the revenue is probable.
| Upstream revenues | | | 3,355 | | | | 4,542 | |
Diluted earnings per share is calculated using the
In conjunction primarily with the sale of its Canadian operations in June 2019, approximately $380 million of Devon’s cash balance is restricted for funding certain tax and other obligations related to the disposed assets.
An excerpt. Shown here: 40 of 653 rewritten, 40 of 319 added and 40 of 251 removed. The counts are complete. For every sentence, read Item 8. Financial Statements and Supplementary Data in the FY2020 filing and the FY2019 filing.
Item 9A. Controls and Procedures
4 rewritten, 0 added, 0 removed, 7 unchanged
Based on their evaluation, our principal executive and principal financial officers have concluded that our disclosure controls and procedures (as defined in Rules 13a-15(e) and 15d-15(e) under the Securities Exchange Act of 1934) were effective as of December 31, [removed: 2019] [added: 2020] to ensure that the information required to be disclosed by Devon in the reports that it files or submits under the Securities Exchange Act of 1934 is recorded, processed, summarized and reported within the time periods specified in the SEC rules and forms.
Based on this evaluation under the 2013 COSO Framework, which was completed on February [removed: 19, 2020,] [added: 17, 2021,] management concluded that its internal control over financial reporting was effective as of December 31, [removed: 2019.][added: 2020.]
The effectiveness of our internal control over financial reporting as of December 31, [removed: 2019] [added: 2020] has been audited by KPMG LLP, an independent registered public accounting firm who audited our consolidated financial statements as of and for the year ended December 31, [removed: 2019,] [added: 2020,] as stated in their report, which is included under “Item 8.
There was no change in our internal control over financial reporting during the fourth quarter of [removed: 2019] [added: 2020] that has materially affected, or is reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. Other Information
0 rewritten, 8 added, 3 removed, 2 unchanged
On December 30, 2020, Devon held a special meeting of stockholders (the “Meeting”) to consider and approve the issuance of shares of Devon common stock in the Merger (the “Stock Issuance”).
More than 70% of the outstanding shares of Devon common stock were present at the Meeting, and over 99% of the votes cast were in favor of approval of the Stock Issuance.
During the weeks following the closing of the Merger, Devon learned that several stockholders had received their proxy materials for the Meeting after the date of the Meeting.
Upon investigation, Devon learned that, while the electronic distribution of proxy materials to stockholders had been timely completed, certain stockholders who were to receive proxy materials by mail had not timely received those materials.
The company retained by Devon to process and distribute proxy materials for the Meeting has indicated that, contrary to prior communication on the subject, certain of the proxy materials were not timely delivered to the U.S. Postal Service, resulting in late delivery of such proxy materials to the holders of less than 15% of the outstanding shares of Devon common stock, including record holders of approximately 0.55% of the outstanding
shares.
In light of Devon’s good faith belief that the proxy materials had been mailed, the overwhelming vote by the Devon stockholders in favor of approval of the Stock Issuance proposal at the Meeting, which approval could not have been altered by the votes of the affected stockholders, and the closing of the Merger and other significant actions taken in reliance upon the approval of the Stock Issuance at the Meeting, Devon is filing an application with the Delaware Chancery Court under Section 205 of the Delaware General Corporation Law seeking an order confirming the validity of the Meeting and the notice of meeting issued in connection therewith.
[Index to Financial Statements](#IndexToFinancialStatements)
On February 18, 2020, we entered into indemnification agreements with each of our directors.
Subject to various terms and conditions, the indemnification agreements provide for, among other things, (i) indemnification rights for the directors with respect to certain claims and liabilities to the fullest extent permitted by Delaware law, (ii) the right to advancement of expenses for the directors with respect to certain claims and liabilities, (iii) clarification for the processes used to determine whether a director is entitled to indemnification and (iv) the maintenance of directors and officers liability insurance coverage for the directors.
The foregoing description of the indemnification agreements is not complete and is subject to and qualified in its entirety by reference to a form of the indemnification agreement, a copy of which is attached hereto as Exhibit 10.40 and the terms of which are incorporated herein by reference.
Item 10. Directors, Executive Officers and Corporate Governance
1 rewritten, 0 added, 0 removed, 0 unchanged
The information called for by this Item 10 is incorporated herein by reference to the definitive Proxy Statement to be filed by Devon pursuant to Regulation 14A of the General Rules and [added: applicable information in] Regulations under the Securities Exchange Act of 1934 no later than 120 days following the fiscal year ended December 31, [removed: 2019.][added: 2020.]
Item 11. Executive Compensation
1 rewritten, 0 added, 0 removed, 0 unchanged
The information called for by this Item 11 is incorporated herein by reference to the definitive Proxy Statement to be filed by Devon pursuant to Regulation 14A of the General Rules and [added: applicable information in] Regulations under the Securities Exchange Act of 1934 no later than 120 days following the fiscal year ended December 31, [removed: 2019.][added: 2020.]
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters
1 rewritten, 0 added, 0 removed, 0 unchanged
The information called for by this Item 12 is incorporated herein by reference to the definitive Proxy Statement to be filed by Devon pursuant to Regulation 14A of the General Rules and [added: applicable information in] Regulations under the Securities Exchange Act of 1934 no later than 120 days following the fiscal year ended December 31, [removed: 2019.][added: 2020.]
Item 13. Certain Relationships and Related Transactions, and Director Independence
1 rewritten, 0 added, 0 removed, 0 unchanged
The information called for by this Item 13 is incorporated herein by reference to the definitive Proxy Statement to be filed by Devon pursuant to Regulation 14A of the General Rules and [added: applicable information in] Regulations under the Securities Exchange Act of 1934 no later than 120 days following the fiscal year ended December 31, [removed: 2019.][added: 2020.]
Item 14. Principal Accountant Fees and Services
1 rewritten, 0 added, 0 removed, 2 unchanged
The information called for by this Item 14 is incorporated herein by reference to the definitive Proxy Statement to be filed by Devon pursuant to Regulation 14A of the General Rules and [added: applicable information in] Regulations under the Securities Exchange Act of 1934 no later than 120 days following the fiscal year ended December 31, [removed: 2019.][added: 2020.]
Item 15. Exhibits and Financial Statement Schedules
60 rewritten, 102 added, 0 removed, 140 unchanged
| 2.2 | | Agreement of Purchase and Sale, dated as of May 28, 2019, among Devon Canada Corporation, Devon Canada Crude Marketing Corporation and Canadian Natural Resources Limited ([incorporated by reference to Exhibit 2.1 to [removed: the Company’s] [added: Registrant’s] Form 8-K filed May 31, 2019; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312519162861/d754489dex21.htm)). |
| 2.3 | | Purchase and Sale Agreement, dated December 17, 2019, by and between Devon Energy Production Company, L.P. and BKV Barnett, LLC ([incorporated by reference to Exhibit 2.1 to [removed: the Company’s] [added: Registrant’s] Form 8-K filed December 18, 2019; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312519317560/d842688dex21.htm)).* |
| 4.10 | | Assignment and Assumption Agreement, dated as of June 19, 2019, by and between Devon Financing Company, L.L.C. and Registrant, relating to that certain Indenture, dated as of October 3, 2001, by and among Devon Financing Company, L.L.C. (f/k/a Devon Financing Company, U.L.C.), as Issuer, Devon Energy Corporation, as Guarantor, and The Bank of New York Mellon Trust Company, N.A., as successor to The Chase Manhattan Bank, as Trustee, and the 7.875% Debentures due 2031 issued thereunder ([incorporated by reference to Exhibit 4.1 to [removed: the Company’s] [added: Registrant’s] Form 10-Q filed August 7, 2019; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459019029786/dvn-ex41_662.htm)). |
| [removed: 4.15] [added: 4.24] | | [Description of Securities Registered under Section 12 of the Securities Exchange Act of [removed: 1934](https://www.sec.gov/Archives/edgar/data/1090012/000156459020005182/dvn-ex415_879.htm).] [added: 1934.](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex424_739.htm)] |
| 10.2 | | [removed: [First] [added: First] Amendment to Credit Agreement and Extension Agreement, dated as of December 13, 2019, by and among Registrant, as U.S. Borrower, Devon Canada Corporation, as Canadian Borrower, Bank of America, N.A., individually and as Administrative Agent, and the Lenders party [removed: thereto.](https://www.sec.gov/Archives/edgar/data/1090012/000156459020005182/EX10_2.htm)] [added: thereto ([incorporated by reference to Exhibit 10.2 to Registrant’s Form 10-K filed February 19, 2020; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459020005182/EX10_2.htm)).] |
| [removed: 10.4] [added: 10.5] | | Devon Energy Corporation 2015 Long-Term Incentive Plan ([incorporated by reference to Exhibit 99.1 to Registrant’s Form S-8 filed June 3, 2015; File No. 333-204666](http://www.sec.gov/Archives/edgar/data/1090012/000119312515211541/d934016dex991.htm)). |
| [removed: 10.5] [added: 10.6] | | Devon Energy Corporation 2017 Long-Term Incentive Plan ([incorporated by reference to Exhibit 99.1 to Registrant’s Form S-8 filed June 7, 2017; File No. 333-218561](http://www.sec.gov/Archives/edgar/data/1090012/000119312517197005/d260413dex991.htm)). |
| [removed: 10.6] [added: 10.4] | | 2013 Amendment (effective as of March 6, 2013) to the Devon Energy Corporation 2009 Long-Term Incentive Plan (as amended and restated effective June 6, 2012) ([incorporated by reference to Exhibit 10.1 to Registrant’s Form 10-Q filed May 1, 2013; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312513192272/d524180dex101.htm)). |
| [removed: 10.7] [added: 10.10] | | Devon Energy Corporation Annual Incentive Compensation Plan (amended and restated effective as of January 1, 2017) ([incorporated by reference to Exhibit 10.1 to Registrant’s Form 8-K filed June 12, 2017; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312517201470/d391476dex101.htm)). |
| [removed: 10.8] [added: 10.11] | | Devon Energy Corporation Non-Qualified Deferred Compensation Plan (amended and restated effective as of April 15, 2014) ([incorporated by reference to Exhibit 10.1 to Registrant’s Form 10-Q filed August 6, 2014; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312514298369/d761940dex101.htm)). |
| [removed: 10.9] [added: 10.12] | | Amendment 2014-2, executed May 9, 2014, to the Devon Energy Corporation Non-Qualified Deferred Compensation Plan [removed: (amended and restated effective April 15, 2014)] ([incorporated by reference to Exhibit 10.11 to Registrant’s Form 10-K filed February 20, 2015; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312515056497/d859923dex1011.htm)). |
| [removed: 10.10] [added: 10.13] | | Amendment 2016-1, executed October 20, 2016, to the Devon Energy Corporation Non-Qualified Deferred Compensation Plan [removed: (amended and restated effective April 15, 2014)] ([incorporated by reference to Exhibit 10.13 to Registrant’s Form 10-K filed February 15, 2017; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459017001607/dvn-ex1013_1996.htm)). |
| [removed: 10.11] [added: 10.14] | | Amendment 2018-1, executed August 21, 2018, to the Devon Energy Corporation Non-Qualified Deferred Compensation Plan [removed: (amended and restated effective April 15, 2014)] [(incorporated by reference to Exhibit 10.10 to Registrant’s Form 10-K filed February 20, 2019; File No. 001-32318)](http://www.sec.gov/Archives/edgar/data/1090012/000156459019003382/dvn-ex1010_985.htm). |
| [removed: 10.12] [added: 10.16] | | Devon Energy Corporation Benefit Restoration Plan (amended and restated effective January 1, 2012) ([incorporated by reference to Exhibit 10.15 to Registrant’s Form 10-K filed February 24, 2012; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312512077085/d298761dex1015.htm)). |
| [removed: 10.13] [added: 10.17] | | Amendment 2014-1, executed March 7, 2014, to the Devon Energy Corporation Benefit Restoration Plan [removed: (amended and restated effective January 1, 2012)] ([incorporated by reference to Exhibit 10.6 to Registrant’s Form 10-Q filed May 9, 2014; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312514192498/d718246dex106.htm)). |
| [removed: 10.14] [added: 10.18] | | Amendment 2015-1, executed April 15, 2015, to the Devon Energy Corporation Benefit Restoration Plan [removed: (amended and restated effective January 1, 2012)] ([incorporated by reference to Exhibit 10.1 to Registrant’s Form 10-Q filed May 6, 2015; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312515174003/d913733dex101.htm)). |
| [removed: 10.15] [added: 10.19] | | [removed: Amendment] [added: [Amendment] 2016-1, executed October 20, 2016, to the Devon Energy Corporation Benefit Restoration Plan (amended and restated effective January 1, 2012) [removed: ([incorporated] [added: (incorporated] by reference to Exhibit 10.17 to Registrant’s Form 10-K filed February 15, 2017; File No. [removed: 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459017001607/dvn-ex1017_1995.htm)).] [added: 001-32318).](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1015_518.htm)] |
| [removed: 10.16] [added: 10.21] | | Devon Energy Corporation Defined Contribution Restoration Plan (amended and restated effective January 1, 2012) ([incorporated by reference to Exhibit 10.16 to Registrant’s Form 10-K filed February 24, 2012; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312512077085/d298761dex1016.htm)). |
| [removed: 10.17] [added: 10.22] | | Amendment 2014-1, executed March 7, 2014, to the Devon Energy Corporation Defined Contribution Restoration Plan [removed: (amended and restated effective January 1, 2012)] ([incorporated by reference to Exhibit 10.7 to Registrant’s Form 10-Q filed May 9, 2014; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312514192498/d718246dex107.htm)). |
| [removed: 10.18] [added: 10.23] | | Amendment 2016-1, executed October 20, 2016, to the Devon Energy Corporation Defined Contribution Restoration Plan [removed: (amended and restated effective January 1, 2012)] ([incorporated by reference to Exhibit 10.20 to Registrant’s Form 10-K filed February 15, 2017; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459017001607/dvn-ex1020_1994.htm)). |
| [removed: 10.19] [added: 10.24] | | Amendment 2018-1, executed August 21, 2018, to the Devon Energy Corporation Defined Contribution Restoration Plan [removed: (amended and restated effective January 1, 2012)] [(incorporated by reference to Exhibit 10.18 to Registrant’s Form 10-K filed February 20, 2019; File No. 001-32318)](http://www.sec.gov/Archives/edgar/data/1090012/000156459019003382/dvn-ex1018_984.htm). |
| [removed: 10.20] [added: 10.25] | | [removed: Amendment] [added: [Amendment] 2019-1, executed June 19, 2019, to the Devon Energy Corporation Defined Contribution Restoration Plan (as amended and restated effective January 1, 2012) [removed: [(incorporated] [added: (incorporated] by reference to Exhibit 10.1 to Registrant’s Form 10-Q filed August 7, 2019; File No. [removed: 001-32318)](http://www.sec.gov/Archives/edgar/data/1090012/000156459019029786/dvn-ex101_660.htm).] [added: 001-32318).](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1020_517.htm)] |
| [removed: 10.21] [added: 10.27] | | Devon Energy Corporation Supplemental Contribution Plan (amended and restated effective January 1, 2012) ([incorporated by reference to Exhibit 10.17 to Registrant’s Form 10-K filed February 24, 2012; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312512077085/d298761dex1017.htm)). |
| [removed: 10.22] [added: 10.28] | | Amendment 2014-1, executed March 7, 2014, to the Devon Energy Corporation Supplemental Contribution Plan [removed: (amended and restated effective January 1, 2012)] ([incorporated by reference to Exhibit 10.8 to Registrant’s Form 10-Q filed May 9, 2014; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312514192498/d718246dex108.htm)). |
| [removed: 10.23] [added: 10.29] | | Amendment 2016-1, executed October 20, 2016, to the Devon Energy Corporation Supplemental Contribution Plan [removed: (amended and restated effective January 1, 2012)] ([incorporated by reference to Exhibit 10.23 to Registrant’s Form 10-K filed February 15, 2017; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459017001607/dvn-ex1023_1993.htm)). |
| [removed: 10.24] [added: 10.30] | | Amendment 2019-1, executed June 19, 2019, to the Devon Energy Corporation Supplemental Contribution Plan [removed: (as amended and restated effective January 1, 2012)] ([incorporated by reference to Exhibit 10.2 to Registrant’s Form 10-Q filed August 7, 2019; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459019029786/dvn-ex102_661.htm)). |
| [removed: 10.25] [added: 10.32] | | Devon Energy Corporation Supplemental Executive Retirement Plan (amended and restated effective January 1, 2012) ([incorporated by reference to Exhibit 10.18 to Registrant’s Form 10-K filed February 24, 2012; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312512077085/d298761dex1018.htm)). |
| [removed: 10.26] [added: 10.33] | | [removed: Amendment] [added: [Amendment] 2016-1, executed October 20, 2016, to the Devon Energy Corporation Supplemental Executive Retirement Plan (amended and restated effective January 1, 2012) [removed: ([incorporated] [added: (incorporated] by reference to Exhibit 10.25 to Registrant’s Form 10-K filed February 15, 2017; File No. [removed: 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459017001607/dvn-ex1025_1991.htm)).] [added: 001-32318).](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1026_515.htm)] |
| [removed: 10.27] [added: 10.34] | | Amendment 2019-1, executed June 19, 2019, to the Devon Energy Corporation Supplemental Executive Retirement Plan [removed: (as amended and restated effective January 1, 2012)] ([incorporated by reference to Exhibit 10.3 to Registrant’s Form 10-Q filed August 7, 2019; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459019029786/dvn-ex103_659.htm)). |
| [removed: 10.28] [added: 10.36] | | Devon Energy Corporation Supplemental Retirement Income Plan (amended and restated effective January 1, 2012) ([incorporated by reference to Exhibit 10.19 to Registrant’s Form 10-K filed February 24, 2012; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312512077085/d298761dex1019.htm)). |
| [removed: 10.29] [added: 10.37] | | Amendment 2014-1, executed March 7, 2014, to the Devon Energy Corporation Supplemental Retirement Income Plan [removed: (amended and restated effective January 1, 2012)] ([incorporated by reference to Exhibit 10.9 to Registrant’s Form 10-Q filed May 9, 2014; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312514192498/d718246dex109.htm)). |
| [removed: 10.30] [added: 10.38] | | Amendment 2016-1, executed October 20, 2016, to the Devon Energy Corporation Supplemental Retirement Income Plan [removed: (amended and restated effective January 1, 2012)] ([incorporated by reference to Exhibit 10.28 to Registrant’s Form 10-K filed February 15, 2017; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459017001607/dvn-ex1028_1992.htm)). |
| [removed: 10.31] [added: 10.39] | | [removed: Amendment] [added: [Amendment] 2019-1, effective September 10, 2019, to the Devon Energy Corporation Supplemental Retirement Income Plan (amended and restated effective January 1, 2012) [removed: ([incorporated] [added: (incorporated] by reference to Exhibit 10.2 to Registrant’s Form 10-Q filed November 6, 2019; File No. [removed: 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459019040774/dvn-ex102_398.htm)).] [added: 001-32318).](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1031_516.htm)] |
| [removed: 10.32] [added: 10.41] | | Devon Energy Corporation Incentive Savings Plan (amended and restated effective January 1, 2018) ([incorporated by reference to Exhibit 10.28 to Registrant’s Form 10-K filed February 21, 2018; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459018002582/dvn-ex1028_300.htm)). |
| [removed: 10.33] [added: 10.42] | | Amendment 2018-1, executed December 14, 2018, to the Devon Energy Corporation Incentive Savings Plan [removed: (amended and restated effective January 1, 2018)] ([incorporated by reference to Exhibit 10.28 to Registrant’s Form 10-K filed February 20, 2019; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459019003382/dvn-ex1028_983.htm)). |
| [removed: 10.34] [added: 10.43] | | Amendment 2019-1, executed June 19, 2019, to the Devon Energy Corporation Incentive Savings Plan [removed: (as amended and restated effective January 1, 2018)] ([incorporated by reference to Exhibit 10.4 to Registrant’s Form 10-Q filed August 7, 2019; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459019029786/dvn-ex104_658.htm)). |
| [removed: 10.35] [added: 10.44] | | [removed: Amended] [added: [Amended] and Restated Form of Employment Agreement between Registrant and certain executive officers [removed: ([incorporated] [added: (incorporated] by reference to Exhibit 10.19 to Registrant’s Form 10-K filed February 27, 2009; File No. [removed: 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000095013409003904/d66379exv10w19.htm)).] [added: 001-32318).](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1035_513.htm)] |
| [removed: 10.36] [added: 10.45] | | Form of Amendment No. 1 to the Amended and Restated Employment Agreement between Registrant and certain executive officers ([incorporated by reference to Exhibit 10.1 to Registrant’s Form 8-K filed April 25, 2011; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000095012311038626/d81608exv10w1.htm)). |
| [removed: 10.37] [added: 10.46] | | Form of Employment Agreement between Registrant and certain executive officers ([incorporated by reference to Exhibit 10.22 to Registrant’s Form 10-K filed February 28, 2014; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312514076267/d656849dex1022.htm)). |
| [removed: 10.38] [added: 10.47] | | Employment Agreement, dated [added: effective] April 19, 2017, by and between Registrant and Mr. Jeffrey L. Ritenour ([incorporated by reference to Exhibit 10.1 to Registrant’s Form 8-K, filed on April 20, 2017; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312517130689/d372080dex101.htm)). |
| 2.4 | | First Amendment to Purchase and Sale Agreement, dated April 13, 2020, by and between Devon Energy Production Company, L.P., BKV Barnett, LLC, and solely with respect to certain provisions therein, BKV Oil & Gas Capital Partners, L.P. ([incorporated by reference to Exhibit 2.1 to Registrant’s Current Report on Form 8-K filed April 14, 2020; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000156459020016686/dvn-ex21_7.htm)). |
| 2.5 | | Agreement and Plan of Merger, dated September 26, 2020, by and among Registrant, East Merger Sub, Inc., and WPX Energy, Inc. ([incorporated by reference to Exhibit 2.1 to Registrant’s Current Report on Form 8-K, filed September 28, 2020; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312520255422/d23566dex21.htm)). |
| 4.15 | | Stockholders’ Agreement, by and among Devon Energy Corporation, Felix Investment Holdings II, LLC, and EnCap Energy Capital Fund X, L.P., dated January 7, 2021. ([incorporated by reference to Exhibit 10.1 to Registrant’s Current Report on Form 8-K filed January 7, 2021; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312521004318/d106721dex101.htm)). |
| 4.16 | | Registration Rights Agreement, by and between Devon Energy Corporation and Felix Investment Holdings II, LLC, dated January 7, 2021 ([incorporated by reference to Exhibit 10.2 to Registrant’s Form 8-K filed January 7, 2021; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312521004318/d106721dex102.htm)). |
| 4.17 | | Indenture, dated as of September 8, 2014, between WPX Energy, Inc. and The Bank of New York Mellon Trust Company, N.A., as trustee ([incorporated herein by reference to Exhibit 4.1 to WPX Energy, Inc.’s Form 8-K filed September 8, 2014; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000119312514335680/d786023dex41.htm)). |
| 4.18 | | First Supplemental Indenture, dated as of September 8, 2014, between WPX Energy, Inc. and The Bank of New York Mellon Trust Company, N.A., as trustee, relating to the 5.25% Senior Notes due 2024 ([incorporated herein by reference to Exhibit 4.2 to WPX Energy, Inc.’s Form 8-K filed September 8, 2014; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000119312514335680/d786023dex42.htm)). |
| 4.19 | | Second Supplemental Indenture, dated as of July 22, 2015, between WPX Energy, Inc. and The Bank of New York Mellon Trust Company, N.A., as trustee, relating to the 8.25% Senior Notes due 2023 ([incorporated herein by reference to Exhibit 4.1 to WPX Energy, Inc.’s Form 8-K filed July 22, 2015; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000119312515260038/d75304dex41.htm)). |
| 4.20 | | Third Supplemental Indenture, dated as of May 23, 2018, between WPX Energy, Inc. and The Bank of New York Mellon Trust Company, N.A. as trustee, relating to the 5.750% Senior Notes due 2026 ([incorporated herein by reference to Exhibit 4.1 to WPX Energy, Inc.’s Form 8-K filed May 23, 2018; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000110465918035453/a18-13028_5ex4d1.htm)). |
| 4.21 | | Fourth Supplemental Indenture, dated as of September 24, 2019, between WPX Energy, Inc. and The Bank of New York Mellon Trust Company, N.A. as trustee, relating to the 5.250% Senior Notes due 2027 ([incorporated herein by reference to Exhibit 4.1 to WPX Energy, Inc.'s Form 8-K filed with the SEC on September 24, 2019; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000141057819001413/tv529864_ex4-1.htm)). |
| 4.22 | | Fifth Supplemental Indenture, dated as of January 10, 2020, between WPX Energy, Inc. and The Bank of New York Mellon Trust Company, N.A. as trustee, relating to the 4.500% Senior Notes due 2030 ([incorporated herein by reference to Exhibit 4.1 to WPX Energy, Inc.’s Form 8-K filed June 17, 2020; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000110465920003062/tm201152d5_ex4-1.htm)). |
| 4.23 | | Sixth Supplemental Indenture, dated as of June 17, 2020, between WPX Energy, Inc. and the Bank of New York Mellon Trust Company, N.A. as trustee, related to the 5.875% Senior Notes due 2028 ([incorporated herein by reference to Exhibit 4.1 to WPX Energy, Inc.’s Form 8-K filed January 10, 2020; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000110465920074179/tm2021306d6_ex4-1.htm)). |
| 10.7 | | [2021 Amendment (effective as of January 7, 2021) to the Devon Energy Corporation 2017 Long-Term Incentive Plan.](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex107_609.htm) |
| 10.8 | | WPX Energy, Inc. 2013 Incentive Plan, and amendments No. 1 and No. 2 thereto ([incorporated by reference to Exhibit 10.1 to WPX Energy, Inc.’s Form 8-K filed with the SEC on February 19, 2018; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000110465918011709/a18-5528_2ex10d1.htm)). |
| 10.9 | | Amendment No. 3 to the WPX Energy, Inc. 2013 Incentive Plan ([incorporated by reference to Appendix A to WPX Energy, Inc.’s definitive proxy statement on Schedule 14A filed March 29, 2018; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000104746918002302/a2234867zdef14a.htm#AA)). |
| 10.15 | | [Amendment 2020-1, executed December 23, 2020, to the Devon Energy Corporation Non-Qualified Deferred Compensation Plan.](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1015_518.htm) |
| 10.20 | | [Amendment 2020-1, executed December 23, 2020, to the Devon Energy Corporation Benefit Restoration Plan.](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1020_517.htm) |
| 10.26 | | [Amendment 2020-1, executed December 23, 2020, to the Devon Energy Corporation Defined Contribution Restoration Plan.](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1026_515.htm) |
| 10.31 | | [Amendment 2020-1, executed December 23, 2020, to the Devon Energy Corporation Supplemental Contribution Plan.](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1031_516.htm) |
| 10.35 | | [Amendment 2020-1, executed December 23, 2020, to the Devon Energy Corporation Supplemental Executive Retirement Plan.](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1035_513.htm) |
| 10.40 | | [Amendment 2020-1, executed December 23, 2020, to the Devon Energy Corporation Supplemental Retirement Income Plan.](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1040_514.htm) |
[Index to Financial Statements](#IndexToFinancialStatements)
| Exhibit No. | | Description |
| --- | --- | --- |
| 10.49 | | Employment Agreement, dated January 7, 2021, by and between Registrant and Richard E. Muncrief ([incorporated by reference to Exhibit 10.3 to Registrant’s Form 8-K filed January 7, 2021; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312521004318/d106721dex103.htm)). |
| 10.50 | | Employment Agreement, dated January 7, 2021, by and between Registrant and Clay M. Gaspar ([incorporated by reference to Exhibit 10.4 to Registrant’s Form 8-K filed January 7, 2021; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312521004318/d106721dex104.htm)). |
| 10.51 | | Employment Agreement, dated January 7, 2021, by and between Registrant and Dennis C. Cameron ([incorporated by reference to Exhibit 10.5 to Registrant’s Form 8-K filed January 7, 2021; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312521004318/d106721dex105.htm)). |
| 10.52 | | Employment Letter Agreement, dated as of September 26, 2020, by and between Registrant and David A. Hager ([incorporated by reference to Exhibit 10.2 to Registrant’s Form 8-K filed September 28, 2020; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312520255422/d23566dex102.htm)). |
| 10.53 | | Employment Letter Agreement, dated as of September 26, 2020, by and between Registrant and Richard E. Muncrief ([incorporated by reference to Exhibit 10.3 to Registrant’s Form 8-K filed September 28, 2020; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312520255422/d23566dex103.htm)). |
| 10.54 | | Employment Letter Agreement, dated as of September 26, 2020, by and between Registrant and Clay M. Gaspar ([incorporated by reference to Exhibit 10.4 to Registrant’s Form 8-K filed September 28, 2020; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312520255422/d23566dex104.htm)). |
| | | |
| 10.55 | | Employment Letter Agreement, dated as of September 26, 2020, by and between Registrant and Dennis C. Cameron ([incorporated by reference to Exhibit 10.45 to Registrant’s Form 8-K filed September 28, 2020; File No. 001-32318](http://www.sec.gov/Archives/edgar/data/1090012/000119312520255422/d23566dex105.htm)). |
| | | |
| 10.56 | | [Severance Agreement, dated March 2, 2010, between Registrant and Tana K. Cashion.](https://www.sec.gov/Archives/edgar/data/1090012/000156459021006239/dvn-ex1056_660.htm) |
| | | |
| 10.57 | | WPX Energy Nonqualified Deferred Compensation Plan, effective January 1, 2013 ([incorporated herein by reference to Exhibit 10.16 to WPX Energy, Inc.’s Form 10-K filed February 28, 2013; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000119312513084857/d448908dex1016.htm)). |
| | | |
| 10.58 | | WPX Energy Board of Directors Nonqualified Deferred Compensation Plan, effective January 1, 2013 ([incorporated herein by reference to Exhibit 10.17 to WPX Energy, Inc.’s Form 10-K filed February 28, 2013; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000119312513084857/d448908dex1017.htm)). |
| | | |
| 10.59 | | Employment Agreement, dated April 29, 2014, between WPX Energy, Inc. and Richard E. Muncrief ([incorporated herein by reference to Exhibit 10.1 to WPX Energy, Inc.’s Form 8-K filed May 2, 2014; File No. 001-35322](http://www.sec.gov/Archives/edgar/data/1518832/000119312514178447/d719641dex101.htm)). |
| | | |
An excerpt. Shown here: 40 of 60 rewritten, 40 of 102 added and all 0 removed. The counts are complete. For every sentence, read Item 15. Exhibits and Financial Statement Schedules in the FY2020 filing and the FY2019 filing.
Item 16. Form 10-K Summary
9 rewritten, 13 added, 10 removed, 32 unchanged
| /s/ [removed: DAVID A. HAGER] [added: RICHARD E. MUNCRIEF] | | President, Chief Executive Officer and | February [removed: 19, 2020] [added: 17, 2021] |
| [removed: David A. Hager] [added: Richard E. Muncrief] | | Director (Principal executive officer) | |
| /s/ JEFFREY L. RITENOUR | | Executive Vice President | February [removed: 19, 2020] [added: 17, 2021] |
| /s/ JEREMY D. HUMPHERS | | Senior Vice President | February [removed: 19, 2020] [added: 17, 2021] |
| /s/ BARBARA M. BAUMANN | | Director | February [removed: 19, 2020] [added: 17, 2021] |
| /s/ JOHN E. BETHANCOURT | | Director | February [removed: 19, 2020] [added: 17, 2021] |
| /s/ ANN G. FOX | | Director | February [removed: 19, 2020] [added: 17, 2021] |
| /s/ JOHN KRENICKI JR. | | Director | February [removed: 19, 2020] [added: 17, 2021] |
| /s/ ROBERT A. MOSBACHER, JR. | | Director | February [removed: 19, 2020] [added: 17, 2021] |
February 17, 2021
| /s/ DAVID A. HAGER | | Executive Chairman of the Board | February 17, 2021 |
| David A. Hager | | | |
| /s/ KELT KINDICK | | Director | February 17, 2021 |
| Kelt Kindick | | | |
| /s/ KARL F. KURZ | | Director | February 17, 2021 |
| Karl F. Kurz | | | |
| /s/ D. MARTIN PHILLIPS | | Director | February 17, 2021 |
| D. Martin Phillips | | | |
| /s/ DUANE C. RADTKE | | Director | February 17, 2021 |
| /s/ VALERIE M. WILLIAMS | | Director | February 17, 2021 |
| --- | --- | --- | --- |
| Valerie M. Williams | | | |
February 19, 2020
| /s/ DUANE C. RADTKE | | Chairman of the Board | February 19, 2020 |
| /s/ ROBERT H. HENRY | | Director | February 19, 2020 |
| Robert H. Henry | | | |
| /s/ MICHAEL M. KANOVSKY | | Director | February 19, 2020 |
| Michael M. Kanovsky | | | |
| /s/ KEITH O. RATTIE | | Director | February 19, 2020 |
| Keith O. Rattie | | | |
| /s/ MARY P. RICCIARDELLO | | Director | February 19, 2020 |
| Mary P. Ricciardello | | | |