 filings.tools
Xylem (XYL) 10-K risk factor changes: FY2015 vs FY2014
The 2015-12-31 10-K against the 2014-12-31 one, compared heading by heading and sentence by sentence. One of these filings carries no fiscal year tag, so its year is the calendar year of the period end.
Item 1A29 rewritten16 added10 removed246 unchanged
All filing items1,042 rewritten532 added512 removed2,044 unchanged
Summary
counted, not written
- Item 1A headings could not be compared: only 0 carried over between the two years, which usually means one filing was read wrongly, so none is reported as new or removed.
- Sentence by sentence, 532 added, 512 removed, 1,042 rewritten and 2,044 unchanged across 19 items that differ.
Sentences by item
21 items, with every count and a link to each item that changed
Underlined words on a shaded ground are new in FY2015; struck-through words were in FY2014. Sentences that are wholly new or wholly gone are labelled rather than marked.
Item 1A. RISK FACTORS
29 rewritten, 16 added, 10 removed, 246 unchanged
We [removed: provide] [added: offer our] products and services [removed: into] [added: in] competitive markets.
Maintaining and improving our competitive position will require [added: successful management of these factors, including] continued investment by us in manufacturing, research and development, engineering, marketing, customer service and support, and our distribution networks.
Pricing pressures also could cause us to adjust the prices of certain products to stay [removed: competitive.][added: competitive, which could adversely affect our financial performance.]
In [removed: 2014, 38%, 35%] [added: 2015, 41%, 32%] and 21% of our total revenue was from customers located in the United States, Europe and emerging markets, respectively.
A slowdown or [added: prolonged] downturn in [removed: these] financial or macro-economic conditions [added: in these areas or in the United States] could have a [removed: significant] [added: material] adverse effect on our business, financial condition and results of operations.
In [removed: 2014, 62%] [added: 2015, 59%] of our total revenue was from customers outside the United States, with 21% of total revenue generated in emerging markets.
| • | changes in tariff and trade barriers and import and export licensing requirements; [removed: and] |
| • | [removed: insurrection] [added: insurrection, armed conflict, terrorism] or war. |
In addition, emerging markets pose other uncertainties, including the [added: difficulty of enforcing agreements, challenges collecting receivables,] protection of our intellectual property and other assets, pressure on the pricing of our products, higher business conduct risks, less qualified talent and risks of political instability.
Any such violation could result in substantial fines, sanctions, civil and/or criminal penalties, and curtailment of operations in certain jurisdictions, and might [added: materially and] adversely affect our business, results of operations or financial condition.
We conduct approximately [removed: 62%] [added: 59%] of our business in various locations outside the United States.
We are exposed to fluctuations in foreign currency transaction exchange rates, particularly with respect to the Euro, Swedish Krona, [removed: British Pound, Australian Dollar,] Canadian Dollar, [added: British Pound,] Polish [removed: Zloty,] [added: Zloty] and [removed: Hungarian Forint.][added: Australian Dollar.]
The translation risk is primarily concentrated in the exchange rate between the U.S. [removed: dollar] [added: Dollar] and the Euro, British Pound, Chinese Yuan, Swedish [removed: Krona and] [added: Krona,] Canadian [added: Dollar and Australian] Dollar.
Weather conditions [added: and climate changes] may adversely [removed: affect] [added: affect, or cause volatility to/in,] our financial results.
Weather conditions, including heavy flooding, droughts and fluctuations in [removed: temperatures,] [added: temperatures or shifting conditions as a result of climate change,] can positively or negatively impact portions of our business.
Given the unpredictable nature of weather [removed: conditions,] [added: conditions and climate change,] this may result in volatility for certain portions of our business, as well as the operations of certain of our customers and suppliers.
Acquisitions involve a number of risks and present financial, managerial and operational challenges, including: diversion of management attention from existing businesses and operations; integration of technology, operations personnel, and financial and other systems; potentially insufficient internal controls over financial activities or financial reporting at an acquired entity that could impact us on a combined basis; the failure to realize expected synergies; the possibility that we [removed: have acquired] [added: become exposed to] substantial undisclosed [removed: liabilities;] [added: liabilities or new material risks associated with the acquired businesses;] and the loss of key employees of the acquired businesses.
As of December 31, [removed: 2014,] [added: 2015,] the net carrying value of our goodwill and other indefinite-lived intangible assets totaled approximately $2 billion.
The successful implementation and execution of [removed: this redesign as well as] our [removed: other] restructuring and realignment [removed: actions,] [added: actions] is critical to achieving our expected cost savings as well as effectively competing in the marketplace.
[removed: Other factors] [added: Factors] that may impede a successful implementation is retention of key employees, the impact of regulatory matters, and adverse economic market conditions.
If the [removed: organizational redesign or] restructuring and realignment actions are not executed successfully, [removed: the Company’s] [added: it could have a material adverse effect on our competitive position, business,] financial [added: condition and] results [removed: could be adversely impacted.][added: of operations.]
We sell our products in more than 150 countries and [removed: 62%] [added: 59%] of our revenue was generated outside the United States in [removed: 2014.][added: 2015.]
Manufacturing or design defects in (including in products or components that we source from third parties), unanticipated use of, or inadequate disclosure of risks relating to the use of products [added: there can be no assurance] that we [removed: make] or [removed: sell] [added: our customers or other third parties will not experience operational process failures or other problems that could result in potential product safety, regulatory or environmental risk which] can lead to personal injury, death or property damage.
As of December 31, [removed: 2014,] [added: 2015,] our total outstanding indebtedness was [removed: $1,288] [added: $1,274] million, including our 3.55% Senior Notes of $600 million aggregate principal amount due September 2016 and 4.875% Senior Notes of $600 million aggregate principal amount due October 2021.
We have an existing [removed: Four Year] [added: Five-Year] Competitive Advance and Revolving Credit Facility (the “Credit Facility”), which provides for an aggregate principal amount of up to $600 million.
We have a Risk Sharing Finance Facility Agreement (the "R&D Facility Agreement") with The European Investment Bank ("EIB") in an aggregate principal amount of up to €120 million (approximately [removed: $146] [added: $132] million).
In addition, as a result of such claims of infringement or misappropriation, we could lose our rights to critical technology, be unable to license critical technology or sell critical products and services, be required to pay substantial damages or license fees with respect to the infringed rights or be required to redesign our products at substantial cost, any of which could adversely impact our competitive [removed: position and] [added: position,] financial [removed: statements.][added: condition and results of operations.]
Certain provisions of our third amended and restated articles of incorporation and our amended and restated by-laws may delay or prevent a merger or acquisition [added: of] part or all of our business operations.
In connection with our Spin-off, ITT and [removed: Exelis] [added: Exelis, acquired by Harris Inc. on May 29, 2015,] will indemnify us for certain liabilities and we will indemnify ITT or Exelis for certain liabilities.
| • | increased costs and risks of developing, staffing and simultaneously managing a number of global operations as a result of distance as well as language and cultural differences; and |
For instance, our 2015 revenue decreased by 8.0% due to unfavorable foreign currency impacts.
Continued strengthening of the U.S. Dollar relative to the Euro and the currencies of the other countries in which we do business, could materially and adversely affect our revenue growth in future periods.
We may not achieve some or all of the expected benefits of our restructuring plans and our restructuring may adversely affect our business.
We have announced restructuring plans in an effort to reposition our European and North American businesses to optimize our cost structure and improve our operational efficiency and effectiveness.
We may not be able to obtain the cost savings and benefits that were initially anticipated in connection with our restructuring.
Additionally, as a
result of our restructuring, we may experience a loss of continuity, loss of accumulated knowledge or inefficiency during transitional periods.
Reorganization and restructuring can require a significant amount of management and other employees' time and focus, which may divert attention from operating and growing our business.
Further, in a declining price environment, our operating margins may contract because we account for inventory using the first-in, first- out method.
Actions we take to mitigate volatility in manufacturing and operating costs may not be successful and, as a result, our business, financial condition and results of operation could be materially and adversely affected.
In addition, we, and some of our third party vendors, have experienced cybersecurity attacks in the past and may experience them in the future, potentially with more frequency.
To date, none have resulted in any material adverse impact to our business or operations.
We have adopted measures to mitigate potential risks associated with information technology disruptions and cybersecurity threats, however, given the unpredictability of the timing, nature and scope of such disruptions, we could potentially be subject to production downtimes, operational delays, other detrimental impacts on our operations or ability to provide products and services to our customers, the compromising of confidential or otherwise protected information, destruction or corruption of data, security breaches, other manipulation or improper use of our systems or networks, financial losses from remedial actions, loss of business or potential liability, regulatory enforcement actions, and/or damage to our reputation, any of which could have a material adverse effect on our competitive position, results of operations, cash flows or financial condition.
| | |
| --- | --- |
We may not be able to compete successfully with our existing or new competitors.
Our ability to successfully execute our organizational redesign as well as other restructuring and realignment actions could impact our business results.
We initiated an organizational redesign during the fourth quarter of 2013, shifting from individually managed businesses to an integrated approach within geographical regions.
We expect that this will enable us to leverage the breadth of the Company’s product and services portfolio to better serve our customers and address market opportunities as well as effectively utilize internal support organizations to realize economies of scale and efficient use of resources.
Further, our ability to realize financial benefits from lean six sigma projects may not be able to mitigate fully or in part these manufacturing and operating cost increases and, as a result, could negatively impact our profitability.
In addition, cybersecurity threats are evolving and include, among others, malicious software, attempts to gain unauthorized access to data, and other electronic security breaches that could lead to disruptions in our systems or our third party vendors’ systems and applications, unauthorized release of confidential or otherwise protected information and corruption of data.
The Spin-off may expose us to potential liabilities arising out of state and federal fraudulent conveyance laws and legal distribution requirements.
The Spin-off could be challenged under various state and federal fraudulent conveyance laws.
An unpaid creditor or an entity vested with the power of such creditor (such as a trustee or debtor-in-possession in a bankruptcy) could claim that the Spin-off left us, ITT and/or Exelis insolvent or with unreasonably small capital or that we, ITT and/or Exelis intended or believed it would incur debts beyond its ability to pay as they mature and that ITT did not receive fair consideration or reasonably equivalent value in the Spin-off.
If a court were to agree with such a plaintiff, then such court could void the Spin-off as a fraudulent transfer and could impose a number of different remedies, which could adversely affect our financial condition and our results of operations.
Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
187 rewritten, 152 added, 132 removed, 398 unchanged
This discussion summarizes the significant factors affecting our results of operations and the financial condition of our business during each of the fiscal years in the three-year period ended December 31, [removed: 2014.][added: 2015.]
Our product and service offerings are organized into two [added: reportable] segments: Water Infrastructure and Applied Water.
| • | Water Infrastructure serves the water infrastructure sector with pump systems that transport water from [removed: oceans, groundwater,] aquifers, lakes, rivers and seas; with filtration, ultraviolet and ozone systems that provide treatment, making the water fit to use; and pumping solutions that move the wastewater to treatment facilities where our mixers, biological treatment, monitoring and control systems provide the primary functions in the treatment process. We provide analytical instrumentation used to measure water quality, [removed: flow,] [added: flow] and level in wastewater, surface [removed: water,] [added: water] and coastal environments. [added: In the Water Infrastructure segment, we provide the majority of our sales directly to customers with strong application expertise, while the remaining amount is through distribution partners.] |
| • | Applied Water serves the usage applications sector with water pressure boosting systems for heating, ventilation and air conditioning and for fire protection systems to the residential and commercial building services markets. In addition, our pumps, heat exchangers, valves and controls provide cooling to power plants and manufacturing facilities, as well as circulation for food and beverage processing. We also provide boosting systems for farming irrigation, pumps for dairy [removed: operations,] [added: operations] and rainwater reuse systems for small scale crop and turf irrigation. [added: In the Applied Water segment, we provide the majority of our sales through long-standing relationships with the world’s leading distributors, with the remainder going directly to customers.] |
In the Water Infrastructure segment, we provide the majority of our sales direct to customers with strong application expertise, while the remaining amount [removed: was] [added: is] through distribution partners.
These metrics, however, are not measures of financial performance under [removed: accounting principles generally accepted in the United States of America (“GAAP”)] [added: GAAP] and should not be considered a substitute for revenue, operating income, net income, earnings per share (basic and diluted) or net cash from operations as determined in accordance with GAAP.
| • | "organic revenue" and "organic orders" defined as revenue and orders, respectively, excluding the impact of [added: fluctuations in] foreign currency [removed: fluctuations] [added: translation, intercompany transactions] and contributions from acquisitions and divestitures. Divestitures include sales of insignificant portions of our business that did not meet the criteria for classification as a discontinued [added: operation. The period-over-period change resulting from foreign currency translation assumes no change in exchange rates from the prior period.] |
| • | "constant currency" defined as financial results adjusted for [added: foreign] currency translation impacts by translating current period and prior period activity using the same currency conversion rate. This approach is used for countries whose functional currency is not the U.S. [removed: dollar.] [added: Dollar.] |
[removed: | • |] [added: -] "adjusted net income" and "adjusted earnings per share" defined as net income and earnings per share, respectively, adjusted to exclude [removed: non-recurring separation costs from the Spin-off (not excluded after 2012),] restructuring and realignment costs, [removed: gain on sale of business,] special [removed: charges and] [added: charges,] tax-related special [removed: items. A reconciliation] [added: items and gain from sale] of [removed: adjusted net income is provided below. |][added: businesses.]
| (in millions, except per share data) | | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | | | [removed: 2012] [added: 2013] | | |
| Net income | | $ | [removed: 337] [added: 340] | | | $ | [removed: 228] [added: 337] | | | $ | [removed: 297] [added: 228] | |
| Restructuring and realignment, net of tax [added: benefit of $5, $12 and $18, respectively] | | [removed: 31] [added: 15] | | | | [removed: 46] [added: 31] | | | | [removed: 17] [added: 46] | | |
| Special charges, net of tax [added: benefit of $0 and $9, respectively] | | [removed: —] [added: 5] | | | | [removed: 23] [added: —] | | | | [removed: —] [added: 23] | | |
| Tax-related special items | | [removed: 5] [added: (15] | | [added: )] | | [removed: 14] [added: 5] | | | | [removed: —] [added: 14] | | |
| Gain on sale of business, net of [added: $0] tax [added: in both years] | | [removed: (11] [added: (9] | | ) | | [removed: —] [added: (11] | | [added: )] | | — | | |
| Adjusted net income | | $ | [removed: 362] [added: 336] | | | $ | [removed: 311] [added: 362] | | | $ | [removed: 330] [added: 311] | |
| Weighted average number of shares - Diluted | | [removed: 184.2] [added: 181.7] | | | | [removed: 186.0] [added: 184.2] | | | | [removed: 186.2] [added: 186.0] | | |
| Adjusted earnings per share | | $ | [removed: 1.97] [added: 1.85] | | | $ | [removed: 1.67] [added: 1.97] | | | $ | [removed: 1.77] [added: 1.67] | |
| • | "operating expenses excluding [removed: separation,] restructuring and realignment costs and special charges" defined as operating expenses, adjusted to exclude [removed: non-recurring separation costs from the Spin-off (not excluded after 2012),] restructuring and realignment costs and special charges. |
| • | "adjusted [removed: segment] operating [removed: income"] [added: income (loss)"] defined as [removed: segment] operating [removed: income,] [added: income (loss),] adjusted to exclude [removed: non-recurring separation costs from the Spin-off (not excluded after 2012),] restructuring and realignment [removed: costs,] [added: costs] and [added: special charges, and] "adjusted [removed: segment] operating margin" defined as adjusted [removed: segment] operating income divided by total [removed: segment] revenue. |
| • | “realignment costs” defined as [removed: non-recurring] costs not included in restructuring costs that are incurred as part of actions taken to reposition our business, including items such as professional fees, [added: severance,] relocation, [removed: travel] [added: travel, facility set-up] and other costs. |
| • | “special charges" defined as costs incurred by the [removed: Company] [added: Company, such as legal and professional fees,] associated with the [removed: settlement of legal proceedings with Xylem Group LLC and certain] [added: Korea matters,] costs incurred for the [removed: change in chief executive officer made during the third quarter] [added: contractual indemnification] of [removed: 2013, as well as] [added: tax obligations to ITT, certain] costs incurred [removed: in] [added: during] the [removed: fourth] [added: third] quarter of 2013 for the [removed: contractual indemnification] [added: settlement] of [removed: federal tax obligations to ITT and costs associated with a] legal [removed: judgment arising from a historical acquisition matter.] [added: proceedings with Xylem Group LLC, as well as the change in chief executive officer and other special non-operating items.] |
[removed: | • |] [added: -] "free cash flow" defined as net cash [removed: provided by] [added: from] operating [removed: activities] [added: activities, as reported in the Statement of Cash Flow,] less capital expenditures, as well as adjustments for other significant items that impact current results that management believes are not related to our ongoing operations and performance. [removed: Our definition of free cash flow does not consider certain non-discretionary cash payments, such as debt. The following table provides a reconciliation of free cash flow. |]
| (in millions) | | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | | | [removed: 2012] [added: 2013] | | |
| Net cash provided by operating activities | | $ | [removed: 416] [added: 464] | | | $ | [removed: 324] [added: 416] | | | $ | [removed: 396] [added: 324] | |
| Capital expenditures | | [removed: (119] [added: (117] | | ) | | [removed: (126] [added: (119] | | ) | | [removed: (112] [added: (126] | | ) |
| Free cash flow | | $ | [removed: 297] [added: 347] | | | $ | [removed: 198] [added: 297] | | | $ | [removed: 312] [added: 198] | |
Xylem reported revenue [removed: for 2014] of [removed: $3,916 million, an increase] [added: $3,653 million for 2015, a decrease] of [removed: 2.1%] [added: 6.7%] from [removed: $3,837] [added: $3,916] million reported in [removed: 2013.][added: 2014.]
Additional financial highlights for [removed: 2014] [added: 2015] include the following:
| • | Net income of [removed: $337] [added: $340] million, or [removed: $1.83] [added: $1.87] per diluted share [removed: ($362] [added: ($336] million or [removed: $1.97] [added: $1.85] per diluted share on an adjusted basis) |
| • | Free cash flow of [removed: $297] [added: $347] million, and net cash from operating activities of [removed: $416] [added: $464] million |
| • | We repurchased [removed: $130] [added: a total of $175] million in shares under [removed: the $250 million] [added: our] share repurchase [removed: program] [added: programs] approved by our Board of Directors [removed: in 2013] as part of our strategy to enhance shareholder return |
| • | Dividends paid to shareholders increased [removed: 10.0%] [added: 10%] in [removed: 2014.] [added: 2015.] |
[removed: 2015] [added: 2016] Business Outlook
We will continue to [added: strategically] execute restructuring and realignment actions [added: primarily] to reposition our European and North American business [added: in an effort] to optimize our cost structure and improve our operational efficiency and effectiveness.
During [removed: 2014,] [added: 2015,] we incurred [removed: $26] [added: $6] million and [removed: $17] [added: $14] million in restructuring and realignment costs, respectively.
[removed: In 2015,] [added: During 2016,] we expect to incur approximately [removed: $20] [added: $25] million in restructuring and realignment costs.
[removed: We] [added: As a result of the restructuring actions in 2015, we realized $2 million of net savings and] expect to realize approximately [removed: $16] [added: $1] million of incremental net savings in [removed: 2015 from actions initiated in 2014, and an additional $2 million of net savings from our 2015 actions.][added: 2016.]
| (in millions) | | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | | | [removed: 2012] [added: 2013] | | | | [removed: 2014] [added: 2015] v. [removed: 2013] [added: 2014] | | | [removed: 2013] [added: 2014] v. [removed: 2012] [added: 2013] | |
| Revenue | | $ | [removed: 3,916] [added: 3,653] | | | $ | [removed: 3,837] [added: 3,916] | | | $ | [removed: 3,791] [added: 3,837] | | | [removed: 2.1] [added: (6.7] | [removed: %] [added: )%] | | [removed: 1.2] [added: 2.1] | % |
A reconciliation of adjusted net income is provided below.
| • | "tax-related special items" defined as tax items, such as tax return versus tax provision adjustments, tax exam impacts, tax law change impacts and other discrete tax adjustments. |
Our definition of free cash flow does not consider certain non-discretionary cash payments, such as debt.
The following table provides a reconciliation of free cash flow.
Revenue increased 1.3% on a constant currency basis due to strong organic growth in the public utility, commercial and residential markets, partially offset by declines in industrial in the oil and gas market.
Operating income for 2015 was $449 million, reflecting a decrease of $14 million or 3.0% compared to $463 million in 2014.
Operating income as a percentage of revenue was 12.3% for 2015 versus 11.8% for 2014, an increase of 50 basis points.
This increase in operating margin was primarily due to reduced restructuring and realignment costs as well as incremental cost savings from continuous improvement initiatives and restructuring actions.
Partially offsetting these actions were cost inflation, unfavorable mix and unfavorable foreign exchange translation impacts.
| • | Orders of $3,711 million (a 0.5% increase from 2014 on an organic basis) |
We continue to anticipate organic revenue growth in the low-to-mid single digits in 2016.
The following is a summary of our outlook by market.
| • | Industrial was down 1% for 2015 as general industrial strength was more than offset by oil and gas declines in Canada and the United States. For 2016, we expect growth to be flat to up in the low-single-digits. This projection assumes low-single-digit growth in light industrial applications, and double-digit declines in oil and gas, and mining applications. |
| • | Public utilities increased 4% for 2015 driven by the United States recovery and continued emerging markets investments. We expect growth in mid-single-digits for 2016 as we anticipate continued growth in the United States and continued investments across emerging markets. We also anticipate that market conditions in Europe will remain stable. |
| • | Commercial experienced growth of 4% for 2015 driven by a recovering institutional building sector in the United States. We expect continued growth in the mid-single-digit range for 2016. Our expectation is that growth in the U.S. institutional building market will continue through the year, urbanization will continue to drive growth in most emerging markets and that conditions in Europe will modestly improve. |
| • | Residential markets grew 4% in 2015 with the strongest growth in the U.S. For 2016 we expect low-to-mid-single digit growth driven by continued strength in the U.S. We also expect continued low-single-digit growth in Europe. |
| • | Our agriculture markets, which is our smallest end market, declined 8% in 2015 driven by unfavorable U.S. weather conditions. We expect 2016 to grow low-single-digits as we will likely see a modest recovery from the significant weather events in 2015. |
We expect to realize approximately $8 million of savings from our 2016 actions.
2015 versus 2014
Revenue generated for 2015 was $3,653 million, a decrease of $263 million, or 6.7%, compared to $3,916 million in 2014.
This increase was primarily driven by strong organic growth within emerging markets, particularly in China and India.
The United States and western Europe also grew organically, which was partially offset by declines in Canada.
In addition, the organic growth was partially offset by the divestiture of the Wolverhampton valves business early in the third quarter of 2014.
| Acquisitions/(Divestitures) | (10 | | ) | | (0.3 | )% |
| 2015 Revenue | $ | 3,653 | | | | |
| Water Infrastructure | $ | 2,231 | | | $ | 2,442 | | | (8.6 | )% | | 0.9 | % |
| Applied Water | 1,422 | | | | 1,474 | | | | (3.5 | )% | | 1.8 | % |
| Total | $ | 3,653 | | | $ | 3,916 | | | (6.7 | )% | | 1.3 | % |
Water Infrastructure’s revenue decreased $211 million, or 8.6% in 2015 (0.9% increase on a constant currency basis) compared to 2014.
The constant currency increase was driven by organic growth of $22 million or 0.9% due to continued strength in the public utility end market partially offset by weakness in the industrial market.
The industrial market performance decline was due to decreases in dewatering applications in the oil and gas market which more than offset increases in the balance of the industrial market.
From an application perspective, organic revenue grew in transport, treatment and test applications.
The organic revenue growth from transport applications was predominately due to public utility strength in the emerging markets, the United States and in western Europe, partially offset by declines in industrial dewatering applications from weakness in the oil and gas market in Canada and the United States.
The organic revenue growth from treatment applications was due to ozone and filtration projects in China and Australia which was somewhat offset by the lapping of a large project in Latin America in 2014 and general weakness in Europe.
Organic revenue growth from test applications was driven by growth in China and India due to demand for new wastewater and river monitoring products.
This increase in the current year was partially offset by the absence of $11 million in revenue from the divested Wolverhampton valves business.
From an applications perspective, the increase in organic revenue was predominately due to continued growth in commercial building services from a recovering institutional building sector in the United States and strength in Asia.
The industrial water application organic revenue grew from project strength in western Europe and the United States, which was partially offset by the aforementioned Wolverhampton divestiture.
Residential building services organic revenue increased primarily in the United States due to improvements in the home construction market and market share gain.
Irrigation applications organic revenue decline was largely impacted by severe flooding conditions in the southeast and southwest regions of the United States and the lapping of a strong fourth quarter in 2014.
References in the consolidated financial statements to "ITT" or the "former parent" refer to ITT Corporation and its consolidated subsidiaries (other than Xylem Inc.).
The Water Infrastructure segment focuses on the transportation, treatment and testing of water, offering a range of products including water and wastewater pumps, treatment and testing equipment, and controls and systems.
The Applied Water segment serves many of the primary uses of water and focuses on the residential, commercial, industrial and agricultural markets.
The segment’s major products include pumps, valves, heat exchangers, controls and dispensing equipment.
operation.
The period-over-period change resulting from foreign currency fluctuations assumes no change in exchange rates from the prior period.
| Separation costs, net of tax (a) | | — | | | | — | | | | 16 | | |
| (a) | Costs of $4 million ($2 million, net of tax) during 2013, associated with non-recurring separation activities are not excluded from adjusted net income. |
| Separation cash payments (a) | | — | | | | — | | | | 28 | | |
| (a) | Separation cash payments associated with non-recurring separation activities are included in the 2013 free cash flow. Separation cash payments are excluded from free cash flow in 2012 and include capital expenditures associated with the Spin-off of $4 million. |
Significant growth in the industrial and public utility end markets combined with strength in the emerging markets, most notably in China, drove the increase.
Continued challenging market conditions limited growth in other regions, Europe, for example, was flat organically year-over-year, while Japan and Australia declined.
Operating income for 2014 was $463 million, reflecting an increase of $100 million or 27.5% compared to $363 million in 2013, which was primarily due to savings from lean six sigma activities, global sourcing initiatives and restructuring actions as well as lapping $24 million in non-recurring special charges in 2013, which more than offset headwinds from cost inflation and unfavorable sales mix.
Additionally, restructuring and realignment cost actions taken to improve the overall cost base of the business were $43 million in 2014 as compared to $64 million in the prior year.
| • | Orders of $4,021 million (a 3.9% increase from 2013 on a constant currency basis) |
In 2015, we are anticipating organic revenue growth of low single digits.
The projected organic growth excludes an expected negative foreign exchange translation impact on growth of high single digits, primarily driven by a weaker Euro to U.S. dollar.
We expect continued strength in the United States industrial markets, but a modest deceleration in emerging market growth and weakness in the oil and gas markets to result in low single digit growth overall for the industrial end market.
We expect public utilities to also increase at low single digits where emerging market infrastructure investments continue to bolster growth and we see improving market conditions in the United States.
In the commercial market, we anticipate growth of low to mid-single digits as the United States appears to continue to slowly recover and emerging markets continue to be strong, which we expect will be partially offset by soft European markets.
We believe the residential markets will be flat to down low single digits as the United States markets moderate and Europe continues to be negative.
Finally, the agriculture markets, which is our smallest end market, we expect will likely be relatively flat compared to 2014 as we are expecting slower growth in the United States from lapping of a strong 2014 combined with stabilization in Europe and continued strength in emerging markets.
As a result of the restructuring actions in 2014, we realized $13 million of net savings.
| Separation costs (a) | | — | | | | — | | | | 22 | | | | — | % | | NM | |
| (a) | Separation costs of $4 million ($2 million, net of tax) during 2013 are included within the $1,048 million of operating expenses. |
| 2013 Revenue | $ | 3,837 | | | | |
| Separation Costs | — | | | | 4 | | | | NM | |
Refer to Note 11, “Goodwill and Other Intangible Assets,” for additional information.
2013 versus 2012
Revenue generated for 2013 was $3,837 million, an increase of $46 million, or 1.2%, compared to $3,791 million in 2012.
| 2012 Revenue | $ | 3,791 | | | | |
| Acquisitions | 82 | | | | 2.2 | % |
| Water Infrastructure | $ | 2,384 | | | $ | 2,349 | | | 1.5 | % | | 1.7 | % |
| Applied Water | 1,453 | | | | 1,442 | | | | 0.8 | % | | 0.3 | % |
| Total | $ | 3,837 | | | $ | 3,791 | | | 1.2 | % | | 1.1 | % |
Water Infrastructure’s revenue increased $35 million, or 1.5% in 2013 (1.7% on a constant currency basis).
Our 2012 and 2013 acquisitions contributed $82 million of incremental revenue in 2013.
Organic revenue decreased $43 million or 1.8% during the year, which was due substantially to lower volumes across the transport, treatment and test applications.
The significant declines were caused primarily by weakness in the Europe, Middle East and Africa treatment markets and declines in transport in the Asia Pacific markets from less mining activity.
Organic revenue performance improved year-over-year in the third and fourth quarters of 2013 driven by increases in transport revenue, which reflected modest market recovery in northern and central Europe as well as the United States.
An excerpt. Shown here: 40 of 187 rewritten, 40 of 152 added and 40 of 132 removed. The counts are complete. For every sentence, read Item 7. MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS in the FY2015 filing and the FY2014 filing.
Item 7A. QUANTITATIVE AND QUALITATIVE DISCLOSURES ABOUT MARKET RISK
6 rewritten, 5 added, 2 removed, 20 unchanged
We are exposed to market risk, primarily related to foreign currency exchange [added: rates] and interest rates.
We conduct approximately [removed: 62%] [added: 59%] of our business in various locations outside the United States.
[removed: In January 2012, we began to] [added: We] enter into currency forward contracts periodically in order to manage the exchange rate fluctuation risk on certain intercompany transactions associated with third party sales and purchases.
Our principal foreign currency transaction exposures primarily relate to the Euro, Swedish Krona, [removed: British Pound,] Canadian Dollar, [added: British Pound,] Polish [removed: Zloty, Australian Dollar] [added: Zloty] and [removed: Hungarian Forint.][added: Australian Dollar.]
The translation risk is primarily concentrated in the exchange rate between the U.S. [removed: dollar] [added: Dollar] and the Euro, British Pound, Chinese Yuan, Swedish [removed: Krona and] [added: Krona,] Canadian [added: Dollar and Australian] Dollar.
We estimate that a hypothetical 10% movement of the [removed: U.S dollar] [added: U.S. Dollar] to the various foreign currency exchange rates we translate from, in the aggregate, could have approximately a 7% impact on Xylem's consolidated revenue and income as reported in U.S. [removed: dollars.][added: Dollars.]
As of December 31, 2015, our debt portfolio is primarily comprised of two fixed-rate senior notes that total $1.2 billion.
The $600 million senior note due 2021 is not exposed to interest rate risk as the bond is at a fixed-rate until maturity.
The other $600 million senior note will mature on September 20th, 2016, and the company intends to refinance the debt with new debt instruments.
Until the company closes the refinancing of the notes due, we are exposed to interest rate risk that can potentially impact the planned issuance of debt instruments.
Based on current interest rate market we do not anticipate material risk associated with our debt refinancing within the target time-frame of completion.
As of December 31, 2014, we do not have a material exposure to interest rate risk as our debt portfolio primarily comprises long-term, fixed-rate instruments.
We do not account for our long-term debt using the fair value option.
Item 1. BUSINESS
73 rewritten, 17 added, 145 removed, 223 unchanged
Xylem, with [removed: 2014] [added: 2015] revenue of [removed: $3.9] [added: $3.7] billion and approximately [removed: 12,500] [added: 12,700] employees, is a world leader in the design, manufacturing, and application of highly engineered technologies for the water industry.
We sell our products in [removed: more than] [added: approximately] 150 countries through a balanced distribution network consisting of our direct sales force and independent channel partners.
In [removed: 2014, 62%] [added: 2015, 59%] of our revenue was generated outside the United States, with 21% of revenue generated in emerging markets.
[removed: ][added: ]
[removed: 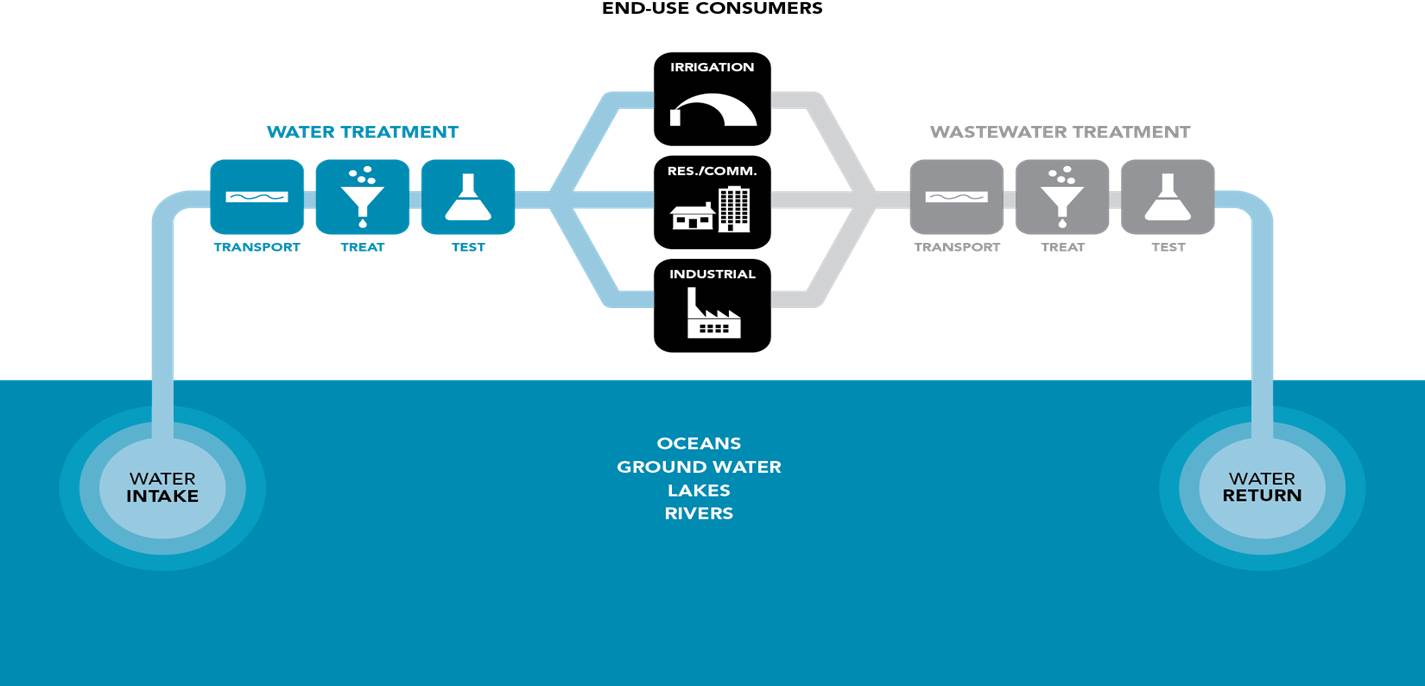][added: 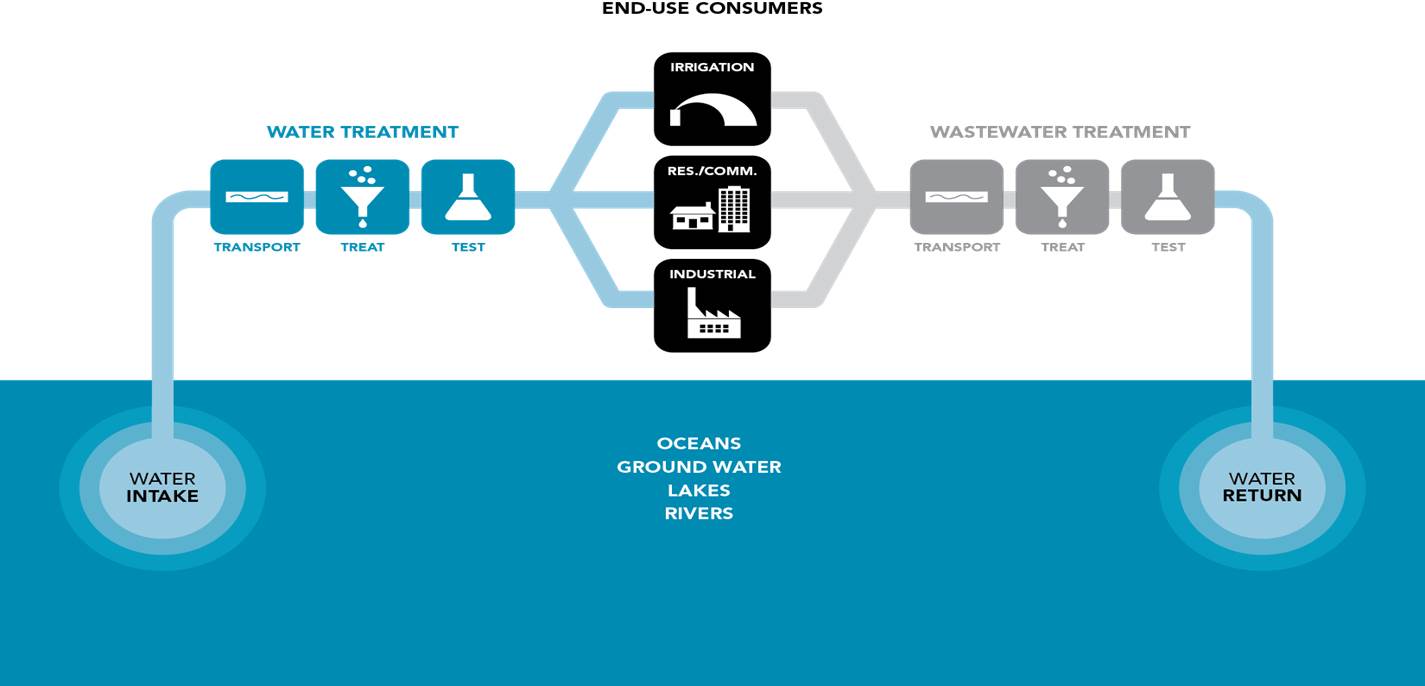]
| • | Emerging [removed: Market Growth] [added: Markets] \- We seek to accelerate our growth in priority emerging markets through increased focus on product localization and channel development. |
| ▪ | Innovation [added: & Technology] \- We seek to enhance the Company’s innovation efforts with increased focus on [removed: disruptive] technologies [added: and innovation] that can significantly improve customers’ water productivity, quality and resilience. |
| • | [removed: Build a] [added: Drive] Continuous [removed: Improvement Culture.] [added: Improvement.] We seek to embed continuous improvement into our culture and simplify our organizational structure to make the Company more agile, more profitable, and create room to re-invest in growth. To accomplish this, we will continue to strengthen our lean six sigma and global [removed: strategic sourcing] [added: procurement] capabilities, and continue to optimize our cost structure [added: through business simplification] by eliminating [removed: unnecessary costs] [added: structural, process] and [removed: inefficient overhead.] [added: product complexity.] |
| • | [removed: Build Superior] Leadership and Talent Development. We seek to continue to invest in attracting, developing and retaining world-class talent with an increased focus on leadership and talent development programs. We will continue to align individual performance to the objectives of the Company and its shareholders. |
| • | [removed: Build a Culture of] [added: Focus on] Execution and Accountability. We seek to ensure the impact of these strategic focus areas by holding our people accountable and streamlining our performance management and goal deployment systems. |
See Note [removed: 21,] [added: 20,] “Segment and Geographic Data,” in our consolidated financial statements for financial information about segments and geographic areas.
| | | Market Applications | | [removed: 2014] [added: 2015] Revenue (in millions) | | | | % Revenue | | | Major Products | | Primary Brands |
| Water Infrastructure | | Transport | | $ | [removed: 1,779] [added: 1,624] | | | 73 | % | | • Water and wastewater pumps • Filtration, disinfection and biological treatment equipment • Test equipment • Controls | | • Flygt • [removed: WEDECO] [added: Wedeco] • Godwin • WTW • Sanitaire • YSI • Leopold |
| Applied Water | | Building Services | | $ | [removed: 781] [added: 774] | | | [removed: 53] [added: 54] | % | | • Pumps • Valves • Heat exchangers • Controls • Dispensing equipment systems | | • Goulds Water Technology • Bell & Gossett • A-C Fire Pump • Standard Xchange • Lowara • Jabsco • Flojet • Flowtronex |
| | Industrial Water | | [removed: 592] [added: 562] | | | | 40 | % | | | | | |
| | Irrigation | | [removed: 101] [added: 86] | | | | [removed: 7] [added: 6] | % | | | | | |
Throughout each of these stages, our analytical systems test [removed: to ensure] [added: the] quality of water for consumption as well as for its return to nature.
We estimate our served market size in this sector to be approximately [removed: $20] [added: $21] billion.
Finally, the Transport application also includes dewatering pumps, equipment and services which provide the safe removal or draining of groundwater and surface water from a riverbed, construction site or mine [removed: shaft.][added: shaft and bypass pumping for the repair of aging public utility infrastructure, as well as emergency water removal during severe weather events.]
With operations on six continents, we also have one of the world’s largest dewatering rental [removed: fleets, serviced with our Flygt and Godwin brands.][added: fleets.]
[removed: In our Water Infrastructure Segment,] Transport accounted for approximately 73% of our [added: Water Infrastructure] segment revenue in [added: both 2015 and] 2014, [removed: 74% in 2013] and [removed: 73%] [added: 74%] in [removed: 2012.][added: 2013.]
The Treatment application includes equipment and services that treat both water for consumption and wastewater to be returned responsibly to the [removed: environment.][added: environment or reused.]
While there are several treatment solutions in the market today, we focus on three basic treatment types: (i) [removed: filtration,] [added: filtration systems,] (ii) disinfection [removed: systems and] [added: systems,] (iii) biological treatment [removed: systems.][added: systems, including mixers.]
[removed: Disinfection] [added: Wedeco offers chemical-free and environmentally friendly disinfection] systems, both UV and ozone oxidation, [added: to] treat [removed: both] public utility drinking [removed: water] [added: water, wastewater] and [removed: wastewater, as well as] industrial process [removed: water, and are provided through our WEDECO brand.][added: water.]
[removed: In our Water Infrastructure Segment,] Treatment accounted for approximately 14% of our [added: Water Infrastructure] segment revenue in [removed: both] [added: 2015,] 2014 and [removed: 2013, and 15% in 2012.][added: 2013.]
[removed: In our Water Infrastructure Segment,] Test accounted for approximately 13% of our [added: Water Infrastructure] segment revenue in [removed: 2014] [added: both 2015] and [added: 2014, and] 12% in [removed: both 2013 and 2012.][added: 2013.]
Since water is used to some degree in almost every aspect of human, economic and environmental activity, this segment has a significant number of [removed: potential] applications and we participate in all major areas of water demand.
Examples of what we provide include: boosting systems for farming irrigation, pumps for dairy operations, and rainwater reuse systems for small scale crop and turf [removed: irrigation.][added: irrigation.We estimate our served market size in this sector to be approximately $16 billion.]
[removed: Our] [added: Industrial Water applications account for water consumption activities that use] pumps, heat exchangers, valves and controls [added: to] provide cooling to power plants and manufacturing facilities, as well as circulation for food and beverage processing.
[removed: The remaining portion of global water use resides in] [added: Residential and Commercial Building Services account for] human and building consumption, where we deliver water boosting systems for drinking, heating, ventilation and air conditioning ("HVAC") and fire protection [removed: systems to Residential and Commercial Building Services.][added: systems.]
We estimate our [added: total] served market size [removed: in this sector] to be approximately [removed: $15] [added: $37] billion.
This business is defined by four [removed: main] [added: primary] uses of water in building services applications, such as in residential homes and commercial buildings, including offices, hotels, hospitals, schools, restaurants and malls.
The second is the supply of potable water for consumption, [removed: such as for] [added: including] drinking [added: water] and [removed: hygiene.][added: for hygienic purposes .]
The Goulds Water [removed: Technology and] [added: Technology,] Lowara [added: and Bell & Gossett] brands [removed: provides] [added: provide] pumps and boosting systems utilized within buildings, sourcing water from distribution networks or from wells.
[added: The fourth water-related building service] area is fire protection, where our [removed: AC] [added: A-C] Fire [added: Pump] brand supplies full pump systems for emergency fire suppression.
[removed: In our Applied Water Segment,] Building Services accounted for approximately [removed: 53%] [added: 54%] of our [added: Applied Water] segment revenue in [removed: 2014, 50%] [added: 2015, 53%] in [removed: 2013] [added: 2014] and [removed: 53%] [added: 50%] in [removed: 2012.][added: 2013.]
Our Goulds Water Technology and Lowara brands supply vertical multistage pumps to bring in source water or to boost pressure for [removed: purposes such as circulating] [added: purposes, including] water [added: circulation] through a manufacturing facility to cool machine tools.
We also service niche applications such as [removed: flexible impeller pumps for] wine processing [removed: facilities served by our] [added: with] Jabsco [removed: brand,] [added: brand flexible impeller pumps,] and water-based detergent dispensing and water circulation [removed: within] [added: for] car washes served by Flojet [removed: and Goulds Water Technology] air-operated [removed: diaphragm and end suction pumps.]
[removed: In our Applied Water Segment,] Industrial Water accounted for approximately 40% of our [added: Applied Water] segment revenue in [added: 2015 and] 2014, [removed: 43% in 2013] and [removed: 40%] [added: 43%] in [removed: 2012.][added: 2013.]
The irrigation business consists of irrigation-related equipment and services associated with bringing water from a source to [removed: the] [added: a production] plant or livestock [removed: need,] [added: facility,] including hoses, sprinklers, center pivot and drip [removed: irrigation.][added: irrigation systems.]
| • | Commercial Leadership - We are strengthening our capabilities by focusing on simplifying our commercial processes along with the supporting backend information technology systems. |
| | Treatment | | 316 | | | | 14 | % | | | | | |
| | Test | | 291 | | | | 13 | % | | | | | |
| | | | | $ | 2,231 | | | 100 | % | | | | |
| | | | | $ | 1,422 | | | 100 | % | | | | |
Our key brands for this application are Flygt and Godwin.
Our key brands for this application are Leopold, Wedeco, Sanitaire and Flygt.
Leopold, has been a worldwide leader in filtration for over 90 years.
Our key brands for this application are WTW and YSI.
The remaining portion of global water use resides in irrigation applications.
diaphragm and Goulds Water Technology end suction pumps.
We can support mines throughout exploration, development and operation.
Our wide range of durable pumps ensures reliability that minimizes risks, maximizes uptime and delivers superior total cost of ownership.
| (in millions) | 2015 | | | | | | | 2014 | | | | | | | 2013 | | | | | |
Timeliness of delivery, quality and the proximity of service centers are important
We invested $95 million, $104 million, and $104 million in R&D in 2015, 2014 and 2013, respectively.
We have R&D and product development capabilities around the world.
In 2014, we began implementing an organizational redesign to integrate our commercial teams within geographical regions.
The integration of our commercial teams creates a cross-Xylem sales and marketing organization, shifting from a dedicated product line organizational structure.
This sales structure is largely in place in the Company’s Europe, Middle East, Africa and Asia regions and to a lesser extent in our other regions.
While this organizational redesign did not change the Company’s reportable segments, it had implications on how the Company manages the business, the most significant of which was the shift of certain responsibilities, namely customer and market-related activities, into the regional selling organizations.
| | |
| --- | --- |
| • | Industry vertical marketing \- We are strengthening vertical marketing capabilities for key end markets to bring the full breadth of the Company’s portfolio to bear on critical customer challenges. |
| • | Commercial team effectiveness \- We continue to strengthen our regional commercial teams, including through the global adoption of improved commercial information technology tools, such as customer relationship management software. |
| | Treatment | | 348 | | | | 14 | % | | | | | |
| | Test | | 315 | | | | 13 | % | | | | | |
| | | | | $ | 2,442 | | | 100 | % | | | | |
| | | | | $ | 1,474 | | | 100 | % | | | | |
Flygt — Flygt is a world-leader in the design and manufacture of dry and submersible pumps and related intelligent controls systems.
Under the Flygt banner, customers have access to a complete range of products and solutions for moving water, wastewater, and advanced monitoring and control equipment to optimize their use.
Founded in Sweden in 1901, Flygt is the originator of the reliable, energy-efficient electrical submersible pump.
Flygt products have applications in various markets, including wastewater lift stations, water and wastewater treatment facilities, pressurized sewage systems, oil and gas, steel, mining and leisure markets.
Customers include public utility and industrial water and wastewater systems operators.
In 2012, Xylem successfully launched Flygt Experior which brings together advanced controls, hydraulics and energy-efficient motor technology to deliver substantial energy savings.
During 2014, we won a large contract to provide large custom-made Flygt pumps for the Xayaburi run-of-river hydropower dam in Laos.
The construction of the dam allows water to be kept within the river’s course and minimally raises the water level to allow fish migration between the Upper and Lower Mekong Rivers, while providing electricity to about 1 million people in Laos and 3 million people in Thailand.
Godwin — With more than 35 years as a leader in pump manufacturing and applications, Godwin has established itself as a well-recognized, market leading brand in the global portable pump market.
Godwin manufactures, sells, rents and services its products.
Its quick response and 24/7 capabilities allow it to provide customized pumping solutions to meet the specific needs of its customers.
Founded in Quenington, England, Godwin is currently headquartered in Bridgeport, New Jersey.
Godwin's products include fully automatic self-priming Dri-Prime® pumps, a full range of Flygt electric submersible pumps, Heidra hydraulic submersible pumps, Wet-Prime gasoline-powered contractor pumps and a broad line of generators and portable light towers, as well as a multitude of pumping accessories and pipe.
Godwin products are primarily used in construction, water & wastewater transport, oil & gas markets, hydraulic fracturing, industrial, mining, and municipal, as well as government, temporary fire protection, environmental, agriculture, and marine.
Godwin products are also instrumental in disaster relief efforts.
After Superstorm Sandy hit the United States in October 2012, Godwin's pumps were instrumental in minimizing or preventing flood damage in various flooded regions throughout the Northeast.
Godwin's fleet of equipment is rented through 45 U.S. branches and a global network of distributors and Xylem rental and sales facilities.
Leopold, with more than 90 years of experience, is our leading filtration brand.
Leopold — Founded in 1924 in Pittsburgh, Pennsylvania, Leopold is a leader in rapid gravity media filtration and clarification solutions for the water and wastewater industry.
In potable drinking water treatment plants, the Clari-DAF system is used to clarify raw water to remove contaminants such as turbidity, algae, color, iron/manganese, organics, and taste and odor compounds.
Several years ago, we augmented our filtration products with membrane technology.
Our filtration products include the rapid gravity media, membranes and reverse osmosis/ultrafine filtration.
Leopold gravity media filtration is used in potable water treatment plants to remove particulate in the final filtration step.
In public utility wastewater treatment plants, the ClariVAC system is used in final clarifiers to remove the sludge solids.
For those areas where nitrogen and phosphorus nutrient removal is required, we provide elimi-NITE systems which convert the filters to become biologically active so that the effluent meets the mandated nitrate and phosphorus levels.
In desalination systems, Leopold Clari-DAF® systems and Filterworx systems are provided to remove contaminants that will harm reverse osmosis membranes, so that salt can be removed from the seawater to make it potable.
Primary customers are public utility water and wastewater systems, as well as desalination plant facilities.
During 2014, Leopold launched Oxelia, which is a cutting-edge, ozone-enhanced biologically active filtration system and multi-barrier solution for municipal wastewater treatment.
An excerpt. Shown here: 40 of 73 rewritten, all 17 added and 40 of 145 removed. The counts are complete. For every sentence, read Item 1. BUSINESS in the FY2015 filing and the FY2014 filing.
Item 3. LEGAL PROCEEDINGS
0 rewritten, 3 added, 21 removed, 0 unchanged
From time to time, we are involved in legal proceedings that are incidental to the operation of our businesses.
Some of these proceedings seek remedies relating to environmental matters, intellectual property matters, personal injury claims, employment and pension matters, government contract issues and commercial or contractual disputes, sometimes related to acquisitions or divestitures.
See Note 18, "Commitments and Contingencies", of the consolidated financial statements included in Item 8 of Part II of this 10-K for information regarding certain legal proceedings in which we are involved.
From time to time, we are involved in legal proceedings that are incidental to the operation of our businesses, including acquisitions and divestitures, environmental matters, intellectual property matters, anti-trust and anti-corruption matters, product liability and personal injury claims, employment and pension matters, government and commercial contract disputes.
Although we cannot predict the outcome of these and other proceedings, including the cases below, with certainty, we believe that they will not have a material adverse effect on our consolidated financial position and results of operations.
On December 17, 2014, the Korea Fair Trade Commission (“KFTC”) issued a written decision regarding an investigation into bid-rigging allegations against Xylem Water Solutions South Korea Co., Ltd. (“Xylem South Korea”), a subsidiary of Xylem Inc. The KFTC found that certain employees of Xylem South Korea had participated in activities that violated Korea’s antitrust laws.
Xylem South Korea was assessed a fine of approximately $1.6 million and the matter was referred for criminal prosecution.
In January 2015, Xylem South Korea paid the fine and filed an appeal of the KFTC’s decision with the Seoul High Court.
In connection with the KFTC matter, the Company commenced an internal investigation relating to the allegations against Xylem South Korea.
In late 2014, the Company broadened this internal investigation to assess related allegations made by certain employees of Xylem South Korea during the investigation into the KFTC matter.
The broadened investigation includes a review of compliance by Xylem South Korea and its employees with the requirements of the Foreign Corrupt Practices Act.
The Company engaged independent outside counsel to assist with its investigation and an independent professional services firm to provide forensic accounting assistance.
In late January 2015, the Company voluntarily contacted the Securities and Exchange Commission and the Department of Justice to advise both agencies of this internal investigation.
The Company will fully cooperate with any government investigation.
Xylem South Korea’s revenue is less than one percent of the Company’s total revenue.
Although the Company currently cannot reasonably estimate the potential liability, if any, related to the
investigation, we currently believe that these matters will not have a material adverse effect on the Company’s business, financial condition or results of operations.
On or about February 17, 2009, following a statement submitted to the Spanish Competition Authority (Comision Nacional de la Competencia, "CNC") by Grupo Industrial Ercole Marelli, S.A. regarding an anti-competitive agreement in which it said it had been participating, the CNC conducted an investigation at ITT Water & Wastewater España S.A. (now named Xylem Water Solutions España S.A.), at the Spanish Association of Fluid Pump Manufacturers (the "Association"), and at the offices of other members of the Association.
On September 16, 2009, the Directorate of Investigation of the CNC commenced formal proceedings for alleged restrictive practices, such as several exchanges of information and a recommendation on general terms and conditions of sale, allegedly prohibited under applicable law.
Following the conclusion of the formal proceedings, the CNC Council imposed fines on the Association and nineteen Spanish manufacturers and distributors of fluid pumps, including a fine of Euro 2,373,675 applied to ITT Water & Wastewater España S.A. and ITT Corporation.
In March 2012, the Company appealed the CNC's decision to the Audiencia Nacional (the "High Court"), and vigorously defended the case.
In March 2013, the High Court upheld the determination of the CNC and the fine previously assessed.
In June 2013, the Company filed an appeal with the Tribunal Supremo, the Supreme Court of Spain.
Xylem is awaiting the decision of the Supreme Court.
Cover and table of contents
29 rewritten, 5 added, 5 removed, 83 unchanged
| | | For the fiscal year ended December 31, [removed: 2014] [added: 2015] | | |
The aggregate market value of the common stock of the registrant held by non-affiliates of the registrant as of June 30, [removed: 2014] [added: 2015] was approximately [removed: $7.1] [added: $6.7] billion.
As of January [removed: 31, 2015,] [added: 29, 2016,] there were [removed: 182,309,721] [added: 178,485,808] outstanding shares of the registrant’s common stock, par value $0.01 per share.
Portions of the registrant’s definitive proxy statement for its [removed: 2015] [added: 2016] Annual Meeting of Shareowners, to be held in May [removed: of 2015,] [added: 2016,] are incorporated by reference into Part II and Part III of this Report.
For the fiscal year ended December 31, [removed: 2014][added: 2015]
| 1A. | [Risk [removed: Factors](#sB1C0E9AC2462E776F7C7A575E42ABA35)] [added: Factors](#s9A5090DBF01F5A1B858A2562DA528236)] | [removed: [17](#sB1C0E9AC2462E776F7C7A575E42ABA35)] [added: [13](#s9A5090DBF01F5A1B858A2562DA528236)] |
| 1B. | [Unresolved Staff [removed: Comments](#s3CCBB0F8253145E336CEA575E438ACAC)] [added: Comments](#s0A0D3FFB017753ACAC33CE042A3C908C)] | [removed: [24](#s3CCBB0F8253145E336CEA575E438ACAC)] [added: [20](#s0A0D3FFB017753ACAC33CE042A3C908C)] |
| 3 | [Legal [removed: Proceedings](#s1CCEC39FB7DE3EE74776A575E48F5B0B)] [added: Proceedings](#s6BAA6655C4D759A1B089D1F757904C03)] | [removed: [25](#s1CCEC39FB7DE3EE74776A575E48F5B0B)] [added: [21](#s6BAA6655C4D759A1B089D1F757904C03)] |
| 4 | [Mine Safety [removed: Disclosures](#sA8CA77AB2EF2D46C748EA575E4E23816)] [added: Disclosures](#sB0503465DA9E5817B6FDC004D9CF84D6)] | [removed: [26](#sA8CA77AB2EF2D46C748EA575E4E23816)] [added: [21](#sB0503465DA9E5817B6FDC004D9CF84D6)] |
| * | [Executive Officers of the [removed: Registrant](#sD8B09E066A891ED8E702A575E4F4CA4D)] [added: Registrant](#s0400244AFAFF5A409E5EE3D5645F7A44)] | [removed: [27](#sD8B09E066A891ED8E702A575E4F4CA4D)] [added: [22](#s0400244AFAFF5A409E5EE3D5645F7A44)] |
| | [Board of [removed: Directors](#sdb60554f4c784dbf979407e2f27e2995)] [added: Directors](#s8E463A9769235A439305ACF6A1D7D5DB)] | [removed: [28](#sdb60554f4c784dbf979407e2f27e2995)] [added: [23](#s8E463A9769235A439305ACF6A1D7D5DB)] |
| 5 | [Market for [added: the] Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity [removed: Securities](#sC05DE0172DE8D5AC99A0A575CBF1C993)] [added: Securities](#s140D489EFC7B51209EE0AEC3C8992ED0)] | [removed: [29](#sC05DE0172DE8D5AC99A0A575CBF1C993)] [added: [24](#s140D489EFC7B51209EE0AEC3C8992ED0)] |
| 6 | [Selected Financial [removed: Data](#sED2FEA270767CDDF9AD0A575E578A320)] [added: Data](#sF98D2B8F98045F09B6E541853051F349)] | [removed: [31](#sED2FEA270767CDDF9AD0A575E578A320)] [added: [27](#sF98D2B8F98045F09B6E541853051F349)] |
| 7 | [Management’s Discussion and Analysis of Financial Condition and Results of [removed: Operations](#sBFB143A833F6E83C1F87A575E59BE2AF)] [added: Operations](#sD0FCEB34A08E5E0997C40E60743D4798)] | [removed: [32](#sBFB143A833F6E83C1F87A575E59BE2AF)] [added: [28](#sD0FCEB34A08E5E0997C40E60743D4798)] |
| 7A. | [Quantitative and Qualitative Disclosures About Market [removed: Risk](#s980E1A7F07F97657B2C7A575E630F9A0)] [added: Risk](#s5B19077265A35F60992FEFA593805C1B)] | [removed: [52](#s980E1A7F07F97657B2C7A575E630F9A0)] [added: [48](#s5B19077265A35F60992FEFA593805C1B)] |
| 8 | [Financial Statements and Supplementary [removed: Data](#sF74C03DC902F1BE6D43FA575E6321711)] [added: Data](#sFDB9FFBDE13C5E0EB4F7F791EDE67460)] | [removed: [53](#sF74C03DC902F1BE6D43FA575E6321711)] [added: [49](#sFDB9FFBDE13C5E0EB4F7F791EDE67460)] |
| 9 | [Changes In and Disagreements With Accountants on Accounting and Financial [removed: Disclosure](#sABDE8A7E21882F9F27D0A575ECCC326B)] [added: Disclosure](#sA0040C9321BC563BA341F10A9BFBF89D)] | [removed: [100](#sABDE8A7E21882F9F27D0A575ECCC326B)] [added: [95](#sA0040C9321BC563BA341F10A9BFBF89D)] |
| 9A. | [Controls and [removed: Procedures](#s0700C425F7F6D9E3BB40A575ED0DB689)] [added: Procedures](#s8C4AB83CC38A5F69A7B6F9DC92977AFE)] | [removed: [100](#s0700C425F7F6D9E3BB40A575ED0DB689)] [added: [95](#s8C4AB83CC38A5F69A7B6F9DC92977AFE)] |
| 9B. | [Other [removed: Information](#sD0C9BCE7B2190F45362EA575ED1D3063)] [added: Information](#sF02C18A0B86E58F5B21555930D6BAA2E)] | [removed: [100](#sD0C9BCE7B2190F45362EA575ED1D3063)] [added: [95](#sF02C18A0B86E58F5B21555930D6BAA2E)] |
| 10 | [Directors, Executive Officers and Corporate [removed: Governance](#sF01ADAF6940C330A5DCBA575EDB26765)] [added: Governance](#s037550FD532154C2AD98A1EC0EF3A42C)] | [removed: [102](#sF01ADAF6940C330A5DCBA575EDB26765)] [added: [97](#s037550FD532154C2AD98A1EC0EF3A42C)] |
| 11 | [Executive [removed: Compensation](#s07F8F5951A046F7B467EA575EDB5FF81)] [added: Compensation](#s3071DD39B9745FD3BA233EFE4D6C5DE6)] | [removed: [102](#s07F8F5951A046F7B467EA575EDB5FF81)] [added: [97](#s3071DD39B9745FD3BA233EFE4D6C5DE6)] |
| 12 | [Security Ownership of Certain Beneficial Owners and Management and Related Stockholder [removed: Matters](#s4C6D1B63EE181F1BA056A575EDE9FEC5)] [added: Matters](#s96C6B75D4EA1544B8690825337353BD2)] | [removed: [102](#s4C6D1B63EE181F1BA056A575EDE9FEC5)] [added: [97](#s96C6B75D4EA1544B8690825337353BD2)] |
| 13 | [Certain Relationships and Related Transactions, and Director [removed: Independence](#s3E48AF81E114C1950E5EA575EE1BC10E)] [added: Independence](#s4BF59D80B19C519994A631848E01A2F2)] | [removed: [102](#s3E48AF81E114C1950E5EA575EE1BC10E)] [added: [97](#s4BF59D80B19C519994A631848E01A2F2)] |
| 14 | [Principal Accounting Fees and [removed: Services](#s7FCC2B7BDCCC7FDB8183A575EE4C5674)] [added: Services](#s8EF376E185F657C39BFF581CF8B196D8)] | [removed: [102](#s7FCC2B7BDCCC7FDB8183A575EE4C5674)] [added: [97](#s8EF376E185F657C39BFF581CF8B196D8)] |
| 15 | [Exhibits, Financial Statement [removed: Schedules](#sB257498C8054E116409CA575EEA06E4D)] [added: Schedules](#s1266D0E4DD51511A80053A9666F1C1BC)] | [removed: [103](#sB257498C8054E116409CA575EEA06E4D)] [added: [98](#s1266D0E4DD51511A80053A9666F1C1BC)] |
Generally, the words “anticipate,” “estimate,” “expect,” “project,” “intend,” “plan,” “forecast,” “believe,” “target,” “will,” “could,” “would,” “should” and similar expressions identify forward-looking [removed: statements, which generally are not historical in nature.][added: statements.]
These forward-looking statements include [added: any] statements [added: that are not historical in nature, including any such statements] about the capitalization of the Company, the Company’s restructuring and realignment, future strategic plans and other statements that describe the Company’s business strategy, outlook, objectives, plans, intentions or goals.
All statements that address operating or financial performance, events or developments that we expect or anticipate will occur in the future [removed: -] including statements relating to orders, revenue, operating margins and earnings per share growth, and statements expressing general views about future operating results [removed: -] are forward-looking statements.
Factors that could cause results to differ materially from those anticipated include: [removed: economic,] [added: overall economic and business conditions,] political and other risks associated with our international operations, including military actions, economic sanctions or trade embargoes that could affect customer markets, and non-compliance with laws, including foreign corrupt practice laws, export and import laws and competition laws; potential for unexpected cancellations or delays of customer orders in our reported backlog; our exposure to fluctuations in foreign currency exchange rates; competition and pricing pressures in the markets we serve; the strength of housing and related markets; weather conditions; ability to retain and attract key members of management; our relationship with and the performance of our channel partners; our ability to [added: successfully identify, complete and integrate acquisitions; our ability to] borrow or to refinance our existing indebtedness and availability of liquidity sufficient to meet our needs; changes in the value of goodwill or intangible assets; risks relating to product defects, product liability and recalls; governmental investigations; security breaches or other disruptions of our information technology systems; litigation and contingent liabilities; and other factors set forth below under “Item 1A.
10-K 1 xyl1231201510k.htm 10-K
| 1 | [Business](#s12AC2E34DBD95292BF475BAFFFD83D76) | [3](#s12AC2E34DBD95292BF475BAFFFD83D76) |
| 2 | [Properties](#sEFA78EDD170651BC946E47F3B98FA6FB) | [21](#sEFA78EDD170651BC946E47F3B98FA6FB) |
| [Signatures](#sC5D829A4A7535B269A1728B9F431CEF4) | | [99](#sC5D829A4A7535B269A1728B9F431CEF4) |
| [Exhibit Index](#s6B7EEC3169E15DCB8CD6DFE21417AFEA) | | [100](#s6B7EEC3169E15DCB8CD6DFE21417AFEA) |
10-K 1 xyl1231201410k.htm 10-K
| 1 | [Business](#s4C452087DE3F064E90D4A575CA31D244) | [3](#s4C452087DE3F064E90D4A575CA31D244) |
| 2 | [Properties](#s538E3D34EEE00A01A17BA575E48DAA7F) | [25](#s538E3D34EEE00A01A17BA575E48DAA7F) |
| [Signatures](#s5CC81B6440EA24B7722CA575CA22AB0D) | | [104](#s5CC81B6440EA24B7722CA575CA22AB0D) |
| [Exhibit Index](#s21515DECED050EFA80CAA575EEFFCEE6) | | [106](#s21515DECED050EFA80CAA575EEFFCEE6) |
Item 2. PROPERTIES
5 rewritten, 0 added, 0 removed, 19 unchanged
We have [removed: more than] [added: approximately] 350 locations in more than 40 countries.
These properties total approximately [removed: 10.4] [added: 10.2] million square feet, of which more than 300 locations, or approximately [removed: 6.0] [added: 5.5] million square feet, are leased.
| Bridgeport | | NJ | | Administration and Manufacturing | | 136,000 | | | [removed: 2015] [added: 2020] |
| Quenington | | UK | | Manufacturing | | 86,000 | | | [removed: 2015] [added: 2020] |
| Cheektowaga | | NY | | Manufacturing | | [removed: 145,000] [added: 147,000] | | | Owned |
Item 4. MINE SAFETY DISCLOSURES
6 rewritten, 5 added, 5 removed, 44 unchanged
The following information is provided regarding the executive officers of [removed: Xylem:][added: Xylem as of February 1, 2016:]
| Patrick K. Decker | | [removed: 50] [added: 51] | | President and Chief Executive Officer (2014) | | • President and Chief Executive Officer, Harsco Corp. (diversified, worldwide industrial company) (2012) • President, Flow Control Segment, Tyco International Ltd. (industrial products and services company) (2003) |
| Tomas Brannemo | | [removed: 43] [added: 46] | | Senior VP and President, Transport (2014) | | • VP, Transport (2013) • VP [removed: Strategy] and [removed: Aftermarket and Service (2010) • VP and] Director of Business Unit Aftermarket and Service (2010) [removed: • VP Marketing and Sales, Customer Support, Volvo Construction Equipment, AB Volvo (multinational manufacturing company) (2008)] |
| Colin R. Sabol | | [removed: 47] [added: 48] | | Senior VP and President, [removed: Dewatering (2013)] [added: Analytics and Treatment (2015)] | | • Senior VP and [added: President, Dewatering (2013) • Senior VP and] Chief Strategy and Growth Officer (2011) [removed: • VP of Marketing and Business Development, Fluid and Motion Control, ITT Corporation (global manufacturing company)(2009)] |
| Claudia S. Toussaint | | [removed: 51] [added: 52] | | Senior VP, General Counsel and Corporate Secretary (2014) | | • Senior VP, General Counsel and Secretary, Barnes Group Inc. (international industrial and aerospace manufacturing) (2012) • General Counsel, Flow Control Segment, Tyco International Ltd. (industrial products and services company) (2012) • Senior VP, General Counsel and Secretary, Barnes Group Inc. (international industrial and aerospace manufacturing) (2010) [removed: • Senior VP, General Counsel and Secretary, Embarq (multinational communications company) (2009)] |
| Victoria D. Harker | | Chief Financial Officer, [removed: Gannett Co.,] [added: TEGNA] Inc. |
| Shashank Patel | | 55 | | Interim Chief Financial Officer (2015) | | • VP, Finance, Applied Water Systems (2010) |
| David Flinton | | 45 | | Senior VP and President, Dewatering (2015) | | • VP, Engineering and Marketing, Applied Water Systems (2013) • VP, Global Product Management, Applied Water Systems (2012) • VP, Strategy and Integrated Management System (former Water Solutions division) (2010) |
| Pak Steven Leung | | 55 | | Senior VP and President, Emerging Markets (2015) | | • VP, Global Sales, Valves and Controls, Pentair Plc (diversified, worldwide industrial manufacturing company) (2013) • VP and General Manager, Global Process, Tyco International Ltd. (industrial products and services company) (2010) |
| Kairus Tarapore | | 54 | | Senior VP and Chief Human Resources Officer (2015) | | • Senior VP and Chief Administrative Officer, Babcock & Wilcox Company (2013) • Executive VP, Human Resources, Ceridian Corporation (2006) |
| | | | | | | |
| Michael T. Speetzen | | 45 | | Senior VP and Chief Financial Officer (2011) | | • VP of Finance, Fluid and Motion Control, ITT Corporation (global manufacturing company) (2009) |
| Christopher R. McIntire | | 51 | | Senior VP and President, Analytics and Treatment (2013) | | • Senior VP and President, Analytics (2011) • President and Chief Operating Officer, Nova Analytics (manufacturing and analytical instruments) (2006) |
| Robyn T. Mingle | | 49 | | Senior VP and Chief Human Resources Officer (2011) | | • Senior VP of Human Resources, Hovnanian Enterprises, Inc. (real estate company) (2003) |
| | | |
| James P. Rogers | | Former Chairman, Chief Executive Officer, Eastman Chemical Company |
Item 5. MARKET FOR THE REGISTRANT’S COMMON EQUITY, RELATED STOCKHOLDER MATTERS AND ISSUER PURCHASES OF EQUITY SECURITIES
13 rewritten, 10 added, 10 removed, 39 unchanged
[removed: 2014] [added: 2015] and [removed: 2013] [added: 2014] Market Price and Dividends
| Fiscal Year ended December 31, [removed: 2013] [added: 2015] | | | | | | | | | | | |
The closing price of our common stock on the NYSE on January [removed: 30, 2015] [added: 29, 2016] was [removed: $34.10] [added: $35.95] per share.
As of January [removed: 30, 2015,] [added: 29, 2016,] there were [removed: 14,700] [added: 13,784] holders of record of our common stock.
In the first quarter of [removed: 2015,] [added: 2016,] we declared a dividend of [removed: $0.1408] [added: $0.1549] per share to be paid on March [removed: 18, 2015] [added: 16, 2016] for shareholders of record on February 18, [removed: 2015.][added: 2016.]
There have been no unregistered offerings of our common stock during [removed: 2014.][added: 2015.]
Fourth Quarter [removed: 2014] [added: 2015] Share Repurchase Activity
The following table summarizes our purchases of our common stock for the quarter ended December 31, [removed: 2014:][added: 2015:]
[removed: | (b) | On August 18, 2012, the Board of Directors authorized the repurchase of up to two million shares of common stock with no expiration date. The program's objective is to offset dilution associated with various Xylem employee stock plans by acquiring shares in the open market from time to time.] There were no shares purchased under this program during the three months ended December 31, [removed: 2014] [added: 2015] and there are [removed: 1.0] [added: 0.3] million shares (approximately [removed: $40] [added: $9] million based on the closing share price on December 31, [removed: 2014)] [added: 2015)] that may still be purchased under this plan. [removed: |]
On August [removed: 20, 2013,] [added: 18, 2012,] the Board of Directors authorized the repurchase of [removed: shares] up to [removed: $250] [added: 2.0] million [added: shares of common stock] with no expiration date.
This graph covers the period from October 13, 2011 (the first day our common stock began “when-issued” trading on the NYSE) through December 31, [removed: 2014.][added: 2015.]
[removed: ][added: ]
| | XYL | | | | S&P 500 | | | | S&P [removed: 1500] [added: 500] Industrials Index | | |
| First Quarter | $ | 38.59 | | | $ | 33.54 | | | $ | 0.1408 | |
| Second Quarter | 37.70 | | | | 34.80 | | | | 0.1408 | | |
| Third Quarter | 37.32 | | | | 29.90 | | | | 0.1408 | | |
| Fourth Quarter | 38.00 | | | | 32.16 | | | | 0.1408 | | |
| 10/1/15 - 10/31/15 | | — | | — | | — | | $479 |
| 11/1/15 - 11/30/15 | | 0.7 | | 36.80 | | 0.7 | | $454 |
| 12/1/15 - 12/31/15 | | 0.7 | | 36.71 | | 0.7 | | $429 |
| (b) | On August 24, 2015, our Board of Directors authorized the repurchase of up to $500 million in shares with no expiration date. The program's objective is to deploy our capital in a manner that benefits our shareholders and maintains our focus on growth. During the three months ended December 31, 2015, we repurchased 1.4 million shares for $50 million. There are up to $420 million in shares that may still be purchased under this plan as of December 31, 2015. |
The program's objective is to offset dilution associated with various Xylem employee stock plans by acquiring shares in the open market from time to time.
| December 31, 2015 | 161 | | | | 186 | | | | 187 | | |
| First Quarter | $ | 29.49 | | | $ | 26.39 | | | $ | 0.1164 | |
| Second Quarter | 29.19 | | | | 25.56 | | | | 0.1164 | | |
| Third Quarter | 29.79 | | | | 23.61 | | | | 0.1164 | | |
| Fourth Quarter | 34.93 | | | | 26.99 | | | | 0.1164 | | |
| 10/1/14 - 10/31/14 | | — | | — | | — | | $108.2 |
| 11/1/14 - 11/30/14 | | — | | — | | — | | $110.2 |
| 12/1/14 - 12/31/14 | | — | | — | | — | | $110.0 |
The program's objective is to deploy our capital in a manner that benefits our shareholders and maintains our focus on growth.
During the three months ended December 31, 2014, there were no shares repurchased under this program.
There are up to $70 million in shares that may still be purchased under this plan.
Item 6. SELECTED FINANCIAL DATA
17 rewritten, 4 added, 4 removed, 21 unchanged
The following table sets forth selected consolidated financial data for the five years ended December 31, [removed: 2014.][added: 2015.]
The Spin-off was completed pursuant to the Distribution Agreement among ITT, Exelis [added: Inc., acquired by Harris] Inc. [added: on May 29, 2015,] and Xylem.
| (in millions, except per share data) | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | | | [removed: 2012] [added: 2013] | | | | [removed: 2011 (b)] [added: 2012] | | | | [removed: 2010 (c)] [added: 2011 (a)] | | |
| Revenue | $ | [removed: 3,916] [added: 3,653] | | | $ | [removed: 3,837] [added: 3,916] | | | $ | [removed: 3,791] [added: 3,837] | | | $ | [removed: 3,803] [added: 3,791] | | | $ | [removed: 3,202] [added: 3,803] | |
| Gross profit | [removed: 1,513] [added: 1,404] | | | | [removed: 1,499] [added: 1,513] | | | | [removed: 1,502] [added: 1,499] | | | | [removed: 1,461] [added: 1,502] | | | | [removed: 1,214] [added: 1,461] | | |
| Gross margin | [removed: 38.6] [added: 38.4] | | % | | [removed: 39.1] [added: 38.6] | | % | | [removed: 39.6] [added: 39.1] | | % | | [removed: 38.4] [added: 39.6] | | % | | [removed: 37.9] [added: 38.4] | | % |
| Operating income | [removed: 463] [added: 449] | | | | [removed: 363] [added: 463] | | | | [removed: 443] [added: 363] | | | | [removed: 395] [added: 443] | | | | [removed: 388] [added: 395] | | |
| Operating margin | [removed: 11.8] [added: 12.3] | | % | | [removed: 9.5] [added: 11.8] | | % | | [removed: 11.7] [added: 9.5] | | % | | [removed: 10.4] [added: 11.7] | | % | | [removed: 12.1] [added: 10.4] | | % |
| Net income | [removed: 337] [added: 340] | | | | [removed: 228] [added: 337] | | | | [removed: 297] [added: 228] | | | | [removed: 279] [added: 297] | | | | [removed: 329] [added: 279] | | |
| Basic | $ | [removed: 1.84] [added: 1.88] | | | $ | [removed: 1.23] [added: 1.84] | | | $ | [removed: 1.60] [added: 1.23] | | | $ | [removed: 1.51] [added: 1.60] | | | $ | [removed: 1.78] [added: 1.51] | |
| Diluted | [removed: 1.83] [added: 1.87] | | | | [removed: 1.22] [added: 1.83] | | | | [removed: 1.59] [added: 1.22] | | | | [removed: 1.50] [added: 1.59] | | | | [removed: 1.78] [added: 1.50] | | |
| Basic shares outstanding [removed: (a)] | [removed: 183.1] [added: 180.9] | | | | [removed: 185.2] [added: 183.1] | | | | [removed: 185.8] [added: 185.2] | | | | [removed: 185.1] [added: 185.8] | | | | [removed: 184.6] [added: 185.1] | | |
| Diluted shares outstanding [removed: (a)] | [removed: 184.2] [added: 181.7] | | | | [removed: 186.0] [added: 184.2] | | | | [removed: 186.2] [added: 186.0] | | | | [removed: 185.3] [added: 186.2] | | | | [removed: 184.6] [added: 185.3] | | |
| Cash dividends per share | $ | [removed: 0.5120] [added: 0.5632] | | | $ | [removed: 0.4656] [added: 0.5120] | | | $ | [removed: 0.4048] [added: 0.4656] | | | $ | [removed: 0.1012] [added: 0.4048] | | | $ | [removed: —] [added: 0.1012] | |
| Cash and cash equivalents | $ | [removed: 663] [added: 680] | | | $ | [removed: 533] [added: 663] | | | $ | [removed: 504] [added: 533] | | | $ | [removed: 318] [added: 504] | | | $ | [removed: 131] [added: 318] | |
| Working capital* | [removed: 882] [added: 810] | | | | [removed: 930] [added: 882] | | | | [removed: 859] [added: 930] | | | | [removed: 834] [added: 859] | | | | [removed: 759] [added: 834] | | |
| [removed: (b)] [added: (a)] | In 2011, we acquired YSI Incorporated, which contributed revenue of $35 million in 2011 and $371 million of total assets on date of acquisition. |
| Total assets (b)(c) | 4,657 | | | | 4,833 | | | | 4,857 | | | | 4,639 | | | | 4,350 | | |
| Total debt (b) | 1,274 | | | | 1,284 | | | | 1,235 | | | | 1,197 | | | | 1,197 | | |
| (b) | Debt issuance costs of $6 million, $8 million and $9 million in 2013, 2012 and 2011, respectively, were reclassified to long-term debt from other non-current assets within the Consolidated Balance Sheet. See Note 2, “Recently Issued Accounting Pronouncements,” of the consolidated financial statements. |
| (c) | Deferred tax assets of $33 million, $32 million and $41 million in 2013, 2012 and 2011, respectively, were reclassified to deferred tax liabilities within the Consolidated Balance Sheet. See Note 2, “Recently Issued Accounting Pronouncements,” of the consolidated financial statements. |
| Total assets | 4,864 | | | | 4,896 | | | | 4,679 | | | | 4,400 | | | | 3,742 | | |
| Total debt | 1,288 | | | | 1,241 | | | | 1,205 | | | | 1,206 | | | | 4 | | |
| (a) | On October 31, 2011, the Spin-off from ITT was completed through a tax-free stock dividend to ITT’s shareholders. ITT shareholders received one share of Xylem common stock for each share of ITT common stock. As a result on October 31, 2011, we had 184.6 million shares of common stock outstanding and this share amount is being utilized to calculate earnings per share and diluted earnings per share for all prior periods presented. |
| (c) | In 2010, we acquired Godwin Pumps of America, Inc. and Nova Analytics Corporation. These businesses in the aggregate contributed revenue of $247 million in 2010 and $1,070 million of total assets on date of acquisition. |
Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA
613 rewritten, 245 added, 159 removed, 877 unchanged
| [Report of Independent Registered Public Accounting [removed: Firm](#sE371A8C828B666F9F786A575E68267B3)] [added: Firm](#s91D5602986475BD4B324D1059D085E9B)] | [removed: [54](#sE371A8C828B666F9F786A575E68267B3)] [added: [50](#s91D5602986475BD4B324D1059D085E9B)] |
| [Consolidated Income Statements for the Years Ended December 31, [removed: 2014, 2013] [added: 2015, 2014] and [removed: 2012](#sDDD28F52C780274AB898A575C0F9D3D7)] [added: 2013](#sA89D080F9B255BBFA2BC0FACD55ACB99)] | [removed: [55](#sDDD28F52C780274AB898A575C0F9D3D7)] [added: [51](#sA89D080F9B255BBFA2BC0FACD55ACB99)] |
| [Consolidated Statements of Comprehensive Income for the Years Ended December 31, [removed: 2014, 2013] [added: 2015, 2014] and [removed: 2012](#s1ADE5FAAFBD939950A3FA575C1A4CFCF)] [added: 2013](#sC10A79A379975BE7A51A9AF5E5E09A63)] | [removed: [56](#s1ADE5FAAFBD939950A3FA575C1A4CFCF)] [added: [52](#sC10A79A379975BE7A51A9AF5E5E09A63)] |
| [Consolidated Balance Sheets as of December 31, [removed: 2014] [added: 2015] and [removed: December 31, 2013](#sC8461AE8B68F85314E06A575C1D32FC5)] [added: 2014](#s0F3CC981EAF55B90B52EDB27B0021B23)] | [removed: [57](#sC8461AE8B68F85314E06A575C1D32FC5)] [added: [53](#s0F3CC981EAF55B90B52EDB27B0021B23)] |
| [Consolidated Statements of Cash Flows for the Years Ended December 31, [removed: 2014, 2013] [added: 2015, 2014] and [removed: 2012](#s3482E2B02818BC956208A575C21200AD)] [added: 2013](#s3471C72E66DD5B54B98929BD95F46FAE)] | [removed: [58](#s3482E2B02818BC956208A575C21200AD)] [added: [54](#s3471C72E66DD5B54B98929BD95F46FAE)] |
| [Consolidated Statements of Changes in Stockholders’ Equity for the Years Ended December 31, [removed: 2014, 2013] [added: 2015, 2014] and [removed: 2012](#sA5C2A4F301ECABCD0B19A575C35955D7)] [added: 2013](#s954F32C46B315AAE8CB509E8CB1CA83A)] | [removed: [59](#sA5C2A4F301ECABCD0B19A575C35955D7)] [added: [55](#s954F32C46B315AAE8CB509E8CB1CA83A)] |
| [Note 1 Summary of Significant Accounting [removed: Policies](#s4007A95A8338C06C4025A575C1472E1D)] [added: Policies](#s877E537381675195A91234F6743F1D7A)] | [removed: [60](#s4007A95A8338C06C4025A575C1472E1D)] [added: [56](#s877E537381675195A91234F6743F1D7A)] |
| [Note 2 Recently Issued Accounting [removed: Pronouncements](#s84740C89CA8FA0187EB9A575C0F9F858)] [added: Pronouncements](#s1EE23E12067D5205B1E8483FBDB34A17)] | [removed: [66](#s84740C89CA8FA0187EB9A575C0F9F858)] [added: [62](#s1EE23E12067D5205B1E8483FBDB34A17)] |
| [Note 3 Acquisitions and [removed: Divestitures](#sAC26262029666BF71686A575C108D67F)] [added: Divestitures](#s874209948E105D89BDE793534446F71C)] | [removed: [68](#sAC26262029666BF71686A575C108D67F)] [added: [64](#s874209948E105D89BDE793534446F71C)] |
| [Note 4 Restructuring and Asset Impairment [removed: Charges](#sD3D89149129B7931B873A575C118BFB6)] [added: Charges](#sF2AB7A4F7D2559B2B0B5FF7C51131614)] | [removed: [69](#sD3D89149129B7931B873A575C118BFB6)] [added: [65](#sF2AB7A4F7D2559B2B0B5FF7C51131614)] |
| [Note [removed: 6] [added: 5] Other Non-Operating Income, [removed: Net](#s7DE707FE656692D37B52A575C1180915)] [added: Net](#s78987BBFC95C5600A1B259E92B4600A6)] | [removed: [71](#s7DE707FE656692D37B52A575C1180915)] [added: [67](#s78987BBFC95C5600A1B259E92B4600A6)] |
| [Note [removed: 7] [added: 6] Income [removed: Taxes](#sAFFD1822D955982DC271A575C118D2A9)] [added: Taxes](#sC6D9AB2D60FF553D83F06588A6CD6270)] | [removed: [71](#sAFFD1822D955982DC271A575C118D2A9)] [added: [67](#sC6D9AB2D60FF553D83F06588A6CD6270)] |
| [Note [removed: 8] [added: 7] Earnings Per [removed: Share](#s535985E4610534C041ECA575C1082BD1)] [added: Share](#s21FDEC03E19452EC9E22D5620498C0DB)] | [removed: [75](#s535985E4610534C041ECA575C1082BD1)] [added: [70](#s21FDEC03E19452EC9E22D5620498C0DB)] |
| [Note [removed: 9 Inventories](#sF520C24F376AA5EBC2DCA575C0F981B1)] [added: 8 Inventories](#s4856DDA5BC9755678F080D44D1D2259D)] | [removed: [76](#sF520C24F376AA5EBC2DCA575C0F981B1)] [added: [70](#s4856DDA5BC9755678F080D44D1D2259D)] |
| [Note [removed: 10] [added: 9] Property, Plant and [removed: Equipment](#sB577A508CAB965D9A995A575C1184C08)] [added: Equipment](#s66ECE03B2A3254E1A4EF32857FDAE09B)] | [removed: [76](#sB577A508CAB965D9A995A575C1184C08)] [added: [71](#s66ECE03B2A3254E1A4EF32857FDAE09B)] |
| [Note [removed: 11] [added: 10] Goodwill and Other Intangible [removed: Assets](#sE0B90EDE69FC725FC3FEA575C1663340)] [added: Assets](#s10644A61E5D353AEB348494A941A5C94)] | [removed: [76](#sE0B90EDE69FC725FC3FEA575C1663340)] [added: [71](#s10644A61E5D353AEB348494A941A5C94)] |
| [Note [removed: 12] [added: 11] Derivative Financial [removed: Instruments](#sB7A045AA9E0E8BD8D6A9A575C17618E1)] [added: Instruments](#sB2205E395E3D577BAD209EC69E311F74)] | [removed: [77](#sB7A045AA9E0E8BD8D6A9A575C17618E1)] [added: [72](#sB2205E395E3D577BAD209EC69E311F74)] |
| [Note [removed: 13] [added: 12] Accrued and Other Current [removed: Liabilities](#s99BFB0585B944501623DA575C0E9986D)] [added: Liabilities](#sCF973DDB675150208071CB30D22A78EB)] | [removed: [78](#s99BFB0585B944501623DA575C0E9986D)] [added: [74](#sCF973DDB675150208071CB30D22A78EB)] |
| [Note [removed: 14] [added: 13] Credit Facilities and Long-Term [removed: Debt](#sE32B0E7724E5EA64B5FFA575C108969A)] [added: Debt](#s2E880B37F21D5AAD944EBBC9A35EA16E)] | [removed: [79](#sE32B0E7724E5EA64B5FFA575C108969A)] [added: [74](#s2E880B37F21D5AAD944EBBC9A35EA16E)] |
| [Note [removed: 15] [added: 14] Postretirement Benefit [removed: Plans](#sEB2BDBE6312C5CFFE9F2A575C0F9AC9D)] [added: Plans](#s7138E7B5D67D5B8CB1E882B57EE9FB5A)] | [removed: [81](#sEB2BDBE6312C5CFFE9F2A575C0F9AC9D)] [added: [76](#s7138E7B5D67D5B8CB1E882B57EE9FB5A)] |
| [Note [removed: 16] [added: 15] Stock-Based [removed: Compensation](#s567E8DDD5F27CD2EE15EA575C0F97CDE)] [added: Compensation Plans](#s26F4AA5D46FD5EBDAE92B3161667A3E9)] | [removed: [89](#s567E8DDD5F27CD2EE15EA575C0F97CDE)] [added: [83](#s26F4AA5D46FD5EBDAE92B3161667A3E9)] |
| [Note [removed: 17] [added: 16] Capital [removed: Stock](#sC3EFA735EFD5687E4D3FA575C12803D8)] [added: Stock](#s786CEAACBE415B0D8FF3C7D3532CE0BA)] | [removed: [92](#sC3EFA735EFD5687E4D3FA575C12803D8)] [added: [85](#s786CEAACBE415B0D8FF3C7D3532CE0BA)] |
| [Note [removed: 18] [added: 17] Accumulated Other Comprehensive Income [removed: (Loss)](#s6F729D0BCF0102795ED5A575C26FF52C)] [added: (Loss)](#sA541F5E474E15746AD807105669A53FB)] | [removed: [93](#s6F729D0BCF0102795ED5A575C26FF52C)] [added: [87](#sA541F5E474E15746AD807105669A53FB)] |
| [removed: [Note 19] Commitment and [removed: Contingencies](#s58320C34AB83B54647EBA575C1B4A24C)] [added: Contingencies (Note 18)] | [removed: [94](#s58320C34AB83B54647EBA575C1B4A24C)] | [added: | | | | | |]
| [Note [removed: 20] [added: 19] Related Party [removed: Transactions](#s3BB7C97919B3C630933FA575C185FC07)] [added: Transactions](#sDCF3DDF5C1295002A25556EB881AC764)] | [removed: [96](#s3BB7C97919B3C630933FA575C185FC07)] [added: [91](#sDCF3DDF5C1295002A25556EB881AC764)] |
| [Note [removed: 21] [added: 20] Segment and Geographic [removed: Data](#sA28C9A5B686208795CEEA575C0F9CF0F)] [added: Data](#s962F7622F3165B9A8C83B9D3447FC9B7)] | [removed: [97](#sA28C9A5B686208795CEEA575C0F9CF0F)] [added: [92](#s962F7622F3165B9A8C83B9D3447FC9B7)] |
| [Note [removed: 23] [added: 22] Quarterly Financial [removed: Data](#sA73944558E58B73D0F2EA575C1767A47)] [added: Data](#sCDAB1A5FC94D536A98CFDAFE7633C6A1)] | [removed: [99](#sA73944558E58B73D0F2EA575C1767A47)] [added: [94](#sCDAB1A5FC94D536A98CFDAFE7633C6A1)] |
We have audited the accompanying consolidated balance sheets of Xylem Inc. and subsidiaries (the "Company") as of December 31, [removed: 2014] [added: 2015] and [removed: 2013,] [added: 2014,] and the related consolidated statements of income, comprehensive income, stockholders' equity, and cash flows for each of the three years in the period ended December 31, [removed: 2014.][added: 2015.]
In our opinion, such consolidated financial statements present fairly, in all material respects, the financial position of Xylem Inc. and subsidiaries as of December 31, [removed: 2014] [added: 2015] and [removed: 2013,] [added: 2014,] and the results of their operations and their cash flows for each of the three years in the period ended December 31, [removed: 2014,] [added: 2015,] in conformity with accounting principles generally accepted in the United States of America.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the Company's internal control over financial reporting as of December 31, [removed: 2014,] [added: 2015,] based on the criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission and our report dated February 26, [removed: 2015] [added: 2016] expressed an unqualified opinion on the Company's internal control over financial reporting.
| Year Ended December 31, | [removed: 2014] [added: 2015] | | | | [removed: 2013] [added: 2014] | | | | [removed: 2012] [added: 2013] | | |
| Revenue | $ | [removed: 3,916] [added: 3,653] | | | $ | [removed: 3,837] [added: 3,916] | | | $ | [removed: 3,791] [added: 3,837] | |
| Cost of revenue | [removed: 2,403] [added: 2,249] | | | | [removed: 2,338] [added: 2,403] | | | | [removed: 2,289] [added: 2,338] | | |
| Gross profit | [removed: 1,513] [added: 1,404] | | | | [removed: 1,499] [added: 1,513] | | | | [removed: 1,502] [added: 1,499] | | |
| Selling, general and administrative expenses | [removed: 920] | | | | [removed: 986] [added: 9] | | | | [removed: 914] | | | [added: | 9 | | |]
| Research and development expenses | [removed: 104] [added: 95] | | | | 104 | | | | [removed: 106] [added: 104] | | |
| Restructuring and asset impairment charges | [removed: 26] [added: 6] | | | | [removed: 42] [added: 26] | | | | [removed: 17] [added: 42] | | |
| Operating income | [removed: 463] [added: 449] | | | | [removed: 363] [added: 463] | | | | [removed: 443] [added: 363] | | |
| Interest expense | [removed: 54] [added: 55] | | | | [removed: 55] [added: 54] | | | | 55 | | |
| Other non-operating income (expense), net | [removed: 1] [added: —] | | | | [removed: (10] [added: 1] | | [removed: )] | | [removed: —] [added: (10] | | [added: )] |
| [Note 21 Valuation and Qualifying Accounts](#s96099B1EFC0855FCBED7EDCEE0F65BE4) | [94](#s96099B1EFC0855FCBED7EDCEE0F65BE4) |
| [Note 23 Subsequent Events](#s769dd01c58f0466f937c0d8c84248883) | [94](#s769dd01c58f0466f937c0d8c84248883) |
February 26, 2016
| Foreign currency gain reclassified into net income | (8 | | ) | | — | | | | — | | |
| Net change in derivative hedge agreements: | | | | | | | | | | | |
| Total assets | $ | 4,657 | | | $ | 4,833 | |
| Total liabilities | 2,573 | | | | 2,706 | | |
| Net income | $ | 340 | | | $ | 337 | | | $ | 228 | |
| Balance at December 31, 2015 | $ | 2 | | | $ | 1,834 | | | $ | 885 | | | $ | (238 | ) | | $ | (399 | ) | | $ | 2,084 | |
XYLEM INC. AND SUBSIDIARIES
Certain prior year amounts have been reclassified to conform to the current year presentation.
While this organizational redesign did not change our reportable segments, it had implications on how we manage our business.
Hedge accounting generally provides for the
The effective portion of changes in the fair value of derivatives designated and that qualify as net investment hedges of foreign exchange risk is recorded in OCI.
Amounts in OCI are reclassified into earnings at the time the hedged net investment is sold or substantially liquidated.
Effectiveness of derivatives designated as net investment hedges is assessed using the forward method.
Any ineffective portion of the change in fair value of the derivative is recognized directly in selling, general and administrative expenses.
NAV Practical Expedient is the measurement of fair value using the net asset value ("NAV") per share (or its equivalent) practical expedient as an alternative to the fair value hierarchy as discussed above.
In February 2016, the Financial Accounting Standards Board (“FASB”) issued guidance amending the accounting for leases.
Specifically, the amended guidance requires all lessees to record a lease liability at lease inception, with a corresponding right of use asset, except for short-term leases.
Lessor accounting is not fundamentally changed.
This amended guidance is effective for interim and annual periods beginning after December 15, 2018 using a modified retrospective approach.
In January 2016, the FASB issued guidance amending the classification and measurement of financial instruments.
Specifically, the amended guidance (1) requires equity securities with readily determinable fair values to be measured at fair value with changes in fair value recognized through net income (2) simplifies the impairment assessment of equity investments without readily determinable fair values by requiring a qualitative impairment assessment at each reporting period and requiring any impaired investment be measured at fair value (3) requires separate presentation of financial assets and financial liabilities by measurement category and form of financial asset on the balance sheet or accompanying notes to the financial statements and (4) eliminates the requirement to disclose the methods and significant assumptions used to estimate the fair value that is required to be disclosed for financial instruments measured at cost on the balance sheet.
This amended guidance is effective for interim and annual periods beginning after December 15, 2017 by means of a cumulative-effect adjustment to the balance sheet as of the beginning of the year of adoption.
Early adoption is permitted for fiscal years or interim periods for which the applicable financial statements have not been issued.
We are evaluating the impact of the guidance on our financial condition and results of operations.
In July 2015, the FASB issued guidance regarding simplifying the measurement of inventory.
Under prior guidance, inventory is measured at the lower of cost or market, where market is defined as replacement cost, with a ceiling of net realizable value and a floor of net realizable value less a normal profit margin.
The amended guidance requires the measurement of inventory at the lower of cost and net realizable value.
Net realizable value is the estimated selling prices in the ordinary course of business, less reasonably predictable costs of completion, disposal, and transportation.
We are evaluating the impact of the guidance on our financial condition and results of operations.
This guidance is effective for interim and annual reporting periods beginning after December 15, 2017 and may be applied retrospectively to each prior period presented or with the cumulative effect recognized as of the date of initial
application.
Early adoption is permitted for interim and annual reporting periods beginning after December 15, 2016.
We are evaluating the impact of the guidance on our financial condition and results of operations.
In November 2015, the FASB issued guidance that changes the presentation of deferred income taxes.
Under prior accounting guidance deferred income tax liabilities and assets are separated into current and noncurrent amounts in an entity’s balance sheet.
The guidance requires that deferred income tax liabilities and assets be classified as noncurrent in an entity’s balance sheet.
This guidance may be applied prospectively or retrospectively to all deferred income tax balances.
| [Note 5 Separation Costs](#s71313D00FEC7F8F2ECAEA575C31B86D0) | [70](#s71313D00FEC7F8F2ECAEA575C31B86D0) |
| [Note 22 Supplemental Information](#s285E06406C9DD6906F6BA575C166FA49) | [99](#s285E06406C9DD6906F6BA575C166FA49) |
February 26, 2015
| | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Separation costs | — | | | | 4 | | | | 22 | | |
| Total assets | $ | 4,864 | | | $ | 4,896 | |
| Deferred income tax liabilities | 158 | | | | 191 | | |
| Total liabilities | 2,737 | | | | 2,655 | | |
| Net transfer to former parent | — | | | | — | | | | (9 | | ) |
| | | | | | | | | | | | | | | | | | | | | | | | |
| --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- | --- |
| Balance at January 1, 2012 | 2 | | | | 1,663 | | | | 44 | | | | 122 | | | | — | | | | 1,831 | | |
The integration of our commercial teams creates a cross Xylem sales and marketing organization shifting from a dedicated product line organizational structure.
This sales structure is largely in place in the Company’s European, Middle East, Africa and Asia regions and to a lesser extent in our other regions.
While this organizational redesign did not change the Company’s reportable segments, it had implications on how the Company manages the business, the most significant of which was the shift of certain responsibilities, namely customer and market related activities, into the regional selling organizations.
Segment orders, revenue and operating income are reallocated between the Company’s two reportable segments, Applied Water and Water Infrastructure.
The Company has recast certain historical amounts between the Company’s two reportable segments, however this change had no impact on the Company’s historical consolidated financial position or results of operations.
The recast financial information does not represent a restatement of previously issued financial statements.
temporarily impaired.
stock on date of grant.
Deferred Financing Costs
adjustments as considered appropriate by management.
derivative contracts with various financial institutions.
The fair value hierarchy gives the highest priority to quoted prices in active markets for identical assets or liabilities (Level 1), then to quoted market prices for similar assets or liabilities in active markets (Level 2) and gives the lowest priority to unobservable inputs (Level 3).
The components of the guidance may be applied either (a) prospectively to all awards granted or modified after the effective date, or (b) retrospectively to all awards outstanding as of the beginning of the earliest annual period presented in the financial statements and to all new or modified awards thereafter.
This guidance is
The impact of this guidance on our financial condition and results of operations will depend on the occurrence and the significance of disposal transactions that meet the criteria described above.
This guidance is effective for fiscal years beginning on or after December 15, 2014 with early adoption permitted.
In July 2013, the FASB issued guidance on the financial statement presentation of an unrecognized tax benefit.
The guidance requires that an unrecognized tax benefit or a portion of an unrecognized tax benefit, be presented as a reduction to a deferred tax asset for a net operating loss carryforward, a similar tax loss, or a tax credit carryforward.
If an applicable deferred tax asset is not available or a company does not expect to use the applicable deferred tax asset, the unrecognized tax benefit should be presented in an entity's financial statements as a liability and should not be combined with a deferred tax asset.
In March 2013, the FASB issued guidance on the release of a cumulative translation adjustment ("CTA") related to an entity's investment in a foreign entity into income.
The guidance requires such CTA to be released when there has been a: (1) sale of a subsidiary or group of net assets within a foreign entity and the sale represents the substantially complete liquidation of the investment in the foreign entity, (2) loss of a controlling financial interest in an investment in a foreign entity or (3) step acquisition for a foreign entity.
In February 2013, the FASB issued guidance related to the measurement and disclosure of obligations resulting from joint and several liability arrangements.
The new guidance requires companies to measure obligations resulting from joint and several liability arrangements as the sum of (1) the amount the company agreed to pay on the basis of its arrangement among co-obligors and (2) any additional amount the company expects to pay on behalf of its co-obligors.
Additionally, the new guidance requires the disclosure of a description of the joint and several arrangement and the total outstanding amount of the obligation for all joint parties.
2012 Acquisitions
Heartland and MJK
On October 26, 2012, we acquired Heartland Pump Rental & Sales, Inc. ("Heartland"), a dewatering pump sale and rental company, for approximately $29 million.
An excerpt. Shown here: 40 of 613 rewritten, 40 of 245 added and 40 of 159 removed. The counts are complete. For every sentence, read Item 8. FINANCIAL STATEMENTS AND SUPPLEMENTARY DATA in the FY2015 filing and the FY2014 filing.
Item 9A. CONTROLS AND PROCEDURES
6 rewritten, 0 added, 0 removed, 6 unchanged
Our management, with the [removed: participation of our] Chief Executive Officer ("CEO") and [removed: our] [added: Interim] Chief Financial Officer [removed: ("CFO"),] [added: ("CFO") of the Company, has] evaluated the effectiveness of the design and operation of our disclosure controls and procedures as of the end of the year ended December 31, [removed: 2014] [added: 2015] pursuant to Rule 13a-15(b) [added: and 15d-15(e)] of the Securities Exchange Act of 1934 (“the Exchange Act”).
Based upon that evaluation, our CEO and our CFO concluded that our disclosure controls and procedures as of the year ended December 31, [removed: 2014] [added: 2015] were effective, in all material respects, and designed to provide reasonable assurance that the information required to be disclosed by us in the reports we file or submit under the Exchange Act is (1) recorded, processed, summarized and reported, within the time periods specified in the SEC's rules and forms and (2) accumulated and communicated to our management, including our CEO and CFO, as appropriate to allow timely decisions regarding required disclosures.
The Company's management, including the CEO and CFO, conducted an assessment of the effectiveness of our internal control over financial reporting as of December 31, [removed: 2014] [added: 2015] based on the framework established in Internal Control - Integrated Framework issued by the Committee of Sponsoring Organization of the Treadway Commission (2013).
Based on our assessment, the Company's management has concluded that our internal control over financial reporting was effective as of December 31, [removed: 2014.][added: 2015.]
The effectiveness of the Company's internal control over financial reporting as of December 31, [removed: 2014] [added: 2015] has been audited by Deloitte & Touche LLP, an independent registered public accounting firm, as stated in their report which appears following Item 9B of this Annual Report on Form 10-K.
There were no changes in the Company's internal control over financial reporting that occurred during the quarter ended December 31, [removed: 2014] [added: 2015] that have materially affected, or are reasonably likely to materially affect, our internal control over financial reporting.
Item 9B. OTHER INFORMATION
3 rewritten, 1 added, 1 removed, 18 unchanged
We have audited the internal control over financial reporting of Xylem Inc. and subsidiaries (the "Company") as of December 31, [removed: 2014,] [added: 2015,] based on criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
In our opinion, the Company maintained, in all material respects, effective internal control over financial reporting as of December 31, [removed: 2014,] [added: 2015,] based on the criteria established in Internal Control - Integrated Framework (2013) issued by the Committee of Sponsoring Organizations of the Treadway Commission.
We have also audited, in accordance with the standards of the Public Company Accounting Oversight Board (United States), the consolidated financial statements as of and for the year ended December 31, [removed: 2014] [added: 2015] of the Company and our report dated February 26, [removed: 2015] [added: 2016] expressed an unqualified opinion on those financial statements.
February 26, 2016
February 26, 2015
Item 10. DIRECTORS, EXECUTIVE OFFICERS AND CORPORATE GOVERNANCE
7 rewritten, 1 added, 1 removed, 1 unchanged
The information required by this Item is incorporated herein by reference to the information in our Definitive Proxy Statement to be filed with the SEC in connection with our [removed: 2015] [added: 2016] Annual Meeting of Shareholders (the [removed: “2015] [added: “2016] Proxy Statement”) [removed: set forth] under the captions “Proposal 1 - Election of Directors,” [removed: "Director Selection] [added: "Identifying] and [removed: Composition," "Committees of the Board of Directors --] [added: Evaluating Director Nominees," "Board Committees -] Audit Committee" and “Section 16(a) Beneficial Ownership Reporting Compliance.”
We have adopted corporate governance principles and charters for each of our [removed: standing] [added: board] committees.
The principles address director qualification standards, responsibilities, access to management and independent advisors, compensation, orientation and continuing education, [removed: management] succession [removed: principles] [added: planning] and board and committee self-evaluation.
The corporate governance principles and [removed: standing] [added: board] committee charters are available on the Company’s website at www.investors.xyleminc.com.
A copy of the corporate governance principles and [removed: standing] [added: board] committee charters [removed: is] [added: are] also available to any shareholder who requests a copy from the Company’s Corporate [removed: Secretary.][added: Secretary at our Principal Executive Offices.]
We have also adopted a written code of conduct which is applicable to all our directors, officers and employees, including the Company’s Chief Executive Officer and [added: Interim] Chief Financial Officer and other executive officers identified pursuant to this Item 10.
In accordance with the SEC’s rules and regulations, a copy of the [removed: code] [added: Code of Conduct] has been posted to our website and [removed: a copy of the code of conduct] [added: it] is also available to any shareholder who requests [removed: it.][added: a copy from our Corporate Secretary.]
We intend to disclose any changes in our Code of Conduct and waivers of the Code of Conduct on our website at www.xyleminc.com within four business days following the date of the amendment or waiver.
We intend to disclose any changes in our code of conduct by posting a revised version on our website at www.xyleminc.com.
Item 11. EXECUTIVE COMPENSATION
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this Item is incorporated herein by reference to the information in our [removed: 2015] [added: 2016] Proxy Statement set forth under captions “Executive Compensation," [removed: "2014 Non-Management Director Compensation" and “Report of the] [added: "Director Compensation", "Board Committees -] Leadership Development [removed: &] [added: and] Compensation [removed: Committee.”][added: Committee" and “Leadership Development and Compensation Committee Report.”]
Item 12. SECURITY OWNERSHIP OF CERTAIN BENEFICIAL OWNERS AND MANAGEMENT AND RELATED STOCKHOLDER MATTERS
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this Item is incorporated herein by reference to the information in our [removed: 2015] [added: 2016] Proxy Statement set forth under the captions “Stock Ownership of Directors, Executive Officers and Certain Beneficial Owners” and "Equity Compensation Plan Information."
Item 13. CERTAIN RELATIONSHIPS AND RELATED TRANSACTIONS, AND DIRECTOR INDEPENDENCE
1 rewritten, 0 added, 0 removed, 0 unchanged
The information required by this Item is incorporated herein by reference to the information in our [removed: 2015] [added: 2016] Proxy Statement set forth under the [removed: caption “Information About our Board of Directors.”][added: captions "Governance - Director Independence" and “Governance - Related Party Transactions.”]
Item 14. PRINCIPAL ACCOUNTING FEES AND SERVICES
1 rewritten, 0 added, 0 removed, 1 unchanged
The information required by this Item is incorporated herein by reference to the information in our [removed: 2015] [added: 2016] Proxy Statement set forth under the [removed: caption “Independent Registered Public Accounting Firm Fees.”][added: captions “Fees of Audit and Other Services Fees” and "Pre-Approval of Audit and Non-Audit Services."]
Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES
44 rewritten, 68 added, 17 removed, 46 unchanged
| | (Principal Accounting [added: Officer and Duly Authorized] Officer) |
| February 26, [removed: 2015] [added: 2016] | | /s/ Patrick K. Decker |
| February 26, [removed: 2015] [added: 2016] | | /s/ Markos I. Tambakeras |
| February 26, [removed: 2015] [added: 2016] | | /s/ Curtis J. Crawford |
| February 26, [removed: 2015] [added: 2016] | | /s/ Robert F. Friel |
| February 26, [removed: 2015] [added: 2016] | | /s/ Victoria D. Harker |
| February 26, [removed: 2015] [added: 2016] | | /s/ Sten E. Jakobsson |
| February 26, [removed: 2015] [added: 2016] | | /s/ Steven R. Loranger |
| February 26, [removed: 2015] [added: 2016] | | /s/ Edward J. Ludwig |
| February 26, [removed: 2015] [added: 2016] | | /s/ Surya N. Mohapatra |
| February 26, [removed: 2015] [added: 2016] | | /s/ Jerome A. Peribere |
| Exhibit Number | [removed: |] Description | Location |
| [removed: (2.1 | )] [added: (2.1)] | Distribution Agreement, dated as of October 25, 2011, among ITT Corporation, Exelis Inc. and Xylem Inc. | Incorporated by reference to Exhibit 10.1 of ITT Corporation’s Form 10-Q Quarterly Report filed on October 28, 2011 (CIK No. 216228, File No. 1-5672). |
| [removed: (3.1 | )] [added: (3.1)] | Third Amended and Restated Articles of Incorporation of Xylem Inc. | Incorporated by reference to Exhibit 3.1 of Xylem Inc.’s Form 10-Q filed on July 29, 2014 (CIK No. 131190969, File No. 1-35229). |
| [removed: (3.2 | )] [added: (3.2)] | Amended and Restated By-laws of Xylem Inc. | Incorporated by reference to Exhibit [removed: 3.2] [added: 3.1] of Xylem Inc.’s Form [removed: 10-Q] [added: 8-K] filed on [removed: July 29, 2014] [added: February 25, 2016] (CIK No. [removed: 131190969,] [added: 1524472,] File No. 1-35229). |
| [removed: (4.1 | )] [added: (4.1)] | Indenture, dated as of September 20, 2011, between Xylem Inc., ITT Corporation, as initial guarantor, and Union Bank, N.A., as trustee | Incorporated by reference to Exhibit 4.2 of ITT Corporation’s Form 8-K Current Report filed on September 21, 2011 (CIK No. 216228, File No. 1-5672). |
| [removed: (4.2 | )] [added: (4.2)] | Form of Xylem Inc. 3.550% Senior Notes due 2016 | Incorporated by reference to Exhibit 4.5 of Xylem Inc.'s Form S-4 Registration Statement filed on May 24, 2012 (CIK No. 1524472, File No. 333-181643). |
| [removed: (4.3 | )] [added: (4.3)] | Form of Xylem Inc. 4.875% Senior Notes due 2021 | Incorporated by reference to Exhibit 4.6 of Xylem Inc.'s Form S-4 Registration Statement filed on May 24, 2012 (CIK No. 1524472, File No. 333-181643). |
| [removed: (10.1 | )] [added: (10.1)] | Form of Xylem 2011 Omnibus Incentive Plan Non-Qualified Stock Option Award Agreement [removed: - 2015] [added: (2015)] | [removed: Filed herewith.] [added: Incorporated by reference to Exhibit 10.1 of Xylem Inc.’s Form 10-K Annual Report filed on February 26, 2015 (CIK No. 1524472, File No. 1-35229).] |
| [removed: (10.2 | )] [added: (10.2)] | Benefits and Compensation Matters Agreement, dated as of October 25, 2011, among ITT Corporation, Exelis Inc. and Xylem Inc. | Incorporated by reference to Exhibit 10.2 of ITT Corporation’s Form 10-Q Quarterly Report filed on October 28, 2011 (CIK No. 216228, File No. 1-5672). |
| [removed: (10.3 | )] [added: (10.3)] | Tax Matters Agreement, dated as of October 25, 2011, among ITT Corporation, Exelis Inc. and Xylem Inc. | Incorporated by reference to Exhibit 10.3 of ITT Corporation’s Form 10-Q Quarterly Report filed on October 28, 2011 (CIK No. 216228, File No. 1-5672). |
| [removed: (10.4 | )] [added: (10.4)] | Master Transition Services Agreement, dated as of October 25, 2011, among ITT Corporation, Exelis Inc. and Xylem Inc. | Incorporated by reference to Exhibit 10.4 of ITT Corporation’s Form 10-Q Quarterly Report filed on October 28, 2011 (CIK No. 216228, File No. 1-5672). |
| [removed: (10.5 | )] [added: (10.5)] | [removed: Four-Year Competitive Advance and] [added: Five-Year] Revolving Credit Facility Agreement, dated as of [removed: October 25, 2011,] [added: March 27, 2015,] among Xylem Inc., the Lenders Named Therein, [removed: J.P. Morgan Chase Bank,] [added: Citibank,] N.A., as Administrative Agent and [removed: Citibank,] [added: J.P. Morgan Chase Bank,] N.A., as Syndication Agent. | Incorporated by reference to Exhibit [removed: 10.5] [added: 10.1] of Xylem [removed: Inc.’s] [added: Inc.'s] Form [removed: 10-Q Quarterly Report] [added: 8-K] filed on [removed: November 21, 2011] [added: March 31, 2015] (CIK No. 1524472, File No. 1-35229). |
| [removed: (10.6 | )] [added: (10.12)] | Xylem [removed: 2011 Omnibus Incentive] [added: Deferred Compensation] Plan | Incorporated by reference to Exhibit [removed: 4.3] [added: 4.5] of Xylem Inc.’s Registration Statement on Form S-8 filed on October 28, 2011 (CIK No. 1524472, File No. 333-177607). |
| [removed: (10.7 | )] [added: (10.11)] | Xylem [removed: 1997 Long-Term Incentive] [added: Supplemental Retirement Savings] Plan | Incorporated by reference to Exhibit [removed: 10.7] [added: 10.11] of Xylem Inc.’s Form 10-Q Quarterly Report filed on November 21, 2011 (CIK No. 1524472, File No. 1-35229). |
| [removed: (10.8 | )] [added: (10.13)] | Xylem [removed: 1997 Annual Incentive] [added: Deferred Compensation] Plan [added: for Non-Employee Directors] | Incorporated by reference to Exhibit [removed: 10.8] [added: 10.13] of Xylem Inc.’s Form 10-Q Quarterly Report filed on November 21, 2011 (CIK No. 1524472, File No. 1-35229). |
| [removed: (10.9 | )] [added: (10.17)] | [added: Form of] Xylem [removed: Annual] [added: 2011 Omnibus] Incentive Plan [removed: for Executive Officers] [added: 2011 Non-Qualified Stock Option Award Agreement — Founders Grant] | Incorporated by reference to Exhibit [removed: 10.9] [added: 10.17] of Xylem Inc.’s Form 10-Q Quarterly Report filed on November 21, 2011 (CIK No. 1524472, File No. 1-35229). |
| [removed: (10.10 | )] [added: (10.10)] | Xylem Retirement Savings Plan | Incorporated by reference to Exhibit 10.1 of Xylem Inc.’s Form 10-Q filed on July 30, 2013 (CIK No. 1524472, File No. 1-35229). |
| [removed: (10.11 | )] [added: (10.18)] | [added: Form of] Xylem [removed: Supplemental Retirement Savings] [added: 2011 Omnibus Incentive] Plan [added: Non-Qualified Stock Option Award Agreement — General Grant] | Incorporated by reference to Exhibit [removed: 10.11] [added: 10.18] of Xylem Inc.’s Form 10-Q Quarterly Report filed on November 21, 2011 (CIK No. 1524472, File No. 1-35229). |
| [removed: (10.13 | )] [added: (10.21)] | [added: Form of] Xylem [removed: Deferred Compensation] [added: 2011 Omnibus Incentive] Plan [removed: for Non-Employee Directors] [added: Non-Qualified Stock Option Award Agreement (2013)] | Incorporated by reference to Exhibit [removed: 10.13] [added: 10.1] of Xylem [removed: Inc.’s] [added: Inc.'s] Form 10-Q Quarterly Report filed on [removed: November 21, 2011] [added: April 30, 2013] (CIK No. 1524472, File No. 1-35229). |
| [removed: (10.14 | )] [added: (10.14)] | [removed: Xylem Enhanced Severance Pay Plan] [added: Form of Non-Employee Director Restricted Stock Unit Award Agreement] | Incorporated by reference to Exhibit [removed: 10.29] [added: 10.1] of Xylem Inc.’s Form 10-Q Quarterly Report filed on [removed: May 3, 2012] [added: July 30, 2015] (CIK No. 1524472, File No. 1-35229). |
| [removed: (10.15 | )] [added: (10.22)] | [added: Letter Agreement between] Xylem [removed: Special Senior Executive Severance Pay Plan] [added: Inc. and Patrick K. Decker] | Incorporated by reference to Exhibit 10.1 of Xylem [removed: Inc.’s] [added: Inc.'s] Form 10-Q Quarterly Report filed on [removed: October 28,] [added: April 29,] 2014 (CIK No. 1524472, File No. 1-35229). |
| [removed: (10.17 | )] [added: (10.23)] | [removed: Form of Xylem 2011 Omnibus Incentive Plan 2011 Non-Qualified] [added: Restricted] Stock [removed: Option Award Agreement — Founders] [added: Unit] Grant [added: Agreement between Xylem Inc. and Patrick K. Decker] | Incorporated by reference to Exhibit [removed: 10.17] [added: 10.1] of Xylem [removed: Inc.’s] [added: Inc.'s] Form [removed: 10-Q Quarterly] [added: 8-K Current] Report filed on [removed: November 21, 2011] [added: March 20, 2014] (CIK No. 1524472, File No. 1-35229). |
| [removed: (10.25 | )] [added: (10.24)] | Research and Development Facility Agreement - Xylem Water Technologies Risk-Sharing Financing Facility First Amended and Restated Finance Contract, dated December 4, 2013, among the European Investment Bank, Xylem Holdings S.a.r.l. and Xylem International S.a.r.l., as borrowers, and Xylem Inc., as guarantor. | Incorporated by reference to Exhibit 10.30 of Xylem Inc.’s Form 10-K Annual Report filed on February 27, 2014 (CIK No. 1524472, File No. 1-35229). |
| [removed: (10.26 | )] [added: (10.25)] | Agreement dated [removed: June 28, 2014,] [added: May 4, 2015,] Amending the Research and Development Facility Agreement - Xylem Water Technologies Risk-Sharing Financing Facility First Amended and Restated Finance Contract, dated [removed: December 4, 2013,] [added: June 28, 2014,] among the European Investment Bank, Xylem Holdings S.á r.l. and Xylem International S.á r.l., as borrowers, and Xylem Inc., as guarantor. | Incorporated by reference to Exhibit [removed: 10.1] [added: 10.2] of Xylem Inc.’s Form 10-Q Quarterly Report filed on July [removed: 29, 2014] [added: 30, 2015] (CIK No. 1524472, File No. [removed: 1-35229)] [added: 1-35229).] |
| [removed: (11.0 | )] [added: (11.0)] | Statement re computation of per share earnings | Information required to be presented in Exhibit 11 is provided under "Earnings Per Share" in Note [removed: 8 to] [added: 7 of] the consolidated financial statements in Part II, Item 8. “Financial Statements and Supplementary Data” of this Annual Report on Form 10-K in accordance with the provisions of Financial Accounting Standards Board Accounting Standards Codification 260, Earnings Per Share. |
| [removed: (12.0 | )] [added: (12.0)] | Statements re computation of ratios | Filed herewith. |
| [removed: (21.0 | )] [added: (21.0)] | Subsidiaries of the Registrant | Filed herewith. |
| [removed: (23.1 | )] [added: (23.1)] | Consent of Independent Registered Public Accounting Firm | Filed herewith. |
| [removed: (31.1 | )] [added: (31.1)] | Certification pursuant to Rule 13a-14(a)/15d-14(a) of the Securities Exchange Act of 1934, as adopted pursuant to Section 302 of the Sarbanes-Oxley Act of 2002 | Filed herewith. |
February 26, 2016
| February 26, 2016 | | /s/ Shashank Patel |
| | | Shashank Patel |
| | | Interim Chief Financial Officer |
| --- | --- | --- |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| (10.6) | Xylem 2011 Omnibus Incentive Plan (Amended as of February 24, 2016) | Filed herewith. |
| | | |
| (10.7) | Form of Xylem Non-Qualified Stock Option Award Agreement (Amended as of February 24, 2016) | Filed herewith. |
| | | |
| (10.8) | Form of Xylem Restricted Stock Unit Agreement (Amended as of February 24, 2016) | Filed herewith. |
| | | |
| | | |
| --- | --- | --- |
| | | |
| Exhibit Number | Description | Location |
| (10.9) | Form of Xylem Performance Share Unit Agreement (Amended as of February 24, 2016) | Filed herewith. |
| | | |
| | | |
| | | |
| | | |
| | | |
| | | |
| (10.15) | Xylem Special Senior Executive Severance Pay Plan (Amended as of February 24, 2016) | Filed herewith. |
| | | |
| (10.16) | Xylem Senior Executive Severance Pay Plan (Amended as of February 24, 2016) | Filed herewith. |
| | | |
| | | |
February 26, 2015
| February 26, 2015 | | /s/ Michael T. Speetzen |
| | | Michael T. Speetzen |
| | | Senior Vice President and Chief Financial Officer |
| February 26, 2015 | | /s/ James P. Rogers |
| | | James P. Rogers, Director |
| | | | |
| --- | --- | --- | --- |
| (10.12 | ) | Xylem Deferred Compensation Plan | Incorporated by reference to Exhibit 4.5 of Xylem Inc.’s Registration Statement on Form S-8 filed on October 28, 2011 (CIK No. 1524472, File No. 333-177607). |
| (10.16 | ) | Xylem Senior Executive Severance Pay Plan | Incorporated by reference to Exhibit 10.16 of Xylem Inc.’s Form 10-Q Quarterly Report filed on November 21, 2011 (CIK No. 1524472, File No. 1-35229). |
| (10.18 | ) | Form of Xylem 2011 Omnibus Incentive Plan Non-Qualified Stock Option Award Agreement — General Grant | Incorporated by reference to Exhibit 10.18 of Xylem Inc.’s Form 10-Q Quarterly Report filed on November 21, 2011 (CIK No. 1524472, File No. 1-35229). |
| (10.19 | ) | Form of Xylem 2011 Omnibus Incentive Plan-Performance Share Unit Agreement | Incorporated by reference to Exhibit 10.3 of Xylem Inc.'s Form 10-Q Quarterly Report filed on April 30, 2013 (CIK No. 1524472, File No. 1-35229). |
| (10.20 | ) | Form of Director’s Indemnification Agreement | Incorporated by reference to Exhibit 10.24 of Xylem Inc.’s Form 10-Q Quarterly Report filed on November 21, 2011 (CIK No. 1524472, File No. 1-35229). |
| (10.21 | ) | Form of Xylem 2011 Omnibus Incentive Plan 2012 Restricted Stock Unit Agreement | Incorporated by reference to Exhibit 10.2 of Xylem Inc.'s Form 10-Q Quarterly Report filed on April 30, 2013 (CIK No. 1524472, File No. 1-35229). |
| (10.22 | ) | Form of Xylem 2011 Omnibus Incentive Plan 2012 Non-Qualified Stock Option Award Agreement | Incorporated by reference to Exhibit 10.1 of Xylem Inc.'s Form 10-Q Quarterly Report filed on April 30, 2013 (CIK No. 1524472, File No. 1-35229). |
| (10.23 | ) | Letter Agreement between Xylem Inc. and Patrick K. Decker | Incorporated by reference to Exhibit 10.1 of Xylem Inc.'s Form 10-Q Quarterly Report filed on April 29, 2014 (CIK No. 1524472, File No. 1-35229). |
| (10.24 | ) | Restricted Stock Unit Grant Agreement between Xylem Inc. and Patrick K. Decker | Incorporated by reference to Exhibit 10.1 of Xylem Inc.'s Form 8-K Current Report filed on March 20, 2014 (CIK No. 1524472, File No. 1-35229). |
An excerpt. Shown here: 40 of 44 rewritten, 40 of 68 added and all 17 removed. The counts are complete. For every sentence, read Item 15. EXHIBITS, FINANCIAL STATEMENT SCHEDULES in the FY2015 filing and the FY2014 filing.